
Audit of Agricultural and other priority sector



















Description: Audit of Agricultural and other priority sector advances Statutory audit of bank branches Friday, 24th March 2023 at Solapur Branch of WIRC of The Institute of Chartered accountants of India, New Delhi Why priority sector ? Focus on rural
Related Topics
Download Presentation
"Audit of Agricultural and other priority sector" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Audit of Agricultural and other priority sector advances Statutory audit of bank branches Friday, 24th March 2023 at
Solapur Branch of WIRC of
The Institute of Chartered accountants of India, New Delhi<br>
slide2. Why priority sector ?
Focus on rural development by the government
Channel resources to areas that are deemed national priorities
Inclusion of poor in the economic growth of the country
Synchronize the bank lending account to national importance Statutory audit of bank branches<br>
slide3. Objective
Objective of priority sector lending program is to ensure adequate fund flows to some of the vulnerable sectors of the economy, which may not be attractive for the banks from the point of view of profitability. Statutory audit of bank branches<br>
slide4. Salient features of the revised guidelines
TARGET
Target for lending to total priority sector and weaker section will continue as 40 per cent and 10 per cent, respectively, of Adjusted Net Bank Credit (ANBC) or credit equivalent of off-balance sheet exposure, whichever is higher, as hitherto.
Agriculture: Distinction between direct and indirect agriculture is dispensed with. Statutory audit of bank branches<br>
slide5. 3. Bank loans to food and agro processing units will form part of Agriculture.
4. Medium Enterprises, Social Infrastructure and Renewable Energy will form part of priority sector.
5. A target of 7.5 per cent of ANBC or credit equivalent of off-balance sheet exposure, whichever is higher, has been prescribed for Micro Enterprises.
6.Education: Distinction between loans for education in India and abroad is dispensed with. Statutory audit of bank branches<br>
slide6. 7. Micro Credit ceases to be a separate category under priority sector.
8. Loan limits for housing loans qualifying under priority sector have been revised.
9. Priority Sector assessment will be monitored through quarterly and annual statements. Statutory audit of bank branches<br>
slide7. Priority Sector includes the following categories:
(i) Agriculture (ii) Micro, Small and Medium Enterprises (iii) Export Credit (iv) Education (v) Affordable Housing (vi) Social Infrastructure (vii) Renewable Energy (viii) Others Statutory audit of bank branches<br>
slide8. Total Priority Sector
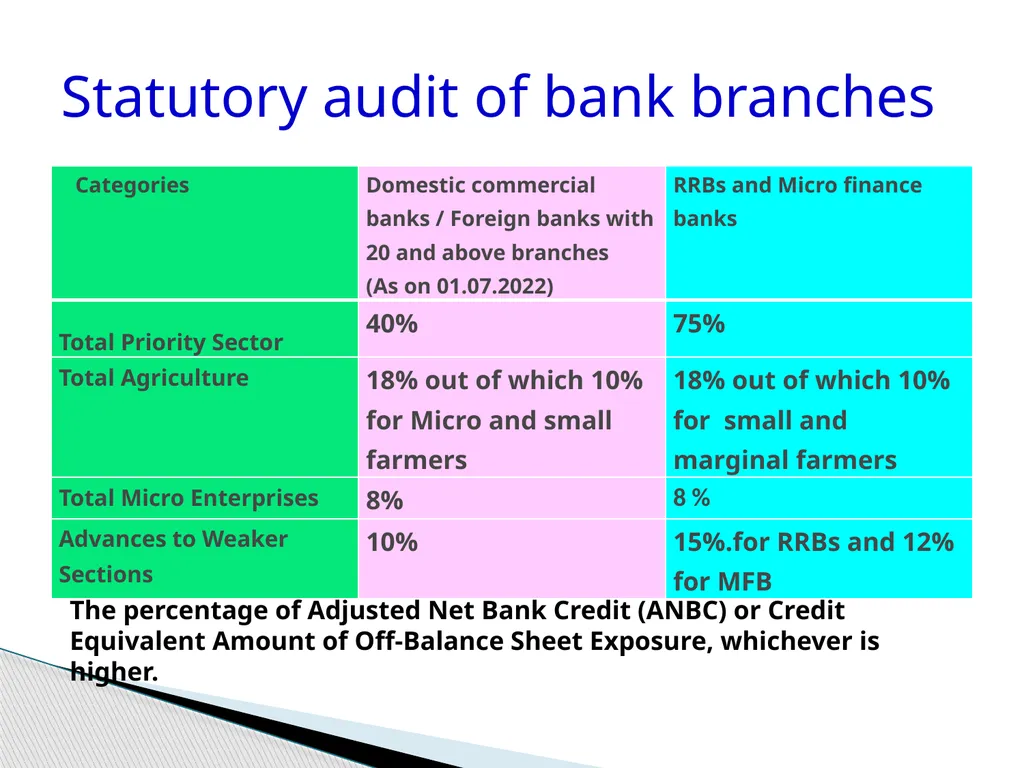
40 percent of Adjusted Net Bank Credit or Credit Equivalent Amount of Off-Balance Sheet Exposure, whichever is higher.
Foreign banks with less than 20 branches have to achieve the Total Priority Sector.
RRBs and Small Finance banks should have a target of 75% each of ANBC Statutory audit of bank branches<br>
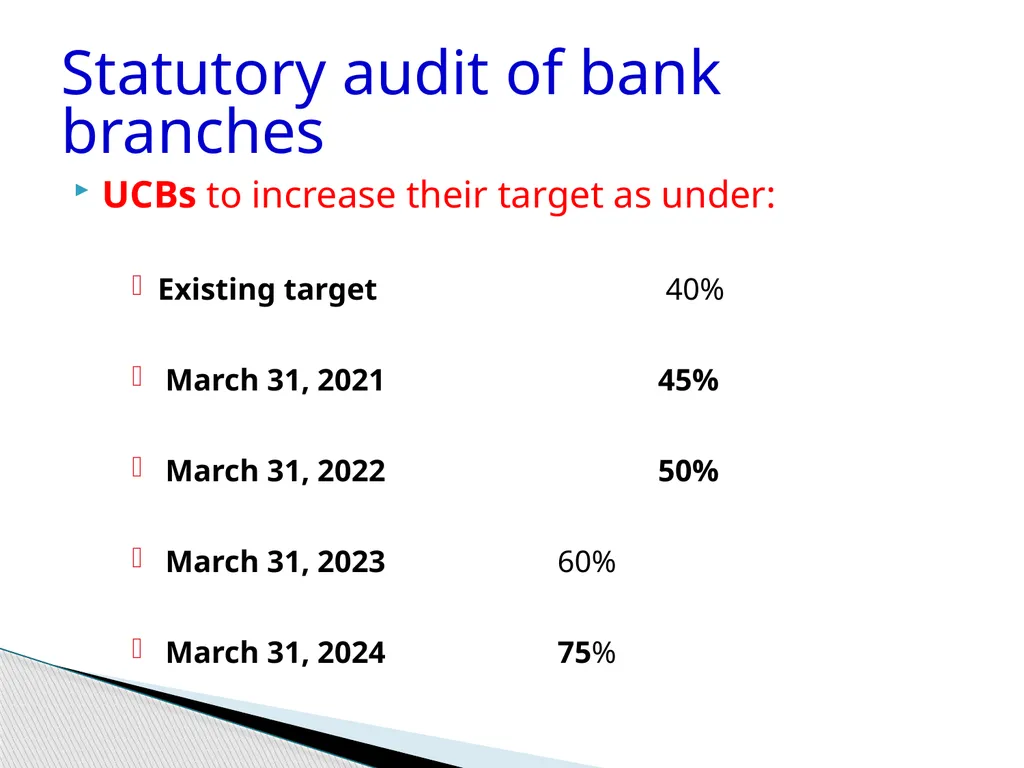
slide9. UCBs to increase their target as under:
Existing target 40%
March 31, 2021 45%
March 31, 2022 50%
March 31, 2023 60%
March 31, 2024 75% Statutory audit of bank branches<br>
slide10. Statutory audit of bank branches The percentage of Adjusted Net Bank Credit (ANBC) or Credit Equivalent Amount of Off-Balance Sheet Exposure, whichever is higher.<br>
slide11. Categories under ‘Agriculture’?
The activities covered under Agriculture are classified under three sub-categories
viz.
1.Farm credit,
2. Agriculture infrastructure and
3. Ancillary activities Statutory audit of bank branches<br>
slide12. Farm Credit - Individual farmers
Loans to individual farmers [including Self Help Groups (SHGs) or Joint Liability Groups (JLGs) i.e. groups of individual farmers, provided banks maintain disaggregated data of such loans] and Proprietorship firms of farmers, directly engaged in Agriculture and Allied Activities, viz. dairy, fishery, animal husbandry, poultry, bee-keeping and sericulture. This will include incidentals too Statutory audit of bank branches<br>
slide13. Farm Credit:
(i) Crop loans to farmers, which will include traditional/non-traditional plantations and horticulture, and, loans for allied activities. Traditional crops include:
(a) Food Crops (Wheat, Maize, Rice, Millets and Pulses etc.)
(b) Cash Crops (Sugarcane, Tobacco, Cotton, Jute and Oilseeds etc.)
(c) Plantation Crops (Coffee, Coconut, Tea, and Rubber etc.)
(d) Horticulture crops (Fruits and Vegetables)
(e) Zaid crops includes (Watermelon. Muskmelon. Cucumber. Bitter gourd. Fodder crops.) Statutory audit of bank branches<br>
slide14. Costliest crop is saffron and the present value is US $ 5000 per KG (Rs 375000)
Non-traditional crops are commonly thought of as low acreage, niche crops such as ethnic fruits and vegetables, culinary and medicinal herbs, and plants for industrial uses (e.g. fibre hemp), sunflower. .. Statutory audit of bank branches<br>
slide15. ii. Medium and long-term loans to farmers for agriculture and allied activities (e.g. purchase of agricultural implements and machinery, loans for irrigation etc.)
(iii)Loans to farmers for pre and post-harvest activities, viz., spraying, weeding, harvesting, transporting their own farm produce. Statutory audit of bank branches<br>
slide16. (iv) Loans to distressed farmers indebted to non-institutional lenders.
(v) Loans to farmers under the Kisan Credit Card Scheme.
(vi)Loans to small and marginal farmers for purchase of land for agricultural purposes.
(vii)Loans against pledge/hypothecation of agricultural produce (including warehouse receipt1) for a period not exceeding 12 months subject to a limit up to ₹50 lakh. Statutory audit of bank branches<br>
slide17. (viii) Loans to farmers for installation of stand-alone Solar Agriculture Pumps and for solarisation of grid connected Agriculture Pumps.
(ix) Loans to farmers for installation of solar power plants on barren/fallow land or in stilt fashion on agriculture land owned by farmer. Statutory audit of bank branches<br>
slide18. Agriculture infrastructure
(a) Loans for the following activities will be subject to an aggregate limit of Rs. 2 crore per borrowing entity:
(b) Loans up to Rs. 50 lakh against pledge/hypothecation of agricultural produce (including warehouse receipts) for a period not exceeding 12 months.
(c) UCBs are not permitted to lend to co- operatives of farmers Statutory audit of bank branches<br>
slide19. (d) Loans up to Rs. 5 crore per borrowing entity to Farmers Producers Organisation/ companies (FPOs) /FPCs undertaking farming with assured marketing of their produce at a pre-determined price.
Agriculture Infrastructure
Loans for agriculture infrastructure will be subject to an aggregate sanctioned limit of Rs. 100 crore per borrower from the banking system. Statutory audit of bank branches<br>
slide20. Small and Marginal Farmers (SMFs)
For the purpose of computation of achievement of the sub-target, Small and Marginal Farmers will include the following:
i. Farmers with landholding of up to 1 hectare (Marginal Farmers).
ii. Farmers with a landholding of more than 1 hectare and up to 2 hectares (Small Farmers). Statutory audit of bank branches<br>
slide21. iii. Landless agricultural labourers, tenant farmers, oral lessees and share-croppers whose share of landholding is within the limits prescribed for SMFs.
Sharecropping is a legal arrangement with regard to agricultural land in which a landowner allows a tenant to use the land in return for a share of the crops produced on that land. Statutory audit of bank branches<br>
slide22. iv. Loans to Self Help Groups (SHGs) or Joint Liability Groups (JLGs), i.e. groups of individual SMFs directly engaged in Agriculture and Allied Activities, provided banks maintain disaggregated data of such loans.
v. Loans up to Rs. 2 lakh to individuals solely engaged in Allied activities without any accompanying land holding criteria. Statutory audit of bank branches<br>
slide23. vi. Loans to FPOs/FPC of individual farmers and co-operatives of farmers directly engaged in Agriculture and Allied Activities where the land-holding share of SMFs is not less than 75 per cent, subject to loan limits prescribed time to time.
UCBs are not permitted to lend to co-operatives of farmers. Statutory audit of bank branches<br>
slide24. General Hints or approach
The audit approach for agriculture advances has to be on the similar lines as that of other advances. The following is a summary of few Key aspects in the audit of Agricultural Advances:
a. Sanctioned amount of Agriculture Loans should be as per scale of finance applicable to the land under cultivation and the crop being cultivated. Further, necessary securities should be obtained as per the guidelines framed by the bank. Statutory audit of bank branches<br>
slide25. b. Auditors should verify that the agricultural credit is extended only after obtaining ‘No dues/ No objection certificates’ from the existing credit agencies in the area of finance.
c. Disbursement of agricultural finance is required to be carried out in various ‘stages’ based on the requirements of farming activity. This needs to be ensured strictly. In some cases, the expenditure is incurred by Statutory audit of bank branches<br>
slide26. farmer from his/her own sources or from non institutional lenders and subsequently banks are requested to reimburse the same. In such cases, auditors have to carefully verify the facts from the documents/evidences available on record. Under all situations, auditors should verify that the bank holds documents evidencing the utilisation of loans for agricultural activities. Statutory audit of bank branches<br>
slide27. d. For crop loans, primary security is normally the standing crops under cultivation, as such pre and post sanction visits by the officers of bank, who are experts in Agriculture finance and adequate documentation of visit report is a key control. Statutory audit of bank branches<br>
slide28. e. While verifying the security offered for agricultural loans, it is to be confirmed that the security is legally enforceable. Standing crops and agricultural machinery and implements are secured by a hypothecation charge, while the agricultural land is secured by a mortgage charge. Auditors have to ensure that amongst others, the following has been duly taken on record by the banks: Statutory audit of bank branches<br>
slide29. 1. Copy of the land revenue extracts. 2. Land Tax Assessment and payment receipt. 3. Copy of record with sub registrar (wherever applicable) 4. Original copies of the title deeds 5. Search of title deeds and Legal opinion from the advocate on the Bank’s approved panel 6. Valuation of land from a valuer on the Bank’s approved panel. Statutory audit of bank branches<br>
slide30. f. Loans granted to farmers against the security of NSC, KVP or Fixed Deposits of Banks, which has been utilised for agricultural purposes, is allowed to be classified under the category of finance to agriculture. However, auditors should carefully verify the loan documents and other supporting documents to ensure that non-agricultural loans are not classified as Agricultural Finance. Statutory audit of bank branches<br>
slide31. g. Agricultural Advances are required to be serviced through realisation of sale proceeds to crop. Auditors should be skeptical about the nature and timing credits coming in to service the agricultural loans and ensure that they are from genuine sources.
h. Ask about the nature of produce in the area ( Rabi and Kharif or Ek Fasli or Do Fasli or Teen Fasli Land)
i. Ask about the work sheet of Branch for calculation of Loan. Statutory audit of bank branches<br>
slide32. J. Find Bank has disbursed loan in single installment or as per FASAL calculation.
K. As Audit guidance point no C above it is clear that disbursement of loan should be as per requirement but generally found Bank disburse whole amount in first installment Not as per FASAL Production, this point should be reported Statutory audit of bank branches<br>
slide33. L. Due diligence and Assessment of Requirements
(Adherence of bank’s credit policy/guidelines)
To check whether
(i) necessary due diligence (i.e. pre-inspection report, lawyer search report, report of credit information company, copy of khasra and khatauni) as per bank’s policy has been carried out; Statutory audit of bank branches<br>
slide34. (ii) credit limits (short term farm credit and term loan components) are assessed on the basis of relevant criteria as per bank’s policy, such as operational land holding, cropping pattern and current scale of finance; and
(iii) RBI guidelines on revised KCC scheme have been adhered meticulously. Statutory audit of bank branches<br>
slide35. FIDD.CO.FSD.BC.No.6/05.05.010/2018-19 July 4, 2018 RBI Master Circular –
Kisan Credit Card (KCC) Scheme and revised KCC Scheme announced by Govt. of India on December 18, 2022. Statutory audit of bank branches<br>
slide36. Disbursement and Documentation
To check whether
(i) disbursement has been made to borrower’s SB account/as per bank’s guidelines/directly to vendor;
(ii) mandatory crop insurance premium has been paid through KCC accounts; and
(iii) Necessary documentation has been duly completed and held on records such as Statutory audit of bank branches<br>
slide37. declaration from borrower for noting charge in land revenue records and mortgage of land
hypothecation of crop and mortgage of agricultural land, if required, per bank’s policy
noting of charge in land revenue records
simple registration of mortgage (SRM) of land, if mortgaged, with sub-registrar. Statutory audit of bank branches<br>
slide38. Audit Hints
:
1. In terms of RBI Circular FIDD CO. FSD BC No 13/05.05.010/2018-19 dated Feb 07, 2019, no collateral (i.e. mortgage on agricultural land) is required for agricultural loans
upto Rs 1.60 lakh. Statutory audit of bank branches<br>
slide39. 2. KCC facility has been extended to Animal
Husbandry farmers and Fisheries for working capital (FIDD. CO. FSD. BC. 12/05.05,010/2018-19 dated Feb 04 2019) updated 18
February 2022 vide RBI circular No. ‘FIDD.CO.FSD. BC.No.6/05.05.010/2022-23’ to be
added.
3. Check few account statements for potential
transfer of disbursement to intermediary
account or to close the existing NPA KCC
account, if any. Statutory audit of bank branches<br>
slide40. Kharif Crops
These crops are sown at the commencement of rainy season in June and are harvested in the autumn season in the beginning of November.
The principal products are rice, maize, cotton, jute, tobacco, groundnut, castor, seasame Statutory audit of bank branches<br>
slide41. Rabi crops
These are sown in the winter season (October November) and harvested in the beginning of summer (March, April)
The main products of the Rabi crops are wheat, barley, gram, linseed, mustard Statutory audit of bank branches<br>
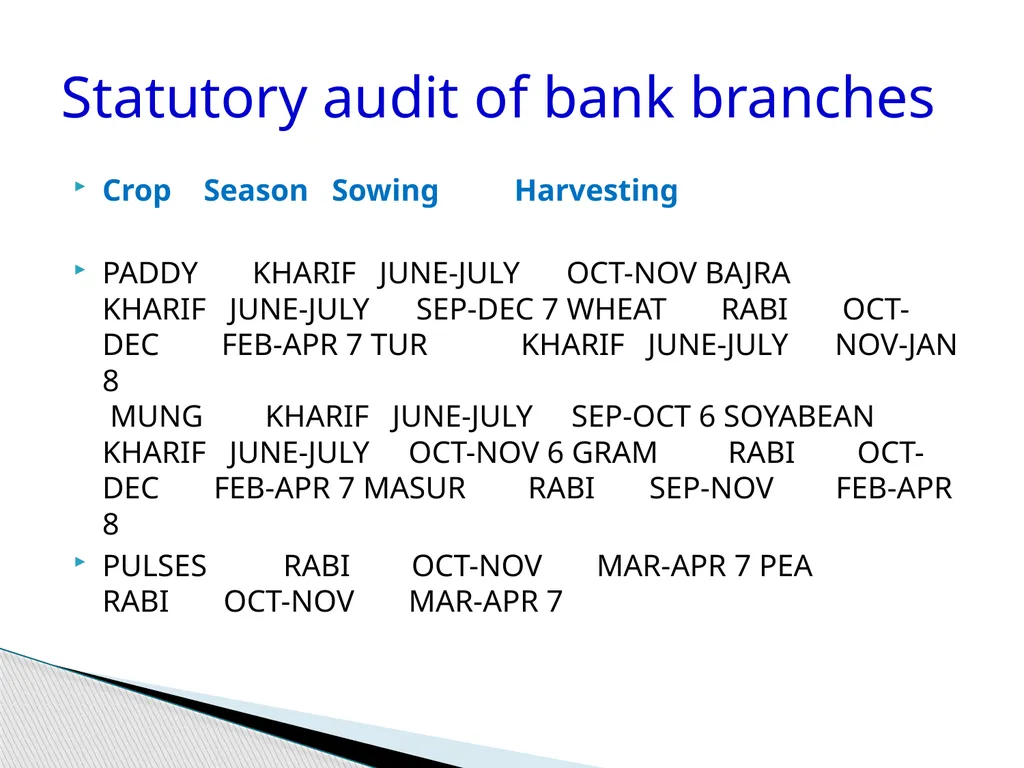
slide42. Crop Season Sowing Harvesting
PADDY KHARIF JUNE-JULY OCT-NOV BAJRA KHARIF JUNE-JULY SEP-DEC 7 WHEAT RABI OCT-DEC FEB-APR 7 TUR KHARIF JUNE-JULY NOV-JAN 8 MUNG KHARIF JUNE-JULY SEP-OCT 6 SOYABEAN KHARIF JUNE-JULY OCT-NOV 6 GRAM RABI OCT-DEC FEB-APR 7 MASUR RABI SEP-NOV FEB-APR 8
PULSES RABI OCT-NOV MAR-APR 7 PEA RABI OCT-NOV MAR-APR 7 Statutory audit of bank branches<br>
slide43. Crop Season Sowing Harvesting
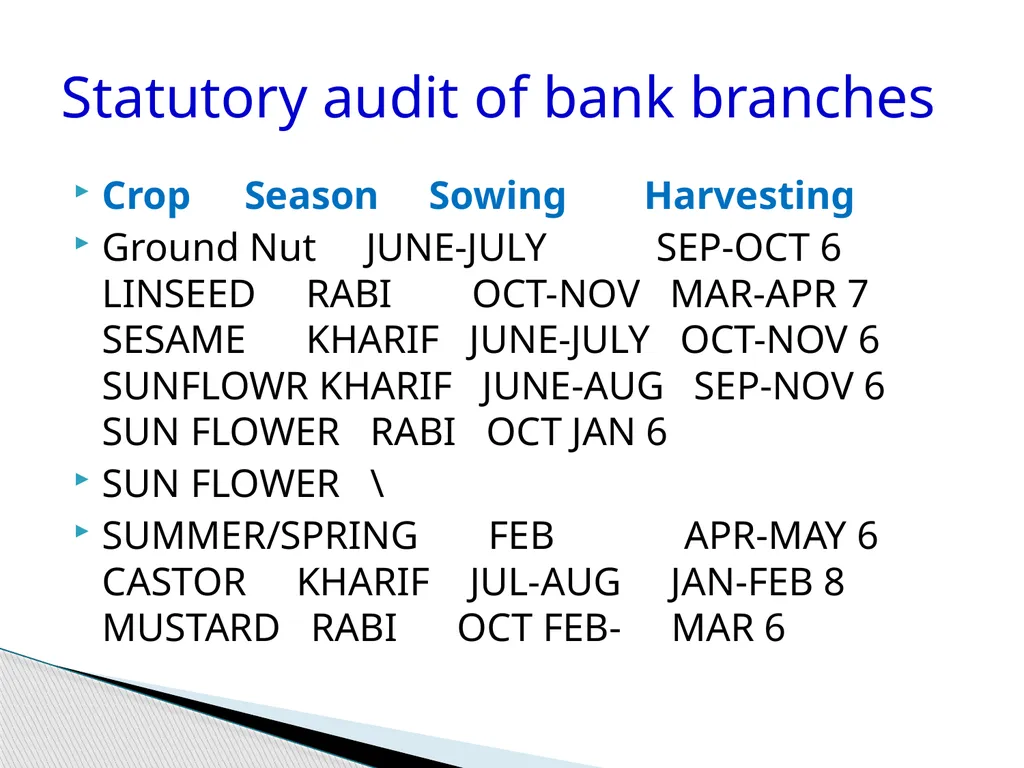
Ground Nut JUNE-JULY SEP-OCT 6 LINSEED RABI OCT-NOV MAR-APR 7 SESAME KHARIF JUNE-JULY OCT-NOV 6 SUNFLOWR KHARIF JUNE-AUG SEP-NOV 6 SUN FLOWER RABI OCT JAN 6
SUN FLOWER \
SUMMER/SPRING FEB APR-MAY 6 CASTOR KHARIF JUL-AUG JAN-FEB 8 MUSTARD RABI OCT FEB- MAR 6 Statutory audit of bank branches<br>
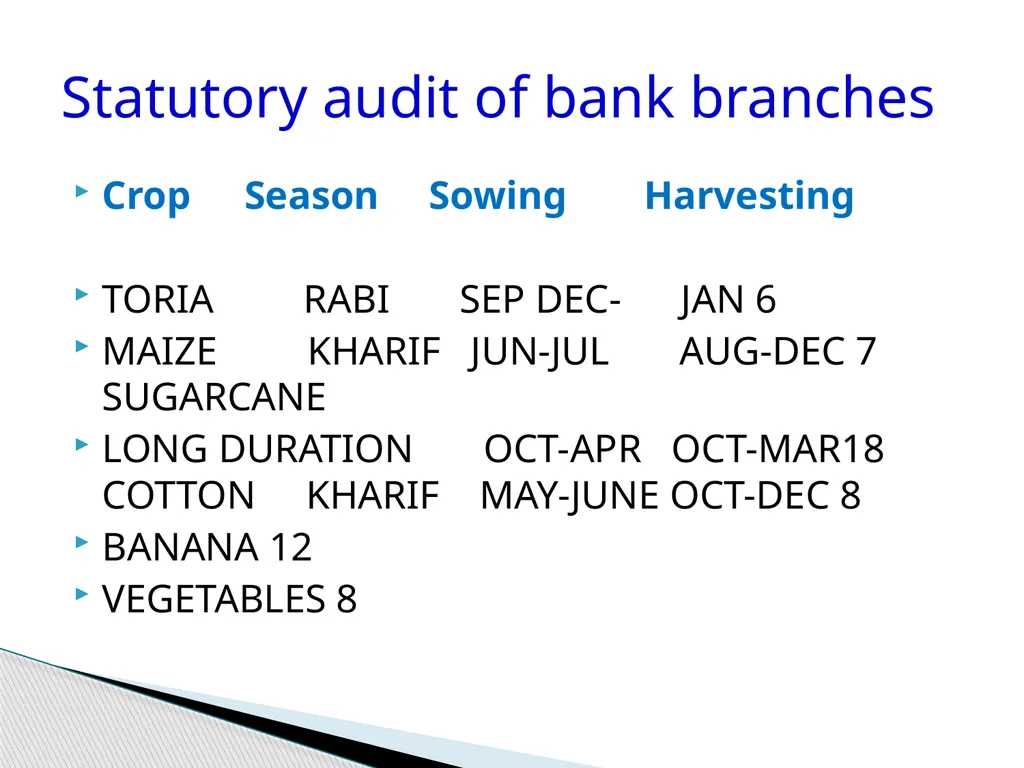
slide44. Crop Season Sowing Harvesting
TORIA RABI SEP DEC- JAN 6
MAIZE KHARIF JUN-JUL AUG-DEC 7 SUGARCANE
LONG DURATION OCT-APR OCT-MAR18 COTTON KHARIF MAY-JUNE OCT-DEC 8
BANANA 12
VEGETABLES 8 Statutory audit of bank branches<br>
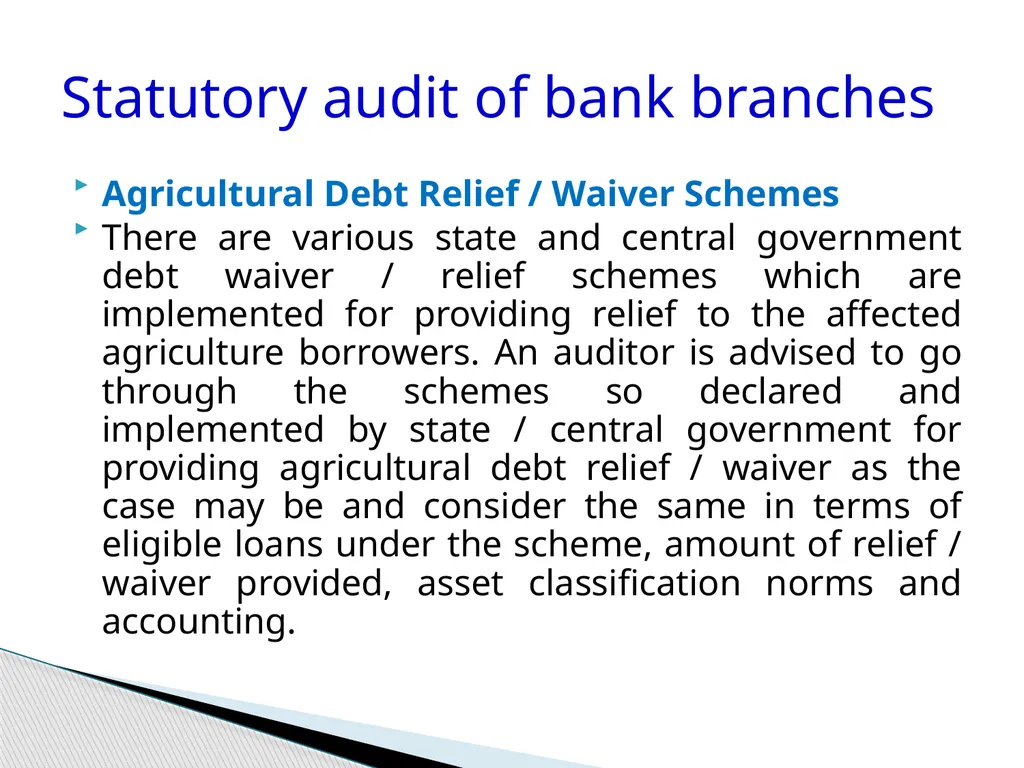
slide45. Agricultural Debt Relief / Waiver Schemes
There are various state and central government debt waiver / relief schemes which are implemented for providing relief to the affected agriculture borrowers. An auditor is advised to go through the schemes so declared and implemented by state / central government for providing agricultural debt relief / waiver as the case may be and consider the same in terms of eligible loans under the scheme, amount of relief / waiver provided, asset classification norms and accounting. Statutory audit of bank branches<br>
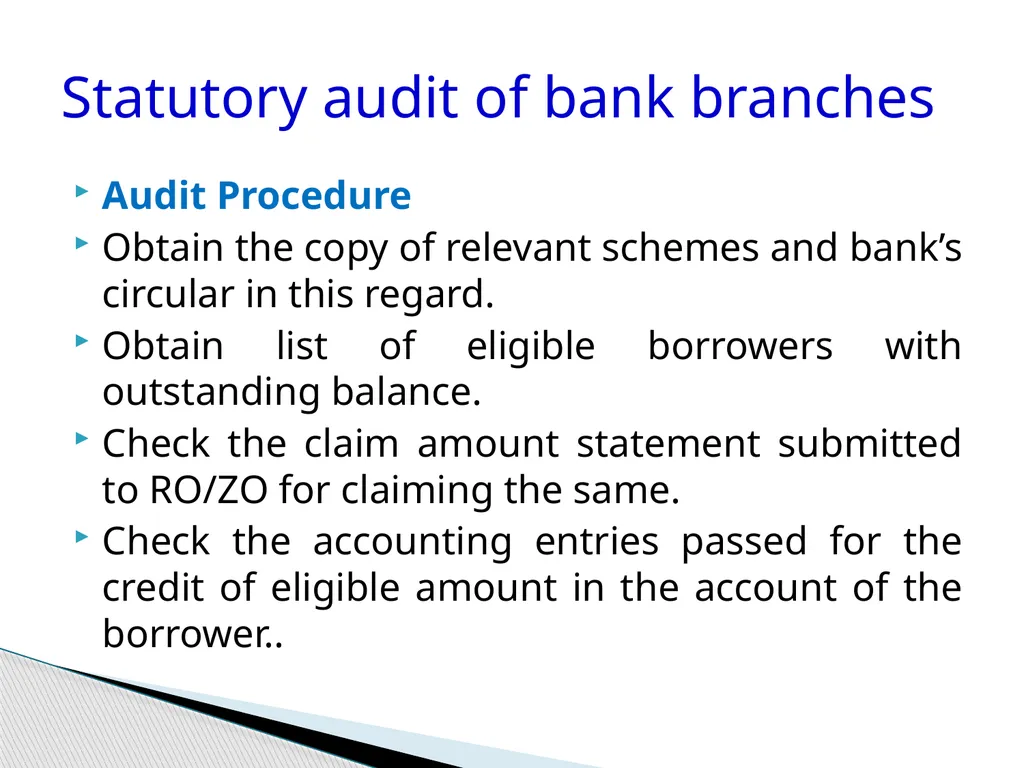
slide46. Audit Procedure
Obtain the copy of relevant schemes and bank’s circular in this regard.
Obtain list of eligible borrowers with outstanding balance.
Check the claim amount statement submitted to RO/ZO for claiming the same.
Check the accounting entries passed for the credit of eligible amount in the account of the borrower.. Statutory audit of bank branches<br>
slide47. Verify the accounting of interest and other charges to be borne by the landing institution as per the scheme
Ensure reporting requirement as per closing instructions of the bank.
Obtain written representation from the management about the scheme and its applicability including cutoff amount and period of loan disbursed Statutory audit of bank branches<br>
slide48. Verification:
a) Visits
b) Verification of history of borrower and guarantors
c) How to read 7/12 extract and 8A extract
d) Inspection reports
e) Compliance of terms and sanction
d) Operation of account with special reference to payments and receipts Statutory audit of bank branches<br>
slide49. What is 7/12 Extract:
The 7/12 extract is named after the two forms that are used to collect the information for the extract: Village
Form VII where it records the entire details of owner and owner rights.
Village Form XII which records the agricultural aspects of the land Statutory audit of bank branches<br>
slide50. What extract 12 means?
Record of Land Rights
The7/12 document or 'Record of Land Rights' is used for looking up the ownership of ancestral land in a village.
This also helps in checking for any past disputes or any litigation orders passed affecting the land. Statutory audit of bank branches<br>
slide51. What is 8A document?
8A is a Record of land ownership or your land is recorded in government record along with details such as Village, Taluka, District, Account Number, Total area of land. 8 A certificate is required with 7/12 certificate for various applications in government sector or private. Statutory audit of bank branches<br>
slide52. How To Read 7/12 extract: (Illustrative)
1)Gaav: (गाव) Village name where the land is located
2) Tahsil: (तहशील)Sub-division of the district
3) Bhumapan Kramank: (भू-मापन क्रमांक) Survey number as provided by the revenue authorities of the state under Rule 3 of Maharashtra Land Revenue Rules, 1969
4)Bhumapan Kramankancha Upbhivaag: (भू-मापन क्रमांकाचा उपविभाग) Sub-division of survey number
5. Hissa:: (हिस्सा किंवा पोट हिस्सा) It deals with portion in percentage of land owning Statutory audit of bank branches<br>
slide53. 6) Bhudharana Paddhiti: (भू-धारणा पद्धती) This denotes the type of occupancy (भोगवटाधारकाची मालकी) It is an important column to be taken note of. There are two types of occupants-
Class 1 and
Class 2.
Occupant Class 1 is of owners who own the land through ancestral rights or purchase and hence can transfer the agricultural land without the collector's approval. Statutory audit of bank branches<br>
slide54. Occupant Class 2 are the lands given by government to small and marginal farmers or landless laborers or farmers
This category also includes those lands which have been given by government to farmers, tenants or others who have purchased the land under Bombay Tenancy Act, 1948 or has been assigned by government on such terms and conditions or duration or for a specific purpose as may have decided. Statutory audit of bank branches<br>
slide55. Violation of these terms and conditions may result into withdrawing land so given by government.
The lands falling in the category of ‘Inam’ or ‘vatan’ fall in this category.
Such owners cannot transfer the land by way of sale, exchange, rent out, mortgage, gift, donate, lease, without the permission of the collector Statutory audit of bank branches<br>
slide56. 7) Bhogvatacharache Naav: (भोगवटाधारकाचे नाव) Name of the occupant.
8) Khate Kramank (खाते क्रमांक)– This is an account number from Khate Pustika issued under MLR. Every landowner is provided with an account number which states the amount of tax the owner has to pay. Updated every generally 10 years
9) Kulanche Naav –(कुळाचे नाव) Name of the tenant and their class- contractual tenant or deemed tenant Statutory audit of bank branches<br>
slide57. 10) Shetache Sthanik Naav- (शेताचे स्थानिक नाव) Farmers give names to their field considering its shape or location. For eg. Khachar (खाचर) or valukhaach (वाळू खाच) etc
11) Lagvadi Yogaya Kshetra – (लागवडीयोग्य क्षेत्र)Total area fit for cultivation. Whether it is Jirayati, bagayati, Rice paddy is specified. The area is specified in Hectors and Aars or Acres and Gunthas
12. Pad : (पड) No cultivation in the land
13. Peek : (पीक पाणी) Crop details. Statutory audit of bank branches<br>
slide58. 14). ( ) When the name goes in bracket, either the person is not owner or dead or otherwise has disposed of the land. When the land is transferred, a bracket has been put on the name of the previous owner and new name has been inserted, who will be regarded as present owner. Some times there is an entry in circle with number next to the name of land owner, which is called as Ferfaar “फेरफार’ which gives detailed information about the change.
Some times there are pencil entries, which are considered as changes of temporary nature. Statutory audit of bank branches<br>
slide59. 15)Potkharabaa:(पो. ख.)Uncultivable portion of land
This is elaborated by explaing how much portion of the uncultivable land is uncultivaable or barren
Part A talks about शेतातील बांध/नाले/खाणी which means space occupied for water storage/stoppage, canal water route within land, occupied by stone or other quarries, if any
Part B talks about space occupied by roads, lake, shet taale (शेत-तळे), canal routes or reservation for any other work, which makes the land uncultivable. Statutory audit of bank branches<br>
slide60. Just below पो.ख. or पोट खराबा the word Akaar ( आकार) is specified that denotes the amount of land cess which is written in rupees.
To the right of Form 7, account no of the said land with the name of the possessor (कुळ वहिवाटदार) is written. If it is given by way of a rent, name of the tenant (कुळ) is also written along with amount of rent payable by tenant Statutory audit of bank branches<br>
slide61. Other rights
The names of the persons whose interest in the said land is specified. This includes amount of loan raised or charge created on this property and information about the fact as to whether loan has been repaid or not.
Some times the entire land is not bought by purchase but a fragment is purchased out of such land. Such portion of land is called as fragment or तुकडा Statutory audit of bank branches<br>
slide62. If it has been written on the form as fragmentation not allowed i.e. 'तुकडेबंदी‘, and if such land is agriculture land then the same is not allowed to be sold out by fragmenting the land into pieces or no one can buy such land in fragmented form under Fragmentation act.
If the land is acquired for Roads, dams etc by the government and to rehabilitate the farmers affected by such acquisition, certain lands are reserved for rehabiltation purposes Statutory audit of bank branches<br>
slide63. ('पुनर्वसनासाठी संपादित‘) and is remarked accordingly. If such remark is there on the form, such land can not be transferred.
If certificate under section 32M has not been ensured or certificate under section 32M has been ensured but ten years have not elapsed from the date of such certificate, such land if marked with a restrictive remark under section 43 of that nature, then such land can not be transferred Statutory audit of bank branches<br>
slide64. If restriction is stipulated on land under Section 84 of the tenancy law, and such agriculture land is used for agriculture purpose, then such land can be purchased only and only by Farmer or agriculturist and not by others, If the purchaser is not a farmer, permission from collector is required. Statutory audit of bank branches<br>
slide65. What are mortgage loans ?
Section 58 (a) of the TRANSFER OF PROPERTY ACT, 1882, defines mortgage as, “A mortgage is the transfer of an interest in specific immovable property for the purpose of securing the payment of money advanced or to be advanced by way of loan, an existing or future debt, or the performance of an engagement which may give rise to a pecuniary liability.
“The bold blue font letters signifies the essential elements for the creation of valid mortgage in favor of the lender over the immoveable property. Statutory audit of bank branches<br>
slide66. 1.Simple Mortgage: It has following characteristics:-
i) That the mortgagor must have bound himself personally to repay the loan
ii) That to secure the loan he has transferred to the mortgagee the right to have the specific immovable property sold in the event of his having failed to repay
iii) That the possession of the property is not delivered to the lender Statutory audit of bank branches<br>
slide67. 2. Mortgage by Conditional Sale:
It’s defined as a situation, where the mortgagor ostensibly sells the mortgaged property –
i) on the condition that on default of payment of the mortgage money (loan) on a certain date the sale shall become absolute or
ii) on condition that on such payment being made the sale shall become void or,
iii) on the condition that in such payment being made the buyer shall transfer the property to the seller, Statutory audit of bank branches<br>
slide68. PROVIDED that no such transaction shall be deemed to be a mortgage, unless the condition is embodied in the document which affects or purports to affect the sale
This kind of mortgage came into vogue in India during Muslim rule and was given legal recognition in the Bengal Regulation Act, 1978 Statutory audit of bank branches<br>
slide69. 3.Unsufructuary Mortgage: It has following characteristics:-
i) That the possession of the property is delivered to the mortgagee;
ii) That the mortgagee is to get rents and profits in lieu of the interest or principal or both;
iii) That no personal liability is incurred by the mortgagor and
iv) The mortgagee cannot foreclose or sue for sale
v) That no time limit can be fixed expressly during which the mortgage is to subsist. This is not prevalent in India Statutory audit of bank branches<br>
slide70. 4. English Mortgage: It has below characteristics:-
i) That the mortgagor should bind himself to repay the mortgage money/loan on a certain day;
ii) That the mortgaged property should be transferred absolutely to the mortgagee ; and
iii) That such absolute transfer should be made subject to a proviso that the mortgagee will recover the property to the mortgagor, upon the payment by him of the mortgage money on the appointed day
The difference between the mortgage by conditional sale and English mortgage is that in English mortgage, the mortgagor binds him personally to repay the money Statutory audit of bank branches<br>
slide71. 5. Mortgage by Deposit of Title Deeds:
In England and popularly in India, this mortgage is called the equitable mortgage. Under the definition under Section 58 (f) of Transfer of Property Act, 1882, the essential requisites of such mortgage are:
i) a debt should be there ii) deposit of the title deed with the lender (most essential) iii) said deposit is with intention that the said title deed shall be security for the debt. Statutory audit of bank branches<br>
slide72. 6. Anamolous Mortgage:
A mortgage which is not a simple mortgage, a mortgage by conditional sale, an usufructuary, an English mortgage or a mortgage by deposit of title deeds within the meaning of Section 58 of Transfer of Property Act is an Anomalous mortgage. Statutory audit of bank branches<br>
slide73. Section 96 of the Transfer of Property Act, 1882 places mortgages by deposit of title deeds on the same footings as simple mortgages.
As such, the security can, like a simple mortgage can be enforced by a suit for sale of mortgaged property, of course, by the process of the law.
And this kind of mortgage does not require registration and is at par with any other legal mortgage. Statutory audit of bank branches<br>
slide74. Limitation
Mortgage enforceable only up to 12 years
Mortgage of land mortgage and development banks is enforeceable up to 30 years
Adverse possession 12 years for general category and 30 years for government lands
SARFESI law not applicable to farmers and agriculture lands Statutory audit of bank branches<br>
slide75. Interest subvention:
From 2006-07 the Government had decided to ensure that farmers receive short term credit at 7% with an upper limit of Rs. 3.00 lakh on the principal amount. The policy came into force with effect from Kharif 2006-07.
The amount of subvention was to be calculated on the amount of crop loan from the date of disbursement up to the actual date of repayment of the crop loan by the farmer or up to the due date of the loan fixed by the banks, whichever is earlier, subject to a maximum period of one year. Statutory audit of bank branches<br>
slide76. Interest subvention is offered by NABARD and RBI
The rate is 2% uniform till 2019-20 except FY 2010-11 it was reduced to 1.5%.
Further, GOI has reduced the interest subvention from 2% to 1.5%, availed on short term loans for FY 2022-23 and 2023-24.
Difference between Subsidy and subvention
Subsidy is the "English" word. Subvention is a word used in Latin languages such as French and Spanish, that has "crossed over" into (uncommon) English usage Statutory audit of bank branches<br>
slide77. Subvention refers to a grant of money in aid or support, mostly by the government. Subsidy is a transfer of money from the government to an entity.
The subvention scheme is different from a subsidy and does not offer anything free.
In a subsidy, the government gives grants in order to boost production and consumption and pays a part of the cost of production of any goods or services. Meanwhile, in subvention schemes, the government offers relief in the loan burden of the buyer. Statutory audit of bank branches<br>
slide78. Relief to farmers
To provide relief to farmers affected by natural calamities, Interest Subvention of 2% (Now 1.5% for 2022-23 and 2023-24) has been made available to banks for the first year on restructured amount of crop loans. Such restructured loans will attract normal rate of interest from the second year onwards as per the policy laid down by the RBI. Statutory audit of bank branches<br>
slide79. Interest Subvention to Small and Marginal Farmers against Negotiable Warehouse Receipts
The benefit of 2% interest subvention will be available to banks on their own funds involved for extending credit support up to Rs 3.00 lakh at 7% interest per annum to Small and Marginal farmers (SF/MF) having Kisan Credit Card for a further period of up to six months post the harvest of the crop against Negotiable Warehouse Receipts issued on the produce stored in warehouses accredited with Warehousing Development Regulatory Authority. SF/MF, who have not availed crop loans through banking system, would not be eligible. Statutory audit of bank branches<br>
slide80. Interest subvention on working capital to Animal Husbandry and Fisheries
GoI has extended the Interest subvention Scheme on KCC issued to crop loan farmers to the KCC issued to Animal Husbandry and Fisheries farmers from 2018-19.
Interest subvention of 2% to banks and 3% to farmers towards Prompt Repayment incentive is extended on short term loans up to Rs. 2 lakh to animal husbandry and fisheries farmers apart from the existing KCC for crop loans, provided the loans are extended by banks @7% per annum. Statutory audit of bank branches<br>
slide81. In case of farmers possessing KCC for raising crops and involved in activities related to Animal Husbandry and/ or Fisheries, the Interest Subvention on short term loan is available on an overall limit of Rs.3 lakh per annum.
Incentive to farmers on prompt repayments
Since the year 2009-10, Government of India introduced additional incentive for farmers who promptly repay the loans on or before the due date or the date fixed by the bank, subject to a maximum period of one year.
Year-wise rate of incentive to prompt-paying farmers was 3% Statutory audit of bank branches<br>
slide82. Withdrawal of Interest subvention on other than KCC accounts
Govt. of India has issued instruction that Interest Subvention to Banks and Prompt Repayment Incentive to farmers will be available only against KCCs from 01.04.2020.
In view of the lockdown to combat the coronavirus pandemic, the government has decided to continue the facility of interest subvention of 2 per cent and prompt repayment incentive of 3 per cent to farmers till August 31, 2020 Statutory audit of bank branches<br>
slide83. Kisan Credit Card Scheme
The Kisan Credit Card is a scheme launched by the Indian banks back in 1998, as a way to fulfill the financial necessities of the agricultural sector. This is done by giving monetary support to farmers, which in turn comes with various features and benefits. The quantum of the loan depends on several factors like cost of cultivation, farm maintenance cost, etc Statutory audit of bank branches<br>
slide84. This has been particularly beneficial for those farmers who are not aware of the banking practices. Moreover, it is meant to protect farmers from harsh and informal creditors, which may land them in a massive debt. The farmers can use the KCC card to withdraw funds for the purpose of crop production and domestic requirements. Statutory audit of bank branches<br>
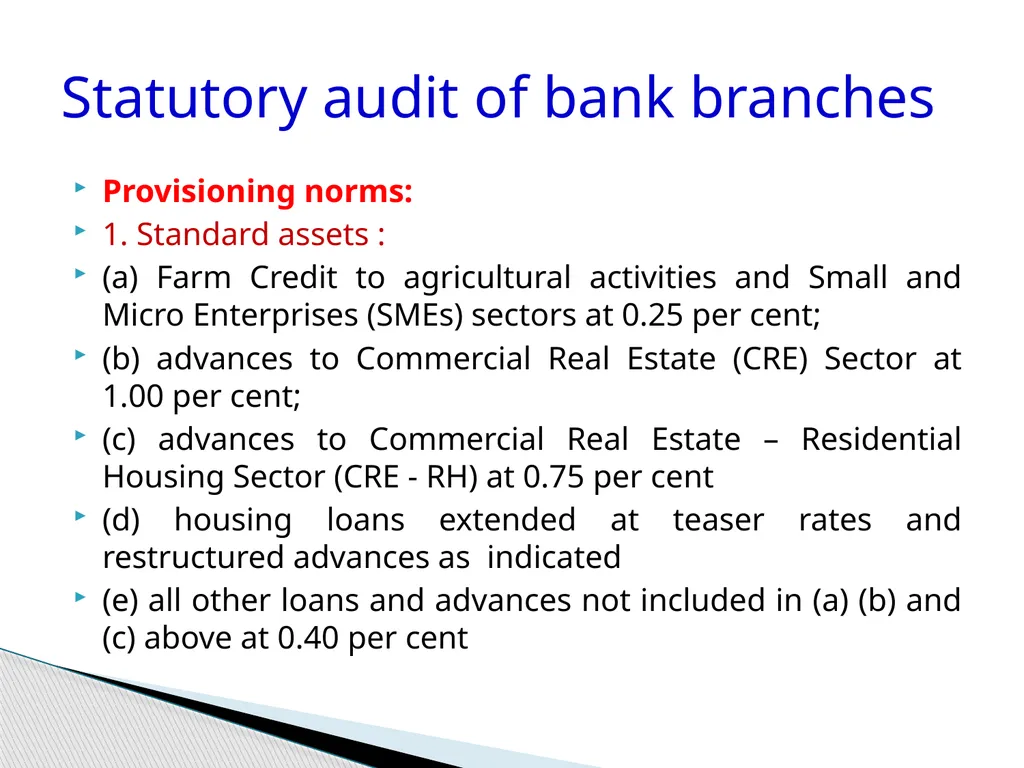
slide85. Provisioning norms:
1. Standard assets :
(a) Farm Credit to agricultural activities and Small and Micro Enterprises (SMEs) sectors at 0.25 per cent;
(b) advances to Commercial Real Estate (CRE) Sector at 1.00 per cent;
(c) advances to Commercial Real Estate – Residential Housing Sector (CRE - RH) at 0.75 per cent
(d) housing loans extended at teaser rates and restructured advances as indicated
(e) all other loans and advances not included in (a) (b) and (c) above at 0.40 per cent Statutory audit of bank branches<br>
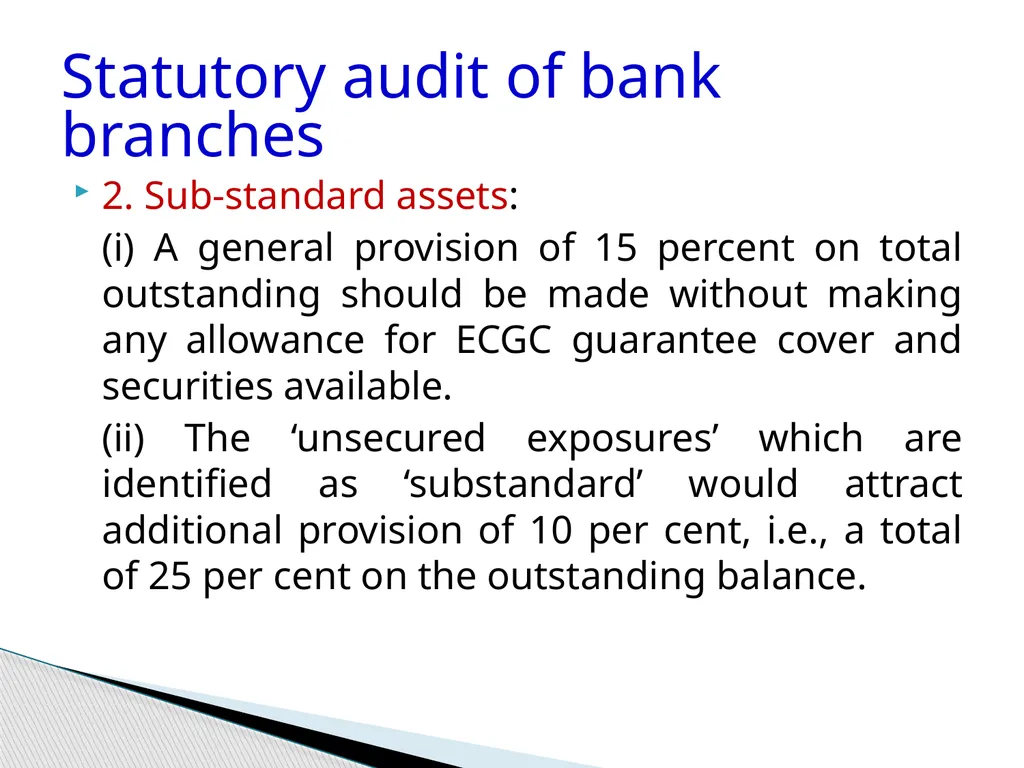
slide86. 2. Sub-standard assets:
(i) A general provision of 15 percent on total outstanding should be made without making any allowance for ECGC guarantee cover and securities available.
(ii) The ‘unsecured exposures’ which are identified as ‘substandard’ would attract additional provision of 10 per cent, i.e., a total of 25 per cent on the outstanding balance. Statutory audit of bank branches<br>
slide87. 3. Doubtful assets :In regard to the secured portion, provision may be made on the following basis, at the rates ranging from 25 percent to 100 percent of the secured portion depending upon the period for which the asset has remained doubtful:
Up-to one year : 25%
One to three years : 40%
More than three years : 100%
100 percent of the extent to which the advance is not covered by the realisable value of the security to which the bank has a valid recourse and the realisable value is estimated on a realistic basis Statutory audit of bank branches<br>
slide88. (4) Loss assets
Loss assets should be written off. If loss assets are permitted to remain in the books for any reason, 100 percent of the outstanding should be provided for.
Full 100% provision is required irrespective secured portion, needs to be noted down.
Provisioning stated above is a standard procedure. However, auditor can recommend provision as he deems fit. Statutory audit of bank branches<br>
slide89. ‘Out of Order’ status
An account should be treated as 'out of order' if the outstanding balance remains continuously in excess of the sanctioned limit/drawing power. In cases where the outstanding balance in the principal operating account is less than the sanctioned limit/drawing power, but there are no credits continuously for 90 days as on the date of Statutory audit of bank branches<br>
slide90. Balance Sheet or credits are not enough to cover the interest debited during the same period, these accounts should be treated as 'out of order'.
‘Overdue’
Any amount due to the bank under any credit facility is ‘overdue’ if it is not paid on the due date fixed by the bank. Statutory audit of bank branches<br>
slide91. NPA Rules
In terms of paragraph No. 4.2.12 of the Master Circular DBOD.No.BP.BC.15/ 21.04.048/ 2002-03 dated August 22, 2003 relating to income recognition, asset classification and provisioning, all direct agricultural advances as listed in the Annexure II to the circular would become NPA, when interest and / or installment of principal remains unpaid after it has become due for two harvest seasons, not exceeding two half years. Statutory audit of bank branches<br>
slide92. In the case of long duration crops, the current prescription of 'not exceeding two half-years' is inadequate. In order to align the repayment dates with harvesting of crops, it has been decided that with effect from September 30, 2004 the following revised norms will be applicable to all direct agricultural advances as listed in the circular Statutory audit of bank branches<br>
slide93. Non Performing Assets
Short duration crops: Loan (principal or interest) remaining outstanding for more than two crop seasons
Long duration crops: Loan (principal or interest) remaining outstanding for more than one crop season
Supreme court Intervention:
Supreme Court has stayed the declaration of NPA accounts by banks due to Covid 19 pandemic in Gajendrasing Sharma vs Union of India . Statutory audit of bank branches<br>
slide94. The honourable Supreme Court has passed an interim order on September 03, 2020 w.r.t. writ petition 825/2020 as ‘the accounts which were not declared NPA till 31.08.2020 shall not be declared NPA till further orders’. The RBI has not issued any notification / circular related to the said interim order. Statutory audit of bank branches<br>
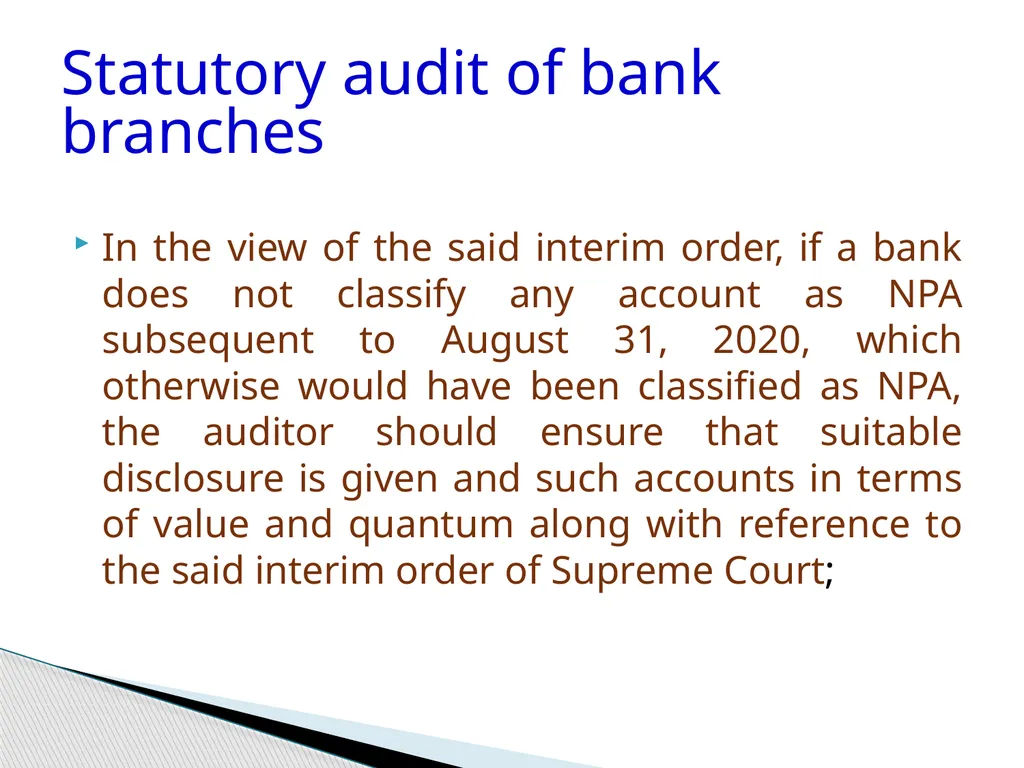
slide95. In the view of the said interim order, if a bank does not classify any account as NPA subsequent to August 31, 2020, which otherwise would have been classified as NPA, the auditor should ensure that suitable disclosure is given and such accounts in terms of value and quantum along with reference to the said interim order of Supreme Court; Statutory audit of bank branches<br>
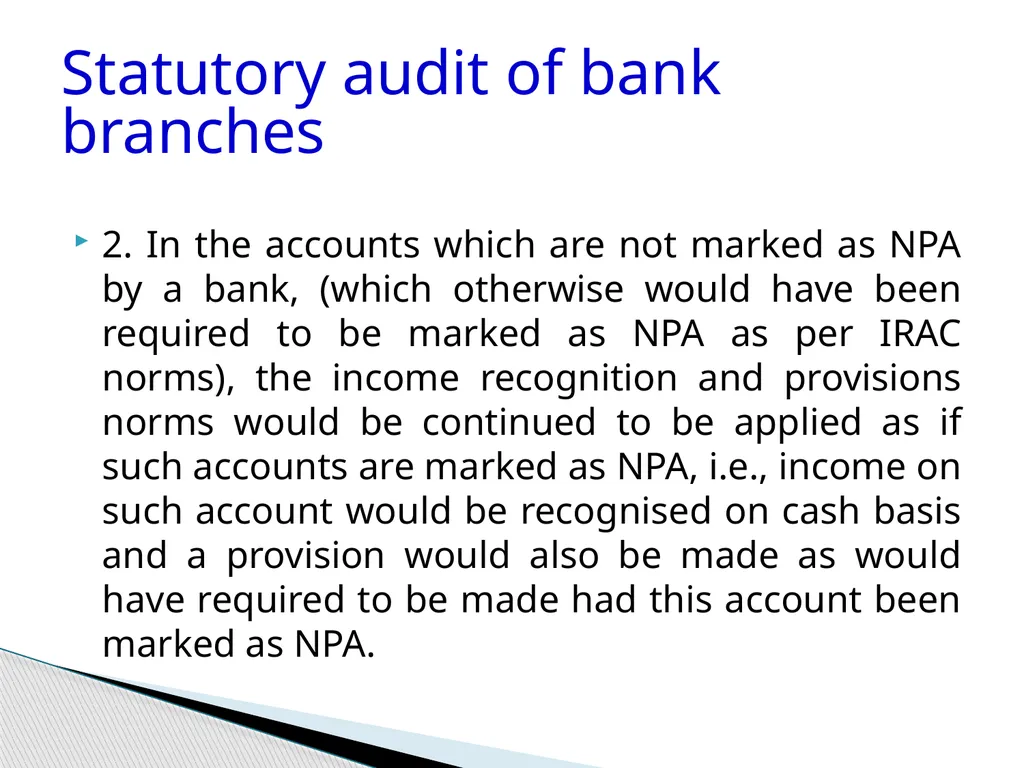
slide96. 2. In the accounts which are not marked as NPA by a bank, (which otherwise would have been required to be marked as NPA as per IRAC norms), the income recognition and provisions norms would be continued to be applied as if such accounts are marked as NPA, i.e., income on such account would be recognised on cash basis and a provision would also be made as would have required to be made had this account been marked as NPA. Statutory audit of bank branches<br>
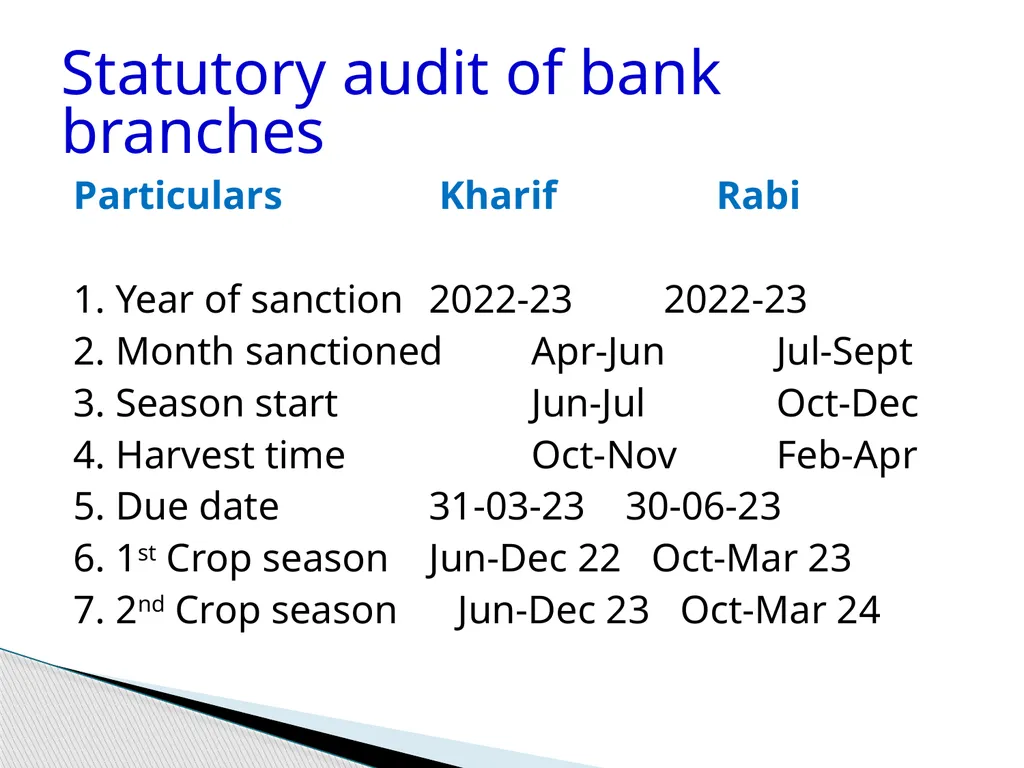
slide97. Particulars Kharif Rabi
1. Year of sanction 2022-23 2022-23
2. Month sanctioned Apr-Jun Jul-Sept
3. Season start Jun-Jul Oct-Dec
4. Harvest time Oct-Nov Feb-Apr
5. Due date 31-03-23 30-06-23
6. 1st Crop season Jun-Dec 22 Oct-Mar 23
7. 2nd Crop season Jun-Dec 23 Oct-Mar 24 Statutory audit of bank branches<br>
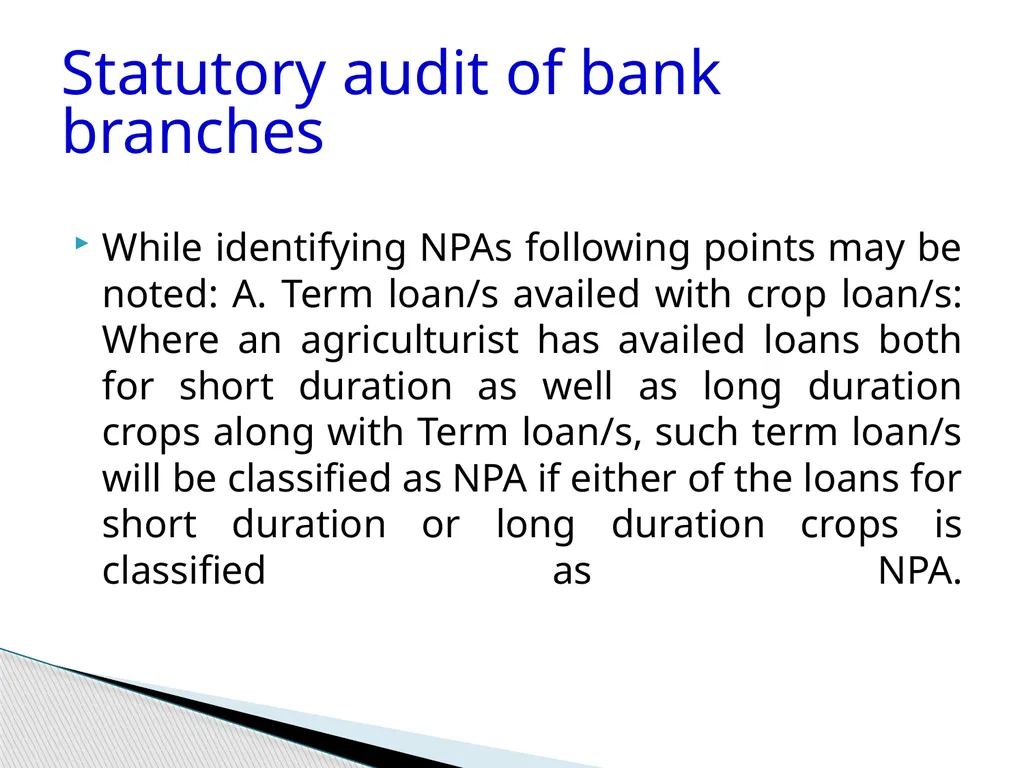
slide98. While identifying NPAs following points may be noted: A. Term loan/s availed with crop loan/s: Where an agriculturist has availed loans both for short duration as well as long duration crops along with Term loan/s, such term loan/s will be classified as NPA if either of the loans for short duration or long duration crops is classified as NPA. Statutory audit of bank branches<br>
slide99. Example 1:
An agriculturist avails following loans Crop loan for kharif crop (a short duration crop) is availed on 1.6.2022 for which repayment due date prescribed is 31.03.2023.
Crop loan for Adsali sugarcane (a long duration crop) is availed on 1.7.2022 for which repayment due date prescribed is 30.06.2025.
A term loan for deepening of well is availed on 01.05.2022 for which first repayment instalment is due on 30.06.2025 Statutory audit of bank branches<br>
slide100. If crop loan for Kharif crop remains overdue up to 31.12.2024 (i.e. overdue for 21 months after repayment due date of 31.03.2023) this crop loan along with the crop loan for sugarcane and term loan for deepening of well, will be classified as NPA with effect from 31.12.2024.
Example 2: In the example 1 referred to above, if only term loan is availed without availing crop loan for kharif crop & sugarcane, which are actually grown by Statutory audit of bank branches<br>
slide101. the borrower, overdue period will be identified as 21 months for kharif crop and 18 months for sugarcane crop.
The term loan will become NPA if its instalment of principal or interest remains overdue for 18 months from repayment due date i.e., from 30.06.2023 (overdue period applicable will be the lower of 18 or 21 months as applicable for crops grown by the borrower). Thus the loan for deepening of well will become NPA on 31.12.2024. Statutory audit of bank branches<br>
slide102. Restructuring of loans
In case of Natural calamities, the banks may decide their own relief measures like conversion of short term facility into a term loan or re-schedulement of repayment period. In all these cases, the account is not treated as NPA.
Covid 19 loans with Central Government guarantee have been sanctioned or old loans have been restructured. Such loans will be PA. Statutory audit of bank branches<br>
slide103. Statutory audit of bank branches Statutory audit of bank branches<br>
slide104. COVID19 Regulatory Package
The RBI issued COVID19 Regulatory package vide circular RBI/2019-20/186 DOR.No.BP. BC. 47/ 21.04.048/2019-20 dated March 27, 2020 granting relief to borrowers, which was further followed by another circular RBI/2019-20/220 DOR.No.BP. BC. 63/21.04.048/2019-20 dated April 17, 2020 on COVID 19 Regulatory Package – Asset Classification and Provisioning, granting relief w.r.t. Asset Classification and Provisioning. Statutory audit of bank branches<br>
slide105. The RBI also issued circular RBI/2019-20/219 DOR.No.BP. BC.62/21.04.048/2019-20 dated April 17, 2020 on COVID 19 Regulatory Package – Review of Resolution Timelines under the Prudential Framework on Resolution of Stressed Assets. Statutory audit of bank branches<br>
slide106. Government guaranteed advances
The credit facilities backed by guarantee of the Central Government though overdue may be treated as NPA only when the Government repudiates its guarantee when invoked. Statutory audit of bank branches<br>
slide107. Resolution Framework for COVID19 related Stress
The RBI issued circular RBI/2020-21/16 DOR.No.BP. BC/3/ 21.04.048/2020-21 dated August 06, 2020 providing window under Prudential Framework to enable lenders to implement a resolution plan in respect of eligible corporate exposures without change in ownership and personal loans, while classifying such exposures as Standard, subject to certain conditions, enabling to retain the class of assets. Statutory audit of bank branches<br>
slide108. LFAR
Previously, the accounts selected for the purpose of auditing were forming part of our documentations and working papers. However, now LFAR expects us to list the accounts selected, which increase our responsibility manifold as the answers to the question in LFAR are expected with reference to the selection. Statutory audit of bank branches<br>
slide109. Where any of the comments made by the auditors in their LFAR is adverse, auditor should consider whether a qualification in their main report is necessary.
Format of LFAR speaks about policies of the bank are in conformity with RBI master directions Statutory audit of bank branches<br>
slide110. Limits prescribed for bank loans to Micro, Small and Medium Enterprises engaged in the manufacture or production of goods:
The manufacturing enterprises are defined in terms of investment in plant and machinery under MSME Act, 2006.
Bank loans up to Rs. 5 crore per unit to Micro and Small Enterprises and Rs. 10 crore to Medium Enterprises engaged in providing or rendering of services and defined in terms of investment in equipment under MSME Act, 2006 are eligible for classification under priority sector. Statutory audit of bank branches<br>
slide111. MSMEs:
Definition of Micro, small, medium enterprises as per Section 7(1) of Micro, small, medium enterprises Development act 2006. Definition effective from 1-7-2020
Manufacturing or service Enterprises :
Micro enterprises – Investment in plant & machinery or equipments does not exceed Rs 1 crore and turnover does not exceed Rs 5 crores irrespective of the location Statutory audit of bank branches<br>
slide112. Small enterprises – Investment in plant & machinery or equipments does not exceed Rs 10 crores and turnover does not exceed Rs 50 crores irrespective of the location
Medium Enterprises:
Investment in plant & machinery or equipments does not exceed Rs 50 crore and turnover does not exceed Rs 250 crores irrespective of the location Statutory audit of bank branches<br>
slide113. Notes:
If the turnover or investment exceeds the parameter, the enterprise will be placed in the higher category but not vice versa.
One PAN one turnover.
Investment to be linked with figure appearing in previous ITR filed
If new entrant with no ITR filed, the value will finalised on the basis of self declaration but without GST
Plant and machinery to include all tangible assets except land, building , furniture & fittings Statutory audit of bank branches<br>
slide114. Bank loans to micro and small enterprises (both manufacturing and service) are eligible to be classified under PS (Priority sector).
The small and micro (service) enterprises include
small road & water transport operators
small business
professional & self-employed persons
Retail trade
Consultancy services Statutory audit of bank branches<br>
slide115. MSME Sector –
Restructuring of Advances The RBI issued circular RBI/2020-21/17 DOR.No.BP. BC/4/21 .04.048/2020-21 dated August 06, in continuation of earlier circular 2020RBI/2019- 20/160 DOR. No.BP. BC.34/21.04.048/2019-20 dated February 11, 2020 extending the one-time restructuring of MSME advances classified as ‘standard’ without a downgrade in the asset classification and aligning the guidelines with the Resolution Framework for COVID19 – related Stress announced for other advances, with amended conditions as specified in the said circular Statutory audit of bank branches<br>
slide116. Other Finance to MSMEs
(i) Loans up to ₹50 crore to Start-ups, as per definition of Ministry of Commerce and Industry, Govt. of India that confirm to the definition of MSME.
(ii) Loans to entities involved in assisting the decentralized sector in the supply of inputs and marketing of output of artisans, village and cottage industries. Statutory audit of bank branches<br>
slide117. (iii) Loans to co-operatives of producers in the decentralized sector viz. artisans, village and cottage industries (Not applicable for UCBs).
(iv) Loans sanctioned by banks to NBFC-MFIs and other MFIs (Societies, Trusts etc.) which are members of RBI recognised SRO for the sector for on-lending to MSME sector
(v) Loans to registered NBFCs (other than MFIs) for on-lending to Micro & Small Enterprises Statutory audit of bank branches<br>
slide118. (vi) Credit outstanding under General Credit Cards (including Artisan Credit Card, Laghu Udyami Card, Swarojgar Credit Card and Weaver’s Card etc. in existence and catering to the non-farm entrepreneurial credit needs of individuals).
(vii) Overdraft to Pradhan Mantri Jan-Dhan Yojana (PMJDY) account holders as per limits prescribed by Department of Financial Services, MoF will qualify as achievement of the target for lending to Micro Enterprises. Statutory audit of bank branches<br>
slide119. Export Credit (not applicable to RRBs and LABs)
Export credit under agriculture and MSME sectors are allowed to be classified as PSL in the respective categories viz. agriculture and MSME. Export Credit (other than in agriculture and MSME) will be allowed to be classified as priority sector
Incremental export credit over corresponding date of the preceding year, up to 2 per cent of ANBC or CEOBE whichever is higher, subject to a sanctioned limit of up to Rs. 40 crore per borrower. Statutory audit of bank branches<br>
slide120. Export credit includes pre-shipment and post-shipment export credit (excluding off-balance sheet items) as defined in Master Circular on Rupee / Foreign Currency Export Credit and Customer Service to Exporters issued by Department of Regulation, Statutory audit of bank branches<br>
slide121. Education
Loans to individuals for educational purposes, including vocational courses, not exceeding ₹ 20 lakh will be considered as eligible for priority sector classification. Loans currently classified as priority sector will continue till maturity. Statutory audit of bank branches<br>
slide122. Housing
1.Loans to Individuals for ‘purchase/ construction’
Rs. 35 lakhs in Metropolitan centres where house value should not be more than Rs 45 lakhs
Rs. 25 lakhs in other area where house value should not be more than Rs 45 lakhs 30 lakhs
2. Loans for ‘repairs’
Rs. 10 lakhs in Metropolitan centres
Rs. 6 lakhs in others Statutory audit of bank branches<br>
slide123. Housing loans to banks’ own employees will not be eligible for classification under the priority sector.
Bank loans to any governmental agency for construction of dwelling units or for slum clearance and rehabilitation of slum dwellers subject to dwelling units with carpet area of not more than 60 sq.m.
Bank loans for affordable housing projects using at least 50% of FSI for dwelling units with carpet area of not more than 60 sq.m. Statutory audit of bank branches<br>
slide124. Statutory audit of bank branches<br>
slide125. Statutory audit of bank branches<br>
slide126. Central registry of mortgaged houses (NABARD & CIBIL)
Mortgage valid for 12 years
AOD every after three years
Frauds
If in society, recording of charge
Disbursement of subsidy Statutory audit of bank branches<br>
slide127. Social Infrastructure
Bank loans to social infrastructure sector as per limits prescribed below are eligible for priority sector classification
Bank loans up to a limit of Rs. 5 cr. per borrower for
1. setting up schools,
2. drinking water facilities Statutory audit of bank branches<br>
slide128. 3. sanitation facilities including construction / refurbishment of household toilets and water improvements at household level, etc. and
4. loans up to a limit of Rs. 10 crore per borrower for building health care facilities including under ‘Ayushman Bharat’ in Tier II to Tier VI centres. Statutory audit of bank branches<br>
slide129. Renewable Energy
Bank loans up to a limit of Rs. 30 crore to borrowers for purposes like solar based power generators, biomass-based power generators, wind mills, micro-hydel plants and for non-conventional energy based public utilities, viz., street lighting systems and remote village electrification etc., will be eligible for Priority Sector classification. For individual households, the loan limit will be Rs. 10 lakh per borrower. Statutory audit of bank branches<br>
slide130. Bank loans to HFCs, approved by NHB for their refinance, for on lending for the purpose of purchase/construction/reconstruction of individual dwelling units or for slum clearance and rehabilitation of slum dwellers, subject to a ceiling as may be specified by RBI per dwelling unit.
The all inclusive interest rate charged to the ultimate borrower should not exceed the lowest lending rate of the lending bank for HLs + 2% per annum Statutory audit of bank branches<br>
slide131. Others (eligible for priority sector classification)
Loans not exceeding Rs. 1.00 lakh per borrower provided directly by banks to individuals and individual members of SHG/JLG, provided the individual borrower’s household annual income in rural areas does not exceed Rs. 1.00 lakh and
for non-rural areas it does not exceed Rs. 1.60 lakh, and loans not exceeding Rs. 2.00 lakh provided directly by banks to SHG/JLG for activities other than agriculture or MSME, viz., loans for meeting social needs, construction or repair of house, construction of toilets or any viable common activity started by the SHGs. Statutory audit of bank branches<br>
slide132. Loans to distressed persons [other than distressed farmers indebted to non-institutional lenders] not exceeding Rs.1.00 lakh per borrower to prepay their debt to non-institutional lenders.
Loans sanctioned to State Sponsored Organisations for Scheduled Castes/ Scheduled Tribes for the specific purpose of purchase and supply of inputs and/or the marketing of the outputs of the beneficiaries of these organisations. Statutory audit of bank branches<br>
slide133. Loans up to Rs. 50 crore to Start-ups, as per definition of Ministry of Commerce and Industry, Govt. of India that are engaged in activities other than Agriculture or MSME.
Weaker Sections
Priority sector loans to the following borrowers will be considered as lending under Weaker Sections category:
1. Small and Marginal Farmers
2. Artisans, village and cottage industries where individual credit limits do not exceed Rs.1 lakh Statutory audit of bank branches<br>
slide134. 3. Beneficiaries under Government Sponsored Schemes such as National Rural Livelihood Mission (NRLM), National Urban Livelihood Mission (NULM) and Self Employment Scheme for Rehabilitation of Manual Scavengers (SRMS)
4. Scheduled Castes and Scheduled Tribes
5. Beneficiaries of Differential Rate of Interest (DRI) scheme
6. Self Help Groups Statutory audit of bank branches<br>
slide135. 7.Distressed farmers indebted to non-institutional lenders
8. Distressed persons other than farmers, with loan amount not exceeding Rs. 1 lakh per borrower to prepay their debt to non-institutional lenders
9. Individual women beneficiaries up to Rs. 1 lakh per borrower (For UCBs, existing loans to women will continue to be classified under weaker sections till their maturity/repayment.)
10. Persons with disabilities
11. Minority communities as may be notified by Government of India from time to time. Statutory audit of bank branches<br>
slide136. Thank you learned participants
Cell 9822850606 Statutory audit of bank branches<br>
Solapur Branch of WIRC of
The Institute of Chartered accountants of India, New Delhi<br>
slide2. Why priority sector ?
Focus on rural development by the government
Channel resources to areas that are deemed national priorities
Inclusion of poor in the economic growth of the country
Synchronize the bank lending account to national importance Statutory audit of bank branches<br>
slide3. Objective
Objective of priority sector lending program is to ensure adequate fund flows to some of the vulnerable sectors of the economy, which may not be attractive for the banks from the point of view of profitability. Statutory audit of bank branches<br>
slide4. Salient features of the revised guidelines
TARGET
Target for lending to total priority sector and weaker section will continue as 40 per cent and 10 per cent, respectively, of Adjusted Net Bank Credit (ANBC) or credit equivalent of off-balance sheet exposure, whichever is higher, as hitherto.
Agriculture: Distinction between direct and indirect agriculture is dispensed with. Statutory audit of bank branches<br>
slide5. 3. Bank loans to food and agro processing units will form part of Agriculture.
4. Medium Enterprises, Social Infrastructure and Renewable Energy will form part of priority sector.
5. A target of 7.5 per cent of ANBC or credit equivalent of off-balance sheet exposure, whichever is higher, has been prescribed for Micro Enterprises.
6.Education: Distinction between loans for education in India and abroad is dispensed with. Statutory audit of bank branches<br>
slide6. 7. Micro Credit ceases to be a separate category under priority sector.
8. Loan limits for housing loans qualifying under priority sector have been revised.
9. Priority Sector assessment will be monitored through quarterly and annual statements. Statutory audit of bank branches<br>
slide7. Priority Sector includes the following categories:
(i) Agriculture (ii) Micro, Small and Medium Enterprises (iii) Export Credit (iv) Education (v) Affordable Housing (vi) Social Infrastructure (vii) Renewable Energy (viii) Others Statutory audit of bank branches<br>
slide8. Total Priority Sector
40 percent of Adjusted Net Bank Credit or Credit Equivalent Amount of Off-Balance Sheet Exposure, whichever is higher.
Foreign banks with less than 20 branches have to achieve the Total Priority Sector.
RRBs and Small Finance banks should have a target of 75% each of ANBC Statutory audit of bank branches<br>
slide9. UCBs to increase their target as under:
Existing target 40%
March 31, 2021 45%
March 31, 2022 50%
March 31, 2023 60%
March 31, 2024 75% Statutory audit of bank branches<br>
slide10. Statutory audit of bank branches The percentage of Adjusted Net Bank Credit (ANBC) or Credit Equivalent Amount of Off-Balance Sheet Exposure, whichever is higher.<br>
slide11. Categories under ‘Agriculture’?
The activities covered under Agriculture are classified under three sub-categories
viz.
1.Farm credit,
2. Agriculture infrastructure and
3. Ancillary activities Statutory audit of bank branches<br>
slide12. Farm Credit - Individual farmers
Loans to individual farmers [including Self Help Groups (SHGs) or Joint Liability Groups (JLGs) i.e. groups of individual farmers, provided banks maintain disaggregated data of such loans] and Proprietorship firms of farmers, directly engaged in Agriculture and Allied Activities, viz. dairy, fishery, animal husbandry, poultry, bee-keeping and sericulture. This will include incidentals too Statutory audit of bank branches<br>
slide13. Farm Credit:
(i) Crop loans to farmers, which will include traditional/non-traditional plantations and horticulture, and, loans for allied activities. Traditional crops include:
(a) Food Crops (Wheat, Maize, Rice, Millets and Pulses etc.)
(b) Cash Crops (Sugarcane, Tobacco, Cotton, Jute and Oilseeds etc.)
(c) Plantation Crops (Coffee, Coconut, Tea, and Rubber etc.)
(d) Horticulture crops (Fruits and Vegetables)
(e) Zaid crops includes (Watermelon. Muskmelon. Cucumber. Bitter gourd. Fodder crops.) Statutory audit of bank branches<br>
slide14. Costliest crop is saffron and the present value is US $ 5000 per KG (Rs 375000)
Non-traditional crops are commonly thought of as low acreage, niche crops such as ethnic fruits and vegetables, culinary and medicinal herbs, and plants for industrial uses (e.g. fibre hemp), sunflower. .. Statutory audit of bank branches<br>
slide15. ii. Medium and long-term loans to farmers for agriculture and allied activities (e.g. purchase of agricultural implements and machinery, loans for irrigation etc.)
(iii)Loans to farmers for pre and post-harvest activities, viz., spraying, weeding, harvesting, transporting their own farm produce. Statutory audit of bank branches<br>
slide16. (iv) Loans to distressed farmers indebted to non-institutional lenders.
(v) Loans to farmers under the Kisan Credit Card Scheme.
(vi)Loans to small and marginal farmers for purchase of land for agricultural purposes.
(vii)Loans against pledge/hypothecation of agricultural produce (including warehouse receipt1) for a period not exceeding 12 months subject to a limit up to ₹50 lakh. Statutory audit of bank branches<br>
slide17. (viii) Loans to farmers for installation of stand-alone Solar Agriculture Pumps and for solarisation of grid connected Agriculture Pumps.
(ix) Loans to farmers for installation of solar power plants on barren/fallow land or in stilt fashion on agriculture land owned by farmer. Statutory audit of bank branches<br>
slide18. Agriculture infrastructure
(a) Loans for the following activities will be subject to an aggregate limit of Rs. 2 crore per borrowing entity:
(b) Loans up to Rs. 50 lakh against pledge/hypothecation of agricultural produce (including warehouse receipts) for a period not exceeding 12 months.
(c) UCBs are not permitted to lend to co- operatives of farmers Statutory audit of bank branches<br>
slide19. (d) Loans up to Rs. 5 crore per borrowing entity to Farmers Producers Organisation/ companies (FPOs) /FPCs undertaking farming with assured marketing of their produce at a pre-determined price.
Agriculture Infrastructure
Loans for agriculture infrastructure will be subject to an aggregate sanctioned limit of Rs. 100 crore per borrower from the banking system. Statutory audit of bank branches<br>
slide20. Small and Marginal Farmers (SMFs)
For the purpose of computation of achievement of the sub-target, Small and Marginal Farmers will include the following:
i. Farmers with landholding of up to 1 hectare (Marginal Farmers).
ii. Farmers with a landholding of more than 1 hectare and up to 2 hectares (Small Farmers). Statutory audit of bank branches<br>
slide21. iii. Landless agricultural labourers, tenant farmers, oral lessees and share-croppers whose share of landholding is within the limits prescribed for SMFs.
Sharecropping is a legal arrangement with regard to agricultural land in which a landowner allows a tenant to use the land in return for a share of the crops produced on that land. Statutory audit of bank branches<br>
slide22. iv. Loans to Self Help Groups (SHGs) or Joint Liability Groups (JLGs), i.e. groups of individual SMFs directly engaged in Agriculture and Allied Activities, provided banks maintain disaggregated data of such loans.
v. Loans up to Rs. 2 lakh to individuals solely engaged in Allied activities without any accompanying land holding criteria. Statutory audit of bank branches<br>
slide23. vi. Loans to FPOs/FPC of individual farmers and co-operatives of farmers directly engaged in Agriculture and Allied Activities where the land-holding share of SMFs is not less than 75 per cent, subject to loan limits prescribed time to time.
UCBs are not permitted to lend to co-operatives of farmers. Statutory audit of bank branches<br>
slide24. General Hints or approach
The audit approach for agriculture advances has to be on the similar lines as that of other advances. The following is a summary of few Key aspects in the audit of Agricultural Advances:
a. Sanctioned amount of Agriculture Loans should be as per scale of finance applicable to the land under cultivation and the crop being cultivated. Further, necessary securities should be obtained as per the guidelines framed by the bank. Statutory audit of bank branches<br>
slide25. b. Auditors should verify that the agricultural credit is extended only after obtaining ‘No dues/ No objection certificates’ from the existing credit agencies in the area of finance.
c. Disbursement of agricultural finance is required to be carried out in various ‘stages’ based on the requirements of farming activity. This needs to be ensured strictly. In some cases, the expenditure is incurred by Statutory audit of bank branches<br>
slide26. farmer from his/her own sources or from non institutional lenders and subsequently banks are requested to reimburse the same. In such cases, auditors have to carefully verify the facts from the documents/evidences available on record. Under all situations, auditors should verify that the bank holds documents evidencing the utilisation of loans for agricultural activities. Statutory audit of bank branches<br>
slide27. d. For crop loans, primary security is normally the standing crops under cultivation, as such pre and post sanction visits by the officers of bank, who are experts in Agriculture finance and adequate documentation of visit report is a key control. Statutory audit of bank branches<br>
slide28. e. While verifying the security offered for agricultural loans, it is to be confirmed that the security is legally enforceable. Standing crops and agricultural machinery and implements are secured by a hypothecation charge, while the agricultural land is secured by a mortgage charge. Auditors have to ensure that amongst others, the following has been duly taken on record by the banks: Statutory audit of bank branches<br>
slide29. 1. Copy of the land revenue extracts. 2. Land Tax Assessment and payment receipt. 3. Copy of record with sub registrar (wherever applicable) 4. Original copies of the title deeds 5. Search of title deeds and Legal opinion from the advocate on the Bank’s approved panel 6. Valuation of land from a valuer on the Bank’s approved panel. Statutory audit of bank branches<br>
slide30. f. Loans granted to farmers against the security of NSC, KVP or Fixed Deposits of Banks, which has been utilised for agricultural purposes, is allowed to be classified under the category of finance to agriculture. However, auditors should carefully verify the loan documents and other supporting documents to ensure that non-agricultural loans are not classified as Agricultural Finance. Statutory audit of bank branches<br>
slide31. g. Agricultural Advances are required to be serviced through realisation of sale proceeds to crop. Auditors should be skeptical about the nature and timing credits coming in to service the agricultural loans and ensure that they are from genuine sources.
h. Ask about the nature of produce in the area ( Rabi and Kharif or Ek Fasli or Do Fasli or Teen Fasli Land)
i. Ask about the work sheet of Branch for calculation of Loan. Statutory audit of bank branches<br>
slide32. J. Find Bank has disbursed loan in single installment or as per FASAL calculation.
K. As Audit guidance point no C above it is clear that disbursement of loan should be as per requirement but generally found Bank disburse whole amount in first installment Not as per FASAL Production, this point should be reported Statutory audit of bank branches<br>
slide33. L. Due diligence and Assessment of Requirements
(Adherence of bank’s credit policy/guidelines)
To check whether
(i) necessary due diligence (i.e. pre-inspection report, lawyer search report, report of credit information company, copy of khasra and khatauni) as per bank’s policy has been carried out; Statutory audit of bank branches<br>
slide34. (ii) credit limits (short term farm credit and term loan components) are assessed on the basis of relevant criteria as per bank’s policy, such as operational land holding, cropping pattern and current scale of finance; and
(iii) RBI guidelines on revised KCC scheme have been adhered meticulously. Statutory audit of bank branches<br>
slide35. FIDD.CO.FSD.BC.No.6/05.05.010/2018-19 July 4, 2018 RBI Master Circular –
Kisan Credit Card (KCC) Scheme and revised KCC Scheme announced by Govt. of India on December 18, 2022. Statutory audit of bank branches<br>
slide36. Disbursement and Documentation
To check whether
(i) disbursement has been made to borrower’s SB account/as per bank’s guidelines/directly to vendor;
(ii) mandatory crop insurance premium has been paid through KCC accounts; and
(iii) Necessary documentation has been duly completed and held on records such as Statutory audit of bank branches<br>
slide37. declaration from borrower for noting charge in land revenue records and mortgage of land
hypothecation of crop and mortgage of agricultural land, if required, per bank’s policy
noting of charge in land revenue records
simple registration of mortgage (SRM) of land, if mortgaged, with sub-registrar. Statutory audit of bank branches<br>
slide38. Audit Hints
:
1. In terms of RBI Circular FIDD CO. FSD BC No 13/05.05.010/2018-19 dated Feb 07, 2019, no collateral (i.e. mortgage on agricultural land) is required for agricultural loans
upto Rs 1.60 lakh. Statutory audit of bank branches<br>
slide39. 2. KCC facility has been extended to Animal
Husbandry farmers and Fisheries for working capital (FIDD. CO. FSD. BC. 12/05.05,010/2018-19 dated Feb 04 2019) updated 18
February 2022 vide RBI circular No. ‘FIDD.CO.FSD. BC.No.6/05.05.010/2022-23’ to be
added.
3. Check few account statements for potential
transfer of disbursement to intermediary
account or to close the existing NPA KCC
account, if any. Statutory audit of bank branches<br>
slide40. Kharif Crops
These crops are sown at the commencement of rainy season in June and are harvested in the autumn season in the beginning of November.
The principal products are rice, maize, cotton, jute, tobacco, groundnut, castor, seasame Statutory audit of bank branches<br>
slide41. Rabi crops
These are sown in the winter season (October November) and harvested in the beginning of summer (March, April)
The main products of the Rabi crops are wheat, barley, gram, linseed, mustard Statutory audit of bank branches<br>
slide42. Crop Season Sowing Harvesting
PADDY KHARIF JUNE-JULY OCT-NOV BAJRA KHARIF JUNE-JULY SEP-DEC 7 WHEAT RABI OCT-DEC FEB-APR 7 TUR KHARIF JUNE-JULY NOV-JAN 8 MUNG KHARIF JUNE-JULY SEP-OCT 6 SOYABEAN KHARIF JUNE-JULY OCT-NOV 6 GRAM RABI OCT-DEC FEB-APR 7 MASUR RABI SEP-NOV FEB-APR 8
PULSES RABI OCT-NOV MAR-APR 7 PEA RABI OCT-NOV MAR-APR 7 Statutory audit of bank branches<br>
slide43. Crop Season Sowing Harvesting
Ground Nut JUNE-JULY SEP-OCT 6 LINSEED RABI OCT-NOV MAR-APR 7 SESAME KHARIF JUNE-JULY OCT-NOV 6 SUNFLOWR KHARIF JUNE-AUG SEP-NOV 6 SUN FLOWER RABI OCT JAN 6
SUN FLOWER \
SUMMER/SPRING FEB APR-MAY 6 CASTOR KHARIF JUL-AUG JAN-FEB 8 MUSTARD RABI OCT FEB- MAR 6 Statutory audit of bank branches<br>
slide44. Crop Season Sowing Harvesting
TORIA RABI SEP DEC- JAN 6
MAIZE KHARIF JUN-JUL AUG-DEC 7 SUGARCANE
LONG DURATION OCT-APR OCT-MAR18 COTTON KHARIF MAY-JUNE OCT-DEC 8
BANANA 12
VEGETABLES 8 Statutory audit of bank branches<br>
slide45. Agricultural Debt Relief / Waiver Schemes
There are various state and central government debt waiver / relief schemes which are implemented for providing relief to the affected agriculture borrowers. An auditor is advised to go through the schemes so declared and implemented by state / central government for providing agricultural debt relief / waiver as the case may be and consider the same in terms of eligible loans under the scheme, amount of relief / waiver provided, asset classification norms and accounting. Statutory audit of bank branches<br>
slide46. Audit Procedure
Obtain the copy of relevant schemes and bank’s circular in this regard.
Obtain list of eligible borrowers with outstanding balance.
Check the claim amount statement submitted to RO/ZO for claiming the same.
Check the accounting entries passed for the credit of eligible amount in the account of the borrower.. Statutory audit of bank branches<br>
slide47. Verify the accounting of interest and other charges to be borne by the landing institution as per the scheme
Ensure reporting requirement as per closing instructions of the bank.
Obtain written representation from the management about the scheme and its applicability including cutoff amount and period of loan disbursed Statutory audit of bank branches<br>
slide48. Verification:
a) Visits
b) Verification of history of borrower and guarantors
c) How to read 7/12 extract and 8A extract
d) Inspection reports
e) Compliance of terms and sanction
d) Operation of account with special reference to payments and receipts Statutory audit of bank branches<br>
slide49. What is 7/12 Extract:
The 7/12 extract is named after the two forms that are used to collect the information for the extract: Village
Form VII where it records the entire details of owner and owner rights.
Village Form XII which records the agricultural aspects of the land Statutory audit of bank branches<br>
slide50. What extract 12 means?
Record of Land Rights
The7/12 document or 'Record of Land Rights' is used for looking up the ownership of ancestral land in a village.
This also helps in checking for any past disputes or any litigation orders passed affecting the land. Statutory audit of bank branches<br>
slide51. What is 8A document?
8A is a Record of land ownership or your land is recorded in government record along with details such as Village, Taluka, District, Account Number, Total area of land. 8 A certificate is required with 7/12 certificate for various applications in government sector or private. Statutory audit of bank branches<br>
slide52. How To Read 7/12 extract: (Illustrative)
1)Gaav: (गाव) Village name where the land is located
2) Tahsil: (तहशील)Sub-division of the district
3) Bhumapan Kramank: (भू-मापन क्रमांक) Survey number as provided by the revenue authorities of the state under Rule 3 of Maharashtra Land Revenue Rules, 1969
4)Bhumapan Kramankancha Upbhivaag: (भू-मापन क्रमांकाचा उपविभाग) Sub-division of survey number
5. Hissa:: (हिस्सा किंवा पोट हिस्सा) It deals with portion in percentage of land owning Statutory audit of bank branches<br>
slide53. 6) Bhudharana Paddhiti: (भू-धारणा पद्धती) This denotes the type of occupancy (भोगवटाधारकाची मालकी) It is an important column to be taken note of. There are two types of occupants-
Class 1 and
Class 2.
Occupant Class 1 is of owners who own the land through ancestral rights or purchase and hence can transfer the agricultural land without the collector's approval. Statutory audit of bank branches<br>
slide54. Occupant Class 2 are the lands given by government to small and marginal farmers or landless laborers or farmers
This category also includes those lands which have been given by government to farmers, tenants or others who have purchased the land under Bombay Tenancy Act, 1948 or has been assigned by government on such terms and conditions or duration or for a specific purpose as may have decided. Statutory audit of bank branches<br>
slide55. Violation of these terms and conditions may result into withdrawing land so given by government.
The lands falling in the category of ‘Inam’ or ‘vatan’ fall in this category.
Such owners cannot transfer the land by way of sale, exchange, rent out, mortgage, gift, donate, lease, without the permission of the collector Statutory audit of bank branches<br>
slide56. 7) Bhogvatacharache Naav: (भोगवटाधारकाचे नाव) Name of the occupant.
8) Khate Kramank (खाते क्रमांक)– This is an account number from Khate Pustika issued under MLR. Every landowner is provided with an account number which states the amount of tax the owner has to pay. Updated every generally 10 years
9) Kulanche Naav –(कुळाचे नाव) Name of the tenant and their class- contractual tenant or deemed tenant Statutory audit of bank branches<br>
slide57. 10) Shetache Sthanik Naav- (शेताचे स्थानिक नाव) Farmers give names to their field considering its shape or location. For eg. Khachar (खाचर) or valukhaach (वाळू खाच) etc
11) Lagvadi Yogaya Kshetra – (लागवडीयोग्य क्षेत्र)Total area fit for cultivation. Whether it is Jirayati, bagayati, Rice paddy is specified. The area is specified in Hectors and Aars or Acres and Gunthas
12. Pad : (पड) No cultivation in the land
13. Peek : (पीक पाणी) Crop details. Statutory audit of bank branches<br>
slide58. 14). ( ) When the name goes in bracket, either the person is not owner or dead or otherwise has disposed of the land. When the land is transferred, a bracket has been put on the name of the previous owner and new name has been inserted, who will be regarded as present owner. Some times there is an entry in circle with number next to the name of land owner, which is called as Ferfaar “फेरफार’ which gives detailed information about the change.
Some times there are pencil entries, which are considered as changes of temporary nature. Statutory audit of bank branches<br>
slide59. 15)Potkharabaa:(पो. ख.)Uncultivable portion of land
This is elaborated by explaing how much portion of the uncultivable land is uncultivaable or barren
Part A talks about शेतातील बांध/नाले/खाणी which means space occupied for water storage/stoppage, canal water route within land, occupied by stone or other quarries, if any
Part B talks about space occupied by roads, lake, shet taale (शेत-तळे), canal routes or reservation for any other work, which makes the land uncultivable. Statutory audit of bank branches<br>
slide60. Just below पो.ख. or पोट खराबा the word Akaar ( आकार) is specified that denotes the amount of land cess which is written in rupees.
To the right of Form 7, account no of the said land with the name of the possessor (कुळ वहिवाटदार) is written. If it is given by way of a rent, name of the tenant (कुळ) is also written along with amount of rent payable by tenant Statutory audit of bank branches<br>
slide61. Other rights
The names of the persons whose interest in the said land is specified. This includes amount of loan raised or charge created on this property and information about the fact as to whether loan has been repaid or not.
Some times the entire land is not bought by purchase but a fragment is purchased out of such land. Such portion of land is called as fragment or तुकडा Statutory audit of bank branches<br>
slide62. If it has been written on the form as fragmentation not allowed i.e. 'तुकडेबंदी‘, and if such land is agriculture land then the same is not allowed to be sold out by fragmenting the land into pieces or no one can buy such land in fragmented form under Fragmentation act.
If the land is acquired for Roads, dams etc by the government and to rehabilitate the farmers affected by such acquisition, certain lands are reserved for rehabiltation purposes Statutory audit of bank branches<br>
slide63. ('पुनर्वसनासाठी संपादित‘) and is remarked accordingly. If such remark is there on the form, such land can not be transferred.
If certificate under section 32M has not been ensured or certificate under section 32M has been ensured but ten years have not elapsed from the date of such certificate, such land if marked with a restrictive remark under section 43 of that nature, then such land can not be transferred Statutory audit of bank branches<br>
slide64. If restriction is stipulated on land under Section 84 of the tenancy law, and such agriculture land is used for agriculture purpose, then such land can be purchased only and only by Farmer or agriculturist and not by others, If the purchaser is not a farmer, permission from collector is required. Statutory audit of bank branches<br>
slide65. What are mortgage loans ?
Section 58 (a) of the TRANSFER OF PROPERTY ACT, 1882, defines mortgage as, “A mortgage is the transfer of an interest in specific immovable property for the purpose of securing the payment of money advanced or to be advanced by way of loan, an existing or future debt, or the performance of an engagement which may give rise to a pecuniary liability.
“The bold blue font letters signifies the essential elements for the creation of valid mortgage in favor of the lender over the immoveable property. Statutory audit of bank branches<br>
slide66. 1.Simple Mortgage: It has following characteristics:-
i) That the mortgagor must have bound himself personally to repay the loan
ii) That to secure the loan he has transferred to the mortgagee the right to have the specific immovable property sold in the event of his having failed to repay
iii) That the possession of the property is not delivered to the lender Statutory audit of bank branches<br>
slide67. 2. Mortgage by Conditional Sale:
It’s defined as a situation, where the mortgagor ostensibly sells the mortgaged property –
i) on the condition that on default of payment of the mortgage money (loan) on a certain date the sale shall become absolute or
ii) on condition that on such payment being made the sale shall become void or,
iii) on the condition that in such payment being made the buyer shall transfer the property to the seller, Statutory audit of bank branches<br>
slide68. PROVIDED that no such transaction shall be deemed to be a mortgage, unless the condition is embodied in the document which affects or purports to affect the sale
This kind of mortgage came into vogue in India during Muslim rule and was given legal recognition in the Bengal Regulation Act, 1978 Statutory audit of bank branches<br>
slide69. 3.Unsufructuary Mortgage: It has following characteristics:-
i) That the possession of the property is delivered to the mortgagee;
ii) That the mortgagee is to get rents and profits in lieu of the interest or principal or both;
iii) That no personal liability is incurred by the mortgagor and
iv) The mortgagee cannot foreclose or sue for sale
v) That no time limit can be fixed expressly during which the mortgage is to subsist. This is not prevalent in India Statutory audit of bank branches<br>
slide70. 4. English Mortgage: It has below characteristics:-
i) That the mortgagor should bind himself to repay the mortgage money/loan on a certain day;
ii) That the mortgaged property should be transferred absolutely to the mortgagee ; and
iii) That such absolute transfer should be made subject to a proviso that the mortgagee will recover the property to the mortgagor, upon the payment by him of the mortgage money on the appointed day
The difference between the mortgage by conditional sale and English mortgage is that in English mortgage, the mortgagor binds him personally to repay the money Statutory audit of bank branches<br>
slide71. 5. Mortgage by Deposit of Title Deeds:
In England and popularly in India, this mortgage is called the equitable mortgage. Under the definition under Section 58 (f) of Transfer of Property Act, 1882, the essential requisites of such mortgage are:
i) a debt should be there ii) deposit of the title deed with the lender (most essential) iii) said deposit is with intention that the said title deed shall be security for the debt. Statutory audit of bank branches<br>
slide72. 6. Anamolous Mortgage:
A mortgage which is not a simple mortgage, a mortgage by conditional sale, an usufructuary, an English mortgage or a mortgage by deposit of title deeds within the meaning of Section 58 of Transfer of Property Act is an Anomalous mortgage. Statutory audit of bank branches<br>
slide73. Section 96 of the Transfer of Property Act, 1882 places mortgages by deposit of title deeds on the same footings as simple mortgages.
As such, the security can, like a simple mortgage can be enforced by a suit for sale of mortgaged property, of course, by the process of the law.
And this kind of mortgage does not require registration and is at par with any other legal mortgage. Statutory audit of bank branches<br>
slide74. Limitation
Mortgage enforceable only up to 12 years
Mortgage of land mortgage and development banks is enforeceable up to 30 years
Adverse possession 12 years for general category and 30 years for government lands
SARFESI law not applicable to farmers and agriculture lands Statutory audit of bank branches<br>
slide75. Interest subvention:
From 2006-07 the Government had decided to ensure that farmers receive short term credit at 7% with an upper limit of Rs. 3.00 lakh on the principal amount. The policy came into force with effect from Kharif 2006-07.
The amount of subvention was to be calculated on the amount of crop loan from the date of disbursement up to the actual date of repayment of the crop loan by the farmer or up to the due date of the loan fixed by the banks, whichever is earlier, subject to a maximum period of one year. Statutory audit of bank branches<br>
slide76. Interest subvention is offered by NABARD and RBI
The rate is 2% uniform till 2019-20 except FY 2010-11 it was reduced to 1.5%.
Further, GOI has reduced the interest subvention from 2% to 1.5%, availed on short term loans for FY 2022-23 and 2023-24.
Difference between Subsidy and subvention
Subsidy is the "English" word. Subvention is a word used in Latin languages such as French and Spanish, that has "crossed over" into (uncommon) English usage Statutory audit of bank branches<br>
slide77. Subvention refers to a grant of money in aid or support, mostly by the government. Subsidy is a transfer of money from the government to an entity.
The subvention scheme is different from a subsidy and does not offer anything free.
In a subsidy, the government gives grants in order to boost production and consumption and pays a part of the cost of production of any goods or services. Meanwhile, in subvention schemes, the government offers relief in the loan burden of the buyer. Statutory audit of bank branches<br>
slide78. Relief to farmers
To provide relief to farmers affected by natural calamities, Interest Subvention of 2% (Now 1.5% for 2022-23 and 2023-24) has been made available to banks for the first year on restructured amount of crop loans. Such restructured loans will attract normal rate of interest from the second year onwards as per the policy laid down by the RBI. Statutory audit of bank branches<br>
slide79. Interest Subvention to Small and Marginal Farmers against Negotiable Warehouse Receipts
The benefit of 2% interest subvention will be available to banks on their own funds involved for extending credit support up to Rs 3.00 lakh at 7% interest per annum to Small and Marginal farmers (SF/MF) having Kisan Credit Card for a further period of up to six months post the harvest of the crop against Negotiable Warehouse Receipts issued on the produce stored in warehouses accredited with Warehousing Development Regulatory Authority. SF/MF, who have not availed crop loans through banking system, would not be eligible. Statutory audit of bank branches<br>
slide80. Interest subvention on working capital to Animal Husbandry and Fisheries
GoI has extended the Interest subvention Scheme on KCC issued to crop loan farmers to the KCC issued to Animal Husbandry and Fisheries farmers from 2018-19.
Interest subvention of 2% to banks and 3% to farmers towards Prompt Repayment incentive is extended on short term loans up to Rs. 2 lakh to animal husbandry and fisheries farmers apart from the existing KCC for crop loans, provided the loans are extended by banks @7% per annum. Statutory audit of bank branches<br>
slide81. In case of farmers possessing KCC for raising crops and involved in activities related to Animal Husbandry and/ or Fisheries, the Interest Subvention on short term loan is available on an overall limit of Rs.3 lakh per annum.
Incentive to farmers on prompt repayments
Since the year 2009-10, Government of India introduced additional incentive for farmers who promptly repay the loans on or before the due date or the date fixed by the bank, subject to a maximum period of one year.
Year-wise rate of incentive to prompt-paying farmers was 3% Statutory audit of bank branches<br>
slide82. Withdrawal of Interest subvention on other than KCC accounts
Govt. of India has issued instruction that Interest Subvention to Banks and Prompt Repayment Incentive to farmers will be available only against KCCs from 01.04.2020.
In view of the lockdown to combat the coronavirus pandemic, the government has decided to continue the facility of interest subvention of 2 per cent and prompt repayment incentive of 3 per cent to farmers till August 31, 2020 Statutory audit of bank branches<br>
slide83. Kisan Credit Card Scheme
The Kisan Credit Card is a scheme launched by the Indian banks back in 1998, as a way to fulfill the financial necessities of the agricultural sector. This is done by giving monetary support to farmers, which in turn comes with various features and benefits. The quantum of the loan depends on several factors like cost of cultivation, farm maintenance cost, etc Statutory audit of bank branches<br>
slide84. This has been particularly beneficial for those farmers who are not aware of the banking practices. Moreover, it is meant to protect farmers from harsh and informal creditors, which may land them in a massive debt. The farmers can use the KCC card to withdraw funds for the purpose of crop production and domestic requirements. Statutory audit of bank branches<br>
slide85. Provisioning norms:
1. Standard assets :
(a) Farm Credit to agricultural activities and Small and Micro Enterprises (SMEs) sectors at 0.25 per cent;
(b) advances to Commercial Real Estate (CRE) Sector at 1.00 per cent;
(c) advances to Commercial Real Estate – Residential Housing Sector (CRE - RH) at 0.75 per cent
(d) housing loans extended at teaser rates and restructured advances as indicated
(e) all other loans and advances not included in (a) (b) and (c) above at 0.40 per cent Statutory audit of bank branches<br>
slide86. 2. Sub-standard assets:
(i) A general provision of 15 percent on total outstanding should be made without making any allowance for ECGC guarantee cover and securities available.
(ii) The ‘unsecured exposures’ which are identified as ‘substandard’ would attract additional provision of 10 per cent, i.e., a total of 25 per cent on the outstanding balance. Statutory audit of bank branches<br>
slide87. 3. Doubtful assets :In regard to the secured portion, provision may be made on the following basis, at the rates ranging from 25 percent to 100 percent of the secured portion depending upon the period for which the asset has remained doubtful:
Up-to one year : 25%
One to three years : 40%
More than three years : 100%
100 percent of the extent to which the advance is not covered by the realisable value of the security to which the bank has a valid recourse and the realisable value is estimated on a realistic basis Statutory audit of bank branches<br>
slide88. (4) Loss assets
Loss assets should be written off. If loss assets are permitted to remain in the books for any reason, 100 percent of the outstanding should be provided for.
Full 100% provision is required irrespective secured portion, needs to be noted down.
Provisioning stated above is a standard procedure. However, auditor can recommend provision as he deems fit. Statutory audit of bank branches<br>
slide89. ‘Out of Order’ status
An account should be treated as 'out of order' if the outstanding balance remains continuously in excess of the sanctioned limit/drawing power. In cases where the outstanding balance in the principal operating account is less than the sanctioned limit/drawing power, but there are no credits continuously for 90 days as on the date of Statutory audit of bank branches<br>
slide90. Balance Sheet or credits are not enough to cover the interest debited during the same period, these accounts should be treated as 'out of order'.
‘Overdue’
Any amount due to the bank under any credit facility is ‘overdue’ if it is not paid on the due date fixed by the bank. Statutory audit of bank branches<br>
slide91. NPA Rules
In terms of paragraph No. 4.2.12 of the Master Circular DBOD.No.BP.BC.15/ 21.04.048/ 2002-03 dated August 22, 2003 relating to income recognition, asset classification and provisioning, all direct agricultural advances as listed in the Annexure II to the circular would become NPA, when interest and / or installment of principal remains unpaid after it has become due for two harvest seasons, not exceeding two half years. Statutory audit of bank branches<br>
slide92. In the case of long duration crops, the current prescription of 'not exceeding two half-years' is inadequate. In order to align the repayment dates with harvesting of crops, it has been decided that with effect from September 30, 2004 the following revised norms will be applicable to all direct agricultural advances as listed in the circular Statutory audit of bank branches<br>
slide93. Non Performing Assets
Short duration crops: Loan (principal or interest) remaining outstanding for more than two crop seasons
Long duration crops: Loan (principal or interest) remaining outstanding for more than one crop season
Supreme court Intervention:
Supreme Court has stayed the declaration of NPA accounts by banks due to Covid 19 pandemic in Gajendrasing Sharma vs Union of India . Statutory audit of bank branches<br>
slide94. The honourable Supreme Court has passed an interim order on September 03, 2020 w.r.t. writ petition 825/2020 as ‘the accounts which were not declared NPA till 31.08.2020 shall not be declared NPA till further orders’. The RBI has not issued any notification / circular related to the said interim order. Statutory audit of bank branches<br>
slide95. In the view of the said interim order, if a bank does not classify any account as NPA subsequent to August 31, 2020, which otherwise would have been classified as NPA, the auditor should ensure that suitable disclosure is given and such accounts in terms of value and quantum along with reference to the said interim order of Supreme Court; Statutory audit of bank branches<br>
slide96. 2. In the accounts which are not marked as NPA by a bank, (which otherwise would have been required to be marked as NPA as per IRAC norms), the income recognition and provisions norms would be continued to be applied as if such accounts are marked as NPA, i.e., income on such account would be recognised on cash basis and a provision would also be made as would have required to be made had this account been marked as NPA. Statutory audit of bank branches<br>
slide97. Particulars Kharif Rabi
1. Year of sanction 2022-23 2022-23
2. Month sanctioned Apr-Jun Jul-Sept
3. Season start Jun-Jul Oct-Dec
4. Harvest time Oct-Nov Feb-Apr
5. Due date 31-03-23 30-06-23
6. 1st Crop season Jun-Dec 22 Oct-Mar 23
7. 2nd Crop season Jun-Dec 23 Oct-Mar 24 Statutory audit of bank branches<br>
slide98. While identifying NPAs following points may be noted: A. Term loan/s availed with crop loan/s: Where an agriculturist has availed loans both for short duration as well as long duration crops along with Term loan/s, such term loan/s will be classified as NPA if either of the loans for short duration or long duration crops is classified as NPA. Statutory audit of bank branches<br>
slide99. Example 1:
An agriculturist avails following loans Crop loan for kharif crop (a short duration crop) is availed on 1.6.2022 for which repayment due date prescribed is 31.03.2023.
Crop loan for Adsali sugarcane (a long duration crop) is availed on 1.7.2022 for which repayment due date prescribed is 30.06.2025.
A term loan for deepening of well is availed on 01.05.2022 for which first repayment instalment is due on 30.06.2025 Statutory audit of bank branches<br>
slide100. If crop loan for Kharif crop remains overdue up to 31.12.2024 (i.e. overdue for 21 months after repayment due date of 31.03.2023) this crop loan along with the crop loan for sugarcane and term loan for deepening of well, will be classified as NPA with effect from 31.12.2024.
Example 2: In the example 1 referred to above, if only term loan is availed without availing crop loan for kharif crop & sugarcane, which are actually grown by Statutory audit of bank branches<br>
slide101. the borrower, overdue period will be identified as 21 months for kharif crop and 18 months for sugarcane crop.
The term loan will become NPA if its instalment of principal or interest remains overdue for 18 months from repayment due date i.e., from 30.06.2023 (overdue period applicable will be the lower of 18 or 21 months as applicable for crops grown by the borrower). Thus the loan for deepening of well will become NPA on 31.12.2024. Statutory audit of bank branches<br>
slide102. Restructuring of loans
In case of Natural calamities, the banks may decide their own relief measures like conversion of short term facility into a term loan or re-schedulement of repayment period. In all these cases, the account is not treated as NPA.
Covid 19 loans with Central Government guarantee have been sanctioned or old loans have been restructured. Such loans will be PA. Statutory audit of bank branches<br>
slide103. Statutory audit of bank branches Statutory audit of bank branches<br>
slide104. COVID19 Regulatory Package
The RBI issued COVID19 Regulatory package vide circular RBI/2019-20/186 DOR.No.BP. BC. 47/ 21.04.048/2019-20 dated March 27, 2020 granting relief to borrowers, which was further followed by another circular RBI/2019-20/220 DOR.No.BP. BC. 63/21.04.048/2019-20 dated April 17, 2020 on COVID 19 Regulatory Package – Asset Classification and Provisioning, granting relief w.r.t. Asset Classification and Provisioning. Statutory audit of bank branches<br>
slide105. The RBI also issued circular RBI/2019-20/219 DOR.No.BP. BC.62/21.04.048/2019-20 dated April 17, 2020 on COVID 19 Regulatory Package – Review of Resolution Timelines under the Prudential Framework on Resolution of Stressed Assets. Statutory audit of bank branches<br>
slide106. Government guaranteed advances
The credit facilities backed by guarantee of the Central Government though overdue may be treated as NPA only when the Government repudiates its guarantee when invoked. Statutory audit of bank branches<br>
slide107. Resolution Framework for COVID19 related Stress
The RBI issued circular RBI/2020-21/16 DOR.No.BP. BC/3/ 21.04.048/2020-21 dated August 06, 2020 providing window under Prudential Framework to enable lenders to implement a resolution plan in respect of eligible corporate exposures without change in ownership and personal loans, while classifying such exposures as Standard, subject to certain conditions, enabling to retain the class of assets. Statutory audit of bank branches<br>
slide108. LFAR
Previously, the accounts selected for the purpose of auditing were forming part of our documentations and working papers. However, now LFAR expects us to list the accounts selected, which increase our responsibility manifold as the answers to the question in LFAR are expected with reference to the selection. Statutory audit of bank branches<br>
slide109. Where any of the comments made by the auditors in their LFAR is adverse, auditor should consider whether a qualification in their main report is necessary.
Format of LFAR speaks about policies of the bank are in conformity with RBI master directions Statutory audit of bank branches<br>
slide110. Limits prescribed for bank loans to Micro, Small and Medium Enterprises engaged in the manufacture or production of goods:
The manufacturing enterprises are defined in terms of investment in plant and machinery under MSME Act, 2006.
Bank loans up to Rs. 5 crore per unit to Micro and Small Enterprises and Rs. 10 crore to Medium Enterprises engaged in providing or rendering of services and defined in terms of investment in equipment under MSME Act, 2006 are eligible for classification under priority sector. Statutory audit of bank branches<br>
slide111. MSMEs:
Definition of Micro, small, medium enterprises as per Section 7(1) of Micro, small, medium enterprises Development act 2006. Definition effective from 1-7-2020
Manufacturing or service Enterprises :
Micro enterprises – Investment in plant & machinery or equipments does not exceed Rs 1 crore and turnover does not exceed Rs 5 crores irrespective of the location Statutory audit of bank branches<br>
slide112. Small enterprises – Investment in plant & machinery or equipments does not exceed Rs 10 crores and turnover does not exceed Rs 50 crores irrespective of the location
Medium Enterprises:
Investment in plant & machinery or equipments does not exceed Rs 50 crore and turnover does not exceed Rs 250 crores irrespective of the location Statutory audit of bank branches<br>
slide113. Notes:
If the turnover or investment exceeds the parameter, the enterprise will be placed in the higher category but not vice versa.
One PAN one turnover.
Investment to be linked with figure appearing in previous ITR filed
If new entrant with no ITR filed, the value will finalised on the basis of self declaration but without GST
Plant and machinery to include all tangible assets except land, building , furniture & fittings Statutory audit of bank branches<br>
slide114. Bank loans to micro and small enterprises (both manufacturing and service) are eligible to be classified under PS (Priority sector).
The small and micro (service) enterprises include
small road & water transport operators
small business
professional & self-employed persons
Retail trade
Consultancy services Statutory audit of bank branches<br>
slide115. MSME Sector –
Restructuring of Advances The RBI issued circular RBI/2020-21/17 DOR.No.BP. BC/4/21 .04.048/2020-21 dated August 06, in continuation of earlier circular 2020RBI/2019- 20/160 DOR. No.BP. BC.34/21.04.048/2019-20 dated February 11, 2020 extending the one-time restructuring of MSME advances classified as ‘standard’ without a downgrade in the asset classification and aligning the guidelines with the Resolution Framework for COVID19 – related Stress announced for other advances, with amended conditions as specified in the said circular Statutory audit of bank branches<br>
slide116. Other Finance to MSMEs
(i) Loans up to ₹50 crore to Start-ups, as per definition of Ministry of Commerce and Industry, Govt. of India that confirm to the definition of MSME.
(ii) Loans to entities involved in assisting the decentralized sector in the supply of inputs and marketing of output of artisans, village and cottage industries. Statutory audit of bank branches<br>
slide117. (iii) Loans to co-operatives of producers in the decentralized sector viz. artisans, village and cottage industries (Not applicable for UCBs).
(iv) Loans sanctioned by banks to NBFC-MFIs and other MFIs (Societies, Trusts etc.) which are members of RBI recognised SRO for the sector for on-lending to MSME sector
(v) Loans to registered NBFCs (other than MFIs) for on-lending to Micro & Small Enterprises Statutory audit of bank branches<br>
slide118. (vi) Credit outstanding under General Credit Cards (including Artisan Credit Card, Laghu Udyami Card, Swarojgar Credit Card and Weaver’s Card etc. in existence and catering to the non-farm entrepreneurial credit needs of individuals).
(vii) Overdraft to Pradhan Mantri Jan-Dhan Yojana (PMJDY) account holders as per limits prescribed by Department of Financial Services, MoF will qualify as achievement of the target for lending to Micro Enterprises. Statutory audit of bank branches<br>
slide119. Export Credit (not applicable to RRBs and LABs)
Export credit under agriculture and MSME sectors are allowed to be classified as PSL in the respective categories viz. agriculture and MSME. Export Credit (other than in agriculture and MSME) will be allowed to be classified as priority sector
Incremental export credit over corresponding date of the preceding year, up to 2 per cent of ANBC or CEOBE whichever is higher, subject to a sanctioned limit of up to Rs. 40 crore per borrower. Statutory audit of bank branches<br>
slide120. Export credit includes pre-shipment and post-shipment export credit (excluding off-balance sheet items) as defined in Master Circular on Rupee / Foreign Currency Export Credit and Customer Service to Exporters issued by Department of Regulation, Statutory audit of bank branches<br>
slide121. Education
Loans to individuals for educational purposes, including vocational courses, not exceeding ₹ 20 lakh will be considered as eligible for priority sector classification. Loans currently classified as priority sector will continue till maturity. Statutory audit of bank branches<br>
slide122. Housing
1.Loans to Individuals for ‘purchase/ construction’
Rs. 35 lakhs in Metropolitan centres where house value should not be more than Rs 45 lakhs
Rs. 25 lakhs in other area where house value should not be more than Rs 45 lakhs 30 lakhs
2. Loans for ‘repairs’
Rs. 10 lakhs in Metropolitan centres
Rs. 6 lakhs in others Statutory audit of bank branches<br>
slide123. Housing loans to banks’ own employees will not be eligible for classification under the priority sector.
Bank loans to any governmental agency for construction of dwelling units or for slum clearance and rehabilitation of slum dwellers subject to dwelling units with carpet area of not more than 60 sq.m.
Bank loans for affordable housing projects using at least 50% of FSI for dwelling units with carpet area of not more than 60 sq.m. Statutory audit of bank branches<br>
slide124. Statutory audit of bank branches<br>
slide125. Statutory audit of bank branches<br>
slide126. Central registry of mortgaged houses (NABARD & CIBIL)
Mortgage valid for 12 years
AOD every after three years
Frauds
If in society, recording of charge
Disbursement of subsidy Statutory audit of bank branches<br>
slide127. Social Infrastructure
Bank loans to social infrastructure sector as per limits prescribed below are eligible for priority sector classification
Bank loans up to a limit of Rs. 5 cr. per borrower for
1. setting up schools,
2. drinking water facilities Statutory audit of bank branches<br>
slide128. 3. sanitation facilities including construction / refurbishment of household toilets and water improvements at household level, etc. and
4. loans up to a limit of Rs. 10 crore per borrower for building health care facilities including under ‘Ayushman Bharat’ in Tier II to Tier VI centres. Statutory audit of bank branches<br>
slide129. Renewable Energy
Bank loans up to a limit of Rs. 30 crore to borrowers for purposes like solar based power generators, biomass-based power generators, wind mills, micro-hydel plants and for non-conventional energy based public utilities, viz., street lighting systems and remote village electrification etc., will be eligible for Priority Sector classification. For individual households, the loan limit will be Rs. 10 lakh per borrower. Statutory audit of bank branches<br>
slide130. Bank loans to HFCs, approved by NHB for their refinance, for on lending for the purpose of purchase/construction/reconstruction of individual dwelling units or for slum clearance and rehabilitation of slum dwellers, subject to a ceiling as may be specified by RBI per dwelling unit.
The all inclusive interest rate charged to the ultimate borrower should not exceed the lowest lending rate of the lending bank for HLs + 2% per annum Statutory audit of bank branches<br>
slide131. Others (eligible for priority sector classification)
Loans not exceeding Rs. 1.00 lakh per borrower provided directly by banks to individuals and individual members of SHG/JLG, provided the individual borrower’s household annual income in rural areas does not exceed Rs. 1.00 lakh and
for non-rural areas it does not exceed Rs. 1.60 lakh, and loans not exceeding Rs. 2.00 lakh provided directly by banks to SHG/JLG for activities other than agriculture or MSME, viz., loans for meeting social needs, construction or repair of house, construction of toilets or any viable common activity started by the SHGs. Statutory audit of bank branches<br>
slide132. Loans to distressed persons [other than distressed farmers indebted to non-institutional lenders] not exceeding Rs.1.00 lakh per borrower to prepay their debt to non-institutional lenders.
Loans sanctioned to State Sponsored Organisations for Scheduled Castes/ Scheduled Tribes for the specific purpose of purchase and supply of inputs and/or the marketing of the outputs of the beneficiaries of these organisations. Statutory audit of bank branches<br>
slide133. Loans up to Rs. 50 crore to Start-ups, as per definition of Ministry of Commerce and Industry, Govt. of India that are engaged in activities other than Agriculture or MSME.
Weaker Sections
Priority sector loans to the following borrowers will be considered as lending under Weaker Sections category:
1. Small and Marginal Farmers
2. Artisans, village and cottage industries where individual credit limits do not exceed Rs.1 lakh Statutory audit of bank branches<br>
slide134. 3. Beneficiaries under Government Sponsored Schemes such as National Rural Livelihood Mission (NRLM), National Urban Livelihood Mission (NULM) and Self Employment Scheme for Rehabilitation of Manual Scavengers (SRMS)
4. Scheduled Castes and Scheduled Tribes
5. Beneficiaries of Differential Rate of Interest (DRI) scheme
6. Self Help Groups Statutory audit of bank branches<br>
slide135. 7.Distressed farmers indebted to non-institutional lenders
8. Distressed persons other than farmers, with loan amount not exceeding Rs. 1 lakh per borrower to prepay their debt to non-institutional lenders
9. Individual women beneficiaries up to Rs. 1 lakh per borrower (For UCBs, existing loans to women will continue to be classified under weaker sections till their maturity/repayment.)
10. Persons with disabilities
11. Minority communities as may be notified by Government of India from time to time. Statutory audit of bank branches<br>
slide136. Thank you learned participants
Cell 9822850606 Statutory audit of bank branches<br>