
Gross Receipts Taxes Louisiana Tax Institute

Description: Gross Receipts Taxes Louisiana Tax Institute January 23, 2018 1 Prepared and presented by Luke Morris Assistant Secretary Office of Legal Affairs Informational Purposes Only This presentation is for informational purposes only and not to be
Related Topics
Download Presentation
"Gross Receipts Taxes Louisiana Tax Institute" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Gross Receipts Taxes
Louisiana Tax Institute
January 23, 2018 1 Prepared and presented by
Luke Morris
Assistant Secretary
Office of Legal Affairs<br>
slide2. Informational Purposes Only This presentation is for informational purposes only and not to be considered advice, informal or otherwise. The material herein is informational in nature and based on publicly available data. 2<br>
slide3. Overview Gross Receipts Taxes, in General
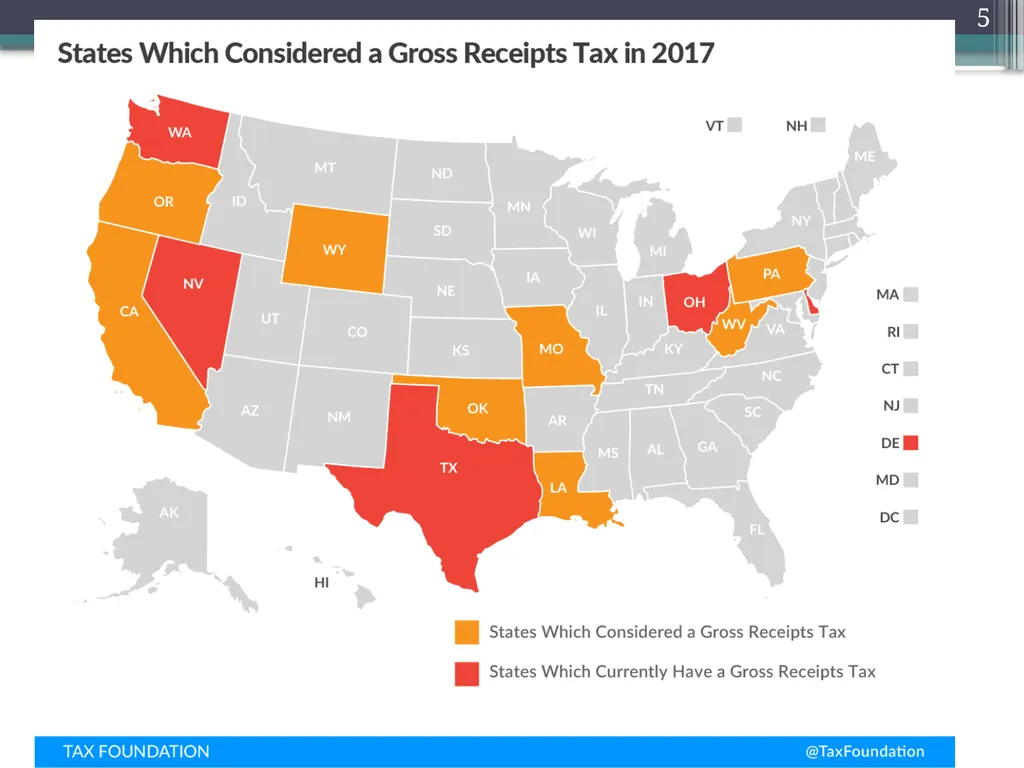
Other States’ Approach to Gross Receipts Taxes
Louisiana Legislation and Fiscal Estimates
Commercial Activity Tax (HB 628) 3<br>
slide4. Gross Receipts Taxes Traditionally, state governments have raised revenue from business by taxing corporate income. In recent years, the growing difficultly of administering state corporate income taxes has prompted a resurgence of the gross receipts tax.
Gross receipts taxes have a simple structure of taxing business sales, similar to a sales tax, but the tax is paid by the business, not the consumer. 4<br>
slide5. 5<br>
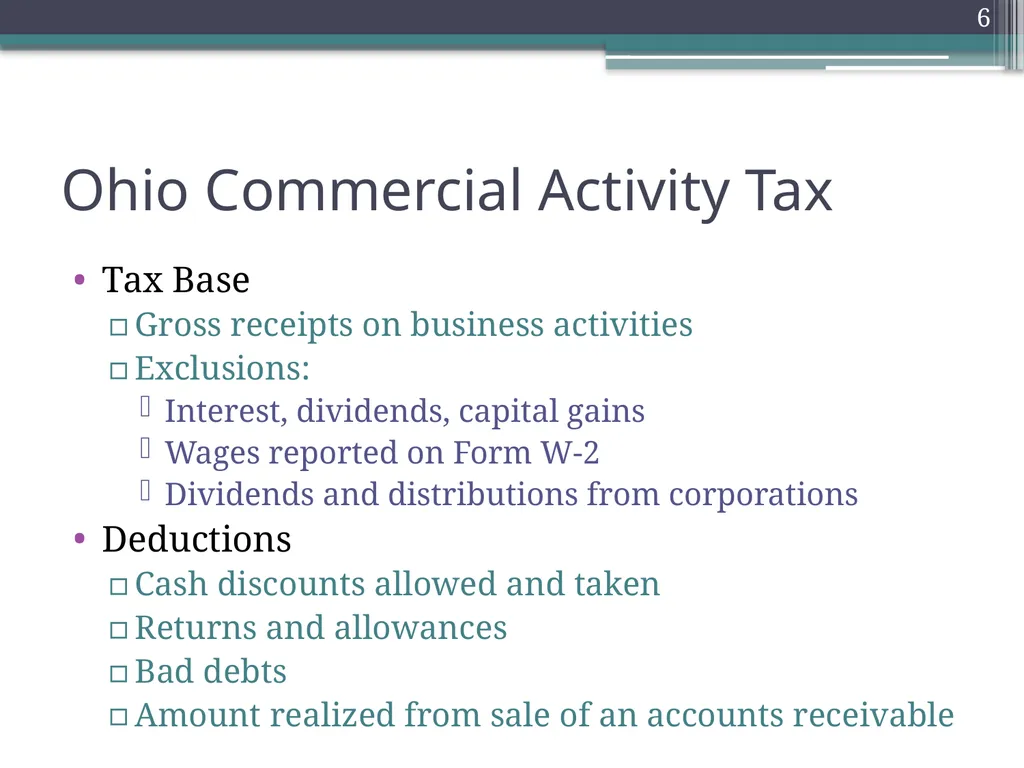
slide6. Ohio Commercial Activity Tax Tax Base
Gross receipts on business activities
Exclusions:
Interest, dividends, capital gains
Wages reported on Form W-2
Dividends and distributions from corporations
Deductions
Cash discounts allowed and taken
Returns and allowances
Bad debts
Amount realized from sale of an accounts receivable 6<br>
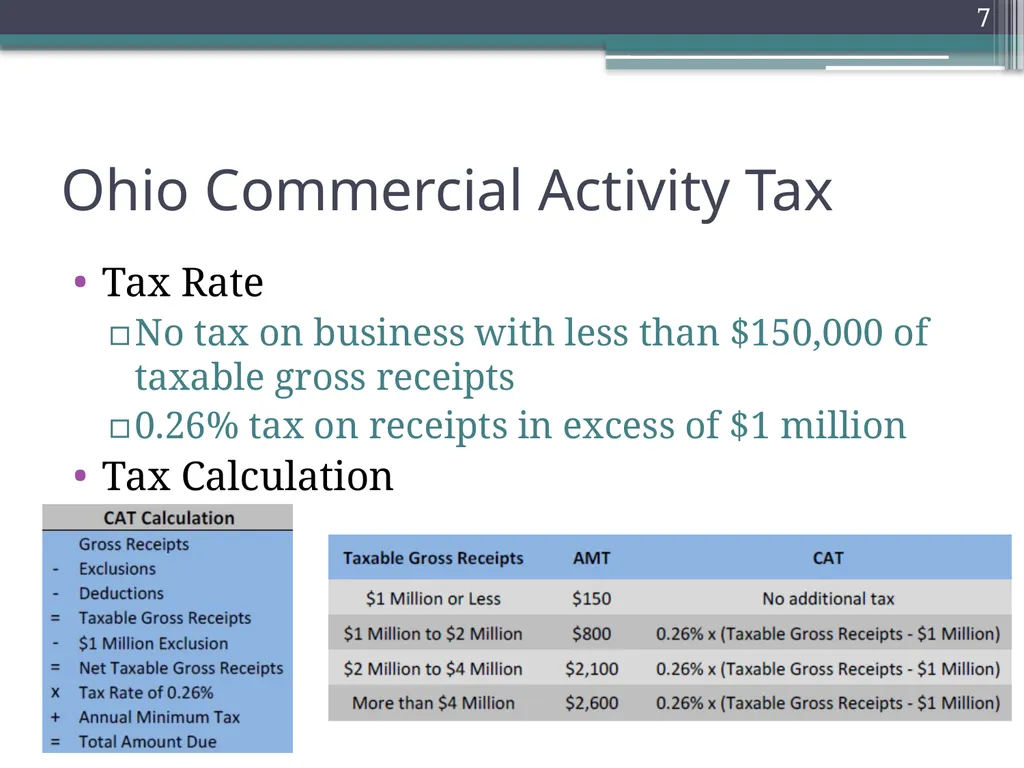
slide7. Ohio Commercial Activity Tax Tax Rate
No tax on business with less than $150,000 of taxable gross receipts
0.26% tax on receipts in excess of $1 million
Tax Calculation 7<br>
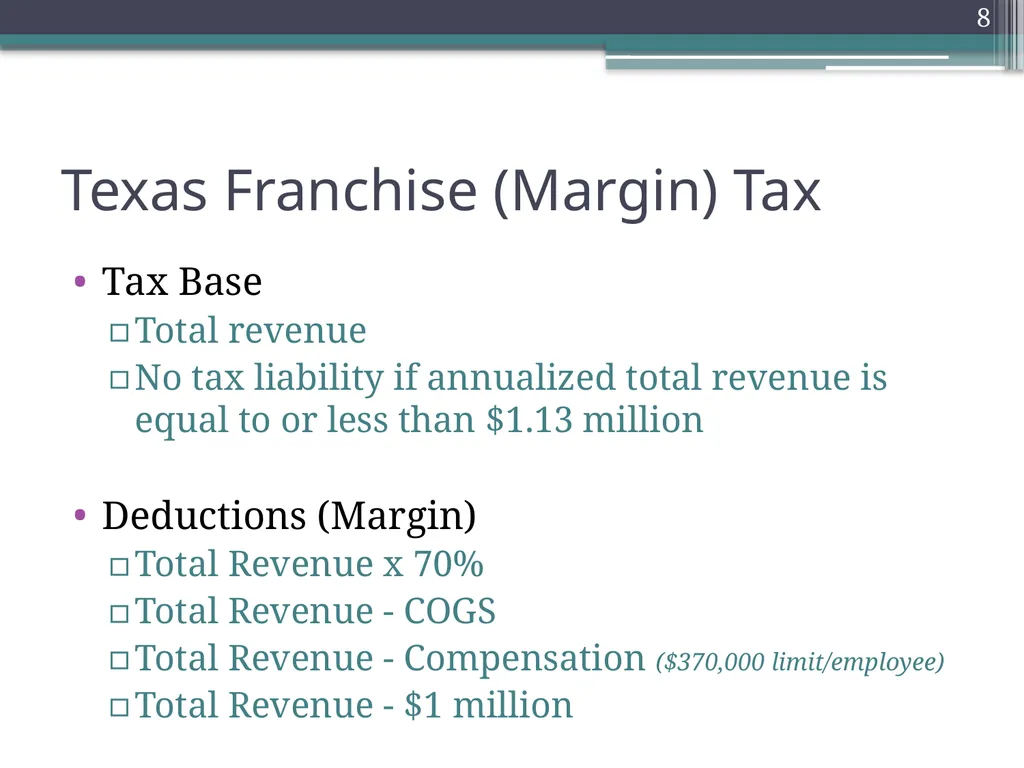
slide8. Texas Franchise (Margin) Tax Tax Base
Total revenue
No tax liability if annualized total revenue is equal to or less than $1.13 million
Deductions (Margin)
Total Revenue x 70%
Total Revenue - COGS
Total Revenue - Compensation ($370,000 limit/employee)
Total Revenue - $1 million 8<br>
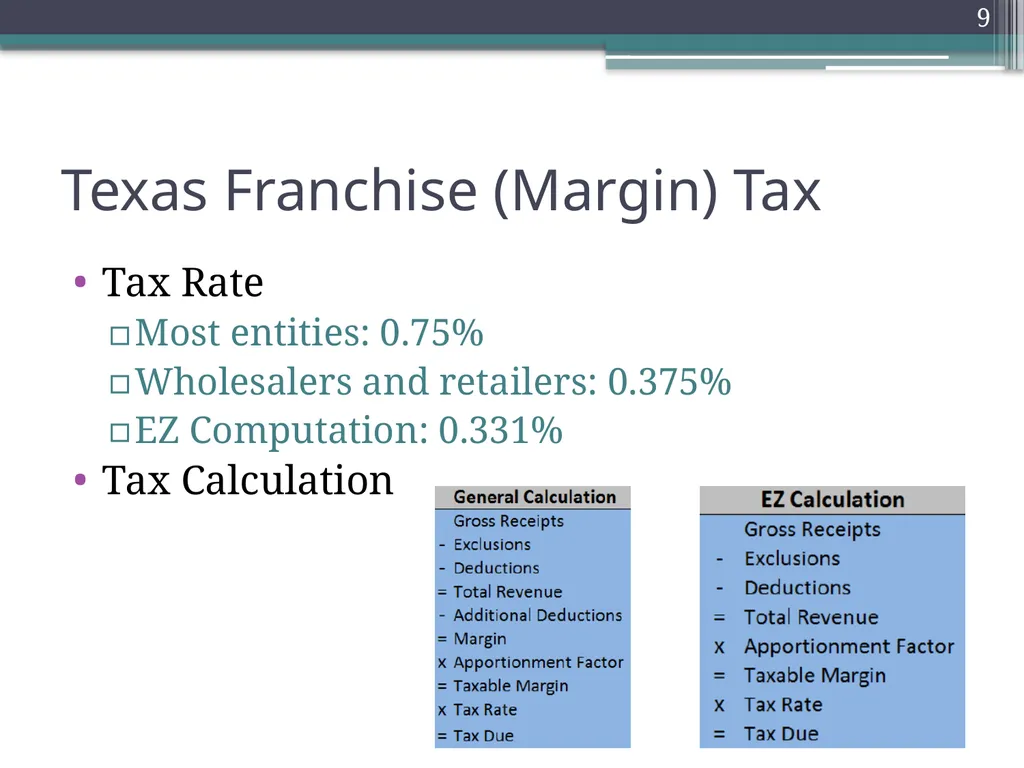
slide9. Texas Franchise (Margin) Tax Tax Rate
Most entities: 0.75%
Wholesalers and retailers: 0.375%
EZ Computation: 0.331%
Tax Calculation 9<br>
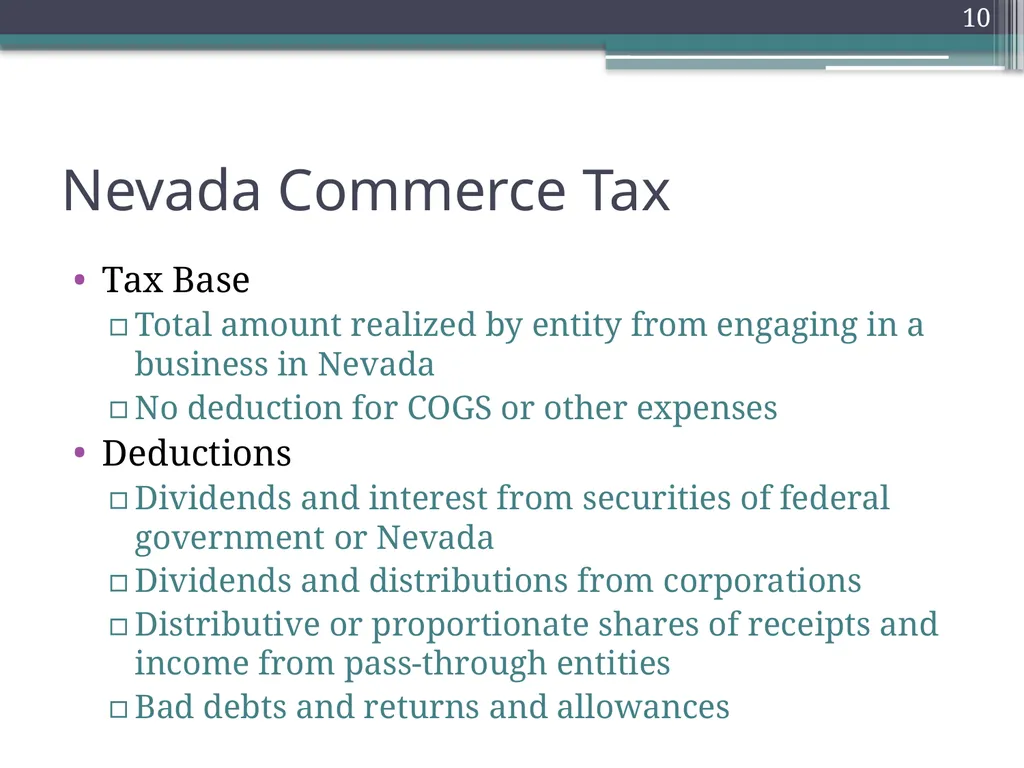
slide10. Nevada Commerce Tax Tax Base
Total amount realized by entity from engaging in a business in Nevada
No deduction for COGS or other expenses
Deductions
Dividends and interest from securities of federal government or Nevada
Dividends and distributions from corporations
Distributive or proportionate shares of receipts and income from pass-through entities
Bad debts and returns and allowances 10<br>
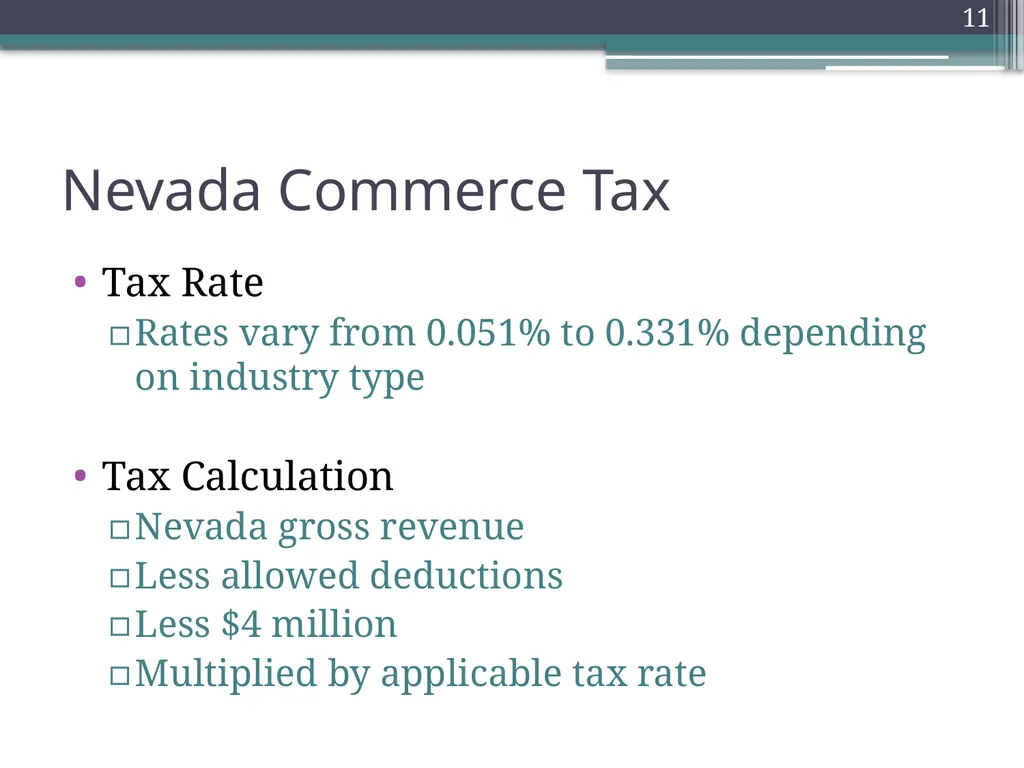
slide11. Nevada Commerce Tax Tax Rate
Rates vary from 0.051% to 0.331% depending on industry type
Tax Calculation
Nevada gross revenue
Less allowed deductions
Less $4 million
Multiplied by applicable tax rate 11<br>
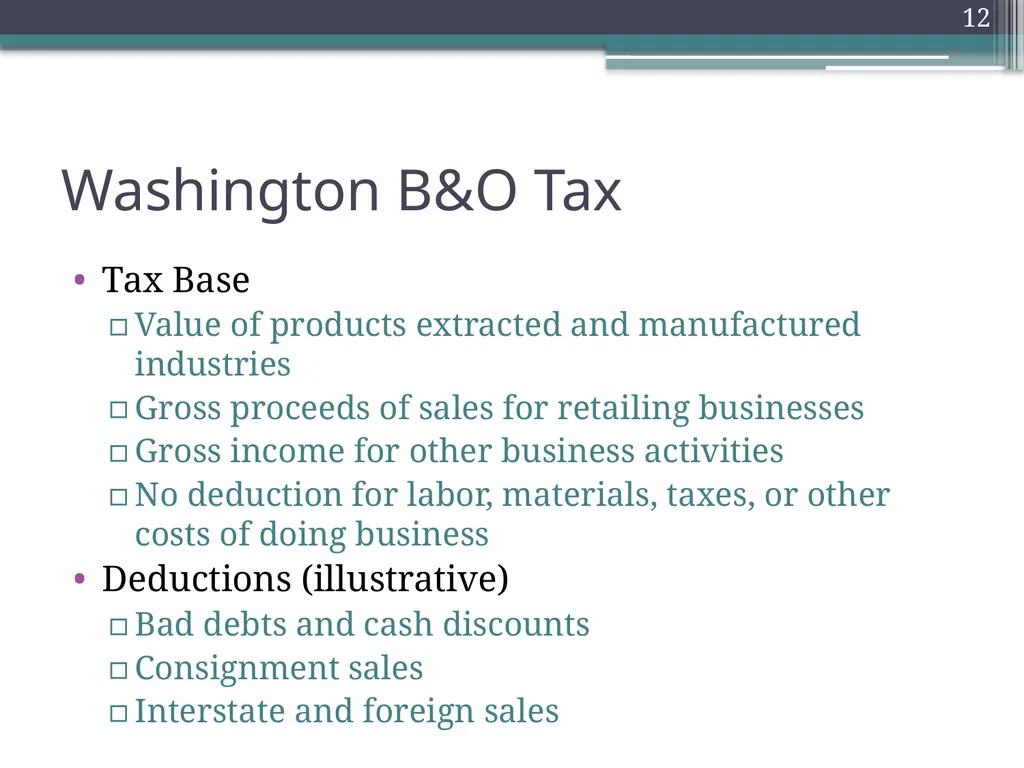
slide12. Washington B&O Tax Tax Base
Value of products extracted and manufactured industries
Gross proceeds of sales for retailing businesses
Gross income for other business activities
No deduction for labor, materials, taxes, or other costs of doing business
Deductions (illustrative)
Bad debts and cash discounts
Consignment sales
Interstate and foreign sales 12<br>
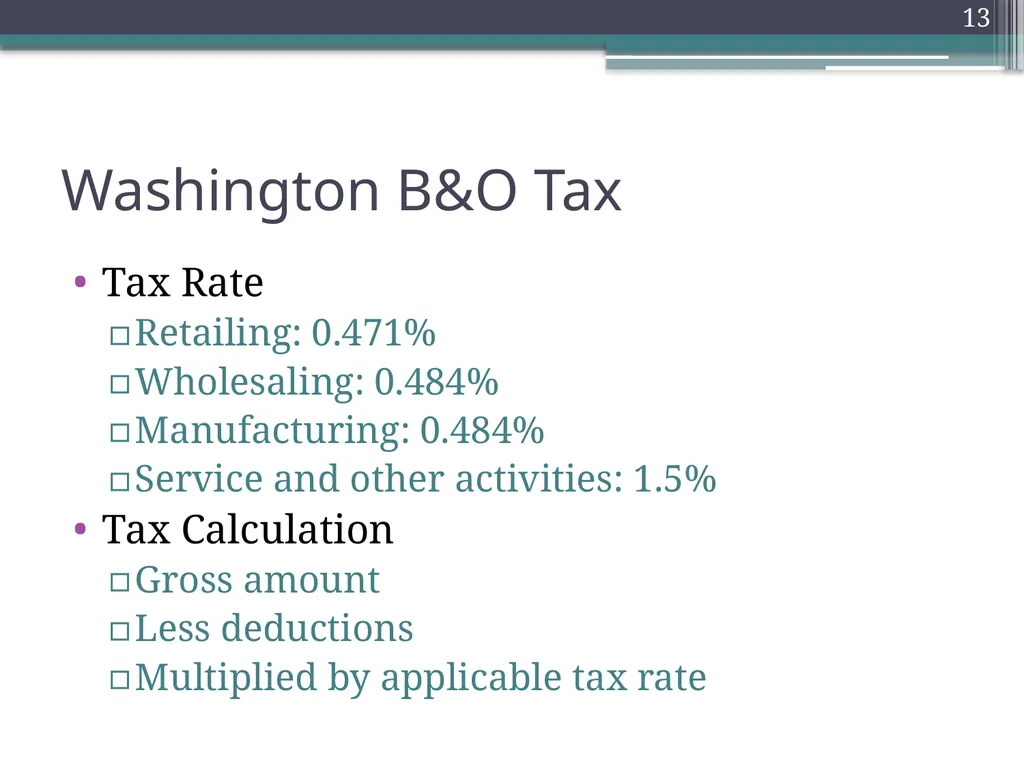
slide13. Washington B&O Tax Tax Rate
Retailing: 0.471%
Wholesaling: 0.484%
Manufacturing: 0.484%
Service and other activities: 1.5%
Tax Calculation
Gross amount
Less deductions
Multiplied by applicable tax rate 13<br>
slide14. LA Commercial Activity Tax House Bill 628
Representative Sam Jones 14<br>
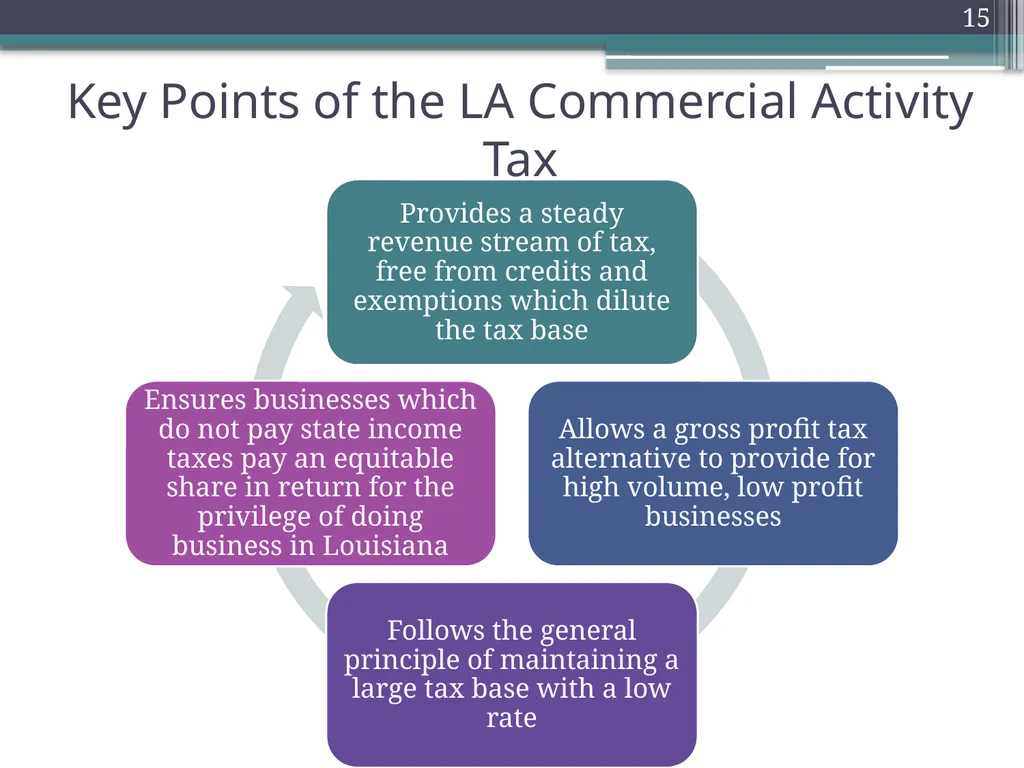
slide15. Key Points of the LA Commercial Activity Tax 15<br>
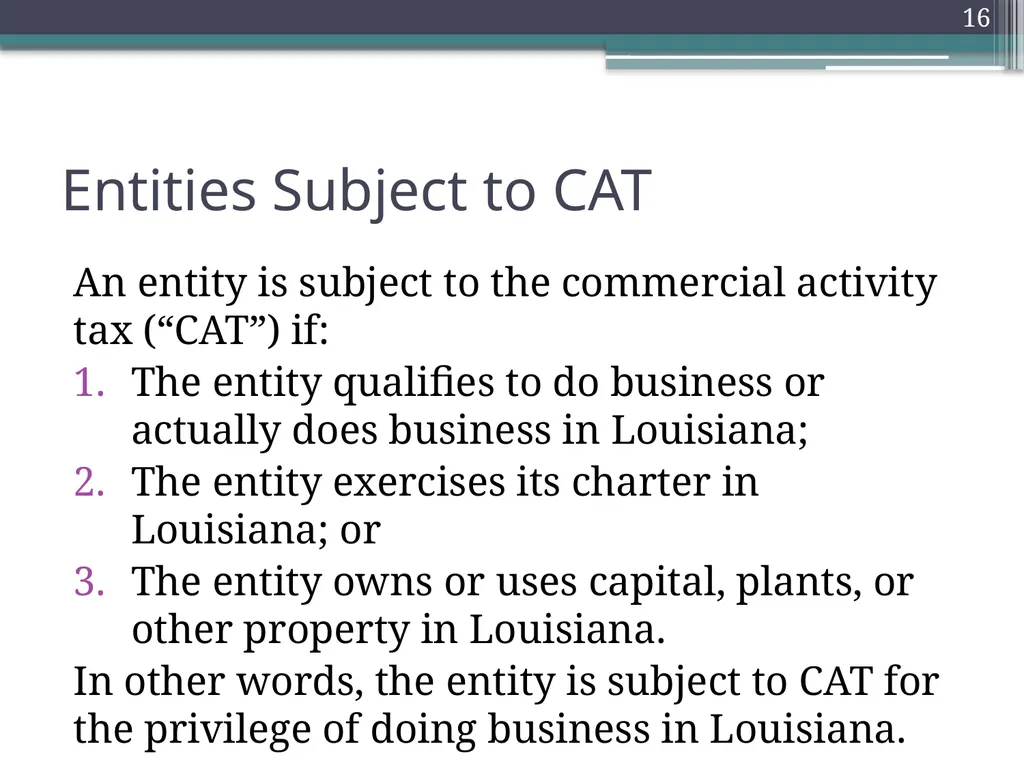
slide16. Entities Subject to CAT An entity is subject to the commercial activity tax (“CAT”) if:
The entity qualifies to do business or actually does business in Louisiana;
The entity exercises its charter in Louisiana; or
The entity owns or uses capital, plants, or other property in Louisiana.
In other words, the entity is subject to CAT for the privilege of doing business in Louisiana. 16<br>
slide17. Overview of CAT Calculation The CAT is calculated differently depending on the entity’s type of organizational structure
Corporations
Pass-throughs
Small Business Exclusion
Regardless of entity, CAT is not due if the entity has gross receipts from all sources less than $150,000 17<br>
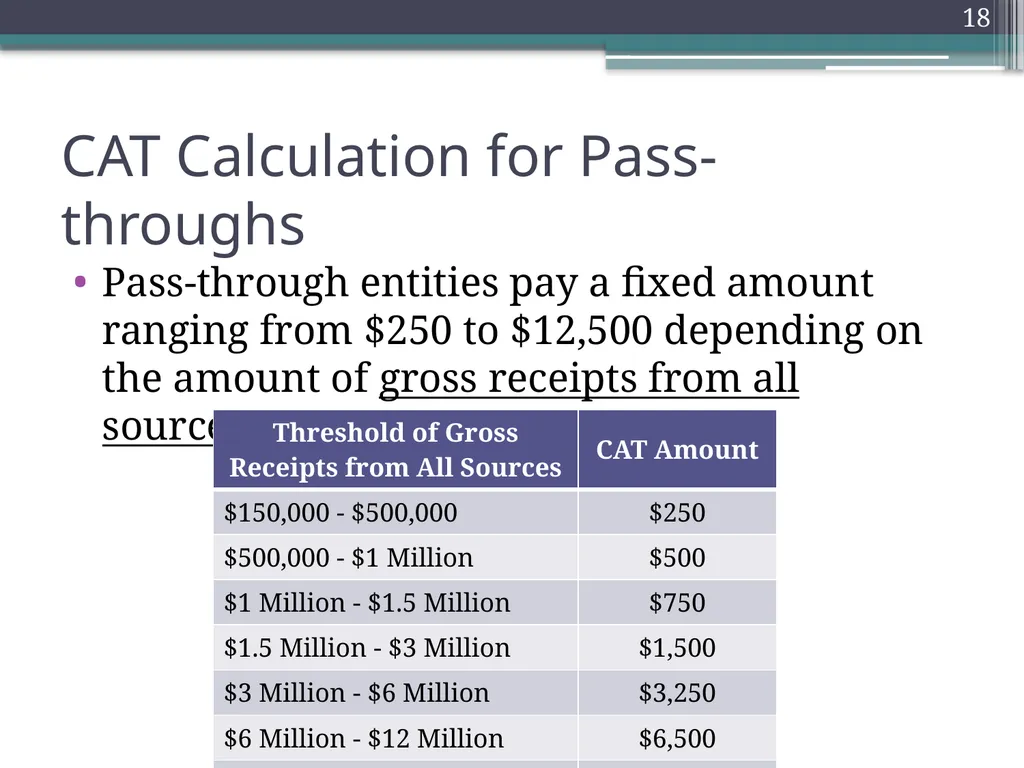
slide18. CAT Calculation for Pass-throughs Pass-through entities pay a fixed amount ranging from $250 to $12,500 depending on the amount of gross receipts from all sources. 18<br>
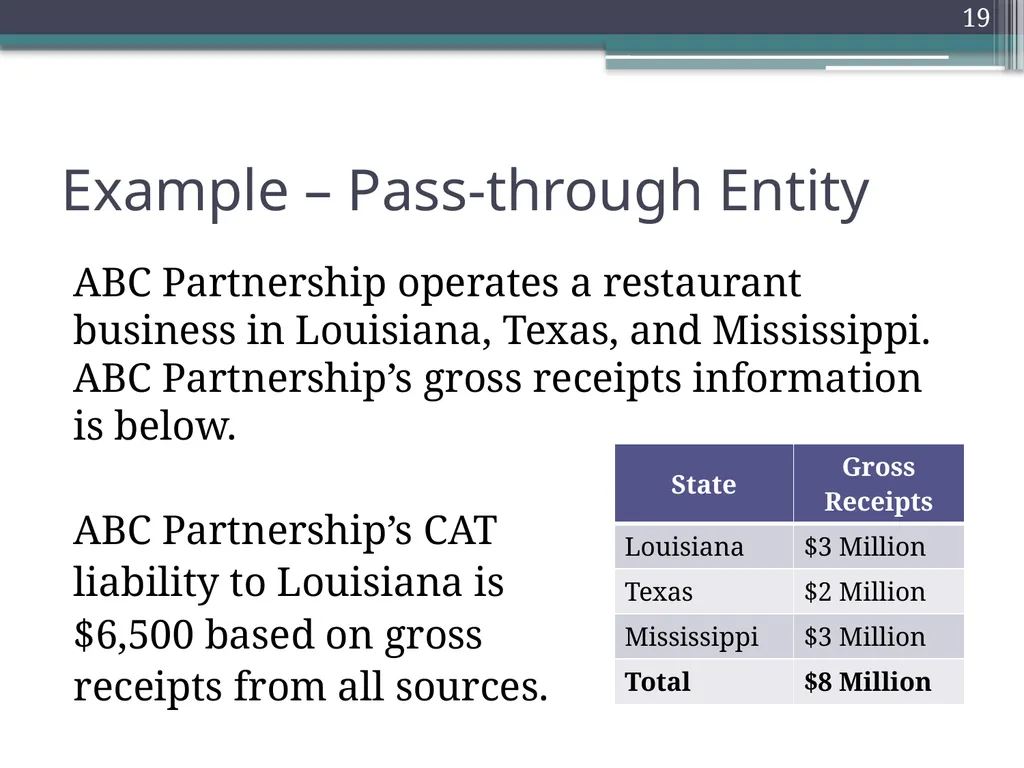
slide19. Example – Pass-through Entity ABC Partnership operates a restaurant business in Louisiana, Texas, and Mississippi. ABC Partnership’s gross receipts information is below.
ABC Partnership’s CAT
liability to Louisiana is
$6,500 based on gross
receipts from all sources. 19<br>
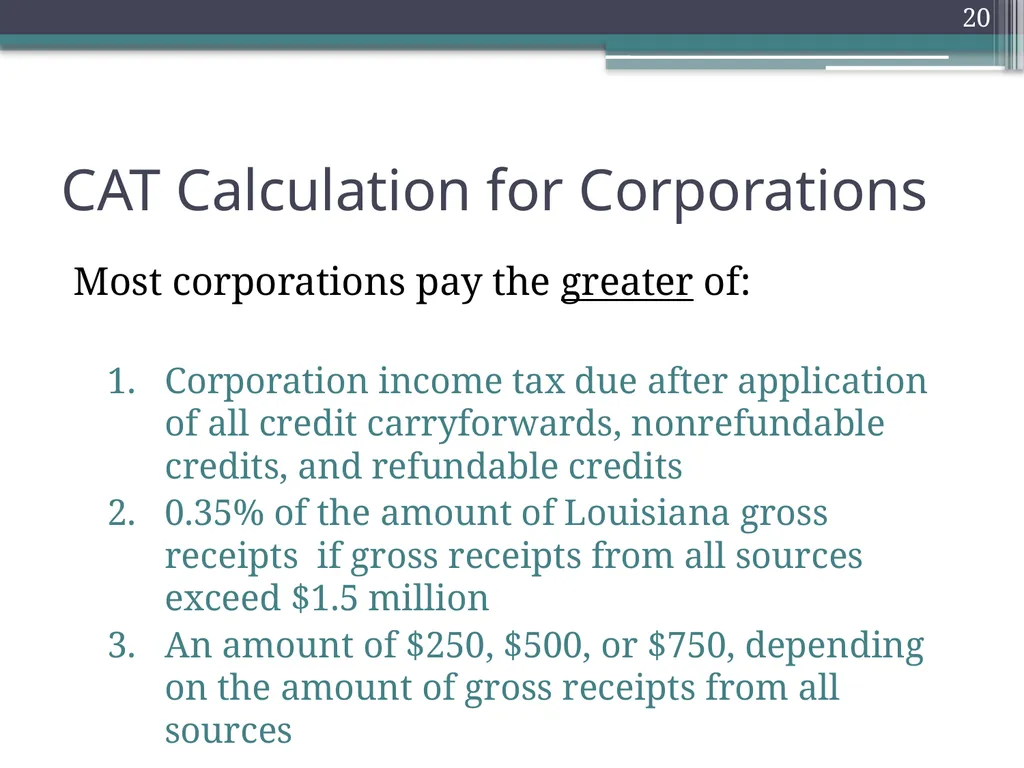
slide20. CAT Calculation for Corporations Most corporations pay the greater of:
Corporation income tax due after application of all credit carryforwards, nonrefundable credits, and refundable credits
0.35% of the amount of Louisiana gross receipts if gross receipts from all sources exceed $1.5 million
An amount of $250, $500, or $750, depending on the amount of gross receipts from all sources 20<br>
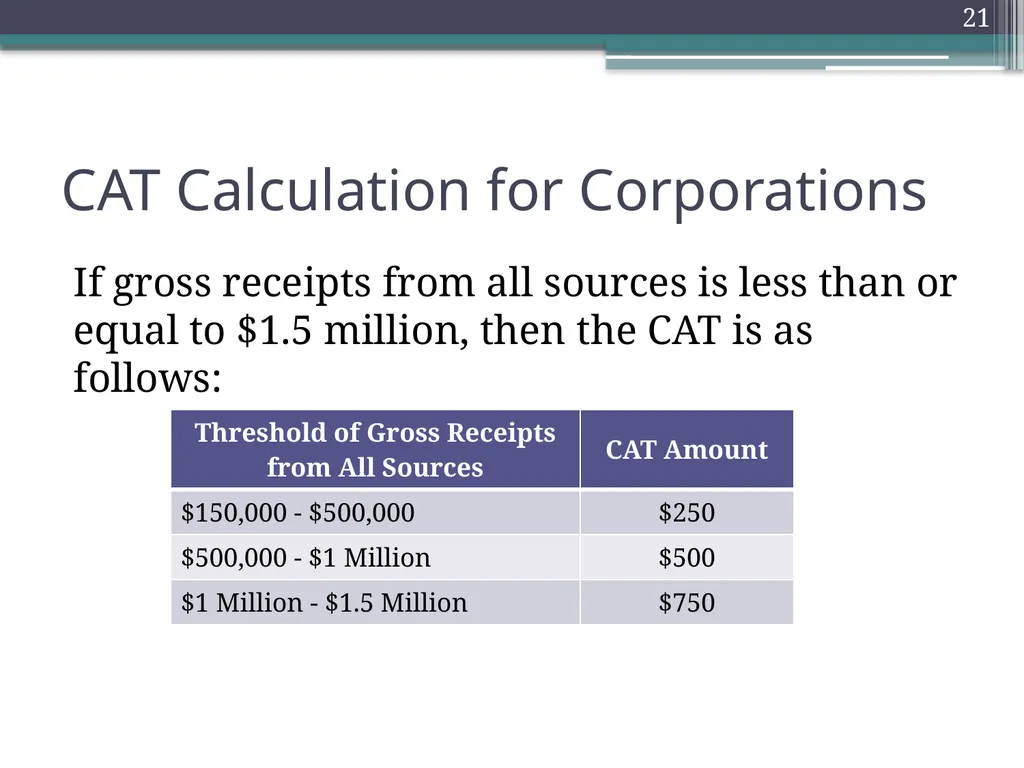
slide21. CAT Calculation for Corporations If gross receipts from all sources is less than or equal to $1.5 million, then the CAT is as follows: 21<br>
slide22. Example – Service Corporation XYZ Corp provides consulting services only in Louisiana. XYZ Corp earns $4 million in gross receipts and pays its consultants $3 million in salaries.
XYZ Corp’s CAT liability before consideration of corporation income tax is $14,000.
($4 million of Louisiana gross receipts multiplied by 0.35%) 22<br>
slide23. CAT Calculation for Merchandising Corporations For corporations in the business of merchandising, whether at wholesale or retail, the calculation includes a gross profits component. 23<br>
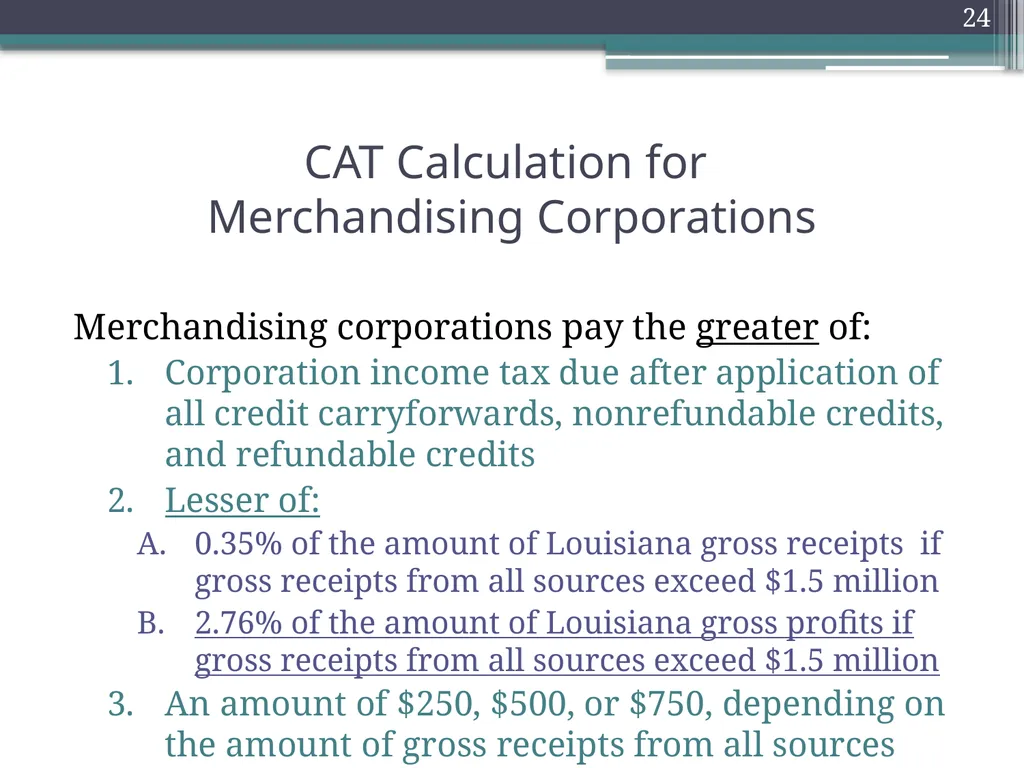
slide24. Merchandising corporations pay the greater of:
Corporation income tax due after application of all credit carryforwards, nonrefundable credits, and refundable credits
Lesser of:
0.35% of the amount of Louisiana gross receipts if gross receipts from all sources exceed $1.5 million
2.76% of the amount of Louisiana gross profits if gross receipts from all sources exceed $1.5 million
An amount of $250, $500, or $750, depending on the amount of gross receipts from all sources 24 CAT Calculation for Merchandising Corporations<br>
slide25. Example – Retail Corporation JKL Corp sells clothing at retail in department stores only in Louisiana. JKL Corp purchases the clothing from a wholesaler. JKL Corp earns $10 million in gross receipts and expends $9.9 million in cost of goods sold.
JKL Corp’s CAT liability before consideration of corporation income tax is $2,760.
($10M x 0.35% = $35,000 > $100,000 x 2.76% = $2,760.) 25<br>
slide26. Consolidated Returns Consolidated returns are required in certain instances:
Corporations owning single member LLCs
Corporations owning qualified Subchapter S subsidiaries
Publicly traded partnerships owning LLC or LP affiliates 26<br>
slide27. Fiscal Effect Legislative Fiscal Office estimated a revenue increase of $416.6 million. 27<br>
Luke Morris
Assistant Secretary
Office of Legal Affairs<br>
slide2. Informational Purposes Only This presentation is for informational purposes only and not to be considered advice, informal or otherwise. The material herein is informational in nature and based on publicly available data. 2<br>
slide3. Overview Gross Receipts Taxes, in General
Other States’ Approach to Gross Receipts Taxes
Louisiana Legislation and Fiscal Estimates
Commercial Activity Tax (HB 628) 3<br>
slide4. Gross Receipts Taxes Traditionally, state governments have raised revenue from business by taxing corporate income. In recent years, the growing difficultly of administering state corporate income taxes has prompted a resurgence of the gross receipts tax.
Gross receipts taxes have a simple structure of taxing business sales, similar to a sales tax, but the tax is paid by the business, not the consumer. 4<br>
slide5. 5<br>
slide6. Ohio Commercial Activity Tax Tax Base
Gross receipts on business activities
Exclusions:
Interest, dividends, capital gains
Wages reported on Form W-2
Dividends and distributions from corporations
Deductions
Cash discounts allowed and taken
Returns and allowances
Bad debts
Amount realized from sale of an accounts receivable 6<br>
slide7. Ohio Commercial Activity Tax Tax Rate
No tax on business with less than $150,000 of taxable gross receipts
0.26% tax on receipts in excess of $1 million
Tax Calculation 7<br>
slide8. Texas Franchise (Margin) Tax Tax Base
Total revenue
No tax liability if annualized total revenue is equal to or less than $1.13 million
Deductions (Margin)
Total Revenue x 70%
Total Revenue - COGS
Total Revenue - Compensation ($370,000 limit/employee)
Total Revenue - $1 million 8<br>
slide9. Texas Franchise (Margin) Tax Tax Rate
Most entities: 0.75%
Wholesalers and retailers: 0.375%
EZ Computation: 0.331%
Tax Calculation 9<br>
slide10. Nevada Commerce Tax Tax Base
Total amount realized by entity from engaging in a business in Nevada
No deduction for COGS or other expenses
Deductions
Dividends and interest from securities of federal government or Nevada
Dividends and distributions from corporations
Distributive or proportionate shares of receipts and income from pass-through entities
Bad debts and returns and allowances 10<br>
slide11. Nevada Commerce Tax Tax Rate
Rates vary from 0.051% to 0.331% depending on industry type
Tax Calculation
Nevada gross revenue
Less allowed deductions
Less $4 million
Multiplied by applicable tax rate 11<br>
slide12. Washington B&O Tax Tax Base
Value of products extracted and manufactured industries
Gross proceeds of sales for retailing businesses
Gross income for other business activities
No deduction for labor, materials, taxes, or other costs of doing business
Deductions (illustrative)
Bad debts and cash discounts
Consignment sales
Interstate and foreign sales 12<br>
slide13. Washington B&O Tax Tax Rate
Retailing: 0.471%
Wholesaling: 0.484%
Manufacturing: 0.484%
Service and other activities: 1.5%
Tax Calculation
Gross amount
Less deductions
Multiplied by applicable tax rate 13<br>
slide14. LA Commercial Activity Tax House Bill 628
Representative Sam Jones 14<br>
slide15. Key Points of the LA Commercial Activity Tax 15<br>
slide16. Entities Subject to CAT An entity is subject to the commercial activity tax (“CAT”) if:
The entity qualifies to do business or actually does business in Louisiana;
The entity exercises its charter in Louisiana; or
The entity owns or uses capital, plants, or other property in Louisiana.
In other words, the entity is subject to CAT for the privilege of doing business in Louisiana. 16<br>
slide17. Overview of CAT Calculation The CAT is calculated differently depending on the entity’s type of organizational structure
Corporations
Pass-throughs
Small Business Exclusion
Regardless of entity, CAT is not due if the entity has gross receipts from all sources less than $150,000 17<br>
slide18. CAT Calculation for Pass-throughs Pass-through entities pay a fixed amount ranging from $250 to $12,500 depending on the amount of gross receipts from all sources. 18<br>
slide19. Example – Pass-through Entity ABC Partnership operates a restaurant business in Louisiana, Texas, and Mississippi. ABC Partnership’s gross receipts information is below.
ABC Partnership’s CAT
liability to Louisiana is
$6,500 based on gross
receipts from all sources. 19<br>
slide20. CAT Calculation for Corporations Most corporations pay the greater of:
Corporation income tax due after application of all credit carryforwards, nonrefundable credits, and refundable credits
0.35% of the amount of Louisiana gross receipts if gross receipts from all sources exceed $1.5 million
An amount of $250, $500, or $750, depending on the amount of gross receipts from all sources 20<br>
slide21. CAT Calculation for Corporations If gross receipts from all sources is less than or equal to $1.5 million, then the CAT is as follows: 21<br>
slide22. Example – Service Corporation XYZ Corp provides consulting services only in Louisiana. XYZ Corp earns $4 million in gross receipts and pays its consultants $3 million in salaries.
XYZ Corp’s CAT liability before consideration of corporation income tax is $14,000.
($4 million of Louisiana gross receipts multiplied by 0.35%) 22<br>
slide23. CAT Calculation for Merchandising Corporations For corporations in the business of merchandising, whether at wholesale or retail, the calculation includes a gross profits component. 23<br>
slide24. Merchandising corporations pay the greater of:
Corporation income tax due after application of all credit carryforwards, nonrefundable credits, and refundable credits
Lesser of:
0.35% of the amount of Louisiana gross receipts if gross receipts from all sources exceed $1.5 million
2.76% of the amount of Louisiana gross profits if gross receipts from all sources exceed $1.5 million
An amount of $250, $500, or $750, depending on the amount of gross receipts from all sources 24 CAT Calculation for Merchandising Corporations<br>
slide25. Example – Retail Corporation JKL Corp sells clothing at retail in department stores only in Louisiana. JKL Corp purchases the clothing from a wholesaler. JKL Corp earns $10 million in gross receipts and expends $9.9 million in cost of goods sold.
JKL Corp’s CAT liability before consideration of corporation income tax is $2,760.
($10M x 0.35% = $35,000 > $100,000 x 2.76% = $2,760.) 25<br>
slide26. Consolidated Returns Consolidated returns are required in certain instances:
Corporations owning single member LLCs
Corporations owning qualified Subchapter S subsidiaries
Publicly traded partnerships owning LLC or LP affiliates 26<br>
slide27. Fiscal Effect Legislative Fiscal Office estimated a revenue increase of $416.6 million. 27<br>