
LRS remittances and Foreign investment by Resident




Description: LRS remittances and Foreign investment by Resident Individuals FEMA Income-tax interplay Indore Branch of ICAI 22nd December 2023 CA Rutvik Sanghvi LRS remittances foreign investments by resident individuals FEMA and Income-tax
Related Topics
Download Presentation
"LRS remittances and Foreign investment by Resident" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. LRS remittances and Foreign investment
by Resident Individuals –
FEMA & Income-tax interplay
Indore Branch of ICAI
22nd December 2023 CA Rutvik Sanghvi<br>
slide2. LRS remittances & foreign investments by resident individuals – FEMA and Income-tax – Presentation Layout 2 CA Rutvik Sanghvi<br>
slide3. Overview<br>
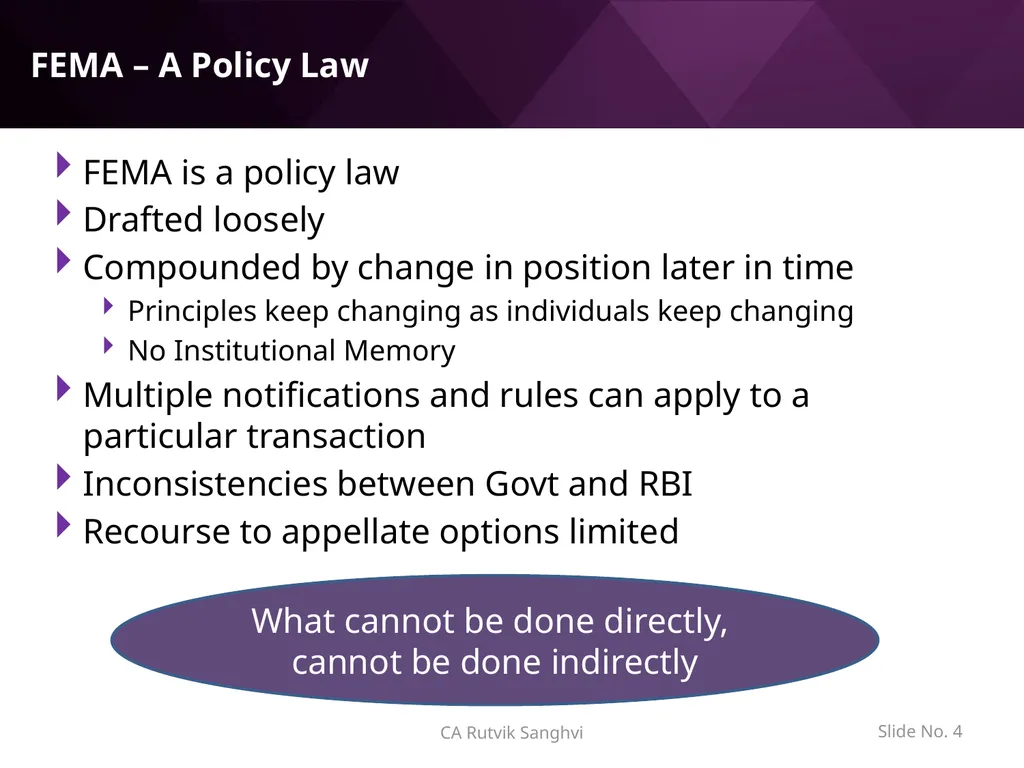
slide4. FEMA – A Policy Law FEMA is a policy law
Drafted loosely
Compounded by change in position later in time
Principles keep changing as individuals keep changing
No Institutional Memory
Multiple notifications and rules can apply to a particular transaction
Inconsistencies between Govt and RBI
Recourse to appellate options limited CA Rutvik Sanghvi Slide No. 4 What cannot be done directly,
cannot be done indirectly<br>
slide5. Compliance with FEMA a must for foreign investments Overseas investments are often fraught with violations – largely due to ignorance of law and ease of doing business abroad
However, FEMA is now more draconian than FERA – especially for foreign investments
Black Money Act while targeted at income-tax also brought in provisions for seizure of assets in India if any person holds any foreign exchange, foreign security or any immovable property outside India in contravention of Section 4 of FEMA
Section 37A newly introduced vide Finance Act, 2015 in FEMA
Can lead to penalty and prosecution 5 CA Rutvik Sanghvi<br>
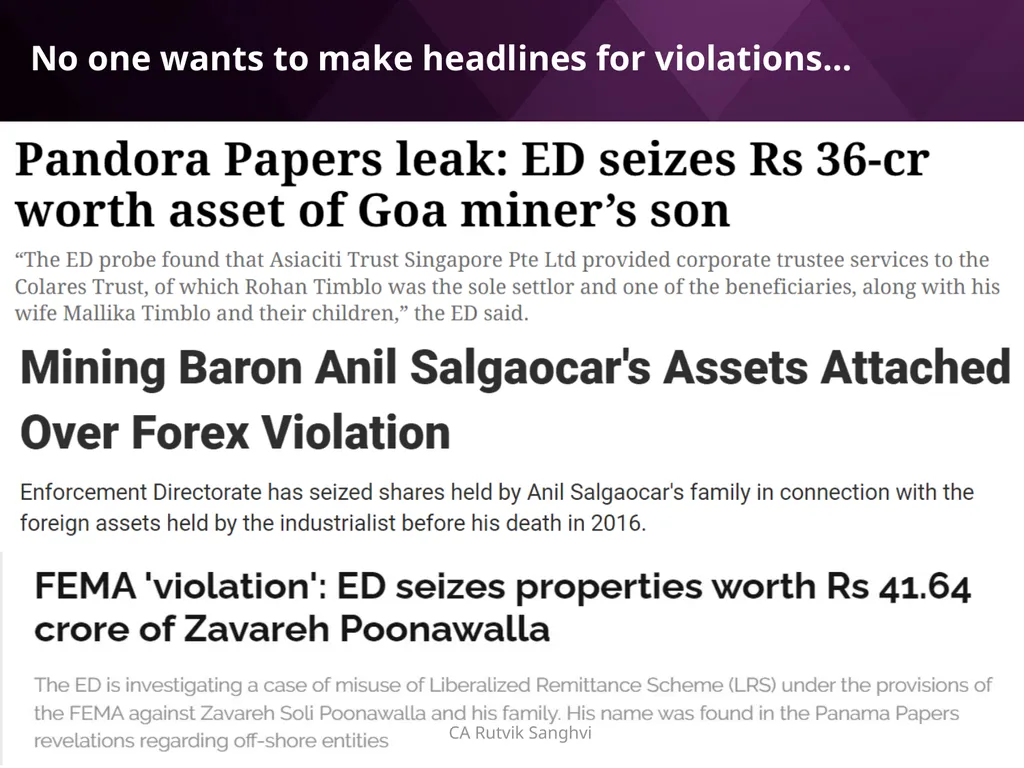
slide6. No one wants to make headlines for violations… 6 CA Rutvik Sanghvi<br>
slide7. Liberalised Remittance Scheme<br>
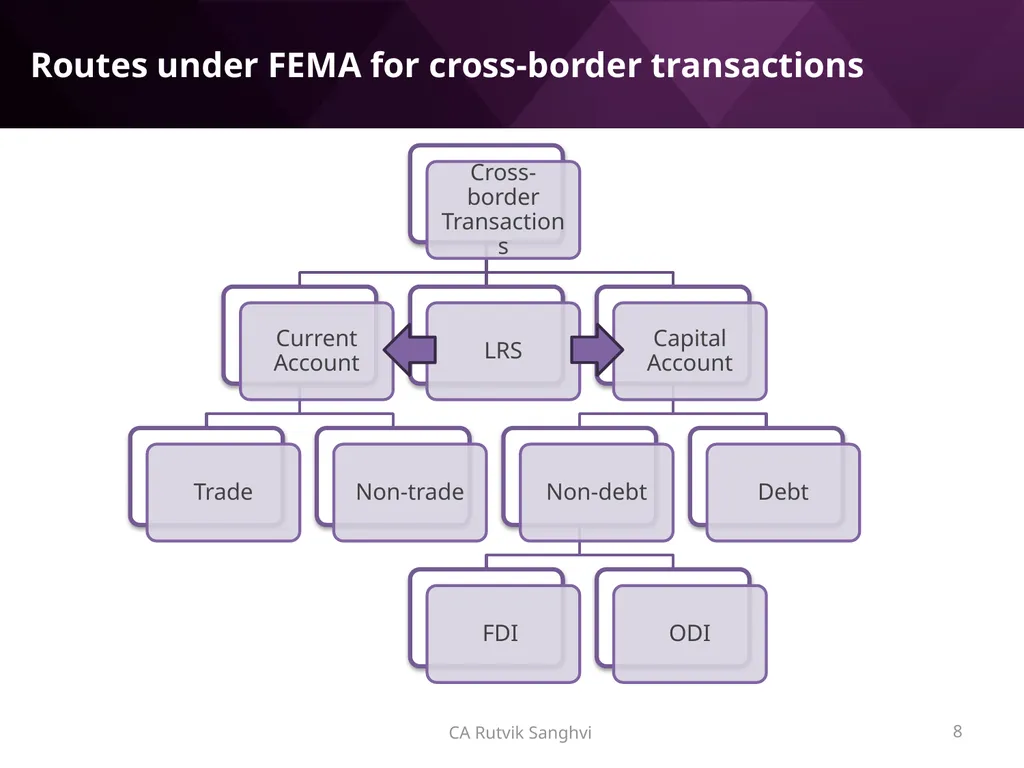
slide8. Routes under FEMA for cross-border transactions CA Rutvik Sanghvi 8<br>
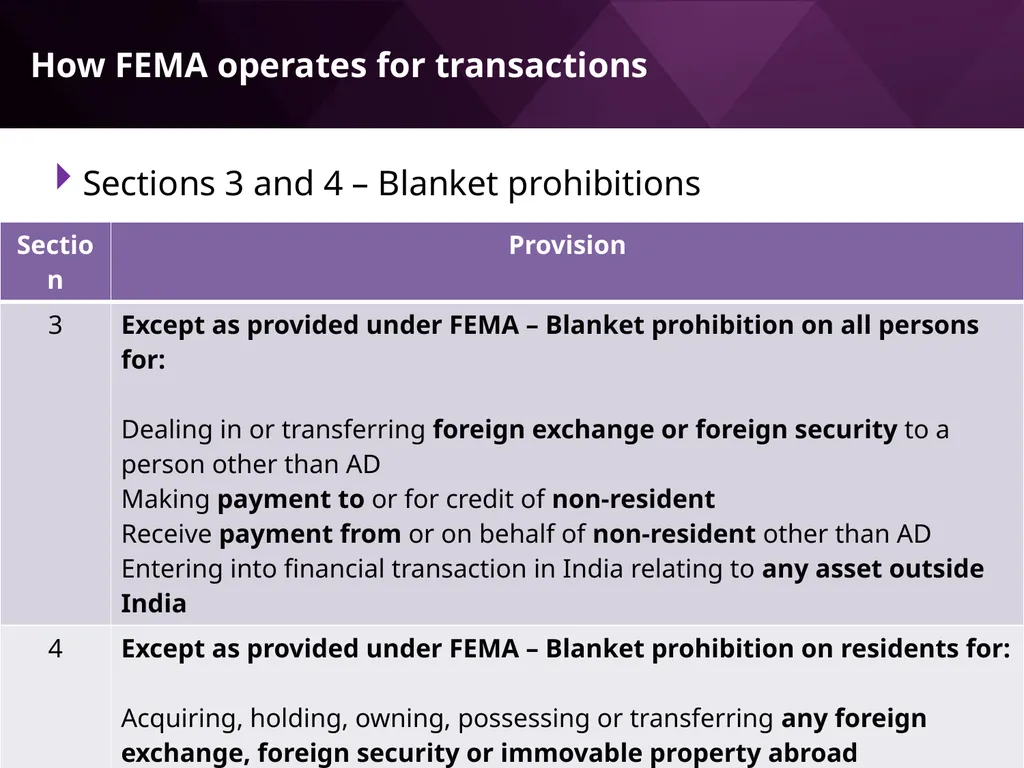
slide9. How FEMA operates for transactions 9 CA Rutvik Sanghvi Sections 3 and 4 – Blanket prohibitions<br>
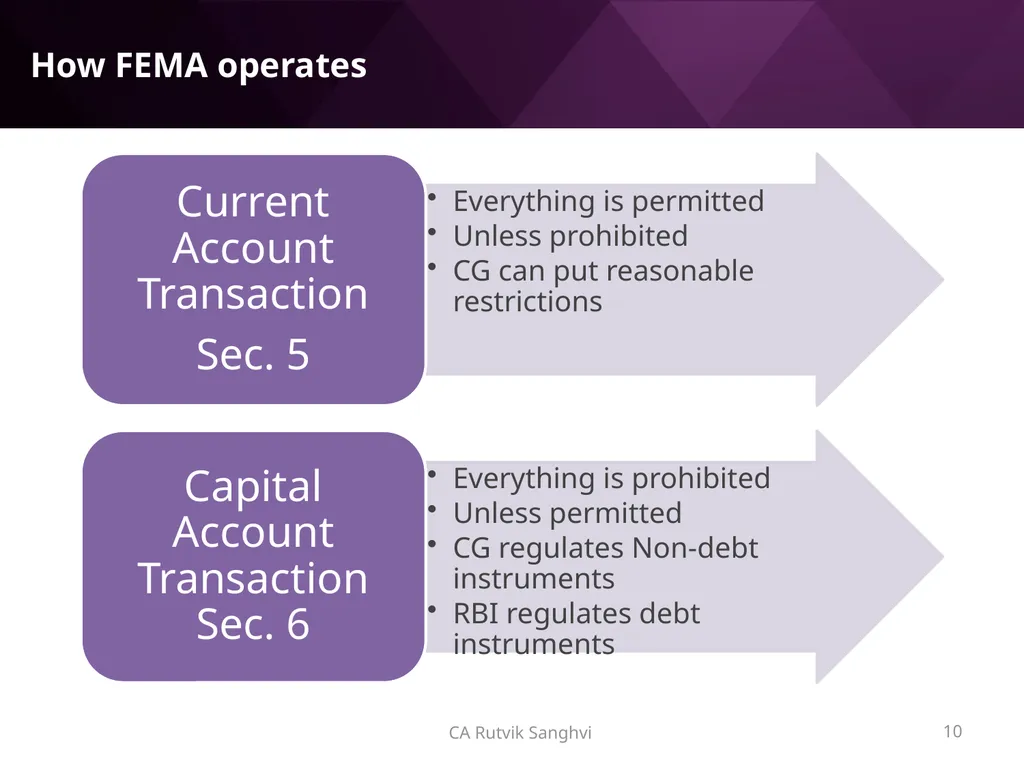
slide10. How FEMA operates 10 CA Rutvik Sanghvi<br>
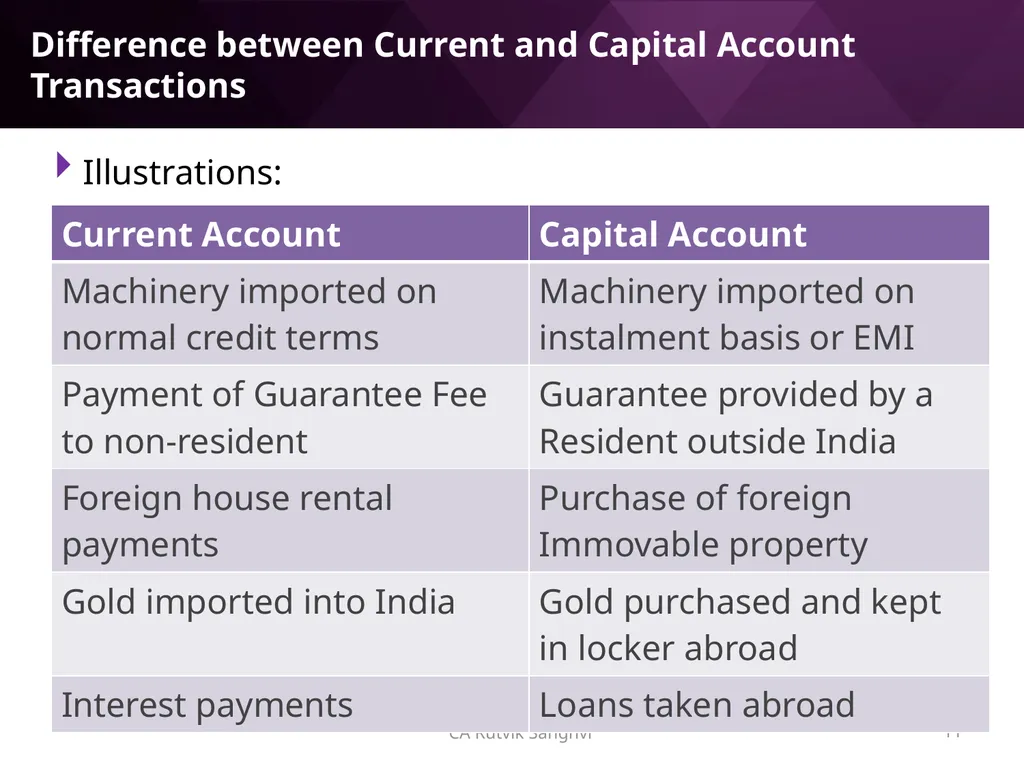
slide11. Difference between Current and Capital Account Transactions Illustrations: CA Rutvik Sanghvi 11<br>
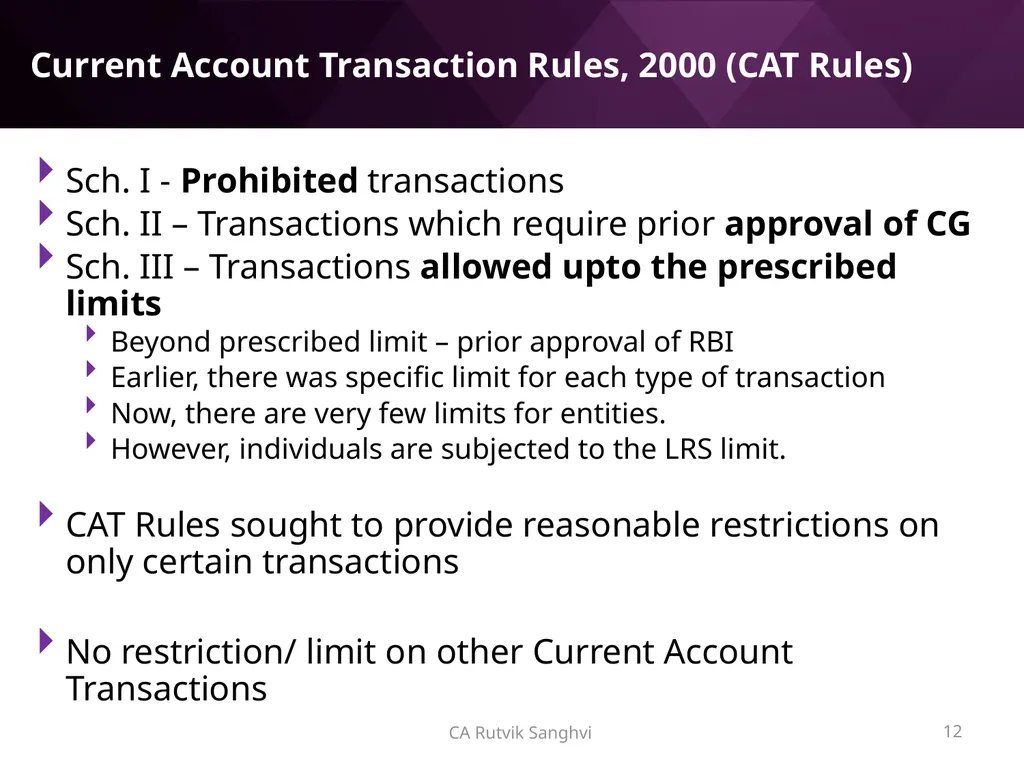
slide12. Current Account Transaction Rules, 2000 (CAT Rules) Sch. I - Prohibited transactions
Sch. II – Transactions which require prior approval of CG
Sch. III – Transactions allowed upto the prescribed limits
Beyond prescribed limit – prior approval of RBI
Earlier, there was specific limit for each type of transaction
Now, there are very few limits for entities.
However, individuals are subjected to the LRS limit.
CAT Rules sought to provide reasonable restrictions on only certain transactions
No restriction/ limit on other Current Account Transactions 12 CA Rutvik Sanghvi<br>
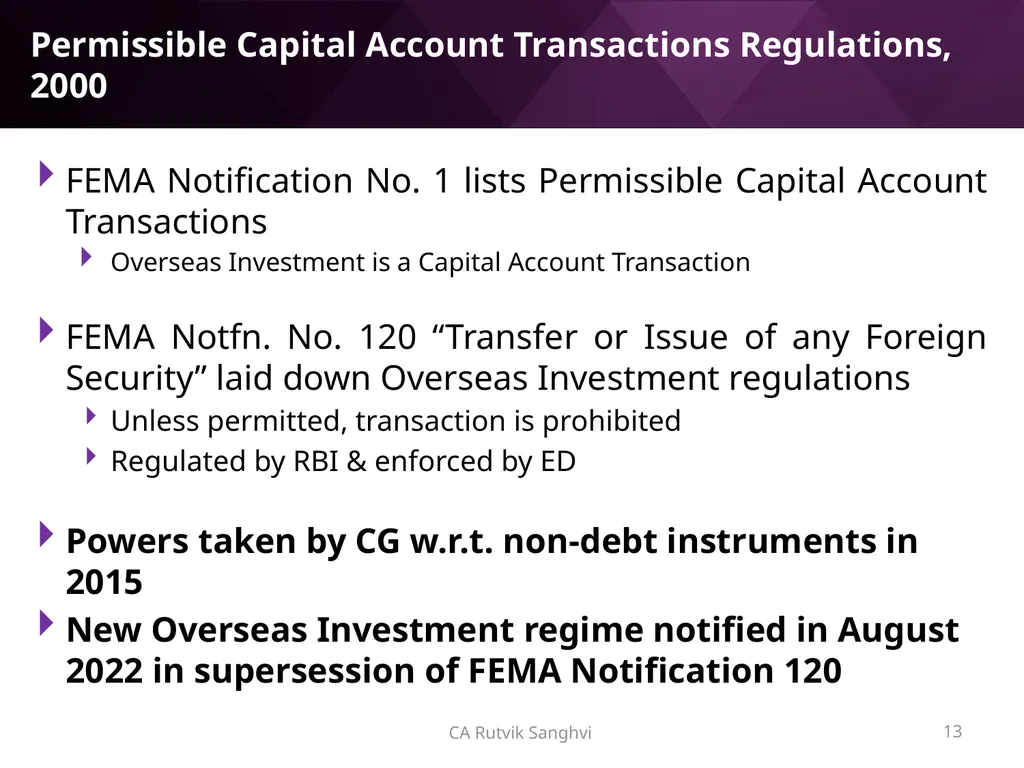
slide13. Permissible Capital Account Transactions Regulations, 2000 FEMA Notification No. 1 lists Permissible Capital Account Transactions
Overseas Investment is a Capital Account Transaction
FEMA Notfn. No. 120 “Transfer or Issue of any Foreign Security” laid down Overseas Investment regulations
Unless permitted, transaction is prohibited
Regulated by RBI & enforced by ED
Powers taken by CG w.r.t. non-debt instruments in 2015
New Overseas Investment regime notified in August 2022 in supersession of FEMA Notification 120 13 CA Rutvik Sanghvi<br>
slide14. Liberalised Remittance Scheme<br>
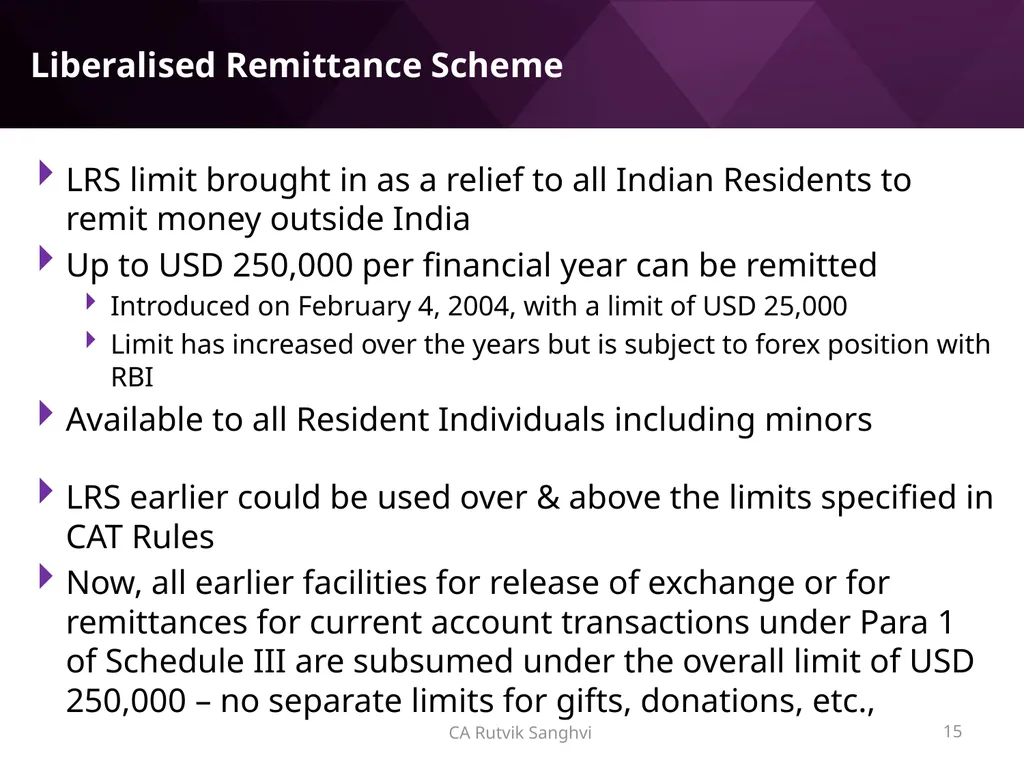
slide15. Liberalised Remittance Scheme LRS limit brought in as a relief to all Indian Residents to remit money outside India
Up to USD 250,000 per financial year can be remitted
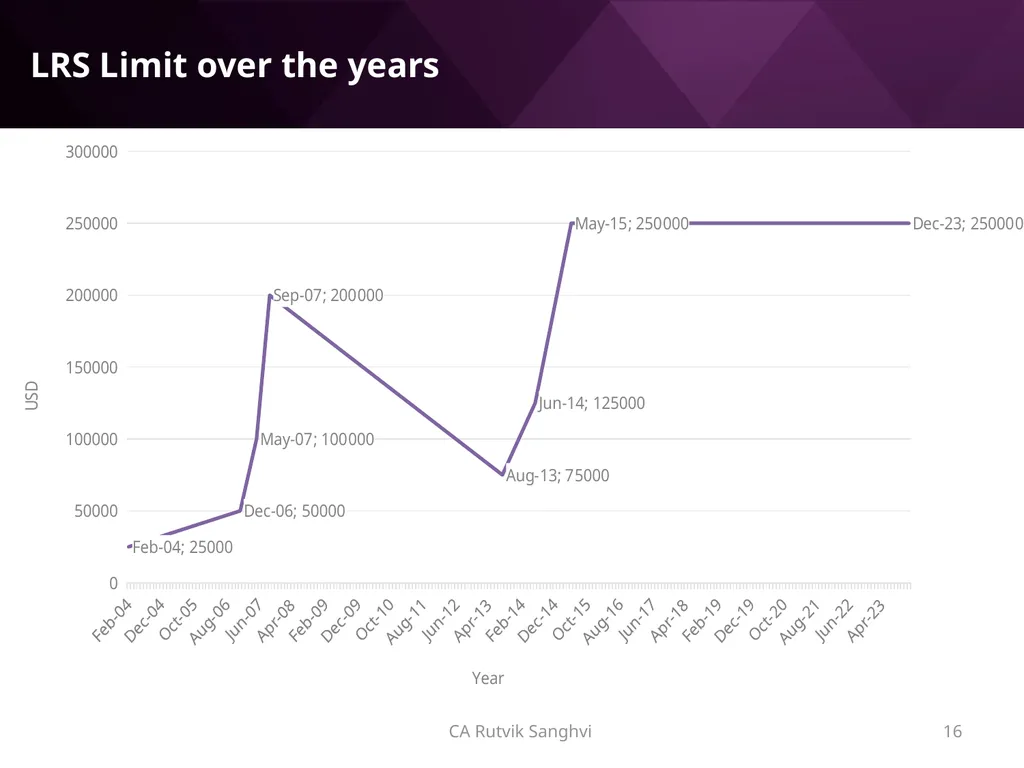
Introduced on February 4, 2004, with a limit of USD 25,000
Limit has increased over the years but is subject to forex position with RBI
Available to all Resident Individuals including minors
LRS earlier could be used over & above the limits specified in CAT Rules
Now, all earlier facilities for release of exchange or for remittances for current account transactions under Para 1 of Schedule III are subsumed under the overall limit of USD 250,000 – no separate limits for gifts, donations, etc., 15 CA Rutvik Sanghvi<br>
slide16. LRS Limit over the years CA Rutvik Sanghvi 16<br>
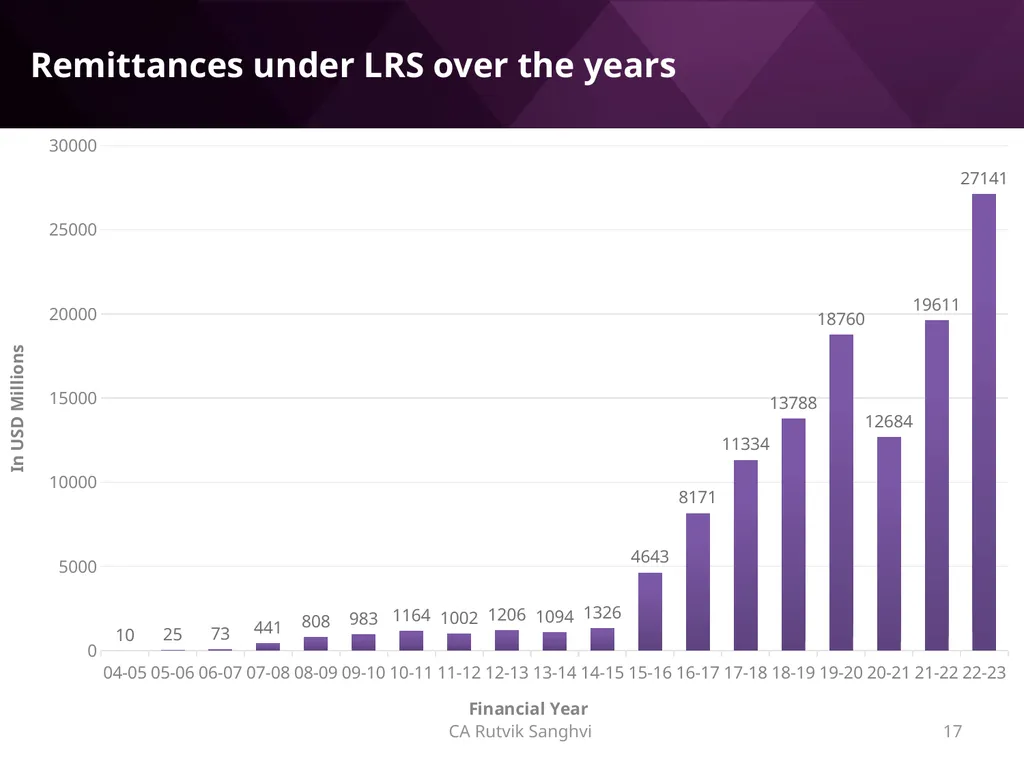
slide17. Remittances under LRS over the years CA Rutvik Sanghvi 17<br>
slide18. LRS - Prohibitions LRS prohibited:
For remittance to FATF identified countries as “non co-operative”
Presently only Iran and North Korea
Prohibition for remittance to Mauritius, Pakistan, Nepal, Bhutan removed though FAQs silent about capital account transactions
For any purpose specifically prohibited under Schedule-I (like purchase of lottery tickets/sweep stakes, proscribed magazines, etc.) or any restricted items under Schedule II of CAT Rules
For remittance from India for margins or margin calls to overseas exchanges / overseas counterparty
For remittance for trading in foreign exchange abroad.
For remittances directly or indirectly to those individuals and entities identified as posing significant risk of committing acts of terrorism
For purchase of FCCBs issued by Indian companies in the overseas secondary market CA Rutvik Sanghvi 18<br>
slide19. LRS Prohibitions contd… Remittance must be out of funds belonging to remitter
Gifts received can be remitted
Once gifted money belongs to remitter - no prohibition in sending funds under LRS
Major issue leading to tax department queries and hence TCS!
Cannot be out of loaned funds?
Master Direction - Banks prohibited from providing credit facilities to facilitate capital account remittances under LRS Scheme
FAQ 16 – Credit facilities allowed for Current Account transactions
What about borrowing from private parties for current account transactions like education & medical expenses
Practically allowed and happening CA Rutvik Sanghvi 19<br>
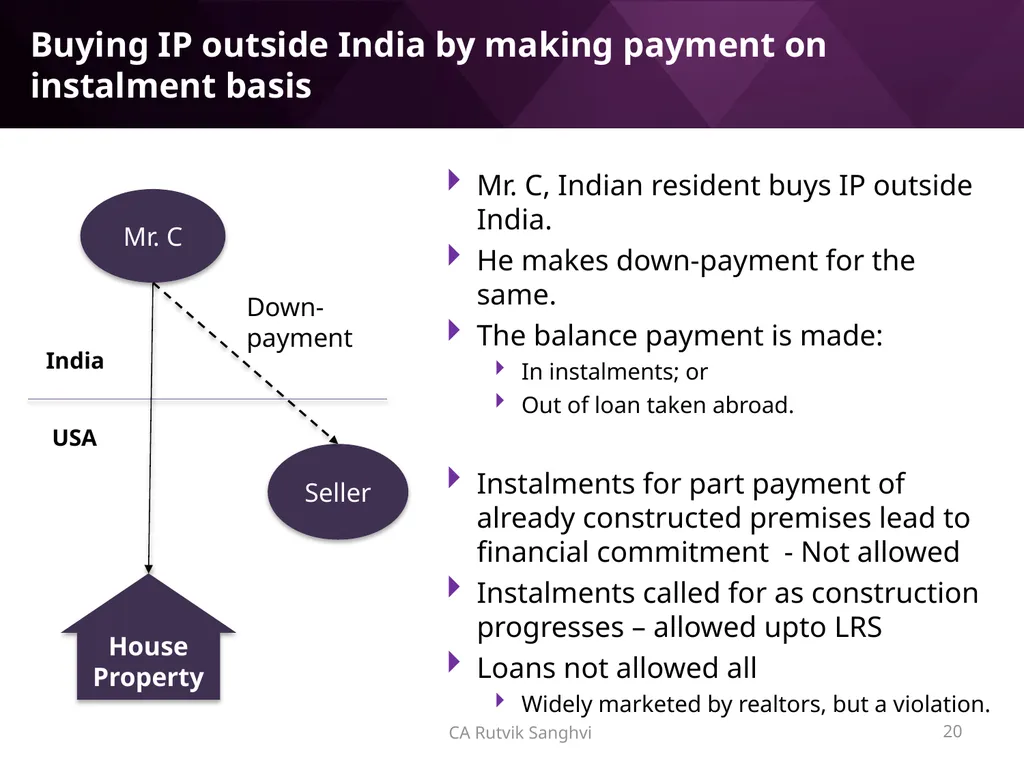
slide20. Mr. C, Indian resident buys IP outside India.
He makes down-payment for the same.
The balance payment is made:
In instalments; or
Out of loan taken abroad.
Instalments for part payment of already constructed premises lead to financial commitment - Not allowed
Instalments called for as construction progresses – allowed upto LRS
Loans not allowed all
Widely marketed by realtors, but a violation. Seller Mr. C India USA Down-payment CA Rutvik Sanghvi 20 House Property Buying IP outside India by making payment on instalment basis<br>
slide21. Pre-LRS position Current Account Transactions (CAT) Rules under Schedule I prohibited and Schedule II allowed only with prior approval of Government specified transactions
Current Account Transactions under Schedule III allowed upto specified limits. Above that, only with RBI Permission
CAT Rules sought to provide restrictions on only certain transactions
Other than above transactions, no restriction or limit on any Current Account Transaction
All Capital Account transactions restricted
Allowed only as specified under Notifications issued by RBI under Section 6 of FEMA, now by Government directly
LRS sought to provide relief from these restrictions up to LRS Limit
Now both restrictions on Current Account Transactions and relief for Capital Account Transactions covered under LRS
Leads to confusion and incorrect application of India’s clear position on Full Current Account Convertibility CA Rutvik Sanghvi 21<br>
slide22. Liberalised Remittance Scheme – Flip Flop Policy LRS when introduced was with clear objective to allow Resident Individuals to remit funds within LRS limit for “any purpose”:
For any Current Account Transaction; or
For any Capital Account Transaction; or
For a combination of both!
Funds up to the limit would be partial capital account convertibility
Can be used to purchase any asset outside India without approval of RBI
Limit of LRS was in addition to limit under Schedule III CA Rutvik Sanghvi 22<br>
slide23. Liberalised Remittance Scheme – Flip Flop Policy Famous Quotes:
RBI Deputy Governor: “We are flush with funds. Use LRS for any purpose – you can as well throw the remitted funds from the Alps.”
In 2004 forex reserves were around USD 100 Billion
RBI Governor Dr. Y V Reddy in his book “Advice & Dissent” quotes Mr. Jaswant Singh, then FM:
“Go and conquer the world, we will be your supporters.”
“This is a no-questions asked window and was in addition to all the existing facilities.”
“The oppressive forex regime that had haunted individuals in India since 1957 was put to an end on 19 February 2004” CA Rutvik Sanghvi 23<br>
slide24. Liberalised Remittance Scheme – Flip Flop Policy Drastic change in position brought in from May 2007
LRS can be used to remit for any ‘permissible’ current or capital account transaction or a combination of both
No guidance on what is ‘permissible’ transaction in 2007
Paradoxical situation as LRS was introduced to allow transactions which otherwise required prior approval!
Permissible capital account transactions under LRS specified only in 2015 as:
Opening of foreign currency account abroad with a bank;
Purchase of property abroad;
Making investments abroad;
Setting up Wholly owned subsidiaries and Joint Ventures abroad;
Extending loans including loans in Indian Rupees to Non-resident Indians (NRIs) who are relatives as defined in Companies Act, 2013. CA Rutvik Sanghvi 24<br>
slide25. LRS - “Current” Account Transactions LRS specifies “permissible” current account transactions
(i) Private visits to any country (except Nepal and Bhutan).
(ii) Gift or donation.
(iii) Going abroad for employment.
(v) Maintenance of close relatives abroad.
(vi) Travel for business or attending a conference or specialised training; or for meeting expenses for meeting medical expenses, or check-up abroad; or for accompanying as attendant to a patient going abroad for medical treatment/ check-up.
(vii) Expenses in connection with medical treatment abroad.
(viii) Studies abroad.
(ix) Any other current account transaction CA Rutvik Sanghvi 25<br>
slide26. LRS - “Current” Account Transactions Limits for Gifts and Donations subsumed under LRS limit
Gift of funds by one resident to another resident outside India not allowed
Gift or donation to non-residents is allowed
But Gift to NRI’s NRO and NRE Account included within LRS limit
Gift of shares limited to USD 50,000 CA Rutvik Sanghvi 26<br>
slide27. LRS - “Capital” Account Transactions Permissible Capital Account Transactions under LRS at present are:
Opening of foreign currency account abroad with a bank;
Acquisition of immovable property abroad
Overseas Direct Investment (ODI)
Overseas Portfolio Investment (OPI)
Extending loans including loans in Indian Rupees to Non-resident Indians (NRIs) who are relatives as defined in Companies Act, 2013. CA Rutvik Sanghvi 27<br>
slide28. LRS - “Capital” Account Transactions Other Capital Account transactions not allowed:
Asset purchased outside India, unless brought into India, lead to capital account transactions
Gold
Art
Long-term lease tantamount to purchase of asset also covered
Guarantees
“Property” mentioned in CAT Rules does not mean all assets
Intention is to cover only immovable property CA Rutvik Sanghvi 28<br>
slide29. Liberalised Remittance Scheme - Issues Can assets be kept outside India?
What about inheritance?
What about change of residence?
Does income earned on such assets have to be remitted back to India?
Income and sum remitted need not be brought back into India and can be reinvested overseas CA Rutvik Sanghvi 29<br>
slide30. LRS – Beyond limits? Prior Approval needed from RBI for remittance beyond LRS limit
Possible if circumstances warrant need for enhanced remittance
Approval not required to remit more than $ 250,000 in following cases:
Emigration:
Only towards meeting incidental expenses in country of immigration.
Not for earning points or credits to become eligible for immigration by way of overseas investments in government bonds; land; commercial enterprise, etc.
Medical treatment:
Based on estimate from a doctor in India or from a hospital/ doctor abroad.
A resident who has fallen sick after proceeding abroad also covered
Additional USD 250,000 per FY allowed to the person accompanying as attendant to a patient going abroad for medical treatment/ check-up
Education: Based on fee estimate from institution/ university abroad
Banks might ask for more documentation CA Rutvik Sanghvi 30<br>
slide31. Permissible capital account transaction by an individual under LRS:
(iii) extending loans including loans in INR to NRIs who are relatives as defined in Companies Act, 2013
OR
(iii) extending loans, including loans in INR, to NRIs who are relatives as defined in Companies Act, 2013
FEMA 3(R) – Borrowing & Lending Regulations
Resident individuals allowed to grant rupee loans to NRI/ OCI relative upto LRS limit subject to prescribed terms and conditions.
Silent on loans by resident individuals to non-residents
Specific relief for providing loans to NRI relatives in INR now considered as the only permissible transaction!
Do Borrowing & Lending Regulations override LRS?
LRS was in addition to all existing facilities! CA Rutvik Sanghvi 31 Extending loans including loans in INR to NRI relatives<br>
slide32. Recent Changes in LRS<br>
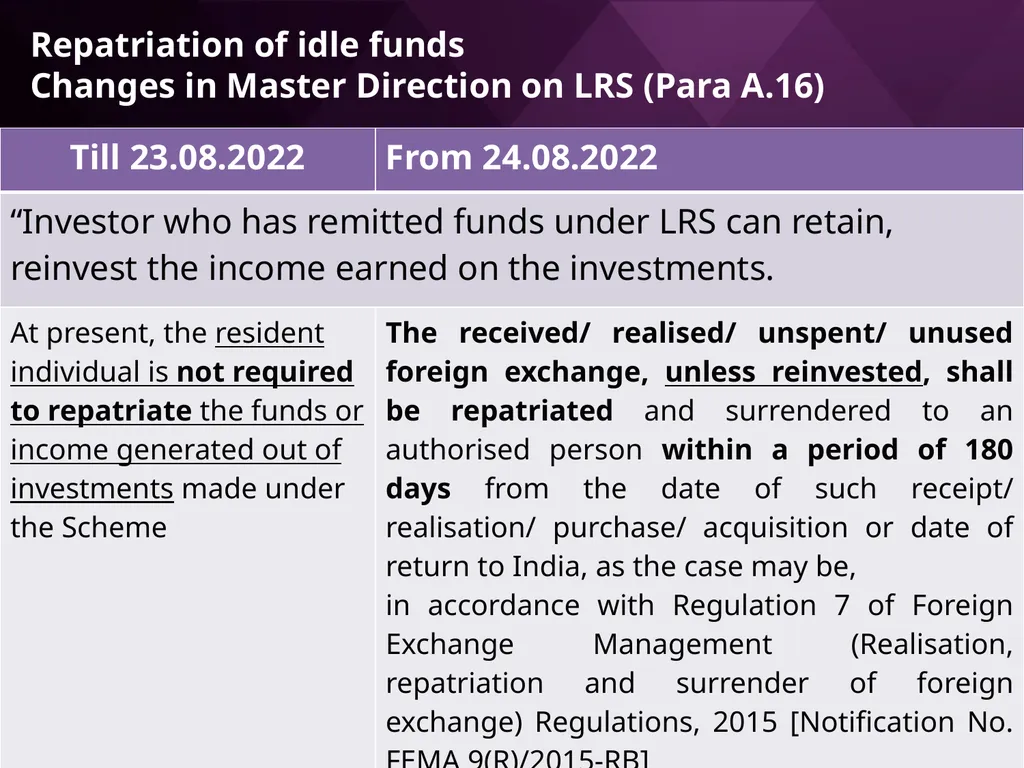
slide33. CA Rutvik Sanghvi 33 Repatriation of idle funds Changes in Master Direction on LRS (Para A.16)<br>
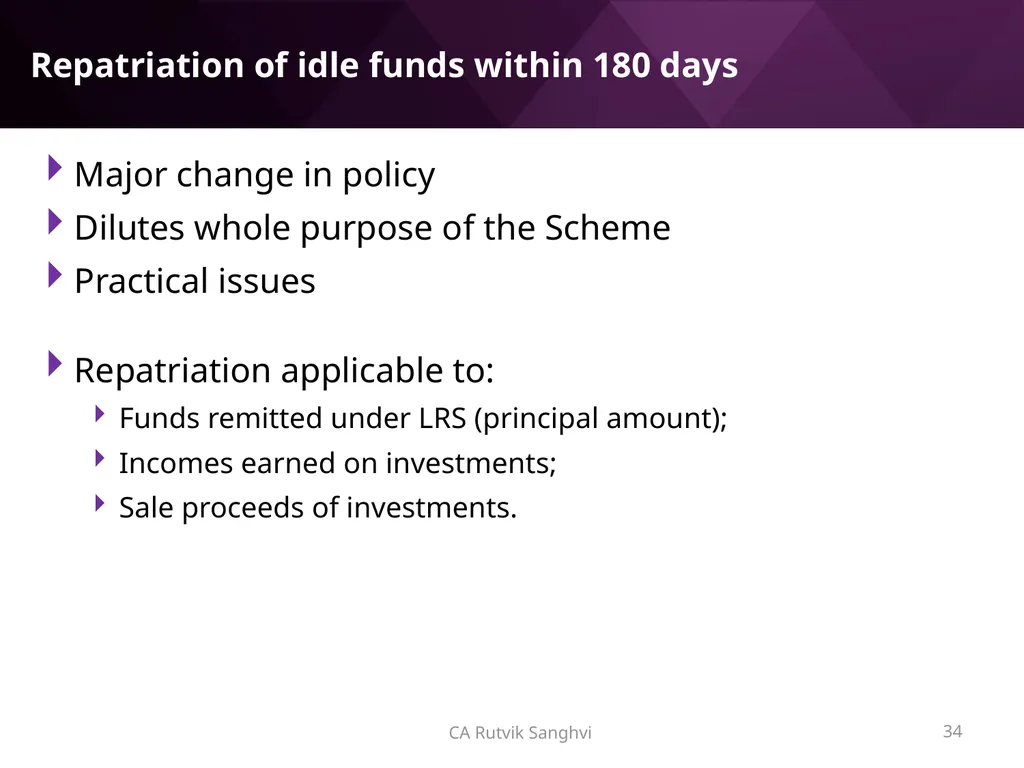
slide34. Major change in policy
Dilutes whole purpose of the Scheme
Practical issues
Repatriation applicable to:
Funds remitted under LRS (principal amount);
Incomes earned on investments;
Sale proceeds of investments. CA Rutvik Sanghvi 34 Repatriation of idle funds within 180 days<br>
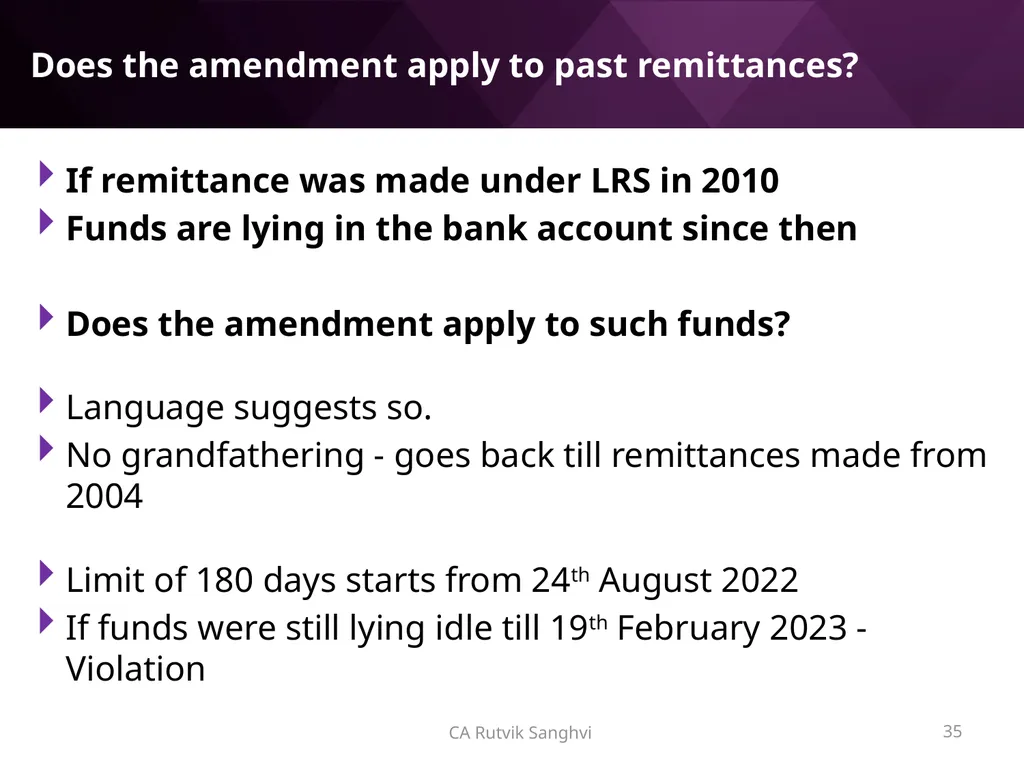
slide35. If remittance was made under LRS in 2010
Funds are lying in the bank account since then
Does the amendment apply to such funds?
Language suggests so.
No grandfathering - goes back till remittances made from 2004
Limit of 180 days starts from 24th August 2022
If funds were still lying idle till 19th February 2023 - Violation CA Rutvik Sanghvi 35 Does the amendment apply to past remittances?<br>
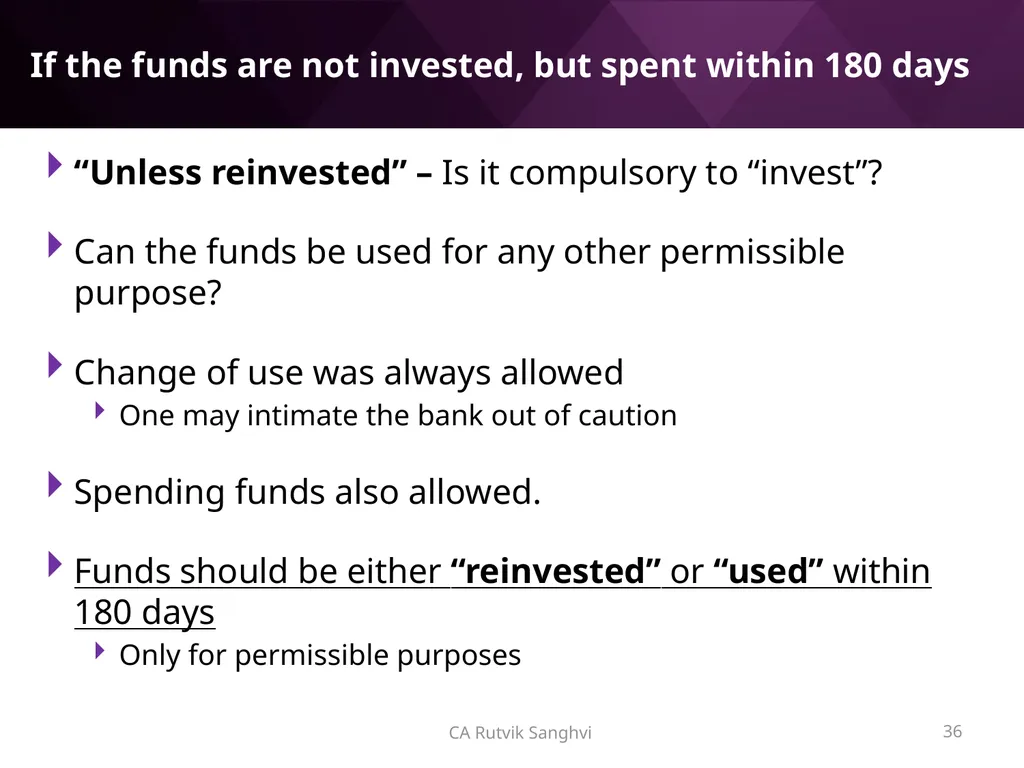
slide36. “Unless reinvested” – Is it compulsory to “invest”?
Can the funds be used for any other permissible purpose?
Change of use was always allowed
One may intimate the bank out of caution
Spending funds also allowed.
Funds should be either “reinvested” or “used” within 180 days
Only for permissible purposes CA Rutvik Sanghvi 36 If the funds are not invested, but spent within 180 days<br>
slide37. If funds are not used/ invested within 180 days: Violation.
Violation needs to be regularised first.
To regularise means to take corrective action – what should have been done earlier.
Does it mean reinvest/ use the funds after the limit is breached??
Allowing investment or utilisation after 180 days defeats the whole purpose of amendment
One will have to repatriate the funds back to India and utilise LRS limit of the respective year to again remit the funds
Violation requires compounding after regularisation. CA Rutvik Sanghvi 37 What if the funds are not invested/ utilised within 180 days?<br>
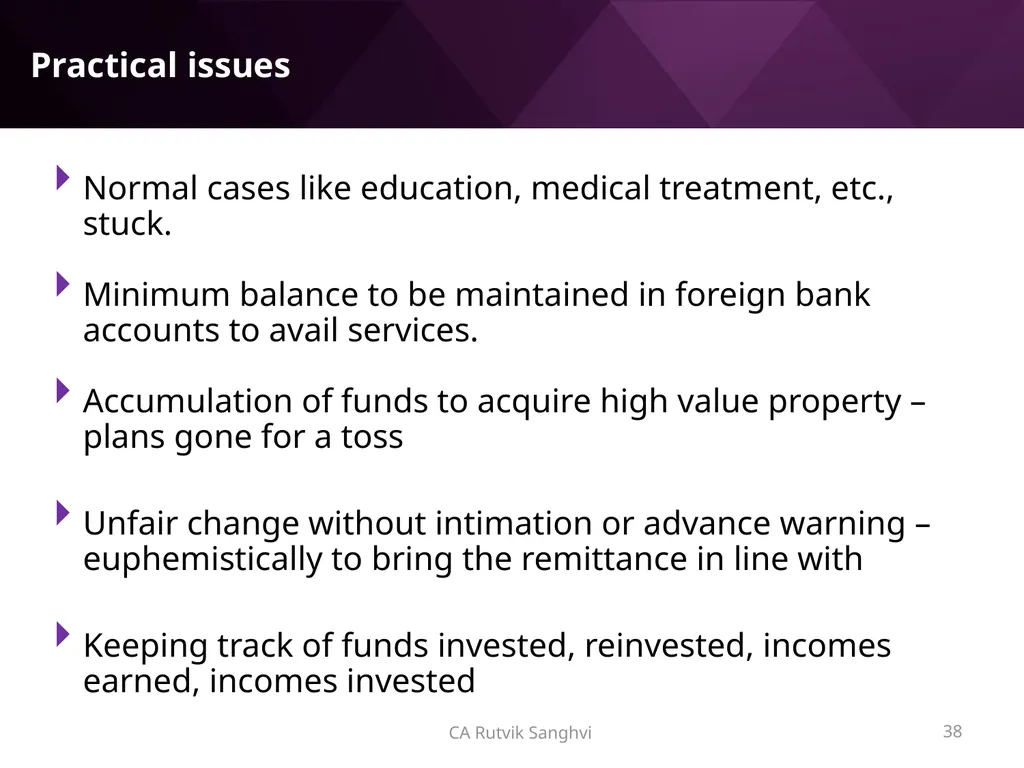
slide38. Normal cases like education, medical treatment, etc., stuck.
Minimum balance to be maintained in foreign bank accounts to avail services.
Accumulation of funds to acquire high value property – plans gone for a toss
Unfair change without intimation or advance warning – euphemistically to bring the remittance in line with
Keeping track of funds invested, reinvested, incomes earned, incomes invested CA Rutvik Sanghvi 38 Practical issues<br>
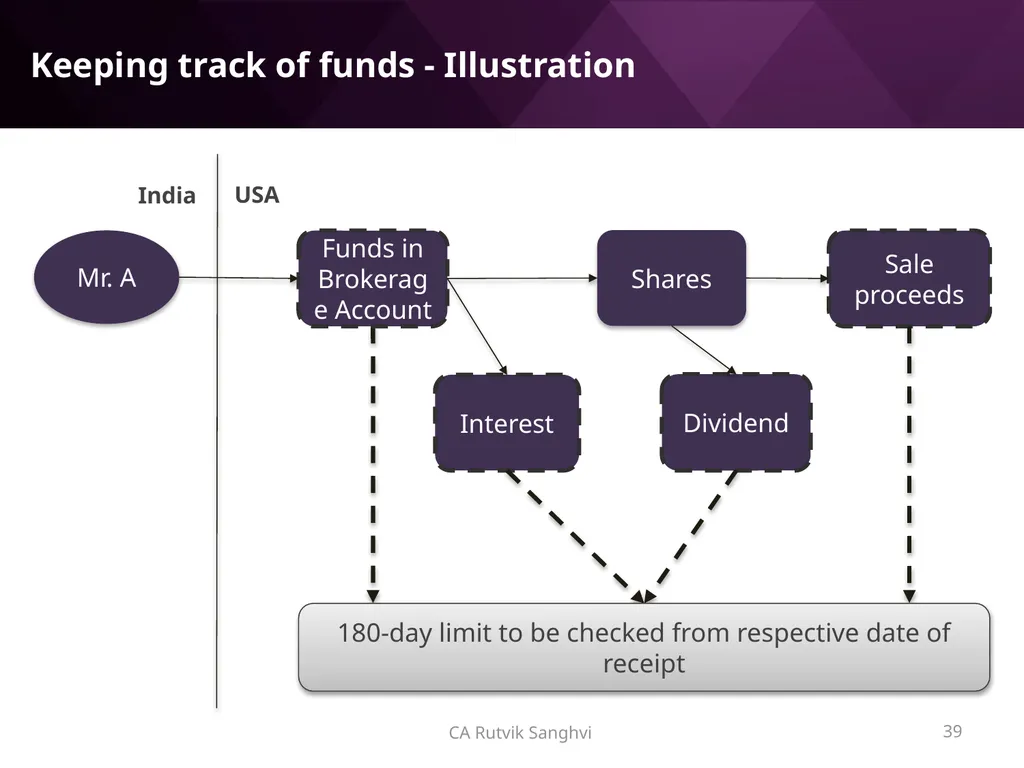
slide39. CA Rutvik Sanghvi 39 Interest Mr. A India USA Dividend Funds in Brokerage Account Shares Sale proceeds 180-day limit to be checked from respective date of receipt Keeping track of funds - Illustration<br>
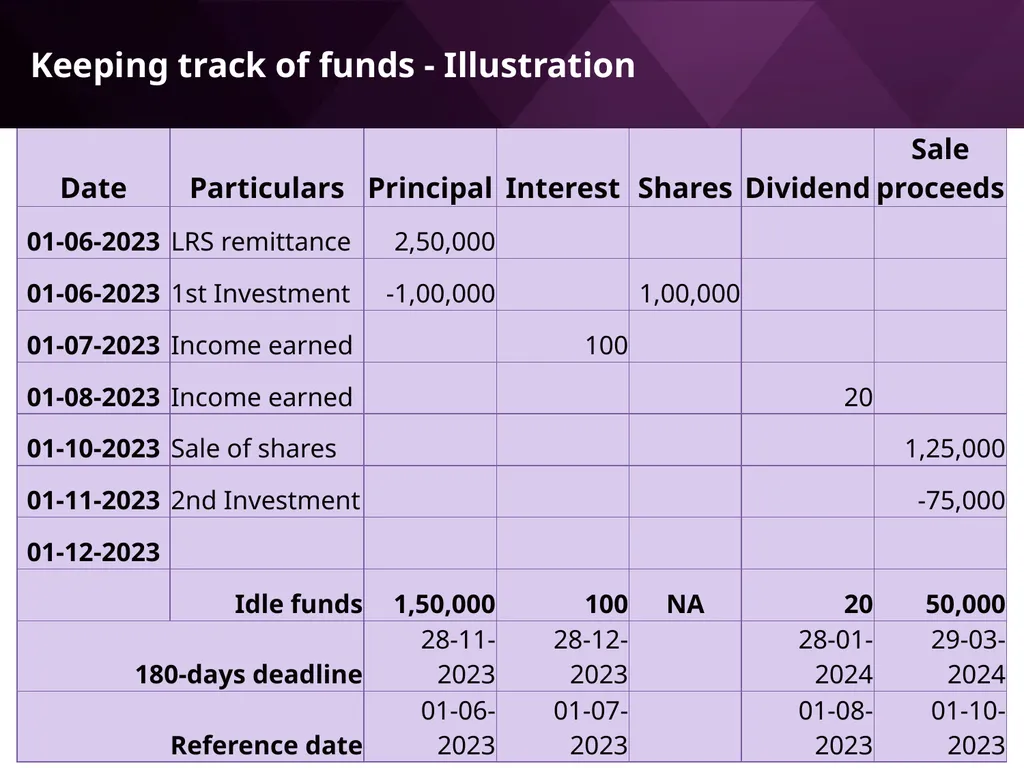
slide40. CA Rutvik Sanghvi 40 Keeping track of funds - Illustration<br>
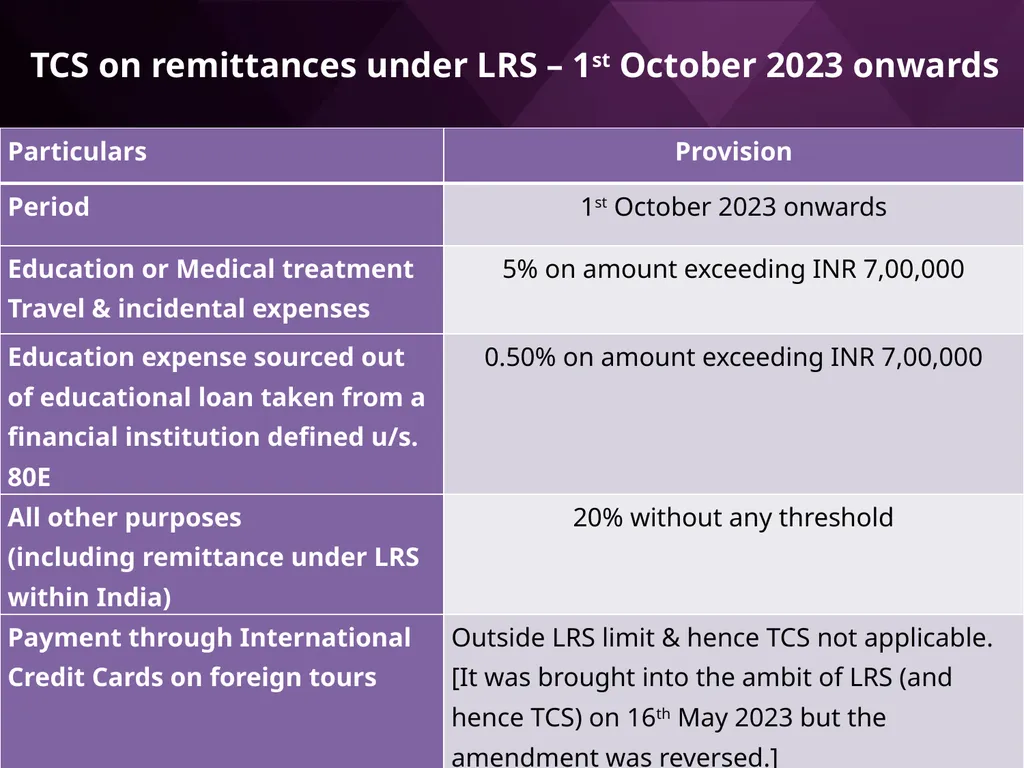
slide41. TCS on remittances under LRS – 1st October 2023 onwards Slide No.: 41 CA Rutvik Sanghvi<br>
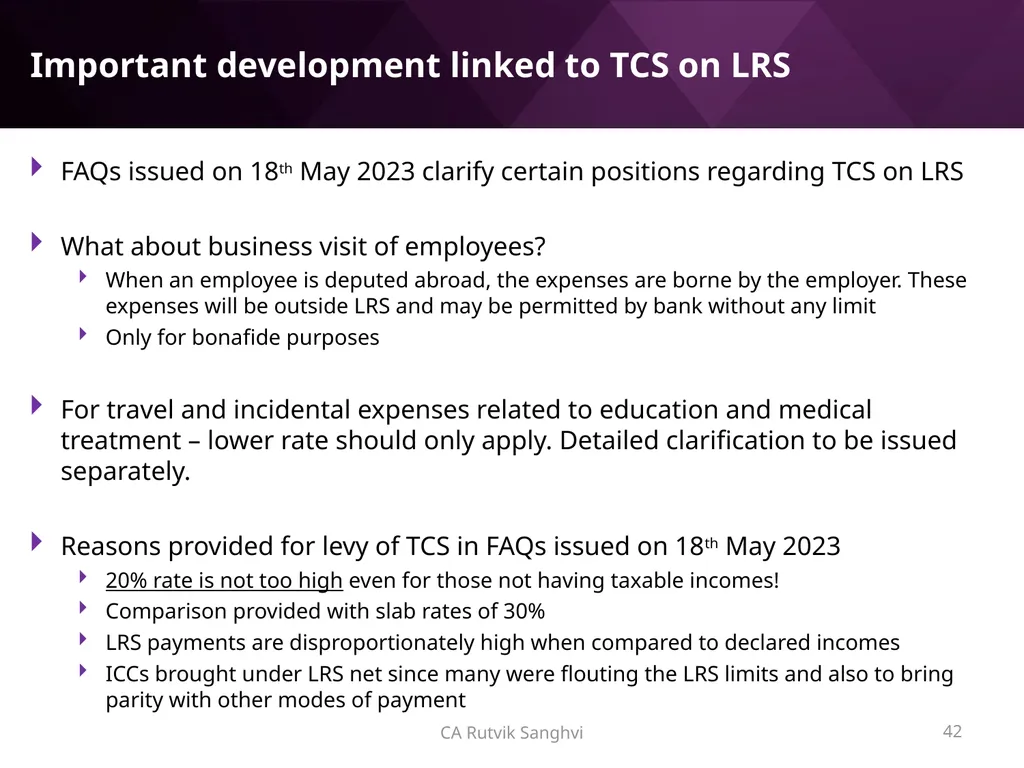
slide42. Important development linked to TCS on LRS FAQs issued on 18th May 2023 clarify certain positions regarding TCS on LRS
What about business visit of employees?
When an employee is deputed abroad, the expenses are borne by the employer. These expenses will be outside LRS and may be permitted by bank without any limit
Only for bonafide purposes
For travel and incidental expenses related to education and medical treatment – lower rate should only apply. Detailed clarification to be issued separately.
Reasons provided for levy of TCS in FAQs issued on 18th May 2023
20% rate is not too high even for those not having taxable incomes!
Comparison provided with slab rates of 30%
LRS payments are disproportionately high when compared to declared incomes
ICCs brought under LRS net since many were flouting the LRS limits and also to bring parity with other modes of payment CA Rutvik Sanghvi 42<br>
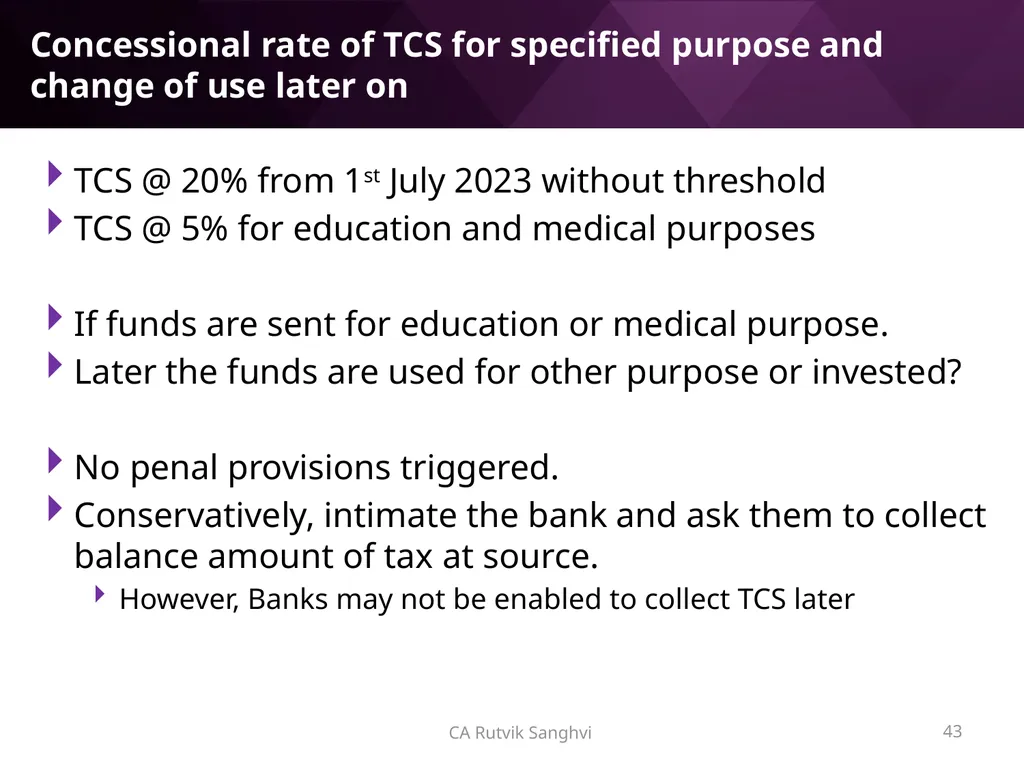
slide43. Concessional rate of TCS for specified purpose and change of use later on TCS @ 20% from 1st July 2023 without threshold
TCS @ 5% for education and medical purposes
If funds are sent for education or medical purpose.
Later the funds are used for other purpose or invested?
No penal provisions triggered.
Conservatively, intimate the bank and ask them to collect balance amount of tax at source.
However, Banks may not be enabled to collect TCS later CA Rutvik Sanghvi 43<br>
slide44. Overseas Investment by Resident Individuals under LRS<br>
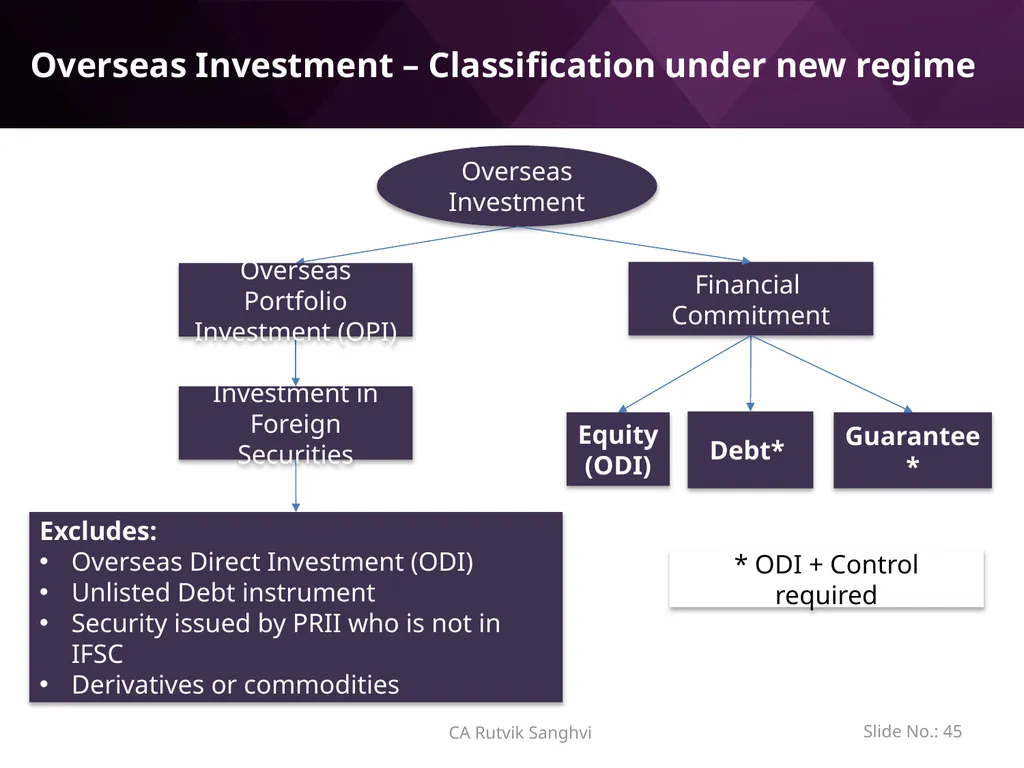
slide45. Overseas Investment – Classification under new regime Slide No.: 45 Investment in Foreign Securities Overseas Investment Equity
(ODI) Debt* Financial Commitment Overseas Portfolio Investment (OPI) Guarantee* Excludes:
Overseas Direct Investment (ODI)
Unlisted Debt instrument
Security issued by PRII who is not in IFSC
Derivatives or commodities * ODI + Control required CA Rutvik Sanghvi<br>
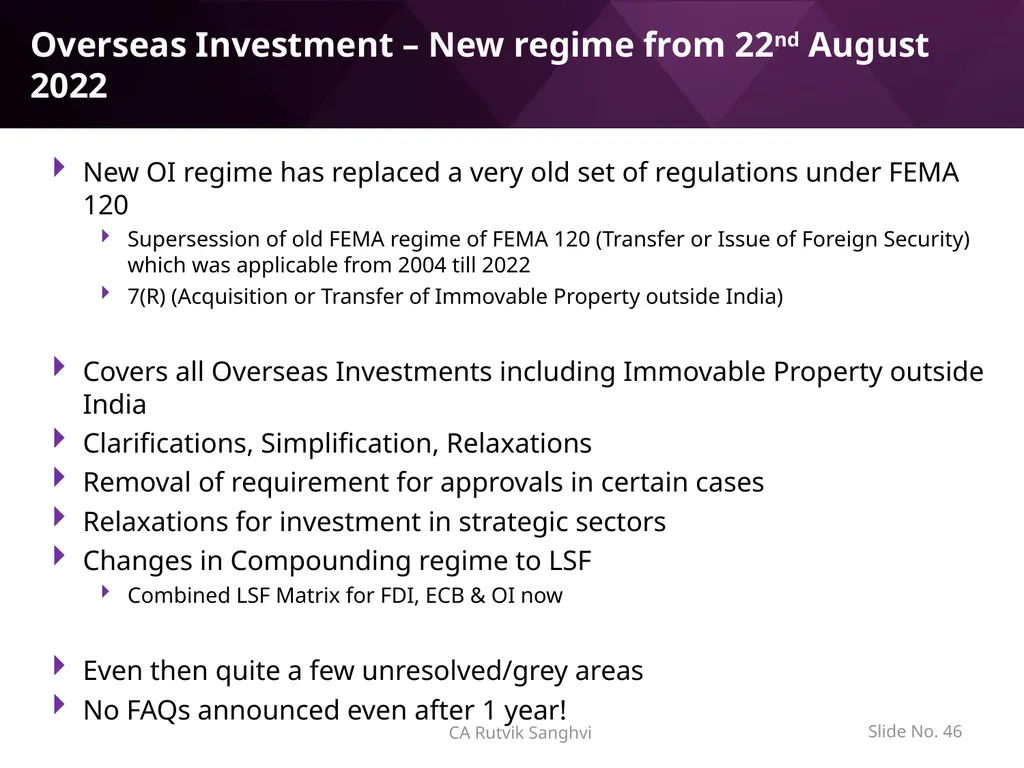
slide46. Overseas Investment – New regime from 22nd August 2022 New OI regime has replaced a very old set of regulations under FEMA 120
Supersession of old FEMA regime of FEMA 120 (Transfer or Issue of Foreign Security) which was applicable from 2004 till 2022
7(R) (Acquisition or Transfer of Immovable Property outside India)
Covers all Overseas Investments including Immovable Property outside India
Clarifications, Simplification, Relaxations
Removal of requirement for approvals in certain cases
Relaxations for investment in strategic sectors
Changes in Compounding regime to LSF
Combined LSF Matrix for FDI, ECB & OI now
Even then quite a few unresolved/grey areas
No FAQs announced even after 1 year! Slide No. 46 CA Rutvik Sanghvi<br>
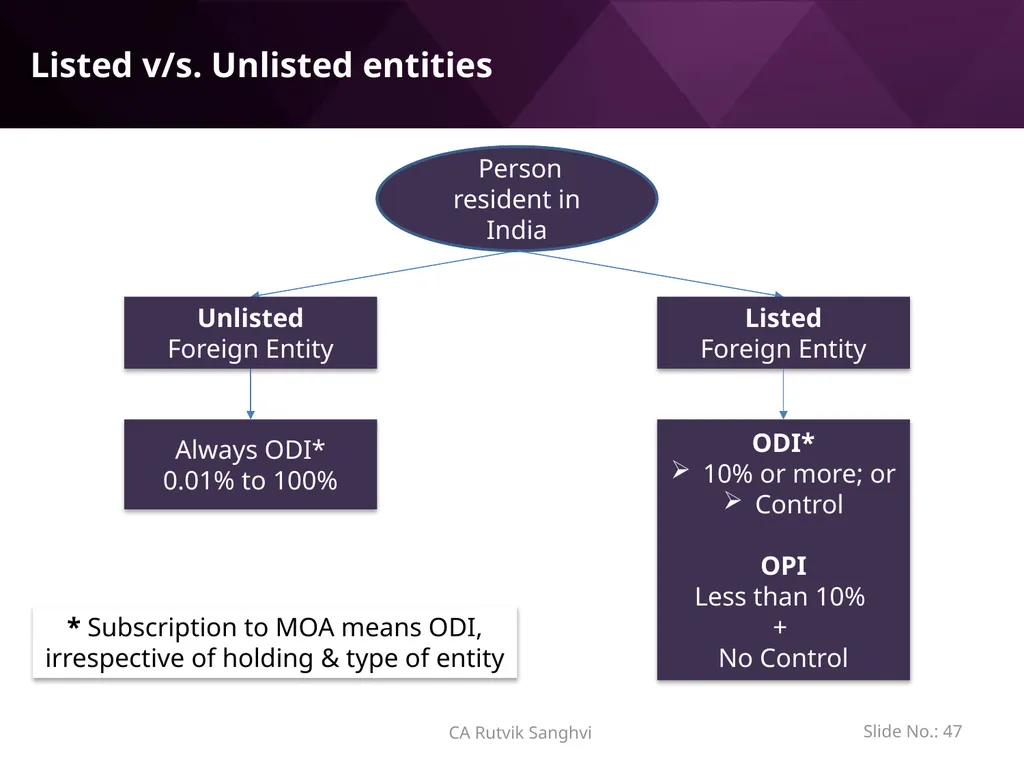
slide47. Listed v/s. Unlisted entities Slide No.: 47 Always ODI*
0.01% to 100% Person resident in India ODI*
10% or more; or
Control
OPI
Less than 10%
+
No Control Listed
Foreign Entity Unlisted
Foreign Entity * Subscription to MOA means ODI,
irrespective of holding & type of entity CA Rutvik Sanghvi<br>
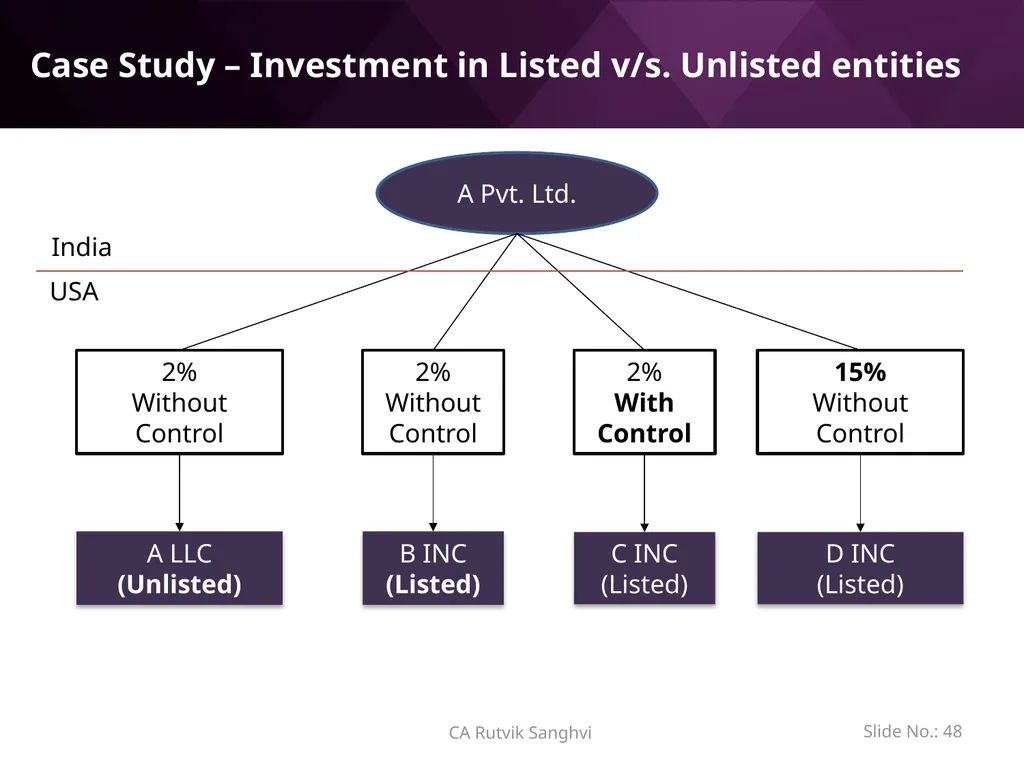
slide48. Case Study – Investment in Listed v/s. Unlisted entities Slide No.: 48 A LLC
(Unlisted) A Pvt. Ltd. B INC
(Listed) C INC
(Listed) D INC
(Listed) 2%
Without Control 2%
Without Control 2%
With Control 15%
Without Control India USA CA Rutvik Sanghvi<br>
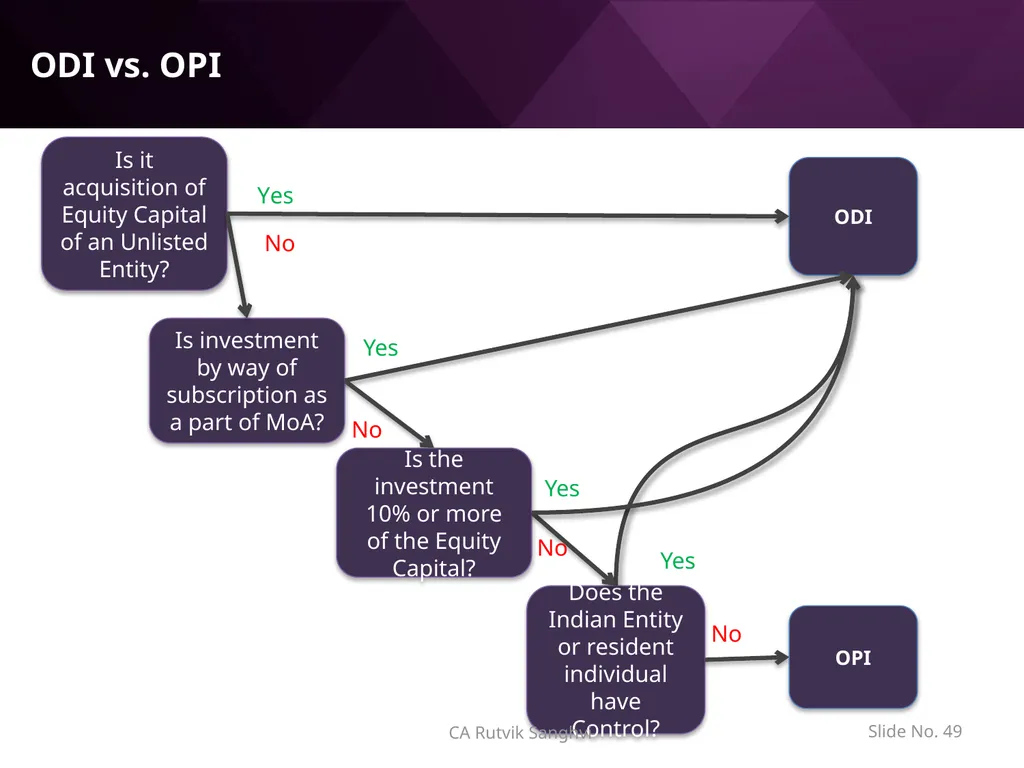
slide49. ODI vs. OPI Slide No. 49 Is investment by way of subscription as a part of MoA? Does the Indian Entity or resident individual have Control? OPI ODI Is it acquisition of Equity Capital of an Unlisted Entity? Is the investment 10% or more of the Equity Capital? CA Rutvik Sanghvi<br>
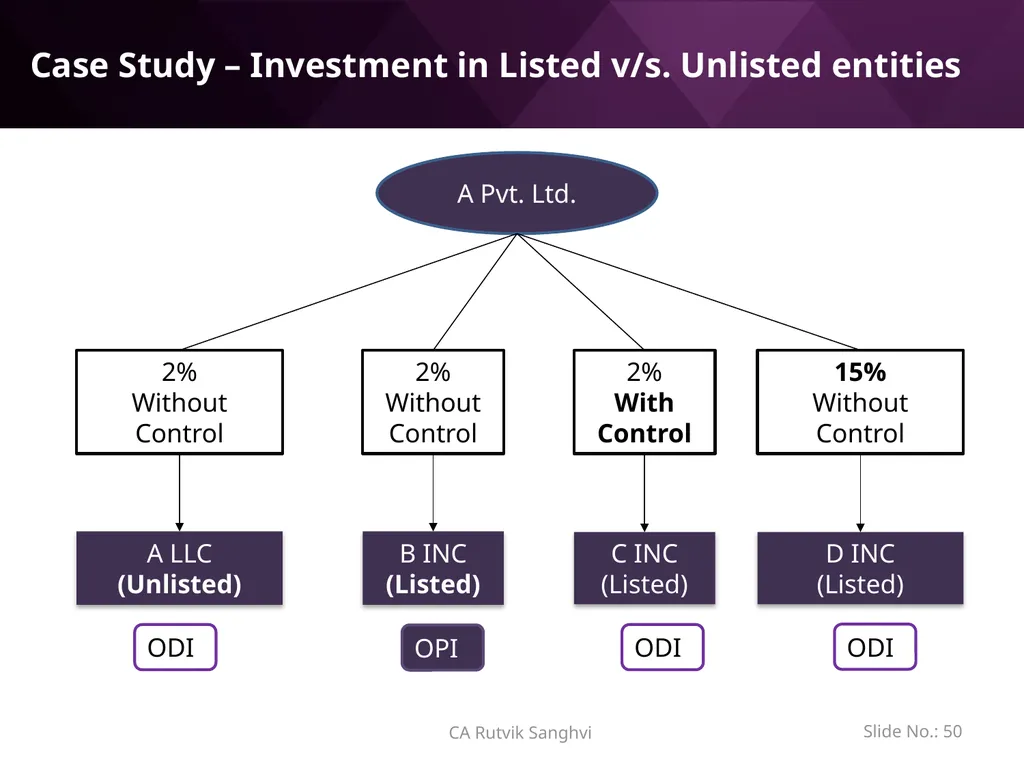
slide50. Case Study – Investment in Listed v/s. Unlisted entities Slide No.: 50 A LLC
(Unlisted) A Pvt. Ltd. B INC
(Listed) C INC
(Listed) D INC
(Listed) 2%
Without Control ODI 2%
Without Control OPI 2%
With Control 15%
Without Control ODI ODI CA Rutvik Sanghvi<br>
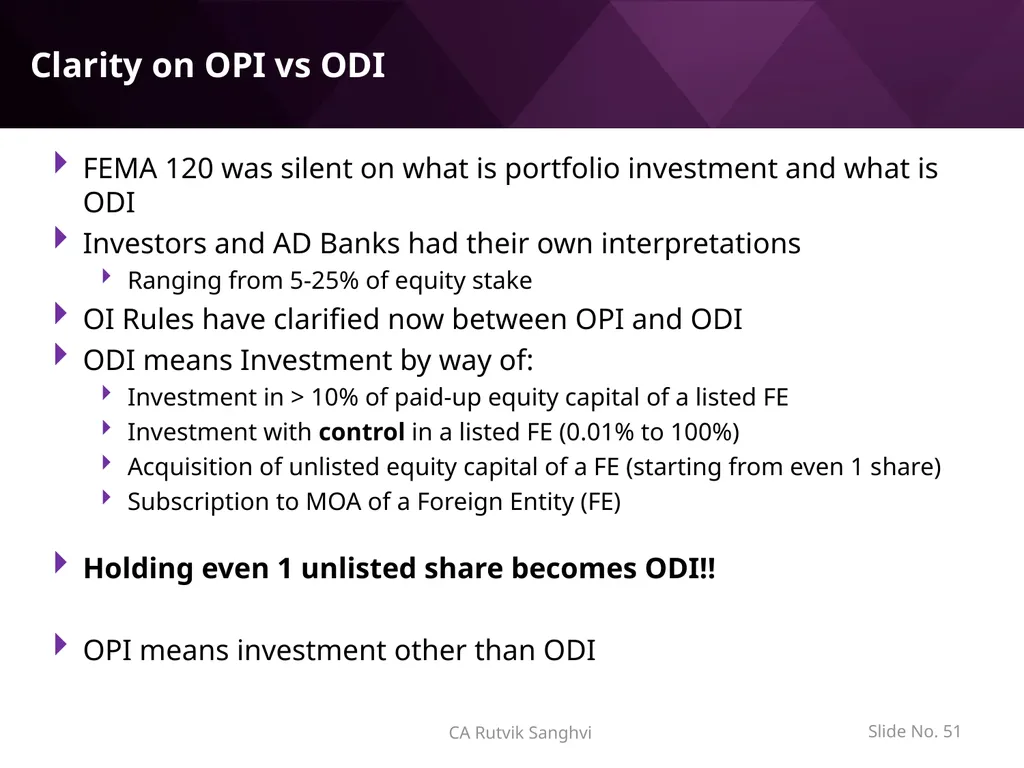
slide51. Clarity on OPI vs ODI FEMA 120 was silent on what is portfolio investment and what is ODI
Investors and AD Banks had their own interpretations
Ranging from 5-25% of equity stake
OI Rules have clarified now between OPI and ODI
ODI means Investment by way of:
Investment in > 10% of paid-up equity capital of a listed FE
Investment with control in a listed FE (0.01% to 100%)
Acquisition of unlisted equity capital of a FE (starting from even 1 share)
Subscription to MOA of a Foreign Entity (FE)
Holding even 1 unlisted share becomes ODI!!
OPI means investment other than ODI Slide No. 51 CA Rutvik Sanghvi<br>
slide52. Important concepts for ODI Slide No.: 52 Important terms – Foreign entity, Financial Commitment, ODI, Subsidiary, Sweat equity shares, Bonafide business activity
Non-applicability of OI Rules in certain cases
No Objection Certificate
Pricing guidelines
Disinvestment alternatives and conditions
Restructuring of foreign entity’s balance sheet
Sectoral prohibitions
Real estate,
Gambling and
Dealing with products linked to INR
Round tripping CA Rutvik Sanghvi<br>
slide53. Important concepts for ODI Slide No.: 53 Start-ups
Financial Services activities
Special reliefs for investments in IFSC
Limit of Financial Commitment – 400% of net worth of Indian entity
Debt and guarantee
Pledge and charge
Deferred consideration
Reporting obligations
Restriction on further investment or disinvestment in case of reporting delays
Late Submission Fees CA Rutvik Sanghvi<br>
slide54. Overseas Portfolio Investment<br>
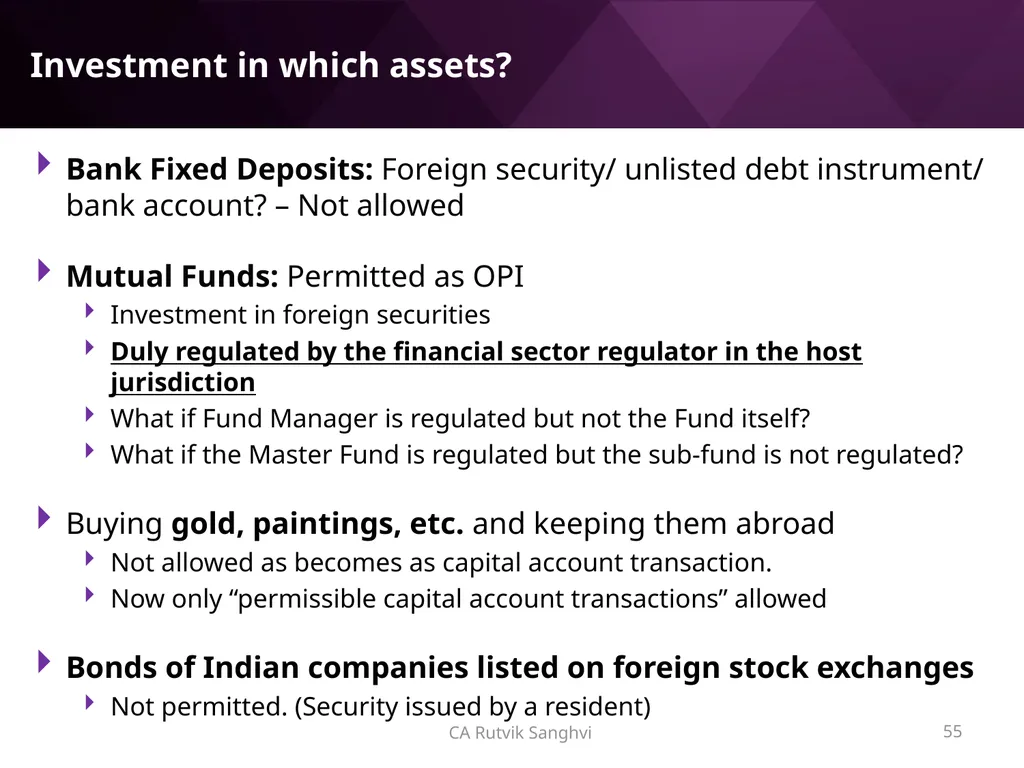
slide55. Bank Fixed Deposits: Foreign security/ unlisted debt instrument/ bank account? – Not allowed
Mutual Funds: Permitted as OPI
Investment in foreign securities
Duly regulated by the financial sector regulator in the host jurisdiction
What if Fund Manager is regulated but not the Fund itself?
What if the Master Fund is regulated but the sub-fund is not regulated?
Buying gold, paintings, etc. and keeping them abroad
Not allowed as becomes as capital account transaction.
Now only “permissible capital account transactions” allowed
Bonds of Indian companies listed on foreign stock exchanges
Not permitted. (Security issued by a resident) CA Rutvik Sanghvi 55 Investment in which assets?<br>
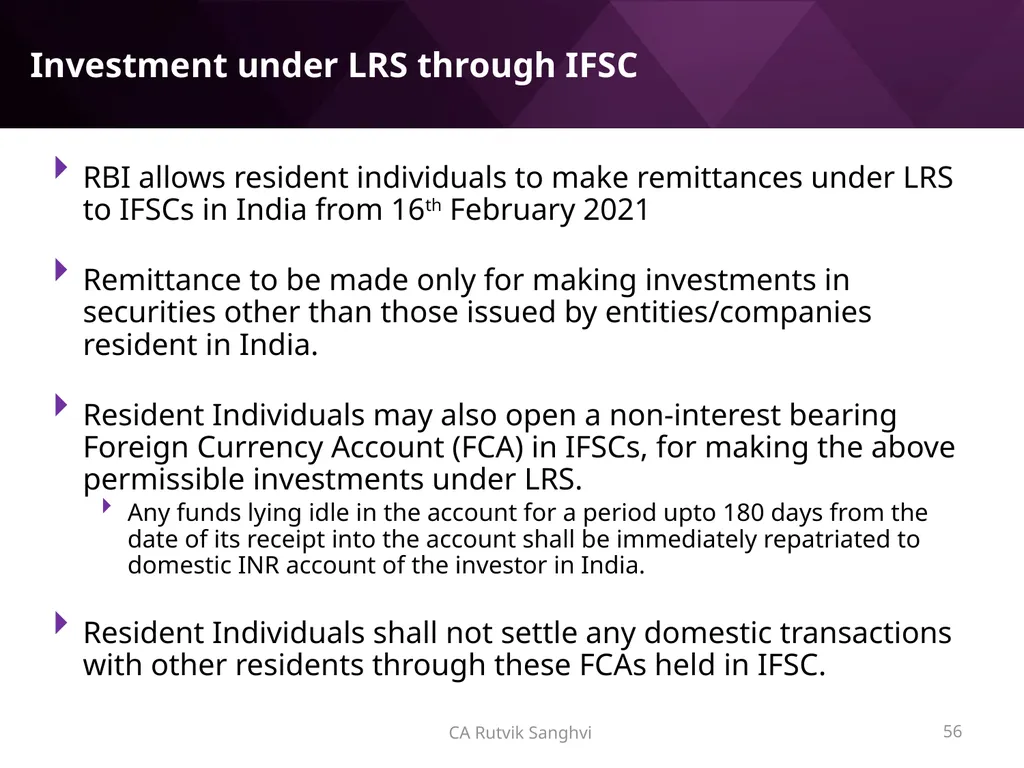
slide56. Investment under LRS through IFSC RBI allows resident individuals to make remittances under LRS to IFSCs in India from 16th February 2021
Remittance to be made only for making investments in securities other than those issued by entities/companies resident in India.
Resident Individuals may also open a non-interest bearing Foreign Currency Account (FCA) in IFSCs, for making the above permissible investments under LRS.
Any funds lying idle in the account for a period upto 180 days from the date of its receipt into the account shall be immediately repatriated to domestic INR account of the investor in India.
Resident Individuals shall not settle any domestic transactions with other residents through these FCAs held in IFSC. CA Rutvik Sanghvi 56<br>
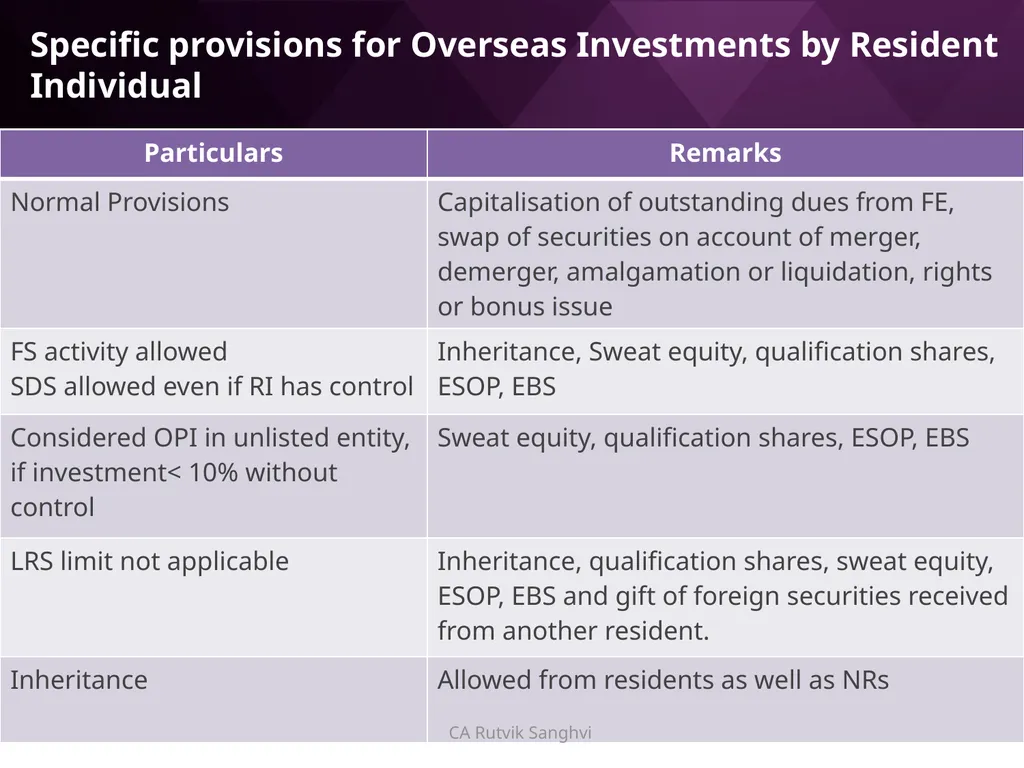
slide57. Specific provisions for Overseas Investments by Resident Individual Slide No.: 57 CA Rutvik Sanghvi<br>
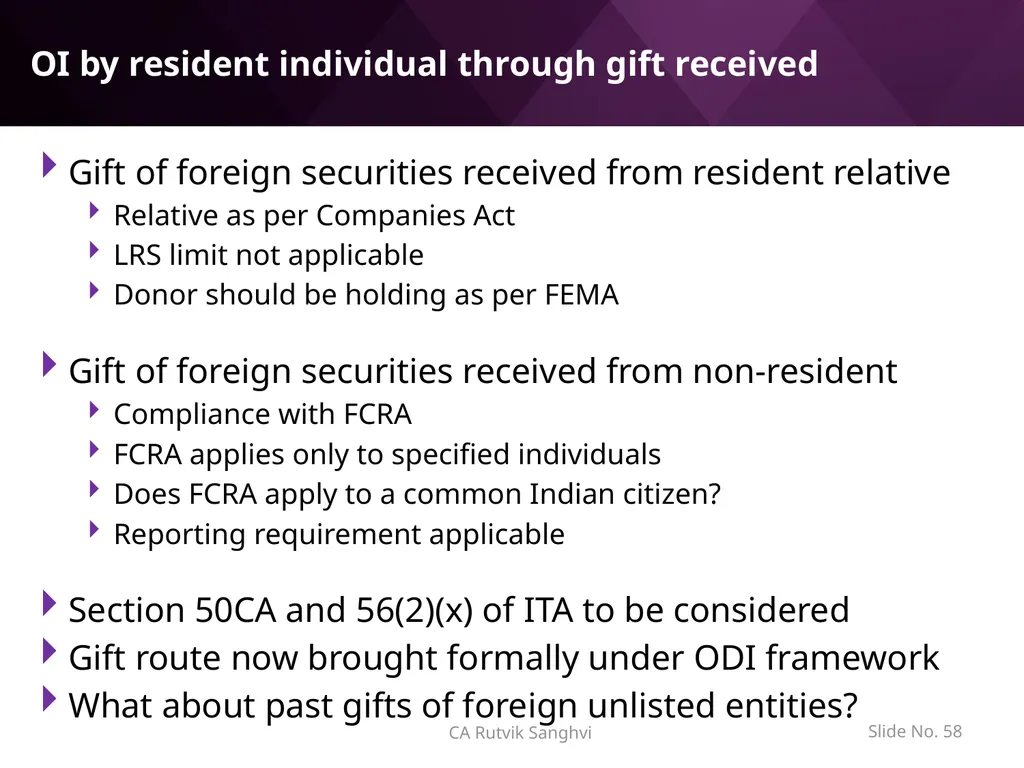
slide58. OI by resident individual through gift received Gift of foreign securities received from resident relative
Relative as per Companies Act
LRS limit not applicable
Donor should be holding as per FEMA
Gift of foreign securities received from non-resident
Compliance with FCRA
FCRA applies only to specified individuals
Does FCRA apply to a common Indian citizen?
Reporting requirement applicable
Section 50CA and 56(2)(x) of ITA to be considered
Gift route now brought formally under ODI framework
What about past gifts of foreign unlisted entities? Slide No. 58 CA Rutvik Sanghvi<br>
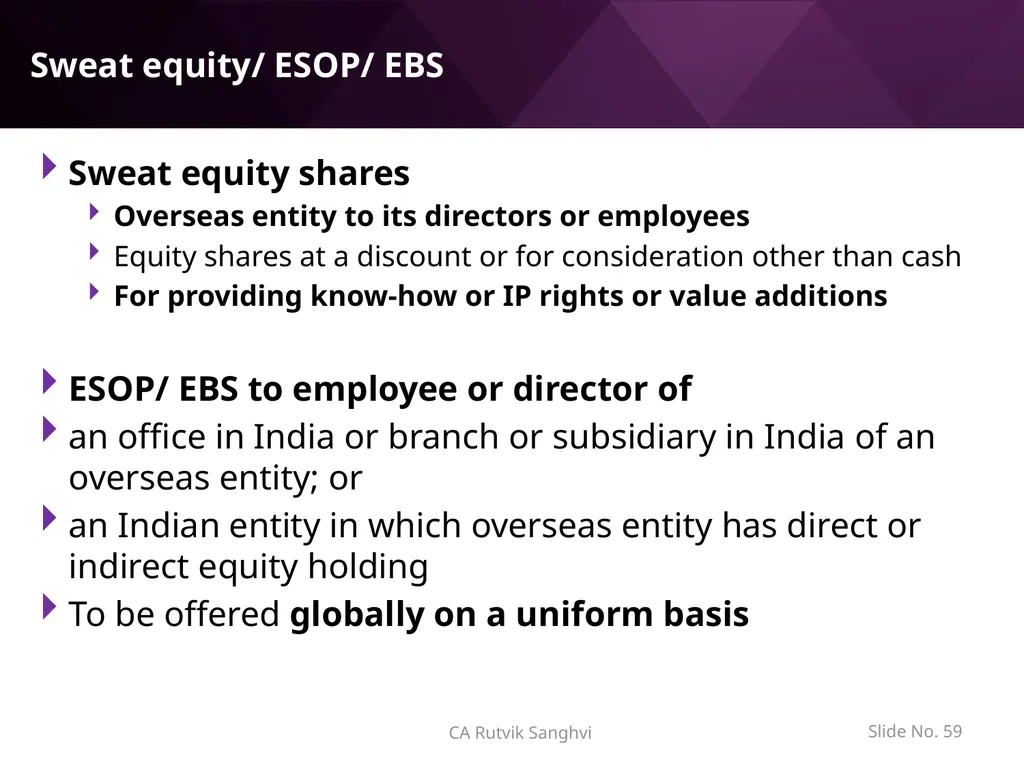
slide59. Sweat equity/ ESOP/ EBS Sweat equity shares
Overseas entity to its directors or employees
Equity shares at a discount or for consideration other than cash
For providing know-how or IP rights or value additions
ESOP/ EBS to employee or director of
an office in India or branch or subsidiary in India of an overseas entity; or
an Indian entity in which overseas entity has direct or indirect equity holding
To be offered globally on a uniform basis Slide No. 59 CA Rutvik Sanghvi<br>
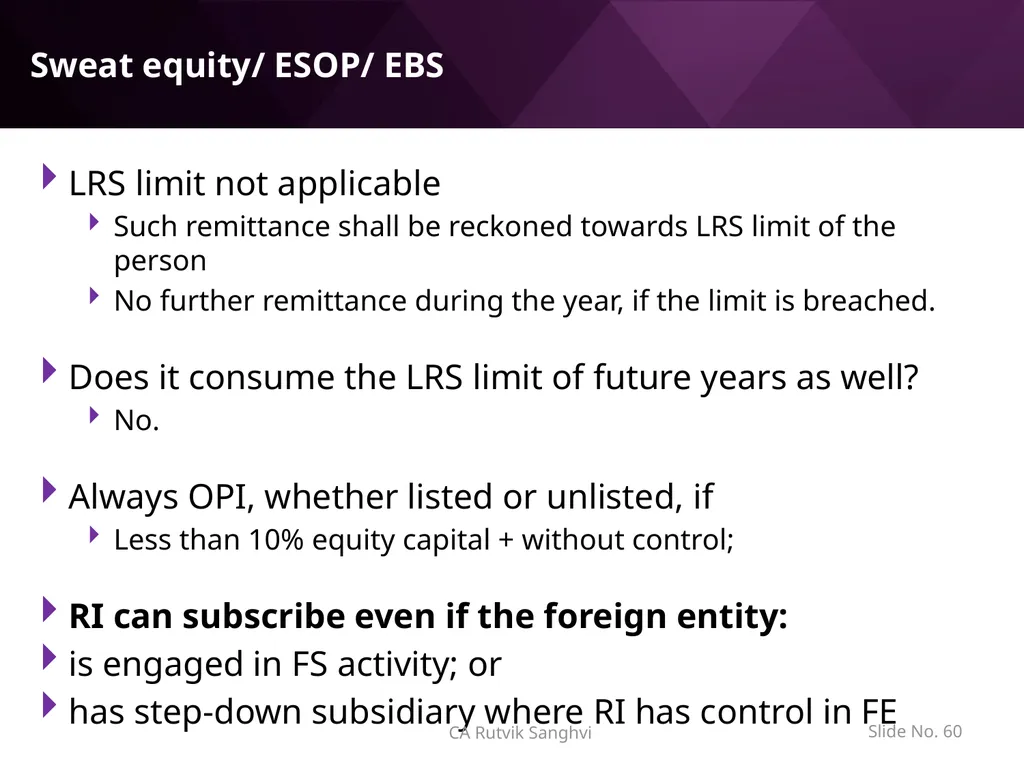
slide60. Sweat equity/ ESOP/ EBS LRS limit not applicable
Such remittance shall be reckoned towards LRS limit of the person
No further remittance during the year, if the limit is breached.
Does it consume the LRS limit of future years as well?
No.
Always OPI, whether listed or unlisted, if
Less than 10% equity capital + without control;
RI can subscribe even if the foreign entity:
is engaged in FS activity; or
has step-down subsidiary where RI has control in FE Slide No. 60 CA Rutvik Sanghvi<br>
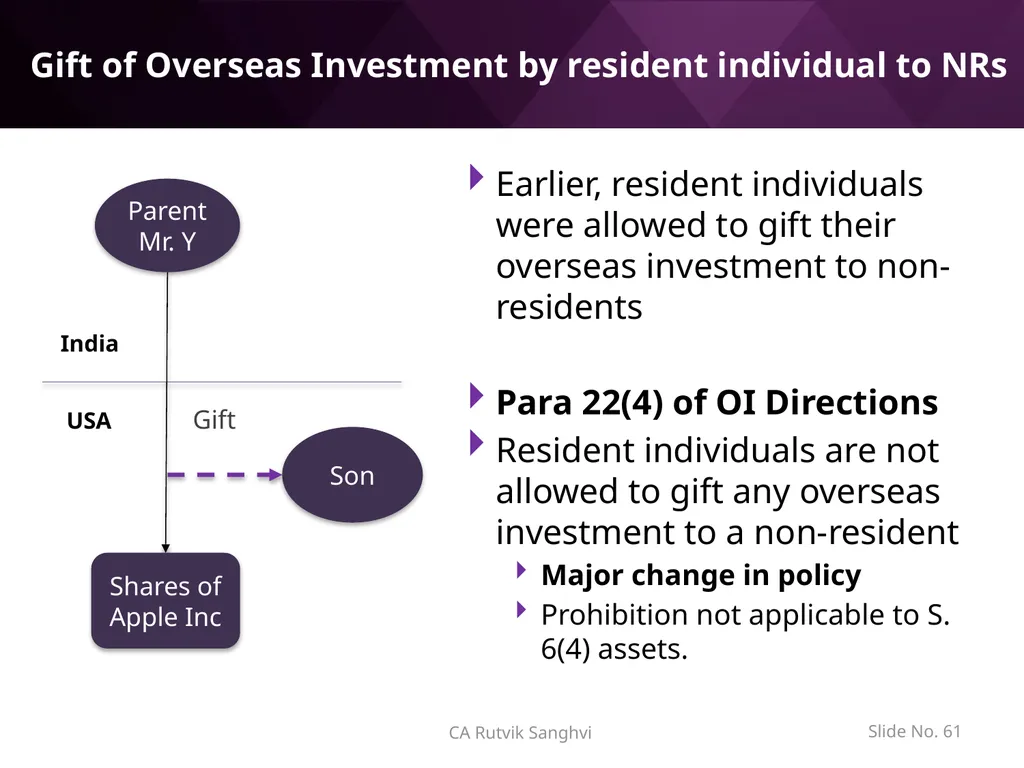
slide61. Gift of Overseas Investment by resident individual to NRs Earlier, resident individuals were allowed to gift their overseas investment to non-residents
Para 22(4) of OI Directions
Resident individuals are not allowed to gift any overseas investment to a non-resident
Major change in policy
Prohibition not applicable to S. 6(4) assets. Slide No. 61 Son Shares of Apple Inc India USA Gift Parent
Mr. Y CA Rutvik Sanghvi<br>
slide62. Immovable Property Outside India - LRS Resident individual can send remittances under LRS for purchasing IP outside India
Such IP can be:
Leased
Sold
Funds from lease and sale can be retained outside India
Funds retained can be reinvested
Multiple LRS remittances can be clubbed for purchase of high value IP
One individual can remit USD 250,000 in foreign bank account over multiple years until sufficient funds are collected CA Rutvik Sanghvi Slide No. 62<br>
slide63. Immovable Property Outside India - LRS A Resident can acquire property situated abroad from a non-resident:
Through inheritance
Through purchase our of forex held in RFC account
Through LRS remittances. Further, LRS remittances of resident relatives can be consolidated, if in compliance with overall LRS scheme
Jointly with a non-resident relative
Out of income or sale proceeds of assets acquired abroad (except ODI)
Gift of property situated abroad by a resident
Gift to a resident: Allowed
Gift to a non-resident: Silent. Not allowed. CA Rutvik Sanghvi Slide No. 63<br>
slide64. Co-ownership condition for buying IP outside India where remittances are consolidated<br>
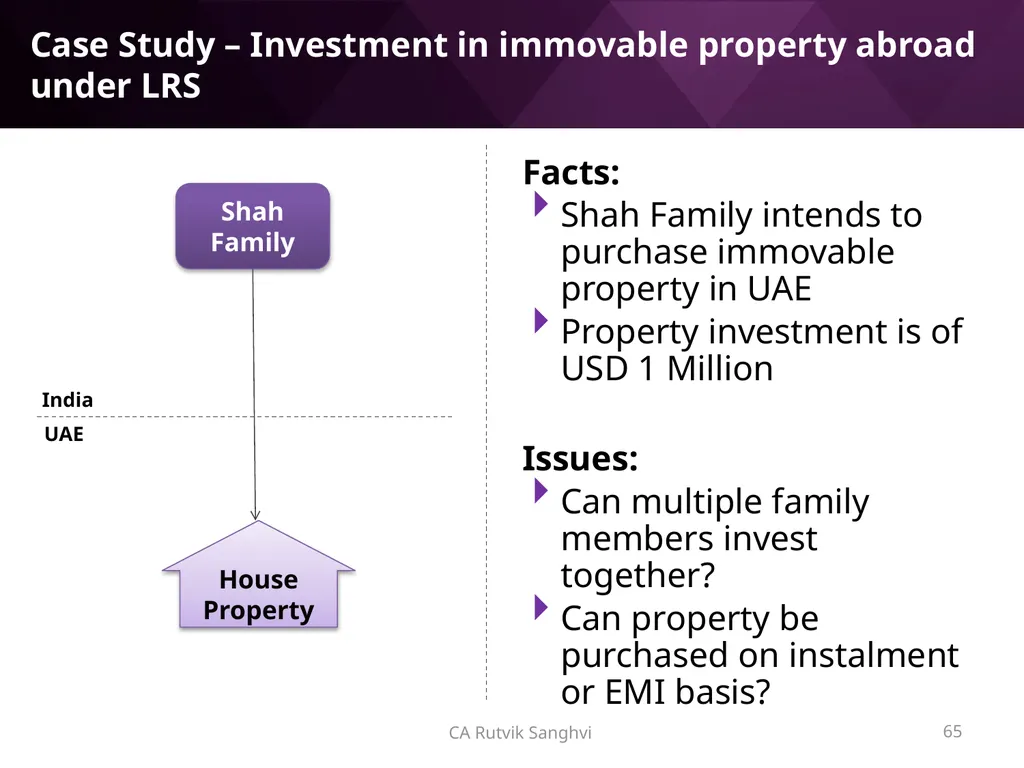
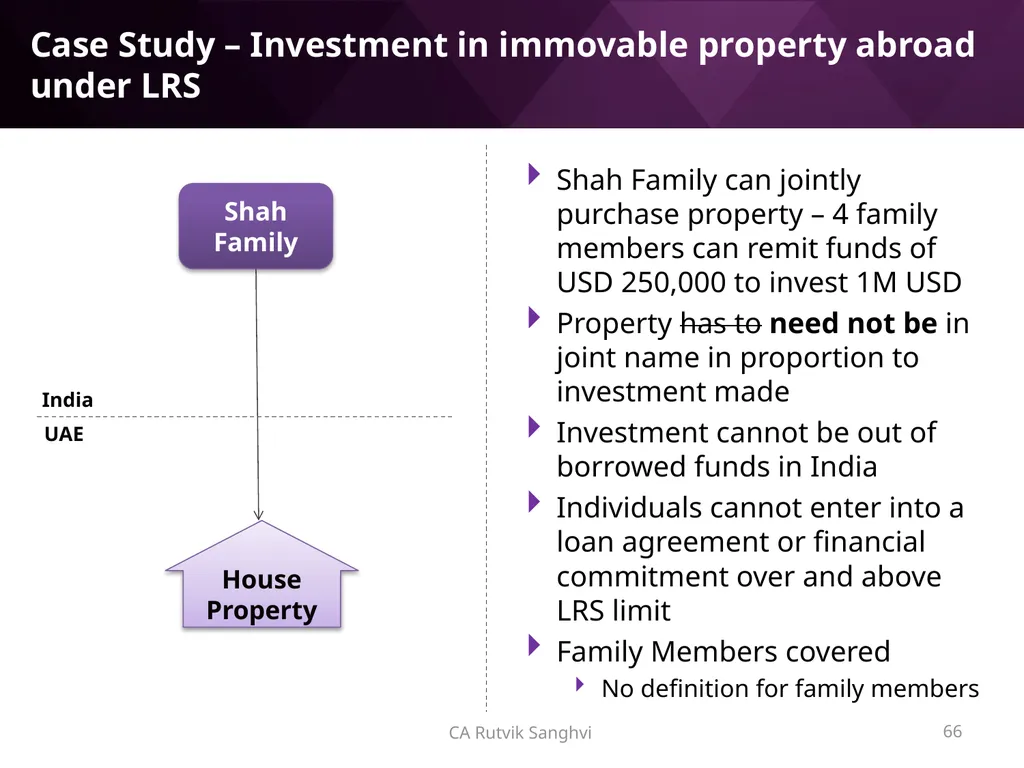
slide65. Case Study – Investment in immovable property abroad under LRS Facts:
Shah Family intends to purchase immovable property in UAE
Property investment is of USD 1 Million
Issues:
Can multiple family members invest together?
Can property be purchased on instalment or EMI basis? 65 UAE India House Property Shah Family CA Rutvik Sanghvi<br>
slide66. Case Study – Investment in immovable property abroad under LRS Shah Family can jointly purchase property – 4 family members can remit funds of USD 250,000 to invest 1M USD
Property has to need not be in joint name in proportion to investment made
Investment cannot be out of borrowed funds in India
Individuals cannot enter into a loan agreement or financial commitment over and above LRS limit
Family Members covered
No definition for family members 66 UAE India House Property Shah Family CA Rutvik Sanghvi<br>
slide67. Streamlines the process of emigration to several countries
USA, Greece, Portugal, Spain, UAE, Austria, Malta, Turkey, Antigua, Dominica, Grenada, St. Kitts, St. Lucia, Cyprus
Funds should not be consolidated in one bank account
Gift of funds outside India between residents is not permitted
Funds to be directly paid to seller from respective account of each relative
Income-tax issues
Clubbing provisions
Automatic exchange of Information
Reporting of foreign assets in Sch. FA
Implications under Black Money Act
For inappropriate/non-reporting of foreign asset held at any time during PY
Intelligent and detailed scrutiny by FAIU
Notices issued to minors as well CA Rutvik Sanghvi 67 Implications and issues<br>
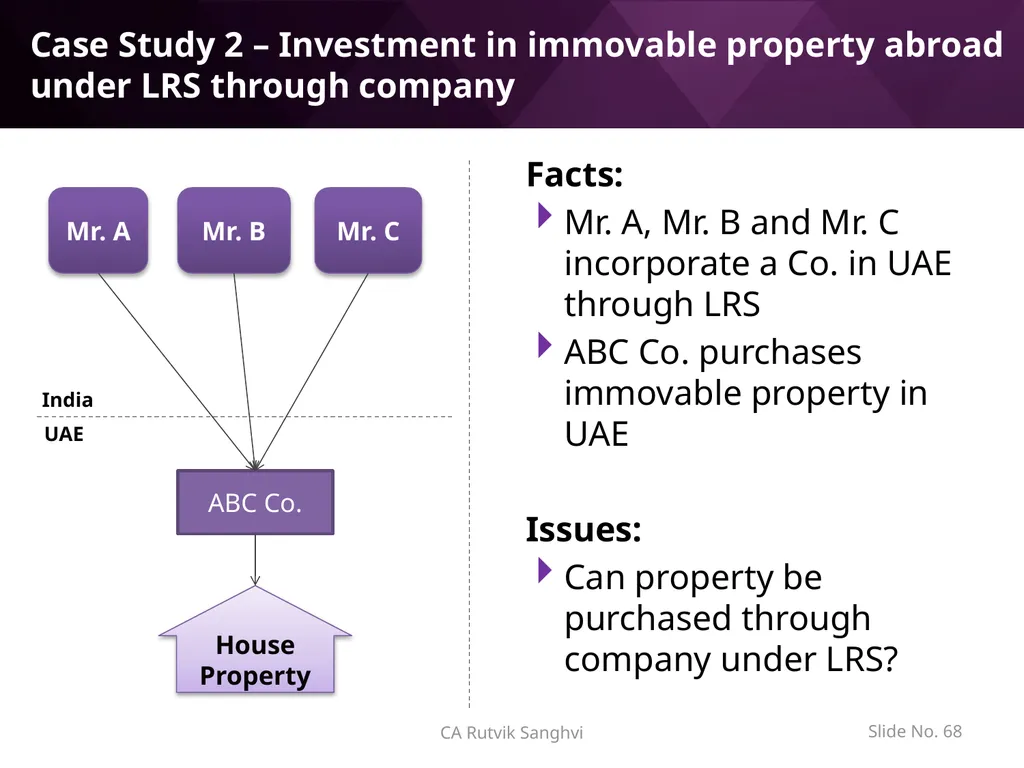
slide68. Case Study 2 – Investment in immovable property abroad under LRS through company Facts:
Mr. A, Mr. B and Mr. C incorporate a Co. in UAE through LRS
ABC Co. purchases immovable property in UAE
Issues:
Can property be purchased through company under LRS? CA Rutvik Sanghvi Slide No. 68 UAE India House Property Mr. B Mr. A Mr. C ABC Co.<br>
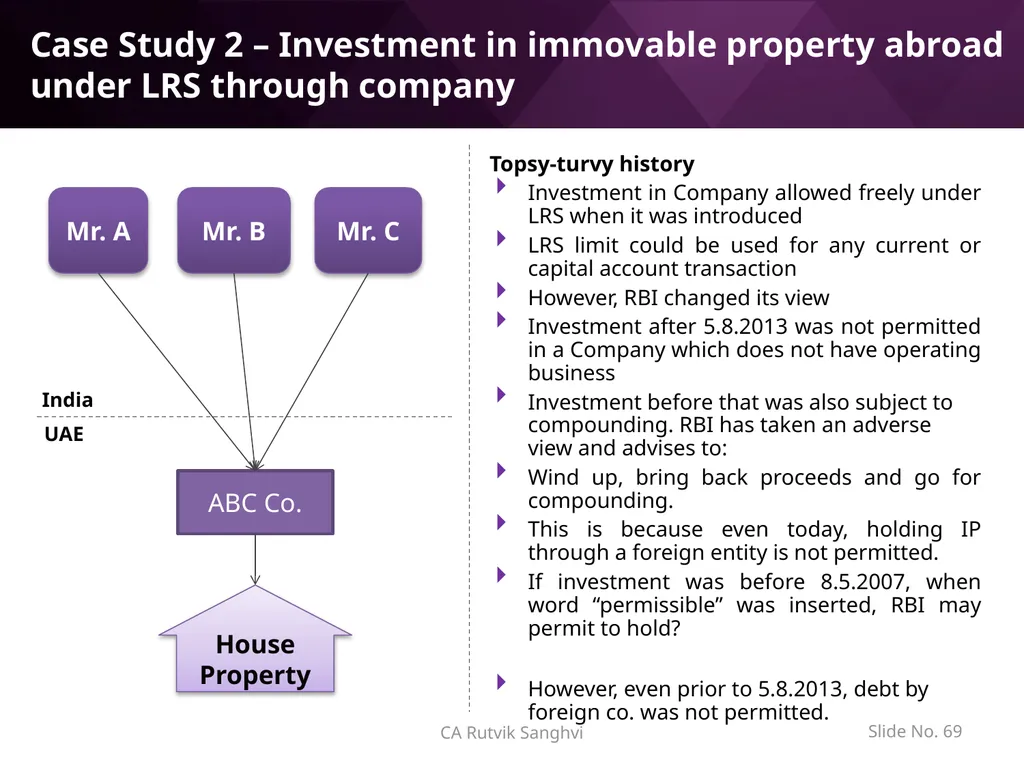
slide69. Case Study 2 – Investment in immovable property abroad under LRS through company Topsy-turvy history
Investment in Company allowed freely under LRS when it was introduced
LRS limit could be used for any current or capital account transaction
However, RBI changed its view
Investment after 5.8.2013 was not permitted in a Company which does not have operating business
Investment before that was also subject to compounding. RBI has taken an adverse view and advises to:
Wind up, bring back proceeds and go for compounding.
This is because even today, holding IP through a foreign entity is not permitted.
If investment was before 8.5.2007, when word “permissible” was inserted, RBI may permit to hold?
However, even prior to 5.8.2013, debt by foreign co. was not permitted. CA Rutvik Sanghvi Slide No. 69 UAE India House Property Mr. B Mr. A Mr. C ABC Co.<br>
slide70. Disclosure of Foreign Assets and Incomes under Income-Tax<br>
slide71. The Five Ws CA Rutvik Sanghvi Slide No. 71<br>
slide72. Foreign Assets Disclosures – WHY??<br>
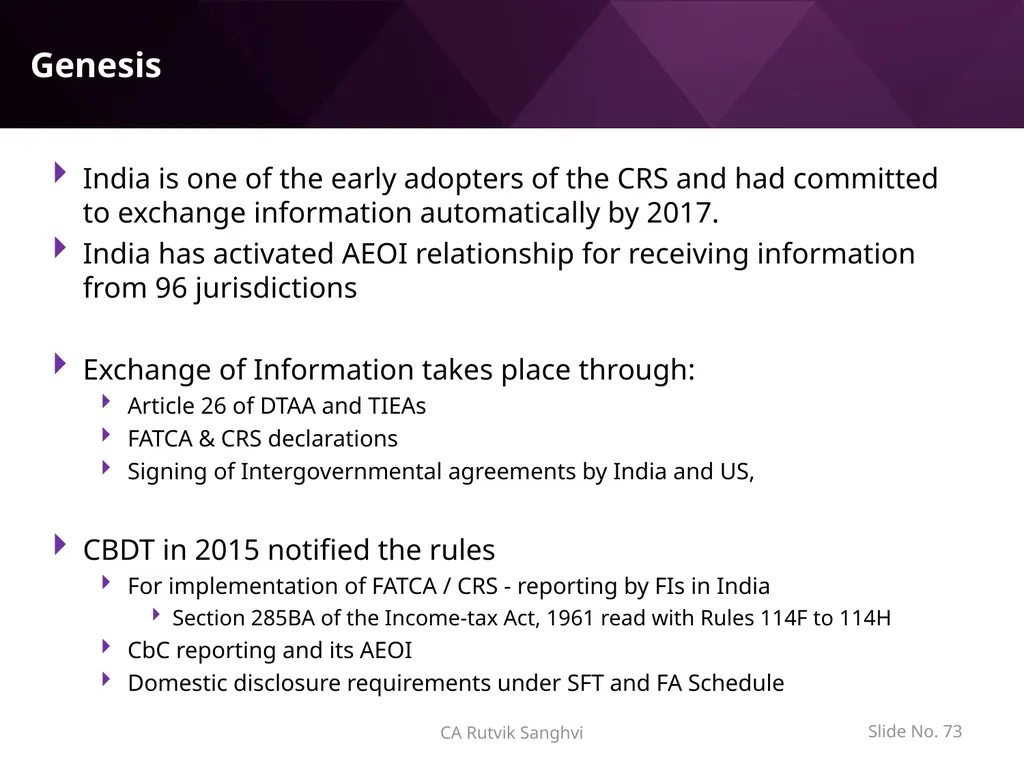
slide73. Genesis India is one of the early adopters of the CRS and had committed to exchange information automatically by 2017.
India has activated AEOI relationship for receiving information from 96 jurisdictions
Exchange of Information takes place through:
Article 26 of DTAA and TIEAs
FATCA & CRS declarations
Signing of Intergovernmental agreements by India and US,
CBDT in 2015 notified the rules
For implementation of FATCA / CRS - reporting by FIs in India
Section 285BA of the Income-tax Act, 1961 read with Rules 114F to 114H
CbC reporting and its AEOI
Domestic disclosure requirements under SFT and FA Schedule CA Rutvik Sanghvi Slide No. 73<br>
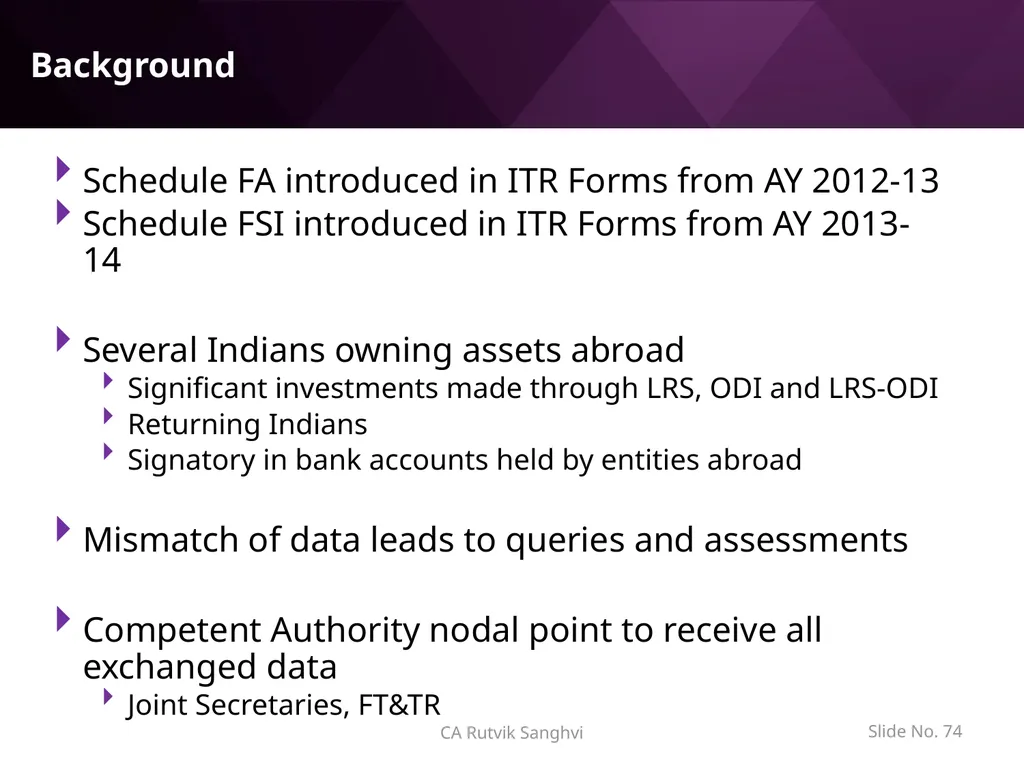
slide74. Background Schedule FA introduced in ITR Forms from AY 2012-13
Schedule FSI introduced in ITR Forms from AY 2013-14
Several Indians owning assets abroad
Significant investments made through LRS, ODI and LRS-ODI
Returning Indians
Signatory in bank accounts held by entities abroad
Mismatch of data leads to queries and assessments
Competent Authority nodal point to receive all exchanged data
Joint Secretaries, FT&TR CA Rutvik Sanghvi Slide No. 74<br>
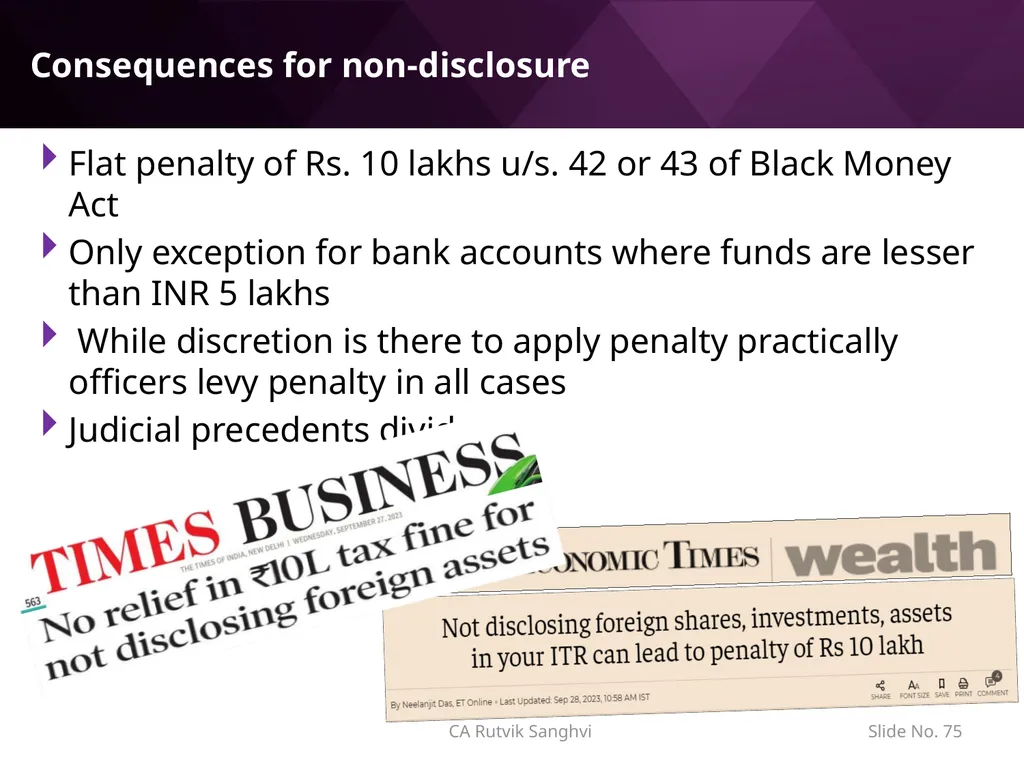
slide75. Consequences for non-disclosure Flat penalty of Rs. 10 lakhs u/s. 42 or 43 of Black Money Act
Only exception for bank accounts where funds are lesser than INR 5 lakhs
While discretion is there to apply penalty practically officers levy penalty in all cases
Judicial precedents divided CA Rutvik Sanghvi Slide No. 75<br>
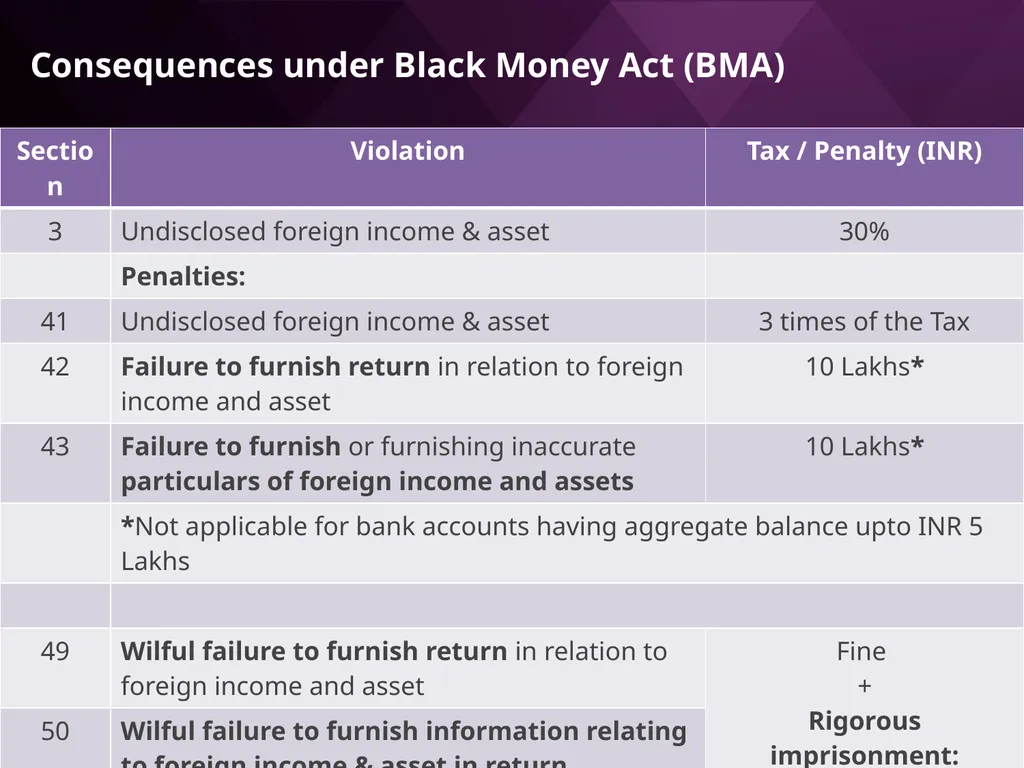
slide76. Consequences under Black Money Act (BMA) CA Rutvik Sanghvi Slide No. 76<br>
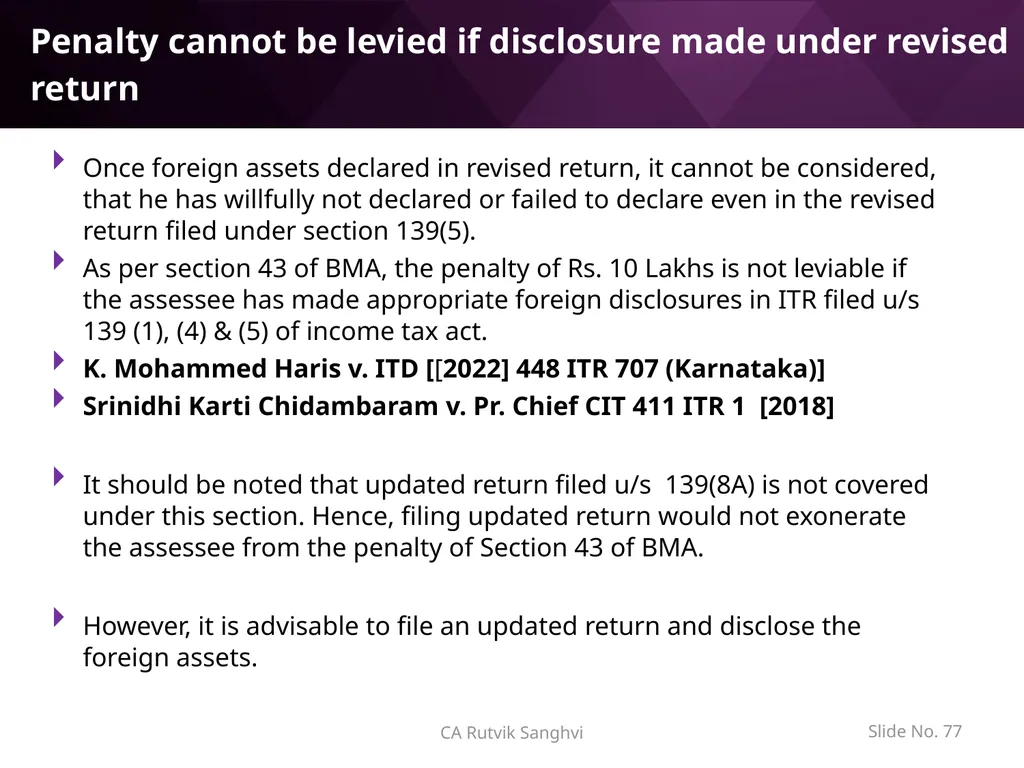
slide77. Penalty cannot be levied if disclosure made under revised return Once foreign assets declared in revised return, it cannot be considered, that he has willfully not declared or failed to declare even in the revised return filed under section 139(5).
As per section 43 of BMA, the penalty of Rs. 10 Lakhs is not leviable if the assessee has made appropriate foreign disclosures in ITR filed u/s 139 (1), (4) & (5) of income tax act.
K. Mohammed Haris v. ITD [[2022] 448 ITR 707 (Karnataka)]
Srinidhi Karti Chidambaram v. Pr. Chief CIT 411 ITR 1 [2018]
It should be noted that updated return filed u/s 139(8A) is not covered under this section. Hence, filing updated return would not exonerate the assessee from the penalty of Section 43 of BMA.
However, it is advisable to file an updated return and disclose the foreign assets. CA Rutvik Sanghvi Slide No. 77<br>
slide78. No penalty u/s 43 of BMA, 2015 – Bona fide case The assessee was signatory, but not the owner of the foreign bank account or the funds lying in the bank account. The bank account was inherited by her mother from her father. Given the poor condition of assessee’s mother the assessee and her husband were just a signatory in the foreign bank account.
Penalty was based on the assertion that the assessee, as a signatory to an undisclosed foreign bank account, was liable for penal consequences under section 43 of the Black Money Act.
Held:
“The unambiguous intent of the legislature thus is to exclude trivial cases of lapses which can be attributed to a reasonable cause.”
Assessing Officer 'may' impose the penalty, and the use of the expression 'may’ signifies that the penalty is not to be imposed in all cases of lapses and that there is no cause and effect relationship simpliciter between the lapse and the penalty.“
The AO has clear discretion in the matter.
Stringent penalties cannot be imposed for bonafide mistakes.
ACIT vs. Leena Gandhi Tiwari [2022] 136 taxmann.com 409 (Mumbai - Trib.) CA Rutvik Sanghvi Slide No. 78<br>
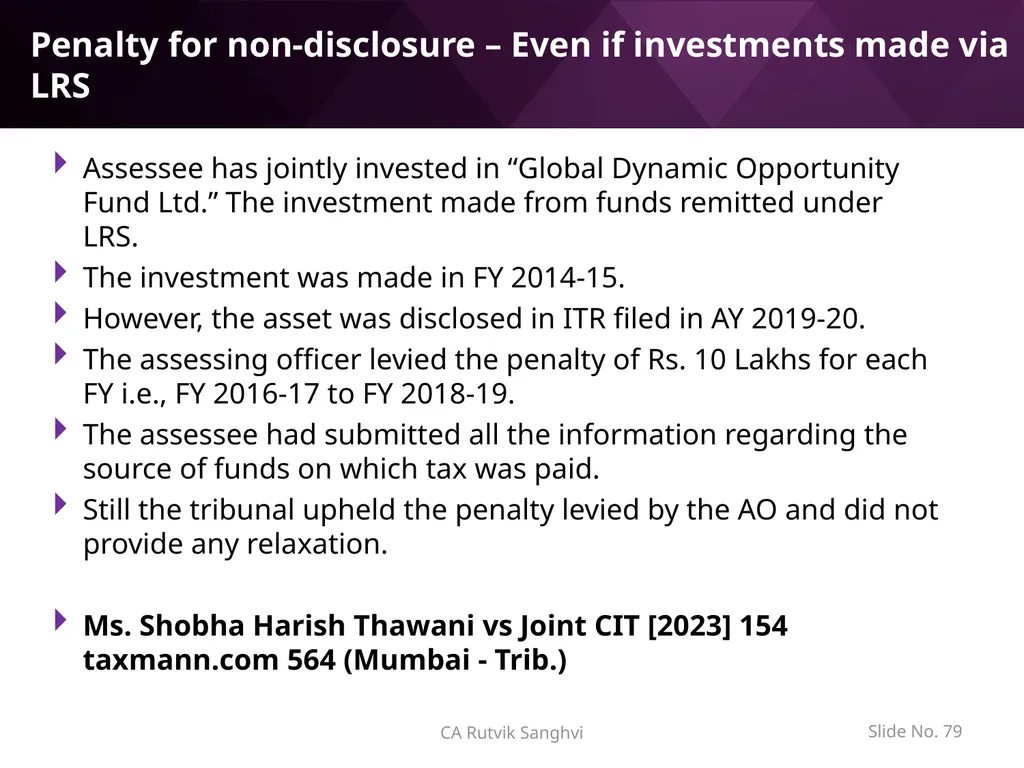
slide79. Penalty for non-disclosure – Even if investments made via LRS Assessee has jointly invested in “Global Dynamic Opportunity Fund Ltd.” The investment made from funds remitted under LRS.
The investment was made in FY 2014-15.
However, the asset was disclosed in ITR filed in AY 2019-20.
The assessing officer levied the penalty of Rs. 10 Lakhs for each FY i.e., FY 2016-17 to FY 2018-19.
The assessee had submitted all the information regarding the source of funds on which tax was paid.
Still the tribunal upheld the penalty levied by the AO and did not provide any relaxation.
Ms. Shobha Harish Thawani vs Joint CIT [2023] 154 taxmann.com 564 (Mumbai - Trib.) CA Rutvik Sanghvi Slide No. 79<br>
slide80. Penalty not levied – As investments disclosed in the Books of Accounts and in FEMA compliances Assessee had an investment in foreign entity - Helen Incorporated S.A., Panama.
This investment was not disclosed in the Schedule FA leading to penalty.
The assessee had disclosed investment as ‘Non-Current Asset’ in the Annual Report as well as in the Balance Sheet in ITR Form. Also, the investment was disclosed with the RBI through the authorized dealer.
Tribunal deleted the penalty and held:
“No doubt the AO is empowered to impose the penalty as discretion is vested with him by using word “May” in the provisions. The discretion is always at wisdom of an authority, however, discretion is required to be exercised judicially and under the Judicial canons of law and in reasonable and justified manner to impart the justice…”
M/s Ocean Diving Centre Ltd. vs CIT - ITAT Mumbai - BMA Nos. 20 to 23/Mum/2023. CA Rutvik Sanghvi Slide No. 80<br>
slide81. Foreign Assets Disclosures – WHAT??<br>
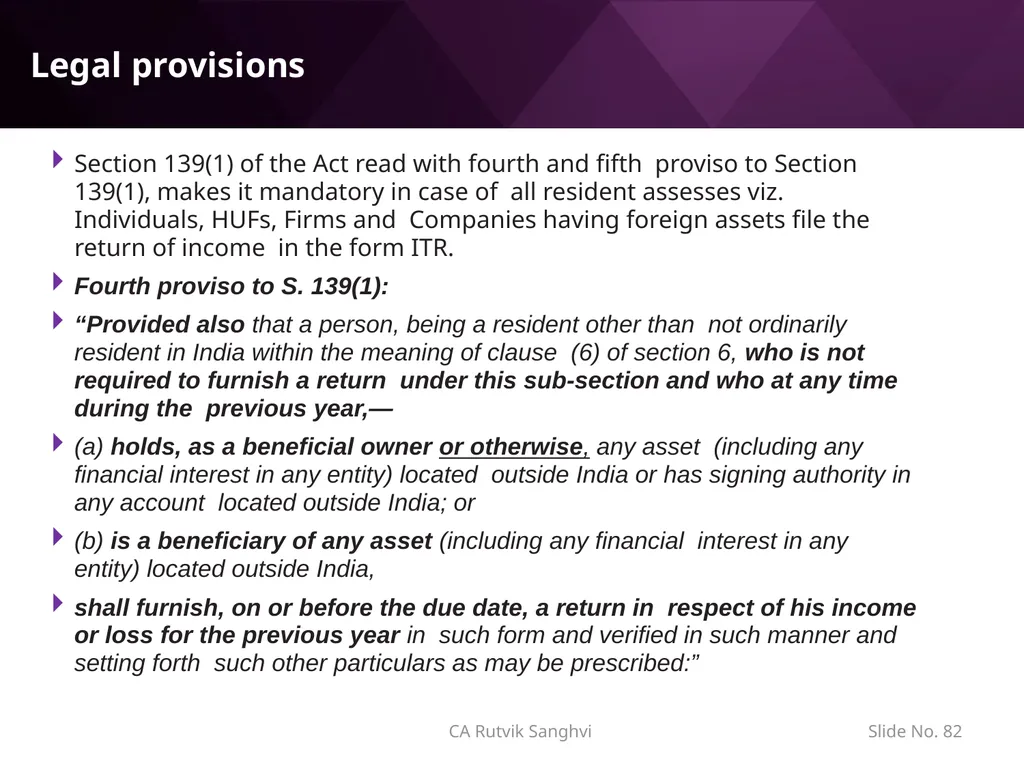
slide82. Legal provisions Section 139(1) of the Act read with fourth and fifth proviso to Section 139(1), makes it mandatory in case of all resident assesses viz. Individuals, HUFs, Firms and Companies having foreign assets file the return of income in the form ITR.
Fourth proviso to S. 139(1):
“Provided also that a person, being a resident other than not ordinarily resident in India within the meaning of clause (6) of section 6, who is not required to furnish a return under this sub-section and who at any time during the previous year,—
(a) holds, as a beneficial owner or otherwise, any asset (including any financial interest in any entity) located outside India or has signing authority in any account located outside India; or
(b) is a beneficiary of any asset (including any financial interest in any entity) located outside India,
shall furnish, on or before the due date, a return in respect of his income or loss for the previous year in such form and verified in such manner and setting forth such other particulars as may be prescribed:” CA Rutvik Sanghvi Slide No. 82<br>
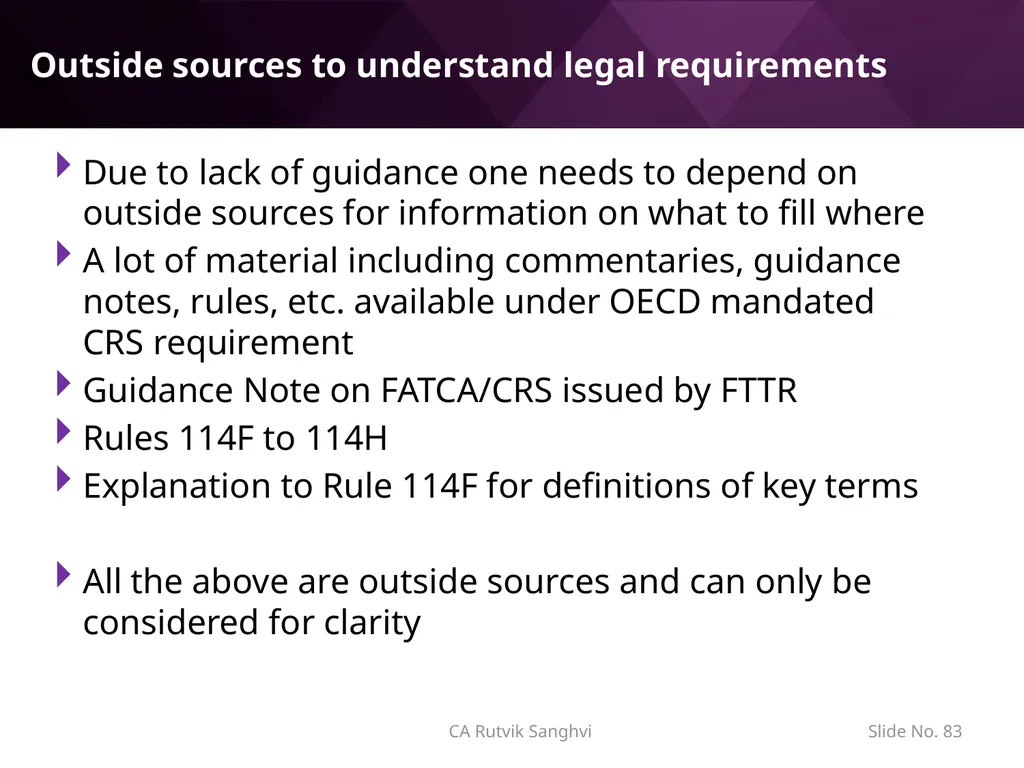
slide83. Outside sources to understand legal requirements Due to lack of guidance one needs to depend on outside sources for information on what to fill where
A lot of material including commentaries, guidance notes, rules, etc. available under OECD mandated CRS requirement
Guidance Note on FATCA/CRS issued by FTTR
Rules 114F to 114H
Explanation to Rule 114F for definitions of key terms
All the above are outside sources and can only be considered for clarity CA Rutvik Sanghvi Slide No. 83<br>
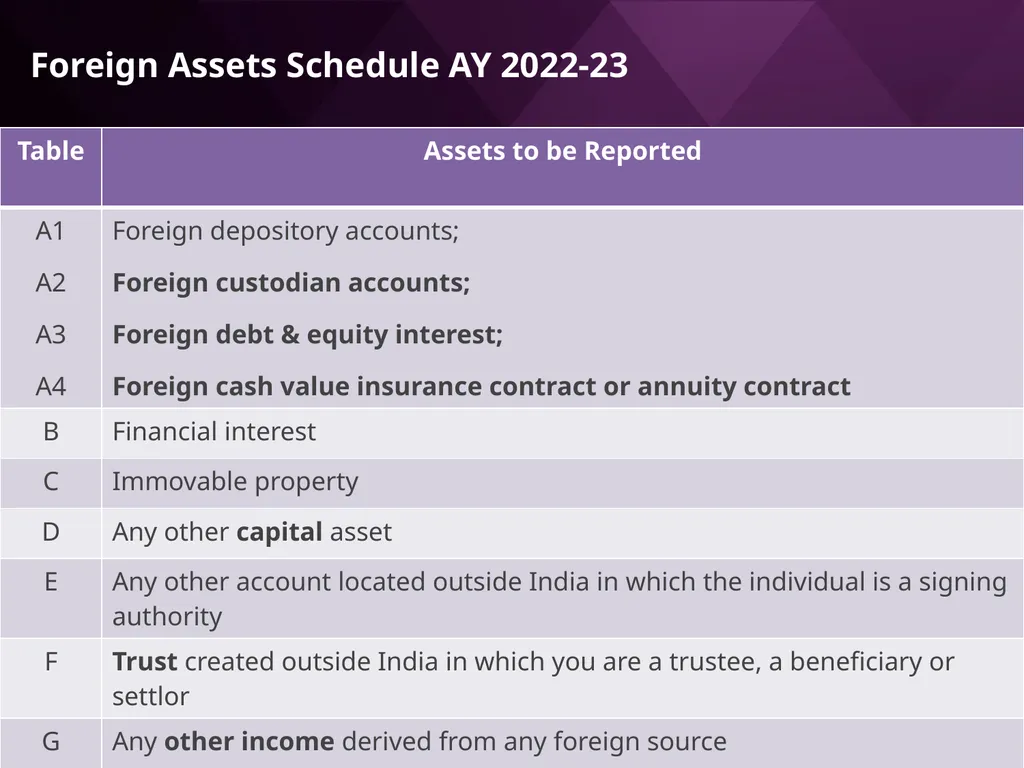
slide84. Foreign Assets Schedule AY 2022-23 CA Rutvik Sanghvi Slide No. 84<br>
slide85. Foreign Assets Disclosures – WHO??<br>
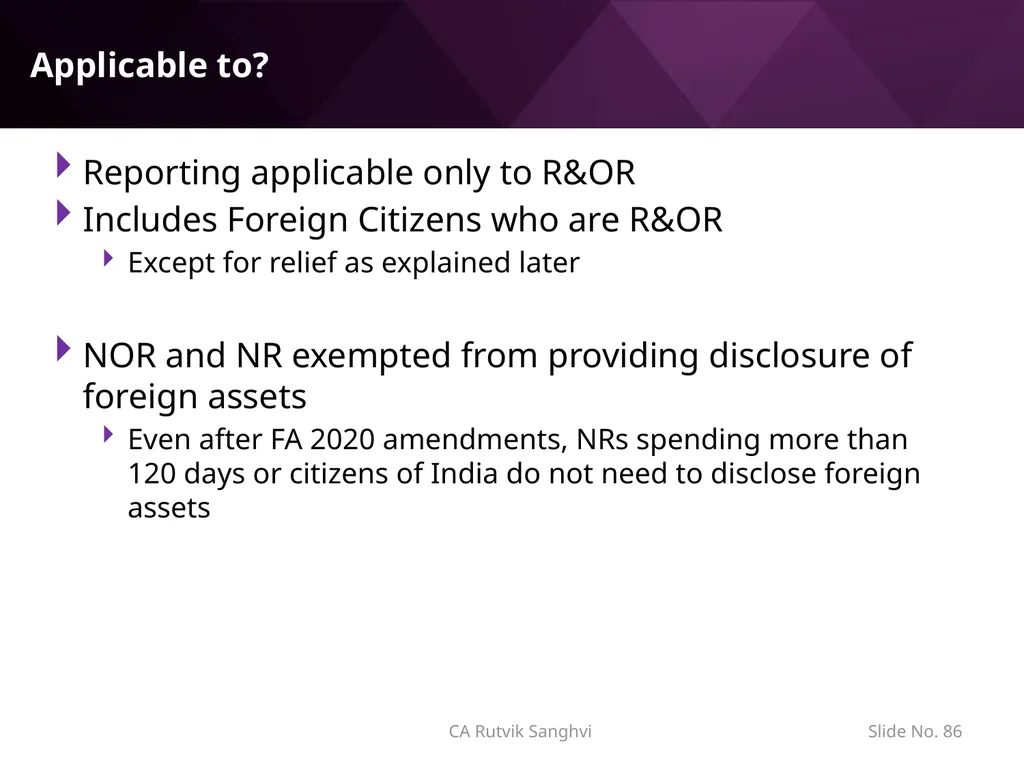
slide86. Applicable to? Reporting applicable only to R&OR
Includes Foreign Citizens who are R&OR
Except for relief as explained later
NOR and NR exempted from providing disclosure of foreign assets
Even after FA 2020 amendments, NRs spending more than 120 days or citizens of India do not need to disclose foreign assets CA Rutvik Sanghvi Slide No. 86<br>
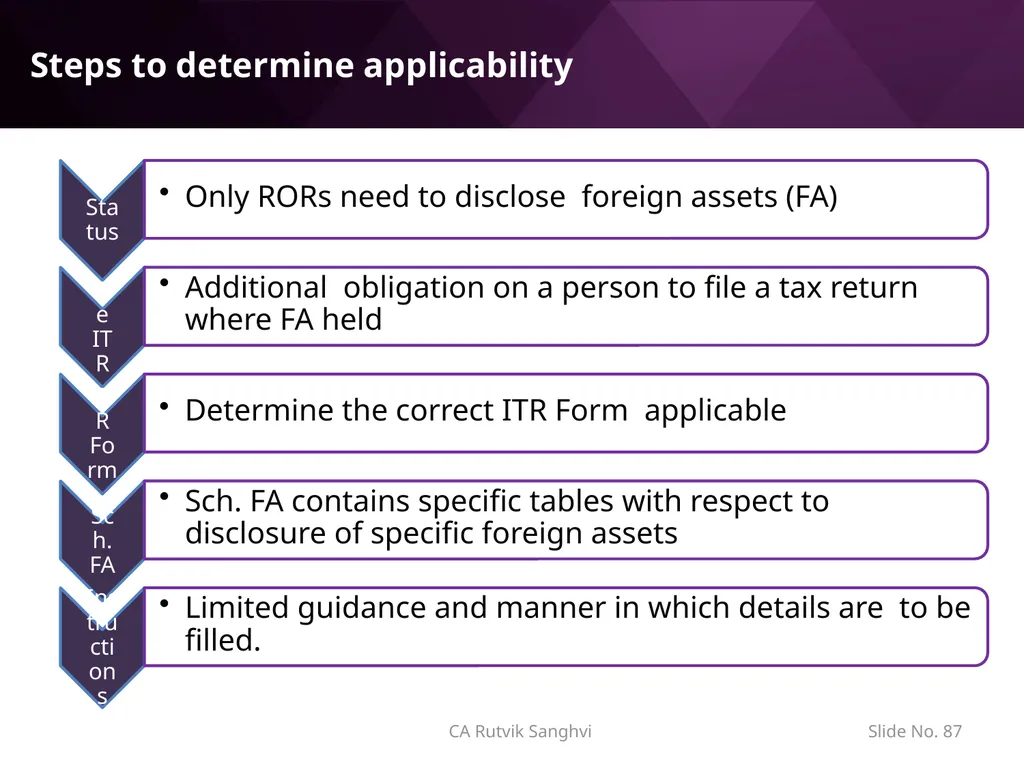
slide87. Steps to determine applicability CA Rutvik Sanghvi Slide No. 87<br>
slide88. Case Study – Applicability of FA disclosures S, a student, leaves India for UK for studies abroad on 19th August 2021. He is Resident for FY 2021-22, AY 2022-23
In UK he opens a bank account.
He has earned no incomes during FY 2021-22
Even if his income is Nil in India, he still needs to file income tax return as he has a foreign asset in form of UK Bank Account CA Rutvik Sanghvi Slide No. 88<br>
slide89. Applicability to Minors holding foreign assets Fifth proviso to section 139(1) provides for an exception from applicability of fourth proviso:
“Provided also that nothing contained in the fourth proviso shall apply to an individual, being a beneficiary of any asset (including any financial interest in any entity) located outside India where, income, if any, arising from such asset is includible in the income of the person referred to in clause (a) of that proviso in accordance with the provisions of this Act:”
Idea behind this exception seems to be to not obligate a beneficiary to file a return (in case beneficiary is otherwise not liable to file) as the legal / beneficial owner of the asset would already be obligated to submit the income in its tax return
But there is no provision for clubbing for disclosure of assets!
This causes an issue for minors who hold foreign assets. CA Rutvik Sanghvi Slide No. 89<br>
slide90. Applicability to Minors holding foreign assets A father and son (minor), both are ROR.
The minor son has invested Rs. 1 Cr in an asset abroad and has received income of Rs. 10 lakhs on the same.
From an income-tax perspective, income of Rs. 10 lakhs will be clubbed with his father’s income as per S. 64(1A) and father will offer the said income to tax in his tax return.
Whether minor son will have to file tax return and disclose the details of foreign asset??
5th proviso to Section 139(1) provides for an exception to the requirement brought out by 4th proviso to Section 139(1).
However, it only covers an individual who, while being a beneficiary of any foreign asset, income therefrom is includible in the income of the legal or beneficial owner of the asset in accordance with the Act.
In the present case, the minor son is the legal and beneficial owner of the foreign asset. The father is neither legal owner nor a beneficial owner of the foreign asset.
5th Proviso strictly does not apply to cases where minors are legal owners CA Rutvik Sanghvi Slide No. 90<br>
slide91. Applicability to Minors holding foreign assets The issue is compounded as the minor cannot file the tax return online due to system inadequacy whereby only if the minor earns income of his or her own then they can file a tax return.
Discussions with DGIT-Systems
Disclose foreign assets in return of parent
Nirmal Bhanwarlal Jain v. ADIT (Inv.)-3(1) [BMA No.13/ MUM/ 2023] – penalty levied on father for non-disclosure of children’s foreign assets!
Penalty levied for all 3 years! CA Rutvik Sanghvi Slide No. 91<br>
slide92. Foreign Assets Disclosures – WHERE??<br>
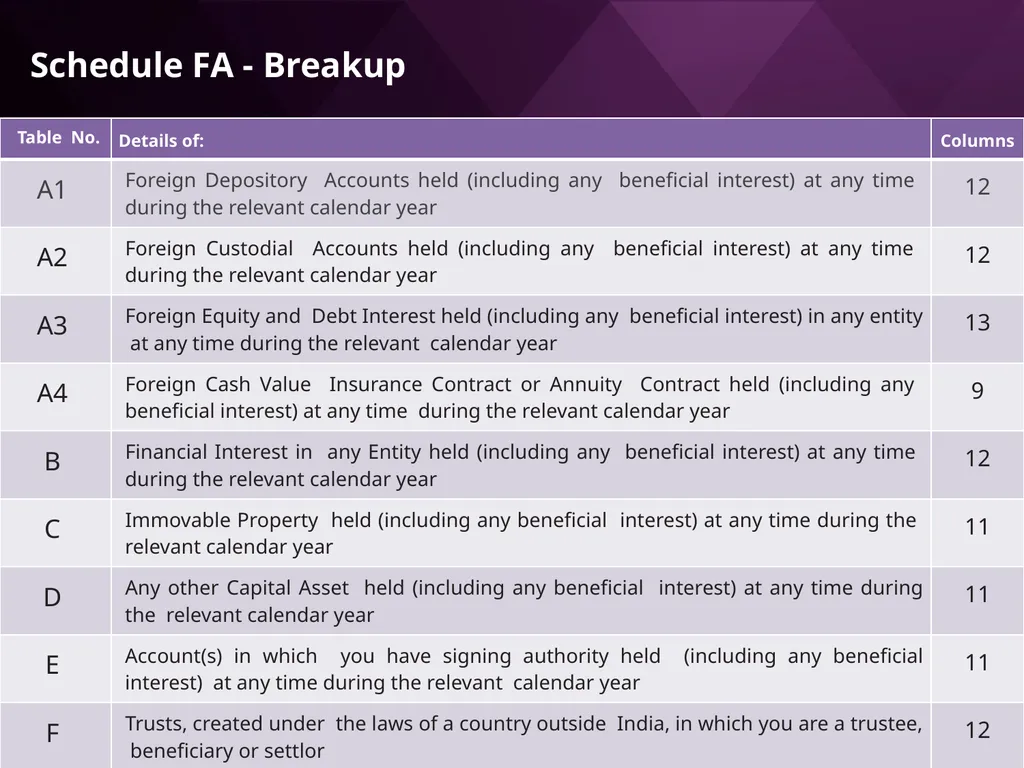
slide93. Schedule FA - Breakup CA Rutvik Sanghvi Slide No. 93<br>
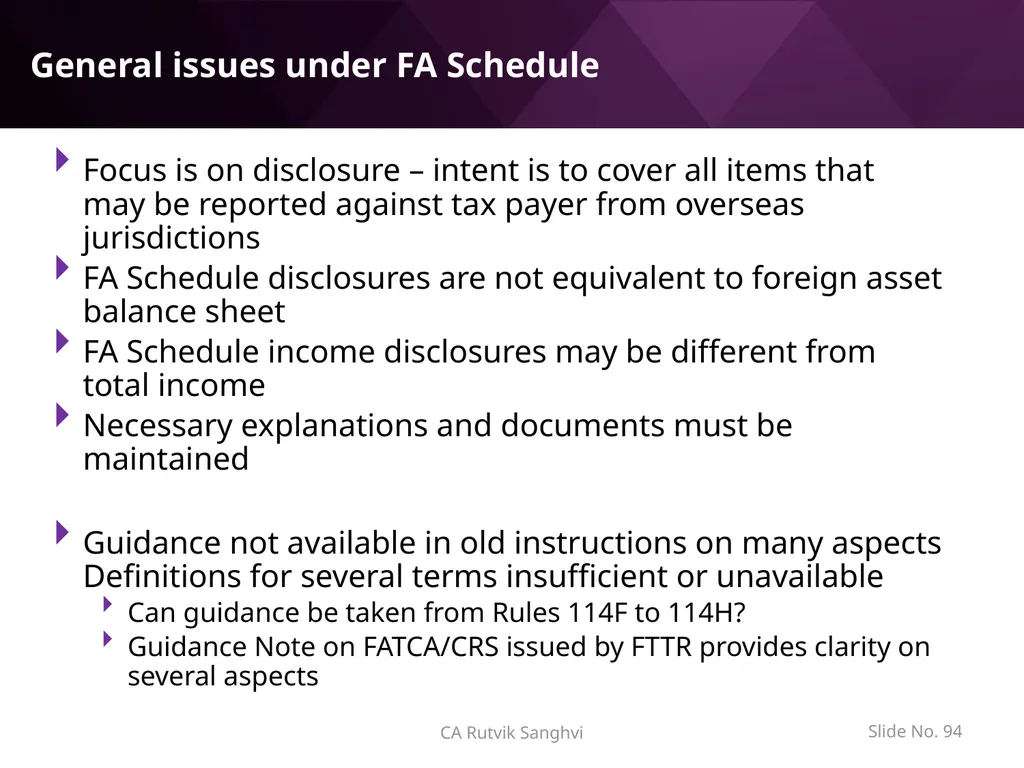
slide94. General issues under FA Schedule Focus is on disclosure – intent is to cover all items that may be reported against tax payer from overseas jurisdictions
FA Schedule disclosures are not equivalent to foreign asset balance sheet
FA Schedule income disclosures may be different from total income
Necessary explanations and documents must be maintained
Guidance not available in old instructions on many aspects Definitions for several terms insufficient or unavailable
Can guidance be taken from Rules 114F to 114H?
Guidance Note on FATCA/CRS issued by FTTR provides clarity on several aspects CA Rutvik Sanghvi Slide No. 94<br>
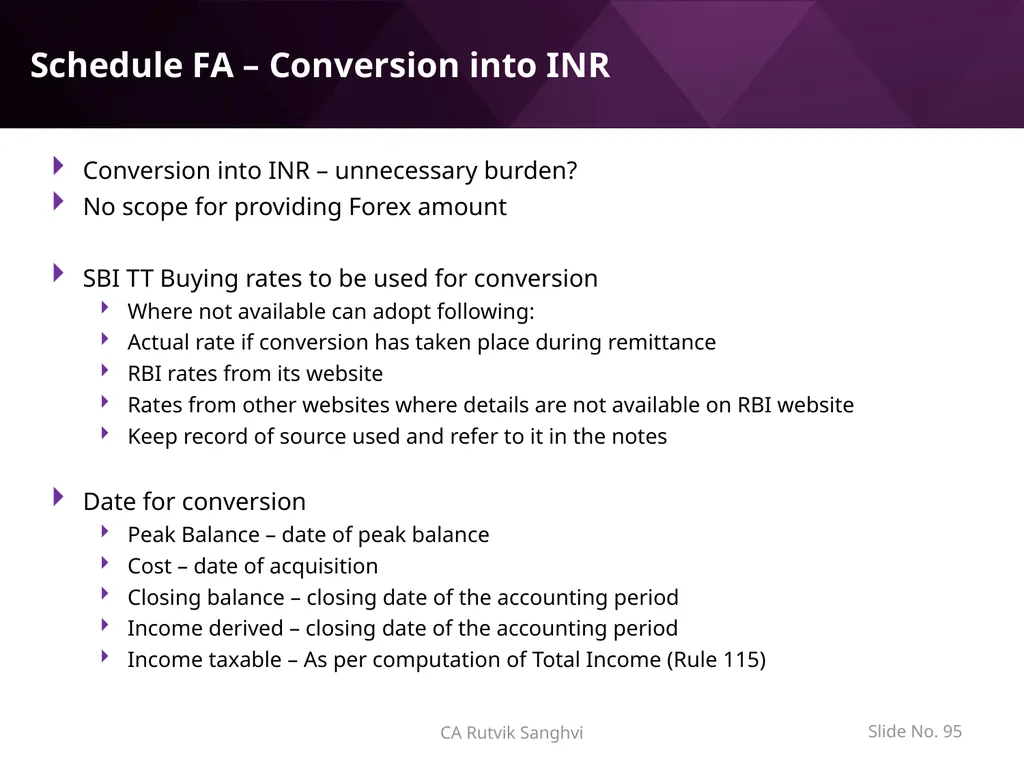
slide95. Schedule FA – Conversion into INR Conversion into INR – unnecessary burden?
No scope for providing Forex amount
SBI TT Buying rates to be used for conversion
Where not available can adopt following:
Actual rate if conversion has taken place during remittance
RBI rates from its website
Rates from other websites where details are not available on RBI website
Keep record of source used and refer to it in the notes
Date for conversion
Peak Balance – date of peak balance
Cost – date of acquisition
Closing balance – closing date of the accounting period
Income derived – closing date of the accounting period
Income taxable – As per computation of Total Income (Rule 115) CA Rutvik Sanghvi Slide No. 95<br>
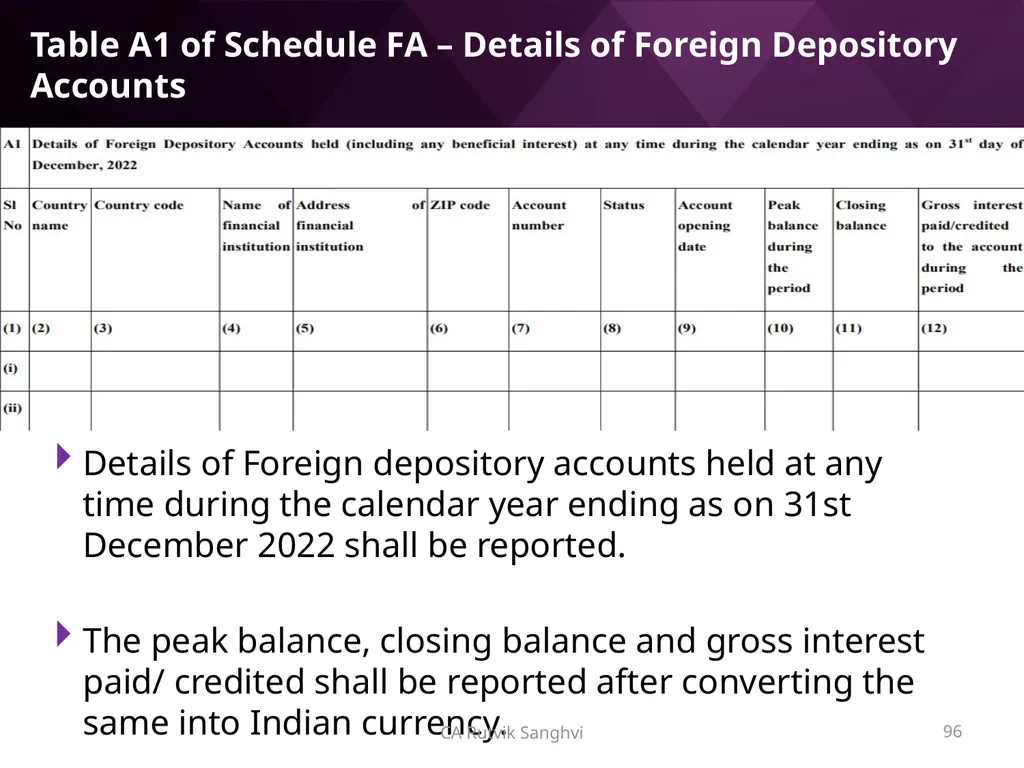
slide96. Table A1 of Schedule FA – Details of Foreign Depository Accounts Details of Foreign depository accounts held at any time during the calendar year ending as on 31st December 2022 shall be reported.
The peak balance, closing balance and gross interest paid/ credited shall be reported after converting the same into Indian currency. CA Rutvik Sanghvi 96<br>
slide97. Table A1 of Schedule FA – Details of Foreign Depository Accounts As per CRS Guidance Note and Rule 114F, Depository Account includes:
Any commercial, checking, savings, time, or thrift account, or
an account that is evidenced by a certificate of deposit, thrift certificate, investment certificate, certificate of indebtedness, or other similar instrument maintained by a financial institution in the ordinary course of a banking or similar business;
An amount that an insurance company holds under an agreement to pay or credit interest thereon;
Does not have to be an interest-bearing account. CA Rutvik Sanghvi Slide No. 97<br>
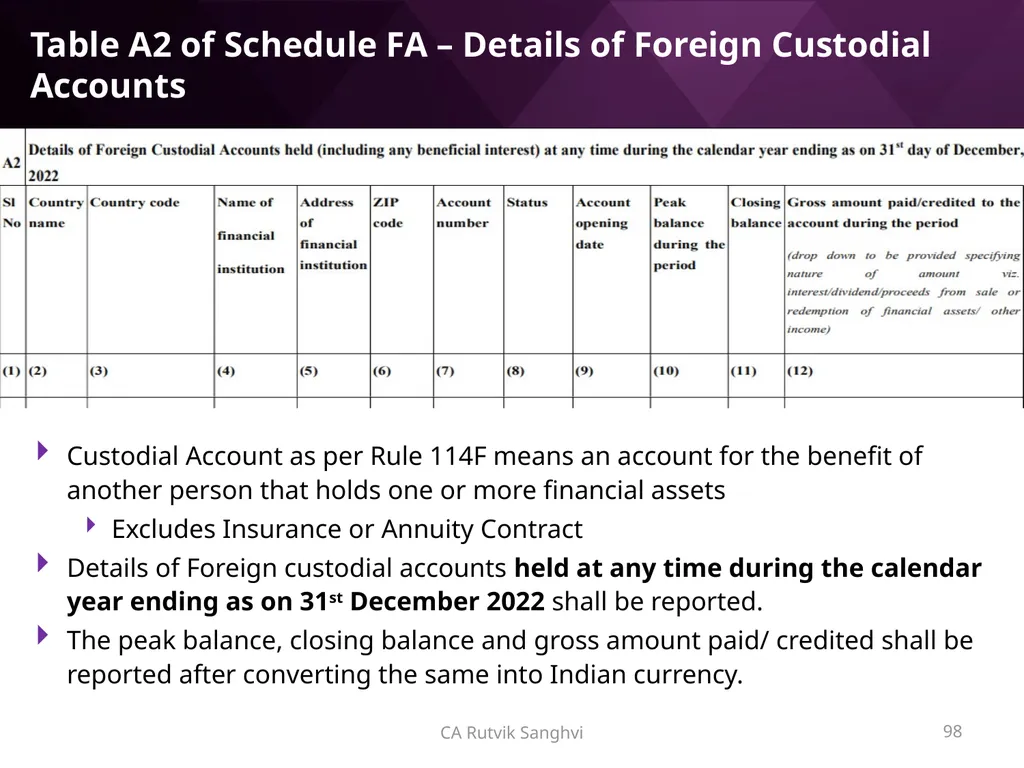
slide98. Table A2 of Schedule FA – Details of Foreign Custodial Accounts Custodial Account as per Rule 114F means an account for the benefit of another person that holds one or more financial assets
Excludes Insurance or Annuity Contract
Details of Foreign custodial accounts held at any time during the calendar year ending as on 31st December 2022 shall be reported.
The peak balance, closing balance and gross amount paid/ credited shall be reported after converting the same into Indian currency. 98 CA Rutvik Sanghvi<br>
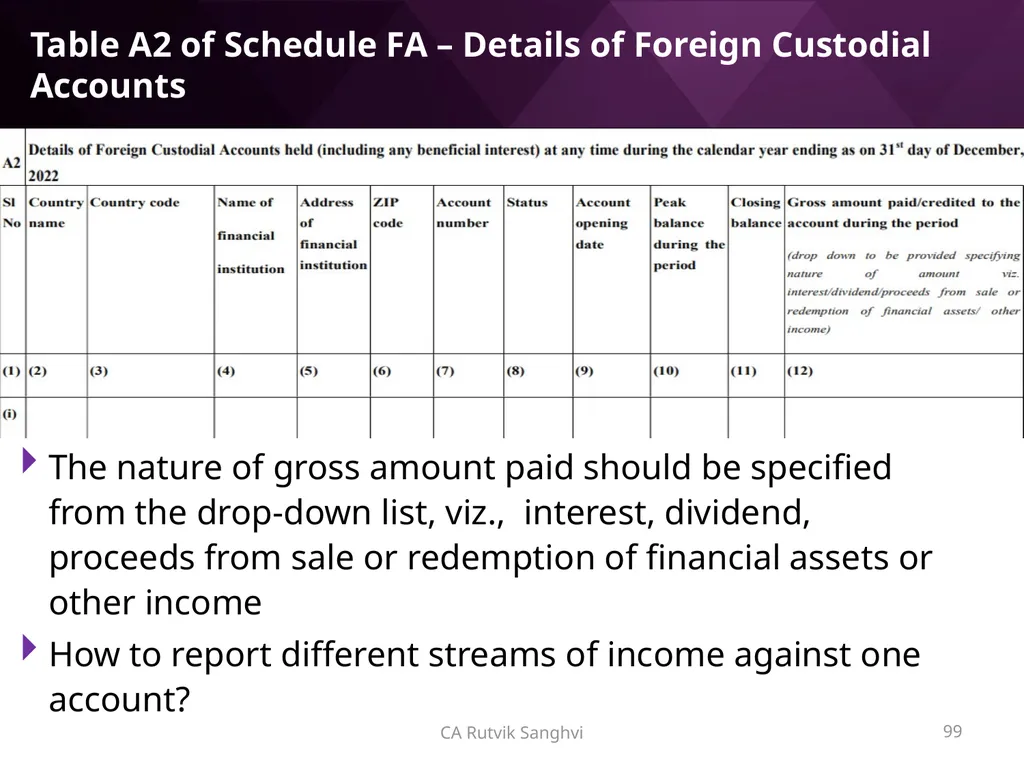
slide99. Table A2 of Schedule FA – Details of Foreign Custodial Accounts 99 CA Rutvik Sanghvi The nature of gross amount paid should be specified from the drop-down list, viz., interest, dividend, proceeds from sale or redemption of financial assets or other income
How to report different streams of income against one account?<br>
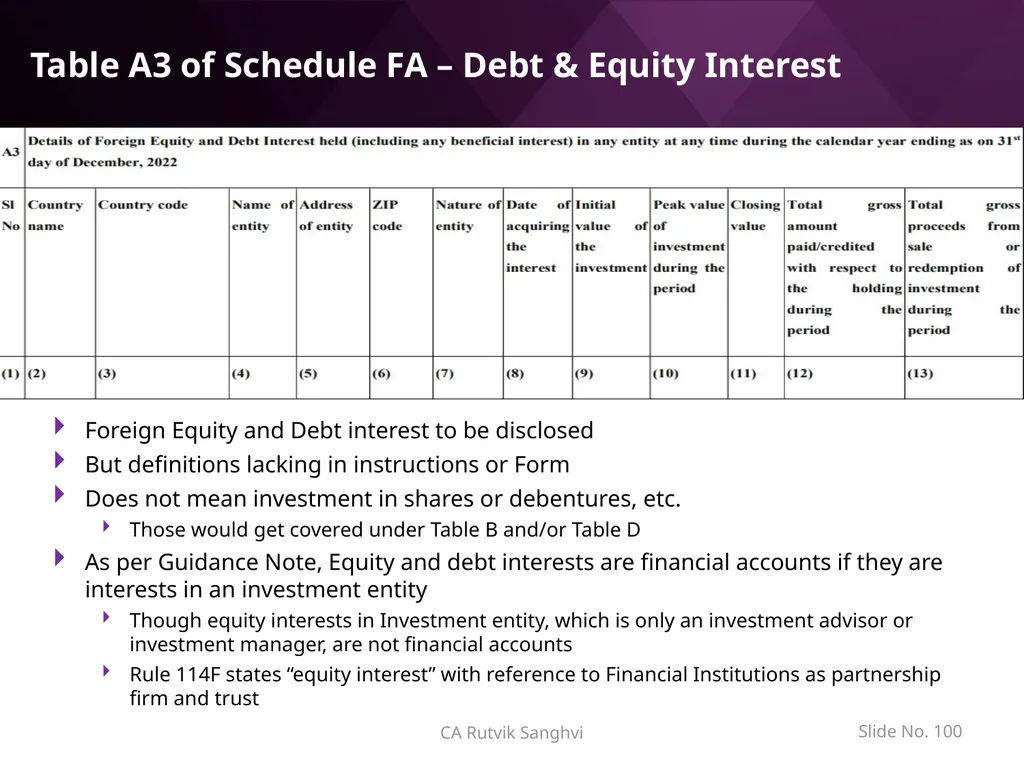
slide100. Table A3 of Schedule FA – Debt & Equity Interest Foreign Equity and Debt interest to be disclosed
But definitions lacking in instructions or Form
Does not mean investment in shares or debentures, etc.
Those would get covered under Table B and/or Table D
As per Guidance Note, Equity and debt interests are financial accounts if they are interests in an investment entity
Though equity interests in Investment entity, which is only an investment advisor or investment manager, are not financial accounts
Rule 114F states “equity interest” with reference to Financial Institutions as partnership firm and trust CA Rutvik Sanghvi Slide No. 100<br>
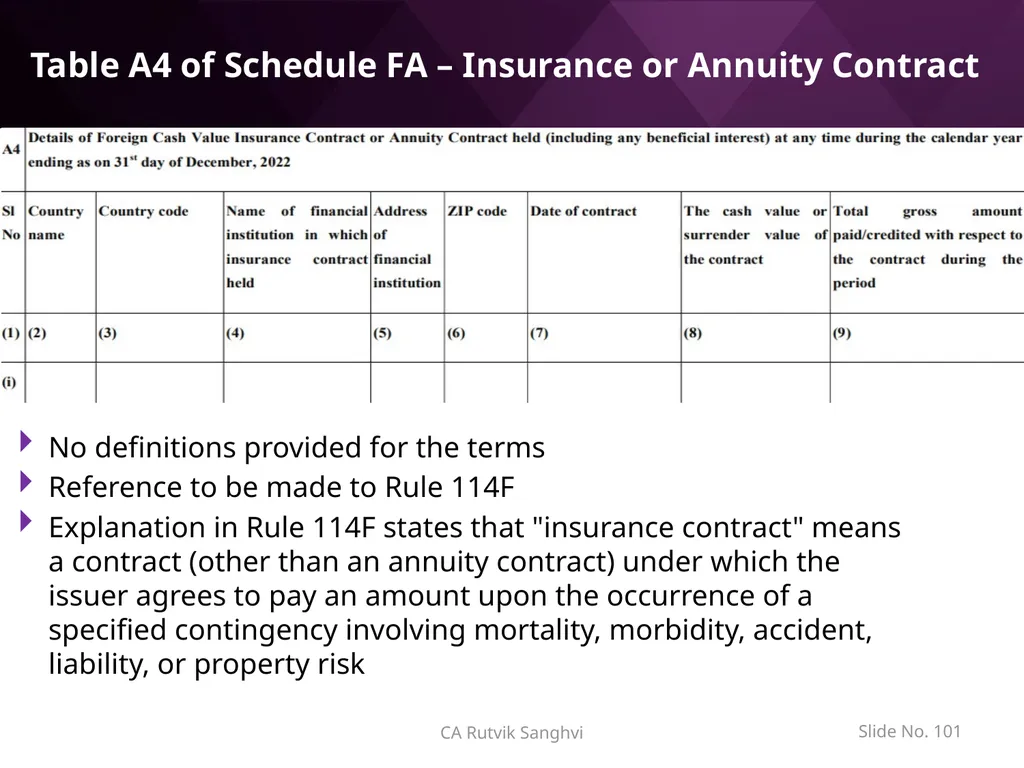
slide101. Table A4 of Schedule FA – Insurance or Annuity Contract No definitions provided for the terms
Reference to be made to Rule 114F
Explanation in Rule 114F states that "insurance contract" means a contract (other than an annuity contract) under which the issuer agrees to pay an amount upon the occurrence of a specified contingency involving mortality, morbidity, accident, liability, or property risk CA Rutvik Sanghvi Slide No. 101<br>
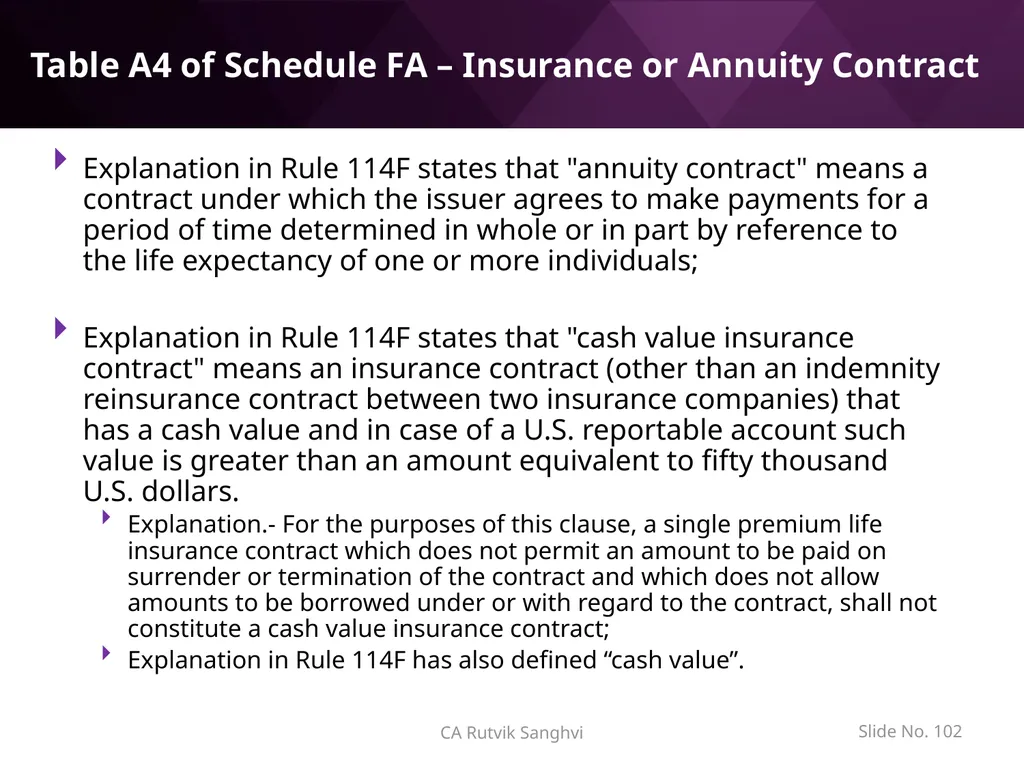
slide102. Table A4 of Schedule FA – Insurance or Annuity Contract Explanation in Rule 114F states that "annuity contract" means a contract under which the issuer agrees to make payments for a period of time determined in whole or in part by reference to the life expectancy of one or more individuals;
Explanation in Rule 114F states that "cash value insurance contract" means an insurance contract (other than an indemnity reinsurance contract between two insurance companies) that has a cash value and in case of a U.S. reportable account such value is greater than an amount equivalent to fifty thousand U.S. dollars.
Explanation.- For the purposes of this clause, a single premium life insurance contract which does not permit an amount to be paid on surrender or termination of the contract and which does not allow amounts to be borrowed under or with regard to the contract, shall not constitute a cash value insurance contract;
Explanation in Rule 114F has also defined “cash value”. CA Rutvik Sanghvi Slide No. 102<br>
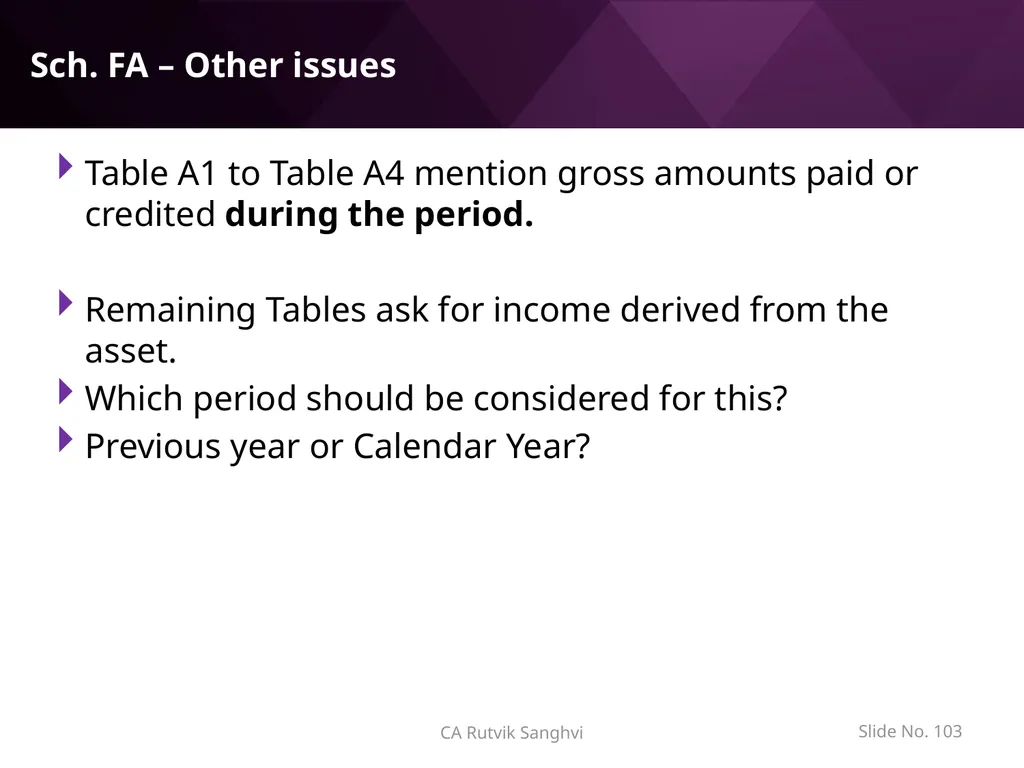
slide103. Sch. FA – Other issues Table A1 to Table A4 mention gross amounts paid or credited during the period.
Remaining Tables ask for income derived from the asset.
Which period should be considered for this?
Previous year or Calendar Year? CA Rutvik Sanghvi Slide No. 103<br>
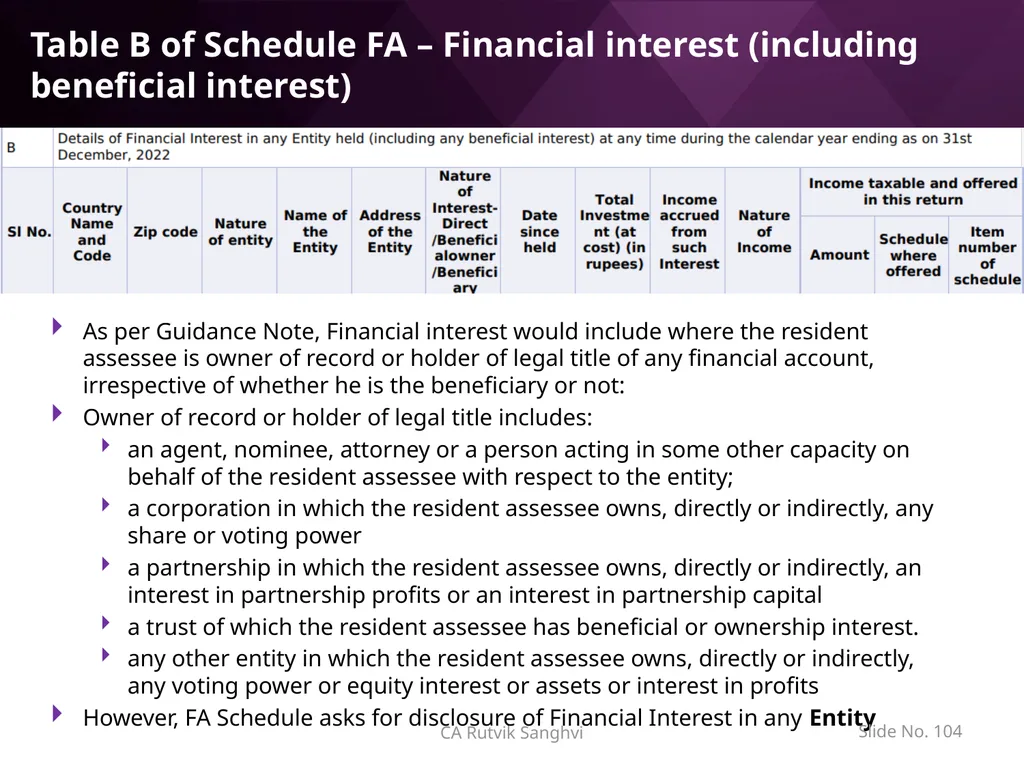
slide104. Table B of Schedule FA – Financial interest (including beneficial interest) As per Guidance Note, Financial interest would include where the resident assessee is owner of record or holder of legal title of any financial account, irrespective of whether he is the beneficiary or not:
Owner of record or holder of legal title includes:
an agent, nominee, attorney or a person acting in some other capacity on behalf of the resident assessee with respect to the entity;
a corporation in which the resident assessee owns, directly or indirectly, any share or voting power
a partnership in which the resident assessee owns, directly or indirectly, an interest in partnership profits or an interest in partnership capital
a trust of which the resident assessee has beneficial or ownership interest.
any other entity in which the resident assessee owns, directly or indirectly, any voting power or equity interest or assets or interest in profits
However, FA Schedule asks for disclosure of Financial Interest in any Entity CA Rutvik Sanghvi Slide No. 104<br>
slide105. Table B of Schedule FA – Financial interest (including beneficial interest) Issues:
If the foreign shares are held by the resident in their own name, the shares shall be reported under
Table A3 ‐ Foreign equity and debt interest;
Table B ‐ Financial interest in any entity outside India; or
Table D ‐ Any other capital assets outside India?
Depends on the type of investment being made CA Rutvik Sanghvi Slide No. 105<br>
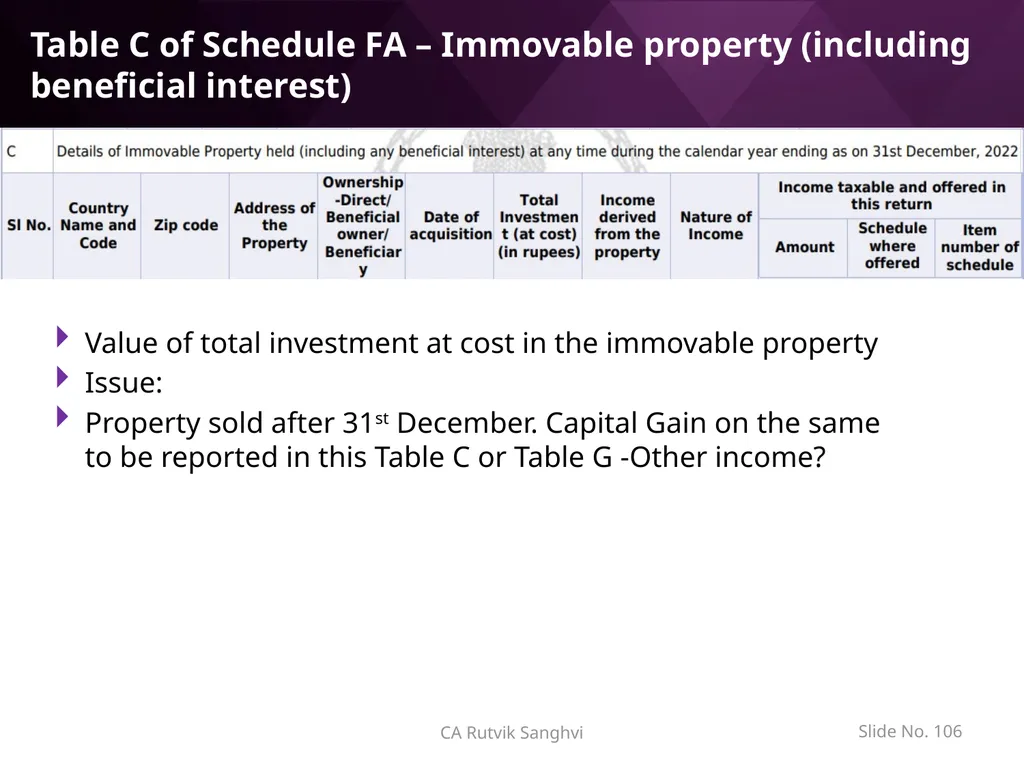
slide106. Table C of Schedule FA – Immovable property (including beneficial interest) CA Rutvik Sanghvi Slide No. 106 Value of total investment at cost in the immovable property
Issue:
Property sold after 31st December. Capital Gain on the same to be reported in this Table C or Table G -Other income?<br>
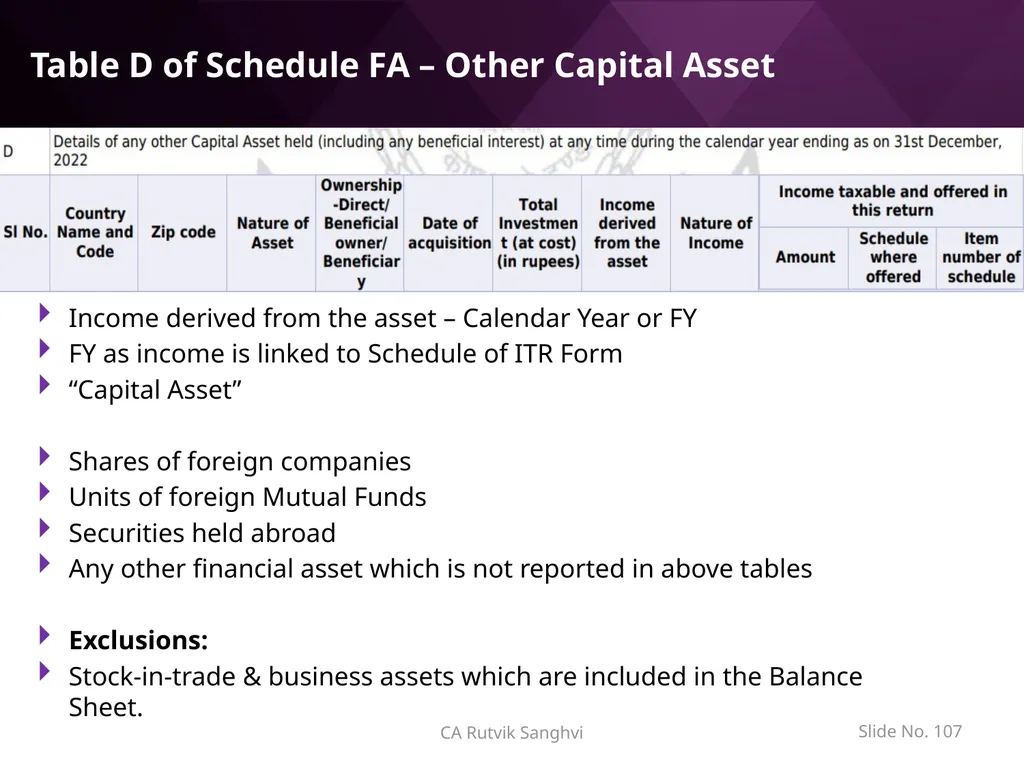
slide107. Table D of Schedule FA – Other Capital Asset Income derived from the asset – Calendar Year or FY
FY as income is linked to Schedule of ITR Form
“Capital Asset”
Shares of foreign companies
Units of foreign Mutual Funds
Securities held abroad
Any other financial asset which is not reported in above tables
Exclusions:
Stock‐in‐trade & business assets which are included in the Balance Sheet. CA Rutvik Sanghvi Slide No. 107<br>
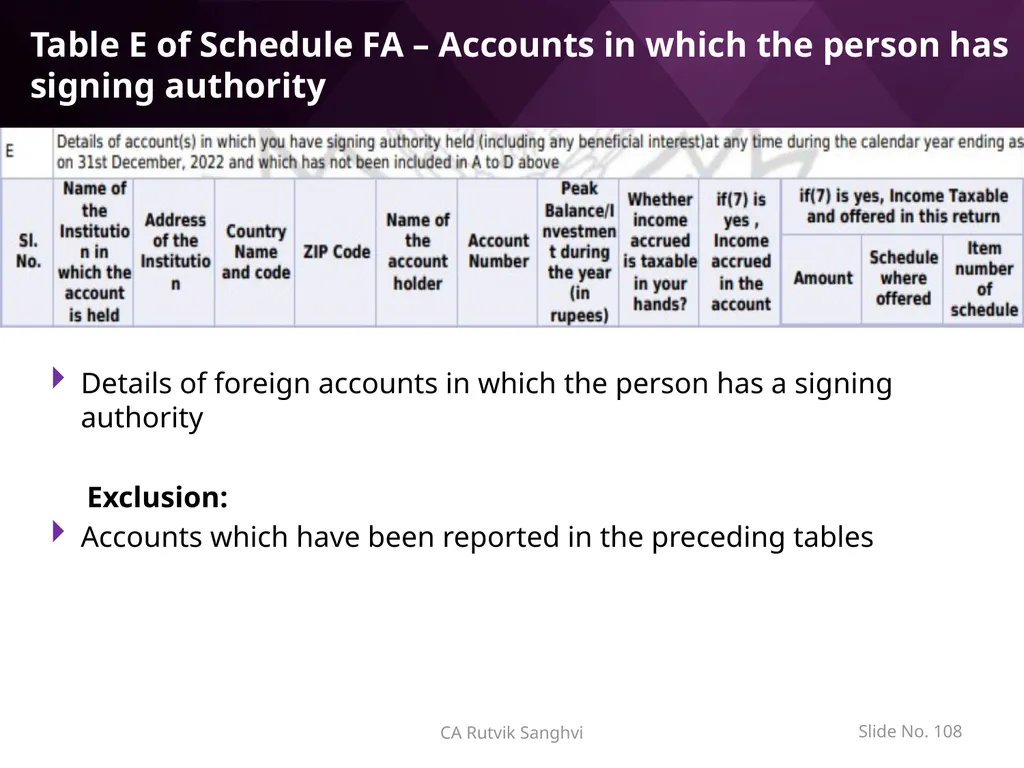
slide108. Table E of Schedule FA – Accounts in which the person has signing authority Details of foreign accounts in which the person has a signing authority
Exclusion:
Accounts which have been reported in the preceding tables CA Rutvik Sanghvi Slide No. 108<br>
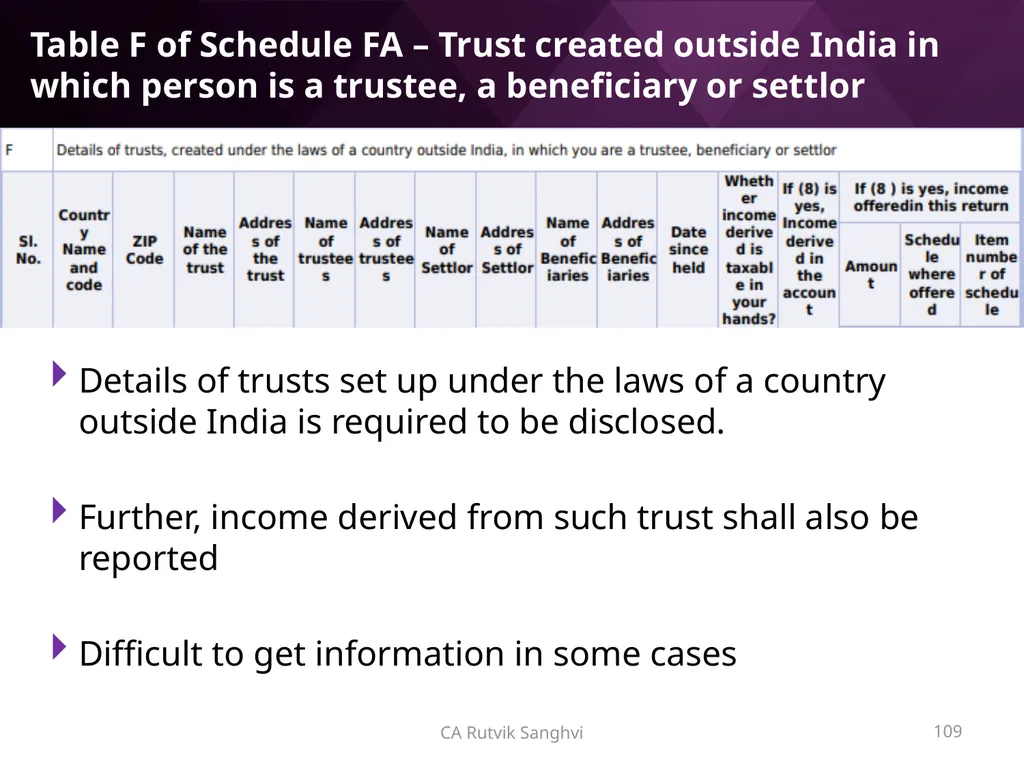
slide109. Table F of Schedule FA – Trust created outside India in which person is a trustee, a beneficiary or settlor Details of trusts set up under the laws of a country outside India is required to be disclosed.
Further, income derived from such trust shall also be reported
Difficult to get information in some cases 109 CA Rutvik Sanghvi<br>
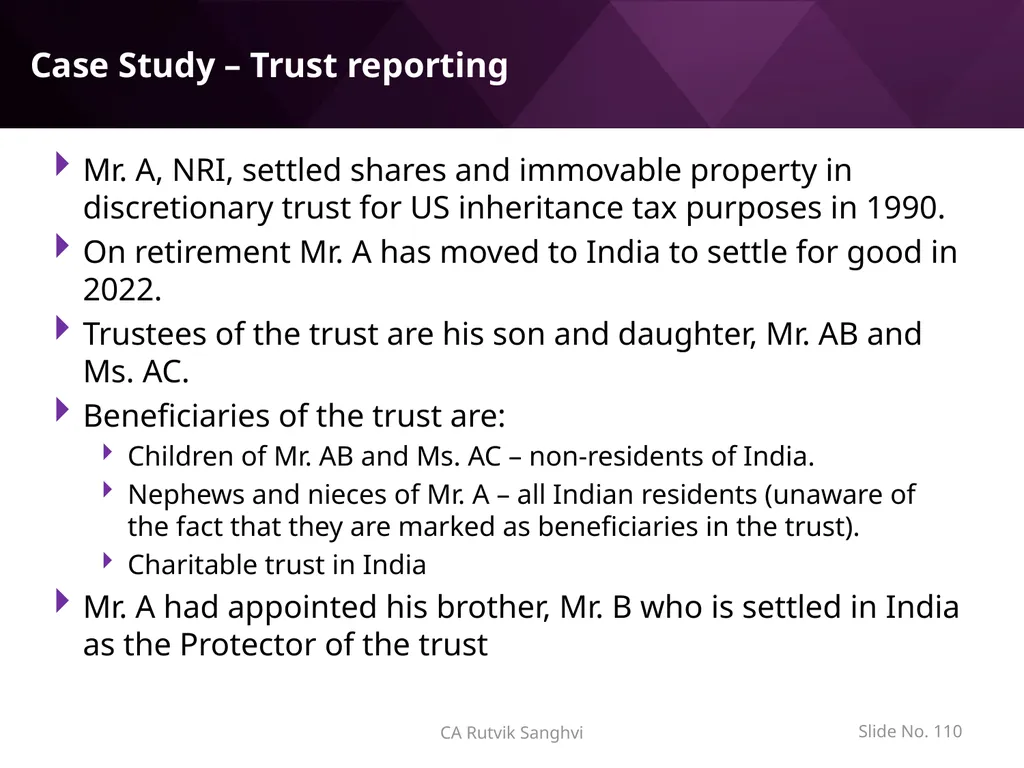
slide110. Case Study – Trust reporting Mr. A, NRI, settled shares and immovable property in discretionary trust for US inheritance tax purposes in 1990.
On retirement Mr. A has moved to India to settle for good in 2022.
Trustees of the trust are his son and daughter, Mr. AB and Ms. AC.
Beneficiaries of the trust are:
Children of Mr. AB and Ms. AC – non-residents of India.
Nephews and nieces of Mr. A – all Indian residents (unaware of the fact that they are marked as beneficiaries in the trust).
Charitable trust in India
Mr. A had appointed his brother, Mr. B who is settled in India as the Protector of the trust Slide No. 110 CA Rutvik Sanghvi<br>
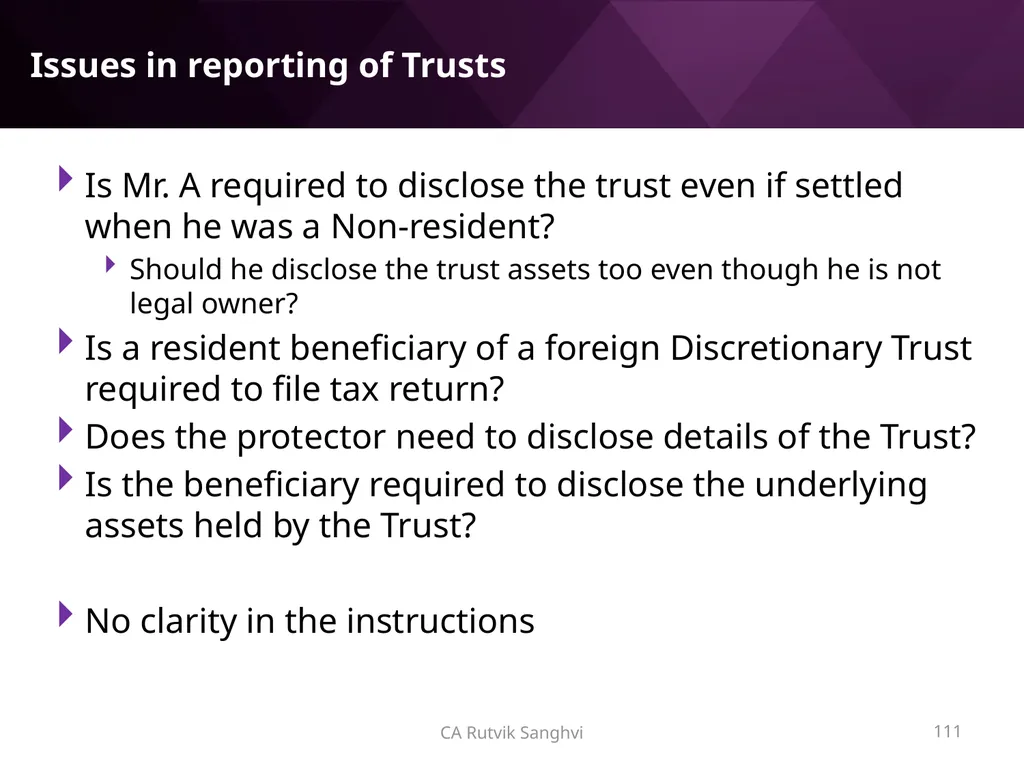
slide111. Issues in reporting of Trusts Is Mr. A required to disclose the trust even if settled when he was a Non-resident?
Should he disclose the trust assets too even though he is not legal owner?
Is a resident beneficiary of a foreign Discretionary Trust required to file tax return?
Does the protector need to disclose details of the Trust?
Is the beneficiary required to disclose the underlying assets held by the Trust?
No clarity in the instructions 111 CA Rutvik Sanghvi<br>
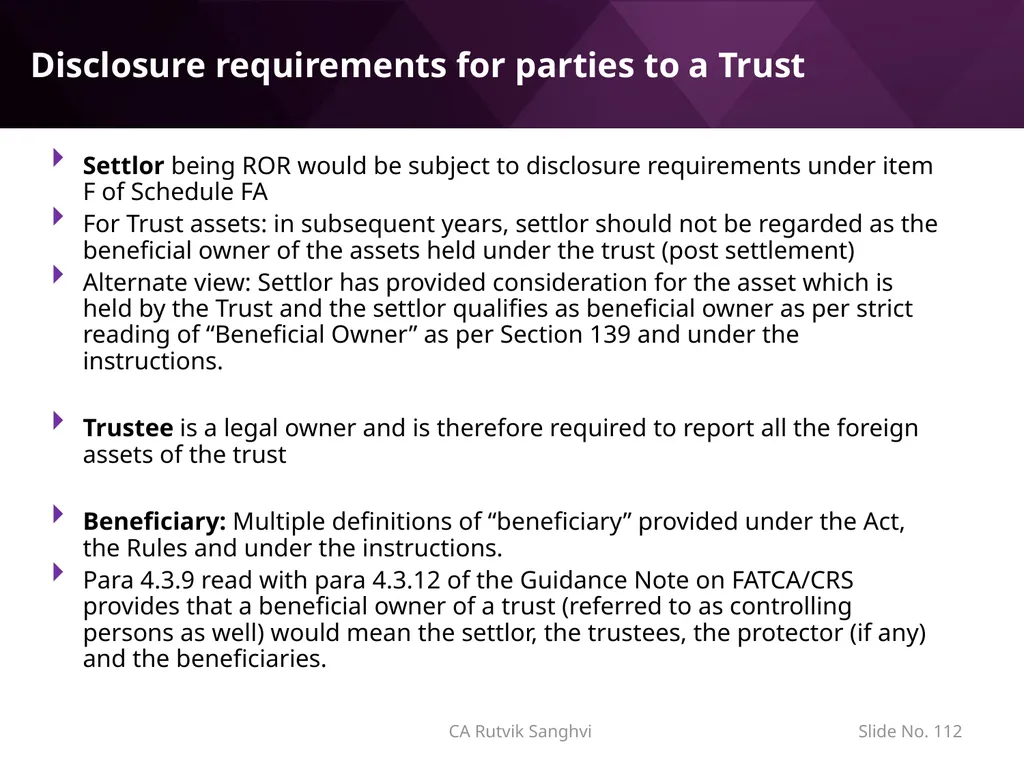
slide112. Disclosure requirements for parties to a Trust Settlor being ROR would be subject to disclosure requirements under item F of Schedule FA
For Trust assets: in subsequent years, settlor should not be regarded as the beneficial owner of the assets held under the trust (post settlement)
Alternate view: Settlor has provided consideration for the asset which is held by the Trust and the settlor qualifies as beneficial owner as per strict reading of “Beneficial Owner” as per Section 139 and under the instructions.
Trustee is a legal owner and is therefore required to report all the foreign assets of the trust
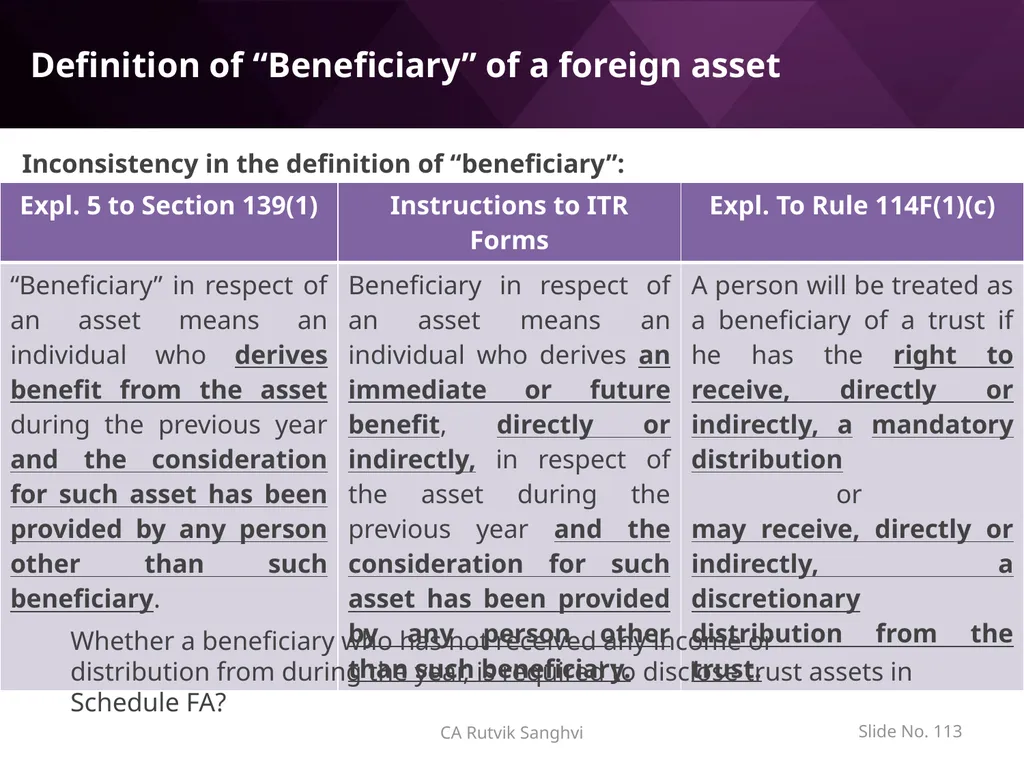
Beneficiary: Multiple definitions of “beneficiary” provided under the Act, the Rules and under the instructions.
Para 4.3.9 read with para 4.3.12 of the Guidance Note on FATCA/CRS provides that a beneficial owner of a trust (referred to as controlling persons as well) would mean the settlor, the trustees, the protector (if any) and the beneficiaries. CA Rutvik Sanghvi Slide No. 112<br>
slide113. Definition of “Beneficiary” of a foreign asset Slide No. 113 Inconsistency in the definition of “beneficiary”: CA Rutvik Sanghvi Whether a beneficiary who has not received any income or distribution from during the year, is required to disclose trust assets in Schedule FA?<br>
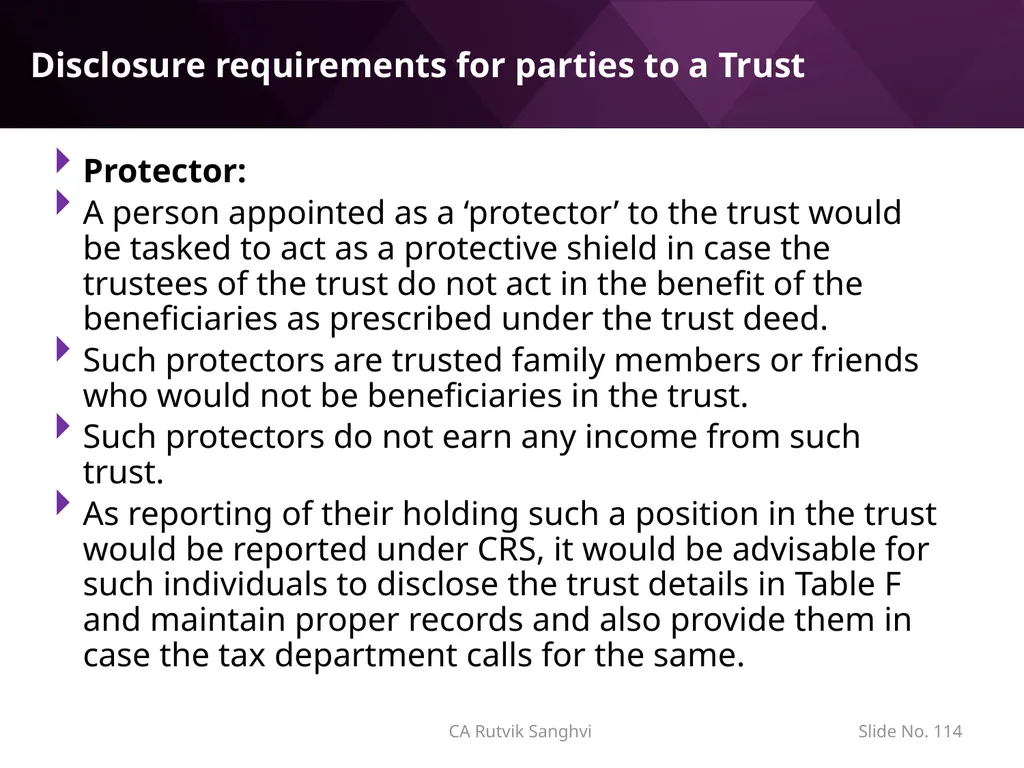
slide114. Disclosure requirements for parties to a Trust Protector:
A person appointed as a ‘protector’ to the trust would be tasked to act as a protective shield in case the trustees of the trust do not act in the benefit of the beneficiaries as prescribed under the trust deed.
Such protectors are trusted family members or friends who would not be beneficiaries in the trust.
Such protectors do not earn any income from such trust.
As reporting of their holding such a position in the trust would be reported under CRS, it would be advisable for such individuals to disclose the trust details in Table F and maintain proper records and also provide them in case the tax department calls for the same. CA Rutvik Sanghvi Slide No. 114<br>
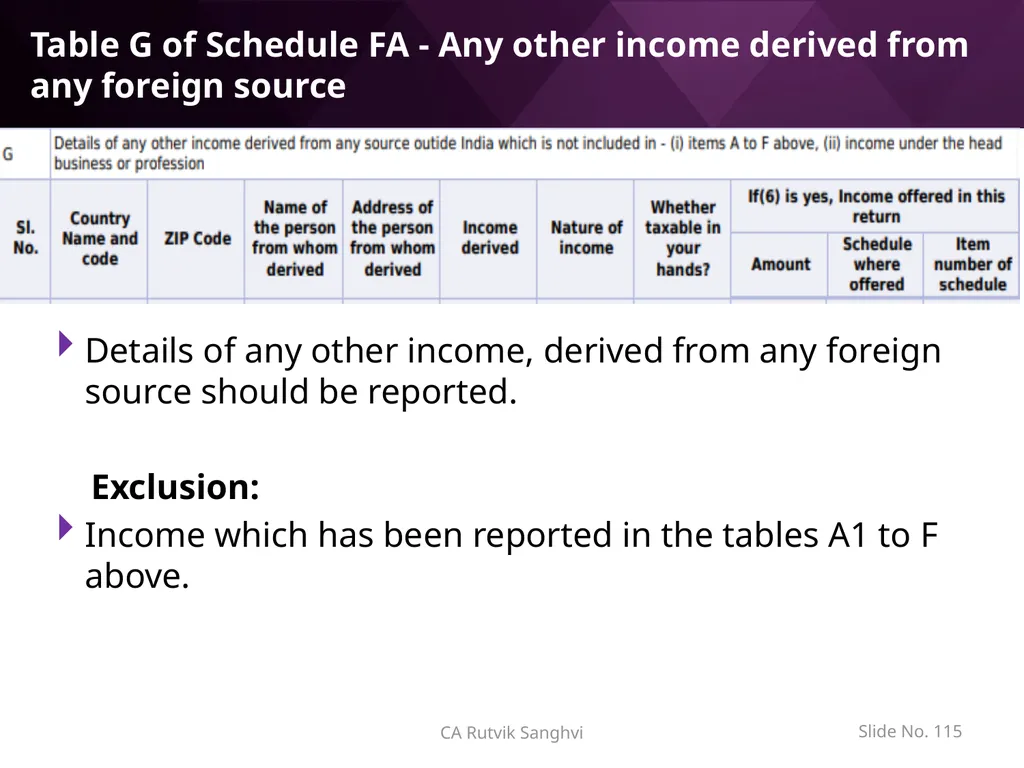
slide115. Table G of Schedule FA - Any other income derived from any foreign source Details of any other income, derived from any foreign source should be reported.
Exclusion:
Income which has been reported in the tables A1 to F above. CA Rutvik Sanghvi Slide No. 115<br>
slide116. Foreign Assets Disclosures – WHEN??<br>
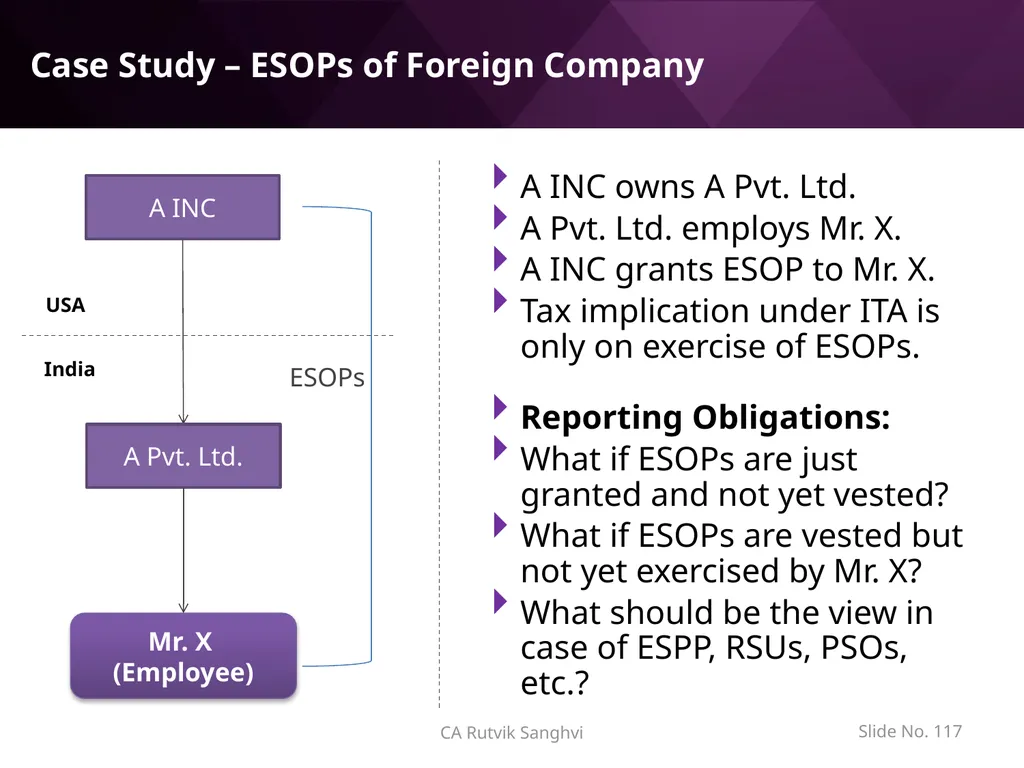
slide117. Case Study – ESOPs of Foreign Company A INC owns A Pvt. Ltd.
A Pvt. Ltd. employs Mr. X.
A INC grants ESOP to Mr. X.
Tax implication under ITA is only on exercise of ESOPs.
Reporting Obligations:
What if ESOPs are just granted and not yet vested?
What if ESOPs are vested but not yet exercised by Mr. X?
What should be the view in case of ESPP, RSUs, PSOs, etc.? CA Rutvik Sanghvi Slide No. 117 USA India A INC Mr. X
(Employee) A Pvt. Ltd. ESOPs<br>
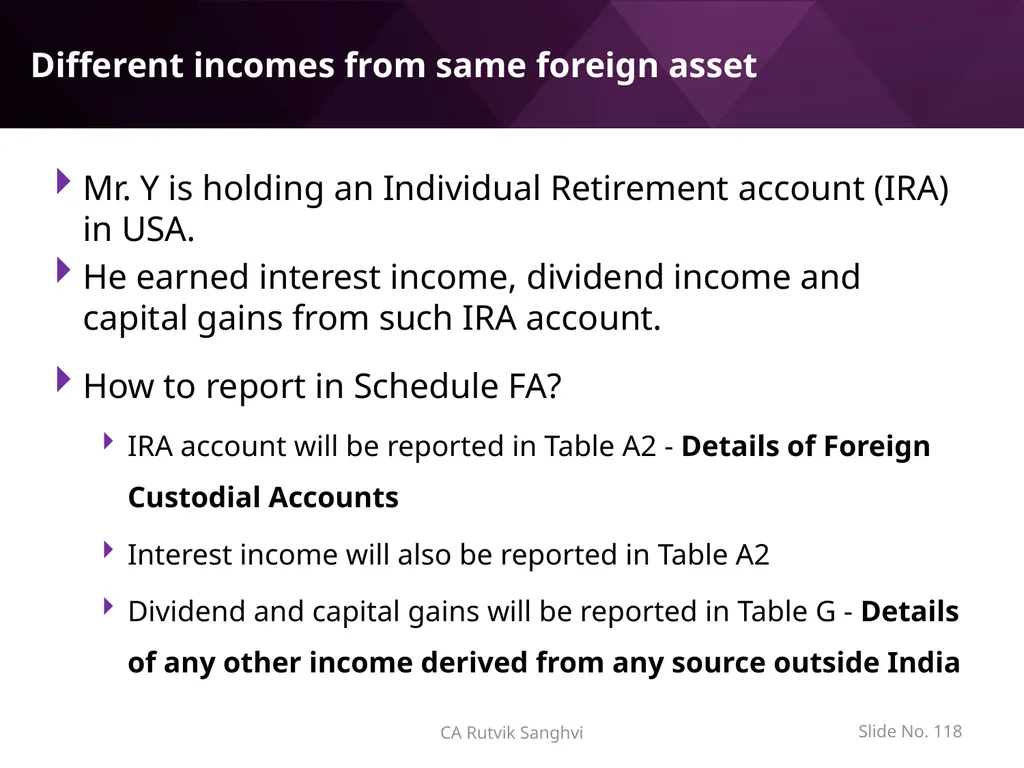
slide118. Different incomes from same foreign asset Mr. Y is holding an Individual Retirement account (IRA) in USA.
He earned interest income, dividend income and capital gains from such IRA account.
How to report in Schedule FA?
IRA account will be reported in Table A2 - Details of Foreign Custodial Accounts
Interest income will also be reported in Table A2
Dividend and capital gains will be reported in Table G - Details of any other income derived from any source outside India CA Rutvik Sanghvi Slide No. 118<br>
slide119. Foreign assets which may not get reported ESOPs of foreign companies granted, but not yet vested
Vehicles, etc., if not capital assets
Stock-in-trade & Business assets included in Balance Sheet
However, caution to be taken and disclosure to be made on conservative basis CA Rutvik Sanghvi Slide No. 119<br>
slide120. Disclosures required at other places Reporting of Unlisted equity shares
In PART A – General of ITR form reporting of Unlisted Equity shares is required
Required of any company, whether domestic or foreign
Reporting required even if the foreign unlisted equity shares are reported in the Schedule FA
Even if the unlisted equity shares are held as a stock in trade
Exemption for shares of foreign company registered on a recognised stock exchange outside India
Disclosure of Directorships in foreign companies
Resident required to disclose directorships in Foreign Companies in PART A – General
Need to choose “foreign company” in the drop-down provided for “type of company”. In such case, PAN is not mandatory CA Rutvik Sanghvi Slide No. 120<br>
slide121. Disclosures required at other places Schedule EI - Incomes exempt as per DTAA
To report foreign incomes which are exempt under DTAA.
And in Table G of Schedule FA.
Schedule AL
If you have held foreign assets during the previous year which have been duly reported in the Schedule FA. Even then you are required to report such foreign asset again in the Schedule AL (if applicable).
Relief u/s. 89A
Incomes earned in Foreign Retirement Benefits Account
New provision introduced by FA 2021, w.e.f. 1st April 2022 CA Rutvik Sanghvi Slide No. 121<br>
slide122. Taxability of Foreign incomes Incomes earned on foreign assets liable to tax in India
Including those not taxable in foreign country
Accounting or tax treatment in foreign country not relevant
Incomes earned in Retirement Benefits account, Pension, Social Security Benefit, etc.
Unless not taxable as per DTAA with India
Relief available without treaty too – but only where DTAA not applicable
Foreign tax credit allowed in India for taxes paid in foreign country
Form 67 to be filed
Computation to be done, if necessary, on estimated basis
Cost-benefit analysis CA Rutvik Sanghvi 122<br>
slide123. Other Tax issues to be considered Slide No.: 123 Place of Effective Management (PoEM)
Transfer Pricing compliance:
Form 3CEB, 3CEAA, 3CEAB, 3CEAC, etc.
Sch. TPSA - Secondary adjustment under Transfer Pricing
Section 94B impact - Clause 30B of Tax Audit Report
Valuation under Sections 56(2)(x) and 56(2)(viib)
Dividend taxation
Tax on dividend distributions at various stages
Underlying Tax Credits (UTC) available in DTAA with only couple of countries - Mauritius and Singapore
UTC available only to Indian companies, not other entities
80M deduction available but tax applicable at high slab rates in hands of individual shareholders/promoters
GAAR and other tax anti-avoidance measures CA Rutvik Sanghvi<br>
slide124. Exchange of Information Automatic Exchange of Information in place since several years
Most countries are eager to share information
Especially tax havens
Gone are the days of tax officer not coming to know
14 FAIUs constituted – millions of data points available with tax department CA Rutvik Sanghvi 124<br>
slide125. Consequences of non-disclosure under FEMA FEMA is now more draconian than FERA for foreign assets
Prosecution which was absent from FEMA earlier now part of it again
If investment is in line with FEMA, no consequences even if not disclosed under Income-tax
Seizure of equivalent assets in India
Section 37A introduced vide Finance Act, 2015 in FEMA
Already applied by ED in a few cases to seize assets in India
Can lead to penalty and prosecution
Consequences under Black Money Act primary and substantial
Penalty of Rs. 10 lakhs
Possibility of prosecution
Chidambaram family’s cases – chargesheets filed for non-disclosure Slide No. 125 CA Rutvik Sanghvi<br>
slide126. Practical issues Slide No.: 126 Jurisdictional analysis from non-tax perspective
Hidden Costs
Automatic issue of capital without remittance
Lack of proper Accounts and Audit
Judicial strength
Political and Economic risks
Tax Havens under scanner – presumption of guilt
Foreign laws to be adhered to
Substance Requirements and BEPS/MLI impact
Succession Planning CA Rutvik Sanghvi<br>
slide127. Conclusion<br>
slide128. Issues to watch out for Residential Status:
Amendments vide FA 2020 provides for deemed NOR status – results in dilution of NR status in future years under S. 6(6)(a) when NR returns to India permanently
Persons stranded in / shifted to India during pandemic
Overseas investments reported under FEMA, but disclosure missed out in tax return
Incomplete data provided by clients – dormant bank accounts, unresponsive foreign institutions, costly exercise to dig out old data
TCS on LRS – tax department has information on investments outside India CA Rutvik Sanghvi Slide No. 128<br>
slide129. In conclusion Being conservative and disclosing all data related for Foreign Assets would help
Proper documentation required to be maintained
Explanatory notes for disclosures and Forms need to be maintained
Blunt and direct explanation to clients about risks they face
FEMA issues may need to be considered in case of non-compliance for foreign investments CA Rutvik Sanghvi Slide No. 129<br>
slide130. Thanks! Questions?
Acknowledgements: CA Bhavya Gandhi
Contact at:
rutvik@rashminsanghvi.com
www.rashminsanghvi.com CA Rutvik Sanghvi Slide No. 130<br>
slide2. LRS remittances & foreign investments by resident individuals – FEMA and Income-tax – Presentation Layout 2 CA Rutvik Sanghvi<br>
slide3. Overview<br>
slide4. FEMA – A Policy Law FEMA is a policy law
Drafted loosely
Compounded by change in position later in time
Principles keep changing as individuals keep changing
No Institutional Memory
Multiple notifications and rules can apply to a particular transaction
Inconsistencies between Govt and RBI
Recourse to appellate options limited CA Rutvik Sanghvi Slide No. 4 What cannot be done directly,
cannot be done indirectly<br>
slide5. Compliance with FEMA a must for foreign investments Overseas investments are often fraught with violations – largely due to ignorance of law and ease of doing business abroad
However, FEMA is now more draconian than FERA – especially for foreign investments
Black Money Act while targeted at income-tax also brought in provisions for seizure of assets in India if any person holds any foreign exchange, foreign security or any immovable property outside India in contravention of Section 4 of FEMA
Section 37A newly introduced vide Finance Act, 2015 in FEMA
Can lead to penalty and prosecution 5 CA Rutvik Sanghvi<br>
slide6. No one wants to make headlines for violations… 6 CA Rutvik Sanghvi<br>
slide7. Liberalised Remittance Scheme<br>
slide8. Routes under FEMA for cross-border transactions CA Rutvik Sanghvi 8<br>
slide9. How FEMA operates for transactions 9 CA Rutvik Sanghvi Sections 3 and 4 – Blanket prohibitions<br>
slide10. How FEMA operates 10 CA Rutvik Sanghvi<br>
slide11. Difference between Current and Capital Account Transactions Illustrations: CA Rutvik Sanghvi 11<br>
slide12. Current Account Transaction Rules, 2000 (CAT Rules) Sch. I - Prohibited transactions
Sch. II – Transactions which require prior approval of CG
Sch. III – Transactions allowed upto the prescribed limits
Beyond prescribed limit – prior approval of RBI
Earlier, there was specific limit for each type of transaction
Now, there are very few limits for entities.
However, individuals are subjected to the LRS limit.
CAT Rules sought to provide reasonable restrictions on only certain transactions
No restriction/ limit on other Current Account Transactions 12 CA Rutvik Sanghvi<br>
slide13. Permissible Capital Account Transactions Regulations, 2000 FEMA Notification No. 1 lists Permissible Capital Account Transactions
Overseas Investment is a Capital Account Transaction
FEMA Notfn. No. 120 “Transfer or Issue of any Foreign Security” laid down Overseas Investment regulations
Unless permitted, transaction is prohibited
Regulated by RBI & enforced by ED
Powers taken by CG w.r.t. non-debt instruments in 2015
New Overseas Investment regime notified in August 2022 in supersession of FEMA Notification 120 13 CA Rutvik Sanghvi<br>
slide14. Liberalised Remittance Scheme<br>
slide15. Liberalised Remittance Scheme LRS limit brought in as a relief to all Indian Residents to remit money outside India
Up to USD 250,000 per financial year can be remitted
Introduced on February 4, 2004, with a limit of USD 25,000
Limit has increased over the years but is subject to forex position with RBI
Available to all Resident Individuals including minors
LRS earlier could be used over & above the limits specified in CAT Rules
Now, all earlier facilities for release of exchange or for remittances for current account transactions under Para 1 of Schedule III are subsumed under the overall limit of USD 250,000 – no separate limits for gifts, donations, etc., 15 CA Rutvik Sanghvi<br>
slide16. LRS Limit over the years CA Rutvik Sanghvi 16<br>
slide17. Remittances under LRS over the years CA Rutvik Sanghvi 17<br>
slide18. LRS - Prohibitions LRS prohibited:
For remittance to FATF identified countries as “non co-operative”
Presently only Iran and North Korea
Prohibition for remittance to Mauritius, Pakistan, Nepal, Bhutan removed though FAQs silent about capital account transactions
For any purpose specifically prohibited under Schedule-I (like purchase of lottery tickets/sweep stakes, proscribed magazines, etc.) or any restricted items under Schedule II of CAT Rules
For remittance from India for margins or margin calls to overseas exchanges / overseas counterparty
For remittance for trading in foreign exchange abroad.
For remittances directly or indirectly to those individuals and entities identified as posing significant risk of committing acts of terrorism
For purchase of FCCBs issued by Indian companies in the overseas secondary market CA Rutvik Sanghvi 18<br>
slide19. LRS Prohibitions contd… Remittance must be out of funds belonging to remitter
Gifts received can be remitted
Once gifted money belongs to remitter - no prohibition in sending funds under LRS
Major issue leading to tax department queries and hence TCS!
Cannot be out of loaned funds?
Master Direction - Banks prohibited from providing credit facilities to facilitate capital account remittances under LRS Scheme
FAQ 16 – Credit facilities allowed for Current Account transactions
What about borrowing from private parties for current account transactions like education & medical expenses
Practically allowed and happening CA Rutvik Sanghvi 19<br>
slide20. Mr. C, Indian resident buys IP outside India.
He makes down-payment for the same.
The balance payment is made:
In instalments; or
Out of loan taken abroad.
Instalments for part payment of already constructed premises lead to financial commitment - Not allowed
Instalments called for as construction progresses – allowed upto LRS
Loans not allowed all
Widely marketed by realtors, but a violation. Seller Mr. C India USA Down-payment CA Rutvik Sanghvi 20 House Property Buying IP outside India by making payment on instalment basis<br>
slide21. Pre-LRS position Current Account Transactions (CAT) Rules under Schedule I prohibited and Schedule II allowed only with prior approval of Government specified transactions
Current Account Transactions under Schedule III allowed upto specified limits. Above that, only with RBI Permission
CAT Rules sought to provide restrictions on only certain transactions
Other than above transactions, no restriction or limit on any Current Account Transaction
All Capital Account transactions restricted
Allowed only as specified under Notifications issued by RBI under Section 6 of FEMA, now by Government directly
LRS sought to provide relief from these restrictions up to LRS Limit
Now both restrictions on Current Account Transactions and relief for Capital Account Transactions covered under LRS
Leads to confusion and incorrect application of India’s clear position on Full Current Account Convertibility CA Rutvik Sanghvi 21<br>
slide22. Liberalised Remittance Scheme – Flip Flop Policy LRS when introduced was with clear objective to allow Resident Individuals to remit funds within LRS limit for “any purpose”:
For any Current Account Transaction; or
For any Capital Account Transaction; or
For a combination of both!
Funds up to the limit would be partial capital account convertibility
Can be used to purchase any asset outside India without approval of RBI
Limit of LRS was in addition to limit under Schedule III CA Rutvik Sanghvi 22<br>
slide23. Liberalised Remittance Scheme – Flip Flop Policy Famous Quotes:
RBI Deputy Governor: “We are flush with funds. Use LRS for any purpose – you can as well throw the remitted funds from the Alps.”
In 2004 forex reserves were around USD 100 Billion
RBI Governor Dr. Y V Reddy in his book “Advice & Dissent” quotes Mr. Jaswant Singh, then FM:
“Go and conquer the world, we will be your supporters.”
“This is a no-questions asked window and was in addition to all the existing facilities.”
“The oppressive forex regime that had haunted individuals in India since 1957 was put to an end on 19 February 2004” CA Rutvik Sanghvi 23<br>
slide24. Liberalised Remittance Scheme – Flip Flop Policy Drastic change in position brought in from May 2007
LRS can be used to remit for any ‘permissible’ current or capital account transaction or a combination of both
No guidance on what is ‘permissible’ transaction in 2007
Paradoxical situation as LRS was introduced to allow transactions which otherwise required prior approval!
Permissible capital account transactions under LRS specified only in 2015 as:
Opening of foreign currency account abroad with a bank;
Purchase of property abroad;
Making investments abroad;
Setting up Wholly owned subsidiaries and Joint Ventures abroad;
Extending loans including loans in Indian Rupees to Non-resident Indians (NRIs) who are relatives as defined in Companies Act, 2013. CA Rutvik Sanghvi 24<br>
slide25. LRS - “Current” Account Transactions LRS specifies “permissible” current account transactions
(i) Private visits to any country (except Nepal and Bhutan).
(ii) Gift or donation.
(iii) Going abroad for employment.
(v) Maintenance of close relatives abroad.
(vi) Travel for business or attending a conference or specialised training; or for meeting expenses for meeting medical expenses, or check-up abroad; or for accompanying as attendant to a patient going abroad for medical treatment/ check-up.
(vii) Expenses in connection with medical treatment abroad.
(viii) Studies abroad.
(ix) Any other current account transaction CA Rutvik Sanghvi 25<br>
slide26. LRS - “Current” Account Transactions Limits for Gifts and Donations subsumed under LRS limit
Gift of funds by one resident to another resident outside India not allowed
Gift or donation to non-residents is allowed
But Gift to NRI’s NRO and NRE Account included within LRS limit
Gift of shares limited to USD 50,000 CA Rutvik Sanghvi 26<br>
slide27. LRS - “Capital” Account Transactions Permissible Capital Account Transactions under LRS at present are:
Opening of foreign currency account abroad with a bank;
Acquisition of immovable property abroad
Overseas Direct Investment (ODI)
Overseas Portfolio Investment (OPI)
Extending loans including loans in Indian Rupees to Non-resident Indians (NRIs) who are relatives as defined in Companies Act, 2013. CA Rutvik Sanghvi 27<br>
slide28. LRS - “Capital” Account Transactions Other Capital Account transactions not allowed:
Asset purchased outside India, unless brought into India, lead to capital account transactions
Gold
Art
Long-term lease tantamount to purchase of asset also covered
Guarantees
“Property” mentioned in CAT Rules does not mean all assets
Intention is to cover only immovable property CA Rutvik Sanghvi 28<br>
slide29. Liberalised Remittance Scheme - Issues Can assets be kept outside India?
What about inheritance?
What about change of residence?
Does income earned on such assets have to be remitted back to India?
Income and sum remitted need not be brought back into India and can be reinvested overseas CA Rutvik Sanghvi 29<br>
slide30. LRS – Beyond limits? Prior Approval needed from RBI for remittance beyond LRS limit
Possible if circumstances warrant need for enhanced remittance
Approval not required to remit more than $ 250,000 in following cases:
Emigration:
Only towards meeting incidental expenses in country of immigration.
Not for earning points or credits to become eligible for immigration by way of overseas investments in government bonds; land; commercial enterprise, etc.
Medical treatment:
Based on estimate from a doctor in India or from a hospital/ doctor abroad.
A resident who has fallen sick after proceeding abroad also covered
Additional USD 250,000 per FY allowed to the person accompanying as attendant to a patient going abroad for medical treatment/ check-up
Education: Based on fee estimate from institution/ university abroad
Banks might ask for more documentation CA Rutvik Sanghvi 30<br>
slide31. Permissible capital account transaction by an individual under LRS:
(iii) extending loans including loans in INR to NRIs who are relatives as defined in Companies Act, 2013
OR
(iii) extending loans, including loans in INR, to NRIs who are relatives as defined in Companies Act, 2013
FEMA 3(R) – Borrowing & Lending Regulations
Resident individuals allowed to grant rupee loans to NRI/ OCI relative upto LRS limit subject to prescribed terms and conditions.
Silent on loans by resident individuals to non-residents
Specific relief for providing loans to NRI relatives in INR now considered as the only permissible transaction!
Do Borrowing & Lending Regulations override LRS?
LRS was in addition to all existing facilities! CA Rutvik Sanghvi 31 Extending loans including loans in INR to NRI relatives<br>
slide32. Recent Changes in LRS<br>
slide33. CA Rutvik Sanghvi 33 Repatriation of idle funds Changes in Master Direction on LRS (Para A.16)<br>
slide34. Major change in policy
Dilutes whole purpose of the Scheme
Practical issues
Repatriation applicable to:
Funds remitted under LRS (principal amount);
Incomes earned on investments;
Sale proceeds of investments. CA Rutvik Sanghvi 34 Repatriation of idle funds within 180 days<br>
slide35. If remittance was made under LRS in 2010
Funds are lying in the bank account since then
Does the amendment apply to such funds?
Language suggests so.
No grandfathering - goes back till remittances made from 2004
Limit of 180 days starts from 24th August 2022
If funds were still lying idle till 19th February 2023 - Violation CA Rutvik Sanghvi 35 Does the amendment apply to past remittances?<br>
slide36. “Unless reinvested” – Is it compulsory to “invest”?
Can the funds be used for any other permissible purpose?
Change of use was always allowed
One may intimate the bank out of caution
Spending funds also allowed.
Funds should be either “reinvested” or “used” within 180 days
Only for permissible purposes CA Rutvik Sanghvi 36 If the funds are not invested, but spent within 180 days<br>
slide37. If funds are not used/ invested within 180 days: Violation.
Violation needs to be regularised first.
To regularise means to take corrective action – what should have been done earlier.
Does it mean reinvest/ use the funds after the limit is breached??
Allowing investment or utilisation after 180 days defeats the whole purpose of amendment
One will have to repatriate the funds back to India and utilise LRS limit of the respective year to again remit the funds
Violation requires compounding after regularisation. CA Rutvik Sanghvi 37 What if the funds are not invested/ utilised within 180 days?<br>
slide38. Normal cases like education, medical treatment, etc., stuck.
Minimum balance to be maintained in foreign bank accounts to avail services.
Accumulation of funds to acquire high value property – plans gone for a toss
Unfair change without intimation or advance warning – euphemistically to bring the remittance in line with
Keeping track of funds invested, reinvested, incomes earned, incomes invested CA Rutvik Sanghvi 38 Practical issues<br>
slide39. CA Rutvik Sanghvi 39 Interest Mr. A India USA Dividend Funds in Brokerage Account Shares Sale proceeds 180-day limit to be checked from respective date of receipt Keeping track of funds - Illustration<br>
slide40. CA Rutvik Sanghvi 40 Keeping track of funds - Illustration<br>
slide41. TCS on remittances under LRS – 1st October 2023 onwards Slide No.: 41 CA Rutvik Sanghvi<br>
slide42. Important development linked to TCS on LRS FAQs issued on 18th May 2023 clarify certain positions regarding TCS on LRS
What about business visit of employees?
When an employee is deputed abroad, the expenses are borne by the employer. These expenses will be outside LRS and may be permitted by bank without any limit
Only for bonafide purposes
For travel and incidental expenses related to education and medical treatment – lower rate should only apply. Detailed clarification to be issued separately.
Reasons provided for levy of TCS in FAQs issued on 18th May 2023
20% rate is not too high even for those not having taxable incomes!
Comparison provided with slab rates of 30%
LRS payments are disproportionately high when compared to declared incomes
ICCs brought under LRS net since many were flouting the LRS limits and also to bring parity with other modes of payment CA Rutvik Sanghvi 42<br>
slide43. Concessional rate of TCS for specified purpose and change of use later on TCS @ 20% from 1st July 2023 without threshold
TCS @ 5% for education and medical purposes
If funds are sent for education or medical purpose.
Later the funds are used for other purpose or invested?
No penal provisions triggered.
Conservatively, intimate the bank and ask them to collect balance amount of tax at source.
However, Banks may not be enabled to collect TCS later CA Rutvik Sanghvi 43<br>
slide44. Overseas Investment by Resident Individuals under LRS<br>
slide45. Overseas Investment – Classification under new regime Slide No.: 45 Investment in Foreign Securities Overseas Investment Equity
(ODI) Debt* Financial Commitment Overseas Portfolio Investment (OPI) Guarantee* Excludes:
Overseas Direct Investment (ODI)
Unlisted Debt instrument
Security issued by PRII who is not in IFSC
Derivatives or commodities * ODI + Control required CA Rutvik Sanghvi<br>
slide46. Overseas Investment – New regime from 22nd August 2022 New OI regime has replaced a very old set of regulations under FEMA 120
Supersession of old FEMA regime of FEMA 120 (Transfer or Issue of Foreign Security) which was applicable from 2004 till 2022
7(R) (Acquisition or Transfer of Immovable Property outside India)
Covers all Overseas Investments including Immovable Property outside India
Clarifications, Simplification, Relaxations
Removal of requirement for approvals in certain cases
Relaxations for investment in strategic sectors
Changes in Compounding regime to LSF
Combined LSF Matrix for FDI, ECB & OI now
Even then quite a few unresolved/grey areas
No FAQs announced even after 1 year! Slide No. 46 CA Rutvik Sanghvi<br>
slide47. Listed v/s. Unlisted entities Slide No.: 47 Always ODI*
0.01% to 100% Person resident in India ODI*
10% or more; or
Control
OPI
Less than 10%
+
No Control Listed
Foreign Entity Unlisted
Foreign Entity * Subscription to MOA means ODI,
irrespective of holding & type of entity CA Rutvik Sanghvi<br>
slide48. Case Study – Investment in Listed v/s. Unlisted entities Slide No.: 48 A LLC
(Unlisted) A Pvt. Ltd. B INC
(Listed) C INC
(Listed) D INC
(Listed) 2%
Without Control 2%
Without Control 2%
With Control 15%
Without Control India USA CA Rutvik Sanghvi<br>
slide49. ODI vs. OPI Slide No. 49 Is investment by way of subscription as a part of MoA? Does the Indian Entity or resident individual have Control? OPI ODI Is it acquisition of Equity Capital of an Unlisted Entity? Is the investment 10% or more of the Equity Capital? CA Rutvik Sanghvi<br>
slide50. Case Study – Investment in Listed v/s. Unlisted entities Slide No.: 50 A LLC
(Unlisted) A Pvt. Ltd. B INC
(Listed) C INC
(Listed) D INC
(Listed) 2%
Without Control ODI 2%
Without Control OPI 2%
With Control 15%
Without Control ODI ODI CA Rutvik Sanghvi<br>
slide51. Clarity on OPI vs ODI FEMA 120 was silent on what is portfolio investment and what is ODI
Investors and AD Banks had their own interpretations
Ranging from 5-25% of equity stake
OI Rules have clarified now between OPI and ODI
ODI means Investment by way of:
Investment in > 10% of paid-up equity capital of a listed FE
Investment with control in a listed FE (0.01% to 100%)
Acquisition of unlisted equity capital of a FE (starting from even 1 share)
Subscription to MOA of a Foreign Entity (FE)
Holding even 1 unlisted share becomes ODI!!
OPI means investment other than ODI Slide No. 51 CA Rutvik Sanghvi<br>
slide52. Important concepts for ODI Slide No.: 52 Important terms – Foreign entity, Financial Commitment, ODI, Subsidiary, Sweat equity shares, Bonafide business activity
Non-applicability of OI Rules in certain cases
No Objection Certificate
Pricing guidelines
Disinvestment alternatives and conditions
Restructuring of foreign entity’s balance sheet
Sectoral prohibitions
Real estate,
Gambling and
Dealing with products linked to INR
Round tripping CA Rutvik Sanghvi<br>
slide53. Important concepts for ODI Slide No.: 53 Start-ups
Financial Services activities
Special reliefs for investments in IFSC
Limit of Financial Commitment – 400% of net worth of Indian entity
Debt and guarantee
Pledge and charge
Deferred consideration
Reporting obligations
Restriction on further investment or disinvestment in case of reporting delays
Late Submission Fees CA Rutvik Sanghvi<br>
slide54. Overseas Portfolio Investment<br>
slide55. Bank Fixed Deposits: Foreign security/ unlisted debt instrument/ bank account? – Not allowed
Mutual Funds: Permitted as OPI
Investment in foreign securities
Duly regulated by the financial sector regulator in the host jurisdiction
What if Fund Manager is regulated but not the Fund itself?
What if the Master Fund is regulated but the sub-fund is not regulated?
Buying gold, paintings, etc. and keeping them abroad
Not allowed as becomes as capital account transaction.
Now only “permissible capital account transactions” allowed
Bonds of Indian companies listed on foreign stock exchanges
Not permitted. (Security issued by a resident) CA Rutvik Sanghvi 55 Investment in which assets?<br>
slide56. Investment under LRS through IFSC RBI allows resident individuals to make remittances under LRS to IFSCs in India from 16th February 2021
Remittance to be made only for making investments in securities other than those issued by entities/companies resident in India.
Resident Individuals may also open a non-interest bearing Foreign Currency Account (FCA) in IFSCs, for making the above permissible investments under LRS.
Any funds lying idle in the account for a period upto 180 days from the date of its receipt into the account shall be immediately repatriated to domestic INR account of the investor in India.
Resident Individuals shall not settle any domestic transactions with other residents through these FCAs held in IFSC. CA Rutvik Sanghvi 56<br>
slide57. Specific provisions for Overseas Investments by Resident Individual Slide No.: 57 CA Rutvik Sanghvi<br>
slide58. OI by resident individual through gift received Gift of foreign securities received from resident relative
Relative as per Companies Act
LRS limit not applicable
Donor should be holding as per FEMA
Gift of foreign securities received from non-resident
Compliance with FCRA
FCRA applies only to specified individuals
Does FCRA apply to a common Indian citizen?
Reporting requirement applicable
Section 50CA and 56(2)(x) of ITA to be considered
Gift route now brought formally under ODI framework
What about past gifts of foreign unlisted entities? Slide No. 58 CA Rutvik Sanghvi<br>
slide59. Sweat equity/ ESOP/ EBS Sweat equity shares
Overseas entity to its directors or employees
Equity shares at a discount or for consideration other than cash
For providing know-how or IP rights or value additions
ESOP/ EBS to employee or director of
an office in India or branch or subsidiary in India of an overseas entity; or
an Indian entity in which overseas entity has direct or indirect equity holding
To be offered globally on a uniform basis Slide No. 59 CA Rutvik Sanghvi<br>
slide60. Sweat equity/ ESOP/ EBS LRS limit not applicable
Such remittance shall be reckoned towards LRS limit of the person
No further remittance during the year, if the limit is breached.
Does it consume the LRS limit of future years as well?
No.
Always OPI, whether listed or unlisted, if
Less than 10% equity capital + without control;
RI can subscribe even if the foreign entity:
is engaged in FS activity; or
has step-down subsidiary where RI has control in FE Slide No. 60 CA Rutvik Sanghvi<br>
slide61. Gift of Overseas Investment by resident individual to NRs Earlier, resident individuals were allowed to gift their overseas investment to non-residents
Para 22(4) of OI Directions
Resident individuals are not allowed to gift any overseas investment to a non-resident
Major change in policy
Prohibition not applicable to S. 6(4) assets. Slide No. 61 Son Shares of Apple Inc India USA Gift Parent
Mr. Y CA Rutvik Sanghvi<br>
slide62. Immovable Property Outside India - LRS Resident individual can send remittances under LRS for purchasing IP outside India
Such IP can be:
Leased
Sold
Funds from lease and sale can be retained outside India
Funds retained can be reinvested
Multiple LRS remittances can be clubbed for purchase of high value IP
One individual can remit USD 250,000 in foreign bank account over multiple years until sufficient funds are collected CA Rutvik Sanghvi Slide No. 62<br>
slide63. Immovable Property Outside India - LRS A Resident can acquire property situated abroad from a non-resident:
Through inheritance
Through purchase our of forex held in RFC account
Through LRS remittances. Further, LRS remittances of resident relatives can be consolidated, if in compliance with overall LRS scheme
Jointly with a non-resident relative
Out of income or sale proceeds of assets acquired abroad (except ODI)
Gift of property situated abroad by a resident
Gift to a resident: Allowed
Gift to a non-resident: Silent. Not allowed. CA Rutvik Sanghvi Slide No. 63<br>
slide64. Co-ownership condition for buying IP outside India where remittances are consolidated<br>
slide65. Case Study – Investment in immovable property abroad under LRS Facts:
Shah Family intends to purchase immovable property in UAE
Property investment is of USD 1 Million
Issues:
Can multiple family members invest together?
Can property be purchased on instalment or EMI basis? 65 UAE India House Property Shah Family CA Rutvik Sanghvi<br>
slide66. Case Study – Investment in immovable property abroad under LRS Shah Family can jointly purchase property – 4 family members can remit funds of USD 250,000 to invest 1M USD
Property has to need not be in joint name in proportion to investment made
Investment cannot be out of borrowed funds in India
Individuals cannot enter into a loan agreement or financial commitment over and above LRS limit
Family Members covered
No definition for family members 66 UAE India House Property Shah Family CA Rutvik Sanghvi<br>
slide67. Streamlines the process of emigration to several countries
USA, Greece, Portugal, Spain, UAE, Austria, Malta, Turkey, Antigua, Dominica, Grenada, St. Kitts, St. Lucia, Cyprus
Funds should not be consolidated in one bank account
Gift of funds outside India between residents is not permitted
Funds to be directly paid to seller from respective account of each relative
Income-tax issues
Clubbing provisions
Automatic exchange of Information
Reporting of foreign assets in Sch. FA
Implications under Black Money Act
For inappropriate/non-reporting of foreign asset held at any time during PY
Intelligent and detailed scrutiny by FAIU
Notices issued to minors as well CA Rutvik Sanghvi 67 Implications and issues<br>
slide68. Case Study 2 – Investment in immovable property abroad under LRS through company Facts:
Mr. A, Mr. B and Mr. C incorporate a Co. in UAE through LRS
ABC Co. purchases immovable property in UAE
Issues:
Can property be purchased through company under LRS? CA Rutvik Sanghvi Slide No. 68 UAE India House Property Mr. B Mr. A Mr. C ABC Co.<br>
slide69. Case Study 2 – Investment in immovable property abroad under LRS through company Topsy-turvy history
Investment in Company allowed freely under LRS when it was introduced
LRS limit could be used for any current or capital account transaction
However, RBI changed its view
Investment after 5.8.2013 was not permitted in a Company which does not have operating business
Investment before that was also subject to compounding. RBI has taken an adverse view and advises to:
Wind up, bring back proceeds and go for compounding.
This is because even today, holding IP through a foreign entity is not permitted.
If investment was before 8.5.2007, when word “permissible” was inserted, RBI may permit to hold?
However, even prior to 5.8.2013, debt by foreign co. was not permitted. CA Rutvik Sanghvi Slide No. 69 UAE India House Property Mr. B Mr. A Mr. C ABC Co.<br>
slide70. Disclosure of Foreign Assets and Incomes under Income-Tax<br>
slide71. The Five Ws CA Rutvik Sanghvi Slide No. 71<br>
slide72. Foreign Assets Disclosures – WHY??<br>
slide73. Genesis India is one of the early adopters of the CRS and had committed to exchange information automatically by 2017.
India has activated AEOI relationship for receiving information from 96 jurisdictions
Exchange of Information takes place through:
Article 26 of DTAA and TIEAs
FATCA & CRS declarations
Signing of Intergovernmental agreements by India and US,
CBDT in 2015 notified the rules
For implementation of FATCA / CRS - reporting by FIs in India
Section 285BA of the Income-tax Act, 1961 read with Rules 114F to 114H
CbC reporting and its AEOI
Domestic disclosure requirements under SFT and FA Schedule CA Rutvik Sanghvi Slide No. 73<br>
slide74. Background Schedule FA introduced in ITR Forms from AY 2012-13
Schedule FSI introduced in ITR Forms from AY 2013-14
Several Indians owning assets abroad
Significant investments made through LRS, ODI and LRS-ODI
Returning Indians
Signatory in bank accounts held by entities abroad
Mismatch of data leads to queries and assessments
Competent Authority nodal point to receive all exchanged data
Joint Secretaries, FT&TR CA Rutvik Sanghvi Slide No. 74<br>
slide75. Consequences for non-disclosure Flat penalty of Rs. 10 lakhs u/s. 42 or 43 of Black Money Act
Only exception for bank accounts where funds are lesser than INR 5 lakhs
While discretion is there to apply penalty practically officers levy penalty in all cases
Judicial precedents divided CA Rutvik Sanghvi Slide No. 75<br>
slide76. Consequences under Black Money Act (BMA) CA Rutvik Sanghvi Slide No. 76<br>
slide77. Penalty cannot be levied if disclosure made under revised return Once foreign assets declared in revised return, it cannot be considered, that he has willfully not declared or failed to declare even in the revised return filed under section 139(5).
As per section 43 of BMA, the penalty of Rs. 10 Lakhs is not leviable if the assessee has made appropriate foreign disclosures in ITR filed u/s 139 (1), (4) & (5) of income tax act.
K. Mohammed Haris v. ITD [[2022] 448 ITR 707 (Karnataka)]
Srinidhi Karti Chidambaram v. Pr. Chief CIT 411 ITR 1 [2018]
It should be noted that updated return filed u/s 139(8A) is not covered under this section. Hence, filing updated return would not exonerate the assessee from the penalty of Section 43 of BMA.
However, it is advisable to file an updated return and disclose the foreign assets. CA Rutvik Sanghvi Slide No. 77<br>
slide78. No penalty u/s 43 of BMA, 2015 – Bona fide case The assessee was signatory, but not the owner of the foreign bank account or the funds lying in the bank account. The bank account was inherited by her mother from her father. Given the poor condition of assessee’s mother the assessee and her husband were just a signatory in the foreign bank account.
Penalty was based on the assertion that the assessee, as a signatory to an undisclosed foreign bank account, was liable for penal consequences under section 43 of the Black Money Act.
Held:
“The unambiguous intent of the legislature thus is to exclude trivial cases of lapses which can be attributed to a reasonable cause.”
Assessing Officer 'may' impose the penalty, and the use of the expression 'may’ signifies that the penalty is not to be imposed in all cases of lapses and that there is no cause and effect relationship simpliciter between the lapse and the penalty.“
The AO has clear discretion in the matter.
Stringent penalties cannot be imposed for bonafide mistakes.
ACIT vs. Leena Gandhi Tiwari [2022] 136 taxmann.com 409 (Mumbai - Trib.) CA Rutvik Sanghvi Slide No. 78<br>
slide79. Penalty for non-disclosure – Even if investments made via LRS Assessee has jointly invested in “Global Dynamic Opportunity Fund Ltd.” The investment made from funds remitted under LRS.
The investment was made in FY 2014-15.
However, the asset was disclosed in ITR filed in AY 2019-20.
The assessing officer levied the penalty of Rs. 10 Lakhs for each FY i.e., FY 2016-17 to FY 2018-19.
The assessee had submitted all the information regarding the source of funds on which tax was paid.
Still the tribunal upheld the penalty levied by the AO and did not provide any relaxation.
Ms. Shobha Harish Thawani vs Joint CIT [2023] 154 taxmann.com 564 (Mumbai - Trib.) CA Rutvik Sanghvi Slide No. 79<br>
slide80. Penalty not levied – As investments disclosed in the Books of Accounts and in FEMA compliances Assessee had an investment in foreign entity - Helen Incorporated S.A., Panama.
This investment was not disclosed in the Schedule FA leading to penalty.
The assessee had disclosed investment as ‘Non-Current Asset’ in the Annual Report as well as in the Balance Sheet in ITR Form. Also, the investment was disclosed with the RBI through the authorized dealer.
Tribunal deleted the penalty and held:
“No doubt the AO is empowered to impose the penalty as discretion is vested with him by using word “May” in the provisions. The discretion is always at wisdom of an authority, however, discretion is required to be exercised judicially and under the Judicial canons of law and in reasonable and justified manner to impart the justice…”
M/s Ocean Diving Centre Ltd. vs CIT - ITAT Mumbai - BMA Nos. 20 to 23/Mum/2023. CA Rutvik Sanghvi Slide No. 80<br>
slide81. Foreign Assets Disclosures – WHAT??<br>
slide82. Legal provisions Section 139(1) of the Act read with fourth and fifth proviso to Section 139(1), makes it mandatory in case of all resident assesses viz. Individuals, HUFs, Firms and Companies having foreign assets file the return of income in the form ITR.
Fourth proviso to S. 139(1):
“Provided also that a person, being a resident other than not ordinarily resident in India within the meaning of clause (6) of section 6, who is not required to furnish a return under this sub-section and who at any time during the previous year,—
(a) holds, as a beneficial owner or otherwise, any asset (including any financial interest in any entity) located outside India or has signing authority in any account located outside India; or
(b) is a beneficiary of any asset (including any financial interest in any entity) located outside India,
shall furnish, on or before the due date, a return in respect of his income or loss for the previous year in such form and verified in such manner and setting forth such other particulars as may be prescribed:” CA Rutvik Sanghvi Slide No. 82<br>
slide83. Outside sources to understand legal requirements Due to lack of guidance one needs to depend on outside sources for information on what to fill where
A lot of material including commentaries, guidance notes, rules, etc. available under OECD mandated CRS requirement
Guidance Note on FATCA/CRS issued by FTTR
Rules 114F to 114H
Explanation to Rule 114F for definitions of key terms
All the above are outside sources and can only be considered for clarity CA Rutvik Sanghvi Slide No. 83<br>
slide84. Foreign Assets Schedule AY 2022-23 CA Rutvik Sanghvi Slide No. 84<br>
slide85. Foreign Assets Disclosures – WHO??<br>
slide86. Applicable to? Reporting applicable only to R&OR
Includes Foreign Citizens who are R&OR
Except for relief as explained later
NOR and NR exempted from providing disclosure of foreign assets
Even after FA 2020 amendments, NRs spending more than 120 days or citizens of India do not need to disclose foreign assets CA Rutvik Sanghvi Slide No. 86<br>
slide87. Steps to determine applicability CA Rutvik Sanghvi Slide No. 87<br>
slide88. Case Study – Applicability of FA disclosures S, a student, leaves India for UK for studies abroad on 19th August 2021. He is Resident for FY 2021-22, AY 2022-23
In UK he opens a bank account.
He has earned no incomes during FY 2021-22
Even if his income is Nil in India, he still needs to file income tax return as he has a foreign asset in form of UK Bank Account CA Rutvik Sanghvi Slide No. 88<br>
slide89. Applicability to Minors holding foreign assets Fifth proviso to section 139(1) provides for an exception from applicability of fourth proviso:
“Provided also that nothing contained in the fourth proviso shall apply to an individual, being a beneficiary of any asset (including any financial interest in any entity) located outside India where, income, if any, arising from such asset is includible in the income of the person referred to in clause (a) of that proviso in accordance with the provisions of this Act:”
Idea behind this exception seems to be to not obligate a beneficiary to file a return (in case beneficiary is otherwise not liable to file) as the legal / beneficial owner of the asset would already be obligated to submit the income in its tax return
But there is no provision for clubbing for disclosure of assets!
This causes an issue for minors who hold foreign assets. CA Rutvik Sanghvi Slide No. 89<br>
slide90. Applicability to Minors holding foreign assets A father and son (minor), both are ROR.
The minor son has invested Rs. 1 Cr in an asset abroad and has received income of Rs. 10 lakhs on the same.
From an income-tax perspective, income of Rs. 10 lakhs will be clubbed with his father’s income as per S. 64(1A) and father will offer the said income to tax in his tax return.
Whether minor son will have to file tax return and disclose the details of foreign asset??
5th proviso to Section 139(1) provides for an exception to the requirement brought out by 4th proviso to Section 139(1).
However, it only covers an individual who, while being a beneficiary of any foreign asset, income therefrom is includible in the income of the legal or beneficial owner of the asset in accordance with the Act.
In the present case, the minor son is the legal and beneficial owner of the foreign asset. The father is neither legal owner nor a beneficial owner of the foreign asset.
5th Proviso strictly does not apply to cases where minors are legal owners CA Rutvik Sanghvi Slide No. 90<br>
slide91. Applicability to Minors holding foreign assets The issue is compounded as the minor cannot file the tax return online due to system inadequacy whereby only if the minor earns income of his or her own then they can file a tax return.
Discussions with DGIT-Systems
Disclose foreign assets in return of parent
Nirmal Bhanwarlal Jain v. ADIT (Inv.)-3(1) [BMA No.13/ MUM/ 2023] – penalty levied on father for non-disclosure of children’s foreign assets!
Penalty levied for all 3 years! CA Rutvik Sanghvi Slide No. 91<br>
slide92. Foreign Assets Disclosures – WHERE??<br>
slide93. Schedule FA - Breakup CA Rutvik Sanghvi Slide No. 93<br>
slide94. General issues under FA Schedule Focus is on disclosure – intent is to cover all items that may be reported against tax payer from overseas jurisdictions
FA Schedule disclosures are not equivalent to foreign asset balance sheet
FA Schedule income disclosures may be different from total income
Necessary explanations and documents must be maintained
Guidance not available in old instructions on many aspects Definitions for several terms insufficient or unavailable
Can guidance be taken from Rules 114F to 114H?
Guidance Note on FATCA/CRS issued by FTTR provides clarity on several aspects CA Rutvik Sanghvi Slide No. 94<br>
slide95. Schedule FA – Conversion into INR Conversion into INR – unnecessary burden?
No scope for providing Forex amount
SBI TT Buying rates to be used for conversion
Where not available can adopt following:
Actual rate if conversion has taken place during remittance
RBI rates from its website
Rates from other websites where details are not available on RBI website
Keep record of source used and refer to it in the notes
Date for conversion
Peak Balance – date of peak balance
Cost – date of acquisition
Closing balance – closing date of the accounting period
Income derived – closing date of the accounting period
Income taxable – As per computation of Total Income (Rule 115) CA Rutvik Sanghvi Slide No. 95<br>
slide96. Table A1 of Schedule FA – Details of Foreign Depository Accounts Details of Foreign depository accounts held at any time during the calendar year ending as on 31st December 2022 shall be reported.
The peak balance, closing balance and gross interest paid/ credited shall be reported after converting the same into Indian currency. CA Rutvik Sanghvi 96<br>
slide97. Table A1 of Schedule FA – Details of Foreign Depository Accounts As per CRS Guidance Note and Rule 114F, Depository Account includes:
Any commercial, checking, savings, time, or thrift account, or
an account that is evidenced by a certificate of deposit, thrift certificate, investment certificate, certificate of indebtedness, or other similar instrument maintained by a financial institution in the ordinary course of a banking or similar business;
An amount that an insurance company holds under an agreement to pay or credit interest thereon;
Does not have to be an interest-bearing account. CA Rutvik Sanghvi Slide No. 97<br>
slide98. Table A2 of Schedule FA – Details of Foreign Custodial Accounts Custodial Account as per Rule 114F means an account for the benefit of another person that holds one or more financial assets
Excludes Insurance or Annuity Contract
Details of Foreign custodial accounts held at any time during the calendar year ending as on 31st December 2022 shall be reported.
The peak balance, closing balance and gross amount paid/ credited shall be reported after converting the same into Indian currency. 98 CA Rutvik Sanghvi<br>
slide99. Table A2 of Schedule FA – Details of Foreign Custodial Accounts 99 CA Rutvik Sanghvi The nature of gross amount paid should be specified from the drop-down list, viz., interest, dividend, proceeds from sale or redemption of financial assets or other income
How to report different streams of income against one account?<br>
slide100. Table A3 of Schedule FA – Debt & Equity Interest Foreign Equity and Debt interest to be disclosed
But definitions lacking in instructions or Form
Does not mean investment in shares or debentures, etc.
Those would get covered under Table B and/or Table D
As per Guidance Note, Equity and debt interests are financial accounts if they are interests in an investment entity
Though equity interests in Investment entity, which is only an investment advisor or investment manager, are not financial accounts
Rule 114F states “equity interest” with reference to Financial Institutions as partnership firm and trust CA Rutvik Sanghvi Slide No. 100<br>
slide101. Table A4 of Schedule FA – Insurance or Annuity Contract No definitions provided for the terms
Reference to be made to Rule 114F
Explanation in Rule 114F states that "insurance contract" means a contract (other than an annuity contract) under which the issuer agrees to pay an amount upon the occurrence of a specified contingency involving mortality, morbidity, accident, liability, or property risk CA Rutvik Sanghvi Slide No. 101<br>
slide102. Table A4 of Schedule FA – Insurance or Annuity Contract Explanation in Rule 114F states that "annuity contract" means a contract under which the issuer agrees to make payments for a period of time determined in whole or in part by reference to the life expectancy of one or more individuals;
Explanation in Rule 114F states that "cash value insurance contract" means an insurance contract (other than an indemnity reinsurance contract between two insurance companies) that has a cash value and in case of a U.S. reportable account such value is greater than an amount equivalent to fifty thousand U.S. dollars.
Explanation.- For the purposes of this clause, a single premium life insurance contract which does not permit an amount to be paid on surrender or termination of the contract and which does not allow amounts to be borrowed under or with regard to the contract, shall not constitute a cash value insurance contract;
Explanation in Rule 114F has also defined “cash value”. CA Rutvik Sanghvi Slide No. 102<br>
slide103. Sch. FA – Other issues Table A1 to Table A4 mention gross amounts paid or credited during the period.
Remaining Tables ask for income derived from the asset.
Which period should be considered for this?
Previous year or Calendar Year? CA Rutvik Sanghvi Slide No. 103<br>
slide104. Table B of Schedule FA – Financial interest (including beneficial interest) As per Guidance Note, Financial interest would include where the resident assessee is owner of record or holder of legal title of any financial account, irrespective of whether he is the beneficiary or not:
Owner of record or holder of legal title includes:
an agent, nominee, attorney or a person acting in some other capacity on behalf of the resident assessee with respect to the entity;
a corporation in which the resident assessee owns, directly or indirectly, any share or voting power
a partnership in which the resident assessee owns, directly or indirectly, an interest in partnership profits or an interest in partnership capital
a trust of which the resident assessee has beneficial or ownership interest.
any other entity in which the resident assessee owns, directly or indirectly, any voting power or equity interest or assets or interest in profits
However, FA Schedule asks for disclosure of Financial Interest in any Entity CA Rutvik Sanghvi Slide No. 104<br>
slide105. Table B of Schedule FA – Financial interest (including beneficial interest) Issues:
If the foreign shares are held by the resident in their own name, the shares shall be reported under
Table A3 ‐ Foreign equity and debt interest;
Table B ‐ Financial interest in any entity outside India; or
Table D ‐ Any other capital assets outside India?
Depends on the type of investment being made CA Rutvik Sanghvi Slide No. 105<br>
slide106. Table C of Schedule FA – Immovable property (including beneficial interest) CA Rutvik Sanghvi Slide No. 106 Value of total investment at cost in the immovable property
Issue:
Property sold after 31st December. Capital Gain on the same to be reported in this Table C or Table G -Other income?<br>
slide107. Table D of Schedule FA – Other Capital Asset Income derived from the asset – Calendar Year or FY
FY as income is linked to Schedule of ITR Form
“Capital Asset”
Shares of foreign companies
Units of foreign Mutual Funds
Securities held abroad
Any other financial asset which is not reported in above tables
Exclusions:
Stock‐in‐trade & business assets which are included in the Balance Sheet. CA Rutvik Sanghvi Slide No. 107<br>
slide108. Table E of Schedule FA – Accounts in which the person has signing authority Details of foreign accounts in which the person has a signing authority
Exclusion:
Accounts which have been reported in the preceding tables CA Rutvik Sanghvi Slide No. 108<br>
slide109. Table F of Schedule FA – Trust created outside India in which person is a trustee, a beneficiary or settlor Details of trusts set up under the laws of a country outside India is required to be disclosed.
Further, income derived from such trust shall also be reported
Difficult to get information in some cases 109 CA Rutvik Sanghvi<br>
slide110. Case Study – Trust reporting Mr. A, NRI, settled shares and immovable property in discretionary trust for US inheritance tax purposes in 1990.
On retirement Mr. A has moved to India to settle for good in 2022.
Trustees of the trust are his son and daughter, Mr. AB and Ms. AC.
Beneficiaries of the trust are:
Children of Mr. AB and Ms. AC – non-residents of India.
Nephews and nieces of Mr. A – all Indian residents (unaware of the fact that they are marked as beneficiaries in the trust).
Charitable trust in India
Mr. A had appointed his brother, Mr. B who is settled in India as the Protector of the trust Slide No. 110 CA Rutvik Sanghvi<br>
slide111. Issues in reporting of Trusts Is Mr. A required to disclose the trust even if settled when he was a Non-resident?
Should he disclose the trust assets too even though he is not legal owner?
Is a resident beneficiary of a foreign Discretionary Trust required to file tax return?
Does the protector need to disclose details of the Trust?
Is the beneficiary required to disclose the underlying assets held by the Trust?
No clarity in the instructions 111 CA Rutvik Sanghvi<br>
slide112. Disclosure requirements for parties to a Trust Settlor being ROR would be subject to disclosure requirements under item F of Schedule FA
For Trust assets: in subsequent years, settlor should not be regarded as the beneficial owner of the assets held under the trust (post settlement)
Alternate view: Settlor has provided consideration for the asset which is held by the Trust and the settlor qualifies as beneficial owner as per strict reading of “Beneficial Owner” as per Section 139 and under the instructions.
Trustee is a legal owner and is therefore required to report all the foreign assets of the trust
Beneficiary: Multiple definitions of “beneficiary” provided under the Act, the Rules and under the instructions.
Para 4.3.9 read with para 4.3.12 of the Guidance Note on FATCA/CRS provides that a beneficial owner of a trust (referred to as controlling persons as well) would mean the settlor, the trustees, the protector (if any) and the beneficiaries. CA Rutvik Sanghvi Slide No. 112<br>
slide113. Definition of “Beneficiary” of a foreign asset Slide No. 113 Inconsistency in the definition of “beneficiary”: CA Rutvik Sanghvi Whether a beneficiary who has not received any income or distribution from during the year, is required to disclose trust assets in Schedule FA?<br>
slide114. Disclosure requirements for parties to a Trust Protector:
A person appointed as a ‘protector’ to the trust would be tasked to act as a protective shield in case the trustees of the trust do not act in the benefit of the beneficiaries as prescribed under the trust deed.
Such protectors are trusted family members or friends who would not be beneficiaries in the trust.
Such protectors do not earn any income from such trust.
As reporting of their holding such a position in the trust would be reported under CRS, it would be advisable for such individuals to disclose the trust details in Table F and maintain proper records and also provide them in case the tax department calls for the same. CA Rutvik Sanghvi Slide No. 114<br>
slide115. Table G of Schedule FA - Any other income derived from any foreign source Details of any other income, derived from any foreign source should be reported.
Exclusion:
Income which has been reported in the tables A1 to F above. CA Rutvik Sanghvi Slide No. 115<br>
slide116. Foreign Assets Disclosures – WHEN??<br>
slide117. Case Study – ESOPs of Foreign Company A INC owns A Pvt. Ltd.
A Pvt. Ltd. employs Mr. X.
A INC grants ESOP to Mr. X.
Tax implication under ITA is only on exercise of ESOPs.
Reporting Obligations:
What if ESOPs are just granted and not yet vested?
What if ESOPs are vested but not yet exercised by Mr. X?
What should be the view in case of ESPP, RSUs, PSOs, etc.? CA Rutvik Sanghvi Slide No. 117 USA India A INC Mr. X
(Employee) A Pvt. Ltd. ESOPs<br>
slide118. Different incomes from same foreign asset Mr. Y is holding an Individual Retirement account (IRA) in USA.
He earned interest income, dividend income and capital gains from such IRA account.
How to report in Schedule FA?
IRA account will be reported in Table A2 - Details of Foreign Custodial Accounts
Interest income will also be reported in Table A2
Dividend and capital gains will be reported in Table G - Details of any other income derived from any source outside India CA Rutvik Sanghvi Slide No. 118<br>
slide119. Foreign assets which may not get reported ESOPs of foreign companies granted, but not yet vested
Vehicles, etc., if not capital assets
Stock-in-trade & Business assets included in Balance Sheet
However, caution to be taken and disclosure to be made on conservative basis CA Rutvik Sanghvi Slide No. 119<br>
slide120. Disclosures required at other places Reporting of Unlisted equity shares
In PART A – General of ITR form reporting of Unlisted Equity shares is required
Required of any company, whether domestic or foreign
Reporting required even if the foreign unlisted equity shares are reported in the Schedule FA
Even if the unlisted equity shares are held as a stock in trade
Exemption for shares of foreign company registered on a recognised stock exchange outside India
Disclosure of Directorships in foreign companies
Resident required to disclose directorships in Foreign Companies in PART A – General
Need to choose “foreign company” in the drop-down provided for “type of company”. In such case, PAN is not mandatory CA Rutvik Sanghvi Slide No. 120<br>
slide121. Disclosures required at other places Schedule EI - Incomes exempt as per DTAA
To report foreign incomes which are exempt under DTAA.
And in Table G of Schedule FA.
Schedule AL
If you have held foreign assets during the previous year which have been duly reported in the Schedule FA. Even then you are required to report such foreign asset again in the Schedule AL (if applicable).
Relief u/s. 89A
Incomes earned in Foreign Retirement Benefits Account
New provision introduced by FA 2021, w.e.f. 1st April 2022 CA Rutvik Sanghvi Slide No. 121<br>
slide122. Taxability of Foreign incomes Incomes earned on foreign assets liable to tax in India
Including those not taxable in foreign country
Accounting or tax treatment in foreign country not relevant
Incomes earned in Retirement Benefits account, Pension, Social Security Benefit, etc.
Unless not taxable as per DTAA with India
Relief available without treaty too – but only where DTAA not applicable
Foreign tax credit allowed in India for taxes paid in foreign country
Form 67 to be filed
Computation to be done, if necessary, on estimated basis
Cost-benefit analysis CA Rutvik Sanghvi 122<br>
slide123. Other Tax issues to be considered Slide No.: 123 Place of Effective Management (PoEM)
Transfer Pricing compliance:
Form 3CEB, 3CEAA, 3CEAB, 3CEAC, etc.
Sch. TPSA - Secondary adjustment under Transfer Pricing
Section 94B impact - Clause 30B of Tax Audit Report
Valuation under Sections 56(2)(x) and 56(2)(viib)
Dividend taxation
Tax on dividend distributions at various stages
Underlying Tax Credits (UTC) available in DTAA with only couple of countries - Mauritius and Singapore
UTC available only to Indian companies, not other entities
80M deduction available but tax applicable at high slab rates in hands of individual shareholders/promoters
GAAR and other tax anti-avoidance measures CA Rutvik Sanghvi<br>
slide124. Exchange of Information Automatic Exchange of Information in place since several years
Most countries are eager to share information
Especially tax havens
Gone are the days of tax officer not coming to know
14 FAIUs constituted – millions of data points available with tax department CA Rutvik Sanghvi 124<br>
slide125. Consequences of non-disclosure under FEMA FEMA is now more draconian than FERA for foreign assets
Prosecution which was absent from FEMA earlier now part of it again
If investment is in line with FEMA, no consequences even if not disclosed under Income-tax
Seizure of equivalent assets in India
Section 37A introduced vide Finance Act, 2015 in FEMA
Already applied by ED in a few cases to seize assets in India
Can lead to penalty and prosecution
Consequences under Black Money Act primary and substantial
Penalty of Rs. 10 lakhs
Possibility of prosecution
Chidambaram family’s cases – chargesheets filed for non-disclosure Slide No. 125 CA Rutvik Sanghvi<br>
slide126. Practical issues Slide No.: 126 Jurisdictional analysis from non-tax perspective
Hidden Costs
Automatic issue of capital without remittance
Lack of proper Accounts and Audit
Judicial strength
Political and Economic risks
Tax Havens under scanner – presumption of guilt
Foreign laws to be adhered to
Substance Requirements and BEPS/MLI impact
Succession Planning CA Rutvik Sanghvi<br>
slide127. Conclusion<br>
slide128. Issues to watch out for Residential Status:
Amendments vide FA 2020 provides for deemed NOR status – results in dilution of NR status in future years under S. 6(6)(a) when NR returns to India permanently
Persons stranded in / shifted to India during pandemic
Overseas investments reported under FEMA, but disclosure missed out in tax return
Incomplete data provided by clients – dormant bank accounts, unresponsive foreign institutions, costly exercise to dig out old data
TCS on LRS – tax department has information on investments outside India CA Rutvik Sanghvi Slide No. 128<br>
slide129. In conclusion Being conservative and disclosing all data related for Foreign Assets would help
Proper documentation required to be maintained
Explanatory notes for disclosures and Forms need to be maintained
Blunt and direct explanation to clients about risks they face
FEMA issues may need to be considered in case of non-compliance for foreign investments CA Rutvik Sanghvi Slide No. 129<br>
slide130. Thanks! Questions?
Acknowledgements: CA Bhavya Gandhi
Contact at:
rutvik@rashminsanghvi.com
www.rashminsanghvi.com CA Rutvik Sanghvi Slide No. 130<br>