
R Conference on Finance, Chicago Collinearity

Description: R Conference on Finance, Chicago Collinearity Visualized May 17-18, 2019 Renato Staub, Ph.D. Senior Risk Capital Analyst FOR INSTITUTIONAL USE ONLY Compliance Disclosure This material is provided by William Blairs Dynamic Allocation
Related Topics
Download Presentation
"R Conference on Finance, Chicago Collinearity" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. R Conference on Finance, Chicago
Collinearity Visualized May 17-18, 2019 Renato Staub, Ph.D.
Senior Risk Capital Analyst FOR INSTITUTIONAL USE ONLY<br>
slide2. Compliance Disclosure This material is provided by William Blair’s Dynamic Allocation Strategies team for informational purposes only and is not intended as investment advice. Any discussion of particular topics is not meant to be comprehensive and may be subject to change. Any investment or strategy mentioned herein may not be suitable for every investor. Factual information has been taken from sources we believe to be reliable, but its accuracy, completeness or interpretation cannot be guaranteed. Information and opinions expressed are those of the author(s) and may not reflect the opinions of other investment teams within William Blair & Company, L.L.C.’s Investment Management division. Information is current as of the date appearing in this material only and subject to change without notice.
There is no guarantee that expected return or risk expectations indicated will equal actual return or risk for any capital market or investment strategy. Return and risk information contained herein is intended to illustrate potential expectations for various capital markets and should not be considered any representation of past or expected future return or risk for any William Blair investment strategy or product. Expected returns are provided are for informational purposes only and not intended to be reflective of results a person should expect to achieve. Expected returns have been calculated based on historical index returns and are not based on actual investment portfolios. Actual results will vary and may be higher or lower than the values indicated. Differences between expected and actual results may be exaggerated in volatile market environments.
Alternative investments, including options, futures and hedge funds, are speculative and typically involve a high degree of risk. These investments are intended for experienced and sophisticated investors who are willing to bear the loss of their entire investment and may not be suitable for all investors. Performance of these products may be volatile, and while they may provide the potential for positive returns in both rising and declining markets, the potential for loss is equal. Some alternative investments can be highly illiquid, may not be required to provide periodic pricing or valuation to investors, and may involve complex tax structures and delays in distribution of important tax information. Certain alternatives are not subject to the same regulatory requirements, charge higher fees and may have limited opportunity for early redemption or transference of interests. Alternative investment strategies are not intended as a complete investment program. Each investor should consult their own advisors regarding the legal, tax, and financial suitability of alternative investments.
William Blair’s Dynamic Allocation Strategies employ sophisticated investment strategies that may not be suitable for all investors, and an investor could lose all, or a substantial amount of their investment. These strategies:
Are speculative and involve a substantial degree of risk;
May use leverage to achieve potentially higher returns through proportionally higher ex-ante risk exposures through, but not limited to, the direct use of swaps, options, foreign exchange contracts, exchange traded funds, futures contracts, and/or by borrowing money to purchase investments;
Are subject to other investment risks including those associated with high yield securities, emerging markets, non-U.S. securities, currency markets and fixed income securities;
Expect to incur, but not target, equity-like risk, over periods of five years or longer but may experience risk and returns significantly different than expectations; and
May produce highly volatile investment returns. 240418<br>
slide3. Inducement – Example High interest rates suggest
a future reversion, that is, a decrease in interest rates
Hence – if stocks are interest rate sensitive – a rising stock market
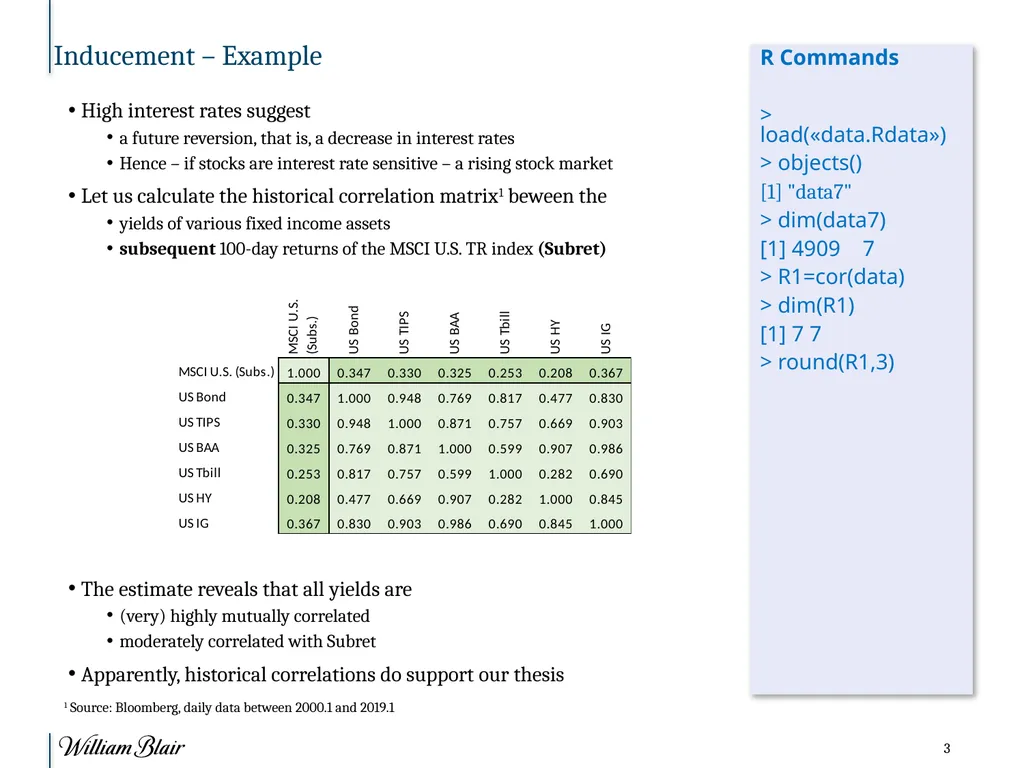
Let us calculate the historical correlation matrix1 beween the
yields of various fixed income assets
subsequent 100-day returns of the MSCI U.S. TR index (Subret)
The estimate reveals that all yields are
(very) highly mutually correlated
moderately correlated with Subret
Apparently, historical correlations do support our thesis R Commands
> load(«data.Rdata»)
> objects()
[1] "data7"
> dim(data7)
[1] 4909 7
> R1=cor(data)
> dim(R1)
[1] 7 7
> round(R1,3) 1 Source: Bloomberg, daily data between 2000.1 and 2019.1<br>
slide4. Inducement – Multiple Regression #1 In order to predict Subret we might rely on a regression
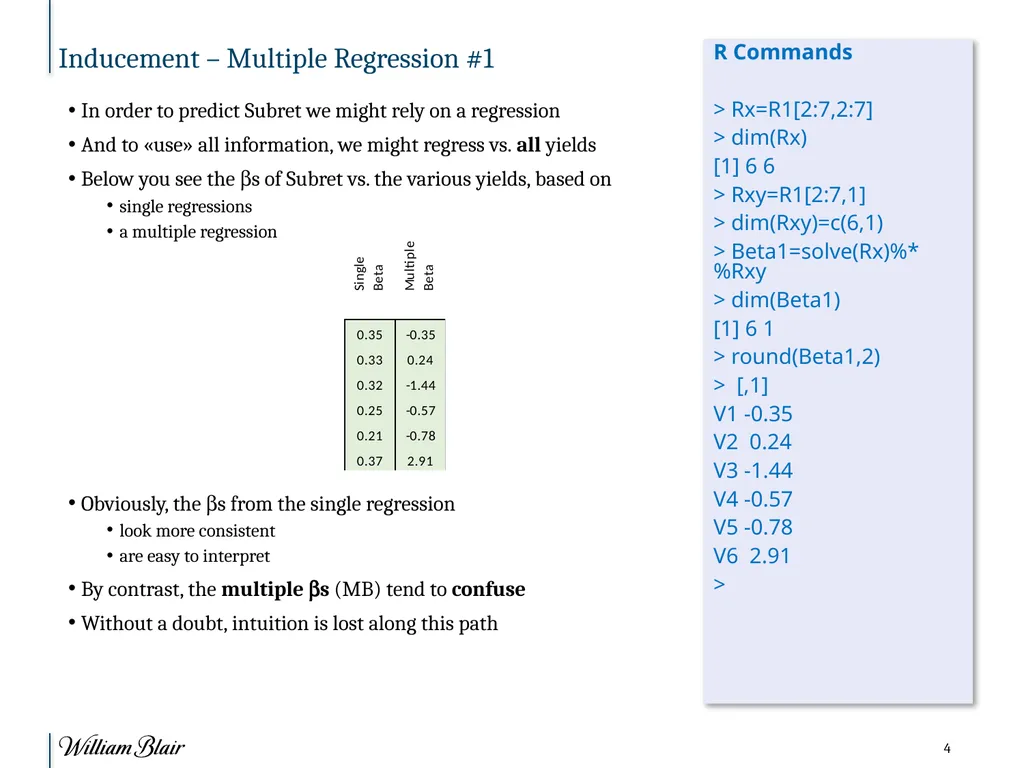
And to «use» all information, we might regress vs. all yields
Below you see the bs of Subret vs. the various yields, based on
single regressions
a multiple regression
Obviously, the bs from the single regression
look more consistent
are easy to interpret
By contrast, the multiple bs (MB) tend to confuse
Without a doubt, intuition is lost along this path R Commands
> Rx=R1[2:7,2:7]
> dim(Rx)
[1] 6 6
> Rxy=R1[2:7,1]
> dim(Rxy)=c(6,1)
> Beta1=solve(Rx)%*%Rxy
> dim(Beta1)
[1] 6 1
> round(Beta1,2)
> [,1]
V1 -0.35
V2 0.24
V3 -1.44
V4 -0.57
V5 -0.78
V6 2.91
><br>
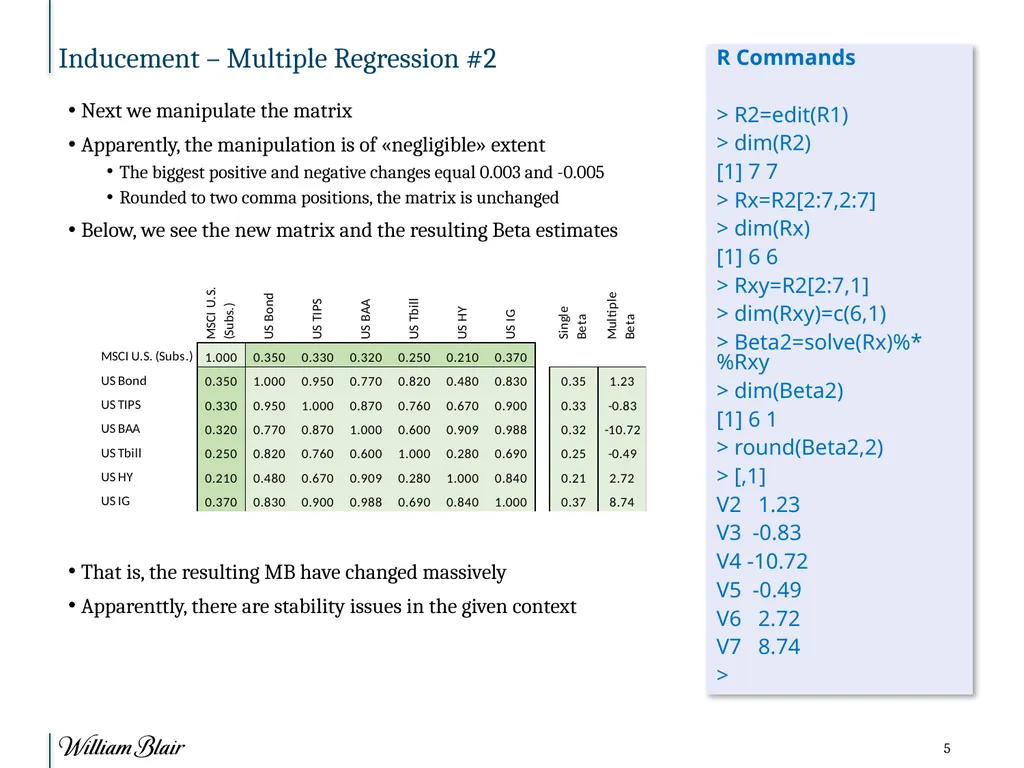
slide5. Inducement – Multiple Regression #2 Next we manipulate the matrix
Apparently, the manipulation is of «negligible» extent
The biggest positive and negative changes equal 0.003 and -0.005
Rounded to two comma positions, the matrix is unchanged
Below, we see the new matrix and the resulting Beta estimates
That is, the resulting MB have changed massively
Apparenttly, there are stability issues in the given context R Commands
> R2=edit(R1)
> dim(R2)
[1] 7 7
> Rx=R2[2:7,2:7]
> dim(Rx)
[1] 6 6
> Rxy=R2[2:7,1]
> dim(Rxy)=c(6,1)
> Beta2=solve(Rx)%*%Rxy
> dim(Beta2)
[1] 6 1
> round(Beta2,2)
> [,1]
V2 1.23
V3 -0.83
V4 -10.72
V5 -0.49
V6 2.72
V7 8.74
><br>
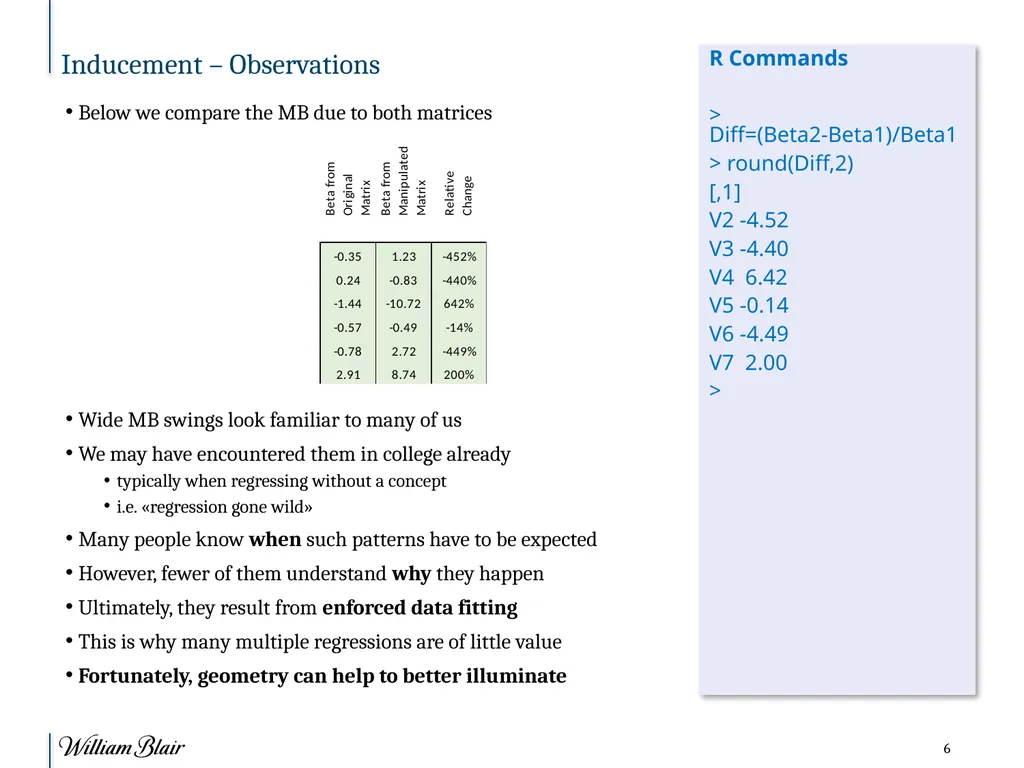
slide6. Inducement – Observations Below we compare the MB due to both matrices
Wide MB swings look familiar to many of us
We may have encountered them in college already
typically when regressing without a concept
i.e. «regression gone wild»
Many people know when such patterns have to be expected
However, fewer of them understand why they happen
Ultimately, they result from enforced data fitting
This is why many multiple regressions are of little value
Fortunately, geometry can help to better illuminate R Commands
> Diff=(Beta2-Beta1)/Beta1
> round(Diff,2)
[,1]
V2 -4.52
V3 -4.40
V4 6.42
V5 -0.14
V6 -4.49
V7 2.00
><br>
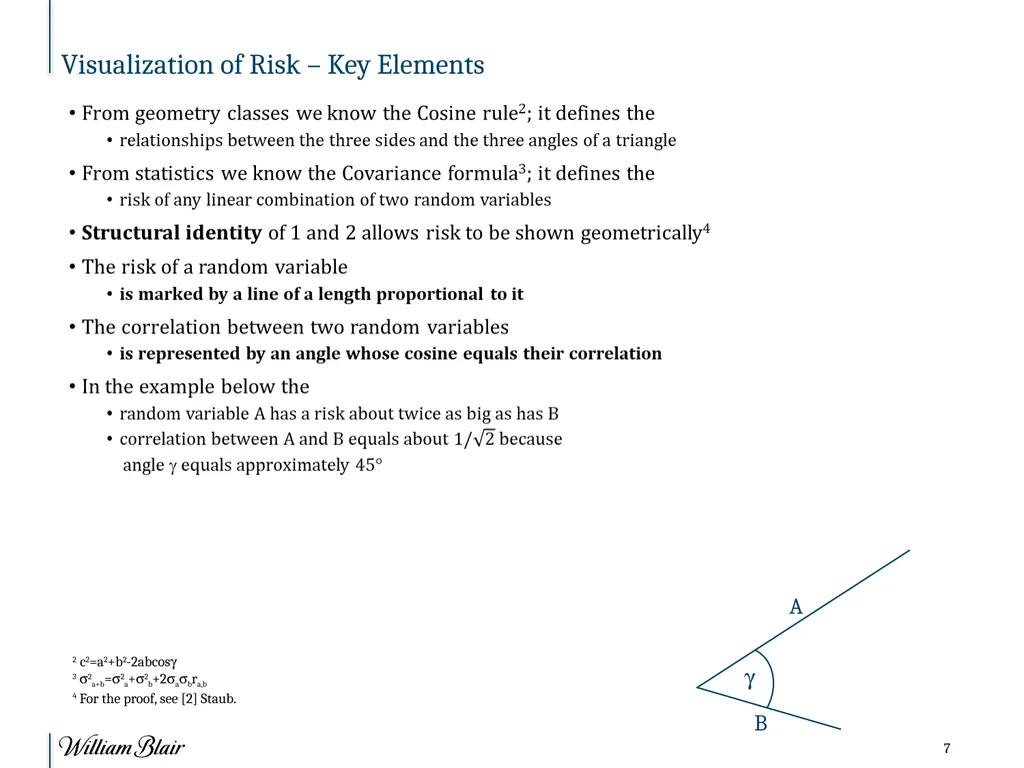
slide7. 232814 Visualization of Risk – Key Elements A B g 2 c2=a2+b2-2abcosg
3 s2a+b=s2a+s2b+2sasbra,b
4 For the proof, see [2] Staub.<br>
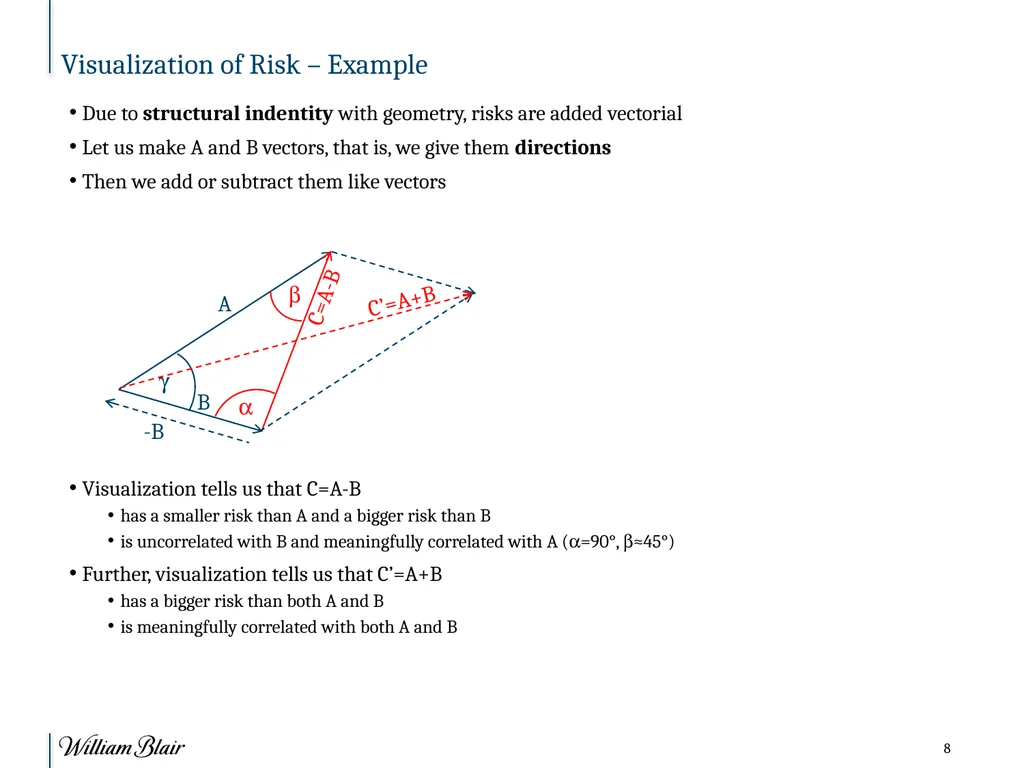
slide8. 232814 Visualization of Risk – Example Due to structural indentity with geometry, risks are added vectorial
Let us make A and B vectors, that is, we give them directions
Then we add or subtract them like vectors
Visualization tells us that C=A-B
has a smaller risk than A and a bigger risk than B
is uncorrelated with B and meaningfully correlated with A (a=90°, b≈45°)
Further, visualization tells us that C’=A+B
has a bigger risk than both A and B
is meaningfully correlated with both A and B A B g C=A-B a b -B C’=A+B<br>
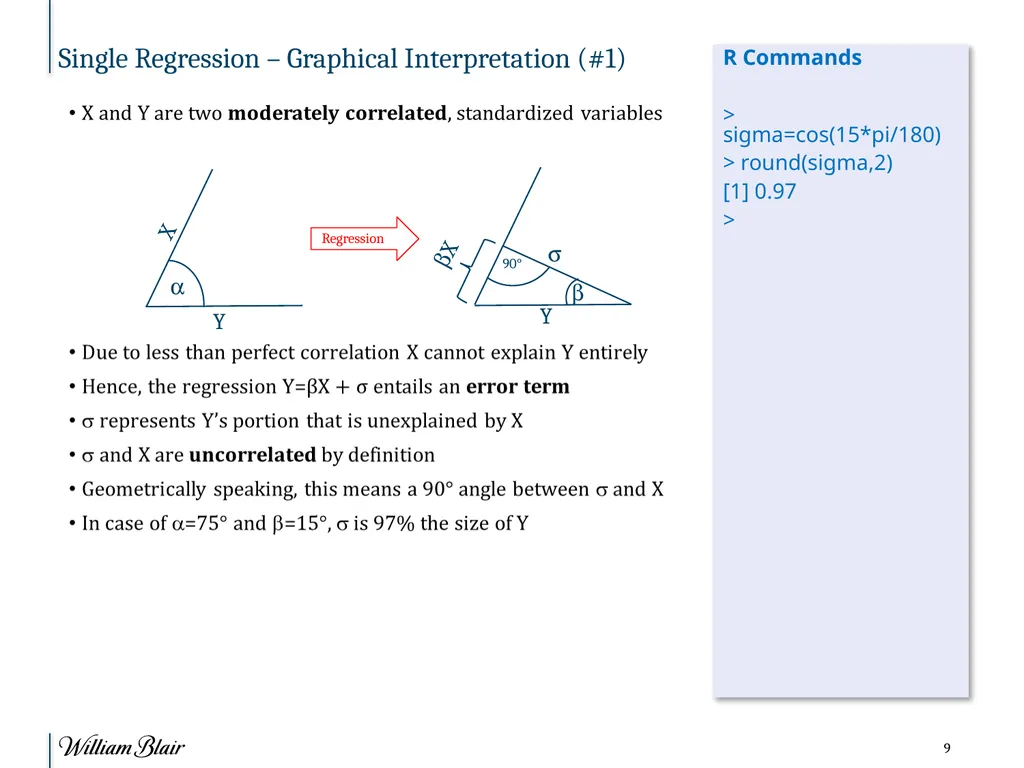
slide9. 232814 Single Regression – Graphical Interpretation (#1) R Commands
> sigma=cos(15*pi/180)
> round(sigma,2)
[1] 0.97
> Y bX 90° Y X s Regression a b<br>
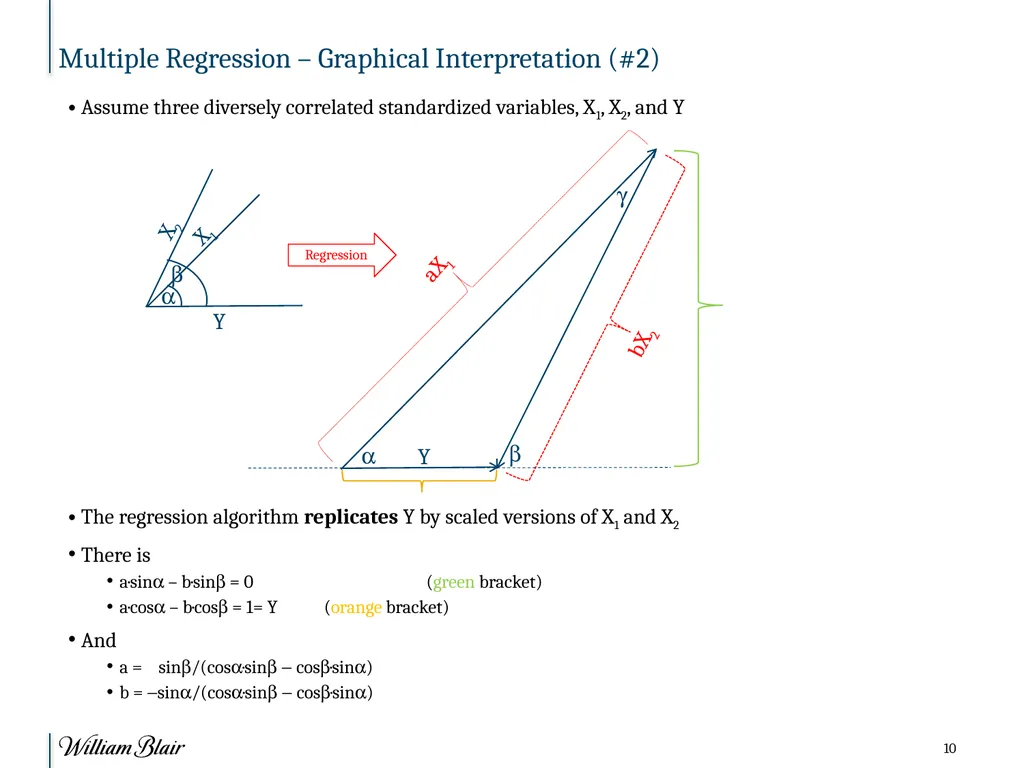
slide10. 232814 Multiple Regression – Graphical Interpretation (#2) Assume three diversely correlated standardized variables, X1, X2, and Y
The regression algorithm replicates Y by scaled versions of X1 and X2
There is
a·sina – b·sinb = 0 (green bracket)
a·cosa – b·cosb = 1= Y (orange bracket)
And
a = sinb/(cosa·sinb - cosb·sina)
b = -sina/(cosa·sinb - cosb·sina) Y X2 Regression X1 Y aX1 bX2 a b a b g<br>
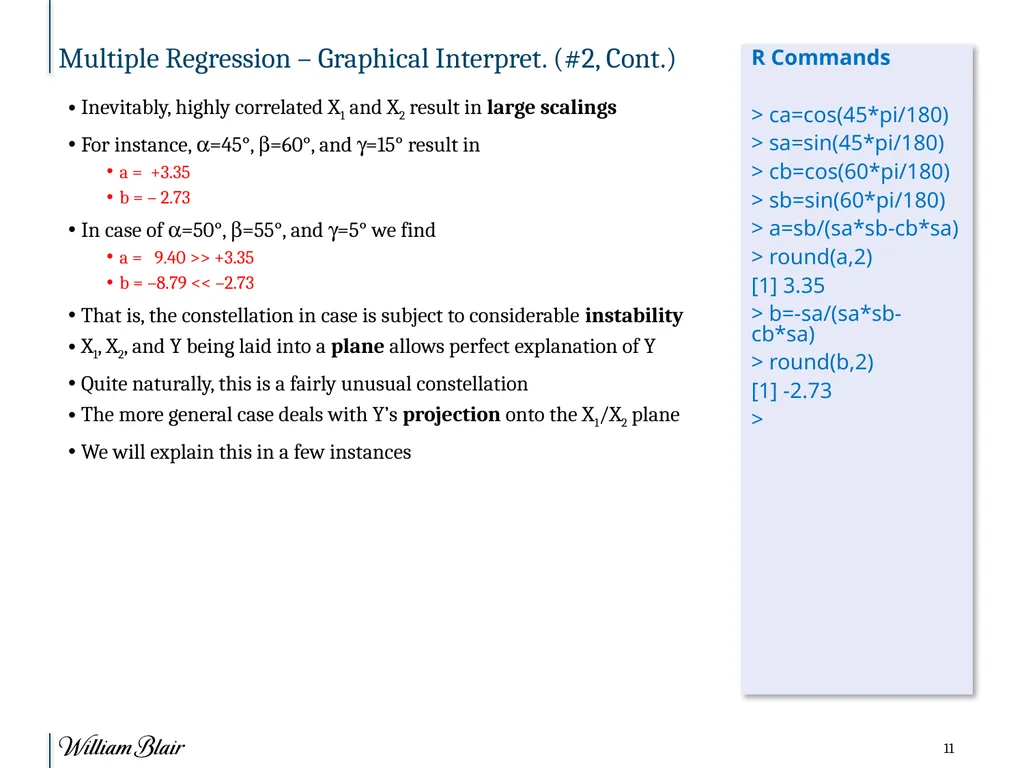
slide11. Multiple Regression – Graphical Interpret. (#2, Cont.) Inevitably, highly correlated X1 and X2 result in large scalings
For instance, a=45°, b=60°, and g=15° result in
a = +3.35
b = – 2.73
In case of a=50°, b=55°, and g=5° we find
a = 9.40 >> +3.35
b = –8.79 << –2.73
That is, the constellation in case is subject to considerable instability
X1, X2, and Y being laid into a plane allows perfect explanation of Y
Quite naturally, this is a fairly unusual constellation
The more general case deals with Y’s projection onto the X1/X2 plane
We will explain this in a few instances R Commands
> ca=cos(45*pi/180)
> sa=sin(45*pi/180)
> cb=cos(60*pi/180)
> sb=sin(60*pi/180)
> a=sb/(sa*sb-cb*sa)
> round(a,2)
[1] 3.35
> b=-sa/(sa*sb-cb*sa)
> round(b,2)
[1] -2.73
><br>
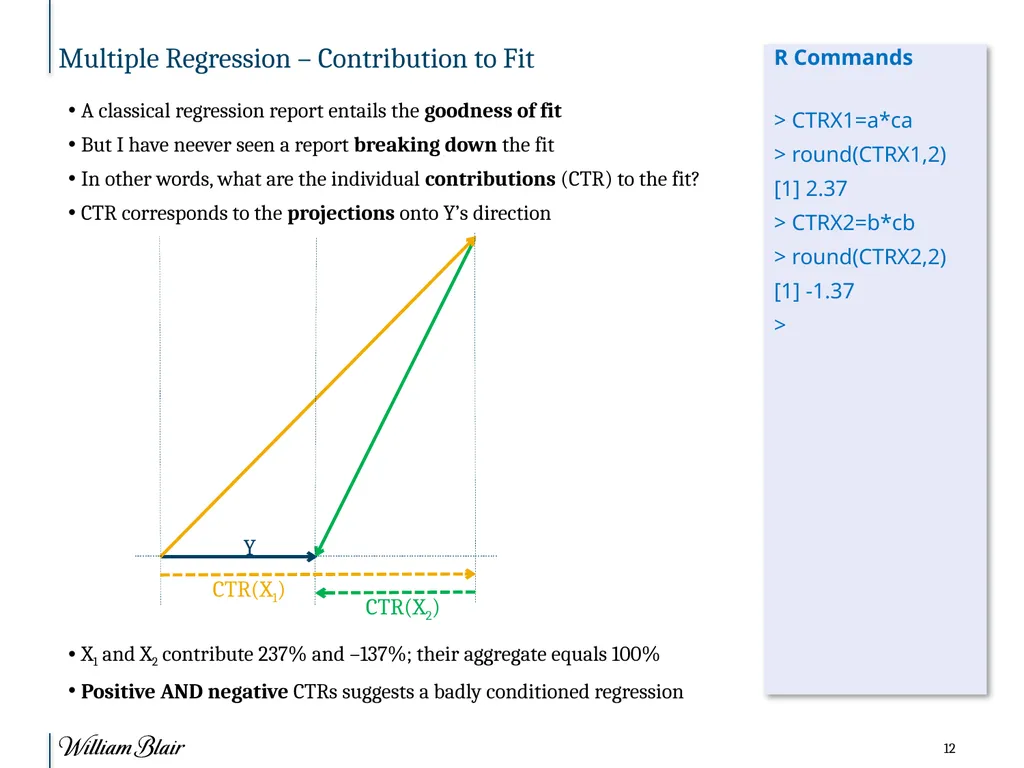
slide12. Multiple Regression – Contribution to Fit A classical regression report entails the goodness of fit
But I have neever seen a report breaking down the fit
In other words, what are the individual contributions (CTR) to the fit?
CTR corresponds to the projections onto Y’s direction
X1 and X2 contribute 237% and –137%; their aggregate equals 100%
Positive AND negative CTRs suggests a badly conditioned regression Y CTR(X1) CTR(X2) R Commands
> CTRX1=a*ca
> round(CTRX1,2)
[1] 2.37
> CTRX2=b*cb
> round(CTRX2,2)
[1] -1.37
><br>
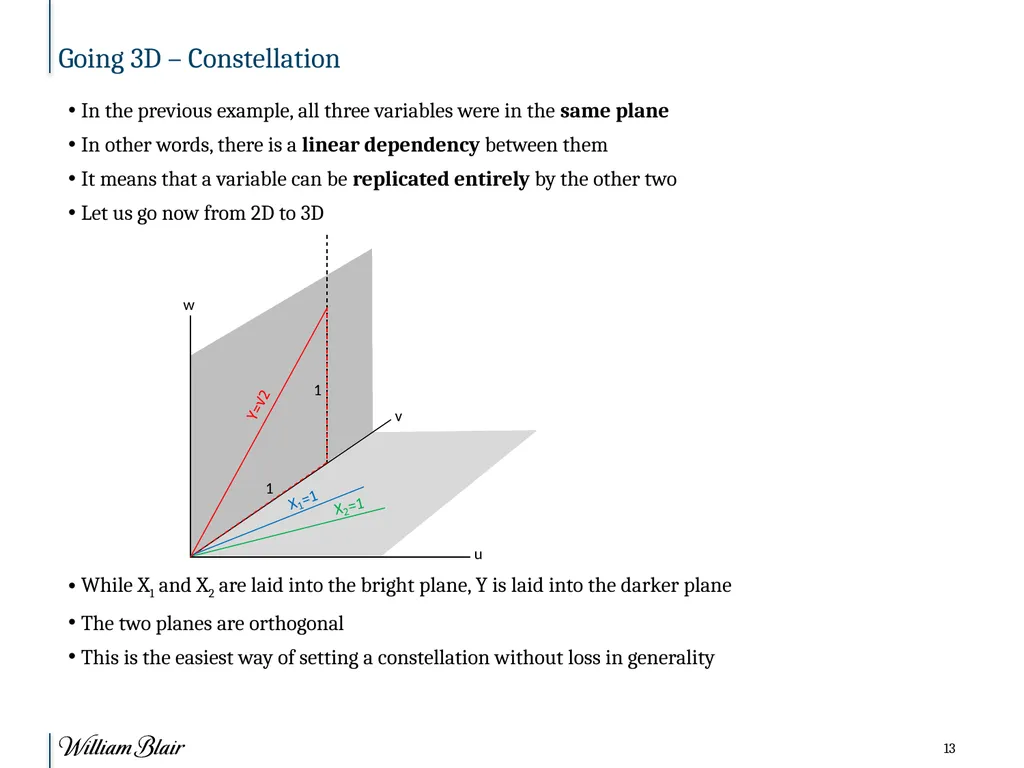
slide13. Going 3D – Constellation In the previous example, all three variables were in the same plane
In other words, there is a linear dependency between them
It means that a variable can be replicated entirely by the other two
Let us go now from 2D to 3D
While X1 and X2 are laid into the bright plane, Y is laid into the darker plane
The two planes are orthogonal
This is the easiest way of setting a constellation without loss in generality<br>
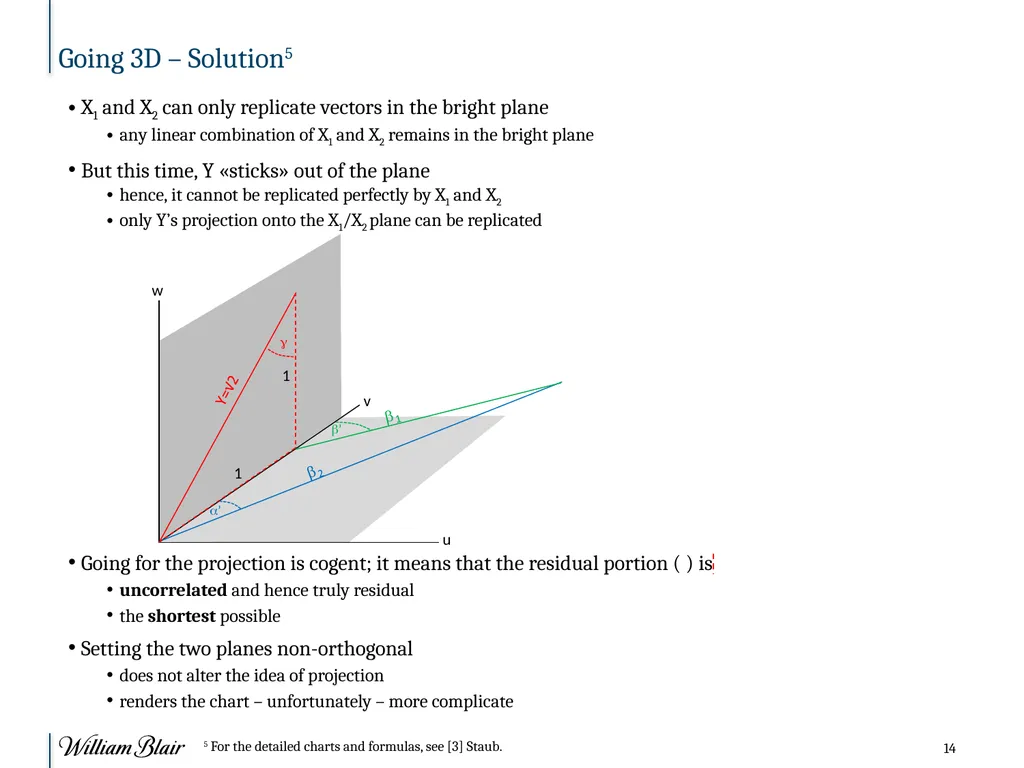
slide14. Going 3D – Solution5 X1 and X2 can only replicate vectors in the bright plane
any linear combination of X1 and X2 remains in the bright plane
But this time, Y «sticks» out of the plane
hence, it cannot be replicated perfectly by X1 and X2
only Y’s projection onto the X1/X2 plane can be replicated
Going for the projection is cogent; it means that the residual portion ( ) is
uncorrelated and hence truly residual
the shortest possible
Setting the two planes non-orthogonal
does not alter the idea of projection
renders the chart – unfortunately – more complicate 5 For the detailed charts and formulas, see [3] Staub.<br>
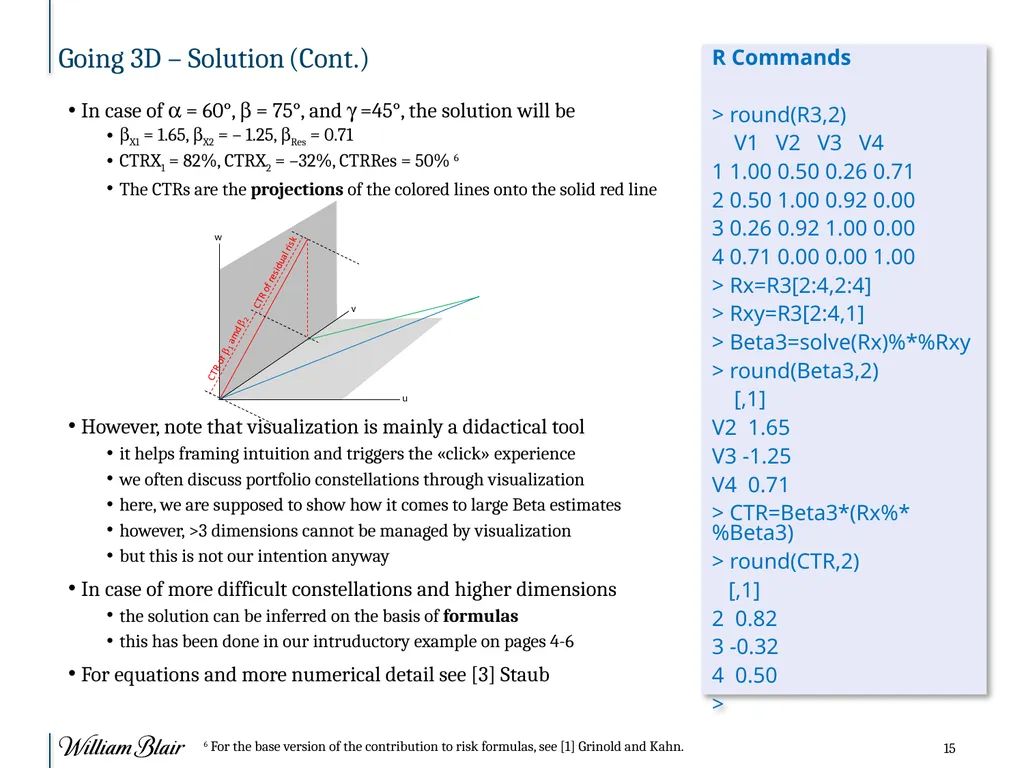
slide15. Going 3D – Solution (Cont.) In case of a = 60°, b = 75°, and g =45°, the solution will be
bX1 = 1.65, bX2 = – 1.25, bRes = 0.71
CTRX1 = 82%, CTRX2 = –32%, CTRRes = 50% 6
The CTRs are the projections of the colored lines onto the solid red line
However, note that visualization is mainly a didactical tool
it helps framing intuition and triggers the «click» experience
we often discuss portfolio constellations through visualization
here, we are supposed to show how it comes to large Beta estimates
however, >3 dimensions cannot be managed by visualization
but this is not our intention anyway
In case of more difficult constellations and higher dimensions
the solution can be inferred on the basis of formulas
this has been done in our intruductory example on pages 4-6
For equations and more numerical detail see [3] Staub R Commands
> round(R3,2)
V1 V2 V3 V4
1 1.00 0.50 0.26 0.71
2 0.50 1.00 0.92 0.00
3 0.26 0.92 1.00 0.00
4 0.71 0.00 0.00 1.00
> Rx=R3[2:4,2:4]
> Rxy=R3[2:4,1]
> Beta3=solve(Rx)%*%Rxy
> round(Beta3,2)
[,1]
V2 1.65
V3 -1.25
V4 0.71
> CTR=Beta3*(Rx%*%Beta3)
> round(CTR,2)
[,1]
2 0.82
3 -0.32
4 0.50
> 6 For the base version of the contribution to risk formulas, see [1] Grinold and Kahn.<br>
slide16. 232814 Summary and Conclusions Strongly correlated independent variables make multiple regressions problematic
The point is that the resulting estimates are far from stable and not intuitive
In the end, the estimates are due to enforced data fitting, that is, optimization
Fortunately, risk and correlation can be represented graphically
This allows us to portray low-dimensional constellations through visualization
Without a doubt, intuition is supported much better by visualization
The reason is easy – there is no need for (tedious) formulas
By means of visulation we can easily explain how it comes to large and unstable Betas
Nonetheless, visualization is mainly a didactical tool
But practical work based on larger data structures should be performed by formulas
The according formulas do exist and they are at our disposal
In contrast to visualization, formulas are not constrained to 3D cases<br>
slide17. 232814 Thank you veRy much for your attention! Euclid, ~300 BC<br>
slide18. 232814 References [1] Grinold, Richard C. and Ronald N. Kahn (1999) Active Portfolio Management. MCGRAW-HILL Professional, Second Edition.
[2] Staub, Renato (2006) Multilayer modeling of a covariance matrix. Journal of Portfolio Management 32(3): 33–44.
[3] Staub, Renato (2018) Collinearity Visualized. Working Paper, William Blair & Company, LLC, Chicago.<br>
slide2. Compliance Disclosure This material is provided by William Blair’s Dynamic Allocation Strategies team for informational purposes only and is not intended as investment advice. Any discussion of particular topics is not meant to be comprehensive and may be subject to change. Any investment or strategy mentioned herein may not be suitable for every investor. Factual information has been taken from sources we believe to be reliable, but its accuracy, completeness or interpretation cannot be guaranteed. Information and opinions expressed are those of the author(s) and may not reflect the opinions of other investment teams within William Blair & Company, L.L.C.’s Investment Management division. Information is current as of the date appearing in this material only and subject to change without notice.
There is no guarantee that expected return or risk expectations indicated will equal actual return or risk for any capital market or investment strategy. Return and risk information contained herein is intended to illustrate potential expectations for various capital markets and should not be considered any representation of past or expected future return or risk for any William Blair investment strategy or product. Expected returns are provided are for informational purposes only and not intended to be reflective of results a person should expect to achieve. Expected returns have been calculated based on historical index returns and are not based on actual investment portfolios. Actual results will vary and may be higher or lower than the values indicated. Differences between expected and actual results may be exaggerated in volatile market environments.
Alternative investments, including options, futures and hedge funds, are speculative and typically involve a high degree of risk. These investments are intended for experienced and sophisticated investors who are willing to bear the loss of their entire investment and may not be suitable for all investors. Performance of these products may be volatile, and while they may provide the potential for positive returns in both rising and declining markets, the potential for loss is equal. Some alternative investments can be highly illiquid, may not be required to provide periodic pricing or valuation to investors, and may involve complex tax structures and delays in distribution of important tax information. Certain alternatives are not subject to the same regulatory requirements, charge higher fees and may have limited opportunity for early redemption or transference of interests. Alternative investment strategies are not intended as a complete investment program. Each investor should consult their own advisors regarding the legal, tax, and financial suitability of alternative investments.
William Blair’s Dynamic Allocation Strategies employ sophisticated investment strategies that may not be suitable for all investors, and an investor could lose all, or a substantial amount of their investment. These strategies:
Are speculative and involve a substantial degree of risk;
May use leverage to achieve potentially higher returns through proportionally higher ex-ante risk exposures through, but not limited to, the direct use of swaps, options, foreign exchange contracts, exchange traded funds, futures contracts, and/or by borrowing money to purchase investments;
Are subject to other investment risks including those associated with high yield securities, emerging markets, non-U.S. securities, currency markets and fixed income securities;
Expect to incur, but not target, equity-like risk, over periods of five years or longer but may experience risk and returns significantly different than expectations; and
May produce highly volatile investment returns. 240418<br>
slide3. Inducement – Example High interest rates suggest
a future reversion, that is, a decrease in interest rates
Hence – if stocks are interest rate sensitive – a rising stock market
Let us calculate the historical correlation matrix1 beween the
yields of various fixed income assets
subsequent 100-day returns of the MSCI U.S. TR index (Subret)
The estimate reveals that all yields are
(very) highly mutually correlated
moderately correlated with Subret
Apparently, historical correlations do support our thesis R Commands
> load(«data.Rdata»)
> objects()
[1] "data7"
> dim(data7)
[1] 4909 7
> R1=cor(data)
> dim(R1)
[1] 7 7
> round(R1,3) 1 Source: Bloomberg, daily data between 2000.1 and 2019.1<br>
slide4. Inducement – Multiple Regression #1 In order to predict Subret we might rely on a regression
And to «use» all information, we might regress vs. all yields
Below you see the bs of Subret vs. the various yields, based on
single regressions
a multiple regression
Obviously, the bs from the single regression
look more consistent
are easy to interpret
By contrast, the multiple bs (MB) tend to confuse
Without a doubt, intuition is lost along this path R Commands
> Rx=R1[2:7,2:7]
> dim(Rx)
[1] 6 6
> Rxy=R1[2:7,1]
> dim(Rxy)=c(6,1)
> Beta1=solve(Rx)%*%Rxy
> dim(Beta1)
[1] 6 1
> round(Beta1,2)
> [,1]
V1 -0.35
V2 0.24
V3 -1.44
V4 -0.57
V5 -0.78
V6 2.91
><br>
slide5. Inducement – Multiple Regression #2 Next we manipulate the matrix
Apparently, the manipulation is of «negligible» extent
The biggest positive and negative changes equal 0.003 and -0.005
Rounded to two comma positions, the matrix is unchanged
Below, we see the new matrix and the resulting Beta estimates
That is, the resulting MB have changed massively
Apparenttly, there are stability issues in the given context R Commands
> R2=edit(R1)
> dim(R2)
[1] 7 7
> Rx=R2[2:7,2:7]
> dim(Rx)
[1] 6 6
> Rxy=R2[2:7,1]
> dim(Rxy)=c(6,1)
> Beta2=solve(Rx)%*%Rxy
> dim(Beta2)
[1] 6 1
> round(Beta2,2)
> [,1]
V2 1.23
V3 -0.83
V4 -10.72
V5 -0.49
V6 2.72
V7 8.74
><br>
slide6. Inducement – Observations Below we compare the MB due to both matrices
Wide MB swings look familiar to many of us
We may have encountered them in college already
typically when regressing without a concept
i.e. «regression gone wild»
Many people know when such patterns have to be expected
However, fewer of them understand why they happen
Ultimately, they result from enforced data fitting
This is why many multiple regressions are of little value
Fortunately, geometry can help to better illuminate R Commands
> Diff=(Beta2-Beta1)/Beta1
> round(Diff,2)
[,1]
V2 -4.52
V3 -4.40
V4 6.42
V5 -0.14
V6 -4.49
V7 2.00
><br>
slide7. 232814 Visualization of Risk – Key Elements A B g 2 c2=a2+b2-2abcosg
3 s2a+b=s2a+s2b+2sasbra,b
4 For the proof, see [2] Staub.<br>
slide8. 232814 Visualization of Risk – Example Due to structural indentity with geometry, risks are added vectorial
Let us make A and B vectors, that is, we give them directions
Then we add or subtract them like vectors
Visualization tells us that C=A-B
has a smaller risk than A and a bigger risk than B
is uncorrelated with B and meaningfully correlated with A (a=90°, b≈45°)
Further, visualization tells us that C’=A+B
has a bigger risk than both A and B
is meaningfully correlated with both A and B A B g C=A-B a b -B C’=A+B<br>
slide9. 232814 Single Regression – Graphical Interpretation (#1) R Commands
> sigma=cos(15*pi/180)
> round(sigma,2)
[1] 0.97
> Y bX 90° Y X s Regression a b<br>
slide10. 232814 Multiple Regression – Graphical Interpretation (#2) Assume three diversely correlated standardized variables, X1, X2, and Y
The regression algorithm replicates Y by scaled versions of X1 and X2
There is
a·sina – b·sinb = 0 (green bracket)
a·cosa – b·cosb = 1= Y (orange bracket)
And
a = sinb/(cosa·sinb - cosb·sina)
b = -sina/(cosa·sinb - cosb·sina) Y X2 Regression X1 Y aX1 bX2 a b a b g<br>
slide11. Multiple Regression – Graphical Interpret. (#2, Cont.) Inevitably, highly correlated X1 and X2 result in large scalings
For instance, a=45°, b=60°, and g=15° result in
a = +3.35
b = – 2.73
In case of a=50°, b=55°, and g=5° we find
a = 9.40 >> +3.35
b = –8.79 << –2.73
That is, the constellation in case is subject to considerable instability
X1, X2, and Y being laid into a plane allows perfect explanation of Y
Quite naturally, this is a fairly unusual constellation
The more general case deals with Y’s projection onto the X1/X2 plane
We will explain this in a few instances R Commands
> ca=cos(45*pi/180)
> sa=sin(45*pi/180)
> cb=cos(60*pi/180)
> sb=sin(60*pi/180)
> a=sb/(sa*sb-cb*sa)
> round(a,2)
[1] 3.35
> b=-sa/(sa*sb-cb*sa)
> round(b,2)
[1] -2.73
><br>
slide12. Multiple Regression – Contribution to Fit A classical regression report entails the goodness of fit
But I have neever seen a report breaking down the fit
In other words, what are the individual contributions (CTR) to the fit?
CTR corresponds to the projections onto Y’s direction
X1 and X2 contribute 237% and –137%; their aggregate equals 100%
Positive AND negative CTRs suggests a badly conditioned regression Y CTR(X1) CTR(X2) R Commands
> CTRX1=a*ca
> round(CTRX1,2)
[1] 2.37
> CTRX2=b*cb
> round(CTRX2,2)
[1] -1.37
><br>
slide13. Going 3D – Constellation In the previous example, all three variables were in the same plane
In other words, there is a linear dependency between them
It means that a variable can be replicated entirely by the other two
Let us go now from 2D to 3D
While X1 and X2 are laid into the bright plane, Y is laid into the darker plane
The two planes are orthogonal
This is the easiest way of setting a constellation without loss in generality<br>
slide14. Going 3D – Solution5 X1 and X2 can only replicate vectors in the bright plane
any linear combination of X1 and X2 remains in the bright plane
But this time, Y «sticks» out of the plane
hence, it cannot be replicated perfectly by X1 and X2
only Y’s projection onto the X1/X2 plane can be replicated
Going for the projection is cogent; it means that the residual portion ( ) is
uncorrelated and hence truly residual
the shortest possible
Setting the two planes non-orthogonal
does not alter the idea of projection
renders the chart – unfortunately – more complicate 5 For the detailed charts and formulas, see [3] Staub.<br>
slide15. Going 3D – Solution (Cont.) In case of a = 60°, b = 75°, and g =45°, the solution will be
bX1 = 1.65, bX2 = – 1.25, bRes = 0.71
CTRX1 = 82%, CTRX2 = –32%, CTRRes = 50% 6
The CTRs are the projections of the colored lines onto the solid red line
However, note that visualization is mainly a didactical tool
it helps framing intuition and triggers the «click» experience
we often discuss portfolio constellations through visualization
here, we are supposed to show how it comes to large Beta estimates
however, >3 dimensions cannot be managed by visualization
but this is not our intention anyway
In case of more difficult constellations and higher dimensions
the solution can be inferred on the basis of formulas
this has been done in our intruductory example on pages 4-6
For equations and more numerical detail see [3] Staub R Commands
> round(R3,2)
V1 V2 V3 V4
1 1.00 0.50 0.26 0.71
2 0.50 1.00 0.92 0.00
3 0.26 0.92 1.00 0.00
4 0.71 0.00 0.00 1.00
> Rx=R3[2:4,2:4]
> Rxy=R3[2:4,1]
> Beta3=solve(Rx)%*%Rxy
> round(Beta3,2)
[,1]
V2 1.65
V3 -1.25
V4 0.71
> CTR=Beta3*(Rx%*%Beta3)
> round(CTR,2)
[,1]
2 0.82
3 -0.32
4 0.50
> 6 For the base version of the contribution to risk formulas, see [1] Grinold and Kahn.<br>
slide16. 232814 Summary and Conclusions Strongly correlated independent variables make multiple regressions problematic
The point is that the resulting estimates are far from stable and not intuitive
In the end, the estimates are due to enforced data fitting, that is, optimization
Fortunately, risk and correlation can be represented graphically
This allows us to portray low-dimensional constellations through visualization
Without a doubt, intuition is supported much better by visualization
The reason is easy – there is no need for (tedious) formulas
By means of visulation we can easily explain how it comes to large and unstable Betas
Nonetheless, visualization is mainly a didactical tool
But practical work based on larger data structures should be performed by formulas
The according formulas do exist and they are at our disposal
In contrast to visualization, formulas are not constrained to 3D cases<br>
slide17. 232814 Thank you veRy much for your attention! Euclid, ~300 BC<br>
slide18. 232814 References [1] Grinold, Richard C. and Ronald N. Kahn (1999) Active Portfolio Management. MCGRAW-HILL Professional, Second Edition.
[2] Staub, Renato (2006) Multilayer modeling of a covariance matrix. Journal of Portfolio Management 32(3): 33–44.
[3] Staub, Renato (2018) Collinearity Visualized. Working Paper, William Blair & Company, LLC, Chicago.<br>