
Special Economic Zones-SEZ Dr M. S. Krishna Kumar,

Description: Special Economic Zones-SEZ Dr M. S. Krishna Kumar, Advocate SEZ- Introduction SEZ- specifically delineated duty-free enclave - deemed to be foreign territory for trade operations, duties and tariffs. Domestic Tariff Area (DTA) means the
Related Topics
Download Presentation
"Special Economic Zones-SEZ Dr M. S. Krishna Kumar," is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Special Economic Zones-SEZ Dr M. S. Krishna Kumar, Advocate<br>
slide2. SEZ- Introduction SEZ- specifically delineated duty-free enclave - deemed to be foreign territory for trade operations, duties and tariffs.
Domestic Tariff Area (DTA) means the whole of India (including the territorial waters and continental shelf) but does not include the areas of the Special Economic Zones.
Export Processing Zone (EPZ) Asia’s first set up in 1965 in Kandla- multiplicity of controls – lack of world-class infrastructure – unstable fiscal regime failed to attract foreign investment – SEZ policy revived in 2000
SEZs in India functioned from 1.11.2000 to 09.02.2006 under the provisions of the FTP - thereafter – SEZ Act 2005 - fiscal incentives were made effective through the provisions of relevant statutes.<br>
slide3. Objectives – Important Features The main objectives of the SEZ Act are:
generation of additional economic activity - promotion of exports of goods and services - promotion of investment from domestic and foreign sources
creation of employment opportunities - development of infrastructure facilities
Important features
key role for State Govt to create infrastructure
single window clearance 19 Member inter ministerial Board of Approval (BoA)
applications recommended by State/UT considered by BoA
decisions of Board are with consensus<br>
slide4. Key Entities in SEZ Key entities in the SEZ Scheme
Department of Commerce (DOC)- Formulation of policy for SEZ and review from time to time
Operational matters - SEZs-developer, co-developer and units - O/o Development Commissioner (DC) consists of DC including officers on deputation from Customs & Central Excise Dept.
Developer - means a person or a State Government which, has been granted a LOA for setting up of SEZ – CG may approve more than one developer if one Developer does not have minimum area for setting up
Co-developer: Any entity co-operated by the developer for setting up infrastructural facilities in the approved SEZ- to enter into agreement with Developer – approved by BoA and granted LOA
SEZ Units- A Unit set up by an entrepreneur in a SEZ-includes an existing Unit, an Offshore Banking Unit and a Unit in an International Financial Services Centre.<br>
slide5. State Govt Assistance – SEZ Land area requirements,
SEZ other than a SEZ for Information Technology(IT) or IT enabled services, Biotech or Health (other than hospital) service, shall have a contiguous land area of 50 hectares or more - minimum processing area in any SEZ cannot be less than 50% of the total area of SEZ
State Govt to endeavour in the following area
Exemption from the State and local taxes, including stamp duty, and taxes levied by local bodies on goods required for authorized operations by a Unit or Developer,
Exemption from electricity duty or taxes on sale, of self-generated or purchased electric power for use in the processing area of a SEZ Allow generation, transmission and distribution of power within a SEZ providing water, electricity and such other services,
Delegation of power to the DC under the Industrial Disputes Act,1947 in relation to the Unit and workmen employed by the developer - Declaration of the SEZ as a Public Utility Service under the Industrial Disputes Act,<br>
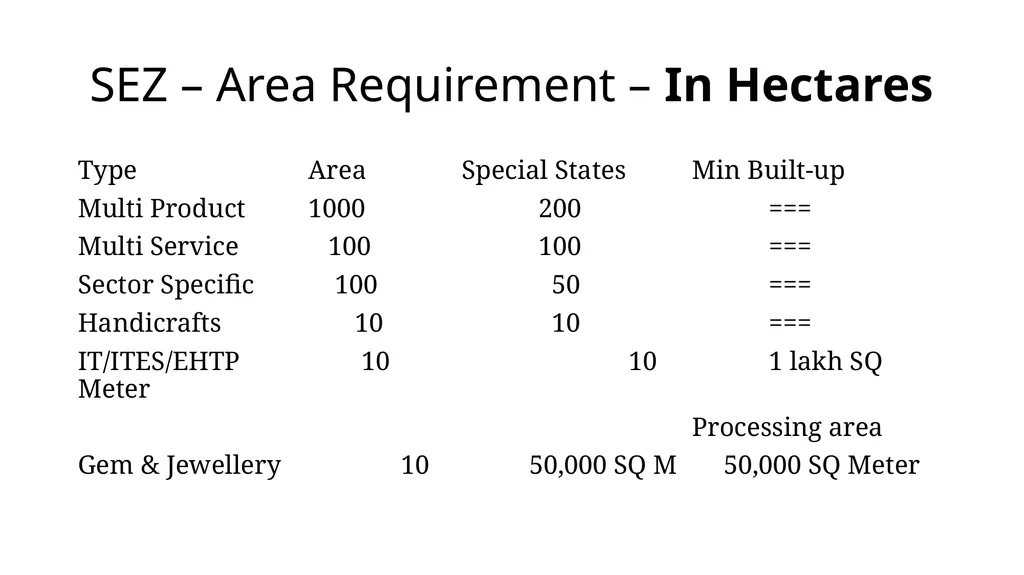
slide6. SEZ – Area Requirement – In Hectares Type Area Special States Min Built-up
Multi Product 1000 200 ===
Multi Service 100 100 ===
Sector Specific 100 50 ===
Handicrafts 10 10 ===
IT/ITES/EHTP 10 10 1 lakh SQ Meter
Processing area
Gem & Jewellery 10 50,000 SQ M 50,000 SQ Meter<br>
slide7. Incentives & Facilities – Developer Incentives and facilities available to SEZ developers include:-
Exemption from customs/excise duties for development of SEZs for authorized operations
Income Tax exemption on income derived from the business of development of the SEZ in a block of 10 years in 15 years under Section 80-IAB of the Income Tax Act. (Sunset Clause for Developers has become effective from 01.04.2017)
Exemption from Minimum Alternate Tax (MAT) under Section 115 JB of the Income Tax Act. (withdrawn w.e.f. 1.4.2012)
Exemption from Dividend Distribution Tax (DDT) under Section 115O of the Income Tax Act. (withdrawn w.e.f. 1.6.2011)
Exemption from Central Sales Tax (CST).
Exemption from Service Tax (Section 7, 26 and Second Schedule of the SEZ Act).<br>
slide8. SEZ- Developer Developer may import, procure goods/services from DTA
To file application to DC with list of goods/services, including machinery, equipment, construction material required for authorized operation – certified by Chartered Engineer
To declare place of storage within the SEZ – to the Specified Officer (SO) – goods imported/procured to be kept in clearly demarcated area for inspection
Developer to execute Bond Cum Legal Undertaking with DC for accounting and utilization of goods within 1 year or such extended period
To file quarterly and half year returns of procurement, consumption, utilization of goods – utilization certificate of Chartered Engineer
Procured goods shall nor be removed from SEZ without permission of SO an on payment of appropriate duties<br>
slide9. Incentives & Facilities available to SEZ Units Incentives and facilities offered to the units in SEZs
Duty free import/domestic procurement of goods for development, operation and maintenance of SEZ units
100% Income Tax exemption on export income for SEZ units under Section 10AA of the Income Tax Act for first 5 years, 50% for next 5 years thereafter and 50% of the ploughed back export profit for next 5 years. (Sunset Clause for Units will become effective from 01.04.2020)
Exemption from Minimum Alternate Tax (MAT) under section 115JB of the Income Tax Act. (withdrawn w.e.f. 1.4.2012)
Exemption from Central Sales Tax, Exemption from Service Tax and Exemption from State sales tax. These have now subsumed into GST and supplies to SEZs are zero rated under IGST Act, 2017.
Other levies as imposed by the respective State Governments. - Single window clearance for Central and State level approvals.<br>
slide10. Salient Features of SEZ Scheme duty free import/domestic procurement of goodsfor units and developers for their operations leading to a substantial saving in costs.
All supplies by DTA to SEZ are treated as exports and are zero rated in terms of application of GST
SEZs are deemed to be an airport, port, Land Custom Stations, and Inland Container Depot under the Customs Act - dedicated customs formation – no routine examination - SEZs ensure ease of doing business and other barrier by ensuring online applications, reducing procedural complexities, bureaucratic hassles to trade.<br>
slide11. Procedure for Setting up SEZ Procedure for setting up of units in SEZ
A consolidated application in form F of SEZ Rules to be made to DC with copy to Developer
The DC after scrutiny will place before Approval Committee which will meet once in every fortnight
BOA may approve with or without modification or reject within 15 days. – subject to fulfilment of criteria NFE, space availability, pollution norms etc
On approval of the proposal, the DC shall issue a LOA (in Form G) for setting up of the unit.<br>
slide12. Sec.26 – Exemptions to SEZ Exemption/Drawback/Concession – Sec.26 SEZ Act 2005
Developer/Unit of SEZ to receive input, input services, capital goods without taxes- supplier to ensure conditions in respective Acts fulfilled
Exemption from any duty of customs on goods imported or services provided in SEZ or Unit to carry on authorized operations by Developer of Entrepreneur
Exemption from any duty of customs on goods/services exported …Exemption from duty of Excise on goods brought from DTA to SEZ<br>
slide13. Procedure for procurement of Goods/Services-Developer Developer may import, procure goods/services from DTA
To file application to DC with list of goods/services, including machinery, equipment, construction material required for authorized operation – certified by Chartered Engineer
To declare place of storage within the SEZ – to the Specified Officer (SO) – goods imported/procured to be kept in clearly demarcated area for inspection
Developer to execute Bond Cum Legal Undertaking with DC for accounting and utilization of goods within 1 year or such extended period
To file quarterly and half year returns of procurement, consumption, utilization of goods – utilization certificate of Chartered Engineer
Procured goods shall nor be removed from SEZ without permission of Specified Officer (SO) an on payment of appropriate duties<br>
slide14. Export – under SEZ Act Sec. 2 (m) – Export - export” means -
(i) taking goods, or providing services, out of India, from a Special Economic Zone, by land, sea or air or by any other mode, whether physical or otherwise; or
(ii) supplying goods, or providing services, from the Domestic Tariff Area to a Unit or Developer; or
(iii) supplying goods, or providing services, from one Unit to another Unit or Developer, in the same or different Special Economic Zone;
Supply of goods/services from DTA to a Unit or Developer in SEZ export – Sec.51 – provisions will override with provisions of other Act<br>
slide15. Import under SEZ Act Sec. 2 (o) – Import - import” means -
(i) bringing goods or receiving services, in a Special Economic Zone, by a Unit or Developer from a place outside India by land, sea or air or by any other mode, whether physical or otherwise; or
(ii) receiving goods, or services by a Unit or Developer from another Unit or Developer of the same Special Economic Zone or a different Special Economic Zone;
Sec.30 of SEZ Act – goods removed from SEZ to DTA shall be chargeable to duty of customs, including ADD, CVD, Safeguard duty etc – if duty is not payable under CA 1962 – no duty on supply from SEZ to DTA<br>
slide16. SEZ Under GST Law Sec. 16 of the IGST Act
S.16(1) – ‘zero rated supply’ means any of the following supplies of goods or services or both, namely
(a) export of goods or services or both; or
(b) supply of goods or services or both to a SEZ Developer of a SEZ unit
Sec.16(2) of IGST Act – subject to provisions of Sec.17(5) (ineligible ITC) – credit of input tax may be availed notwithstanding such supplies are exempt
Sec.7(5) of IGST Act – supply to SEZ developer/Unit shall be considered as inter-state supply. (Sec.12 (3)(c ) of IGST Act – services in relation to immovable property to be treated as intra-state supply – accommodation/conferencing/banqueting etc<br>
slide17. SEZ - Miscellaneous Value of Bond Cum Legal Undertaking (BLUT) equal to taxes on imports/domestic procurement of CG, RM, Spares, Consumables, intermediaries, components, parts, packing materials not levied – (Rule 12 SEZ Rules 2006).
to carry out authorized operations, the SEZ Developer may import or procure goods and or services from the DTA without payment of duty, taxes and cess. (Rule 12)
No duties, taxes or cess would be required to be paid in such cases of export or transfer to another SEZ Developer, or to a SEZ Unit. (Rule 13 SEZ Rules)
FDI upto 100% allowed for setting up SEZ under automatic route – approval of Central Govt given by BoA – to ensure promoter equity not below 51%
Goods can be imported/procured only for authorized operations – not for personal use (Rule 27 (3) SEZ)
No export obligation for SEZ Unit – to achieve positive NFE during 5 year period of operation<br>
slide18. SEZ – Miscellaneous Areas to be earmarked for –residential- commercial – social facilities – residential not more than 25% of non processing area – commercial not more than 10% (Rule 11A (3)) - Schools, colleges, post office, banks, socio-cultural centres in remaining area
The goods which are brought into SEZ shall not be allowed to be removed to DDTA except with the permission of the Specified Officer and on payment of applicable duties, cess and taxes (Rule 13)
To submit Quarterly Performance Report (QPR) and Annual Performance Report (APR) to DC
SEZ Units shall be permitted to export prohibited items also provided the raw materials for the same are imported (Rule 26)<br>
slide19. Free Trade Warehousing Zone- FTWZ “Free Trade and Warehousing Zone’ (FTWZ) also a SEZ - wherein mainly trading and warehousing and other activities related thereto are carried on. It is a special category of Special Economic Zone with a focus on trading and warehousing.
Objectives
Create trade related infrastructure to import/export goods & services in free currency
duty free import of all goods (except prohibited items, arms and ammunitions, hazardous wastes and SCOMET items) for ware housing.
Such goods are permitted to be re-sold/re-invoices or re-exported. Re-export is permitted without any restrictions
Packing or re-packing without processing, and labelling as per customer or marketing requirements can be undertaken within FTWZ.
Sales to DTA buyer, customs duties as applicable on date of sale are payable.
Maximum warehouse period 2 years – on expiry customs duty payable unless re-exported within stipulated period<br>
slide20. FTWZ FTWZ Units allowed to hold the goods on account of the foreign supplier -can trade with or without labelling, packing or re-packing without any processing. units can re-sell or re-invoice or re-export the goods imported by them.
FTWZ deemed port/airport/ICD – goods moved without any documentation from port/airport under sub-manifest – if goods sold to DTA , DTA will file B/E for home consumption and pay duty-No filing of B/E till sold – B/L is identification document till sold<br>
slide21. THANK YOU<br>
slide2. SEZ- Introduction SEZ- specifically delineated duty-free enclave - deemed to be foreign territory for trade operations, duties and tariffs.
Domestic Tariff Area (DTA) means the whole of India (including the territorial waters and continental shelf) but does not include the areas of the Special Economic Zones.
Export Processing Zone (EPZ) Asia’s first set up in 1965 in Kandla- multiplicity of controls – lack of world-class infrastructure – unstable fiscal regime failed to attract foreign investment – SEZ policy revived in 2000
SEZs in India functioned from 1.11.2000 to 09.02.2006 under the provisions of the FTP - thereafter – SEZ Act 2005 - fiscal incentives were made effective through the provisions of relevant statutes.<br>
slide3. Objectives – Important Features The main objectives of the SEZ Act are:
generation of additional economic activity - promotion of exports of goods and services - promotion of investment from domestic and foreign sources
creation of employment opportunities - development of infrastructure facilities
Important features
key role for State Govt to create infrastructure
single window clearance 19 Member inter ministerial Board of Approval (BoA)
applications recommended by State/UT considered by BoA
decisions of Board are with consensus<br>
slide4. Key Entities in SEZ Key entities in the SEZ Scheme
Department of Commerce (DOC)- Formulation of policy for SEZ and review from time to time
Operational matters - SEZs-developer, co-developer and units - O/o Development Commissioner (DC) consists of DC including officers on deputation from Customs & Central Excise Dept.
Developer - means a person or a State Government which, has been granted a LOA for setting up of SEZ – CG may approve more than one developer if one Developer does not have minimum area for setting up
Co-developer: Any entity co-operated by the developer for setting up infrastructural facilities in the approved SEZ- to enter into agreement with Developer – approved by BoA and granted LOA
SEZ Units- A Unit set up by an entrepreneur in a SEZ-includes an existing Unit, an Offshore Banking Unit and a Unit in an International Financial Services Centre.<br>
slide5. State Govt Assistance – SEZ Land area requirements,
SEZ other than a SEZ for Information Technology(IT) or IT enabled services, Biotech or Health (other than hospital) service, shall have a contiguous land area of 50 hectares or more - minimum processing area in any SEZ cannot be less than 50% of the total area of SEZ
State Govt to endeavour in the following area
Exemption from the State and local taxes, including stamp duty, and taxes levied by local bodies on goods required for authorized operations by a Unit or Developer,
Exemption from electricity duty or taxes on sale, of self-generated or purchased electric power for use in the processing area of a SEZ Allow generation, transmission and distribution of power within a SEZ providing water, electricity and such other services,
Delegation of power to the DC under the Industrial Disputes Act,1947 in relation to the Unit and workmen employed by the developer - Declaration of the SEZ as a Public Utility Service under the Industrial Disputes Act,<br>
slide6. SEZ – Area Requirement – In Hectares Type Area Special States Min Built-up
Multi Product 1000 200 ===
Multi Service 100 100 ===
Sector Specific 100 50 ===
Handicrafts 10 10 ===
IT/ITES/EHTP 10 10 1 lakh SQ Meter
Processing area
Gem & Jewellery 10 50,000 SQ M 50,000 SQ Meter<br>
slide7. Incentives & Facilities – Developer Incentives and facilities available to SEZ developers include:-
Exemption from customs/excise duties for development of SEZs for authorized operations
Income Tax exemption on income derived from the business of development of the SEZ in a block of 10 years in 15 years under Section 80-IAB of the Income Tax Act. (Sunset Clause for Developers has become effective from 01.04.2017)
Exemption from Minimum Alternate Tax (MAT) under Section 115 JB of the Income Tax Act. (withdrawn w.e.f. 1.4.2012)
Exemption from Dividend Distribution Tax (DDT) under Section 115O of the Income Tax Act. (withdrawn w.e.f. 1.6.2011)
Exemption from Central Sales Tax (CST).
Exemption from Service Tax (Section 7, 26 and Second Schedule of the SEZ Act).<br>
slide8. SEZ- Developer Developer may import, procure goods/services from DTA
To file application to DC with list of goods/services, including machinery, equipment, construction material required for authorized operation – certified by Chartered Engineer
To declare place of storage within the SEZ – to the Specified Officer (SO) – goods imported/procured to be kept in clearly demarcated area for inspection
Developer to execute Bond Cum Legal Undertaking with DC for accounting and utilization of goods within 1 year or such extended period
To file quarterly and half year returns of procurement, consumption, utilization of goods – utilization certificate of Chartered Engineer
Procured goods shall nor be removed from SEZ without permission of SO an on payment of appropriate duties<br>
slide9. Incentives & Facilities available to SEZ Units Incentives and facilities offered to the units in SEZs
Duty free import/domestic procurement of goods for development, operation and maintenance of SEZ units
100% Income Tax exemption on export income for SEZ units under Section 10AA of the Income Tax Act for first 5 years, 50% for next 5 years thereafter and 50% of the ploughed back export profit for next 5 years. (Sunset Clause for Units will become effective from 01.04.2020)
Exemption from Minimum Alternate Tax (MAT) under section 115JB of the Income Tax Act. (withdrawn w.e.f. 1.4.2012)
Exemption from Central Sales Tax, Exemption from Service Tax and Exemption from State sales tax. These have now subsumed into GST and supplies to SEZs are zero rated under IGST Act, 2017.
Other levies as imposed by the respective State Governments. - Single window clearance for Central and State level approvals.<br>
slide10. Salient Features of SEZ Scheme duty free import/domestic procurement of goodsfor units and developers for their operations leading to a substantial saving in costs.
All supplies by DTA to SEZ are treated as exports and are zero rated in terms of application of GST
SEZs are deemed to be an airport, port, Land Custom Stations, and Inland Container Depot under the Customs Act - dedicated customs formation – no routine examination - SEZs ensure ease of doing business and other barrier by ensuring online applications, reducing procedural complexities, bureaucratic hassles to trade.<br>
slide11. Procedure for Setting up SEZ Procedure for setting up of units in SEZ
A consolidated application in form F of SEZ Rules to be made to DC with copy to Developer
The DC after scrutiny will place before Approval Committee which will meet once in every fortnight
BOA may approve with or without modification or reject within 15 days. – subject to fulfilment of criteria NFE, space availability, pollution norms etc
On approval of the proposal, the DC shall issue a LOA (in Form G) for setting up of the unit.<br>
slide12. Sec.26 – Exemptions to SEZ Exemption/Drawback/Concession – Sec.26 SEZ Act 2005
Developer/Unit of SEZ to receive input, input services, capital goods without taxes- supplier to ensure conditions in respective Acts fulfilled
Exemption from any duty of customs on goods imported or services provided in SEZ or Unit to carry on authorized operations by Developer of Entrepreneur
Exemption from any duty of customs on goods/services exported …Exemption from duty of Excise on goods brought from DTA to SEZ<br>
slide13. Procedure for procurement of Goods/Services-Developer Developer may import, procure goods/services from DTA
To file application to DC with list of goods/services, including machinery, equipment, construction material required for authorized operation – certified by Chartered Engineer
To declare place of storage within the SEZ – to the Specified Officer (SO) – goods imported/procured to be kept in clearly demarcated area for inspection
Developer to execute Bond Cum Legal Undertaking with DC for accounting and utilization of goods within 1 year or such extended period
To file quarterly and half year returns of procurement, consumption, utilization of goods – utilization certificate of Chartered Engineer
Procured goods shall nor be removed from SEZ without permission of Specified Officer (SO) an on payment of appropriate duties<br>
slide14. Export – under SEZ Act Sec. 2 (m) – Export - export” means -
(i) taking goods, or providing services, out of India, from a Special Economic Zone, by land, sea or air or by any other mode, whether physical or otherwise; or
(ii) supplying goods, or providing services, from the Domestic Tariff Area to a Unit or Developer; or
(iii) supplying goods, or providing services, from one Unit to another Unit or Developer, in the same or different Special Economic Zone;
Supply of goods/services from DTA to a Unit or Developer in SEZ export – Sec.51 – provisions will override with provisions of other Act<br>
slide15. Import under SEZ Act Sec. 2 (o) – Import - import” means -
(i) bringing goods or receiving services, in a Special Economic Zone, by a Unit or Developer from a place outside India by land, sea or air or by any other mode, whether physical or otherwise; or
(ii) receiving goods, or services by a Unit or Developer from another Unit or Developer of the same Special Economic Zone or a different Special Economic Zone;
Sec.30 of SEZ Act – goods removed from SEZ to DTA shall be chargeable to duty of customs, including ADD, CVD, Safeguard duty etc – if duty is not payable under CA 1962 – no duty on supply from SEZ to DTA<br>
slide16. SEZ Under GST Law Sec. 16 of the IGST Act
S.16(1) – ‘zero rated supply’ means any of the following supplies of goods or services or both, namely
(a) export of goods or services or both; or
(b) supply of goods or services or both to a SEZ Developer of a SEZ unit
Sec.16(2) of IGST Act – subject to provisions of Sec.17(5) (ineligible ITC) – credit of input tax may be availed notwithstanding such supplies are exempt
Sec.7(5) of IGST Act – supply to SEZ developer/Unit shall be considered as inter-state supply. (Sec.12 (3)(c ) of IGST Act – services in relation to immovable property to be treated as intra-state supply – accommodation/conferencing/banqueting etc<br>
slide17. SEZ - Miscellaneous Value of Bond Cum Legal Undertaking (BLUT) equal to taxes on imports/domestic procurement of CG, RM, Spares, Consumables, intermediaries, components, parts, packing materials not levied – (Rule 12 SEZ Rules 2006).
to carry out authorized operations, the SEZ Developer may import or procure goods and or services from the DTA without payment of duty, taxes and cess. (Rule 12)
No duties, taxes or cess would be required to be paid in such cases of export or transfer to another SEZ Developer, or to a SEZ Unit. (Rule 13 SEZ Rules)
FDI upto 100% allowed for setting up SEZ under automatic route – approval of Central Govt given by BoA – to ensure promoter equity not below 51%
Goods can be imported/procured only for authorized operations – not for personal use (Rule 27 (3) SEZ)
No export obligation for SEZ Unit – to achieve positive NFE during 5 year period of operation<br>
slide18. SEZ – Miscellaneous Areas to be earmarked for –residential- commercial – social facilities – residential not more than 25% of non processing area – commercial not more than 10% (Rule 11A (3)) - Schools, colleges, post office, banks, socio-cultural centres in remaining area
The goods which are brought into SEZ shall not be allowed to be removed to DDTA except with the permission of the Specified Officer and on payment of applicable duties, cess and taxes (Rule 13)
To submit Quarterly Performance Report (QPR) and Annual Performance Report (APR) to DC
SEZ Units shall be permitted to export prohibited items also provided the raw materials for the same are imported (Rule 26)<br>
slide19. Free Trade Warehousing Zone- FTWZ “Free Trade and Warehousing Zone’ (FTWZ) also a SEZ - wherein mainly trading and warehousing and other activities related thereto are carried on. It is a special category of Special Economic Zone with a focus on trading and warehousing.
Objectives
Create trade related infrastructure to import/export goods & services in free currency
duty free import of all goods (except prohibited items, arms and ammunitions, hazardous wastes and SCOMET items) for ware housing.
Such goods are permitted to be re-sold/re-invoices or re-exported. Re-export is permitted without any restrictions
Packing or re-packing without processing, and labelling as per customer or marketing requirements can be undertaken within FTWZ.
Sales to DTA buyer, customs duties as applicable on date of sale are payable.
Maximum warehouse period 2 years – on expiry customs duty payable unless re-exported within stipulated period<br>
slide20. FTWZ FTWZ Units allowed to hold the goods on account of the foreign supplier -can trade with or without labelling, packing or re-packing without any processing. units can re-sell or re-invoice or re-export the goods imported by them.
FTWZ deemed port/airport/ICD – goods moved without any documentation from port/airport under sub-manifest – if goods sold to DTA , DTA will file B/E for home consumption and pay duty-No filing of B/E till sold – B/L is identification document till sold<br>
slide21. THANK YOU<br>