
An Overview of Debt Financing for Florida Local

Description: An Overview of Debt Financing for Florida Local Governments March 13, 2025 Presentation Participants Nick Rocca: PFM Financial Advisors LLC Financial Advisor roccanpfm.com, (407-406-5773) Michael Broschart: Nabors, Giblin Nickerson
Related Topics
Download Presentation
"An Overview of Debt Financing for Florida Local" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. An Overview of Debt Financing for
Florida Local Governments
March 13, 2025<br>
slide2. Presentation Participants Nick Rocca: PFM Financial Advisors LLC – Financial Advisor
roccan@pfm.com, (407-406-5773)
Michael Broschart: Nabors, Giblin & Nickerson – Bond/Disclosure Counsel
mbroschart@ngn-tampa.com, (813-281-2222) 2<br>
slide3. Presentation Overview Municipal Market/Economic Update
Financing Structures
Financing Team
Methods of Public Bond Sale
Disclosure (Initial and Continuing)
Credit Ratings
Tax Compliance 3<br>
slide4. Municipal Market/Economic Update<br>
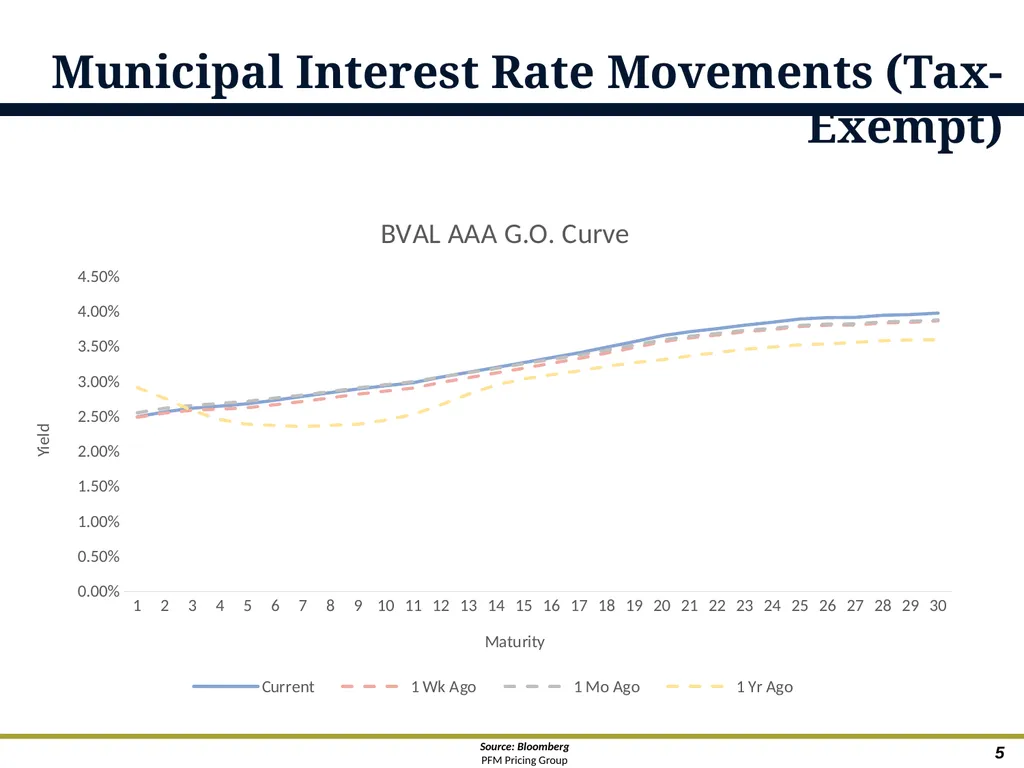
slide5. Spot Rates Municipal Interest Rate Movements (Tax-Exempt) Source: Bloomberg
PFM Pricing Group 5<br>
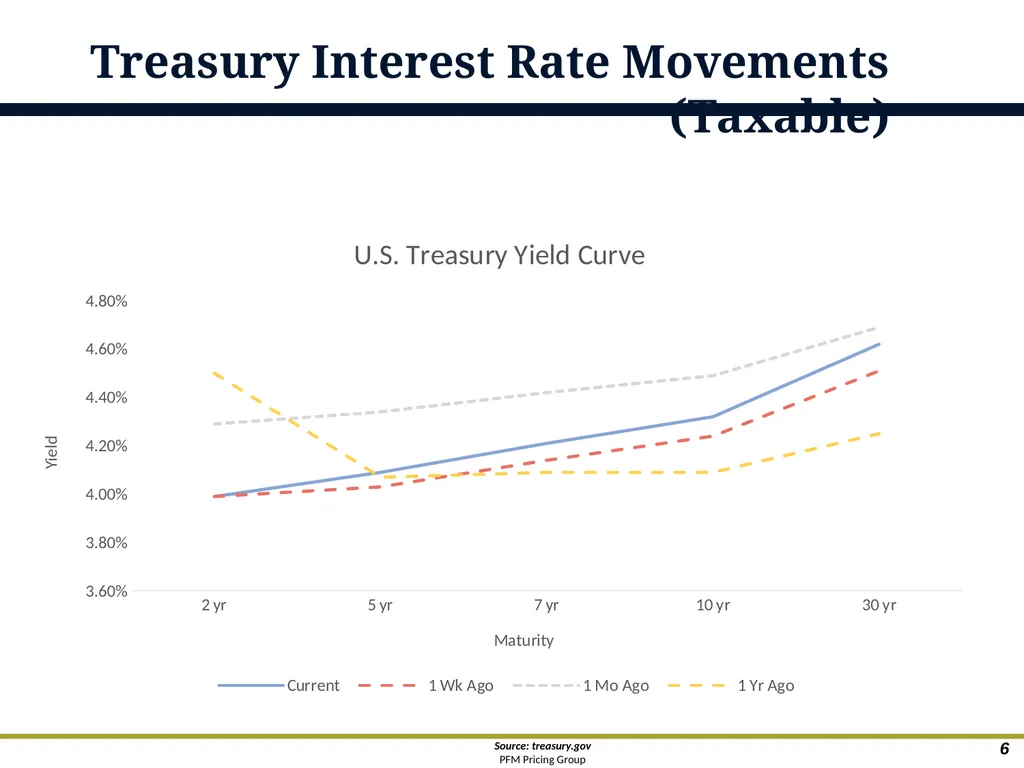
slide6. Source: treasury.gov
PFM Pricing Group Treasury Interest Rate Movements (Taxable) 6<br>
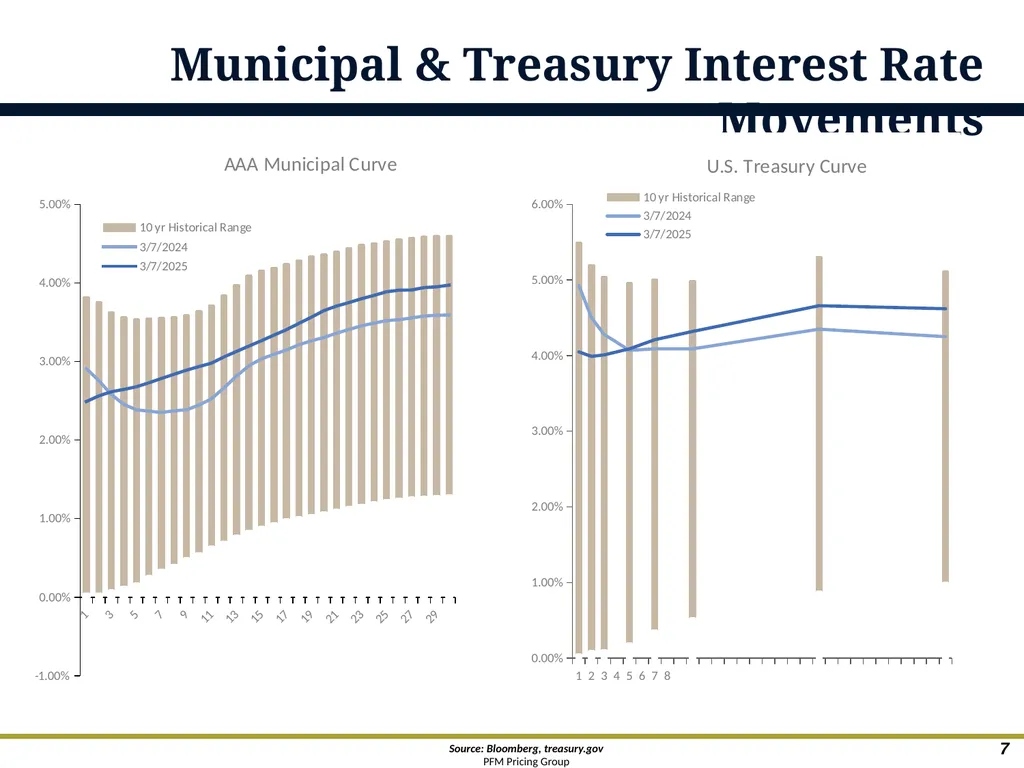
slide7. Municipal & Treasury Interest Rate Movements Source: Bloomberg, treasury.gov
PFM Pricing Group 7<br>
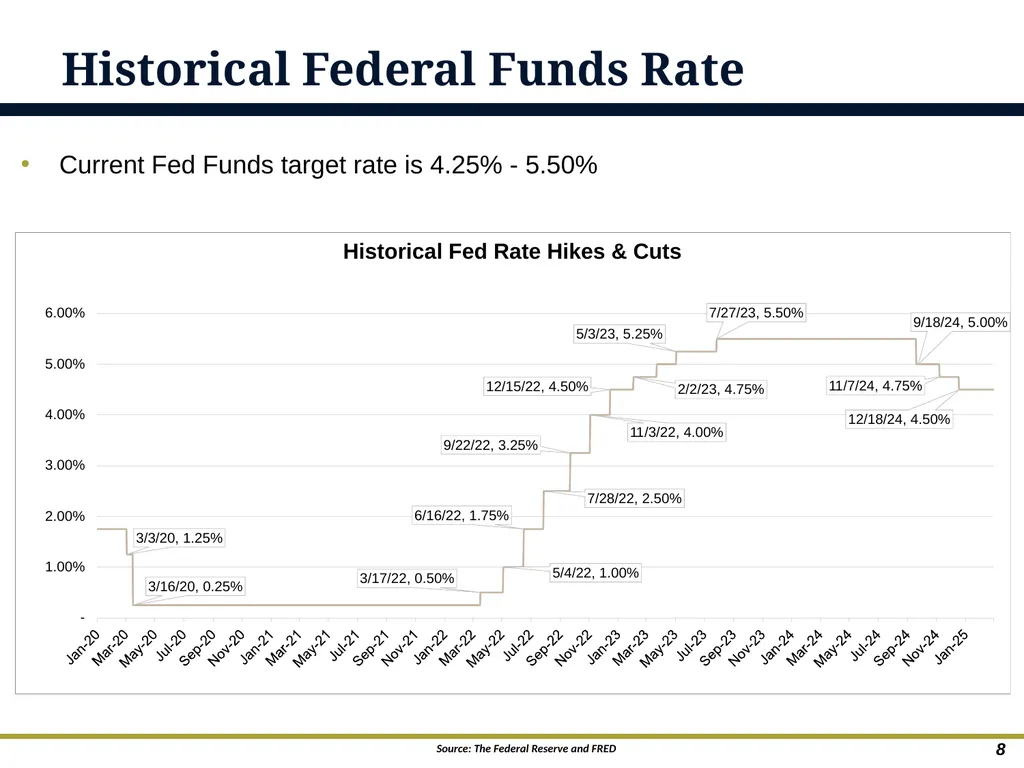
slide8. Historical Federal Funds Rate Current Fed Funds target rate is 4.25% - 5.50% 8 Source: The Federal Reserve and FRED<br>
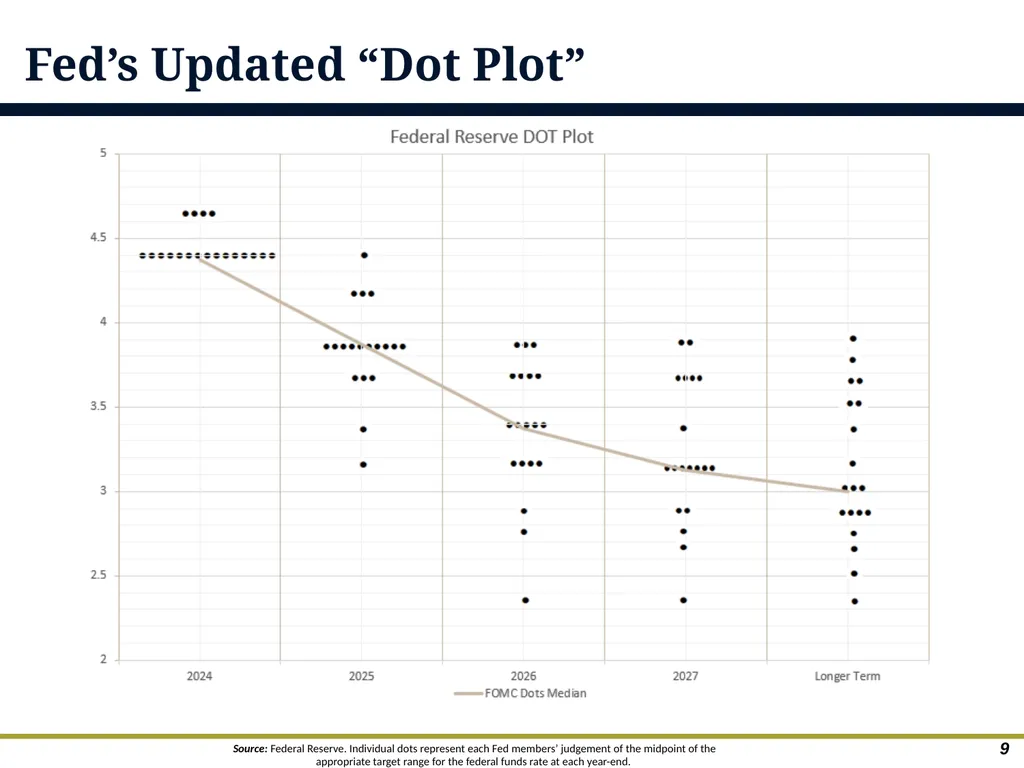
slide9. Fed’s Updated “Dot Plot” 9 Source: Federal Reserve. Individual dots represent each Fed members’ judgement of the midpoint of the appropriate target range for the federal funds rate at each year-end.<br>
slide10. Current Municipal Topics of Discussion Threat of Tax-Exemption elimination from municipal bonds
Congress looking to cut costs, removal of tax-exemption one of many proposed ideas
Possible reduction/changes to Federal Grants
Uncertainty around possible federal funding freeze that could impact local governments
Continuing Disclosure and Timing of ACFR Filing 10<br>
slide11. Financing Structures<br>
slide12. Why Borrow? Large capital projects often can’t be broken into smaller phases and funded out of annual budget
Mitigate rising construction costs
Taxpayer / Ratepayer equity – if multiple generations of tax or rate payers benefit from a capital project, then they should all pay for it
Refunding for debt service savings or restructuring
Historically speaking, interest rates for municipalities are low 12<br>
slide13. 13 Municipal Bonds, also called “munis,” are debt securities issued by states, cities, counties and other government entities
General Obligation Bonds are bonds backed by the full faith and credit of the issuer, which has the power to tax residents to pay bondholders (require voter referendum in Florida)
Revenue Bonds are bonds that are backed by revenues from a specific project or source, such as sales tax, gas tax, utility revenues, tolls, etc.
Certificates of Participation are secured by annual lease payments (subject to annual appropriation) derived from a specific revenue source, basket of revenues, or any other available revenues
Conduit Bonds are issued by governments on behalf of private entities such as non-profit colleges or hospitals -- these “conduit” borrowers agree to repay the issuer who in turn pays the interest and principal on the bonds – if the conduit borrower fails to make a payment, typically the issuer is not required to pay the bondholders What Types Of Bonds Are There?<br>
slide14. What is the best/appropriate repayment source?
Legally available for capital purpose
Dedicated to repayment
Reliably generated
Robust
Repayment of debt will normally take a priority position on use of revenues
Planning should include integration of adequate revenues to cover operating and maintenance of capital project
Potential sources of security utilized by Local Governments:
Ad Valorem Tax (approved via voter referendum)
Half Cent Sales Tax Revenues
Covenant to budget and appropriate legally available non ad valorem revenues (CBA)
Gas Taxes (Constitutional and Local Option)
Tourist Development Tax Revenues
Water and Sewer Revenues
Solid Waste Revenues
State Revenue Sharing Repayment of Debt 14<br>
slide15. 15 Fixed Rate Debt
Interest rate is fixed through the final term of the loan at time of pricing
Most municipal fixed rate debt is structured with semi-annual interest payments and annual principal payments
Traditionally associated with long-term debt but is also available for interim and short-term debt
Bonds, COPs, state revolving loans/programs, WIFIA, bank loans, notes
Variable Rate Debt
Interest rate resets weekly, bi-weekly, monthly or yearly based on an index or open market pricing
Commonly structured with monthly interest payments and yearly or semi-annually principal payments
Depending on type of debt, may require issuer to secure external liquidity (letter of credit)
Variable Rate Demand Obligations (VRDO), Floating Rate Notes, bank loans, lines of credit
Synthetic Fixed or Variable Rate Debt
Interest rate mode of underlying debt can be changed via a separate interest rate hedge agreement
Debt issued in variable rate mode can be converted to fixed rate mode and vice-versa
Requires a higher level of sophistication and understanding than traditional fixed or variable rate debt
Mark-to-market (MTM) can result in substantial penalties to terminate the contract voluntarily or involuntarily Interest Rate Modes<br>
slide16. Tax-Exempt Bonds
The interest earnings on most municipal bonds (depending on purpose of financing) generally is exempt from federal tax, making them an important investment vehicle for institutions and high net worth individuals
Issuance must be authorized by a governing body and proceeds must be used for public government purposes and to current refund existing debt
Subject to arbitrage rebate
Taxable Bonds
A fixed-income security issued by a government or related agencies, the income from which is not exempt from taxation
Generally issued to finance a project or activity that contains a private use or function -- in such cases, the federal government will not permit tax-exemption or to advance refund existing debt
Not subject to arbitrage rebate (can invest proceeds at a profit) 16 Tax Status Of Municipal Bonds<br>
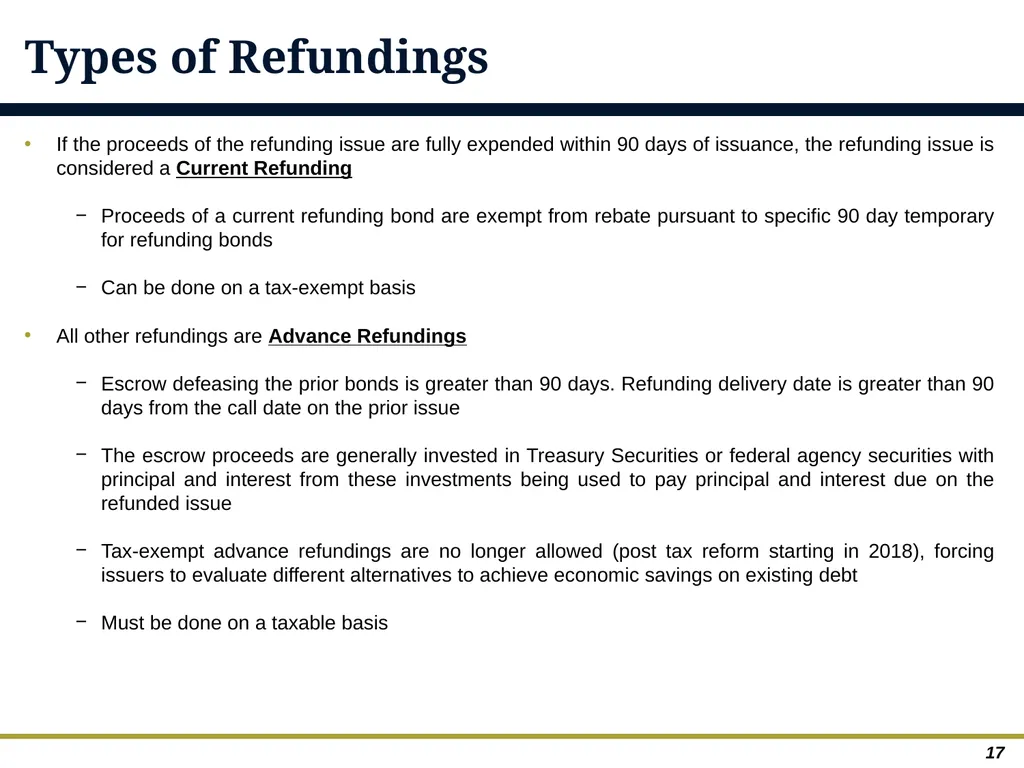
slide17. If the proceeds of the refunding issue are fully expended within 90 days of issuance, the refunding issue is considered a Current Refunding
Proceeds of a current refunding bond are exempt from rebate pursuant to specific 90 day temporary for refunding bonds
Can be done on a tax-exempt basis
All other refundings are Advance Refundings
Escrow defeasing the prior bonds is greater than 90 days. Refunding delivery date is greater than 90 days from the call date on the prior issue
The escrow proceeds are generally invested in Treasury Securities or federal agency securities with principal and interest from these investments being used to pay principal and interest due on the refunded issue
Tax-exempt advance refundings are no longer allowed (post tax reform starting in 2018), forcing issuers to evaluate different alternatives to achieve economic savings on existing debt
Must be done on a taxable basis 17 Types of Refundings<br>
slide18. 18 1. Because You Have To
Project or activity does not provide a major benefit to the public or has more than insignificant private benefit or use (private activity bonds)
Parking garage at an airport that is used by rental car companies
Pension obligation bonds/non-capital
Some sports facility projects
Pre-event financings for catastrophe related issuers
2. Because You Want To
Advance refund outstanding debt
Provides issuer more operational flexibility
Provides issuer a larger investment base Why Issue Taxable Municipal Bonds?<br>
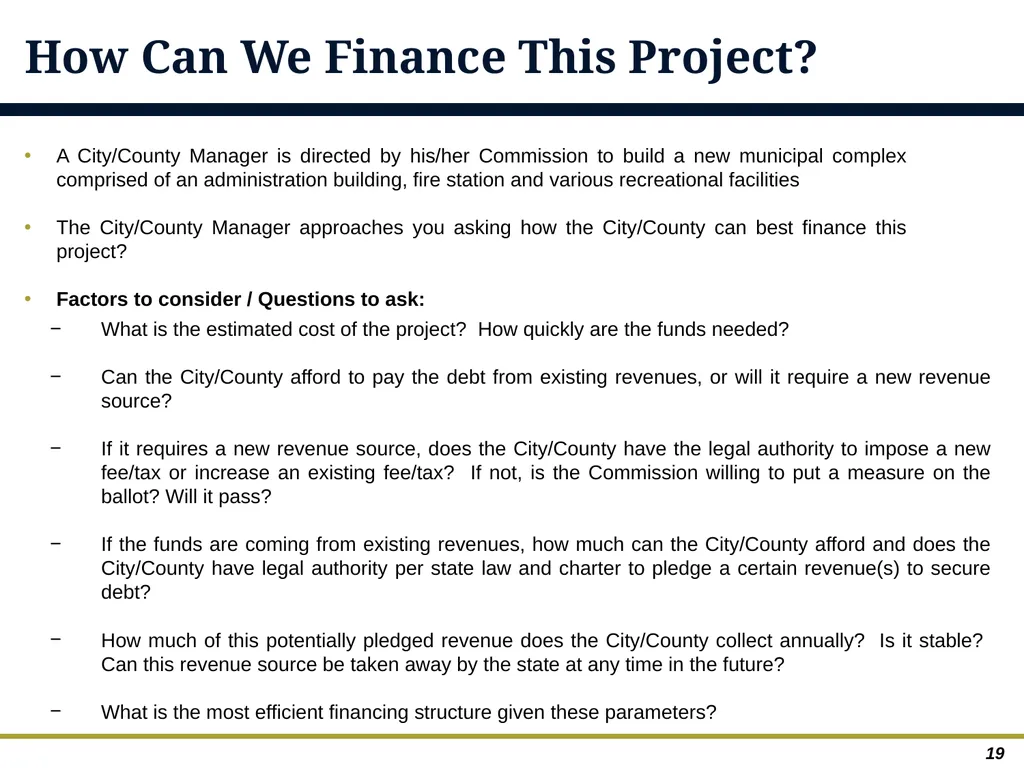
slide19. 19 A City/County Manager is directed by his/her Commission to build a new municipal complex comprised of an administration building, fire station and various recreational facilities
The City/County Manager approaches you asking how the City/County can best finance this project?
Factors to consider / Questions to ask: What is the estimated cost of the project? How quickly are the funds needed?
Can the City/County afford to pay the debt from existing revenues, or will it require a new revenue source?
If it requires a new revenue source, does the City/County have the legal authority to impose a new fee/tax or increase an existing fee/tax? If not, is the Commission willing to put a measure on the ballot? Will it pass?
If the funds are coming from existing revenues, how much can the City/County afford and does the City/County have legal authority per state law and charter to pledge a certain revenue(s) to secure debt?
How much of this potentially pledged revenue does the City/County collect annually? Is it stable? Can this revenue source be taken away by the state at any time in the future?
What is the most efficient financing structure given these parameters? How Can We Finance This Project?<br>
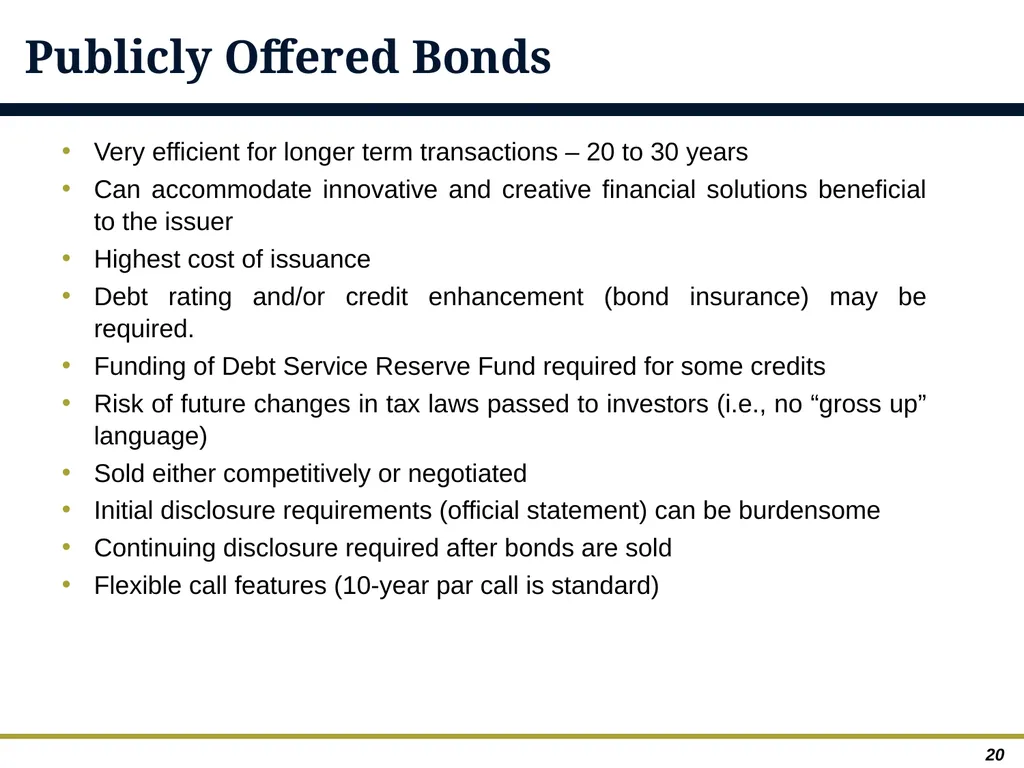
slide20. Very efficient for longer term transactions – 20 to 30 years
Can accommodate innovative and creative financial solutions beneficial to the issuer
Highest cost of issuance
Debt rating and/or credit enhancement (bond insurance) may be required.
Funding of Debt Service Reserve Fund required for some credits
Risk of future changes in tax laws passed to investors (i.e., no “gross up” language)
Sold either competitively or negotiated
Initial disclosure requirements (official statement) can be burdensome
Continuing disclosure required after bonds are sold
Flexible call features (10-year par call is standard) 20 Publicly Offered Bonds<br>
slide21. Privately Placed Bank Loans Does not require that transaction be rated or insured
No offering documents or registration required
Banks usually do not require a Debt Service Reserve Fund
Disclosure usually limited to receipt of ACFR and budget (no official statement)
Minimal cost of issuance 21<br>
slide22. Privately Placed Bank Loans Risk of future tax law changes retained by the issuer. Bank loans usually contain interest rate “gross up” language; providing the bank the right to increase the loan rate should tax law changes negatively impact the bank’s after tax yield.
Term limited typically to 20 years and some banks will not provide a fixed rate for the entire term. Instead, the bank would have a “put” option during the term of the loan (5, 10, or 15 years). This gives the bank the option to “put” the loan back to the issuer and force them to refinance at the then current market rates.
Level of municipal finance expertise varies. Larger banks have dedicated professionals; while smaller institutions may not. 22<br>
slide23. Commercial Paper/Line of Credit Ability to Drawdown Proceeds over time to fund Project
Bridge/Interim Financing, usually refinanced with a long-term debt issuance
Desired Repayment is short (5 years or less) and repayment timing is flexible
Interest rate is variable
Letter of Credit (LOC) may be required from bank. Also leaves issuer exposed to credit risk of the bank as well as renewal risk on LOC.
Early Prepayment Flexibility 23<br>
slide24. SRF Loan State Revolving Fund Loans (SRF) are limited to water and sewer type projects.
State of Florida issues bonds to generate a pool of funds, which are then used to make loans to local governments.
Issuer must complete application about projects to be financed, which is then reviewed by the State. Assuming the projects qualify, and funds are available, then all or a portion of the project may receive SRF funding. 24<br>
slide25. SRF Loan Interest rates are generally lower than what is available through public bond market or private bank market because interest rates are subsidized by the State.
The term of these loans is 20 years (10 years if funding design expenses) with debt service paid on a level semi-annual basis. As a result, the issuer has little structuring flexibility.
Revenue pledged as security typically subordinate to other water and sewer debt of the issuer (very important to make sure SRF documents comply with existing water and sewer bond documents to the extent issuer has other debt).
Funds are generally provided on a reimbursement basis so some type of interim financing or internal financing may be required.
Limited amount of capacity and typically abundant demand.
Stringent ongoing reporting/compliance requirements (a lot of paperwork).
Covenants are non-negotiable and generally not issuer friendly.
Consent required for additional bonds, even if additional bonds test requirement is met. 25<br>
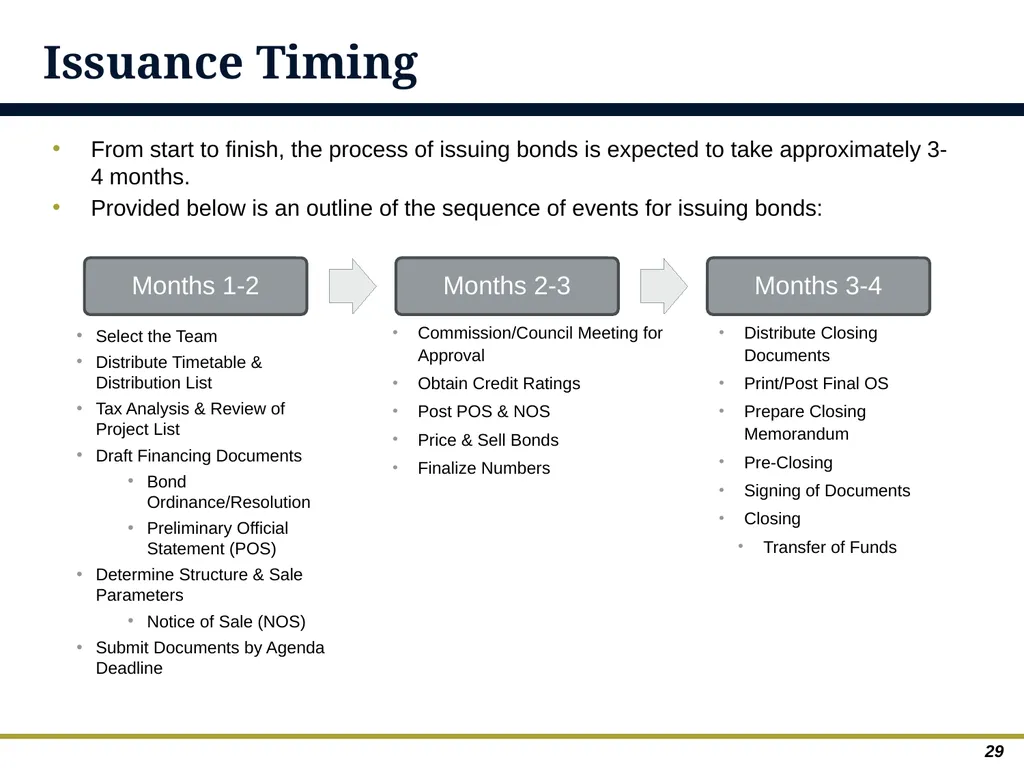
slide26. Issuance Timing From start to finish, the process of issuing bonds is expected to take approximately 3-4 months.
Provided below is an outline of the sequence of events for issuing bonds: Select the Team
Distribute Timetable & Distribution List
Tax Analysis & Review of Project List
Draft Financing Documents
Bond Ordinance/Resolution
Preliminary Official Statement (POS)
Determine Structure & Sale Parameters
Notice of Sale (NOS)
Submit Documents by Agenda Deadline Commission/Council Meeting for Approval
Obtain Credit Ratings
Post POS & NOS
Price & Sell Bonds
Finalize Numbers Distribute Closing Documents
Print/Post Final OS
Prepare Closing Memorandum
Pre-Closing
Signing of Documents
Closing
Transfer of Funds 29<br>
slide27. Recent Gulf Coast Area Financings Tampa Bay Water – $545,885,000 Utility Revenue and Refunding Bonds, Series 2024
2024A Bonds: $395,430,000 of tax-exempt new money capital projects
2024B Bonds: $94,405,000 of tax-exempt refunding bonds
2024C Bonds: $56,050,000 of taxable refunding bonds
Pasco County – $64,870,000 Half-Cent Sales Tax Improvement Revenue Bonds, Series 2024A
Finance capital improvements for parks and recreation facilities and jail facilities
City of Tampa - $130,000,000 Solid Waste System Revenue Note (BANA Line of Credit), Series 2025
City of Tampa - $120,500,000 Non-Ad Valorem Revenue Note (Waste-to-Energy Retrofit Project), Series 2024
2024 Bonds: $120,500,000 of tax-exempt new money capital projects
City of Tampa - $231,030,000 Water and Wastewater Systems Revenue Bonds, Series 2024
2024 Bonds: $231,030,000 of tax-exempt new money capital projects
City of Tampa - $34,935,000 Special Assessment Revenue Bonds (Central and Lower Basin Stormwater Improvements), Series 2023
2023 Bonds: $34,935,000 of tax-exempt new money capital projects 27<br>
slide28. Financing Team<br>
slide29. The Internal Team The core members or point persons of the internal bond financing team vary from issuer to issuer but typically representatives for a transaction include:
Administration – City/County Manager, Assistant City/County Manager, Finance/Budget or other designee
Legal – City/County Attorney or Assistant
Clerk – Clerk or Deputy, Finance Director
Transaction Dependent Members – Utility Director, City/County planning specialist, Fire/Police Chief, etc. 29<br>
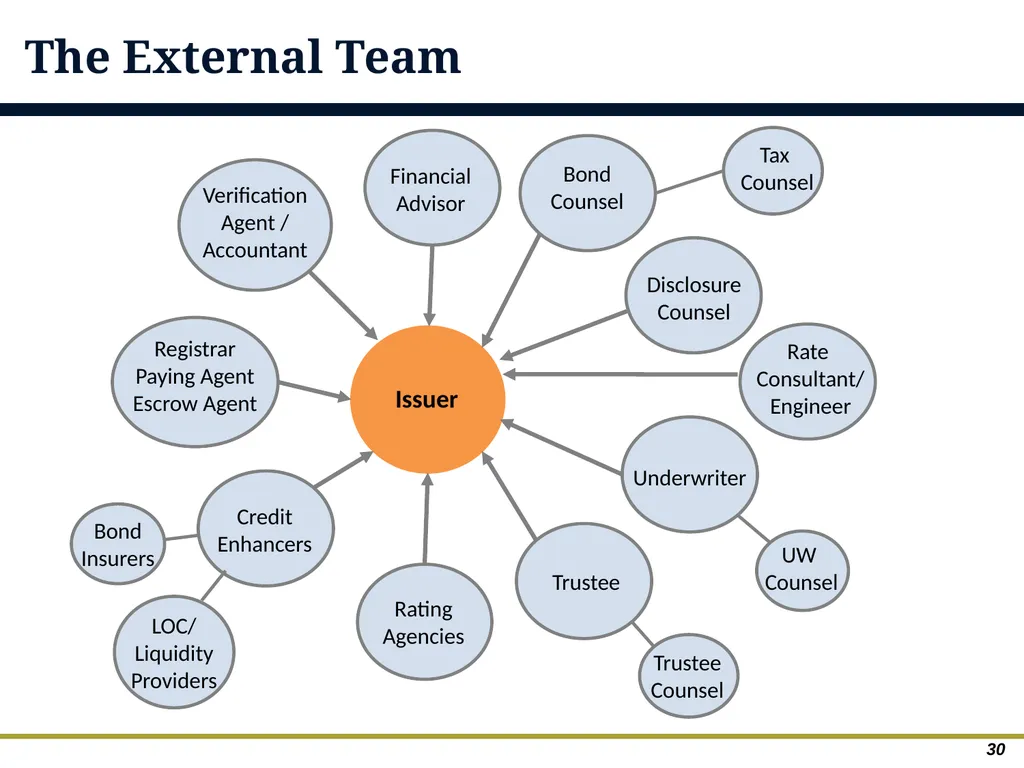
slide30. The External Team 30 Disclosure
Counsel<br>
slide31. The External Team Core Team
Financial Advisor
Bond Counsel
Disclosure Counsel
Transaction Dependent Team Members
Underwriter
Underwriter’s Counsel (if negotiated sale)
Paying Agent/Trustee
Verification Agent (if refunding)
Other specialty consultants and/or service providers (rate consultant/engineer/bond insurer) 31<br>
slide32. Financial Advisor Duties Role may vary according to:
Expertise of issuer staff
Type of bonds
Method of sale
Relationship may be on a transactional basis, or may be on a “retainer” basis
Financial advisor has a fiduciary responsibility to represent the Issuer, and only the issuer, in debt financings
Assists with capital planning, plan of finance development and transaction management tasks (including rating agency relations and bond pricing)
Acts as extension of staff 32<br>
slide33. Bond Counsel Duties Draft Principal Legal Documents
Bond Resolution/Trust Indenture
Escrow Deposit Agreement
Loan Agreements
Closing Documents
Opinions
Analyze applicable federal, state and local legal issues
Federal tax analysis
Assist in structuring transaction
Coordinate closing
Issue approving opinion 33<br>
slide34. Disclosure Counsel Duties Draft the Official Statement;
Conduct due diligence investigation;
10b-5 opinion;
Monitor legislative changes in primary and secondary market disclosure;
Prepare Continuing Disclosure Certificate.
Review the continuing disclosure submissions of the client and give advice related thereto. 34<br>
slide35. Methods of Public Bond Sale<br>
slide36. Competitive Sale Process:
The working group (finance staff, bond counsel, disclosure counsel, City/County attorney and financial advisor) prepares the bond documents and then advertises that bids for the bonds will be accepted on a specific date and time
The underwriter providing a bid on the day of sale to purchase the bonds at the lowest true interest cost (TIC) is awarded the bonds
The City/County does not have control over which underwriters participate in the bidding process and what investors the bonds are finally sold to, but awards to lowest true interest cost bid
Negotiated Sale Process:
The City/County undertakes a request of proposals (RFP) to procure the underwriting team at the outset of the transaction
This underwriting team would work with the rest of the working group to prepare the bond documents
On the sale date, the City/County (in consultation with its financial advisor) would negotiate the interest rates at which the bonds would be sold directly with the underwriting team
This method of sale allows the City/County to control the make up of the underwriting team and designate a priority as to which investors have the 1st opportunity to purchase the bonds Competitive vs. Negotiated Sale 36<br>
slide37. No universally accepted findings as to which method is preferable
Issuers should select method of sale most likely to achieve the lowest cost of borrowing and the most flexibility
Decision should be based on analysis of relevant rating, security, and structural features of the bonds
Other considerations can include desire to include small/minority owned businesses and ability to give local investors priority to purchase bonds Competitive vs. Negotiated Sale 37<br>
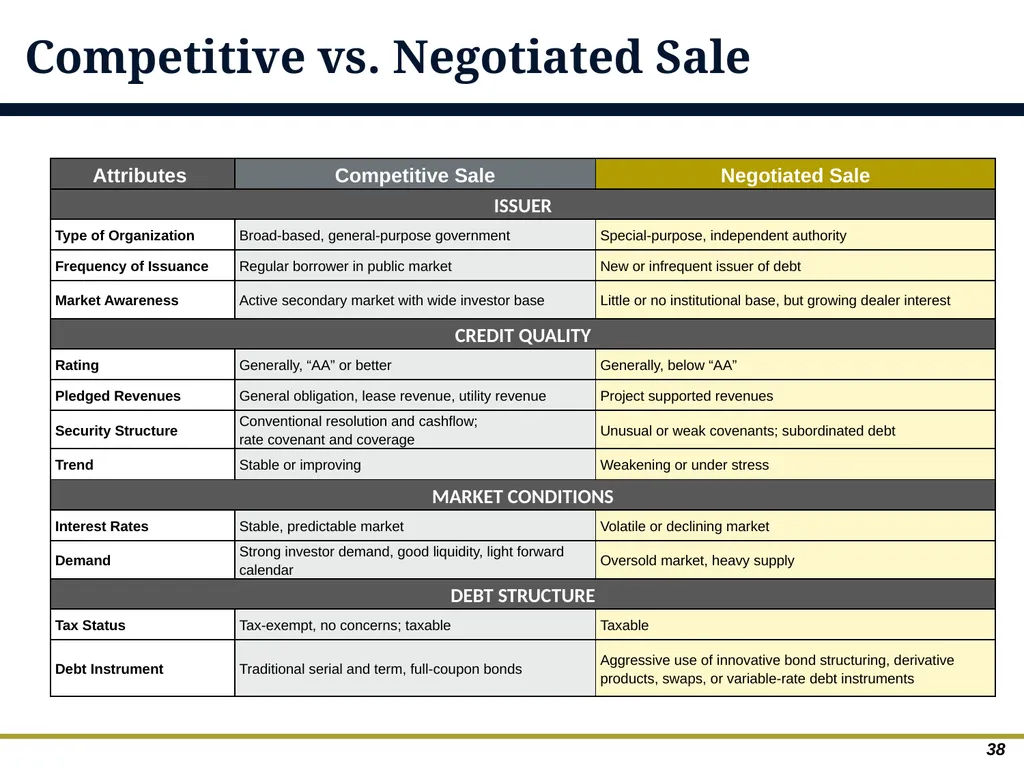
slide38. Competitive vs. Negotiated Sale 38<br>
slide39. Disclosure (Initial and Continuing)<br>
slide40. Disclosure: The New Normal SEC’s enforcement activity in public finance
In fiscal year 2024, the SEC brought 14 standalone enforcement cases in the municipal finance area.
The SEC will initiate an investigation when it has reason to suspect the federal securities laws have been violated.
Type of conduct generally involved in these cases
Fraud
Misrepresentations or omissions
What this looks like;
Where it is usually found;
Public finance materials and marketing materials for bond and other securities offerings. 40<br>
slide41. What Disclosure are Subject to Securities Law Scrutiny? Federal securities laws require issuers to exercise reasonable care in the preparation of offering documents and their statements to investors;
Any statement reasonably expected to reach investment community is subject to anti-fraud rules and includes:
Preliminary and Final Official Statement (Primary Offering);
Annual Continuing Disclosure Filings;
Periodic Notification of Material Events;
Public Statements such as websites, reports by the issuer, other public statements. 41<br>
slide42. Official Statement SEC Rule 15c2-12 defines a ‘final official statement’ to mean a document or set of documents prepared by an issuer of municipal securities, or its agents, setting forth information concerning the issuer of the municipal securities and the terms of the proposed offering (including financial information and operating data) that is complete on the date of its delivery to underwriters. MSRB Rule 32 has a similar definition.
Purpose is to describe the debt, issuer and sources of repayment.
Disclose all material facts.
Rule 10b-5 Anti-fraud provisions;
Do not make untrue statements of a material fact or omit to state a material fact necessary in order to make the statements made not misleading;
What is material?
Important fact to investor in making a decision to purchase the bonds;
Determined on the basis of the facts and circumstances in each instance. 42<br>
slide43. What goes in an Official Statement and why? Section 517.051, Florida Statutes, and Rule 3E-400.003, Florida Administrative Code, requires disclosure in the official statement of defaults of any bonds issued since December 31, 1975 that would be considered material by a reasonable investor, other than conduit bond defaults.
Section 218.386, Florida Statutes, requires disclosure in the official statement of any “finder” fees paid by the underwriter in connection with the sale of bonds issued by a local government. A “finder” is generally defined to mean a person not regularly employed by the underwriter and who enters into an understanding with the underwriter for compensation solely to influence the issuer to steer business to the underwriter. An example would be a paid lobbyist who is not a banker but nevertheless tries to influence award of business to the underwriter 43<br>
slide44. What goes in an Official Statement and why? Industry custom and the antifraud provisions of SEC Rule 10b-5 govern the remainder of the content:
Tax language (tax-exempt? bank qualified?);
Description of authority to issue the bonds, purpose of the bonds, and source of security for payment;
Description of bond covenants, including redemption language, rate covenants, if applicable, and parity test (e.g., conditional notice disclosure);
Description of sources and uses of funds, and debt service;
Description of credit enhancement (insurance and/or surety bonds), as well as ratings;
Description of investment policy ;
Description of material litigation; 44<br>
slide45. What goes in an Official Statement and why? Disclosure of professionals working on the transaction, as well as whether any of them are working on a contingent fee basis (in theory, can impact their impartiality);
Disclosure whether auditor consent was requested (we generally advise that this occur to ensure that we are aware of any potential problems which they are aware of, sort of a double check, and SEC Chairman has commented that auditor consent should be obtained, and if it is not obtained, that fact should be disclosed and what that means should be disclosed, i.e., that certain procedures have not been done, some of which are designed to discover material events that might have occurred since the date of the audit);
Appendices (general information about the issuer; form bond contract; audit; form Bond Counsel opinion; specimen insurance policy; reports of independent consultants, if applicable).
Disclosure Counsel may assist you in preparing the OS, but it is imperative that you review the OS for accuracy before it is published. Failure to do so could result in untrue statements, thereby subjecting the Issuer and/or individuals to liability. 45<br>
slide46. Annual Continuing Disclosure SEC Rule 15c2-12 Designed to prevent fraudulent, deceptive or manipulative acts or practices by underwriters.
Requires underwriters to determine that an issuer has undertaken in a written agreement to file updated financial information and operating data annually with EMMA (Electronic Municipal Market Access System) by a specified date and file material event notices →Continuing Disclosure Agreement.
Requires underwriters to reasonably determine that the issuer has complied “in all material respects” with the prior undertakings prior to offering for sale the related securities. 46<br>
slide47. Material Events Material events are required to be submitted to the EMMA system within 10 business days of the event occurring.
Some events need to be disclosed regardless if they are “material” or not:
Principal and interest payment delinquencies
Unscheduled draws on debt service reserves reflecting financial difficulties
Unscheduled draws on credit enhancement reflecting financial difficulties
Substitution of credit or liquidity providers, or their failure to perform
Adverse tax opinions
Defeasances
Rating changes
IRS proposed or final determinations of taxability
Tender offers
Bankruptcy, insolvency, receivership or similar event of the obligated person
Consummation of a merger, consideration or acquisition, or certain asset ales, involving the obligated person, or entry into or termination of a definitive agreement to the foregoing (if material)
Appointment of a successor or additional trustee or the change of name of a trustee (if material) 47<br>
slide48. Material Events (continued) An amendment to the Rule added two new material events that must be included in any continuing disclosure agreement that is executed on or after February 27, 2019
Incurrence of a financial obligation of the issuer or obligated person, if material, or agreement to covenants, events of default, remedies, priority rights, or other similar terms of a financial obligation of the issuer or obligated person, any of which affect security holders, if material
Default, event of acceleration, termination event, modification of terms, or other similar events under the terms of the financial obligation of the issuer or obligated person, any of which reflect financial difficulties
The term financial obligation means a: (A) Debt obligation; (B) Derivative instrument entered into in connection with or pledged as security or a source of payment for, an existing or planned debt obligation; or (C) Guarantee of (A) or (B).
The term financial obligation shall not include municipal securities as to which a final official statement has been provided to the MSRB consistent with the rule.
The term includes an issuer’s or obligated person’s debt, debt‐like, and debt‐related obligations.
The term does not include ordinary financial and operating liabilities incurred in the normal course of an issuer’s or obligated person’s business. 48<br>
slide49. Future Continuing Disclosure Agreements Future Continuing Disclosure Agreements
make it easy to comply;
make it easy for third party to determine if you’ve complied;
avoid using “X” number of days after fiscal year;
choose a date that you can comply with;
discuss “content” with underwriter prior to executing Continuing Disclosure Agreement;
what information is important for future investors to trade the bonds?;
are you able to provide such information for the life of the bonds (30 years);
consider availability of information from third-party sources;
if there are multiple obligated persons, clearly identify each party’s obligations. 49<br>
slide50. Continuing Disclosure Compliance BEST PRACTICES:
Copies of Continuing Disclosure Agreement, Official Statement, Dissemination Agent Agreement Materials.
Appoint someone (“Responsible Staff”) to be responsible for assembling and maintaining copies of the final Continuing Disclosure Agreements and final Official Statements for each applicable bond issue, together with any third-party Dissemination Agent Agreements, if applicable (DAC).
Compile Information Required by the Continuing Disclosure Agreements
At least 30 days prior to the earliest filing deadline, the Responsible Staff shall begin the process of compiling necessary information required by the Continuing Disclosure Agreements.
Ensure Completeness of Filing
At least 10 days prior to each filing deadline, the Responsible Staff shall determine whether all necessary items have been compiled for filing pursuant to the Continuing Disclosure Agreement requirements.
After filing, check EMMA and be aware of what was posted. 50<br>
slide51. Credit Ratings<br>
slide52. Bond Ratings What is a Bond Rating?
Measure of risk to bondholders
Reflects issuer’s ability & willingness to repay debt on time and in full (who, how, what?)
Factors in expected loss and recovery
Denotes credit quality by rating level
Independent opinion (subjective process)
Forward looking projection
A Bond Rating is Not
Audit
Recommendation to buy, sell or hold a security
Static or permanent
Opinion of community’s quality of life
Performance evaluation of current political leadership
Judgment of quality of service delivery 52<br>
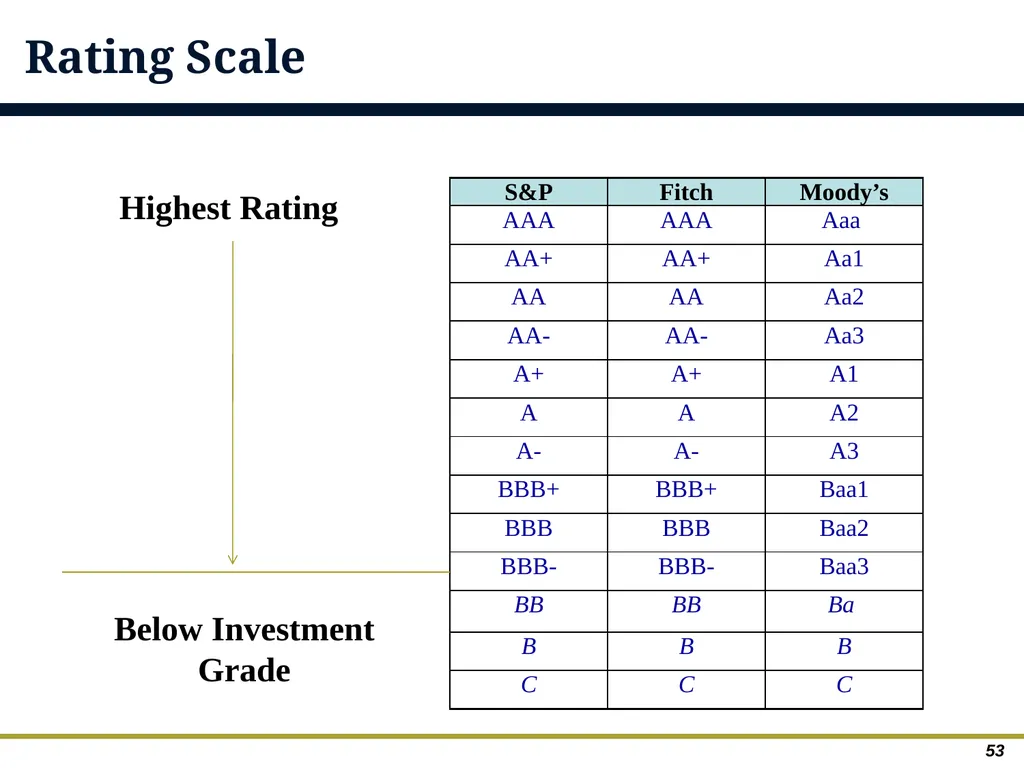
slide53. Highest Rating Below Investment Grade 53 Rating Scale<br>
slide54. 54 Applying for a Rating Issuer usually requests or applies for ratings from one or more agencies several weeks prior to the sale
Moody’s Investors Service, S&P Global Ratings and Fitch Ratings are the traditional rating agencies. Kroll Bond Rating Agency is the fourth agency working to increase market share
Issuer sends “credit package” to rating agencies
Ratings are assigned when the analyst has completed the credit analysis & makes a recommendation to a rating committee, which assigns the rating
Fee is paid to rating agency out of bond proceeds at closing<br>
slide55. Rating Agency Guidance What do rating agencies look for?
Diverse economy
A broad economic base that can withstand economic downturns
Demonstrated tax base stability
Sound financial position with strong reserves and liquidity
Financial flexibility to address unforeseen circumstances
History of strong management
Track record of making tough decisions during challenging fiscal times
Documented good management policies and practices
Manageable debt burden
Debt service as percent of operating expenditures
Rapid amortization of debt
Pension and OBEP liabilities
Other Considerations
Environmental
Cyber Security 45<br>
slide56. Credit Strategy Managing credit ratings takes preparation, long-term planning and an in-depth understanding of credit agency criteria
One role of the municipal/financial advisor is to provide that credit expertise
This means providing credit advice during the decision-making process to understand how policies, practices and financial decisions impact credit BEFORE implementing policies or making those decisions
Municipal/financial advisors are in regular communication with rating agencies and should be able to update you on changing rating agency methodologies and how they impact you as you plan for new debt issuance 46<br>
slide57. Tax Compliance<br>
slide58. Pre-Tax Analysis Analysis of pre-issuance type compliance issues
Is the project financeable with tax-exempt bond proceeds?
What is the level of private benefit or use?
Can the proceeds of the Bonds reasonably be expended within three years?
Does the issuer expect to reimburse itself for prior expenditures from the bond proceeds?
Does the issuer know how the capital improvements will be utilized (ie, purchase of land) 58<br>
slide59. Post Issuance Tax Issues Use of Bond Proceeds
Consistent accounting treatment for tracking investments and expenditures
Proper reimbursement
Timely expenditure
Qualified use of proceeds
Maintenance and retention of records
Use of excess proceeds
Monitoring Private Business Use
Identification and tracking of bond financed property
Awareness by key personnel of general rules
Review of contracts relating to bond financed property -- leases, sales contracts, management contracts, use agreements, etc.
Remediation
Maintenance and retention of records 59<br>
slide60. Post Issuance Tax Compliance Procedures Responsibility
Training/Awareness
Communication with Bond Counsel
Monitoring of Tax-Exempt Bonds
Review of Procedures and Rules 60<br>
slide61. Tax Agreements and Certificates Review and be familiar with/ask questions of Bond Counsel
Outline general requirements for each bond issue
Arbitrage Rebate
Temporary periods
FMV of investments
Reserve levels
Rebate 61<br>
slide62. Disclosures SPECIAL DISCLAIMER REGARDING THE RESEARCH AND FORECASTS INCLUDED IN THIS PRODUCT
This research and any forecasts are based on current public information as of 04/27/2023 that we consider reliable, but we do not represent it is accurate or complete, and it should not be relied on as such. The information, opinions, estimates and forecasts contained herein are as of the date hereof and are subject to change without prior notification.
ABOUT PFM
PFM is the marketing name for a group of affiliated companies providing a range of services. All services are provided through separate agreements with each company. This material is for general information purposes only and is not intended to provide specific advice or a specific recommendation.
Financial advisory services are provided by PFM Financial Advisors LLC a registered municipal advisor with the Securities and Exchange Commission (SEC) and the Municipal Securities Rulemaking Board (MSRB) under the Dodd-Frank Act of 2010. Additional applicable regulatory information is available upon request.
Consulting services are provided through PFM Group Consulting LLC. Institutional purchasing card services are provided through PFM Financial Services LLC. PFM’s financial modelling platform for strategic forecasting is provided through PFM Solutions LLC.
For more information regarding PFM’s services or entities, please visit www.pfm.com. 64<br>
slide2. Presentation Participants Nick Rocca: PFM Financial Advisors LLC – Financial Advisor
roccan@pfm.com, (407-406-5773)
Michael Broschart: Nabors, Giblin & Nickerson – Bond/Disclosure Counsel
mbroschart@ngn-tampa.com, (813-281-2222) 2<br>
slide3. Presentation Overview Municipal Market/Economic Update
Financing Structures
Financing Team
Methods of Public Bond Sale
Disclosure (Initial and Continuing)
Credit Ratings
Tax Compliance 3<br>
slide4. Municipal Market/Economic Update<br>
slide5. Spot Rates Municipal Interest Rate Movements (Tax-Exempt) Source: Bloomberg
PFM Pricing Group 5<br>
slide6. Source: treasury.gov
PFM Pricing Group Treasury Interest Rate Movements (Taxable) 6<br>
slide7. Municipal & Treasury Interest Rate Movements Source: Bloomberg, treasury.gov
PFM Pricing Group 7<br>
slide8. Historical Federal Funds Rate Current Fed Funds target rate is 4.25% - 5.50% 8 Source: The Federal Reserve and FRED<br>
slide9. Fed’s Updated “Dot Plot” 9 Source: Federal Reserve. Individual dots represent each Fed members’ judgement of the midpoint of the appropriate target range for the federal funds rate at each year-end.<br>
slide10. Current Municipal Topics of Discussion Threat of Tax-Exemption elimination from municipal bonds
Congress looking to cut costs, removal of tax-exemption one of many proposed ideas
Possible reduction/changes to Federal Grants
Uncertainty around possible federal funding freeze that could impact local governments
Continuing Disclosure and Timing of ACFR Filing 10<br>
slide11. Financing Structures<br>
slide12. Why Borrow? Large capital projects often can’t be broken into smaller phases and funded out of annual budget
Mitigate rising construction costs
Taxpayer / Ratepayer equity – if multiple generations of tax or rate payers benefit from a capital project, then they should all pay for it
Refunding for debt service savings or restructuring
Historically speaking, interest rates for municipalities are low 12<br>
slide13. 13 Municipal Bonds, also called “munis,” are debt securities issued by states, cities, counties and other government entities
General Obligation Bonds are bonds backed by the full faith and credit of the issuer, which has the power to tax residents to pay bondholders (require voter referendum in Florida)
Revenue Bonds are bonds that are backed by revenues from a specific project or source, such as sales tax, gas tax, utility revenues, tolls, etc.
Certificates of Participation are secured by annual lease payments (subject to annual appropriation) derived from a specific revenue source, basket of revenues, or any other available revenues
Conduit Bonds are issued by governments on behalf of private entities such as non-profit colleges or hospitals -- these “conduit” borrowers agree to repay the issuer who in turn pays the interest and principal on the bonds – if the conduit borrower fails to make a payment, typically the issuer is not required to pay the bondholders What Types Of Bonds Are There?<br>
slide14. What is the best/appropriate repayment source?
Legally available for capital purpose
Dedicated to repayment
Reliably generated
Robust
Repayment of debt will normally take a priority position on use of revenues
Planning should include integration of adequate revenues to cover operating and maintenance of capital project
Potential sources of security utilized by Local Governments:
Ad Valorem Tax (approved via voter referendum)
Half Cent Sales Tax Revenues
Covenant to budget and appropriate legally available non ad valorem revenues (CBA)
Gas Taxes (Constitutional and Local Option)
Tourist Development Tax Revenues
Water and Sewer Revenues
Solid Waste Revenues
State Revenue Sharing Repayment of Debt 14<br>
slide15. 15 Fixed Rate Debt
Interest rate is fixed through the final term of the loan at time of pricing
Most municipal fixed rate debt is structured with semi-annual interest payments and annual principal payments
Traditionally associated with long-term debt but is also available for interim and short-term debt
Bonds, COPs, state revolving loans/programs, WIFIA, bank loans, notes
Variable Rate Debt
Interest rate resets weekly, bi-weekly, monthly or yearly based on an index or open market pricing
Commonly structured with monthly interest payments and yearly or semi-annually principal payments
Depending on type of debt, may require issuer to secure external liquidity (letter of credit)
Variable Rate Demand Obligations (VRDO), Floating Rate Notes, bank loans, lines of credit
Synthetic Fixed or Variable Rate Debt
Interest rate mode of underlying debt can be changed via a separate interest rate hedge agreement
Debt issued in variable rate mode can be converted to fixed rate mode and vice-versa
Requires a higher level of sophistication and understanding than traditional fixed or variable rate debt
Mark-to-market (MTM) can result in substantial penalties to terminate the contract voluntarily or involuntarily Interest Rate Modes<br>
slide16. Tax-Exempt Bonds
The interest earnings on most municipal bonds (depending on purpose of financing) generally is exempt from federal tax, making them an important investment vehicle for institutions and high net worth individuals
Issuance must be authorized by a governing body and proceeds must be used for public government purposes and to current refund existing debt
Subject to arbitrage rebate
Taxable Bonds
A fixed-income security issued by a government or related agencies, the income from which is not exempt from taxation
Generally issued to finance a project or activity that contains a private use or function -- in such cases, the federal government will not permit tax-exemption or to advance refund existing debt
Not subject to arbitrage rebate (can invest proceeds at a profit) 16 Tax Status Of Municipal Bonds<br>
slide17. If the proceeds of the refunding issue are fully expended within 90 days of issuance, the refunding issue is considered a Current Refunding
Proceeds of a current refunding bond are exempt from rebate pursuant to specific 90 day temporary for refunding bonds
Can be done on a tax-exempt basis
All other refundings are Advance Refundings
Escrow defeasing the prior bonds is greater than 90 days. Refunding delivery date is greater than 90 days from the call date on the prior issue
The escrow proceeds are generally invested in Treasury Securities or federal agency securities with principal and interest from these investments being used to pay principal and interest due on the refunded issue
Tax-exempt advance refundings are no longer allowed (post tax reform starting in 2018), forcing issuers to evaluate different alternatives to achieve economic savings on existing debt
Must be done on a taxable basis 17 Types of Refundings<br>
slide18. 18 1. Because You Have To
Project or activity does not provide a major benefit to the public or has more than insignificant private benefit or use (private activity bonds)
Parking garage at an airport that is used by rental car companies
Pension obligation bonds/non-capital
Some sports facility projects
Pre-event financings for catastrophe related issuers
2. Because You Want To
Advance refund outstanding debt
Provides issuer more operational flexibility
Provides issuer a larger investment base Why Issue Taxable Municipal Bonds?<br>
slide19. 19 A City/County Manager is directed by his/her Commission to build a new municipal complex comprised of an administration building, fire station and various recreational facilities
The City/County Manager approaches you asking how the City/County can best finance this project?
Factors to consider / Questions to ask: What is the estimated cost of the project? How quickly are the funds needed?
Can the City/County afford to pay the debt from existing revenues, or will it require a new revenue source?
If it requires a new revenue source, does the City/County have the legal authority to impose a new fee/tax or increase an existing fee/tax? If not, is the Commission willing to put a measure on the ballot? Will it pass?
If the funds are coming from existing revenues, how much can the City/County afford and does the City/County have legal authority per state law and charter to pledge a certain revenue(s) to secure debt?
How much of this potentially pledged revenue does the City/County collect annually? Is it stable? Can this revenue source be taken away by the state at any time in the future?
What is the most efficient financing structure given these parameters? How Can We Finance This Project?<br>
slide20. Very efficient for longer term transactions – 20 to 30 years
Can accommodate innovative and creative financial solutions beneficial to the issuer
Highest cost of issuance
Debt rating and/or credit enhancement (bond insurance) may be required.
Funding of Debt Service Reserve Fund required for some credits
Risk of future changes in tax laws passed to investors (i.e., no “gross up” language)
Sold either competitively or negotiated
Initial disclosure requirements (official statement) can be burdensome
Continuing disclosure required after bonds are sold
Flexible call features (10-year par call is standard) 20 Publicly Offered Bonds<br>
slide21. Privately Placed Bank Loans Does not require that transaction be rated or insured
No offering documents or registration required
Banks usually do not require a Debt Service Reserve Fund
Disclosure usually limited to receipt of ACFR and budget (no official statement)
Minimal cost of issuance 21<br>
slide22. Privately Placed Bank Loans Risk of future tax law changes retained by the issuer. Bank loans usually contain interest rate “gross up” language; providing the bank the right to increase the loan rate should tax law changes negatively impact the bank’s after tax yield.
Term limited typically to 20 years and some banks will not provide a fixed rate for the entire term. Instead, the bank would have a “put” option during the term of the loan (5, 10, or 15 years). This gives the bank the option to “put” the loan back to the issuer and force them to refinance at the then current market rates.
Level of municipal finance expertise varies. Larger banks have dedicated professionals; while smaller institutions may not. 22<br>
slide23. Commercial Paper/Line of Credit Ability to Drawdown Proceeds over time to fund Project
Bridge/Interim Financing, usually refinanced with a long-term debt issuance
Desired Repayment is short (5 years or less) and repayment timing is flexible
Interest rate is variable
Letter of Credit (LOC) may be required from bank. Also leaves issuer exposed to credit risk of the bank as well as renewal risk on LOC.
Early Prepayment Flexibility 23<br>
slide24. SRF Loan State Revolving Fund Loans (SRF) are limited to water and sewer type projects.
State of Florida issues bonds to generate a pool of funds, which are then used to make loans to local governments.
Issuer must complete application about projects to be financed, which is then reviewed by the State. Assuming the projects qualify, and funds are available, then all or a portion of the project may receive SRF funding. 24<br>
slide25. SRF Loan Interest rates are generally lower than what is available through public bond market or private bank market because interest rates are subsidized by the State.
The term of these loans is 20 years (10 years if funding design expenses) with debt service paid on a level semi-annual basis. As a result, the issuer has little structuring flexibility.
Revenue pledged as security typically subordinate to other water and sewer debt of the issuer (very important to make sure SRF documents comply with existing water and sewer bond documents to the extent issuer has other debt).
Funds are generally provided on a reimbursement basis so some type of interim financing or internal financing may be required.
Limited amount of capacity and typically abundant demand.
Stringent ongoing reporting/compliance requirements (a lot of paperwork).
Covenants are non-negotiable and generally not issuer friendly.
Consent required for additional bonds, even if additional bonds test requirement is met. 25<br>
slide26. Issuance Timing From start to finish, the process of issuing bonds is expected to take approximately 3-4 months.
Provided below is an outline of the sequence of events for issuing bonds: Select the Team
Distribute Timetable & Distribution List
Tax Analysis & Review of Project List
Draft Financing Documents
Bond Ordinance/Resolution
Preliminary Official Statement (POS)
Determine Structure & Sale Parameters
Notice of Sale (NOS)
Submit Documents by Agenda Deadline Commission/Council Meeting for Approval
Obtain Credit Ratings
Post POS & NOS
Price & Sell Bonds
Finalize Numbers Distribute Closing Documents
Print/Post Final OS
Prepare Closing Memorandum
Pre-Closing
Signing of Documents
Closing
Transfer of Funds 29<br>
slide27. Recent Gulf Coast Area Financings Tampa Bay Water – $545,885,000 Utility Revenue and Refunding Bonds, Series 2024
2024A Bonds: $395,430,000 of tax-exempt new money capital projects
2024B Bonds: $94,405,000 of tax-exempt refunding bonds
2024C Bonds: $56,050,000 of taxable refunding bonds
Pasco County – $64,870,000 Half-Cent Sales Tax Improvement Revenue Bonds, Series 2024A
Finance capital improvements for parks and recreation facilities and jail facilities
City of Tampa - $130,000,000 Solid Waste System Revenue Note (BANA Line of Credit), Series 2025
City of Tampa - $120,500,000 Non-Ad Valorem Revenue Note (Waste-to-Energy Retrofit Project), Series 2024
2024 Bonds: $120,500,000 of tax-exempt new money capital projects
City of Tampa - $231,030,000 Water and Wastewater Systems Revenue Bonds, Series 2024
2024 Bonds: $231,030,000 of tax-exempt new money capital projects
City of Tampa - $34,935,000 Special Assessment Revenue Bonds (Central and Lower Basin Stormwater Improvements), Series 2023
2023 Bonds: $34,935,000 of tax-exempt new money capital projects 27<br>
slide28. Financing Team<br>
slide29. The Internal Team The core members or point persons of the internal bond financing team vary from issuer to issuer but typically representatives for a transaction include:
Administration – City/County Manager, Assistant City/County Manager, Finance/Budget or other designee
Legal – City/County Attorney or Assistant
Clerk – Clerk or Deputy, Finance Director
Transaction Dependent Members – Utility Director, City/County planning specialist, Fire/Police Chief, etc. 29<br>
slide30. The External Team 30 Disclosure
Counsel<br>
slide31. The External Team Core Team
Financial Advisor
Bond Counsel
Disclosure Counsel
Transaction Dependent Team Members
Underwriter
Underwriter’s Counsel (if negotiated sale)
Paying Agent/Trustee
Verification Agent (if refunding)
Other specialty consultants and/or service providers (rate consultant/engineer/bond insurer) 31<br>
slide32. Financial Advisor Duties Role may vary according to:
Expertise of issuer staff
Type of bonds
Method of sale
Relationship may be on a transactional basis, or may be on a “retainer” basis
Financial advisor has a fiduciary responsibility to represent the Issuer, and only the issuer, in debt financings
Assists with capital planning, plan of finance development and transaction management tasks (including rating agency relations and bond pricing)
Acts as extension of staff 32<br>
slide33. Bond Counsel Duties Draft Principal Legal Documents
Bond Resolution/Trust Indenture
Escrow Deposit Agreement
Loan Agreements
Closing Documents
Opinions
Analyze applicable federal, state and local legal issues
Federal tax analysis
Assist in structuring transaction
Coordinate closing
Issue approving opinion 33<br>
slide34. Disclosure Counsel Duties Draft the Official Statement;
Conduct due diligence investigation;
10b-5 opinion;
Monitor legislative changes in primary and secondary market disclosure;
Prepare Continuing Disclosure Certificate.
Review the continuing disclosure submissions of the client and give advice related thereto. 34<br>
slide35. Methods of Public Bond Sale<br>
slide36. Competitive Sale Process:
The working group (finance staff, bond counsel, disclosure counsel, City/County attorney and financial advisor) prepares the bond documents and then advertises that bids for the bonds will be accepted on a specific date and time
The underwriter providing a bid on the day of sale to purchase the bonds at the lowest true interest cost (TIC) is awarded the bonds
The City/County does not have control over which underwriters participate in the bidding process and what investors the bonds are finally sold to, but awards to lowest true interest cost bid
Negotiated Sale Process:
The City/County undertakes a request of proposals (RFP) to procure the underwriting team at the outset of the transaction
This underwriting team would work with the rest of the working group to prepare the bond documents
On the sale date, the City/County (in consultation with its financial advisor) would negotiate the interest rates at which the bonds would be sold directly with the underwriting team
This method of sale allows the City/County to control the make up of the underwriting team and designate a priority as to which investors have the 1st opportunity to purchase the bonds Competitive vs. Negotiated Sale 36<br>
slide37. No universally accepted findings as to which method is preferable
Issuers should select method of sale most likely to achieve the lowest cost of borrowing and the most flexibility
Decision should be based on analysis of relevant rating, security, and structural features of the bonds
Other considerations can include desire to include small/minority owned businesses and ability to give local investors priority to purchase bonds Competitive vs. Negotiated Sale 37<br>
slide38. Competitive vs. Negotiated Sale 38<br>
slide39. Disclosure (Initial and Continuing)<br>
slide40. Disclosure: The New Normal SEC’s enforcement activity in public finance
In fiscal year 2024, the SEC brought 14 standalone enforcement cases in the municipal finance area.
The SEC will initiate an investigation when it has reason to suspect the federal securities laws have been violated.
Type of conduct generally involved in these cases
Fraud
Misrepresentations or omissions
What this looks like;
Where it is usually found;
Public finance materials and marketing materials for bond and other securities offerings. 40<br>
slide41. What Disclosure are Subject to Securities Law Scrutiny? Federal securities laws require issuers to exercise reasonable care in the preparation of offering documents and their statements to investors;
Any statement reasonably expected to reach investment community is subject to anti-fraud rules and includes:
Preliminary and Final Official Statement (Primary Offering);
Annual Continuing Disclosure Filings;
Periodic Notification of Material Events;
Public Statements such as websites, reports by the issuer, other public statements. 41<br>
slide42. Official Statement SEC Rule 15c2-12 defines a ‘final official statement’ to mean a document or set of documents prepared by an issuer of municipal securities, or its agents, setting forth information concerning the issuer of the municipal securities and the terms of the proposed offering (including financial information and operating data) that is complete on the date of its delivery to underwriters. MSRB Rule 32 has a similar definition.
Purpose is to describe the debt, issuer and sources of repayment.
Disclose all material facts.
Rule 10b-5 Anti-fraud provisions;
Do not make untrue statements of a material fact or omit to state a material fact necessary in order to make the statements made not misleading;
What is material?
Important fact to investor in making a decision to purchase the bonds;
Determined on the basis of the facts and circumstances in each instance. 42<br>
slide43. What goes in an Official Statement and why? Section 517.051, Florida Statutes, and Rule 3E-400.003, Florida Administrative Code, requires disclosure in the official statement of defaults of any bonds issued since December 31, 1975 that would be considered material by a reasonable investor, other than conduit bond defaults.
Section 218.386, Florida Statutes, requires disclosure in the official statement of any “finder” fees paid by the underwriter in connection with the sale of bonds issued by a local government. A “finder” is generally defined to mean a person not regularly employed by the underwriter and who enters into an understanding with the underwriter for compensation solely to influence the issuer to steer business to the underwriter. An example would be a paid lobbyist who is not a banker but nevertheless tries to influence award of business to the underwriter 43<br>
slide44. What goes in an Official Statement and why? Industry custom and the antifraud provisions of SEC Rule 10b-5 govern the remainder of the content:
Tax language (tax-exempt? bank qualified?);
Description of authority to issue the bonds, purpose of the bonds, and source of security for payment;
Description of bond covenants, including redemption language, rate covenants, if applicable, and parity test (e.g., conditional notice disclosure);
Description of sources and uses of funds, and debt service;
Description of credit enhancement (insurance and/or surety bonds), as well as ratings;
Description of investment policy ;
Description of material litigation; 44<br>
slide45. What goes in an Official Statement and why? Disclosure of professionals working on the transaction, as well as whether any of them are working on a contingent fee basis (in theory, can impact their impartiality);
Disclosure whether auditor consent was requested (we generally advise that this occur to ensure that we are aware of any potential problems which they are aware of, sort of a double check, and SEC Chairman has commented that auditor consent should be obtained, and if it is not obtained, that fact should be disclosed and what that means should be disclosed, i.e., that certain procedures have not been done, some of which are designed to discover material events that might have occurred since the date of the audit);
Appendices (general information about the issuer; form bond contract; audit; form Bond Counsel opinion; specimen insurance policy; reports of independent consultants, if applicable).
Disclosure Counsel may assist you in preparing the OS, but it is imperative that you review the OS for accuracy before it is published. Failure to do so could result in untrue statements, thereby subjecting the Issuer and/or individuals to liability. 45<br>
slide46. Annual Continuing Disclosure SEC Rule 15c2-12 Designed to prevent fraudulent, deceptive or manipulative acts or practices by underwriters.
Requires underwriters to determine that an issuer has undertaken in a written agreement to file updated financial information and operating data annually with EMMA (Electronic Municipal Market Access System) by a specified date and file material event notices →Continuing Disclosure Agreement.
Requires underwriters to reasonably determine that the issuer has complied “in all material respects” with the prior undertakings prior to offering for sale the related securities. 46<br>
slide47. Material Events Material events are required to be submitted to the EMMA system within 10 business days of the event occurring.
Some events need to be disclosed regardless if they are “material” or not:
Principal and interest payment delinquencies
Unscheduled draws on debt service reserves reflecting financial difficulties
Unscheduled draws on credit enhancement reflecting financial difficulties
Substitution of credit or liquidity providers, or their failure to perform
Adverse tax opinions
Defeasances
Rating changes
IRS proposed or final determinations of taxability
Tender offers
Bankruptcy, insolvency, receivership or similar event of the obligated person
Consummation of a merger, consideration or acquisition, or certain asset ales, involving the obligated person, or entry into or termination of a definitive agreement to the foregoing (if material)
Appointment of a successor or additional trustee or the change of name of a trustee (if material) 47<br>
slide48. Material Events (continued) An amendment to the Rule added two new material events that must be included in any continuing disclosure agreement that is executed on or after February 27, 2019
Incurrence of a financial obligation of the issuer or obligated person, if material, or agreement to covenants, events of default, remedies, priority rights, or other similar terms of a financial obligation of the issuer or obligated person, any of which affect security holders, if material
Default, event of acceleration, termination event, modification of terms, or other similar events under the terms of the financial obligation of the issuer or obligated person, any of which reflect financial difficulties
The term financial obligation means a: (A) Debt obligation; (B) Derivative instrument entered into in connection with or pledged as security or a source of payment for, an existing or planned debt obligation; or (C) Guarantee of (A) or (B).
The term financial obligation shall not include municipal securities as to which a final official statement has been provided to the MSRB consistent with the rule.
The term includes an issuer’s or obligated person’s debt, debt‐like, and debt‐related obligations.
The term does not include ordinary financial and operating liabilities incurred in the normal course of an issuer’s or obligated person’s business. 48<br>
slide49. Future Continuing Disclosure Agreements Future Continuing Disclosure Agreements
make it easy to comply;
make it easy for third party to determine if you’ve complied;
avoid using “X” number of days after fiscal year;
choose a date that you can comply with;
discuss “content” with underwriter prior to executing Continuing Disclosure Agreement;
what information is important for future investors to trade the bonds?;
are you able to provide such information for the life of the bonds (30 years);
consider availability of information from third-party sources;
if there are multiple obligated persons, clearly identify each party’s obligations. 49<br>
slide50. Continuing Disclosure Compliance BEST PRACTICES:
Copies of Continuing Disclosure Agreement, Official Statement, Dissemination Agent Agreement Materials.
Appoint someone (“Responsible Staff”) to be responsible for assembling and maintaining copies of the final Continuing Disclosure Agreements and final Official Statements for each applicable bond issue, together with any third-party Dissemination Agent Agreements, if applicable (DAC).
Compile Information Required by the Continuing Disclosure Agreements
At least 30 days prior to the earliest filing deadline, the Responsible Staff shall begin the process of compiling necessary information required by the Continuing Disclosure Agreements.
Ensure Completeness of Filing
At least 10 days prior to each filing deadline, the Responsible Staff shall determine whether all necessary items have been compiled for filing pursuant to the Continuing Disclosure Agreement requirements.
After filing, check EMMA and be aware of what was posted. 50<br>
slide51. Credit Ratings<br>
slide52. Bond Ratings What is a Bond Rating?
Measure of risk to bondholders
Reflects issuer’s ability & willingness to repay debt on time and in full (who, how, what?)
Factors in expected loss and recovery
Denotes credit quality by rating level
Independent opinion (subjective process)
Forward looking projection
A Bond Rating is Not
Audit
Recommendation to buy, sell or hold a security
Static or permanent
Opinion of community’s quality of life
Performance evaluation of current political leadership
Judgment of quality of service delivery 52<br>
slide53. Highest Rating Below Investment Grade 53 Rating Scale<br>
slide54. 54 Applying for a Rating Issuer usually requests or applies for ratings from one or more agencies several weeks prior to the sale
Moody’s Investors Service, S&P Global Ratings and Fitch Ratings are the traditional rating agencies. Kroll Bond Rating Agency is the fourth agency working to increase market share
Issuer sends “credit package” to rating agencies
Ratings are assigned when the analyst has completed the credit analysis & makes a recommendation to a rating committee, which assigns the rating
Fee is paid to rating agency out of bond proceeds at closing<br>
slide55. Rating Agency Guidance What do rating agencies look for?
Diverse economy
A broad economic base that can withstand economic downturns
Demonstrated tax base stability
Sound financial position with strong reserves and liquidity
Financial flexibility to address unforeseen circumstances
History of strong management
Track record of making tough decisions during challenging fiscal times
Documented good management policies and practices
Manageable debt burden
Debt service as percent of operating expenditures
Rapid amortization of debt
Pension and OBEP liabilities
Other Considerations
Environmental
Cyber Security 45<br>
slide56. Credit Strategy Managing credit ratings takes preparation, long-term planning and an in-depth understanding of credit agency criteria
One role of the municipal/financial advisor is to provide that credit expertise
This means providing credit advice during the decision-making process to understand how policies, practices and financial decisions impact credit BEFORE implementing policies or making those decisions
Municipal/financial advisors are in regular communication with rating agencies and should be able to update you on changing rating agency methodologies and how they impact you as you plan for new debt issuance 46<br>
slide57. Tax Compliance<br>
slide58. Pre-Tax Analysis Analysis of pre-issuance type compliance issues
Is the project financeable with tax-exempt bond proceeds?
What is the level of private benefit or use?
Can the proceeds of the Bonds reasonably be expended within three years?
Does the issuer expect to reimburse itself for prior expenditures from the bond proceeds?
Does the issuer know how the capital improvements will be utilized (ie, purchase of land) 58<br>
slide59. Post Issuance Tax Issues Use of Bond Proceeds
Consistent accounting treatment for tracking investments and expenditures
Proper reimbursement
Timely expenditure
Qualified use of proceeds
Maintenance and retention of records
Use of excess proceeds
Monitoring Private Business Use
Identification and tracking of bond financed property
Awareness by key personnel of general rules
Review of contracts relating to bond financed property -- leases, sales contracts, management contracts, use agreements, etc.
Remediation
Maintenance and retention of records 59<br>
slide60. Post Issuance Tax Compliance Procedures Responsibility
Training/Awareness
Communication with Bond Counsel
Monitoring of Tax-Exempt Bonds
Review of Procedures and Rules 60<br>
slide61. Tax Agreements and Certificates Review and be familiar with/ask questions of Bond Counsel
Outline general requirements for each bond issue
Arbitrage Rebate
Temporary periods
FMV of investments
Reserve levels
Rebate 61<br>
slide62. Disclosures SPECIAL DISCLAIMER REGARDING THE RESEARCH AND FORECASTS INCLUDED IN THIS PRODUCT
This research and any forecasts are based on current public information as of 04/27/2023 that we consider reliable, but we do not represent it is accurate or complete, and it should not be relied on as such. The information, opinions, estimates and forecasts contained herein are as of the date hereof and are subject to change without prior notification.
ABOUT PFM
PFM is the marketing name for a group of affiliated companies providing a range of services. All services are provided through separate agreements with each company. This material is for general information purposes only and is not intended to provide specific advice or a specific recommendation.
Financial advisory services are provided by PFM Financial Advisors LLC a registered municipal advisor with the Securities and Exchange Commission (SEC) and the Municipal Securities Rulemaking Board (MSRB) under the Dodd-Frank Act of 2010. Additional applicable regulatory information is available upon request.
Consulting services are provided through PFM Group Consulting LLC. Institutional purchasing card services are provided through PFM Financial Services LLC. PFM’s financial modelling platform for strategic forecasting is provided through PFM Solutions LLC.
For more information regarding PFM’s services or entities, please visit www.pfm.com. 64<br>