04
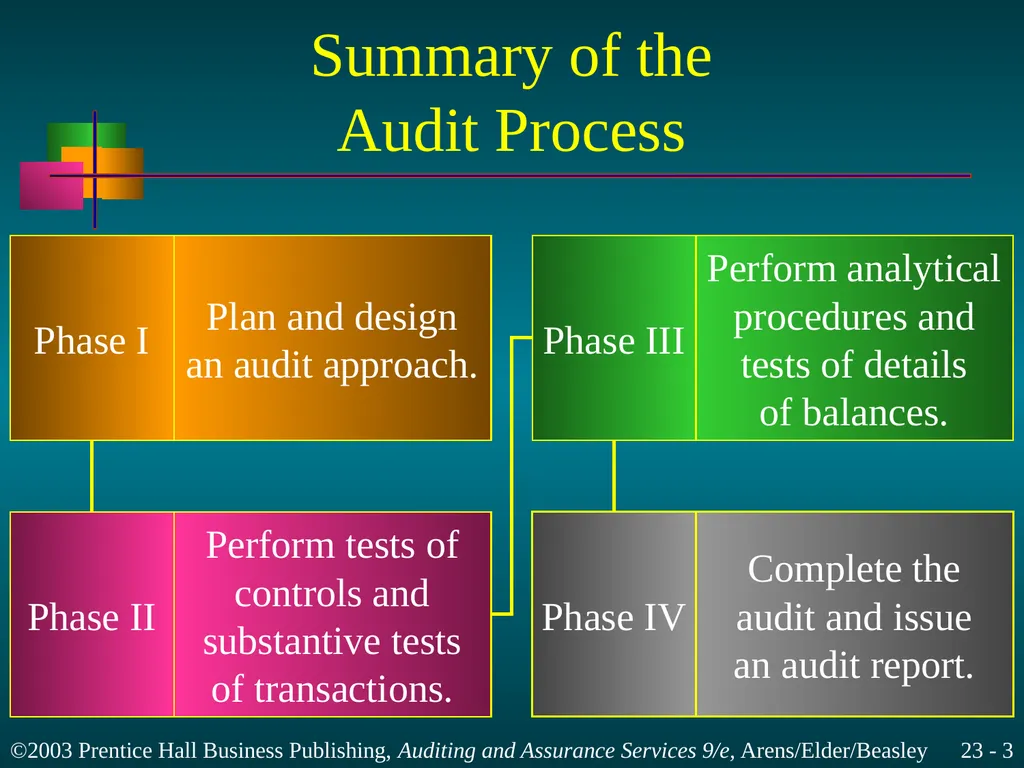
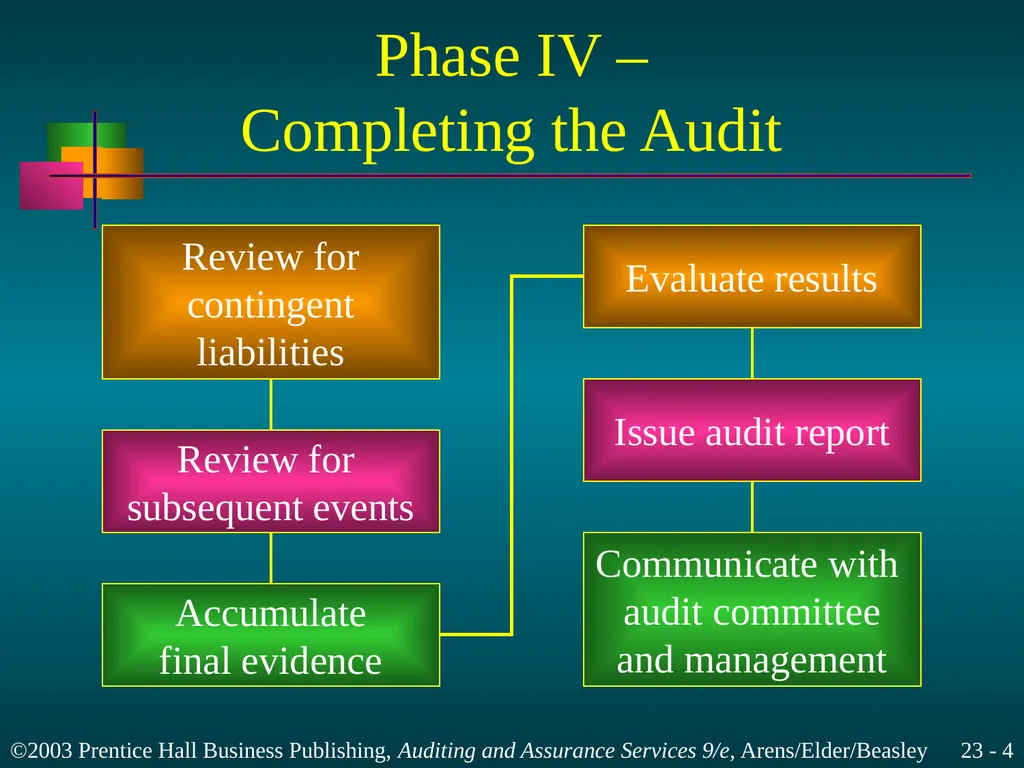
Phase IV –�Completing the Audit Review for
contingent
liabilities Review for
subsequent events Accumulate
final evidence Evaluate results Issue audit report Communicate with
audit committee
and management<br>
05
A contingent liability is potential future
obligation to an outside party for an
unknown amount resulting from
activities that have already taken place. Contingent Liabilities<br>
06
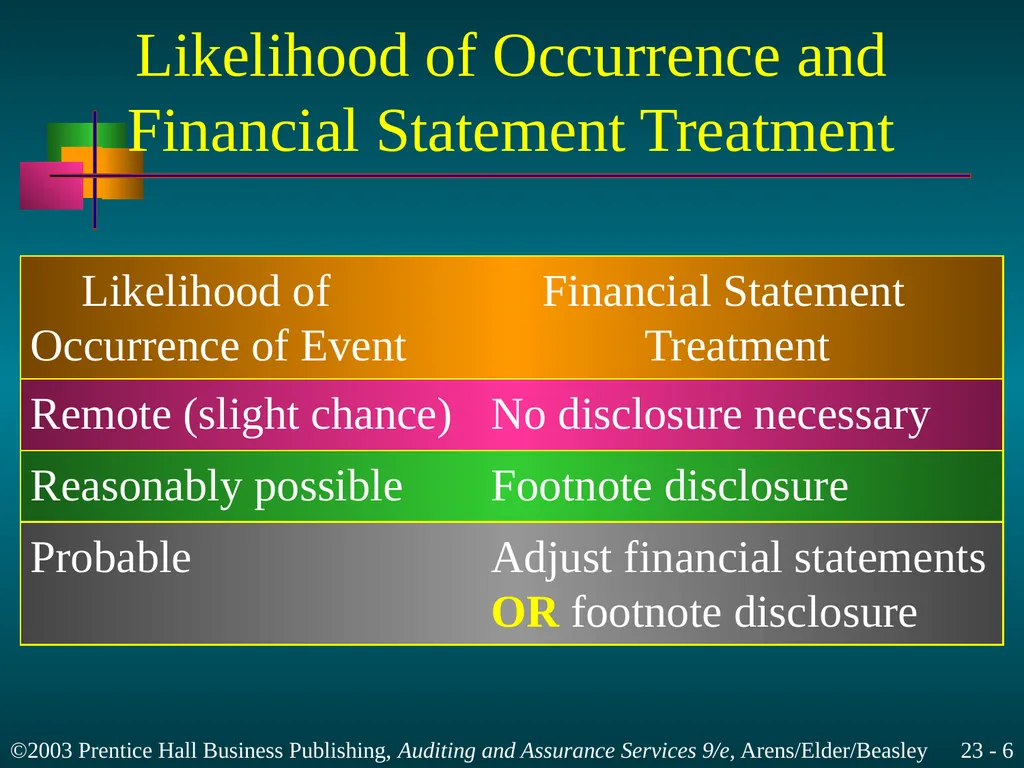
Likelihood of Occurrence and Financial Statement Treatment Likelihood of Financial Statement
Occurrence of Event Treatment Remote (slight chance) No disclosure necessary Reasonably possible Footnote disclosure Probable Adjust financial statements
OR footnote disclosure<br>
07
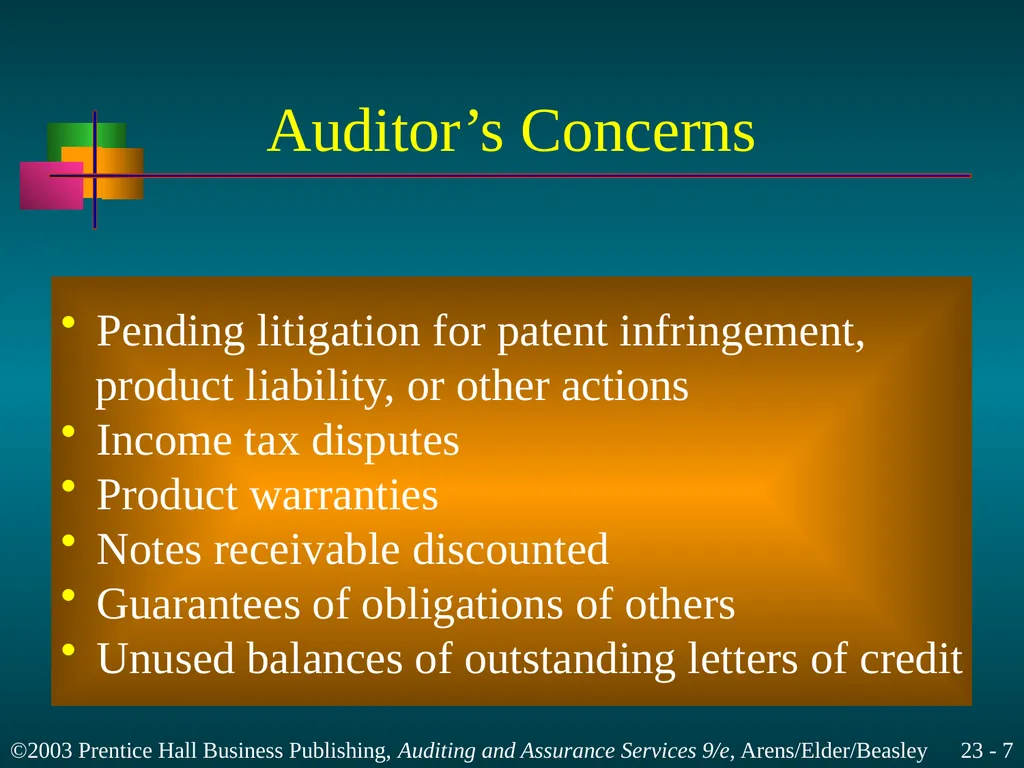
Pending litigation for patent infringement,
product liability, or other actions
Income tax disputes
Product warranties
Notes receivable discounted
Guarantees of obligations of others
Unused balances of outstanding letters of credit Auditor’s Concerns<br>
08
Audit Procedures for�Finding Contingencies Inquire of management (orally and in writing)
about the possibility of unrecorded contingencies. Review current and previous years’ internal
revenue reports for income tax settlements. Review the minutes of directors’ and stockholders’
meetings for indications of lawsuits.<br>
09
Audit Procedures for�Finding Contingencies Analyze legal expenses and review invoices
and statements from legal counsel. Obtain a letter from each major attorney of the
client as to the status of pending litigation. Examine letters of credit in force. Review audit documentation for any information
that may indicate a potential contingency.<br>
10
Learning Objective 2 Obtain and evaluate letters
from the client’s attorneys.<br>
11
A list including (1) pending threatened litigation and
(2) asserted or unasserted claims or assessments
with which the attorney has had involvement. A request that the attorney furnish information or
comment about the progress of each item listed. Inquiry of Client’s Attorneys<br>
12
A request for the identification of any unlisted
pending or threatened legal action or a statement
that the client’s list is complete. A statement informing the attorney of the attorney’s
responsibility to inform management of legal matters
requiring disclosure in the financial statements and
to respond directly to the auditor. Inquiry of Client’s Attorneys<br>
13
Learning Objective 3 Conduct a post-balance-sheet
review for subsequent events.<br>
14
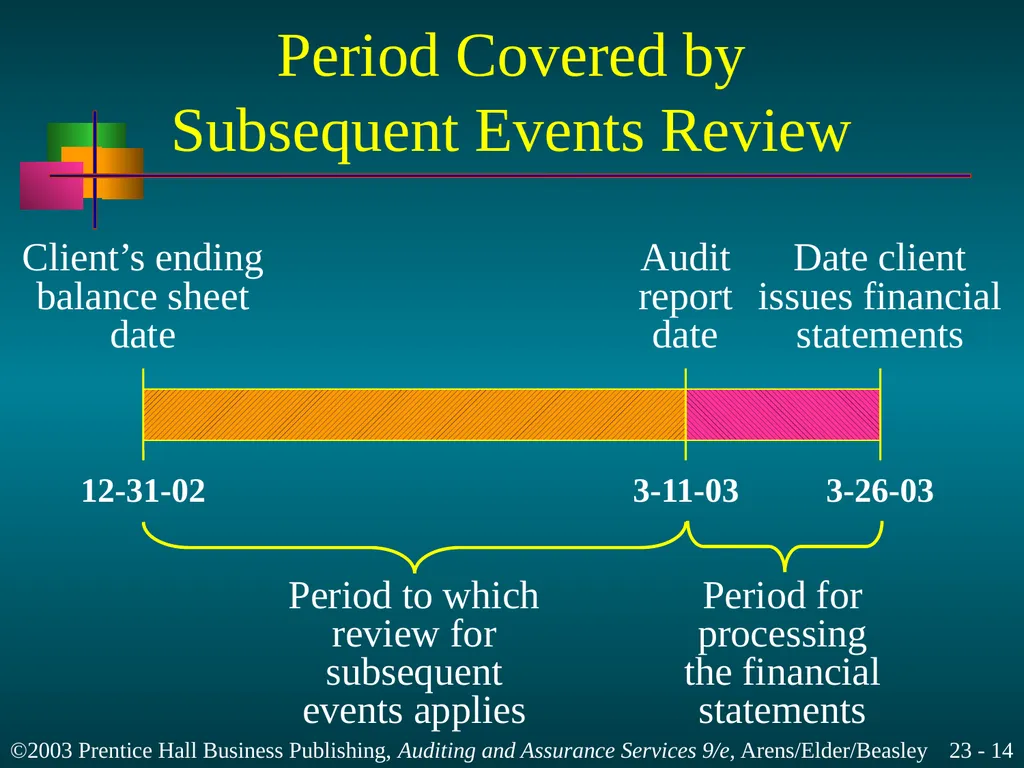
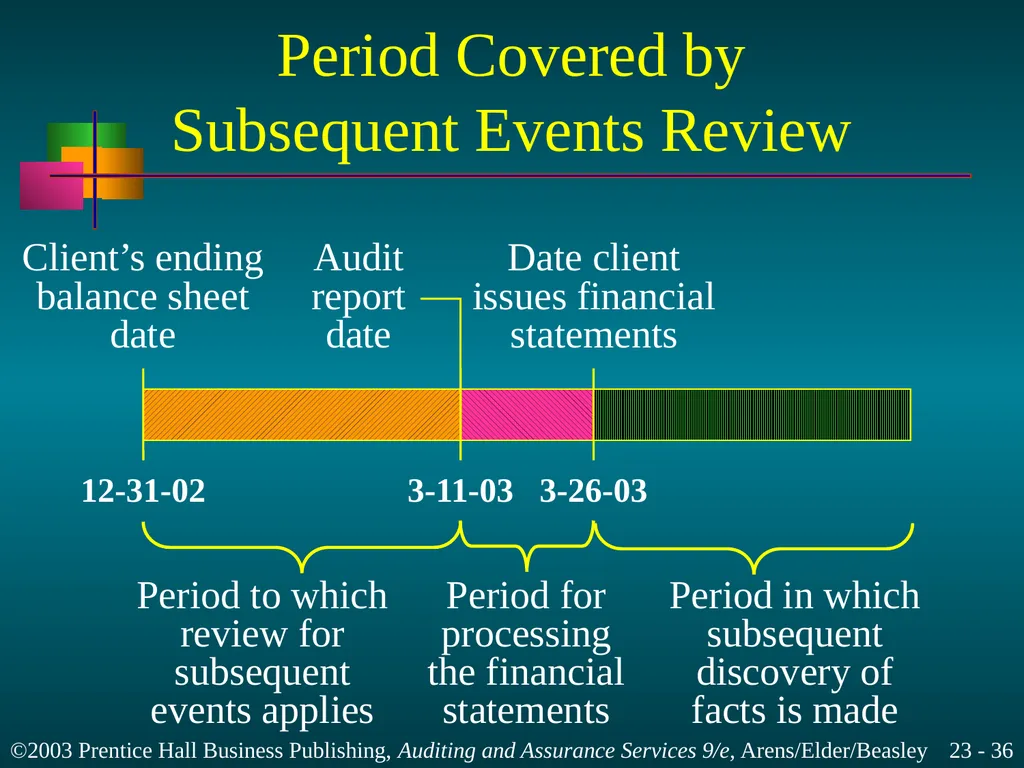
Period Covered by�Subsequent Events Review Client’s ending
balance sheet
date Audit
report
date Date client
issues financial
statements Period to which
review for
subsequent
events applies Period for
processing
the financial
statements 12-31-02 3-11-03 3-26-03<br>
15
Those that have a direct effect on the
financial statements and require adjustment Those that have no direct effect on the
financial statements but for which
disclosure is advisable Types of Subsequent Events<br>
16
Declaration of bankruptcy by a customer
with an accounts receivable balance
Settlement of a litigation at an amount
different from the amount recorded on
the books Requiring Adjustment<br>
17
Disposal of equipment not being used in
operations at a price below the current
book value
Sale of investments at a price below
recorded cost Requiring Adjustment<br>
18
Advisability of Disclosure Decline in the market value of securities
held for temporary investment or resale
Issuance of bonds or equity securities
Decline in the market value of inventory as
consequence of government action barring
further sale of a product
Uninsured loss of inventories as a result of fire
A merger or an acquisition<br>
19
Inquiry of management
Correspond with attorneys
Review internal statements prepared
subsequent to the balance sheet date
Review records prepared subsequent
to the balance sheet date
Examine minutes issued subsequent
to the balance sheet date
Obtain a letter of representation Audit Tests<br>
20
The first date is the date for the completion
of field work except for a specific exception. The second date, which is always later,
deals with the exception. Dual Dating<br>
21
Learning Objective 4 Design and perform the final steps
in the evidence-accumulation
segment of the audit.<br>
22
1. Perform final analytical procedures.
2. Evaluate the going-concern assumption.
3. Obtain a management representation letter.
4. Consider information accompanying the basic financial statements.
5. Read other information in the annual report Final Evidence Accumulation<br>
23
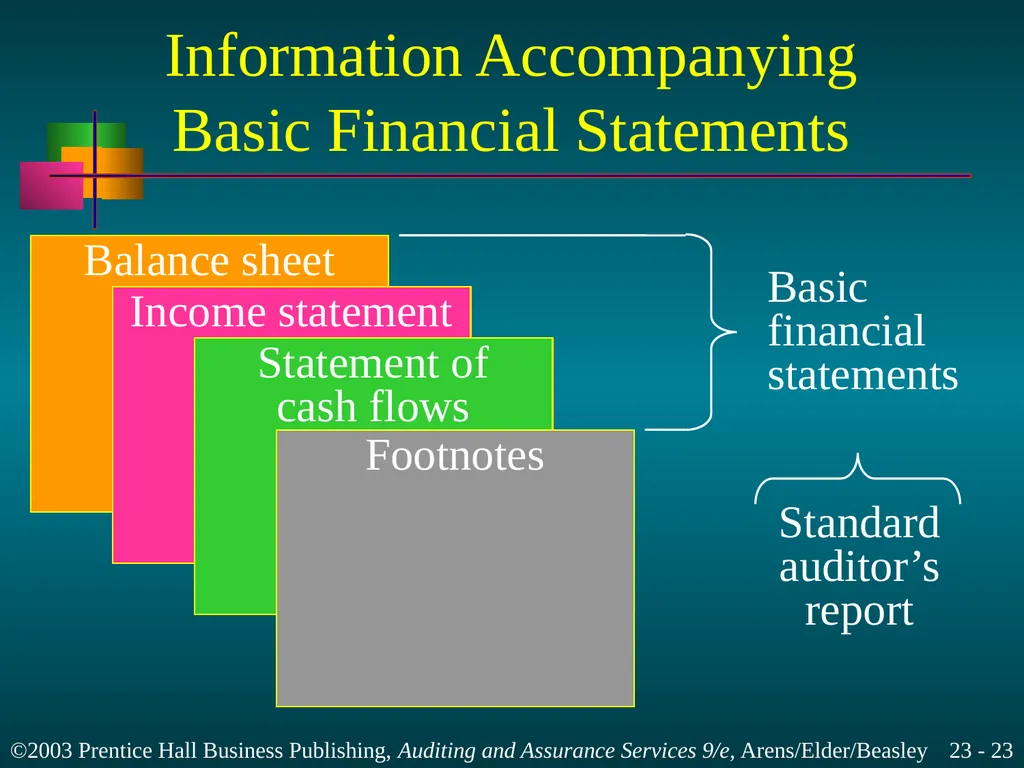
Information Accompanying Basic Financial Statements Balance sheet Income statement Statement of
cash flows Footnotes Basic
financial
statements Standard
auditor’s
report<br>
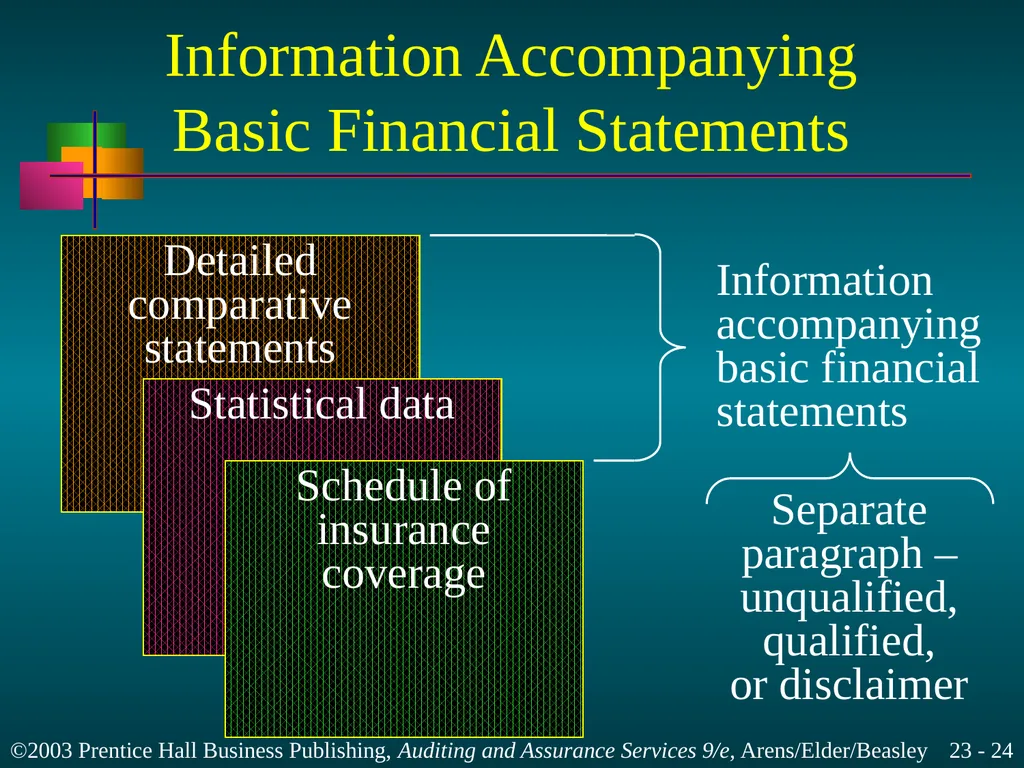
24
Information Accompanying Basic Financial Statements Detailed
comparative
statements Statistical data Schedule of
insurance
coverage Information
accompanying
basic financial
statements Separate
paragraph –
unqualified,
qualified,
or disclaimer<br>
25
Learning Objective 5 Integrate the audit evidence
gathered, and evaluate the
overall audit results.<br>
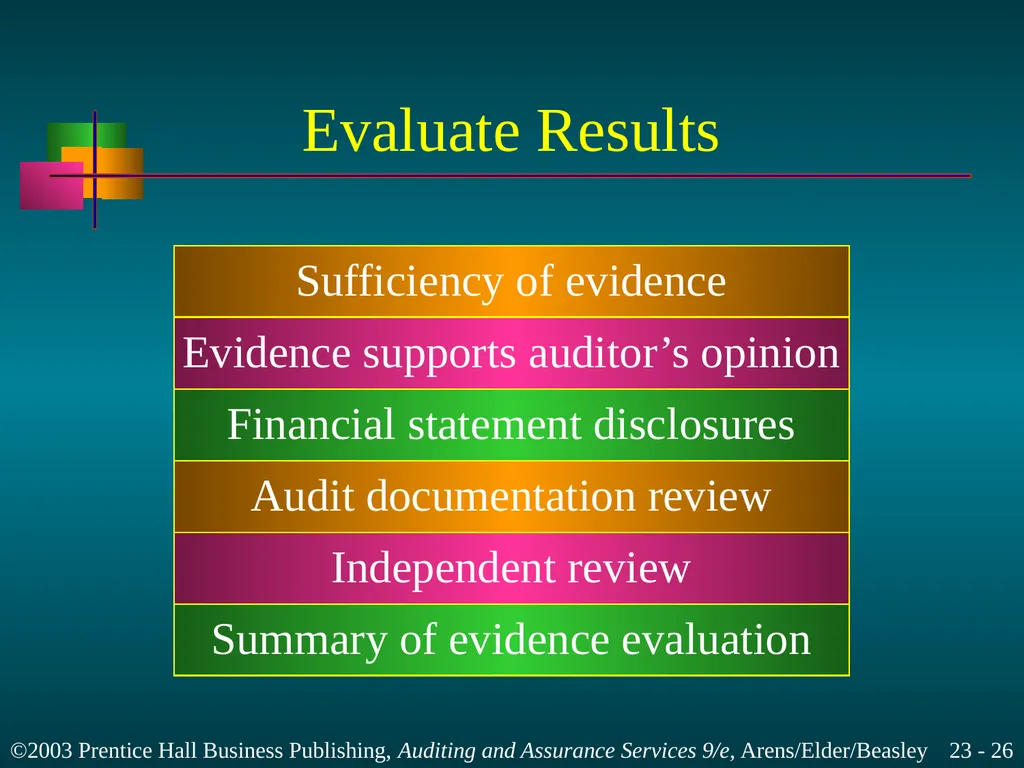
26
Sufficiency of evidence Evidence supports auditor’s opinion Financial statement disclosures Audit documentation review Independent review Evaluate Results Summary of evidence evaluation<br>
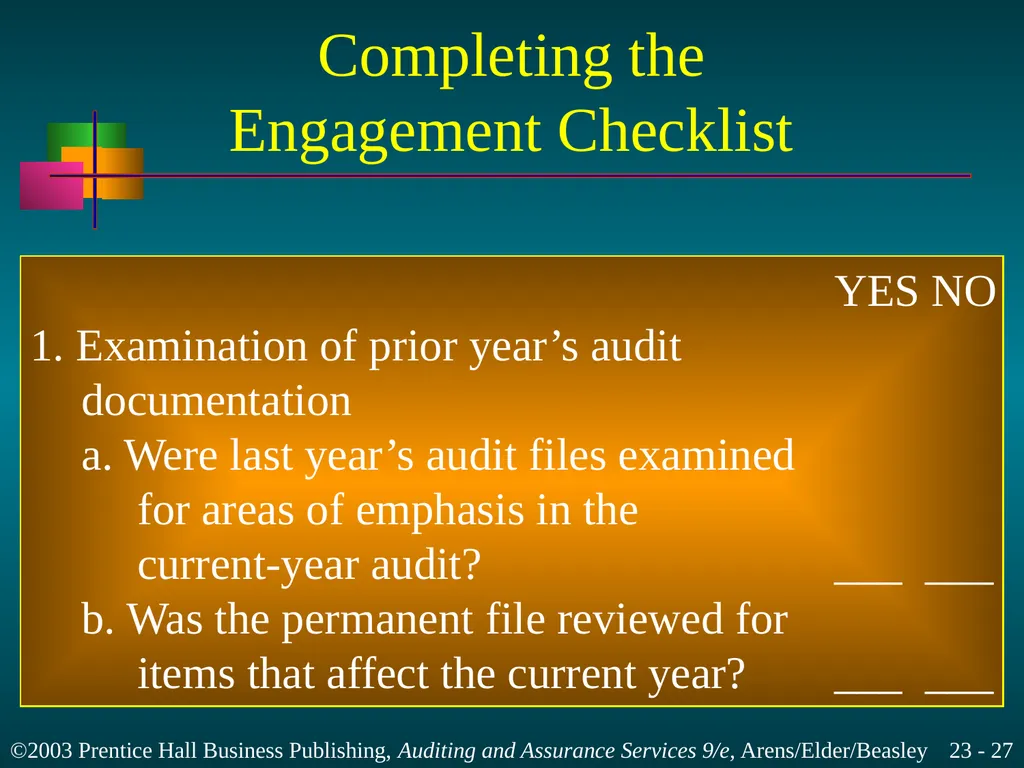
27
YES NO
1. Examination of prior year’s audit
documentation
a. Were last year’s audit files examined
for areas of emphasis in the
current-year audit? ___ ___
b. Was the permanent file reviewed for
items that affect the current year? ___ ___ Completing the�Engagement Checklist<br>
28
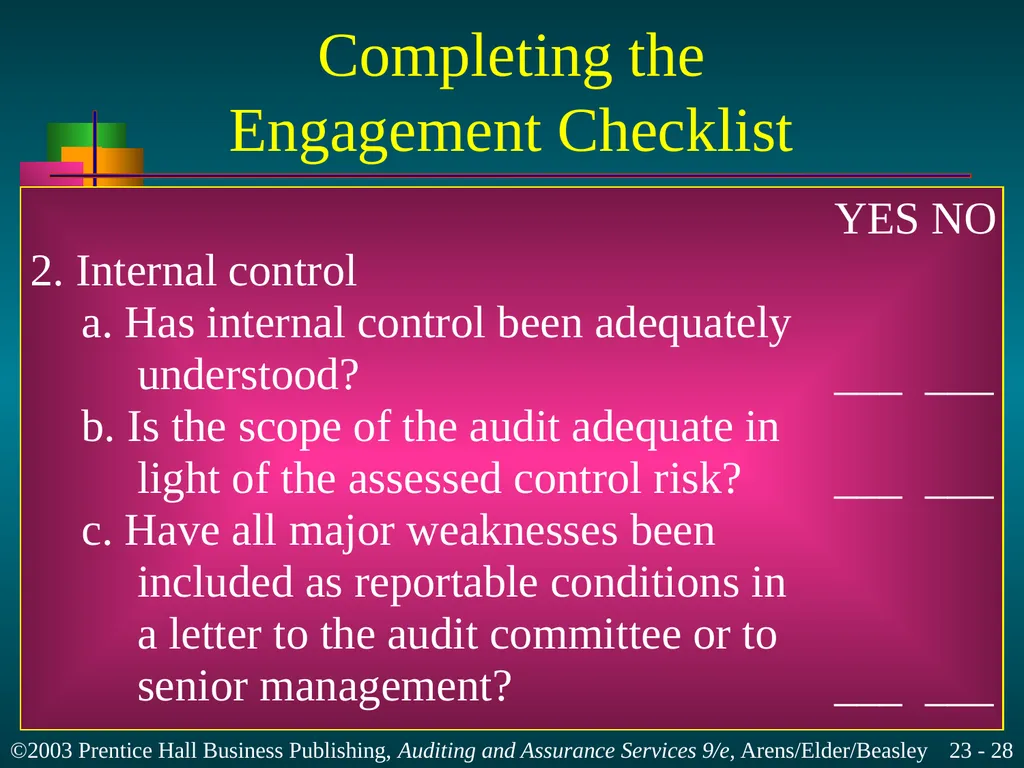
YES NO
2. Internal control
a. Has internal control been adequately
understood? ___ ___
b. Is the scope of the audit adequate in
light of the assessed control risk? ___ ___
c. Have all major weaknesses been
included as reportable conditions in
a letter to the audit committee or to
senior management? ___ ___ Completing the�Engagement Checklist<br>
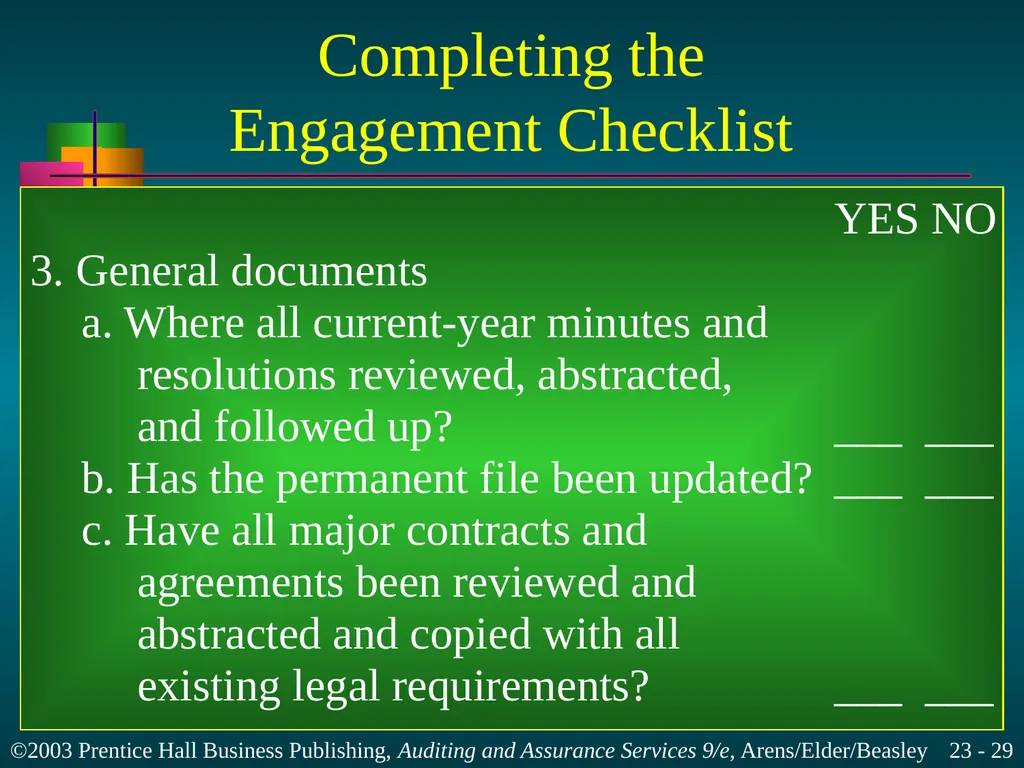
29
YES NO
3. General documents
a. Where all current-year minutes and
resolutions reviewed, abstracted,
and followed up? ___ ___
b. Has the permanent file been updated? ___ ___
c. Have all major contracts and
agreements been reviewed and
abstracted and copied with all
existing legal requirements? ___ ___ Completing the�Engagement Checklist<br>
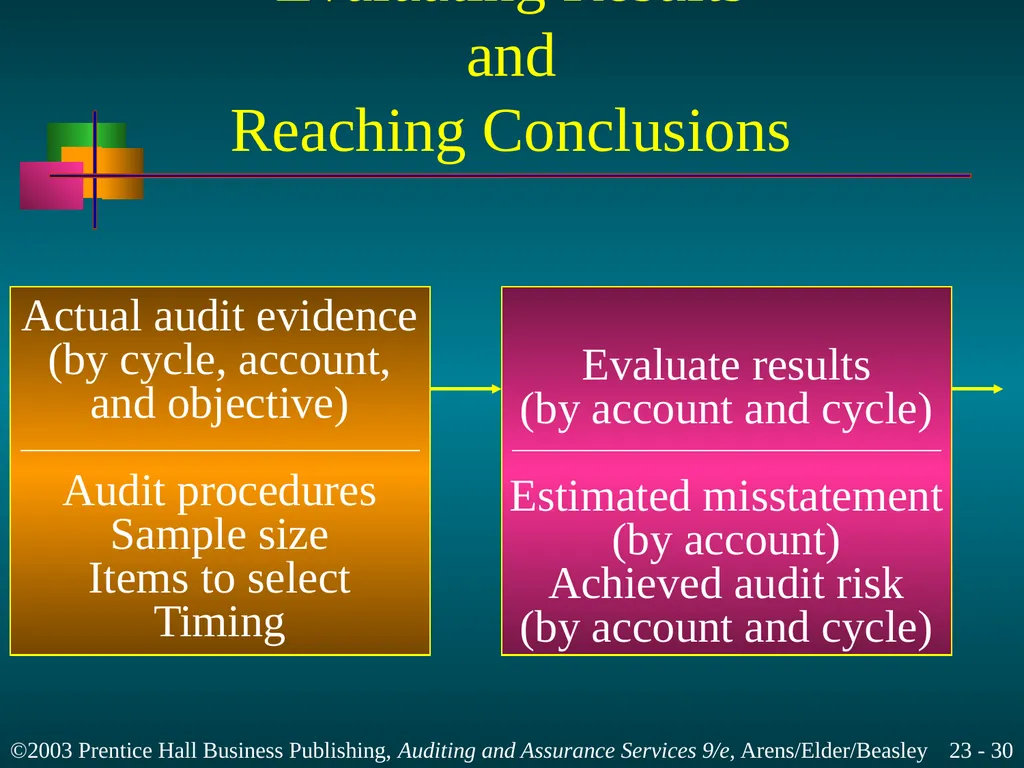
30
Evaluating Results and�Reaching Conclusions Actual audit evidence
(by cycle, account,
and objective)
Audit procedures
Sample size
Items to select
Timing Evaluate results
(by account and cycle)
Estimated misstatement
(by account)
Achieved audit risk
(by account and cycle)<br>
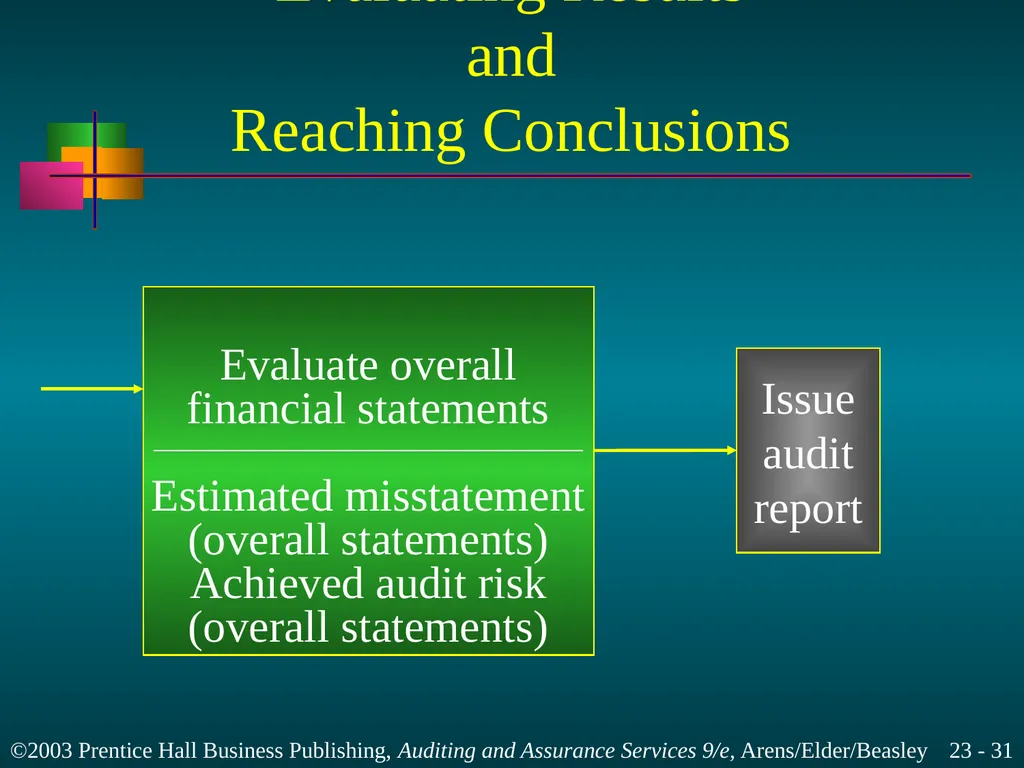
31
Evaluating Results and�Reaching Conclusions Evaluate overall
financial statements
Estimated misstatement
(overall statements)
Achieved audit risk
(overall statements) Issue
audit
report<br>
32
The audit report is the only thing that most users
see in the audit process and the consequences of
issuing an inappropriate report can be severe. Issue the Audit Report<br>
33
Learning Objective 6 Communicate effectively with the
audit committee and management.<br>
34
Communicate fraud and illegal acts
Communicate reportable conditions
Other communication with audit committee
Management letters Communicate with the Audit Committee and Management<br>
35
Learning Objective 7 Identify the auditor’s
responsibilities when
facts affecting the audit
report are discovered
after its issuance.<br>
36
Period Covered by�Subsequent Events Review Client’s ending
balance sheet
date Audit
report
date Date client
issues financial
statements Period to which
review for
subsequent
events applies Period for
processing
the financial
statements 12-31-02 3-11-03 3-26-03 Period in which
subsequent
discovery of
facts is made<br>