
ICMA secondary credit market study: meeting the





Description: ICMA secondary credit market study: meeting the liquidity challenge Amsterdam, November 10th 2015 Andy Hill Corporate bond markets and the real economy Corporate bond markets can be considered an important ingredient in economic growth,
Related Topics
Download Presentation
"ICMA secondary credit market study: meeting the" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. ICMA secondary credit market study:
meeting the liquidity challenge
Amsterdam, November 10th 2015 Andy Hill<br>
slide2. Corporate bond markets and the real economy “Corporate bond markets can be considered an important ingredient in economic growth, financial stability and economic recovery, particularly in the wake of the crisis. They provide a key capital funding flow to firms allowing them to expand, innovate, offer employment, and provide the goods and services societies demand.”
- IOSCO, 2014, ‘Corporate Bond Markets: A Global Perspective ICMA secondary credit market study<br>
slide3. The current state and future evolution of the European investment grade corporate bond secondary market: perspectives from the market ICMA secondary credit market study<br>
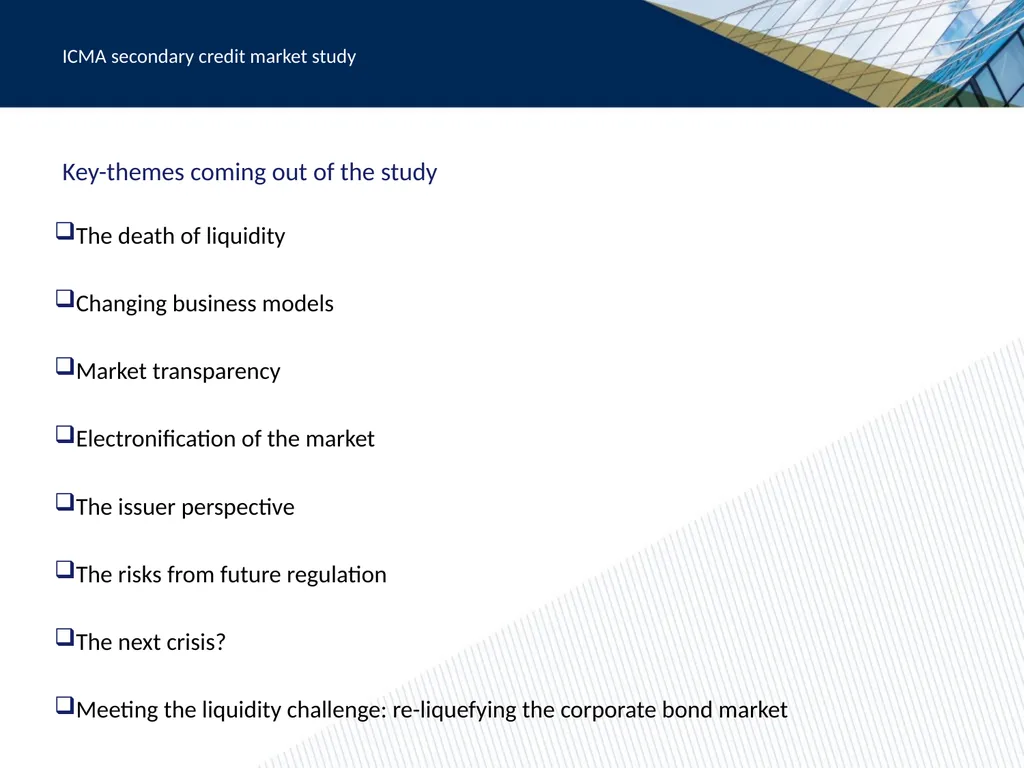
slide4. Key-themes coming out of the study The death of liquidity
Changing business models
Market transparency
Electronification of the market
The issuer perspective
The risks from future regulation
The next crisis?
Meeting the liquidity challenge: re-liquefying the corporate bond market ICMA secondary credit market study<br>
slide5. What do we mean by liquidity “Liquidity is the ability to get a price in any instrument, in any size, at any time.”
- Fund manager
Means different things to different participants
2002-2007 a liquidity bubble? [CDS/structured derivatives]
Dynamic (market cycles and bond life cycles)
Quantifiable? As much a state as a measure
“The golden age of liquidity was a very brief period, and driven by leverage.”
- Credit trader ICMA secondary credit market study<br>
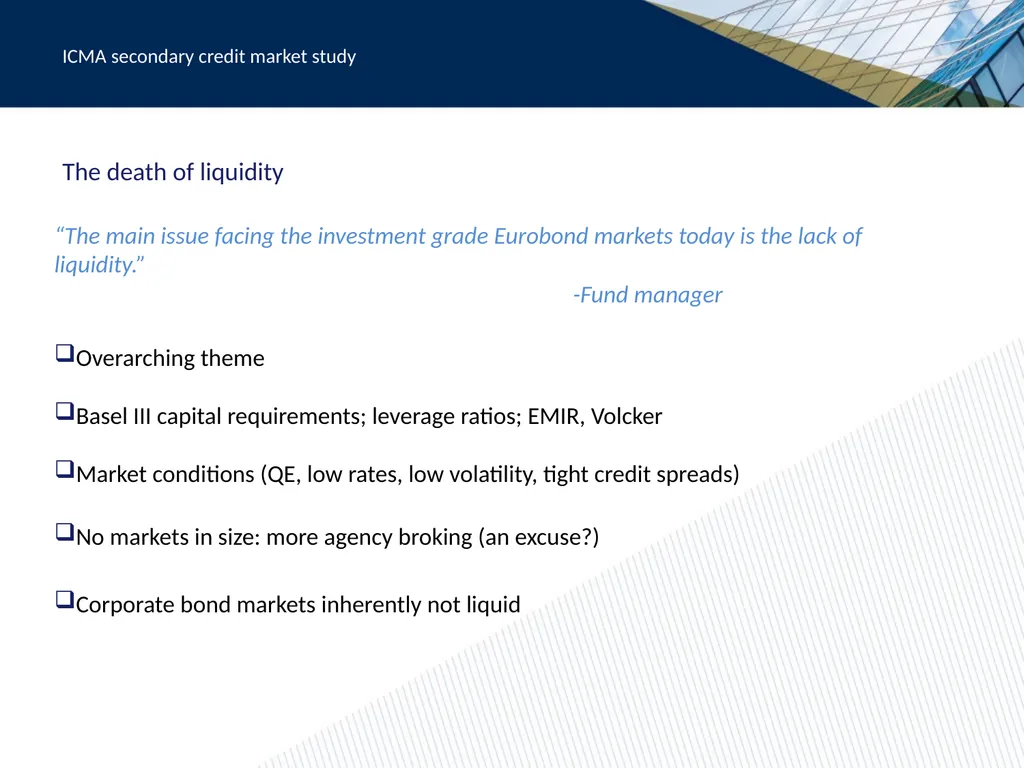
slide6. The death of liquidity “The main issue facing the investment grade Eurobond markets today is the lack of liquidity.”
-Fund manager
Overarching theme
Basel III capital requirements; leverage ratios; EMIR, Volcker
Market conditions (QE, low rates, low volatility, tight credit spreads)
No markets in size: more agency broking (an excuse?)
Corporate bond markets inherently not liquid ICMA secondary credit market study<br>
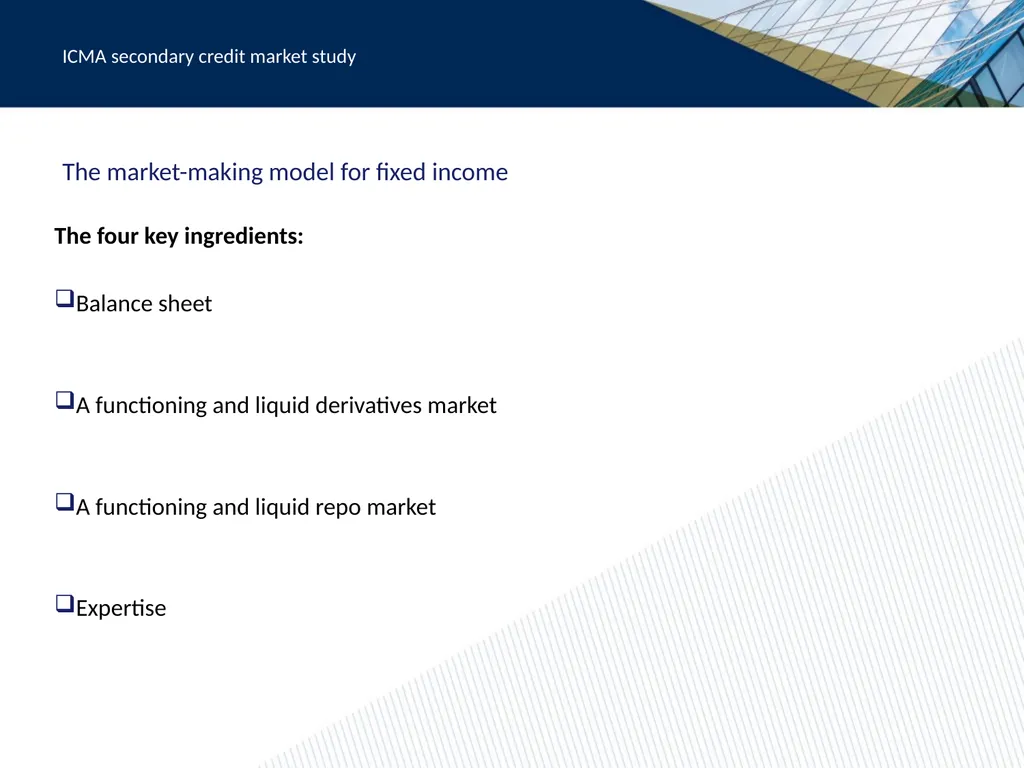
slide7. The market-making model for fixed income The four key ingredients:
Balance sheet
A functioning and liquid derivatives market
A functioning and liquid repo market
Expertise ICMA secondary credit market study<br>
slide8. The market-making model for fixed income Breaking the model:
Balance sheet
Basel III capital ratios
A functioning and liquid derivatives market
EMIR
A functioning and liquid repo market
Basel III leverage ratio
Expertise
Attrition and ‘juniorization’ ICMA secondary credit market study<br>
slide9. Changing business models – broker-dealers “The sell-side used to give liquidity away for free; now, if the buy-side wants it, they should pay for it”
- Credit trader
Better balance sheet allocation and focus on risk-weighted return on capital
Reduced inventories, more client/axe focused (commission based model?)
More niche players / specialization
Down-sizing and down-grading of bank broker-dealers ICMA secondary credit market study<br>
slide10. Changing investor behaviour “Investment managers may become driven more by liquidity considerations, rather than by valuations or investment strategies”
- Fund manager
Splitting orders
Internalized liquidity
Primary markets as source of liquidity
Buy-and-hold (increased due diligence)
Less liquid investments (‘hunt for yield’)
More use of derivatives / ETFs ICMA secondary credit market study<br>
slide11. The issuers perspective “We have enjoyed good market conditions; there is a lot of cash around, it is difficult to be overly concerned”
- Corporate issuer
Market has been good, but issuers becoming increasingly concerned
Secondary markets help price primary issuance
Selection of banks to award lead manager mandates?
Standardized issuance? ICMA secondary credit market study<br>
slide12. The risks from future regulation MiFID II/MiFIR: pre and post trade transparency requirements
The winners curse (the transparency paradox)
Confusion between transparency and liquidity
Draft RTS seem much better than originally feared
“Transparency is fine for retail trades, but it will kill the wholesale market”
- Credit analyst
CSDR: mandatory buy-ins
A solution looking for a problem
The end of short-selling
ICMA CSDR Mandatory Buy-in Impact Study (Feb 2015)
“Mandatory buy-ins will be the final nail in the coffin of market liquidity”
- Credit trader ICMA secondary credit market study<br>
slide13. The next crisis? “This is a classic bull market; valuations have gone out the window”
- E-platform provider
A common thread in the various discussions with all participants is the inevitability of the meltdown in global credit markets.
Regulation has shifted risk from banks to investors.
While market cycles are nothing new, the common concern is that, largely because of regulation, financial markets have never been worse placed to deal with a sharp correction.
A combination of larger bond markets, with fewer, larger investment firms, and a weakened capacity for bank intermediation, all makes for the perfect storm.
While some see the lack of liquidity in the secondary markets as exacerbating any correction, others are more concerned about how a non-functioning secondary market could impede any return to normality. ICMA secondary credit market study – meeting the liquidity challenge<br>
slide14. Re-liquefying the corporate bond market Electronification of the market
Buy-side initiatives
Issuer initiatives
Better regulation ICMA secondary credit market study – meeting the liquidity challenge<br>
slide15. Electronification of the market “When liquidity does come back, there will be fewer people and more technology”
- E-platform founder
Increase in use, and expected to grow with more entrants
Improved scope for connectivity and new protocols (‘all-to-all’ /‘buy-side-to-buy-side’)
Big data to support more ‘intelligent’ broking models
Virtual liquidity (or ‘liquidity sourcing’)
A replacement for market-making? ICMA secondary credit market study – meeting the liquidity challenge<br>
slide16. Re-liquefying the corporate bond market Buy-side initiatives
Internalized liquidity
Price-makers
Redemption gates
ETFs and derivatives
But: is it the responsibility of the buy-side?
Issuer initiatives
More selective awarding of mandates
Standardized issuance (‘benchmarking’)
But: is it the responsibility of issuers?
Better regulation
Winners and losers?
Functioning and efficient markets a social good
Connection between market regulation and real economy ICMA secondary credit market study – meeting the liquidity challenge<br>
slide17. Conclusion The interviews for this study suggest that the European investment grade credit market is a dramatically changing landscape.
Liquidity, by most definitions, is rapidly evaporating, primarily as a result of financial regulation and extraordinary monetary stimulus.
Banks and investors are adapting to the new environment, as are electronic intermediaries who are looking to provide possible solutions. Issuers, as yet, are relatively unaffected, but are becoming increasingly concerned.
While a number of market led solutions are being discussed, at some stage the impact of regulation on market liquidity and efficiency will need to be considered, not least as the role of capital markets in supporting economic growth comes ever more into focus. ICMA secondary credit market study – meeting the liquidity challenge<br>
slide18. Conclusion Ultimately, if the challenges facing the corporate bond secondary markets are to be addressed and solutions found this will require the constructive and coordinated effort of all stakeholders: market-makers, investment managers, trading platforms and intermediaries, the issuers, and the various regulatory bodies and authorities.
Functioning and efficient capital markets are a social good that support economic activity and growth. For those who provide, use, and oversee capital markets, this should be a collective responsibility. ICMA secondary credit market study – meeting the liquidity challenge<br>
slide19. ICMA Secondary Market Practices Committee (SMPC) Open forum for sell-side and buys-side members active in the European high grade corporate bond market.
Key functions:
Agreeing best practice for the corporate bond secondary market.
Maintaining and developing the ICMA Rules and Recommendations for the secondary market (‘The ICMA Rule Book’) to ensure that they remain relevant and consistent with regulatory requirements.
Leading initiatives to improve corporate bond secondary market liquidity and efficiency.
Providing a forum for discussing the likely impact of relevant regulation on secondary market practices, and for consolidating input and feedback in the regulatory consultation process.
Three sub-committee working groups: (i) MiFID II/R WG; (ii) CSDR/Buy-ins WG; (iii) Electronic Trading WG ICMA secondary credit market study – Annexes<br>
slide20. About the author/presenter Andy Hill is a Director in ICMA’s Market Practice and Regulatory Policy group. For seventeen years he has been a repo and money-market trader, and for ten years he was an Executive Director at Goldman Sachs. He has also worked as a consultant in the Aid and Development sector, primarily based in Cambodia, and previously served on the Board of the Cambodian NGO Education Partnership in Phnom Penh while under a Goldman Sachs Public Service Fellowship. He holds a BSc (Hons) in Business Studies from Cass Business School and an MSc in Poverty Reduction and Development Management from the University of Birmingham.
Email: andy.hill@icmagroup.org ICMA secondary credit market study - Annexes<br>
slide2. Corporate bond markets and the real economy “Corporate bond markets can be considered an important ingredient in economic growth, financial stability and economic recovery, particularly in the wake of the crisis. They provide a key capital funding flow to firms allowing them to expand, innovate, offer employment, and provide the goods and services societies demand.”
- IOSCO, 2014, ‘Corporate Bond Markets: A Global Perspective ICMA secondary credit market study<br>
slide3. The current state and future evolution of the European investment grade corporate bond secondary market: perspectives from the market ICMA secondary credit market study<br>
slide4. Key-themes coming out of the study The death of liquidity
Changing business models
Market transparency
Electronification of the market
The issuer perspective
The risks from future regulation
The next crisis?
Meeting the liquidity challenge: re-liquefying the corporate bond market ICMA secondary credit market study<br>
slide5. What do we mean by liquidity “Liquidity is the ability to get a price in any instrument, in any size, at any time.”
- Fund manager
Means different things to different participants
2002-2007 a liquidity bubble? [CDS/structured derivatives]
Dynamic (market cycles and bond life cycles)
Quantifiable? As much a state as a measure
“The golden age of liquidity was a very brief period, and driven by leverage.”
- Credit trader ICMA secondary credit market study<br>
slide6. The death of liquidity “The main issue facing the investment grade Eurobond markets today is the lack of liquidity.”
-Fund manager
Overarching theme
Basel III capital requirements; leverage ratios; EMIR, Volcker
Market conditions (QE, low rates, low volatility, tight credit spreads)
No markets in size: more agency broking (an excuse?)
Corporate bond markets inherently not liquid ICMA secondary credit market study<br>
slide7. The market-making model for fixed income The four key ingredients:
Balance sheet
A functioning and liquid derivatives market
A functioning and liquid repo market
Expertise ICMA secondary credit market study<br>
slide8. The market-making model for fixed income Breaking the model:
Balance sheet
Basel III capital ratios
A functioning and liquid derivatives market
EMIR
A functioning and liquid repo market
Basel III leverage ratio
Expertise
Attrition and ‘juniorization’ ICMA secondary credit market study<br>
slide9. Changing business models – broker-dealers “The sell-side used to give liquidity away for free; now, if the buy-side wants it, they should pay for it”
- Credit trader
Better balance sheet allocation and focus on risk-weighted return on capital
Reduced inventories, more client/axe focused (commission based model?)
More niche players / specialization
Down-sizing and down-grading of bank broker-dealers ICMA secondary credit market study<br>
slide10. Changing investor behaviour “Investment managers may become driven more by liquidity considerations, rather than by valuations or investment strategies”
- Fund manager
Splitting orders
Internalized liquidity
Primary markets as source of liquidity
Buy-and-hold (increased due diligence)
Less liquid investments (‘hunt for yield’)
More use of derivatives / ETFs ICMA secondary credit market study<br>
slide11. The issuers perspective “We have enjoyed good market conditions; there is a lot of cash around, it is difficult to be overly concerned”
- Corporate issuer
Market has been good, but issuers becoming increasingly concerned
Secondary markets help price primary issuance
Selection of banks to award lead manager mandates?
Standardized issuance? ICMA secondary credit market study<br>
slide12. The risks from future regulation MiFID II/MiFIR: pre and post trade transparency requirements
The winners curse (the transparency paradox)
Confusion between transparency and liquidity
Draft RTS seem much better than originally feared
“Transparency is fine for retail trades, but it will kill the wholesale market”
- Credit analyst
CSDR: mandatory buy-ins
A solution looking for a problem
The end of short-selling
ICMA CSDR Mandatory Buy-in Impact Study (Feb 2015)
“Mandatory buy-ins will be the final nail in the coffin of market liquidity”
- Credit trader ICMA secondary credit market study<br>
slide13. The next crisis? “This is a classic bull market; valuations have gone out the window”
- E-platform provider
A common thread in the various discussions with all participants is the inevitability of the meltdown in global credit markets.
Regulation has shifted risk from banks to investors.
While market cycles are nothing new, the common concern is that, largely because of regulation, financial markets have never been worse placed to deal with a sharp correction.
A combination of larger bond markets, with fewer, larger investment firms, and a weakened capacity for bank intermediation, all makes for the perfect storm.
While some see the lack of liquidity in the secondary markets as exacerbating any correction, others are more concerned about how a non-functioning secondary market could impede any return to normality. ICMA secondary credit market study – meeting the liquidity challenge<br>
slide14. Re-liquefying the corporate bond market Electronification of the market
Buy-side initiatives
Issuer initiatives
Better regulation ICMA secondary credit market study – meeting the liquidity challenge<br>
slide15. Electronification of the market “When liquidity does come back, there will be fewer people and more technology”
- E-platform founder
Increase in use, and expected to grow with more entrants
Improved scope for connectivity and new protocols (‘all-to-all’ /‘buy-side-to-buy-side’)
Big data to support more ‘intelligent’ broking models
Virtual liquidity (or ‘liquidity sourcing’)
A replacement for market-making? ICMA secondary credit market study – meeting the liquidity challenge<br>
slide16. Re-liquefying the corporate bond market Buy-side initiatives
Internalized liquidity
Price-makers
Redemption gates
ETFs and derivatives
But: is it the responsibility of the buy-side?
Issuer initiatives
More selective awarding of mandates
Standardized issuance (‘benchmarking’)
But: is it the responsibility of issuers?
Better regulation
Winners and losers?
Functioning and efficient markets a social good
Connection between market regulation and real economy ICMA secondary credit market study – meeting the liquidity challenge<br>
slide17. Conclusion The interviews for this study suggest that the European investment grade credit market is a dramatically changing landscape.
Liquidity, by most definitions, is rapidly evaporating, primarily as a result of financial regulation and extraordinary monetary stimulus.
Banks and investors are adapting to the new environment, as are electronic intermediaries who are looking to provide possible solutions. Issuers, as yet, are relatively unaffected, but are becoming increasingly concerned.
While a number of market led solutions are being discussed, at some stage the impact of regulation on market liquidity and efficiency will need to be considered, not least as the role of capital markets in supporting economic growth comes ever more into focus. ICMA secondary credit market study – meeting the liquidity challenge<br>
slide18. Conclusion Ultimately, if the challenges facing the corporate bond secondary markets are to be addressed and solutions found this will require the constructive and coordinated effort of all stakeholders: market-makers, investment managers, trading platforms and intermediaries, the issuers, and the various regulatory bodies and authorities.
Functioning and efficient capital markets are a social good that support economic activity and growth. For those who provide, use, and oversee capital markets, this should be a collective responsibility. ICMA secondary credit market study – meeting the liquidity challenge<br>
slide19. ICMA Secondary Market Practices Committee (SMPC) Open forum for sell-side and buys-side members active in the European high grade corporate bond market.
Key functions:
Agreeing best practice for the corporate bond secondary market.
Maintaining and developing the ICMA Rules and Recommendations for the secondary market (‘The ICMA Rule Book’) to ensure that they remain relevant and consistent with regulatory requirements.
Leading initiatives to improve corporate bond secondary market liquidity and efficiency.
Providing a forum for discussing the likely impact of relevant regulation on secondary market practices, and for consolidating input and feedback in the regulatory consultation process.
Three sub-committee working groups: (i) MiFID II/R WG; (ii) CSDR/Buy-ins WG; (iii) Electronic Trading WG ICMA secondary credit market study – Annexes<br>
slide20. About the author/presenter Andy Hill is a Director in ICMA’s Market Practice and Regulatory Policy group. For seventeen years he has been a repo and money-market trader, and for ten years he was an Executive Director at Goldman Sachs. He has also worked as a consultant in the Aid and Development sector, primarily based in Cambodia, and previously served on the Board of the Cambodian NGO Education Partnership in Phnom Penh while under a Goldman Sachs Public Service Fellowship. He holds a BSc (Hons) in Business Studies from Cass Business School and an MSc in Poverty Reduction and Development Management from the University of Birmingham.
Email: andy.hill@icmagroup.org ICMA secondary credit market study - Annexes<br>