
Internal Audit in Pharma Industry BY AVNS
Description: Internal Audit in Pharma Industry BY AVNS NAGESWARA RAO M.COM L.LB ACS FCMA PRACTICING COST ACCOUNTANT CHAIRMAN-SIRC OF ICAI 2009-10 Internal Audit definition Chartered Institute of Management Accountants, UK (CIMA): An independent
Related Topics
Download Presentation
"Internal Audit in Pharma Industry BY AVNS" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Internal Audit in
Pharma Industry BY
AVNS NAGESWARA RAO
M.COM L.LB ACS FCMA
PRACTICING COST ACCOUNTANT
CHAIRMAN-SIRC OF ICAI [2009-10]<br>
slide2. Internal Audit definition
Chartered Institute of Management Accountants, UK (CIMA):
‘An independent appraisal activity established within an organization as a service to it. It is a control which functions by examining and evaluating the adequacy and effectiveness of other controls; a management tool which analyses the effectiveness of all parts of an organization’s operations and management.’
Institute of Internal Auditors (IIA):
‘Internal auditing is an independent, objective assurance and consulting activity designed to add value and improve an organization’s operations. It helps an organization accomplish its objectives by bringing a systematic, disciplined approach to evaluate and improve the effectiveness of risk management, control, and governance processes.’<br>
slide3. Need for Internal Audit
The Internal Audit will primarily concentrate on flow of data and justification of basis instead of vouching.
The materiality of cost and product under consideration would always be borne in mind during Internal Audit process.
Objectivity in approach would be a consistent feature in Internal Audit.
Main thrust would always be on deviations and significance of deviations with impact of the same on the performance of the organization.<br>
slide4. Objectives of Internal Audit
Develop and monitor control frameworks
Establish reporting structures and formalize communication processes
Aid the cost reduction and operational performance appraisals
Develop and continuously monitor risk assessment and management
Undertake workshops for training and awareness
Assure compliance with all relevant rules and regulations
Supporting corporate governance and developing resources for management information<br>
slide5. Functions of the Internal Audit
As per the above definitions functions of the Internal Audit activity are:
Internal Control: Internal controls direct, monitor, and measures the company's resources and help to detect and prevent fraud from occurring within an organization.
It can be defined as a process which is performed by the employees of the company as well as the information technology systems that are used to assist the company in achieving its objectives.
The management of a company is responsible for establishing the system of internal controls within the organization, but internal auditors test the controls to make sure they are working effectively.
Management Tool:
Internal Audit has been used as a management tool which monitors and evaluates the effectiveness of operational processes and risk management of a company.
How an organization sets their objectives and responds to the risks associated with their objective is part of the risk management process.
Risk management is a way for companies to manage uncertainty through risk assessment, to develop strategies to manage risk and to mitigate risk by using managerial resources.<br>
slide6. Management Reporting & Internal Control Systems
Management reporting and internal control systems in place will enable the management to monitor performance, strategy, operations, business environment, organization, procedures, funding, risk and internal control that ensures effective financial reporting procedures.
The management reporting and internal control systems include
Plans
A business plan including strategic planning and corporate objectives for the upcoming three years;
An annual budget
Monthly reports
Quarterly reports including updates of annual estimates, if any<br>
slide7. B. Reporting
Financial performance and financial position;
Comparison of budgeted and actual performance;
Analysis of cash flows;
Production / Project management and cost control; identification of responsible project managers and regular reporting and follow-up;
Summaries of management key performance indicators;
Controls over purchasing and maintenance of assets;
Review of potential claims and litigation;
Review to ensure that all commitments and liabilities are recognized as well as all incomes to which Company is entitled
C. Policies and procedures
Financial Policy guiding the investments of liquid assets
Authorization manual guiding the incurrence of expenses and investments
The Employee manual guiding on policies, rules and procedures associated with the Employment of people at various levels in the Company
Detailed controls to ensure the completeness and accuracy of accounting records.<br>
slide8. Control and Risk Assessment
Risk management is the management function used for developing, maintaining and implementing the Risk Management Framework, strategy and policy. Pointers to the need for a change in behavior and mindset in relation to risk management are:
Well defined risk factors that act as indicators to risk assessments does not exist
Risk awareness among staff and management is low
The organization begins to focus on financial control of expenses rather than a broad level internal control through guidelines
The top level management start believing that risk management is not their concern and agenda in meetings
Internal control system review is viewed as a compliance report rather than a daily activity
There is a lack of clearly defined business objectives in the short term<br>
slide9. Risk management process embraces
A clear understanding of the organization’s long and short term objectives
Identification of the risks associated with non-performance or deviation from set objectives
Assessment of the probability and potential impact of particular risks factors that are crucial to achieving operational performance
Development of action plans and delivery programs to address the identified risks
Monitoring and evaluating the risks on a continuous basis<br>
slide10. Internal Audit Strategy
Internal Audit strategy acts as a link between the internal audit charter and the work plan.
Purpose of Internal Audit Strategy
A bird’s eye view of the overall governance, risk management and control system of the organization,
Focusing the internal audit effort where it is most useful and effective, keeping track of the budgeted time and cost,
Minimizing repetition and eliminating duplication of assurance effort,
Ensuring that there are no gaps in the internal audit function and the entire spectrum of control system is analyzed,
Identifying the requisite skills, resources and specializations to deliver an efficient internal audit function,
Providing a reference point and setting up the basic framework for performance appraisal of all functions.
Assessing risk and identifying steps and procedures to mitigate risk.
Introducing a culture of continuous improvement and enhancing feedback by formalizing the communication channel.<br>
slide11. A good of Internal Audit Strategy assimilates
A brief description of the approach of internal audit selected in developing the strategy and a list of key managers who approved the strategy;
A summary of the organization’s short, medium and long term strategic mission and objectives or KPIs (Key Performance Indicators) to be targeted;
A short summary on the organization’s prima facie risks (both external and internal);
A description of the industry that the organization operates in and positioning of the organization in comparison to the industry standards;
A general SWOT analysis of the organization banks on to deliver commitments and sustain growth;
An estimate of the financial, operational, sales, and human resources budgets and targets over the period of the strategy;
The parameters of time, effort and costs considered to formulate the internal audit work plan;
The allocation of resources to the Internal Audit function along with the time lines for delivery;
The balance of various types of internal audits to be undertaken along with the approved audit scope;
The frequency, distribution and level of detail in the internal audit report;
The details of function-wise and SBU-wise KPI and KRA (Key result areas);
The formal procedure for review and update of internal audit strategy;<br>
slide12. Business Models of Pharma Industry
Company manufacturing its own bulk drugs and formulations
Company manufacturing its own bulk drugs and formulations but part of the process and / or recovery of chemicals is outsourced.
Company purchasing input from a related party or selling it to related party.
Company manufacturing at site of support manufacturer but, the clearance and payment of excise duty is undertaken in name of principal company
Manufacturing of life saving drugs exempted from excise.
The product is subject to state excise duty and not central excise duty.
Drug Discovery and Development Solutions (DDDS)
Clinical Research Services
Contract Research and manufacturing Services (CRAMS)
Principal to principal (p2p)
Loan Licensing
Manufacturing of Bulk Drug / API and / or Formulations in 100% Export Oriented Unit (100% EOU) or in Special Economic Zone (SEZ) with an intent to export<br>
slide14. Key Functional areas for Internal audit in Pharma Industry
Statutory compliance
Quality Management with reference to the quality cost
Human Resources utilization and costs
Buildings and Facilities utilization
Process Equipment utilization
Documentation and Records
Materials Management and controls
Production and In Process Controls
Packaging and Identification Labeling of APIs and IM
Storage and Distribution cost and control
Inventory control
Inventory valuation
Rejection and Re-Use of Materials
Complaints and Recalls
Contract Manufacturers (including Laboratories)
Transactions with Agents, Brokers, Traders, Distributors, Re-packers, and Re-labelers
APIs for Use in Clinical Trials
Pollution control facilities utilization and costs<br>
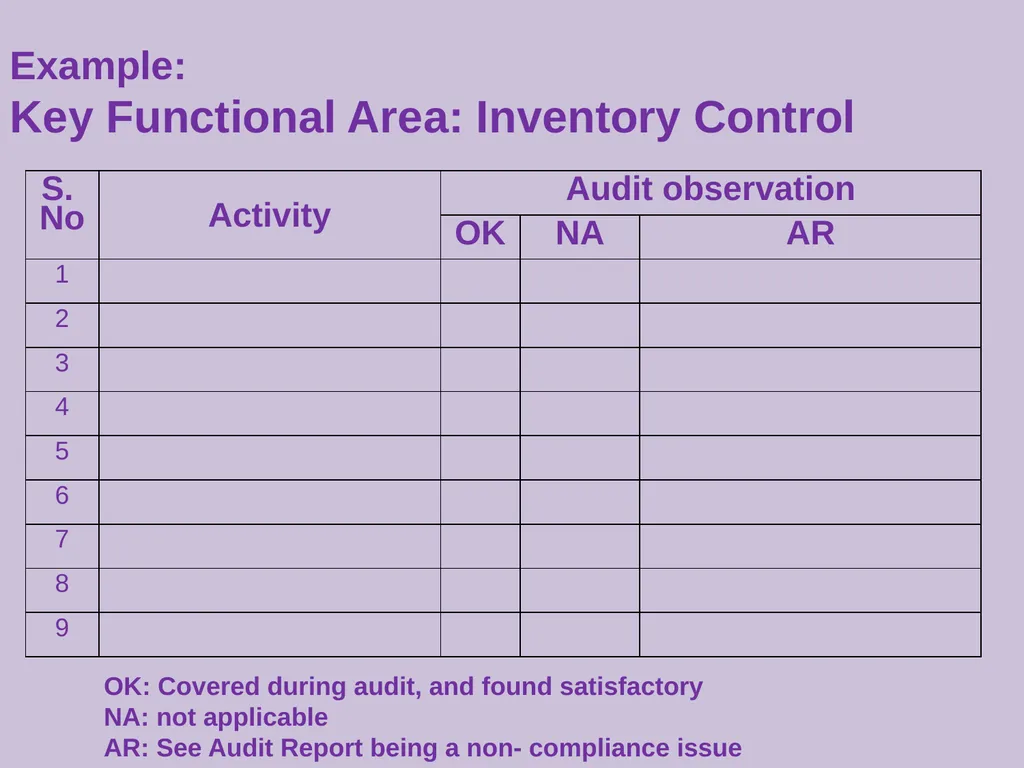
slide15. Example:
Key Functional Area: Inventory Control OK: Covered during audit, and found satisfactory
NA: not applicable
AR: See Audit Report being a non- compliance issue<br>
slide16. Audit observations & Qualifications
Critical deficiency is one which:
Has produced, or leads to a significant risk of producing an Active Pharmaceutical Ingredient that could be harmful to the human or veterinary patient.
Major deficiency is a non-critical deficiency which:
Has produced or may produce a product, which does not comply with its Specification; or
Indicates a major deviation from Good Manufacturing Practice; or
Indicates a failure to carry out satisfactory procedures for release of batches<br>
slide17. Minor deficiency is other deficiency which:
Cannot be classified as either critical or major, but which indicates a departure from good practice. (A deficiency may be “other” either because it is judged as minor or because there is insufficient information to classify it as a major or critical deficiency).
A combination of several “other” deficiencies, none of which on their own may be major, but which may together represent a major deficiency and should be explained and reported as such;<br>
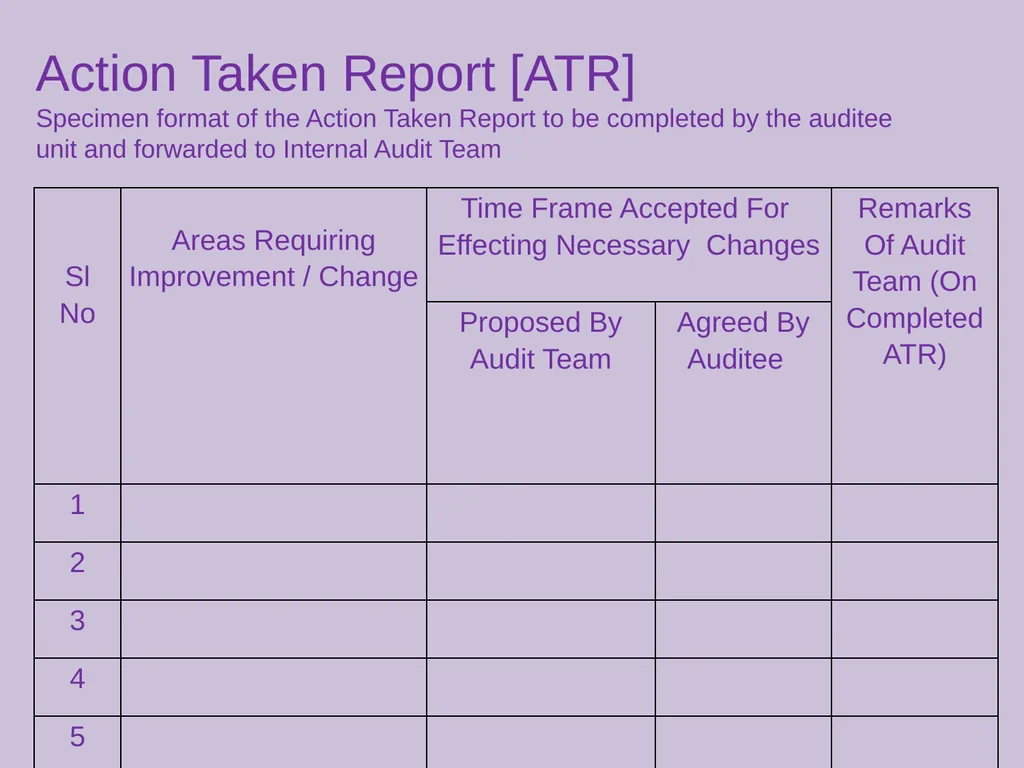
slide18. Action Taken Report [ATR]
Specimen format of the Action Taken Report to be completed by the auditee unit and forwarded to Internal Audit Team<br>
slide19. Internal Audit Check lists
A. Outsourcing
Ensure that Norms are set in respect of Input - Output of outsourcing jobs.
Ensure that control is kept over the outsourcing jobs on a consignment to consignment basis. The consignment wise control should be exercised for Input - Output. Any shortages / deviation from the set input-output Norms on the basis of every consignment should be inquired into and suitable recovery made from the processor. Norms should also be set for process loss / Wastage/ Scrap etc.
Quantity / Value reconciliation with the processor should also be made on a consignment to Consignment basis and monthly stock certificates are obtained from the processor.
Any shortage / Excess in input-output should be adjusted / accounted for
in the books also on a consignment to consignment basis so as to ensure proper control over the quantity of raw material sent to the job processor and the quantity of finished product received from the processor.<br>
slide20. Check whether the contract with the job processors is entered for a fixed period subject to renewal.
Check whether the contract clearly lays down all the relevant terms and conditions
Check whether the rates for carrying out the jobs work are finalized after a proper comparison of the rates and further negotiation.
Check whether the terms and conditions of the contract include the period within which the processor has to carry out the job after the receipt of the material and a penal clause included in the contract to this effect.
Check whether there is a proper control on Raw materials, packing materials, moulds etc sent to outsourcing parties and the same are reconciled with periodic statements received from the parties with the total quantity dispatched by plants.<br>
slide21. Check whether there is a central Agency (such as Outsourcing Department, HO) who deals with all the Raw materials, packing materials, moulds etc and distributes the work accordingly from the plants.
Check whether Raw materials, packing materials, moulds etc directly received by party from vendors / suppliers are reported to / accounted for by the respective plants.
Check whether all excess Raw materials, packing materials, moulds etc are returned by parties concerned to the respective locations / plants, once the jobs are completed.
Check whether Raw materials, packing materials, moulds etc sent to the contractors are not returned to the Company within a period of six months, a debit note or invoice on the excise duty paid by the company is raised on the contractor.<br>
slide22. B. Production
Verify the production records such as production slips / memos to ensure that the records are properly maintained.
Also verify the log books of machinery to check the details of production. Check the production log books.
Check the budgeted production of all the products with the actual result on a monthly / annual basis. Ascertain the reason for a shortfall in the production if any and comment upon it.
Check the production capacity utilization of all the production plants and enquire in to the reasons for lower capacity utilization and comment upon it.
Check the system / procedure / method of recording the input and output.<br>
slide23. Check whether the Input / Output Norms have been determined of each process of manufacture / process loss/ wastage (Accounted) losses and the unaccounted loss and gain.
Check format of the Input and Output statement and ensure that all the relevant data/information related to the following are shown separately. Opening stocks of RM / WIP.
Closing stock of RM / WIP . Total Input
RM issued.
Other material issued.
Accounted losses – various types (Norm v/s Actual)
Finished goods (Norm v/s Actual )
Unaccounted losses (Norm v/s Actual)<br>
slide24. Check the production slips with the entries in the excise record (RG-1).
Comment upon the deviation in the norms set for Input / Output ie Norm v/s actual position.
Check the production schedules to verify whether the production has been carried out as per the scheduled production.
Check the details in respect of yield - Budgeted yield v/s actual yield in respect of all the products and enquire in to the reason for lower yield and comment upon it.<br>
slide25. C. Production planning and control
Study the system/ method and the procedure of production planning and the procedure for the preparation of weekly / monthly / annual production budgets.
Check the status of orders received from the Marketing Department for production of various products.
Check the machine utilization status report and comment upon the idle time - reason thereof and the steps to reduce idle time.<br>
slide26. Check the log book in respect of all the plant machinery and equipments are kept properly and up to date. Verify the machine log books and comment on the discrepancies observed.
Check that there is a proper lay out for free flow of materials.
Check that the actual production is carried out as per Production Planning and comment upon the deviation from the production planning figures.
Carry out a study of machine efficiency and utilization to ensure that the machine is utilized as per the laid standards of efficiency and utilization.<br>
slide27. Thank Q<br>
AVNS NAGESWARA RAO
M.COM L.LB ACS FCMA
PRACTICING COST ACCOUNTANT
CHAIRMAN-SIRC OF ICAI [2009-10]<br>
slide2. Internal Audit definition
Chartered Institute of Management Accountants, UK (CIMA):
‘An independent appraisal activity established within an organization as a service to it. It is a control which functions by examining and evaluating the adequacy and effectiveness of other controls; a management tool which analyses the effectiveness of all parts of an organization’s operations and management.’
Institute of Internal Auditors (IIA):
‘Internal auditing is an independent, objective assurance and consulting activity designed to add value and improve an organization’s operations. It helps an organization accomplish its objectives by bringing a systematic, disciplined approach to evaluate and improve the effectiveness of risk management, control, and governance processes.’<br>
slide3. Need for Internal Audit
The Internal Audit will primarily concentrate on flow of data and justification of basis instead of vouching.
The materiality of cost and product under consideration would always be borne in mind during Internal Audit process.
Objectivity in approach would be a consistent feature in Internal Audit.
Main thrust would always be on deviations and significance of deviations with impact of the same on the performance of the organization.<br>
slide4. Objectives of Internal Audit
Develop and monitor control frameworks
Establish reporting structures and formalize communication processes
Aid the cost reduction and operational performance appraisals
Develop and continuously monitor risk assessment and management
Undertake workshops for training and awareness
Assure compliance with all relevant rules and regulations
Supporting corporate governance and developing resources for management information<br>
slide5. Functions of the Internal Audit
As per the above definitions functions of the Internal Audit activity are:
Internal Control: Internal controls direct, monitor, and measures the company's resources and help to detect and prevent fraud from occurring within an organization.
It can be defined as a process which is performed by the employees of the company as well as the information technology systems that are used to assist the company in achieving its objectives.
The management of a company is responsible for establishing the system of internal controls within the organization, but internal auditors test the controls to make sure they are working effectively.
Management Tool:
Internal Audit has been used as a management tool which monitors and evaluates the effectiveness of operational processes and risk management of a company.
How an organization sets their objectives and responds to the risks associated with their objective is part of the risk management process.
Risk management is a way for companies to manage uncertainty through risk assessment, to develop strategies to manage risk and to mitigate risk by using managerial resources.<br>
slide6. Management Reporting & Internal Control Systems
Management reporting and internal control systems in place will enable the management to monitor performance, strategy, operations, business environment, organization, procedures, funding, risk and internal control that ensures effective financial reporting procedures.
The management reporting and internal control systems include
Plans
A business plan including strategic planning and corporate objectives for the upcoming three years;
An annual budget
Monthly reports
Quarterly reports including updates of annual estimates, if any<br>
slide7. B. Reporting
Financial performance and financial position;
Comparison of budgeted and actual performance;
Analysis of cash flows;
Production / Project management and cost control; identification of responsible project managers and regular reporting and follow-up;
Summaries of management key performance indicators;
Controls over purchasing and maintenance of assets;
Review of potential claims and litigation;
Review to ensure that all commitments and liabilities are recognized as well as all incomes to which Company is entitled
C. Policies and procedures
Financial Policy guiding the investments of liquid assets
Authorization manual guiding the incurrence of expenses and investments
The Employee manual guiding on policies, rules and procedures associated with the Employment of people at various levels in the Company
Detailed controls to ensure the completeness and accuracy of accounting records.<br>
slide8. Control and Risk Assessment
Risk management is the management function used for developing, maintaining and implementing the Risk Management Framework, strategy and policy. Pointers to the need for a change in behavior and mindset in relation to risk management are:
Well defined risk factors that act as indicators to risk assessments does not exist
Risk awareness among staff and management is low
The organization begins to focus on financial control of expenses rather than a broad level internal control through guidelines
The top level management start believing that risk management is not their concern and agenda in meetings
Internal control system review is viewed as a compliance report rather than a daily activity
There is a lack of clearly defined business objectives in the short term<br>
slide9. Risk management process embraces
A clear understanding of the organization’s long and short term objectives
Identification of the risks associated with non-performance or deviation from set objectives
Assessment of the probability and potential impact of particular risks factors that are crucial to achieving operational performance
Development of action plans and delivery programs to address the identified risks
Monitoring and evaluating the risks on a continuous basis<br>
slide10. Internal Audit Strategy
Internal Audit strategy acts as a link between the internal audit charter and the work plan.
Purpose of Internal Audit Strategy
A bird’s eye view of the overall governance, risk management and control system of the organization,
Focusing the internal audit effort where it is most useful and effective, keeping track of the budgeted time and cost,
Minimizing repetition and eliminating duplication of assurance effort,
Ensuring that there are no gaps in the internal audit function and the entire spectrum of control system is analyzed,
Identifying the requisite skills, resources and specializations to deliver an efficient internal audit function,
Providing a reference point and setting up the basic framework for performance appraisal of all functions.
Assessing risk and identifying steps and procedures to mitigate risk.
Introducing a culture of continuous improvement and enhancing feedback by formalizing the communication channel.<br>
slide11. A good of Internal Audit Strategy assimilates
A brief description of the approach of internal audit selected in developing the strategy and a list of key managers who approved the strategy;
A summary of the organization’s short, medium and long term strategic mission and objectives or KPIs (Key Performance Indicators) to be targeted;
A short summary on the organization’s prima facie risks (both external and internal);
A description of the industry that the organization operates in and positioning of the organization in comparison to the industry standards;
A general SWOT analysis of the organization banks on to deliver commitments and sustain growth;
An estimate of the financial, operational, sales, and human resources budgets and targets over the period of the strategy;
The parameters of time, effort and costs considered to formulate the internal audit work plan;
The allocation of resources to the Internal Audit function along with the time lines for delivery;
The balance of various types of internal audits to be undertaken along with the approved audit scope;
The frequency, distribution and level of detail in the internal audit report;
The details of function-wise and SBU-wise KPI and KRA (Key result areas);
The formal procedure for review and update of internal audit strategy;<br>
slide12. Business Models of Pharma Industry
Company manufacturing its own bulk drugs and formulations
Company manufacturing its own bulk drugs and formulations but part of the process and / or recovery of chemicals is outsourced.
Company purchasing input from a related party or selling it to related party.
Company manufacturing at site of support manufacturer but, the clearance and payment of excise duty is undertaken in name of principal company
Manufacturing of life saving drugs exempted from excise.
The product is subject to state excise duty and not central excise duty.
Drug Discovery and Development Solutions (DDDS)
Clinical Research Services
Contract Research and manufacturing Services (CRAMS)
Principal to principal (p2p)
Loan Licensing
Manufacturing of Bulk Drug / API and / or Formulations in 100% Export Oriented Unit (100% EOU) or in Special Economic Zone (SEZ) with an intent to export<br>
slide14. Key Functional areas for Internal audit in Pharma Industry
Statutory compliance
Quality Management with reference to the quality cost
Human Resources utilization and costs
Buildings and Facilities utilization
Process Equipment utilization
Documentation and Records
Materials Management and controls
Production and In Process Controls
Packaging and Identification Labeling of APIs and IM
Storage and Distribution cost and control
Inventory control
Inventory valuation
Rejection and Re-Use of Materials
Complaints and Recalls
Contract Manufacturers (including Laboratories)
Transactions with Agents, Brokers, Traders, Distributors, Re-packers, and Re-labelers
APIs for Use in Clinical Trials
Pollution control facilities utilization and costs<br>
slide15. Example:
Key Functional Area: Inventory Control OK: Covered during audit, and found satisfactory
NA: not applicable
AR: See Audit Report being a non- compliance issue<br>
slide16. Audit observations & Qualifications
Critical deficiency is one which:
Has produced, or leads to a significant risk of producing an Active Pharmaceutical Ingredient that could be harmful to the human or veterinary patient.
Major deficiency is a non-critical deficiency which:
Has produced or may produce a product, which does not comply with its Specification; or
Indicates a major deviation from Good Manufacturing Practice; or
Indicates a failure to carry out satisfactory procedures for release of batches<br>
slide17. Minor deficiency is other deficiency which:
Cannot be classified as either critical or major, but which indicates a departure from good practice. (A deficiency may be “other” either because it is judged as minor or because there is insufficient information to classify it as a major or critical deficiency).
A combination of several “other” deficiencies, none of which on their own may be major, but which may together represent a major deficiency and should be explained and reported as such;<br>
slide18. Action Taken Report [ATR]
Specimen format of the Action Taken Report to be completed by the auditee unit and forwarded to Internal Audit Team<br>
slide19. Internal Audit Check lists
A. Outsourcing
Ensure that Norms are set in respect of Input - Output of outsourcing jobs.
Ensure that control is kept over the outsourcing jobs on a consignment to consignment basis. The consignment wise control should be exercised for Input - Output. Any shortages / deviation from the set input-output Norms on the basis of every consignment should be inquired into and suitable recovery made from the processor. Norms should also be set for process loss / Wastage/ Scrap etc.
Quantity / Value reconciliation with the processor should also be made on a consignment to Consignment basis and monthly stock certificates are obtained from the processor.
Any shortage / Excess in input-output should be adjusted / accounted for
in the books also on a consignment to consignment basis so as to ensure proper control over the quantity of raw material sent to the job processor and the quantity of finished product received from the processor.<br>
slide20. Check whether the contract with the job processors is entered for a fixed period subject to renewal.
Check whether the contract clearly lays down all the relevant terms and conditions
Check whether the rates for carrying out the jobs work are finalized after a proper comparison of the rates and further negotiation.
Check whether the terms and conditions of the contract include the period within which the processor has to carry out the job after the receipt of the material and a penal clause included in the contract to this effect.
Check whether there is a proper control on Raw materials, packing materials, moulds etc sent to outsourcing parties and the same are reconciled with periodic statements received from the parties with the total quantity dispatched by plants.<br>
slide21. Check whether there is a central Agency (such as Outsourcing Department, HO) who deals with all the Raw materials, packing materials, moulds etc and distributes the work accordingly from the plants.
Check whether Raw materials, packing materials, moulds etc directly received by party from vendors / suppliers are reported to / accounted for by the respective plants.
Check whether all excess Raw materials, packing materials, moulds etc are returned by parties concerned to the respective locations / plants, once the jobs are completed.
Check whether Raw materials, packing materials, moulds etc sent to the contractors are not returned to the Company within a period of six months, a debit note or invoice on the excise duty paid by the company is raised on the contractor.<br>
slide22. B. Production
Verify the production records such as production slips / memos to ensure that the records are properly maintained.
Also verify the log books of machinery to check the details of production. Check the production log books.
Check the budgeted production of all the products with the actual result on a monthly / annual basis. Ascertain the reason for a shortfall in the production if any and comment upon it.
Check the production capacity utilization of all the production plants and enquire in to the reasons for lower capacity utilization and comment upon it.
Check the system / procedure / method of recording the input and output.<br>
slide23. Check whether the Input / Output Norms have been determined of each process of manufacture / process loss/ wastage (Accounted) losses and the unaccounted loss and gain.
Check format of the Input and Output statement and ensure that all the relevant data/information related to the following are shown separately. Opening stocks of RM / WIP.
Closing stock of RM / WIP . Total Input
RM issued.
Other material issued.
Accounted losses – various types (Norm v/s Actual)
Finished goods (Norm v/s Actual )
Unaccounted losses (Norm v/s Actual)<br>
slide24. Check the production slips with the entries in the excise record (RG-1).
Comment upon the deviation in the norms set for Input / Output ie Norm v/s actual position.
Check the production schedules to verify whether the production has been carried out as per the scheduled production.
Check the details in respect of yield - Budgeted yield v/s actual yield in respect of all the products and enquire in to the reason for lower yield and comment upon it.<br>
slide25. C. Production planning and control
Study the system/ method and the procedure of production planning and the procedure for the preparation of weekly / monthly / annual production budgets.
Check the status of orders received from the Marketing Department for production of various products.
Check the machine utilization status report and comment upon the idle time - reason thereof and the steps to reduce idle time.<br>
slide26. Check the log book in respect of all the plant machinery and equipments are kept properly and up to date. Verify the machine log books and comment on the discrepancies observed.
Check that there is a proper lay out for free flow of materials.
Check that the actual production is carried out as per Production Planning and comment upon the deviation from the production planning figures.
Carry out a study of machine efficiency and utilization to ensure that the machine is utilized as per the laid standards of efficiency and utilization.<br>
slide27. Thank Q<br>