
Mergers & acquisitions, Chapter 1 (Business
TD
Published · 140 slides · 0 views

1 / 1





Description
Mergers acquisitions, Chapter 1 (Business Associations, Chapter 4) Shareholder Activism Prof. Amitai Aviram Aviramillinois.edu University of Illinois College of Law Copyright Amitai Aviram. All Rights Reserved S22 Shareholder Activism
Related Topics
Share
Embed code
Download this presentation From Below
"Mergers & acquisitions, Chapter 1 (Business" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Mergers & acquisitions, Chapter 1
(Business Associations, Chapter 4)
Shareholder Activism Prof. Amitai Aviram
Aviram@illinois.edu
University of Illinois College of Law
Copyright © Amitai Aviram. All Rights Reserved
S22<br>
Aviram@illinois.edu
University of Illinois College of Law
Copyright © Amitai Aviram. All Rights Reserved
S22<br>
02
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Share ownership
Ownership structure
Ownership mechanics (in public firms)
M&A players (SH incentives)
FD of SHs
Shareholder voting
Shareholder litigation<br>
Share ownership
Ownership structure
Ownership mechanics (in public firms)
M&A players (SH incentives)
FD of SHs
Shareholder voting
Shareholder litigation<br>
03
Ownership structure
Sole ownership Ownership in a firm means the control rights to direct its behavior and the economic rights to its residual assets (either periodically as dividends, or at the time the firm is liquidated)
Sole ownership: one person has all firm’s control & economic rights
The most common situation of sole ownership is a wholly-owned subsidiary
Agent problem (cost/risk that corporate actors will exploit owners): low relative to other firms – sole owner can discipline corporate actors (has a strong incentive to monitor the actors & able to punish unaccountable actors)
Principal problem (cost/risk that some owners will exploit other owners): none, since there is just one owner
Access to equity capital: none, because firm can’t raise capital by selling shares; it can still finance itself from its profits, from the owner’s funding, and by borrowing (but lenders don’t get to control the firm, so they’d be reluctant to lend much or will demand high interest and collateral)<br>
04
Ownership structure
Concentrated ownership Concentrated ownership: Firm has C (SH with enough control rights to exercise the authority of the SH meeting), as well as mSHs
C may be 1 person, or group that effectively exercises direct control:
Low cost to act collectively (e.g., clear hierarchy, easy for group to meet)
Similar business interests
Equal access to info/expertise
Typically, >50%, but in many firms less than 50% is still enough to control (and if SH voting requires a supermajority, 51% may not be enough)
Sometimes concentrated ownership results from C owning a special class of “supervoting shares” (more votes per share), or mSHs owning nonvoting shares
Agent problem: medium; C can discipline corporate actors, but:
C bears 100% of costs of monitoring actors, but gets less than 100% of benefits, so puts less effort into monitoring than a sole owner;
C may collude with corporate actors to extract value from firm at expense of mSHs
Principal problem: high; C has incentive & ability to tunnel
Access to equity capital: limited; firm can issue shares, but:
Limited in # of voting shares it issues, because C won’t allow losing control
Potential SHs deterred by risk of C’s tunneling<br>
05
Ownership structure
Dispersed ownership Dispersed ownership: Firm does not have a C; only mSHs
Example: firm in which largest SH has 4%; largest 10 SHs together have 15%
Another example: Italian mutually-owned banks (Popolari) has a rule of one vote per SH (rather than one vote per share) – result is that no one can control the firm, since buying more shares does not increase one’s votes
Agent problem: high; mSHs unlikely to discipline corporate actors
Each mSH only gets tiny portion of value of monitoring actors, but bears full cost
Even if mSH did monitor & find a problem, mSH can’t do much to control the board
Exception: activist SHs are mSHs who are willing & able to monitor corporate actors, typically in the hopes of creating a large short-term profit (activism is expensive and risky, so the ordinary returns of a good firm are likely not enough, and activist wants to be able to cut losses quick and move on)
Principal problem: none / medium; no controller, but empowered SHs may force firm to act in their benefit, even if not in benefit of other mSHs
Access to equity capital: broad; firm can issue shares
mSHs don’t object to dilution of control rights (since they can’t/won’t exercise control rights), as long as price of shares is fair
No risk of C tunneling to deter potential SHs<br>
06
Ownership structure
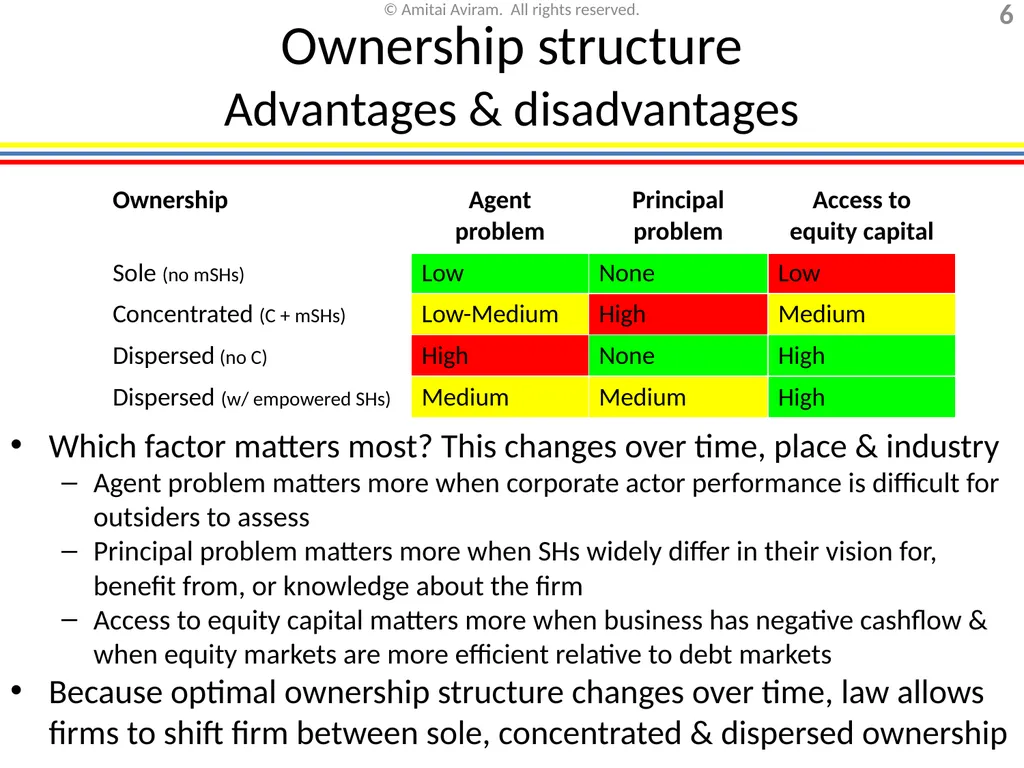
Advantages & disadvantages Which factor matters most? This changes over time, place & industry
Agent problem matters more when corporate actor performance is difficult for outsiders to assess
Principal problem matters more when SHs widely differ in their vision for, benefit from, or knowledge about the firm
Access to equity capital matters more when business has negative cashflow & when equity markets are more efficient relative to debt markets
Because optimal ownership structure changes over time, law allows firms to shift firm between sole, concentrated & dispersed ownership<br>
07
Ownership structure
Shifting from one ownership structure to another Dispersing control
Sole to concentrated: firm issues new shares to mSHs
Sole to dispersed: issue more shares to mSHs (or C sells some of her shares to many different SHs), so no SH has enough shares to control
Concentrated to dispersed: same as sole to dispersed
Consolidating control
Dispersed to concentrated: C buys shares from many mSHs, until she has enough shares to control the firm
Concentrated/dispersed to sole
This is a challenge, because some mSHs are likely to hold-out and not sell to C, in order to get more money
Solution: freezeout (deal between C & firm that forces mSHs to sell their interest in the firm to C; similar to eminent domain in property law)
E.g., short form merger (“SFM”): if C owns ≥90% of shares, law allows C to force mSHs to sell to her, but mSHs can petition court to determine fair price
C can also freezeout without first owning 90% of shares – in that case (illustrated on the next slide) transaction is called a long-form merger (“LFM”)
LFMs require approval by majority of SHs (SFMs don’t require SH approval)<br>
08
Ownership structure
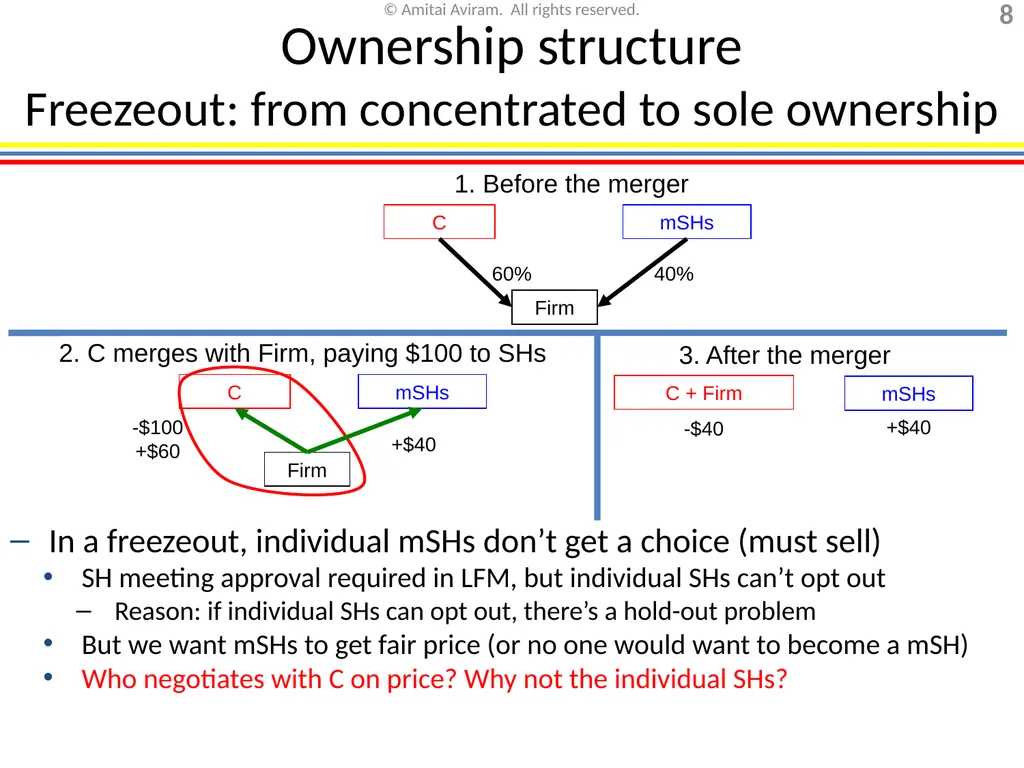
Freezeout: from concentrated to sole ownership In a freezeout, individual mSHs don’t get a choice (must sell)
SH meeting approval required in LFM, but individual SHs can’t opt out
Reason: if individual SHs can opt out, there’s a hold-out problem
But we want mSHs to get fair price (or no one would want to become a mSH)
Who negotiates with C on price? Why not the individual SHs? Firm C 60% mSHs 40% 1. Before the merger 2. C merges with Firm, paying $100 to SHs Firm C mSHs C + Firm mSHs 3. After the merger -$40 +$40 +$40 -$100 +$60<br>
09
Ownership structure
Freezeout: ensuring a fair price One solution to the fair price problem is to have an independent party (a judge) decide the fair price
This is called an appraisal: SHs reject the price offered by C, and petition the court to determine the fair price
Delaware law gives SHs the option of appraisal
This can result in some SHs (who accepted C’s offer) getting the price C offered, while other SHs (who dissented) getting a different price determined by the court
Why not have universal appraisal (all SHs get price determined by the court)?
Indeed, Delaware’s appraisal rules intentionally impose procedural barriers & don’t allow a class action, in order to limit the # of SHs demanding appraisal (more about these rules in Section 2a)
Optional appraisal still leaves consenting SHs vulnerable
Solution: Encourage C & firm to negotiate freezeout in a way that bypasses CoI
Typically, this is done by creating a special board committee composed of independent members, which negotiates with C on firm’s behalf
If C & XB follow a fair process that minimizes CoI, FD challenge to the freezeout is evaluated under BJR, not entire fairness<br>
10
Ownership mechanics
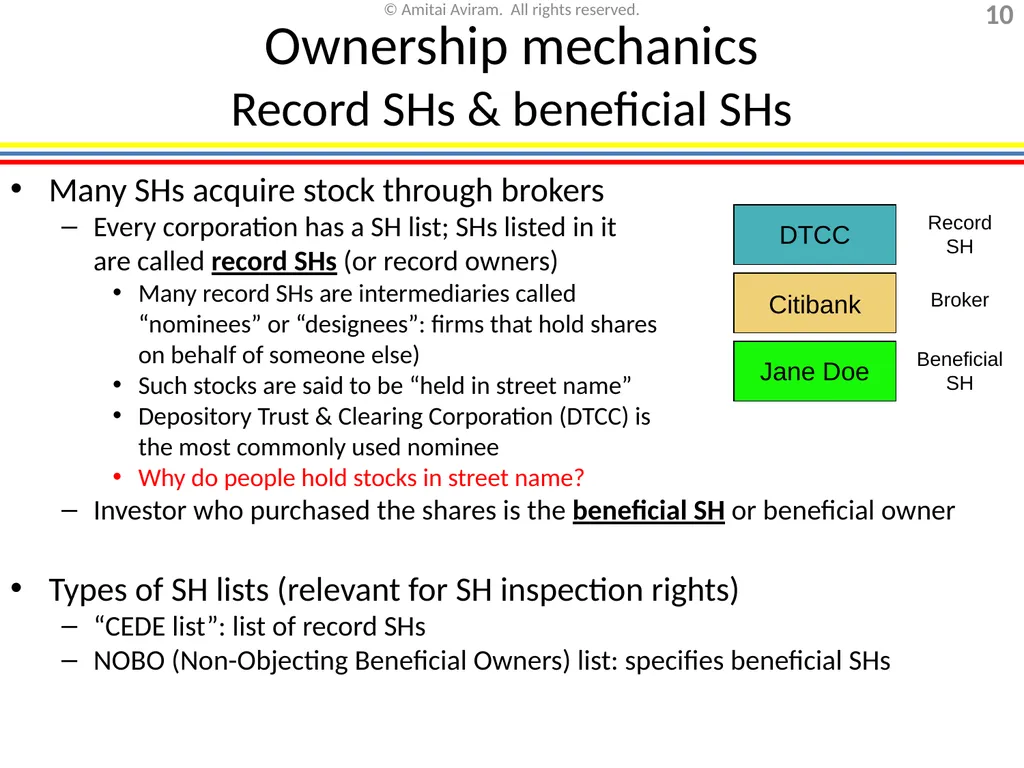
Record SHs & beneficial SHs Many SHs acquire stock through brokers
Every corporation has a SH list; SHs listed in it are called record SHs (or record owners)
Many record SHs are intermediaries called “nominees” or “designees”: firms that hold shares on behalf of someone else)
Such stocks are said to be “held in street name”
Depository Trust & Clearing Corporation (DTCC) is the most commonly used nominee
Why do people hold stocks in street name?
Investor who purchased the shares is the beneficial SH or beneficial owner
Types of SH lists (relevant for SH inspection rights)
“CEDE list”: list of record SHs
NOBO (Non-Objecting Beneficial Owners) list: specifies beneficial SHs DTCC Citibank Jane Doe Beneficial SH Broker Record SH<br>
11
Ownership mechanics
Designee’s ability to vote shares Designee’s ability to vote the shares is limited by contract & stock exchange rules
Exchange Act §6(b) requires exchanges to prohibit designees from voting shares in director elections, with respect to executive compensation & any other significant matter as determined by SEC rules
NYSE rule 452 allows designees, who solicited but didn’t receive instructions from beneficial SH, to vote the shares on “routine” matters
Matters addressed by Exchange Act §6(b) would be “non-routine”
On non-routine matters, these shares (called “broker non-votes”, see Licht, FN 8) do not count as “voting power present”
However, since these shares can still vote on routine matters, they count for establishing a quorum if any routine matter was voted on in the SH meeting<br>
12
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Share ownership
Ownership structure
Ownership mechanics (in public firms)
M&A “players” (SH incentives)
FD of SHs
Shareholder voting
Shareholder litigation<br>
Share ownership
Ownership structure
Ownership mechanics (in public firms)
M&A “players” (SH incentives)
FD of SHs
Shareholder voting
Shareholder litigation<br>
13
M&A “players”
Types of acquirers Financial acquirer: Y interested in owning X because of the financial gains from X’s assets
Growth (capital gains): gains in the share price (bought it for $5/share, now share trades for $100); realized when you sell the shares
Current price already reflects future sales & profitability, so to get capital gains, firm usually needs to increase revenue or profit margin
Growth more likely in younger industries
Income: dividends paid periodically by the firm
Income more likely in mature, low-growth industries (because they don’t need to reinvest their profits in the business, and they have predictable profits)
Strategic acquirer: Y interested in owning X because of the impact ownership has on Y’s other assets
E.g., Google bought YouTube to gain synergies (in selling ads, gaining user information, improving search engine results) from owning both a search engine and a video streaming service
E.g., Ferrero (maker of Nutella & Tic-Tacs) bought Nestle’s U.S. chocolate business (maker of Butterfinger, Baby Ruth), gaining economies of scale & marketing synergies on all its US products<br>
14
M&A “players”
Typical controllers Strategic controller
Firm controls several businesses related horizontally (have same suppliers/customers) or vertically (one business is the other’s supplier/customer)
Strategic owners like to control/wholly-own firm to max synergies/avoid CoI
Founders/active family
Deep personal attachment to firm, usually work in firm
Resist losing control of the firm
Typically want growth (sometimes become strategic acquirers)
Private equity
Take controlling positions in firms (usually buying the whole firm, sometimes with other investors if the PE firm can’t afford to buy it alone
Clients of PE firms are locked-in for several years (e.g., 7 years), so PE firms have a longer time horizon than hedge funds & other short-term players
PE firms look for disfavored firms that require changes that take years to implement
After the PE firm acquires a firm, it makes those changes, and when they are done the firm is either sold to a strategic firm or to the public
PE firms use a lot of leverage in their acquisitions (borrow, issue junk bonds) & use the target as collateral, so they like firms that generate stable, predictable income<br>
15
M&A “players”
Typical mSHs Strategic mSH
Sometimes firm uses a minority investment to support an alliance with another firm, gain influence on it/knowledge from it, or as “beachhead” to control stake
Passive family
Descendants of firm’s founder, but not involved with the firm; ownership in firm is often a large part of their total wealth
Typically want income, or want to sell and diversify
Retail investors
Ordinary people owning stock; typically very small positions & very passive (either buy & hold, or sell rather than fight if they’re unhappy)
Institutional investors
Organizations that pool money & invest it
Tend to take non-controlling positions (allows to invest in more firms & diversify)
Tend to be passive (i.e., can’t become experts on all their investments), so if they don’t like the way firm is managed, they are more likely to sell their investment than fight the management (however, occasionally they team up with activist SHs to fight)
Less likely to use leverage (sometimes prohibited from using leverage)
Vary from very long-term investing to short-term investing
Common institutional investors are: endowments, sovereign wealth fund, insurance companies, pension funds, employee stock ownership plans (ESOPs), active mutual funds, passive mutual funds (index funds)<br>
16
M&A “players”
Typical mSHs Hedge funds
Less-regulated mutual fund (only open to “sophisticated” investors), charge higher fees than mutual funds
Tend to take non-controlling positions in a firm (to diversity & move quickly)
Tend to have short time horizons (their clients can often take out their money once a quarter, so the funds need to show a good performance every three months or risk that investors abandon them)
Hedge funds differ widely in their strategies
High frequency traders: use computers to capitalize on tiny market discrepancies
Merger arbitrageurs (“arbs”): buy shares in potential X, betting it will be acquired
Activists: pick underperforming firms, then fight a public campaign for firm to take certain actions that are likely to cause a quick increase in share price (e.g., forcing a company to sell itself or split itself into multiple firms). If they fail to persuade the board, they may try to replace it in a proxy fight.
Tend to use a lot of leverage
Look for firms they can easily & secretly buy/sell large amounts of shares<br>
17
M&A “players”
Leverage and the junk bond market SHs can increase risk & return by using mostly borrowed money to acquire shares; the borrowed money can come from a bank (loan) or from the market (bonds)
Lenders often take a secured interest in the acquired assets (the target firm)
Lenders care mostly about three things:
Amount of leverage used (how much of the borrowers own money is used together with the borrowed money)
Cash generation capacity of the acquired firm/element (it must generate enough cash to pay the interest charges)
Volatility of cash generation (the more stable the business, the more appealing it is to the lenders, since it is less likely that at any given point insufficient cash will be generated to pay the interest)
So, significant amounts of money could be borrowed to acquire assets with low earning volatility, but it is difficult to borrow much for assets with high volatility – buyers would have to borrow less and use more of their own money<br>
18
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Share ownership
M&A “players” (SH incentives)
FD of SHs
SH’s act (that does not involve the firm)
Firm’s act
Shareholder voting
Shareholder litigation<br>
Share ownership
M&A “players” (SH incentives)
FD of SHs
SH’s act (that does not involve the firm)
Firm’s act
Shareholder voting
Shareholder litigation<br>
19
FD of SHs
Purpose of FD Why impose FD on controllers? (They don’t act on behalf of the firm)
Similar to logic of apparent authority in agency: C can hide behind the directors – hire judgment proof directors, have them divert value from mSHs to C, and mSHs would not be able to collect that value from the directors
So, C owes a FD if it can influence the board
The board still owes a FD as well, and they would breach it if they give C preferential treatment to the mSHs
FD lets courts examine the fairness of deals between firm & C, as well as other deals in which C may tunnel (deals in which C receive better terms than the mSH)
This is undesirable; courts are not good in allocating value among SHs
Instead, the law tries to prevent CoI, by giving C & firm an incentive to negotiate deals in a process that approximates arm’s-length negoitations
Deal negotiated by a special committee of independent directors
Deal approved by a majority of mSHs
Fairness review is used as a threat if this process is not followed<br>
20
FD of SHs
Analysis: Duty When does a SH owe a FD to mSHs?
SH owes a FD “only if it owns a majority interest in or exercises control over the business affairs of the corporation” (Ivanhoe Partners v. Newmont Mining Corp. [Del. 1987])
Control groups: Multiple SHs considered as a single control group when connected in some legally meaningful way (e.g., contract to work together towards a shared goal) (Frank v. Elgamal)
Connection may need to be related to the challenged transaction (Patel v. Duncan [Del.Ch.2021])<br>
21
FD of SHs
Analysis: SoR Which SoR applies?
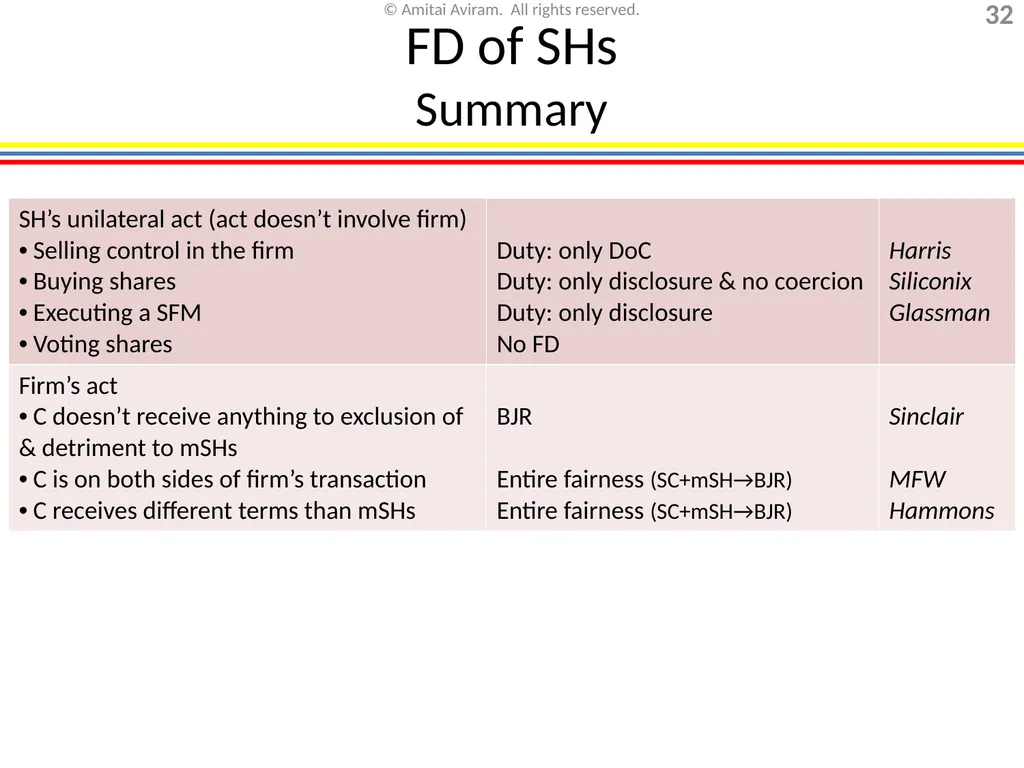
When C acts without involving the firm, C’s FD is limited to a duty of care (no negligence), a duty of disclosure, and a duty not to coerce mSHs (so, C is allowed to self-deal); SoR is always BJR (Harris)
When the firm acts:
If C is on both sides of a transaction, SoR is entire fairness unless firm implemented “robust procedural protections”, in which case SoR is BJR (MFW)
Same if C is only on the mSHs’ side of the transaction, but C receives different terms than mSHs (Frank)<br>
22
FD of SHs
SH’s unilateral act: Policy This category usually involves:
C sells her shares
C buys shares from mSHs
C executes a SFM
C votes her shares
Rule: C may act self-interestedly (no prohibition on self-dealing) when the firm is not involved (since C’s influence on the firm is irrelevant)
Selling shares
When C offers to sell her shares, the buyer (new C) can be a looter (buyer who plans to tunnel value from firm) or a non-looter (who shares value with mSHs)
Looter would value firm higher than non-looter, so a looter is likely to offer C a better price than a non-looter
C has incentive to accept the looter’s offer (since she won’t be a SH anymore)
To prevent this perverse incentive, a duty of care to mSHs is imposed on C when she sells control of the firm to someone<br>
23
FD of SHs
SH’s unilateral act: Harris v. Carter [Del. Ch. 1990] Carter sells control of Atlas to Mascolo
The Carter group (owners of 52% of Atlas) sold their shares to Mascolo in return for shares in ISA
Mascolo falsely claimed that ISA owned two insurance companies
Mascolo provided Carter with a draft financial statement of ISA that falsely claimed ownership in another insurance co.
Atlas CFO analyzed statement & raised questions about its accuracy, but Carter did not demand explanations
Mascolo loots Atlas
Mascolo merges Atlas with ISA
Result: Mascolo owns 75%; Carter group 13%; others 12%
Why would Carter agree to drop from 52% to 13%?
Mascolo makes Atlas buy shares of Hughes (which he owns)
Harris alleges that price was unfair (too high)
Does Carter lose something is Harris is correct?
Presumably Carter wouldn’t do this deal if he suspected Mascolo was looting
Can Carter be liable to mSHs if he didn’t know Mascolo was looting?<br>
24
FD of SHs
SH’s unilateral act: Harris Is Carter liable to mSHs for the looting?
Insuranshares [E.D.Pa. 1940]: C breaches DoC to mSHs when selling to a looter, if C knew of looting plans or if a reasonably prudent person would have suspected buyer is dishonest & C didn’t conduct a sufficient investigation
Levy [NY 1942]: DoC breached only if C knew of looting plans (otherwise, no liability for negligence)
Court follows Insuranshares (standard: gross negligence)
Concerned that Levy standard encourages seller to have “head in the sand”. What does the court mean?
But dicta in Abraham [Del.Ch. 2006] suggests Levy more appropriate if firm’s charter has a §102(b)(7) exculpatory provision
On exam assume Abraham correctly states the law<br>
25
FD of SHs
Other unilateral acts C buys shares from mSHs
Solomon v. Pathe Comm. Corp. [Del. 1996]: no duty to offer a fair price; duty only to provide full disclosure & not coerce the sellers
In re Siliconix Inc. Shareholders Litigation [Del.Ch. 2001]: court confirms entire fairness does not apply to freeze-out via tender offer
C executes a SFM (freezes out mSHs)
Glassman [Del. 2001]: No duty to offer fair price in a SFM; only duty is to provide full disclosure of facts required for mSHs to decide if they should opt for appraisal
C votes her shares
No duty to mSHs<br>
26
FD of SHs
SH’s unilateral act: Some related issues… Selling shares: Contractual protection for mSHs
Common contractual techniques for mSHs to share control premium
“Tag along” provision (C promises to sell only if mSHs also included in deal)
mSHs receive a “put option” (option to sell to C), triggered if C sells to someone else
When is a C likely to agree to such terms?
Selling shares: Mandatory “tag along” protection for mSHs
Some non-US jurisdictions’ corporate laws require an acquirer who buys control (e.g., over 40%) to offer to buy mSHs’ shares at same price
Is “C’s unilateral act” a diminishing category?
Board can, if it chooses, implement takeover defenses that block an acquirer from buying C’s shares
Because C’s “unilateral” sale of control depends on firm not imposing takeover defenses, perhaps Frank should apply?
Court may rule on this in future. On exam, assume Harris, not Frank, applies.<br>
27
FD of SHs
Firm’s act: When is C self-dealing? When the firm is involved in an act, C is not allowed to self-deal
Transactions in which C is on both sides of the deal (Kahn v. MFW)
E.g., Firm sells assets to/buys assets from C
Most common cases in this category involve freezeouts
Transactions in which C receives different terms than mSHs (Frank v. Elgamal)
E.g., X’s board agrees to sell X to Y. Under the deal, Y pays $10/X share to mSHs, and pays 1 Y share/X share to C
In either of these cases:
SoR is BJR if firm implemented “robust procedural protections” (deal negotiated by independent special committee & approved by majority of mSHs);
Otherwise, SoR is entire fairness
In some cases a firm’s act isn’t a transaction in which C can be on the other side or receive different terms than mSHs
In such cases, when you can’t apply MFW or Frank, you can use an older precedent as a backup: Under Sinclair Oil Corp. v. Levien (Del. 1971), SoR is entire fairness if C receives something to the exclusion of & detriment to mSHs; otherwise SoR is BJR<br>
28
FD of SHs
Firm’s act: “Robust procedural protections” Transaction negotiated & approved by a special committee or an independent board majority
Committee is independent
Committee satisfied its duty of care
Committee authorized to freely select its advisors (& they’re independent)
Committee authorized to use firm’s full bargaining power (e.g., implement takeover defenses) & to consider all of the firm’s options
Transaction approved by majority of mSHs
Approval is informed (all material info was disclosed to mSHs)
There is no coercion of the minority (specifically, mSH approval must be an unwaivable condition to the transaction)
Majority of all mSHs, not just those present at the meeting
What if firm implemented each of these protections imperfectly?
SoR is entire fairness; positive aspects of process play role in “fair process”
What if firm implemented only one of the two protections?
Kahn v. Lynch [Del. 1994]: Normally when plaintiff proves C is self-dealing, burden of proof is on C to show the challenged transaction’s fairness. However, if transaction was approved by either the special committee or the majority of mSHs, burden of proof to show fairness shifts to the plaintiff<br>
29
FD of SHs
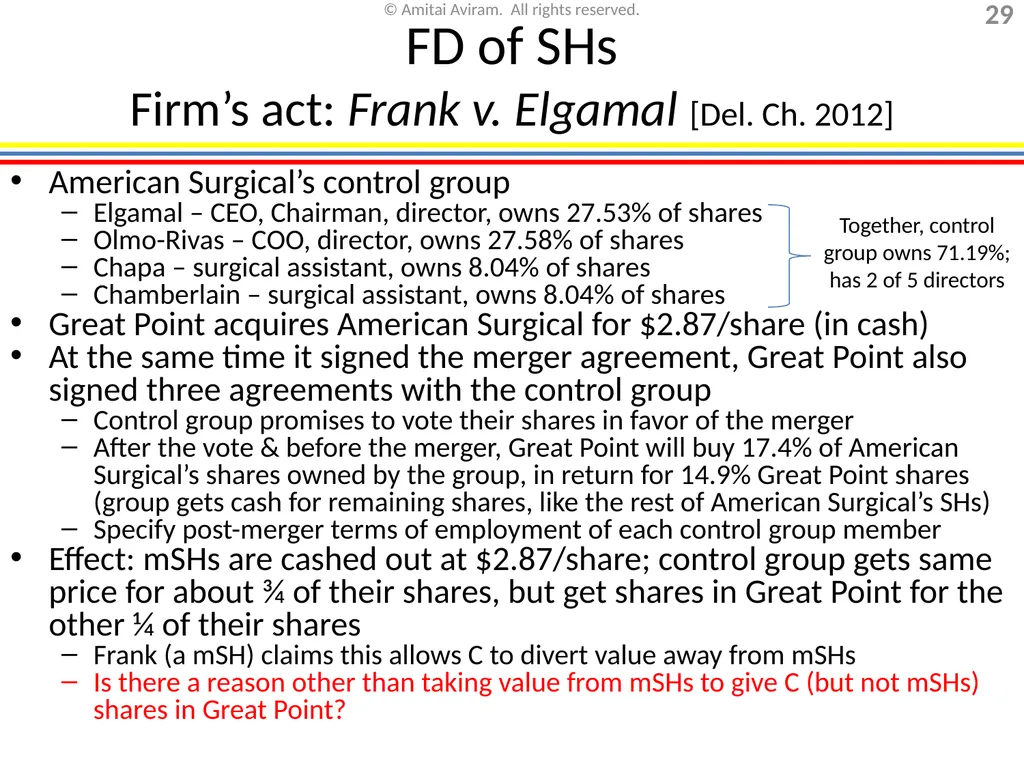
Firm’s act: Frank v. Elgamal [Del. Ch. 2012] American Surgical’s control group
Elgamal – CEO, Chairman, director, owns 27.53% of shares
Olmo-Rivas – COO, director, owns 27.58% of shares
Chapa – surgical assistant, owns 8.04% of shares
Chamberlain – surgical assistant, owns 8.04% of shares
Great Point acquires American Surgical for $2.87/share (in cash)
At the same time it signed the merger agreement, Great Point also signed three agreements with the control group
Control group promises to vote their shares in favor of the merger
After the vote & before the merger, Great Point will buy 17.4% of American Surgical’s shares owned by the group, in return for 14.9% Great Point shares (group gets cash for remaining shares, like the rest of American Surgical’s SHs)
Specify post-merger terms of employment of each control group member
Effect: mSHs are cashed out at $2.87/share; control group gets same price for about ¾ of their shares, but get shares in Great Point for the other ¼ of their shares
Frank (a mSH) claims this allows C to divert value away from mSHs
Is there a reason other than taking value from mSHs to give C (but not mSHs) shares in Great Point? Together, control group owns 71.19%; has 2 of 5 directors<br>
30
FD of SHs
Firm’s act: Frank Duty
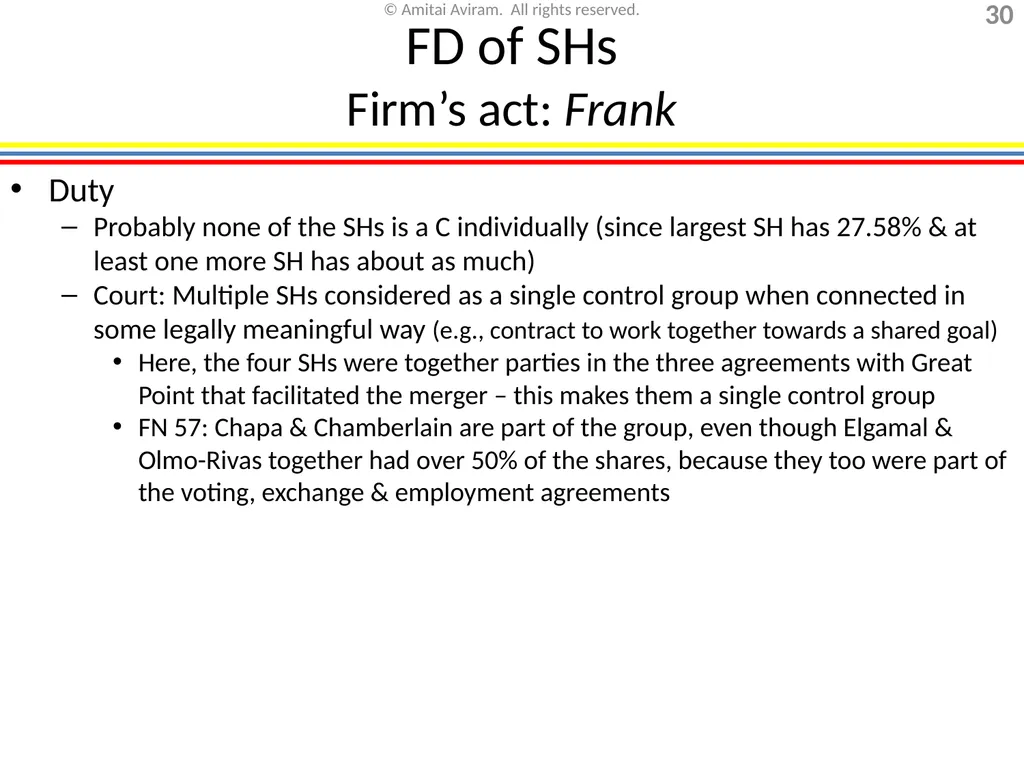
Probably none of the SHs is a C individually (since largest SH has 27.58% & at least one more SH has about as much)
Court: Multiple SHs considered as a single control group when connected in some legally meaningful way (e.g., contract to work together towards a shared goal)
Here, the four SHs were together parties in the three agreements with Great Point that facilitated the merger – this makes them a single control group
FN 57: Chapa & Chamberlain are part of the group, even though Elgamal & Olmo-Rivas together had over 50% of the shares, because they too were part of the voting, exchange & employment agreements<br>
31
FD of SHs
Firm’s act: Frank SoR
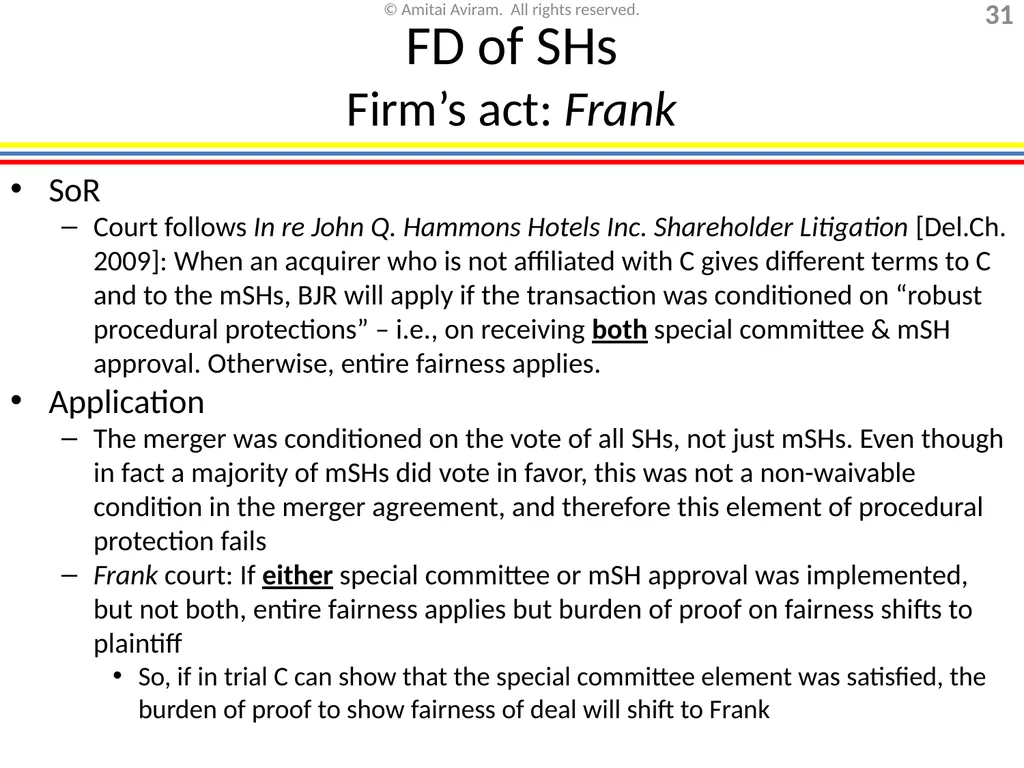
Court follows In re John Q. Hammons Hotels Inc. Shareholder Litigation [Del.Ch. 2009]: When an acquirer who is not affiliated with C gives different terms to C and to the mSHs, BJR will apply if the transaction was conditioned on “robust procedural protections” – i.e., on receiving both special committee & mSH approval. Otherwise, entire fairness applies.
Application
The merger was conditioned on the vote of all SHs, not just mSHs. Even though in fact a majority of mSHs did vote in favor, this was not a non-waivable condition in the merger agreement, and therefore this element of procedural protection fails
Frank court: If either special committee or mSH approval was implemented, but not both, entire fairness applies but burden of proof on fairness shifts to plaintiff
So, if in trial C can show that the special committee element was satisfied, the burden of proof to show fairness of deal will shift to Frank<br>
32
FD of SHs
Summary<br>
33
Shareholder Activism (MA1/BA4)
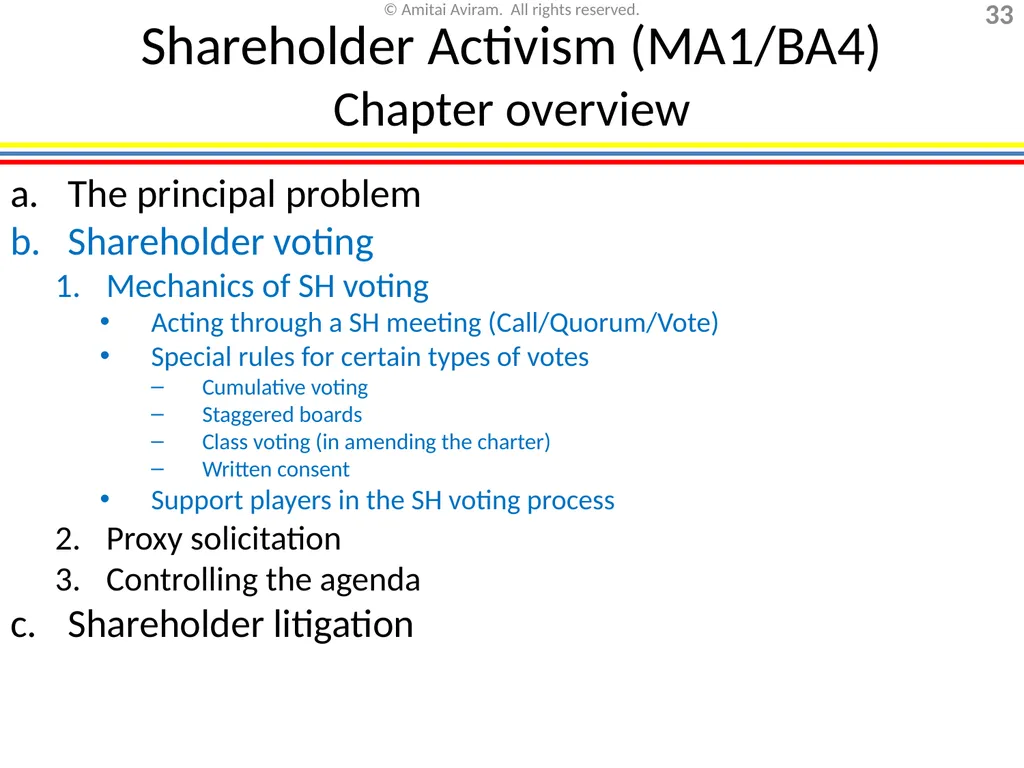
Chapter overview The principal problem
Shareholder voting
Mechanics of SH voting
Acting through a SH meeting (Call/Quorum/Vote)
Special rules for certain types of votes
Cumulative voting
Staggered boards
Class voting (in amending the charter)
Written consent
Support players in the SH voting process
Proxy solicitation
Controlling the agenda
Shareholder litigation<br>
34
Mechanics of SH voting
How do SHs act for the corporation? SHs act through a SH meeting by approving resolutions that satisfy these elements:
Call (authority to summon the meeting + appropriate notice)
Quorum (sufficient shares present at the meeting)
Vote (sufficient shares support the resolution)<br>
Call (authority to summon the meeting + appropriate notice)
Quorum (sufficient shares present at the meeting)
Vote (sufficient shares support the resolution)<br>
35
Call
Authority to summon a SH meeting Types of SH meetings
Annual SH meeting [DGCL §211(b)]: unless it elects directors by written consent, firm must hold an annual SH meeting
Special SH meetings [§211(d)]: any meeting other than the annual SH meeting (the law allows but does not require calling such meetings)
Board often calls special meetings when they need SH approval quickly (e.g., approve merger, amend charter to allow some transaction)
SHs often call special meetings (if they can) to replace board (e.g., in takeover battle)
The ‘call’ element considers two issues
Who has authority to call a SH meeting?
What is required for the notice to be valid?
Authority to call a SH meeting
As stated in bylaws [DGCL §211(b)]
Court, if no meeting was called for 13 months [§211(c)]
For special meeting: board + as stated in bylaws/charter [§211(d)]
Unlike Delaware, MBCA §7.01(c) allows 10% SHs to call a special meeting<br>
36
Call
Appropriate notice DGCL §222(a): Notice must be in writing and specify
Place of meeting
DGCL §211(a)(1): By default, place provided in charter or bylaws; if no such place is specified, meetings held in location determined by board
What if board, not wanting a particular SH to attend, decides to hold the meeting on a corporate jet during flight (knowing SH is afraid of flying)?
Date & hour of meeting
Means of remote communications, if any
For special SH meetings: purposes for which the meeting is called
DGCL §222(b): notice must be given no less than 10 days or more than 60 days before the meeting<br>
37
Quorum
Were enough SHs present? The ‘quorum’ element considers whether enough shares were present to consider the event a valid meeting
Which shares are considered present?
Shares that are entitled to vote, and are either present (SH is present at the meeting) or represented (SH gave valid proxy & proxy holder is present at the meeting)
If a share is present for any issue at the meeting, it counts towards the quorum for the entire meeting
Example: Joe attends the first 10 minutes of a meeting, voting on issue 1, then leaves to grab lunch and is not present when there’s a vote on issue 2. Joe’s shares are considered present for establishing a quorum for issue 2.
How many shares must be present?
DGCL §216(1): by default, majority of shares entitled to vote
Charter/bylaws can opt out of default, but never less than ⅓<br>
38
Quorum
Who is the shareholder? Example: Board sends SHs notice on June 4 that a SH meeting will take place on August 1. Alice owned a share on June 4, but sold it to Bart on June 10, so on August 1, Bart owns the share.
Q: Who gets to vote the share, Alice or Bart? A: depends on the record date (the date on which the owner is considered entitled to vote & receive notice of an upcoming SH meeting)
Record date is set as part of calling the SH meeting
Suppose the rule is that the record date is the time of the vote
Problem for the firm: who to notify about upcoming SH meeting?
Problem for board & insurgents: who to solicit proxies from?<br>
39
Quorum
Who is the shareholder? Suppose the rule is that the record date is the time the meeting is called
Hypo: Microsoft agrees to merge with Yahoo!, and calls a SH meeting to approve the merger
Microsoft sets May 3rd as the record date (both voting & notice)
Edna owned Microsoft shares until May 5th, when she sold them
She now has no incentive to bother voting, which makes it harder to establish a quorum and get an absolute majority of SHs to approve the merger (even if most SHs who care about MS favor the merger)
And if Edna does vote, she might not vote in the best interest of Microsoft (since she no longer has a stake in the company)
So there are problems with either record date (when meeting is called/when vote is held)<br>
40
Quorum
Who is the shareholder? DGCL §213(a) creates record dates for notice & voting
Owner of a share on record date is entitled to notice
Record date can’t be earlier than the day of the resolution fixing it
No earlier than 60 days before the meeting, no later than 10 days
Board may set separate record date for voting
This mitigates the problem of votes by former SHs
Default record dates
Notice
Day before notice is given to the SHs; If notice was waived by SHs, record date is day before meeting
Voting
Same date as notice record date<br>
41
Quorum
Who is the shareholder? Example
Acme will hold its annual SH meeting on May 1
It sends a notice of the meeting (with the proxy materials) to SHs on March 5 (<60 days but >10 days from meeting date)
If Acme’s board does not decide on a different notice record date, by default the notice record date is March 4
I.e., anyone owning Acme shares on March 4 is entitled to a notice
If Acme’s board does not decide on a different voting record date, by default the voting record date is also March 4
I.e., anyone owning Acme shares on March 4 is entitled to vote
But if the board wants to reduce the problem of voting by former SHs, it can decide on a later voting record date (e.g., April 15)<br>
42
Vote The ‘vote’ element considers the number of votes that need to support a resolution for it to pass
What vote is required to pass?
How to count abstentions & withheld votes?<br>
What vote is required to pass?
How to count abstentions & withheld votes?<br>
43
Vote
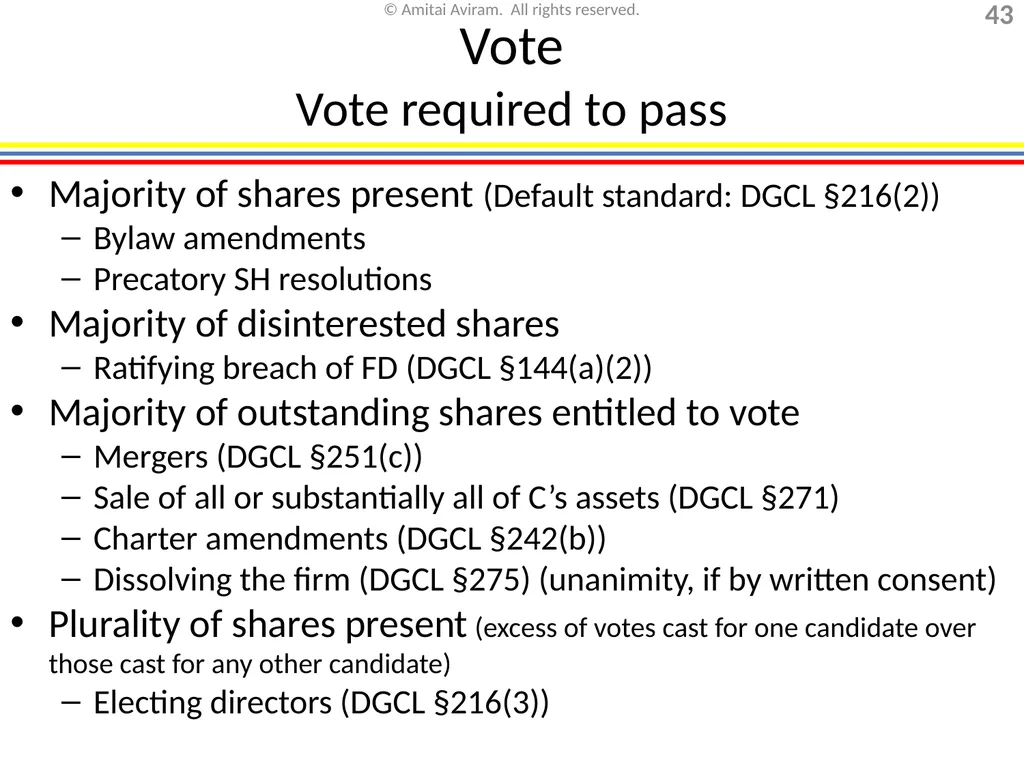
Vote required to pass Majority of shares present (Default standard: DGCL §216(2))
Bylaw amendments
Precatory SH resolutions
Majority of disinterested shares
Ratifying breach of FD (DGCL §144(a)(2))
Majority of outstanding shares entitled to vote
Mergers (DGCL §251(c))
Sale of all or substantially all of C’s assets (DGCL §271)
Charter amendments (DGCL §242(b))
Dissolving the firm (DGCL §275) (unanimity, if by written consent)
Plurality of shares present (excess of votes cast for one candidate over those cast for any other candidate)
Electing directors (DGCL §216(3))<br>
44
Vote
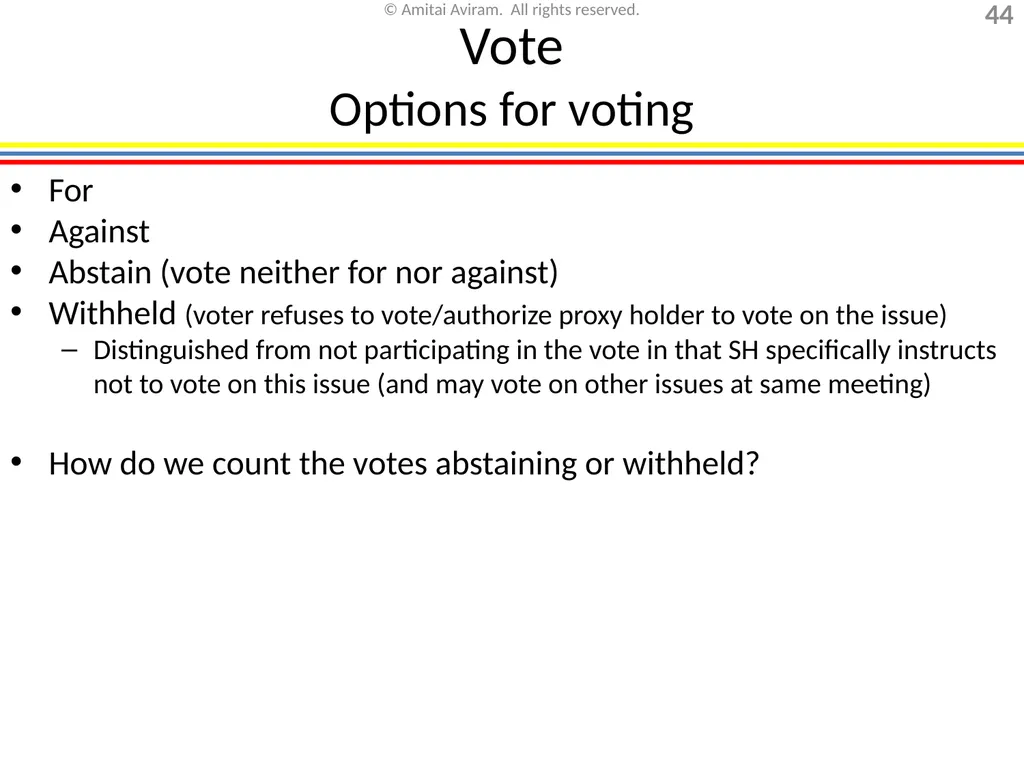
Options for voting For
Against
Abstain (vote neither for nor against)
Withheld (voter refuses to vote/authorize proxy holder to vote on the issue)
Distinguished from not participating in the vote in that SH specifically instructs not to vote on this issue (and may vote on other issues at same meeting)
How do we count the votes abstaining or withheld?<br>
45
Vote
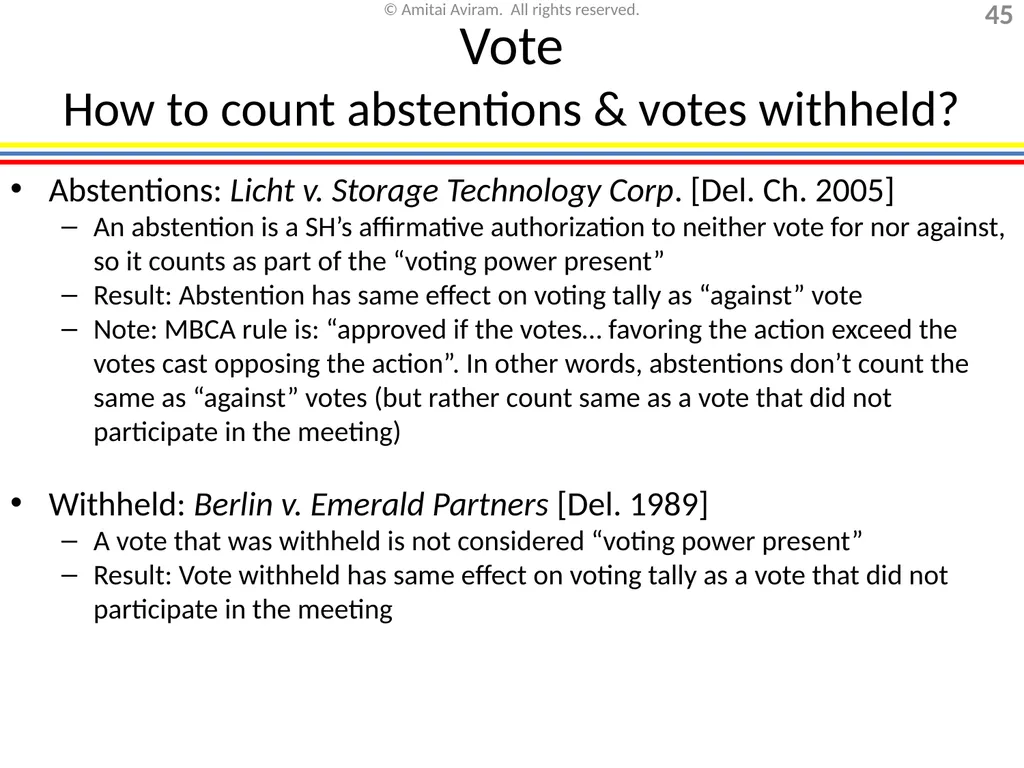
How to count abstentions & votes withheld? Abstentions: Licht v. Storage Technology Corp. [Del. Ch. 2005]
An abstention is a SH’s affirmative authorization to neither vote for nor against, so it counts as part of the “voting power present”
Result: Abstention has same effect on voting tally as “against” vote
Note: MBCA rule is: “approved if the votes… favoring the action exceed the votes cast opposing the action”. In other words, abstentions don’t count the same as “against” votes (but rather count same as a vote that did not participate in the meeting)
Withheld: Berlin v. Emerald Partners [Del. 1989]
A vote that was withheld is not considered “voting power present”
Result: Vote withheld has same effect on voting tally as a vote that did not participate in the meeting<br>
46
Special rules for certain votes
Cumulative voting Under the default voting rules, controller gets to appoint all directors
If C has >50% of votes, all of C’s candidates win
Cumulative voting allows mSHs to be represented on board
The votes for all open director seats are connected, in that SHs allocate their votes among the candidates in any way they wish
Minority SHs can concentrate all of their votes on a single (or a few) candidates, while C has to spread her votes over multiple candidates, giving mSHs a chance to get at least one candidate on the board
Empowers minority representation at the expense of board cohesion<br>
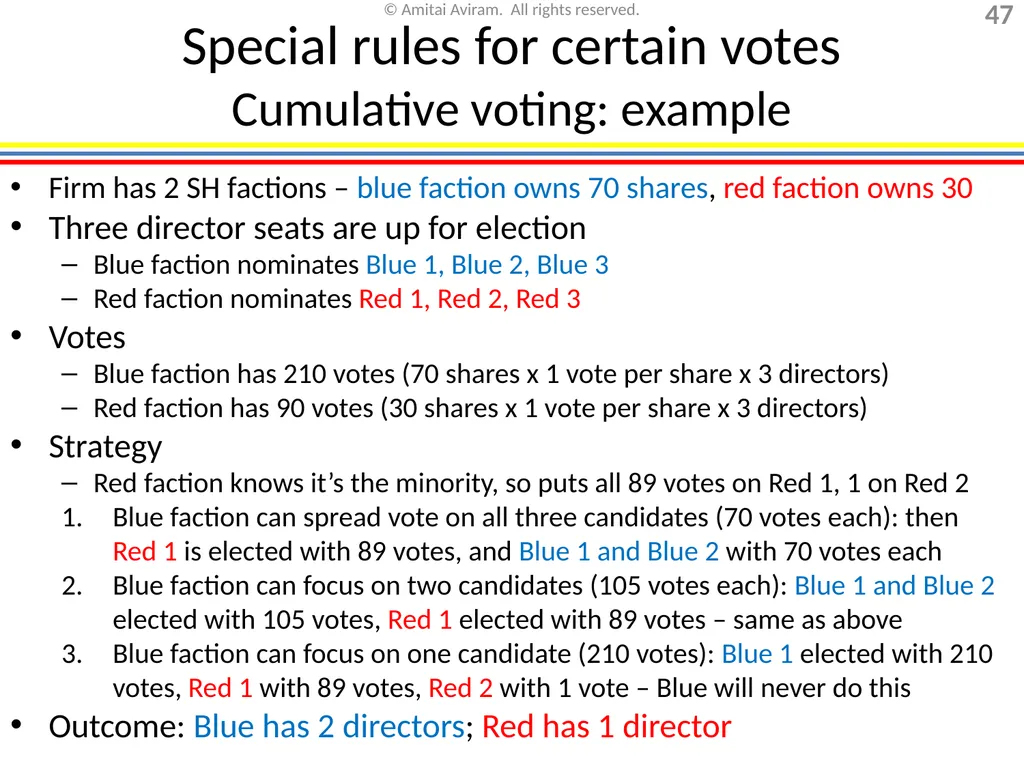
47
Special rules for certain votes
Cumulative voting: example Firm has 2 SH factions – blue faction owns 70 shares, red faction owns 30
Three director seats are up for election
Blue faction nominates Blue 1, Blue 2, Blue 3
Red faction nominates Red 1, Red 2, Red 3
Votes
Blue faction has 210 votes (70 shares x 1 vote per share x 3 directors)
Red faction has 90 votes (30 shares x 1 vote per share x 3 directors)
Strategy
Red faction knows it’s the minority, so puts all 89 votes on Red 1, 1 on Red 2
Blue faction can spread vote on all three candidates (70 votes each): then Red 1 is elected with 89 votes, and Blue 1 and Blue 2 with 70 votes each
Blue faction can focus on two candidates (105 votes each): Blue 1 and Blue 2 elected with 105 votes, Red 1 elected with 89 votes – same as above
Blue faction can focus on one candidate (210 votes): Blue 1 elected with 210 votes, Red 1 with 89 votes, Red 2 with 1 vote – Blue will never do this
Outcome: Blue has 2 directors; Red has 1 director<br>
48
Special rules for certain votes
Staggered (classified) boards U.S. Constitution, Art. I, Sec. 3: Senators are elected for 6-year terms. Every 2 years, ⅓ of Senate seats are open for election.
Reasons: maintaining experience & policy continuity
A corporation may have a staggered (classified) board of directors
DGCL §141(d): Firm may provide in charter or bylaws for a staggered board (composed of 2 or 3 groups)
Main motivation for staggered boards: takeover defense<br>
Reasons: maintaining experience & policy continuity
A corporation may have a staggered (classified) board of directors
DGCL §141(d): Firm may provide in charter or bylaws for a staggered board (composed of 2 or 3 groups)
Main motivation for staggered boards: takeover defense<br>
49
Special rules for certain votes
Class voting in charter amendments When the charter is amended, all SHs vote as a single group
This risks exploitation of SH classes with minority of votes
Example
Acme has two classes of shares. Both classes have the same rights, except that Class B shares have a $2/share dividend preference
Acme issues 200 Class A shares & 100 Class B shares
A year later, Acme’s board brings to a SH vote a proposal to amend the charter to reduce B shares’ dividend preference to $1/share
To prevent this exploitation from happening, DGCL §242(b)(2) requires an additional class vote if the charter amendment would:
Increase or decrease the aggregate number of authorized shares of such class
Increase or decrease the par value of the shares of such class
Alter or change the powers, preferences, or special rights of the shares of such class so as to affect them adversely<br>
50
Special rules for certain votes
Written consent SHs may act by written consent in lieu of a SH meeting
A valid written consent requires participation (“vote”) sufficient for act to pass in a meeting in which all voting power is present
E.g., bylaw amendment requires (by default) majority of voting power present
So in a meeting in which 60% of shares were present, a 30.1% vote is enough
But in a written consent, 50.1% will be necessary (because we assume all voting power was present)<br>
51
Mechanics of SH voting
Support players in the SH voting process Custody & clearance of securities
Acts as record SH, provides proxies to facilitate beneficial SH’s use of SH powers (e.g., voting), settles securities deals
Dominant player: Depository Trust Corporation (DTC)
Proxy & voting services
Distribute proxy materials to beneficial SHs, process proxies, tabulate votes
Dominant player: Broadridge (spun-off from Automatic Data Processing (ADP))
Governance analysis
Proxy advisory firms investigate issues that SHs are asked to vote on & write reports recommending to SHs how to vote on these issues
Dominant players: Institutional Shareholder Services (ISS); Glass, Lewis & Co.<br>
52
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Mechanics of SH voting
Proxy solicitation
Controlling the agenda
Shareholder litigation<br>
Shareholder voting
Mechanics of SH voting
Proxy solicitation
Controlling the agenda
Shareholder litigation<br>
53
Proxy solicitation
Effect of SH apathy on voting From BA: difficult for beneficiaries to govern when they have -
High cost to act collectively
Unequal access to info/expertise
Differing business interests
This is the typical situation with SHs in public firms, which is why we need delegated control (firm managed by the board)
SH voting serves as a check on the board, but it is a form of collective action, so most SHs are likely to be rationally apathetic
E.g., Acme is worth $10B; Joe owns $10,000 of stock (one-millionth of the firm)
Voting for the “right” directors adds $1B to the value of the firm
Joe’s share of the added value is $1,000 – not enough to cover travel & lodging expenses for the SH meeting
If we want mSHs to vote, we need to make it very inexpensive for them to do so
How? Voting by proxy: cheaper participation at the cost of lower quality of deliberation<br>
54
Proxy solicitation
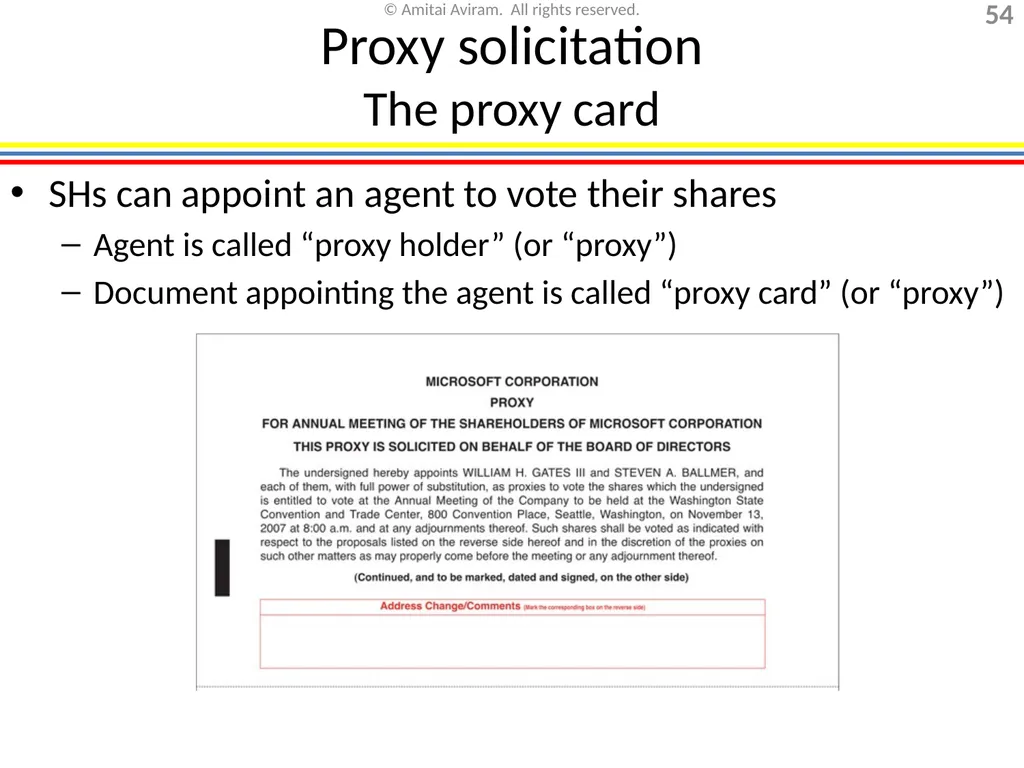
The proxy card SHs can appoint an agent to vote their shares
Agent is called “proxy holder” (or “proxy”)
Document appointing the agent is called “proxy card” (or “proxy”)<br>
Agent is called “proxy holder” (or “proxy”)
Document appointing the agent is called “proxy card” (or “proxy”)<br>
55
Proxy solicitation
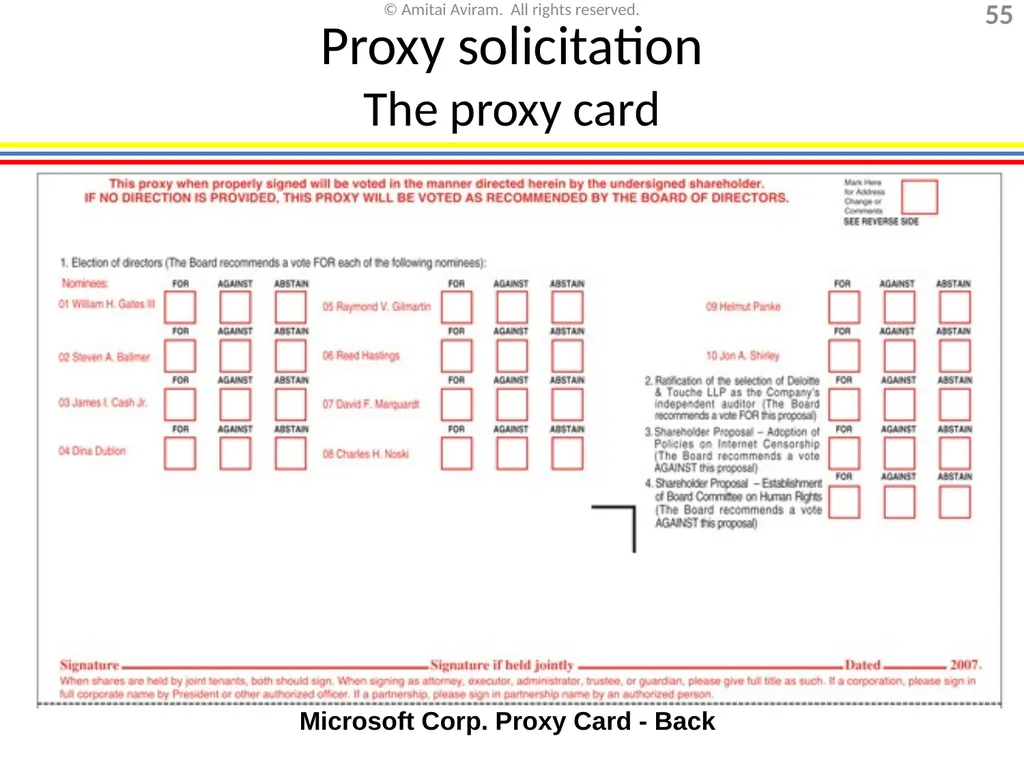
The proxy card Microsoft Corp. Proxy Card - Back<br>
56
Proxy solicitation
Application of §14(a) Exchange Act §14(a): “It shall be unlawful for any person… in contravention of such rules and regulations as the Commission may prescribe… to solicit or to permit the use of his name to solicit any proxy or consent or authorization in respect of any [registered security]”
§14(a) relies on SEC rules to provide it with content
Applies only to registered securities
Applies only to solicitations<br>
§14(a) relies on SEC rules to provide it with content
Applies only to registered securities
Applies only to solicitations<br>
57
Proxy solicitation
Application of §14(a) – “solicitation” Rule 14a-1(l)(1): “Solicitation” includes
Request for a proxy
Whether or not accompanied by or included in a form of proxy
Request to execute/not to execute/to revoke a proxy
Furnishing a form of proxy or other communication to security holders under circumstances reasonably calculated to result in procurement, withholding or revocation of a proxy
Rules 14a-1(l)(2) & 14a-2 exempt certain activities from the definition of “solicitation” or from some or all of the SEC rules regarding solicitations<br>
58
Proxy solicitation
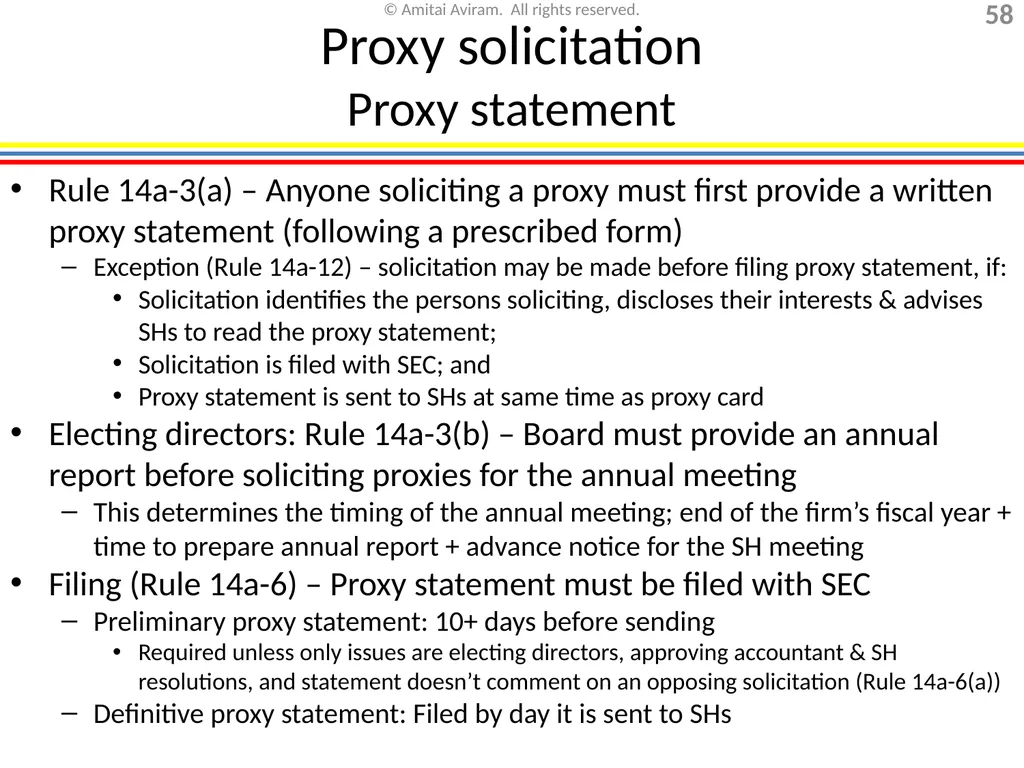
Proxy statement Rule 14a-3(a) – Anyone soliciting a proxy must first provide a written proxy statement (following a prescribed form)
Exception (Rule 14a-12) – solicitation may be made before filing proxy statement, if:
Solicitation identifies the persons soliciting, discloses their interests & advises SHs to read the proxy statement;
Solicitation is filed with SEC; and
Proxy statement is sent to SHs at same time as proxy card
Electing directors: Rule 14a-3(b) – Board must provide an annual report before soliciting proxies for the annual meeting
This determines the timing of the annual meeting; end of the firm’s fiscal year + time to prepare annual report + advance notice for the SH meeting
Filing (Rule 14a-6) – Proxy statement must be filed with SEC
Preliminary proxy statement: 10+ days before sending
Required unless only issues are electing directors, approving accountant & SH resolutions, and statement doesn’t comment on an opposing solicitation (Rule 14a-6(a))
Definitive proxy statement: Filed by day it is sent to SHs<br>
59
Proxy solicitation
Additional §14(a) Rules SH proposals: Rule 14a-8 requires, under certain circumstances, that the board include in its own proxy materials proposals that a SH wants to vote on in the SH meeting
We will address this rule when we discuss controlling the SH meeting agenda
Fraud: Rule 14a-9 prohibits false or misleading statements in connection with soliciting proxies
We will address now how Rule 14a-9 is enforced<br>
We will address this rule when we discuss controlling the SH meeting agenda
Fraud: Rule 14a-9 prohibits false or misleading statements in connection with soliciting proxies
We will address now how Rule 14a-9 is enforced<br>
60
Proxy solicitation
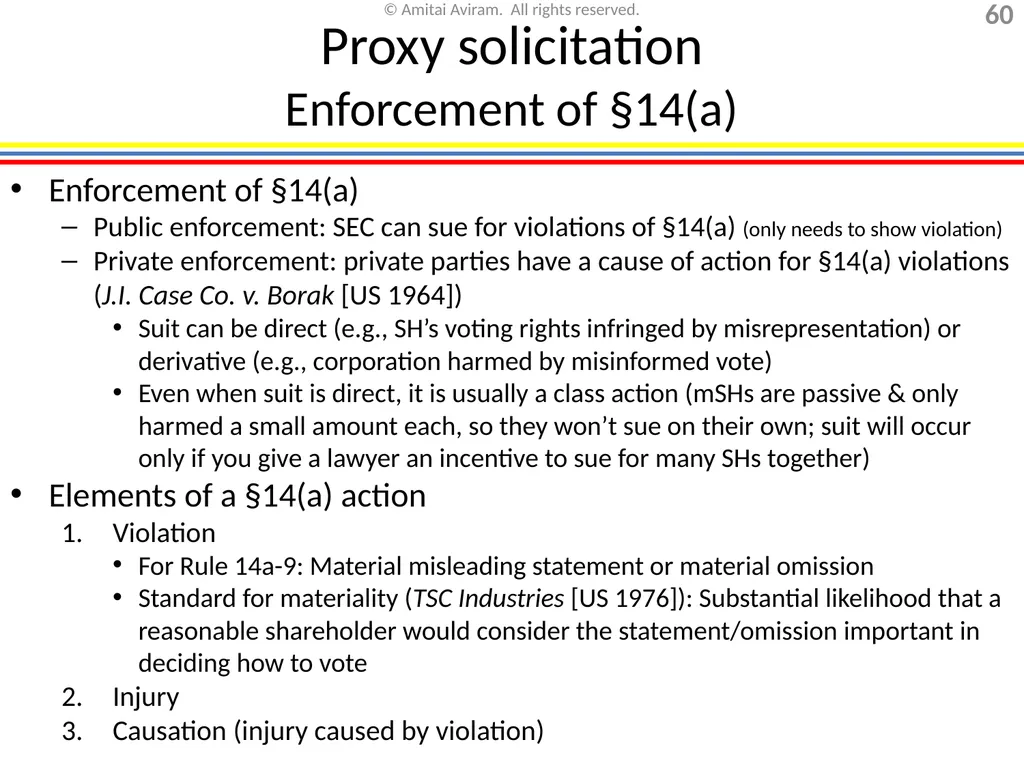
Enforcement of §14(a) Enforcement of §14(a)
Public enforcement: SEC can sue for violations of §14(a) (only needs to show violation)
Private enforcement: private parties have a cause of action for §14(a) violations (J.I. Case Co. v. Borak [US 1964])
Suit can be direct (e.g., SH’s voting rights infringed by misrepresentation) or derivative (e.g., corporation harmed by misinformed vote)
Even when suit is direct, it is usually a class action (mSHs are passive & only harmed a small amount each, so they won’t sue on their own; suit will occur only if you give a lawyer an incentive to sue for many SHs together)
Elements of a §14(a) action
Violation
For Rule 14a-9: Material misleading statement or material omission
Standard for materiality (TSC Industries [US 1976]): Substantial likelihood that a reasonable shareholder would consider the statement/omission important in deciding how to vote
Injury
Causation (injury caused by violation)<br>
61
Proxy solicitation
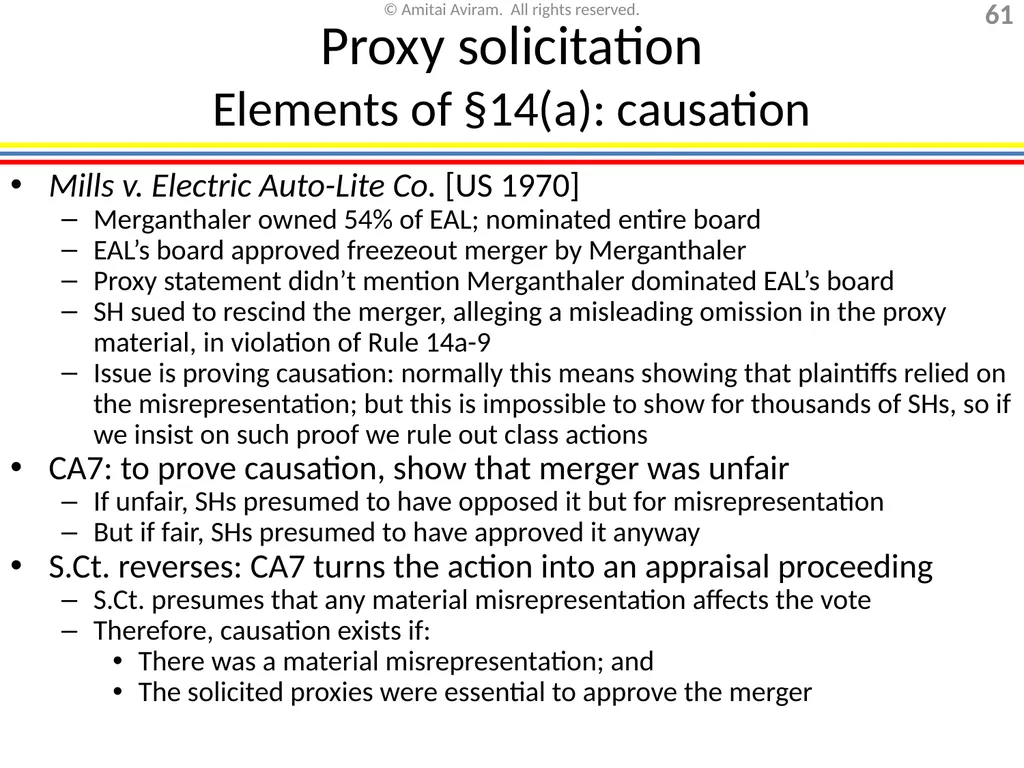
Elements of §14(a): causation Mills v. Electric Auto-Lite Co. [US 1970]
Merganthaler owned 54% of EAL; nominated entire board
EAL’s board approved freezeout merger by Merganthaler
Proxy statement didn’t mention Merganthaler dominated EAL’s board
SH sued to rescind the merger, alleging a misleading omission in the proxy material, in violation of Rule 14a-9
Issue is proving causation: normally this means showing that plaintiffs relied on the misrepresentation; but this is impossible to show for thousands of SHs, so if we insist on such proof we rule out class actions
CA7: to prove causation, show that merger was unfair
If unfair, SHs presumed to have opposed it but for misrepresentation
But if fair, SHs presumed to have approved it anyway
S.Ct. reverses: CA7 turns the action into an appraisal proceeding
S.Ct. presumes that any material misrepresentation affects the vote
Therefore, causation exists if:
There was a material misrepresentation; and
The solicited proxies were essential to approve the merger<br>
62
Proxy solicitation
Elements of §14(a): causation What about a situation where solicited proxies are not essential to approve the merger?
Virginia Bankshares, Inc. v. Sandberg [US 1991]
VBI owned 85% of a bank & executed freezeout merger
Merger required approval by vote of 2/3 of the SHs
Since VBI owned 85% it didn’t need to solicit proxies, but did
S.Ct.: Even if there was a misleading statement in the proxy materials, plaintiff can’t show causation because transaction would have been approved even without the proxies<br>
63
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Mechanics of SH voting
Proxy solicitation
Controlling the agenda
Proxy contests
Proxy access
Shareholder proposals
Shareholder litigation<br>
Shareholder voting
Mechanics of SH voting
Proxy solicitation
Controlling the agenda
Proxy contests
Proxy access
Shareholder proposals
Shareholder litigation<br>
64
Controlling the agenda
The self-perpetuating board Acme’s directors are Larry, Curly & Moe (each owns 1% Acme’s shares)
Sarah, who owns 4%, disagrees with the way LCM manage Acme & wants to replace them
Sarah launches a campaign against LCM, urging SHs to vote against them
She is successful; of the 93% not owned by Sarah or LCM (SHs who will vote by proxy), 66% vote against LCM on their proxy cards; 27% vote in favor of LCM
Outcome: LCM get 30 votes in favor, 70 votes against: they are elected because they have a plurality of the votes (DGCL §216(3))<br>
65
Controlling the agenda
The self-perpetuating board Suppose Acme has majority voting for directors: LCM election fails
But directors hold office until successor is elected (DGCL §141(b)), so LCM stay
If Curly dies or resigns, board can appoint a replacement director (DGCL §223(1))
Suppose Sarah asks SHs to boycott (not sign the board’s proxy card)
If successful, outcome is no quorum (only 30% of shares represented), so no new directors elected. Again, LCM stay in office.
Sarah needs a valid meeting (w/quorum), in which other candidates are proposed
Meeting showdown: Sarah shows up at SH meeting
Sarah wants the meeting to vote on her candidates: Alvin, Simon & Theodore
To do this, she must first amend the SH meeting agenda to vote on them
At the meeting, Sarah moves to amend agenda & vote on electing AST as directors. LCM vote against the amendment their 3% + the 93 shares to which they hold proxies. Motion is defeated 96-4.
Agency law: proxy holders may use discretionary authority to vote the shares on issues on which they were not instructed how to vote<br>
66
Controlling the agenda
What can a SH do? To replace the board, it’s not enough to have sufficient SH votes; Sarah needs to control the SH meeting agenda
Ton control the agenda, Sarah needs a presence on proxies
Proxy contest: solicit from other SHs proxies to vote their shares on the desired issue or for the desired candidate
Proxy access: ask the board to include the desired issue/candidate on the agenda (and on the board’s proxy card)<br>
Ton control the agenda, Sarah needs a presence on proxies
Proxy contest: solicit from other SHs proxies to vote their shares on the desired issue or for the desired candidate
Proxy access: ask the board to include the desired issue/candidate on the agenda (and on the board’s proxy card)<br>
67
Controlling the agenda
Proxy contest Proxy contests are expensive
Example: In May 2009 Pershing Square launched a proxy contest to appoint its nominees to the board of Target
Estimated cost to Pershing Square: $15M
Each additional mailing to SHs cost $1.6M (FT, May 11, 2009)
Insurgents don’t capture all the value from the contest
Suppose that a proxy contest cost Sarah $15M, and electing AST instead of LCM will increase Acme’s value by $100M
Sarah’s profit from the change: $4M (4% of $100M)
But Sarah bears the entire $15M cost
Sarah can’t get other SHs who agree with her to share the costs, because of the collective action problem. For each SH:
If others don’t pay – why should I be the sucker?
If others pay more than enough – I don’t need to pay
If others pay but not enough – lose your money for nothing<br>
68
Controlling the agenda
Proxy contest Should the firm be required to reimburse proxy contest costs?
Suppose that Sarah doesn’t have a better strategy, but she launches a proxy contest anyway
Suppose also that the proxy contest costs Acme $15M, and Sarah another $15M (if uncontested, cost to Acme is $10M)
If Sarah wins, she gets control of Acme (and gets reimbursed)
If she loses, she doesn’t pay anything (expenses are reimbursed), and Acme might pay her up to $20M to withdraw from the contest, in order to save Acme the costs of the proxy contest ($30M-10M)
So Sarah has an incentive to always contest the board (to extort a side payment), even if she doesn’t have a better strategy<br>
69
Controlling the agenda
Proxy contest No affirmative right to be reimbursed contest costs
But firm can authorize a reimbursement, if:
Contest involved a question of policy, not personnel; and
Expenses are reasonable in amount & reasonably necessary to inform SHs
Reimbursing insurgents
If insurgents won, same rules as reimbursing incumbents
Case law suggests SHs need to authorize insurgent reimbursement
If insurgents lost, same rules but board is unlikely to authorize reimbursement, or bring it to SH vote
DGCL §113: Bylaws may create other reimbursement arrangements<br>
70
Controlling the agenda
Proxy access Ask board to include the issue on the agenda (& on proxy card)
Such requests are typically regulated by an advance notice bylaw
Bylaw specifying how SHs can add issues to the agenda
Such bylaws often restrict which SHs can do so & requires SHs to disclose info beyond federal securities laws requirements
JANA v. CNet [Del.Ch. 2008]
Ambiguity in these bylaws is interpreted in favor of SHs’ electoral rights
Void if it unduly restrict SH franchise or applied inequitably (rarely happens; inquiry is very fact-specific)
When is the board forced to include an issue on the proxy card?
Electing directors (proxy access) – limited access
DGCL §112: Bylaws may contain a proxy access provision, allowing SHs to nominate their candidates for directors on the board’s proxy card, and create certain limitations on this right
Other SH decisions (SH proposals) – broader access
Why distinguish electing directors from other decisions? Because judges don’t want to intervene in takeover battles & tip balance of power in favor of hostile acquirers (will explain why SHs might want board to block acquisitions in Section 2a3 “M&A dance”)<br>
71
Controlling the agenda
SH proposals Rule 14a-8: When must board include SH proposal on its proxy?
Qualifying SHs
Own at least $2K or 1% of shares
Owned shares for at least 1 year & hold the shares through the date of the SH meeting
Submitted no more than 1 proposal per SH meeting
SH or her agent must appear at meeting to present proposal
Proposal (including supporting statement) may not exceed 500 words
Firm may write in proxy statement an objection to the SH proposal<br>
72
SH proposals
Procedure for exclusion Rule 14a-8(i) allows firm to exclude certain proposals
Procedure for exclusion – minimum requirements
Firm must notify SH of defect within 14 days (unless defect cannot be remedied – e.g., submitting proposal after deadline); SH then has 14 days to respond
Firm must notify SEC (& copy SH) of intent to exclude a proposal at least 80 days before filing the definitive proxy statement
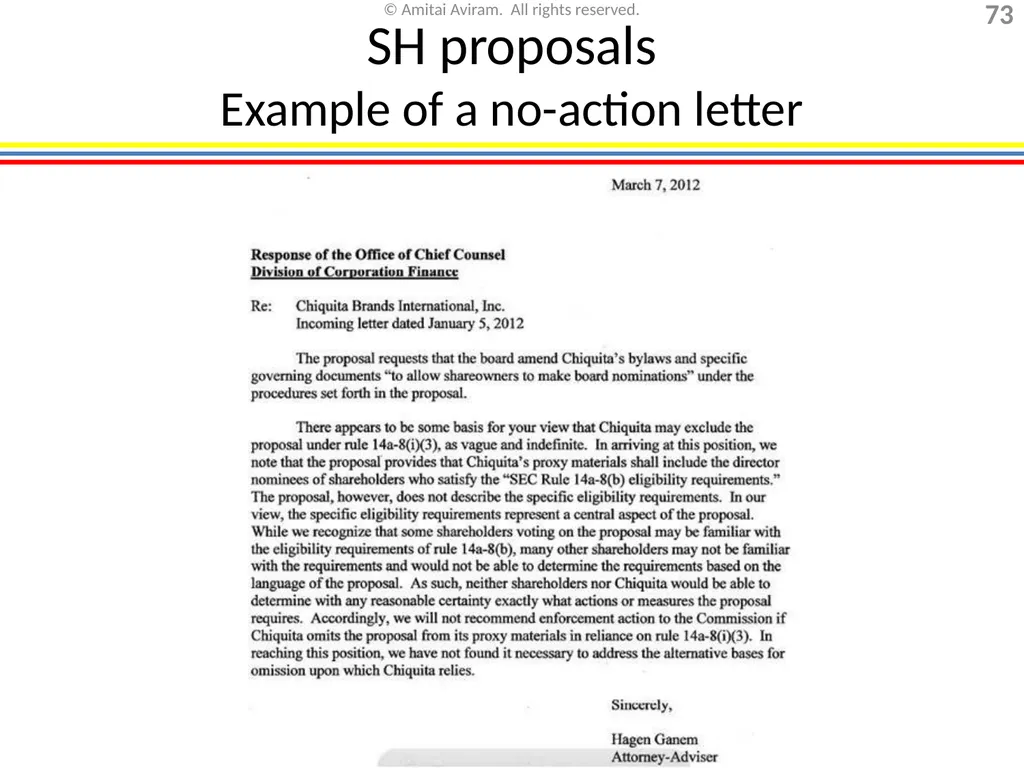
When firm notifies SEC, it typically requests a no-action letter in which SEC’s staff states that based on information provided, it doesn’t intend to challenge exclusion
If either side doesn’t like the outcome, they can appeal to the SEC commissioners
Letter doesn’t prevent SHs from suing in court, nor binds court if SHs sue
Practice point: when considering whether a proposal is excludable, look not only at caselaw, but also at prior no-action letters<br>
73
SH proposals
Example of a no-action letter<br>
74
SH proposals
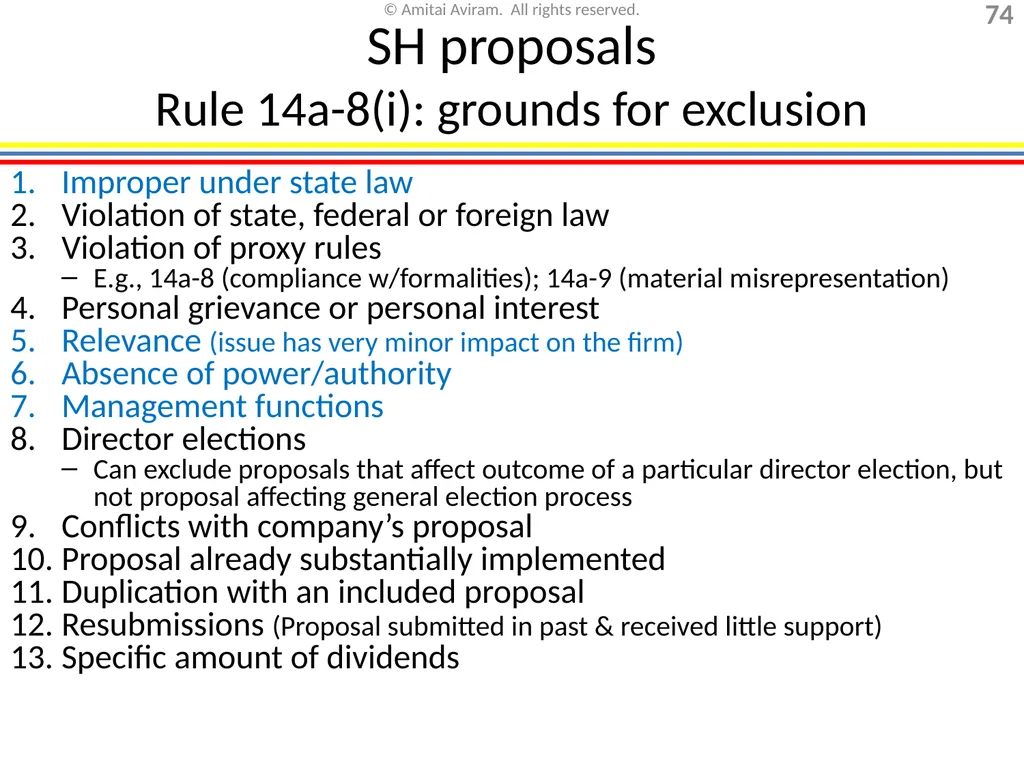
Rule 14a-8(i): grounds for exclusion Improper under state law
Violation of state, federal or foreign law
Violation of proxy rules
E.g., 14a-8 (compliance w/formalities); 14a-9 (material misrepresentation)
Personal grievance or personal interest
Relevance (issue has very minor impact on the firm)
Absence of power/authority
Management functions
Director elections
Can exclude proposals that affect outcome of a particular director election, but not proposal affecting general election process
Conflicts with company’s proposal
Proposal already substantially implemented
Duplication with an included proposal
Resubmissions (Proposal submitted in past & received little support)
Specific amount of dividends<br>
75
SH proposals
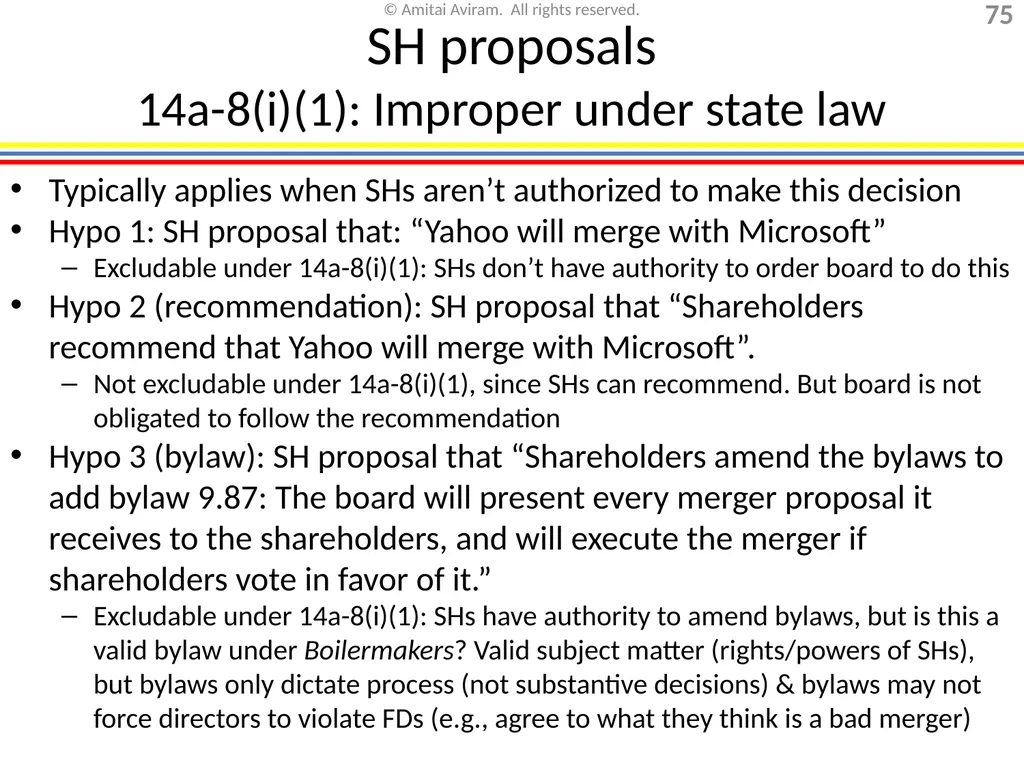
14a-8(i)(1): Improper under state law Typically applies when SHs aren’t authorized to make this decision
Hypo 1: SH proposal that: “Yahoo will merge with Microsoft”
Excludable under 14a-8(i)(1): SHs don’t have authority to order board to do this
Hypo 2 (recommendation): SH proposal that “Shareholders recommend that Yahoo will merge with Microsoft”.
Not excludable under 14a-8(i)(1), since SHs can recommend. But board is not obligated to follow the recommendation
Hypo 3 (bylaw): SH proposal that “Shareholders amend the bylaws to add bylaw 9.87: The board will present every merger proposal it receives to the shareholders, and will execute the merger if shareholders vote in favor of it.”
Excludable under 14a-8(i)(1): SHs have authority to amend bylaws, but is this a valid bylaw under Boilermakers? Valid subject matter (rights/powers of SHs), but bylaws only dictate process (not substantive decisions) & bylaws may not force directors to violate FDs (e.g., agree to what they think is a bad merger)<br>
76
SH proposals
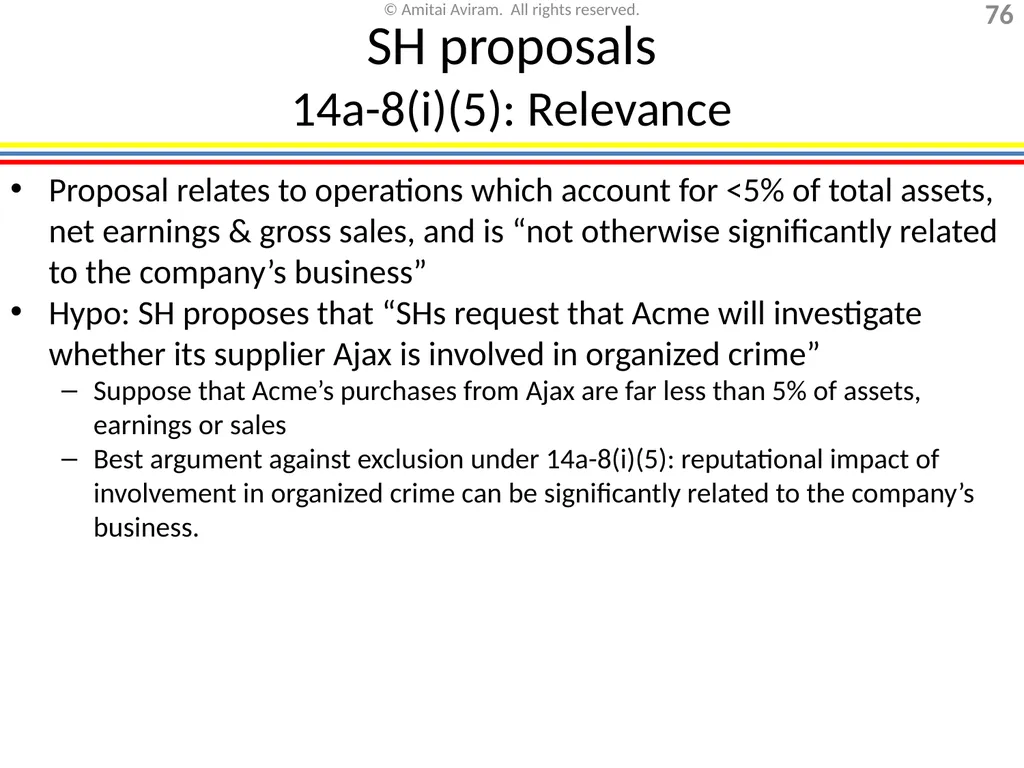
14a-8(i)(5): Relevance Proposal relates to operations which account for <5% of total assets, net earnings & gross sales, and is “not otherwise significantly related to the company’s business”
Hypo: SH proposes that “SHs request that Acme will investigate whether its supplier Ajax is involved in organized crime”
Suppose that Acme’s purchases from Ajax are far less than 5% of assets, earnings or sales
Best argument against exclusion under 14a-8(i)(5): reputational impact of involvement in organized crime can be significantly related to the company’s business.<br>
77
SH proposals
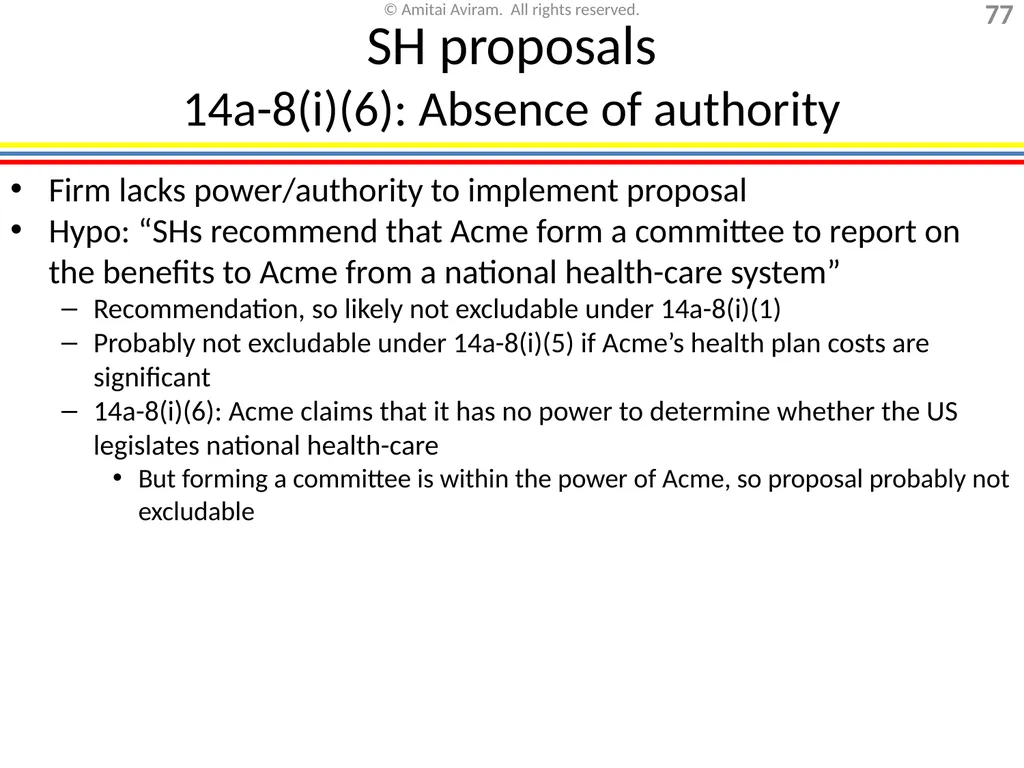
14a-8(i)(6): Absence of authority Firm lacks power/authority to implement proposal
Hypo: “SHs recommend that Acme form a committee to report on the benefits to Acme from a national health-care system”
Recommendation, so likely not excludable under 14a-8(i)(1)
Probably not excludable under 14a-8(i)(5) if Acme’s health plan costs are significant
14a-8(i)(6): Acme claims that it has no power to determine whether the US legislates national health-care
But forming a committee is within the power of Acme, so proposal probably not excludable<br>
78
SH proposals
14a-8(i)(7): Management functions Proposal deals with a matter relating to the firm’s ordinary business operations
Example (based on Austin v. ConEd)
“SHs recommend that Acme offer employees a more generous retirement plan”
Court finds this excludable under 14a-8(i)(7)
Example (social/political issues)
“SHs recommend that Acme will add sexual orientation to its non-discrimination policy”
Acme claims employment policies are part of its ordinary business operations; SHs claim it’s a social policy issue that goes beyond ordinary business
In 1992, SEC sides with the firm (Cracker Barrel), in 1998 SEC reverses course and sides with SHs; trend is towards less exclusion of social issue proposals<br>
79
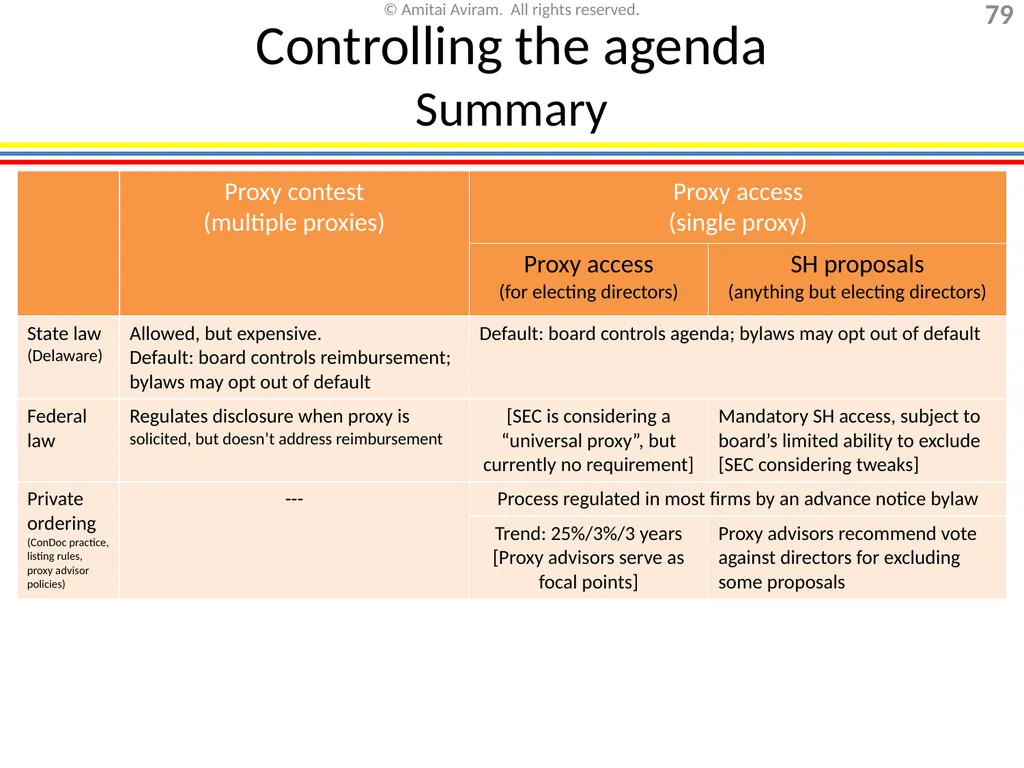
Controlling the agenda
Summary<br>
80
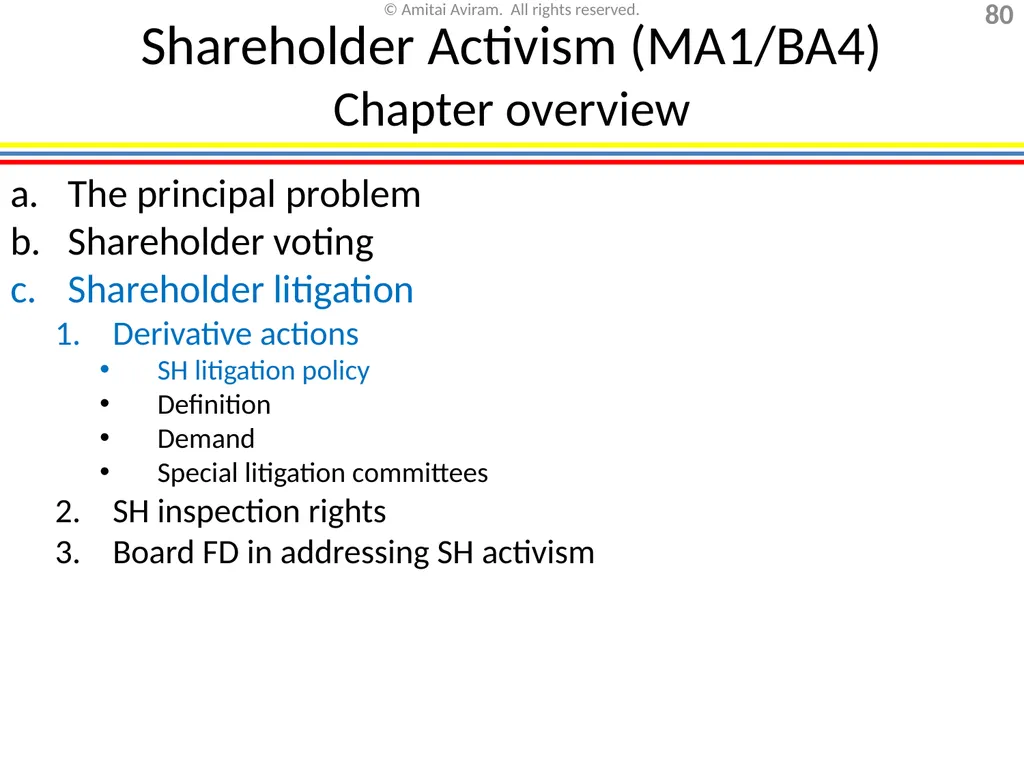
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition
Demand
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition
Demand
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
81
Derivative actions
Review of litigation process Before we discuss derivative actions, I want to remind you of some material from Civil Procedure: aspects of the litigation process that are most relevant for this course
Stages of litigation
Preliminaries
Pleadings
Pre-trial
Trial
Post-trial<br>
Stages of litigation
Preliminaries
Pleadings
Pre-trial
Trial
Post-trial<br>
82
Review of litigation process
Preliminaries Choice of law
The “internal affairs doctrine” provides that the internal affairs of a firm (disputes between the firm, corporate actors & SHs) are governed by the law of the state of incorporation (McDermott Inc. v. Lewis [Del. 1987])
Jurisdiction
Del. Court of Chancery has jurisdiction “to hear and determine all matters and causes in equity” (10 Del. C. 341), and doesn’t have jurisdiction “to determine any matter wherein sufficient remedy may be had by common law, or statute [before another jurisdiction]” (10 Del. C. 342)
Venue
Courts outside Delaware may have jurisdiction over SH litigation of Delaware corporations; in recent years, Delaware has been losing market share in SH litigation of Delaware corporations.
In response, companies have started to adopt forum selection bylaws directing disputes to Delaware courts<br>
83
Review of litigation process
Pleadings Complaint
Plaintiff’s complaint commences the lawsuit; must allege:
Jurisdiction
Claim (facts showing that plaintiff is entitled to relief)
Relief (a demand for an appropriate remedy)
Provisional remedies
Plaintiff can ask judge for immediate (provisional) remedies when waiting for a post-trial remedy would cause irreparable harm
TRO (temporary restraining order): issued before opponent can respond
Preliminary injunction: issued after opponent responds (but before trial)
Standard (for both): (a) reasonable probability of success on the merits; (b) reasonable likelihood moving party will suffer irreparable harm absent the provisional remedy & that harm outweighs harm to non-moving party from granting the provisional remedy<br>
84
Review of litigation process
Pleadings Pre-answer motions (motion to dismiss)
Can be based on procedural flaw (lack of jurisdiction, improper venue, faulty process or service) or substantive flaw (failure to state a claim)
Standard for dismissal for failure to state a claim (Rule 12(b)(6))
Federal courts: “a complaint must contain sufficient factual matter, accepted as true, to state a claim to relief that is plausible on its face” (Twombly [US 2007], Iqbal [US 2009])
Delaware: complaint dismissed for failing to state a claim only if, accepting plaintiff’s factual allegations as true, “plaintiff would not be entitled to recover under any reasonably conceivable set of circumstances” (Central Mortgage [Del. 2011])
Non-moving party’s well-pled allegations are accepted as true, and factual inferences are made in light most favorable to non-moving party
Answer
Defendant responds to complaint, including asserting defenses, counter-claims (against plaintiff) & joinder (requesting that other necessary parties be included in the litigation)
Post-pleading motions (motion for judgment on the pleadings)
Rule 12(c): granted if pleadings fail to reveal existence of any disputed material fact & movant is entitled to judgment as a matter of law
Same standard as a motion to dismiss for failure to state a claim
Defendant more likely to use a Rule 12(b)(6) motion (than a 12(c) motion) – answering limits defendant’s future arguments<br>
85
Review of litigation process
Later stages of litigation Pre-trial: Discovery
Initial disclosures (info on witnesses, documents & objects that party may use to support its claims or defenses; computation of damages; insurance information)
Discretionary discovery (e.g., interrogatories, depositions, requests for producing evidence)
Pre-trial: Motion for summary judgment
No genuine dispute as to any material fact, and the moving party is entitled to a judgment as a matter of law
Genuine dispute: if a rational factfinder could rule in favor of non-moving party
Material fact: if fact could affect the outcome of the lawsuit
Factual inferences are made in light most favorable to non-moving party
Trial
No jury trials in Delaware Court of Chancery (it is an equity court)
Post-trial
Post-trial motions, enforcement of judgment, appeal<br>
86
Review of litigation process
Why do we have class actions? When a party inflicts a small amount of harm on a large number of parties, individual lawsuits aren’t a strong deterrent
E.g., a store illegally overcharges each of its 1M customers $1/month over two years (total benefit for store: $24M)
Total cost for each customer: $24 (not enough to hire a lawyer to sue)
This is a common problem in SH litigation & especially in derivative actions
Each SH has a small stake in the firm, so directors can steal $24M from the firm & it won’t make sense for each of firm’s 1M SHs to sue
Solution: class actions
Class actions allow an individual plaintiff to sue on behalf of all persons with the same cause of action, and in return plaintiff is reimbursed the legal expenses incurred in the class action (sort of an “involuntary agency”)
When a SH sues to vindicate a cause of action belonging to the firm, it is called a derivative action. This is similar to a class action for all SHs, except that litigation involves a single cause of action belonging to the firm, not many identical causes of action each belonging to an individual plaintiff.<br>
87
Litigation process: policy
Key theme about litigation procedure Litigation outcome is often decided at the pleading stage
Most SH litigation imposes discovery/trial costs disproportionately on firm
Firm’s reputation harmed by litigation; plaintiff usually doesn’t have a reputation to risk
Usually firm/actors can’t counterclaim against SH (SH’s only cost of losing is attorney’s fees)
Typically firm/actors can’t impose significant discovery costs on SH
Firm has time-sensitive events that can be thwarted if delayed by litigation (M&A deals, IPOs)
Firm will settle a case if costs less than their litigation costs
Result: If firm can’t get a dismissal at pleadings stage, it will likely settle the case on terms favorable to the plaintiff
So motion to dismiss has huge importance. In this section we will discuss plaintiff’s ability to survive it against two challenges:
Standing (cause of action belongs to firm, not SHs): derivative actions
Factual basis (insufficient facts to support legal cause of action): SH inspection<br>
88
Litigation process: policy
The agent problem… again Dispersed ownership -> SH apathy
Solution, in day to day operating of firm: Board of directors
But how to keep the board accountable?
SH voting
SH litigation
SH apathy comes back in SH voting
Proxy voting addresses ability to vote, but board control of agenda revives the problem
Solution: activist SHs (plus laws empowering small SHs in voting)
Will activist SHs also solve agent problem in SH litigation?
No. The stakes in most SH litigation are too small (given investment & alternatives)
E.g., suppose SH vote forces a hostile merger that boosts stock price of a $100B firm by 20% within a few months, and activist SH has a 5% stake. Activist earns $1B in a few months ($100B x 20% x 5%)
In contrast, litigation can take much longer, and it is unlikely to result in a recovery of $20B for the company (or in attorney fees of $1B for the activist)
So who can solve SH apathy in SH litigation?<br>
89
Litigation process: policy
Who solves SH apathy in SH litigation? Tooley [Del. 2004]: Credit Suisse acquires DLJ (investment bank)
Credit Suisse buys from AXA (owner of 71% of DLJ) its DLJ shares
Credit Suisse launches a tender offer for the remaining 29%
DLJ merges with Credit Suisse subsidiary (freezeout merger)
The tender offer (step 2)
Tender offer to expire after 20 days, but extension is allowed by agreement between DLJ & Credit Suisse
DLJ & Credit Suisse agree on additional 22-day extension
Eventually, tender offer closes successfully & freezeout merger takes place
The lawsuit
Tooley (a former DLJ SH) challenges the 22-day extension of the tender offer
Demands the interest he would have received had the tender offer closed 22 days earlier<br>
90
Litigation process: policy
Who solves SH apathy in SH litigation? Why does Tooley bother suing?
Interest rate Tooley could have received on his money in Oct.-Nov. 2000: 6.55% [Avg. interest rate on a 1-month CD in October 2000]
For 22 days, this equals ~0.39%
If Tooley is a small SH owning $10,000 of DLJ stock, he’s suing for $39.48
With $39.48 you can hire an experienced attorney (20+ yrs.) for 6 minutes, 14 seconds; or hire an inexperienced attorney (fresh out of law school) for 13’, 10” [03-04 Laffey Matrix, U.S. Attorney’s Office, District of Columbia]
Even if Tooley is a (large) activist SH owning 5% of DLJ ($575M of DLJ stock, since DLJ was bought for $11.5B), he’s suing for $2.27M
That’s a lousy return on a $575M investment, especially since it requires continuing to hold on to the stock during litigation
Clearly the SH plaintiffs are not behind this lawsuit. So who is? Plaintiff’s lawyer.<br>
91
Litigation process: policy
Who solves SH apathy in SH litigation? Class actions enlist lawyers as law enforcers, when SHs & government can’t do the job adequately
Why does plaintiff’s lawyer find it profitable, when activist SH didn’t?
Recall, our hypothetical activism in voting yielded the activist $1B in a few months; most SH litigation yields fees in the hundreds of thousands to few millions, likely over a longer time period.
But SH activism in voting requires a big capital expenditure – e.g., owning 5% of the shares of a $100B firm costs $5B
In contrast, the capital expenditure for litigation is much smaller, and is mostly in the form of labor (lawyer’s efforts), so lawyers without much cash to invest find this business model profitable
In SH litigation, this reduces SHs vs. management agency costs but creates SHs vs. lawyer agency costs<br>
92
Litigation process: policy
Dysfunctional outcomes In re Oracle Corp. Derivative Litigation [Cal. Super. 2005]
Larry Ellison, CEO of software giant Oracle Corp., allegedly engaged in insider trading, selling some Oracle shares while he knew non-public, disappointing information about Oracle (which ultimately resulted in a 22% drop in share price)
Joseph Tobacco Jr., a lawyer, brings a class action in California on behalf of Oracle SHs. The settlement:
Ellison promises to donate in Oracle’s name $100M over 5 years to a charity of Ellison’s choice (Ellison had already been donating over $30M a year)
Oracle will pay Tobacco’s legal fees of $22.5M
Benefit to Oracle SHs from this settlement?
Settling derivative actions is subject to a judge’s approval
Why would a judge approve a settlement like this one?
Outcome: In Nov. 2005, a San Mateo Superior Court judge approved the settlement, but only after it was modified so that Ellison, rather than Oracle, paid Tobacco’s legal fees<br>
93
Litigation process: policy
Dysfunctional outcomes Why do we see these dysfunctional outcomes?
Guilty defendants may “bribe” plaintiff’s lawyer to extinguish a meritorious suit
Innocent defendants may be extorted by plaintiff’s lawyer to extinguish a frivolous suit
Good faith plaintiff’s lawyer may have preferences that do not represent most SHs’ preferences
E.g., plaintiff’s lawyer may sincerely want Oracle to give more to charity, but this may not be what most SHs want<br>
94
Litigation (sue the lawyers if they do not represent faithfully)
SHs won’t sue; decision to sue lawyers suffers from same collective action problem that justified having class actions in the first place
Exit (allow dissenting SHs not to participate in the suit)
Allowed in many class actions, but not practical in derivative actions because the issue is legal rights of the firm (suit’s outcome affects all SHs; can’t limit the impact to only participating SHs)
Voice (allow SHs to dismiss the suit)
SH review (SH meetings to decide whether to pursue each suit)?
Not feasible: very costly, so extortion problem may become worse
Compromise solution: Board review (as a representative of SHs)
If an informed and independent board makes a business judgment that a derivative suit is not in the firm’s interest, court will not second guess that
Because a SH, not the board, initiates the suit, a process (called a demand on the board) is needed to facilitate board review:
Alert the board to plaintiff’s allegations
Allow the board to make a business judgment whether firm should sue Litigation process: policy Can agency solutions control plaintiff’s lawyer?<br>
95
Litigation process: policy
Derivative actions: why do we care? When an action is derivative (rather than direct), the cause of action belongs to the firm.
Plaintiff SH faces a standing issue that may lead to suit’s dismissal.
But if we only allowed the board to control firm’s causes of action, firm would never enforce causes of action against the board (or those the board favors)
So SHs may bring derivative actions on behalf of the firm, subject to four limitations
Plaintiff is a stakeholder with the right to bring a derivative action
Contemporaneous ownership requirement
Demand requirement
Board’s/SLC’s qualified ability to intervene<br>
96
Litigation process: policy
Implications of action being derivative Plaintiff must have the right to pursue a derivative action
Common SHs – Yes
Preferred SHs – Yes, unless this right was specifically limited in charter or another “appropriate document” [Maginn (Del. Ch. 2010)]
Creditors [Gheewalla (Del. 2007)]: Yes, when firm is insolvent; unclear, when firm is in the “zone of insolvency”; no, in all other situations.
Directors – No (maybe in future if needed to prevent “complete failure of justice”) [Schoon (Del. 2008)]
Plaintiff must satisfy Rule 23.1’s contemporaneous ownership requirement
Suit dismissed unless plaintiff owned shares at time of the alleged wrong & maintained ownership throughout the litigation
E.g., Tooley lost his shares as result of the DLJ merger, so if action is derivative, he lacks standing unless:
Merger was fraudulently designed solely to eliminate standing; or
Merger was merely a “reorganization” that doesn’t affect SHs’ ownership of the enterprise
Plaintiff must satisfy Rule 23.1’s demand requirement, unless demand is futile and therefore excused / Board (or SLC) may exercise business judgment on whether firm should sue
To be explained in the next class<br>
97
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition (Is the action direct?)
Demand
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition (Is the action direct?)
Demand
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
98
Derivative actions
Definition: Is the action direct? Del. Ch. Court Rule 23.1 applies the demand & contemporaneous ownership requirements only to “a derivative action… to enforce a right of a corporation…”
So an action is derivative when the cause of action belongs to the firm
But how do we know if a cause of action belongs to the firm or the SHs?
Delaware test is in Tooley v. DLJ [Del. 2004]<br>
So an action is derivative when the cause of action belongs to the firm
But how do we know if a cause of action belongs to the firm or the SHs?
Delaware test is in Tooley v. DLJ [Del. 2004]<br>
99
Derivative actions
Definition: Is the action direct? Tooley test – whether suit is derivative or direct depends on:
Who suffered the alleged harm – corporation or plaintiff SH individually?
Who would receive the benefit of recovery or other remedy?<br>
Who suffered the alleged harm – corporation or plaintiff SH individually?
Who would receive the benefit of recovery or other remedy?<br>
100
Derivative actions
Definition: Is the action direct? Tooley test – whether suit is derivative or direct depends on:
Who suffered the alleged harm – corporation or plaintiff SH individually?
Tooley endorses test in Agostino v. Hicks [Del.Ch. 2004]: “… [Can plaintiff] prevail without showing an injury to the corporation?”
Who would receive the benefit of recovery or other remedy?<br>
Who suffered the alleged harm – corporation or plaintiff SH individually?
Tooley endorses test in Agostino v. Hicks [Del.Ch. 2004]: “… [Can plaintiff] prevail without showing an injury to the corporation?”
Who would receive the benefit of recovery or other remedy?<br>
101
Derivative actions
Definition: Is the action direct? Tooley test – whether suit is derivative or direct depends on:
Who suffered the alleged harm – corporation or plaintiff SH individually?
Tooley endorses test in Agostino v. Hicks [Del.Ch. 2004]: “… [Can plaintiff] prevail without showing an injury to the corporation?”
Who would receive the benefit of recovery or other remedy?
This prong gives a clear answer when the remedy is monetary damages, but often less clear when injunctive remedies are requested<br>
102
Derivative actions
Definition: Is the action direct? Tooley test – whether suit is derivative or direct depends on:
Who suffered the alleged harm – corporation or plaintiff SH individually?
Tooley endorses test in Agostino v. Hicks [Del.Ch. 2004]: “… [Can plaintiff] prevail without showing an injury to the corporation?”
Who would receive the benefit of recovery or other remedy?
This prong gives a clear answer when the remedy is monetary damages, but often less clear when injunctive remedies are requested
Tooley rejected two old tests:
Whether there was a “special injury” suffered only by some SHs (Lipton)
Presumption that claim is derivative if it affects all SH equally (Bokat)<br>
103
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition (Is the action direct?)
Demand (Effect of an action being derivative)
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition (Is the action direct?)
Demand (Effect of an action being derivative)
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
104
Derivative actions
Implications of action being derivative Plaintiff is a stakeholder with the right to bring a derivative action
Contemporaneous ownership requirement: Plaintiff must have been a SH at time of the alleged wrong & maintained that status throughout the litigation
Demand requirement: SH must ask board to sue before suing derivatively
Facilitates board’s qualified ability to intervene (to keep plaintiff’s lawyer accountable)
In some jurisdictions (e.g., MBCA), demand is universal (must always be made)
In other jurisdictions (e.g., Delaware), demand is excused when it is futile – the differences will be explored in the next sub-section
Board’s/SLC’s qualified ability to intervene<br>
105
Demand
MBCA (universal demand) MBCA §7.42
A demand is required in all derivative actions
SH must not bring suit for 90 days after demand is made, unless irreparable injury would result, or board rejected demand
MBCA §7.44 - Alternatives for review of the demand:
If independent directors constitute a quorum, the demand may be reviewed by the board (but only the independent directors vote)
In all cases, the independent directors may appoint by majority vote a committee of two or more independent directors to review the demand
Upon motion by corporation, court may appoint an independent panel
MBCA §7.44 (continued)
If the reviewing institution determines in good faith, after conducting a reasonable investigation, that the maintenance of the derivative action is not in the best interest of the corporation, the court will dismiss the complaint (without examining the reasonableness of the determination)
Burden of proof as to good faith and reasonable investigation lies on:
SH, if majority of board is independent, or review was by court appointed panel
Corporation, if majority of board is not independent<br>
106
Demand
Delaware (excusable demand) Delaware has a narrower demand requirement: Where the directors cannot be expected to make a fair decision, demand would be futile and is excused
If a demand was made, the directors may reach a decision whether the company should pursue the cause of action
BJR applies to the board decision, unless rebutted<br>
If a demand was made, the directors may reach a decision whether the company should pursue the cause of action
BJR applies to the board decision, unless rebutted<br>
107
Demand
Delaware: litigation strategy Under Del. law, demand must be made unless it is futile
Making a demand is deemed a concession that a demand was required
If demand is made, board’s decision regarding the demand benefits from the BJR, unless it is rebutted
At this point, plaintiff isn’t entitled to discovery, so info on firm must come from public sources & SH inspection rights
Why is this important?
Result: Plaintiff usually loses if demand was made & board rejected it
Harm to plaintiff from foregoing demand?
If demand is required & plaintiff didn’t make the demand, litigation will be stayed while plaintiff makes the demand
Conclusion: Typically, a plaintiff will not make a demand, and instead argue that demand was excused
So, most litigation is about whether demand was futile (rather than whether demand was wrongfully rejected)<br>
108
Demand
Delaware: demand excusal United Food & Commercial Workers Union v. Zuckerberg [Del. 2021]: Courts should ask the following three questions on a director-by-director basis when evaluating allegations of demand futility:
whether the director received a material personal benefit from the alleged misconduct that is the subject of the litigation demand;
whether the director faces a substantial likelihood of liability on any of the claims that would be the subject of the litigation demand; and
whether the director lacks independence from someone who received a material personal benefit from the alleged misconduct that would be the subject of the litigation demand or who would face a substantial likelihood of liability on any of the claims that are the subject of the litigation demand.
If the answer to any of the questions is “yes” for at least half of the members of the demand board, then demand is excused as futile.
Note: Zuckerberg replaced the “reasonable doubt” tests (Aronson and Rales).<br>
109
Demand
Delaware: demand excusal The test for lacking independence (third prong of the Zuckerberg test): Beam v. Stewart (Del. 2004): “a plaintiff must plead facts that would support the inference that… the non-interested director would be more willing to risk his or her reputation than risk the relationship with the interested director.”
Note that under the Zuckerberg test, a director may be independent even if she:
approved the challenged transaction;
was named as a defendant in the derivative action; or
was nominated by the alleged wrongdoer<br>
Note that under the Zuckerberg test, a director may be independent even if she:
approved the challenged transaction;
was named as a defendant in the derivative action; or
was nominated by the alleged wrongdoer<br>
110
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition
Demand
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
Shareholder voting
Shareholder litigation
Derivative actions
SH litigation policy
Definition
Demand
Special litigation committees
SH inspection rights
Board FD in addressing SH activism<br>
111
Special litigation committees
Vulnerability of biased boards Firms get one more chance to dismiss a derivative suit when demand is futile, by forming a Special Litigation Committee
This is because fair decisions that happen to have been made by a conflicted board create attractive targets for strike suits
Firm asks court to apply BJR (i.e., defer) to a decision of an SLC (composed of disinterested directors) that the derivative action lacks merit
Unlike demand futility litigation, in SLC litigation plaintiff is entitled to limited discovery (as to the independence of the SLC members)
Most states simply apply BJR analysis to SLC’s decision
Delaware applies two steps (Zapata Corp. v. Maldonado [Del. 1981])
Quasi-BJR analysis to SLC’s decision
SLC independence & good faith
Reasonable bases for the SLC’s recommendations
Court may apply its own “independent business judgment” as to whether to dismiss the suit<br>
112
Special litigation committees
In re Oracle Deriv. Litig. [Del. Ch. 2003] Plaintiffs allege that four directors of Oracle – Ellison, Henley, Lucas and Boskin - engaged in insider trading
Upon being sued, Oracle appoints an SLC of two new directors (weren’t on the board when alleged events took place)
Garcia-Molina: chairman of Stanford’s computer science department
Grundfest: professor at Stanford law school
Directs Stanford’s director college & the program in law, business and corporate governance.<br>
113
Special litigation committees
Oracle Compensation: $250/hour (below their market price)
To preserve their objectivity, SLC members agreed to give up compensation if court determined that it impaired their impartiality
Advisors’ objectivity
The SLC hires legal counsel (Simpson Thacher) & economists (NERA). Court examines the advisors’ objectivity and finds no problem.
What evidence would taint the advisors’ objectivity?
SLC’s report
SLC interviewed 70 witnesses. Its report was 1,110 pages long. Court finds no problems with the SLC’s investigation procedure
SLC recommends to dismiss the claims<br>
114
Special litigation committees
Oracle Legal analysis (Zapata)
Step 1: Quasi-BJR analysis
SLC members’ independence
SLC members’ good faith
Reasonable bases for the SLC’s recommendations
Step 2: “Independent business judgment”<br>
Step 1: Quasi-BJR analysis
SLC members’ independence
SLC members’ good faith
Reasonable bases for the SLC’s recommendations
Step 2: “Independent business judgment”<br>
115
Special litigation committees
Oracle Ellison Boskin Lucas Garcia-Molina Grundfest SLC members’ independence What the SLC report disclosed:
Boskin is a Stanford Professor
Lucas made certain donations to Stanford, and donated $50,000 to after Grundfest delivered a speech to a Venture Capital Fund in which Lucas’ son is a partner (half the money went to Grundfest’s research account)<br>
Boskin is a Stanford Professor
Lucas made certain donations to Stanford, and donated $50,000 to after Grundfest delivered a speech to a Venture Capital Fund in which Lucas’ son is a partner (half the money went to Grundfest’s research account)<br>
116
Special litigation committees
Oracle Boskin
Taught Grundfest when G was a Ph.D. student
Both Boskin & Grundfest are steering committee members at the Stanford Institute for Economic Policy Research
Lucas
A major donor to Stanford Law School & Stanford Institute for Economic Policy Research
Ellison
Ellison & Oracle make significant contributions to Stanford
But: Ellison’s child applied to Stanford and was rejected
Ellison apparently continued to consider donations to Stanford after this<br>
117
Special litigation committees
Comparing Beam & Oracle Why is the analysis and outcome different? Beam: “…for presuit demand purposes, friendship must be accompanied by substantially more…” Oracle: “Homo sapiens is not merely homo economicus… an array of other motivations exist to influence human behavior… envy… love, friendship, and collegiality.”<br>
118
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Shareholder litigation
Derivative actions
SH inspection rights
Board FD in addressing SH activism<br>
Shareholder voting
Shareholder litigation
Derivative actions
SH inspection rights
Board FD in addressing SH activism<br>
119
SH inspection rights
Purposes SH inspection rights can:
Facilitate SH litigation: getting non-public information that sufficiently substantiates allegations that the complaint survives a motion to dismiss
Facilitate SH voting: getting non-public information that will persuade SHs to support an insurgent in proxy contest (e.g., uncovering info that shows the board did a poor job managing the firm & shouldn’t be re-elected)
Why not give SH an automatic right to access all of the corporation’s info?
Reduce candor in board discussions
May reveal trade secrets
May be used to harass/extort firm (imposing costs on firm)<br>
120
SH inspection rights
DGCL Proper purpose (DGCL §220(b))
SH must make a written demand, presenting a “proper purpose” (i.e., a purpose “reasonably related to such person’s interest as a stockholder”)
Who has BoP whether purpose is proper? (DGCL §220(c))
If SH seeks access to the SH list, BoP on the firm to show that SH does not have a “proper purpose”
If SH seeks access to other corporate records, BoP on the SH to prove “proper purpose”<br>
121
SH inspection rights
Pershing Square v. Ceridian [Del. Ch. 2007] Pershing Square, a hedge fund, is Ceridian’s largest SH (11.3%)
Ackman is its portfolio manager
Comdata is Ceridian’s largest operating subsidiary
Krow is Comdata’s president
Ackman learns that Krow sold Ceridian stock; calls Krow to learn why
How does Ackman know about Krow’s sale of stock?<br>
Ackman is its portfolio manager
Comdata is Ceridian’s largest operating subsidiary
Krow is Comdata’s president
Ackman learns that Krow sold Ceridian stock; calls Krow to learn why
How does Ackman know about Krow’s sale of stock?<br>
122
SH inspection rights
Pershing Square v. Ceridian Krow tells Ackman he’s about to quit because he disagrees with the business strategy pursued by Marinello, Ceridian’s new CEO
Krow wants Comdata spun off
Marinello prefers to keep Comdata & make new acquisitions
Possible motivations for Marinello, Krow and Ackman in choosing between the strategies Gary Krow Kathryn Marinello<br>
Krow wants Comdata spun off
Marinello prefers to keep Comdata & make new acquisitions
Possible motivations for Marinello, Krow and Ackman in choosing between the strategies Gary Krow Kathryn Marinello<br>
123
SH inspection rights
Pershing Square v. Ceridian On the phone, Ackman & Krow discuss Pershing Square running a slate of directors at the upcoming elections
Krow then meets with Ackman at an airport
Tells Ackman which Ceridian SHs supported a Comdata spin-off and would support Ackman’s director slate
Also tells Ackman that he wrote two letters to Ceridian’s board, detailing mismanagement by the previous Ceridian CEO & hinting that the board failed to oversee the CEO
How is the info useful for Pershing’s bid to elect directors?
Previous CEO was terminated & replaced by Marinello, but Krow thinks that the letters damaged his relationship with the board & Marinello was hired with the intention of firing Krow<br>
124
SH inspection rights
Pershing Square v. Ceridian Pershing makes a DGCL §220 demand to receive:
A copy of Ceridian’s current bylaws
SH list
Copies of the two letters Krow mentioned
Pershing cites as its purposes
To communicate with other SHs about board elections
To investigate the suitability of Ceridian’s nominees to serve on the board
Ceridian provides bylaws & SH list; refuses to provide the letters
Claims confidentiality & lack of proper purpose
Court examines stated purposes
Purpose is proper if it is reasonably related to one’s interest as a SH
Communicating with fellow shareholders about board elections
Investigating suitability of directors
Ceridian: This makes every board-level document available for inspection
Court: stating a proper purpose does not automatically grant inspection rights<br>
125
SH inspection rights
Pershing Square v. Ceridian Conditions for SH inspection right:
Written demand from a shareholder (record owner or beneficial owner)
Proper purpose
Stated purpose is proper if it’s reasonably related to one’s interest as a SH
Stated purpose must be SH’s true/primary purpose
SH must have evidence establishing a credible basis for the stated purpose
Proper records
Requested records are necessary & essential for the purpose
[Proper use]
[Safeguards may be imposed to protect confidentiality of the records]
In this case:
Pershing’s stated purposes are proper
But Pershing’s true purpose is improper: finding a legal vehicle to publicly broadcast improperly obtained confidential information<br>
126
Shareholder Activism (MA1/BA4)
Chapter overview The principal problem
Shareholder voting
Shareholder litigation
Derivative actions
SH inspection rights
Board FD in addressing SH activism
Historical background on SH activism
Legal analysis of Board FD in influencing SH voting<br>
Shareholder voting
Shareholder litigation
Derivative actions
SH inspection rights
Board FD in addressing SH activism
Historical background on SH activism
Legal analysis of Board FD in influencing SH voting<br>
127
Board FD in addressing SH activism
Historical background on SH activism What’s so special about the 1980s? Unocal (1985)
Revlon (1986)
Blasius (1988)
Hostile M&A (& the SH activism it requires) only took off in 1980s. Why then? 80s<br>
Revlon (1986)
Blasius (1988)
Hostile M&A (& the SH activism it requires) only took off in 1980s. Why then? 80s<br>
128
Board FD in addressing SH activism
Historical background on SH activism Corporate America in the 1980s
Start a bit earlier…
Post-World War 2 Corporate America
Management as an expertise
Diversification theory
Result: trend towards conglomerates
More predictable profits
But lower profits
Low debt (reliance on reinvested profits)
Bond market primarily used by large, creditworthy firms
Small & less creditworthy firms borrow from banks/customers/suppliers
Firms that can borrow large amounts are a small, elite club
Result: Hostile takeovers are rare. Without the threat of a hostile takeover, SHs have little power to discipline boards.<br>
129
Board FD in addressing SH activism
Historical background on SH activism Corporate America in the 1980s: Trends
Mutual funds become popular
Less demand for investing in conglomerates
Junk bond finance emerges
Don’t need to be a conglomerate to access bond market
“Nobodys” can borrow enough money to take over big, established firms
This breaks up the “gentlemen’s code” that discouraged hostile takeovers…
… Just at a time that out-of-fashion conglomerates are juicy targets for hostile takeovers Fake cover of Fortune magazine, used in the movie Wall Street<br>
130
Board FD in addressing SH activism
Historical background on SH activism Corporate America in the 1980s: Results
Hostile takeovers increase
Conglomerates are broken up
Boards try to preempt potential raiders
Increasing SH profit at the expense of firm stability
Focus on short-term profitability
Long-term plans that depress short-term results invite hostile takeovers
Keeping less cash & borrowing more
Harder to turn quick profit from hostile takeover when company has little cash & much debt
Also, using more borrowed money increases both risk & return of the company From: Financial Times (2/21/09)
Note: By 4/2016, only 2 firms have AAA rating (MSFT, JNJ)<br>
131
Board FD in addressing SH activism
Blasius Indus. v. Atlas Corp. [Del. Ch. 1988] This is the world in which Atlas operates
Atlas is a conglomerate
Owns a variety of businesses; profitability low
Atlas realizes it is a potential takeover target
Weaver (CEO) sells 3 of 5 divisions
Closes domestic Uranium operations
Focuses on gold-mining business
But is Atlas too late?<br>
Atlas is a conglomerate
Owns a variety of businesses; profitability low
Atlas realizes it is a potential takeover target
Weaver (CEO) sells 3 of 5 divisions
Closes domestic Uranium operations
Focuses on gold-mining business
But is Atlas too late?<br>
132
Board FD in addressing SH activism
Blasius Blasius is a private equity firm
Raises money from public by selling junk bonds
Looks for poorly performing firms to buy, fix & sell
Blasius buys 9.1% of Atlas’ common stock
Announces it considers taking control of Atlas
But what more does it want Atlas to do?<br>
Raises money from public by selling junk bonds
Looks for poorly performing firms to buy, fix & sell
Blasius buys 9.1% of Atlas’ common stock
Announces it considers taking control of Atlas
But what more does it want Atlas to do?<br>
133
Board FD in addressing SH activism
Blasius Blasius’ plan for Atlas: Leveraged restructuring
Under the plan, Atlas will sell assets & borrow money (using its assets, such as gold reserves, as collateral). Atlas will then distribute this money as dividends.
Example: Suppose Atlas has $150 in assets & no debt
Atlas sells $50 in assets, then borrows another $90, secured by the remaining assets ($100). Atlas then distributes a dividend of $140.
Atlas now has $100 in assets and $90 in debt<br>
134
Board FD in addressing SH activism
Blasius Atlas drags its feet
Atlas takes a month until it meets with Blasius to hear its plan
Meet on Dec. 2
Atlas doesn’t want to meet again until January
Why is Atlas stalling?<br>
Atlas takes a month until it meets with Blasius to hear its plan
Meet on Dec. 2
Atlas doesn’t want to meet again until January
Why is Atlas stalling?<br>
135
Board FD in addressing SH activism
Blasius Blasius attacks: Solicits SHs for a written consent
Resolution recommending the board implements Blasius’ plan
Why not order implementation of the plan?
Because SHs lack authority
So why bother recommending?
Public relations: get publicity for cause; embarrass board
Anger SHs who don’t feel strongly about the issue but dislike SHs being ignored by the board
Amend Atlas’ bylaws to expand the board from 7 to 15 members
15 is maximum size allowed under Atlas’ charter
Fill the eight new board positions with Blasius’ nominees
What’s the effect of the written consent?
Atlas had a staggered board, so one election can’t replace majority of directors, but expanding board allows seizing control immediately
Why use a written consent (rather than SH meeting)?
SHs may not be able to call meeting; also faster, secret (can be sprung on board)<br>
136
Board FD in addressing SH activism
Blasius Weaver learns about solicitation & counter-attacks
Rushes to hold board meeting by phone a day after he learns about the solicitation
Board amends bylaws to expand board from 7 to 9 and appoint two directors (Weaver’s nominees)
What is the effect of the board’s actions?<br>
Rushes to hold board meeting by phone a day after he learns about the solicitation
Board amends bylaws to expand board from 7 to 9 and appoint two directors (Weaver’s nominees)
What is the effect of the board’s actions?<br>
137
Board FD in addressing SH activism
Blasius To decide on SoR, court determines that:
Board’s actions were intended to thwart Blasius’ written consent solicitation
But board did not act for the purpose of entrenchment; board sincerely believed Blasius’ plan was bad for Atlas’ SHs
Suppose the court found that the board’s purpose was to keep their jobs (entrenchment)
What SoR applies to the board’s actions?
Now suppose the court found that the board’s purpose was not to thwart Blasius (just to appoint useful new directors)
What SoR applies to the board’s actions?<br>
138
Board FD in addressing SH activism
Blasius Black letter law of Blasius: If plaintiff proves that the board acted for the primary purpose of interfering with the free exercise of the SHs’ franchise, board must demonstrate that there was a compelling justification for its actions
Blasius court: Atlas board didn’t have a compelling justification
This appears to be a special rule for encroaching on SH voting
But in Mercier v. Inter-Tel (Del.Ch. 2007), court re-interprets Blasius as an application of the enhanced scrutiny SoR to cases of SH voting<br>
Blasius court: Atlas board didn’t have a compelling justification
This appears to be a special rule for encroaching on SH voting
But in Mercier v. Inter-Tel (Del.Ch. 2007), court re-interprets Blasius as an application of the enhanced scrutiny SoR to cases of SH voting<br>
139
Board FD in addressing SH activism
When does the enhanced scrutiny SoR apply? Applies when the board deploys corporate power against SHs to achieve greater good for the corporation
Blasius: a specific example, in which the board acts for the primary purpose of interfering with the free exercise of the SHs’ franchise<br>
Blasius: a specific example, in which the board acts for the primary purpose of interfering with the free exercise of the SHs’ franchise<br>
140
Board FD in addressing SH activism
Application of enhanced scrutiny Quasi-BJR: did the board find, in good faith & after a reasonable investigation, a legitimate purpose that warranted the board’s act?
Legitimate purpose: No bad faith (i.e., no corporate waste or illegality)
Good faith: No self-dealing
Reasonable investigation: No negligence
Was the act a reasonable response proportionate to the purpose?
The language in Blasius (“compelling justification”) suggests a tougher standard than just “reasonable”
Perhaps Mercier has softened the standard
Or perhaps noting short of a “compelling justification” is “reasonable” when encroaching on SH voting<br>