
Review of Commonwealth’s Debt Programs A Briefing
TF
Published · 20 slides · 0 views

1 / 1
Description
Review of Commonwealths Debt Programs A Briefing for the Commission on School Construction and Modernization Manju S. Ganeriwala State Treasurer James D. Mahone Public Finance Manager September 29, 2021 Overview Commonwealth Debt Debt
Related Topics
Share
Embed code
Download this presentation From Below
"Review of Commonwealth’s Debt Programs A Briefing" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Review of Commonwealth’s Debt Programs
A Briefing for the Commission on
School Construction and Modernization Manju S. Ganeriwala
State Treasurer
James D. Mahone Public Finance Manager
September 29, 2021<br>
James D. Mahone Public Finance Manager
September 29, 2021<br>
02
Overview Commonwealth Debt
Debt Management Overview
Constitutional Framework and Types of Debt
Debt Capacity Advisory Committee
Virginia Public School Authority
Who We Are
Capital Financing Options
VPSA Pooled Bond Program
Literary Fund
Background
Recommendation Letter 2<br>
Debt Management Overview
Constitutional Framework and Types of Debt
Debt Capacity Advisory Committee
Virginia Public School Authority
Who We Are
Capital Financing Options
VPSA Pooled Bond Program
Literary Fund
Background
Recommendation Letter 2<br>
03
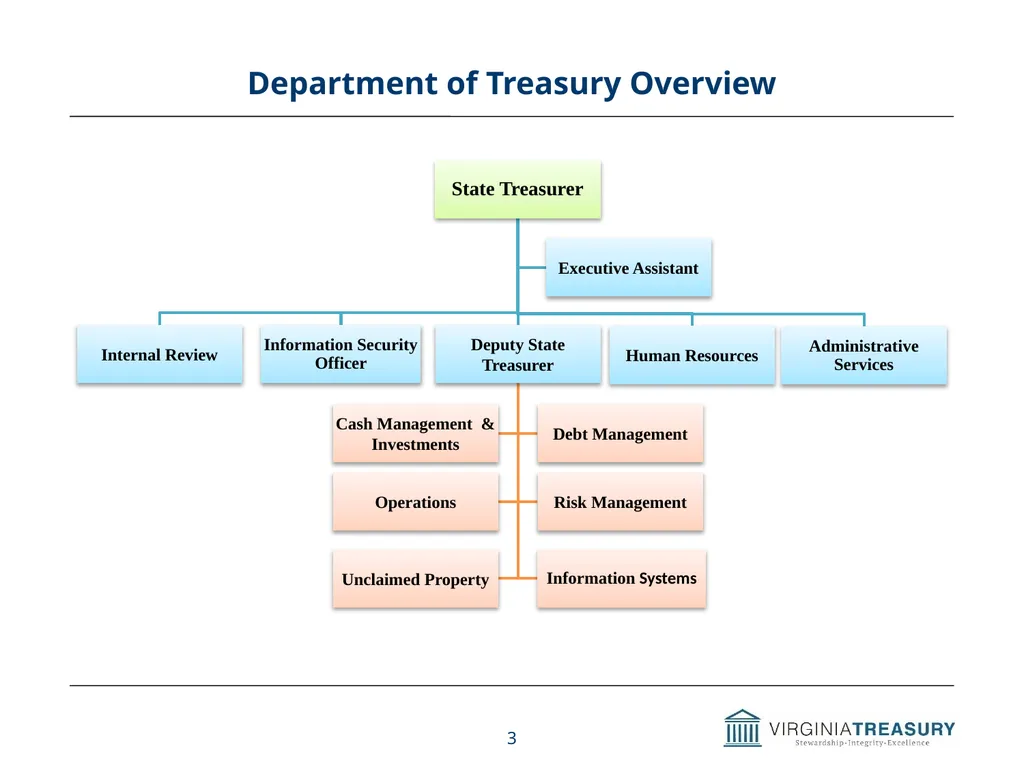
Department of Treasury Overview 3<br>
04
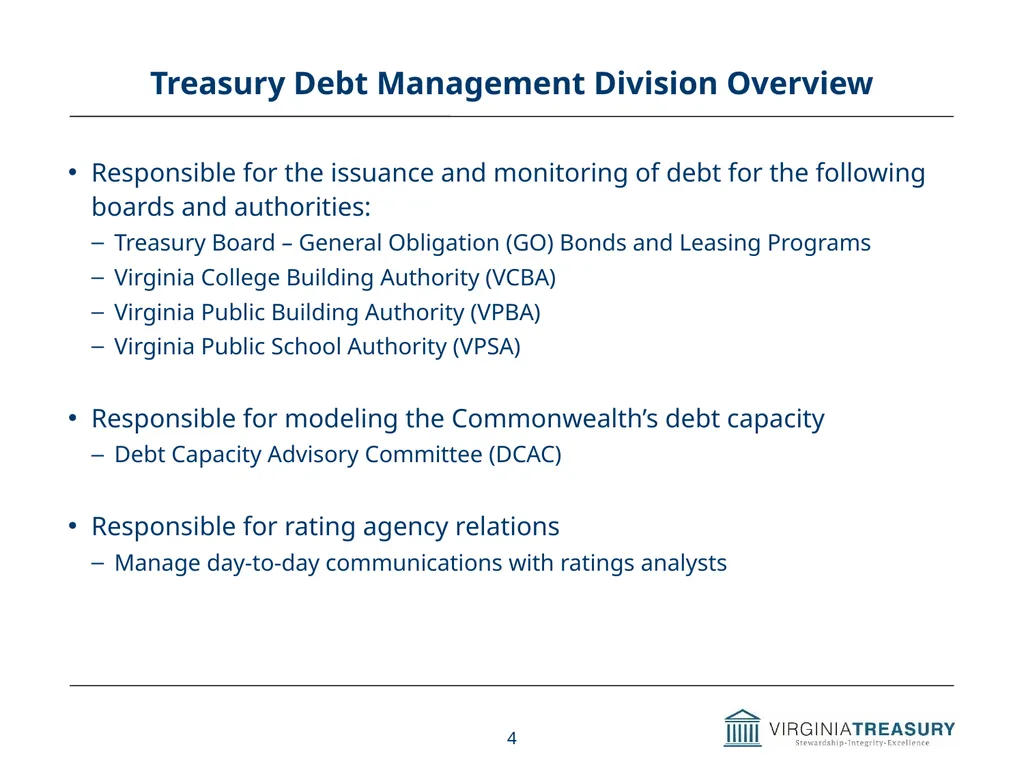
Treasury Debt Management Division Overview Responsible for the issuance and monitoring of debt for the following boards and authorities:
Treasury Board – General Obligation (GO) Bonds and Leasing Programs
Virginia College Building Authority (VCBA)
Virginia Public Building Authority (VPBA)
Virginia Public School Authority (VPSA)
Responsible for modeling the Commonwealth’s debt capacity
Debt Capacity Advisory Committee (DCAC)
Responsible for rating agency relations
Manage day-to-day communications with ratings analysts 4<br>
05
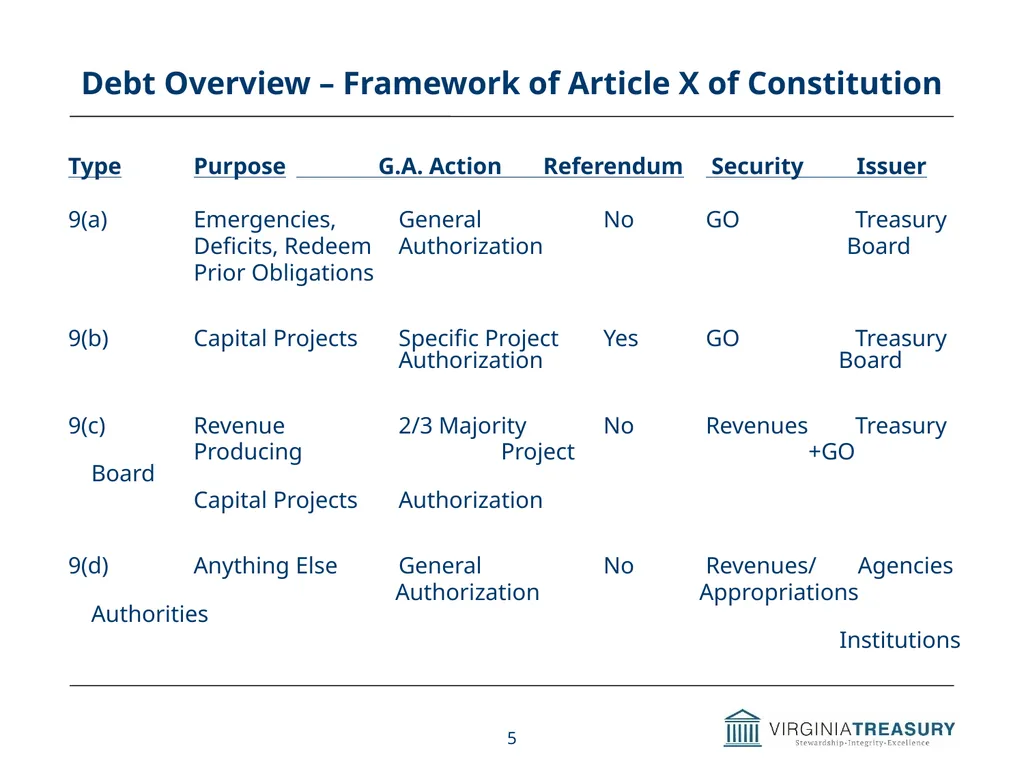
Debt Overview – Framework of Article X of Constitution 5 Type Purpose G.A. Action Referendum Security Issuer
9(a) Emergencies, General No GO Treasury
Deficits, Redeem Authorization Board
Prior Obligations
9(b) Capital Projects Specific Project Yes GO Treasury Authorization Board
9(c) Revenue 2/3 Majority No Revenues Treasury
Producing Project +GO Board
Capital Projects Authorization
9(d) Anything Else General No Revenues/ Agencies
Authorization Appropriations Authorities
Institutions<br>
06
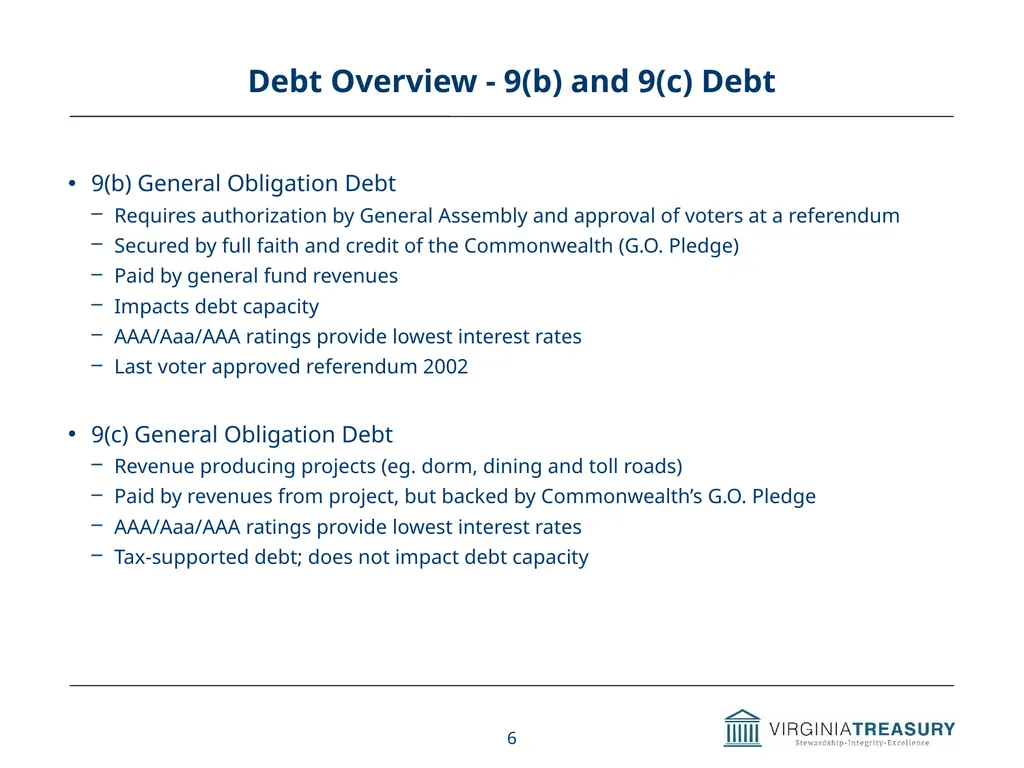
Debt Overview - 9(b) and 9(c) Debt 9(b) General Obligation Debt
Requires authorization by General Assembly and approval of voters at a referendum
Secured by full faith and credit of the Commonwealth (G.O. Pledge)
Paid by general fund revenues
Impacts debt capacity
AAA/Aaa/AAA ratings provide lowest interest rates
Last voter approved referendum 2002
9(c) General Obligation Debt
Revenue producing projects (eg. dorm, dining and toll roads)
Paid by revenues from project, but backed by Commonwealth’s G.O. Pledge
AAA/Aaa/AAA ratings provide lowest interest rates
Tax-supported debt; does not impact debt capacity 6<br>
07
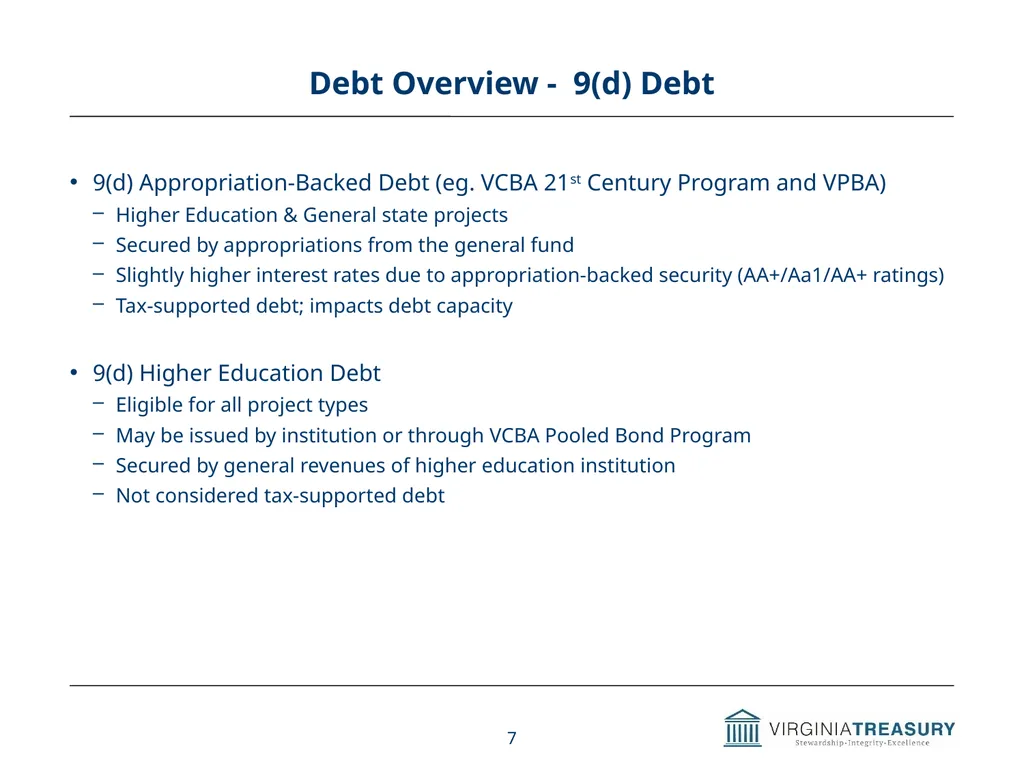
Debt Overview - 9(d) Debt 9(d) Appropriation-Backed Debt (eg. VCBA 21st Century Program and VPBA)
Higher Education & General state projects
Secured by appropriations from the general fund
Slightly higher interest rates due to appropriation-backed security (AA+/Aa1/AA+ ratings)
Tax-supported debt; impacts debt capacity
9(d) Higher Education Debt
Eligible for all project types
May be issued by institution or through VCBA Pooled Bond Program
Secured by general revenues of higher education institution
Not considered tax-supported debt 7<br>
08
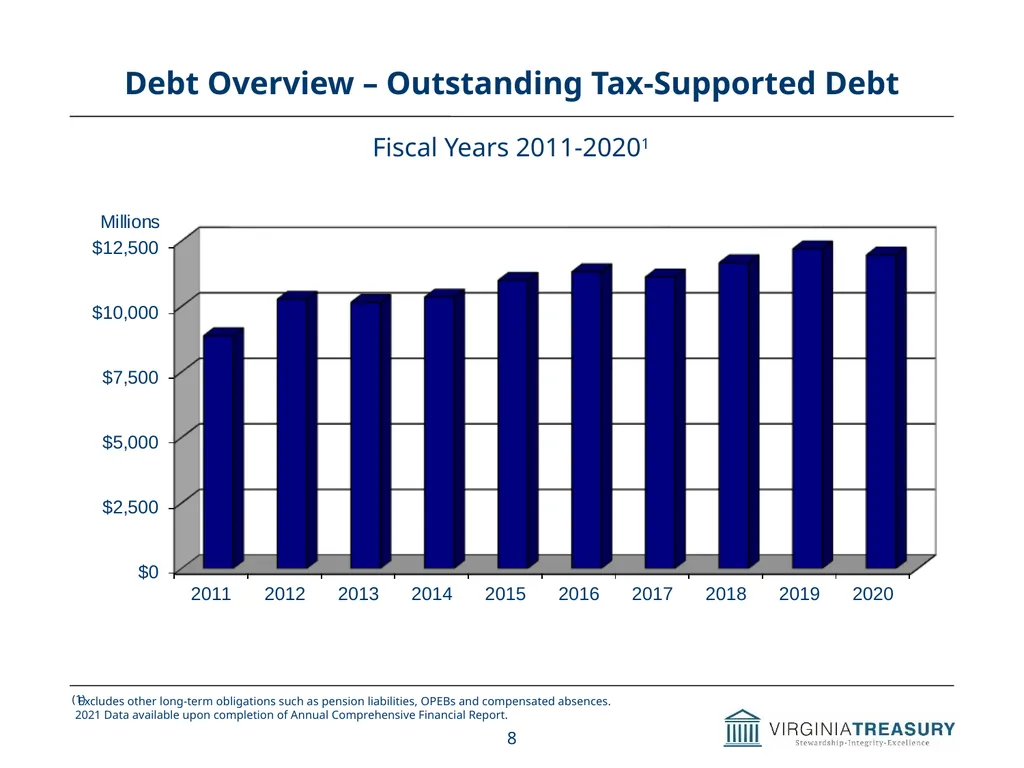
Debt Overview – Outstanding Tax-Supported Debt 8 Fiscal Years 2011-20201<br>
09
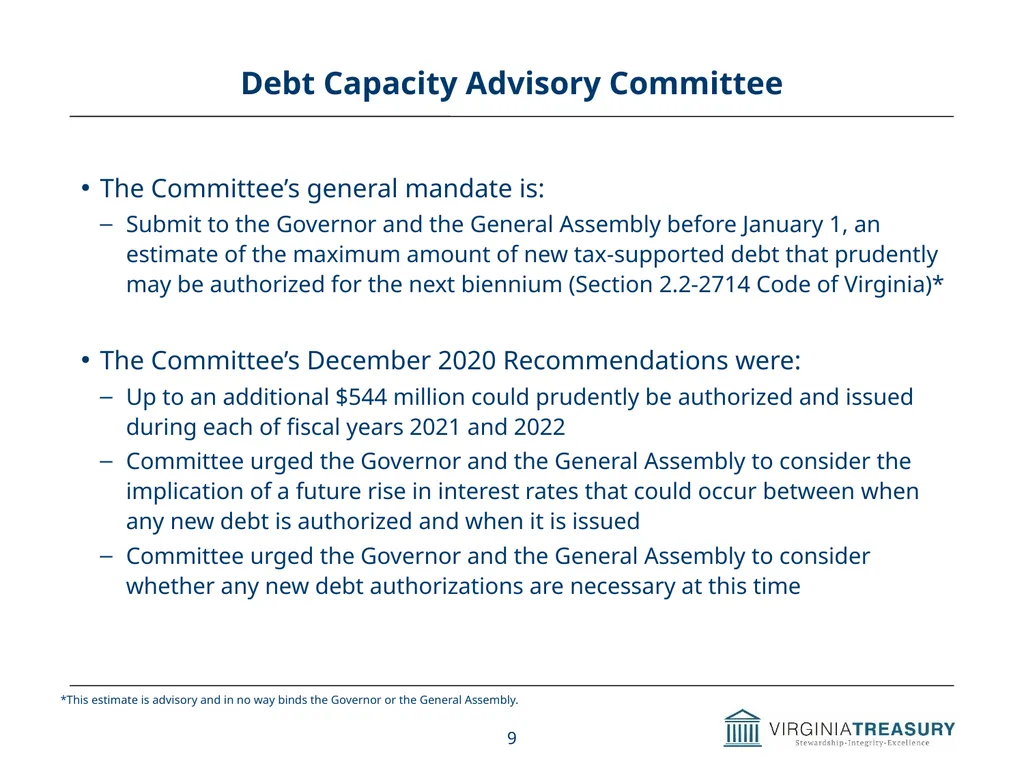
Debt Capacity Advisory Committee The Committee’s general mandate is:
Submit to the Governor and the General Assembly before January 1, an estimate of the maximum amount of new tax-supported debt that prudently may be authorized for the next biennium (Section 2.2-2714 Code of Virginia)*
The Committee’s December 2020 Recommendations were:
Up to an additional $544 million could prudently be authorized and issued during each of fiscal years 2021 and 2022
Committee urged the Governor and the General Assembly to consider the implication of a future rise in interest rates that could occur between when any new debt is authorized and when it is issued
Committee urged the Governor and the General Assembly to consider whether any new debt authorizations are necessary at this time 9<br>
10
Virginia Public School Authority – Who We Are 10<br>
11
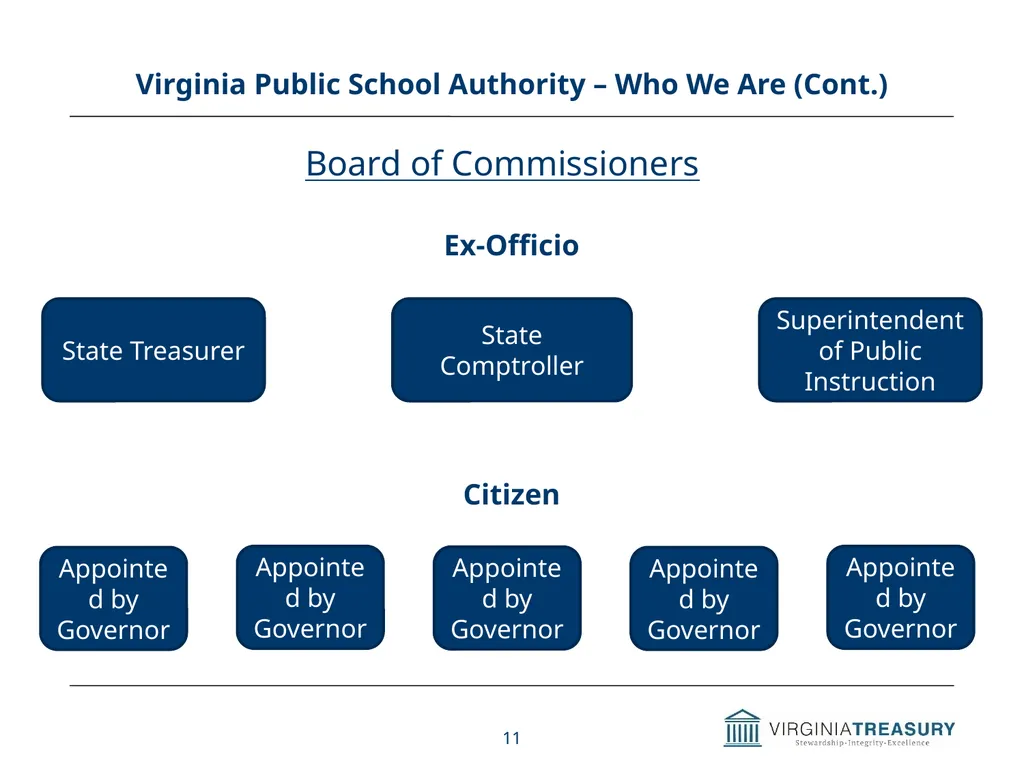
Virginia Public School Authority – Who We Are (Cont.) 11 Board of Commissioners Ex-Officio State Treasurer State Comptroller Superintendent of Public Instruction Citizen Appointed by Governor Appointed by Governor Appointed by Governor Appointed by Governor Appointed by Governor<br>
12
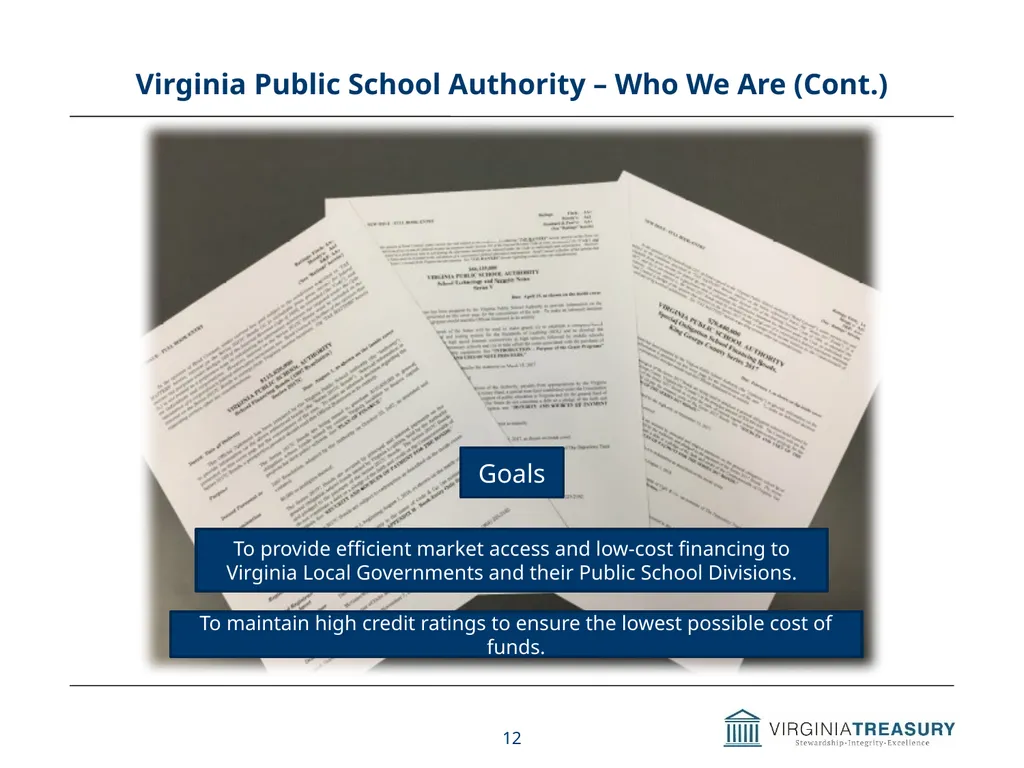
Virginia Public School Authority – Who We Are (Cont.) 12 Goals To provide efficient market access and low-cost financing to Virginia Local Governments and their Public School Divisions. To maintain high credit ratings to ensure the lowest possible cost of funds.<br>
13
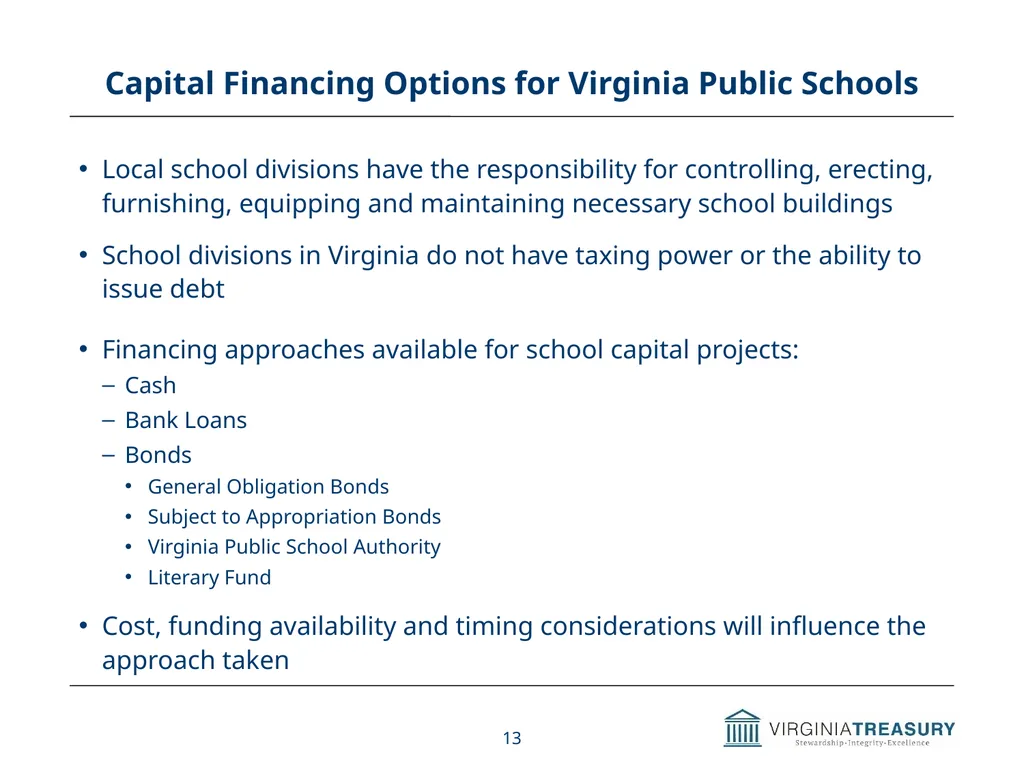
Capital Financing Options for Virginia Public Schools 13 Local school divisions have the responsibility for controlling, erecting, furnishing, equipping and maintaining necessary school buildings
School divisions in Virginia do not have taxing power or the ability to issue debt
Financing approaches available for school capital projects:
Cash
Bank Loans
Bonds
General Obligation Bonds
Subject to Appropriation Bonds
Virginia Public School Authority
Literary Fund
Cost, funding availability and timing considerations will influence the approach taken<br>
14
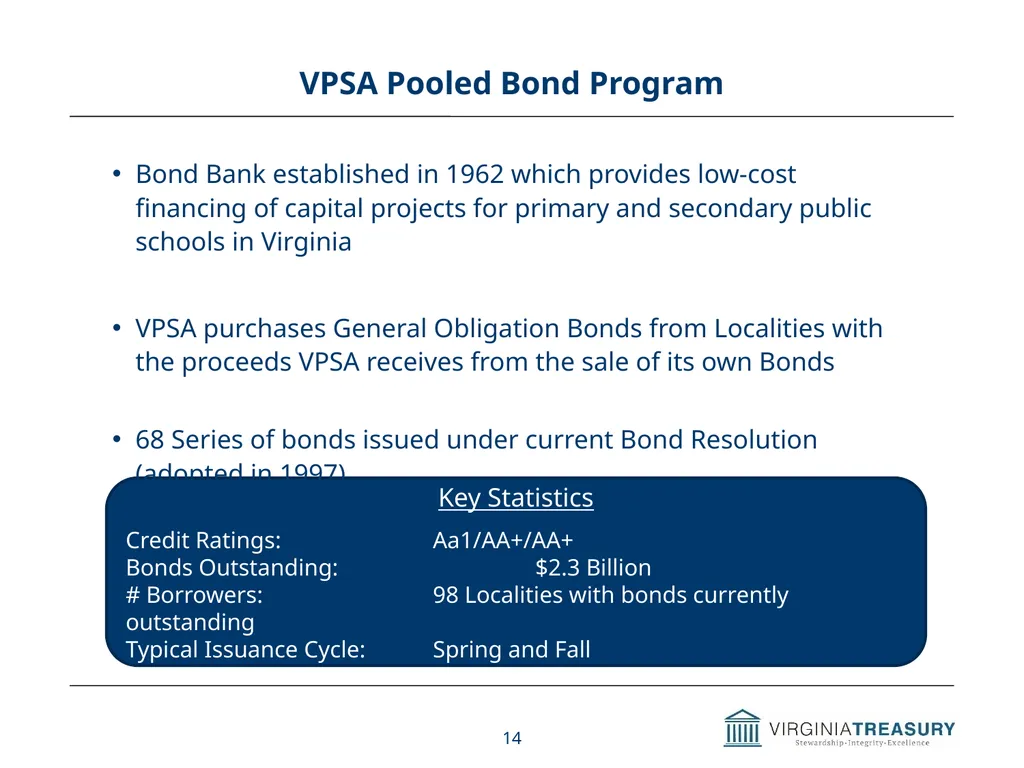
VPSA Pooled Bond Program 14 Key Statistics
Credit Ratings: Aa1/AA+/AA+
Bonds Outstanding: $2.3 Billion
# Borrowers: 98 Localities with bonds currently outstanding
Typical Issuance Cycle: Spring and Fall Bond Bank established in 1962 which provides low-cost financing of capital projects for primary and secondary public schools in Virginia
VPSA purchases General Obligation Bonds from Localities with the proceeds VPSA receives from the sale of its own Bonds
68 Series of bonds issued under current Bond Resolution (adopted in 1997)<br>
15
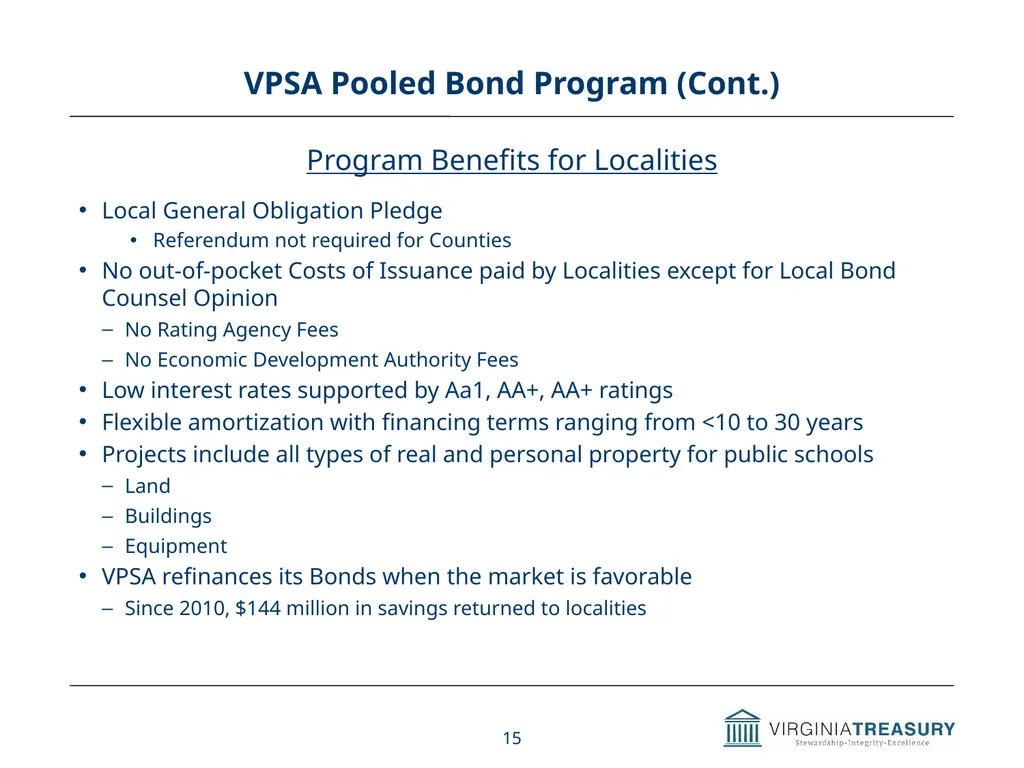
VPSA Pooled Bond Program (Cont.) 15 Program Benefits for Localities
Local General Obligation Pledge
Referendum not required for Counties
No out-of-pocket Costs of Issuance paid by Localities except for Local Bond Counsel Opinion
No Rating Agency Fees
No Economic Development Authority Fees
Low interest rates supported by Aa1, AA+, AA+ ratings
Flexible amortization with financing terms ranging from <10 to 30 years
Projects include all types of real and personal property for public schools
Land
Buildings
Equipment
VPSA refinances its Bonds when the market is favorable
Since 2010, $144 million in savings returned to localities<br>
16
VPSA Pooled Bond Program (Cont.) 16 Bond Bank
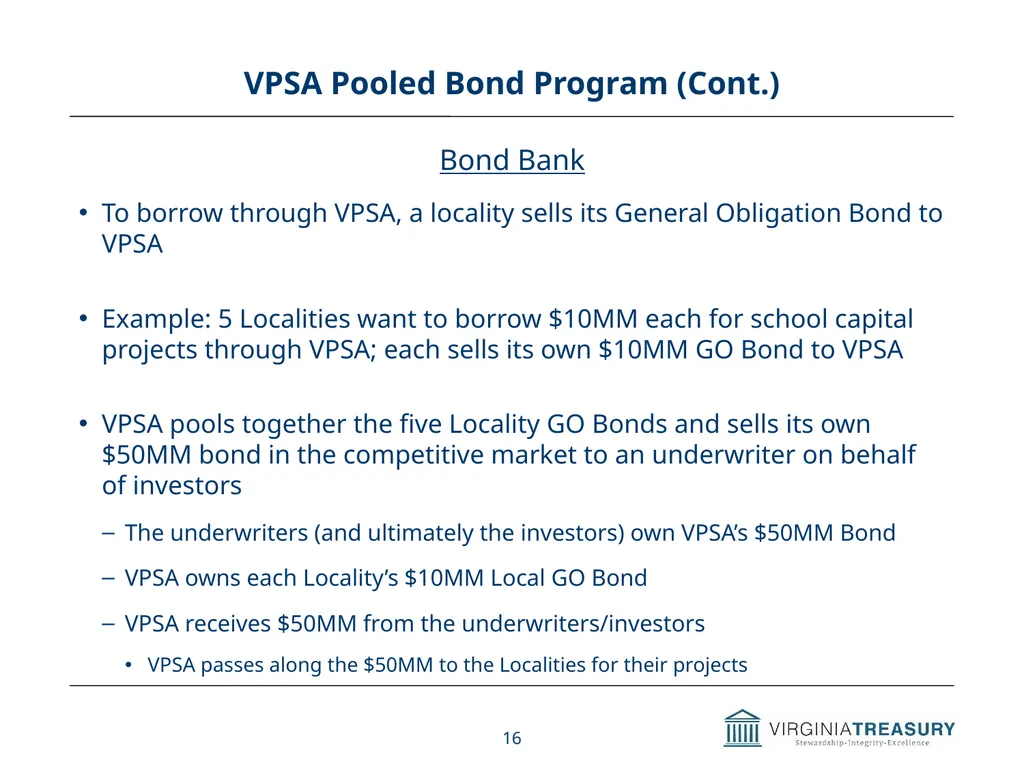
To borrow through VPSA, a locality sells its General Obligation Bond to VPSA
Example: 5 Localities want to borrow $10MM each for school capital projects through VPSA; each sells its own $10MM GO Bond to VPSA
VPSA pools together the five Locality GO Bonds and sells its own $50MM bond in the competitive market to an underwriter on behalf of investors
The underwriters (and ultimately the investors) own VPSA’s $50MM Bond
VPSA owns each Locality’s $10MM Local GO Bond
VPSA receives $50MM from the underwriters/investors
VPSA passes along the $50MM to the Localities for their projects<br>
17
VPSA Pooled Bond Program (Cont.) 17 Bond Bank
The Locality pays no up-front fee to VPSA
The Locality’s interest rate on its GO Bond sold to VPSA is 5 basis points (0.05%) higher than VPSA’s interest rate on its Bonds
VPSA pays for its bond ratings, its bond counsel fee, its financial advisor fee and all other cost of issuance out of pocket
Over time, the additional 5 basis points from the Localities reimburses VPSA for the costs of issuance as well as paying VPSA’s operating expenses<br>
18
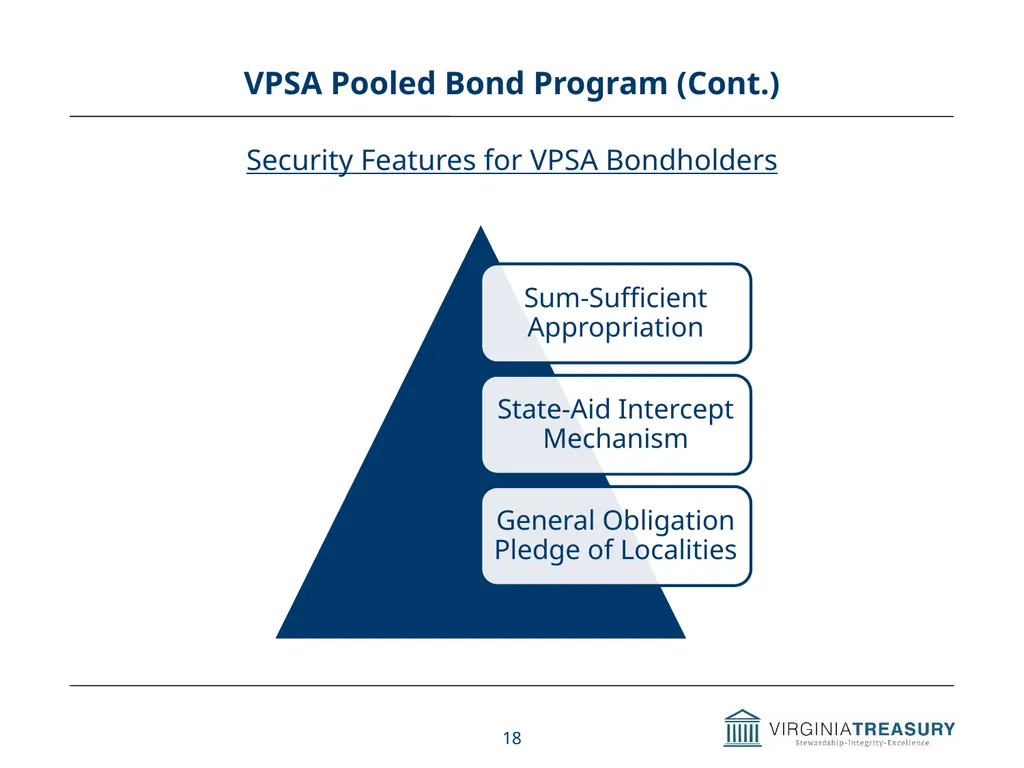
VPSA Pooled Bond Program (Cont.) 18 Security Features for VPSA Bondholders<br>
19
Literary Fund 19 The Literary Fund (“LF”) is a permanent and perpetual school fund established in the Constitution of Virginia for public school purposes
LF must maintain minimum balance of $80MM, after which funds can be used for other school purposes; LF loans count as assets
LF receipts come from Unclaimed Property, Fines, Fees & Forfeitures, Unclaimed Lottery Prizes, and interest earnings
Disbursements from the LF are made for Literary Fund Loans, School Technology and Security Notes debt service, and Teacher Retirement
32 Localities currently have outstanding LF Loans totaling $65.6 million
LF Loans outstanding projected to decrease 43% by 2026
Average Percentage of Literary Fund Revenues used for Teacher Retirement transfers:
FY1981 - 2008: 46.79%
FY2009 - 2021: 72.73%<br>
20
Literary Fund Recommendation Letter 20 Item 145(C)(11)(e) of the 2021 Appropriation Act, Chapter 552 required the Departments of Education and Treasury to (1) develop recommendations to make the Literary Fund loan program more competitive and attractive to school divisions and (2) increase the fiscal health of the Literary Fund. This report was provided to the Governor and to the Chairpersons of the House Appropriations and Senate Finance and Appropriations Committees on July 27, 2021
Prioritize and Increase Construction Loans
Decrease the use of Literary Fund revenues for VRS and other payments
Establish a minimum asset base of $250 million
Increase Maximum Loan Amount from $7.5 million to $25 million
Lower Literary Fund Rate Range, Prioritize Using Local Composite Index, and Conduct Annual Application Process
Remove Inactive Projects from the Waiting List
Provide Higher Loan Amount for School Consolidation
Provide Incentive Grants for Loan Closing Costs<br>