
Risk based Internal audit Balanced scorecard slide
Description: Risk based Internal audit Balanced scorecard slide 10 CA Rajnikant M. Patel Concept of Internal Audit. Changing role of Internal Audit.( Traditional Vs Modern) Skill Set Capabilities. Approach towards Internal Auditing with Reporting.
Related Topics
Download Presentation
"Risk based Internal audit Balanced scorecard slide" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Risk based Internal audit Balanced scorecard slide 10 CA Rajnikant M. Patel<br>
slide2. Concept of Internal Audit.
Changing role of Internal Audit.( Traditional V/s Modern)
Skill Set & Capabilities.
Approach towards Internal Auditing with Reporting.
Opportunities Content:<br>
slide3. Concept of Internal Audit<br>
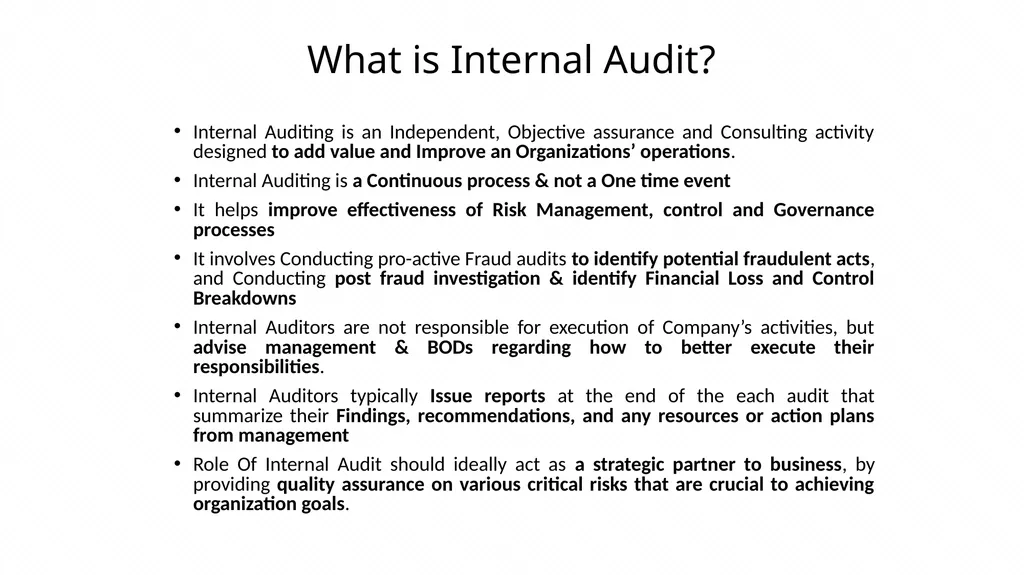
slide4. Internal Auditing is an Independent, Objective assurance and Consulting activity designed to add value and Improve an Organizations’ operations.
Internal Auditing is a Continuous process & not a One time event
It helps improve effectiveness of Risk Management, control and Governance processes
It involves Conducting pro-active Fraud audits to identify potential fraudulent acts, and Conducting post fraud investigation & identify Financial Loss and Control Breakdowns
Internal Auditors are not responsible for execution of Company’s activities, but advise management & BODs regarding how to better execute their responsibilities.
Internal Auditors typically Issue reports at the end of the each audit that summarize their Findings, recommendations, and any resources or action plans from management
Role Of Internal Audit should ideally act as a strategic partner to business, by providing quality assurance on various critical risks that are crucial to achieving organization goals. What is Internal Audit?<br>
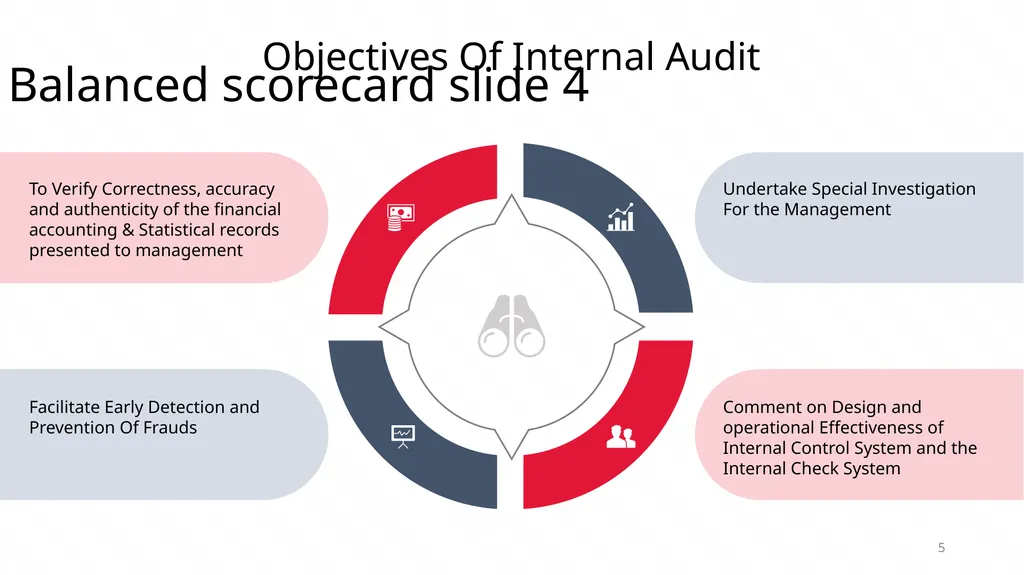
slide5. 5 Balanced scorecard slide 4 Objectives Of Internal Audit To Verify Correctness, accuracy and authenticity of the financial accounting & Statistical records presented to management Facilitate Early Detection and Prevention Of Frauds Undertake Special Investigation For the Management Comment on Design and operational Effectiveness of Internal Control System and the Internal Check System<br>
slide6. Changing role of Internal Audit (Traditional V/S Modern)<br>
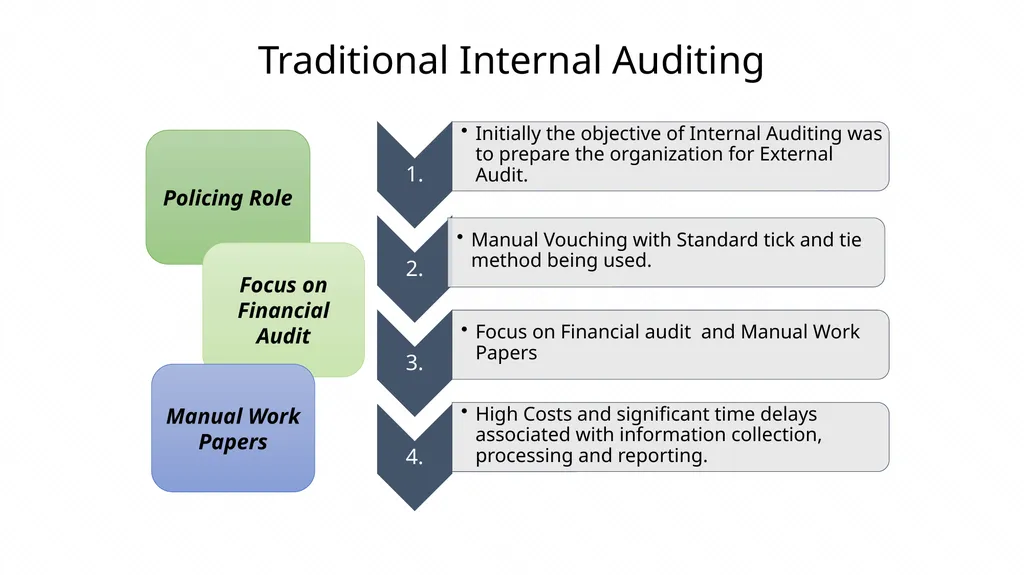
slide7. Policing Role Focus on Financial Audit Manual Work Papers Traditional Internal Auditing<br>
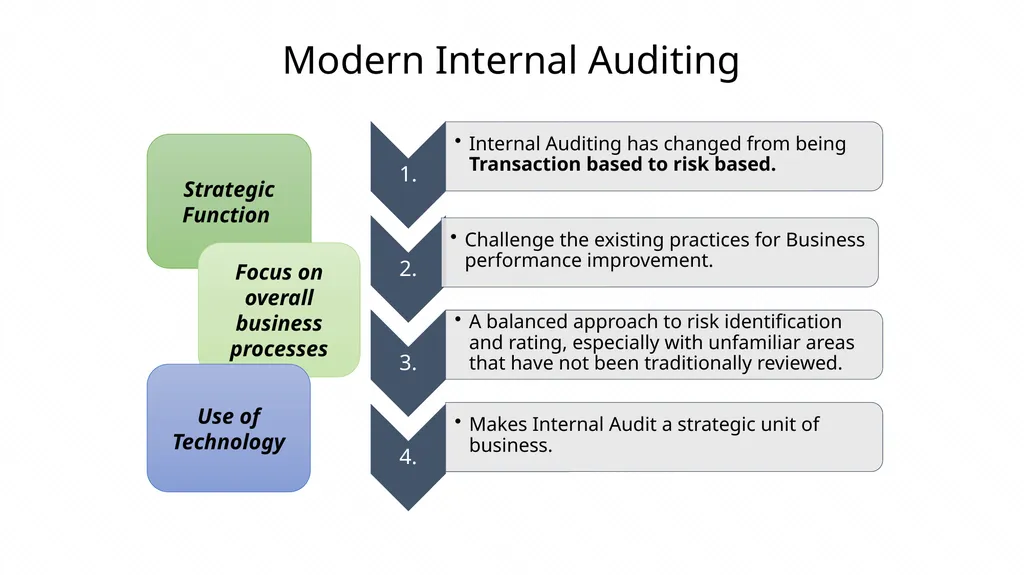
slide8. Strategic Function Focus on overall business processes Use of Technology Modern Internal Auditing<br>
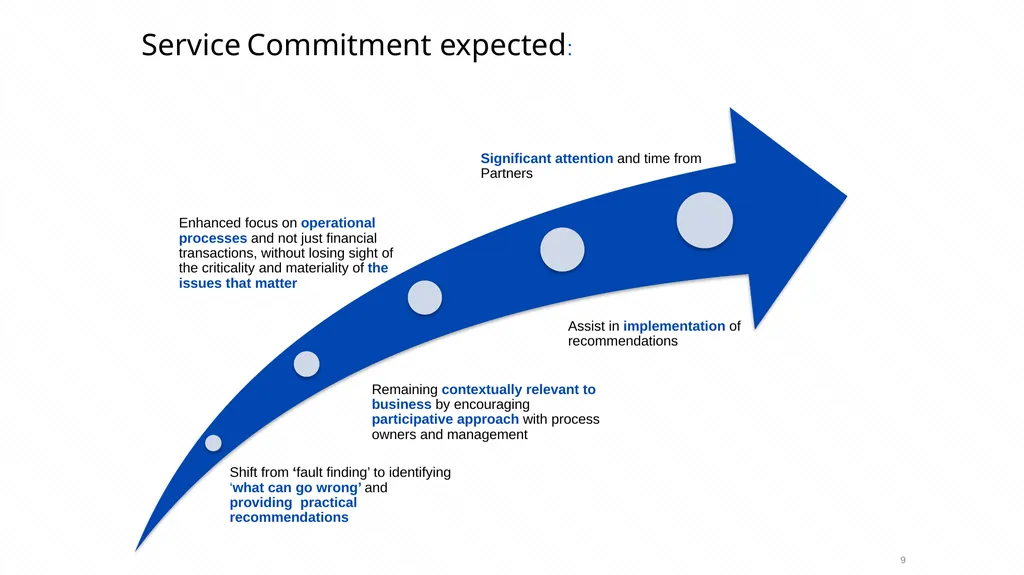
slide9. 9 Service Commitment expected:<br>
slide10. Skill Set and Capabilities<br>
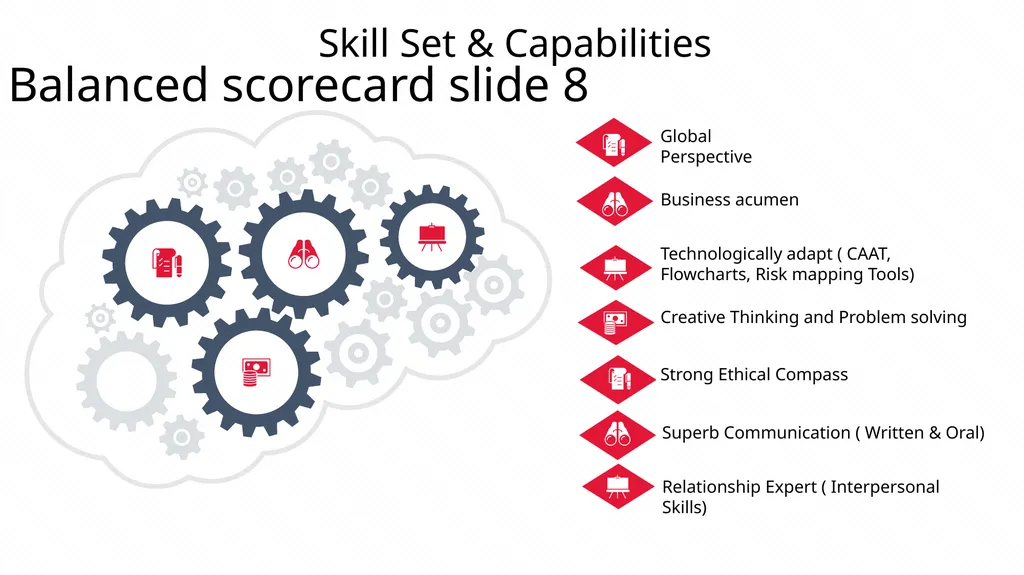
slide11. Balanced scorecard slide 8 Skill Set & Capabilities Global Perspective Technologically adapt ( CAAT, Flowcharts, Risk mapping Tools) Creative Thinking and Problem solving Business acumen Strong Ethical Compass Superb Communication ( Written & Oral) Relationship Expert ( Interpersonal Skills)<br>
slide12. Approach towards Internal Auditing with Reporting<br>
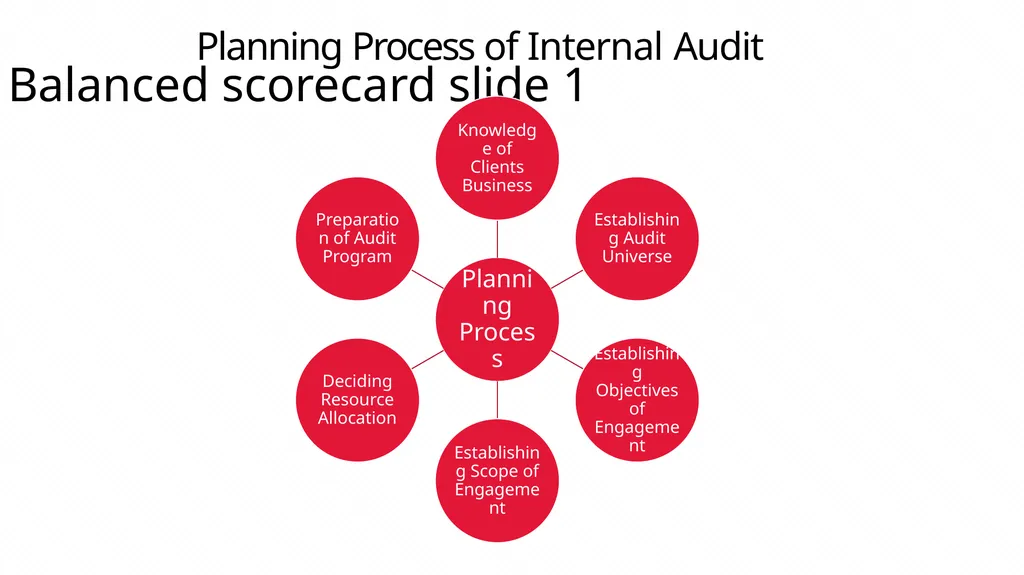
slide13. Balanced scorecard slide 1 Planning Process of Internal Audit<br>
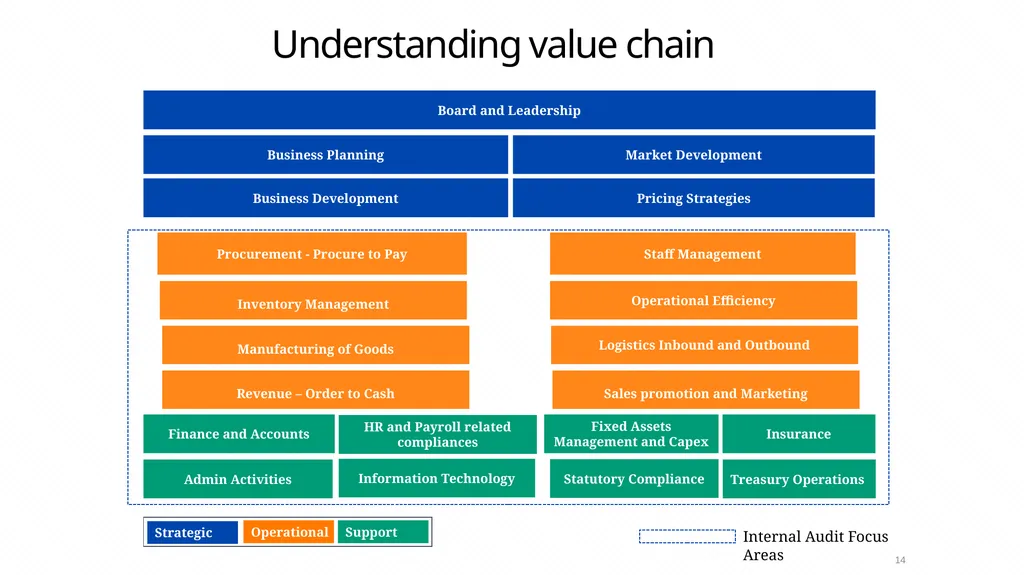
slide14. Understanding value chain Business Planning Market Development Business Development Pricing Strategies HR and Payroll related compliances Fixed Assets Management and Capex Information Technology Finance and Accounts Statutory Compliance Procurement - Procure to Pay Operational Efficiency Insurance Internal Audit Focus Areas Inventory Management Board and Leadership 14 Staff Management Admin Activities Manufacturing of Goods Logistics Inbound and Outbound Revenue – Order to Cash Sales promotion and Marketing Treasury Operations<br>
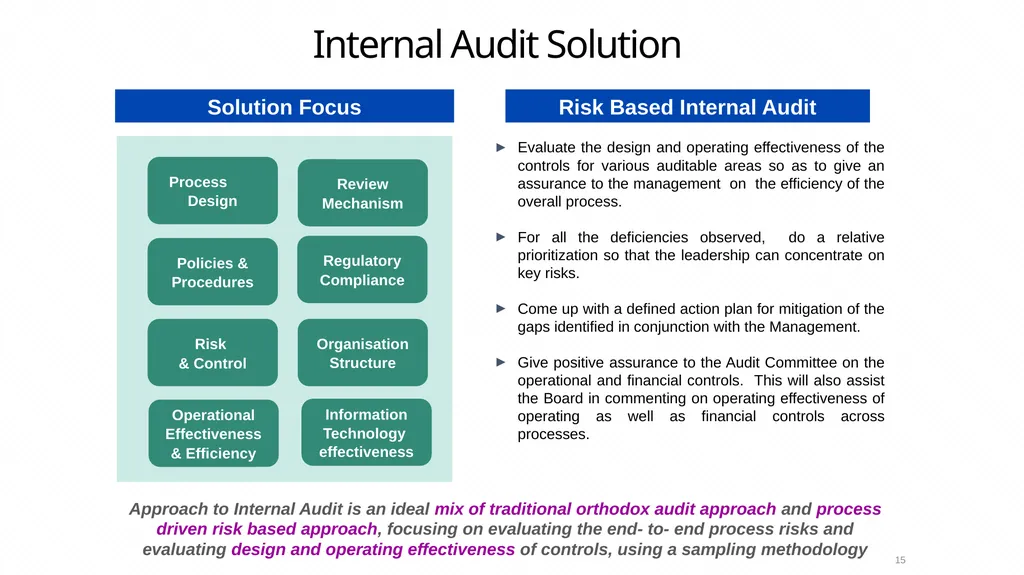
slide15. Internal Audit Solution 15 Solution Focus Risk Based Internal Audit Evaluate the design and operating effectiveness of the controls for various auditable areas so as to give an assurance to the management on the efficiency of the overall process.
For all the deficiencies observed, do a relative prioritization so that the leadership can concentrate on key risks.
Come up with a defined action plan for mitigation of the gaps identified in conjunction with the Management.
Give positive assurance to the Audit Committee on the operational and financial controls. This will also assist the Board in commenting on operating effectiveness of operating as well as financial controls across processes. Approach to Internal Audit is an ideal mix of traditional orthodox audit approach and process driven risk based approach, focusing on evaluating the end- to- end process risks and evaluating design and operating effectiveness of controls, using a sampling methodology<br>
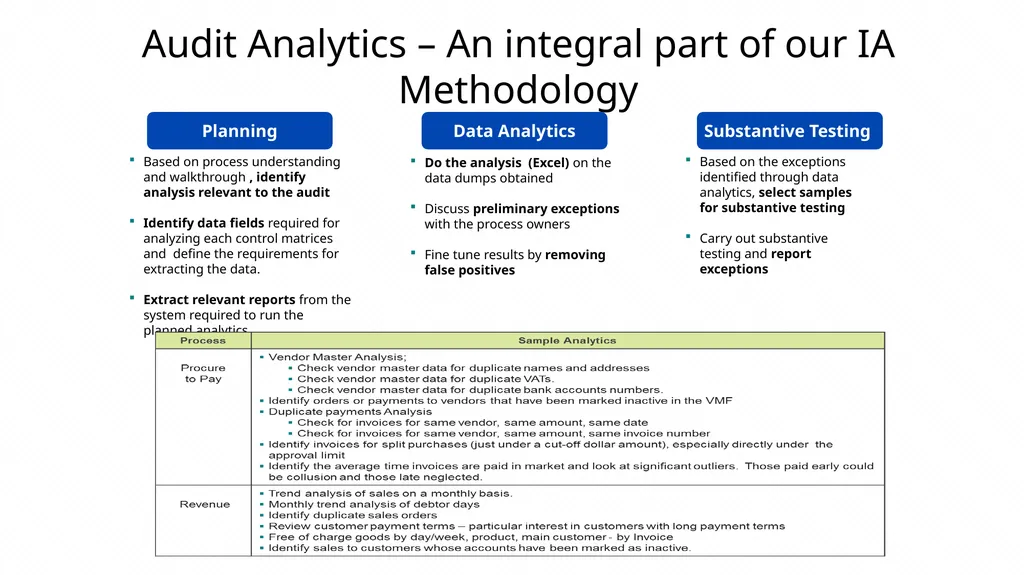
slide16. Audit Analytics – An integral part of our IA Methodology Planning Data Analytics Substantive Testing Based on process understanding and walkthrough , identify analysis relevant to the audit
Identify data fields required for analyzing each control matrices and define the requirements for extracting the data.
Extract relevant reports from the system required to run the planned analytics Do the analysis (Excel) on the data dumps obtained
Discuss preliminary exceptions with the process owners
Fine tune results by removing false positives Based on the exceptions identified through data analytics, select samples for substantive testing
Carry out substantive testing and report exceptions<br>
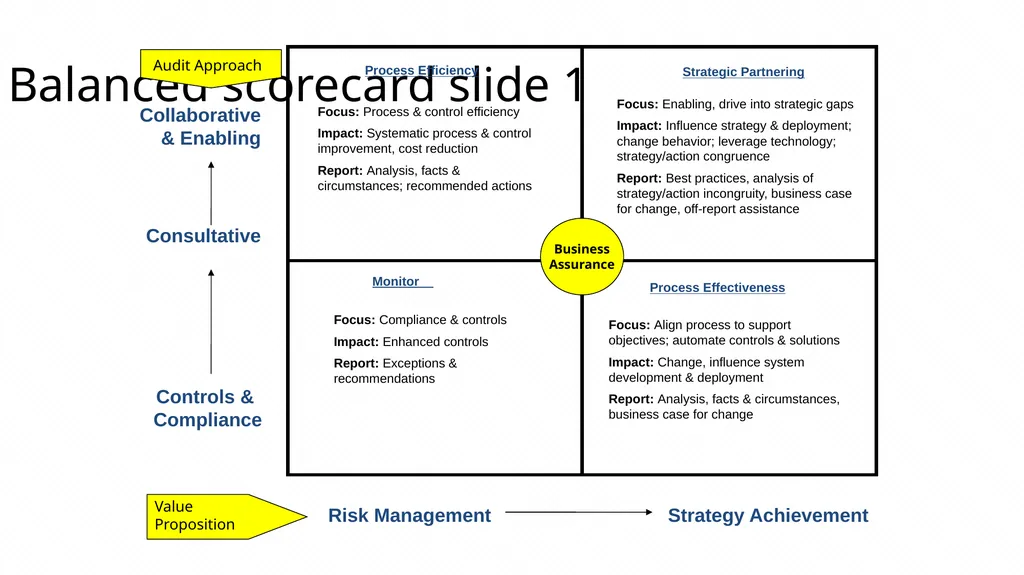
slide17. Balanced scorecard slide 1 Focus: Process & control efficiency
Impact: Systematic process & control improvement, cost reduction
Report: Analysis, facts & circumstances; recommended actions Process Efficiency Focus: Enabling, drive into strategic gaps
Impact: Influence strategy & deployment; change behavior; leverage technology; strategy/action congruence
Report: Best practices, analysis of strategy/action incongruity, business case for change, off-report assistance Strategic Partnering Monitor Focus: Compliance & controls
Impact: Enhanced controls
Report: Exceptions & recommendations Focus: Align process to support objectives; automate controls & solutions
Impact: Change, influence system development & deployment
Report: Analysis, facts & circumstances, business case for change Process Effectiveness Audit Approach Collaborative & Enabling
Consultative Controls & Compliance Risk Management Strategy Achievement Value Proposition Business
Assurance<br>
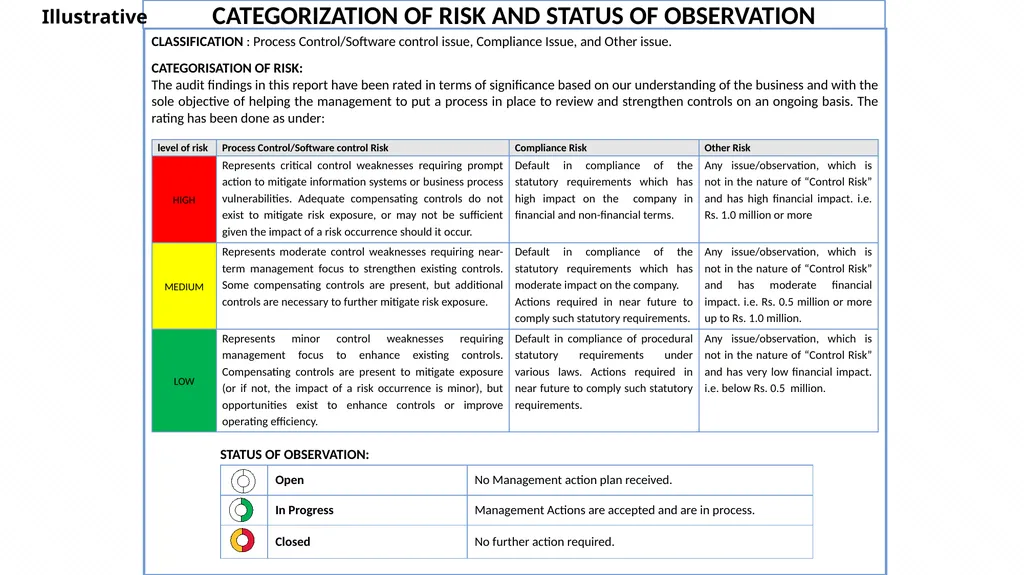
slide18. Illustrative<br>
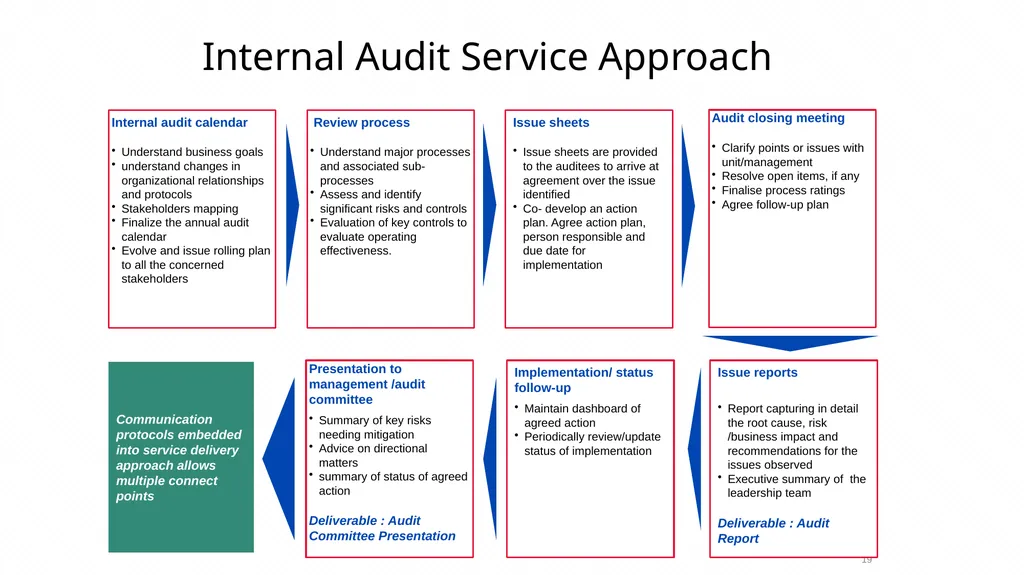
slide19. 19 Internal Audit Service Approach Presentation to management /audit committee
Summary of key risks needing mitigation
Advice on directional matters
summary of status of agreed action
Deliverable : Audit Committee Presentation Implementation/ status follow-up
Maintain dashboard of agreed action
Periodically review/update status of implementation Issue reports
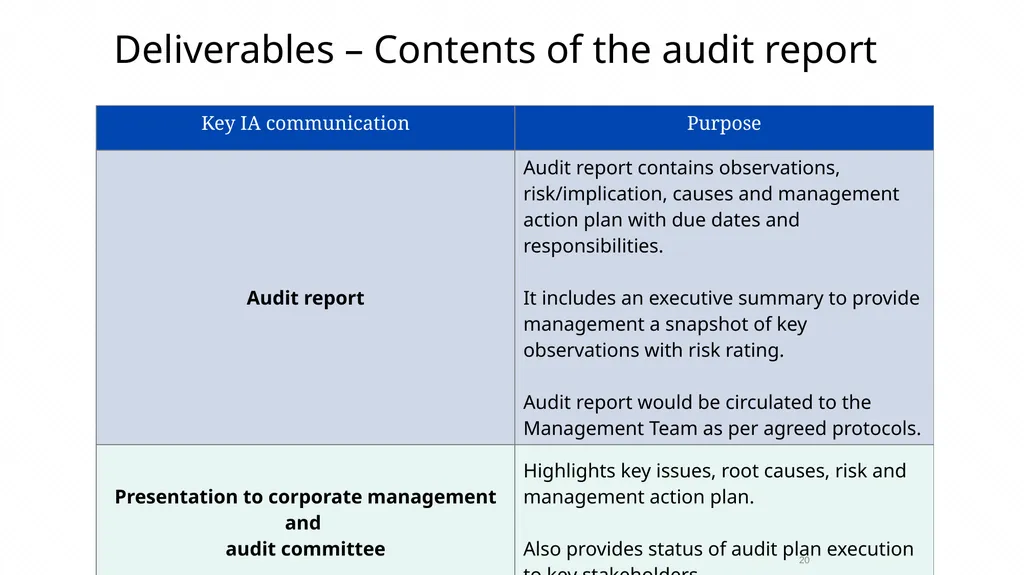
Report capturing in detail the root cause, risk /business impact and recommendations for the issues observed
Executive summary of the leadership team
Deliverable : Audit Report Internal audit calendar
Understand business goals
understand changes in organizational relationships and protocols
Stakeholders mapping
Finalize the annual audit calendar
Evolve and issue rolling plan to all the concerned stakeholders Review process
Understand major processes and associated sub-processes
Assess and identify significant risks and controls
Evaluation of key controls to evaluate operating effectiveness. Issue sheets
Issue sheets are provided to the auditees to arrive at agreement over the issue identified
Co- develop an action plan. Agree action plan, person responsible and due date for implementation Audit closing meeting
Clarify points or issues with unit/management
Resolve open items, if any
Finalise process ratings
Agree follow-up plan Communication protocols embedded into service delivery approach allows multiple connect points<br>
slide20. Deliverables – Contents of the audit report 20<br>
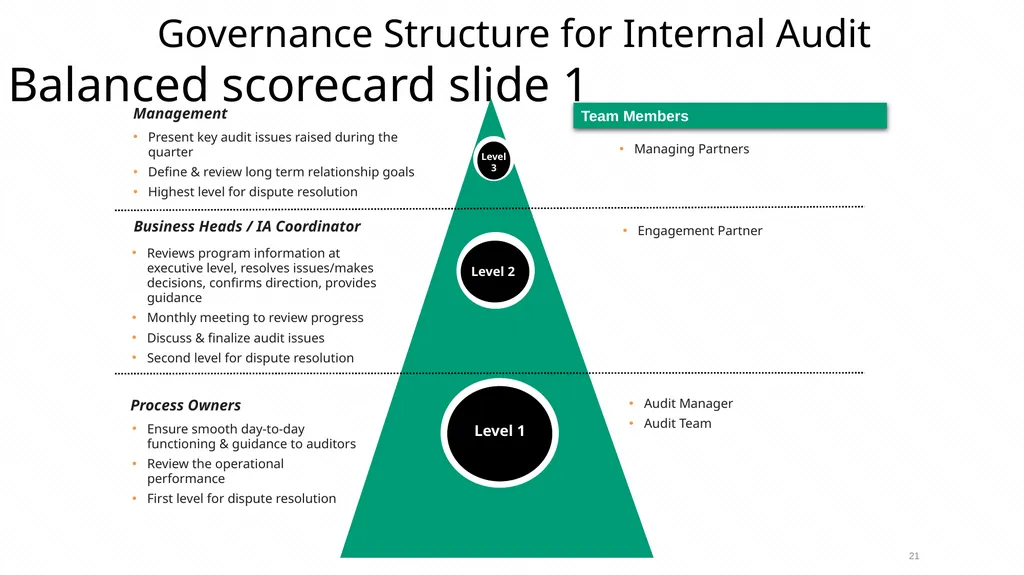
slide21. Balanced scorecard slide 1 21 Governance Structure for Internal Audit Team Members Managing Partners Audit Manager
Audit Team Level 2 Level 3 Management Business Heads / IA Coordinator Present key audit issues raised during the quarter
Define & review long term relationship goals
Highest level for dispute resolution Reviews program information at executive level, resolves issues/makes decisions, confirms direction, provides guidance
Monthly meeting to review progress
Discuss & finalize audit issues
Second level for dispute resolution Ensure smooth day-to-day functioning & guidance to auditors
Review the operational performance
First level for dispute resolution Level 1 Process Owners Engagement Partner<br>
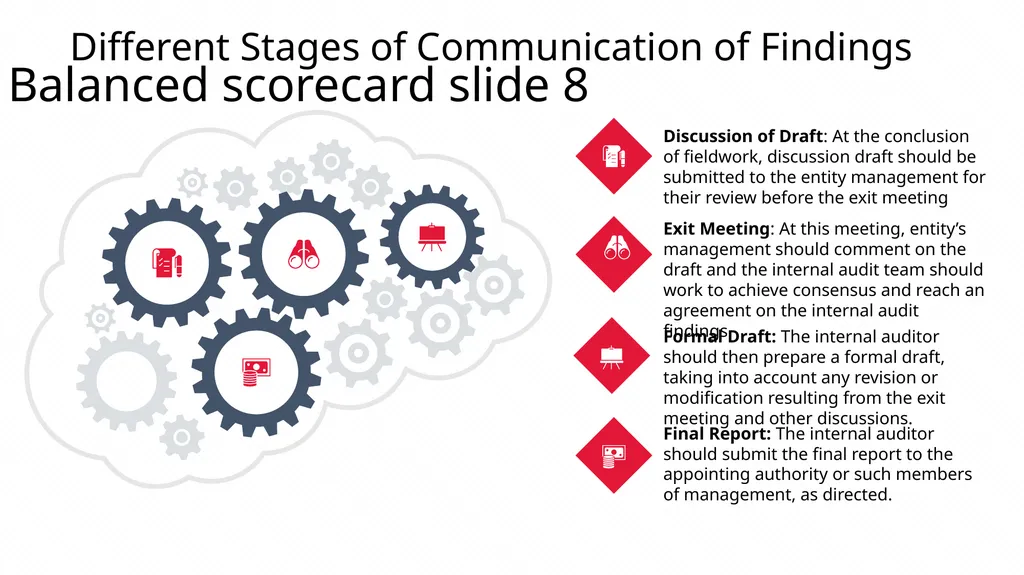
slide22. Balanced scorecard slide 8 Different Stages of Communication of Findings Discussion of Draft: At the conclusion of fieldwork, discussion draft should be submitted to the entity management for their review before the exit meeting Formal Draft: The internal auditor should then prepare a formal draft, taking into account any revision or modification resulting from the exit meeting and other discussions. Final Report: The internal auditor should submit the final report to the appointing authority or such members of management, as directed. Exit Meeting: At this meeting, entity’s management should comment on the draft and the internal audit team should work to achieve consensus and reach an agreement on the internal audit findings<br>
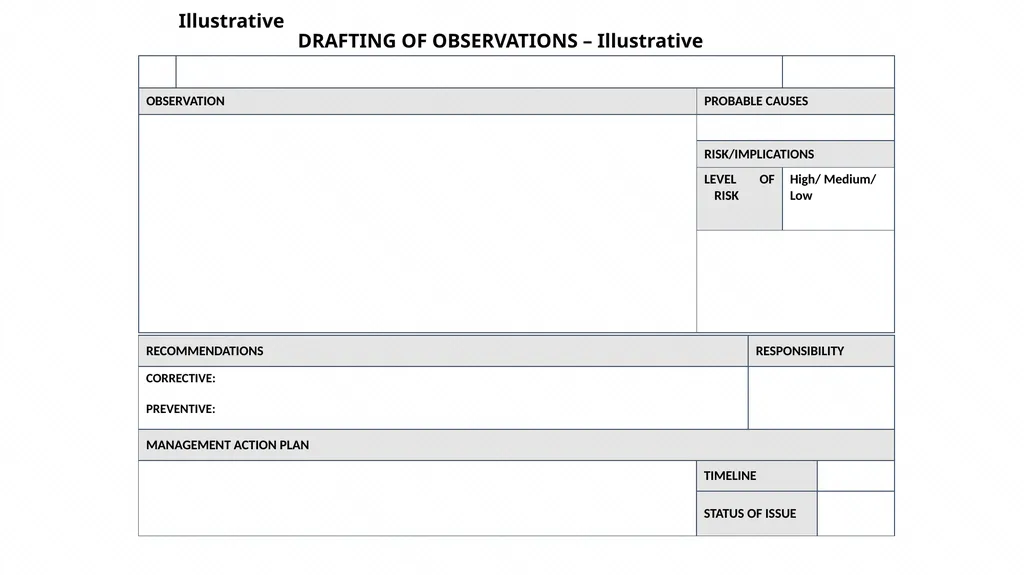
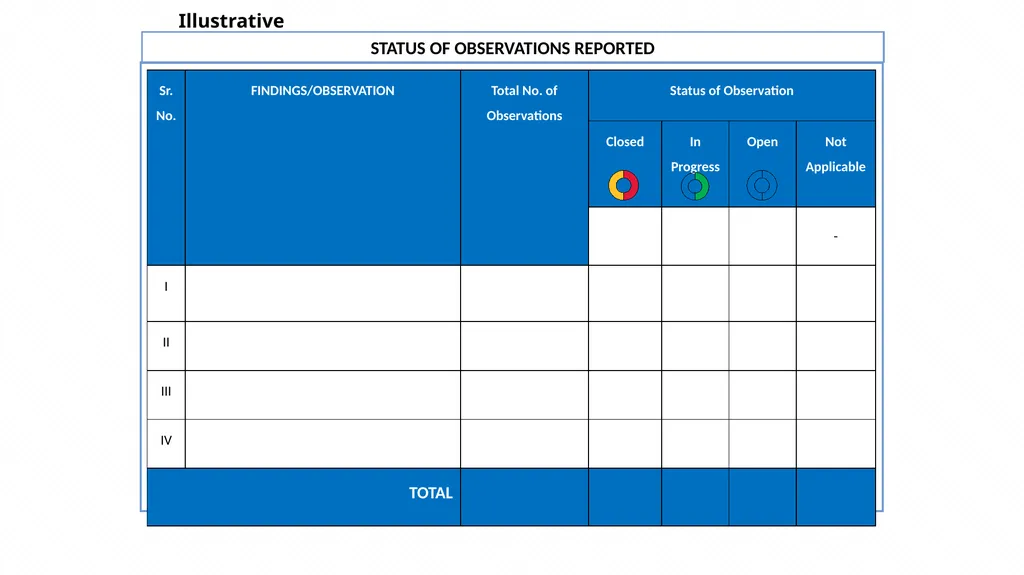
slide23. DRAFTING OF OBSERVATIONS – Illustrative Illustrative<br>
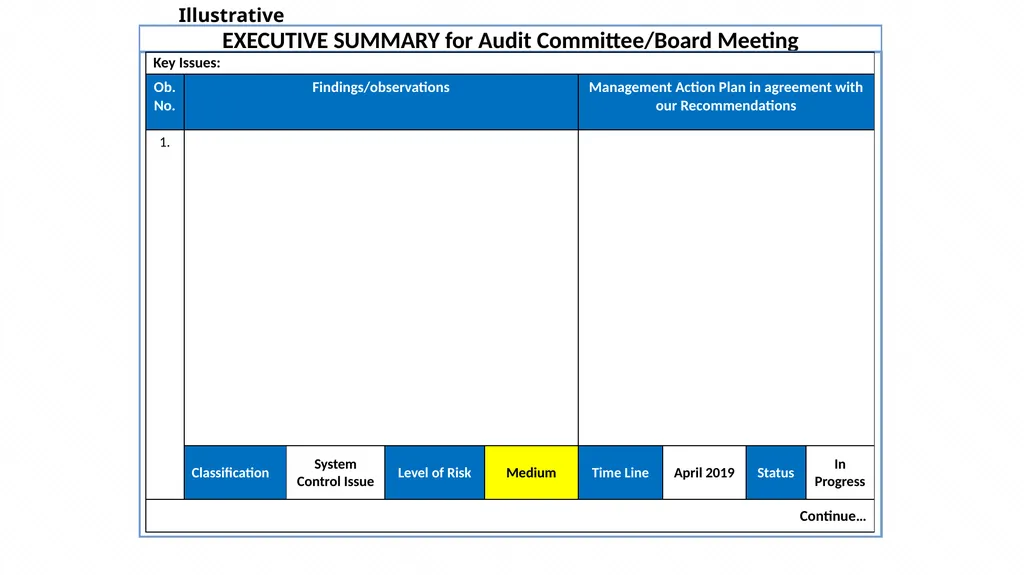
slide24. Illustrative<br>
slide25. Illustrative<br>
slide26. Opportunities<br>
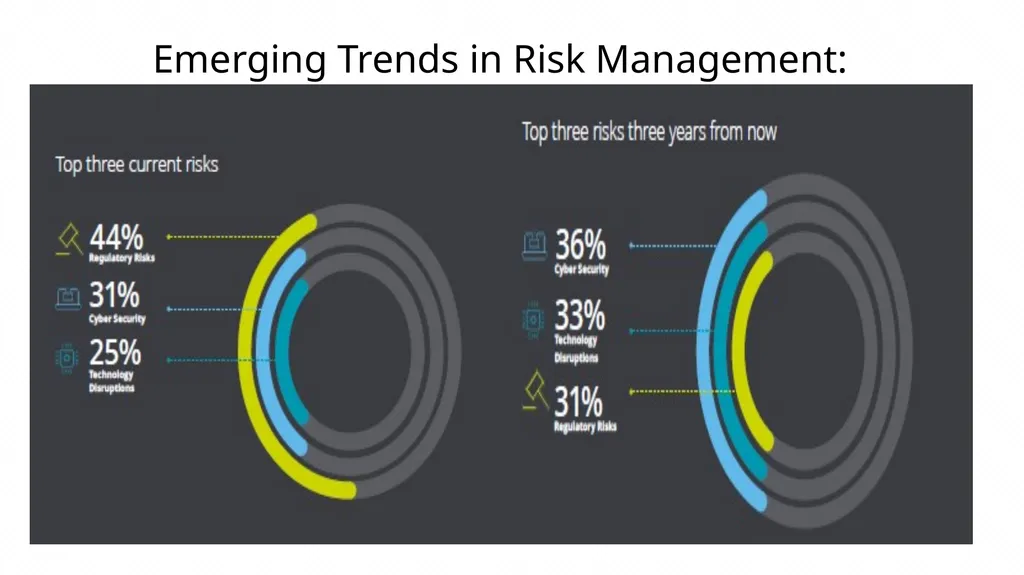
slide27. Emerging Trends in Risk Management:<br>
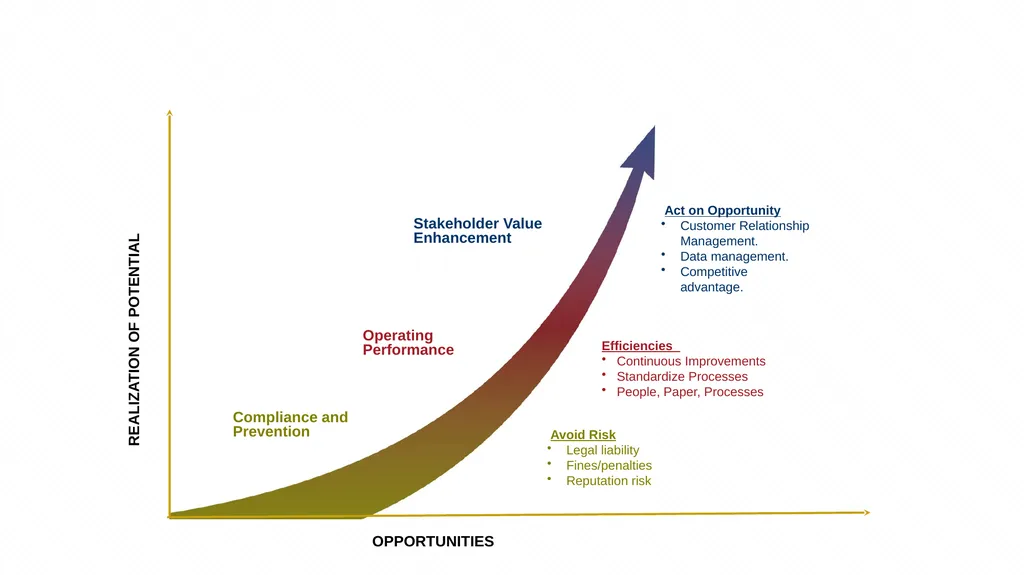
slide28. OPPORTUNITIES Compliance and Prevention Operating Performance Stakeholder Value
Enhancement Act on Opportunity
Customer Relationship Management.
Data management.
Competitive advantage. Avoid Risk
Legal liability
Fines/penalties
Reputation risk Efficiencies
Continuous Improvements
Standardize Processes
People, Paper, Processes REALIZATION OF POTENTIAL<br>
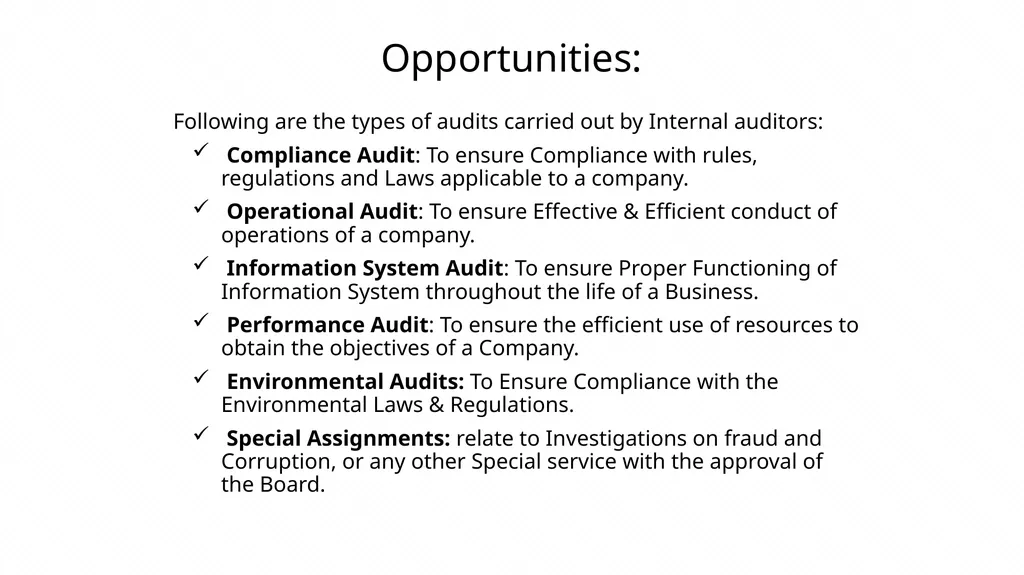
slide29. Opportunities: Following are the types of audits carried out by Internal auditors:
Compliance Audit: To ensure Compliance with rules, regulations and Laws applicable to a company.
Operational Audit: To ensure Effective & Efficient conduct of operations of a company.
Information System Audit: To ensure Proper Functioning of Information System throughout the life of a Business.
Performance Audit: To ensure the efficient use of resources to obtain the objectives of a Company.
Environmental Audits: To Ensure Compliance with the Environmental Laws & Regulations.
Special Assignments: relate to Investigations on fraud and Corruption, or any other Special service with the approval of the Board.<br>
slide30. Internal Auditors helps to achieve the right balance between risk and reward by establishing an environment for timely and effective response to the ever changing business risks. 30 How We Help Our Customers:<br>
slide31. Thank you Balanced scorecard slide 10 CA Rajnikant M. Patel<br>
slide2. Concept of Internal Audit.
Changing role of Internal Audit.( Traditional V/s Modern)
Skill Set & Capabilities.
Approach towards Internal Auditing with Reporting.
Opportunities Content:<br>
slide3. Concept of Internal Audit<br>
slide4. Internal Auditing is an Independent, Objective assurance and Consulting activity designed to add value and Improve an Organizations’ operations.
Internal Auditing is a Continuous process & not a One time event
It helps improve effectiveness of Risk Management, control and Governance processes
It involves Conducting pro-active Fraud audits to identify potential fraudulent acts, and Conducting post fraud investigation & identify Financial Loss and Control Breakdowns
Internal Auditors are not responsible for execution of Company’s activities, but advise management & BODs regarding how to better execute their responsibilities.
Internal Auditors typically Issue reports at the end of the each audit that summarize their Findings, recommendations, and any resources or action plans from management
Role Of Internal Audit should ideally act as a strategic partner to business, by providing quality assurance on various critical risks that are crucial to achieving organization goals. What is Internal Audit?<br>
slide5. 5 Balanced scorecard slide 4 Objectives Of Internal Audit To Verify Correctness, accuracy and authenticity of the financial accounting & Statistical records presented to management Facilitate Early Detection and Prevention Of Frauds Undertake Special Investigation For the Management Comment on Design and operational Effectiveness of Internal Control System and the Internal Check System<br>
slide6. Changing role of Internal Audit (Traditional V/S Modern)<br>
slide7. Policing Role Focus on Financial Audit Manual Work Papers Traditional Internal Auditing<br>
slide8. Strategic Function Focus on overall business processes Use of Technology Modern Internal Auditing<br>
slide9. 9 Service Commitment expected:<br>
slide10. Skill Set and Capabilities<br>
slide11. Balanced scorecard slide 8 Skill Set & Capabilities Global Perspective Technologically adapt ( CAAT, Flowcharts, Risk mapping Tools) Creative Thinking and Problem solving Business acumen Strong Ethical Compass Superb Communication ( Written & Oral) Relationship Expert ( Interpersonal Skills)<br>
slide12. Approach towards Internal Auditing with Reporting<br>
slide13. Balanced scorecard slide 1 Planning Process of Internal Audit<br>
slide14. Understanding value chain Business Planning Market Development Business Development Pricing Strategies HR and Payroll related compliances Fixed Assets Management and Capex Information Technology Finance and Accounts Statutory Compliance Procurement - Procure to Pay Operational Efficiency Insurance Internal Audit Focus Areas Inventory Management Board and Leadership 14 Staff Management Admin Activities Manufacturing of Goods Logistics Inbound and Outbound Revenue – Order to Cash Sales promotion and Marketing Treasury Operations<br>
slide15. Internal Audit Solution 15 Solution Focus Risk Based Internal Audit Evaluate the design and operating effectiveness of the controls for various auditable areas so as to give an assurance to the management on the efficiency of the overall process.
For all the deficiencies observed, do a relative prioritization so that the leadership can concentrate on key risks.
Come up with a defined action plan for mitigation of the gaps identified in conjunction with the Management.
Give positive assurance to the Audit Committee on the operational and financial controls. This will also assist the Board in commenting on operating effectiveness of operating as well as financial controls across processes. Approach to Internal Audit is an ideal mix of traditional orthodox audit approach and process driven risk based approach, focusing on evaluating the end- to- end process risks and evaluating design and operating effectiveness of controls, using a sampling methodology<br>
slide16. Audit Analytics – An integral part of our IA Methodology Planning Data Analytics Substantive Testing Based on process understanding and walkthrough , identify analysis relevant to the audit
Identify data fields required for analyzing each control matrices and define the requirements for extracting the data.
Extract relevant reports from the system required to run the planned analytics Do the analysis (Excel) on the data dumps obtained
Discuss preliminary exceptions with the process owners
Fine tune results by removing false positives Based on the exceptions identified through data analytics, select samples for substantive testing
Carry out substantive testing and report exceptions<br>
slide17. Balanced scorecard slide 1 Focus: Process & control efficiency
Impact: Systematic process & control improvement, cost reduction
Report: Analysis, facts & circumstances; recommended actions Process Efficiency Focus: Enabling, drive into strategic gaps
Impact: Influence strategy & deployment; change behavior; leverage technology; strategy/action congruence
Report: Best practices, analysis of strategy/action incongruity, business case for change, off-report assistance Strategic Partnering Monitor Focus: Compliance & controls
Impact: Enhanced controls
Report: Exceptions & recommendations Focus: Align process to support objectives; automate controls & solutions
Impact: Change, influence system development & deployment
Report: Analysis, facts & circumstances, business case for change Process Effectiveness Audit Approach Collaborative & Enabling
Consultative Controls & Compliance Risk Management Strategy Achievement Value Proposition Business
Assurance<br>
slide18. Illustrative<br>
slide19. 19 Internal Audit Service Approach Presentation to management /audit committee
Summary of key risks needing mitigation
Advice on directional matters
summary of status of agreed action
Deliverable : Audit Committee Presentation Implementation/ status follow-up
Maintain dashboard of agreed action
Periodically review/update status of implementation Issue reports
Report capturing in detail the root cause, risk /business impact and recommendations for the issues observed
Executive summary of the leadership team
Deliverable : Audit Report Internal audit calendar
Understand business goals
understand changes in organizational relationships and protocols
Stakeholders mapping
Finalize the annual audit calendar
Evolve and issue rolling plan to all the concerned stakeholders Review process
Understand major processes and associated sub-processes
Assess and identify significant risks and controls
Evaluation of key controls to evaluate operating effectiveness. Issue sheets
Issue sheets are provided to the auditees to arrive at agreement over the issue identified
Co- develop an action plan. Agree action plan, person responsible and due date for implementation Audit closing meeting
Clarify points or issues with unit/management
Resolve open items, if any
Finalise process ratings
Agree follow-up plan Communication protocols embedded into service delivery approach allows multiple connect points<br>
slide20. Deliverables – Contents of the audit report 20<br>
slide21. Balanced scorecard slide 1 21 Governance Structure for Internal Audit Team Members Managing Partners Audit Manager
Audit Team Level 2 Level 3 Management Business Heads / IA Coordinator Present key audit issues raised during the quarter
Define & review long term relationship goals
Highest level for dispute resolution Reviews program information at executive level, resolves issues/makes decisions, confirms direction, provides guidance
Monthly meeting to review progress
Discuss & finalize audit issues
Second level for dispute resolution Ensure smooth day-to-day functioning & guidance to auditors
Review the operational performance
First level for dispute resolution Level 1 Process Owners Engagement Partner<br>
slide22. Balanced scorecard slide 8 Different Stages of Communication of Findings Discussion of Draft: At the conclusion of fieldwork, discussion draft should be submitted to the entity management for their review before the exit meeting Formal Draft: The internal auditor should then prepare a formal draft, taking into account any revision or modification resulting from the exit meeting and other discussions. Final Report: The internal auditor should submit the final report to the appointing authority or such members of management, as directed. Exit Meeting: At this meeting, entity’s management should comment on the draft and the internal audit team should work to achieve consensus and reach an agreement on the internal audit findings<br>
slide23. DRAFTING OF OBSERVATIONS – Illustrative Illustrative<br>
slide24. Illustrative<br>
slide25. Illustrative<br>
slide26. Opportunities<br>
slide27. Emerging Trends in Risk Management:<br>
slide28. OPPORTUNITIES Compliance and Prevention Operating Performance Stakeholder Value
Enhancement Act on Opportunity
Customer Relationship Management.
Data management.
Competitive advantage. Avoid Risk
Legal liability
Fines/penalties
Reputation risk Efficiencies
Continuous Improvements
Standardize Processes
People, Paper, Processes REALIZATION OF POTENTIAL<br>
slide29. Opportunities: Following are the types of audits carried out by Internal auditors:
Compliance Audit: To ensure Compliance with rules, regulations and Laws applicable to a company.
Operational Audit: To ensure Effective & Efficient conduct of operations of a company.
Information System Audit: To ensure Proper Functioning of Information System throughout the life of a Business.
Performance Audit: To ensure the efficient use of resources to obtain the objectives of a Company.
Environmental Audits: To Ensure Compliance with the Environmental Laws & Regulations.
Special Assignments: relate to Investigations on fraud and Corruption, or any other Special service with the approval of the Board.<br>
slide30. Internal Auditors helps to achieve the right balance between risk and reward by establishing an environment for timely and effective response to the ever changing business risks. 30 How We Help Our Customers:<br>
slide31. Thank you Balanced scorecard slide 10 CA Rajnikant M. Patel<br>