
SABOA Presentation to the Parliamentary Portfolio







Description: SABOA Presentation to the Parliamentary Portfolio Committee on Transport on the commuter bus industry 4 August 2015 Overview of the presentation The financial crisis in the industry A cost model to depicting the impact of the lack of
Related Topics
Download Presentation
"SABOA Presentation to the Parliamentary Portfolio" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. SABOA Presentation to the Parliamentary Portfolio Committee on Transport on the commuter bus industry 4 August 2015<br>
slide2. Overview of the presentation The financial crisis in the industry
A cost model to depicting the impact of the lack of adequate industry funding
The operational impact of the lack of adequate funding on operators (Gauteng example)
SABOA initiatives to address the funding issue
Conclusions on the funding issue
Options in dealing with the funding issue
The empowerment of SMMEs
Operational issues
Conclusions<br>
slide3. The context of the financial crisis in the commuter bus industry The financial crisis in the commuter bus industry is escalating due to the inadequate annual increase of the PTOG supplementary grant
Since 2009 commuter bus subsidies have been included as a conditional grant in DORA
To remove the funding uncertainty for the DoT due to the passenger-type subsidy that existed up to 2009 (unknown and escalating passenger volumes)
To ensure that the commuter subsidies are used by the provinces for this purpose (ring-fenced)
To change from a passenger subsidy to a kilometer-based subsidy and to cap the kilometres operated for each operator
To provide a three year forward view of expected subsidies
The PTOG is seen as a supplementary grant and it is expected of provinces to assist in funding the shortfall between the grant amount and the cost escalation experienced by operators – based on agreed escalation formulae in the operating contracts<br>
slide4. The contractual relationship between provinces and bus operators Transport authorities (provinces) contract bus companies to render services. These authorities specify in their contracts with operators matters such as:
Escalation formulae (agreed to with industry)
Time tables
Fare levels
Routes and service frequencies
Route kms
Approval of fare increases
Fleet age profile
The industry renders these services based on the contract specifications whilst being exposed to exchange rates, uncontrollable fuel costs and Bargaining Council decisions on wages.
An estimated 50% - 60% of industry costs are impacted by exchange rates affecting the costs of imported engines, gearboxes, rear axles, bus electronics, diesel costs, ticket machines etc.
To compensate for cost increases contracts contain negotiated and agreed escalation formulae<br>
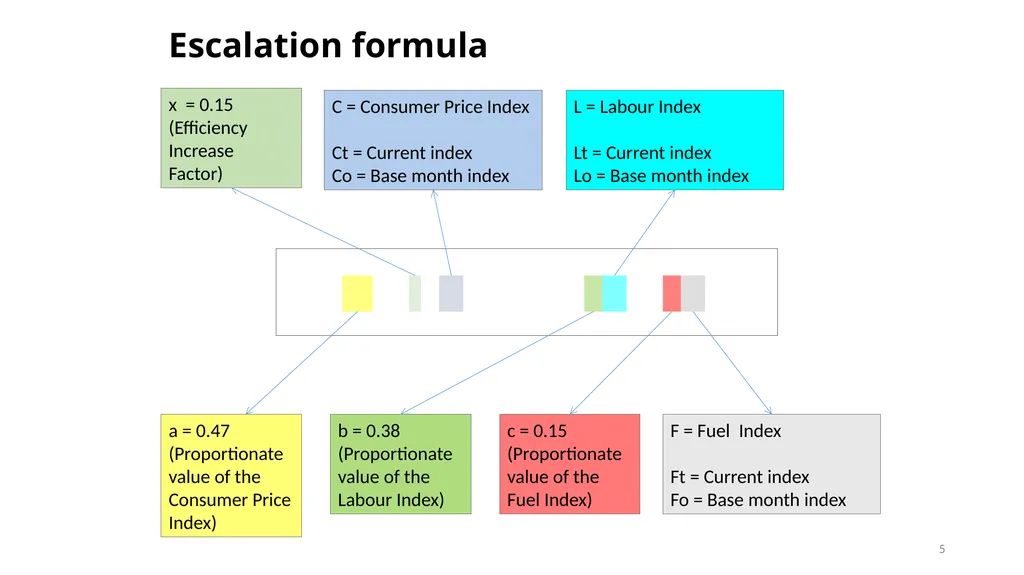
slide5. Escalation formula a = 0.47 (Proportionate value of the Consumer Price Index) x = 0.15 (Efficiency Increase
Factor) C = Consumer Price Index
Ct = Current index
Co = Base month index b = 0.38 (Proportionate value of the Labour Index) c = 0.15 (Proportionate value of the Fuel Index) L = Labour Index
Lt = Current index
Lo = Base month index F = Fuel Index
Ft = Current index
Fo = Base month index 5<br>
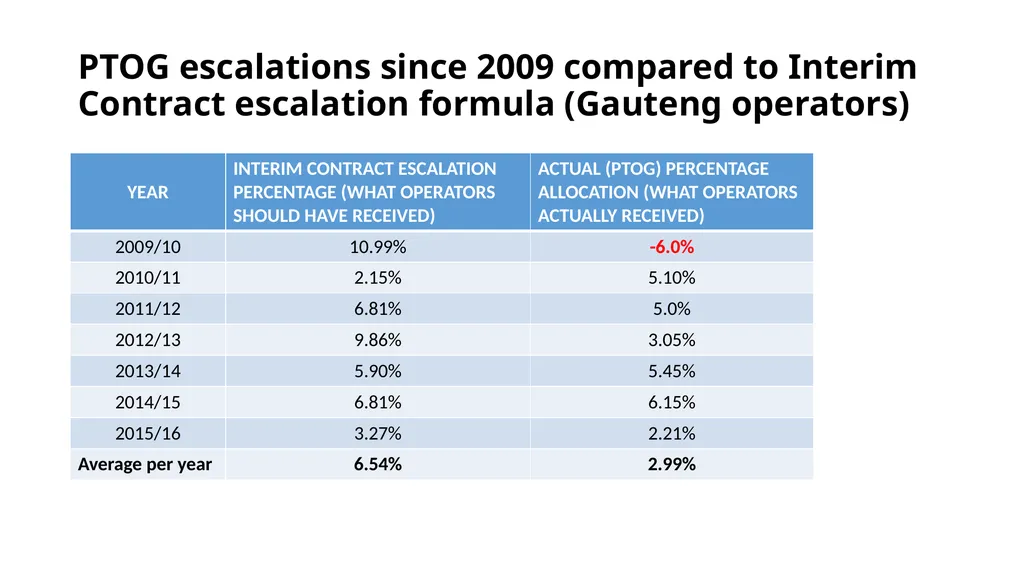
slide6. PTOG escalations since 2009 compared to Interim Contract escalation formula (Gauteng operators)<br>
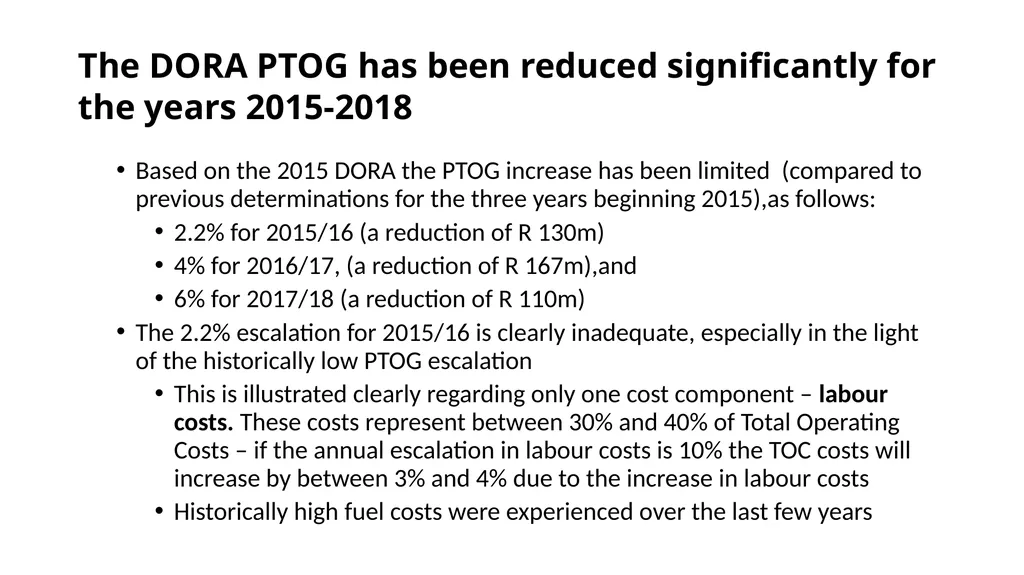
slide7. The DORA PTOG has been reduced significantly for the years 2015-2018 Based on the 2015 DORA the PTOG increase has been limited (compared to previous determinations for the three years beginning 2015),as follows:
2.2% for 2015/16 (a reduction of R 130m)
4% for 2016/17, (a reduction of R 167m),and
6% for 2017/18 (a reduction of R 110m)
The 2.2% escalation for 2015/16 is clearly inadequate, especially in the light of the historically low PTOG escalation
This is illustrated clearly regarding only one cost component – labour costs. These costs represent between 30% and 40% of Total Operating Costs – if the annual escalation in labour costs is 10% the TOC costs will increase by between 3% and 4% due to the increase in labour costs
Historically high fuel costs were experienced over the last few years<br>
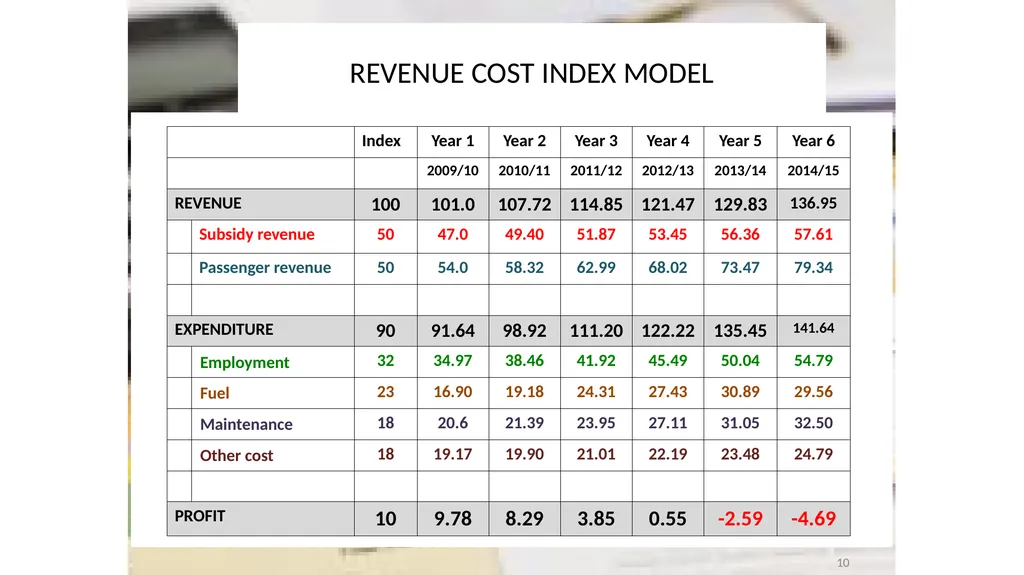
slide8. Cost model depicting the impact of the PTOG A detailed cost model was developed by Thys Heyns to illustrate the impact of the low escalation rates on the financial viability of bus companies
Only the summary and conclusions of the model will be shown here but the total modal is available<br>
slide9. 9 INTERPRETING THE REVENUE-COST INDEX MODEL TO SHOW THE EFFECTS OF THE PTOG ON BUS COMPANIES<br>
slide10. REVENUE COST INDEX MODEL 10<br>
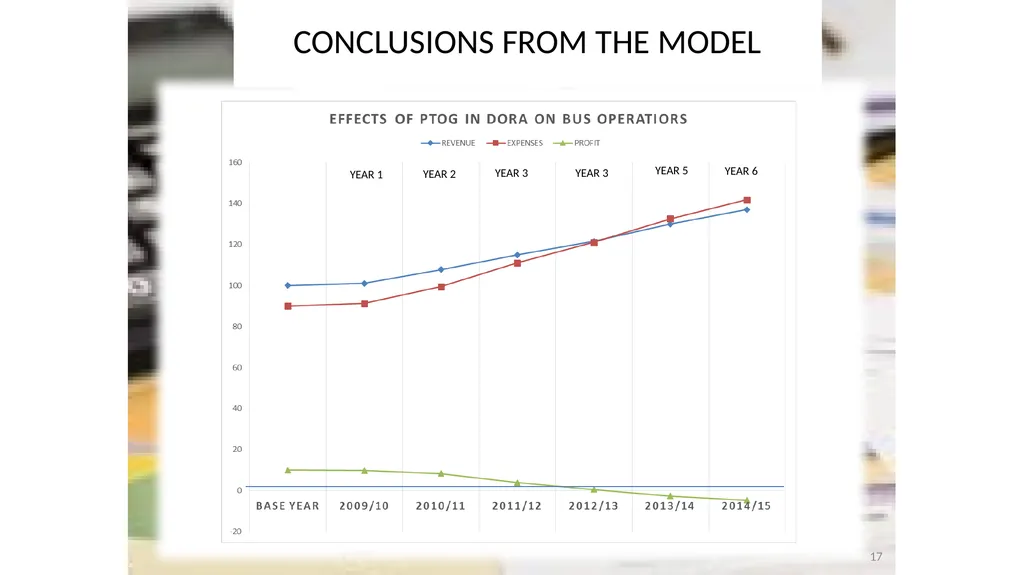
slide11. CONCLUSIONS FROM THE MODEL 11 Based on the Based on the model, we can conclude the following:-
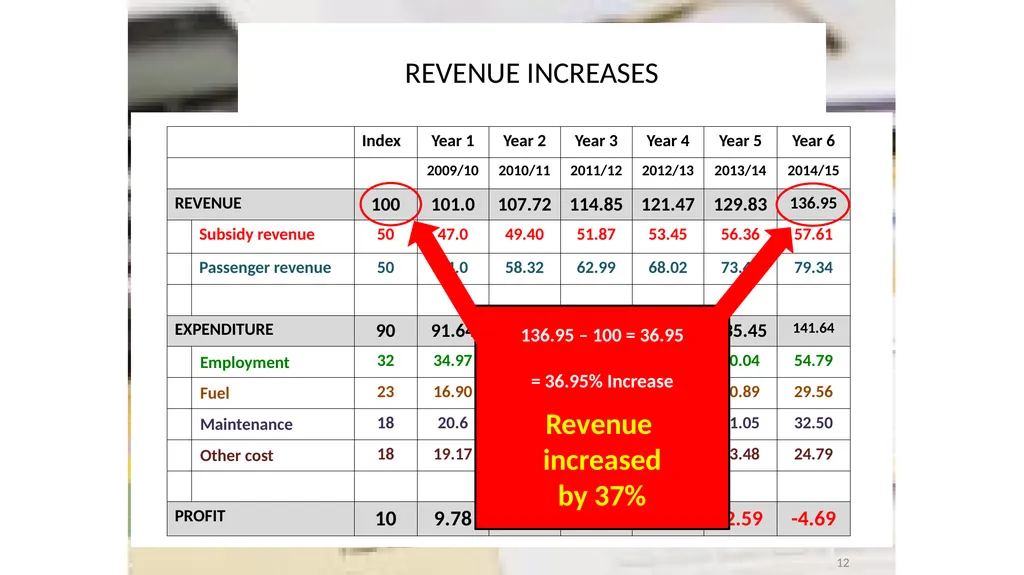
The revenue of a typical commuter bus company increased by 37% over the 6 year period.<br>
slide12. REVENUE INCREASES 12 136.95 – 100 = 36.95
= 36.95% Increase
Revenue
increased
by 37%<br>
slide13. CONCLUSIONS FROM THE MODEL 13 Based on the Based on the model, we can conclude the following:-
The revenue of a typical commuter bus company increased by 37% over the 6 year period.
The expenditure of a typical commuter bus company increased by 57% over the 6 year period (consisting of employment, fuel, maintenance and “other” costs).<br>
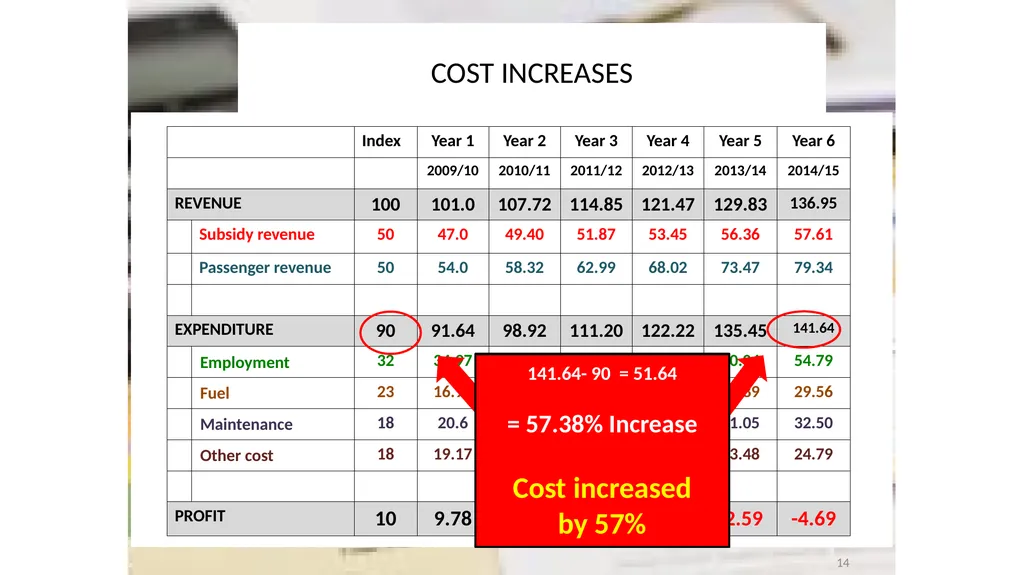
slide14. COST INCREASES 14 141.64- 90 = 51.64
= 57.38% Increase
Cost increased
by 57%<br>
slide15. CONCLUSIONS FROM THE MODEL 15 Based on the Based on the model, we can conclude the following:-
The revenue of a typical commuter bus company increased by 37% over the 6 year period.
The expenditure of a typical commuter bus company increased by 57% over the 5 year period.
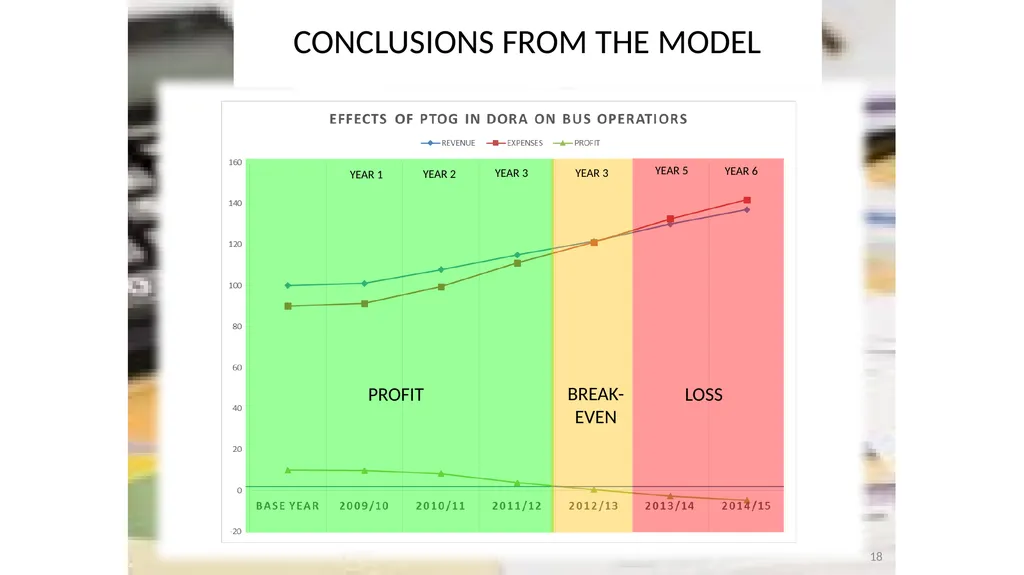
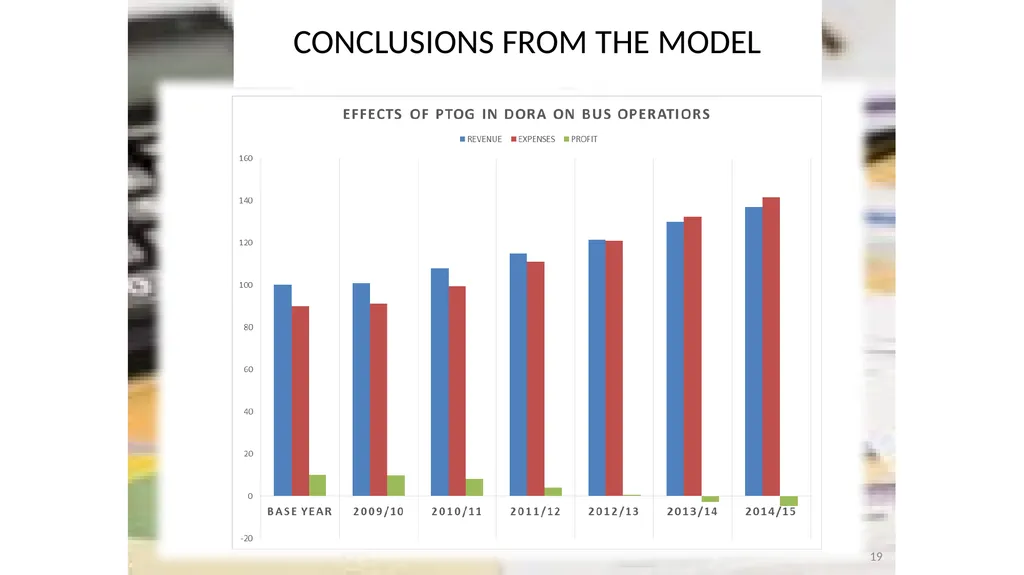
The profit margin of the bus company reduced every year since 2009 and turned into a loss in year 5 and a bigger loss in year 6.<br>
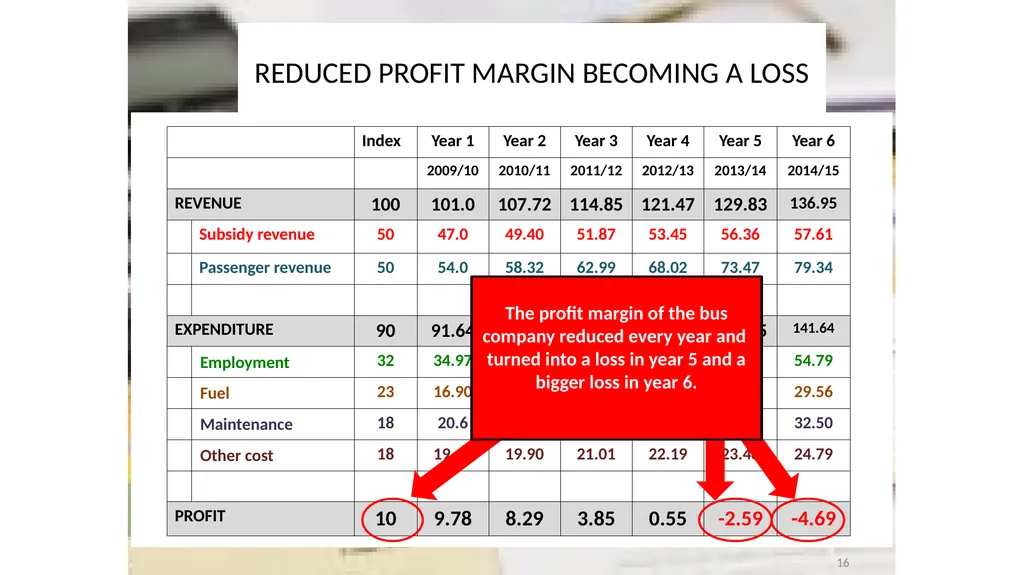
slide16. REDUCED PROFIT MARGIN BECOMING A LOSS 16 The profit margin of the bus company reduced every year and turned into a loss in year 5 and a bigger loss in year 6.<br>
slide17. CONCLUSIONS FROM THE MODEL 17 Based on the YEAR 1 YEAR 2 YEAR 3 YEAR 3 YEAR 5 YEAR 6<br>
slide18. CONCLUSIONS FROM THE MODEL 18 Based on the PROFIT BREAK-EVEN LOSS YEAR 1 YEAR 2 YEAR 3 YEAR 3 YEAR 5 YEAR 6<br>
slide19. CONCLUSIONS FROM THE MODEL 19 Based on the<br>
slide20. OTHER CONCLUSIONS 20 Based on the Based on the model, we can further see the following:-
Subsidies increased by only 15% over the 6 years, while operating costs increased by 57%. This is due to the non-application of the contractual escalation formula.<br>
slide21. THERE WE HAVE AN OBJECTIVE, ACCURATE AND FACTUAL REVENUE – COST INDEX MODEL 21 141.64- 90 = 51.64
= 57.38% Increase
Cost increased
by 57% 57.61 – 50.0 = 7.61
= 15.22% Increase
Subsidy increased by 15%<br>
slide22. OTHER CONCLUSIONS 22 Based on the Based on the model, we can further see the following:-
While expenditure keeps increasing at a faster rate than revenue, all bus companies will fail. Some may fail sooner, some may fail later, but no company can survive this unsustainable business model on the medium and long term.
Profitability and cash flow problems are unavoidable.
Service quality to bus passengers, fleet condition, maintenance standards and eventually safety standards will be compromised if this trend is not reversed.
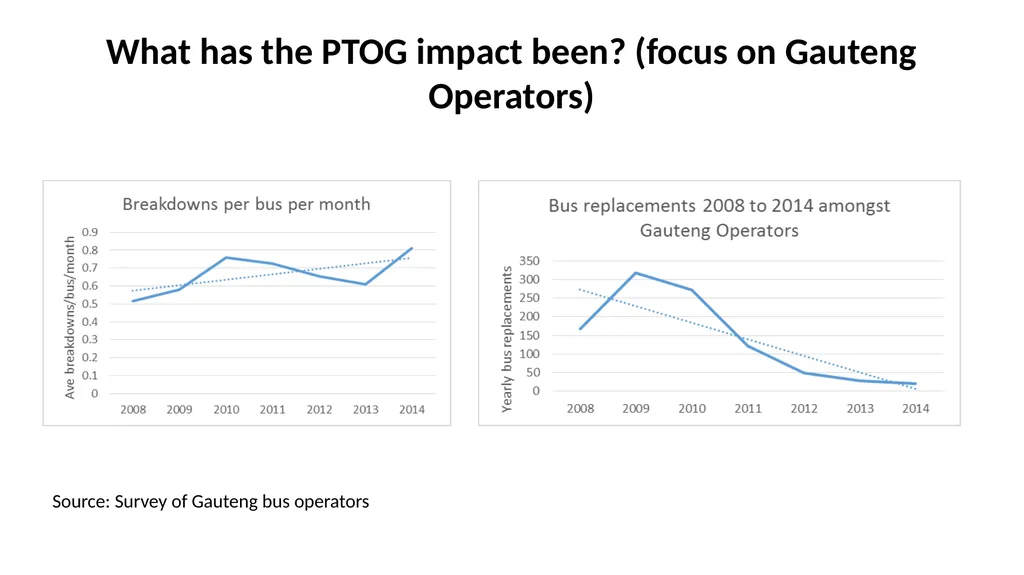
This is already evident amongst Gauteng operators (as evidenced in more bus breakdowns and a lack of adequate bus replacement programmes)<br>
slide23. 23 Based on the NO MATTER HOW YOU LOOK AT THE CURRENT ARRANGEMENT WITH CONVENTIONAL BUS CONTRACTS IN SOUTH AFRICA, IT IS AN
UNSUSTAINABLE
BUSINESS MODEL.<br>
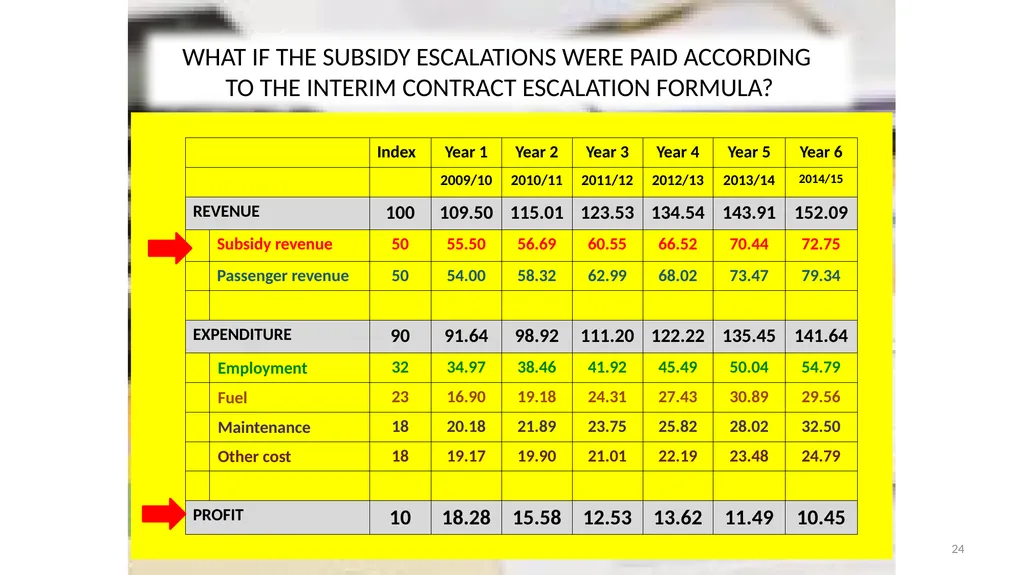
slide24. 24 WHAT IF THE SUBSIDY ESCALATIONS WERE PAID ACCORDING TO THE INTERIM CONTRACT ESCALATION FORMULA?<br>
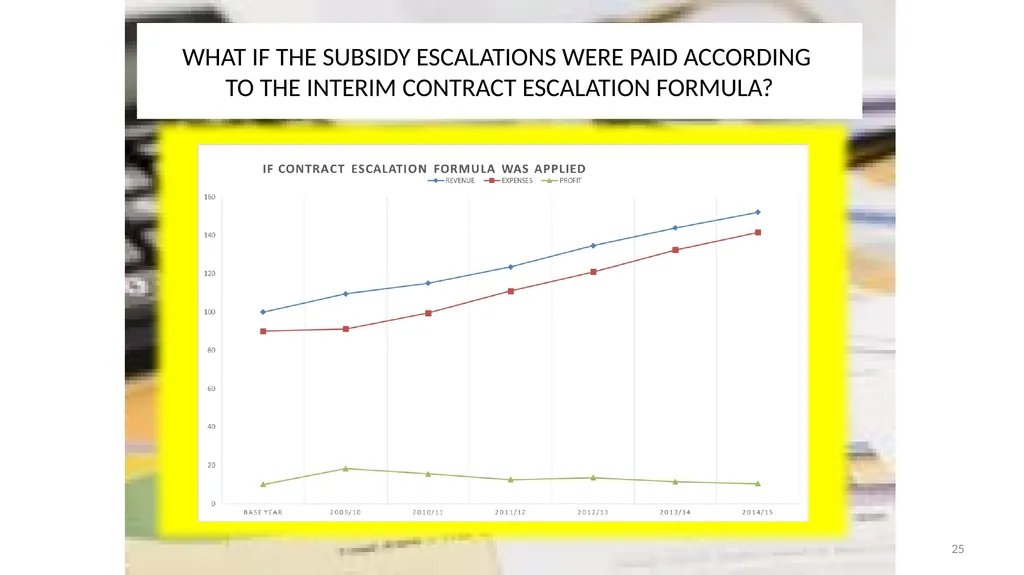
slide25. WHAT IF THE SUBSIDY ESCALATIONS WERE PAID ACCORDING TO THE INTERIM CONTRACT ESCALATION FORMULA? 25<br>
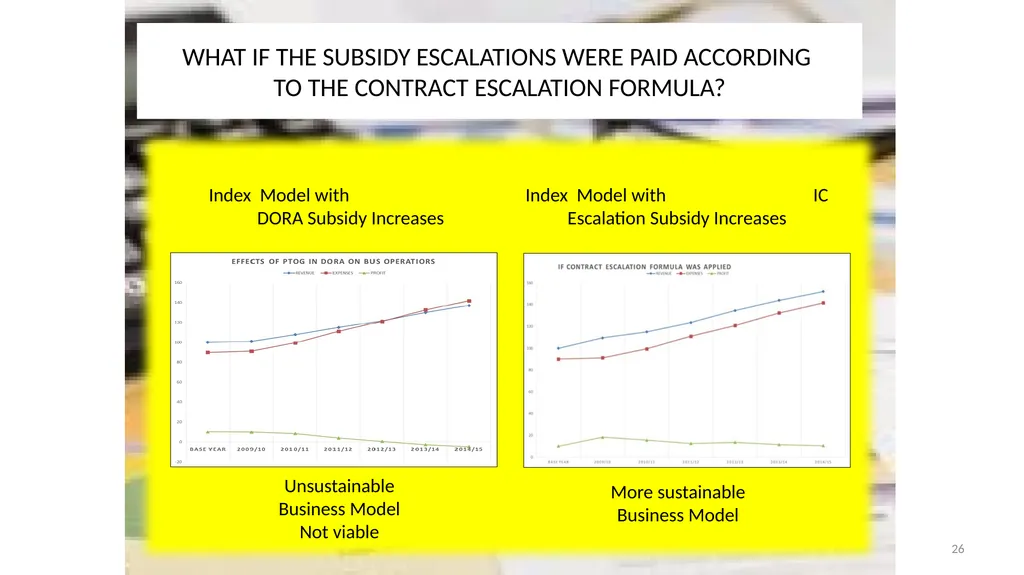
slide26. WHAT IF THE SUBSIDY ESCALATIONS WERE PAID ACCORDING TO THE CONTRACT ESCALATION FORMULA? 26 Index Model with DORA Subsidy Increases Index Model with IC Escalation Subsidy Increases Unsustainable
Business Model
Not viable More sustainable
Business Model<br>
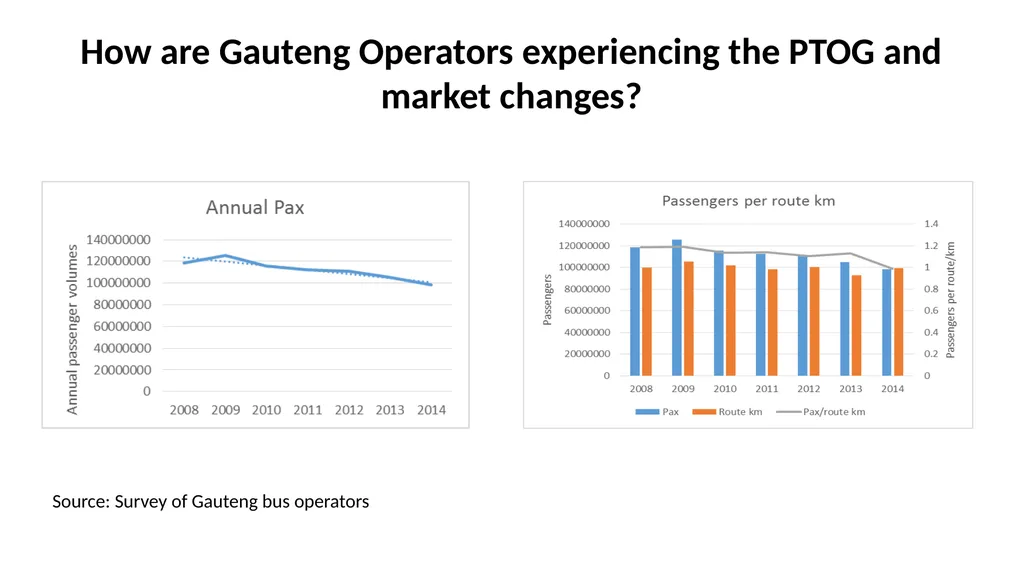
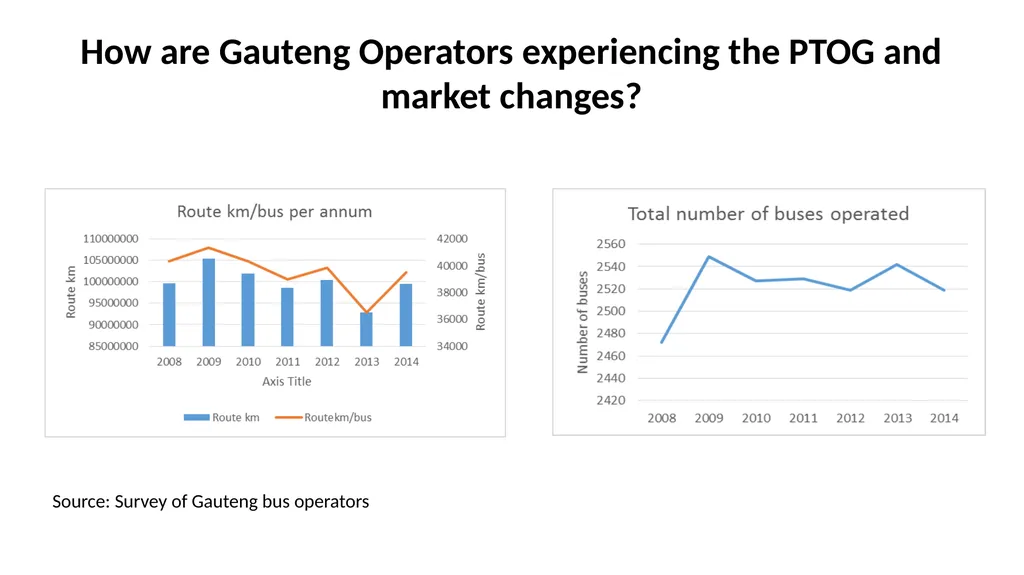
slide27. What has the impact been on bus operations? The following few slides depict the situation of Gauteng operators
Survey was undertaken in 2014
Since then, in 2015, Putco gave up certain non-viable contracts 27<br>
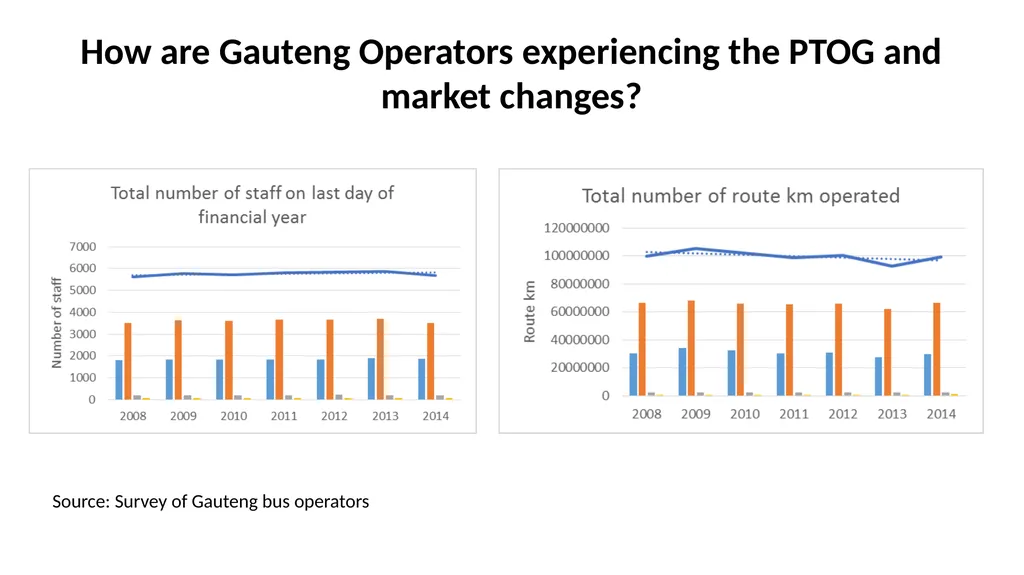
slide28. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
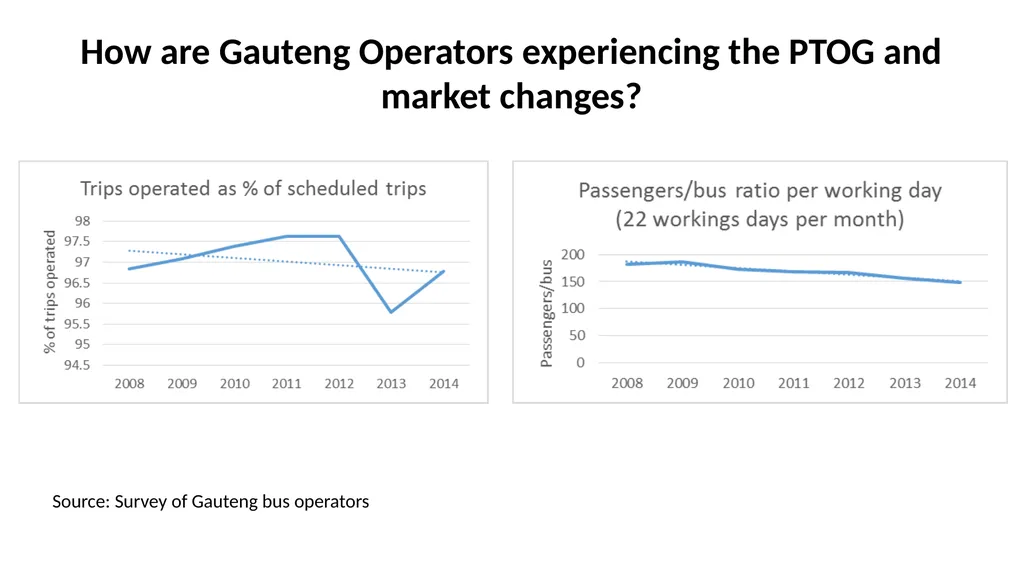
slide29. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
slide30. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
slide31. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
slide32. What has the PTOG impact been? (focus on Gauteng Operators) Source: Survey of Gauteng bus operators<br>
slide33. SABOA initiatives to address the funding matter SABOA has had numerous meetings to bring the financial problem to the attention of the authorities and industry stakeholders
It has been involved in, and facilitated at least 28 meetings with parties such as:
Department of Transport
Dept of Finance
National Treasury (twice)
The Parliamentary Portfolio Committee on Transport (twice)
Gauteng Department of Roads and Transport (numerous meetings)
The Western Cape MEC for Transport
Nedlac; Cosatu; SARPBAC etc.<br>
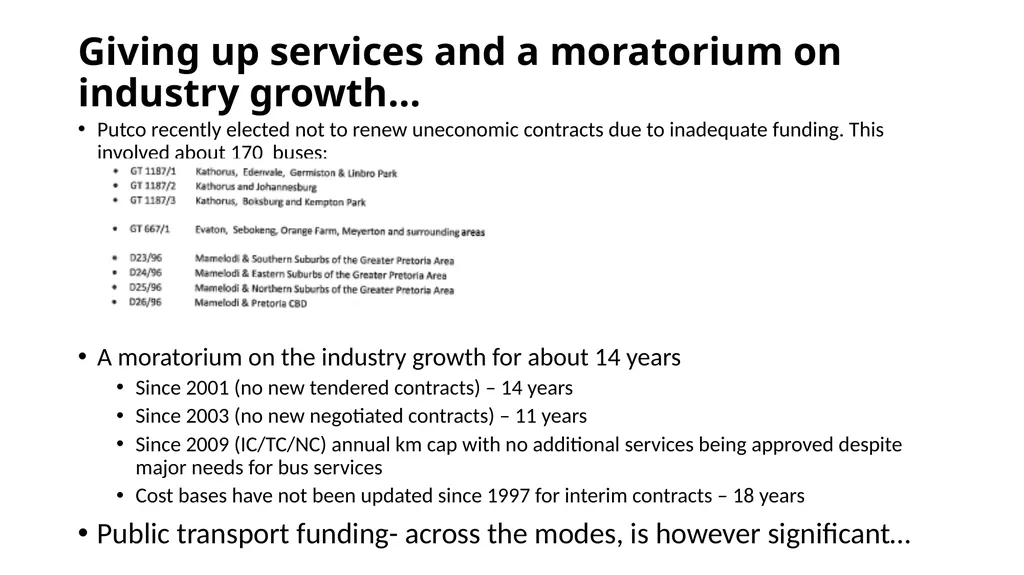
slide34. Giving up services and a moratorium on industry growth… Putco recently elected not to renew uneconomic contracts due to inadequate funding. This involved about 170 buses:
A moratorium on the industry growth for about 14 years
Since 2001 (no new tendered contracts) – 14 years
Since 2003 (no new negotiated contracts) – 11 years
Since 2009 (IC/TC/NC) annual km cap with no additional services being approved despite major needs for bus services
Cost bases have not been updated since 1997 for interim contracts – 18 years
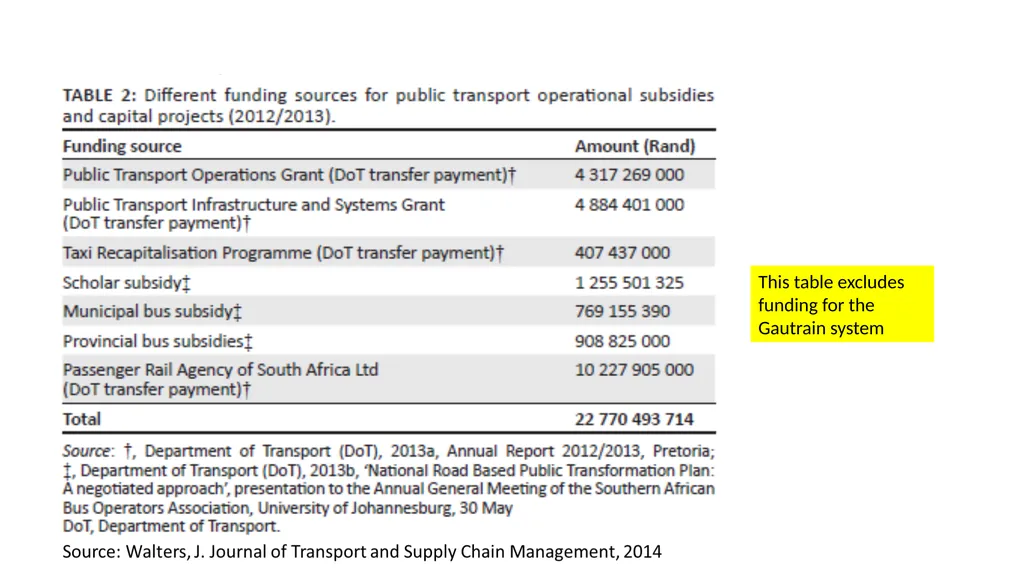
Public transport funding- across the modes, is however significant…<br>
slide35. Current PT funding sources This table excludes funding for the Gautrain system<br>
slide36. The funding of BRTs – are these “value for money”? In the mean time…
Bus sales are flourishing for the BRTs.
The “value for money” proposition of BRT systems need to be re-looked due to SAs low urban densities, the infrastructural and operational cost of these systems (not only now, but also to maintain them in the future) and the potential opportunity costs of investing these funds elsewhere in the public transport system and gaining much more passenger/km benefits
It is, however, extremely difficult to compare the TOC of a conventional bus service with that of a BRT service:
Local Authorities don’t appear to “ring fence” the operational, capital and infrastructure costs of their BRTs to obtain a complete picture of a service’s costs
No reports are available (that we could access) to study the performance of BRTs
Philip van Ryneveld did attempt to quantify these costs…<br>
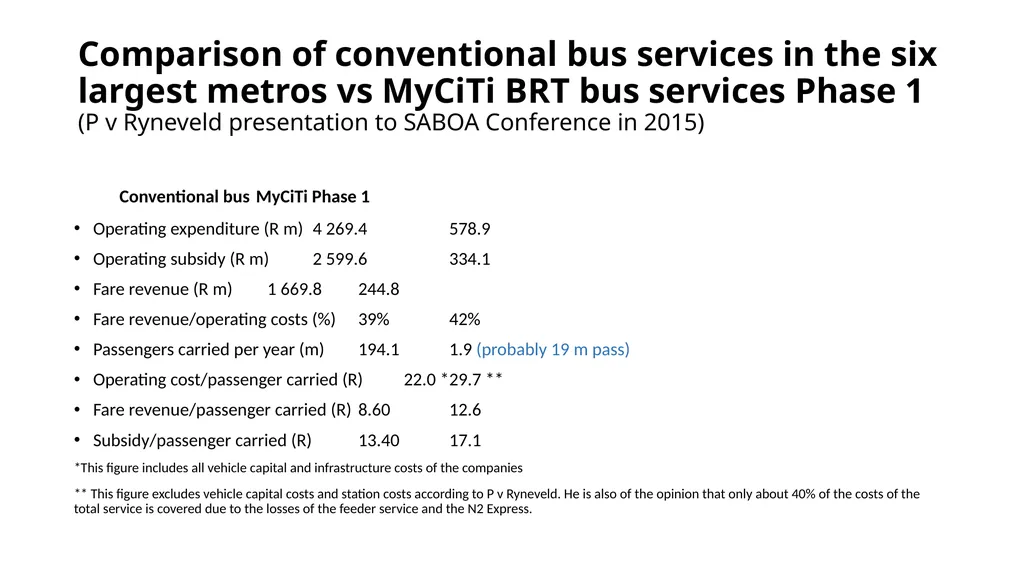
slide37. Comparison of conventional bus services in the six largest metros vs MyCiTi BRT bus services Phase 1 (P v Ryneveld presentation to SABOA Conference in 2015) Conventional bus MyCiTi Phase 1
Operating expenditure (R m) 4 269.4 578.9
Operating subsidy (R m) 2 599.6 334.1
Fare revenue (R m) 1 669.8 244.8
Fare revenue/operating costs (%) 39% 42%
Passengers carried per year (m) 194.1 1.9 (probably 19 m pass)
Operating cost/passenger carried (R) 22.0 * 29.7 **
Fare revenue/passenger carried (R) 8.60 12.6
Subsidy/passenger carried (R) 13.40 17.1
*This figure includes all vehicle capital and infrastructure costs of the companies
** This figure excludes vehicle capital costs and station costs according to P v Ryneveld. He is also of the opinion that only about 40% of the costs of the total service is covered due to the losses of the feeder service and the N2 Express.<br>
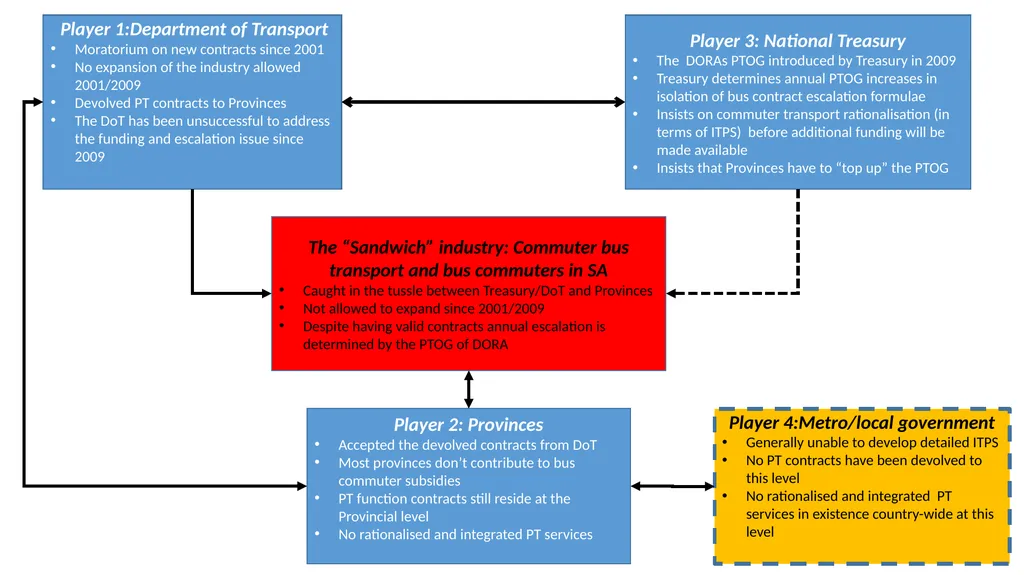
slide38. Conclusions to the funding issues The commuter bus industry has become caught up in “political game playing” as it is continuously deflected by all the industry-relevant governmental institutional structures as no-one wants to take ownership of the current industry financial mess
This is illustrated in the following figure:<br>
slide39. Player 3: National Treasury
The DORAs PTOG introduced by Treasury in 2009
Treasury determines annual PTOG increases in isolation of bus contract escalation formulae
Insists on commuter transport rationalisation (in terms of ITPS) before additional funding will be made available
Insists that Provinces have to “top up” the PTOG Player 1:Department of Transport
Moratorium on new contracts since 2001
No expansion of the industry allowed 2001/2009
Devolved PT contracts to Provinces
The DoT has been unsuccessful to address the funding and escalation issue since 2009 Player 2: Provinces
Accepted the devolved contracts from DoT
Most provinces don’t contribute to bus commuter subsidies
PT function contracts still reside at the Provincial level
No rationalised and integrated PT services Player 4:Metro/local government
Generally unable to develop detailed ITPS
No PT contracts have been devolved to this level
No rationalised and integrated PT services in existence country-wide at this level The “Sandwich” industry: Commuter bus transport and bus commuters in SA
Caught in the tussle between Treasury/DoT and Provinces
Not allowed to expand since 2001/2009
Despite having valid contracts annual escalation is determined by the PTOG of DORA<br>
slide40. Conclusions to the funding issues The lack of concrete action to deal with the bus industry sustainability issues directly affects communities that are public transport dependent
A Two-Tier public transport industry is developing:
Gautrain and BRTs on selected routes as well as the R120b being spent of Commuter Rail, and
Conventional commuter bus and taxi services that provide the bulk of public transport services
The lack of ITPs at the metro/local government level seems to be some years away and calls for a financial stabilisation plan for the bus industry until such time as these plans are implemented.
The industry has NO ability to control the development, roll-out and implementation of ITPs<br>
slide41. Options to deal with the financial issues faced by the industry In the absence of cost-related escalations in the PTOG, as well as the inability and/or unwillingness of provinces to supplement the PTOG, the following are the only reasonable options available:
Continue to ensure that services are operated efficiently and effectively, within the framework of the contractual agreements operators have with the authorities
Withdraw loss-making services
Withdraw services that are operated due to community pressure – mostly non- subsidised
Postpone or reduce the scale of bus replacement programmes
Rationalise services in general (take out bus frequencies)
Provinces however vigorously oppose this option due to the impact on potential job losses and impacts on the mobility of communities<br>
slide42. How rationalisation can be used in practice to keep the rate per kilometre sustainable<br>
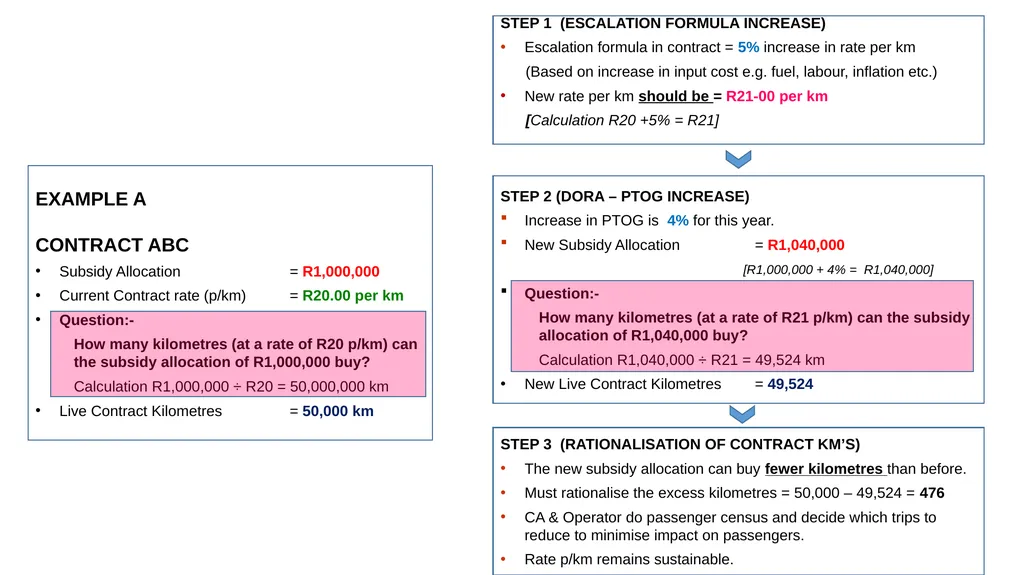
slide43. EXAMPLE A
CONTRACT ABC
Subsidy Allocation = R1,000,000
Current Contract rate (p/km) = R20.00 per km
Question:-
How many kilometres (at a rate of R20 p/km) can the subsidy allocation of R1,000,000 buy?
Calculation R1,000,000 ÷ R20 = 50,000,000 km
Live Contract Kilometres = 50,000 km STEP 1 (ESCALATION FORMULA INCREASE)
Escalation formula in contract = 5% increase in rate per km
(Based on increase in input cost e.g. fuel, labour, inflation etc.)
New rate per km should be = R21-00 per km
[Calculation R20 +5% = R21] STEP 2 (DORA – PTOG INCREASE)
Increase in PTOG is 4% for this year.
New Subsidy Allocation = R1,040,000
[R1,000,000 + 4% = R1,040,000]
Question:-
How many kilometres (at a rate of R21 p/km) can the subsidy allocation of R1,040,000 buy?
Calculation R1,040,000 ÷ R21 = 49,524 km
New Live Contract Kilometres = 49,524 STEP 3 (RATIONALISATION OF CONTRACT KM’S)
The new subsidy allocation can buy fewer kilometres than before.
Must rationalise the excess kilometres = 50,000 – 49,524 = 476
CA & Operator do passenger census and decide which trips to reduce to minimise impact on passengers.
Rate p/km remains sustainable.<br>
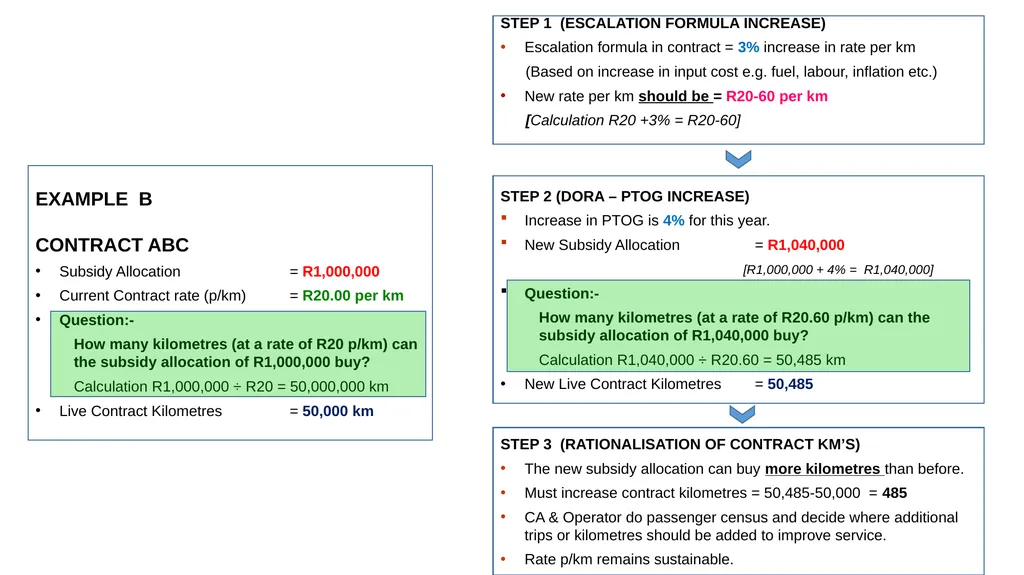
slide44. EXAMPLE B
CONTRACT ABC
Subsidy Allocation = R1,000,000
Current Contract rate (p/km) = R20.00 per km
Question:-
How many kilometres (at a rate of R20 p/km) can the subsidy allocation of R1,000,000 buy?
Calculation R1,000,000 ÷ R20 = 50,000,000 km
Live Contract Kilometres = 50,000 km STEP 1 (ESCALATION FORMULA INCREASE)
Escalation formula in contract = 3% increase in rate per km
(Based on increase in input cost e.g. fuel, labour, inflation etc.)
New rate per km should be = R20-60 per km
[Calculation R20 +3% = R20-60] STEP 2 (DORA – PTOG INCREASE)
Increase in PTOG is 4% for this year.
New Subsidy Allocation = R1,040,000
[R1,000,000 + 4% = R1,040,000]
Question:-
How many kilometres (at a rate of R20.60 p/km) can the subsidy allocation of R1,040,000 buy?
Calculation R1,040,000 ÷ R20.60 = 50,485 km
New Live Contract Kilometres = 50,485 STEP 3 (RATIONALISATION OF CONTRACT KM’S)
The new subsidy allocation can buy more kilometres than before.
Must increase contract kilometres = 50,485-50,000 = 485
CA & Operator do passenger census and decide where additional trips or kilometres should be added to improve service.
Rate p/km remains sustainable.<br>
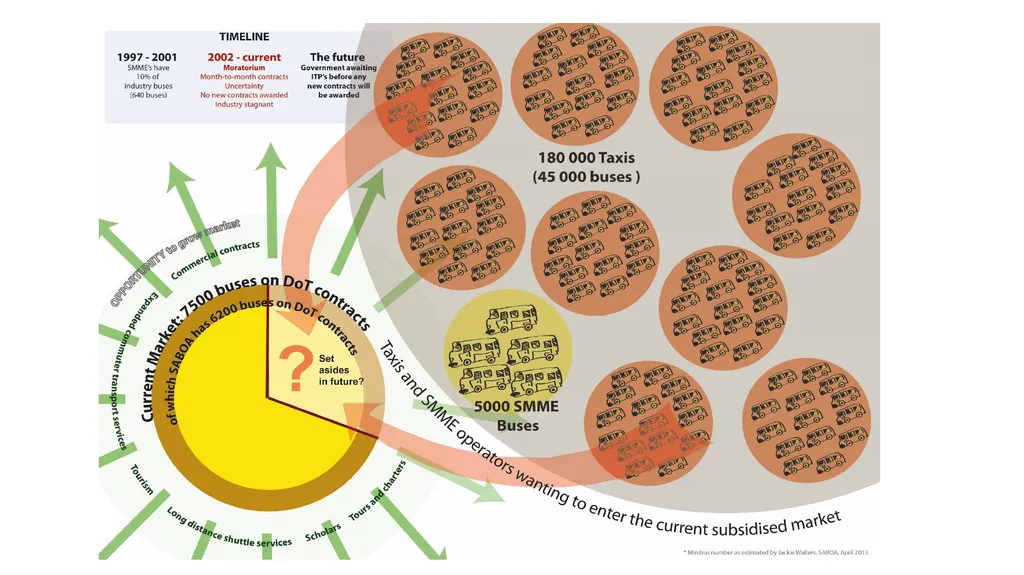
slide45. Empowerment of SMME bus operators SMME bus operators need to become part of the contracting system.
This requirement is also evident from the recent survey that was undertaken by UJ and the Department of Transport.
The taxi industry is being assisted in terms of a vehicle recapitalisation programme and through their involvement in BRT services.
SMME bus operators have received no assistance from government in terms of vehicle recapitalisation and are being excluded from participation in BRT systems.
The average age of vehicles of SMME bus operators are in excess of 20 years and are in urgent need to be upgraded / replaced. If not addressed soon, it could become a major safety risk.
Without long-term contracts as security, financial institutions are reluctant to grant SMME bus operators loans for the purchasing of vehicles
But…. the funding issues must be addressed to fundamentally transform the PT industry<br>
slide47. Operational issues: Taxi intimidation Taxi intimidation is escalating and affects large and small (SMME) bus operators.
Bus operators are viewed as “soft targets.”
A strong message needs to be sent to the taxi industry by government to stop intimidation
Taxi intimidation is experienced in Gauteng, Eastern Cape, Northwest, Limpopo, KZN and on cross-border routes.
Taxi intimidation and violence is mainly due to an overtraded situation in the taxi industry<br>
slide48. Operational issues: Operating licence issues Most PRE’s / OLB’s are not functioning effectively.
Long delays are being experienced by operators at most of the PRE’s/ OLB’s to finalise their applications for operating licenses.
Even “over the counter” applications are taking weeks and in some instances months to be finalised before permits/operating licenses are issued.
PRE’s / OLB’s are reluctant to meet with the industry to address the industry’s concerns.
Even the National Department of Transport is experiencing difficulties to assist the industry in setting up meetings with PRE’s / OLB’s.
The NPTR needs to be made operational as a matter of urgency so that it can fulfil its function to, inter alia, “oversee public transport in the country in general and the activities of Provincial Regulatory Entities and municipalities in relation to their land transport functions.”<br>
slide49. Conclusion It is proposed that a number of Task Teams be constituted to discuss and provide guidelines on:
The funding issues of the industry (inclusive of Provinces, LAs and Treasury)
Rationalisation options (Inclusive of Provinces, LAs and Treasury)
Empowerment of SMME bus operators
Operational issues faced by the industry<br>
slide50. Thank You<br>
slide2. Overview of the presentation The financial crisis in the industry
A cost model to depicting the impact of the lack of adequate industry funding
The operational impact of the lack of adequate funding on operators (Gauteng example)
SABOA initiatives to address the funding issue
Conclusions on the funding issue
Options in dealing with the funding issue
The empowerment of SMMEs
Operational issues
Conclusions<br>
slide3. The context of the financial crisis in the commuter bus industry The financial crisis in the commuter bus industry is escalating due to the inadequate annual increase of the PTOG supplementary grant
Since 2009 commuter bus subsidies have been included as a conditional grant in DORA
To remove the funding uncertainty for the DoT due to the passenger-type subsidy that existed up to 2009 (unknown and escalating passenger volumes)
To ensure that the commuter subsidies are used by the provinces for this purpose (ring-fenced)
To change from a passenger subsidy to a kilometer-based subsidy and to cap the kilometres operated for each operator
To provide a three year forward view of expected subsidies
The PTOG is seen as a supplementary grant and it is expected of provinces to assist in funding the shortfall between the grant amount and the cost escalation experienced by operators – based on agreed escalation formulae in the operating contracts<br>
slide4. The contractual relationship between provinces and bus operators Transport authorities (provinces) contract bus companies to render services. These authorities specify in their contracts with operators matters such as:
Escalation formulae (agreed to with industry)
Time tables
Fare levels
Routes and service frequencies
Route kms
Approval of fare increases
Fleet age profile
The industry renders these services based on the contract specifications whilst being exposed to exchange rates, uncontrollable fuel costs and Bargaining Council decisions on wages.
An estimated 50% - 60% of industry costs are impacted by exchange rates affecting the costs of imported engines, gearboxes, rear axles, bus electronics, diesel costs, ticket machines etc.
To compensate for cost increases contracts contain negotiated and agreed escalation formulae<br>
slide5. Escalation formula a = 0.47 (Proportionate value of the Consumer Price Index) x = 0.15 (Efficiency Increase
Factor) C = Consumer Price Index
Ct = Current index
Co = Base month index b = 0.38 (Proportionate value of the Labour Index) c = 0.15 (Proportionate value of the Fuel Index) L = Labour Index
Lt = Current index
Lo = Base month index F = Fuel Index
Ft = Current index
Fo = Base month index 5<br>
slide6. PTOG escalations since 2009 compared to Interim Contract escalation formula (Gauteng operators)<br>
slide7. The DORA PTOG has been reduced significantly for the years 2015-2018 Based on the 2015 DORA the PTOG increase has been limited (compared to previous determinations for the three years beginning 2015),as follows:
2.2% for 2015/16 (a reduction of R 130m)
4% for 2016/17, (a reduction of R 167m),and
6% for 2017/18 (a reduction of R 110m)
The 2.2% escalation for 2015/16 is clearly inadequate, especially in the light of the historically low PTOG escalation
This is illustrated clearly regarding only one cost component – labour costs. These costs represent between 30% and 40% of Total Operating Costs – if the annual escalation in labour costs is 10% the TOC costs will increase by between 3% and 4% due to the increase in labour costs
Historically high fuel costs were experienced over the last few years<br>
slide8. Cost model depicting the impact of the PTOG A detailed cost model was developed by Thys Heyns to illustrate the impact of the low escalation rates on the financial viability of bus companies
Only the summary and conclusions of the model will be shown here but the total modal is available<br>
slide9. 9 INTERPRETING THE REVENUE-COST INDEX MODEL TO SHOW THE EFFECTS OF THE PTOG ON BUS COMPANIES<br>
slide10. REVENUE COST INDEX MODEL 10<br>
slide11. CONCLUSIONS FROM THE MODEL 11 Based on the Based on the model, we can conclude the following:-
The revenue of a typical commuter bus company increased by 37% over the 6 year period.<br>
slide12. REVENUE INCREASES 12 136.95 – 100 = 36.95
= 36.95% Increase
Revenue
increased
by 37%<br>
slide13. CONCLUSIONS FROM THE MODEL 13 Based on the Based on the model, we can conclude the following:-
The revenue of a typical commuter bus company increased by 37% over the 6 year period.
The expenditure of a typical commuter bus company increased by 57% over the 6 year period (consisting of employment, fuel, maintenance and “other” costs).<br>
slide14. COST INCREASES 14 141.64- 90 = 51.64
= 57.38% Increase
Cost increased
by 57%<br>
slide15. CONCLUSIONS FROM THE MODEL 15 Based on the Based on the model, we can conclude the following:-
The revenue of a typical commuter bus company increased by 37% over the 6 year period.
The expenditure of a typical commuter bus company increased by 57% over the 5 year period.
The profit margin of the bus company reduced every year since 2009 and turned into a loss in year 5 and a bigger loss in year 6.<br>
slide16. REDUCED PROFIT MARGIN BECOMING A LOSS 16 The profit margin of the bus company reduced every year and turned into a loss in year 5 and a bigger loss in year 6.<br>
slide17. CONCLUSIONS FROM THE MODEL 17 Based on the YEAR 1 YEAR 2 YEAR 3 YEAR 3 YEAR 5 YEAR 6<br>
slide18. CONCLUSIONS FROM THE MODEL 18 Based on the PROFIT BREAK-EVEN LOSS YEAR 1 YEAR 2 YEAR 3 YEAR 3 YEAR 5 YEAR 6<br>
slide19. CONCLUSIONS FROM THE MODEL 19 Based on the<br>
slide20. OTHER CONCLUSIONS 20 Based on the Based on the model, we can further see the following:-
Subsidies increased by only 15% over the 6 years, while operating costs increased by 57%. This is due to the non-application of the contractual escalation formula.<br>
slide21. THERE WE HAVE AN OBJECTIVE, ACCURATE AND FACTUAL REVENUE – COST INDEX MODEL 21 141.64- 90 = 51.64
= 57.38% Increase
Cost increased
by 57% 57.61 – 50.0 = 7.61
= 15.22% Increase
Subsidy increased by 15%<br>
slide22. OTHER CONCLUSIONS 22 Based on the Based on the model, we can further see the following:-
While expenditure keeps increasing at a faster rate than revenue, all bus companies will fail. Some may fail sooner, some may fail later, but no company can survive this unsustainable business model on the medium and long term.
Profitability and cash flow problems are unavoidable.
Service quality to bus passengers, fleet condition, maintenance standards and eventually safety standards will be compromised if this trend is not reversed.
This is already evident amongst Gauteng operators (as evidenced in more bus breakdowns and a lack of adequate bus replacement programmes)<br>
slide23. 23 Based on the NO MATTER HOW YOU LOOK AT THE CURRENT ARRANGEMENT WITH CONVENTIONAL BUS CONTRACTS IN SOUTH AFRICA, IT IS AN
UNSUSTAINABLE
BUSINESS MODEL.<br>
slide24. 24 WHAT IF THE SUBSIDY ESCALATIONS WERE PAID ACCORDING TO THE INTERIM CONTRACT ESCALATION FORMULA?<br>
slide25. WHAT IF THE SUBSIDY ESCALATIONS WERE PAID ACCORDING TO THE INTERIM CONTRACT ESCALATION FORMULA? 25<br>
slide26. WHAT IF THE SUBSIDY ESCALATIONS WERE PAID ACCORDING TO THE CONTRACT ESCALATION FORMULA? 26 Index Model with DORA Subsidy Increases Index Model with IC Escalation Subsidy Increases Unsustainable
Business Model
Not viable More sustainable
Business Model<br>
slide27. What has the impact been on bus operations? The following few slides depict the situation of Gauteng operators
Survey was undertaken in 2014
Since then, in 2015, Putco gave up certain non-viable contracts 27<br>
slide28. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
slide29. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
slide30. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
slide31. How are Gauteng Operators experiencing the PTOG and market changes? Source: Survey of Gauteng bus operators<br>
slide32. What has the PTOG impact been? (focus on Gauteng Operators) Source: Survey of Gauteng bus operators<br>
slide33. SABOA initiatives to address the funding matter SABOA has had numerous meetings to bring the financial problem to the attention of the authorities and industry stakeholders
It has been involved in, and facilitated at least 28 meetings with parties such as:
Department of Transport
Dept of Finance
National Treasury (twice)
The Parliamentary Portfolio Committee on Transport (twice)
Gauteng Department of Roads and Transport (numerous meetings)
The Western Cape MEC for Transport
Nedlac; Cosatu; SARPBAC etc.<br>
slide34. Giving up services and a moratorium on industry growth… Putco recently elected not to renew uneconomic contracts due to inadequate funding. This involved about 170 buses:
A moratorium on the industry growth for about 14 years
Since 2001 (no new tendered contracts) – 14 years
Since 2003 (no new negotiated contracts) – 11 years
Since 2009 (IC/TC/NC) annual km cap with no additional services being approved despite major needs for bus services
Cost bases have not been updated since 1997 for interim contracts – 18 years
Public transport funding- across the modes, is however significant…<br>
slide35. Current PT funding sources This table excludes funding for the Gautrain system<br>
slide36. The funding of BRTs – are these “value for money”? In the mean time…
Bus sales are flourishing for the BRTs.
The “value for money” proposition of BRT systems need to be re-looked due to SAs low urban densities, the infrastructural and operational cost of these systems (not only now, but also to maintain them in the future) and the potential opportunity costs of investing these funds elsewhere in the public transport system and gaining much more passenger/km benefits
It is, however, extremely difficult to compare the TOC of a conventional bus service with that of a BRT service:
Local Authorities don’t appear to “ring fence” the operational, capital and infrastructure costs of their BRTs to obtain a complete picture of a service’s costs
No reports are available (that we could access) to study the performance of BRTs
Philip van Ryneveld did attempt to quantify these costs…<br>
slide37. Comparison of conventional bus services in the six largest metros vs MyCiTi BRT bus services Phase 1 (P v Ryneveld presentation to SABOA Conference in 2015) Conventional bus MyCiTi Phase 1
Operating expenditure (R m) 4 269.4 578.9
Operating subsidy (R m) 2 599.6 334.1
Fare revenue (R m) 1 669.8 244.8
Fare revenue/operating costs (%) 39% 42%
Passengers carried per year (m) 194.1 1.9 (probably 19 m pass)
Operating cost/passenger carried (R) 22.0 * 29.7 **
Fare revenue/passenger carried (R) 8.60 12.6
Subsidy/passenger carried (R) 13.40 17.1
*This figure includes all vehicle capital and infrastructure costs of the companies
** This figure excludes vehicle capital costs and station costs according to P v Ryneveld. He is also of the opinion that only about 40% of the costs of the total service is covered due to the losses of the feeder service and the N2 Express.<br>
slide38. Conclusions to the funding issues The commuter bus industry has become caught up in “political game playing” as it is continuously deflected by all the industry-relevant governmental institutional structures as no-one wants to take ownership of the current industry financial mess
This is illustrated in the following figure:<br>
slide39. Player 3: National Treasury
The DORAs PTOG introduced by Treasury in 2009
Treasury determines annual PTOG increases in isolation of bus contract escalation formulae
Insists on commuter transport rationalisation (in terms of ITPS) before additional funding will be made available
Insists that Provinces have to “top up” the PTOG Player 1:Department of Transport
Moratorium on new contracts since 2001
No expansion of the industry allowed 2001/2009
Devolved PT contracts to Provinces
The DoT has been unsuccessful to address the funding and escalation issue since 2009 Player 2: Provinces
Accepted the devolved contracts from DoT
Most provinces don’t contribute to bus commuter subsidies
PT function contracts still reside at the Provincial level
No rationalised and integrated PT services Player 4:Metro/local government
Generally unable to develop detailed ITPS
No PT contracts have been devolved to this level
No rationalised and integrated PT services in existence country-wide at this level The “Sandwich” industry: Commuter bus transport and bus commuters in SA
Caught in the tussle between Treasury/DoT and Provinces
Not allowed to expand since 2001/2009
Despite having valid contracts annual escalation is determined by the PTOG of DORA<br>
slide40. Conclusions to the funding issues The lack of concrete action to deal with the bus industry sustainability issues directly affects communities that are public transport dependent
A Two-Tier public transport industry is developing:
Gautrain and BRTs on selected routes as well as the R120b being spent of Commuter Rail, and
Conventional commuter bus and taxi services that provide the bulk of public transport services
The lack of ITPs at the metro/local government level seems to be some years away and calls for a financial stabilisation plan for the bus industry until such time as these plans are implemented.
The industry has NO ability to control the development, roll-out and implementation of ITPs<br>
slide41. Options to deal with the financial issues faced by the industry In the absence of cost-related escalations in the PTOG, as well as the inability and/or unwillingness of provinces to supplement the PTOG, the following are the only reasonable options available:
Continue to ensure that services are operated efficiently and effectively, within the framework of the contractual agreements operators have with the authorities
Withdraw loss-making services
Withdraw services that are operated due to community pressure – mostly non- subsidised
Postpone or reduce the scale of bus replacement programmes
Rationalise services in general (take out bus frequencies)
Provinces however vigorously oppose this option due to the impact on potential job losses and impacts on the mobility of communities<br>
slide42. How rationalisation can be used in practice to keep the rate per kilometre sustainable<br>
slide43. EXAMPLE A
CONTRACT ABC
Subsidy Allocation = R1,000,000
Current Contract rate (p/km) = R20.00 per km
Question:-
How many kilometres (at a rate of R20 p/km) can the subsidy allocation of R1,000,000 buy?
Calculation R1,000,000 ÷ R20 = 50,000,000 km
Live Contract Kilometres = 50,000 km STEP 1 (ESCALATION FORMULA INCREASE)
Escalation formula in contract = 5% increase in rate per km
(Based on increase in input cost e.g. fuel, labour, inflation etc.)
New rate per km should be = R21-00 per km
[Calculation R20 +5% = R21] STEP 2 (DORA – PTOG INCREASE)
Increase in PTOG is 4% for this year.
New Subsidy Allocation = R1,040,000
[R1,000,000 + 4% = R1,040,000]
Question:-
How many kilometres (at a rate of R21 p/km) can the subsidy allocation of R1,040,000 buy?
Calculation R1,040,000 ÷ R21 = 49,524 km
New Live Contract Kilometres = 49,524 STEP 3 (RATIONALISATION OF CONTRACT KM’S)
The new subsidy allocation can buy fewer kilometres than before.
Must rationalise the excess kilometres = 50,000 – 49,524 = 476
CA & Operator do passenger census and decide which trips to reduce to minimise impact on passengers.
Rate p/km remains sustainable.<br>
slide44. EXAMPLE B
CONTRACT ABC
Subsidy Allocation = R1,000,000
Current Contract rate (p/km) = R20.00 per km
Question:-
How many kilometres (at a rate of R20 p/km) can the subsidy allocation of R1,000,000 buy?
Calculation R1,000,000 ÷ R20 = 50,000,000 km
Live Contract Kilometres = 50,000 km STEP 1 (ESCALATION FORMULA INCREASE)
Escalation formula in contract = 3% increase in rate per km
(Based on increase in input cost e.g. fuel, labour, inflation etc.)
New rate per km should be = R20-60 per km
[Calculation R20 +3% = R20-60] STEP 2 (DORA – PTOG INCREASE)
Increase in PTOG is 4% for this year.
New Subsidy Allocation = R1,040,000
[R1,000,000 + 4% = R1,040,000]
Question:-
How many kilometres (at a rate of R20.60 p/km) can the subsidy allocation of R1,040,000 buy?
Calculation R1,040,000 ÷ R20.60 = 50,485 km
New Live Contract Kilometres = 50,485 STEP 3 (RATIONALISATION OF CONTRACT KM’S)
The new subsidy allocation can buy more kilometres than before.
Must increase contract kilometres = 50,485-50,000 = 485
CA & Operator do passenger census and decide where additional trips or kilometres should be added to improve service.
Rate p/km remains sustainable.<br>
slide45. Empowerment of SMME bus operators SMME bus operators need to become part of the contracting system.
This requirement is also evident from the recent survey that was undertaken by UJ and the Department of Transport.
The taxi industry is being assisted in terms of a vehicle recapitalisation programme and through their involvement in BRT services.
SMME bus operators have received no assistance from government in terms of vehicle recapitalisation and are being excluded from participation in BRT systems.
The average age of vehicles of SMME bus operators are in excess of 20 years and are in urgent need to be upgraded / replaced. If not addressed soon, it could become a major safety risk.
Without long-term contracts as security, financial institutions are reluctant to grant SMME bus operators loans for the purchasing of vehicles
But…. the funding issues must be addressed to fundamentally transform the PT industry<br>
slide47. Operational issues: Taxi intimidation Taxi intimidation is escalating and affects large and small (SMME) bus operators.
Bus operators are viewed as “soft targets.”
A strong message needs to be sent to the taxi industry by government to stop intimidation
Taxi intimidation is experienced in Gauteng, Eastern Cape, Northwest, Limpopo, KZN and on cross-border routes.
Taxi intimidation and violence is mainly due to an overtraded situation in the taxi industry<br>
slide48. Operational issues: Operating licence issues Most PRE’s / OLB’s are not functioning effectively.
Long delays are being experienced by operators at most of the PRE’s/ OLB’s to finalise their applications for operating licenses.
Even “over the counter” applications are taking weeks and in some instances months to be finalised before permits/operating licenses are issued.
PRE’s / OLB’s are reluctant to meet with the industry to address the industry’s concerns.
Even the National Department of Transport is experiencing difficulties to assist the industry in setting up meetings with PRE’s / OLB’s.
The NPTR needs to be made operational as a matter of urgency so that it can fulfil its function to, inter alia, “oversee public transport in the country in general and the activities of Provincial Regulatory Entities and municipalities in relation to their land transport functions.”<br>
slide49. Conclusion It is proposed that a number of Task Teams be constituted to discuss and provide guidelines on:
The funding issues of the industry (inclusive of Provinces, LAs and Treasury)
Rationalisation options (Inclusive of Provinces, LAs and Treasury)
Empowerment of SMME bus operators
Operational issues faced by the industry<br>
slide50. Thank You<br>