SALES TAX GUIDELINES FOR SCHOOL DISTRICTS Purchases Admissions Sales By: Marissa D. Walker, Staff Auditor Purchases Certificate of Exemption ONLY applies to purchases. Exemption DOES NOT apply to sales. Purchases by schools should support
Related Topics
Share
Embed code
Download this presentation From Below
"SALES TAX GUIDELINES FOR SCHOOL DISTRICTS" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
SALES TAX GUIDELINES FOR SCHOOL DISTRICTS Purchases
Admissions
Sales
By: Marissa D. Walker, Staff Auditor<br>
02
Purchases Certificate of Exemption ONLY applies to purchases. Exemption DOES NOT apply to sales.
Purchases by schools should support the exempt nature of the School District which is to provide a quality education to Pasco County students.
Purchases are either for the school’s use or for resale.
If the purchase is for school use, it is exempt.
If the purchase is for resale, it is taxable.<br>
03
Option to pay tax to supplier on cost of items resold Per Rule 12A-1.0011, schools have the option of paying tax to suppliers on the cost of certain items purchased for resale (rather than collect sales tax at the time of sale):
School materials and supplies (supplies sold at the school store, instruments, uniforms).
Items sold for fundraising (such as candy, y-ties, greeting cards, T-shirts, smencils, sports bottles, car magnets, and similar items).<br>
04
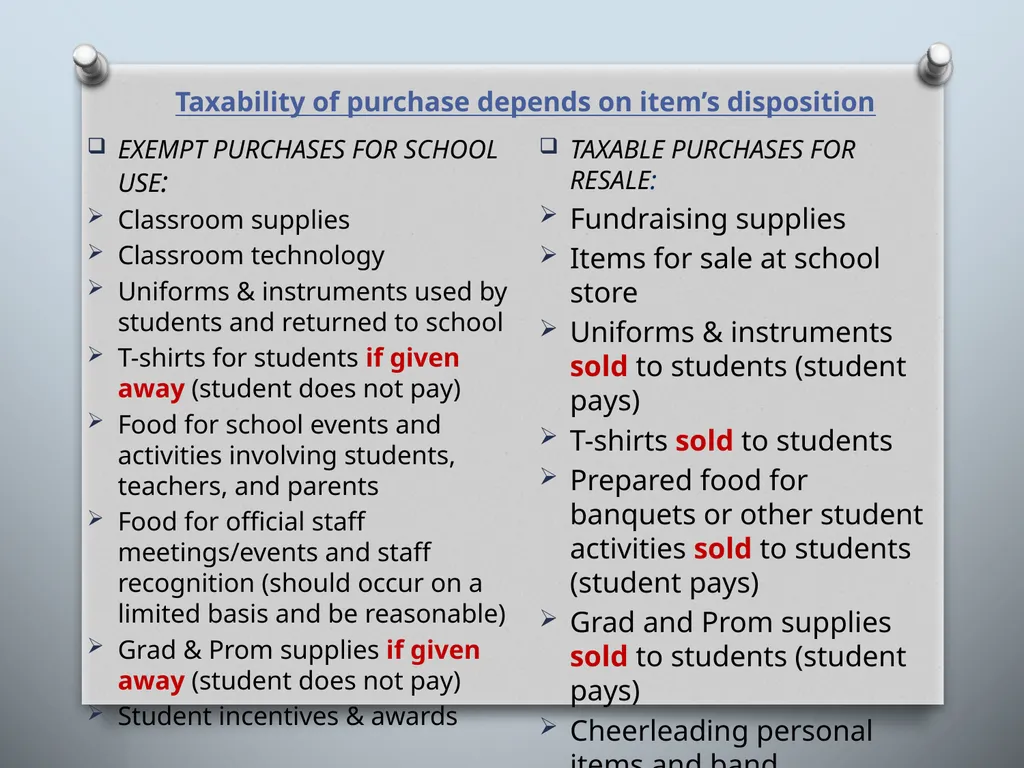
Taxability of purchase depends on item’s disposition EXEMPT PURCHASES FOR SCHOOL USE:
Classroom supplies
Classroom technology
Uniforms & instruments used by students and returned to school
T-shirts for students if given away (student does not pay)
Food for school events and activities involving students, teachers, and parents
Food for official staff meetings/events and staff recognition (should occur on a limited basis and be reasonable)
Grad & Prom supplies if given away (student does not pay)
Student incentives & awards TAXABLE PURCHASES FOR RESALE:
Fundraising supplies
Items for sale at school store
Uniforms & instruments sold to students (student pays)
T-shirts sold to students
Prepared food for banquets or other student activities sold to students (student pays)
Grad and Prom supplies sold to students (student pays)
Cheerleading personal items and band consumables sold to students (student pays)<br>
05
Promotion and Public Relations These expenditures include activities related to student registration, official meetings and receptions, recognition of service of a staff member, and staff hospitality.
Per State Board of Education Rule 6A-1.0143, these expenditures should “directly benefit” or “be in the best interest of the district”.<br>
06
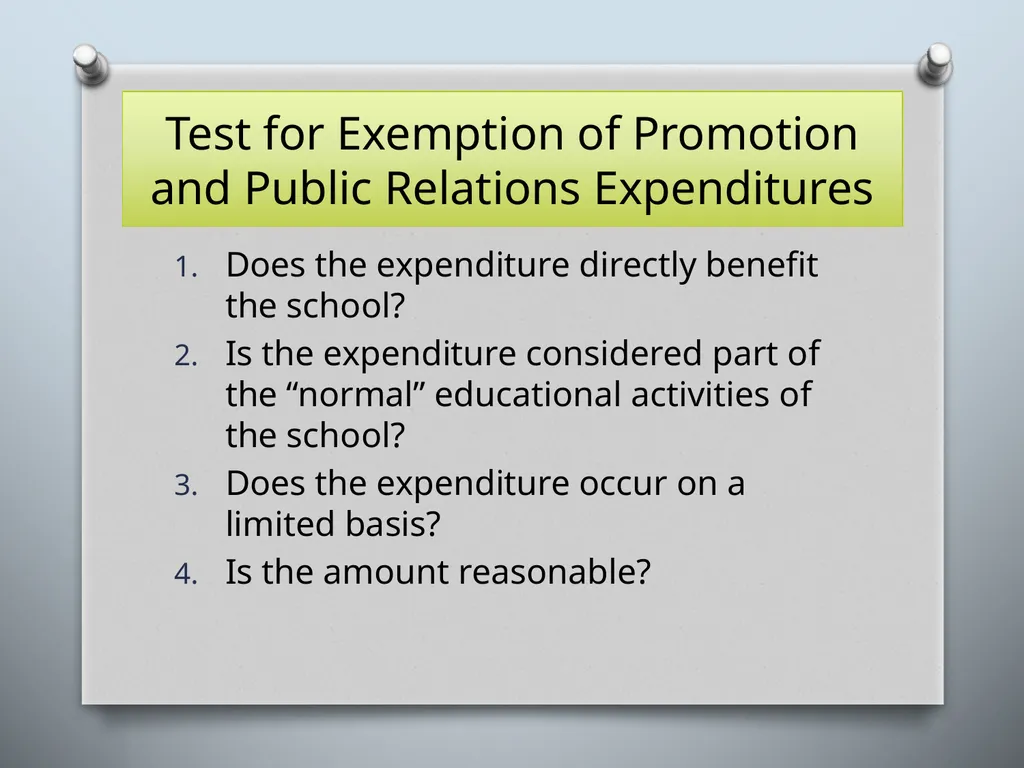
Test for Exemption of Promotion and Public Relations Expenditures Does the expenditure directly benefit the school?
Is the expenditure considered part of the “normal” educational activities of the school?
Does the expenditure occur on a limited basis?
Is the amount reasonable?<br>
07
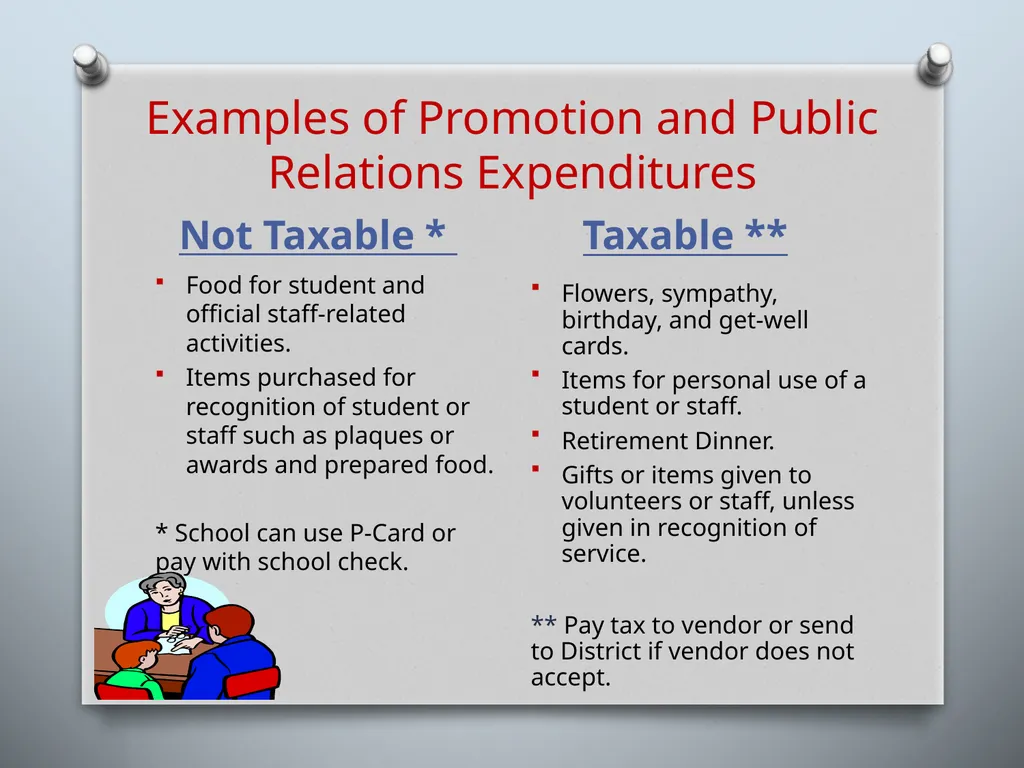
Examples of Promotion and Public Relations Expenditures Not Taxable * Taxable ** Food for student and official staff-related activities.
Items purchased for recognition of student or staff such as plaques or awards and prepared food.
* School can use P-Card or pay with school check. Flowers, sympathy, birthday, and get-well cards.
Items for personal use of a student or staff.
Retirement Dinner.
Gifts or items given to volunteers or staff, unless given in recognition of service.
** Pay tax to vendor or send to District if vendor does not accept.<br>
08
Examples of Exempt Promotion and Public Relations Examples of food for student and official staff-related activities and items purchased for recognition:
Parent/Teacher and Staff Planning Meetings
Teacher and Bus Driver Appreciation
I-Moms, All-Pro Dads, Mentors, Volunteers
Student incentives, recognition awards
Athletics banquet (student does not pay)
Student of the Month, Teacher of the Year
Judges participating in a school activity<br>
09
Admissions Admission to an athletic or other event sponsored by a school where ONLY student or faculty is used is exempt. (Rule 12A-1.005)
Examples:
School sporting events
School drama plays
School band concerts<br>
10
Resale of Admissions Rule 12A-1.005(5) An admission is considered to be resold when we collect money from the student to pay for the admission. The school purchases an admission for the students and then “resells” the admission to the students or requires the student to pay.
A school CANNOT buy an admission tax exempt if the admission will be “resold” or paid by an individual outside the school.<br>
11
Resale of Admissions Field Trips, Grad Night, Senior Prom, and other student activities that involve the resale of admissions are TAXABLE. If the student pays for the admission, the purchase of the admission is taxable to the school (the individual does not have the exemption, the school does; the school is used as a “pass-thru” to buy the admission).
If an admission is resold to students at cost or less, sales tax IS NOT collected from the student. (Example A)
If an admission is resold to students for more than cost, sales tax IS collected from the student based on the sales price. (Example B)<br>
12
Resale of Admissions-Example A Example A: The school purchases admission tickets for Grad Night at $53.50 (includes tax paid) per student and resells the tickets to the students at $53.50 or less.
the school is required to pay tax on the purchase of the admission. NO tax will be charged on the “sale” of the admission.<br>
13
Resale of Admissions-Example B Example B: The school purchases admission tickets for Grad Night at $53.50 (includes tax paid) per student and resells the tickets to the students at $55.00:
the school is required to collect sales tax from the sale of the admission if it resells the admission at a higher price.<br>
14
Taxable Sales at Adult Ed Centers Textbooks sold to adults.
Tool kits sold to adults, i.e. carpentry and cosmetology tools.
Safety glasses sold to adults.
Scrubs and uniforms sold to adults.
ID badges sold to adults.
(Rule 12A-1.0011 applies to K-12 only)<br>
15
Tax Exempt Sales Sales of textbooks and workbooks for K-12 students.
Sales of yearbooks.
Sales of food and beverages served in the school cafeteria as part of the regular school lunch served to students (teachers, school employees and school guests also exempt).<br>