
THE IMPACT OF THE FINANCIAL AND ECONOMIC CRISIS



Description: THE IMPACT OF THE FINANCIAL AND ECONOMIC CRISIS UPON GLOBAL INSECURITY: LOOKING THROUGH THE LENS OF NATO TO 2020 AND BEYOND Adrian Kendry Former NATO Head of Defence and Security Economics and Senior Defence Economist 2001-2013
Related Topics
Download Presentation
"THE IMPACT OF THE FINANCIAL AND ECONOMIC CRISIS" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. THE IMPACT OF THE FINANCIAL AND ECONOMIC CRISIS UPON GLOBAL INSECURITY:
LOOKING THROUGH THE LENS OF NATO TO 2020 AND BEYOND Adrian Kendry
Former NATO Head of
Defence and Security Economics
and
Senior Defence Economist 2001-2013
adriankendry@hotmail.com 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 1<br>
slide2. THUCYDIDES AND FUNERAL ORATION FOR PERICLES (495-429 BC)
“It is not a matter of predicting the future but of being prepared“ 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 2<br>
slide3. NATO 2001-2013: AN ALLIANCE IN EVOLUTION Members :
19 nations (01) v 28 (13)
Partners:
NATO-Russia Council (2002)
NATO Ukraine Commission (1997)
Euro-Atlantic Partnership Council (28 + 21) and
Partnership for Peace Bilateral Cooperation
Mediterranean Dialogue (7)
Istanbul Cooperation Initiative (4)
Partners across the Globe (8) (AFG, AUS, IRQ, JAP, RoK, NZ, MONG, PAK) 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 3<br>
slide4. NATO 2001-2013: A PERSONAL HISTORY 2001 - 2003: 9/11, Iraq: NATO and the Transatlantic Relationship: the Economic and Financial Dimensions of Countering Terrorism
2004: The Istanbul Summit: The Partnership Action Plan on Defence Institution Building and the inception of the Building Integrity programme on accountability and transparency in the defence and security sector
2005-2009: Defining NATO’s Role in Energy Security: The Economics and Security of Energy
2010-2012: Afghanistan and regional economic security: Assessing Afghanistan’s economic capacity post 2014
2009-2013: The Financial and Economic Crisis: Understanding, measuring and assessing the impact of the crisis on NATO budgets and capabilities 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 4<br>
slide5. NATO: THE THREE GAPS 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 5<br>
slide6. THE PROLOGUE: NATO AND THE TALE OF THREE GAPS The Intra-European gap:
Will NATO European Allies still be capable of operating together in international crisis management?
The Transatlantic Gap:
Will the growing imbalance in transatlantic defence spending undermine US support for NATO?
The Global Gap:
Will the emerging economic powers increase their capacity for regional action and international influence at a time when NATO’s capacities could diminish 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 6<br>
slide7. THE PROLOGUE: NATO AND THE TALE OF THREE GAPS Disproportionate defence cuts are likely to weaken NATO military forces and the industries that support them, and also undermine innovation, exports, and employment
Additionally, inadequate defence spending and investment will exacerbate economic insecurity linked to emerging security challenges
The Emerging Security Challenges Division came into being in 2010 and is increasingly pre-occupied with cyber security and NATO’s contribution to national cyber security efforts 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 7<br>
slide8. GLOBAL INSECURITIES: THE PRESENT 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 8<br>
slide9. NATO FOREIGN MINISTERIAL 3-4 DECEMBER 2013: CONFRONTING GLOBAL REALITIES The NATO 2014 Summit in the UK: Afghanistan, partnerships and improving military capabilities
Measures to strengthen NATO partnerships across the globe 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 9<br>
slide10. NATO FOREIGN MINISTERIAL 3-4 DECEMBER 2013: CONFRONTING GLOBAL REALITIES The NATO Russia Council and closing the disagreement on Syria, Afghanistan, Missile Defence and Transparency
Afghanistan 2014 and the end of ISAF: NATO will work closely with the Afghan government in the weeks ahead to put in place the necessary legal framework for the deployment of the NATO-led mission to train, advise and assist the Afghan security forces after 2014 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 10<br>
slide11. NATO POST-AFGHANISTAN In 2015 NATO will no longer have a combat operation and will shift from being “Operationally Engaged” to being “Operationally Prepared”
NATO will need to maintain effective capabilities through reinforcing the three pillars of collective defence, cooperative security and crisis response operations
Measuring the costs of investing in security and insecurity 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 11<br>
slide12. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 12 “All countries are increasingly reliant on the vital communication, transport and transit routes on which international trade, energy security and prosperity depend. They require greater international efforts to ensure their resilience against attack or disruption” NATO’S STRATEGIC CONCEPT, EMERGING SECURITY CHALLENGES AND ECONOMIC SECURITY: FROM LISBON TO CHICAGO<br>
slide13. GLOBAL INSECURITIES: A HUNDRED YEARS OF TURMOIL 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 13<br>
slide14. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 14 ONE HUNDRED YEARS OF INSECURITY: FROM 1913 TO 2013 1913: The Road to Sarajevo and World War One global conflict
1963: United States: assassinations, and racial insecurity<br>
slide15. ONE HUNDRED YEARS OF INSECUITY: 2013 Syria: economics, religion and regional conflict
Afghanistan, Elections and ISAF withdrawal 2014
Iran, the Gulf and consequences of the nuclear accord
Transatlantic economic fragility:
January and February 2014: return of US budget and debt crisis
Continuing frailty of the Eurozone economy 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 15<br>
slide16. ONE HUNDRED YEARS OF INSECURITY: 2013 The East China Sea: China, Japan, the Diaoyou and Senkaku Islands: Strategic competition and growing tensions
Caught in the Middle: the conflicting ambitions of Ukraine, the EU Eastern Partnership and Russia
The Central African Republic: resources, but political fragility, weak infrastructure and business insecurity equal feeble growth and poverty reduction 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 16<br>
slide17. THE ECONOMIC AND SECURITY CHALLENGES FOR THE TRANSATLANTIC PARTNERSHIP 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 17<br>
slide18. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 18 THE FUTURE OF THE TRANSATLANTIC TRADE AND INVESTMENT PARTNERSHIP The transatlantic economy is the largest and wealthiest market in the world
54% of world GDP in terms of value and 40% in terms of purchasing power
Even with the financial crisis, US and EU financial markets continue to account for more than 66% of global banking assets and 75% of global financial services 18<br>
slide19. The Demographic Time bomb: the declining working-age population, the growing implicit debt on pensions and medical care
The Widening Economic Capability Gap between the USA and Europe
The United States Fiscal Cliff and the impact of Fiscal Impasse and Sequestration on federal budget deficits, federal debt
Energy Independence and Dependence: Europe’s growing import dependency and the US growing self-sufficiency (but the continuing importance of the Gulf of Guinea) THE ECONOMIC AND SECURITY CHALLENGES FOR THE TRANSATLANTIC PARTNERSHIP 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 19<br>
slide20. OECD high-income countries median age will rise from 37.9 years in 2010 to 42.8 years by 2030
Increasing percentage of people aged 65 years and above— the pensions bulge
Pressure to reduce discretionary state spending and increase the tax burden 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 20 THE DEMOGRAPHIC DESTINY<br>
slide21. Natural gas prices have fallen sharply in the US with the prospects of becoming a major energy exporter in the 2020s
The European Union’s foreign energy dependency is expected to rise to 70% in the next 20-30 years and higher prices will undermine European economic competitiveness
European increasing dependency will clash with the emerging economic powers in pursuing energy and other scarce resources. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 21 TRANSATLANTIC ENERGY DEPENDENCY<br>
slide22. NATO AND THE CONSEQUENCES OF THE ECONOMIC AND FINANCIAL CRISIS 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 22<br>
slide23. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 23 THE ECONOMIC CRISIS AND RISKS TO SECURITY "I am clear that the single biggest strategic risk facing the UK today is economic rather than military“
Gen Sir David Richards, Chief of the UK Defence Staff, (RUSI 2012)<br>
slide24. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 24 Article 2 of the 1949 North Atlantic Treaty (“eliminate conflict in international economic policies....”)
Impact of crisis on Alliance and Partners:
DIRECT negative consequences (Common Funding, defence expenditure, capabilities, multinational weapons projects, missions and operations)
INDIRECT negative consequences: failed states, international economic aid, shifts in global balance of economic power, climate change, energy security, scarcity of water and food, migration, poverty and extremism NATO AND THE GLOBAL ECONOMIC AND FINANCIAL CRISIS<br>
slide25. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 25 SMART DEFENCE AND ECONOMIC AUSTERITY Most European defence budgets experienced smaller reductions than other sectors of government 2010-2011(Alliance commitments, contractual obligations, industrial concerns)
Unsustainable defence spending projections 2011-2016: fiscal deficits and debts imply deep cuts in force levels, capabilities, readiness and delayed procurement
UK, France and Germany are crucial for NATO Europe: 65% of all NATO Europe Defence Expenditure, 88% of Research and Technology<br>
slide26. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 26 SMART BUDGETS, SMART TECHNOLOGIES, SMART DEFENCE Overcoming the transatlantic barriers to trade, export reform and licensing
Integrating Europe’s competitive advantages in emerging technologies in defence transformation (cost-saving unmanned platforms)
Avoid duplication between the EDA and NATO (Agencies and ACT)
Increasing the effective, targeted, fully accountable and transparent use of European defence resources and procurement<br>
slide27. THE GLOBALISATION OF DEFENCE AND SECURITY 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 27<br>
slide28. From 2020, the G-7 will account for a falling share of total global military spending.
In 2012, Asian defence spending exceeded NATO Europe spending
In 2021, Asian defence spending is projected to outstrip NATO
The US will still be the leading military power in 2030 but the gap with the rest of the world will have shrunk and it is likely to rely less on its European partners. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 28 GLOBALISATION AND TRENDS IN DEFENCE SPENDING<br>
slide29. The US devoted some 7% of GDP on average to national defence during the Cold War period
This percentage fell below 5% during the past decade, taking account of spending on Iraq and Afghanistan
Federal spending for major entitlement programmes (particularly Social Security, Medicare, and Medicaid) has grown rapidly over the past several decades 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 29 DEFENCE SPENDING IN THE UNITED STATES<br>
slide30. With an aging population and the prospect of higher interest rates in the future, the rising entitlement costs will consume an increasing proportion of the Federal budget
Without major reform of the programs or substantially increased tax revenues.
An affordable long-term level for national defence could be 1.6 - 2.6 percent of GDP
This is substantially below the current 4.2% and the projection through 2020, even taking account of the Panetta cuts and the BCA Sequestration reductions 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 30 DEFENCE SPENDING IN THE USA<br>
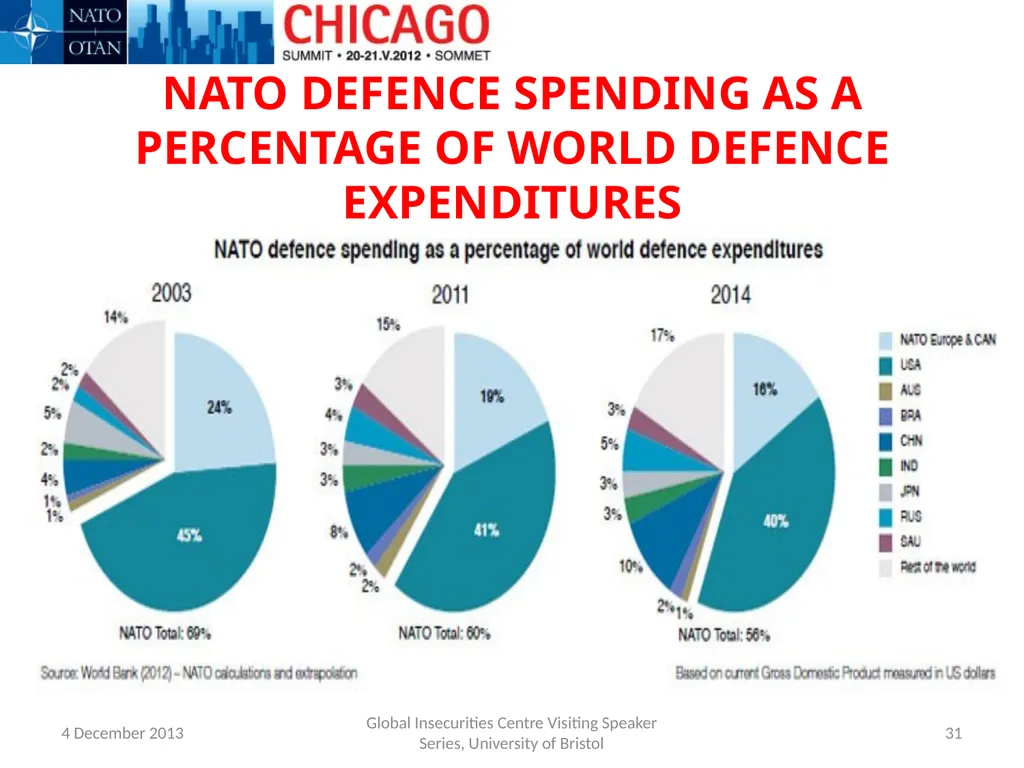
slide31. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 31 NATO DEFENCE SPENDING AS A PERCENTAGE OF WORLD DEFENCE EXPENDITURES<br>
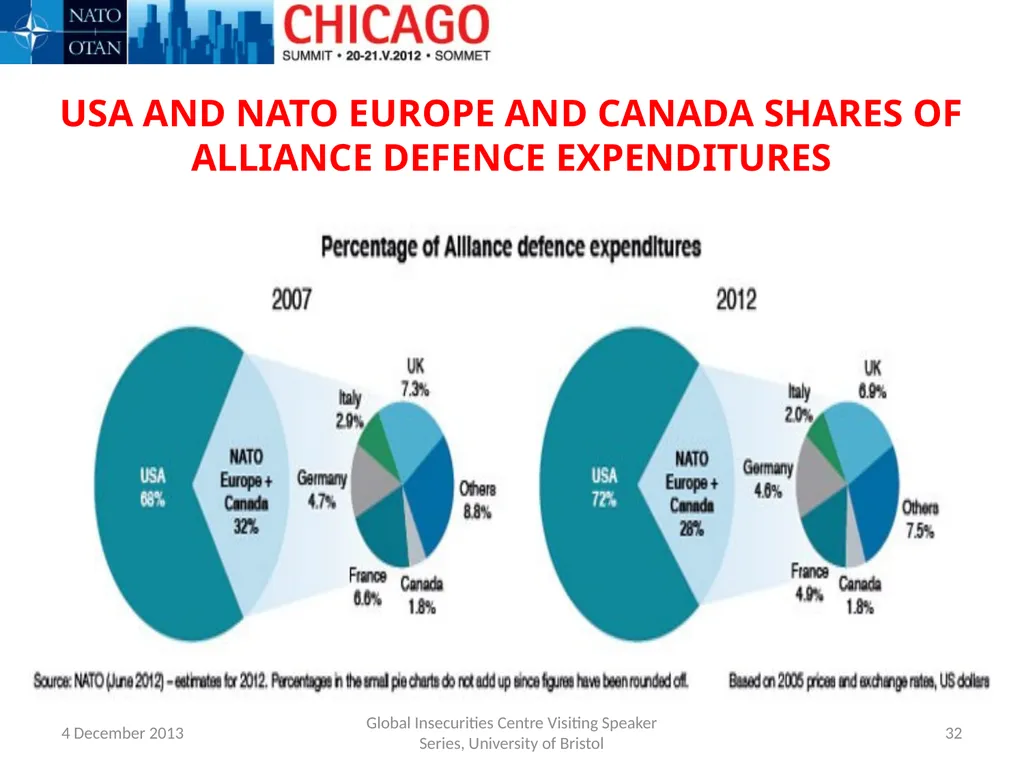
slide32. USA AND NATO EUROPE AND CANADA SHARES OF ALLIANCE DEFENCE EXPENDITURES 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 32<br>
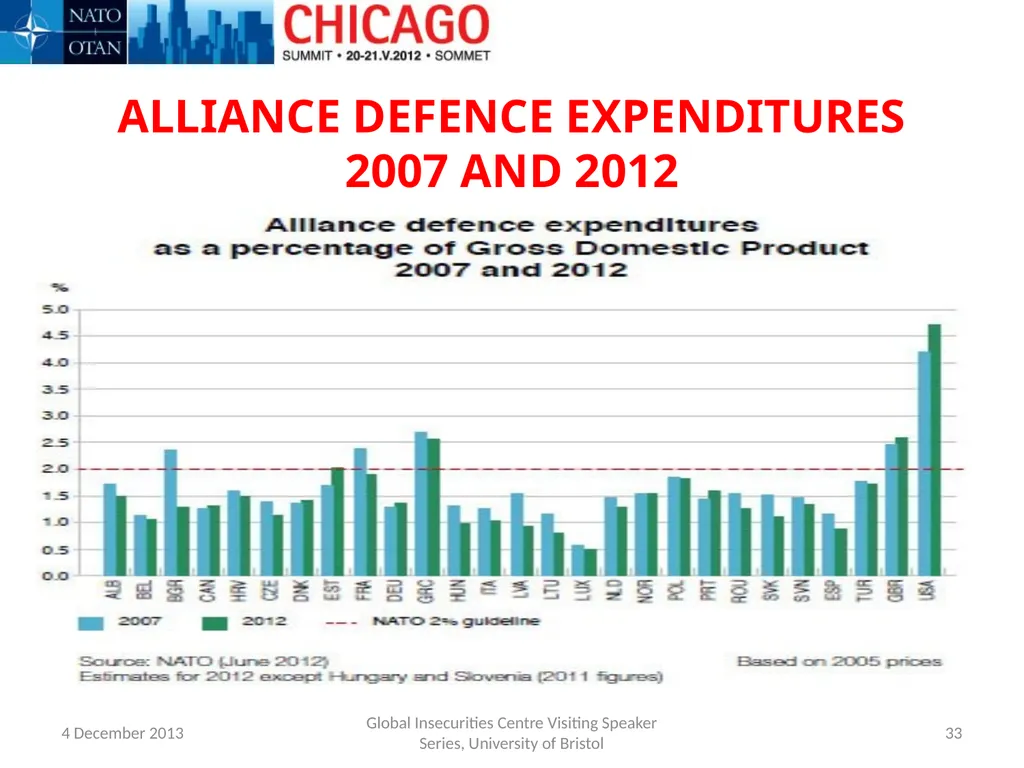
slide33. ALLIANCE DEFENCE EXPENDITURES 2007 AND 2012 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 33<br>
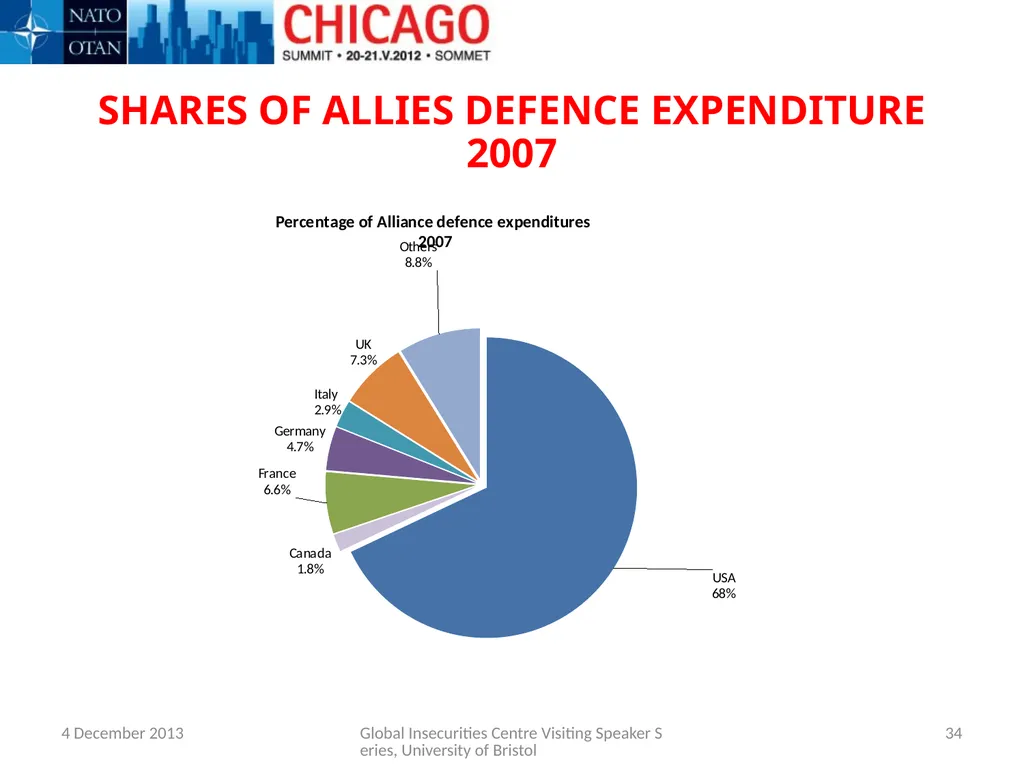
slide34. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 34 SHARES OF ALLIES DEFENCE EXPENDITURE 2007<br>
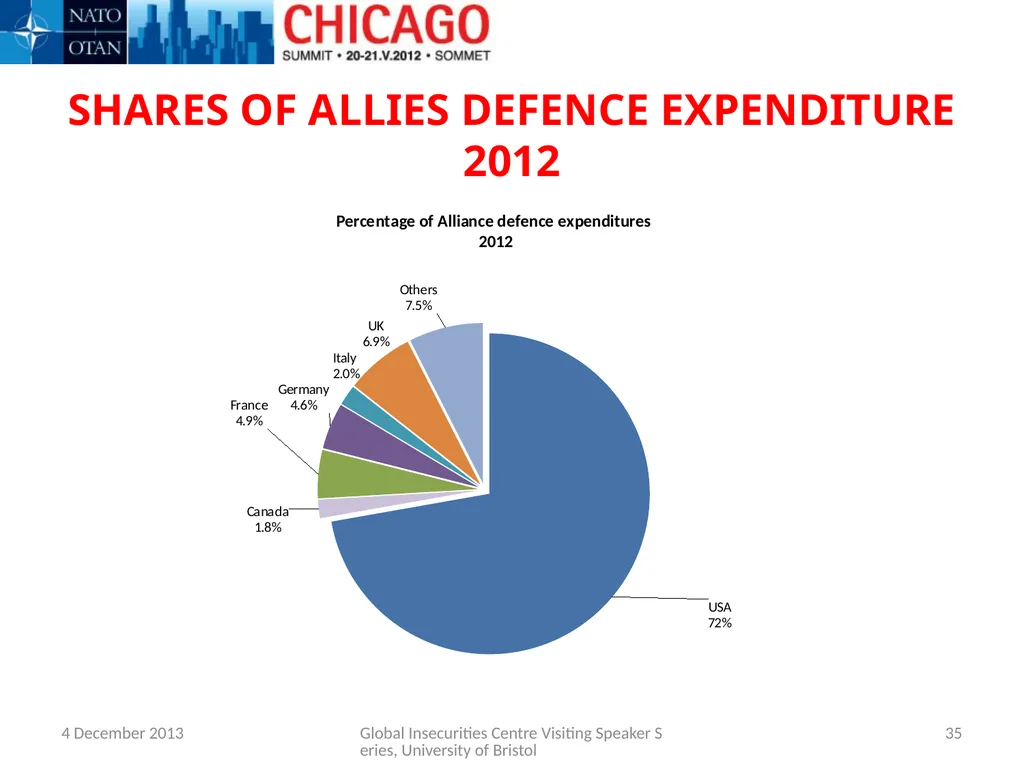
slide35. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 35 SHARES OF ALLIES DEFENCE EXPENDITURE 2012<br>
slide36. THE CHANGING BALANCE OF INTERNATIONAL ECONOMIC POWER 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 36<br>
slide37. In a hyper-connected world, globalisation will intensify
the global labour supply will be augmented by two billion workers from China and India
new technologies will eliminate more jobs in the service and manufacturing sectors
the crisis in social balance sheets will mirror the growing pool of the long-term unemployed
advanced economies are increasingly in debt while emerging economies have become creditors
Pensions and health care will be strained by the inability of governments to afford commitments to future generations. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 37 LONG-TERM GLOBAL ECONOMIC TRENDS 2020 AND BEYOND (IMF)<br>
slide38. By 2030, Asia as a whole will have surpassed North America and Europe combined in terms of economic power, largely reversing the historic rise of the West since 1750.
China itself is projected to surpass the overall economic size (GDP) of the United States later in the 2020s 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 38 THE UNITED STATES NATIONAL INTELLIGENCE COUNCIL REPORT “ GLOBAL TRENDS 2030: ALTERNATIVE WORLDS”<br>
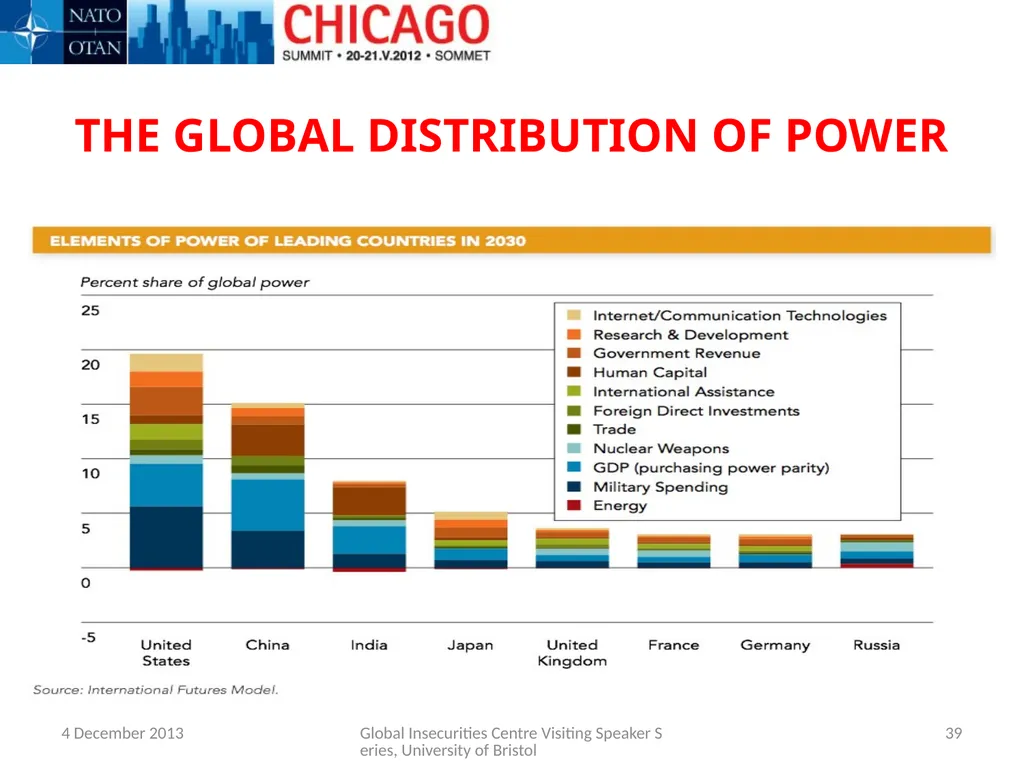
slide39. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 39 THE GLOBAL DISTRIBUTION OF POWER<br>
slide40. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 40 By 2050 the Working Age Population will:
Rise by 40% in Emerging Economies
Fall by 0.5% in Non-European Developed Economies
Fall by 20% in Europe
1 Uri Dadush and William Shaw Juggernaut: How Emerging Markets are Reshaping Globalisation, Carnegie Endowment for International Peace THE CHANGING BALANCE OF INTERNATIONAL ECONOMIC POWER1<br>
slide41. WEST AND EAST: PER CAPITA INCOME PROJECTIONS By 2030 , using current exchange rates, the total GDP of the Emerging 7 (China, India, Brazil, Russia, Indonesia, Mexico and Turkey) will exceed the G7 (US, Canada, UK, France, Germany, Italy, Japan)
However, in 2050, per capita income (ppp) for China will be < 50% of USA
In 2050, India will have total economic output larger than either Japan or EU (ppp) but per capita income (ppp) only 30% of Japan 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 41<br>
slide42. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 42 NATO AND THE STRATEGIC GLOBAL ENVIRONMENT Post 2014 Afghanistan and engagement with Global Partners
The economics and security of the Emerging Powers: Competition for Resources and Defence and Security Spending
Reaching out to the emerging powers: Global governance and ambitions of BRICS, regional security, regional arms races
Mutual benefits from cooperation?<br>
slide43. NATO AND COOPERATION WITH ASIA At the end of the Afghan Mission, NATO and global partnerships in Asia
Fostering long-term stability with the emerging powers through the sharing of core values and initiatives (such as training and education)
Enhanced dialogue on the global financial and economic crisis; and disaster relief, humanitarian aid and maritime and cyber security 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 43<br>
Former NATO Head of
Defence and Security Economics
and
Senior Defence Economist 2001-2013
adriankendry@hotmail.com 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 1<br>
slide2. THUCYDIDES AND FUNERAL ORATION FOR PERICLES (495-429 BC)
“It is not a matter of predicting the future but of being prepared“ 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 2<br>
slide3. NATO 2001-2013: AN ALLIANCE IN EVOLUTION Members :
19 nations (01) v 28 (13)
Partners:
NATO-Russia Council (2002)
NATO Ukraine Commission (1997)
Euro-Atlantic Partnership Council (28 + 21) and
Partnership for Peace Bilateral Cooperation
Mediterranean Dialogue (7)
Istanbul Cooperation Initiative (4)
Partners across the Globe (8) (AFG, AUS, IRQ, JAP, RoK, NZ, MONG, PAK) 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 3<br>
slide4. NATO 2001-2013: A PERSONAL HISTORY 2001 - 2003: 9/11, Iraq: NATO and the Transatlantic Relationship: the Economic and Financial Dimensions of Countering Terrorism
2004: The Istanbul Summit: The Partnership Action Plan on Defence Institution Building and the inception of the Building Integrity programme on accountability and transparency in the defence and security sector
2005-2009: Defining NATO’s Role in Energy Security: The Economics and Security of Energy
2010-2012: Afghanistan and regional economic security: Assessing Afghanistan’s economic capacity post 2014
2009-2013: The Financial and Economic Crisis: Understanding, measuring and assessing the impact of the crisis on NATO budgets and capabilities 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 4<br>
slide5. NATO: THE THREE GAPS 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 5<br>
slide6. THE PROLOGUE: NATO AND THE TALE OF THREE GAPS The Intra-European gap:
Will NATO European Allies still be capable of operating together in international crisis management?
The Transatlantic Gap:
Will the growing imbalance in transatlantic defence spending undermine US support for NATO?
The Global Gap:
Will the emerging economic powers increase their capacity for regional action and international influence at a time when NATO’s capacities could diminish 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 6<br>
slide7. THE PROLOGUE: NATO AND THE TALE OF THREE GAPS Disproportionate defence cuts are likely to weaken NATO military forces and the industries that support them, and also undermine innovation, exports, and employment
Additionally, inadequate defence spending and investment will exacerbate economic insecurity linked to emerging security challenges
The Emerging Security Challenges Division came into being in 2010 and is increasingly pre-occupied with cyber security and NATO’s contribution to national cyber security efforts 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 7<br>
slide8. GLOBAL INSECURITIES: THE PRESENT 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 8<br>
slide9. NATO FOREIGN MINISTERIAL 3-4 DECEMBER 2013: CONFRONTING GLOBAL REALITIES The NATO 2014 Summit in the UK: Afghanistan, partnerships and improving military capabilities
Measures to strengthen NATO partnerships across the globe 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 9<br>
slide10. NATO FOREIGN MINISTERIAL 3-4 DECEMBER 2013: CONFRONTING GLOBAL REALITIES The NATO Russia Council and closing the disagreement on Syria, Afghanistan, Missile Defence and Transparency
Afghanistan 2014 and the end of ISAF: NATO will work closely with the Afghan government in the weeks ahead to put in place the necessary legal framework for the deployment of the NATO-led mission to train, advise and assist the Afghan security forces after 2014 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 10<br>
slide11. NATO POST-AFGHANISTAN In 2015 NATO will no longer have a combat operation and will shift from being “Operationally Engaged” to being “Operationally Prepared”
NATO will need to maintain effective capabilities through reinforcing the three pillars of collective defence, cooperative security and crisis response operations
Measuring the costs of investing in security and insecurity 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 11<br>
slide12. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 12 “All countries are increasingly reliant on the vital communication, transport and transit routes on which international trade, energy security and prosperity depend. They require greater international efforts to ensure their resilience against attack or disruption” NATO’S STRATEGIC CONCEPT, EMERGING SECURITY CHALLENGES AND ECONOMIC SECURITY: FROM LISBON TO CHICAGO<br>
slide13. GLOBAL INSECURITIES: A HUNDRED YEARS OF TURMOIL 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 13<br>
slide14. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 14 ONE HUNDRED YEARS OF INSECURITY: FROM 1913 TO 2013 1913: The Road to Sarajevo and World War One global conflict
1963: United States: assassinations, and racial insecurity<br>
slide15. ONE HUNDRED YEARS OF INSECUITY: 2013 Syria: economics, religion and regional conflict
Afghanistan, Elections and ISAF withdrawal 2014
Iran, the Gulf and consequences of the nuclear accord
Transatlantic economic fragility:
January and February 2014: return of US budget and debt crisis
Continuing frailty of the Eurozone economy 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 15<br>
slide16. ONE HUNDRED YEARS OF INSECURITY: 2013 The East China Sea: China, Japan, the Diaoyou and Senkaku Islands: Strategic competition and growing tensions
Caught in the Middle: the conflicting ambitions of Ukraine, the EU Eastern Partnership and Russia
The Central African Republic: resources, but political fragility, weak infrastructure and business insecurity equal feeble growth and poverty reduction 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 16<br>
slide17. THE ECONOMIC AND SECURITY CHALLENGES FOR THE TRANSATLANTIC PARTNERSHIP 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 17<br>
slide18. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 18 THE FUTURE OF THE TRANSATLANTIC TRADE AND INVESTMENT PARTNERSHIP The transatlantic economy is the largest and wealthiest market in the world
54% of world GDP in terms of value and 40% in terms of purchasing power
Even with the financial crisis, US and EU financial markets continue to account for more than 66% of global banking assets and 75% of global financial services 18<br>
slide19. The Demographic Time bomb: the declining working-age population, the growing implicit debt on pensions and medical care
The Widening Economic Capability Gap between the USA and Europe
The United States Fiscal Cliff and the impact of Fiscal Impasse and Sequestration on federal budget deficits, federal debt
Energy Independence and Dependence: Europe’s growing import dependency and the US growing self-sufficiency (but the continuing importance of the Gulf of Guinea) THE ECONOMIC AND SECURITY CHALLENGES FOR THE TRANSATLANTIC PARTNERSHIP 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 19<br>
slide20. OECD high-income countries median age will rise from 37.9 years in 2010 to 42.8 years by 2030
Increasing percentage of people aged 65 years and above— the pensions bulge
Pressure to reduce discretionary state spending and increase the tax burden 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 20 THE DEMOGRAPHIC DESTINY<br>
slide21. Natural gas prices have fallen sharply in the US with the prospects of becoming a major energy exporter in the 2020s
The European Union’s foreign energy dependency is expected to rise to 70% in the next 20-30 years and higher prices will undermine European economic competitiveness
European increasing dependency will clash with the emerging economic powers in pursuing energy and other scarce resources. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 21 TRANSATLANTIC ENERGY DEPENDENCY<br>
slide22. NATO AND THE CONSEQUENCES OF THE ECONOMIC AND FINANCIAL CRISIS 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 22<br>
slide23. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 23 THE ECONOMIC CRISIS AND RISKS TO SECURITY "I am clear that the single biggest strategic risk facing the UK today is economic rather than military“
Gen Sir David Richards, Chief of the UK Defence Staff, (RUSI 2012)<br>
slide24. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 24 Article 2 of the 1949 North Atlantic Treaty (“eliminate conflict in international economic policies....”)
Impact of crisis on Alliance and Partners:
DIRECT negative consequences (Common Funding, defence expenditure, capabilities, multinational weapons projects, missions and operations)
INDIRECT negative consequences: failed states, international economic aid, shifts in global balance of economic power, climate change, energy security, scarcity of water and food, migration, poverty and extremism NATO AND THE GLOBAL ECONOMIC AND FINANCIAL CRISIS<br>
slide25. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 25 SMART DEFENCE AND ECONOMIC AUSTERITY Most European defence budgets experienced smaller reductions than other sectors of government 2010-2011(Alliance commitments, contractual obligations, industrial concerns)
Unsustainable defence spending projections 2011-2016: fiscal deficits and debts imply deep cuts in force levels, capabilities, readiness and delayed procurement
UK, France and Germany are crucial for NATO Europe: 65% of all NATO Europe Defence Expenditure, 88% of Research and Technology<br>
slide26. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 26 SMART BUDGETS, SMART TECHNOLOGIES, SMART DEFENCE Overcoming the transatlantic barriers to trade, export reform and licensing
Integrating Europe’s competitive advantages in emerging technologies in defence transformation (cost-saving unmanned platforms)
Avoid duplication between the EDA and NATO (Agencies and ACT)
Increasing the effective, targeted, fully accountable and transparent use of European defence resources and procurement<br>
slide27. THE GLOBALISATION OF DEFENCE AND SECURITY 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 27<br>
slide28. From 2020, the G-7 will account for a falling share of total global military spending.
In 2012, Asian defence spending exceeded NATO Europe spending
In 2021, Asian defence spending is projected to outstrip NATO
The US will still be the leading military power in 2030 but the gap with the rest of the world will have shrunk and it is likely to rely less on its European partners. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 28 GLOBALISATION AND TRENDS IN DEFENCE SPENDING<br>
slide29. The US devoted some 7% of GDP on average to national defence during the Cold War period
This percentage fell below 5% during the past decade, taking account of spending on Iraq and Afghanistan
Federal spending for major entitlement programmes (particularly Social Security, Medicare, and Medicaid) has grown rapidly over the past several decades 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 29 DEFENCE SPENDING IN THE UNITED STATES<br>
slide30. With an aging population and the prospect of higher interest rates in the future, the rising entitlement costs will consume an increasing proportion of the Federal budget
Without major reform of the programs or substantially increased tax revenues.
An affordable long-term level for national defence could be 1.6 - 2.6 percent of GDP
This is substantially below the current 4.2% and the projection through 2020, even taking account of the Panetta cuts and the BCA Sequestration reductions 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 30 DEFENCE SPENDING IN THE USA<br>
slide31. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 31 NATO DEFENCE SPENDING AS A PERCENTAGE OF WORLD DEFENCE EXPENDITURES<br>
slide32. USA AND NATO EUROPE AND CANADA SHARES OF ALLIANCE DEFENCE EXPENDITURES 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 32<br>
slide33. ALLIANCE DEFENCE EXPENDITURES 2007 AND 2012 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 33<br>
slide34. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 34 SHARES OF ALLIES DEFENCE EXPENDITURE 2007<br>
slide35. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 35 SHARES OF ALLIES DEFENCE EXPENDITURE 2012<br>
slide36. THE CHANGING BALANCE OF INTERNATIONAL ECONOMIC POWER 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 36<br>
slide37. In a hyper-connected world, globalisation will intensify
the global labour supply will be augmented by two billion workers from China and India
new technologies will eliminate more jobs in the service and manufacturing sectors
the crisis in social balance sheets will mirror the growing pool of the long-term unemployed
advanced economies are increasingly in debt while emerging economies have become creditors
Pensions and health care will be strained by the inability of governments to afford commitments to future generations. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 37 LONG-TERM GLOBAL ECONOMIC TRENDS 2020 AND BEYOND (IMF)<br>
slide38. By 2030, Asia as a whole will have surpassed North America and Europe combined in terms of economic power, largely reversing the historic rise of the West since 1750.
China itself is projected to surpass the overall economic size (GDP) of the United States later in the 2020s 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 38 THE UNITED STATES NATIONAL INTELLIGENCE COUNCIL REPORT “ GLOBAL TRENDS 2030: ALTERNATIVE WORLDS”<br>
slide39. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 39 THE GLOBAL DISTRIBUTION OF POWER<br>
slide40. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 40 By 2050 the Working Age Population will:
Rise by 40% in Emerging Economies
Fall by 0.5% in Non-European Developed Economies
Fall by 20% in Europe
1 Uri Dadush and William Shaw Juggernaut: How Emerging Markets are Reshaping Globalisation, Carnegie Endowment for International Peace THE CHANGING BALANCE OF INTERNATIONAL ECONOMIC POWER1<br>
slide41. WEST AND EAST: PER CAPITA INCOME PROJECTIONS By 2030 , using current exchange rates, the total GDP of the Emerging 7 (China, India, Brazil, Russia, Indonesia, Mexico and Turkey) will exceed the G7 (US, Canada, UK, France, Germany, Italy, Japan)
However, in 2050, per capita income (ppp) for China will be < 50% of USA
In 2050, India will have total economic output larger than either Japan or EU (ppp) but per capita income (ppp) only 30% of Japan 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 41<br>
slide42. 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 42 NATO AND THE STRATEGIC GLOBAL ENVIRONMENT Post 2014 Afghanistan and engagement with Global Partners
The economics and security of the Emerging Powers: Competition for Resources and Defence and Security Spending
Reaching out to the emerging powers: Global governance and ambitions of BRICS, regional security, regional arms races
Mutual benefits from cooperation?<br>
slide43. NATO AND COOPERATION WITH ASIA At the end of the Afghan Mission, NATO and global partnerships in Asia
Fostering long-term stability with the emerging powers through the sharing of core values and initiatives (such as training and education)
Enhanced dialogue on the global financial and economic crisis; and disaster relief, humanitarian aid and maritime and cyber security 4 December 2013 Global Insecurities Centre Visiting Speaker Series, University of Bristol 43<br>