
1 Overview of SA’s debt management process Tebogo

Description: 1 Overview of SAs debt management process Tebogo Mosepele Director: Growth Table of contents 1) Background 2) History of South Africas Bond Market 2 3) Funding Strategy and Instruments 4) Primary auctions 5) Foreign bond issuance
Related Topics
Download Presentation
"1 Overview of SA’s debt management process Tebogo" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. 1 Overview of SA’s debt management process
Tebogo Mosepele
Director: Growth<br>
slide2. Table of contents 1) Background 2) History of South Africa’s Bond Market 2 3) Funding Strategy and Instruments 4) Primary auctions 5) Foreign bond issuance<br>
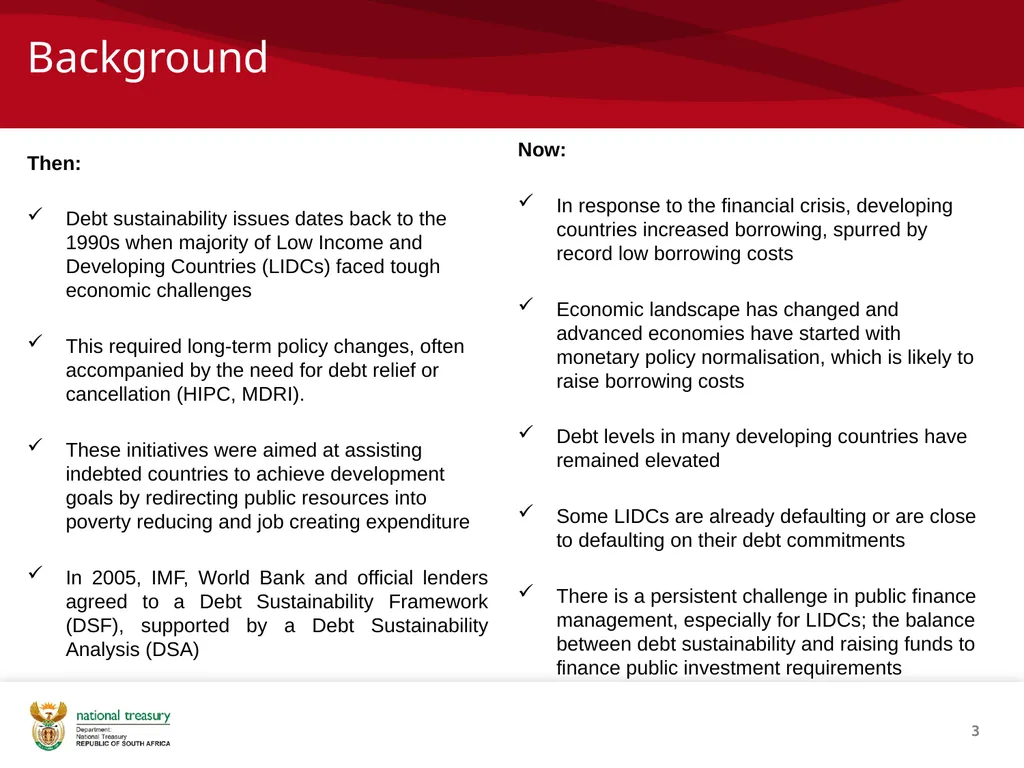
slide3. Background Then:
Debt sustainability issues dates back to the 1990s when majority of Low Income and Developing Countries (LIDCs) faced tough economic challenges
This required long-term policy changes, often accompanied by the need for debt relief or cancellation (HIPC, MDRI).
These initiatives were aimed at assisting indebted countries to achieve development goals by redirecting public resources into poverty reducing and job creating expenditure
In 2005, IMF, World Bank and official lenders agreed to a Debt Sustainability Framework (DSF), supported by a Debt Sustainability Analysis (DSA) Now:
In response to the financial crisis, developing countries increased borrowing, spurred by record low borrowing costs
Economic landscape has changed and advanced economies have started with monetary policy normalisation, which is likely to raise borrowing costs
Debt levels in many developing countries have remained elevated
Some LIDCs are already defaulting or are close to defaulting on their debt commitments
There is a persistent challenge in public finance management, especially for LIDCs; the balance between debt sustainability and raising funds to finance public investment requirements 3<br>
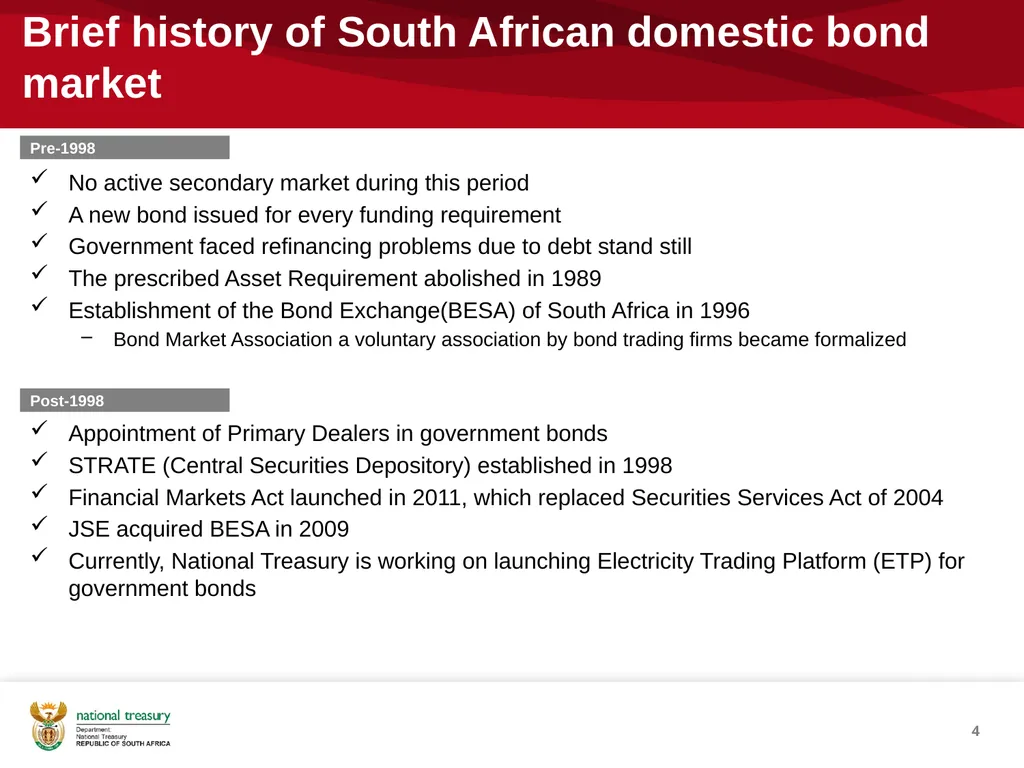
slide4. 4 Brief history of South African domestic bond market No active secondary market during this period
A new bond issued for every funding requirement
Government faced refinancing problems due to debt stand still
The prescribed Asset Requirement abolished in 1989
Establishment of the Bond Exchange(BESA) of South Africa in 1996
Bond Market Association a voluntary association by bond trading firms became formalized
Appointment of Primary Dealers in government bonds
STRATE (Central Securities Depository) established in 1998
Financial Markets Act launched in 2011, which replaced Securities Services Act of 2004
JSE acquired BESA in 2009
Currently, National Treasury is working on launching Electricity Trading Platform (ETP) for government bonds Pre-1998 Post-1998<br>
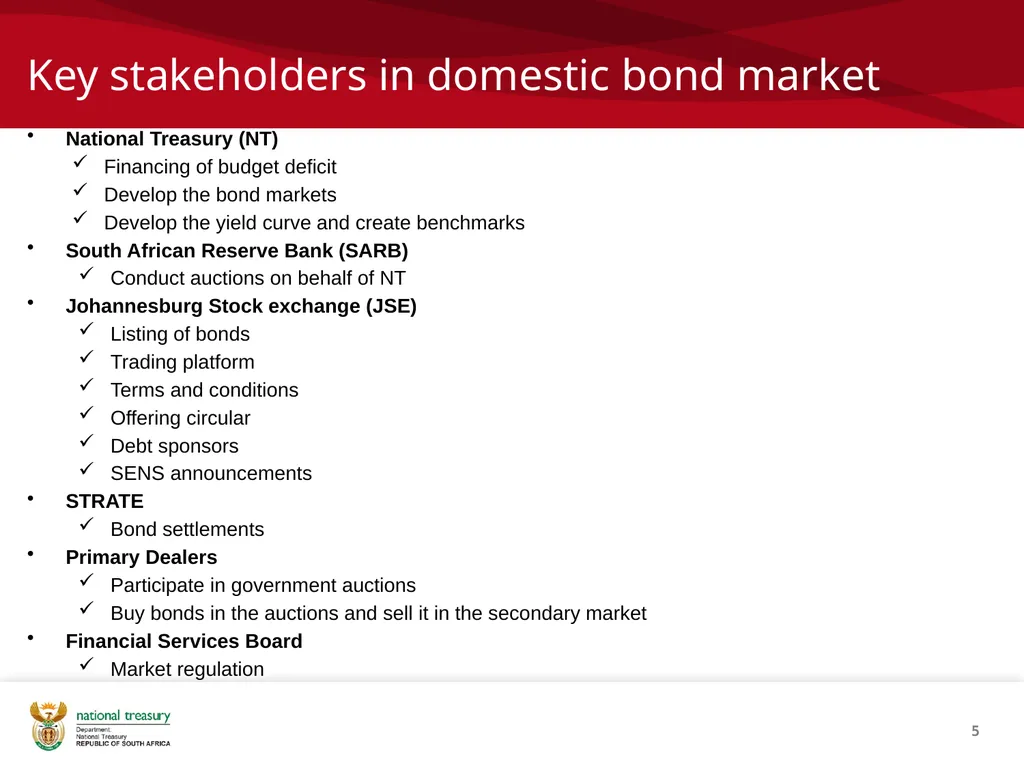
slide5. Key stakeholders in domestic bond market National Treasury (NT)
Financing of budget deficit
Develop the bond markets
Develop the yield curve and create benchmarks
South African Reserve Bank (SARB)
Conduct auctions on behalf of NT
Johannesburg Stock exchange (JSE)
Listing of bonds
Trading platform
Terms and conditions
Offering circular
Debt sponsors
SENS announcements
STRATE
Bond settlements
Primary Dealers
Participate in government auctions
Buy bonds in the auctions and sell it in the secondary market
Financial Services Board
Market regulation 5<br>
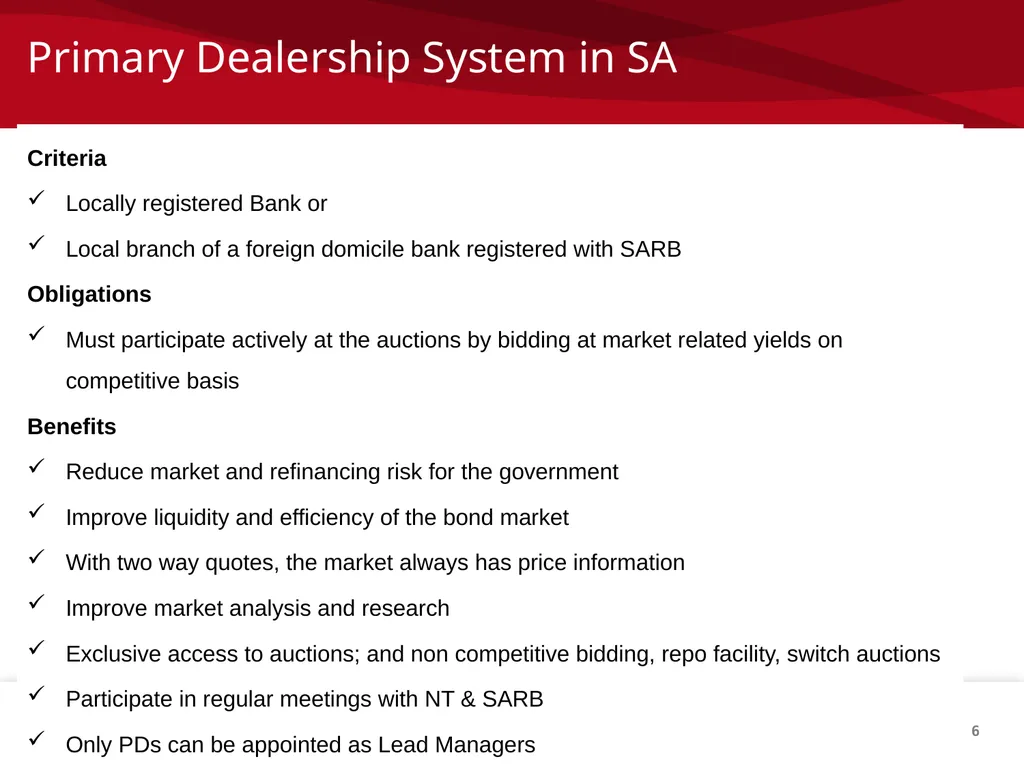
slide6. Primary Dealership System in SA Criteria
Locally registered Bank or
Local branch of a foreign domicile bank registered with SARB
Obligations
Must participate actively at the auctions by bidding at market related yields on competitive basis
Benefits
Reduce market and refinancing risk for the government
Improve liquidity and efficiency of the bond market
With two way quotes, the market always has price information
Improve market analysis and research
Exclusive access to auctions; and non competitive bidding, repo facility, switch auctions
Participate in regular meetings with NT & SARB
Only PDs can be appointed as Lead Managers 6<br>
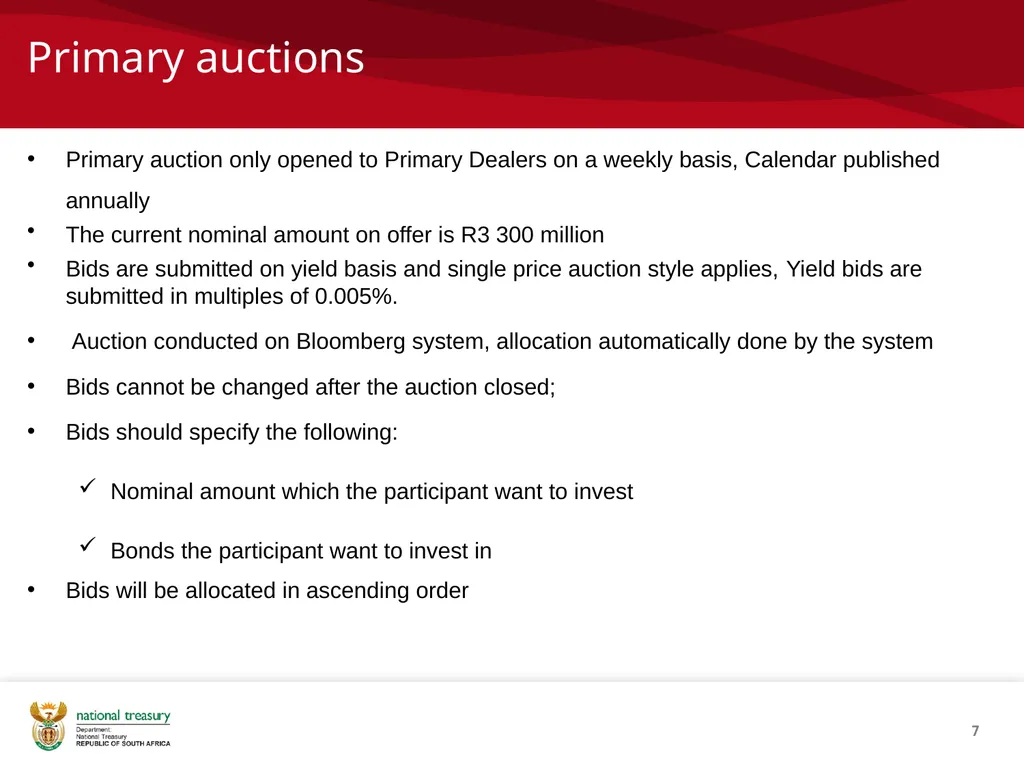
slide7. Primary auctions Primary auction only opened to Primary Dealers on a weekly basis, Calendar published annually
The current nominal amount on offer is R3 300 million
Bids are submitted on yield basis and single price auction style applies, Yield bids are submitted in multiples of 0.005%.
Auction conducted on Bloomberg system, allocation automatically done by the system
Bids cannot be changed after the auction closed;
Bids should specify the following:
Nominal amount which the participant want to invest
Bonds the participant want to invest in
Bids will be allocated in ascending order 7<br>
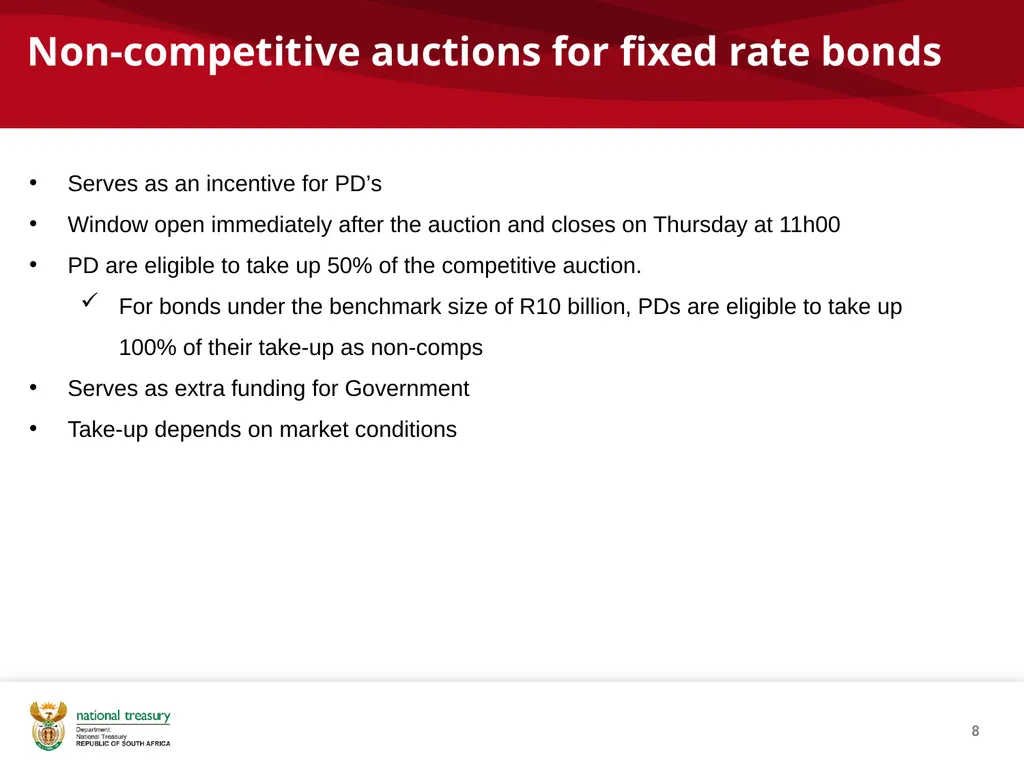
slide8. Non-competitive auctions for fixed rate bonds 8 Serves as an incentive for PD’s
Window open immediately after the auction and closes on Thursday at 11h00
PD are eligible to take up 50% of the competitive auction.
For bonds under the benchmark size of R10 billion, PDs are eligible to take up 100% of their take-up as non-comps
Serves as extra funding for Government
Take-up depends on market conditions<br>
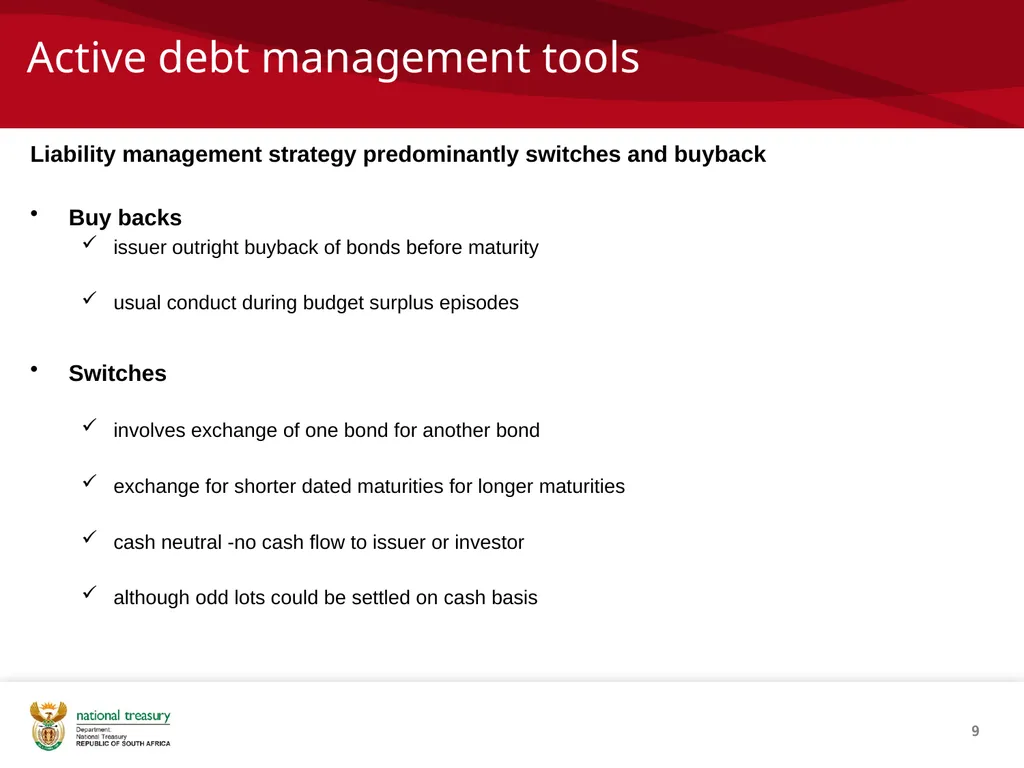
slide9. Active debt management tools Liability management strategy predominantly switches and buyback
Buy backs
issuer outright buyback of bonds before maturity
usual conduct during budget surplus episodes
Switches
involves exchange of one bond for another bond
exchange for shorter dated maturities for longer maturities
cash neutral -no cash flow to issuer or investor
although odd lots could be settled on cash basis 9<br>
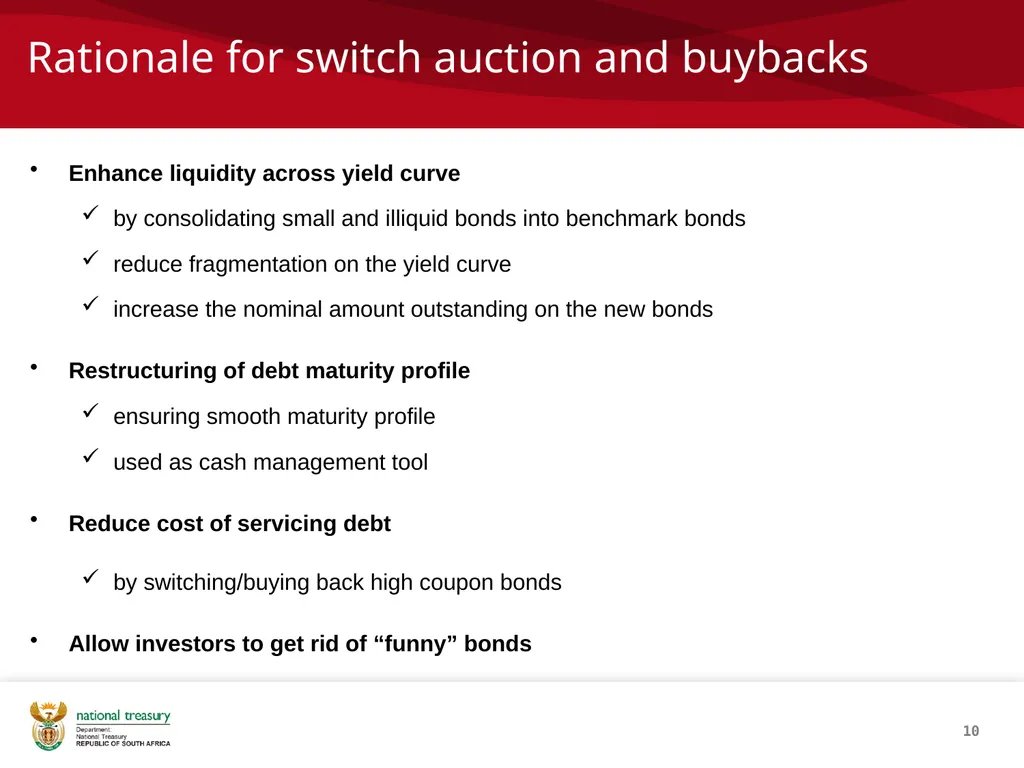
slide10. Rationale for switch auction and buybacks 10 Enhance liquidity across yield curve
by consolidating small and illiquid bonds into benchmark bonds
reduce fragmentation on the yield curve
increase the nominal amount outstanding on the new bonds
Restructuring of debt maturity profile
ensuring smooth maturity profile
used as cash management tool
Reduce cost of servicing debt
by switching/buying back high coupon bonds
Allow investors to get rid of “funny” bonds<br>
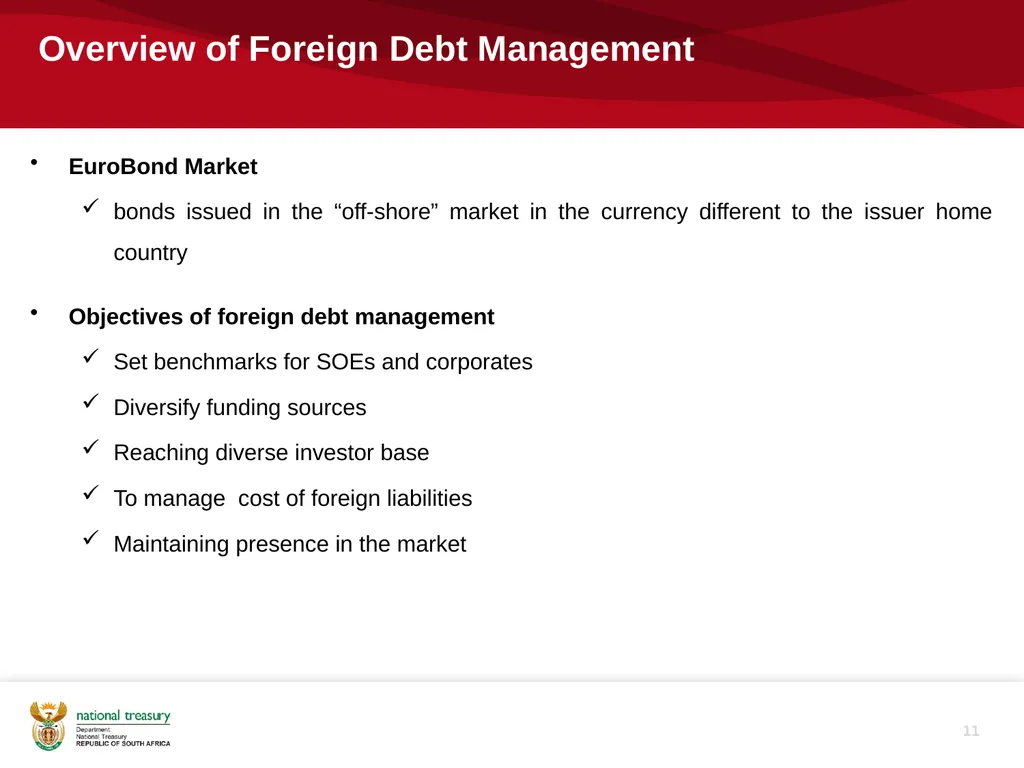
slide11. Overview of Foreign Debt Management EuroBond Market
bonds issued in the “off-shore” market in the currency different to the issuer home country
Objectives of foreign debt management
Set benchmarks for SOEs and corporates
Diversify funding sources
Reaching diverse investor base
To manage cost of foreign liabilities
Maintaining presence in the market 11<br>
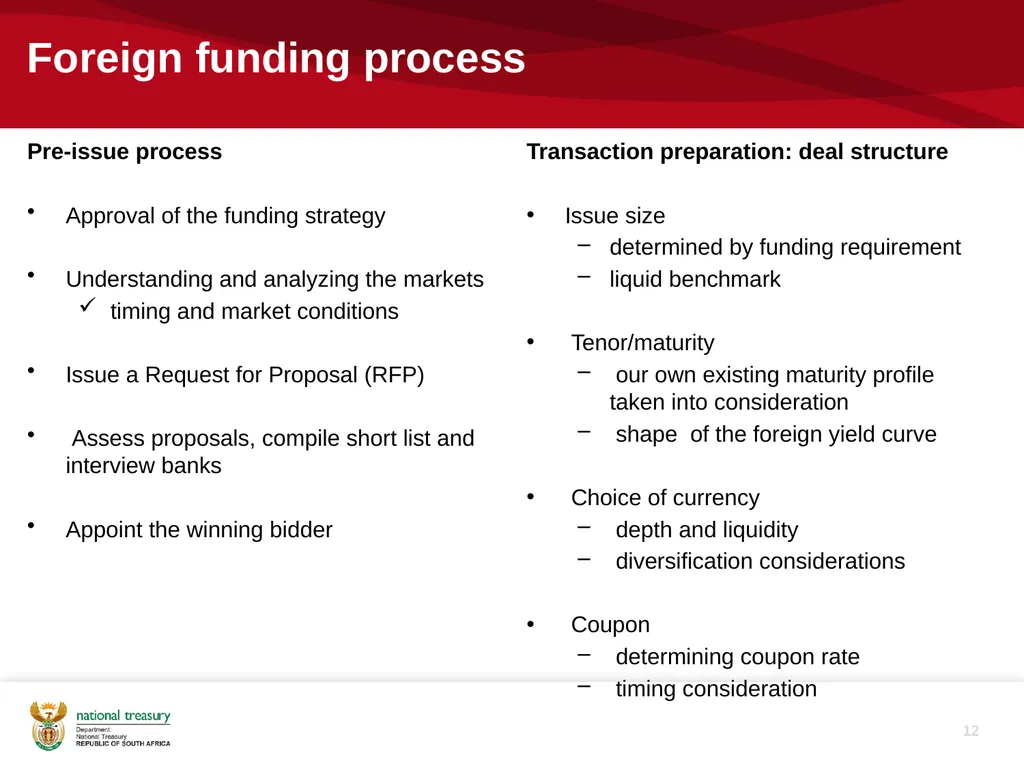
slide12. Foreign funding process Pre-issue process
Approval of the funding strategy
Understanding and analyzing the markets
timing and market conditions
Issue a Request for Proposal (RFP)
Assess proposals, compile short list and interview banks
Appoint the winning bidder Transaction preparation: deal structure
Issue size
determined by funding requirement
liquid benchmark
Tenor/maturity
our own existing maturity profile taken into consideration
shape of the foreign yield curve
Choice of currency
depth and liquidity
diversification considerations
Coupon
determining coupon rate
timing consideration 12<br>
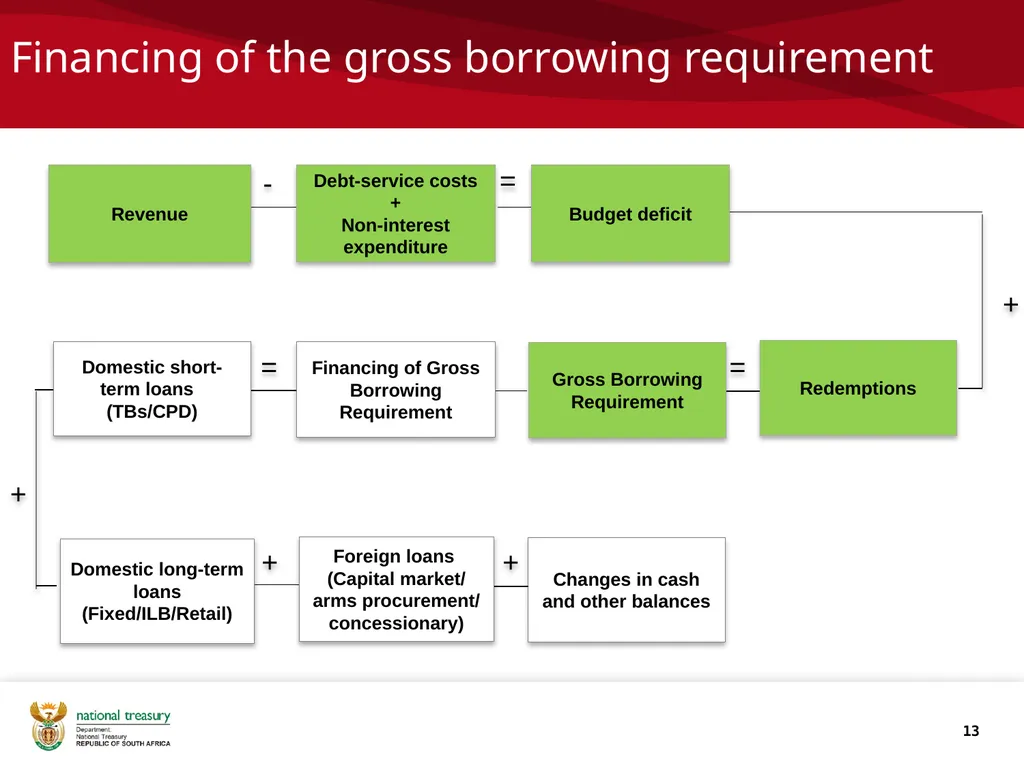
slide13. Financing of the gross borrowing requirement 13 Revenue = - = = + Changes in cash and other balances + + + Financing of Gross Borrowing Requirement Gross Borrowing Requirement Domestic short-term loans
(TBs/CPD) Budget deficit Redemptions Domestic long-term loans
(Fixed/ILB/Retail) Foreign loans
(Capital market/
arms procurement/
concessionary) Debt-service costs
+
Non-interest expenditure<br>
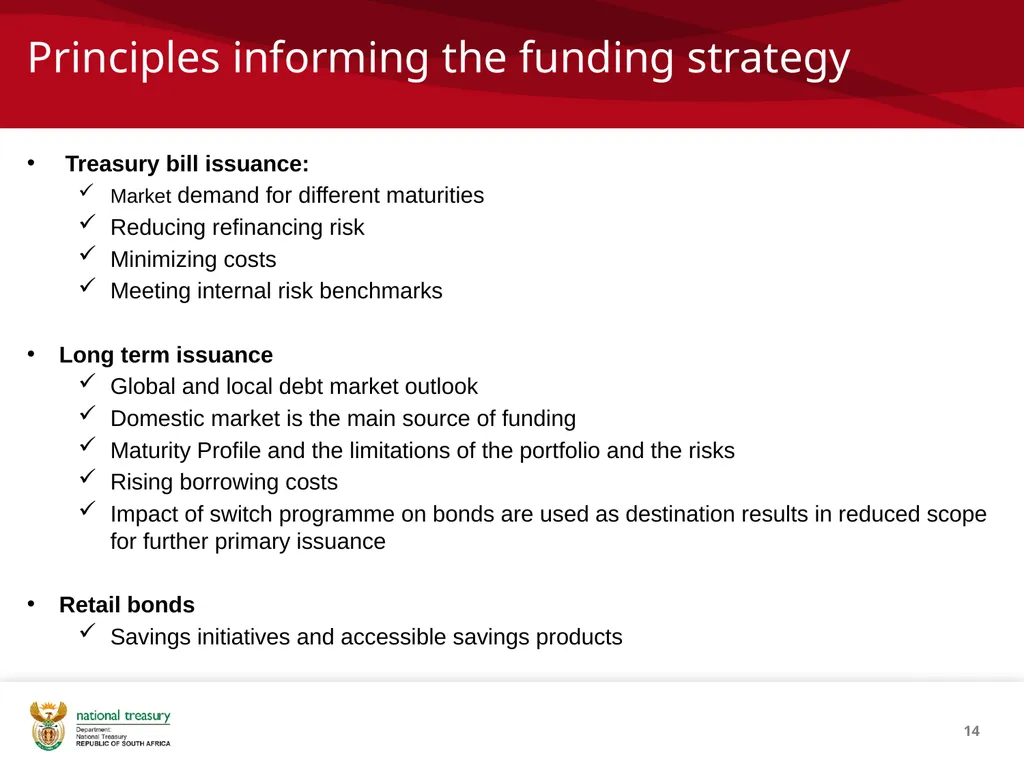
slide14. Principles informing the funding strategy Treasury bill issuance:
Market demand for different maturities
Reducing refinancing risk
Minimizing costs
Meeting internal risk benchmarks
Long term issuance
Global and local debt market outlook
Domestic market is the main source of funding
Maturity Profile and the limitations of the portfolio and the risks
Rising borrowing costs
Impact of switch programme on bonds are used as destination results in reduced scope for further primary issuance
Retail bonds
Savings initiatives and accessible savings products 14<br>
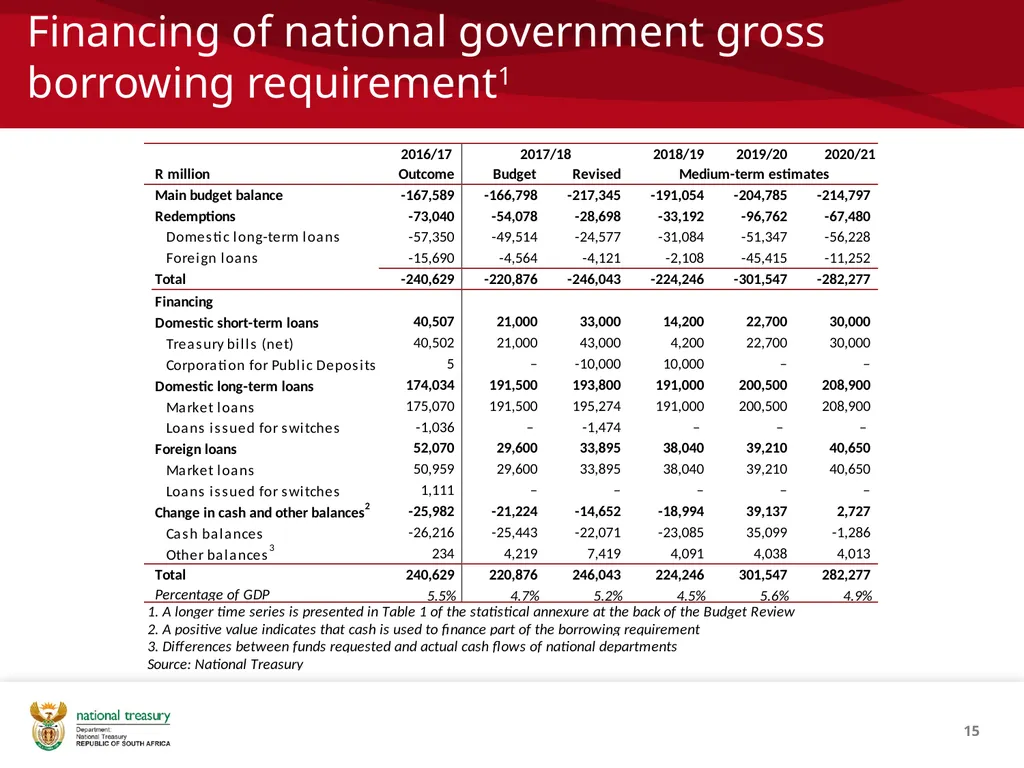
slide15. Financing of national government gross borrowing requirement1 15<br>
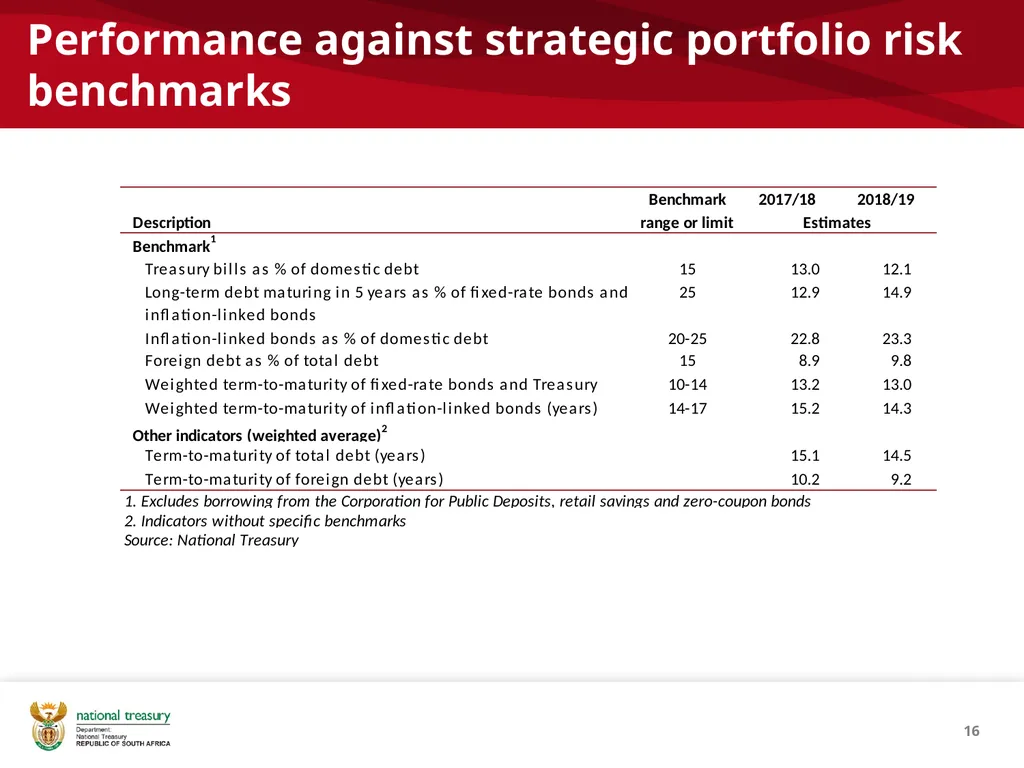
slide16. Performance against strategic portfolio risk benchmarks 16<br>
slide17. Key challenge for SA debt management and how we are addressing it Trading within the bond market under the primary dealer system takes place primarily on a bilateral basis
Direct impact of this include;
Liquidity is not optimised
Weak price discoveries
Lack of transparency
To address some of these challenges, the National Treasury, JSE, SA Reserve Bank, STRATE and primary dealer banks are working to establish an Electronic Trading Platform (ETP) which will be launched in FY2018/19
The primary objective of ETP is to implement an electronic trading platform where Primary Dealer Quoting Obligations are automated in a central venue
The platform is expected to increase liquidity and transparency, and to reduce funding costs, by simplifying access to government bonds.
Phase I of the project will limit participation on the ETP to the PDs appointed by NT
JSE will be the front-line supervisor of the ETP market 17<br>
slide18. Conclusion Strengthening of debt management has become an increasingly important aspect of development and sustainable financing
Effective public debt management can reduce financial vulnerabilities, contribute to macroeconomic stability and improve investor confidence
The current global environment requires countries to be even more prudent in their debt management, given monetary policy normalisation in Advanced Economies
The World Bank highlights that debt managers need to properly assess risks and mitigate them by relying on a diverse range of financing sources, while maintaining borrowing costs at low levels 18<br>
slide19. Q&A Thank You 19<br>
slide2. Table of contents 1) Background 2) History of South Africa’s Bond Market 2 3) Funding Strategy and Instruments 4) Primary auctions 5) Foreign bond issuance<br>
slide3. Background Then:
Debt sustainability issues dates back to the 1990s when majority of Low Income and Developing Countries (LIDCs) faced tough economic challenges
This required long-term policy changes, often accompanied by the need for debt relief or cancellation (HIPC, MDRI).
These initiatives were aimed at assisting indebted countries to achieve development goals by redirecting public resources into poverty reducing and job creating expenditure
In 2005, IMF, World Bank and official lenders agreed to a Debt Sustainability Framework (DSF), supported by a Debt Sustainability Analysis (DSA) Now:
In response to the financial crisis, developing countries increased borrowing, spurred by record low borrowing costs
Economic landscape has changed and advanced economies have started with monetary policy normalisation, which is likely to raise borrowing costs
Debt levels in many developing countries have remained elevated
Some LIDCs are already defaulting or are close to defaulting on their debt commitments
There is a persistent challenge in public finance management, especially for LIDCs; the balance between debt sustainability and raising funds to finance public investment requirements 3<br>
slide4. 4 Brief history of South African domestic bond market No active secondary market during this period
A new bond issued for every funding requirement
Government faced refinancing problems due to debt stand still
The prescribed Asset Requirement abolished in 1989
Establishment of the Bond Exchange(BESA) of South Africa in 1996
Bond Market Association a voluntary association by bond trading firms became formalized
Appointment of Primary Dealers in government bonds
STRATE (Central Securities Depository) established in 1998
Financial Markets Act launched in 2011, which replaced Securities Services Act of 2004
JSE acquired BESA in 2009
Currently, National Treasury is working on launching Electricity Trading Platform (ETP) for government bonds Pre-1998 Post-1998<br>
slide5. Key stakeholders in domestic bond market National Treasury (NT)
Financing of budget deficit
Develop the bond markets
Develop the yield curve and create benchmarks
South African Reserve Bank (SARB)
Conduct auctions on behalf of NT
Johannesburg Stock exchange (JSE)
Listing of bonds
Trading platform
Terms and conditions
Offering circular
Debt sponsors
SENS announcements
STRATE
Bond settlements
Primary Dealers
Participate in government auctions
Buy bonds in the auctions and sell it in the secondary market
Financial Services Board
Market regulation 5<br>
slide6. Primary Dealership System in SA Criteria
Locally registered Bank or
Local branch of a foreign domicile bank registered with SARB
Obligations
Must participate actively at the auctions by bidding at market related yields on competitive basis
Benefits
Reduce market and refinancing risk for the government
Improve liquidity and efficiency of the bond market
With two way quotes, the market always has price information
Improve market analysis and research
Exclusive access to auctions; and non competitive bidding, repo facility, switch auctions
Participate in regular meetings with NT & SARB
Only PDs can be appointed as Lead Managers 6<br>
slide7. Primary auctions Primary auction only opened to Primary Dealers on a weekly basis, Calendar published annually
The current nominal amount on offer is R3 300 million
Bids are submitted on yield basis and single price auction style applies, Yield bids are submitted in multiples of 0.005%.
Auction conducted on Bloomberg system, allocation automatically done by the system
Bids cannot be changed after the auction closed;
Bids should specify the following:
Nominal amount which the participant want to invest
Bonds the participant want to invest in
Bids will be allocated in ascending order 7<br>
slide8. Non-competitive auctions for fixed rate bonds 8 Serves as an incentive for PD’s
Window open immediately after the auction and closes on Thursday at 11h00
PD are eligible to take up 50% of the competitive auction.
For bonds under the benchmark size of R10 billion, PDs are eligible to take up 100% of their take-up as non-comps
Serves as extra funding for Government
Take-up depends on market conditions<br>
slide9. Active debt management tools Liability management strategy predominantly switches and buyback
Buy backs
issuer outright buyback of bonds before maturity
usual conduct during budget surplus episodes
Switches
involves exchange of one bond for another bond
exchange for shorter dated maturities for longer maturities
cash neutral -no cash flow to issuer or investor
although odd lots could be settled on cash basis 9<br>
slide10. Rationale for switch auction and buybacks 10 Enhance liquidity across yield curve
by consolidating small and illiquid bonds into benchmark bonds
reduce fragmentation on the yield curve
increase the nominal amount outstanding on the new bonds
Restructuring of debt maturity profile
ensuring smooth maturity profile
used as cash management tool
Reduce cost of servicing debt
by switching/buying back high coupon bonds
Allow investors to get rid of “funny” bonds<br>
slide11. Overview of Foreign Debt Management EuroBond Market
bonds issued in the “off-shore” market in the currency different to the issuer home country
Objectives of foreign debt management
Set benchmarks for SOEs and corporates
Diversify funding sources
Reaching diverse investor base
To manage cost of foreign liabilities
Maintaining presence in the market 11<br>
slide12. Foreign funding process Pre-issue process
Approval of the funding strategy
Understanding and analyzing the markets
timing and market conditions
Issue a Request for Proposal (RFP)
Assess proposals, compile short list and interview banks
Appoint the winning bidder Transaction preparation: deal structure
Issue size
determined by funding requirement
liquid benchmark
Tenor/maturity
our own existing maturity profile taken into consideration
shape of the foreign yield curve
Choice of currency
depth and liquidity
diversification considerations
Coupon
determining coupon rate
timing consideration 12<br>
slide13. Financing of the gross borrowing requirement 13 Revenue = - = = + Changes in cash and other balances + + + Financing of Gross Borrowing Requirement Gross Borrowing Requirement Domestic short-term loans
(TBs/CPD) Budget deficit Redemptions Domestic long-term loans
(Fixed/ILB/Retail) Foreign loans
(Capital market/
arms procurement/
concessionary) Debt-service costs
+
Non-interest expenditure<br>
slide14. Principles informing the funding strategy Treasury bill issuance:
Market demand for different maturities
Reducing refinancing risk
Minimizing costs
Meeting internal risk benchmarks
Long term issuance
Global and local debt market outlook
Domestic market is the main source of funding
Maturity Profile and the limitations of the portfolio and the risks
Rising borrowing costs
Impact of switch programme on bonds are used as destination results in reduced scope for further primary issuance
Retail bonds
Savings initiatives and accessible savings products 14<br>
slide15. Financing of national government gross borrowing requirement1 15<br>
slide16. Performance against strategic portfolio risk benchmarks 16<br>
slide17. Key challenge for SA debt management and how we are addressing it Trading within the bond market under the primary dealer system takes place primarily on a bilateral basis
Direct impact of this include;
Liquidity is not optimised
Weak price discoveries
Lack of transparency
To address some of these challenges, the National Treasury, JSE, SA Reserve Bank, STRATE and primary dealer banks are working to establish an Electronic Trading Platform (ETP) which will be launched in FY2018/19
The primary objective of ETP is to implement an electronic trading platform where Primary Dealer Quoting Obligations are automated in a central venue
The platform is expected to increase liquidity and transparency, and to reduce funding costs, by simplifying access to government bonds.
Phase I of the project will limit participation on the ETP to the PDs appointed by NT
JSE will be the front-line supervisor of the ETP market 17<br>
slide18. Conclusion Strengthening of debt management has become an increasingly important aspect of development and sustainable financing
Effective public debt management can reduce financial vulnerabilities, contribute to macroeconomic stability and improve investor confidence
The current global environment requires countries to be even more prudent in their debt management, given monetary policy normalisation in Advanced Economies
The World Bank highlights that debt managers need to properly assess risks and mitigate them by relying on a diverse range of financing sources, while maintaining borrowing costs at low levels 18<br>
slide19. Q&A Thank You 19<br>