
22nd to 23rd August, 2013 Shangri La Hotel


Description: 22nd to 23rd August, 2013 Shangri La Hotel Singapore A STRATEGY FOR ASEAN Organiser Co-Organiser Network ASEAN Forum 2013 CONNECTIVITY 22nd - 23rd August 2013 Connectivity context Highly dynamic ecosystem with critical role for ASEAN
Related Topics
Download Presentation
"22nd to 23rd August, 2013 Shangri La Hotel" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. 22nd to 23rd August, 2013
Shangri La Hotel
Singapore A STRATEGY FOR ASEAN Organiser Co-Organiser<br>
slide2. Network ASEAN Forum 2013 CONNECTIVITY 22nd - 23rd August 2013<br>
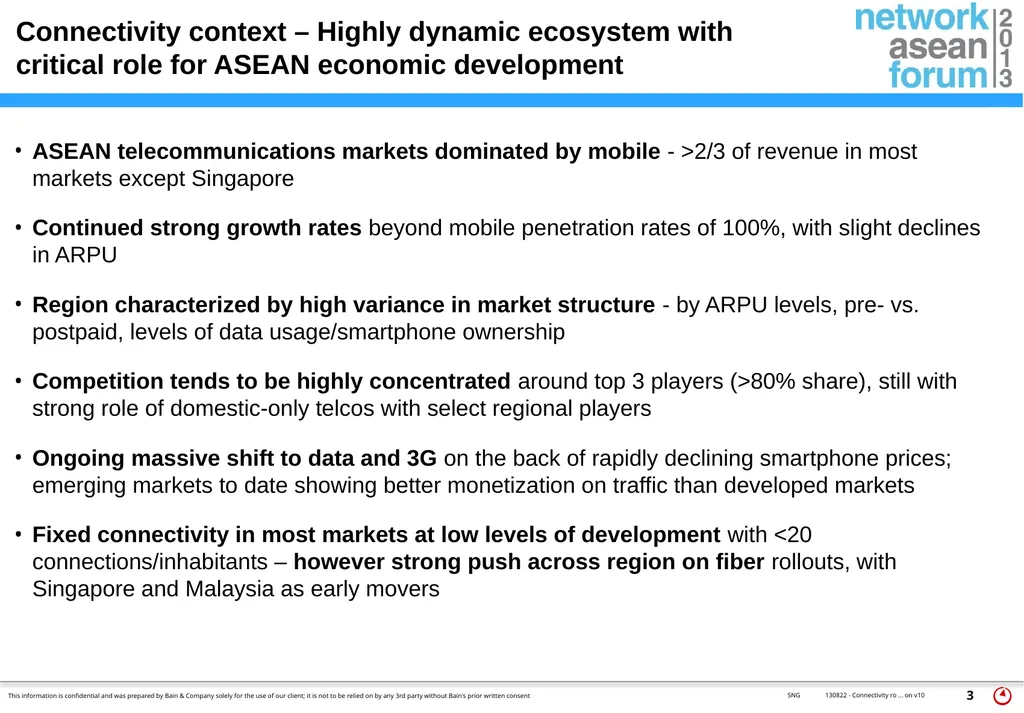
slide3. Connectivity context – Highly dynamic ecosystem with critical role for ASEAN economic development 7_85 ASEAN telecommunications markets dominated by mobile - >2/3 of revenue in most markets except Singapore
Continued strong growth rates beyond mobile penetration rates of 100%, with slight declines in ARPU
Region characterized by high variance in market structure - by ARPU levels, pre- vs. postpaid, levels of data usage/smartphone ownership
Competition tends to be highly concentrated around top 3 players (>80% share), still with strong role of domestic-only telcos with select regional players
Ongoing massive shift to data and 3G on the back of rapidly declining smartphone prices; emerging markets to date showing better monetization on traffic than developed markets
Fixed connectivity in most markets at low levels of development with <20 connections/inhabitants – however strong push across region on fiber rollouts, with Singapore and Malaysia as early movers<br>
slide4. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
slide5. Roaming charges in ASEAN countries are significantly higher than in Europe and vary across Telcos Data charges
(per MB) Voice charges - calls made
(per min) Voice charges - calls received
(per min) SMS charges Range n/a Note: Charges are for usage within/across ASEAN countries; charges vary based on call or usage destination; charges exclude VAT
Source: Telco websites<br>
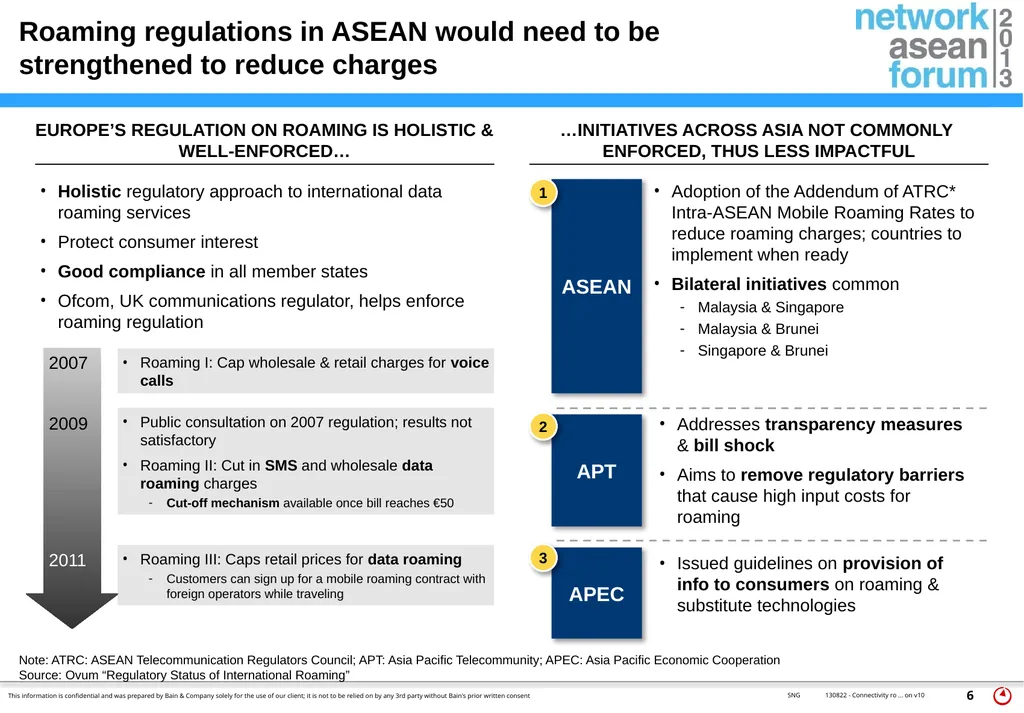
slide6. ASEAN APT APEC Roaming regulations in ASEAN would need to be strengthened to reduce charges 6_85 14_85 15_85 16_85 18_85 11_85 13_85 Europe’s regulation on roaming is holistic & well-enforced… …initiatives across Asia not commonly enforced, thus less impactful Holistic regulatory approach to international data roaming services
Protect consumer interest
Good compliance in all member states
Ofcom, UK communications regulator, helps enforce roaming regulation 2009 2011 2007 Roaming III: Caps retail prices for data roaming
Customers can sign up for a mobile roaming contract with foreign operators while traveling Public consultation on 2007 regulation; results not satisfactory
Roaming II: Cut in SMS and wholesale data roaming charges
Cut-off mechanism available once bill reaches €50 Roaming I: Cap wholesale & retail charges for voice calls Note: ATRC: ASEAN Telecommunication Regulators Council; APT: Asia Pacific Telecommunity; APEC: Asia Pacific Economic Cooperation
Source: Ovum “Regulatory Status of International Roaming” Adoption of the Addendum of ATRC* Intra-ASEAN Mobile Roaming Rates to reduce roaming charges; countries to implement when ready
Bilateral initiatives common
Malaysia & Singapore
Malaysia & Brunei
Singapore & Brunei 1 2 3 Addresses transparency measures & bill shock
Aims to remove regulatory barriers that cause high input costs for roaming Issued guidelines on provision of info to consumers on roaming & substitute technologies<br>
slide7. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
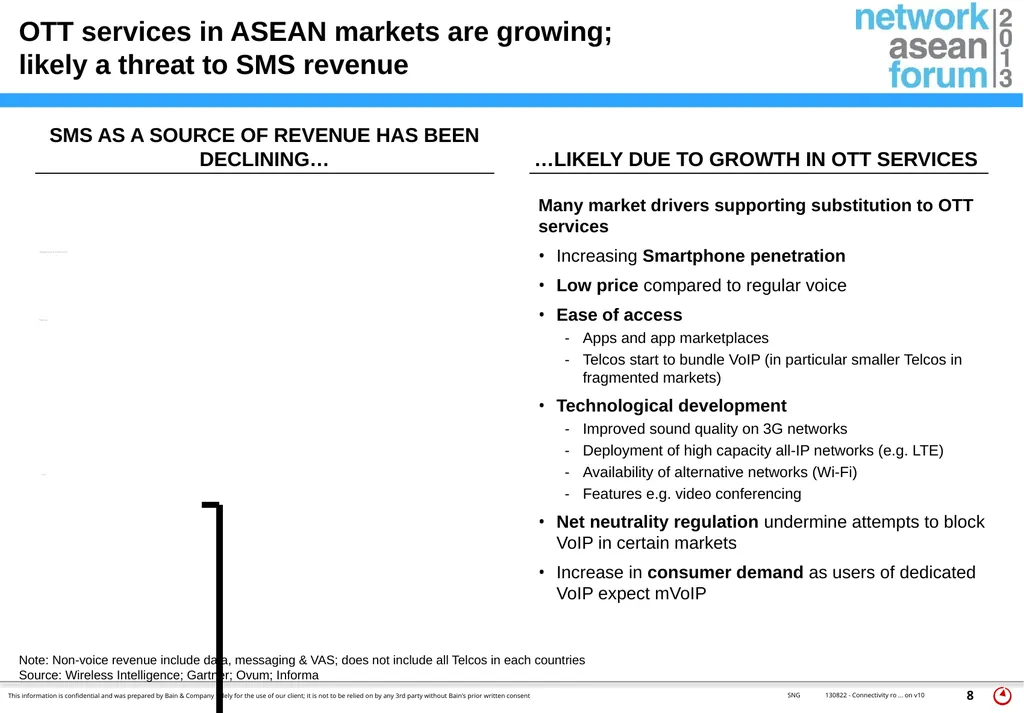
slide8. OTT services in ASEAN markets are growing; likely a threat to SMS revenue SMS as a source of revenue has been declining… …likely due to growth in ott services Many market drivers supporting substitution to OTT services
Increasing Smartphone penetration
Low price compared to regular voice
Ease of access
Apps and app marketplaces
Telcos start to bundle VoIP (in particular smaller Telcos in fragmented markets)
Technological development
Improved sound quality on 3G networks
Deployment of high capacity all-IP networks (e.g. LTE)
Availability of alternative networks (Wi-Fi)
Features e.g. video conferencing
Net neutrality regulation undermine attempts to block VoIP in certain markets
Increase in consumer demand as users of dedicated VoIP expect mVoIP 13_85 Note: Non-voice revenue include data, messaging & VAS; does not include all Telcos in each countries
Source: Wireless Intelligence; Gartner; Ovum; Informa<br>
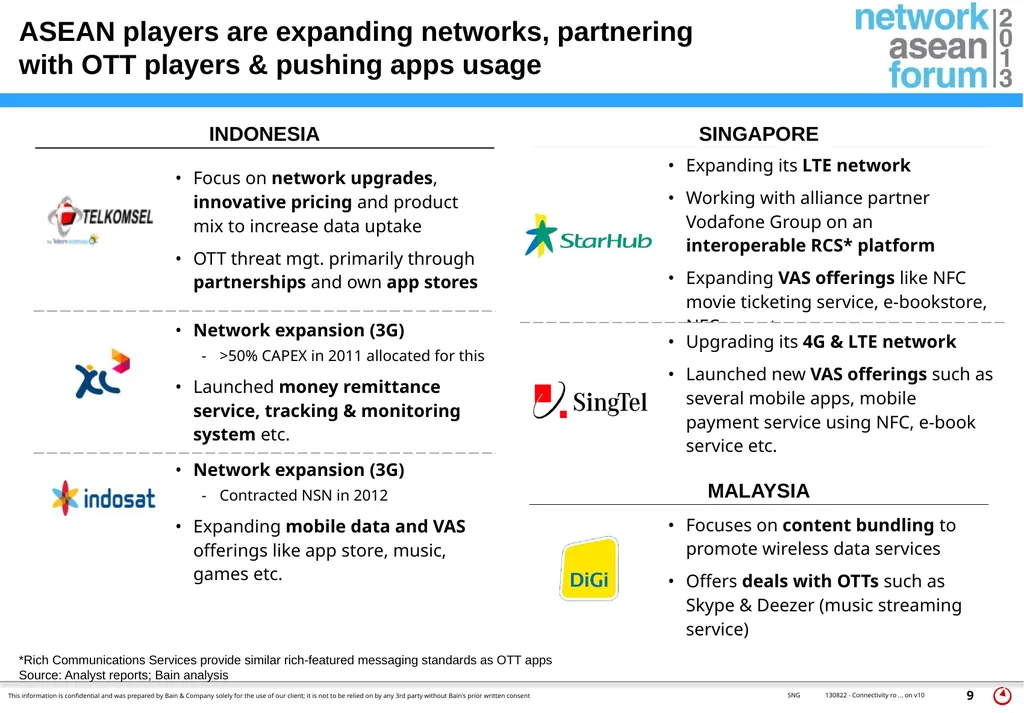
slide9. 8_85 16_85 ASEAN players are expanding networks, partnering with OTT players & pushing apps usage INDONESIA Singapore *Rich Communications Services provide similar rich-featured messaging standards as OTT apps
Source: Analyst reports; Bain analysis Malaysia<br>
slide10. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
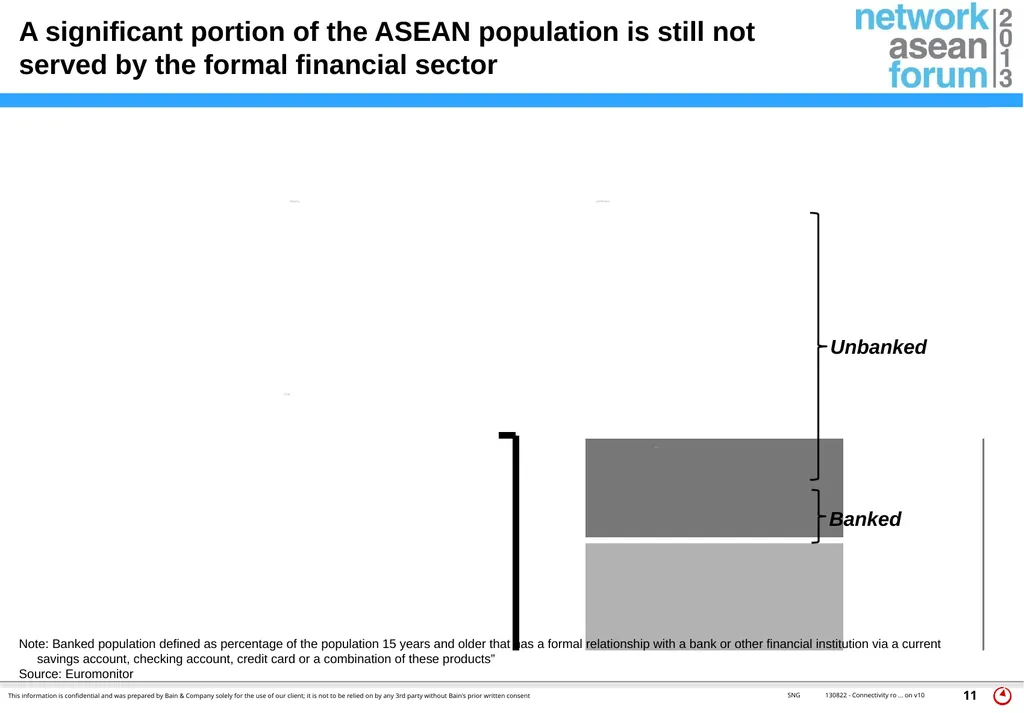
slide11. A significant portion of the ASEAN population is still not served by the formal financial sector Note: Banked population defined as percentage of the population 15 years and older that has a formal relationship with a bank or other financial institution via a current savings account, checking account, credit card or a combination of these products”
Source: Euromonitor Banked Unbanked<br>
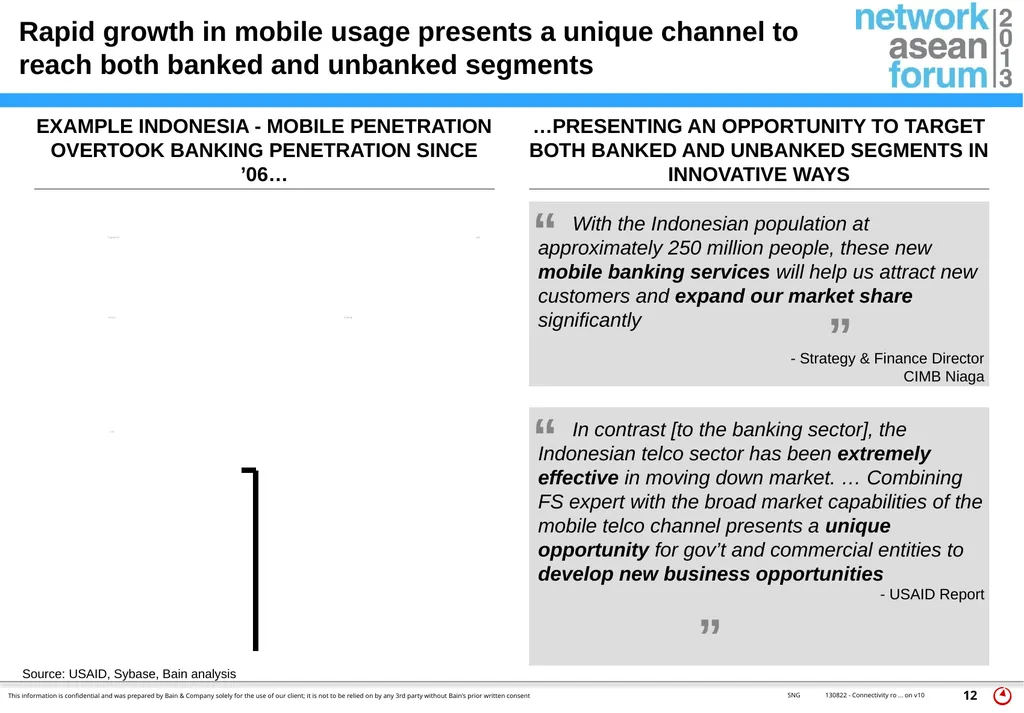
slide12. Rapid growth in mobile usage presents a unique channel to reach both banked and unbanked segments Source: USAID, Sybase, Bain analysis In contrast [to the banking sector], the Indonesian telco sector has been extremely effective in moving down market. … Combining FS expert with the broad market capabilities of the mobile telco channel presents a unique opportunity for gov’t and commercial entities to develop new business opportunities
- USAID Report “ ” With the Indonesian population at approximately 250 million people, these new mobile banking services will help us attract new customers and expand our market share significantly
- Strategy & Finance Director
CIMB Niaga ” “ EXAMPLE Indonesia - Mobile penetration overtook banking penetration since ’06… …Presenting an opportunity to target both banked and unbanked segments in innovative ways<br>
slide13. Opportunities in mobile money along three categories of usage Transactions Services Mobile Commerce Mobile Banking Source: Bain analysis 1 2 3 Utility bill payments
Remittances (domestic, international)
Cash-in/cash-out
Via banks, retailers, agents
Including government cash payments Stored value account
Mobile top-up
Mobile wallet-to-wallet transfers (P2P) M-Wallet Traditional Payments E.g., online shopping, online games, media, virtual products Mobile consumer services Mobile shop/portal services Mobile Banking Banking inquiries
E.g., account balances, SMS alerts
Mobile/online savings accounts
Mobile/online loan applications and disbursements
Insurance E.g., customer loyalty, mobile ads, coupons and offers Mobile marketing services New mobile merchant payment technology (mobile POS, P2P on the spot, …) Mobile merchant services New mobile consumer payment technology (NFC, QR code, …)<br>
slide14. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
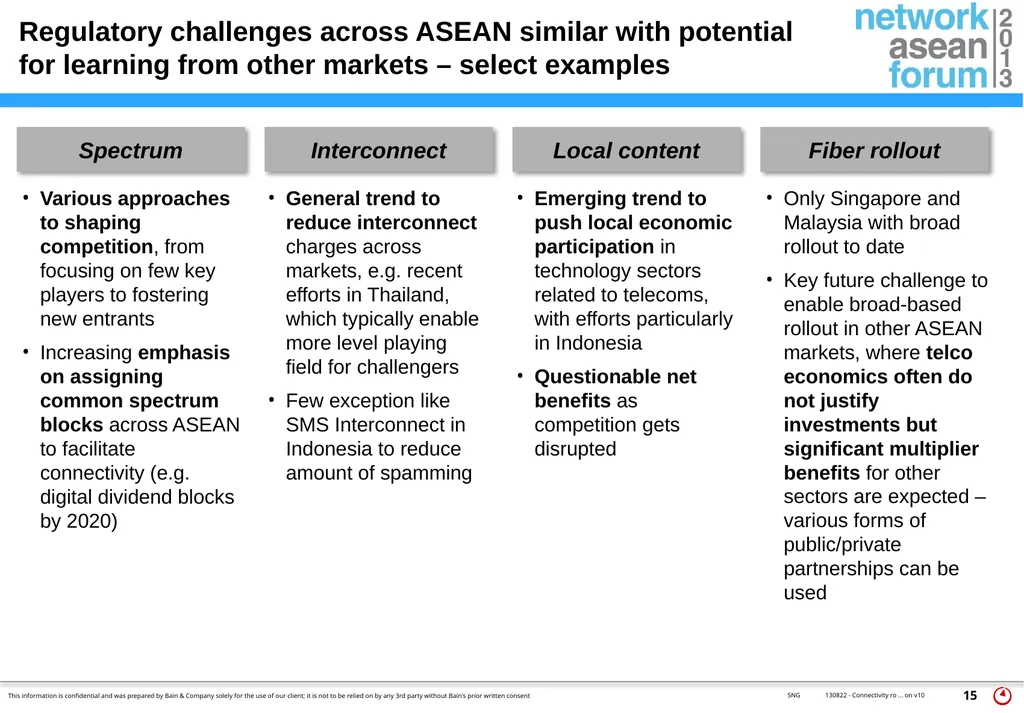
slide15. Regulatory challenges across ASEAN similar with potential for learning from other markets – select examples 19_85 48_85 50_85 51_85 Spectrum Interconnect Fiber rollout Various approaches to shaping competition, from focusing on few key players to fostering new entrants
Increasing emphasis on assigning common spectrum blocks across ASEAN to facilitate connectivity (e.g. digital dividend blocks by 2020) General trend to reduce interconnect charges across markets, e.g. recent efforts in Thailand, which typically enable more level playing field for challengers
Few exception like SMS Interconnect in Indonesia to reduce amount of spamming Local content Emerging trend to push local economic participation in technology sectors related to telecoms, with efforts particularly in Indonesia
Questionable net benefits as competition gets disrupted Only Singapore and Malaysia with broad rollout to date
Key future challenge to enable broad-based rollout in other ASEAN markets, where telco economics often do not justify investments but significant multiplier benefits for other sectors are expected – various forms of public/private partnerships can be used<br>
slide17. THANK YOU Organiser Co-Organiser<br>
Singapore A STRATEGY FOR ASEAN Organiser Co-Organiser<br>
slide2. Network ASEAN Forum 2013 CONNECTIVITY 22nd - 23rd August 2013<br>
slide3. Connectivity context – Highly dynamic ecosystem with critical role for ASEAN economic development 7_85 ASEAN telecommunications markets dominated by mobile - >2/3 of revenue in most markets except Singapore
Continued strong growth rates beyond mobile penetration rates of 100%, with slight declines in ARPU
Region characterized by high variance in market structure - by ARPU levels, pre- vs. postpaid, levels of data usage/smartphone ownership
Competition tends to be highly concentrated around top 3 players (>80% share), still with strong role of domestic-only telcos with select regional players
Ongoing massive shift to data and 3G on the back of rapidly declining smartphone prices; emerging markets to date showing better monetization on traffic than developed markets
Fixed connectivity in most markets at low levels of development with <20 connections/inhabitants – however strong push across region on fiber rollouts, with Singapore and Malaysia as early movers<br>
slide4. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
slide5. Roaming charges in ASEAN countries are significantly higher than in Europe and vary across Telcos Data charges
(per MB) Voice charges - calls made
(per min) Voice charges - calls received
(per min) SMS charges Range n/a Note: Charges are for usage within/across ASEAN countries; charges vary based on call or usage destination; charges exclude VAT
Source: Telco websites<br>
slide6. ASEAN APT APEC Roaming regulations in ASEAN would need to be strengthened to reduce charges 6_85 14_85 15_85 16_85 18_85 11_85 13_85 Europe’s regulation on roaming is holistic & well-enforced… …initiatives across Asia not commonly enforced, thus less impactful Holistic regulatory approach to international data roaming services
Protect consumer interest
Good compliance in all member states
Ofcom, UK communications regulator, helps enforce roaming regulation 2009 2011 2007 Roaming III: Caps retail prices for data roaming
Customers can sign up for a mobile roaming contract with foreign operators while traveling Public consultation on 2007 regulation; results not satisfactory
Roaming II: Cut in SMS and wholesale data roaming charges
Cut-off mechanism available once bill reaches €50 Roaming I: Cap wholesale & retail charges for voice calls Note: ATRC: ASEAN Telecommunication Regulators Council; APT: Asia Pacific Telecommunity; APEC: Asia Pacific Economic Cooperation
Source: Ovum “Regulatory Status of International Roaming” Adoption of the Addendum of ATRC* Intra-ASEAN Mobile Roaming Rates to reduce roaming charges; countries to implement when ready
Bilateral initiatives common
Malaysia & Singapore
Malaysia & Brunei
Singapore & Brunei 1 2 3 Addresses transparency measures & bill shock
Aims to remove regulatory barriers that cause high input costs for roaming Issued guidelines on provision of info to consumers on roaming & substitute technologies<br>
slide7. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
slide8. OTT services in ASEAN markets are growing; likely a threat to SMS revenue SMS as a source of revenue has been declining… …likely due to growth in ott services Many market drivers supporting substitution to OTT services
Increasing Smartphone penetration
Low price compared to regular voice
Ease of access
Apps and app marketplaces
Telcos start to bundle VoIP (in particular smaller Telcos in fragmented markets)
Technological development
Improved sound quality on 3G networks
Deployment of high capacity all-IP networks (e.g. LTE)
Availability of alternative networks (Wi-Fi)
Features e.g. video conferencing
Net neutrality regulation undermine attempts to block VoIP in certain markets
Increase in consumer demand as users of dedicated VoIP expect mVoIP 13_85 Note: Non-voice revenue include data, messaging & VAS; does not include all Telcos in each countries
Source: Wireless Intelligence; Gartner; Ovum; Informa<br>
slide9. 8_85 16_85 ASEAN players are expanding networks, partnering with OTT players & pushing apps usage INDONESIA Singapore *Rich Communications Services provide similar rich-featured messaging standards as OTT apps
Source: Analyst reports; Bain analysis Malaysia<br>
slide10. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
slide11. A significant portion of the ASEAN population is still not served by the formal financial sector Note: Banked population defined as percentage of the population 15 years and older that has a formal relationship with a bank or other financial institution via a current savings account, checking account, credit card or a combination of these products”
Source: Euromonitor Banked Unbanked<br>
slide12. Rapid growth in mobile usage presents a unique channel to reach both banked and unbanked segments Source: USAID, Sybase, Bain analysis In contrast [to the banking sector], the Indonesian telco sector has been extremely effective in moving down market. … Combining FS expert with the broad market capabilities of the mobile telco channel presents a unique opportunity for gov’t and commercial entities to develop new business opportunities
- USAID Report “ ” With the Indonesian population at approximately 250 million people, these new mobile banking services will help us attract new customers and expand our market share significantly
- Strategy & Finance Director
CIMB Niaga ” “ EXAMPLE Indonesia - Mobile penetration overtook banking penetration since ’06… …Presenting an opportunity to target both banked and unbanked segments in innovative ways<br>
slide13. Opportunities in mobile money along three categories of usage Transactions Services Mobile Commerce Mobile Banking Source: Bain analysis 1 2 3 Utility bill payments
Remittances (domestic, international)
Cash-in/cash-out
Via banks, retailers, agents
Including government cash payments Stored value account
Mobile top-up
Mobile wallet-to-wallet transfers (P2P) M-Wallet Traditional Payments E.g., online shopping, online games, media, virtual products Mobile consumer services Mobile shop/portal services Mobile Banking Banking inquiries
E.g., account balances, SMS alerts
Mobile/online savings accounts
Mobile/online loan applications and disbursements
Insurance E.g., customer loyalty, mobile ads, coupons and offers Mobile marketing services New mobile merchant payment technology (mobile POS, P2P on the spot, …) Mobile merchant services New mobile consumer payment technology (NFC, QR code, …)<br>
slide14. Agenda International roaming
OTT in ASEAN
New services - Mobile money/virtual CC; potential for mobile advertising
Regulatory maturity in ASEAN – spectrum, interconnect, local content requirements 3_89<br>
slide15. Regulatory challenges across ASEAN similar with potential for learning from other markets – select examples 19_85 48_85 50_85 51_85 Spectrum Interconnect Fiber rollout Various approaches to shaping competition, from focusing on few key players to fostering new entrants
Increasing emphasis on assigning common spectrum blocks across ASEAN to facilitate connectivity (e.g. digital dividend blocks by 2020) General trend to reduce interconnect charges across markets, e.g. recent efforts in Thailand, which typically enable more level playing field for challengers
Few exception like SMS Interconnect in Indonesia to reduce amount of spamming Local content Emerging trend to push local economic participation in technology sectors related to telecoms, with efforts particularly in Indonesia
Questionable net benefits as competition gets disrupted Only Singapore and Malaysia with broad rollout to date
Key future challenge to enable broad-based rollout in other ASEAN markets, where telco economics often do not justify investments but significant multiplier benefits for other sectors are expected – various forms of public/private partnerships can be used<br>
slide17. THANK YOU Organiser Co-Organiser<br>