
2nd quarter and 1st half 2020 | 04.08.2020 BRD





Description: 2nd quarter and 1st half 2020 04.08.2020 BRD GROUP RESULTS DISCLAIMER The consolidated and separate financial position and income statement for the period ended June 30, 2020 were examined by the Board of Directors on July 30, 2020. The
Related Topics
Download Presentation
"2nd quarter and 1st half 2020 | 04.08.2020 BRD" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. 2nd quarter and 1st half 2020 | 04.08.2020 BRD GROUP RESULTS<br>
slide2. DISCLAIMER The consolidated and separate financial position and income statement for the period ended June 30, 2020 were examined by the Board of Directors on July 30, 2020.
The financial information presented for the period ended June 30, 2020 and comparative periods has been prepared according to IFRS as adopted by the European Union and applicable at this date.
This financial information is at group level, does not constitute a full set of financial statements and is not audited.
This presentation may contain forward-looking statements relating to the targets and strategies of BRD, based on a series of assumptions. These forward-looking statements would have been developed from scenarios based on a number of economic assumptions in the context of a given competitive and regulatory environment. BRD may be unable to anticipate all the risks, uncertainties or other factors likely to affect its business and to appraise their potential consequences, and to evaluate the extent to which the occurrence of a risk or a combination of risks could cause actual results to differ materially from those provided in this document.
Investors and analysts are advised to take into account factors of uncertainty and risk likely to impact the operations of BRD when considering the information contained in any such forward-looking statements. Other than as required by applicable law, BRD does not undertake any obligation to update or revise any forward-looking information or statements.<br>
slide3. INTRODUCTION 1<br>
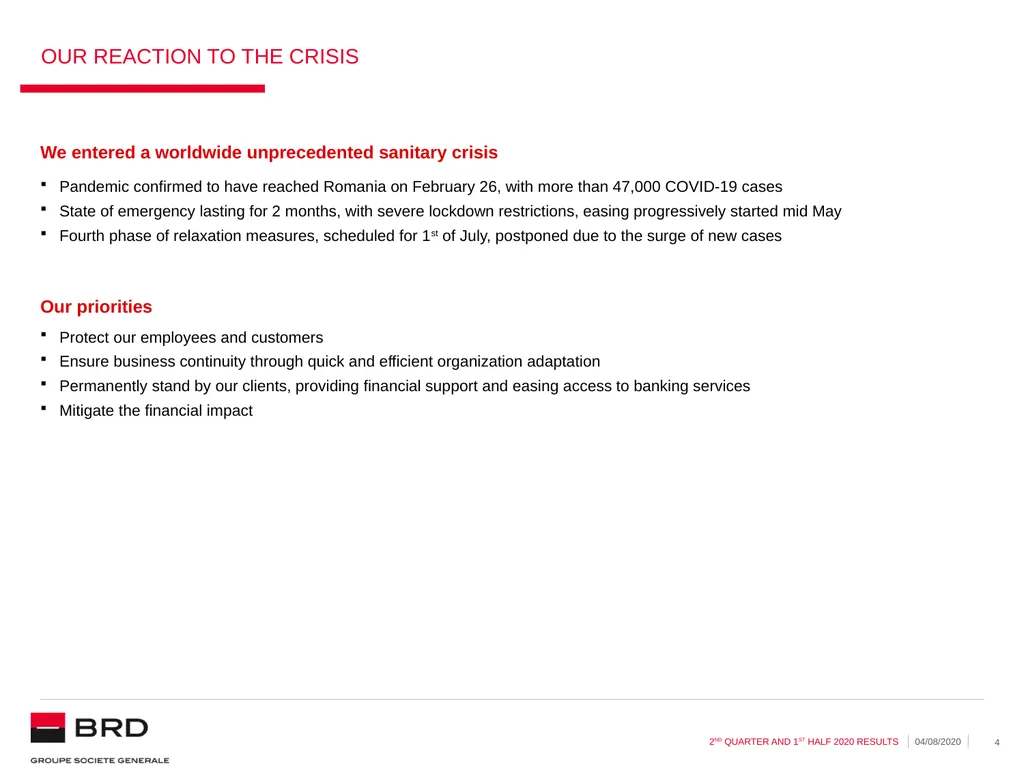
slide4. We entered a worldwide unprecedented sanitary crisis Pandemic confirmed to have reached Romania on February 26, with more than 47,000 COVID-19 cases
State of emergency lasting for 2 months, with severe lockdown restrictions, easing progressively started mid May
Fourth phase of relaxation measures, scheduled for 1st of July, postponed due to the surge of new cases OUR REACTION TO THE CRISIS Our priorities Protect our employees and customers
Ensure business continuity through quick and efficient organization adaptation
Permanently stand by our clients, providing financial support and easing access to banking services
Mitigate the financial impact<br>
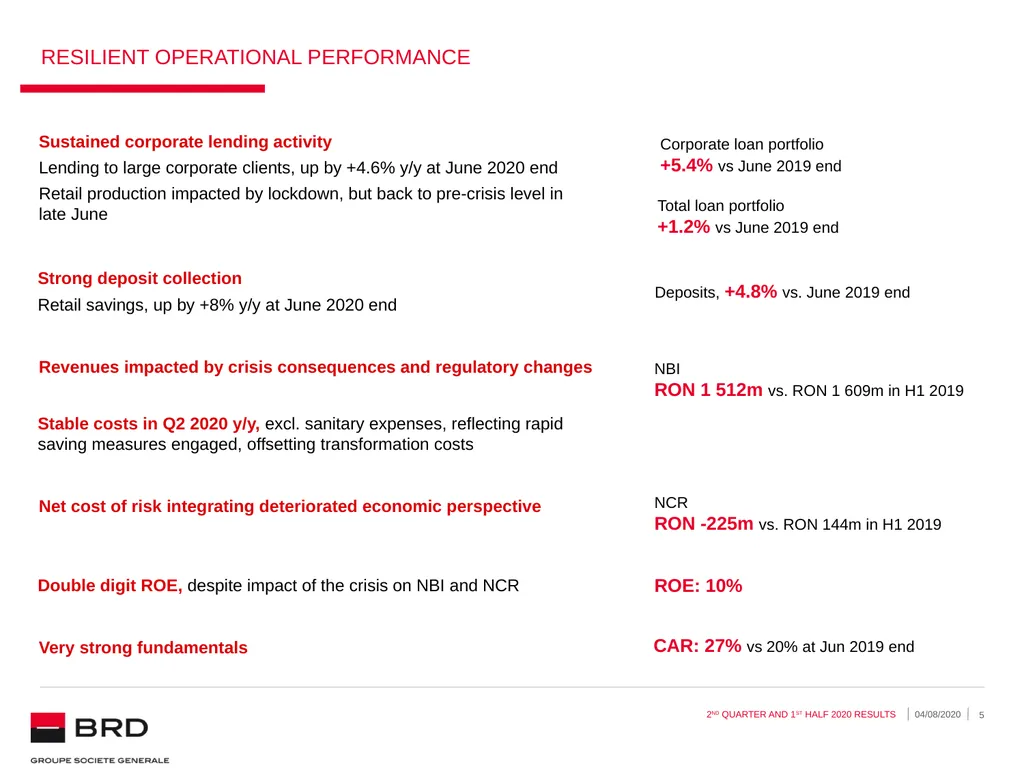
slide5. 04/08/2020 5 2nd Quarter and 1st Half 2020 RESULTS RESILIENT operational performance CAR: 27% vs 20% at Jun 2019 end Sustained corporate lending activity
Lending to large corporate clients, up by +4.6% y/y at June 2020 end
Retail production impacted by lockdown, but back to pre-crisis level in late June Very strong fundamentals NCR
RON -225m vs. RON 144m in H1 2019 Stable costs in Q2 2020 y/y, excl. sanitary expenses, reflecting rapid saving measures engaged, offsetting transformation costs Revenues impacted by crisis consequences and regulatory changes Total loan portfolio
+1.2% vs June 2019 end Net cost of risk integrating deteriorated economic perspective Double digit ROE, despite impact of the crisis on NBI and NCR Strong deposit collection
Retail savings, up by +8% y/y at June 2020 end ROE: 10% Corporate loan portfolio
+5.4% vs June 2019 end Deposits, +4.8% vs. June 2019 end NBI
RON 1 512m vs. RON 1 609m in H1 2019<br>
slide6. Macroeconomic environment 2<br>
slide7. COVID-19 crisis puts an end to a 9 Year expansionary cycle GDP GROWTH Q1 2020 confirmed the end of the expansionary phase of the cycle
EU GDP registered the sharpest decline observed since 1995, when reporting started, as COVID-19 containment measures began to be widely introduced
Romania’s GDP growth of 2.7%, though showing initial effects of crisis, marked the highest rate in EU
Domestic demand remains the main driver of economic expansion, followed by gross fixed capital formation
Net exports kept their negative contribution to growth
In Q2, the lockdown led to a strong contraction of activity and consumption Inflation rate down
CPI dropped at a fast pace in the first months of the year printing at +2.6% y/y at June 2020 end (vs 4.0% at Dec-19 end), on disinflationary base effects, the plunge in oil price, the removal of the special excise duty on motor fuels, outpacing strong food inflation generated by Covid-19 outbreak 2020 GDP expected to drop by 6%-7%* * In a scenario of continued progressive lifting of restrictions<br>
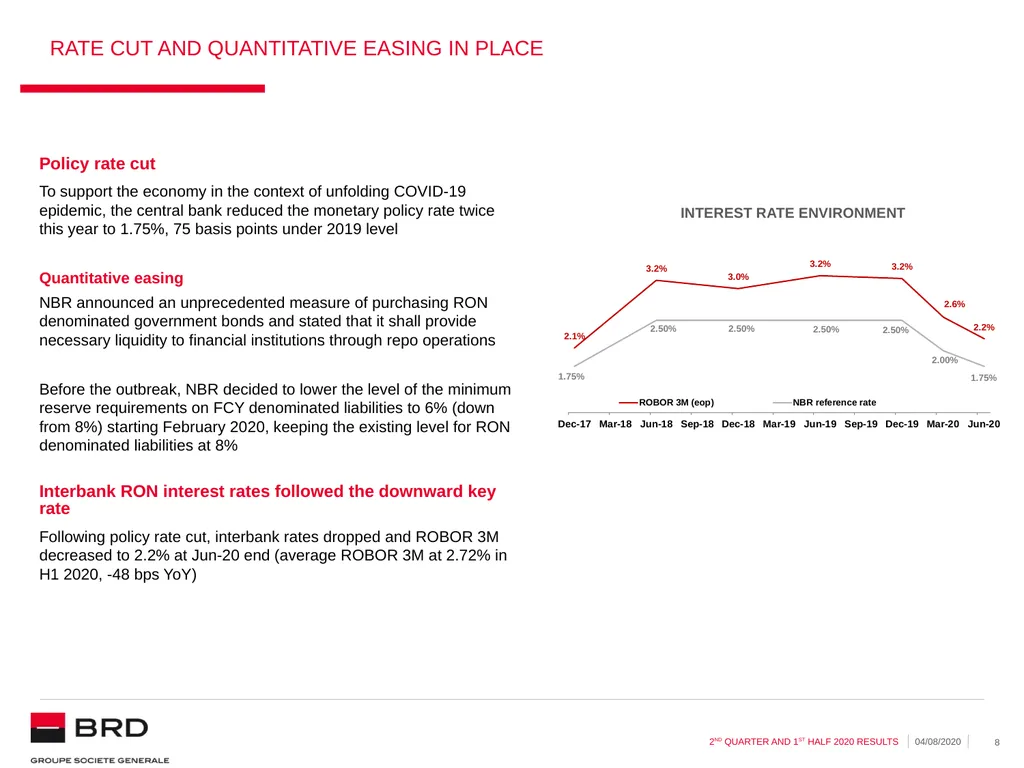
slide8. Rate cut and quantitative easing in place INTEREST RATE ENVIRONMENT Policy rate cut
To support the economy in the context of unfolding COVID-19 epidemic, the central bank reduced the monetary policy rate twice this year to 1.75%, 75 basis points under 2019 level
Quantitative easing
NBR announced an unprecedented measure of purchasing RON denominated government bonds and stated that it shall provide necessary liquidity to financial institutions through repo operations
Before the outbreak, NBR decided to lower the level of the minimum reserve requirements on FCY denominated liabilities to 6% (down from 8%) starting February 2020, keeping the existing level for RON denominated liabilities at 8% Interbank RON interest rates followed the downward key rate
Following policy rate cut, interbank rates dropped and ROBOR 3M decreased to 2.2% at Jun-20 end (average ROBOR 3M at 2.72% in H1 2020, -48 bps YoY)<br>
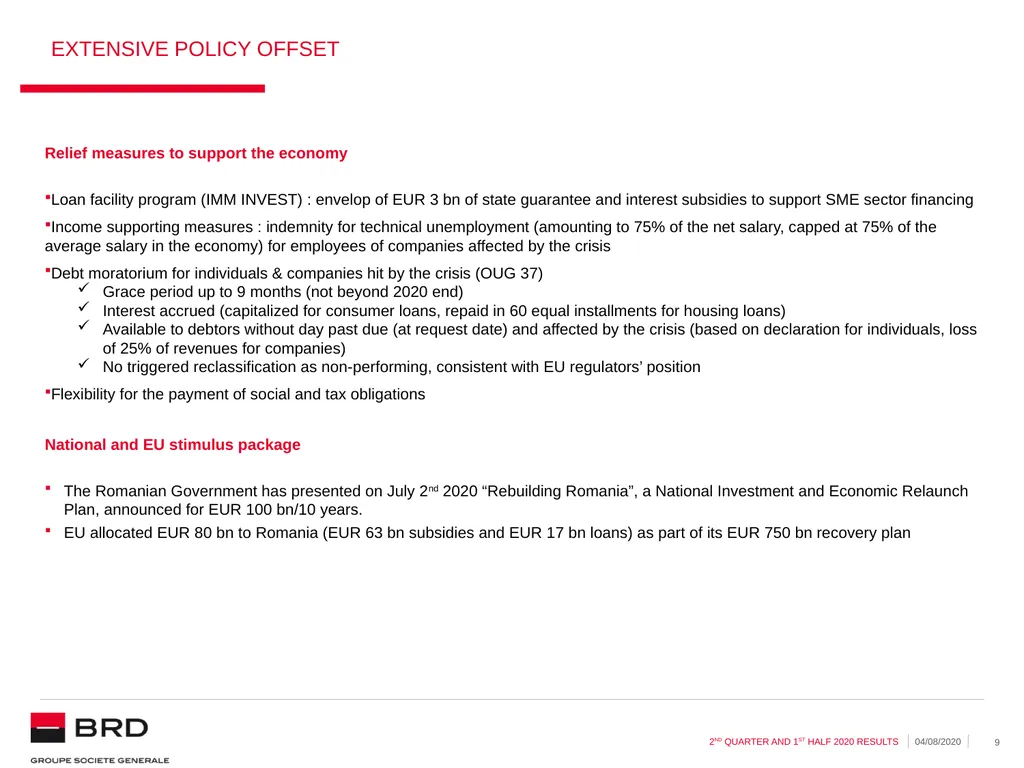
slide9. EXTENSIVE POLICY OFFSET Relief measures to support the economy
Loan facility program (IMM INVEST) : envelop of EUR 3 bn of state guarantee and interest subsidies to support SME sector financing
Income supporting measures : indemnity for technical unemployment (amounting to 75% of the net salary, capped at 75% of the average salary in the economy) for employees of companies affected by the crisis
Debt moratorium for individuals & companies hit by the crisis (OUG 37)
Grace period up to 9 months (not beyond 2020 end)
Interest accrued (capitalized for consumer loans, repaid in 60 equal installments for housing loans)
Available to debtors without day past due (at request date) and affected by the crisis (based on declaration for individuals, loss of 25% of revenues for companies)
No triggered reclassification as non-performing, consistent with EU regulators’ position
Flexibility for the payment of social and tax obligations
National and EU stimulus package
The Romanian Government has presented on July 2nd 2020 “Rebuilding Romania”, a National Investment and Economic Relaunch Plan, announced for EUR 100 bn/10 years.
EU allocated EUR 80 bn to Romania (EUR 63 bn subsidies and EUR 17 bn loans) as part of its EUR 750 bn recovery plan<br>
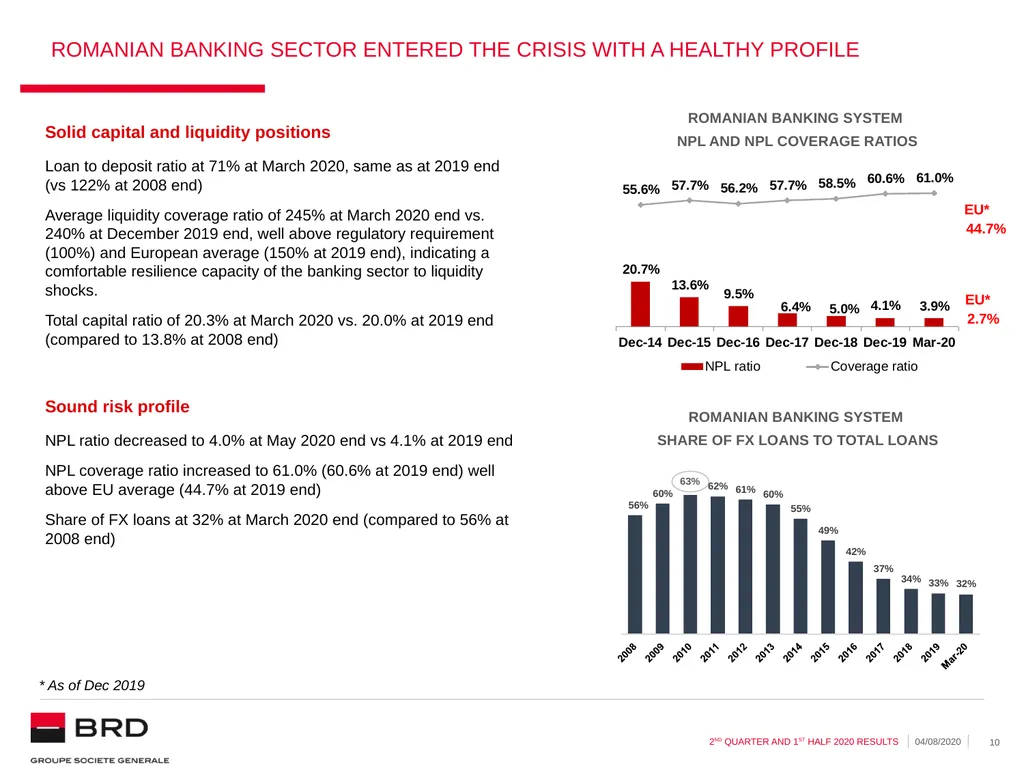
slide10. Romanian BANKING SECTOR entered the crisis with a healthy profile Sound risk profile
NPL ratio decreased to 4.0% at May 2020 end vs 4.1% at 2019 end
NPL coverage ratio increased to 61.0% (60.6% at 2019 end) well above EU average (44.7% at 2019 end)
Share of FX loans at 32% at March 2020 end (compared to 56% at 2008 end) Solid capital and liquidity positions
Loan to deposit ratio at 71% at March 2020, same as at 2019 end (vs 122% at 2008 end)
Average liquidity coverage ratio of 245% at March 2020 end vs. 240% at December 2019 end, well above regulatory requirement (100%) and European average (150% at 2019 end), indicating a comfortable resilience capacity of the banking sector to liquidity shocks.
Total capital ratio of 20.3% at March 2020 vs. 20.0% at 2019 end (compared to 13.8% at 2008 end) ROMANIAN BANKING SYSTEM
NPL AND NPL COVERAGE RATIOS ROMANIAN BANKING SYSTEM
SHARE OF FX LOANS TO TOTAL LOANS * As of Dec 2019<br>
slide11. 2nd quarter and 1st half 2020 brd group results 3<br>
slide12. Quickly adapting to address the crisis situation, ensure business continuity and provide operational support to our clients Protect our customers and employees through implementation of adequate sanitary measures and prevention actions in all business outlets
Ensure business continuity with extended WFH, split teams deployed in different work locations
Facilitate access to banking services for our customers
Permanent communication with the clients, a dedicated web page and integrated communication (website, branches, ATMs, Facebook, etc.)
Enhanced contact centre capabilities: number of answered customer calls increased by +46% y/y in H1 2020
Promoting digital channels, with My BRD Mobile and My BRD Net free of charge for 3 months<br>
slide13. Fully committed TO support our clients WITH FINANCING SOLUTIONS Moratorium
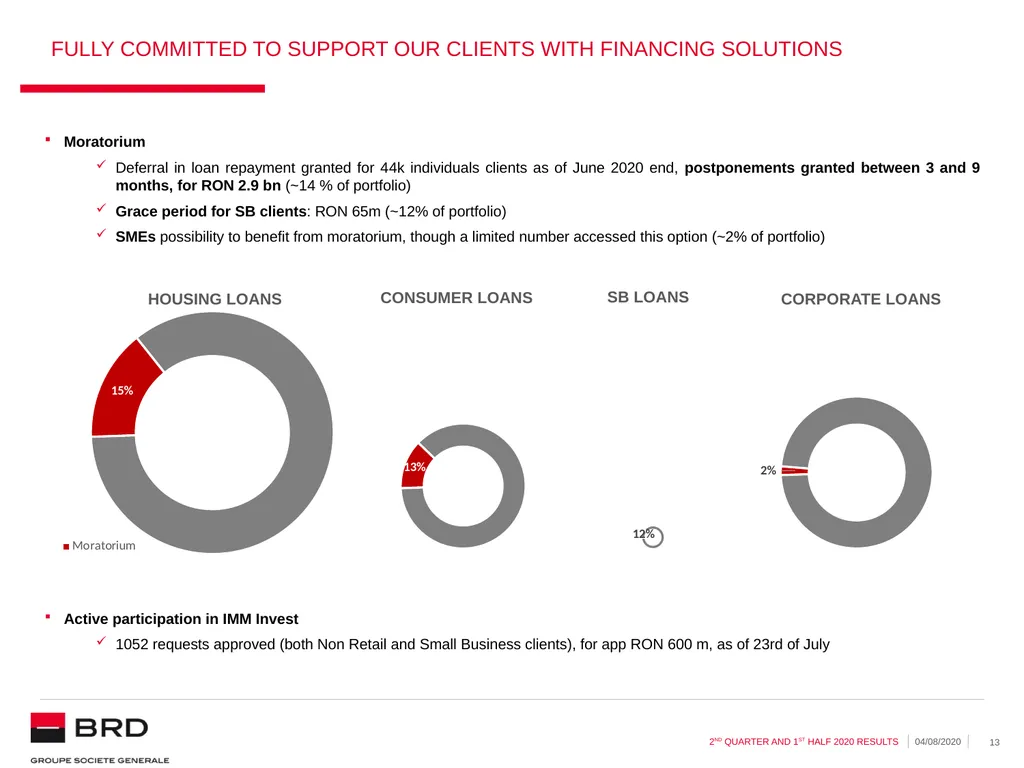
Deferral in loan repayment granted for 44k individuals clients as of June 2020 end, postponements granted between 3 and 9 months, for RON 2.9 bn (~14 % of portfolio)
Grace period for SB clients: RON 65m (~12% of portfolio)
SMEs possibility to benefit from moratorium, though a limited number accessed this option (~2% of portfolio) HOUSING LOANS CONSUMER LOANS SB LOANS CORPORATE LOANS Active participation in IMM Invest
1052 requests approved (both Non Retail and Small Business clients), for app RON 600 m, as of 23rd of July<br>
slide14. Acceleration of our digital roadmap Fewer branches
More specialized
Better service Contact Center Apps & website Apple Pay, a safer and faster way to pay, available to BRD digital users
Possibility for clients to update their data through the website brd.ro Growing digital penetration
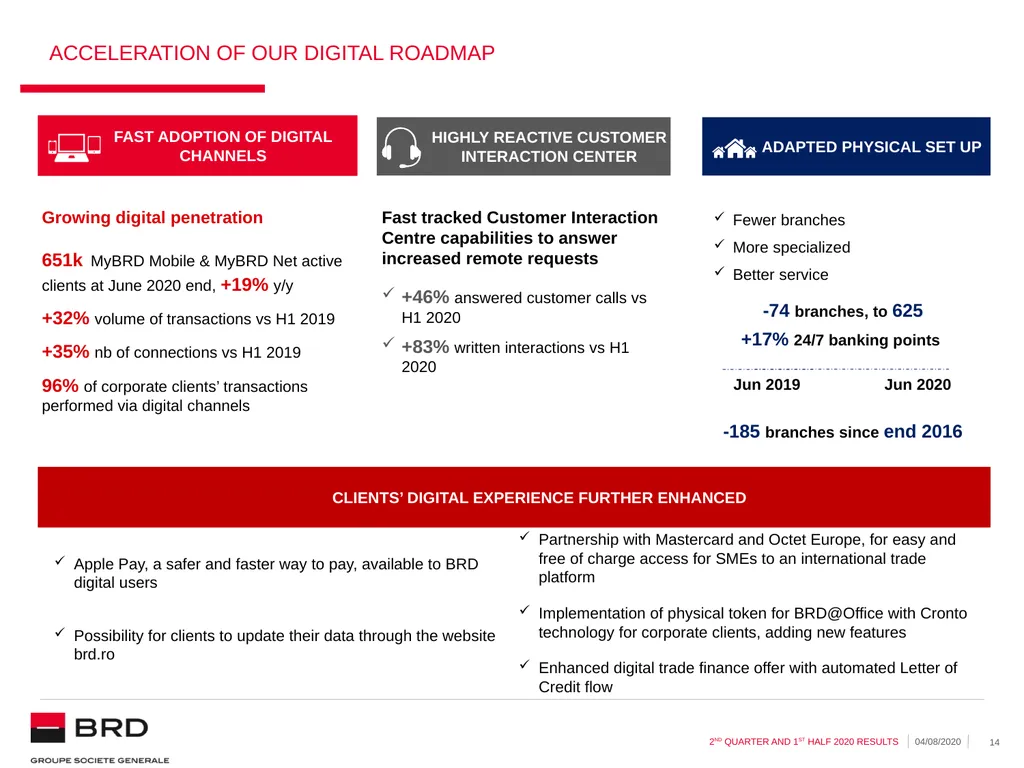
651k MyBRD Mobile & MyBRD Net active clients at June 2020 end, +19% y/y
+32% volume of transactions vs H1 2019
+35% nb of connections vs H1 2019
96% of corporate clients’ transactions performed via digital channels FAST ADOPTION OF DIGITAL CHANNELS ADAPTED PHYSICAL SET UP HIGHLY REACTIVE CUSTOMER INTERACTION CENTER Fast tracked Customer Interaction Centre capabilities to answer increased remote requests
+46% answered customer calls vs H1 2020
+83% written interactions vs H1 2020 CLIENTS’ DIGITAL EXPERIENCE FURTHER ENHANCED Partnership with Mastercard and Octet Europe, for easy and free of charge access for SMEs to an international trade platform
Implementation of physical token for BRD@Office with Cronto technology for corporate clients, adding new features
Enhanced digital trade finance offer with automated Letter of Credit flow -185 branches since end 2016<br>
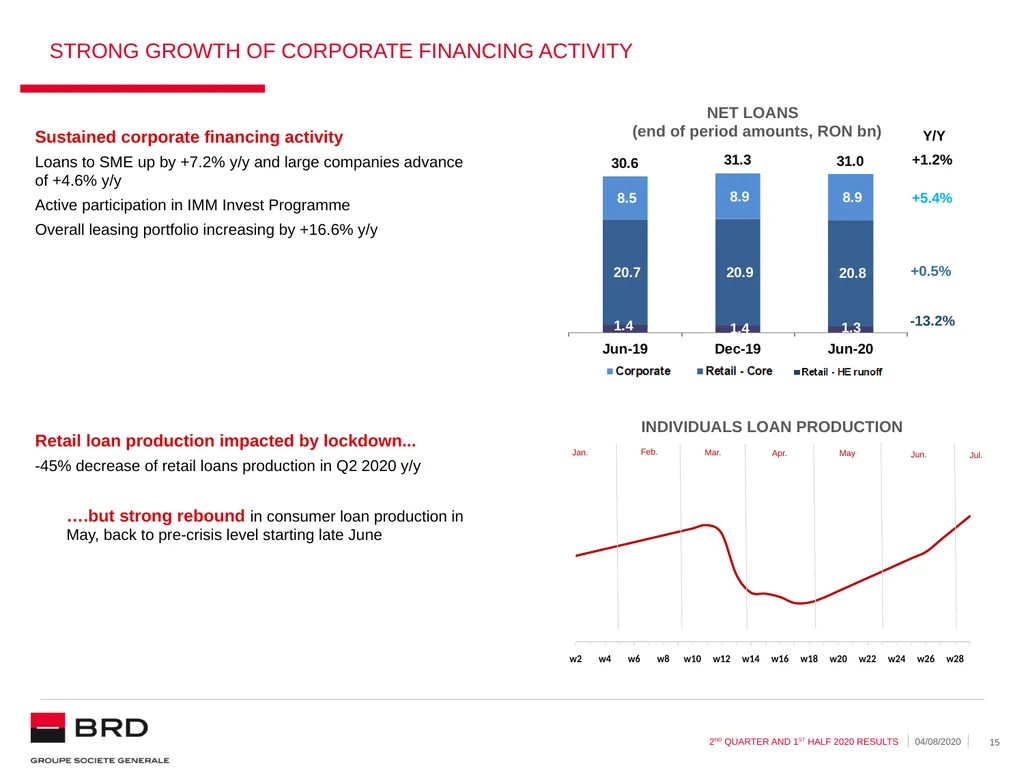
slide15. STRONG GROWTH OF corporate financing ACTIVITY NET LOANS
(end of period amounts, RON bn) Y/Y +1.2% +0.5% -13.2% Retail loan production impacted by lockdown...
-45% decrease of retail loans production in Q2 2020 y/y
….but strong rebound in consumer loan production in May, back to pre-crisis level starting late June Sustained corporate financing activity
Loans to SME up by +7.2% y/y and large companies advance of +4.6% y/y
Active participation in IMM Invest Programme
Overall leasing portfolio increasing by +16.6% y/y INDIVIDUALS LOAN PRODUCTION +5.4% Jan. Feb. Mar. Apr. May Jun. Jul.<br>
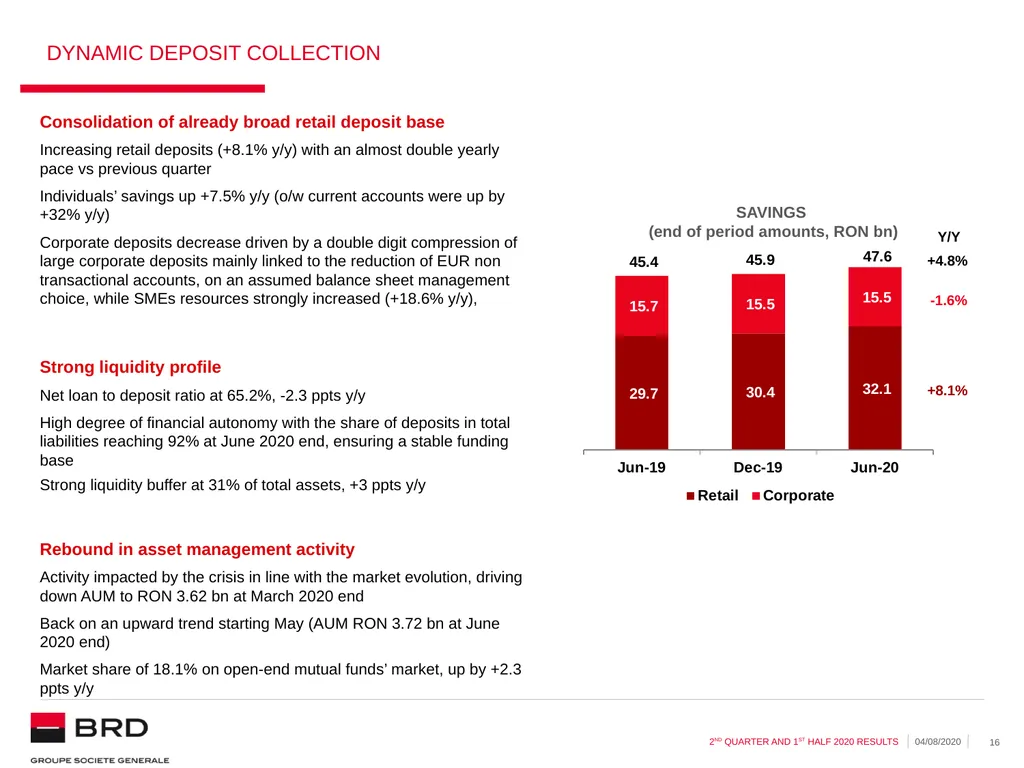
slide16. Y/Y DYNAMIC DEPOSIT COLLECTION SAVINGS
(end of period amounts, RON bn) +4.8% -1.6% +8.1% Consolidation of already broad retail deposit base
Increasing retail deposits (+8.1% y/y) with an almost double yearly pace vs previous quarter
Individuals’ savings up +7.5% y/y (o/w current accounts were up by +32% y/y)
Corporate deposits decrease driven by a double digit compression of large corporate deposits mainly linked to the reduction of EUR non transactional accounts, on an assumed balance sheet management choice, while SMEs resources strongly increased (+18.6% y/y),
Strong liquidity profile
Net loan to deposit ratio at 65.2%, -2.3 ppts y/y
High degree of financial autonomy with the share of deposits in total liabilities reaching 92% at June 2020 end, ensuring a stable funding base
Strong liquidity buffer at 31% of total assets, +3 ppts y/y
Rebound in asset management activity
Activity impacted by the crisis in line with the market evolution, driving down AUM to RON 3.62 bn at March 2020 end
Back on an upward trend starting May (AUM RON 3.72 bn at June 2020 end)
Market share of 18.1% on open-end mutual funds’ market, up by +2.3 ppts y/y<br>
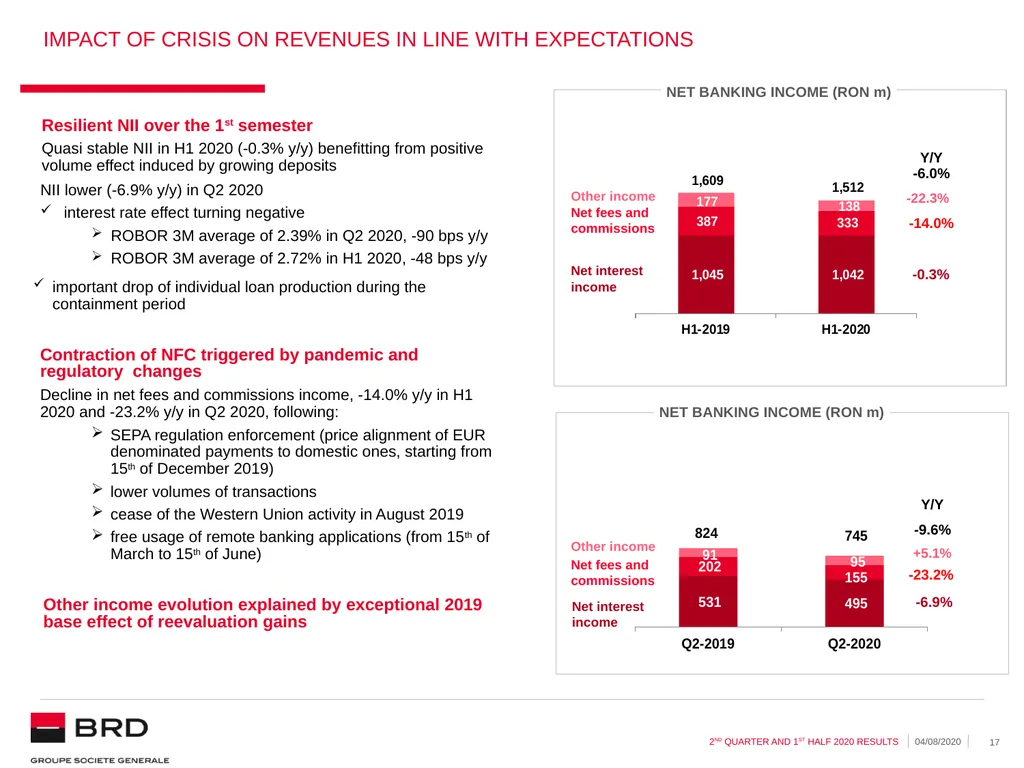
slide17. IMPACT OF CRISIS ON REVENUES IN LINE WITH EXPECTATIONS NET BANKING INCOME (RON m) Other income Net fees and commissions Net interest income Y/Y -6.0% -22.3% -14.0% -0.3% Contraction of NFC triggered by pandemic and regulatory changes
Decline in net fees and commissions income, -14.0% y/y in H1 2020 and -23.2% y/y in Q2 2020, following:
SEPA regulation enforcement (price alignment of EUR denominated payments to domestic ones, starting from 15th of December 2019)
lower volumes of transactions
cease of the Western Union activity in August 2019
free usage of remote banking applications (from 15th of March to 15th of June) Resilient NII over the 1st semester
Quasi stable NII in H1 2020 (-0.3% y/y) benefitting from positive volume effect induced by growing deposits Other income evolution explained by exceptional 2019 base effect of reevaluation gains NET BANKING INCOME (RON m) Other income Net fees and commissions Net interest income Y/Y -9.6% +5.1% -23.2% -6.9% NII lower (-6.9% y/y) in Q2 2020
interest rate effect turning negative
ROBOR 3M average of 2.39% in Q2 2020, -90 bps y/y
ROBOR 3M average of 2.72% in H1 2020, -48 bps y/y important drop of individual loan production during the containment period<br>
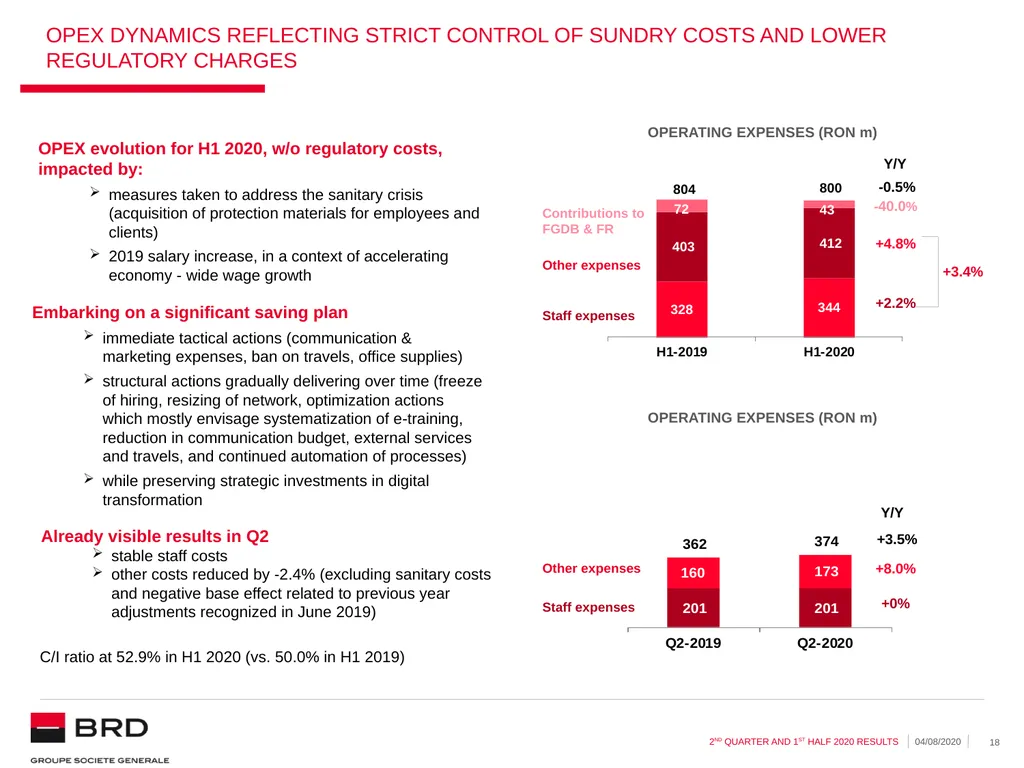
slide18. OPEX DYNAMICs reflecting strict control of sundry costs and lower regulatory charges OPERATING EXPENSES (RON m) Other expenses Staff expenses -0.5% +2.2% +4.8% Y/Y Contributions to FGDB & FR OPEX evolution for H1 2020, w/o regulatory costs, impacted by:
measures taken to address the sanitary crisis (acquisition of protection materials for employees and clients)
2019 salary increase, in a context of accelerating economy - wide wage growth -40.0% OPERATING EXPENSES (RON m) Already visible results in Q2
stable staff costs
other costs reduced by -2.4% (excluding sanitary costs and negative base effect related to previous year adjustments recognized in June 2019) Other expenses Staff expenses +3.5% +0% +8.0% Y/Y Embarking on a significant saving plan
immediate tactical actions (communication & marketing expenses, ban on travels, office supplies)
structural actions gradually delivering over time (freeze of hiring, resizing of network, optimization actions which mostly envisage systematization of e-training, reduction in communication budget, external services and travels, and continued automation of processes)
while preserving strategic investments in digital transformation C/I ratio at 52.9% in H1 2020 (vs. 50.0% in H1 2019) +3.4%<br>
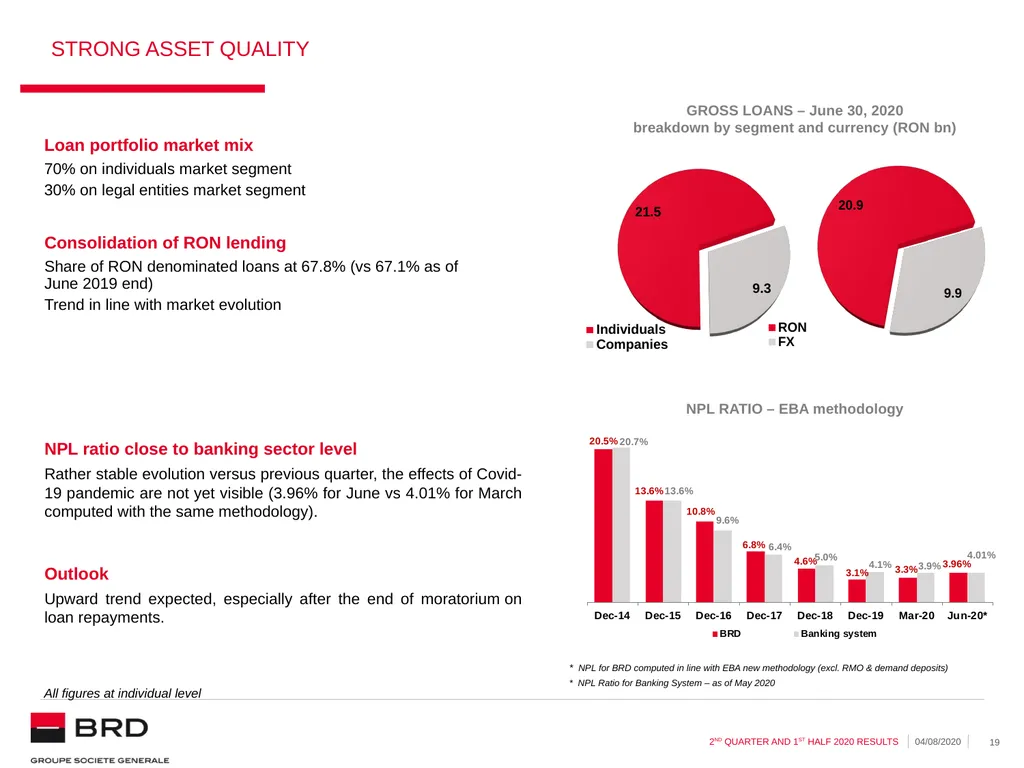
slide19. strong ASSET QUALITY All figures at individual level NPL RATIO – EBA methodology Loan portfolio market mix
70% on individuals market segment
30% on legal entities market segment Consolidation of RON lending
Share of RON denominated loans at 67.8% (vs 67.1% as of June 2019 end)
Trend in line with market evolution GROSS LOANS – June 30, 2020
breakdown by segment and currency (RON bn) NPL ratio close to banking sector level
Rather stable evolution versus previous quarter, the effects of Covid-19 pandemic are not yet visible (3.96% for June vs 4.01% for March computed with the same methodology).
Outlook
Upward trend expected, especially after the end of moratorium on loan repayments. * NPL for BRD computed in line with EBA new methodology (excl. RMO & demand deposits)
* NPL Ratio for Banking System – as of May 2020<br>
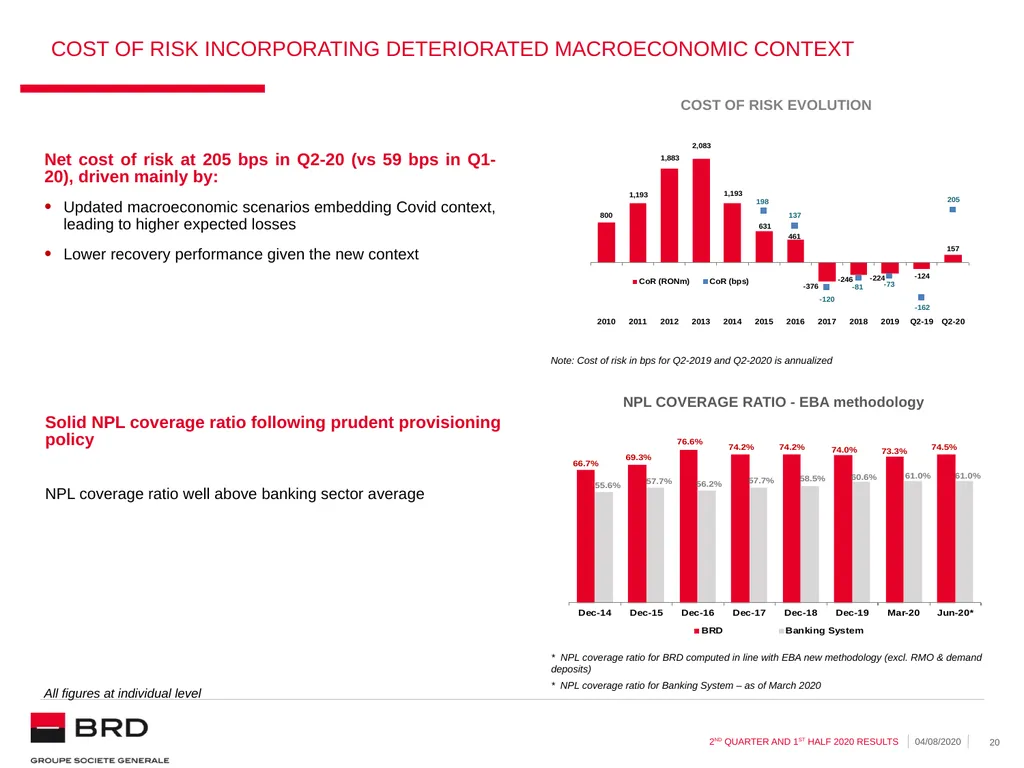
slide20. cost of risk INCORPORATING DETERIORATED MACROECONOMIC CONTEXT NPL COVERAGE RATIO - EBA methodology All figures at individual level COST OF RISK EVOLUTION Solid NPL coverage ratio following prudent provisioning policy
NPL coverage ratio well above banking sector average * NPL coverage ratio for BRD computed in line with EBA new methodology (excl. RMO & demand deposits)
* NPL coverage ratio for Banking System – as of March 2020 Note: Cost of risk in bps for Q2-2019 and Q2-2020 is annualized Net cost of risk at 205 bps in Q2-20 (vs 59 bps in Q1-20), driven mainly by:
Updated macroeconomic scenarios embedding Covid context, leading to higher expected losses
Lower recovery performance given the new context<br>
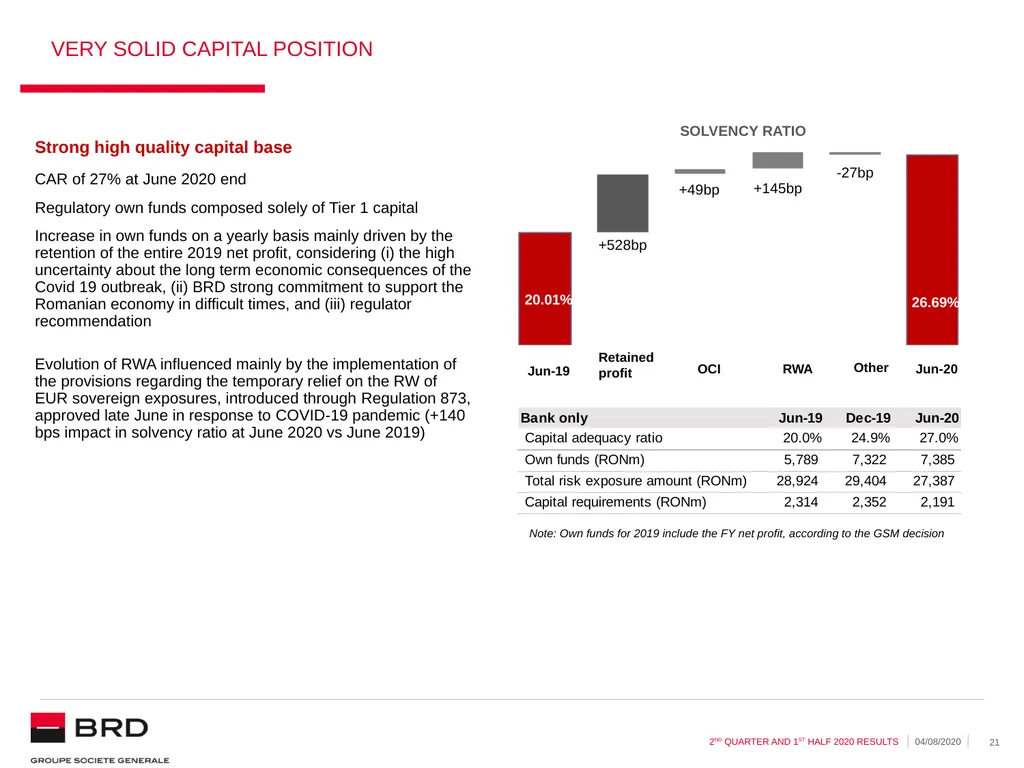
slide21. Very Solid capital position SOLVENCY RATIO Jun-19 Jun-20 Retained profit OCI RWA Other 20.01% Note: Own funds for 2019 include the FY net profit, according to the GSM decision +528bp +145bp -27bp +49bp 26.69% Strong high quality capital base
CAR of 27% at June 2020 end
Regulatory own funds composed solely of Tier 1 capital
Increase in own funds on a yearly basis mainly driven by the retention of the entire 2019 net profit, considering (i) the high uncertainty about the long term economic consequences of the Covid 19 outbreak, (ii) BRD strong commitment to support the Romanian economy in difficult times, and (iii) regulator recommendation
Evolution of RWA influenced mainly by the implementation of the provisions regarding the temporary relief on the RW of EUR sovereign exposures, introduced through Regulation 873, approved late June in response to COVID-19 pandemic (+140 bps impact in solvency ratio at June 2020 vs June 2019)<br>
slide22. conclusions 5<br>
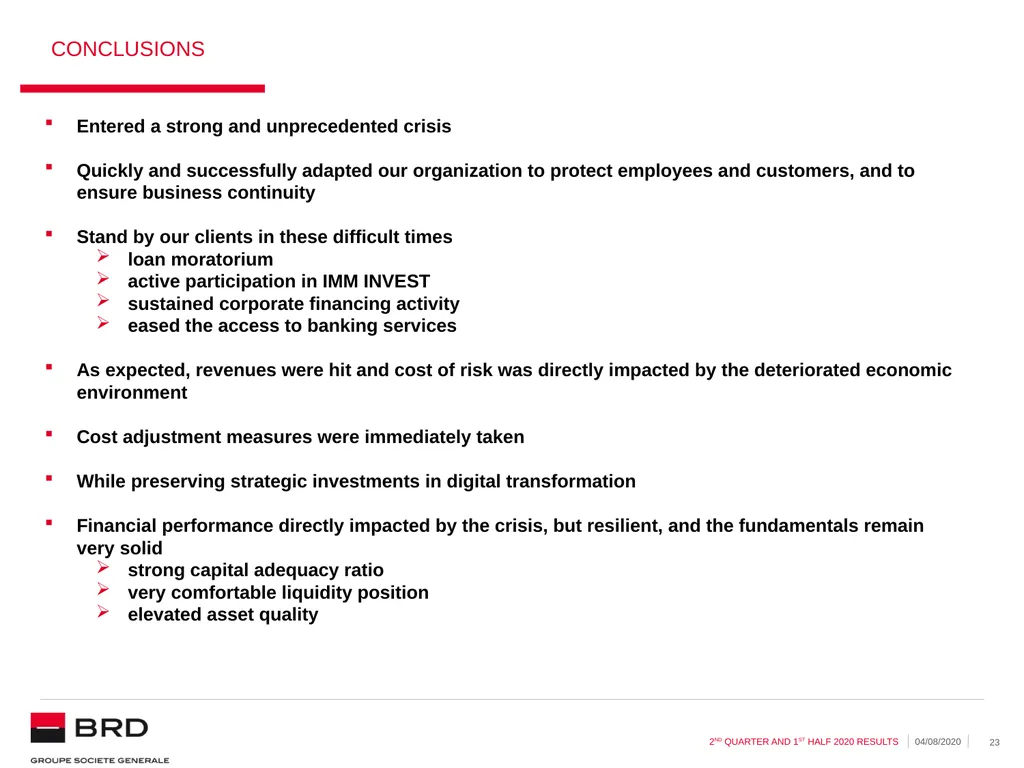
slide23. conclusions Entered a strong and unprecedented crisis
Quickly and successfully adapted our organization to protect employees and customers, and to ensure business continuity
Stand by our clients in these difficult times
loan moratorium
active participation in IMM INVEST
sustained corporate financing activity
eased the access to banking services
As expected, revenues were hit and cost of risk was directly impacted by the deteriorated economic environment
Cost adjustment measures were immediately taken
While preserving strategic investments in digital transformation
Financial performance directly impacted by the crisis, but resilient, and the fundamentals remain very solid
strong capital adequacy ratio
very comfortable liquidity position
elevated asset quality<br>
slide24. Q&A SESSION 6<br>
slide25. APPENDIX brd group – key figures brd standalone - key figures stock prIce performance FINANCIAL CALENDAR FOR 2020 GLOSSARY – CLIENT SEGMENTATION<br>
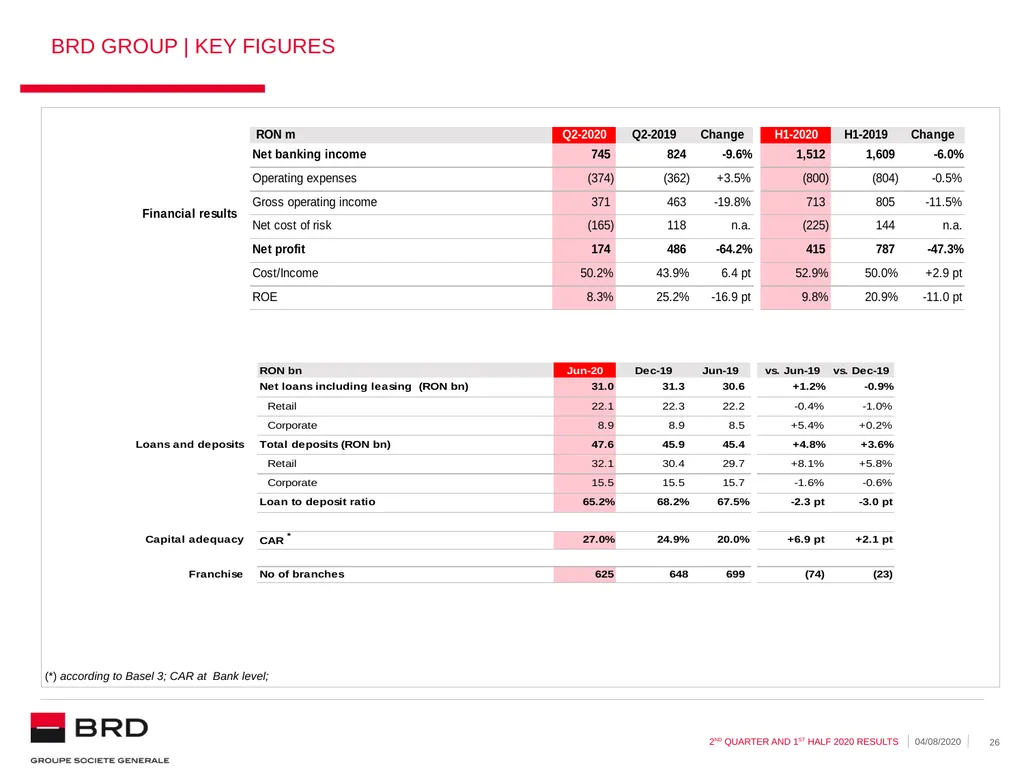
slide26. BRD GROUP | KEY FIGURES (1) Variations at constant exchange rate; (2) Bank only, including impact of prudential filters in Sep-17 and Dec-17; (*) according to Basel 3; CAR at Bank level;<br>
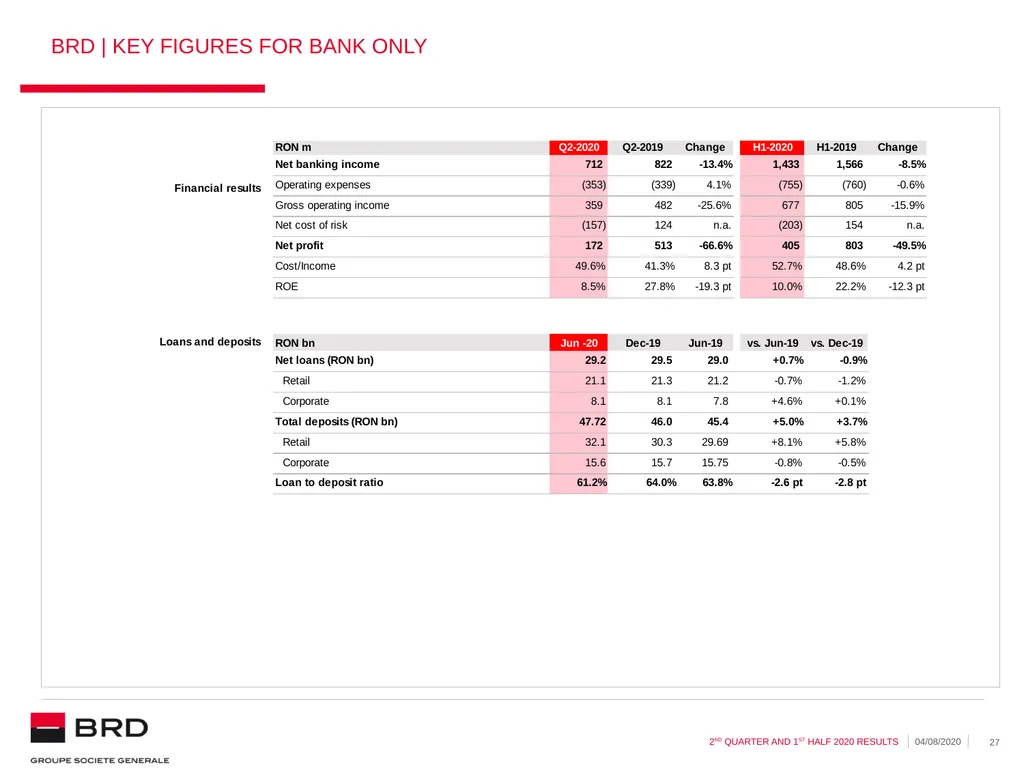
slide27. BRD | KEY FIGURES FOR BANK ONLY (1) Variations at constant exchange rate; (2) Bank only, including impact of prudential filters in Sep-17 and Dec-17;<br>
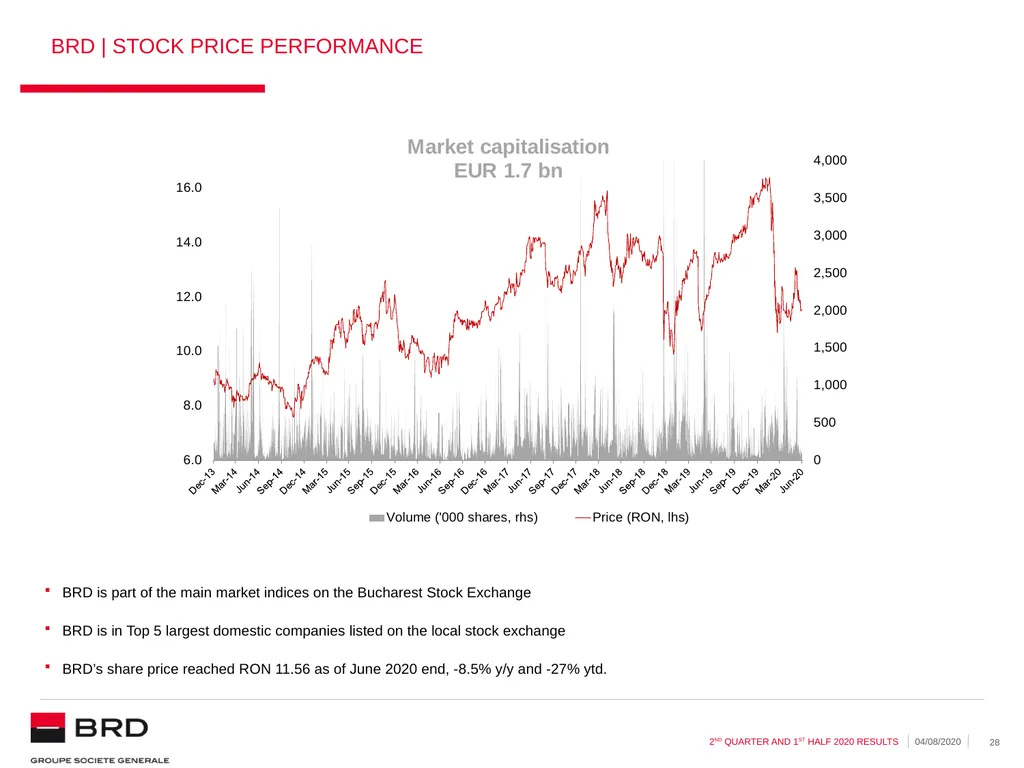
slide28. BRD | STOCK PRICE PERFORMANCE BRD is part of the main market indices on the Bucharest Stock Exchange
BRD is in Top 5 largest domestic companies listed on the local stock exchange
BRD’s share price reached RON 11.56 as of June 2020 end, -8.5% y/y and -27% ytd.<br>
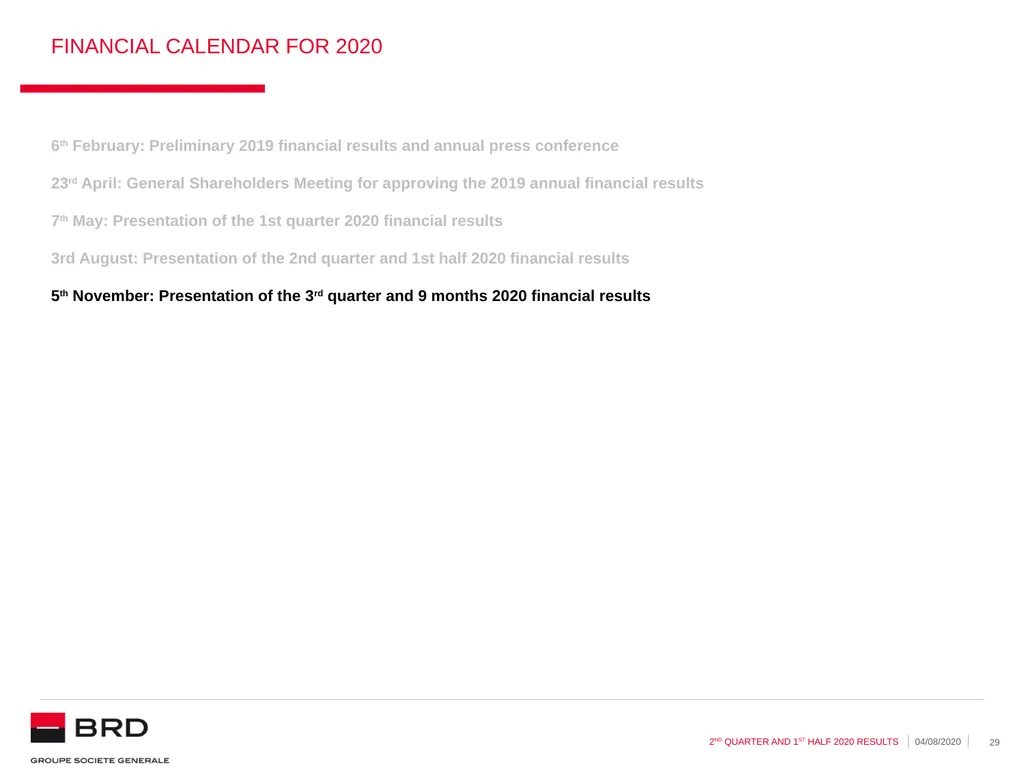
slide29. Financial calendar for 2020 6th February: Preliminary 2019 financial results and annual press conference
23rd April: General Shareholders Meeting for approving the 2019 annual financial results
7th May: Presentation of the 1st quarter 2020 financial results
3rd August: Presentation of the 2nd quarter and 1st half 2020 financial results
5th November: Presentation of the 3rd quarter and 9 months 2020 financial results<br>
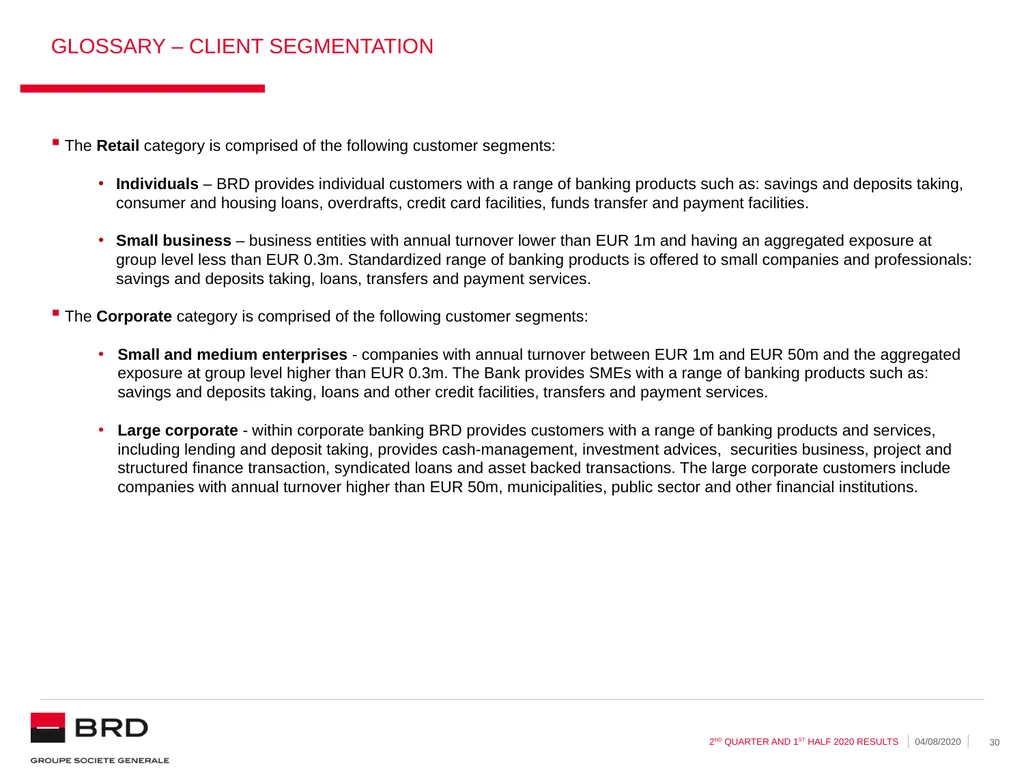
slide30. GLOSSARY – CLIENT SEGMENTATION The Retail category is comprised of the following customer segments:
Individuals – BRD provides individual customers with a range of banking products such as: savings and deposits taking, consumer and housing loans, overdrafts, credit card facilities, funds transfer and payment facilities.
Small business – business entities with annual turnover lower than EUR 1m and having an aggregated exposure at group level less than EUR 0.3m. Standardized range of banking products is offered to small companies and professionals: savings and deposits taking, loans, transfers and payment services.
The Corporate category is comprised of the following customer segments:
Small and medium enterprises - companies with annual turnover between EUR 1m and EUR 50m and the aggregated exposure at group level higher than EUR 0.3m. The Bank provides SMEs with a range of banking products such as: savings and deposits taking, loans and other credit facilities, transfers and payment services.
Large corporate - within corporate banking BRD provides customers with a range of banking products and services, including lending and deposit taking, provides cash-management, investment advices, securities business, project and structured finance transaction, syndicated loans and asset backed transactions. The large corporate customers include companies with annual turnover higher than EUR 50m, municipalities, public sector and other financial institutions.<br>
slide31. BRD GROUPE SOCIETE GENERALE - INVESTOR RELATIONS +4 021 380 47 62 | investor@brd.ro; www.brd.ro<br>
slide2. DISCLAIMER The consolidated and separate financial position and income statement for the period ended June 30, 2020 were examined by the Board of Directors on July 30, 2020.
The financial information presented for the period ended June 30, 2020 and comparative periods has been prepared according to IFRS as adopted by the European Union and applicable at this date.
This financial information is at group level, does not constitute a full set of financial statements and is not audited.
This presentation may contain forward-looking statements relating to the targets and strategies of BRD, based on a series of assumptions. These forward-looking statements would have been developed from scenarios based on a number of economic assumptions in the context of a given competitive and regulatory environment. BRD may be unable to anticipate all the risks, uncertainties or other factors likely to affect its business and to appraise their potential consequences, and to evaluate the extent to which the occurrence of a risk or a combination of risks could cause actual results to differ materially from those provided in this document.
Investors and analysts are advised to take into account factors of uncertainty and risk likely to impact the operations of BRD when considering the information contained in any such forward-looking statements. Other than as required by applicable law, BRD does not undertake any obligation to update or revise any forward-looking information or statements.<br>
slide3. INTRODUCTION 1<br>
slide4. We entered a worldwide unprecedented sanitary crisis Pandemic confirmed to have reached Romania on February 26, with more than 47,000 COVID-19 cases
State of emergency lasting for 2 months, with severe lockdown restrictions, easing progressively started mid May
Fourth phase of relaxation measures, scheduled for 1st of July, postponed due to the surge of new cases OUR REACTION TO THE CRISIS Our priorities Protect our employees and customers
Ensure business continuity through quick and efficient organization adaptation
Permanently stand by our clients, providing financial support and easing access to banking services
Mitigate the financial impact<br>
slide5. 04/08/2020 5 2nd Quarter and 1st Half 2020 RESULTS RESILIENT operational performance CAR: 27% vs 20% at Jun 2019 end Sustained corporate lending activity
Lending to large corporate clients, up by +4.6% y/y at June 2020 end
Retail production impacted by lockdown, but back to pre-crisis level in late June Very strong fundamentals NCR
RON -225m vs. RON 144m in H1 2019 Stable costs in Q2 2020 y/y, excl. sanitary expenses, reflecting rapid saving measures engaged, offsetting transformation costs Revenues impacted by crisis consequences and regulatory changes Total loan portfolio
+1.2% vs June 2019 end Net cost of risk integrating deteriorated economic perspective Double digit ROE, despite impact of the crisis on NBI and NCR Strong deposit collection
Retail savings, up by +8% y/y at June 2020 end ROE: 10% Corporate loan portfolio
+5.4% vs June 2019 end Deposits, +4.8% vs. June 2019 end NBI
RON 1 512m vs. RON 1 609m in H1 2019<br>
slide6. Macroeconomic environment 2<br>
slide7. COVID-19 crisis puts an end to a 9 Year expansionary cycle GDP GROWTH Q1 2020 confirmed the end of the expansionary phase of the cycle
EU GDP registered the sharpest decline observed since 1995, when reporting started, as COVID-19 containment measures began to be widely introduced
Romania’s GDP growth of 2.7%, though showing initial effects of crisis, marked the highest rate in EU
Domestic demand remains the main driver of economic expansion, followed by gross fixed capital formation
Net exports kept their negative contribution to growth
In Q2, the lockdown led to a strong contraction of activity and consumption Inflation rate down
CPI dropped at a fast pace in the first months of the year printing at +2.6% y/y at June 2020 end (vs 4.0% at Dec-19 end), on disinflationary base effects, the plunge in oil price, the removal of the special excise duty on motor fuels, outpacing strong food inflation generated by Covid-19 outbreak 2020 GDP expected to drop by 6%-7%* * In a scenario of continued progressive lifting of restrictions<br>
slide8. Rate cut and quantitative easing in place INTEREST RATE ENVIRONMENT Policy rate cut
To support the economy in the context of unfolding COVID-19 epidemic, the central bank reduced the monetary policy rate twice this year to 1.75%, 75 basis points under 2019 level
Quantitative easing
NBR announced an unprecedented measure of purchasing RON denominated government bonds and stated that it shall provide necessary liquidity to financial institutions through repo operations
Before the outbreak, NBR decided to lower the level of the minimum reserve requirements on FCY denominated liabilities to 6% (down from 8%) starting February 2020, keeping the existing level for RON denominated liabilities at 8% Interbank RON interest rates followed the downward key rate
Following policy rate cut, interbank rates dropped and ROBOR 3M decreased to 2.2% at Jun-20 end (average ROBOR 3M at 2.72% in H1 2020, -48 bps YoY)<br>
slide9. EXTENSIVE POLICY OFFSET Relief measures to support the economy
Loan facility program (IMM INVEST) : envelop of EUR 3 bn of state guarantee and interest subsidies to support SME sector financing
Income supporting measures : indemnity for technical unemployment (amounting to 75% of the net salary, capped at 75% of the average salary in the economy) for employees of companies affected by the crisis
Debt moratorium for individuals & companies hit by the crisis (OUG 37)
Grace period up to 9 months (not beyond 2020 end)
Interest accrued (capitalized for consumer loans, repaid in 60 equal installments for housing loans)
Available to debtors without day past due (at request date) and affected by the crisis (based on declaration for individuals, loss of 25% of revenues for companies)
No triggered reclassification as non-performing, consistent with EU regulators’ position
Flexibility for the payment of social and tax obligations
National and EU stimulus package
The Romanian Government has presented on July 2nd 2020 “Rebuilding Romania”, a National Investment and Economic Relaunch Plan, announced for EUR 100 bn/10 years.
EU allocated EUR 80 bn to Romania (EUR 63 bn subsidies and EUR 17 bn loans) as part of its EUR 750 bn recovery plan<br>
slide10. Romanian BANKING SECTOR entered the crisis with a healthy profile Sound risk profile
NPL ratio decreased to 4.0% at May 2020 end vs 4.1% at 2019 end
NPL coverage ratio increased to 61.0% (60.6% at 2019 end) well above EU average (44.7% at 2019 end)
Share of FX loans at 32% at March 2020 end (compared to 56% at 2008 end) Solid capital and liquidity positions
Loan to deposit ratio at 71% at March 2020, same as at 2019 end (vs 122% at 2008 end)
Average liquidity coverage ratio of 245% at March 2020 end vs. 240% at December 2019 end, well above regulatory requirement (100%) and European average (150% at 2019 end), indicating a comfortable resilience capacity of the banking sector to liquidity shocks.
Total capital ratio of 20.3% at March 2020 vs. 20.0% at 2019 end (compared to 13.8% at 2008 end) ROMANIAN BANKING SYSTEM
NPL AND NPL COVERAGE RATIOS ROMANIAN BANKING SYSTEM
SHARE OF FX LOANS TO TOTAL LOANS * As of Dec 2019<br>
slide11. 2nd quarter and 1st half 2020 brd group results 3<br>
slide12. Quickly adapting to address the crisis situation, ensure business continuity and provide operational support to our clients Protect our customers and employees through implementation of adequate sanitary measures and prevention actions in all business outlets
Ensure business continuity with extended WFH, split teams deployed in different work locations
Facilitate access to banking services for our customers
Permanent communication with the clients, a dedicated web page and integrated communication (website, branches, ATMs, Facebook, etc.)
Enhanced contact centre capabilities: number of answered customer calls increased by +46% y/y in H1 2020
Promoting digital channels, with My BRD Mobile and My BRD Net free of charge for 3 months<br>
slide13. Fully committed TO support our clients WITH FINANCING SOLUTIONS Moratorium
Deferral in loan repayment granted for 44k individuals clients as of June 2020 end, postponements granted between 3 and 9 months, for RON 2.9 bn (~14 % of portfolio)
Grace period for SB clients: RON 65m (~12% of portfolio)
SMEs possibility to benefit from moratorium, though a limited number accessed this option (~2% of portfolio) HOUSING LOANS CONSUMER LOANS SB LOANS CORPORATE LOANS Active participation in IMM Invest
1052 requests approved (both Non Retail and Small Business clients), for app RON 600 m, as of 23rd of July<br>
slide14. Acceleration of our digital roadmap Fewer branches
More specialized
Better service Contact Center Apps & website Apple Pay, a safer and faster way to pay, available to BRD digital users
Possibility for clients to update their data through the website brd.ro Growing digital penetration
651k MyBRD Mobile & MyBRD Net active clients at June 2020 end, +19% y/y
+32% volume of transactions vs H1 2019
+35% nb of connections vs H1 2019
96% of corporate clients’ transactions performed via digital channels FAST ADOPTION OF DIGITAL CHANNELS ADAPTED PHYSICAL SET UP HIGHLY REACTIVE CUSTOMER INTERACTION CENTER Fast tracked Customer Interaction Centre capabilities to answer increased remote requests
+46% answered customer calls vs H1 2020
+83% written interactions vs H1 2020 CLIENTS’ DIGITAL EXPERIENCE FURTHER ENHANCED Partnership with Mastercard and Octet Europe, for easy and free of charge access for SMEs to an international trade platform
Implementation of physical token for BRD@Office with Cronto technology for corporate clients, adding new features
Enhanced digital trade finance offer with automated Letter of Credit flow -185 branches since end 2016<br>
slide15. STRONG GROWTH OF corporate financing ACTIVITY NET LOANS
(end of period amounts, RON bn) Y/Y +1.2% +0.5% -13.2% Retail loan production impacted by lockdown...
-45% decrease of retail loans production in Q2 2020 y/y
….but strong rebound in consumer loan production in May, back to pre-crisis level starting late June Sustained corporate financing activity
Loans to SME up by +7.2% y/y and large companies advance of +4.6% y/y
Active participation in IMM Invest Programme
Overall leasing portfolio increasing by +16.6% y/y INDIVIDUALS LOAN PRODUCTION +5.4% Jan. Feb. Mar. Apr. May Jun. Jul.<br>
slide16. Y/Y DYNAMIC DEPOSIT COLLECTION SAVINGS
(end of period amounts, RON bn) +4.8% -1.6% +8.1% Consolidation of already broad retail deposit base
Increasing retail deposits (+8.1% y/y) with an almost double yearly pace vs previous quarter
Individuals’ savings up +7.5% y/y (o/w current accounts were up by +32% y/y)
Corporate deposits decrease driven by a double digit compression of large corporate deposits mainly linked to the reduction of EUR non transactional accounts, on an assumed balance sheet management choice, while SMEs resources strongly increased (+18.6% y/y),
Strong liquidity profile
Net loan to deposit ratio at 65.2%, -2.3 ppts y/y
High degree of financial autonomy with the share of deposits in total liabilities reaching 92% at June 2020 end, ensuring a stable funding base
Strong liquidity buffer at 31% of total assets, +3 ppts y/y
Rebound in asset management activity
Activity impacted by the crisis in line with the market evolution, driving down AUM to RON 3.62 bn at March 2020 end
Back on an upward trend starting May (AUM RON 3.72 bn at June 2020 end)
Market share of 18.1% on open-end mutual funds’ market, up by +2.3 ppts y/y<br>
slide17. IMPACT OF CRISIS ON REVENUES IN LINE WITH EXPECTATIONS NET BANKING INCOME (RON m) Other income Net fees and commissions Net interest income Y/Y -6.0% -22.3% -14.0% -0.3% Contraction of NFC triggered by pandemic and regulatory changes
Decline in net fees and commissions income, -14.0% y/y in H1 2020 and -23.2% y/y in Q2 2020, following:
SEPA regulation enforcement (price alignment of EUR denominated payments to domestic ones, starting from 15th of December 2019)
lower volumes of transactions
cease of the Western Union activity in August 2019
free usage of remote banking applications (from 15th of March to 15th of June) Resilient NII over the 1st semester
Quasi stable NII in H1 2020 (-0.3% y/y) benefitting from positive volume effect induced by growing deposits Other income evolution explained by exceptional 2019 base effect of reevaluation gains NET BANKING INCOME (RON m) Other income Net fees and commissions Net interest income Y/Y -9.6% +5.1% -23.2% -6.9% NII lower (-6.9% y/y) in Q2 2020
interest rate effect turning negative
ROBOR 3M average of 2.39% in Q2 2020, -90 bps y/y
ROBOR 3M average of 2.72% in H1 2020, -48 bps y/y important drop of individual loan production during the containment period<br>
slide18. OPEX DYNAMICs reflecting strict control of sundry costs and lower regulatory charges OPERATING EXPENSES (RON m) Other expenses Staff expenses -0.5% +2.2% +4.8% Y/Y Contributions to FGDB & FR OPEX evolution for H1 2020, w/o regulatory costs, impacted by:
measures taken to address the sanitary crisis (acquisition of protection materials for employees and clients)
2019 salary increase, in a context of accelerating economy - wide wage growth -40.0% OPERATING EXPENSES (RON m) Already visible results in Q2
stable staff costs
other costs reduced by -2.4% (excluding sanitary costs and negative base effect related to previous year adjustments recognized in June 2019) Other expenses Staff expenses +3.5% +0% +8.0% Y/Y Embarking on a significant saving plan
immediate tactical actions (communication & marketing expenses, ban on travels, office supplies)
structural actions gradually delivering over time (freeze of hiring, resizing of network, optimization actions which mostly envisage systematization of e-training, reduction in communication budget, external services and travels, and continued automation of processes)
while preserving strategic investments in digital transformation C/I ratio at 52.9% in H1 2020 (vs. 50.0% in H1 2019) +3.4%<br>
slide19. strong ASSET QUALITY All figures at individual level NPL RATIO – EBA methodology Loan portfolio market mix
70% on individuals market segment
30% on legal entities market segment Consolidation of RON lending
Share of RON denominated loans at 67.8% (vs 67.1% as of June 2019 end)
Trend in line with market evolution GROSS LOANS – June 30, 2020
breakdown by segment and currency (RON bn) NPL ratio close to banking sector level
Rather stable evolution versus previous quarter, the effects of Covid-19 pandemic are not yet visible (3.96% for June vs 4.01% for March computed with the same methodology).
Outlook
Upward trend expected, especially after the end of moratorium on loan repayments. * NPL for BRD computed in line with EBA new methodology (excl. RMO & demand deposits)
* NPL Ratio for Banking System – as of May 2020<br>
slide20. cost of risk INCORPORATING DETERIORATED MACROECONOMIC CONTEXT NPL COVERAGE RATIO - EBA methodology All figures at individual level COST OF RISK EVOLUTION Solid NPL coverage ratio following prudent provisioning policy
NPL coverage ratio well above banking sector average * NPL coverage ratio for BRD computed in line with EBA new methodology (excl. RMO & demand deposits)
* NPL coverage ratio for Banking System – as of March 2020 Note: Cost of risk in bps for Q2-2019 and Q2-2020 is annualized Net cost of risk at 205 bps in Q2-20 (vs 59 bps in Q1-20), driven mainly by:
Updated macroeconomic scenarios embedding Covid context, leading to higher expected losses
Lower recovery performance given the new context<br>
slide21. Very Solid capital position SOLVENCY RATIO Jun-19 Jun-20 Retained profit OCI RWA Other 20.01% Note: Own funds for 2019 include the FY net profit, according to the GSM decision +528bp +145bp -27bp +49bp 26.69% Strong high quality capital base
CAR of 27% at June 2020 end
Regulatory own funds composed solely of Tier 1 capital
Increase in own funds on a yearly basis mainly driven by the retention of the entire 2019 net profit, considering (i) the high uncertainty about the long term economic consequences of the Covid 19 outbreak, (ii) BRD strong commitment to support the Romanian economy in difficult times, and (iii) regulator recommendation
Evolution of RWA influenced mainly by the implementation of the provisions regarding the temporary relief on the RW of EUR sovereign exposures, introduced through Regulation 873, approved late June in response to COVID-19 pandemic (+140 bps impact in solvency ratio at June 2020 vs June 2019)<br>
slide22. conclusions 5<br>
slide23. conclusions Entered a strong and unprecedented crisis
Quickly and successfully adapted our organization to protect employees and customers, and to ensure business continuity
Stand by our clients in these difficult times
loan moratorium
active participation in IMM INVEST
sustained corporate financing activity
eased the access to banking services
As expected, revenues were hit and cost of risk was directly impacted by the deteriorated economic environment
Cost adjustment measures were immediately taken
While preserving strategic investments in digital transformation
Financial performance directly impacted by the crisis, but resilient, and the fundamentals remain very solid
strong capital adequacy ratio
very comfortable liquidity position
elevated asset quality<br>
slide24. Q&A SESSION 6<br>
slide25. APPENDIX brd group – key figures brd standalone - key figures stock prIce performance FINANCIAL CALENDAR FOR 2020 GLOSSARY – CLIENT SEGMENTATION<br>
slide26. BRD GROUP | KEY FIGURES (1) Variations at constant exchange rate; (2) Bank only, including impact of prudential filters in Sep-17 and Dec-17; (*) according to Basel 3; CAR at Bank level;<br>
slide27. BRD | KEY FIGURES FOR BANK ONLY (1) Variations at constant exchange rate; (2) Bank only, including impact of prudential filters in Sep-17 and Dec-17;<br>
slide28. BRD | STOCK PRICE PERFORMANCE BRD is part of the main market indices on the Bucharest Stock Exchange
BRD is in Top 5 largest domestic companies listed on the local stock exchange
BRD’s share price reached RON 11.56 as of June 2020 end, -8.5% y/y and -27% ytd.<br>
slide29. Financial calendar for 2020 6th February: Preliminary 2019 financial results and annual press conference
23rd April: General Shareholders Meeting for approving the 2019 annual financial results
7th May: Presentation of the 1st quarter 2020 financial results
3rd August: Presentation of the 2nd quarter and 1st half 2020 financial results
5th November: Presentation of the 3rd quarter and 9 months 2020 financial results<br>
slide30. GLOSSARY – CLIENT SEGMENTATION The Retail category is comprised of the following customer segments:
Individuals – BRD provides individual customers with a range of banking products such as: savings and deposits taking, consumer and housing loans, overdrafts, credit card facilities, funds transfer and payment facilities.
Small business – business entities with annual turnover lower than EUR 1m and having an aggregated exposure at group level less than EUR 0.3m. Standardized range of banking products is offered to small companies and professionals: savings and deposits taking, loans, transfers and payment services.
The Corporate category is comprised of the following customer segments:
Small and medium enterprises - companies with annual turnover between EUR 1m and EUR 50m and the aggregated exposure at group level higher than EUR 0.3m. The Bank provides SMEs with a range of banking products such as: savings and deposits taking, loans and other credit facilities, transfers and payment services.
Large corporate - within corporate banking BRD provides customers with a range of banking products and services, including lending and deposit taking, provides cash-management, investment advices, securities business, project and structured finance transaction, syndicated loans and asset backed transactions. The large corporate customers include companies with annual turnover higher than EUR 50m, municipalities, public sector and other financial institutions.<br>
slide31. BRD GROUPE SOCIETE GENERALE - INVESTOR RELATIONS +4 021 380 47 62 | investor@brd.ro; www.brd.ro<br>