Accuracy in Credit Reporting Presentation for the CFPB Academic Research Council November 20th, 2020 Jonah Kaplan (Markets), Nicholas Li (Research) and Judith Ricks (Research) Credit access plays a vital role in the lives of consumers. Many
"Accuracy in Credit Reporting Presentation for the" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
Accuracy in Credit Reporting Presentation for the CFPB Academic Research Council
November 20th, 2020
Jonah Kaplan (Markets), Nicholas Li (Research) and Judith Ricks (Research)<br>
02
Credit access plays a vital role in the lives of consumers. Many consumers have varying types of credit (e.g., mortgages, auto loans) and often have multiple of the same account types (e.g., credit cards, student loans)
The status of any account can be reported in an individual’s credit report.
This credit reporting is directly tied to credit scoring algorithms and a consumer’s access to credit. 2<br>
03
Potential effects of inaccurate credit reporting Inaccurate credit reporting can affect a consumer’s credit score.
Effect could be positive or negative
Example: Reporting error due to a current account being misreported as delinquent.
Similar consumers can have arbitrarily different credit scores.
Example: Institutional differences in the approach to furnishing information.
Consumers have to make a choice between
Spending resources (e.g., time and money) to correct inaccurate information OR
Bearing the cost of the inaccuracies 3<br>
04
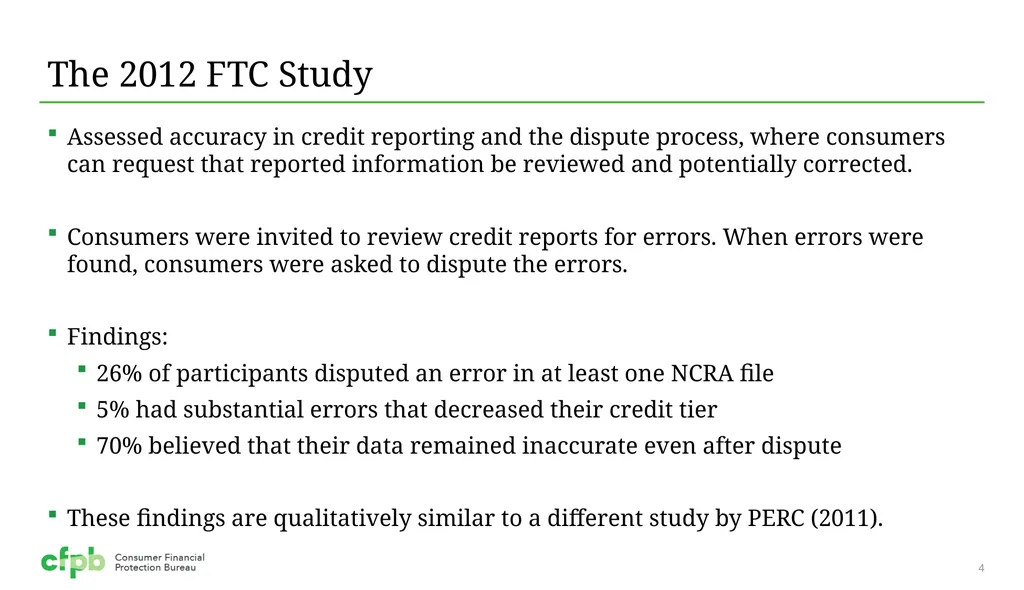
The 2012 FTC Study 4 Assessed accuracy in credit reporting and the dispute process, where consumers can request that reported information be reviewed and potentially corrected.
Consumers were invited to review credit reports for errors. When errors were found, consumers were asked to dispute the errors.
Findings:
26% of participants disputed an error in at least one NCRA file
5% had substantial errors that decreased their credit tier
70% believed that their data remained inaccurate even after dispute
These findings are qualitatively similar to a different study by PERC (2011).<br>
05
A lot has changed since the 2012 FTC study There has been an increased regulatory focus on accuracy.
CFPB’s Supervisory program
Multi-state/Nationwide Credit Reporting Agency (NCRA) settlement
There has been substantial growth in consumer awareness of credit reporting and scoring issues.
No fee score access programs available through financial institutions and lead generation firms (e.g., Credit Karma)
Data breaches (e.g., Equifax breach in September 2017) 5<br>
06
A lot has changed since the 2012 FTC study (continued) There also has been an increased interest among policy experts to understand credit reporting and accuracy.
Natural Disasters and Credit Reporting (CFPB, 2018)
Payment Amount Furnishing and Credit Reporting (CFPB, 2020) 6<br>
07
Considerations for new analysis Use of the Bureau’s Consumer Credit Panel (CCP)
The CCP is a 1-in-48 sample of consumer credit reports with tradeline-level information.
The CCP can be used to analyze aggregate trends in credit reporting (furnishing) and disputes over time.
A refresh of the 2012 FTC study
Given the growing awareness surrounding credit reporting, a similar analysis may offer very different results than the earlier study.
A new study would also allow for modifications to the FTC study, including the experimental design and outcomes of interest. 7<br>
08
Considerations for new analysis (continued) Other possibilities
A consumer survey on experiences related to credit reporting and accuracy, potentially based off of a sample from the Bureau’s CCP.
Testing of the dispute process undergone by NCRAs through, e.g., dispute simulations.
Randomly sample furnished data to assess accuracy and correctness. 8<br>
09
Discussion What should be the Bureau’s top-of-mind research priorities with respect to credit reporting accuracy?
What are the policy-relevant areas?
What do you see as the key outcomes of interest for a new study?
If the Bureau were to conduct an original analysis on credit reporting accuracy, should the focus be on a one-time study or recurring analysis?
An example of a one-time study could include a lab study similar to the 2012 FTC analysis.
An example of recurring analysis could include regular surveys to consumers. 9<br>
10
Discussion (continued) If the Bureau were to conduct an original analysis on credit reporting accuracy, should new analysis focus on consumer experiences, NCRA processes, or institutional furnishing?
If the Bureau were to conduct a refresh of the 2012 FTC study
What do you see as the primary challenges?
How would you improve on the earlier study? 10<br>