
Actuarial Valuation of Public Sector Enterprises

Description: Actuarial Valuation of Public Sector Enterprises Speakers: Sh. A D Gupta Consulting Actuary Chairperson, Advisory Group on PEBSS Khushwant Pahwa Founder and Consulting Actuary, KP Actuaries and Consultants (KPAC) Secretary, Advisory Group
Related Topics
Download Presentation
"Actuarial Valuation of Public Sector Enterprises" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Actuarial Valuation of Public Sector Enterprises Speakers:
Sh. A D Gupta
Consulting Actuary
Chairperson, Advisory Group on PEBSS
Khushwant Pahwa
Founder and Consulting Actuary, KP Actuaries and Consultants (KPAC)
Secretary, Advisory Group on PEBSS Data Support:
Sh. D.K. Pandit
Consulting Actuary, KA Pandit (Actuaries and Consultants)
Member, Advisory Group on PEBSS<br>
slide2. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
slide3. Setting the context… Not a new issue.
Not a small issue.
Not an issue likely to go away soon.
Carries reputation risk?
Not immediate solution
Perhaps an opportunity?<br>
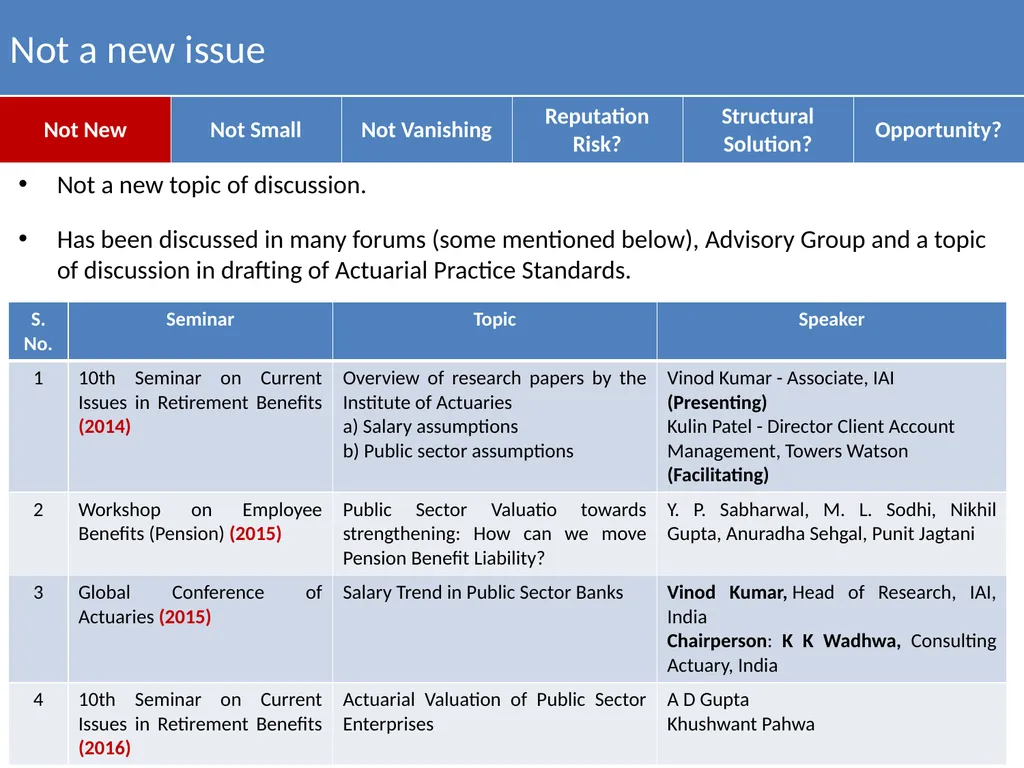
slide4. Not a new issue Not a new topic of discussion.
Has been discussed in many forums (some mentioned below), Advisory Group and a topic of discussion in drafting of Actuarial Practice Standards.<br>
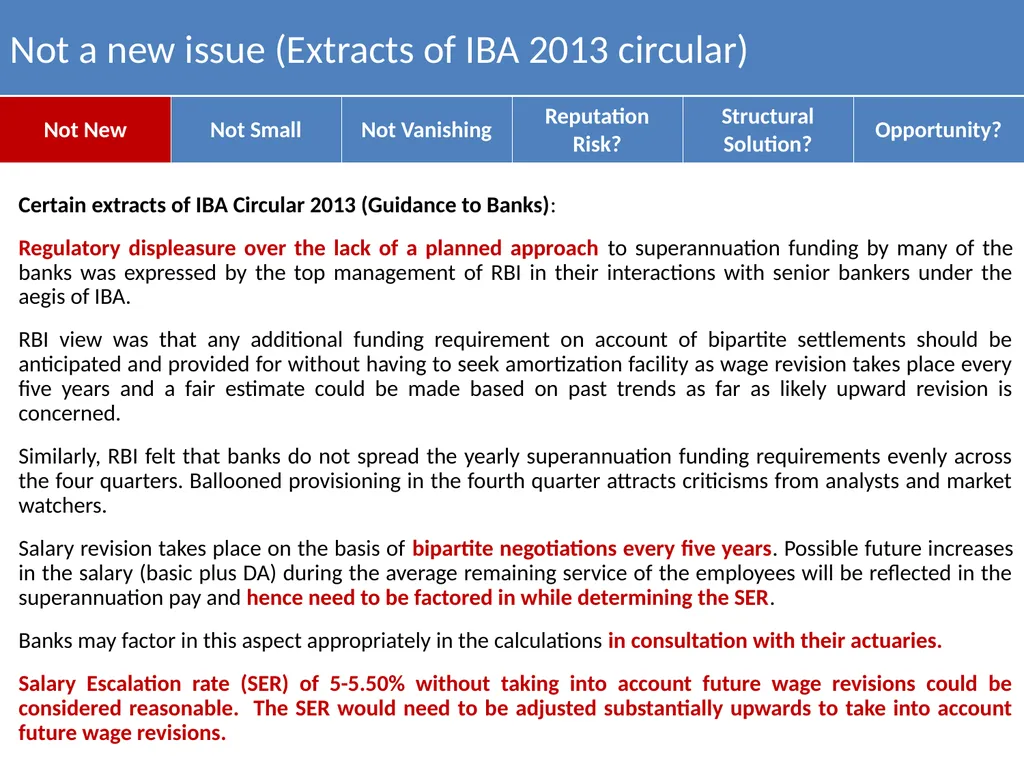
slide5. Not a new issue (Extracts of IBA 2013 circular) Certain extracts of IBA Circular 2013 (Guidance to Banks):
Regulatory displeasure over the lack of a planned approach to superannuation funding by many of the banks was expressed by the top management of RBI in their interactions with senior bankers under the aegis of IBA.
RBI view was that any additional funding requirement on account of bipartite settlements should be anticipated and provided for without having to seek amortization facility as wage revision takes place every five years and a fair estimate could be made based on past trends as far as likely upward revision is concerned.
Similarly, RBI felt that banks do not spread the yearly superannuation funding requirements evenly across the four quarters. Ballooned provisioning in the fourth quarter attracts criticisms from analysts and market watchers.
Salary revision takes place on the basis of bipartite negotiations every five years. Possible future increases in the salary (basic plus DA) during the average remaining service of the employees will be reflected in the superannuation pay and hence need to be factored in while determining the SER.
Banks may factor in this aspect appropriately in the calculations in consultation with their actuaries.
Salary Escalation rate (SER) of 5-5.50% without taking into account future wage revisions could be considered reasonable. The SER would need to be adjusted substantially upwards to take into account future wage revisions.<br>
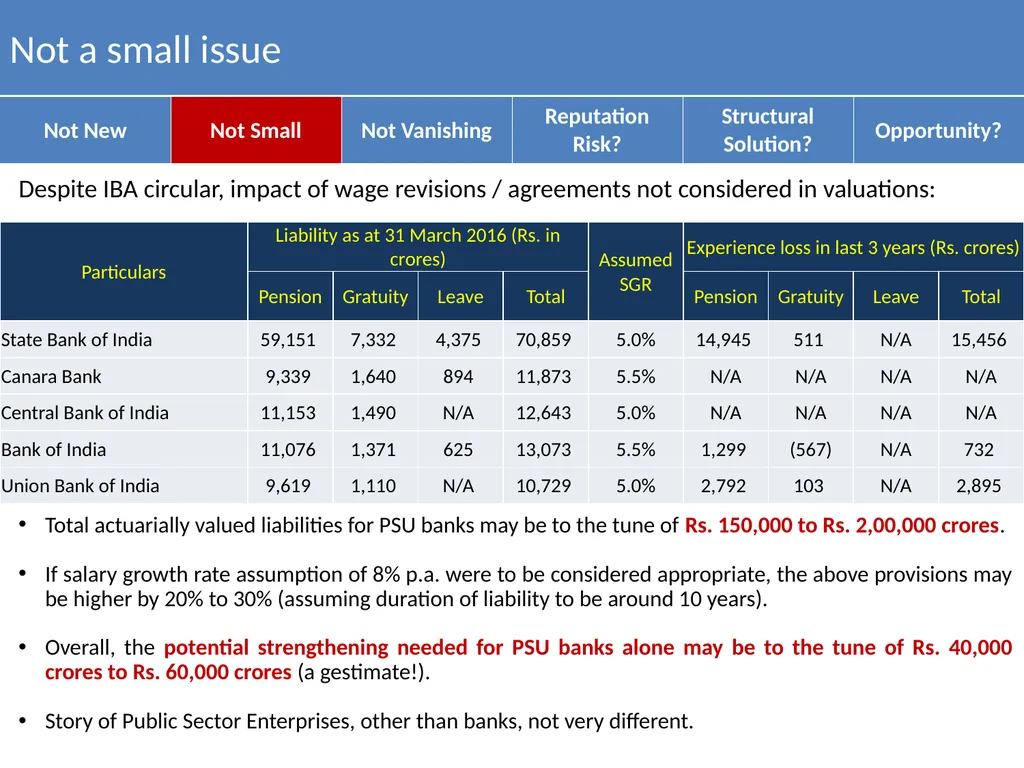
slide6. Not a small issue Despite IBA circular, impact of wage revisions / agreements not considered in valuations: Total actuarially valued liabilities for PSU banks may be to the tune of Rs. 150,000 to Rs. 2,00,000 crores.
If salary growth rate assumption of 8% p.a. were to be considered appropriate, the above provisions may be higher by 20% to 30% (assuming duration of liability to be around 10 years).
Overall, the potential strengthening needed for PSU banks alone may be to the tune of Rs. 40,000 crores to Rs. 60,000 crores (a gestimate!).
Story of Public Sector Enterprises, other than banks, not very different.<br>
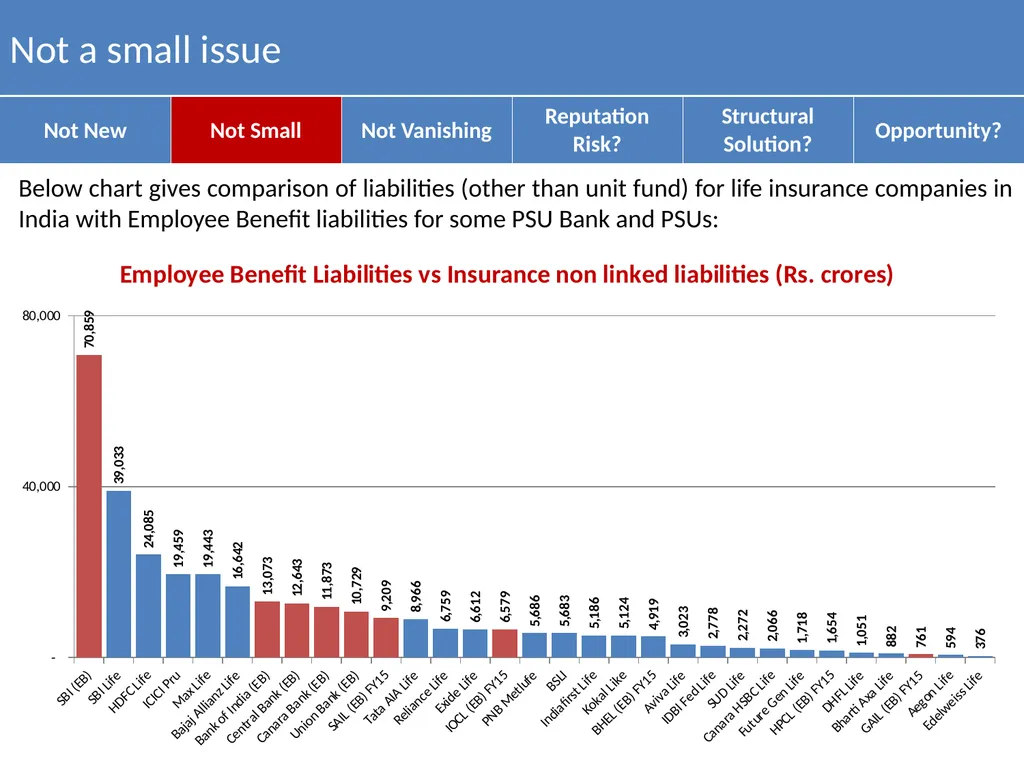
slide7. Not a small issue Below chart gives comparison of liabilities (other than unit fund) for life insurance companies in India with Employee Benefit liabilities for some PSU Bank and PSUs:<br>
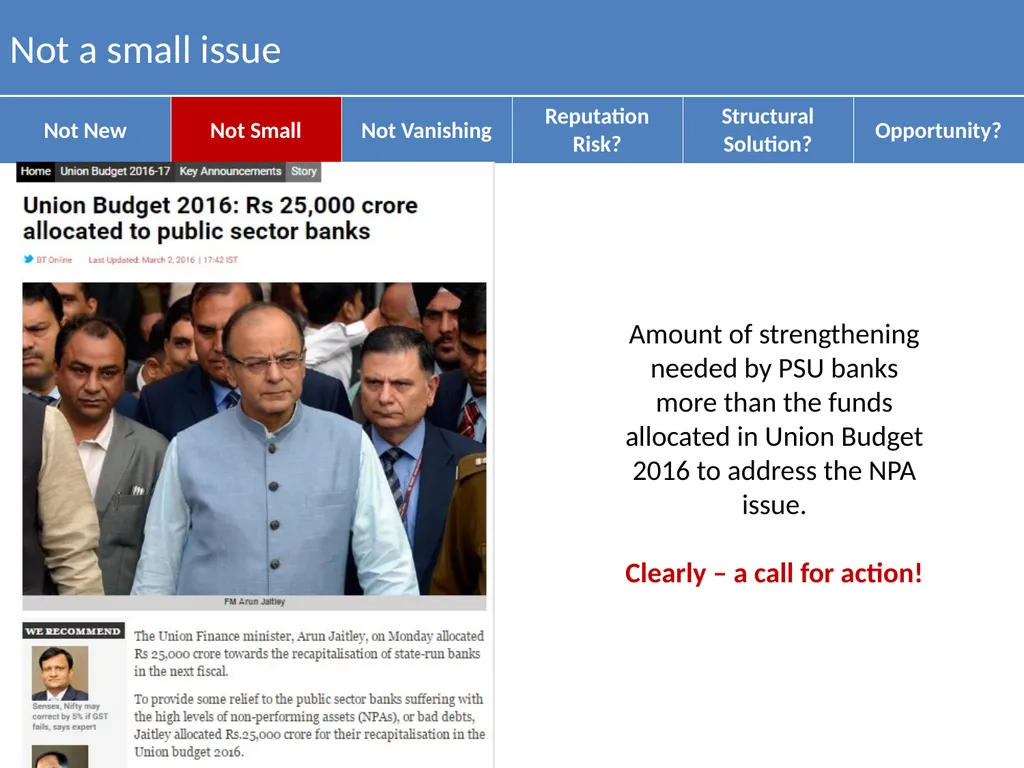
slide8. Not a small issue Amount of strengthening needed by PSU banks more than the funds allocated in Union Budget 2016 to address the NPA issue.
Clearly – a call for action!<br>
slide9. Not Vanishing….in fact may become more challenging…<br>
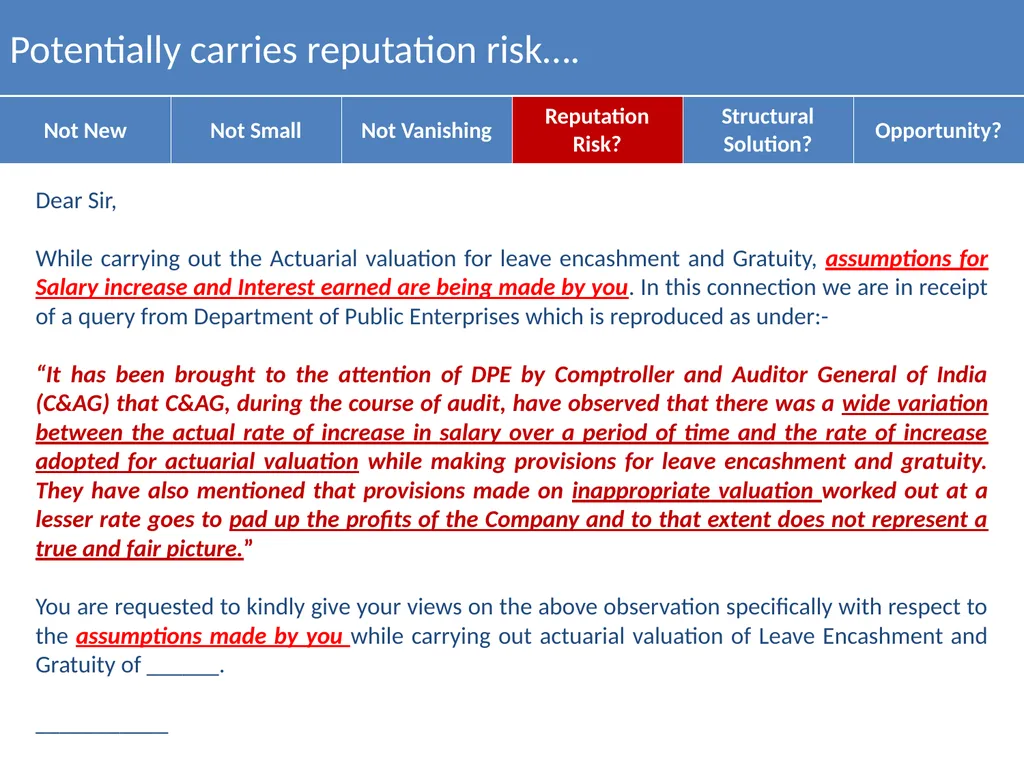
slide10. Potentially carries reputation risk…. Dear Sir,
While carrying out the Actuarial valuation for leave encashment and Gratuity, assumptions for Salary increase and Interest earned are being made by you. In this connection we are in receipt of a query from Department of Public Enterprises which is reproduced as under:-
“It has been brought to the attention of DPE by Comptroller and Auditor General of India (C&AG) that C&AG, during the course of audit, have observed that there was a wide variation between the actual rate of increase in salary over a period of time and the rate of increase adopted for actuarial valuation while making provisions for leave encashment and gratuity. They have also mentioned that provisions made on inappropriate valuation worked out at a lesser rate goes to pad up the profits of the Company and to that extent does not represent a true and fair picture.”
You are requested to kindly give your views on the above observation specifically with respect to the assumptions made by you while carrying out actuarial valuation of Leave Encashment and Gratuity of ______.
___________<br>
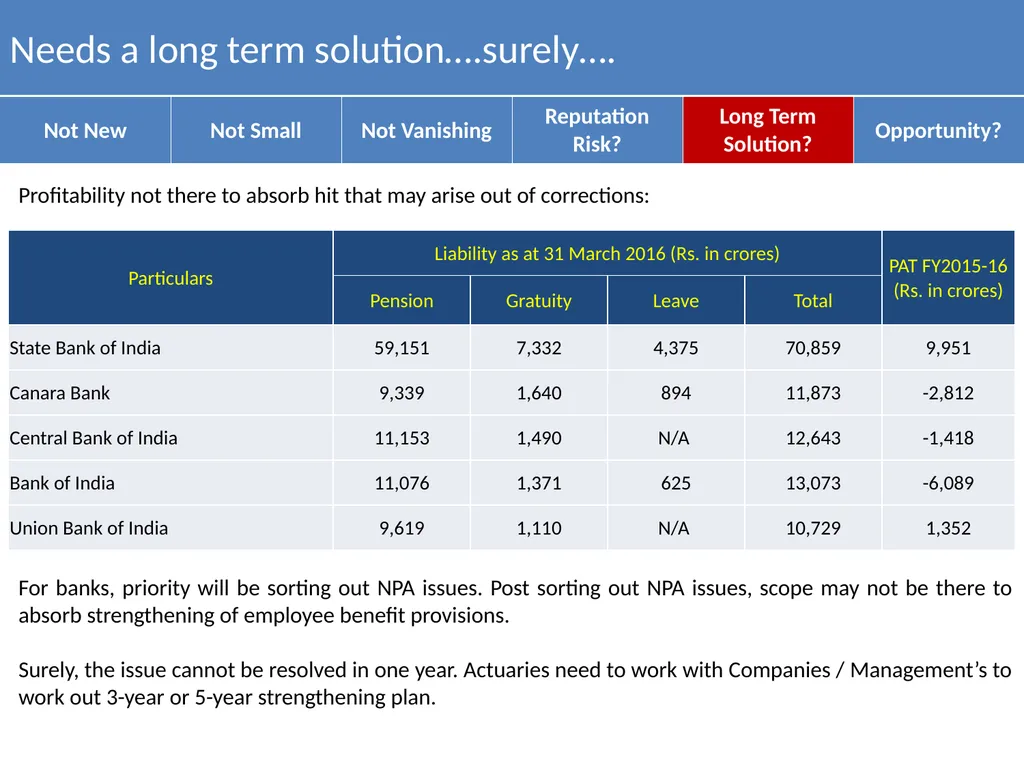
slide11. Needs a long term solution….surely…. Profitability not there to absorb hit that may arise out of corrections: For banks, priority will be sorting out NPA issues. Post sorting out NPA issues, scope may not be there to absorb strengthening of employee benefit provisions.
Surely, the issue cannot be resolved in one year. Actuaries need to work with Companies / Management’s to work out 3-year or 5-year strengthening plan.<br>
slide12. An opportunity to work with the government? Opportunity to work with the government and help these enterprises strengthen.
Opportunity to highlight and showcase the importance of our profession.
Ind ASs may present an opportunity as the entire strengthening may not be routed through Income Statement. On pensions and gratuity, same will be routed through Other Comprehensive Income (OCI).<br>
slide13. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
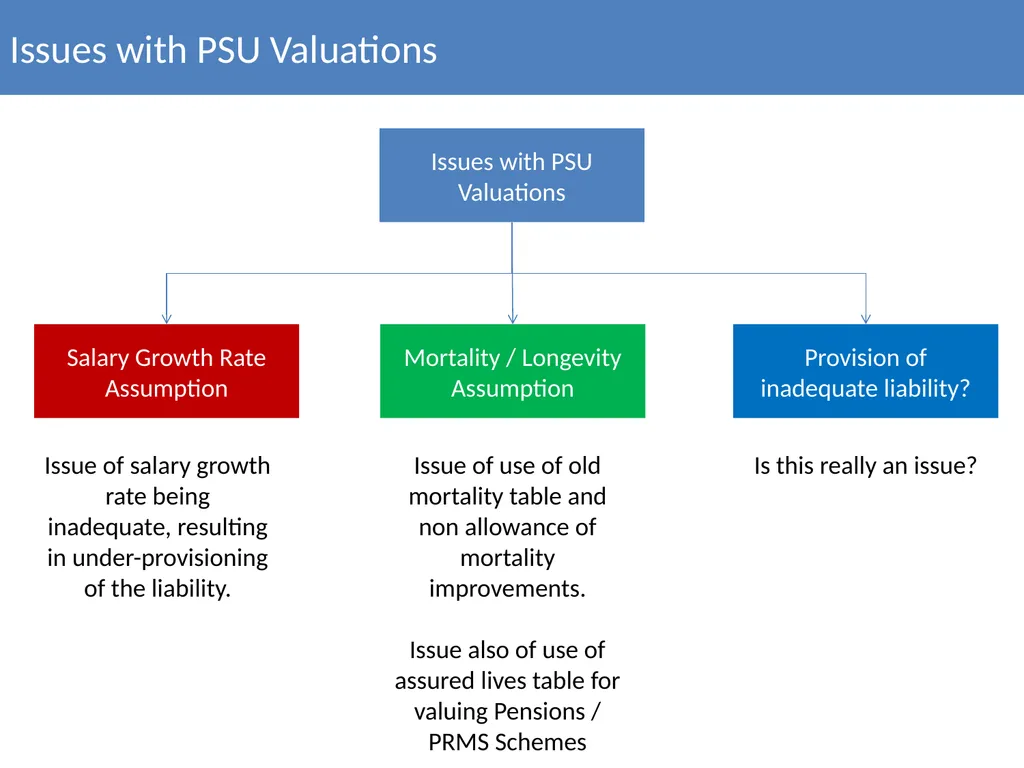
slide14. Issues with PSU Valuations Issues with PSU Valuations Salary Growth Rate Assumption Mortality / Longevity Assumption Provision of inadequate liability? Issue of salary growth rate being inadequate, resulting in under-provisioning of the liability. Issue of use of old mortality table and non allowance of mortality improvements.
Issue also of use of assured lives table for valuing Pensions / PRMS Schemes Is this really an issue?<br>
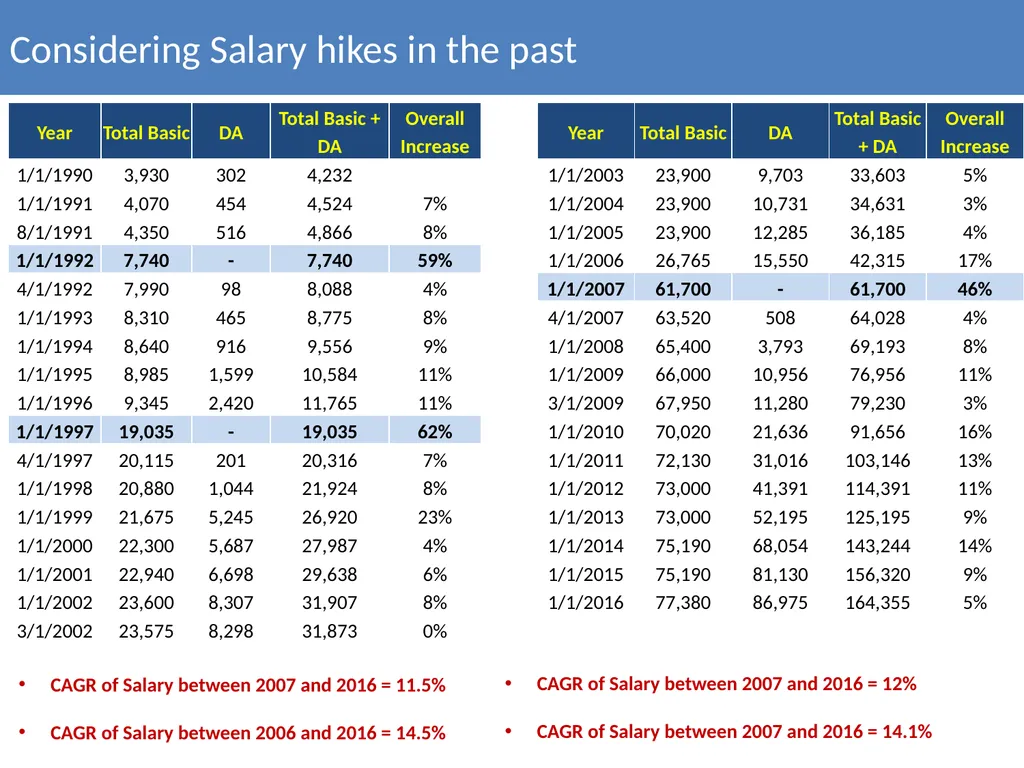
slide15. Considering Salary hikes in the past CAGR of Salary between 2007 and 2016 = 11.5%
CAGR of Salary between 2006 and 2016 = 14.5% CAGR of Salary between 2007 and 2016 = 12%
CAGR of Salary between 2007 and 2016 = 14.1%<br>
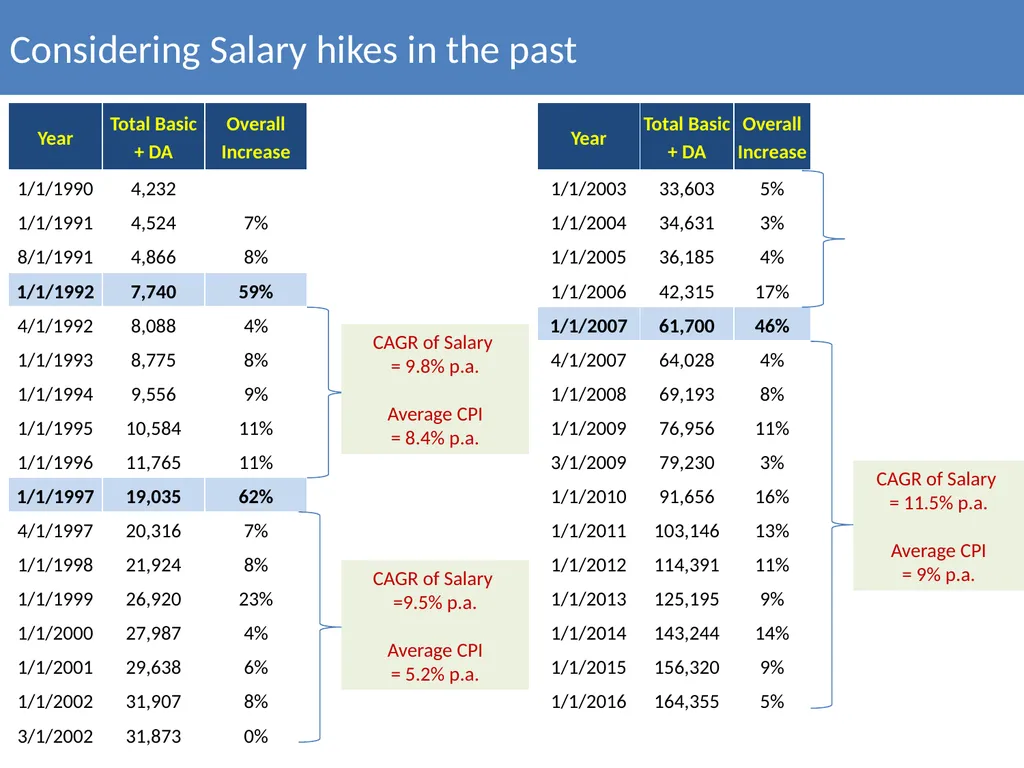
slide16. Considering Salary hikes in the past CAGR of Salary
= 11.5% p.a.
Average CPI
= 9% p.a. CAGR of Salary
=9.5% p.a.
Average CPI
= 5.2% p.a. CAGR of Salary
= 9.8% p.a.
Average CPI
= 8.4% p.a.<br>
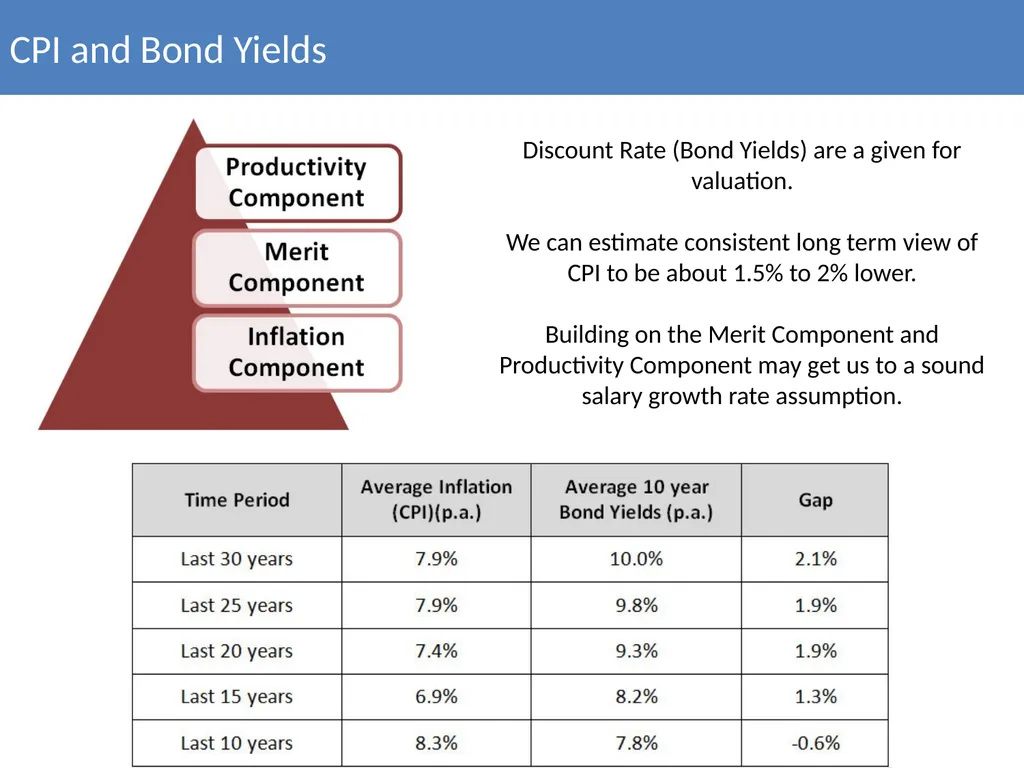
slide17. CPI and Bond Yields Discount Rate (Bond Yields) are a given for valuation.
We can estimate consistent long term view of CPI to be about 1.5% to 2% lower.
Building on the Merit Component and Productivity Component may get us to a sound salary growth rate assumption.<br>
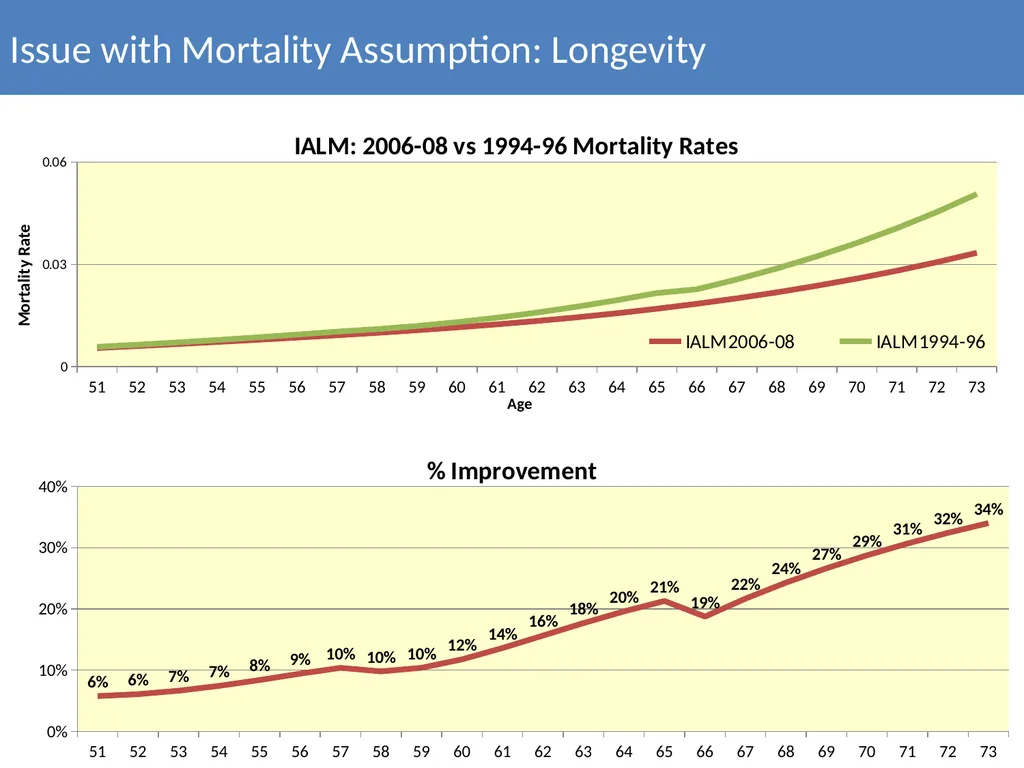
slide18. Issue with Mortality Assumption: Longevity<br>
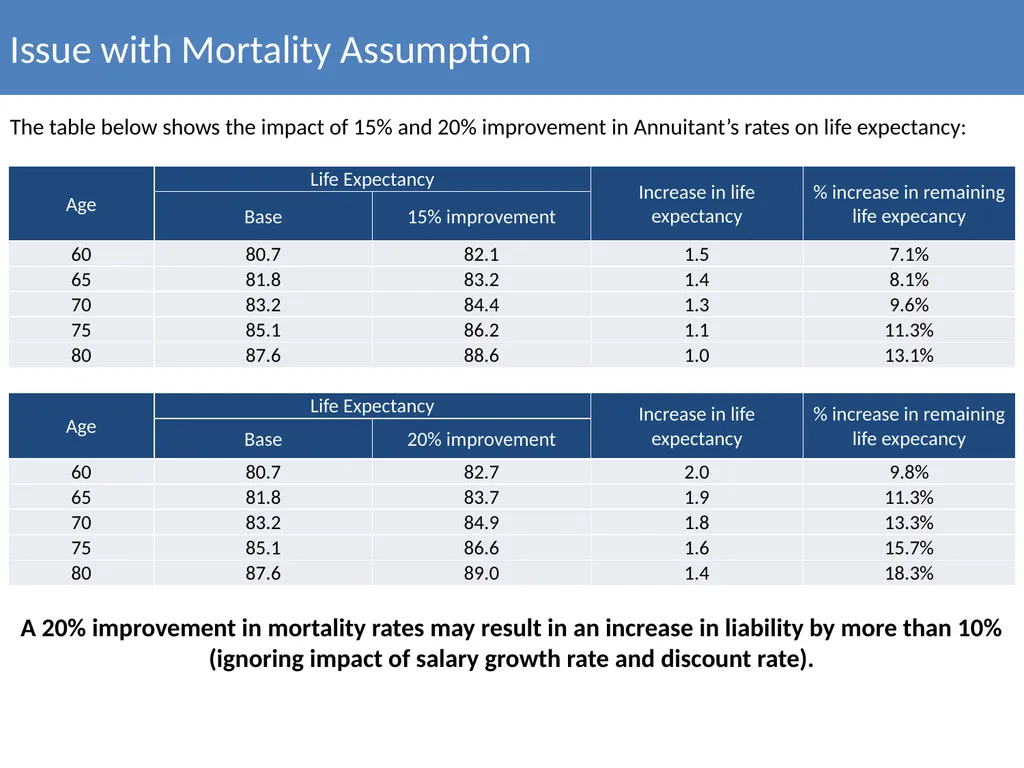
slide19. Issue with Mortality Assumption The table below shows the impact of 15% and 20% improvement in Annuitant’s rates on life expectancy: A 20% improvement in mortality rates may result in an increase in liability by more than 10% (ignoring impact of salary growth rate and discount rate).<br>
slide20. Provision of inadequate liability<br>
slide21. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
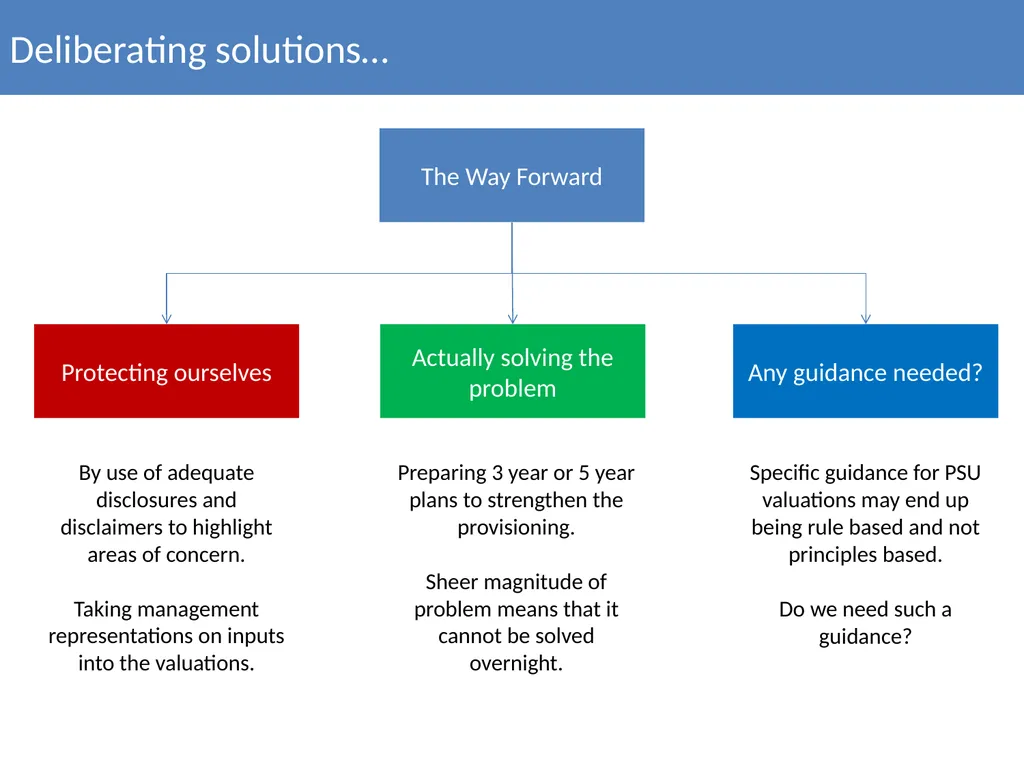
slide22. Deliberating solutions… The Way Forward Protecting ourselves Actually solving the problem Any guidance needed? By use of adequate disclosures and disclaimers to highlight areas of concern.
Taking management representations on inputs into the valuations. Preparing 3 year or 5 year plans to strengthen the provisioning.
Sheer magnitude of problem means that it cannot be solved overnight. Specific guidance for PSU valuations may end up being rule based and not principles based.
Do we need such a guidance?<br>
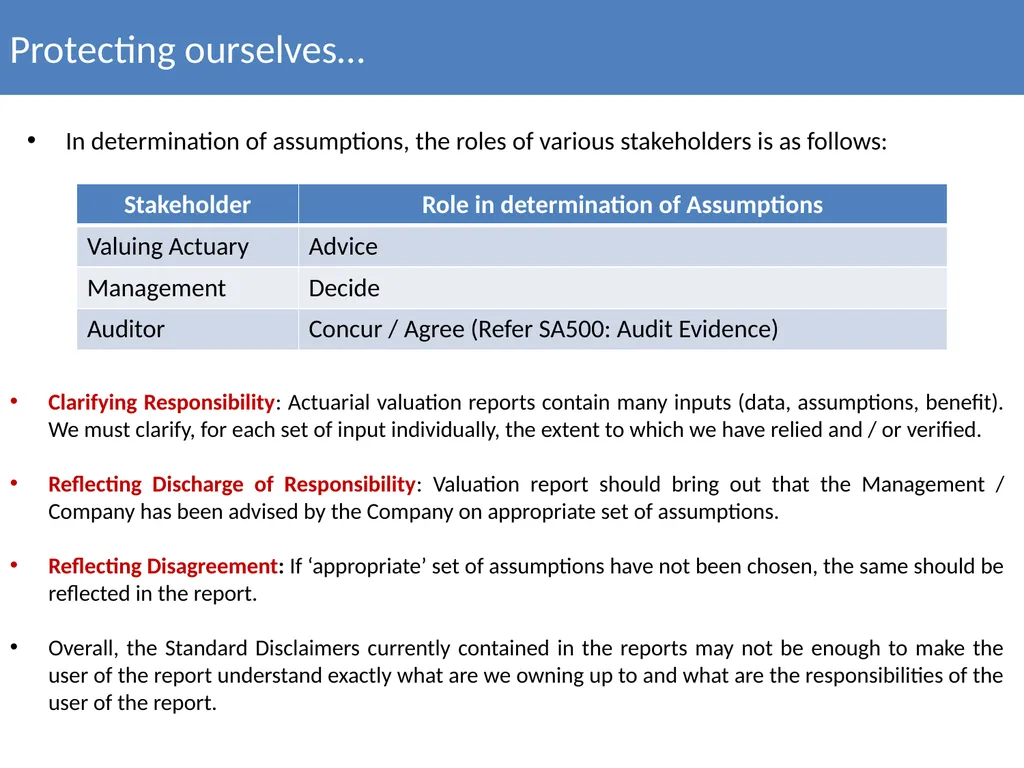
slide23. Protecting ourselves… In determination of assumptions, the roles of various stakeholders is as follows: Clarifying Responsibility: Actuarial valuation reports contain many inputs (data, assumptions, benefit). We must clarify, for each set of input individually, the extent to which we have relied and / or verified.
Reflecting Discharge of Responsibility: Valuation report should bring out that the Management / Company has been advised by the Company on appropriate set of assumptions.
Reflecting Disagreement: If ‘appropriate’ set of assumptions have not been chosen, the same should be reflected in the report.
Overall, the Standard Disclaimers currently contained in the reports may not be enough to make the user of the report understand exactly what are we owning up to and what are the responsibilities of the user of the report.<br>
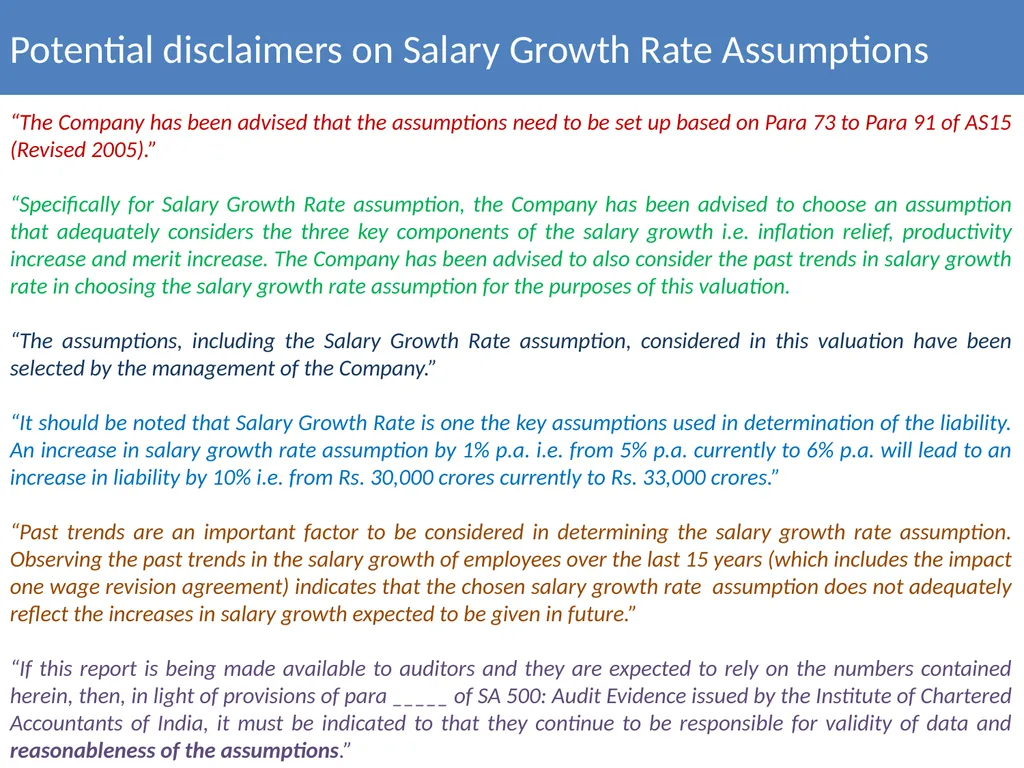
slide24. Potential disclaimers on Salary Growth Rate Assumptions “The Company has been advised that the assumptions need to be set up based on Para 73 to Para 91 of AS15 (Revised 2005).”
“Specifically for Salary Growth Rate assumption, the Company has been advised to choose an assumption that adequately considers the three key components of the salary growth i.e. inflation relief, productivity increase and merit increase. The Company has been advised to also consider the past trends in salary growth rate in choosing the salary growth rate assumption for the purposes of this valuation.
“The assumptions, including the Salary Growth Rate assumption, considered in this valuation have been selected by the management of the Company.”
“It should be noted that Salary Growth Rate is one the key assumptions used in determination of the liability. An increase in salary growth rate assumption by 1% p.a. i.e. from 5% p.a. currently to 6% p.a. will lead to an increase in liability by 10% i.e. from Rs. 30,000 crores currently to Rs. 33,000 crores.”
“Past trends are an important factor to be considered in determining the salary growth rate assumption. Observing the past trends in the salary growth of employees over the last 15 years (which includes the impact one wage revision agreement) indicates that the chosen salary growth rate assumption does not adequately reflect the increases in salary growth expected to be given in future.”
“If this report is being made available to auditors and they are expected to rely on the numbers contained herein, then, in light of provisions of para _____ of SA 500: Audit Evidence issued by the Institute of Chartered Accountants of India, it must be indicated to that they continue to be responsible for validity of data and reasonableness of the assumptions.”<br>
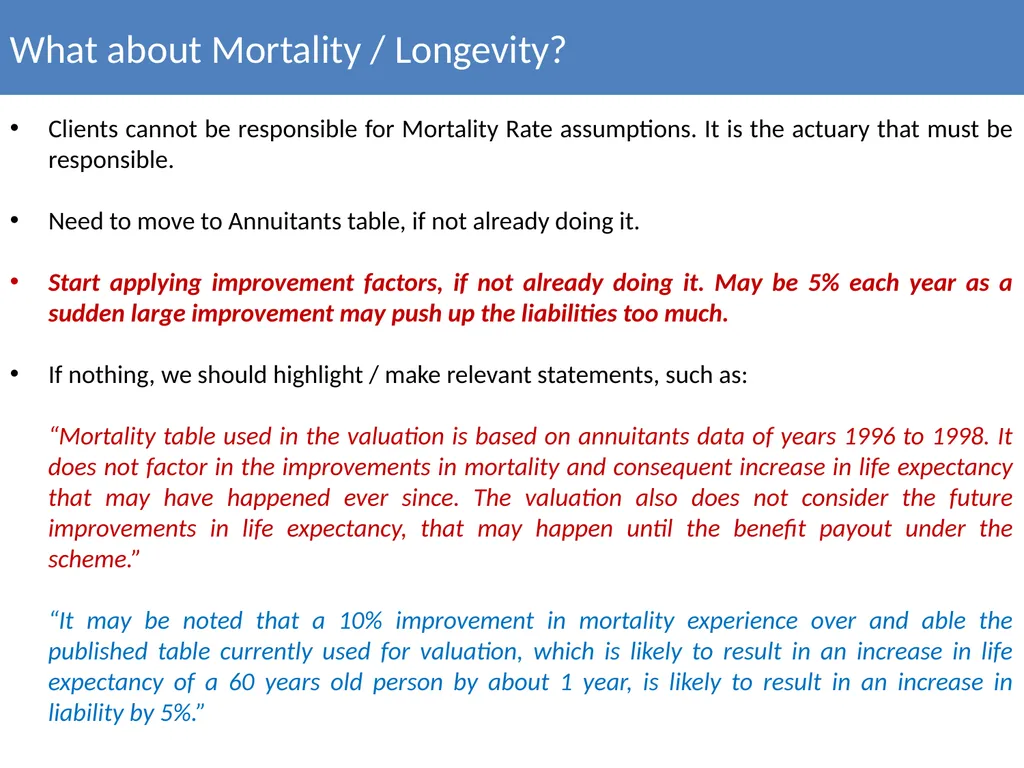
slide25. What about Mortality / Longevity? Clients cannot be responsible for Mortality Rate assumptions. It is the actuary that must be responsible.
Need to move to Annuitants table, if not already doing it.
Start applying improvement factors, if not already doing it. May be 5% each year as a sudden large improvement may push up the liabilities too much.
If nothing, we should highlight / make relevant statements, such as:
“Mortality table used in the valuation is based on annuitants data of years 1996 to 1998. It does not factor in the improvements in mortality and consequent increase in life expectancy that may have happened ever since. The valuation also does not consider the future improvements in life expectancy, that may happen until the benefit payout under the scheme.”
“It may be noted that a 10% improvement in mortality experience over and able the published table currently used for valuation, which is likely to result in an increase in life expectancy of a 60 years old person by about 1 year, is likely to result in an increase in liability by 5%.”<br>
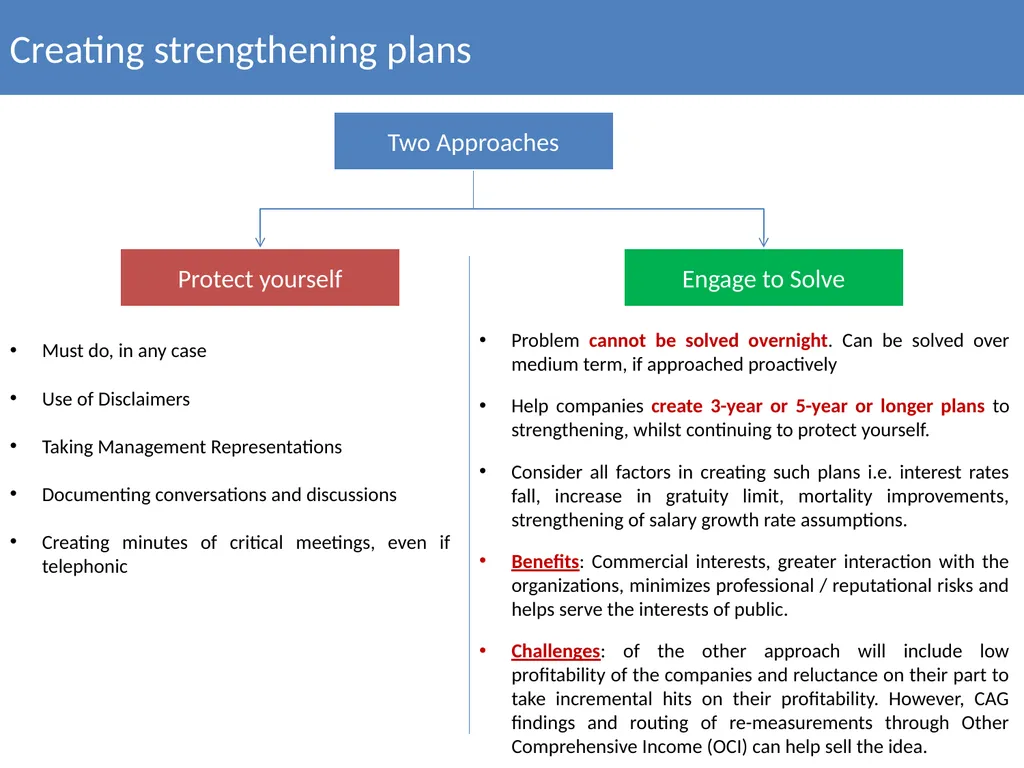
slide26. Creating strengthening plans Two Approaches Protect yourself Engage to Solve Must do, in any case
Use of Disclaimers
Taking Management Representations
Documenting conversations and discussions
Creating minutes of critical meetings, even if telephonic Problem cannot be solved overnight. Can be solved over medium term, if approached proactively
Help companies create 3-year or 5-year or longer plans to strengthening, whilst continuing to protect yourself.
Consider all factors in creating such plans i.e. interest rates fall, increase in gratuity limit, mortality improvements, strengthening of salary growth rate assumptions.
Benefits: Commercial interests, greater interaction with the organizations, minimizes professional / reputational risks and helps serve the interests of public.
Challenges: of the other approach will include low profitability of the companies and reluctance on their part to take incremental hits on their profitability. However, CAG findings and routing of re-measurements through Other Comprehensive Income (OCI) can help sell the idea.<br>
slide27. Need for professional guidance? Need a Standard for PSU valuations? Need for profession to engage with DPE? Need for mandating Peer Review of liabilities of PSUs? Need support from AG on drafting disclaimers / qualifications to consider? Any other support needed from AG? Any other thoughts?<br>
slide28. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding Thoughts<br>
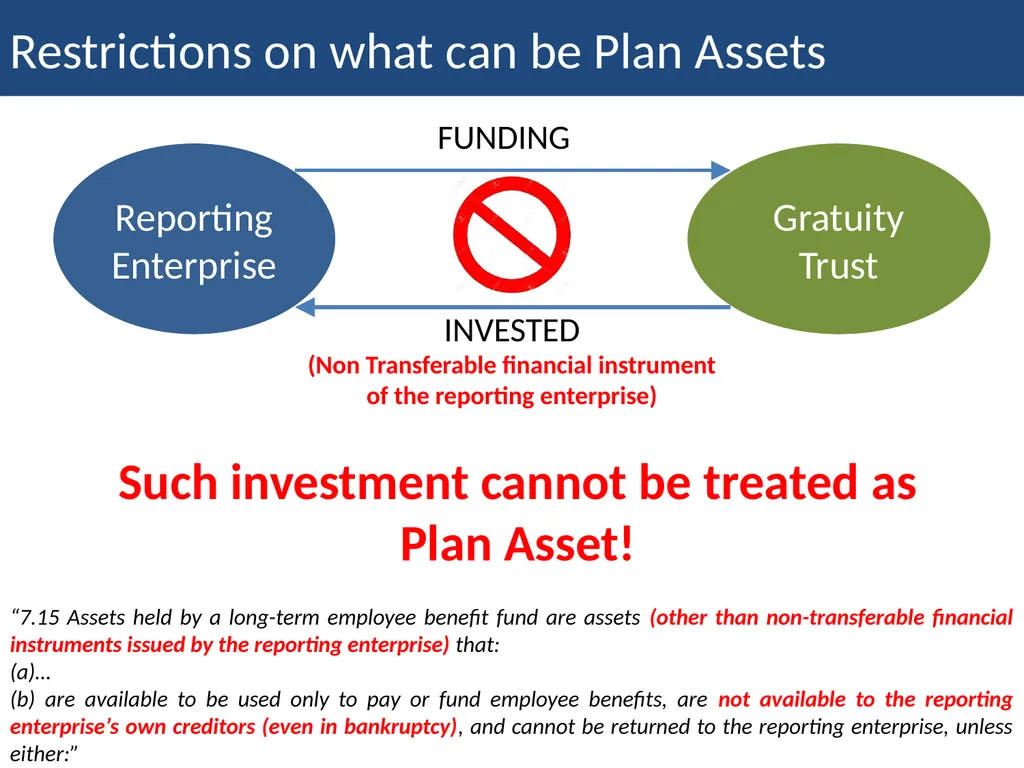
slide29. Restrictions on what can be Plan Assets Reporting Enterprise Gratuity Trust FUNDING “7.15 Assets held by a long-term employee benefit fund are assets (other than non-transferable financial instruments issued by the reporting enterprise) that:
(a)…
(b) are available to be used only to pay or fund employee benefits, are not available to the reporting enterprise’s own creditors (even in bankruptcy), and cannot be returned to the reporting enterprise, unless either:” INVESTED
(Non Transferable financial instrument of the reporting enterprise) Such investment cannot be treated as Plan Asset!<br>
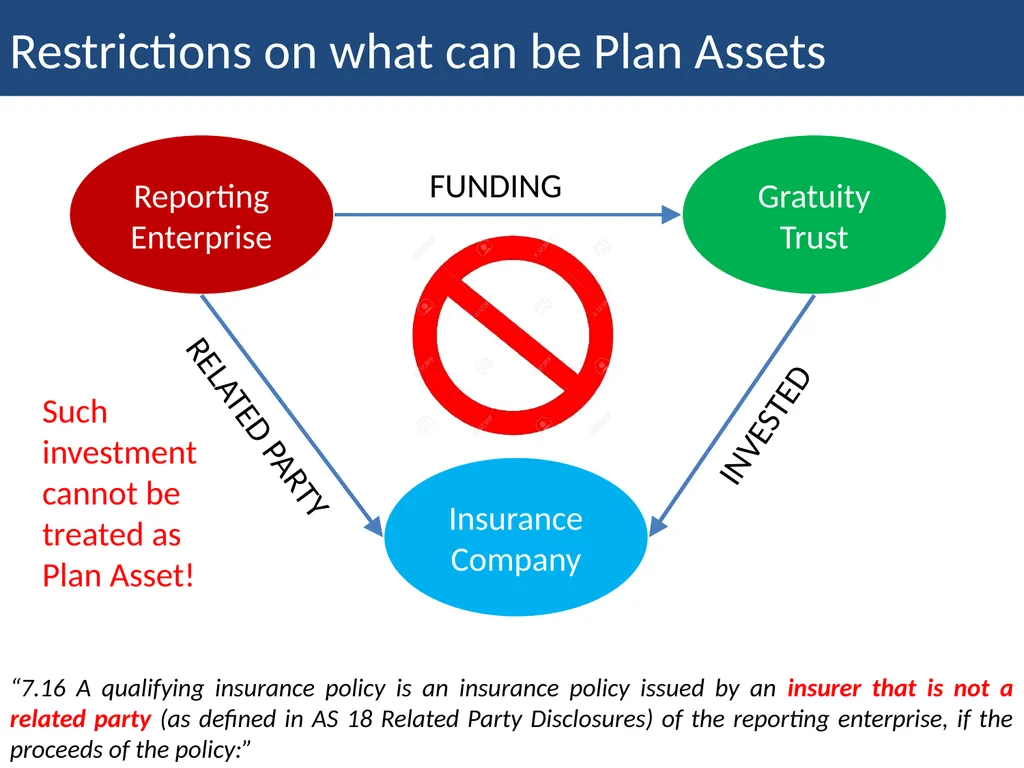
slide30. Restrictions on what can be Plan Assets Reporting Enterprise Gratuity Trust Insurance Company FUNDING INVESTED RELATED PARTY “7.16 A qualifying insurance policy is an insurance policy issued by an insurer that is not a related party (as defined in AS 18 Related Party Disclosures) of the reporting enterprise, if the proceeds of the policy:” Such investment cannot be treated as Plan Asset!<br>
slide31. Consider including disclaimer for above… May consider incorporating some disclaimer regarding plan assets in the report.
Examples:
Information relating to Plan Assets contained in this report, including the fair value of plan assets as at the valuation date, has been provided to me by the Company. The same has not been verified or validated by me.
I have not verified whether the qualifying conditions for Plan Assets, as indicated in AS15 Employee Benefits, have been met.<br>
slide32. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
slide33. Concluding thoughts Issue too large to be ignored or considered lightly.
We must seek to protect ourselves and the reputation of our profession.
We must ensure audit trails, documentation, management representations and adequate disclaimers / qualifications in our reports.
We must be able to prove discharge of our advisory responsibility.
We may engage proactively with clients to create strengthening plans.
If need is felt, should the profession engage with DPE to help protect actuaries and help companies create strengthening plan?
Please write to AG on PEBSS for any questions / suggestions / recommendations in this regard. You may write to compliance@actuariesindia.org.<br>
slide34. Any questions?<br>
Sh. A D Gupta
Consulting Actuary
Chairperson, Advisory Group on PEBSS
Khushwant Pahwa
Founder and Consulting Actuary, KP Actuaries and Consultants (KPAC)
Secretary, Advisory Group on PEBSS Data Support:
Sh. D.K. Pandit
Consulting Actuary, KA Pandit (Actuaries and Consultants)
Member, Advisory Group on PEBSS<br>
slide2. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
slide3. Setting the context… Not a new issue.
Not a small issue.
Not an issue likely to go away soon.
Carries reputation risk?
Not immediate solution
Perhaps an opportunity?<br>
slide4. Not a new issue Not a new topic of discussion.
Has been discussed in many forums (some mentioned below), Advisory Group and a topic of discussion in drafting of Actuarial Practice Standards.<br>
slide5. Not a new issue (Extracts of IBA 2013 circular) Certain extracts of IBA Circular 2013 (Guidance to Banks):
Regulatory displeasure over the lack of a planned approach to superannuation funding by many of the banks was expressed by the top management of RBI in their interactions with senior bankers under the aegis of IBA.
RBI view was that any additional funding requirement on account of bipartite settlements should be anticipated and provided for without having to seek amortization facility as wage revision takes place every five years and a fair estimate could be made based on past trends as far as likely upward revision is concerned.
Similarly, RBI felt that banks do not spread the yearly superannuation funding requirements evenly across the four quarters. Ballooned provisioning in the fourth quarter attracts criticisms from analysts and market watchers.
Salary revision takes place on the basis of bipartite negotiations every five years. Possible future increases in the salary (basic plus DA) during the average remaining service of the employees will be reflected in the superannuation pay and hence need to be factored in while determining the SER.
Banks may factor in this aspect appropriately in the calculations in consultation with their actuaries.
Salary Escalation rate (SER) of 5-5.50% without taking into account future wage revisions could be considered reasonable. The SER would need to be adjusted substantially upwards to take into account future wage revisions.<br>
slide6. Not a small issue Despite IBA circular, impact of wage revisions / agreements not considered in valuations: Total actuarially valued liabilities for PSU banks may be to the tune of Rs. 150,000 to Rs. 2,00,000 crores.
If salary growth rate assumption of 8% p.a. were to be considered appropriate, the above provisions may be higher by 20% to 30% (assuming duration of liability to be around 10 years).
Overall, the potential strengthening needed for PSU banks alone may be to the tune of Rs. 40,000 crores to Rs. 60,000 crores (a gestimate!).
Story of Public Sector Enterprises, other than banks, not very different.<br>
slide7. Not a small issue Below chart gives comparison of liabilities (other than unit fund) for life insurance companies in India with Employee Benefit liabilities for some PSU Bank and PSUs:<br>
slide8. Not a small issue Amount of strengthening needed by PSU banks more than the funds allocated in Union Budget 2016 to address the NPA issue.
Clearly – a call for action!<br>
slide9. Not Vanishing….in fact may become more challenging…<br>
slide10. Potentially carries reputation risk…. Dear Sir,
While carrying out the Actuarial valuation for leave encashment and Gratuity, assumptions for Salary increase and Interest earned are being made by you. In this connection we are in receipt of a query from Department of Public Enterprises which is reproduced as under:-
“It has been brought to the attention of DPE by Comptroller and Auditor General of India (C&AG) that C&AG, during the course of audit, have observed that there was a wide variation between the actual rate of increase in salary over a period of time and the rate of increase adopted for actuarial valuation while making provisions for leave encashment and gratuity. They have also mentioned that provisions made on inappropriate valuation worked out at a lesser rate goes to pad up the profits of the Company and to that extent does not represent a true and fair picture.”
You are requested to kindly give your views on the above observation specifically with respect to the assumptions made by you while carrying out actuarial valuation of Leave Encashment and Gratuity of ______.
___________<br>
slide11. Needs a long term solution….surely…. Profitability not there to absorb hit that may arise out of corrections: For banks, priority will be sorting out NPA issues. Post sorting out NPA issues, scope may not be there to absorb strengthening of employee benefit provisions.
Surely, the issue cannot be resolved in one year. Actuaries need to work with Companies / Management’s to work out 3-year or 5-year strengthening plan.<br>
slide12. An opportunity to work with the government? Opportunity to work with the government and help these enterprises strengthen.
Opportunity to highlight and showcase the importance of our profession.
Ind ASs may present an opportunity as the entire strengthening may not be routed through Income Statement. On pensions and gratuity, same will be routed through Other Comprehensive Income (OCI).<br>
slide13. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
slide14. Issues with PSU Valuations Issues with PSU Valuations Salary Growth Rate Assumption Mortality / Longevity Assumption Provision of inadequate liability? Issue of salary growth rate being inadequate, resulting in under-provisioning of the liability. Issue of use of old mortality table and non allowance of mortality improvements.
Issue also of use of assured lives table for valuing Pensions / PRMS Schemes Is this really an issue?<br>
slide15. Considering Salary hikes in the past CAGR of Salary between 2007 and 2016 = 11.5%
CAGR of Salary between 2006 and 2016 = 14.5% CAGR of Salary between 2007 and 2016 = 12%
CAGR of Salary between 2007 and 2016 = 14.1%<br>
slide16. Considering Salary hikes in the past CAGR of Salary
= 11.5% p.a.
Average CPI
= 9% p.a. CAGR of Salary
=9.5% p.a.
Average CPI
= 5.2% p.a. CAGR of Salary
= 9.8% p.a.
Average CPI
= 8.4% p.a.<br>
slide17. CPI and Bond Yields Discount Rate (Bond Yields) are a given for valuation.
We can estimate consistent long term view of CPI to be about 1.5% to 2% lower.
Building on the Merit Component and Productivity Component may get us to a sound salary growth rate assumption.<br>
slide18. Issue with Mortality Assumption: Longevity<br>
slide19. Issue with Mortality Assumption The table below shows the impact of 15% and 20% improvement in Annuitant’s rates on life expectancy: A 20% improvement in mortality rates may result in an increase in liability by more than 10% (ignoring impact of salary growth rate and discount rate).<br>
slide20. Provision of inadequate liability<br>
slide21. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
slide22. Deliberating solutions… The Way Forward Protecting ourselves Actually solving the problem Any guidance needed? By use of adequate disclosures and disclaimers to highlight areas of concern.
Taking management representations on inputs into the valuations. Preparing 3 year or 5 year plans to strengthen the provisioning.
Sheer magnitude of problem means that it cannot be solved overnight. Specific guidance for PSU valuations may end up being rule based and not principles based.
Do we need such a guidance?<br>
slide23. Protecting ourselves… In determination of assumptions, the roles of various stakeholders is as follows: Clarifying Responsibility: Actuarial valuation reports contain many inputs (data, assumptions, benefit). We must clarify, for each set of input individually, the extent to which we have relied and / or verified.
Reflecting Discharge of Responsibility: Valuation report should bring out that the Management / Company has been advised by the Company on appropriate set of assumptions.
Reflecting Disagreement: If ‘appropriate’ set of assumptions have not been chosen, the same should be reflected in the report.
Overall, the Standard Disclaimers currently contained in the reports may not be enough to make the user of the report understand exactly what are we owning up to and what are the responsibilities of the user of the report.<br>
slide24. Potential disclaimers on Salary Growth Rate Assumptions “The Company has been advised that the assumptions need to be set up based on Para 73 to Para 91 of AS15 (Revised 2005).”
“Specifically for Salary Growth Rate assumption, the Company has been advised to choose an assumption that adequately considers the three key components of the salary growth i.e. inflation relief, productivity increase and merit increase. The Company has been advised to also consider the past trends in salary growth rate in choosing the salary growth rate assumption for the purposes of this valuation.
“The assumptions, including the Salary Growth Rate assumption, considered in this valuation have been selected by the management of the Company.”
“It should be noted that Salary Growth Rate is one the key assumptions used in determination of the liability. An increase in salary growth rate assumption by 1% p.a. i.e. from 5% p.a. currently to 6% p.a. will lead to an increase in liability by 10% i.e. from Rs. 30,000 crores currently to Rs. 33,000 crores.”
“Past trends are an important factor to be considered in determining the salary growth rate assumption. Observing the past trends in the salary growth of employees over the last 15 years (which includes the impact one wage revision agreement) indicates that the chosen salary growth rate assumption does not adequately reflect the increases in salary growth expected to be given in future.”
“If this report is being made available to auditors and they are expected to rely on the numbers contained herein, then, in light of provisions of para _____ of SA 500: Audit Evidence issued by the Institute of Chartered Accountants of India, it must be indicated to that they continue to be responsible for validity of data and reasonableness of the assumptions.”<br>
slide25. What about Mortality / Longevity? Clients cannot be responsible for Mortality Rate assumptions. It is the actuary that must be responsible.
Need to move to Annuitants table, if not already doing it.
Start applying improvement factors, if not already doing it. May be 5% each year as a sudden large improvement may push up the liabilities too much.
If nothing, we should highlight / make relevant statements, such as:
“Mortality table used in the valuation is based on annuitants data of years 1996 to 1998. It does not factor in the improvements in mortality and consequent increase in life expectancy that may have happened ever since. The valuation also does not consider the future improvements in life expectancy, that may happen until the benefit payout under the scheme.”
“It may be noted that a 10% improvement in mortality experience over and able the published table currently used for valuation, which is likely to result in an increase in life expectancy of a 60 years old person by about 1 year, is likely to result in an increase in liability by 5%.”<br>
slide26. Creating strengthening plans Two Approaches Protect yourself Engage to Solve Must do, in any case
Use of Disclaimers
Taking Management Representations
Documenting conversations and discussions
Creating minutes of critical meetings, even if telephonic Problem cannot be solved overnight. Can be solved over medium term, if approached proactively
Help companies create 3-year or 5-year or longer plans to strengthening, whilst continuing to protect yourself.
Consider all factors in creating such plans i.e. interest rates fall, increase in gratuity limit, mortality improvements, strengthening of salary growth rate assumptions.
Benefits: Commercial interests, greater interaction with the organizations, minimizes professional / reputational risks and helps serve the interests of public.
Challenges: of the other approach will include low profitability of the companies and reluctance on their part to take incremental hits on their profitability. However, CAG findings and routing of re-measurements through Other Comprehensive Income (OCI) can help sell the idea.<br>
slide27. Need for professional guidance? Need a Standard for PSU valuations? Need for profession to engage with DPE? Need for mandating Peer Review of liabilities of PSUs? Need support from AG on drafting disclaimers / qualifications to consider? Any other support needed from AG? Any other thoughts?<br>
slide28. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding Thoughts<br>
slide29. Restrictions on what can be Plan Assets Reporting Enterprise Gratuity Trust FUNDING “7.15 Assets held by a long-term employee benefit fund are assets (other than non-transferable financial instruments issued by the reporting enterprise) that:
(a)…
(b) are available to be used only to pay or fund employee benefits, are not available to the reporting enterprise’s own creditors (even in bankruptcy), and cannot be returned to the reporting enterprise, unless either:” INVESTED
(Non Transferable financial instrument of the reporting enterprise) Such investment cannot be treated as Plan Asset!<br>
slide30. Restrictions on what can be Plan Assets Reporting Enterprise Gratuity Trust Insurance Company FUNDING INVESTED RELATED PARTY “7.16 A qualifying insurance policy is an insurance policy issued by an insurer that is not a related party (as defined in AS 18 Related Party Disclosures) of the reporting enterprise, if the proceeds of the policy:” Such investment cannot be treated as Plan Asset!<br>
slide31. Consider including disclaimer for above… May consider incorporating some disclaimer regarding plan assets in the report.
Examples:
Information relating to Plan Assets contained in this report, including the fair value of plan assets as at the valuation date, has been provided to me by the Company. The same has not been verified or validated by me.
I have not verified whether the qualifying conditions for Plan Assets, as indicated in AS15 Employee Benefits, have been met.<br>
slide32. Agenda Introduction to the issue
Identifying the problem
Deliberating potential solutions
Plan Assets
Concluding remarks<br>
slide33. Concluding thoughts Issue too large to be ignored or considered lightly.
We must seek to protect ourselves and the reputation of our profession.
We must ensure audit trails, documentation, management representations and adequate disclaimers / qualifications in our reports.
We must be able to prove discharge of our advisory responsibility.
We may engage proactively with clients to create strengthening plans.
If need is felt, should the profession engage with DPE to help protect actuaries and help companies create strengthening plan?
Please write to AG on PEBSS for any questions / suggestions / recommendations in this regard. You may write to compliance@actuariesindia.org.<br>
slide34. Any questions?<br>