
Audit Planning and Analytical Procedures Chapter 8
Description: Audit Planning and Analytical Procedures Chapter 8 Learning Objective 1 Discuss why adequate audit planning is essential. Planning The work is to be adequately planned, and assistants, if any, are to be properly supervised. Acceptable audit
Related Topics
Download Presentation
"Audit Planning and Analytical Procedures Chapter 8" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Audit Planning and
Analytical Procedures Chapter 8<br>
slide2. Learning Objective 1 Discuss why adequate audit
planning is essential.<br>
slide3. Planning The work is to be adequately planned, and
assistants, if any, are to be properly supervised. Acceptable audit risk Inherent risk<br>
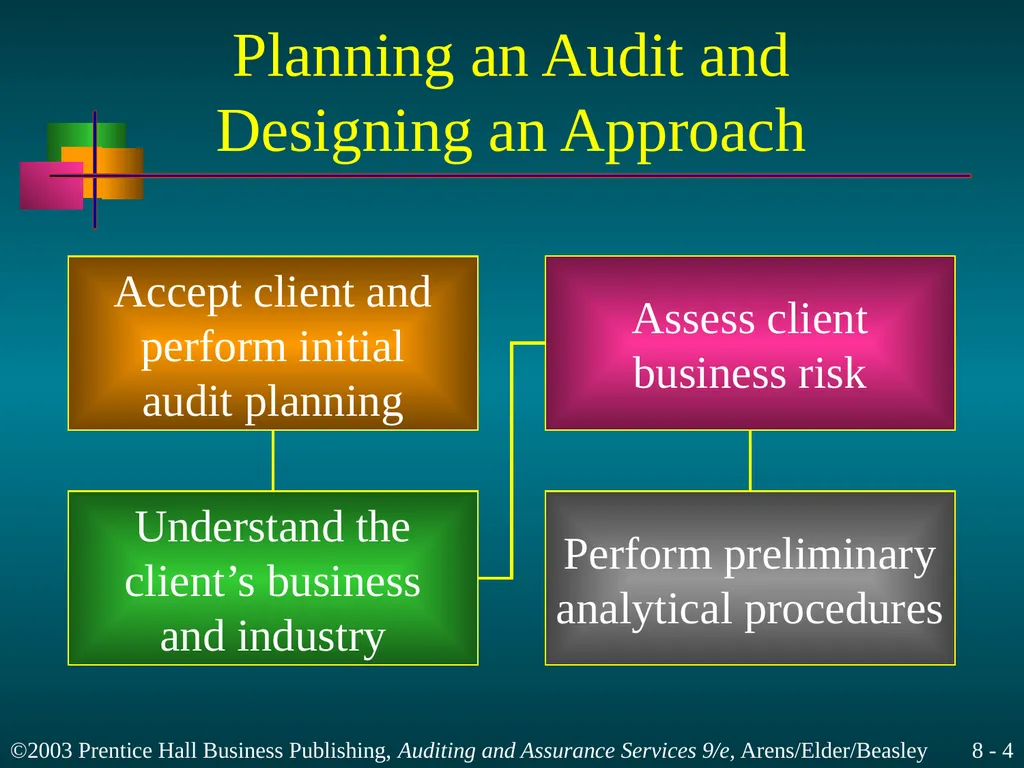
slide4. Planning an Audit and Designing an Approach Accept client and
perform initial
audit planning Understand the
client’s business
and industry Assess client
business risk Perform preliminary
analytical procedures<br>
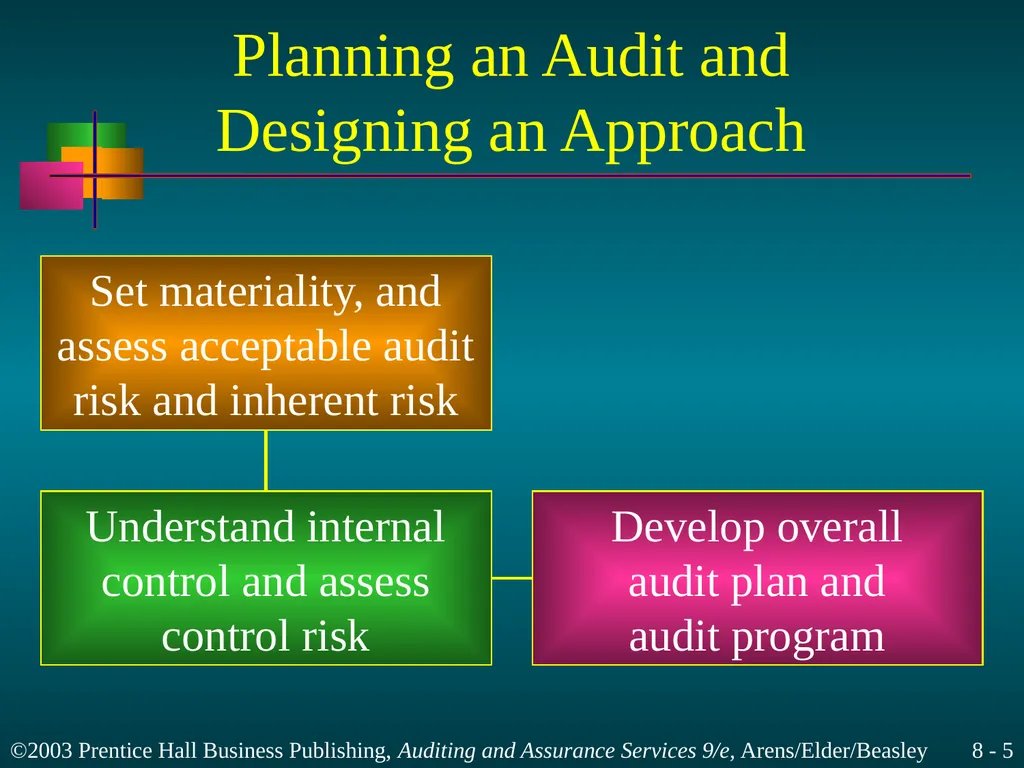
slide5. Planning an Audit and Designing an Approach Set materiality, and
assess acceptable audit
risk and inherent risk Understand internal
control and assess
control risk Develop overall
audit plan and
audit program<br>
slide6. Learning Objective 2 Make client acceptance
decisions and perform
initial audit planning.<br>
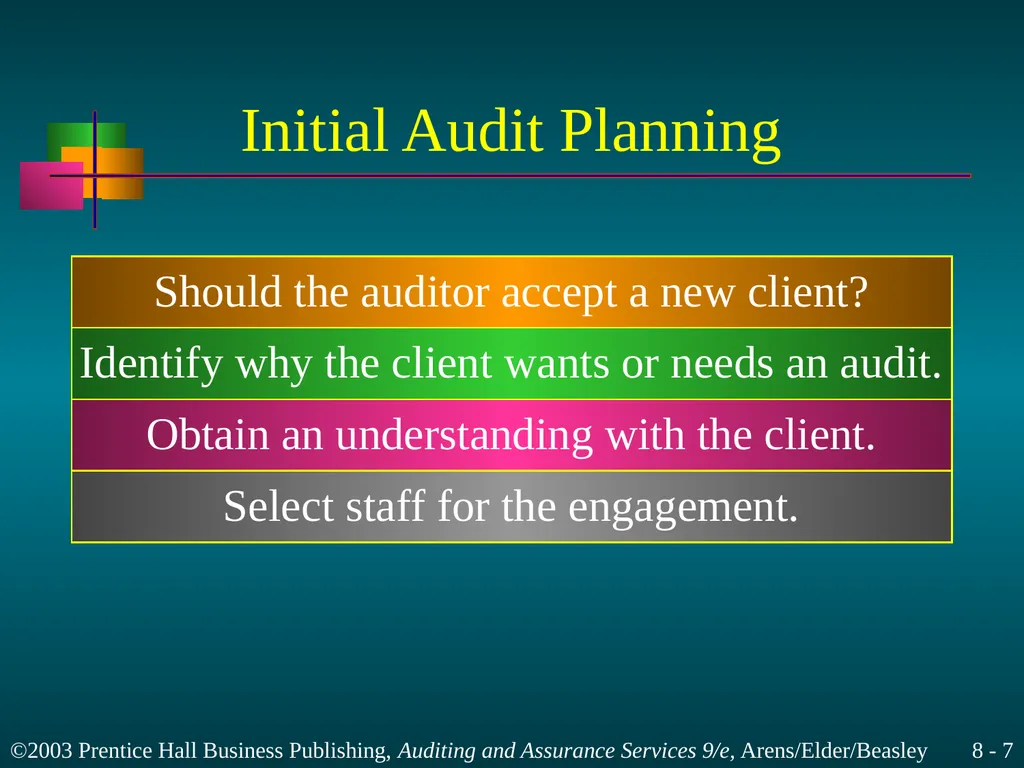
slide7. Initial Audit Planning Should the auditor accept a new client? Identify why the client wants or needs an audit. Obtain an understanding with the client. Select staff for the engagement.<br>
slide8. Learning Objective 3 Gain an understanding of the
client’s business and industry.<br>
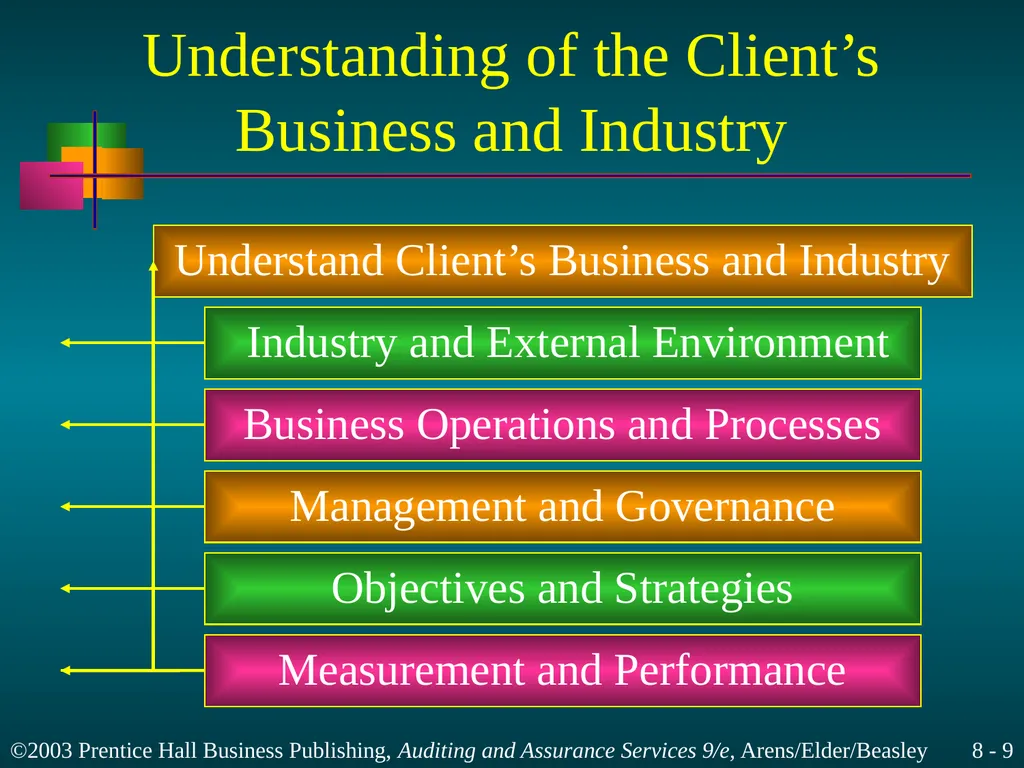
slide9. Understanding of the Client’s Business and Industry Understand Client’s Business and Industry Industry and External Environment Business Operations and Processes Management and Governance Objectives and Strategies Measurement and Performance<br>
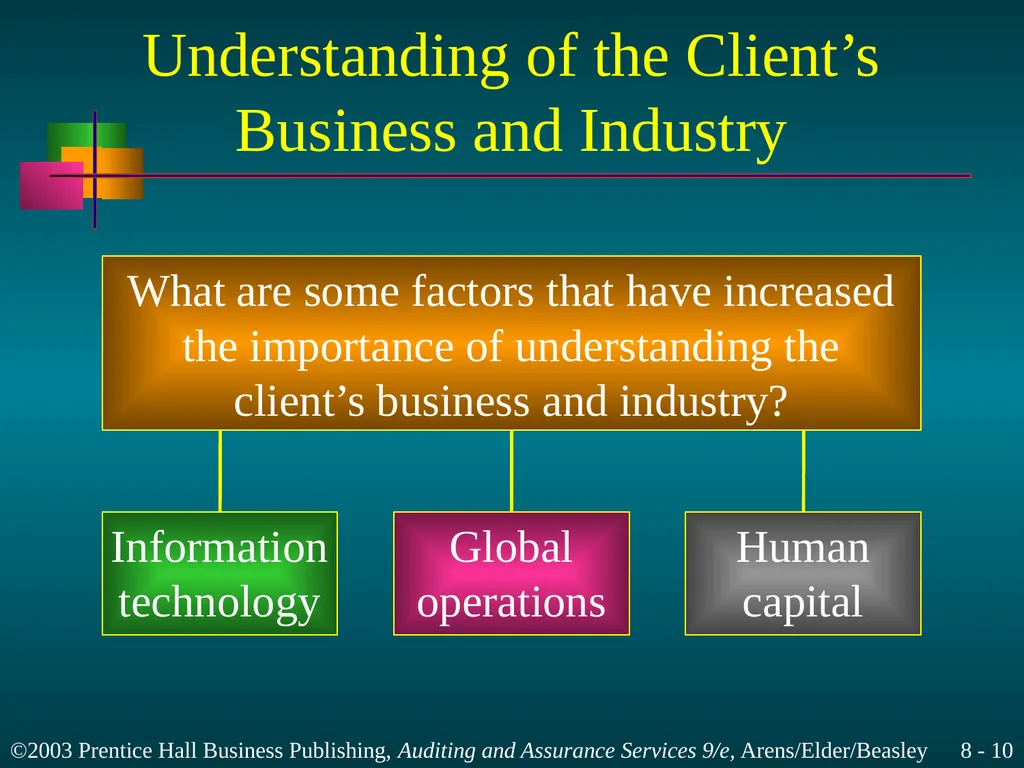
slide10. Understanding of the Client’s Business and Industry What are some factors that have increased
the importance of understanding the
client’s business and industry? Information
technology Global
operations Human
capital<br>
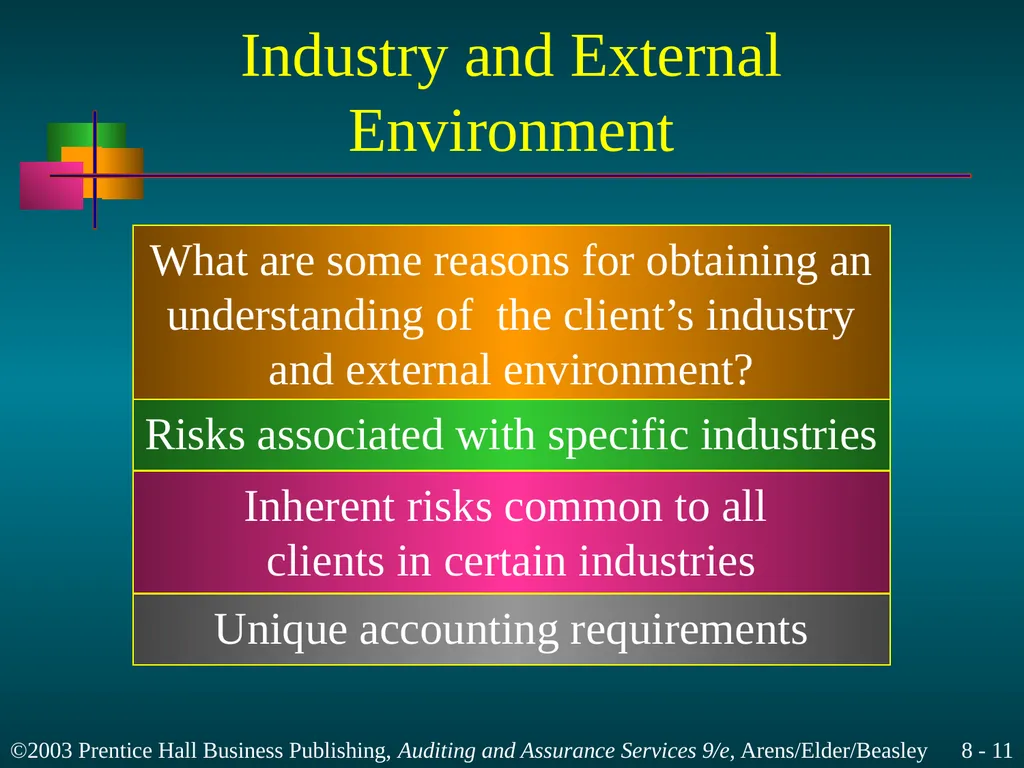
slide11. Industry and External Environment What are some reasons for obtaining an
understanding of the client’s industry
and external environment? Risks associated with specific industries Inherent risks common to all
clients in certain industries Unique accounting requirements<br>
slide12. Business Operations and Processes Factors the auditor should understand: – major sources of revenue – sources of revenue – key customers and suppliers – sources of financing – information about related parties – ability to obtain financing<br>
slide13. Management and Governance Management establishes the strategies and
processes followed by the client’s business. Governance includes the client’s organizational
structure, as well as the activities of the board
of directors and the audit committee. Corporate charter and bylaws Minutes of meetings<br>
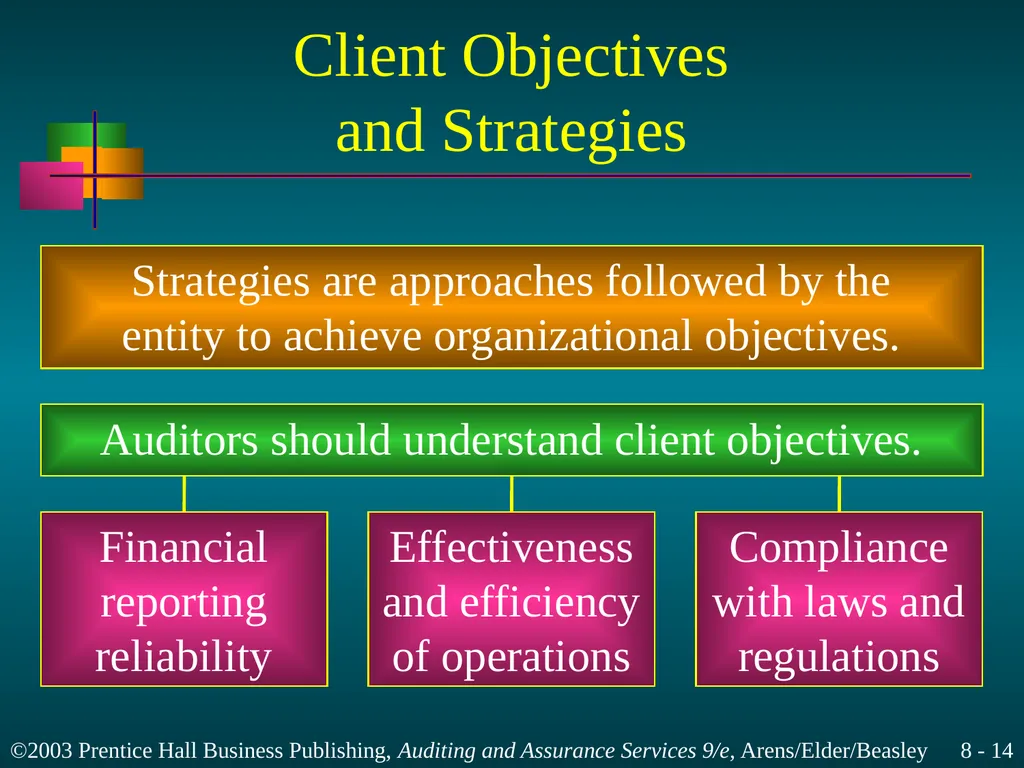
slide14. Client Objectives and Strategies Strategies are approaches followed by the
entity to achieve organizational objectives. Auditors should understand client objectives. Financial
reporting
reliability Effectiveness
and efficiency
of operations Compliance
with laws and
regulations<br>
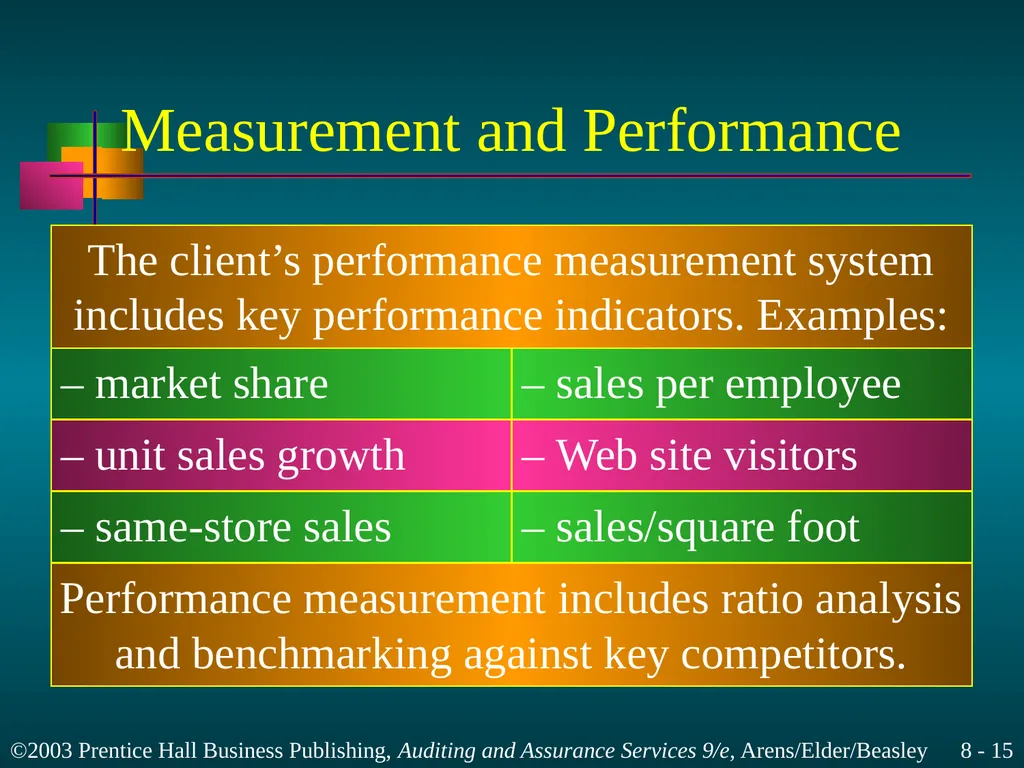
slide15. Measurement and Performance The client’s performance measurement system
includes key performance indicators. Examples: Performance measurement includes ratio analysis
and benchmarking against key competitors. – market share – sales per employee – unit sales growth – Web site visitors – same-store sales – sales/square foot<br>
slide16. Learning Objective 4 Assess client business risk.<br>
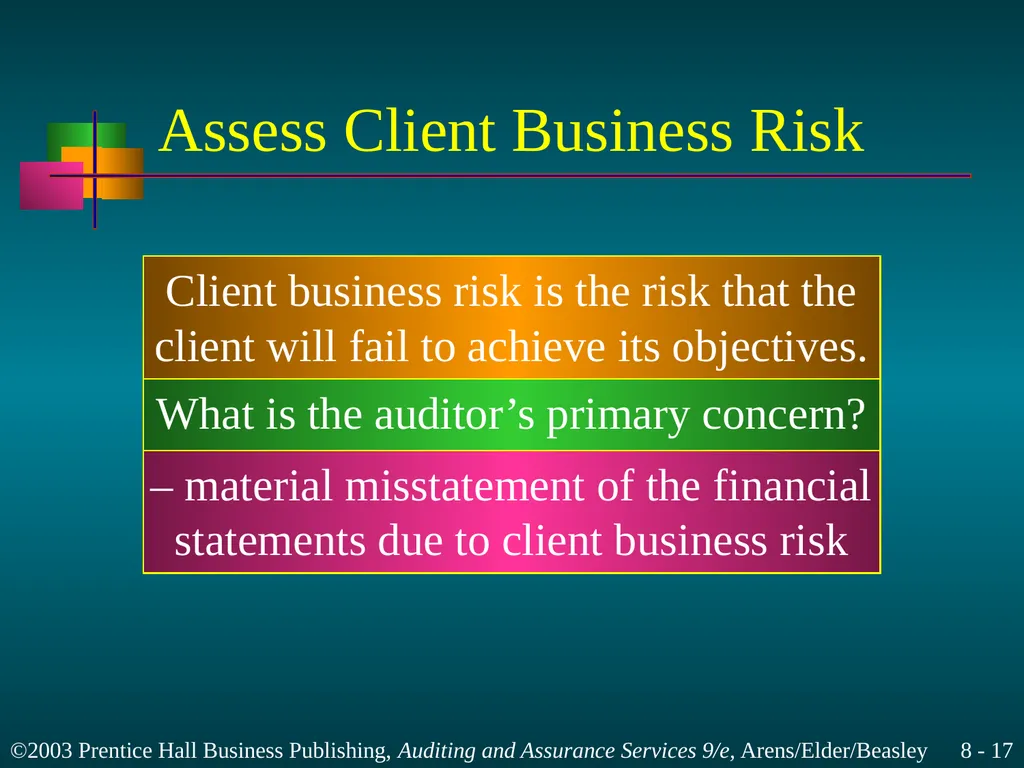
slide17. Assess Client Business Risk Client business risk is the risk that the
client will fail to achieve its objectives. What is the auditor’s primary concern? – material misstatement of the financial
statements due to client business risk<br>
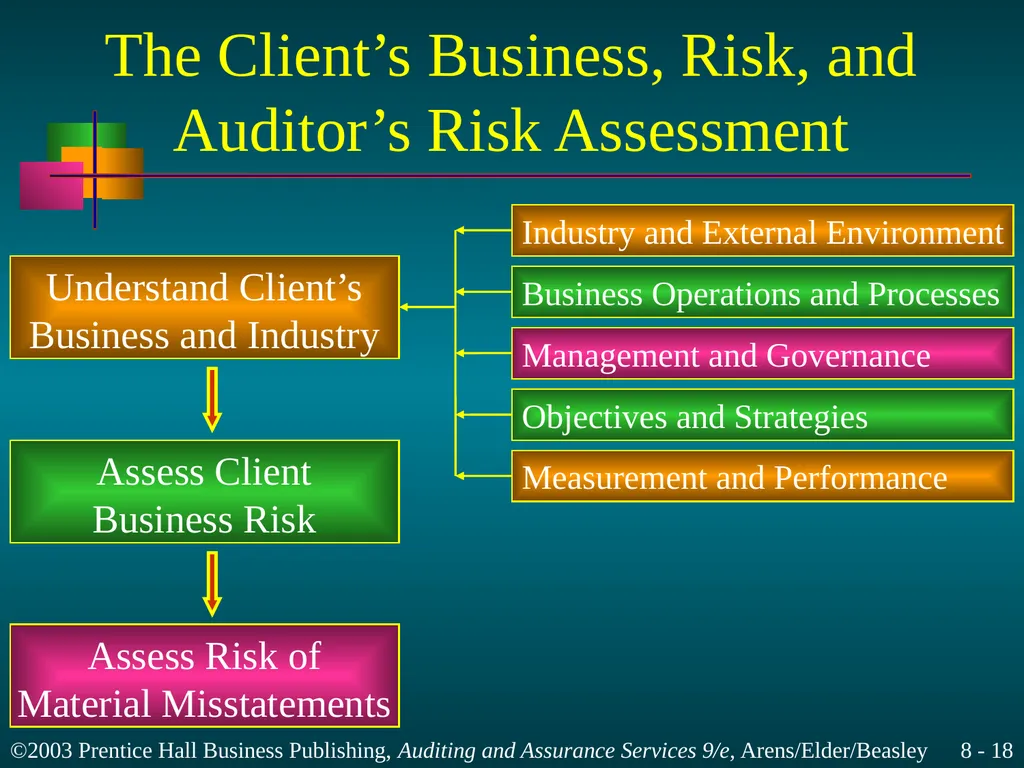
slide18. The Client’s Business, Risk, and Auditor’s Risk Assessment Industry and External Environment Business Operations and Processes Management and Governance Objectives and Strategies Measurement and Performance Understand Client’s
Business and Industry Assess Client
Business Risk Assess Risk of
Material Misstatements<br>
slide19. Learning Objective 5 Perform preliminary
analytical procedures.<br>
slide20. Preliminary Analytical Procedures Comparison of client ratios to industry
or competitor benchmarks provides an
indication of the company’s performance. Analytical procedures are also an important
part of testing throughout the audit.<br>
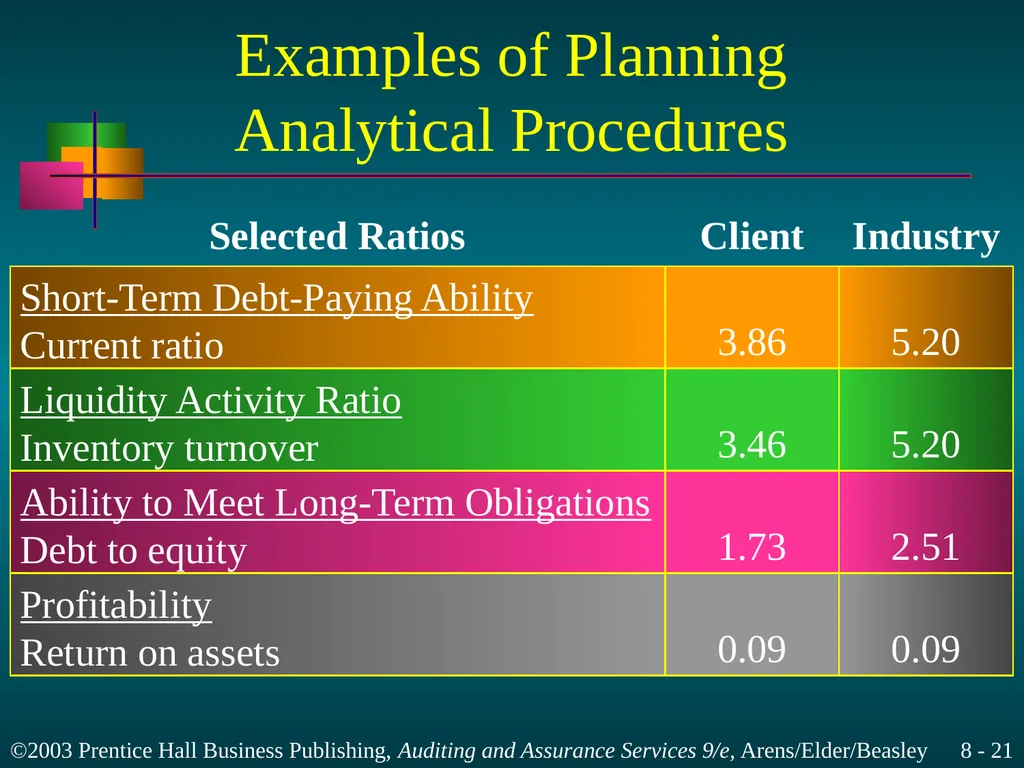
slide21. Examples of Planning Analytical Procedures Client Industry Short-Term Debt-Paying Ability
Current ratio Liquidity Activity Ratio
Inventory turnover Ability to Meet Long-Term Obligations
Debt to equity Profitability
Return on assets 3.86 5.20 3.46 5.20 1.73 2.51 0.09 0.09 Selected Ratios<br>
slide22. Summary of the Purposes of Auditing Planning A major purpose is to gain an understanding
of the client’s business and industry.<br>
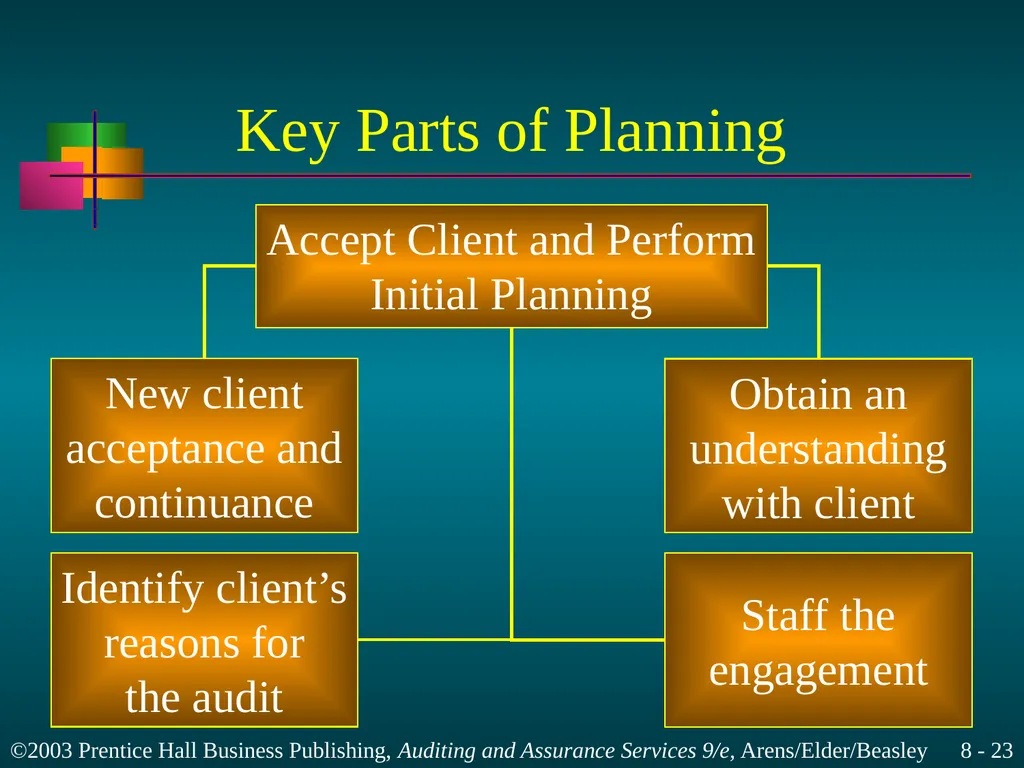
slide23. Key Parts of Planning Accept Client and Perform
Initial Planning New client
acceptance and
continuance Identify client’s
reasons for
the audit Obtain an
understanding
with client Staff the
engagement<br>
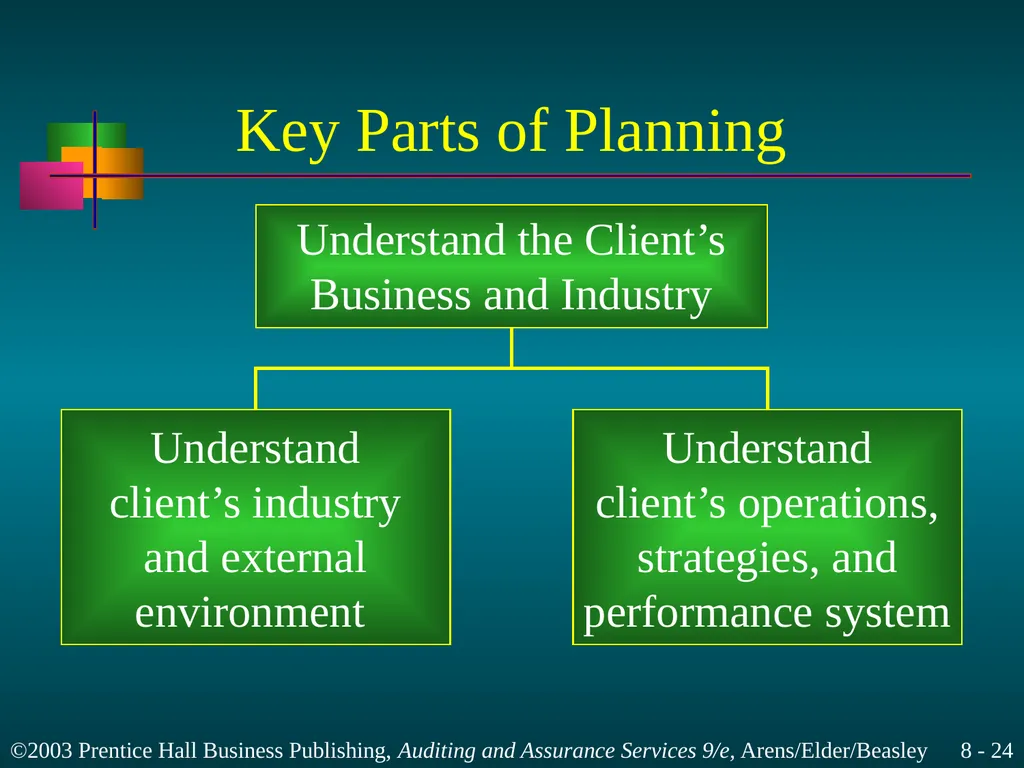
slide24. Key Parts of Planning Understand the Client’s
Business and Industry Understand
client’s industry
and external
environment Understand
client’s operations,
strategies, and
performance system<br>
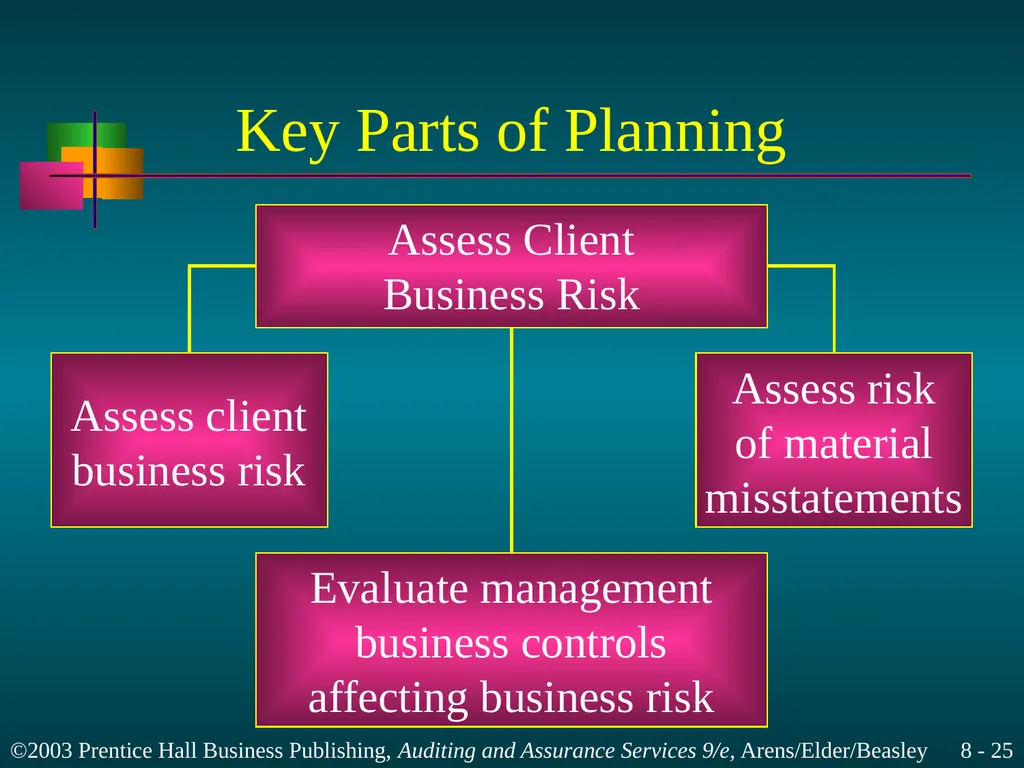
slide25. Key Parts of Planning Assess Client
Business Risk Assess client
business risk Evaluate management
business controls
affecting business risk Assess risk
of material
misstatements<br>
slide26. Key Parts of Planning Perform Preliminary
Analytical Procedures<br>
slide27. Learning Objective 6 State the purposes of analytical
procedures and the timing of
each purpose.<br>
slide28. Analytical Procedures Analytical procedures use comparisons and
relationships to assess whether account
balances or other data appear reasonable. SAS 56 emphasizes the expectations
developed by the auditor.<br>
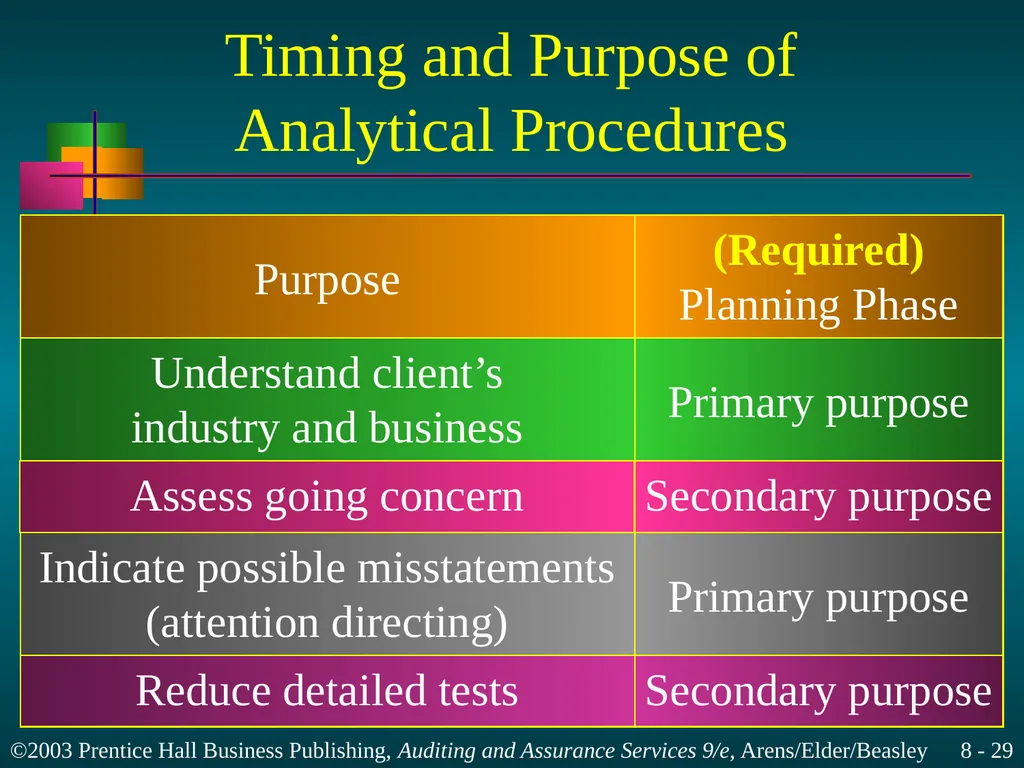
slide29. Timing and Purpose of Analytical Procedures (Required)
Planning Phase Purpose Understand client’s
industry and business Assess going concern Indicate possible misstatements
(attention directing) Reduce detailed tests Primary purpose Secondary purpose Primary purpose Secondary purpose<br>
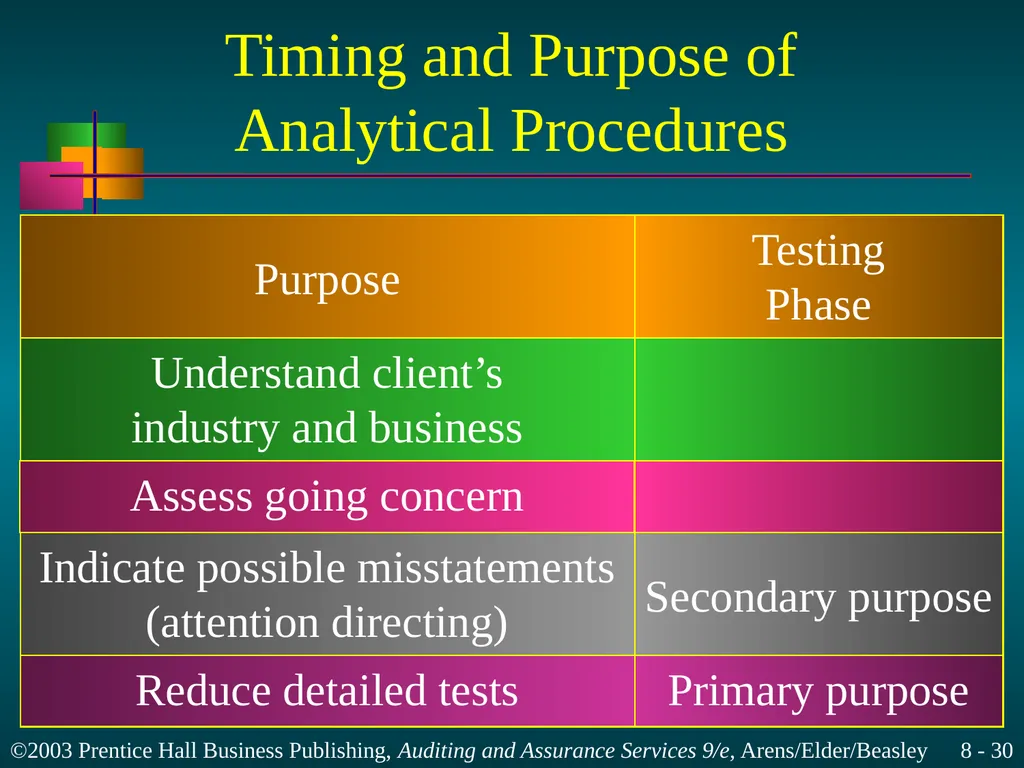
slide30. Timing and Purpose of Analytical Procedures Testing
Phase Purpose Understand client’s
industry and business Assess going concern Indicate possible misstatements
(attention directing) Reduce detailed tests Secondary purpose Primary purpose<br>
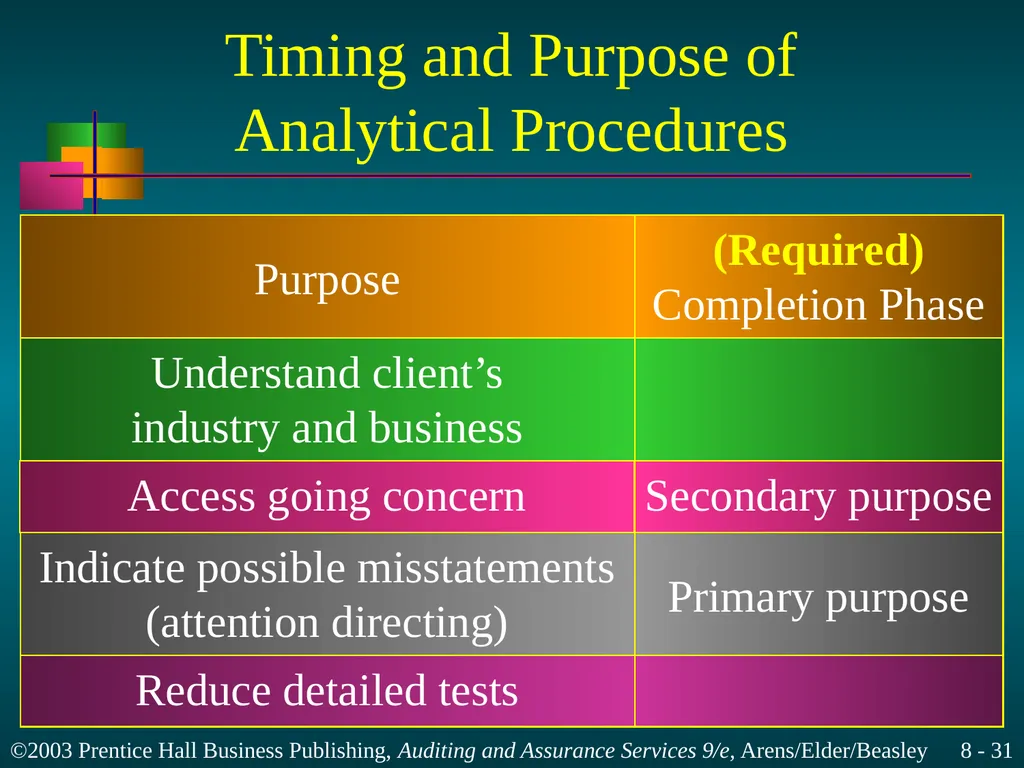
slide31. Timing and Purpose of Analytical Procedures (Required)
Completion Phase Purpose Understand client’s
industry and business Access going concern Indicate possible misstatements
(attention directing) Reduce detailed tests Secondary purpose Primary purpose<br>
slide32. Learning Objective 7 Select the most appropriate
analytical procedure from
among the five major types.<br>
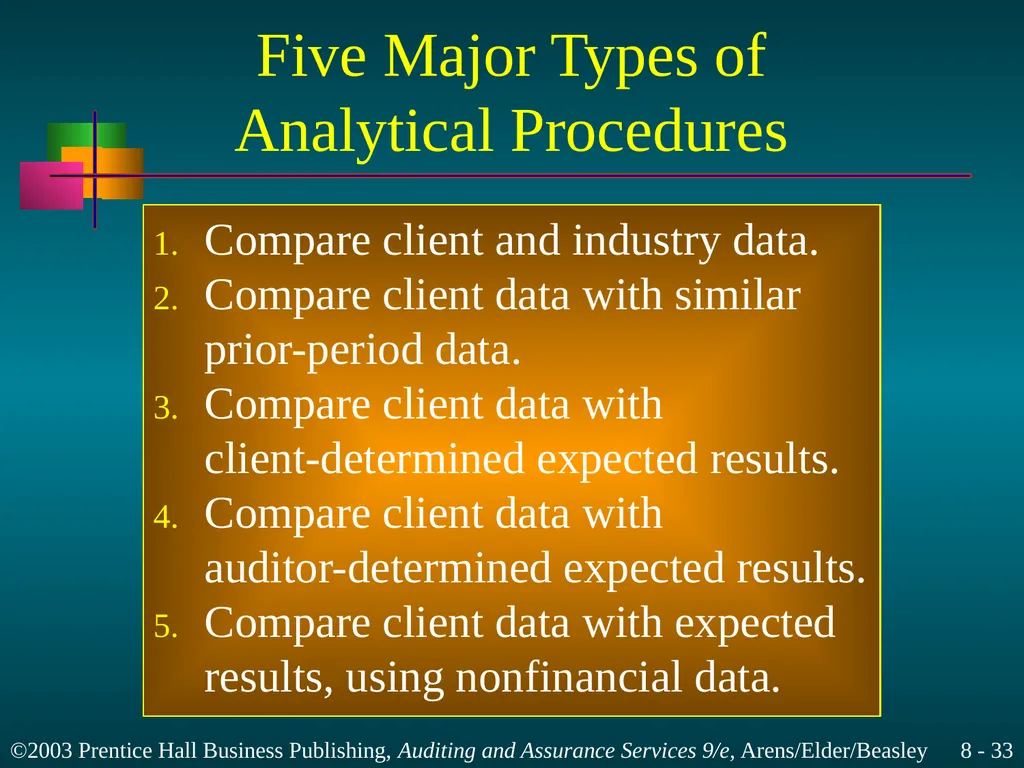
slide33. Five Major Types of Analytical Procedures Compare client and industry data.
Compare client data with similar prior-period data.
Compare client data with client-determined expected results.
Compare client data with auditor-determined expected results.
Compare client data with expected results, using nonfinancial data.<br>
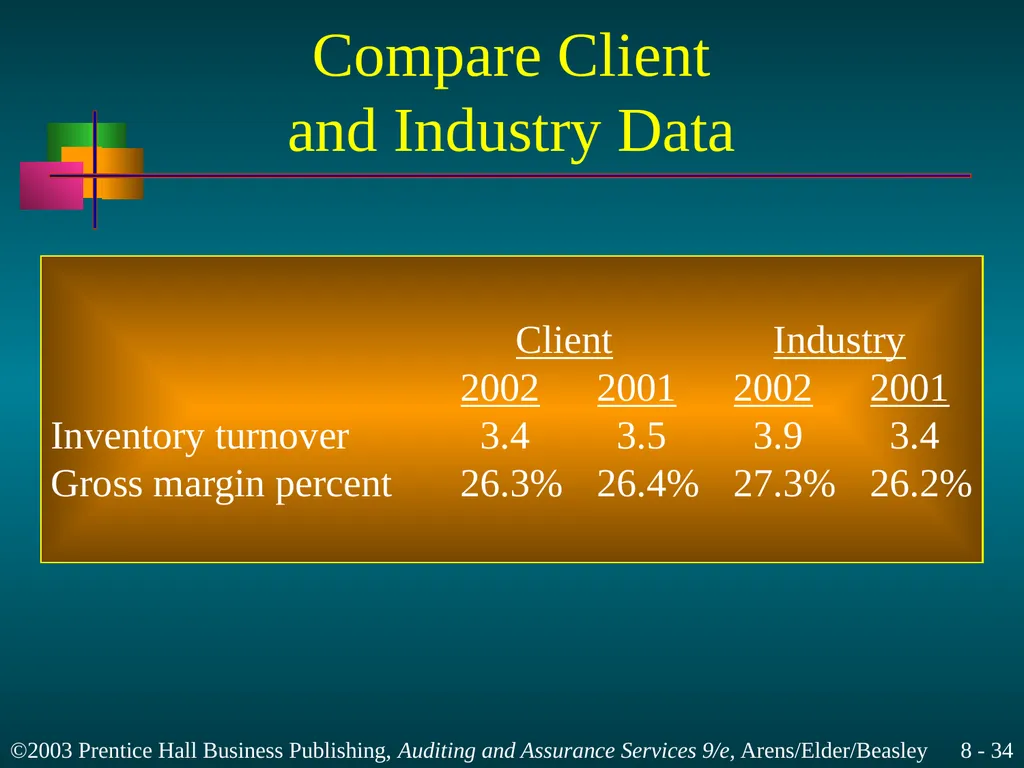
slide34. Compare Client and Industry Data Client Industry
2002 2001 2002 2001
Inventory turnover 3.4 3.5 3.9 3.4
Gross margin percent 26.3% 26.4% 27.3% 26.2%<br>
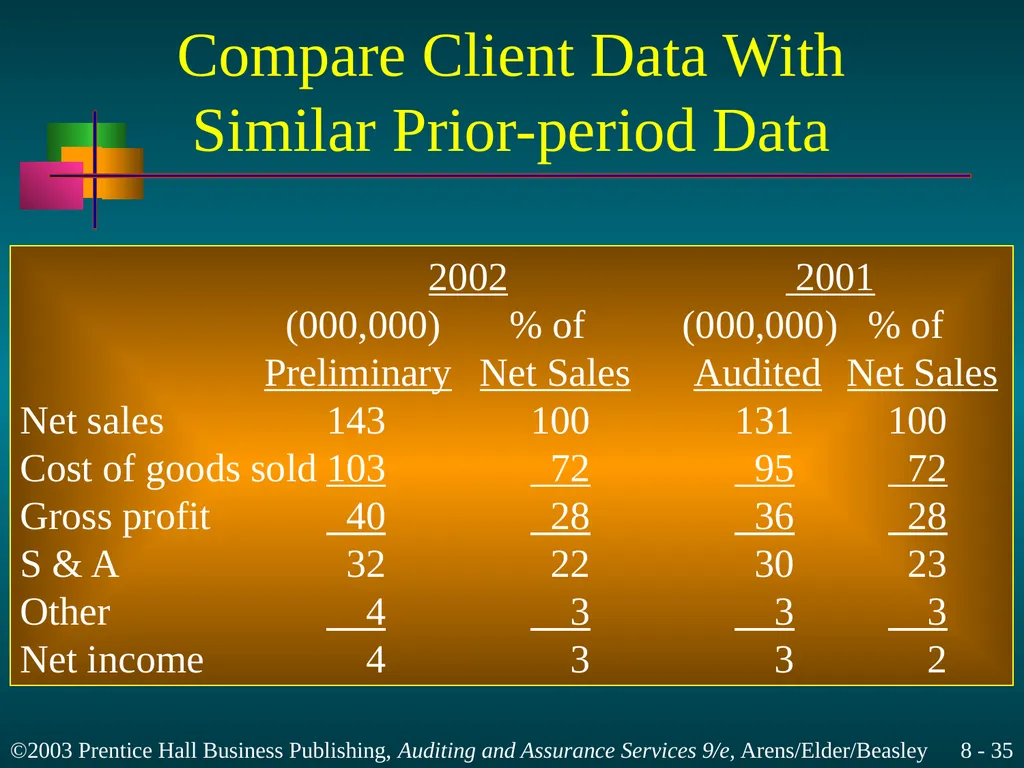
slide35. Compare Client Data With Similar Prior-period Data 2002 2001
(000,000) % of (000,000) % of
Preliminary Net Sales Audited Net Sales
Net sales 143 100 131 100
Cost of goods sold 103 72 95 72
Gross profit 40 28 36 28
S & A 32 22 30 23
Other 4 3 3 3
Net income 4 3 3 2<br>
slide36. Learning Objective 8 Compute common
financial ratios.<br>
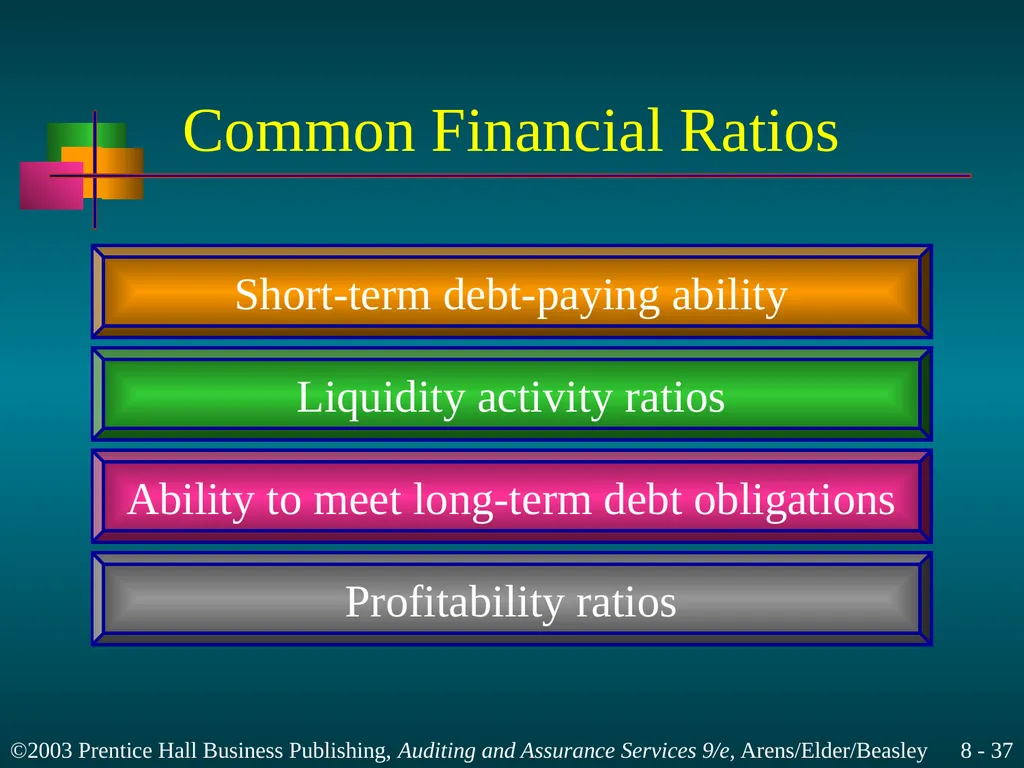
slide37. Common Financial Ratios Short-term debt-paying ability Liquidity activity ratios Ability to meet long-term debt obligations Profitability ratios<br>
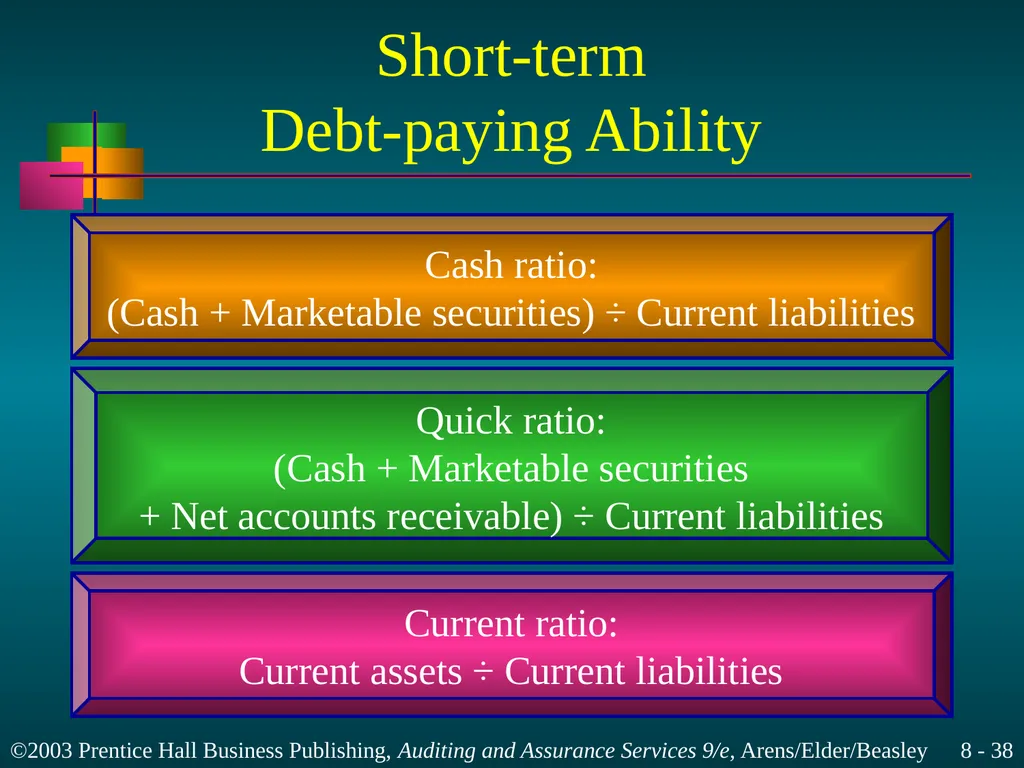
slide38. Short-term Debt-paying Ability Cash ratio:
(Cash + Marketable securities) ÷ Current liabilities Quick ratio:
(Cash + Marketable securities
+ Net accounts receivable) ÷ Current liabilities Current ratio:
Current assets ÷ Current liabilities<br>
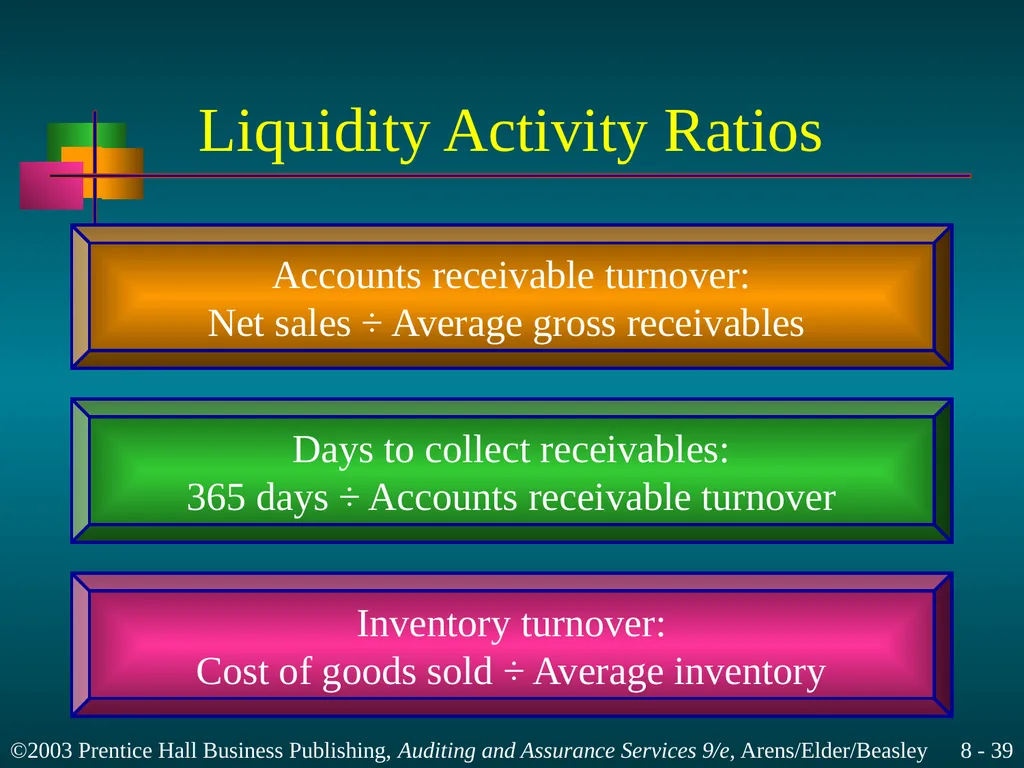
slide39. Liquidity Activity Ratios Accounts receivable turnover:
Net sales ÷ Average gross receivables Days to collect receivables:
365 days ÷ Accounts receivable turnover Inventory turnover:
Cost of goods sold ÷ Average inventory<br>
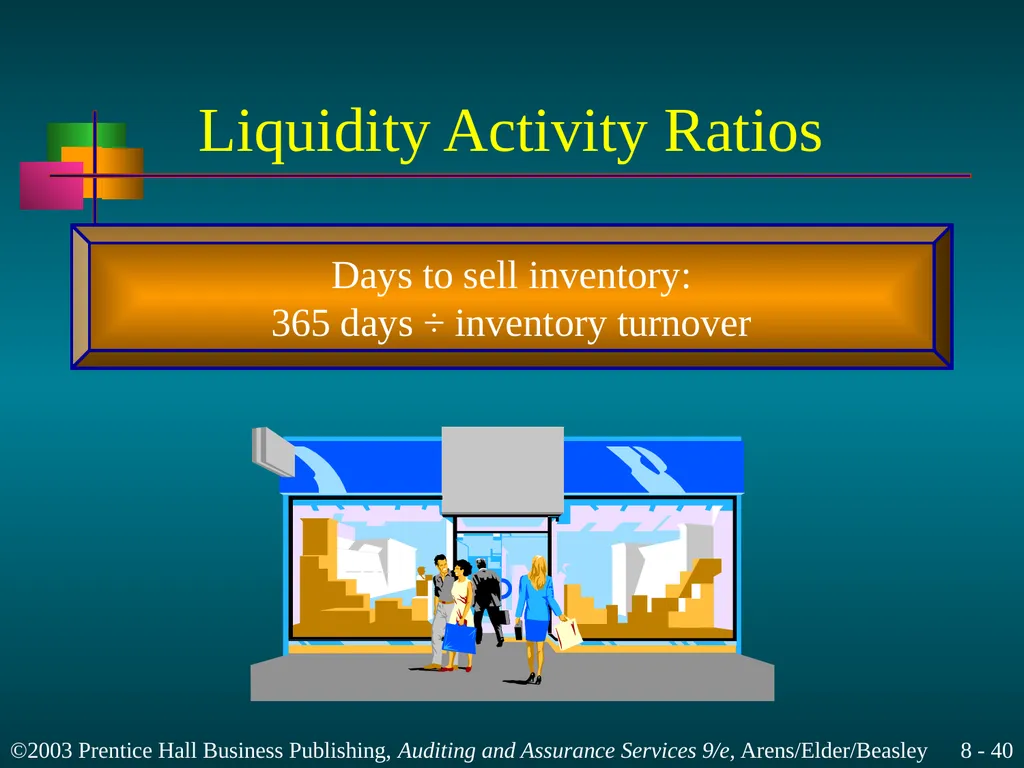
slide40. Liquidity Activity Ratios Days to sell inventory:
365 days ÷ inventory turnover<br>
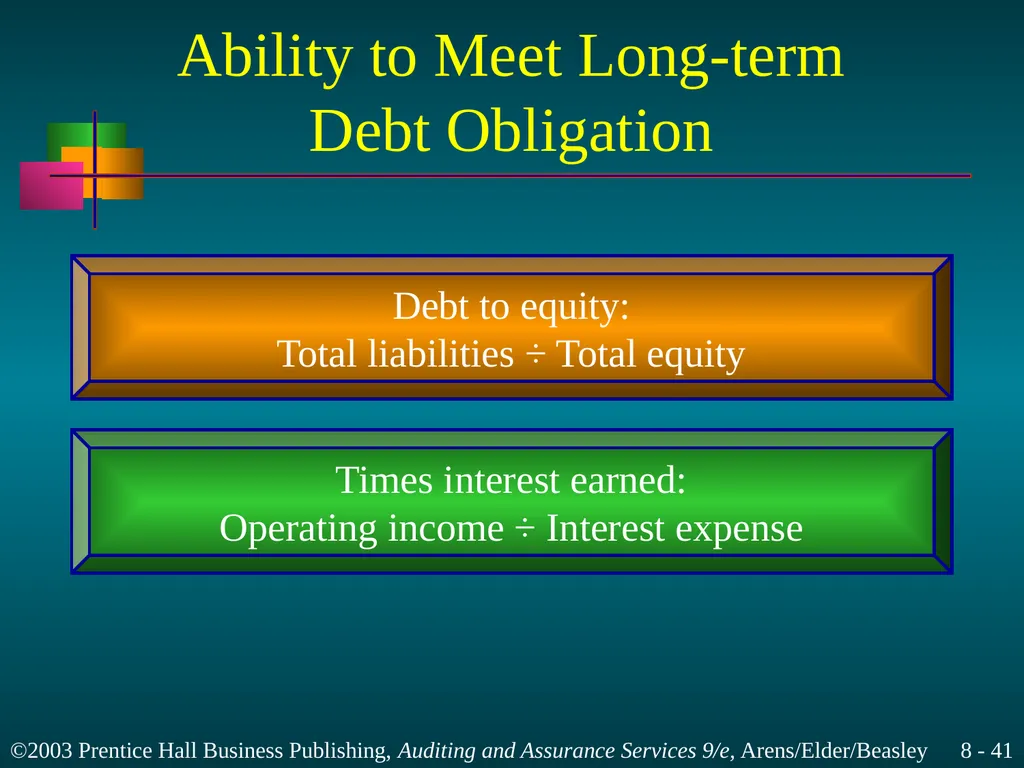
slide41. Ability to Meet Long-term Debt Obligation Debt to equity:
Total liabilities ÷ Total equity Times interest earned:
Operating income ÷ Interest expense<br>
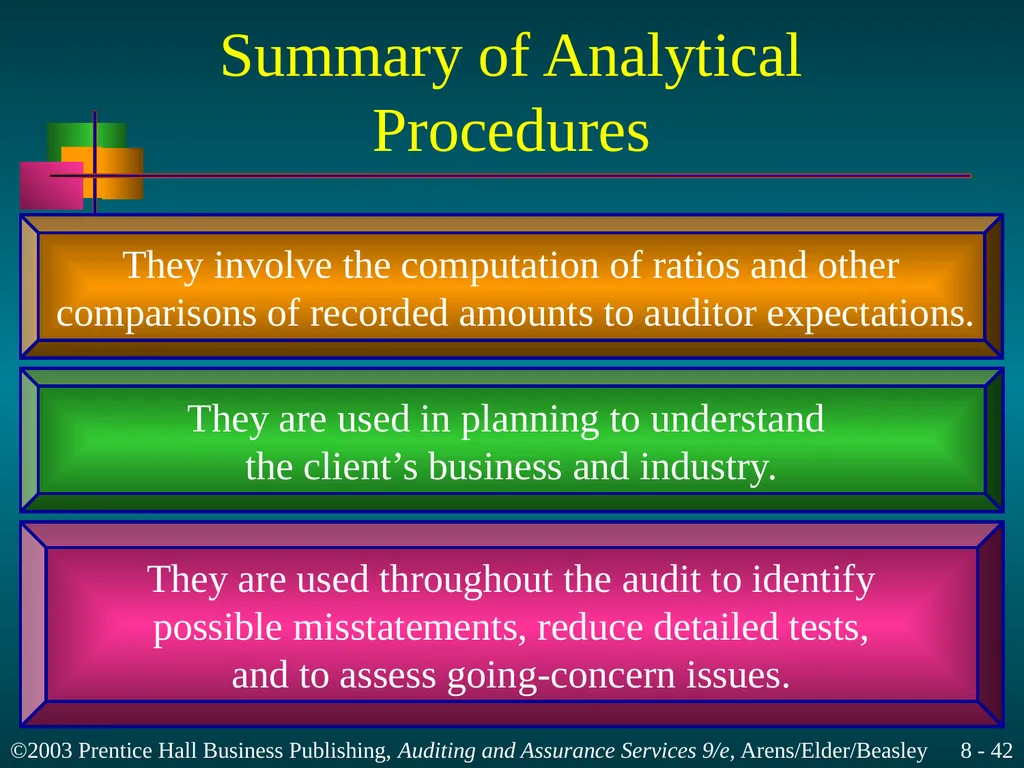
slide42. Summary of Analytical Procedures They involve the computation of ratios and other
comparisons of recorded amounts to auditor expectations. They are used in planning to understand
the client’s business and industry. They are used throughout the audit to identify
possible misstatements, reduce detailed tests,
and to assess going-concern issues.<br>
slide43. End of Chapter 8<br>
slide2. Learning Objective 1 Discuss why adequate audit
planning is essential.<br>
slide3. Planning The work is to be adequately planned, and
assistants, if any, are to be properly supervised. Acceptable audit risk Inherent risk<br>
slide4. Planning an Audit and Designing an Approach Accept client and
perform initial
audit planning Understand the
client’s business
and industry Assess client
business risk Perform preliminary
analytical procedures<br>
slide5. Planning an Audit and Designing an Approach Set materiality, and
assess acceptable audit
risk and inherent risk Understand internal
control and assess
control risk Develop overall
audit plan and
audit program<br>
slide6. Learning Objective 2 Make client acceptance
decisions and perform
initial audit planning.<br>
slide7. Initial Audit Planning Should the auditor accept a new client? Identify why the client wants or needs an audit. Obtain an understanding with the client. Select staff for the engagement.<br>
slide8. Learning Objective 3 Gain an understanding of the
client’s business and industry.<br>
slide9. Understanding of the Client’s Business and Industry Understand Client’s Business and Industry Industry and External Environment Business Operations and Processes Management and Governance Objectives and Strategies Measurement and Performance<br>
slide10. Understanding of the Client’s Business and Industry What are some factors that have increased
the importance of understanding the
client’s business and industry? Information
technology Global
operations Human
capital<br>
slide11. Industry and External Environment What are some reasons for obtaining an
understanding of the client’s industry
and external environment? Risks associated with specific industries Inherent risks common to all
clients in certain industries Unique accounting requirements<br>
slide12. Business Operations and Processes Factors the auditor should understand: – major sources of revenue – sources of revenue – key customers and suppliers – sources of financing – information about related parties – ability to obtain financing<br>
slide13. Management and Governance Management establishes the strategies and
processes followed by the client’s business. Governance includes the client’s organizational
structure, as well as the activities of the board
of directors and the audit committee. Corporate charter and bylaws Minutes of meetings<br>
slide14. Client Objectives and Strategies Strategies are approaches followed by the
entity to achieve organizational objectives. Auditors should understand client objectives. Financial
reporting
reliability Effectiveness
and efficiency
of operations Compliance
with laws and
regulations<br>
slide15. Measurement and Performance The client’s performance measurement system
includes key performance indicators. Examples: Performance measurement includes ratio analysis
and benchmarking against key competitors. – market share – sales per employee – unit sales growth – Web site visitors – same-store sales – sales/square foot<br>
slide16. Learning Objective 4 Assess client business risk.<br>
slide17. Assess Client Business Risk Client business risk is the risk that the
client will fail to achieve its objectives. What is the auditor’s primary concern? – material misstatement of the financial
statements due to client business risk<br>
slide18. The Client’s Business, Risk, and Auditor’s Risk Assessment Industry and External Environment Business Operations and Processes Management and Governance Objectives and Strategies Measurement and Performance Understand Client’s
Business and Industry Assess Client
Business Risk Assess Risk of
Material Misstatements<br>
slide19. Learning Objective 5 Perform preliminary
analytical procedures.<br>
slide20. Preliminary Analytical Procedures Comparison of client ratios to industry
or competitor benchmarks provides an
indication of the company’s performance. Analytical procedures are also an important
part of testing throughout the audit.<br>
slide21. Examples of Planning Analytical Procedures Client Industry Short-Term Debt-Paying Ability
Current ratio Liquidity Activity Ratio
Inventory turnover Ability to Meet Long-Term Obligations
Debt to equity Profitability
Return on assets 3.86 5.20 3.46 5.20 1.73 2.51 0.09 0.09 Selected Ratios<br>
slide22. Summary of the Purposes of Auditing Planning A major purpose is to gain an understanding
of the client’s business and industry.<br>
slide23. Key Parts of Planning Accept Client and Perform
Initial Planning New client
acceptance and
continuance Identify client’s
reasons for
the audit Obtain an
understanding
with client Staff the
engagement<br>
slide24. Key Parts of Planning Understand the Client’s
Business and Industry Understand
client’s industry
and external
environment Understand
client’s operations,
strategies, and
performance system<br>
slide25. Key Parts of Planning Assess Client
Business Risk Assess client
business risk Evaluate management
business controls
affecting business risk Assess risk
of material
misstatements<br>
slide26. Key Parts of Planning Perform Preliminary
Analytical Procedures<br>
slide27. Learning Objective 6 State the purposes of analytical
procedures and the timing of
each purpose.<br>
slide28. Analytical Procedures Analytical procedures use comparisons and
relationships to assess whether account
balances or other data appear reasonable. SAS 56 emphasizes the expectations
developed by the auditor.<br>
slide29. Timing and Purpose of Analytical Procedures (Required)
Planning Phase Purpose Understand client’s
industry and business Assess going concern Indicate possible misstatements
(attention directing) Reduce detailed tests Primary purpose Secondary purpose Primary purpose Secondary purpose<br>
slide30. Timing and Purpose of Analytical Procedures Testing
Phase Purpose Understand client’s
industry and business Assess going concern Indicate possible misstatements
(attention directing) Reduce detailed tests Secondary purpose Primary purpose<br>
slide31. Timing and Purpose of Analytical Procedures (Required)
Completion Phase Purpose Understand client’s
industry and business Access going concern Indicate possible misstatements
(attention directing) Reduce detailed tests Secondary purpose Primary purpose<br>
slide32. Learning Objective 7 Select the most appropriate
analytical procedure from
among the five major types.<br>
slide33. Five Major Types of Analytical Procedures Compare client and industry data.
Compare client data with similar prior-period data.
Compare client data with client-determined expected results.
Compare client data with auditor-determined expected results.
Compare client data with expected results, using nonfinancial data.<br>
slide34. Compare Client and Industry Data Client Industry
2002 2001 2002 2001
Inventory turnover 3.4 3.5 3.9 3.4
Gross margin percent 26.3% 26.4% 27.3% 26.2%<br>
slide35. Compare Client Data With Similar Prior-period Data 2002 2001
(000,000) % of (000,000) % of
Preliminary Net Sales Audited Net Sales
Net sales 143 100 131 100
Cost of goods sold 103 72 95 72
Gross profit 40 28 36 28
S & A 32 22 30 23
Other 4 3 3 3
Net income 4 3 3 2<br>
slide36. Learning Objective 8 Compute common
financial ratios.<br>
slide37. Common Financial Ratios Short-term debt-paying ability Liquidity activity ratios Ability to meet long-term debt obligations Profitability ratios<br>
slide38. Short-term Debt-paying Ability Cash ratio:
(Cash + Marketable securities) ÷ Current liabilities Quick ratio:
(Cash + Marketable securities
+ Net accounts receivable) ÷ Current liabilities Current ratio:
Current assets ÷ Current liabilities<br>
slide39. Liquidity Activity Ratios Accounts receivable turnover:
Net sales ÷ Average gross receivables Days to collect receivables:
365 days ÷ Accounts receivable turnover Inventory turnover:
Cost of goods sold ÷ Average inventory<br>
slide40. Liquidity Activity Ratios Days to sell inventory:
365 days ÷ inventory turnover<br>
slide41. Ability to Meet Long-term Debt Obligation Debt to equity:
Total liabilities ÷ Total equity Times interest earned:
Operating income ÷ Interest expense<br>
slide42. Summary of Analytical Procedures They involve the computation of ratios and other
comparisons of recorded amounts to auditor expectations. They are used in planning to understand
the client’s business and industry. They are used throughout the audit to identify
possible misstatements, reduce detailed tests,
and to assess going-concern issues.<br>
slide43. End of Chapter 8<br>