
Build A Bear Workshop, Inc. (NYSE: BBW) NDIC –
TD
Published · 23 slides · 0 views
1 / 1
Description
Build A Bear Workshop, Inc. (NYSE: BBW) NDIC February 20th, 2020 Zach Margovskiy, Alejandro Perez Elorza Arce, Chris Clinton Which Company Does Not Belong? 2 Investment Thesis Recommendation: Given Build a Bears (NYSE:BBW) unique
Related Topics
Share
Embed code
Download this presentation From Below
"Build A Bear Workshop, Inc. (NYSE: BBW) NDIC –" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Build A Bear Workshop, Inc. (NYSE: BBW)
NDIC – February 20th, 2020
Zach Margovskiy, Alejandro Perez Elorza Arce, Chris Clinton<br>
02
Which Company Does Not Belong? 2<br>
03
Investment Thesis Recommendation: Given Build a Bear’s (NYSE:BBW) unique experience in the toy industry, their potential for strategic partnerships, and their undervalued brand equity, it offers a very attractive equity investment opportunity with substantial 3 year upside; we recommend a buy at this time
Rationale
Given Build a Bear’s experiential retail, they are well poised to survive the retail apocalypse, with their future strategic partnerships, and their undervalued brand equity, we believe that the market is discounting them too negatively--BBW offers a very attractive equity investment opportunity with substantial multiyear upside, they are therefore we recommend a buy at this time
1 Retail as an experience: More than a product
2 Exploiting strategic partnerships
3 Strong brand equity & high customer awareness
The Brands Moms Trust and Kids Love
“You don’t go to build a bear just for a stuffed animal, you go for an experience”- Anonymous 3 Final Price Target:
$5.57
Upside: 26.59%<br>
04
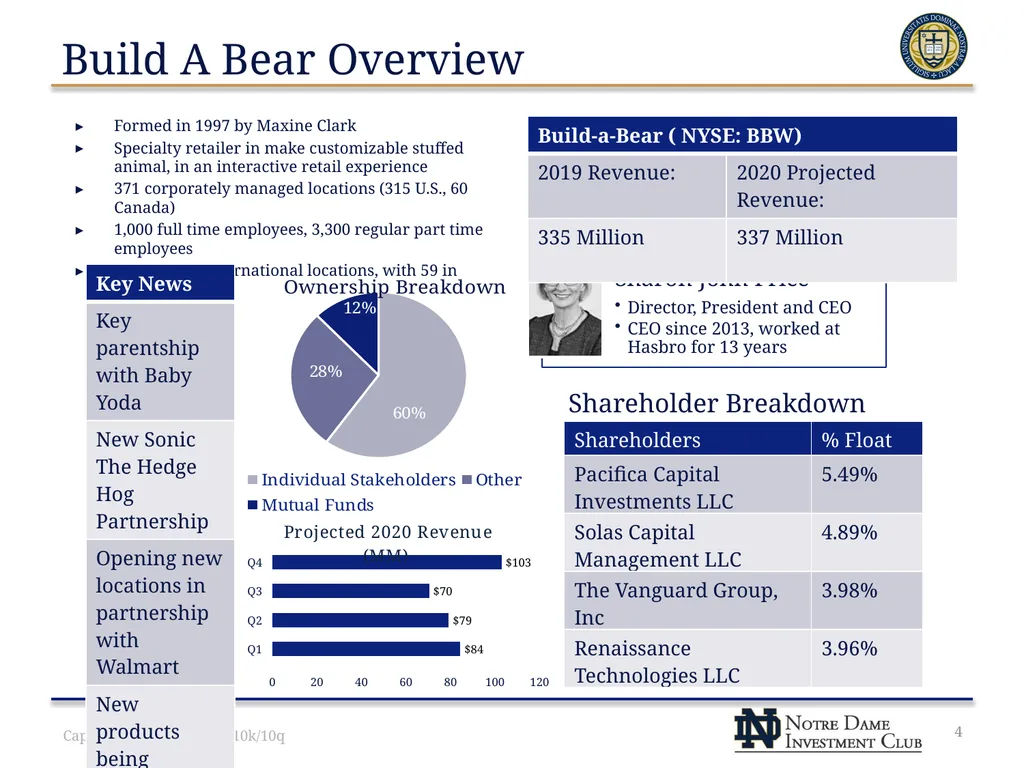
Build A Bear Overview Formed in 1997 by Maxine Clark
Specialty retailer in make customizable stuffed animal, in an interactive retail experience
371 corporately managed locations (315 U.S., 60 Canada)
1,000 full time employees, 3,300 regular part time employees
Total of 104 international locations, with 59 in Europe 4 Cap IQ, Bloomberg, BBW 10k/10q Shareholder Breakdown<br>
05
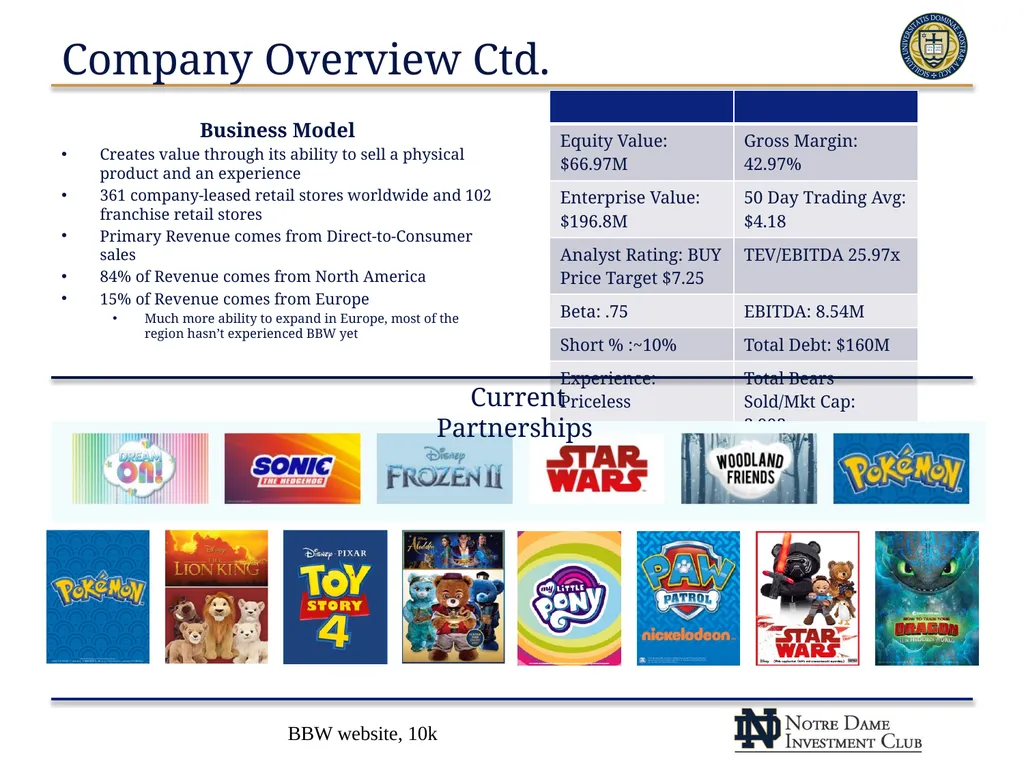
Company Overview Ctd. BBW website, 10k Business Model
Creates value through its ability to sell a physical product and an experience
361 company-leased retail stores worldwide and 102 franchise retail stores
Primary Revenue comes from Direct-to-Consumer sales
84% of Revenue comes from North America
15% of Revenue comes from Europe
Much more ability to expand in Europe, most of the region hasn’t experienced BBW yet Current Partnerships<br>
06
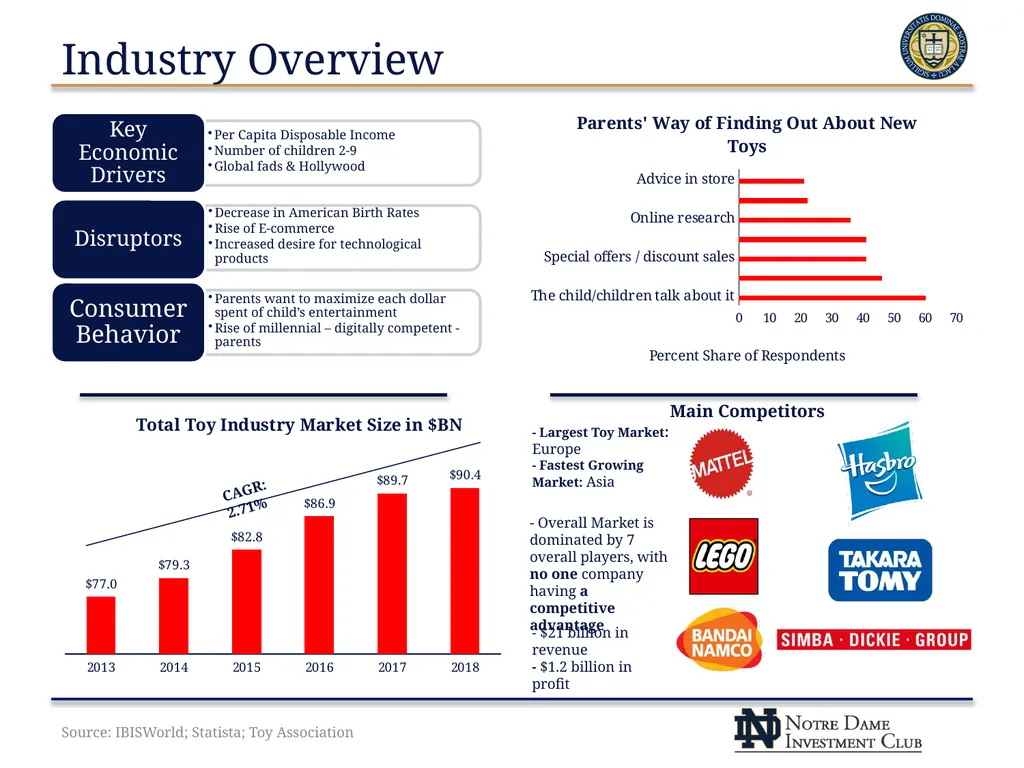
Industry Overview Source: IBISWorld; Statista; Toy Association Main Competitors CAGR: 2.71% - Largest Toy Market: Europe
- Fastest Growing Market: Asia - Overall Market is dominated by 7 overall players, with no one company having a competitive advantage - $21 billion in revenue
- $1.2 billion in profit<br>
- Fastest Growing Market: Asia - Overall Market is dominated by 7 overall players, with no one company having a competitive advantage - $21 billion in revenue
- $1.2 billion in profit<br>
07
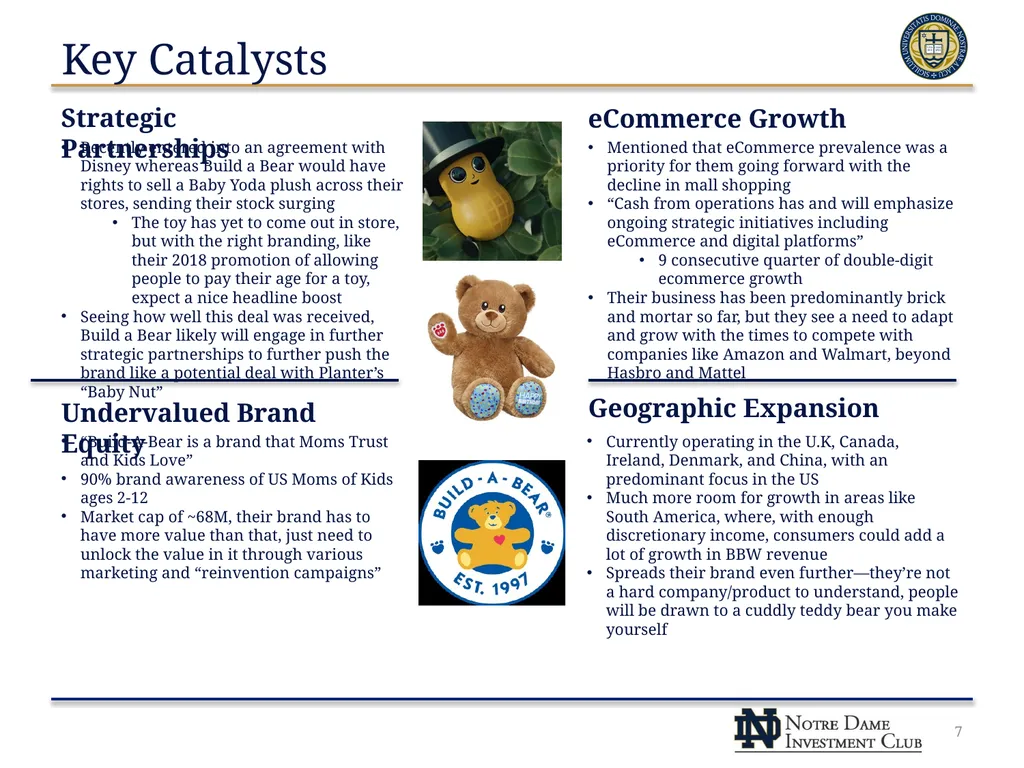
Key Catalysts 7 Recently entered into an agreement with Disney whereas Build a Bear would have rights to sell a Baby Yoda plush across their stores, sending their stock surging
The toy has yet to come out in store, but with the right branding, like their 2018 promotion of allowing people to pay their age for a toy, expect a nice headline boost
Seeing how well this deal was received, Build a Bear likely will engage in further strategic partnerships to further push the brand like a potential deal with Planter’s “Baby Nut” Mentioned that eCommerce prevalence was a priority for them going forward with the decline in mall shopping
“Cash from operations has and will emphasize ongoing strategic initiatives including eCommerce and digital platforms”
9 consecutive quarter of double-digit ecommerce growth
Their business has been predominantly brick and mortar so far, but they see a need to adapt and grow with the times to compete with companies like Amazon and Walmart, beyond Hasbro and Mattel “Build-A-Bear is a brand that Moms Trust and Kids Love”
90% brand awareness of US Moms of Kids ages 2-12
Market cap of ~68M, their brand has to have more value than that, just need to unlock the value in it through various marketing and “reinvention campaigns” Currently operating in the U.K, Canada, Ireland, Denmark, and China, with an predominant focus in the US
Much more room for growth in areas like South America, where, with enough discretionary income, consumers could add a lot of growth in BBW revenue
Spreads their brand even further—they’re not a hard company/product to understand, people will be drawn to a cuddly teddy bear you make yourself Strategic Partnerships eCommerce Growth Undervalued Brand Equity Geographic Expansion<br>
08
Advantages to firm/undervalued brand They’re a safe company in the prevailing doom of retail
BBW doesn’t sell you just a bear, you can get that anywhere—the message is that they allow you to build something with your own hands with your kid
They’re taking steps to monetize their brand assets through their excess cash through more advertising
Since they have no long-term debt—all just short term leases, if they see an emerging trend or future growth in a sector, they can capitalize on it immediately
Their goal is to deliver long-term sustainable profitable growth
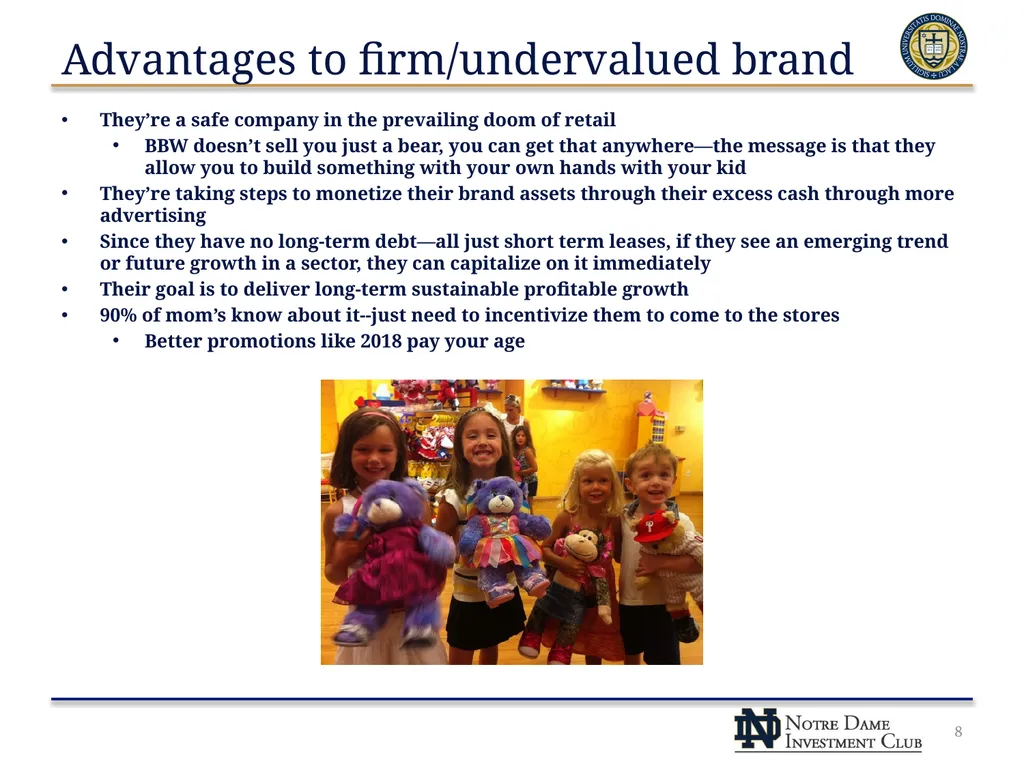
90% of mom’s know about it--just need to incentivize them to come to the stores
Better promotions like 2018 pay your age 8<br>
09
The Build A Bear Experience Build a Bear Offers More Than A Toy
7 Step Experience
Ability to choose your new friend
Options range from superhero to mascot to animal
Ability to add sound effects
Ability to customize you new friend
Option to choose their sounds, scents, stuffing, and special hear
First Hug
Have the opportunity to hug your friend for the first time to make sure his stuffing in just right
Ability to dress your new friend
Choose from a variety of outfits and accessories
Name your new friend
The first time you build a personal connection with your furry friend
Take your new friend home
Make memories forever Why this Matters
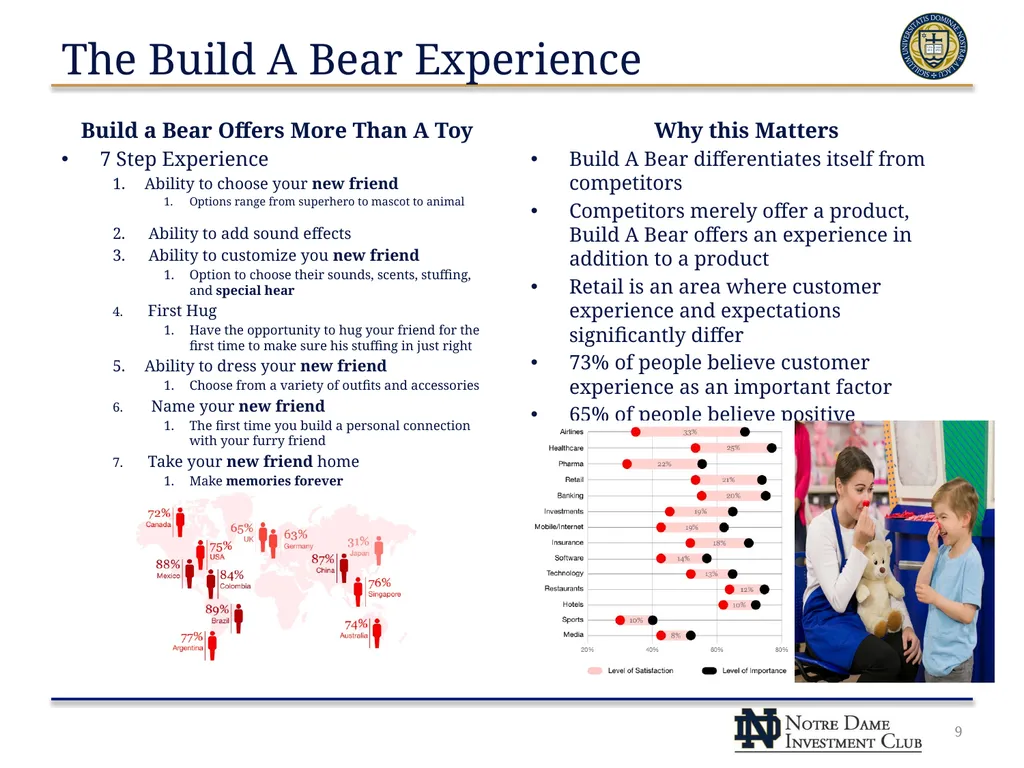
Build A Bear differentiates itself from competitors
Competitors merely offer a product, Build A Bear offers an experience in addition to a product
Retail is an area where customer experience and expectations significantly differ
73% of people believe customer experience as an important factor
65% of people believe positive experience is more influential than great advertising
You cannot offer an experience via e-commerce 9<br>
10
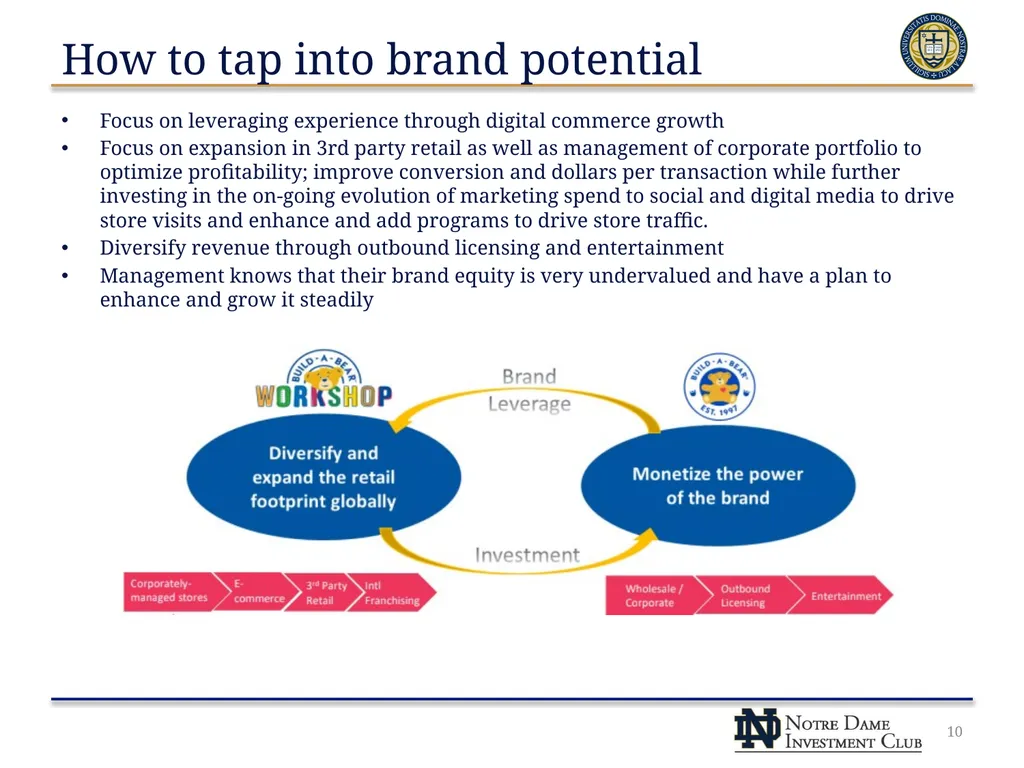
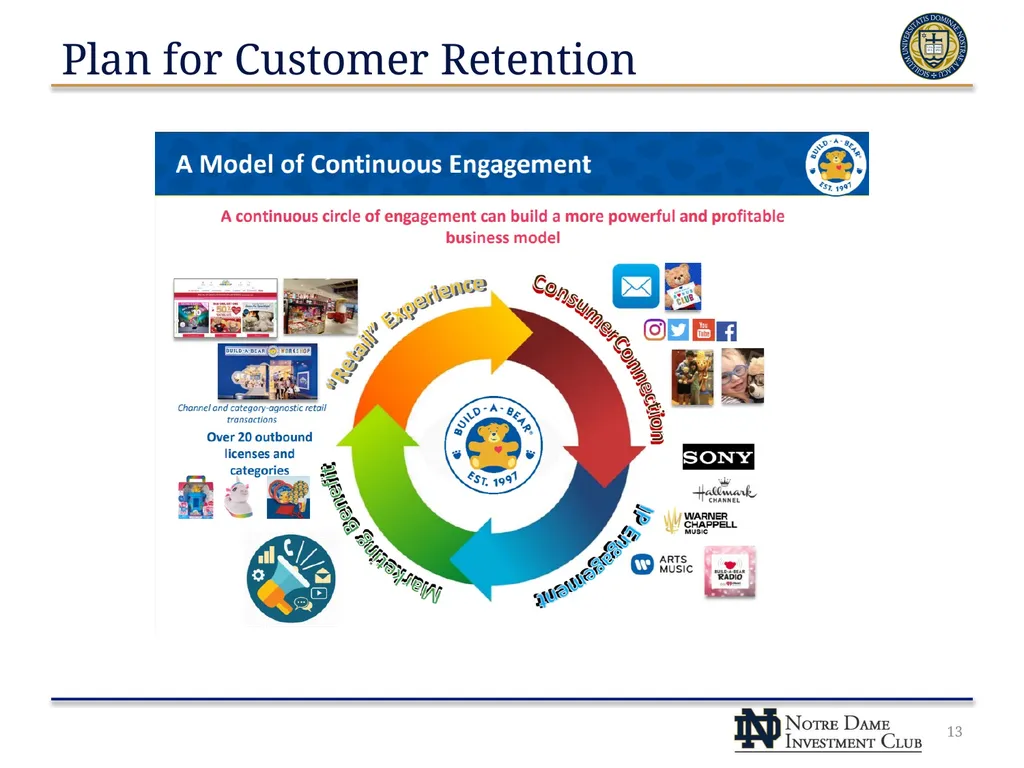
How to tap into brand potential Focus on leveraging experience through digital commerce growth
Focus on expansion in 3rd party retail as well as management of corporate portfolio to optimize profitability; improve conversion and dollars per transaction while further investing in the on-going evolution of marketing spend to social and digital media to drive store visits and enhance and add programs to drive store traffic.
Diversify revenue through outbound licensing and entertainment
Management knows that their brand equity is very undervalued and have a plan to enhance and grow it steadily 10<br>
11
eCommerce and Digital plan 11 Expect to leverage trends to online
shopping as well as our own current
momentum to continue to fuel growth
• Focus on secondary store segments of
gift givers and affinity that prefer to
shop online has driven growth without
cannibalizing traditional retail
• Opportunity to expand adult
gifting merchandise categories
• Affinity segments connect with
limited and web-exclusive products
• Expect to expand omni-channel model • Continue to refine digital marketing Expect to leverage rich data from
engaged Bonus Club membership to
drive incremental purchases
• Over 7 million total Bonus Club
members and 8 million opted-in
email accounts for marketing
• Opportunity to further develop
segmentation and consumer
journey models
• Implementation of enhanced site
features to personalize offers and
drive traffic and productivity Opportunity to grow with third party
marketplaces (e.g. Amazon) as well as
primary store shopping segment
(families with children)
• Prime certified, branded shopfront
on Amazon.com starting to deliver
revenue growth
• Opportunity to add innovative digital
shopping experiences to engage
consumers seeking experience (over
convenience)<br>
12
What is the Market missing? Build a Bear is not a typical brick and mortar toy retailer—they’re different and it offers them a path for survival unlike Macy’s or JC Penny
Believe in the experience, buying a toy in a plastic box off of a shelf is no replacement for building it with your own hands with your children—this is a product that can’t really be replicated because it’s so well known
They have options for turning around or looking for strategic alternatives, their brand has more embedded value in it than the market prices in, they just really need to tap into it
They have no immediate competitor—there is no prevailing Nordstrom out there 12 There is a have turnaround plan in place; management has talked about an aggressive digital first approach including:
Shifting to Bonus club activation, personalized gifting, and much more licensed products
95% of managed stores have positive four-wall contribution, they’re doing okay overall
With 70% of their stores having options for leases in the next three years, changes to more profitable locations can and will easily be had
BBW does not deserve to be relegated to the dog house with the rest of retail This store is Amazon impervious, the value of BBW is not the goods, it’s the experience and Amazon can’t take that away, plus they have no real competitors in the space
Analysts have been so negative on the company for so long that all they have to do is mildly surprise and their stock should have a relief rally
Plus, even just their name and logo is worth more than ~$68 Million, they’ve completely penetrated and dominated the market<br>
13
Plan for Customer Retention 13<br>
14
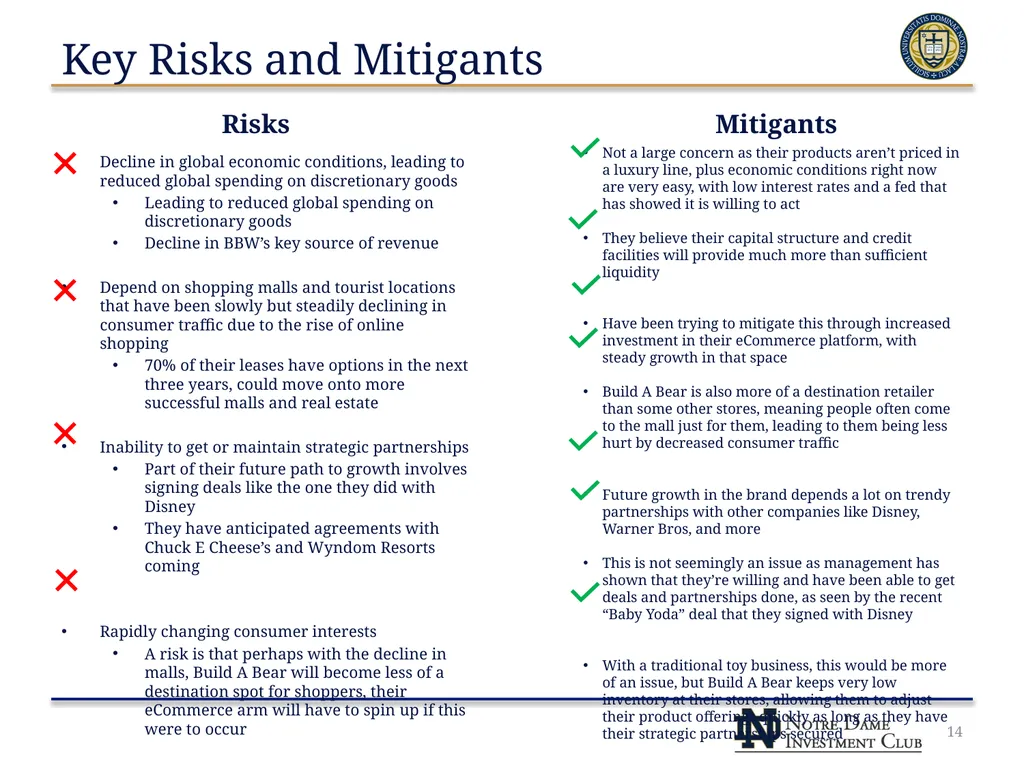
Key Risks and Mitigants Decline in global economic conditions, leading to reduced global spending on discretionary goods
Leading to reduced global spending on discretionary goods
Decline in BBW’s key source of revenue
Depend on shopping malls and tourist locations that have been slowly but steadily declining in consumer traffic due to the rise of online shopping
70% of their leases have options in the next three years, could move onto more successful malls and real estate
Inability to get or maintain strategic partnerships
Part of their future path to growth involves signing deals like the one they did with Disney
They have anticipated agreements with Chuck E Cheese’s and Wyndom Resorts coming
Rapidly changing consumer interests
A risk is that perhaps with the decline in malls, Build A Bear will become less of a destination spot for shoppers, their eCommerce arm will have to spin up if this were to occur 14 Not a large concern as their products aren’t priced in a luxury line, plus economic conditions right now are very easy, with low interest rates and a fed that has showed it is willing to act
They believe their capital structure and credit facilities will provide much more than sufficient liquidity
Have been trying to mitigate this through increased investment in their eCommerce platform, with steady growth in that space
Build A Bear is also more of a destination retailer than some other stores, meaning people often come to the mall just for them, leading to them being less hurt by decreased consumer traffic
Future growth in the brand depends a lot on trendy partnerships with other companies like Disney, Warner Bros, and more
This is not seemingly an issue as management has shown that they’re willing and have been able to get deals and partnerships done, as seen by the recent “Baby Yoda” deal that they signed with Disney
With a traditional toy business, this would be more of an issue, but Build A Bear keeps very low inventory at their stores, allowing them to adjust their product offerings quickly as long as they have their strategic partnerships secured Risks Mitigants<br>
15
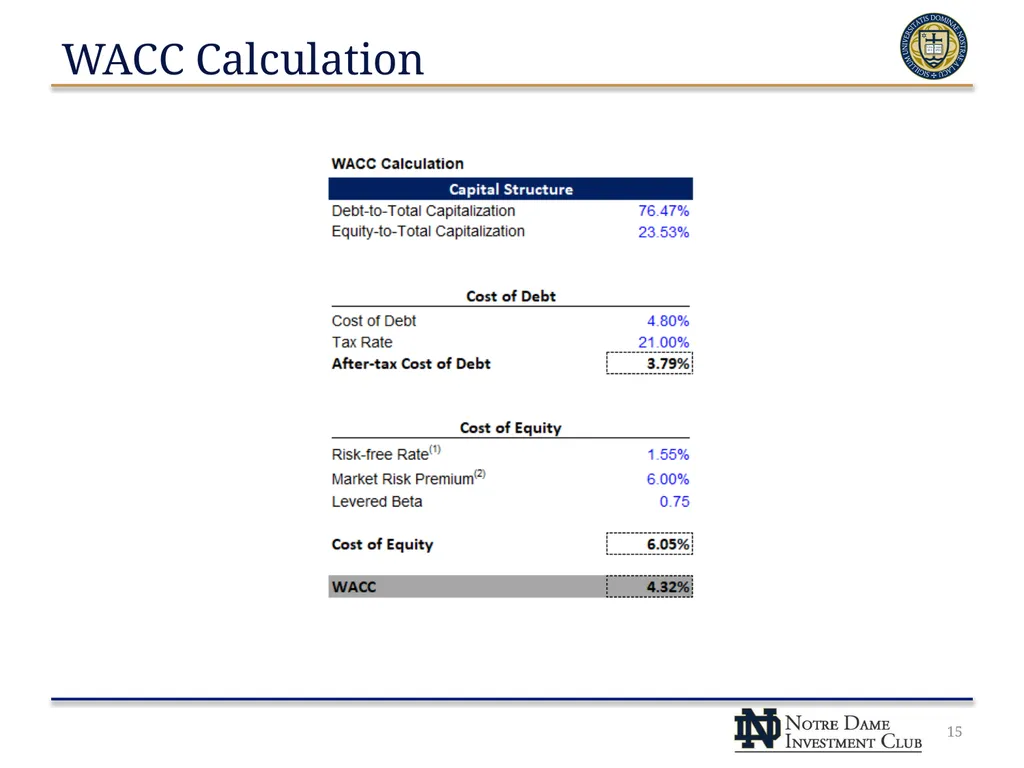
WACC Calculation 15<br>
16
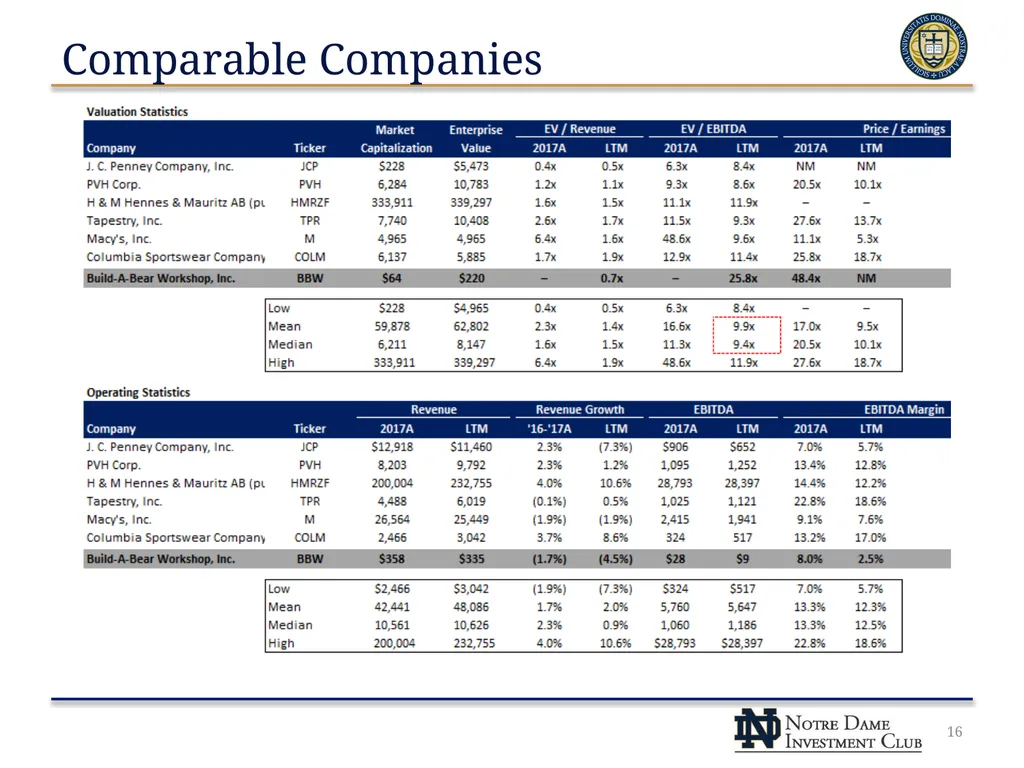
Comparable Companies 16<br>
17
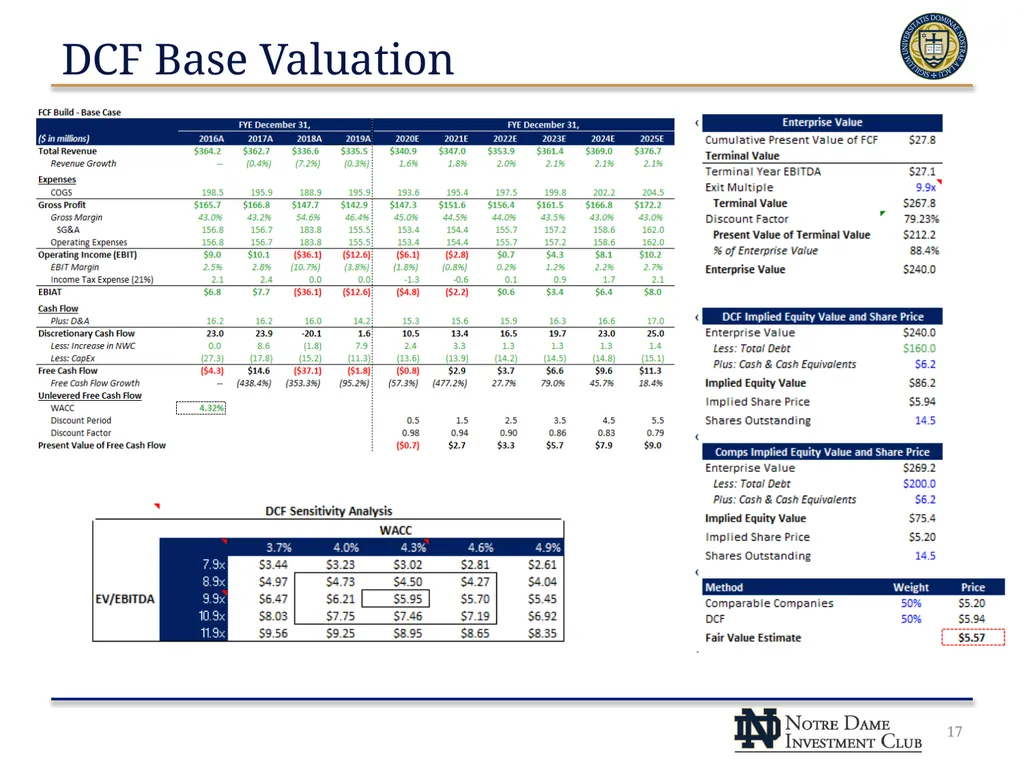
DCF Base Valuation 17<br>
18
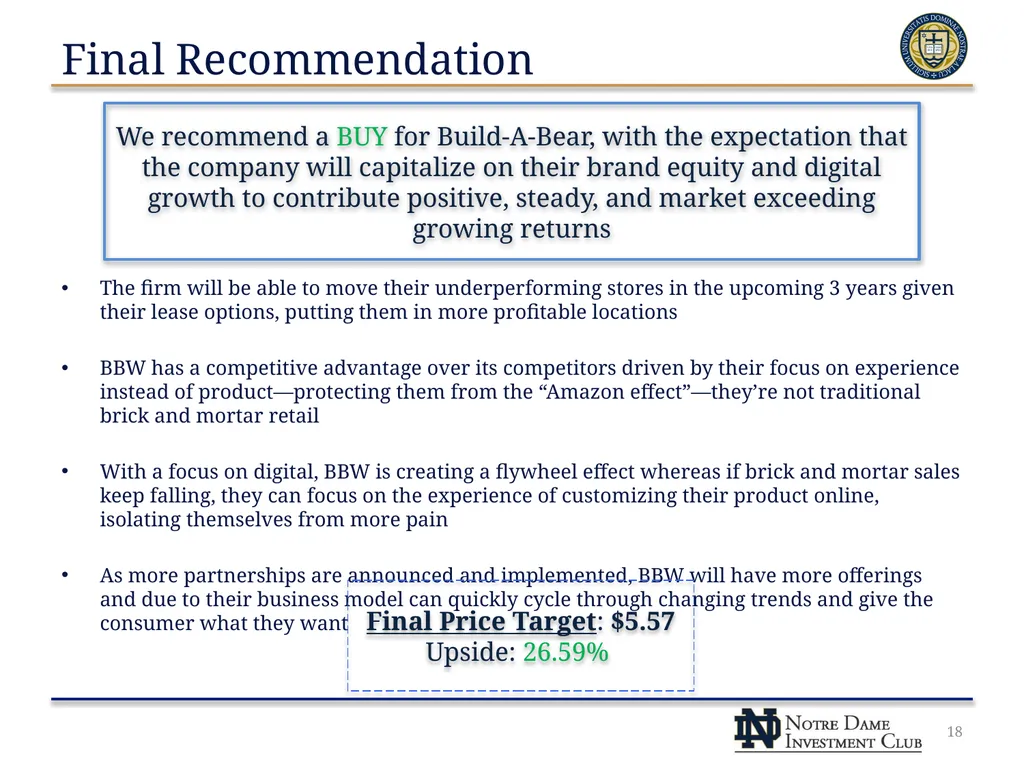
Final Recommendation The firm will be able to move their underperforming stores in the upcoming 3 years given their lease options, putting them in more profitable locations
BBW has a competitive advantage over its competitors driven by their focus on experience instead of product—protecting them from the “Amazon effect”—they’re not traditional brick and mortar retail
With a focus on digital, BBW is creating a flywheel effect whereas if brick and mortar sales keep falling, they can focus on the experience of customizing their product online, isolating themselves from more pain
As more partnerships are announced and implemented, BBW will have more offerings and due to their business model can quickly cycle through changing trends and give the consumer what they want 18 We recommend a BUY for Build-A-Bear, with the expectation that the company will capitalize on their brand equity and digital growth to contribute positive, steady, and market exceeding growing returns Final Price Target: $5.57
Upside: 26.59%<br>
19
Appendix 19<br>
20
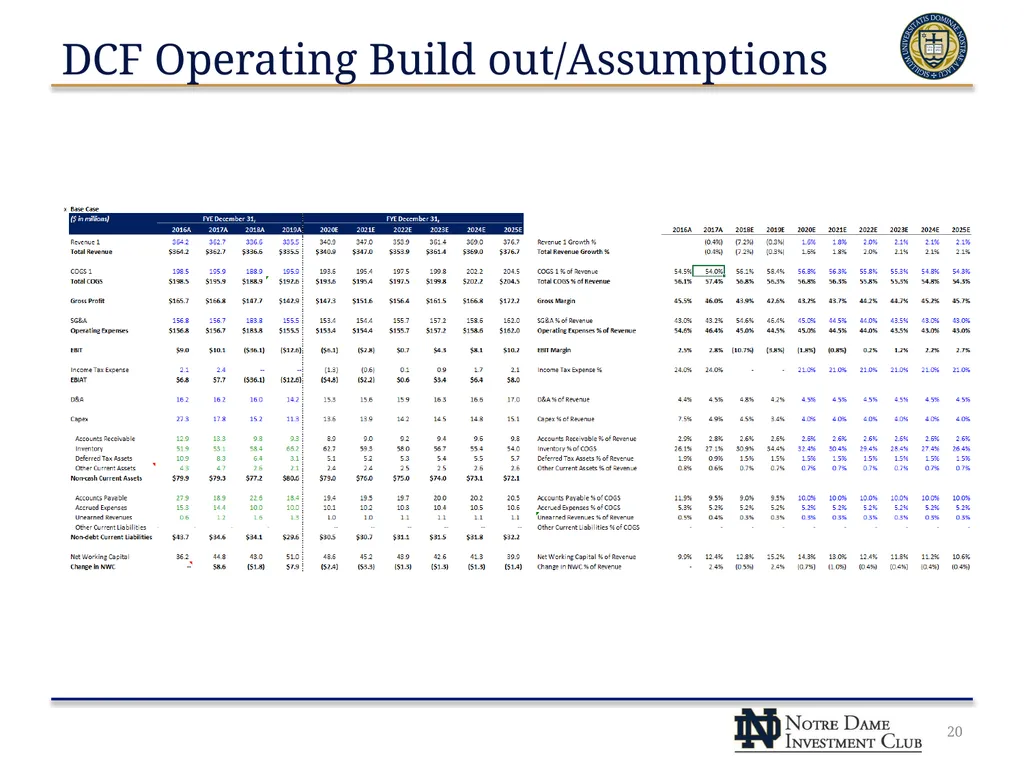
DCF Operating Build out/Assumptions 20<br>
21
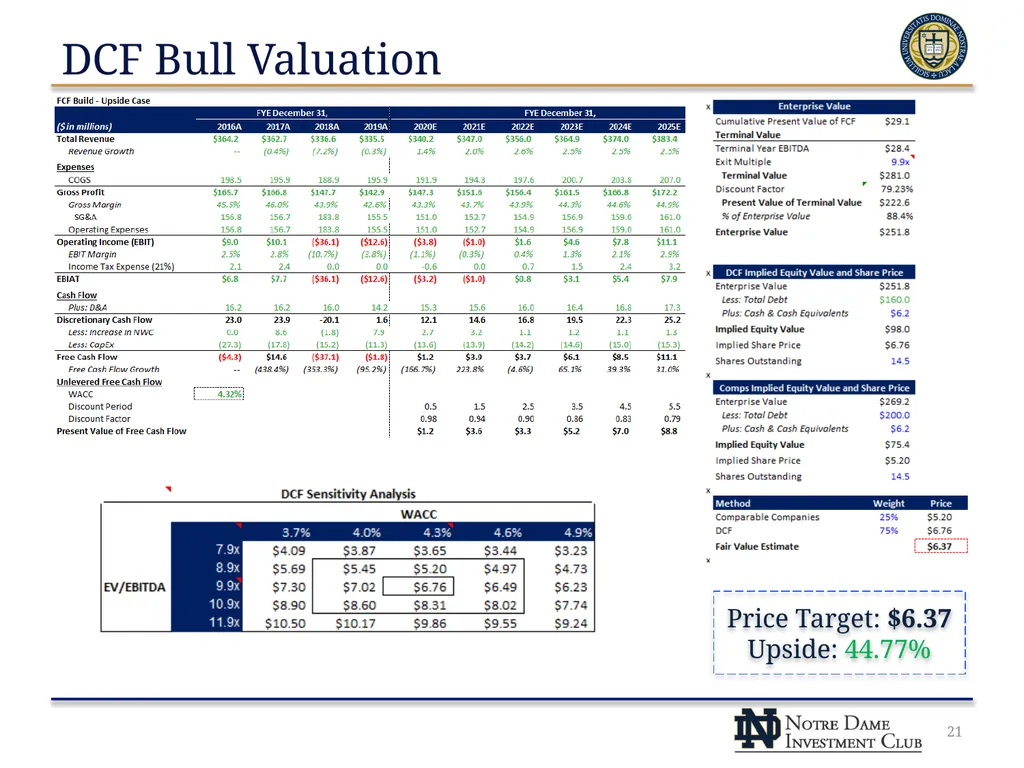
DCF Bull Valuation 21 Price Target: $6.37
Upside: 44.77%<br>
Upside: 44.77%<br>
22
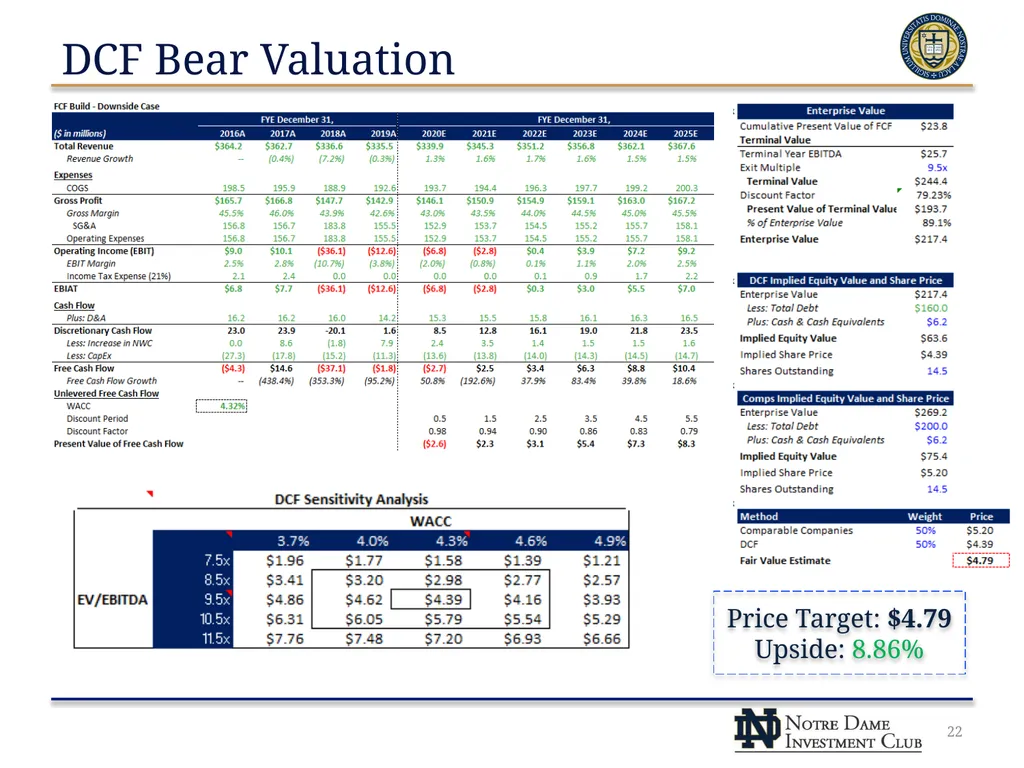
DCF Bear Valuation 22 Price Target: $4.79
Upside: 8.86%<br>
Upside: 8.86%<br>
23
23 Questions?<br>