
Calcutta Club case - GST implications & Important
AS
Published · 65 slides · 0 views

1 / 1










Description
Calcutta Club case - GST implications Important Judicial Pronouncements in GST CA V.Raghuraman, Advocate Supreme Court decision in Calcutta Club on mutuality LANDMARK DECISION ON APPLICABILITY OF MUTUALITY IN INDIRECT TAX Mutuality
Related Topics
Share
Embed code
Download this presentation From Below
"Calcutta Club case - GST implications & Important" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Calcutta Club case - GST implications
&
Important Judicial Pronouncements in GST CA V.Raghuraman,
Advocate<br>
Advocate<br>
02
Supreme Court decision in Calcutta Club on mutuality LANDMARK DECISION ON APPLICABILITY OF MUTUALITY IN INDIRECT TAX<br>
03
Mutuality – Concept and Meaning: “No man, in my opinion, can trade with himself; he cannot, in my opinion, make, in what is its true sense or meaning, taxable profit by dealing with himself”. [Dublin Corporation vs. M'Adam (Surveyor of Taxes), (1887) 2 Tax Cas. 387 (D)]
“The true construction of the Rules is that the members were the joint owners of the general property in all the goods of the club, and that the trustees were their agents with respect to the general property in the goods.” [Graff v. Evans (1882) 8 QBD 373]
When a number of individuals agree to contribute funds for a common purpose, such as the payment of annuities or of capital sums, to some or all of them, on the occurrence of events, certain or uncertain, and stipulate that their contributions, so far as not required for that purpose, shall be repaid to them, neither can they be regarded as ‘traders’ nor can the surplus returned to the members be called ‘profits’. [Styles v. New York Life Insurance Co. [1889] 2 TC 460 (HL)]<br>
04
Larger Bench of Supreme Court in State of WB vs Calcutta Club 2019-TIOL-449-SC-ST-LB Whether clubs having no shareholders, dividends declaration and distribution of profits can be treated as separate in law from their members?
Held:
If persons carry on a certain activity in such a way that there is a commonality between contributors of funds and participators in the activity, a complete identity between the two is then established.
This identity is not snapped because the surplus that arising from the common fund is not distributed among the members. It is enough that there is a right of disposal over the surplus, and in exercise of that right they may agree that on winding up, the surplus will be transferred to a club or association with similar activities.
Further, the surplus that is made does not come back to the members of the club as shareholders of a company in the form of dividends upon their shares. Since the members perform the activities of the club for themselves, the fact that they incorporate a legal entity to do it for them makes no difference.
What is of essence, therefore, in applying this doctrine is that there is no sale transaction between two persons, as one person cannot sell goods to itself.<br>
05
CTO Vs Young Men's Indian Association (1970) 1 SCC 462 The Respondent-Association challenged levy of sales tax for supplying snacks, beverages and other articles to their members or guests.
Held:
If there is no transfer of property from one person to another person, there is no sale which could be exigible to tax.
The Club, even though a distinct legal entity, only acts as agent of its members in the matter of supply of various preparations to its members. Therefore, no sale is involved as element of transfer of property is absent.
Club does not transfer property belonging to it to its members. Instead, it acts as an agent of its members by making available property belonging to its members.
There could be no sale as the member could not be regarded as vendor as well as purchaser.<br>
06
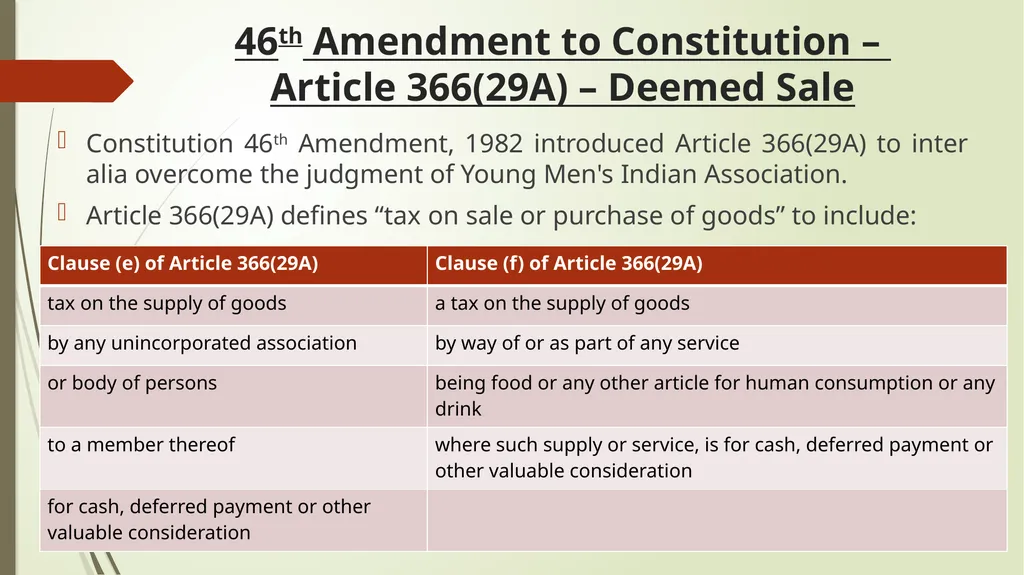
46th Amendment to Constitution –
Article 366(29A) – Deemed Sale Constitution 46th Amendment, 1982 introduced Article 366(29A) to inter alia overcome the judgment of Young Men's Indian Association.
Article 366(29A) defines “tax on sale or purchase of goods” to include:<br>
Article 366(29A) defines “tax on sale or purchase of goods” to include:<br>
07
Reference to Larger Bench in State of WB vs Calcutta Club 2019-TIOL-449-SC-ST-LB Whether Constitution 46th Amendment has done away with principles of mutuality? OR Whether the judgment in Young Men's Indian Association holds filed?
Held:
61st Law Commission Report: There cannot be said to be any evasion of tax as a member of members' clubs "really takes his own goods" and, therefore, did not seek to tax such goods.
The 46th amendment presumed that, in view of judgment in Young Men's Indian Association, only transactions between unincorporated persons and its members were not taxable. It assumed that sale of goods by members' clubs in the corporate form were taxable.
But whereas, even prior to 46th Amendment, a sale of goods by a club having a corporate status to members was not taxable.<br>
08
State of WB vs Calcutta Club 2019-TIOL-449-SC-ST-LB Whether service tax was leviable on clubs or associations prior to 2012?
Prior to 2012, “clubs or associations” was defined to include anybody established or constituted by or under any law for the time being in force.
Held:
Incorporated entities providing services to their members would be outside the service tax net prior to 1st July, 2012.
Company ‘incorporated’ under Companies Act or cooperative society registered as cooperative society under State Act is “constituted” under any law for time being in force.<br>
09
State of WB vs Calcutta Club 2019-TIOL-449-SC-ST-LB Whether service tax was leviable on clubs or associations post 2012 (i.e, in the negative list regime)?
Section 65B(44) – ‘Service’ definition requires presence of two separate persons.
Explanation 3(a) to Section 65B(44) said that an unincorporated association/BOP and a member thereof shall be treated as distinct persons.
Section 65B(37) defines ‘person’ but does not include incorporated company or cooperative society
Held:
The services by an incorporated club/association to its members would amount to service to self and hence would not qualify as a ‘service’.
Explanation 3(a), “Body of persons” may subsume persons who come together for common purpose, but it does not include company or registered cooperative society. Hence, it may be assumed that legislature has continued with pre-2012 scheme of not taxing members’ clubs when they are in incorporated form.<br>
10
State of WB vs Calcutta Club 2019-TIOL-449-SC-ST-LB Whether observations made in by SC in BSNLs case (2006) 3 SCC 1 was binding?
It was observed in the said case that:
Sub-clause (e) Article 366(29A) covers which in law may not have amounted to sale because the member of an incorporated association would have in a sense begun as both the supplier and the recipient of the supply of goods.
Sub-clause (e) of Article 366(29A) was introduced to neutralize the ruling of SC in Young Men's Indian Association.
Held:
Above observations made cannot possibly be said to form the ratio decidendi of the judgment.
It could not have possibly referred to “incorporated” associations contrary to the plain language of sub-clause (e), which refers to “unincorporated” associations.
Sub-clause (e) of Article 366(29A) had not neutralized the ruling of SC in Young Men's Indian Association.<br>
11
State of WB vs Calcutta Club 2019-TIOL-449-SC-ST-LB Whether mutuality concept could be applicable to proprietary clubs?
Held:
Reliance was placed on Cosmopolitan Club Vs State of TN (2009) 19 VST 456.
The doctrine of mutuality would not be applicable inasmuch as some of the shareholders may not be members of the club and vice versa and outsiders could well use the club.
The persons participating and persons enjoying should be the same. If not, mutuality does not exist.<br>
12
Whether Supreme Court decision in Calcutta Club applies to GST Regime? The term ‘supply’ is defined extensively in section 7 of the Act to include all forms of supply of goods or services or both, such as sale, transfer, barter, exchange, licence, rental, lease or disposal made or agreed to be made for a consideration by a person in the course or furtherance of business.
The doctrine of mutuality continues to apply even under GST. In terms of section 7 of the CGST Act, 2017, for the transaction to constitute a supply, there should be sale, barter etc. for a consideration, which requires two persons. In case of clubs, as there no two persons, there cannot be ‘supply’ of goods or services by the club to its members.
The concept of mutuality is clearly applicable under GST regime as well, hence no GST is leviable on the services provided by Club to its members.<br>
13
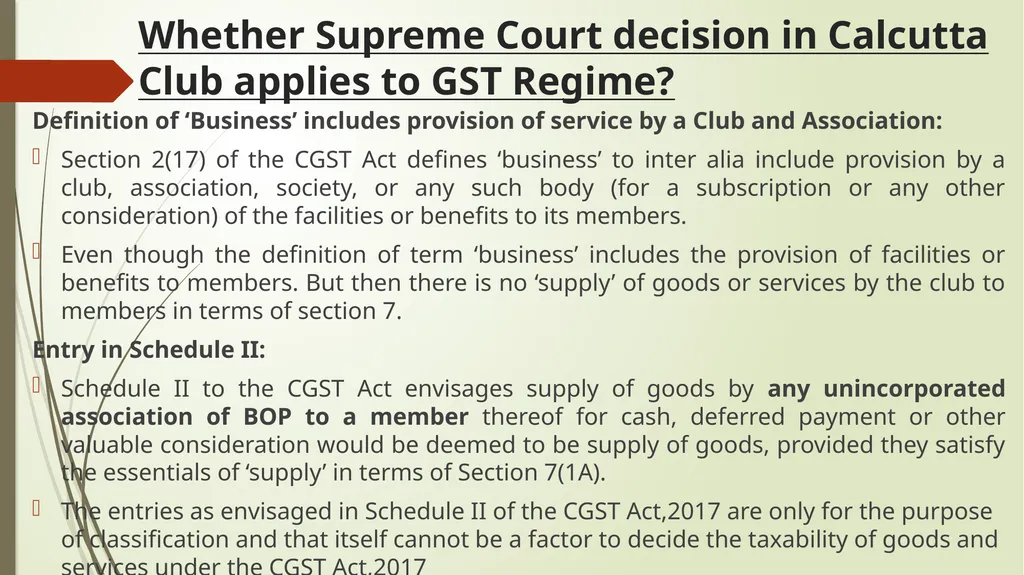
Whether Supreme Court decision in Calcutta Club applies to GST Regime? Definition of ‘Business’ includes provision of service by a Club and Association:
Section 2(17) of the CGST Act defines ‘business’ to inter alia include provision by a club, association, society, or any such body (for a subscription or any other consideration) of the facilities or benefits to its members.
Even though the definition of term ‘business’ includes the provision of facilities or benefits to members. But then there is no ‘supply’ of goods or services by the club to members in terms of section 7.
Entry in Schedule II:
Schedule II to the CGST Act envisages supply of goods by any unincorporated association of BOP to a member thereof for cash, deferred payment or other valuable consideration would be deemed to be supply of goods, provided they satisfy the essentials of ‘supply’ in terms of Section 7(1A).
The entries as envisaged in Schedule II of the CGST Act,2017 are only for the purpose of classification and that itself cannot be a factor to decide the taxability of goods and services under the CGST Act,2017<br>
14
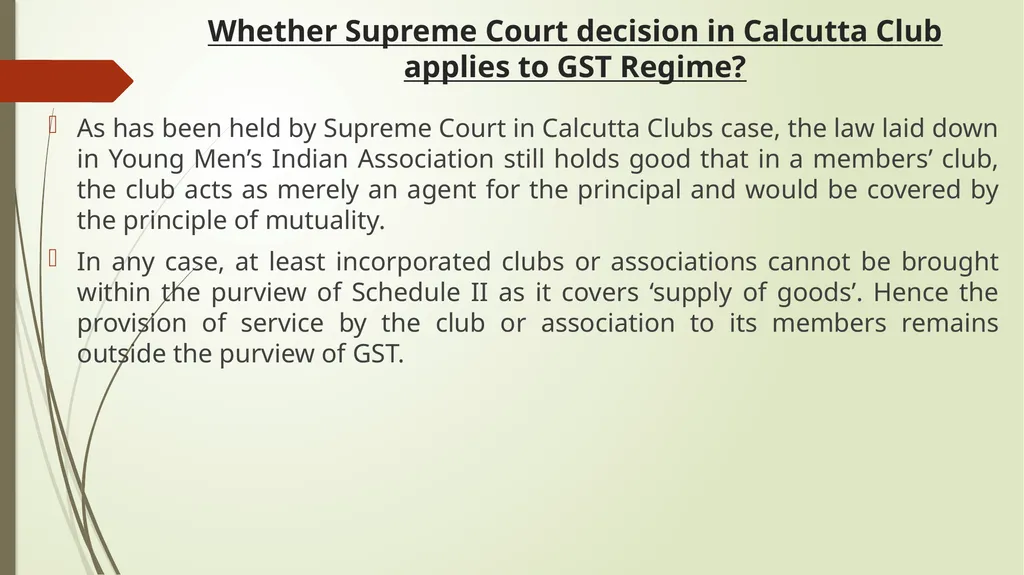
Whether Supreme Court decision in Calcutta Club applies to GST Regime? As has been held by Supreme Court in Calcutta Clubs case, the law laid down in Young Men’s Indian Association still holds good that in a members’ club, the club acts as merely an agent for the principal and would be covered by the principle of mutuality.
In any case, at least incorporated clubs or associations cannot be brought within the purview of Schedule II as it covers ‘supply of goods’. Hence the provision of service by the club or association to its members remains outside the purview of GST.<br>
In any case, at least incorporated clubs or associations cannot be brought within the purview of Schedule II as it covers ‘supply of goods’. Hence the provision of service by the club or association to its members remains outside the purview of GST.<br>
15
Important judicial decisions in GST<br>
16
Transitional issues under GST<br>
17
M/s. Siddharath Enterprises Vs The Nodal Officer 2019-TIOL-2068-HC-AHM-GST The applicants were unable to file Form GST Tran-1 on account of technical glitches in terms of poor net connectivity and other technical difficulties on the common portal and they were unable to carry forward the credit in terms of Section 140(3) of the CGST Act, 2017.
Held:
Restriction of one year time limit to avail the credit in terms of Section 140(3)(iv) is irrational: The benefit of credit of eligible duties on the purchases made by the first stage dealer as per the then existing CENVAT credit rules was a vested right. By virtue of section 140(3)(iv), such right has been taken away with retrospective effect in relation to only those goods which were purchased prior to one year from the appointed day. The condition imposed with retrospective effect has no rational basis.
The denial of carry forward of credit, leads to cascading effect of tax: The right to carry forward of cenvat credit for non-filing of Tran-1 would offend the policy of the Government to remove the cascading effect of tax as mentioned in the ‘Objects and Reasons of the Constitution 122nd Amendment Bill, 2014’ clearly set out that it is intended to remove the cascading effect of taxes and to bring out a nationwide taxation system.<br>
18
M/s. Siddharath Enterprises Vs The Nodal Officer 2019-TIOL-2068-HC-AHM-GST (Cont.) Held:
Rule 117 is violative of Article 14 of the Constitution: It is arbitrary, irrational and unreasonable to discriminate in terms of the time-limit to allow the availment of the input tax credit with respect to the purchase of goods and services made in the pre-GST regime and post-GST regime and, therefore, it is violative of Article 14 of the Constitution. Further, it was observed that disallowing the vested right is offensive against Article 14 of the Constitution as it goes against the essence of doctrine of legitimate expectation.
Rule 117 violates the mandate of Article 19(1)(g) of the Constitution: By not allowing the right to carry forward the Cenvat Credit, may severely dent the assesses working capital and may diminish their ability to continue with the business. Accordingly, such action violates the mandate of Article 19(1)(g) of the Constitution of India.
Rule 117 is violative of Article 300A of the Constitution: CENVAT credit earned under the erstwhile Central Excise Law is the property of the assessee and it cannot be appropriated for merely failing to file a declaration in the absence of Law in that respect. It could have been appropriated by the government by providing for the same in the CGST Act but it cannot be taken away by virtue of merely framing Rules in this regard.
Decision of the Court: The respondents were directed to permit the petitioner to file form GST Tran-1 & Tran-2 so as to enable to claim the transitional credit. Furthermore, it was declared that the due date contemplated under Rule 117 of the CGST Rules, 2017 is procedural in nature and thus should not be construed as a mandatory provision under the law.<br>
19
Adfert Technologies Pvt Ltd Vs UOI & Ors 2019-TIOL-2519-HC-P&H-GST Denial of Transitional credit on account of non-filing or incorrect filing of Form TRAN-1 by the stipulated last date i.e. 27.12.2017:
Rule 117(1A) & Rule 120A - absence of any time period in Section 140 of CGST Act indicates that there is no intention of Govt to deny carry forward of unutilized credit of duty/tax already paid on the ground of time limit.
GST is an electronic based tax regime and most of people of India are not well conversant with electronic mechanism.
Respondent authorities were having complete record of already registered persons and at present they are free to verify fact and figures of any Petitioner. Respondent cannot deprive Petitioners from their valuable right of credit.
HC directed Dept to permit Petitioners to file or revise already filed incorrect TRAN-1 either electronically or manually TRAN-1 on or before 30th November 2019.
Department at liberty to verify genuineness Petitioners claim but shall not deny carry forward legitimate CENVAT/ITC on the ground of non-filing of TRAN-1 by 27.12.2017.<br>
20
Sutherland Global Services Pvt Ltd Vs AC GST & CE 2019-TIOL-2516-HC-MAD-GST Question: Whether accumulated credit pertaining to E-Cess, SHE-Cess and KK-Cess could be carried forward to GST regime u/s 140(1) CGST Act?
Held:
Such credit continues to be available till such time it is expressly stated to have lapsed. In the present case, there is no notification/circular/instruction that has expressly provided that the credit accumulated would lapse.
CBEC circular dated 07.12.2015 reveal a policy decision not to allow utilization of accumulated credit of E-Cess and SHE-Cess but nowhere states that the credit has lapsed.
Accumulated credit cannot be said to have been wiped out unless there is a specific order under which it lapses.
After 2018 amendment to CGST Act, only cenvat credit of “eligible duties” were allowed to be carried forward u/s 140(1). Whereas, “eligible duties” was defined in the explanation to Section 140. Even if E-Cess and SHE-Cess could not be carried forward u/s 140(1), it can still be carried forward u/s 140(8) which was untouched by the amendment.<br>
21
Filco Trade Centre Pvt. Ltd. Vs. UOI- 2018(17) GSTL 3 (Guj) Issues involved: Challenge to vires of the condition as Cl.(iv) of S.140(3) prescribing the validity period of ‘12 months’ for the invoices for input in stock/WIP to claim ITC in terms of S. 140(3) of the CGST Act.
Gujarat High Court held that the no such restriction existed in prior regime and the said condition does impose burden with retrospective effect without any justification. Hence, the condition in Clause (iv) of Section 140(3) of Central Goods and Services Tax Act, 2017 is held to be unconstitutional and to be struck down.
Note: Department has filed an appeal before Supreme Court, wherein notice has been issued and Stay granted - 2019 (21) GSTL J120 (Supreme Court).
However, Bombay High Court in JCB India Ltd. Vs. UOI- 2018(15) GSTL 145(Bom.) held that condition in in Clause (iv) of Section 140(3) of CGST Act is constitutionally valid.<br>
22
RSPL Ltd Vs UOI 2018-TIOL-946-HC-AHM-GST Issues involved: Admissibility of Credit on the capital goods in transit as on 01.07.2017 under S. 140(5) of the CGST Act.
Gujarat High Court held that this demarcation between capital goods and inputs was not artificial, arbitrary or discriminatory, and there was no violation of Article 14 or Article 19(1)(g) of Constitution of India.
High Court noted that capital goods and inputs used in manufacturing process have always been treated differently by earlier statutes - Since inputs and capital goods form distinct and different classes, the question of sub-classification or artificial demarcation would not arise.<br>
23
Whether service tax demand by issuing SCN under Finance Act, 1994 is valid after 1.7.2017 – S. 174 of CGST Act No service tax proceedings is valid consequent to 101st Amendment to Constitution dated 16.9.2016 as Article 246A overrides Article 246 & 248.
Section 173 of CGST Act omits the provisions of Finance Act, 1994 - Rayala Corporation (P) Ltd Vs. Directorate of Enforcement reported in 1969 (2) SCC 412
Section 174 itself is beyond the constitutional mandate – Since as per Section 19 of 101st Constitution Amendment, there is only power to repeal or amend that has been provided and no power to save such deletion or omission
Kerala High Court in Sheen Golden Jewels India 2019 (23) G.S.T.L. 4 (Ker.) held that Section 174 enacted by Kerala State Legislature relating to repeal and saving of provisions of Kerala Value Added Tax Act, 2003 not unconstitutional in view of amended Entry 54 of List II of Seventh Schedule to Constitution of India w.e.f. 16-9-2016 on the basis of finding that Section 19 of Constitution (One Hundred and First Amendment) Act, 2016 is transitional and not a saving clause though it may have been a repealing clause simplicitor - Job of saving is done by Section 174 of Kerala Goods and Services Tax Act, 2017.<br>
24
Whether GSTR-3B is return u/s 39 of CGST Act?
AAP & Co Vs UOI 2019-TIOL-1422-HC-AHM-GST Facts: The writ petition was filed seeking to quash and set aside the press release dated 18.10.2018, to the extent that para 3 of the press release, purports to clarify that the last date for availing input tax credit relating to the invoices issued during the period from July, 2017 to March, 2018 is the last date for the filing of return in Form GSTR-3B, as it is contrary to the provisions of Section 16(4) of the CGST Act, 2017 read with Section 39(1) of the CGST Act along with Rule 61 of the CGST Rules/GGST Rules.
Press release dated 18.10.2018: Taxpayers self-assessing and availing ITC through return in FORM GSTR-3B, the last date for availing ITC in relation to the invoices issued during the period from July 2017 to March, 2018 by the supplier, is the last date for the filing of such return for the month of September, 2018 i.e. 20th October, 2018.
Question: In terms of Section 16(4) of the CGST Act, 2017, the last date for availing input tax credit in respect of any invoice or the debit note is the due date of furnishing return under section 39 or the date of annual return, whichever is earlier. Therefore, the moot question to decide was that whether the return in Form GSTR-3B is a return required to be filed under Section 39 of the CGST Act/GGST Act?<br>
25
AAP & Co Vs UOI 2019-TIOL-1422-HC-AHM-GST Held:
Is Form GSTR-3B is a valid return under section 39 of the CGST Act?: Initially, it was decided to have three returns i.e. return for outward supplies in GSTR-1, return for inward supplies in GSTR-2 and a combined return in Form GSTR-3. However, due to the technical difficulties in the portal and the difficulty faced by the taxpayer, the return in form GSTR-2 & 3 are in abeyance. Accordingly, in order to ease the burden of taxpayer, shorter return in form GSTR-3B was introduced but it was not in lieu of Form GSTR-3.
Therefore, it was observed that the return in Form GSTR-3B is only a temporary stop gap arrangement till due date of filing the return in Form GSTR-3 is notified. However, notifications were issued from time to time extending due date for filing Form GSTR-3 and which shall be subsequently notified in the Official Gazette.<br>
26
AAP & Co Vs UOI 2019-TIOL-1422-HC-AHM-GST Decision of the Court: The press release dated 18.10.2018, was declared as illegal and said to be contrary to the provisions of Section 16(4) of the CGST Act/GGST Act read with Section 39(1) of the CGST Act read with Rule 61 of the CGST Rules.
Based on the observation of the Court it can be said that the last date for availing input tax credit for the period June 2017 to March 2018, would the date of filing annual return i.e. in Form GSTR -9 or 9A or 9B or 9C as the case may be.
Consequences of the decision: Pursuant to the discussions in the 37th Council Meeting, Notification No. 49/2019 – CT dated 9th October, 2019 was issued which amended Rule 61(5) of the CGST Rules providing that GSTR 3B shall be a return u/s 39 of CGST Act, 2017 and such rule is amended retrospectively with effect from 1st July, 2017.<br>
27
GST on Duty Free Shops
Atin Krishna Vs UOI 2019-TIOL-1136-HC-All-GST The Duty Free Shops are located in the Custom area as per Section 2(11) of the Customs Act 1962
Supply of imported goods to & from the duty free shops do not cross the Customs frontier & hence such supplies classify as inter-State supply u/s 7(2) of the IGST Act.
Hence the same cannot attract CGST and SGST u/s 9 of either Act: HC
The supply of warehoused goods by the duty free shops at the departure terminal is made to departing international passengers who are destined for some foreign location –
Hence the goods supplied are never cleared for home consumption & the warehoused goods are exported - Hence no Customs or IGST is leviable - IGST is not payable on the supply either to or from the DFS located at the arrival or at departure terminal<br>
28
GST on Duty Free Shops
Sandeep Patil Vs UOI 2019-TIOL-2348-HC-MUM-GST Whether the duty free shops (‘DFS’, the petitioner) at Mumbai International Airport Ltd (MIAL) can be saddled with burden of taxes on amounts paid towards the minimum guaranteed fees/ concession fees for grant of rights and use of licensed premises in the departure or arrival area of international airport?
Held:
Supply by DFS of petitioner at international Airport to outbound passenger constitutes ‘exports’ by DFS u/s 2(5) IGST Act. Consequently, in terms of section 16(1) of IGST Act, 2017, it becomes a zero rate supply. Reliance was placed on Atin Krishna Vs UOI 2019-TIOL-1136-HC-ALL-GST and A-1 Cuisines Pvt Ltd Vs UOI 2018-TIOL-2916-HC-MUM-GST.
Further, as per article 286 of the Constitution of India, supply made in course of import into India or in course of export out of India, can not be subjected to any tax.
If the duty free shop, which caters to the outgoing or incoming international passengers, is subjected to local taxes by the State, the tax burden will increase and the price of the goods, which are supposed to be free of taxes and duties, will go up, and the same would prevent the duty free shops in India from competing with DFSs at international airports elsewhere in the world. This will also hamper and prejudicially affect foreign trade, and augmentation and conservation of foreign exchange and will also negate the intent and purpose of article 286 of the Constitution of India.<br>
29
GST on Ocean Freight
Mohit Minerals Pvt Ltd Vs UOI 2018 (10) GSTL 424 (Guj) Issues involved: Challenge to levy of IGST on ocean freight. Petitioner also challenged the vires of Notification No. 8/2017-IGST Dt.. 28.06.2017 and Notification No. 10/2017- IGST Dt.. 28.06.21017
High Court held that petitioner being an importer of non-cooking coal challenging vires of aforesaid notifications on the ground that once having paid IGST on full value of imported goods inclusive of freight element, charging GST again on ocean freight not permissible. Further, both service provider and recipient being located abroad in case of CIF contracts, levy under RCM not permissible and that in case of High Sea Sales, importer not being recipient of service cannot be charged with GST.<br>
High Court held that petitioner being an importer of non-cooking coal challenging vires of aforesaid notifications on the ground that once having paid IGST on full value of imported goods inclusive of freight element, charging GST again on ocean freight not permissible. Further, both service provider and recipient being located abroad in case of CIF contracts, levy under RCM not permissible and that in case of High Sea Sales, importer not being recipient of service cannot be charged with GST.<br>
30
Whether ‘Fees’ charged by Receiver is liable to GST?
Bai Mamubai Trust Vs Suchitra 2019-TIOL-2158-HC-MUM-GST Facts: Defendant was alleged as occupying a property illegally and the plaintiff had filed suit in Bombay High Court. The High Court appointed Court Receiver to take 'formal possession' of the property under the provisions of the Civil Procedure Code, while allowing the defendant to remain in actual possession of the property. Court further ordered payment of a particular sum per month to the Receiver towards royalty / compensation.
Held:
Receiver is a department of the Court. Fees received by Receiver would fall under Entry 2 of Schedule III of CGST Act which covers. Therefore, no GST is liable to be paid.
Payment of royalty is not ‘consideration’ for supply. Royalty paid was towards damages or compensation for violation of plaintiff's legal right in the suit premises. The defendant was permitted to remain in possession despite having no right to be in occupation of the premises subject to payment of such amount. Therefore, basis of this payment is the alleged illegal occupation or trespass by the defendant.
It cannot be said that royalty is, in substance, rent and the receiver acts as an agent of the plaintiff who is in the business of renting of property and therefore, the same is liable to tax.
Where no reciprocal relationship exists, and the plaintiff alleges violation of a legal right and seeks damages or compensation from a court to make good the said violation (in closes possible monetary terms) it cannot be said that a supply has taken place.<br>
31
GST - Input Tax Credit issues<br>
32
Shabnam Petrofils Pvt Ltd VS UOI 2019-TIOL-1656-HC-AHM-GST Challenge: Validity of Notification No 20/2018-CT(R) dated 26.07.2018.
Provisions referred to:
Section 54(3) of the CGST Act provides for refund of unutilized ITC at the end of the year. However, the first proviso thereto states that such refunds does not enure inter alia when tax paid on inputs is higher than tax paid on outputs (i.e, inverted rates).
But even in such cases, refund would be available to supplies of specified goods. Accordingly, Notification No 5/2017-CT(R) specified the goods where refund would enure even in cases of inverted rate structure. The said Notification was amended vide the impugned Notification No 20/2018-CT(R) dated 26.07.2018 which inserted the following two clauses:
Refund on ITC accumulated upto 31st July 2018: Accumulated ITC in respect of certain inward supplies lying unutilized after payment of tax for and upto July 31st, 2018 would lapse after such date.
Refund on ITC accumulated from/after 1st August 2018: Refund would not enure to ITC accumulated on certain supplies received on or after 1st August 2018.<br>
33
Shabnam Petrofils Pvt Ltd VS UOI 2019-TIOL-1656-HC-AHM-GST Question: Whether the central government could make a notification providing for lapse of accumulated ITC u/s 54(3)?
Observation and Findings:
Credit must enure as soon as duty is paid on inputs and input services and used for making outward supplies: Relying on the case of Dai Ichi Karkaria Ltd 1999 (112) ELT 353 (SC) and Eicher Motors Ltd Vs UOI 1999 (106) ELT 3 (SC) held that when credit has been validly taken, it is available to manufacturer without any time limit. The credit is indefeasible.
Section 54(3) does not provide for lapsing of accumulated ITC: The only power conferred u/s 54(3) is to notify the goods and services not entitled for refund of ITC accumulated on account of inverted rates. It does not provide for lapsing of accumulated credit.
Notification No 20/2018-CT(R) suffers from the vice of excessive delegation: The impugned Notification being made thereunder providing for lapsing of accumulated ITC would be ultra vires Section 54(3).
Special provisions in Sections 17(4) and 18(4) are made for lapsing: Section 17(4) provides for opting of taking 50% of credit in case of a banking company or an NBFC and rest would lapse. Section 18(4) provides for lapsing of credit in case of composition scheme.
Therefore, High Court held that Notification No 20/2018-CT(R) dt 26.07.2018 is ex-facie invalid and liable to be struck down.<br>
34
Safari Retreats Pvt Ltd Vs Chief Commissioner of CGST [2019] 25 GSTL 341 (Orissa) Question: Whether GST paid on inputs (i.e, goods or services) purchased for the purpose of construction of immovable property can be taken to set off GST obligations in respect of renting of immovable property and the same is not hit by Section 17(1)(d) of the CGST Act?
Arguments of the petitioner:
Section 17(5)(d) must apply only in cases of constructions where tax chain is broken. Its purport must be restricted to cases where the intention to construct a building, is to sell it after issuance of completion certificate.
The sale of a property after issuing of a completion certificate is not taxable in the GST regime as per entry 5 of III Schedule to CGST Act. Therefore, the chain of taxation gets broken and restricting ITC in such cases would be completely valid.
However, in the instant case the tax chain continues as the mall which has been constructed generates rental income which is liable to GST. Hence, the taxation which starts when the petitioner buys goods and services for the construction of the mall, continues till the taxation of rental income arising out of the same construction.
Further, under section 16 of the CGST Act, GST registered persons are entitled to take credit of input tax charged on any supply of goods or services to him which are used or intended to be used in the course or furtherance of his business. It contemplates availment and utilization of ITC by persons who have a uniform tax chain in their transactions from input till output.<br>
35
Safari Retreats Pvt Ltd Vs Chief Commissioner of CGST [2019] 25 GSTL 341 (Orissa) Held:
The very purpose of the CGST Act is to make uniform provisions for levy and collection of tax and to prevent multi-taxation.
Input tax credit accumulated on account of inputs purchased/used for construction of immovable property against renting of immovable property is that supply of input goods for construction of a shopping mall and the same being used for renting out units in the mall constitute a single supply chain and benefit of ITC should be available to the assessee.
Section 17(5)(d) of the CGST Act was read down by allowing use of ITC on goods and services consumed in construction of shopping mall against paying GST on rentals received from tenants in shopping mall as the very purpose of credit is to give benefit to the assessee.<br>
36
D. Pauls Travels & Tours Ltd Vs UOI 2018 (11) GSTL 255 (Del) Issues involved: Assessee in business of booking tours and hotel packages for customers charge Integrated Goods and Services Tax (IGST) from customers for bookings in hotels located outside Delhi - Assessee unable to avail Input Tax Credit on State Goods and Services Tax (SGST) charged by hotels located outside Delhi as it was not registered in that State.
Whether assessees would have to be registered in all States and Union Territories to avail input credit of SGST?
High Court held that different provisions applicable in case of online bookings through web travel portals and assessee able to avail credit, issued direction to Government to examine assertions and inform Tribunal on treatment accorded on sale of manufactured goods and other services provided by an assessee across country - Government also directed to examine and consider whether matter should be placed before GST Council.<br>
37
GST – Refund issues<br>
38
RED COIN PAPER PRODUCT Vs. DEPUTY COMMISSIONER OF STATE TAX [2019-TIOL-1353-HC-AHM-GST ] Refund claim on account of exports were not paid fully but partly allowed.
However, the credit which was reversed on claiming refund was not credited back to the electronic credit ledger to the extent of rejection.
High Court directed the respondent to re-credit.<br>
However, the credit which was reversed on claiming refund was not credited back to the electronic credit ledger to the extent of rejection.
High Court directed the respondent to re-credit.<br>
39
M/s AMIT COTTON INDUSTRIES Vs Pr. CC [2019-TIOL-1443-HC-AHM-GST ] Refund claim on account of exports were withheld on the ground that the assessee has claimed 1% rebate [period of export-July 2017]
Before the Court the respondents contended that in terms of circular No. 37/2018-Customs dt. 9.10.2018, the refund cannot be granted where the rebate is claimed.
The Court interpreting the provisions of Section 54 of CGST ACT, 2017 read with Rule 96 of CGST Rules, (as applicable during the said period) held that there is no provision to withheld the refund and the circular is not applicable to the present case.
The Court ordered refund of the amount due along with interest of 7% from the date of shipping bill.<br>
40
Inverted duty structure – challenge to Rule 89(5) Raymond Uco Denim Pvt Ltd Vs UOI & Ors 2019-TIOL-1900-HC-MUM-GST
Petitioner challenged the vires of Rule 89 (5) of CGST Rules as being contrary to Section 54 (3) of the Act, 2017.
It was contended that Rule 89(5) gives the formula for computation of refund of input tax credit and explanation (a)therein excludes input tax service credit from the definition of Net ITC, though it is shown under the turn over of inverted rated supply of goods.
Hon’ble High Court issued ‘Notice’ to the respondents-department for final disposal of the matter.
Similar challenge to Rule 89(5) in High Courts:
The Quarry Owners Association Vs UIO [2019-TIOL-1726-HC-AHM-GST]
Adani Wilmar ltd Vs UIO [2019-TIOL-1891-HC-AHM-GST]<br>
41
G Nxt Power Corp. Vs UOI (2019) 109 taxmann.com 305(Kerala) Facts: The petitioner is an exporter, claimed refund of IGST as per the provisions of section 16 of IGST paid in cash on the Zero rated supply. The respondent department denied to grant the IGST, as the petitioner has already availed the benefit of Higher rate of duty draw back. Hence, the petitioner was directed to repay the amount of duty drawback with interest availed by them to get the refund of IGST paid in cash.
Held:
Once the IGST paid in cash by the assessee / petitioner, it may on the account of erroneous or voluntarily, the authority has the obligation to refund of the amount of IGST paid in cash.
The court directed to the respondents that they have full liberty to adjust the amount already availed by the petitioner on account of higher rate of duty drawback and to pay the balance of IGST payable. (i.e. IGST minus higher rate of duty drawback) within period of 6 weeks from the date of receipt of the order.
If the respondents failed to comply with the directions given by the court within the timeline fixed by the court. Then, they have the obligations to pay the interest on the refundable amount from the dated of receipt of the refund application.<br>
42
Prosecution under GST<br>
43
PV Ramana Reddy Vs UOI 2019-TIOL-873-HC-TELANGANA-GST Issue involved: Petitioner challenged the summons issued u/s 70 of CGST Act, 2017 and the invocation of penal provisions under Section 69 of the Act. The Directors of a few Private Limited Companies, a Chief Financial Officer of a company and the Partner of a Partnership Firm have come up with the writ petitions.
What the petitioners seek in these cases is a direction to the respondents not to arrest them in exercise of the power conferred by Section 69(1) of the CGST Act, 2017.
High Court noted that this in essence, is akin to a prayer for anticipatory bail.<br>
What the petitioners seek in these cases is a direction to the respondents not to arrest them in exercise of the power conferred by Section 69(1) of the CGST Act, 2017.
High Court noted that this in essence, is akin to a prayer for anticipatory bail.<br>
44
PV Ramana Reddy Vs UOI 2019-TIOL-873-HC-TELANGANA-GST The main allegation against the petitioners is that they are guilty of circular trading by claiming input tax credit on materials never purchased and passing on such input tax credit to companies to whom they never sold any goods.
High Court rejected the contention of petitioner that prosecution can be launched only after the completion of assessment as being contrary to Section 132 of the CGST Act, 2017. Issue of invoices or bills without supply of goods and the availing of ITC by using such invoices or bills, are made offences under clauses (b) and (c) of sub-Section (1) of Section 132 of CGST Act.
The prosecutions for these offences do not depend upon the completion of assessment, High Court rejected that the argument that there cannot be an arrest even before adjudication or assessment.<br>
45
PV Ramana Reddy Vs UOI 2019-TIOL-873-HC-TELANGANA-GST Accordingly, High Court dismissed the Writ Petitions and refused to grant relief to the petitioner against arrest, in view of the special circumstances and allegations of the present case.
High Court refused to grant relief, despite the finding that the writ petitions are maintainable and despite finding that the protection under Sections 41 and 41-A of Cr.P.C., may be available to persons said to have committed cognizable and non-bailable offences under this Act and despite the finding that there are incongruities within Section 69 and between Sections 69 and 132 of the CGST Act, 2017.<br>
High Court refused to grant relief, despite the finding that the writ petitions are maintainable and despite finding that the protection under Sections 41 and 41-A of Cr.P.C., may be available to persons said to have committed cognizable and non-bailable offences under this Act and despite the finding that there are incongruities within Section 69 and between Sections 69 and 132 of the CGST Act, 2017.<br>
46
PV Ramana Reddy Vs UOI 2019-TIOL-873-HC-TELANGANA-GST Question: Whether Arrest/Prosecution can Precede Assessment?
To say that a prosecution can be launched only after the completion of assessment, goes contrary to Section 132.
Offences mentioned in Section 132 have no co-relation to and do not depend on any assessment and adjudication.
Arrest can be made even when offence is compoundable.
Article 226 can be used as a substitute to section 438 CrPC to obtain anticipatory bail.
Same view was taken in Bharath Raj Punj Vs CCGST 2019-TIOL-678-HC-RAJ-GST;<br>
47
Jayachandran Alloys Vs Superintendent of GST 2019-TIOL-1021-HC-MAD-GST Issue involved: Petitioner’s premises were subjected to Search proceedings during the relevant period for several days, whereupon voluminous amount of documents were seized and Statements of various persons, including Managing Director of petitioner, were recorded. However, when petitioner-assessee sought copies of the statements recorded as well as of other material seized, there was response from the Revenue.
Hence, assessee filed the writ petition seeking that directions be issued to the Revenue to provide the material sought for by the assessee. Further, another Miscellaneous Petition was also filed by the assessee seeking that interim injunction be granted, restraining the Revenue from taking coercive steps against the assessee such as arrest u/s 69 of the Act, pending disposal of the writ.<br>
Hence, assessee filed the writ petition seeking that directions be issued to the Revenue to provide the material sought for by the assessee. Further, another Miscellaneous Petition was also filed by the assessee seeking that interim injunction be granted, restraining the Revenue from taking coercive steps against the assessee such as arrest u/s 69 of the Act, pending disposal of the writ.<br>
48
Jayachandran Alloys Vs Superintendent of GST 2019-TIOL-1021-HC-MAD-GST Madras High Court held that while the Revenue's interests are paramount & must be protected, the actions of the Revenue draw their power only from a holistic interpretation of the legal provisions. Any excess in this regard vitiates the legitimacy of the exercise.
Section 132 of Act imposes punishment on an assessee who commits an offence, the term commits clarifies that the act of committal of the offence is to be fixed first before punishment is imposed.
The Revenue's allegation is that the assessee contravened provisions of Section 16(2) of the Act by availing excess ITC without movement of goods & existence of bogus transactions, hence determination of excess credit as per procedure u/s 73 or 74 is prerequisite for recovery thereof.<br>
49
Jayachandran Alloys Vs Superintendent of GST 2019-TIOL-1021-HC-MAD-GST High Court held that when recovery is made subject to determination in an assessment, the Revenue's argument that punishment for the offence alleged can be imposed even prior to such assessment, is clearly incorrect and amounts to putting the cart before the horse.
The exceptions to this rule of assessment are only those cases where the assessee is a habitual offender penalized for violating legal provisions. Only then is the Revenue justified by pre-empting assessment to initiate action u/s 132.
There is no allegation that the assessee is an offender, leave alone a habitual one. The Revenue attempted to intimidate the assessee with the possibility of punishment u/s 132 & such action is contrary to the scheme of the CGST Act.
Hence the power to punish is triggered only after establishing that an assessee committed an offence that has to necessarily be post-determination of the demand due from an assessee, that itself has to necessarily follow the process of an assessment.<br>
50
Jayachandran Alloys Vs Superintendent of GST 2019-TIOL-1021-HC-MAD-GST Question: Whether Arrest/Prosecution can Precede Assessment?
The term ‘commits’ clarifies that the act of committal of the offence is to be fixed first before punishment is imposed. When recovery is made subject to determination in an assessment, the Revenue's argument that punishment for the offence alleged can be imposed even prior to such assessment, is clearly incorrect and amounts to putting the cart before the horse.
There must be determination that a person is "liable to a penalty“. Till that point of time, the entire case proceeds on the basis that there must be an apprehended evasion of tax by the assessee.
Reliance was placed on UOI Vs Makemytrip India Pvt Ltd 2019-TIOL-65-SC-ST where it was held that the Revenue cannot bypass Section 73A of the Finance Act, 1994 before going ahead with arrest u/s 90, 91 (arrest) of FA, 1994.
Similar view was taken in case of Vimal Yashwantgiri Goswami Vs State of Gujarat 2019-TIOL-1746-HC-AHM-GST
UoI Vs Sapna Jain 2019-TIOL-217-SC-GST – Matters are referred to larger bench of the SC<br>
51
C Pradeep Vs C. GST & CE, SELAM & Anr 2019-TIOL-339-SC-GST The petitioner contended that penal provisions of Section 132 of the CGST Act could not have been invoked in his case, where assessment proceedings for the relevant period had not been completed.
The petitioner further expressed willingness to pre-deposit 10% of the disputed duty demand, so as to exercise option of filing appeal after the assessment order is passed.
Supreme Court issued an interim order granting stay and ordered that no coercive action be taken against the petitioner in connection with the alleged offence and the interim protection will continue subject to payment of pre-deposit of 10% of tax demand until the disposal of this Special Leave Petition.<br>
52
Akhil Krishan Maggu Vs Deputy Director, DGGSTI 2019-TIOL-2615-HC-P&H-GST It was alleged that certain exporters were dummy owners and had availed huge amount of refund of IGST. Search was conducted, FIRs were registered and statements of the exporters were recorded. On naming certain names including that of the petitioner, a practicing lawyer, he was arrested on the ground of obstruction in performance of official duty. He was asked to appear before DGGI to give statements against dummy exporters. Writ petition was filed apprehending further coercive action.
Held:
Power of arrest should not be exercised at whims and caprices of any officer or for sake of recovery or terrorizing any businessman or create an atmosphere of fear, whereas it should be exercised in exceptional circumstances during investigation.
Persons against whom there is no documentary or otherwise concrete evidences to establish direct involvement in evasion of huge amounts of tax, should not be arrested prior to determination of liability and imposition of penalty.
Arrest of Chartered Accountant or Advocates who had filed returns or otherwise assisted in business but are not beneficiary or part of fraud merely on basis of statement without any corroborative evidence linking professional with alleged offence should be avoided.
Arrest deprives any person from his right of liberty enshrined under Article 21 of the Constitution. Provisions of CrPC [Section 41 and 41A] would be applicable.<br>
53
GOVIND ENTERPRISES Vs St. of UP and Others - 2019-TIOL-1170-HC-ALL-GST Petitioner sought quashing of first information report (FIR) dated 30.11.2018 lodged by Assistant Commissioner, Commercial Tax at police station under Sections 420, 467, 468, 471, 34, 120-B IPC – on the allegations of bogus purchases without actual receipt of goods
The Court while dismissing the petition held that:
Sections 69, 134, and 135 of the U.P. Act are applicable in respect of offences punishable under the U.P. Act - They have no application on offences punishable under the Penal Code.
Further, there is no provision in the U.P. Act which may suggest that the provisions of the U.P. Act overrides or expressly or impliedly repeals the provisions of the Penal Code.
With exception for offences specified in sub-section (5) of section 132, sub-section (4) of section 132 of the U.P. Act renders all offences under the U.P. Act non cognizable, therefore no FIR can be lodged, is not acceptable, because sub-section (4) speaks of offences under the U.P. Act and not in respect of offences under the Penal Code<br>
54
Advance Authorisation – ‘Pre-import’ and ‘Physical exports’ conditions struck down
Maxim Tubes Company Pvt Ltd Vs UOI 2019-TIOL-459-HC-AHM-CUS Issue involved: The conditions of ‘physical exports’ and ‘pre-import condition’ under Notification No. 18/2015-Cus as amended by Notification No. 79/2017-Cus dated 13.10.2017 were challenged.
High Court held that the condition of physical export and pre-import put forth by the DRI, it is more or less impossible to make any exports under an Advance Authorisation without violating the condition of pre-import.
High Court held that the impugned conditions do not meet with the test of reasonableness and are also not in consonance with the scheme of Advance Authorisation. Accordingly, High Court struck down the "pre-import condition" contained in paragraph 4.14 of FTP 2015-2020 inserted vide Notification No.33/2015-2020 dated 13.10.2017 and inserted vide clause (xii) in Notification No.18/2015-Cus vide Notification No.79/2017-Cus dated 13.10.2017, as being ultra vires the Advance Authorisation Scheme of FTP, 2015-2020.<br>
55
Recovery of tax under GST<br>
56
Patran Steel Rolling Mill Vs Asst Commr of Sales Tax - 2018-TIOL-197-HC-AHM-GST Issues involved: Petitioner challenged the maintainability of the attachment of Bank accounts ordered u/s. 83 of the CGST Act and seizure of goods.
Impugned orders of Commissioner for attachment of bank accounts and seizure of goods are quashed and set aside by High Court by holding that in absence of any proceedings undertaken and penalty imposed, Authorities are not justified in resorting to such a drastic coercive measure of attachment of bank accounts and seizure of goods, which results in bringing assessee’s business halt.
High Court also passed strictures to Departmental Authorities holding that the powers regarding provisional attachment of goods including bank accounts, to be exercised not as matter of course but only after due application of mind to relevant factors.<br>
57
Valerius Industries Vs UOI 2019-TIOL-2094-HC-AHM-GST Facts: Dept had ordered provisional attachment of the stock of goods amounting to Rs.1.60 crores along with bank accounts of the petitioner.
Held:
Power conferred upon authority u/s 83 for provisional attachment is very drastic and far-reaching power; such power to be used sparingly and only on substantive weighty grounds and reasons.
Order of attachment is justified only if authority is of the opinion that it is to protect the interest of revenue.
Power u/s 83 should neither be used as a tool to harass the assessee nor should it be used in a manner which may have an irreversible detrimental effect on the business of the assessee.
The following factors must be taken into consideration:
whether it is a revenue neutral situation;
The statement of "output liability or input credit“, having regard to the amount paid by reversing the input tax credit, if the interest of the revenue is sufficiently secured
Gujarat High Court in Pranit Hem Desai Vs Addl. Director Gen. [2019] 30 GSTL 396 (Guj)<br>
58
M/s CENGRES TILES LIMITED Vs. St. Of Guj [2019 ACR 309 High Court Gujarat – Spl Civil Application No. 19180 of 2018 ] The writ applicant challenged the provisional attachment orders dated 26/11/2018 directing the attachment of the Bank Account of the writ applicant.
Hon’ble High Court held that the action of Respondent for attachment of Bank account under sec. 83 of CGST Act,2017 is not in accordance with law in as much as the provisional attachment u/s 83 cannot be invoked unless notice under section 46 is issued and assessment under section 62 is undertaken<br>
Hon’ble High Court held that the action of Respondent for attachment of Bank account under sec. 83 of CGST Act,2017 is not in accordance with law in as much as the provisional attachment u/s 83 cannot be invoked unless notice under section 46 is issued and assessment under section 62 is undertaken<br>
59
Release of seized goods – whether HC can entertain Writ?
State Of Uttar Pradesh Vs Kay Pan Fragrance Pvt Ltd 2019-TIOL-517-SC-GST Facts: SLP was filed by the State of UP questioning the interim order passed by the High Court directing the State to release the seized goods, subject to deposit of security other than cash or bank guarantee or an indemnity bond.
Issue: When a complete mechanism for release (including provisional release) and disposal of seized goods, is prescribed in the Act and the Rules, then, whether High Court could entertain the Writ Petition questioning the seizure and release of goods?
Held:
The recourse must be taken to the mechanism already provided for in the Act and the Rules for release, on a provisional basis, upon execution of a bond and furnishing of a security, in such manner and of such quantum (even upto the total value of goods involved), respectively, as may be prescribed.
The High Court has erroneously extricated the assessees concerned from paying the applicable tax amount in cash, which is contrary to the provisions of section 68 and the Rules prescribed thereof.
Any order passed by the High Court which is contrary to the provisions of law need not be given effect.
Instead, relief was given to the assesse to approach the authorities and the said authorities shall process the claims of the concerned assessee afresh as per the express stipulations in Section 67 of the Act read with the relevant rules in that regard.<br>
60
Nirman Estate Developers Pvt Ltd Vs UOI 2018-TIOL-195-HC-MUM-GST The petitioner contests the constitutional validity of Notification No No.4 of 2018-Central Tax (Rate) and Notification No.4 of 2018-ST (Rate), both dated Jan 25, 2018.
Petitioner claimed that both notifications seek to tax an activity which is neither service nor supply of service & so is ultra vires of the CGST Act 2017.
Bombay High Court ordered issue notice to respondents.<br>
Petitioner claimed that both notifications seek to tax an activity which is neither service nor supply of service & so is ultra vires of the CGST Act 2017.
Bombay High Court ordered issue notice to respondents.<br>
61
GSTAT – Setting up of Appellate Tribunal under GST regime Revenue Bar Association Vs UOI 2019-TIOL-2188-HC-MAD-GST: The Madras High Court inter alia struck down Section 109(3) and 109(9) of the Central Goods and Services Act, 2017 on the basis that the composition of the GSTAT to include one Judicial Member and two Technical Members is unconstitutional.
Allahabad High Court in Oudh Bar Association Vs UOI 2019 (25) GSTL 374 (All) held that the seat where the Tribunal is to be established is an issue which is within the domain of the Executive in terms of Section 109 of CGST Act ordinarily and is not justiciable in view of the decision of the Supreme Court in the case of Lalit Kumar (supra). Further, while directing the government to fill up vacancies and unfilled posts in tribunals, it was observed that on account of non-functioning of the tribunal, the litigants are rushing to the High Court adding to the existing pendency.
GST Appellate Tribunal (‘GSTAT’) vide Notification No. S.O. 3009(E) [No. 1/2019 (F. No. A. 50050/99/2018 - AD.1C (CESTAT)] dated 21.08.2019<br>
62
What happens if Assessee pays IGST instead of CGST+SGST? Option 1: Once again pay the taxes under CGST+SGST and claim refund of IGST under S.77 of CGST Act.
Option 2: To get direction from jurisdictional High Court to transfer taxes already paid (IGST) to the heading CGST + SGST relying upon Kerala High Court decision in Saji S & Others Vs. Commissioner of State GST 2018-TIOL-2902-HC-KERALA-GST, wherein in the context of ‘inter-state supply’, High Court directed the Department that the taxes remitted under the 'SGST' is transferred to the head 'IGST’.<br>
Option 2: To get direction from jurisdictional High Court to transfer taxes already paid (IGST) to the heading CGST + SGST relying upon Kerala High Court decision in Saji S & Others Vs. Commissioner of State GST 2018-TIOL-2902-HC-KERALA-GST, wherein in the context of ‘inter-state supply’, High Court directed the Department that the taxes remitted under the 'SGST' is transferred to the head 'IGST’.<br>
63
Whether police authorities can take action under GST Md.Tajal Hussain vs State of Assam (2019) 112 taxmann.com 107 (Gauhati), where the High Court held that police authorities can only take action under IPC and not under GST legislations for which the GST authorities are only competent to do so.<br>
64
Where liability is declared under GSTR 1 recovery notice is necessary under Sec.73 High Court of Madhya Pradesh in Kabeer Realty vs UOI (2019) 112 taxmann.com held that where liability was declared in GSTR 1, then the same has to be paid and no adjudication is necessary under Sec.73. This view seems to have been taken as the assessee filed GSTR 1 and not GSTR 3B as stated by the High Court. Even the department did not rely on Section 75(12) which may be required to be challenged.<br>
65
V.RAGHURAMAN, B.Com., FCA, ACS, Grad.CWA LLB, THANK YOU
Email: vraghuraman@vraghuraman.in<br>
Email: vraghuraman@vraghuraman.in<br>