
Co-movement of Stock Prices in the CARICOM Region

Description: Co-movement of Stock Prices in the CARICOM Region John Cozier AND PATRICK WATSON Bbf5 confeRence May 2-3, 2013 Outline of Presentation Introduction Methodology and Data Empirical Analysis Preliminary Estimation of GARCH Estimation of Copula
Related Topics
Download Presentation
"Co-movement of Stock Prices in the CARICOM Region" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Co-movement of Stock Prices in the CARICOM Region John Cozier
AND
PATRICK WATSON
Bbf5 confeRence
May 2-3, 2013<br>
slide2. Outline of Presentation Introduction
Methodology and Data
Empirical Analysis
Preliminary
Estimation of GARCH
Estimation of Copula
Conclusions<br>
slide3. Introduction Financial integration in the CARICOM Region
Importance of stock price comovement
Baur (2003)
Stock price comovement in the literature
Developed markets
Kim and Langrin (CARICOM markets)<br>
slide4. Methodology and Data Preliminary Analysis
Correlation coefficients
January 1, 1998 – December 31, 2011
January 1, 1998 – March 31, 2008
April 1, 2008 – December 31, 2011
Sharpe Ratio
GARCH-Copula
Bollerslev (2008)<br>
slide5. Methodology and Data Data
End of day values of the Composite Indices from January 1, 1998 – December 31, 2011
BSE
JSE
TTSE
NYSE
GARCH Copula: End of day values from April 1, 2008 – December 31, 2011<br>
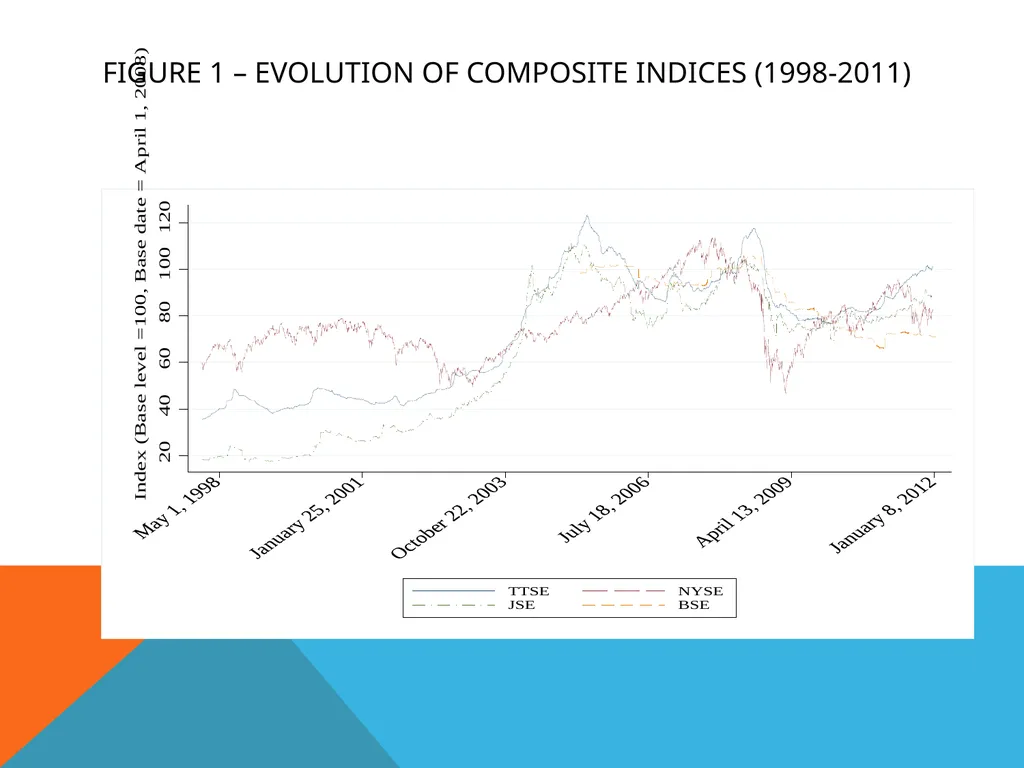
slide6. Figure 1 – Evolution of Composite Indices (1998-2011)<br>
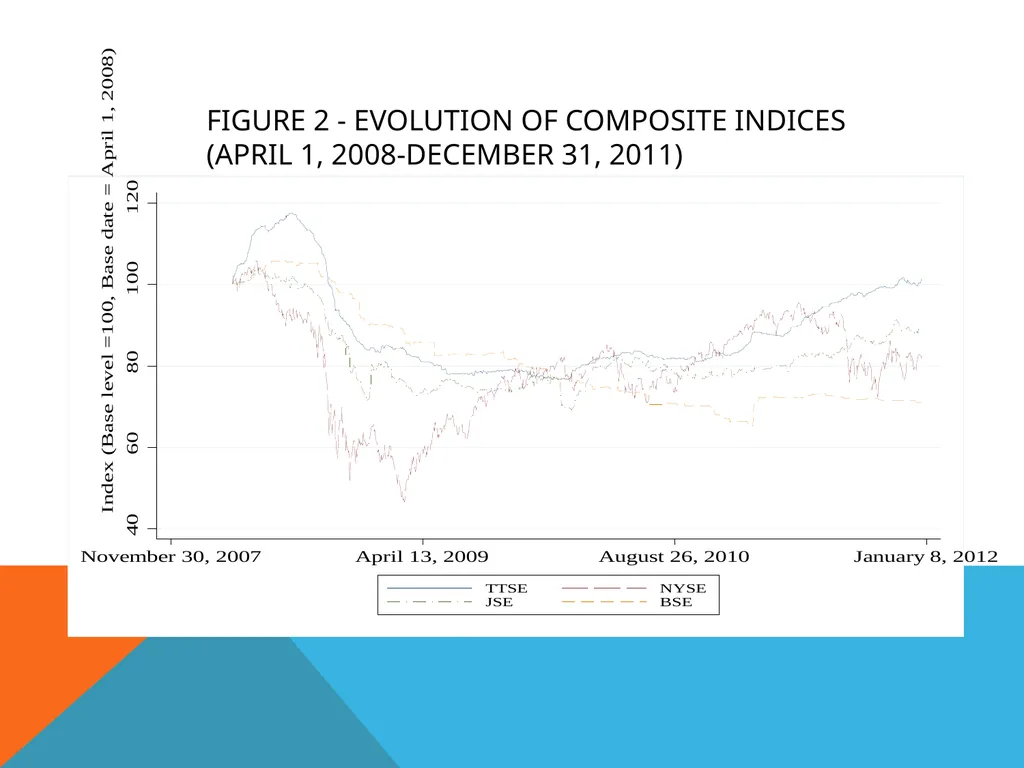
slide7. Figure 2 - Evolution of Composite Indices (April 1, 2008-December 31, 2011) (April 1, 2008-December 31, 2011)<br>
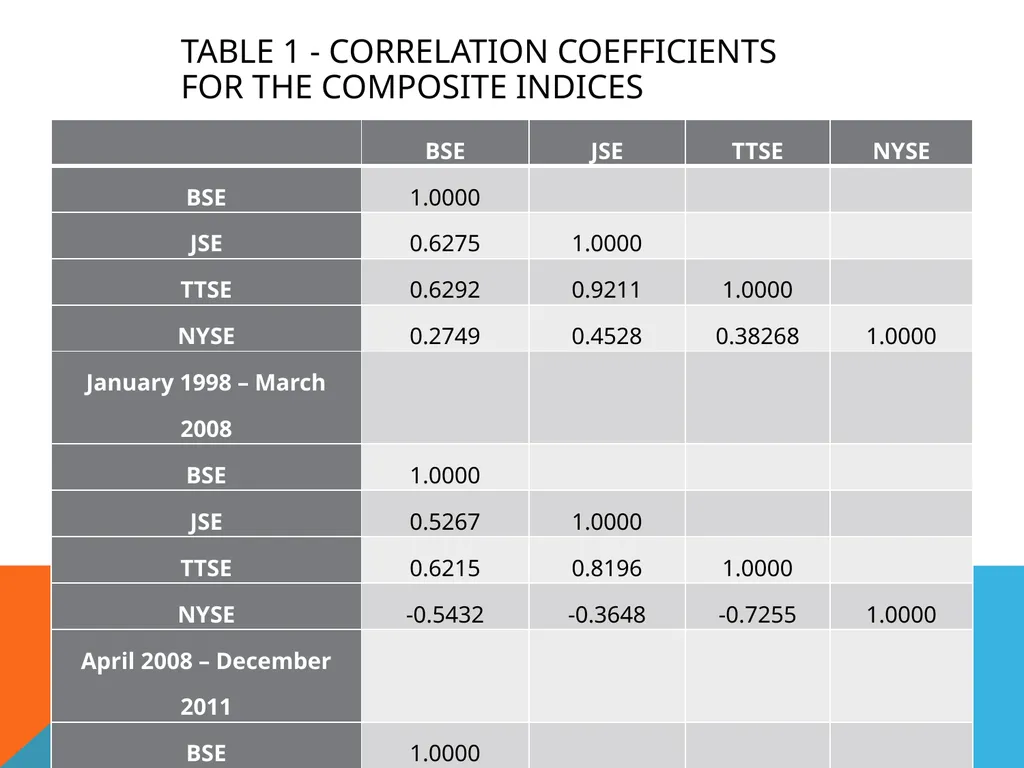
slide8. Table 1 - Correlation Coefficients for the Composite Indices<br>
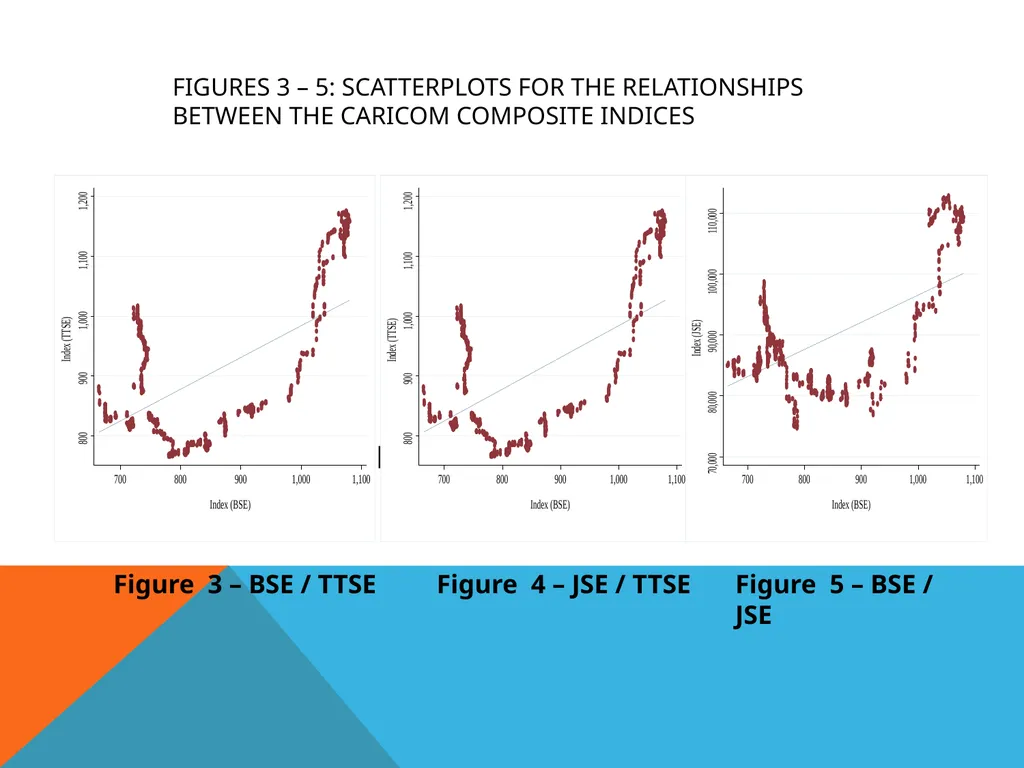
slide9. Figures 3 – 5: Scatterplots for the relationships between the CARICOM Composite Indices Figure 3 - TTSE/BSE Figure 4 - TTSE/JSE Figure 5 – JSE/BSE Figure 3 – BSE / TTSE Figure 4 – JSE / TTSE Figure 5 – BSE / JSE<br>
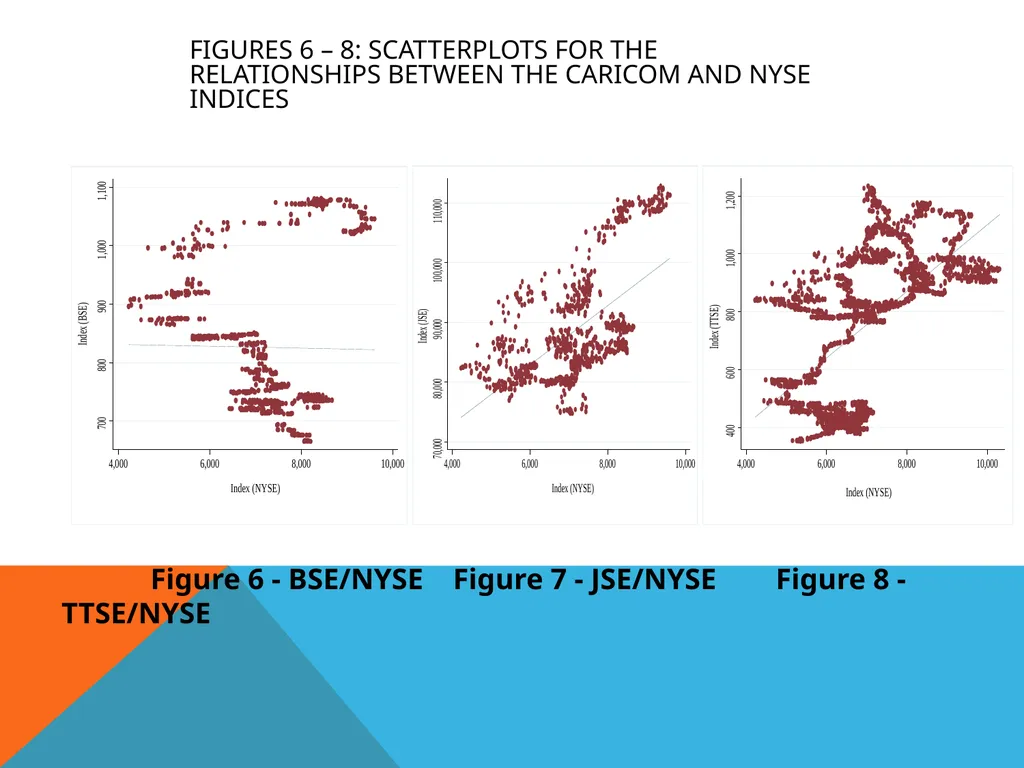
slide10. Figures 6 – 8: Scatterplots for the relationships between the CARICOM and NYSE Indices Figure 6 - BSE/NYSE Figure 7 - JSE/NYSE Figure 8 - TTSE/NYSE<br>
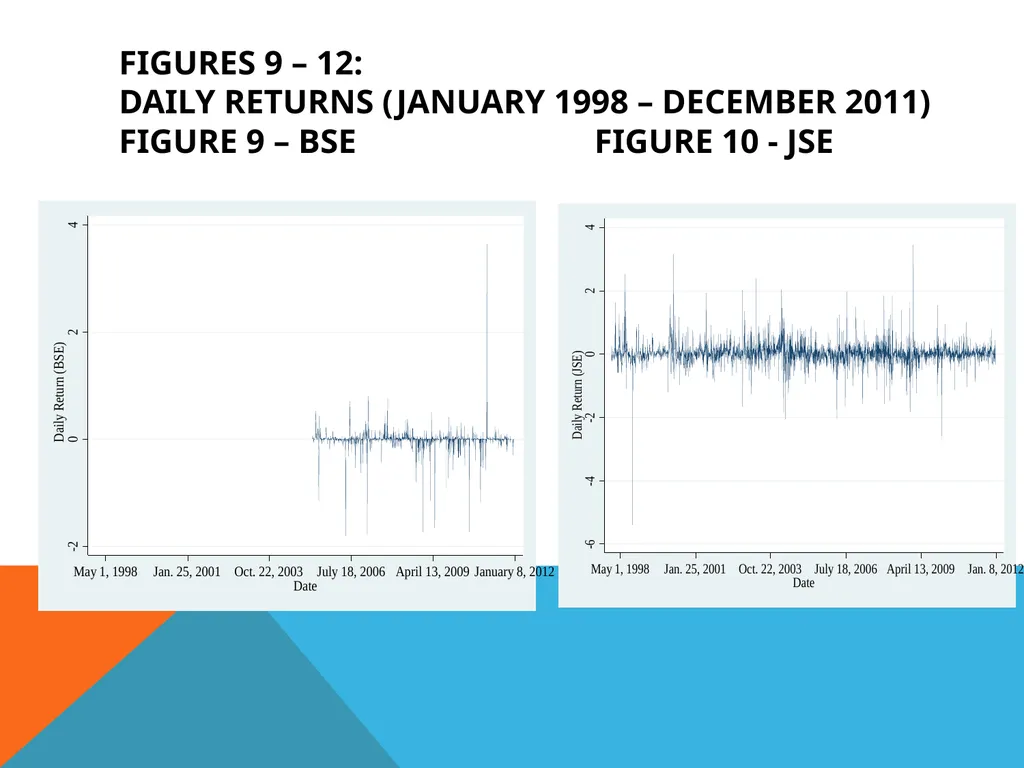
slide11. Figures 9 – 12: Daily Returns (January 1998 – December 2011) Figure 9 – BSE figure 10 - JSE<br>
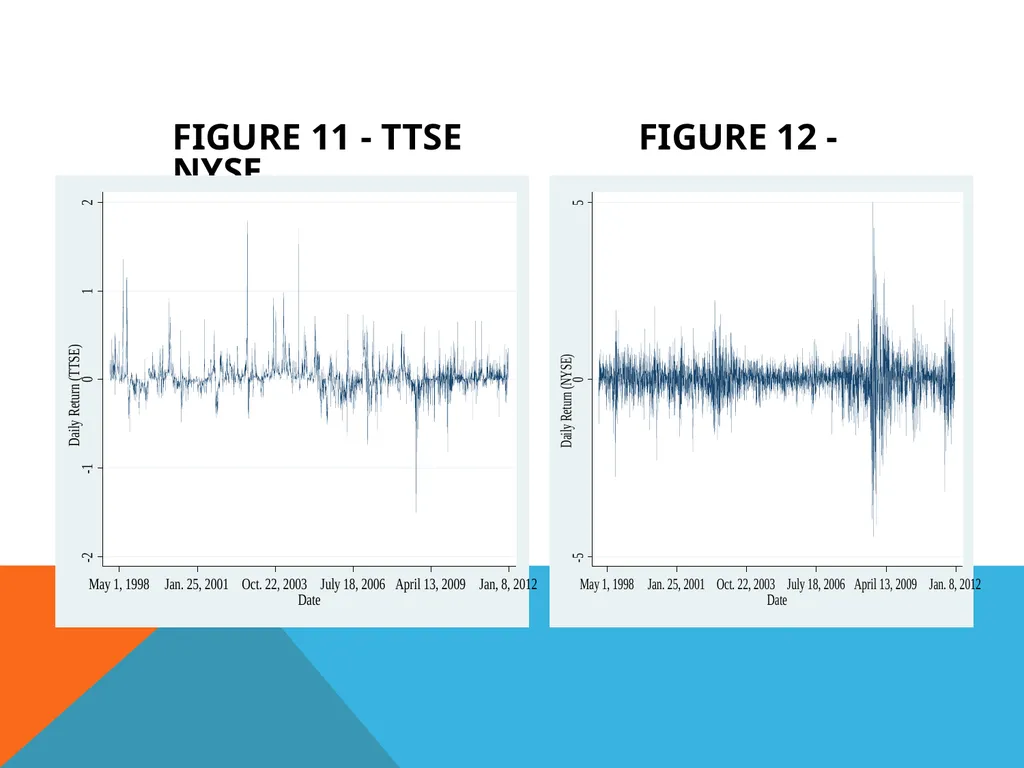
slide12. Figure 11 - TTSE Figure 12 - NYSE<br>
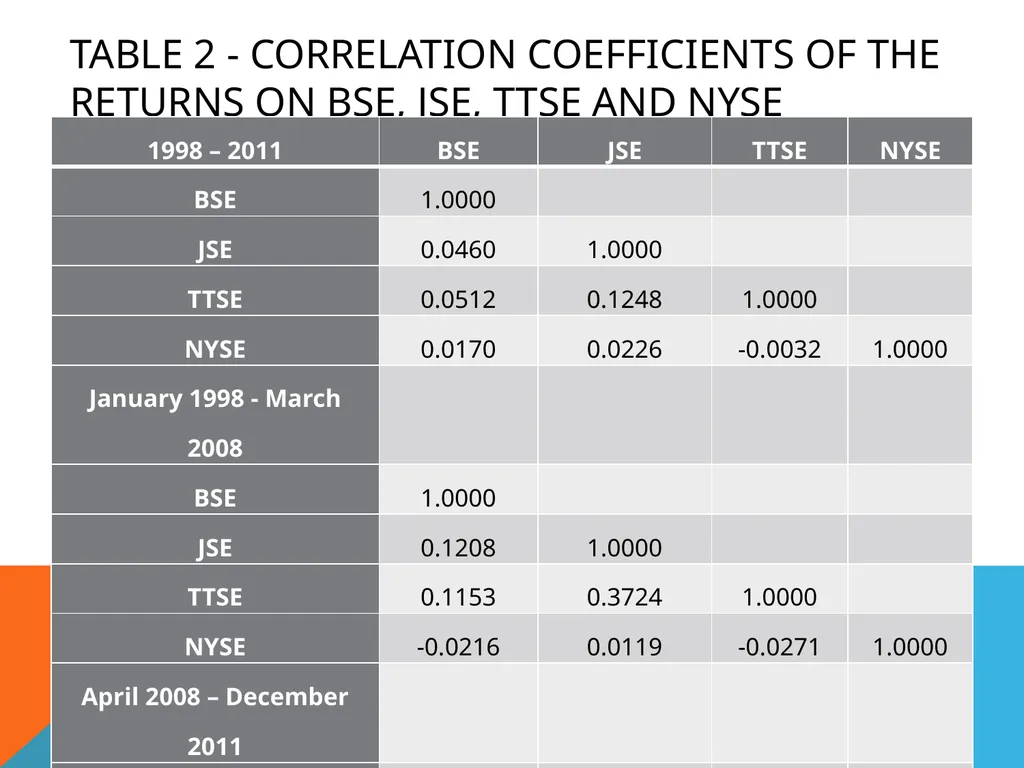
slide13. Table 2 - Correlation Coefficients of the returns on BSE, JSE, TTSE and NYSE<br>
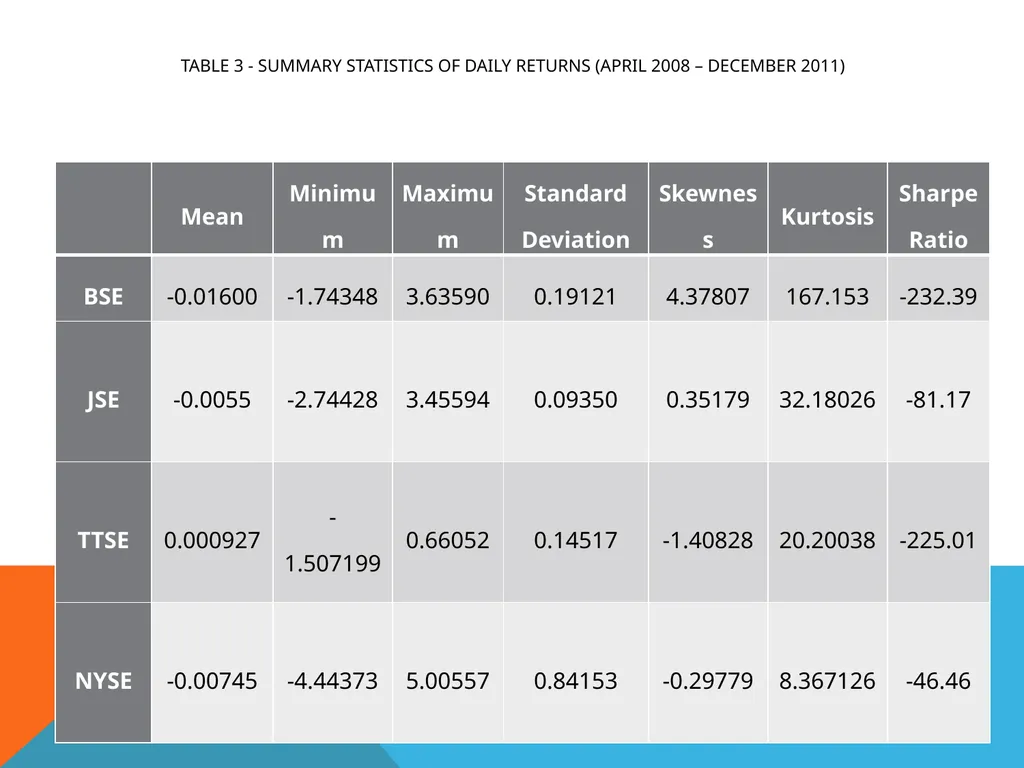
slide14. Table 3 - Summary Statistics of Daily Returns (April 2008 – December 2011)<br>
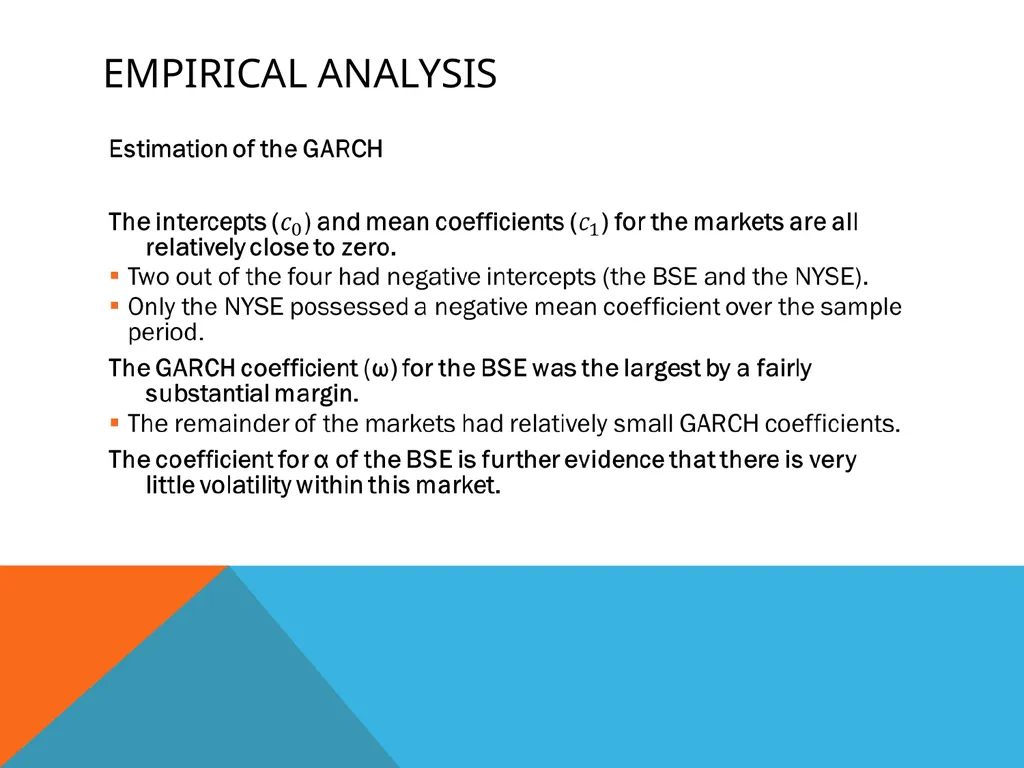
slide15. Empirical Analysis<br>
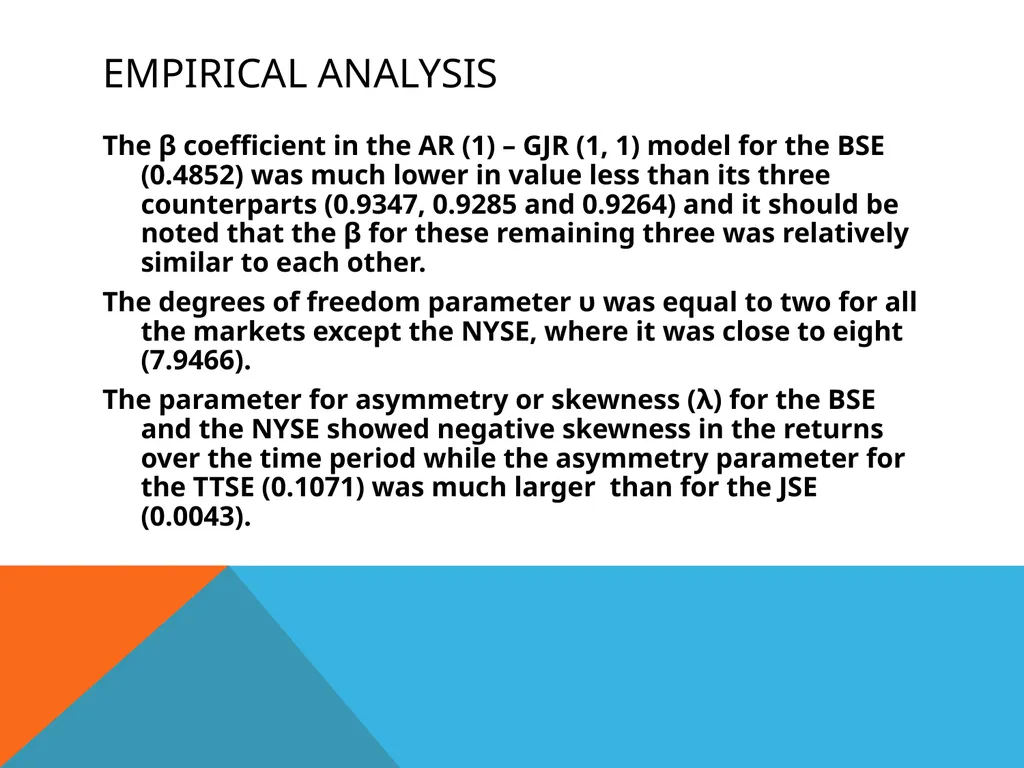
slide16. Empirical Analysis The β coefficient in the AR (1) – GJR (1, 1) model for the BSE (0.4852) was much lower in value less than its three counterparts (0.9347, 0.9285 and 0.9264) and it should be noted that the β for these remaining three was relatively similar to each other.
The degrees of freedom parameter υ was equal to two for all the markets except the NYSE, where it was close to eight (7.9466).
The parameter for asymmetry or skewness (λ) for the BSE and the NYSE showed negative skewness in the returns over the time period while the asymmetry parameter for the TTSE (0.1071) was much larger than for the JSE (0.0043).<br>
slide17. Empirical Analysis<br>
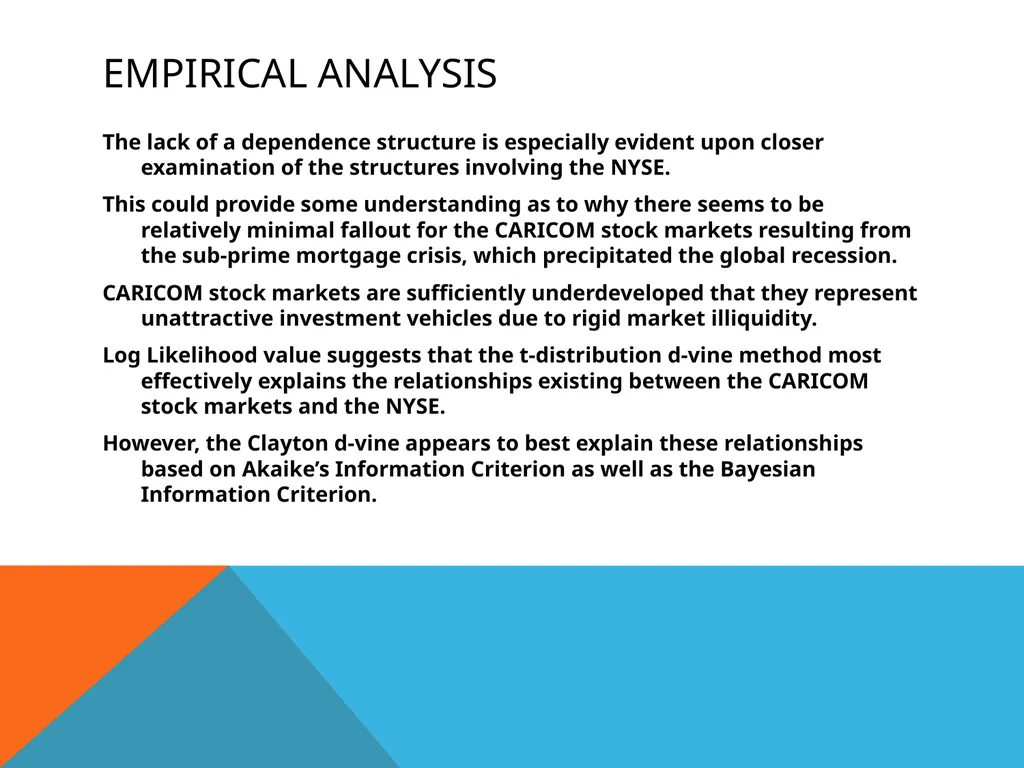
slide18. Empirical Analysis The lack of a dependence structure is especially evident upon closer examination of the structures involving the NYSE.
This could provide some understanding as to why there seems to be relatively minimal fallout for the CARICOM stock markets resulting from the sub-prime mortgage crisis, which precipitated the global recession.
CARICOM stock markets are sufficiently underdeveloped that they represent unattractive investment vehicles due to rigid market illiquidity.
Log Likelihood value suggests that the t-distribution d-vine method most effectively explains the relationships existing between the CARICOM stock markets and the NYSE.
However, the Clayton d-vine appears to best explain these relationships based on Akaike’s Information Criterion as well as the Bayesian Information Criterion.<br>
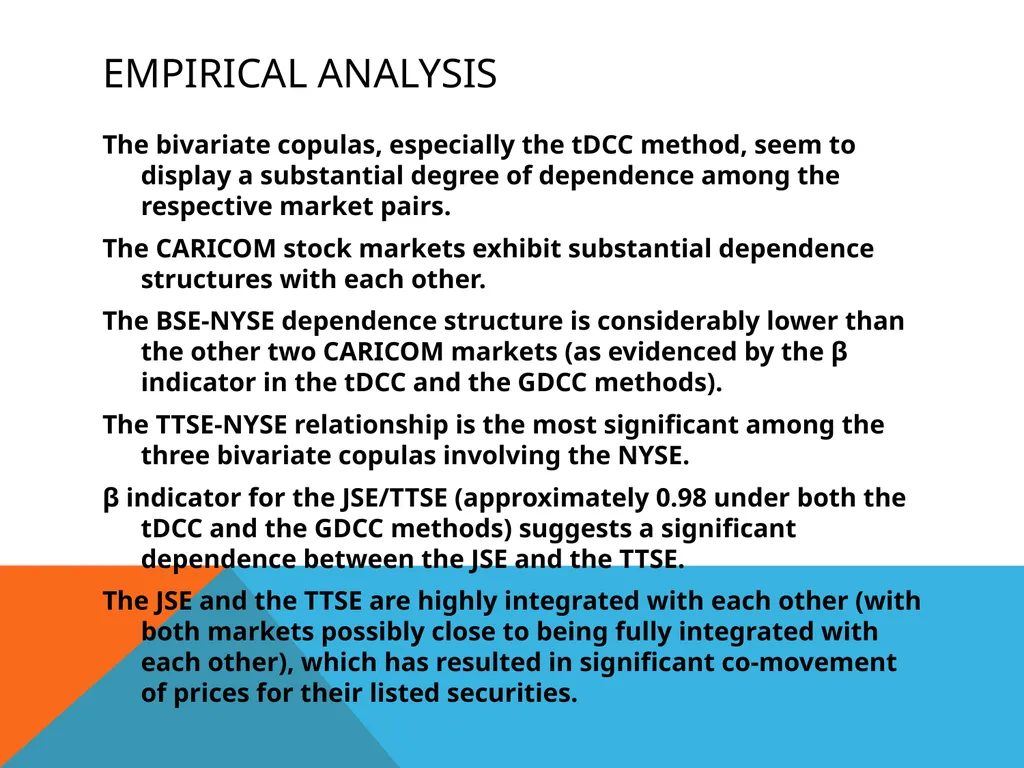
slide19. Empirical Analysis The bivariate copulas, especially the tDCC method, seem to display a substantial degree of dependence among the respective market pairs.
The CARICOM stock markets exhibit substantial dependence structures with each other.
The BSE-NYSE dependence structure is considerably lower than the other two CARICOM markets (as evidenced by the β indicator in the tDCC and the GDCC methods).
The TTSE-NYSE relationship is the most significant among the three bivariate copulas involving the NYSE.
β indicator for the JSE/TTSE (approximately 0.98 under both the tDCC and the GDCC methods) suggests a significant dependence between the JSE and the TTSE.
The JSE and the TTSE are highly integrated with each other (with both markets possibly close to being fully integrated with each other), which has resulted in significant co-movement of prices for their listed securities.<br>
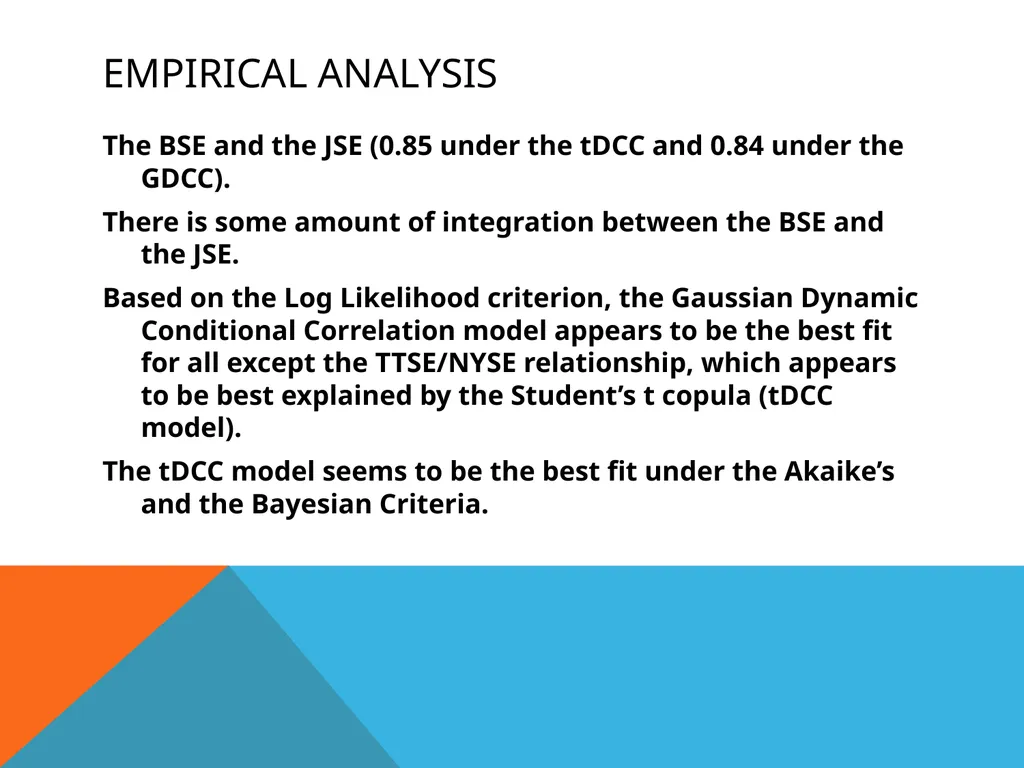
slide20. Empirical Analysis The BSE and the JSE (0.85 under the tDCC and 0.84 under the GDCC).
There is some amount of integration between the BSE and the JSE.
Based on the Log Likelihood criterion, the Gaussian Dynamic Conditional Correlation model appears to be the best fit for all except the TTSE/NYSE relationship, which appears to be best explained by the Student’s t copula (tDCC model).
The tDCC model seems to be the best fit under the Akaike’s and the Bayesian Criteria.<br>
slide21. Empirical Analysis<br>
slide22. Empirical Analysis There are some disparities in determining which of the three models has the best goodness of fit indicator.
If the Log Likelihood criterion is used for this purpose, the tvSJC copula is most appropriate for explaining the dependence structures for the BSE/TTSE and the JSE/TTSE.
The SJC copula is appropriate for the BSE/JSE.
The tvSJC copula is best for the BSE/JSE and the JSE/TTSE structures under the Akaike’s Information Criterion (the tvC copula for BSE/TTSE).
The tvSJC copula is arguably best fit for all three under the Bayesian Information Criterion.<br>
slide23. Empirical Analysis The copulas involving the NYSE (as seen in Table 8) yielded some interesting results.
JSE/NYSE: Negative in all of its parameters for the time varying Clayton copula (-7.4874, -1.7807 and -0.8482).
The estimations for the SJC copula show little to no difference between the tails and little variance occurring.
BSE/NYSE: The only one out of the three possible relationships which shows relative closeness between the β parameters for the lower and upper tails (2.2552 and 3.7025) when one analyses the tvSJC copula.
JSE/NYSE and the TTSE/NYSE: Significant differences between these parameters (0.3859, 8.6022 for the former and 0.7031, 4.0764 for the latter).<br>
slide24. Conclusions It can be argued that there appears to be co-movement in stock prices within the CARICOM stock markets.
This is evidenced by the derived bivariate copula estimations.
The tDCC copula estimations suggest significant dependence structures between the three CARICOM stock markets, with the most significant being the one between the JSE and the TTSE.<br>
slide25. Conclusions However, this does not seem to be fully the case for the structures between each of the CARICOM markets and the NYSE.
The TTSE is argued to possess the most developed dependence structure with the NYSE among the three CARICOM stock markets studied.
It can be argued that the level of dependence among the CARICOM markets, both as a group and individually, with the NYSE is underdeveloped and not as pronounced.
This could be an explanation why the regional markets were not as affected in the fallout from the U.S. originated financial crisis.<br>
slide26. Conclusions Further research may be needed to ascertain the factors which affect the dependence among the regional markets as well as whether it is important for the regional markets to strengthen the dependence structure with the NYSE.<br>
slide27. The end THANK YOU FOR YOUR ATTENTION.<br>
AND
PATRICK WATSON
Bbf5 confeRence
May 2-3, 2013<br>
slide2. Outline of Presentation Introduction
Methodology and Data
Empirical Analysis
Preliminary
Estimation of GARCH
Estimation of Copula
Conclusions<br>
slide3. Introduction Financial integration in the CARICOM Region
Importance of stock price comovement
Baur (2003)
Stock price comovement in the literature
Developed markets
Kim and Langrin (CARICOM markets)<br>
slide4. Methodology and Data Preliminary Analysis
Correlation coefficients
January 1, 1998 – December 31, 2011
January 1, 1998 – March 31, 2008
April 1, 2008 – December 31, 2011
Sharpe Ratio
GARCH-Copula
Bollerslev (2008)<br>
slide5. Methodology and Data Data
End of day values of the Composite Indices from January 1, 1998 – December 31, 2011
BSE
JSE
TTSE
NYSE
GARCH Copula: End of day values from April 1, 2008 – December 31, 2011<br>
slide6. Figure 1 – Evolution of Composite Indices (1998-2011)<br>
slide7. Figure 2 - Evolution of Composite Indices (April 1, 2008-December 31, 2011) (April 1, 2008-December 31, 2011)<br>
slide8. Table 1 - Correlation Coefficients for the Composite Indices<br>
slide9. Figures 3 – 5: Scatterplots for the relationships between the CARICOM Composite Indices Figure 3 - TTSE/BSE Figure 4 - TTSE/JSE Figure 5 – JSE/BSE Figure 3 – BSE / TTSE Figure 4 – JSE / TTSE Figure 5 – BSE / JSE<br>
slide10. Figures 6 – 8: Scatterplots for the relationships between the CARICOM and NYSE Indices Figure 6 - BSE/NYSE Figure 7 - JSE/NYSE Figure 8 - TTSE/NYSE<br>
slide11. Figures 9 – 12: Daily Returns (January 1998 – December 2011) Figure 9 – BSE figure 10 - JSE<br>
slide12. Figure 11 - TTSE Figure 12 - NYSE<br>
slide13. Table 2 - Correlation Coefficients of the returns on BSE, JSE, TTSE and NYSE<br>
slide14. Table 3 - Summary Statistics of Daily Returns (April 2008 – December 2011)<br>
slide15. Empirical Analysis<br>
slide16. Empirical Analysis The β coefficient in the AR (1) – GJR (1, 1) model for the BSE (0.4852) was much lower in value less than its three counterparts (0.9347, 0.9285 and 0.9264) and it should be noted that the β for these remaining three was relatively similar to each other.
The degrees of freedom parameter υ was equal to two for all the markets except the NYSE, where it was close to eight (7.9466).
The parameter for asymmetry or skewness (λ) for the BSE and the NYSE showed negative skewness in the returns over the time period while the asymmetry parameter for the TTSE (0.1071) was much larger than for the JSE (0.0043).<br>
slide17. Empirical Analysis<br>
slide18. Empirical Analysis The lack of a dependence structure is especially evident upon closer examination of the structures involving the NYSE.
This could provide some understanding as to why there seems to be relatively minimal fallout for the CARICOM stock markets resulting from the sub-prime mortgage crisis, which precipitated the global recession.
CARICOM stock markets are sufficiently underdeveloped that they represent unattractive investment vehicles due to rigid market illiquidity.
Log Likelihood value suggests that the t-distribution d-vine method most effectively explains the relationships existing between the CARICOM stock markets and the NYSE.
However, the Clayton d-vine appears to best explain these relationships based on Akaike’s Information Criterion as well as the Bayesian Information Criterion.<br>
slide19. Empirical Analysis The bivariate copulas, especially the tDCC method, seem to display a substantial degree of dependence among the respective market pairs.
The CARICOM stock markets exhibit substantial dependence structures with each other.
The BSE-NYSE dependence structure is considerably lower than the other two CARICOM markets (as evidenced by the β indicator in the tDCC and the GDCC methods).
The TTSE-NYSE relationship is the most significant among the three bivariate copulas involving the NYSE.
β indicator for the JSE/TTSE (approximately 0.98 under both the tDCC and the GDCC methods) suggests a significant dependence between the JSE and the TTSE.
The JSE and the TTSE are highly integrated with each other (with both markets possibly close to being fully integrated with each other), which has resulted in significant co-movement of prices for their listed securities.<br>
slide20. Empirical Analysis The BSE and the JSE (0.85 under the tDCC and 0.84 under the GDCC).
There is some amount of integration between the BSE and the JSE.
Based on the Log Likelihood criterion, the Gaussian Dynamic Conditional Correlation model appears to be the best fit for all except the TTSE/NYSE relationship, which appears to be best explained by the Student’s t copula (tDCC model).
The tDCC model seems to be the best fit under the Akaike’s and the Bayesian Criteria.<br>
slide21. Empirical Analysis<br>
slide22. Empirical Analysis There are some disparities in determining which of the three models has the best goodness of fit indicator.
If the Log Likelihood criterion is used for this purpose, the tvSJC copula is most appropriate for explaining the dependence structures for the BSE/TTSE and the JSE/TTSE.
The SJC copula is appropriate for the BSE/JSE.
The tvSJC copula is best for the BSE/JSE and the JSE/TTSE structures under the Akaike’s Information Criterion (the tvC copula for BSE/TTSE).
The tvSJC copula is arguably best fit for all three under the Bayesian Information Criterion.<br>
slide23. Empirical Analysis The copulas involving the NYSE (as seen in Table 8) yielded some interesting results.
JSE/NYSE: Negative in all of its parameters for the time varying Clayton copula (-7.4874, -1.7807 and -0.8482).
The estimations for the SJC copula show little to no difference between the tails and little variance occurring.
BSE/NYSE: The only one out of the three possible relationships which shows relative closeness between the β parameters for the lower and upper tails (2.2552 and 3.7025) when one analyses the tvSJC copula.
JSE/NYSE and the TTSE/NYSE: Significant differences between these parameters (0.3859, 8.6022 for the former and 0.7031, 4.0764 for the latter).<br>
slide24. Conclusions It can be argued that there appears to be co-movement in stock prices within the CARICOM stock markets.
This is evidenced by the derived bivariate copula estimations.
The tDCC copula estimations suggest significant dependence structures between the three CARICOM stock markets, with the most significant being the one between the JSE and the TTSE.<br>
slide25. Conclusions However, this does not seem to be fully the case for the structures between each of the CARICOM markets and the NYSE.
The TTSE is argued to possess the most developed dependence structure with the NYSE among the three CARICOM stock markets studied.
It can be argued that the level of dependence among the CARICOM markets, both as a group and individually, with the NYSE is underdeveloped and not as pronounced.
This could be an explanation why the regional markets were not as affected in the fallout from the U.S. originated financial crisis.<br>
slide26. Conclusions Further research may be needed to ascertain the factors which affect the dependence among the regional markets as well as whether it is important for the regional markets to strengthen the dependence structure with the NYSE.<br>
slide27. The end THANK YOU FOR YOUR ATTENTION.<br>