
Compiled by CMA Dr. Sanjay R. Bhargave. Value
LO
Published · 23 slides · 0 views
1 / 1
Description
Compiled by CMA Dr. Sanjay R. Bhargave. Value Creation through Indirect Taxes Post GST - Tax Structure in India Direct Taxes Income Tax Corporate Tax Wealth Tax Indirect Taxes Customs Duty GST Foreign Trade Policy CMA Dr. Sanjay R. Bhargave
Related Topics
Share
Embed code
Download this presentation From Below
"Compiled by CMA Dr. Sanjay R. Bhargave. Value" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Compiled by
CMA Dr. Sanjay R. Bhargave. Value Creation through Indirect Taxes<br>
CMA Dr. Sanjay R. Bhargave. Value Creation through Indirect Taxes<br>
02
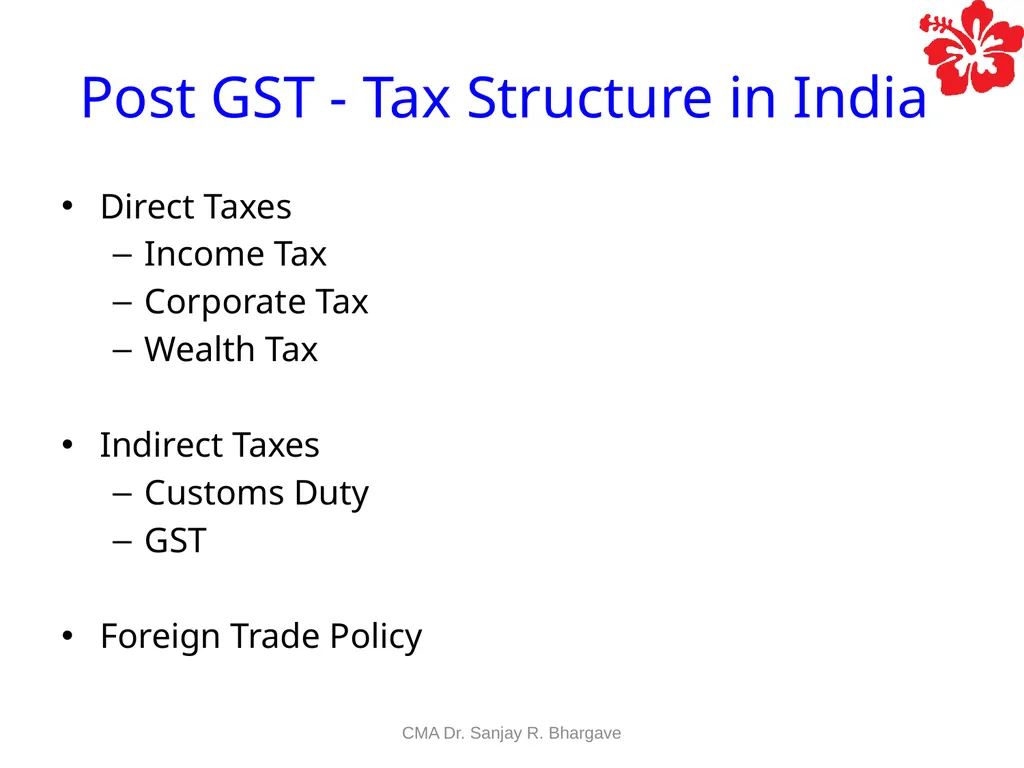
Post GST - Tax Structure in India Direct Taxes
Income Tax
Corporate Tax
Wealth Tax
Indirect Taxes
Customs Duty
GST
Foreign Trade Policy CMA Dr. Sanjay R. Bhargave<br>
Income Tax
Corporate Tax
Wealth Tax
Indirect Taxes
Customs Duty
GST
Foreign Trade Policy CMA Dr. Sanjay R. Bhargave<br>
03
Major defects in earlier
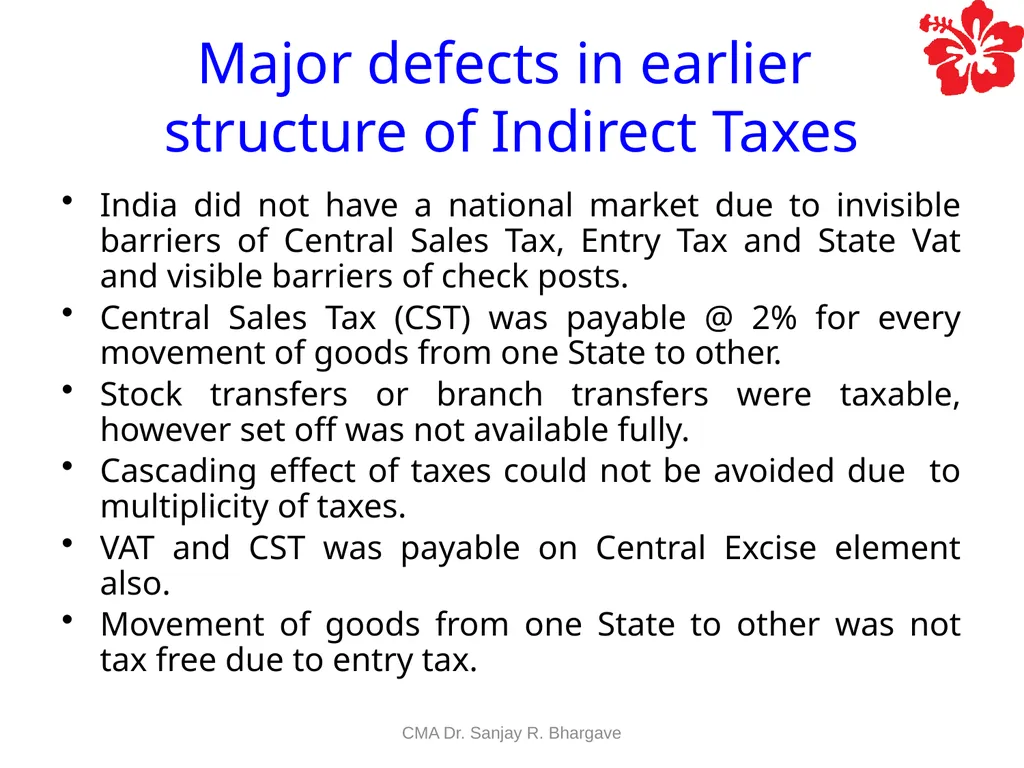
structure of Indirect Taxes India did not have a national market due to invisible barriers of Central Sales Tax, Entry Tax and State Vat and visible barriers of check posts.
Central Sales Tax (CST) was payable @ 2% for every movement of goods from one State to other.
Stock transfers or branch transfers were taxable, however set off was not available fully.
Cascading effect of taxes could not be avoided due to multiplicity of taxes.
VAT and CST was payable on Central Excise element also.
Movement of goods from one State to other was not tax free due to entry tax. CMA Dr. Sanjay R. Bhargave<br>
04
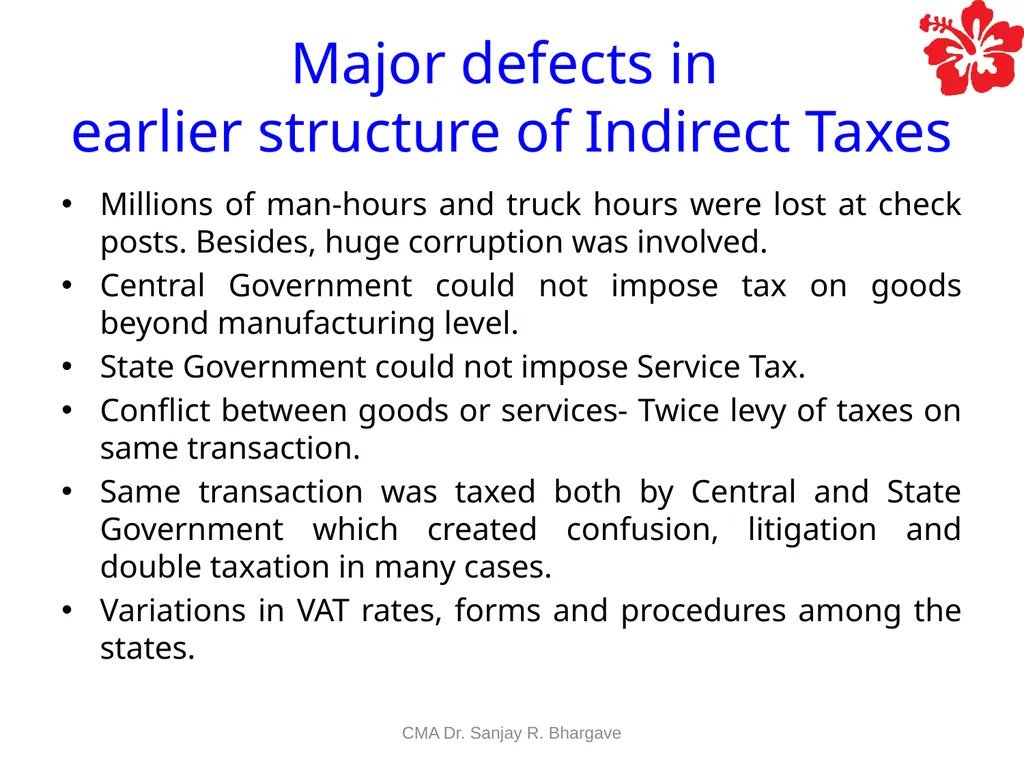
Millions of man-hours and truck hours were lost at check posts. Besides, huge corruption was involved.
Central Government could not impose tax on goods beyond manufacturing level.
State Government could not impose Service Tax.
Conflict between goods or services- Twice levy of taxes on same transaction.
Same transaction was taxed both by Central and State Government which created confusion, litigation and double taxation in many cases.
Variations in VAT rates, forms and procedures among the states. Major defects in earlier structure of Indirect Taxes CMA Dr. Sanjay R. Bhargave<br>
05
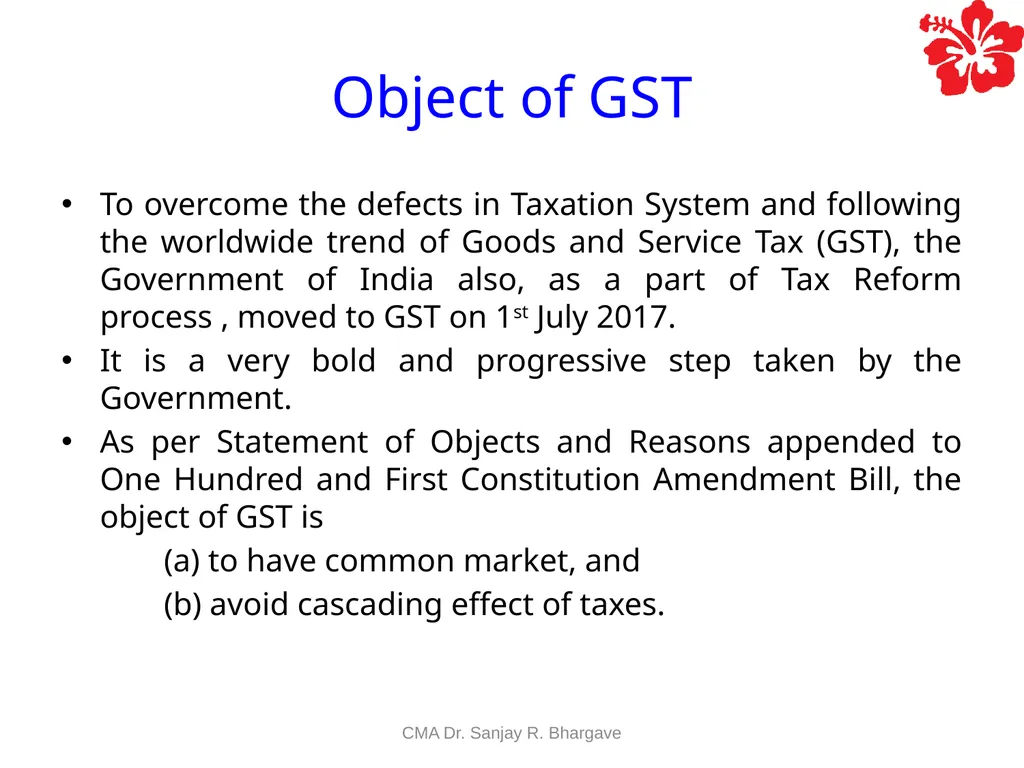
Object of GST To overcome the defects in Taxation System and following the worldwide trend of Goods and Service Tax (GST), the Government of India also, as a part of Tax Reform process , moved to GST on 1st July 2017.
It is a very bold and progressive step taken by the Government.
As per Statement of Objects and Reasons appended to One Hundred and First Constitution Amendment Bill, the object of GST is
(a) to have common market, and
(b) avoid cascading effect of taxes. CMA Dr. Sanjay R. Bhargave<br>
It is a very bold and progressive step taken by the Government.
As per Statement of Objects and Reasons appended to One Hundred and First Constitution Amendment Bill, the object of GST is
(a) to have common market, and
(b) avoid cascading effect of taxes. CMA Dr. Sanjay R. Bhargave<br>
06
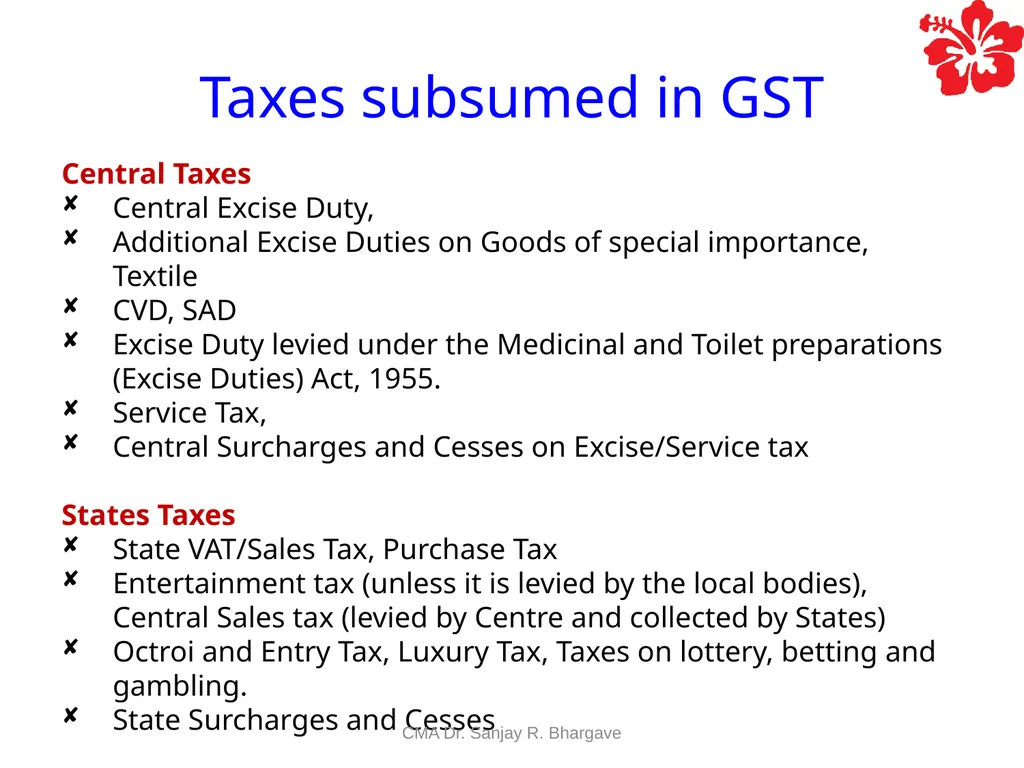
Taxes subsumed in GST Central Taxes
Central Excise Duty,
Additional Excise Duties on Goods of special importance, Textile
CVD, SAD
Excise Duty levied under the Medicinal and Toilet preparations (Excise Duties) Act, 1955.
Service Tax,
Central Surcharges and Cesses on Excise/Service tax
States Taxes
State VAT/Sales Tax, Purchase Tax
Entertainment tax (unless it is levied by the local bodies), Central Sales tax (levied by Centre and collected by States)
Octroi and Entry Tax, Luxury Tax, Taxes on lottery, betting and gambling.
State Surcharges and Cesses CMA Dr. Sanjay R. Bhargave<br>
07
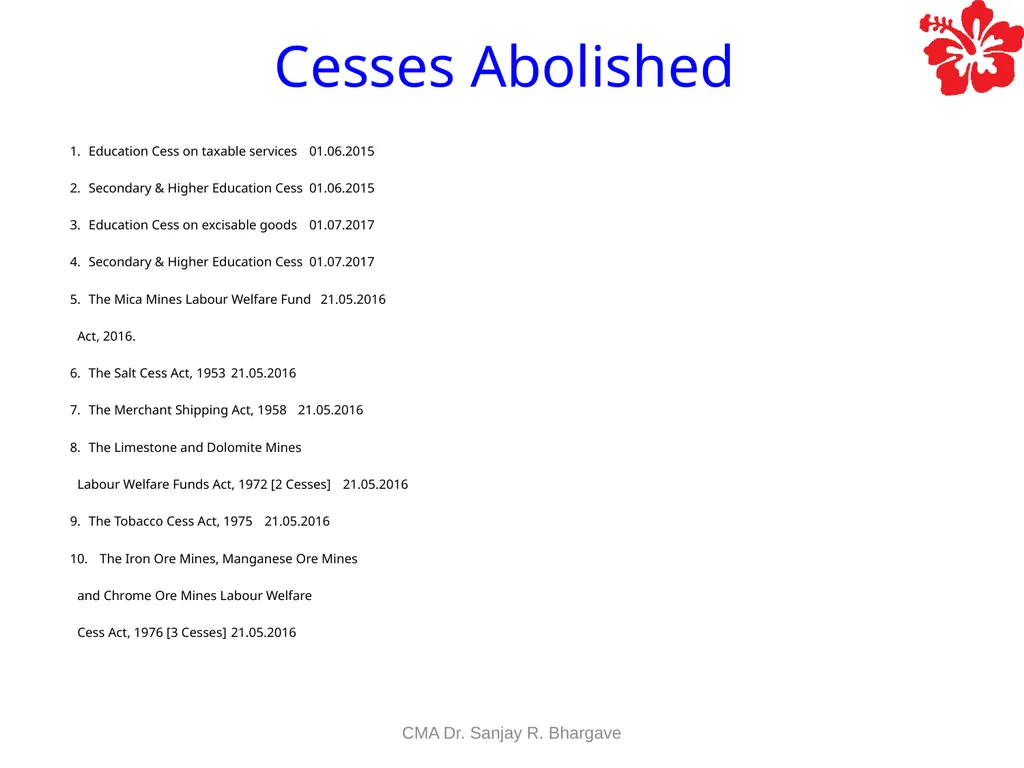
Cesses Abolished 1. Education Cess on taxable services 01.06.2015
2. Secondary & Higher Education Cess 01.06.2015
3. Education Cess on excisable goods 01.07.2017
4. Secondary & Higher Education Cess 01.07.2017
5. The Mica Mines Labour Welfare Fund 21.05.2016
Act, 2016.
6. The Salt Cess Act, 1953 21.05.2016
7. The Merchant Shipping Act, 1958 21.05.2016
8. The Limestone and Dolomite Mines
Labour Welfare Funds Act, 1972 [2 Cesses] 21.05.2016
9. The Tobacco Cess Act, 1975 21.05.2016
10. The Iron Ore Mines, Manganese Ore Mines
and Chrome Ore Mines Labour Welfare
Cess Act, 1976 [3 Cesses] 21.05.2016 CMA Dr. Sanjay R. Bhargave<br>
08
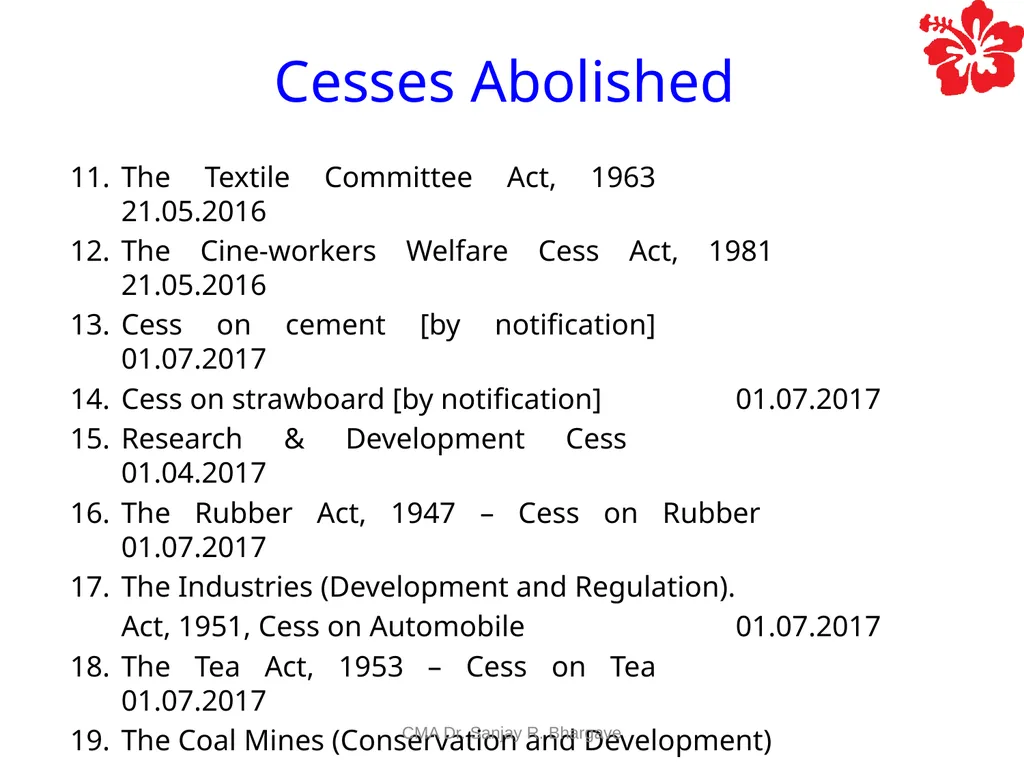
Cesses Abolished The Textile Committee Act, 1963 21.05.2016
The Cine-workers Welfare Cess Act, 1981 21.05.2016
Cess on cement [by notification] 01.07.2017
Cess on strawboard [by notification] 01.07.2017
Research & Development Cess 01.04.2017
The Rubber Act, 1947 – Cess on Rubber 01.07.2017
The Industries (Development and Regulation).
Act, 1951, Cess on Automobile 01.07.2017
The Tea Act, 1953 – Cess on Tea 01.07.2017
The Coal Mines (Conservation and Development)
Act, 1974 – Cess on Coal 01.07.2017
20. The Bidi Workers’ Welfare Cess Act, 1976 –
Cess on Bidis 01.07.2017 CMA Dr. Sanjay R. Bhargave<br>
09
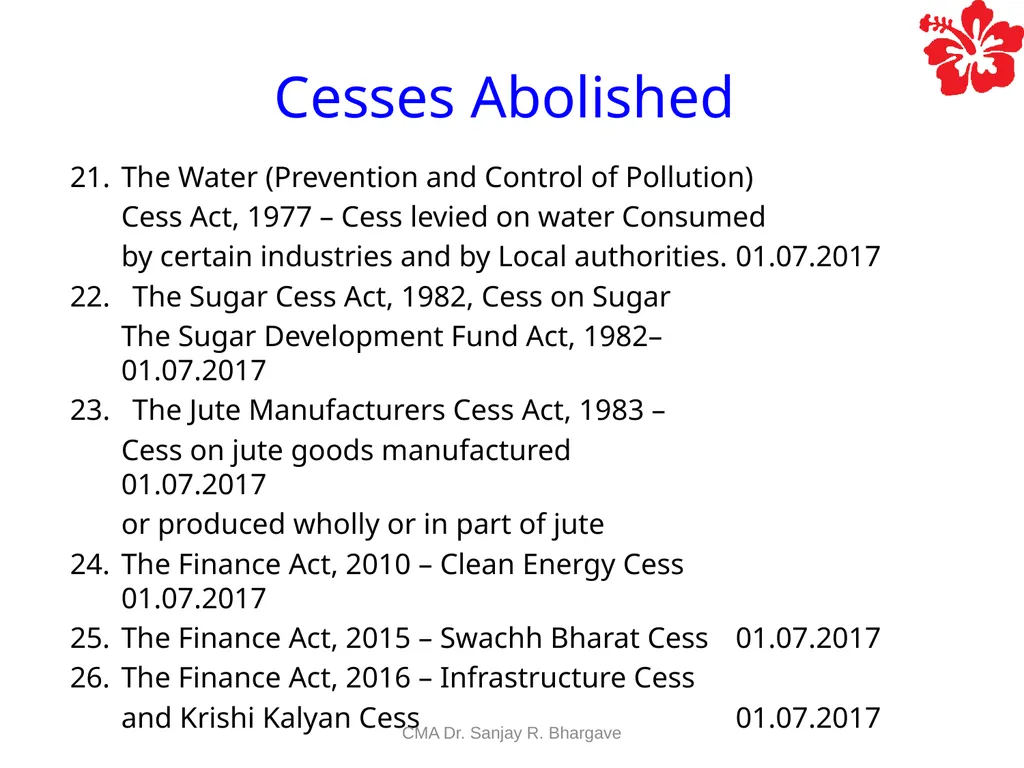
Cesses Abolished 21. The Water (Prevention and Control of Pollution)
Cess Act, 1977 – Cess levied on water Consumed
by certain industries and by Local authorities. 01.07.2017
22. The Sugar Cess Act, 1982, Cess on Sugar
The Sugar Development Fund Act, 1982– 01.07.2017
23. The Jute Manufacturers Cess Act, 1983 –
Cess on jute goods manufactured 01.07.2017
or produced wholly or in part of jute
The Finance Act, 2010 – Clean Energy Cess 01.07.2017
The Finance Act, 2015 – Swachh Bharat Cess 01.07.2017
The Finance Act, 2016 – Infrastructure Cess
and Krishi Kalyan Cess 01.07.2017 CMA Dr. Sanjay R. Bhargave<br>
10
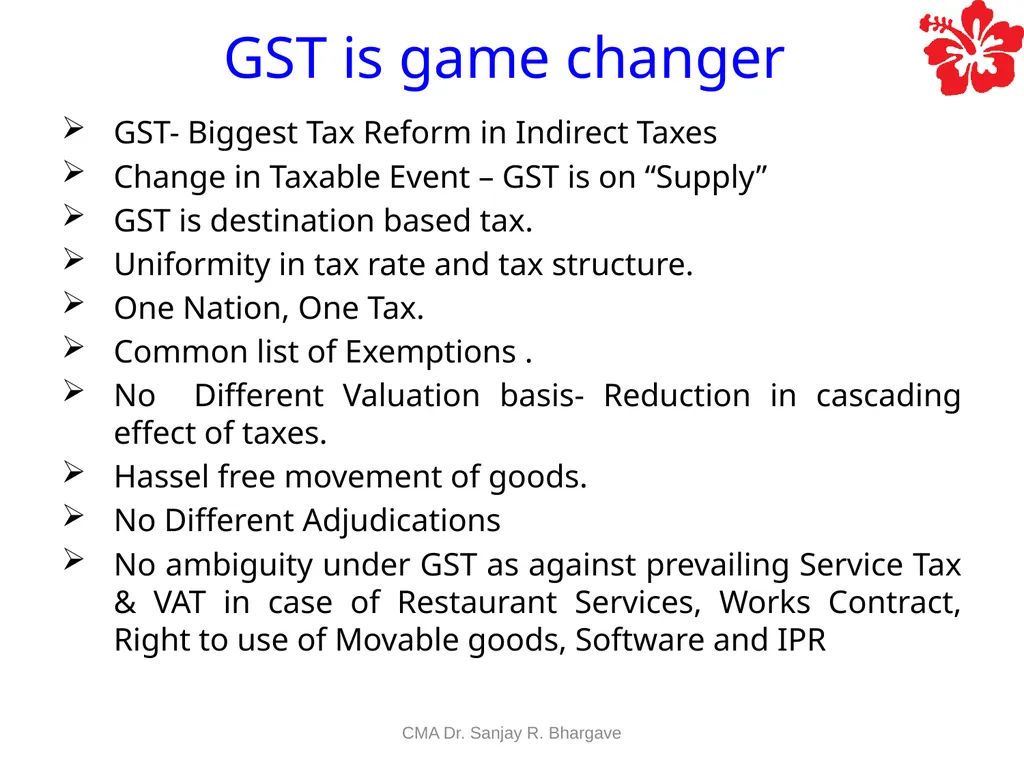
GST- Biggest Tax Reform in Indirect Taxes
Change in Taxable Event – GST is on “Supply”
GST is destination based tax.
Uniformity in tax rate and tax structure.
One Nation, One Tax.
Common list of Exemptions .
No Different Valuation basis- Reduction in cascading effect of taxes.
Hassel free movement of goods.
No Different Adjudications
No ambiguity under GST as against prevailing Service Tax & VAT in case of Restaurant Services, Works Contract, Right to use of Movable goods, Software and IPR GST is game changer CMA Dr. Sanjay R. Bhargave<br>
11
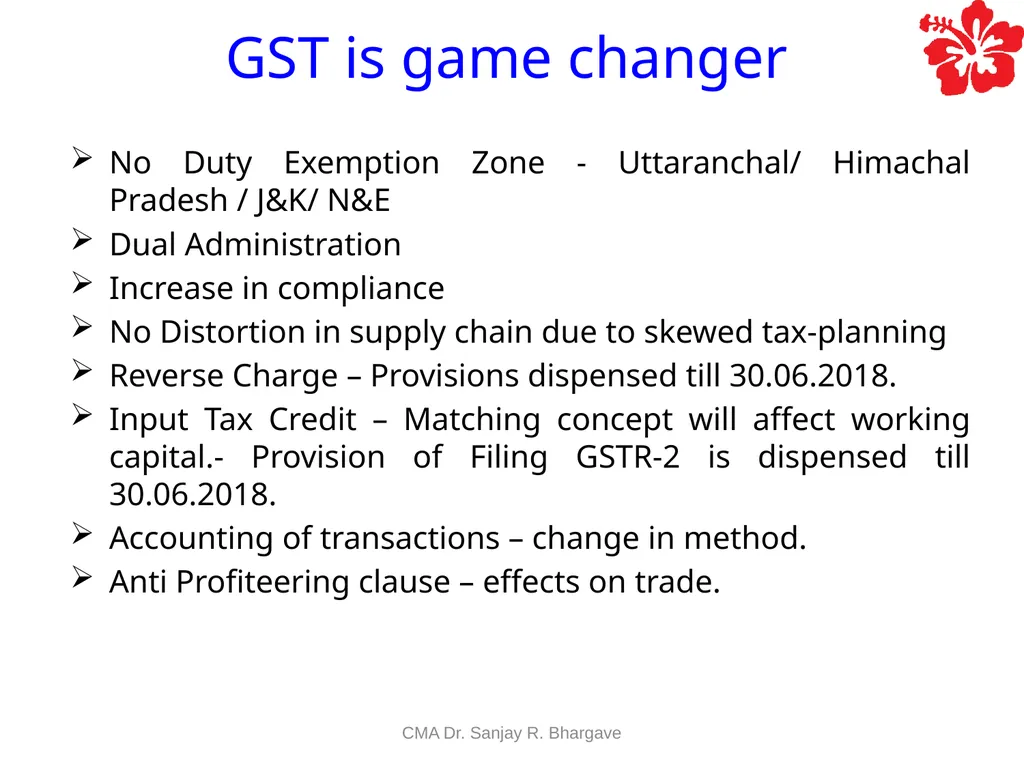
GST is game changer No Duty Exemption Zone - Uttaranchal/ Himachal Pradesh / J&K/ N&E
Dual Administration
Increase in compliance
No Distortion in supply chain due to skewed tax-planning
Reverse Charge – Provisions dispensed till 30.06.2018.
Input Tax Credit – Matching concept will affect working capital.- Provision of Filing GSTR-2 is dispensed till 30.06.2018.
Accounting of transactions – change in method.
Anti Profiteering clause – effects on trade. CMA Dr. Sanjay R. Bhargave<br>
12
Opportunities Trade and Business :-
Common Economic Market
Restructuring of business .
Improvement in supply chain management.
Reduction in corruption.
More opportunities to professionals.
Government :-
Growth of revenue in States and Union .
Development in Infrastructure of the Country
Reduction in transaction cost.
Better control on tax administration
Creating Trust amongst the other countries. CMA Dr. Sanjay R. Bhargave<br>
13
Opportunities Researchers :-
Impact of GST on regional growth
Impact on Society.
Exploring Tax Planning under GST.
Impact on Transaction Cost.
Strengthening Internal Control to have better compliance under GST. CMA Dr. Sanjay R. Bhargave<br>
Impact of GST on regional growth
Impact on Society.
Exploring Tax Planning under GST.
Impact on Transaction Cost.
Strengthening Internal Control to have better compliance under GST. CMA Dr. Sanjay R. Bhargave<br>
14
Challenges Trade and Business :-
More competition
Compliance under GST
Lack of awareness in initial phase-Determination of correct taxes
Meeting Working Capital requirements.
Robust IT infrastructure-Computer literacy among the tax payers
Government :-
Allocation of revenue to states
Compensation to States and Local Bodies.
Effect on Regional Growth.
Controlling inflation
Curb Tax evasion.
Creating trust amongst tax payers. CMA Dr. Sanjay R. Bhargave<br>
15
General:-
GST preparedness among tax payers as well as Government is missing
Lack of clarity on GST provisions-Half cooked meal
Increased compliance, with increase in the number of returns to be filed annually
Preparedness of IT system- GSTN is backbone of GST
Lack of skilled resources and need for change in mind set CMA Dr. Sanjay R. Bhargave Challenges<br>
16
Value Creation Understand the Law
Understand the Business of the Client.
Understand the procedures and systems followed by client.
Identify Gaps
Change focus from compliance to value creation
Indentify scope for re engineering
Explore possibilities of Tax Planning
Explore possibilities of Cost Reduction CMA Dr. Sanjay R. Bhargave<br>
17
Scope for Re Engineering Supply Chain Management
Movement of Goods
Hub and Spokes arrangement for distribution
Warehousing Services – scope for outsourcing
Inventory Management – JIT
Centralized vs Decentralized Billing CMA Dr. Sanjay R. Bhargave<br>
Movement of Goods
Hub and Spokes arrangement for distribution
Warehousing Services – scope for outsourcing
Inventory Management – JIT
Centralized vs Decentralized Billing CMA Dr. Sanjay R. Bhargave<br>
18
Procurement of Goods Imports
Concessional rate of duty in case of imports from preferential trade countries.
Project Imports
Advance Authorization, DFIA
EPCG
BCD payments by using licenses available in the markets CMA Dr. Sanjay R. Bhargave<br>
Concessional rate of duty in case of imports from preferential trade countries.
Project Imports
Advance Authorization, DFIA
EPCG
BCD payments by using licenses available in the markets CMA Dr. Sanjay R. Bhargave<br>
19
Procurement of Goods Domestic
Outsourcing compliance in various states.
Job work planning
Input Tax Credits on border line cases
ISD vs Cross charge
Whether to claim conditional exemptions.
CST – no longer a cost.
Negotiations with Vendors in view of Anti Profiteering. CMA Dr. Sanjay R. Bhargave<br>
Outsourcing compliance in various states.
Job work planning
Input Tax Credits on border line cases
ISD vs Cross charge
Whether to claim conditional exemptions.
CST – no longer a cost.
Negotiations with Vendors in view of Anti Profiteering. CMA Dr. Sanjay R. Bhargave<br>
20
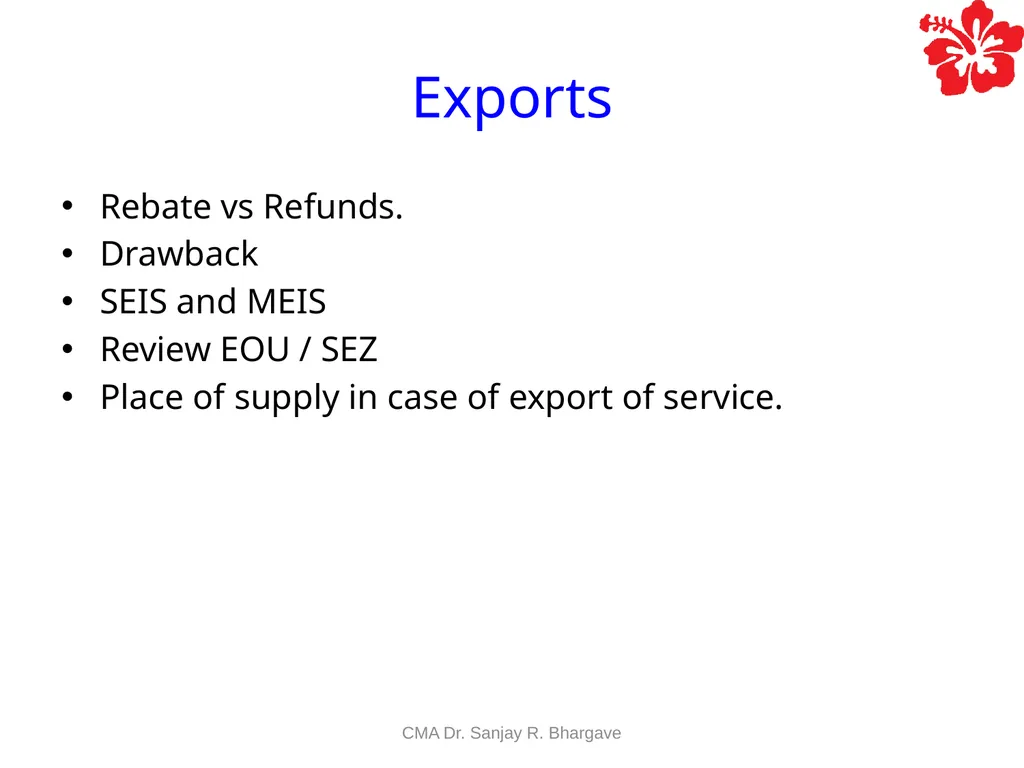
Exports Rebate vs Refunds.
Drawback
SEIS and MEIS
Review EOU / SEZ
Place of supply in case of export of service. CMA Dr. Sanjay R. Bhargave<br>
Drawback
SEIS and MEIS
Review EOU / SEZ
Place of supply in case of export of service. CMA Dr. Sanjay R. Bhargave<br>
21
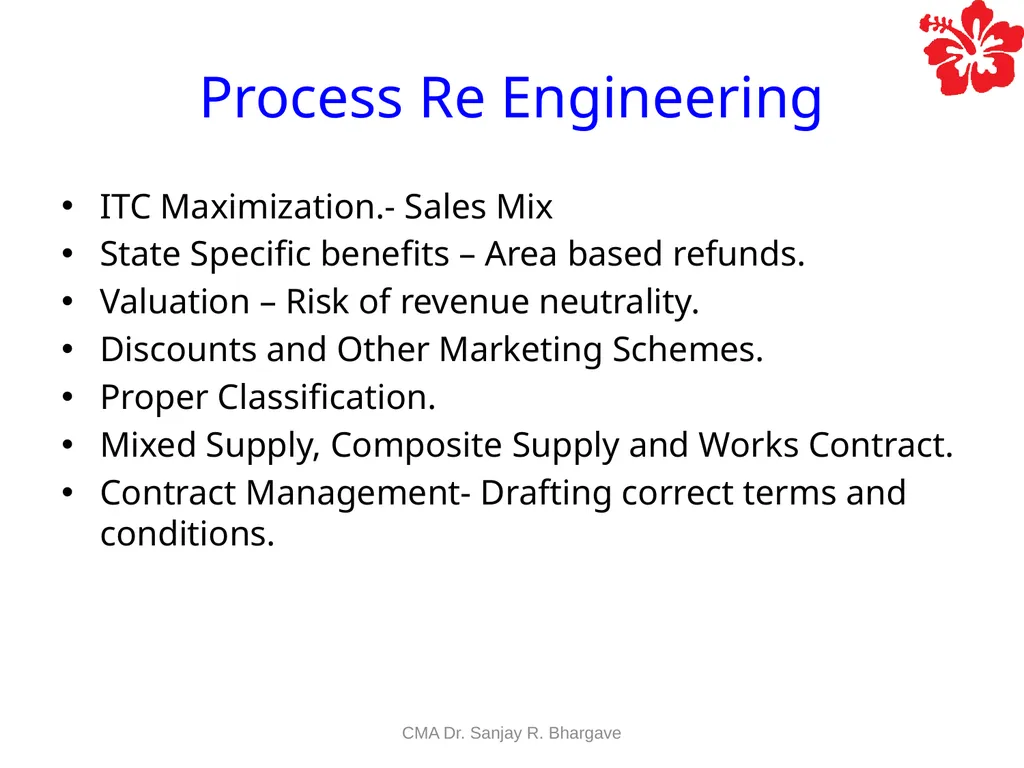
Process Re Engineering ITC Maximization.- Sales Mix
State Specific benefits – Area based refunds.
Valuation – Risk of revenue neutrality.
Discounts and Other Marketing Schemes.
Proper Classification.
Mixed Supply, Composite Supply and Works Contract.
Contract Management- Drafting correct terms and conditions. CMA Dr. Sanjay R. Bhargave<br>
State Specific benefits – Area based refunds.
Valuation – Risk of revenue neutrality.
Discounts and Other Marketing Schemes.
Proper Classification.
Mixed Supply, Composite Supply and Works Contract.
Contract Management- Drafting correct terms and conditions. CMA Dr. Sanjay R. Bhargave<br>
22
Suggested Steps GST Due Diligence – Health Check.
Avoid unpleasant surprises – interest and penalties
Periodical internal control review.
Cross Audit
Knowledge updation and Training Programmes. CMA Dr. Sanjay R. Bhargave<br>
Avoid unpleasant surprises – interest and penalties
Periodical internal control review.
Cross Audit
Knowledge updation and Training Programmes. CMA Dr. Sanjay R. Bhargave<br>
23
Thank You
CMA Dr. Sanjay Bhargave
sanjaybhargave@bhargaves.com
bhargaves@vsnl.net
9822045215 CMA Dr. Sanjay R. Bhargave<br>
CMA Dr. Sanjay Bhargave
sanjaybhargave@bhargaves.com
bhargaves@vsnl.net
9822045215 CMA Dr. Sanjay R. Bhargave<br>