
CONCEPT OF VALUATION CMA PRANAB KR.CHAKRABARTY

Description: CONCEPT OF VALUATION CMA PRANAB KR.CHAKRABARTY VALUATION MEANING As per dictionary meaning- an estimation of the worth of something , especially one carried out by a professional valuer. International Valuation Standard Council has defined
Related Topics
Download Presentation
"CONCEPT OF VALUATION CMA PRANAB KR.CHAKRABARTY" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. CONCEPT OF VALUATION
CMA PRANAB KR.CHAKRABARTY<br>
slide2. VALUATION MEANING As per dictionary meaning- an estimation of the worth of something , especially one carried out by a professional valuer.
International Valuation Standard Council has defined Valuation as :
“ the process of determining the ‘Economic Worth’ of an Asset or Company under certain assumptions and limiting conditions and subject to the data available on the valuation date.<br>
slide3. Valuation Introduction “Some men know the price of everything and the value of nothing “ - Oscar Wilde
“ Appraisers have a value in mind before they start the process and try to back into it”
- Aswath Damaodaran, Jan 14,2009
“ There is a vast difference between understanding something well enough to buy it as opposed to understanding it well enough to sell it.”
- Zig Ziglar, Secrets of Closing the Sale, 1984<br>
slide4. It determine 3 factors :
Cost : Expenditure incurred to produce a commodity having a value - Historical fact.
Price : Additional reward to the producer for the labour and capital involved – Value Consideration
Value : Opinion and varies from purpose to purpose- enjoyment benefit.<br>
slide5. Why Valuation ? To understand the worth of the Business .
For expanding the Business .
To see a baseline value for the business and develop a strategy to improve the profitability of the business and increase the value of the business for an exit strategy.
To evaluate an offer and negotiate a strategic sale of a business .
To determine the annual per share value of an Employee Stock Ownership Plan (ESOP)<br>
slide6. Why Valuation ? To identify the weakness of the business to refocus the operational efforts to improve the profitability and the bottom line .
For Buying and selling and funding for the New Project.
To evaluate the Equity Value .
Financial Reporting Purposes.
Determine the intrinsic value .
Determine the value for Insolvency and Liquidation.
Determine the value for winding up, Merger & Acquisition.<br>
slide7. Areas for Valuation Merger and Acquisition.
Fund raising .
Sale or Reconstruction of the Business.
Issue of Shares , ESOP, Sweat Equity , Buy Back .
Impairment of Assets.
FDI and Foreign Exchange related transaction.
Insolvency and Liquidation Process.
Legal and Statutory obligation.
Insurance Valuation.<br>
slide8. Types of Value Book Value- Value in the Balance Sheet
Market Value – Price at which Buyer & Seller trades.
Fair Market Value – Municipal Valuation, Insurance Industry.
Intrinsic Value – True Value of an Asset both in respect of tangible & intangible factors. It may not be same as current market value .
Extrinsic Value –When option price is greater than the intrinsic value , difference price is called as extrinsic value.
Going concern is always greater than the liquidation value.
Security or Financial Assets.<br>
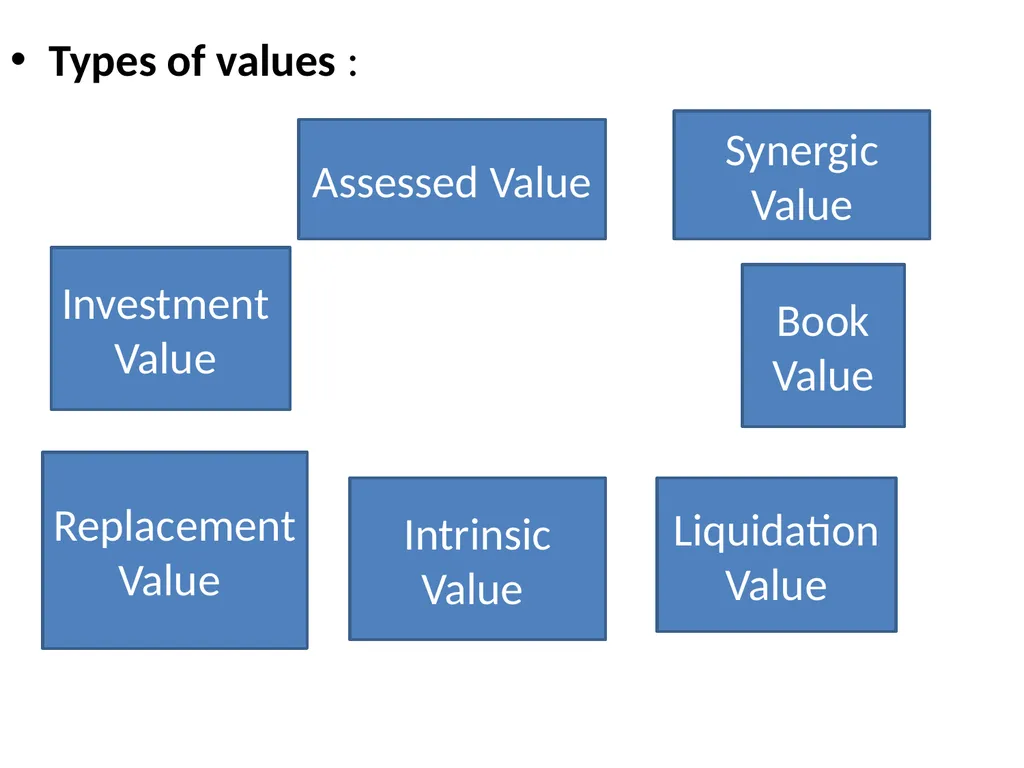
slide9. Types of values : Assessed Value Investment Value Replacement Value Book Value Liquidation Value Intrinsic Value Synergic Value<br>
slide10. Class of Assets Land & Building.
Plant & Machinery
Security or Financial Assets.<br>
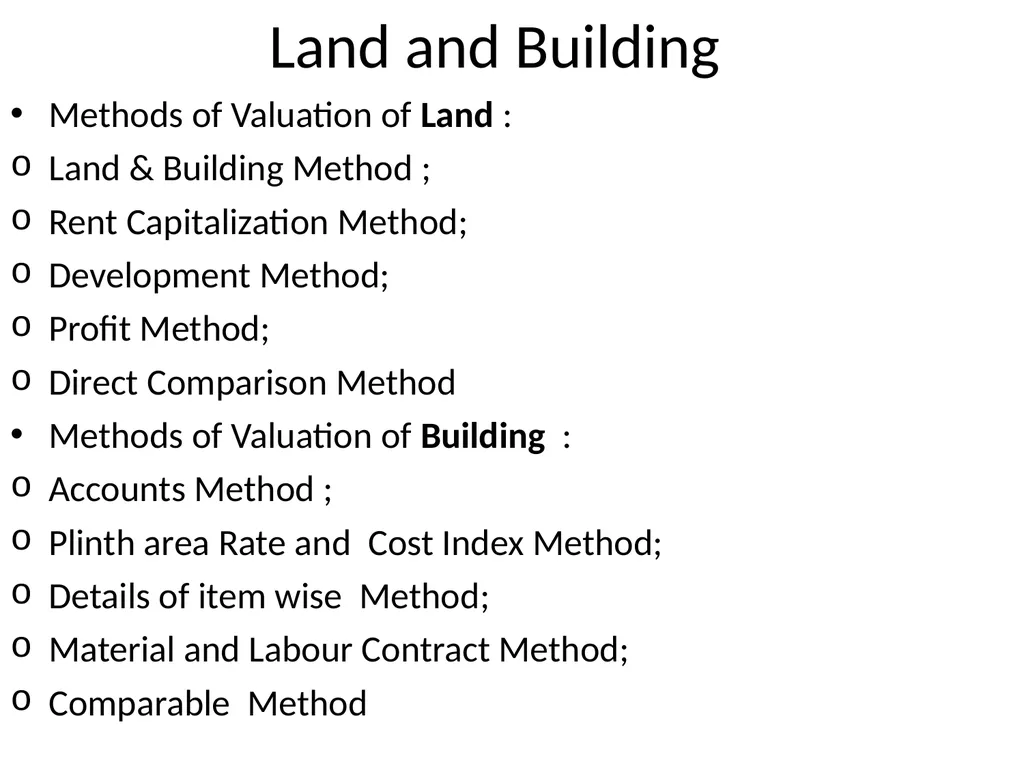
slide11. Land and Building Methods of Valuation of Land :
Land & Building Method ;
Rent Capitalization Method;
Development Method;
Profit Method;
Direct Comparison Method
Methods of Valuation of Building :
Accounts Method ;
Plinth area Rate and Cost Index Method;
Details of item wise Method;
Material and Labour Contract Method;
Comparable Method<br>
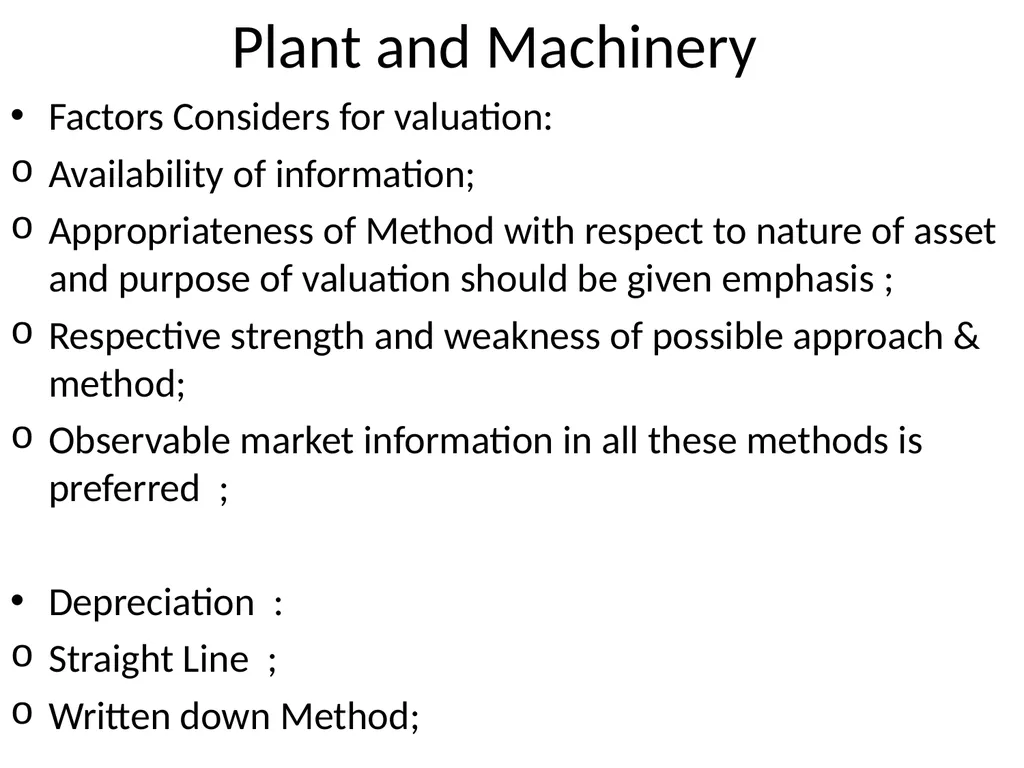
slide12. Plant and Machinery Factors Considers for valuation:
Availability of information;
Appropriateness of Method with respect to nature of asset and purpose of valuation should be given emphasis ;
Respective strength and weakness of possible approach & method;
Observable market information in all these methods is preferred ;
Depreciation :
Straight Line ;
Written down Method;<br>
slide13. Approaches Income
Market
Cost .<br>
slide14. Valuation Rules 2017 Under Chapter XVII ,Section 247 of the Companies Act,’13 governs the provisions of valuations and the Registered Valuers .
Valuation Rules,2017 has been notified on 18th October,2017 .
Registered Valuer has to be registered with the authority for carrying out valuation of the class , the valuer been registered .
The valuer shall also be registered with the Registered Valuer Organization of an asset class , the organization been recognized by the authority.<br>
slide15. Valuation Rules in a nutshell Structure – 6 Chapters,21 Rules,5 forms,4 annex.
Registering Authority –IBBI.
Valuer –Passed the Valuation Examination.
RVO – Registered U/s 25 of the Companies Act’56/Section 8 of the Companies Act’13.
Valuation Standard – To follow the International Valuation Standard,2017 , till the standard is formulated by the Central Govt. in consultation with the RVOs.
Valuation Standard as specified by the SEBI/RBI/any other specified authority.<br>
slide16. Areas of Valuation Valuation for further issue of shares
Valuation of Assets involved in arrangement of Non Cash transaction involving Directors .
Valuation of Assets under debt restructuring.
Valuation under scheme of Compromise/Arrangement;
Valuation of Eq. Shares held by the Minority Sh-holding.
Valuation Report to be submitted to the liquidator.
Report of experts for valuation for circulation to creditor/members<br>
slide17. Valuation under the Companies Act Section 62(1)© - Further Issue of Shares – Issue is authorised by the Spl.Resolution & Price is determined by the Regd.Valuer.
Non Cash transaction by the Director shall be approved in AGM and value shall be approved by the Valuer u/s 192(2).
Compromise/arrangement with creditor and members u/s 230(2)(iv) through NCLT on the basis of Valuation Report by Regd Valuer.
Purchase of minority shareholding of 10% or below u/s 236(2) is to be paid on the basis of report of Regd. Valuer<br>
slide18. Valuation under the Companies Act’13 Section 281(1)(a) – Winding up of a Company Valuer report is to be submitted to the NCLT.
Section 305(2) – Voluntary winding up of a company for solvency requires report of the Regd.Valuer.<br>
slide19. SEBI’s regulatory requirement SEBI (ISSUE OF CAPITAL AND DISCLOSURE REQUIREMENTS)
Regulations, 2009
SEBI (LISTING OBLIGATIONS AND DISCLOSURE REQUIREMENTS) REGULATIONS, 2015
SEBI (MUTUAL FUND) REGULATIONS, 1996
SEBI (SHARE BASED EMPLOYEE BENEFITS) REGULATIONS, 2014
SEBI (SUBSTANTIAL ACQUISITION OF SHARES AND TAKEOVERS) REGULATIONS, 2011
SEBI (DELISTING OF EQUITY SHARES) REGULATIONS, 2009<br>
slide20. Other regulatory requirement Under FEMA , valuation is also to be done in respect of Instrument transferred by or to a person resident of India and outside India.
RBI has , from time to time, issued guidelines to the Banks in India.
Companies Act’2013.
ESOP Regulation.<br>
slide21. ICDR - Applicability A public issue;
A rights issue, where the aggregate value of specified securities offered is fifty lakh rupees or more;
A preferential issue;
An issue of bonus shares by a listed issuer;
A qualified institutions placement by a listed issuer;
An issue of Indian Depository Receipts<br>
slide22. Valuation under the ICDR For QIP , Special resolution is wanting in Genl. Meeting U/s 62(1)(c) of the 2013 Act. And also , partly paid-up securities would not be offered and in-principle approval from the stock exchanges.
Exit offer price shall be the volume-weighted average market price of such shares for a period of sixty trading days immediately preceding the relevant date as traded on exchange where the maximum volume of trading in the shares of the issuer are recorded during such period, provided such shares are frequently traded; where not frequently traded, the price determined by the promoters or shareholders having control and the merchant banker taking into account valuation parameters including book value, comparable trading multiples, and such other parameters as are customary for valuation of shares of such issuers.
Where specified securities are issued on a preferential basis to promoters/relatives, for consideration other than cash, valuation be done by an independent qualified valuer.<br>
slide23. Obligation under the LODR Applicability- Securities listed in recognized Exchange
Board of Directors
Meeting of Board- 4 meeting , Gap of two meeting is 120 days.
Compliance Report.
Valuation of Shares to Directors & ESOP
Credit Rating
Committee Including Audit Committee, Risk Management Committee, Stakeholders relationship Committee, Nomination & remuneration committee.
Financial Report – Quarterly , Annual Report.
Website<br>
slide24. Mutual Funds Fund established in the form of Trust. Application by the Sponsor holding 40% of NW . Appoint ARC & operate Schemes.
Valuation shall be NAV of a scheme.
Traded Securities valued at the last quoted closing price on the stock exchange. When traded more than one recognised stock exchange, valued in stock exchange where the security is principally traded.
Valuation principles has been laid down in Reg 43 to 49 . Equity on basis of Capitalization of earnings based on NAV and for Debentures,G’Sec based on Yield to Maturity<br>
slide25. SAST Shall apply to direct and indirect acquisition of shares or voting rights in, or control over target company.
offer for acquiring shares shall be made at a price not lower than price highest of :
Negotiated price ;
Volume-weighted average price paid or payable;
Highest price paid or payable;
volume-weighted average market price of such shares as traded on stock exchange where maximum volume of trading in the shares of target company are recorded.<br>
slide26. Delisting Compulsory delisting- Exchange may by order delist any equity shares of a company on any ground prescribed in rules made under section 21A of Securities Contracts (Regulation) Act, 1956 .
Company may by publication apply to the recognized stock exchange for delisting .
Delisting is not permissible :
Pursuant to Buy back of equity shares by company,
Unless 3 years has elapsed since listing,
Delisting of convertible securities,
Sought to be delisted are outstanding.<br>
slide27. FEMA FDI –Investment through Capital Instrument by Resident outside India in unlisted Indian Co., or 10% or more in post issue paid up equity of listed Indian Co.
Foreign Portfolio Investors – Person residing outside India through capital investment of less than 10% in post issue paid up equity in listed Indian Co and registered in SEBI .
Govt. approval –Approval of different secretariate for industrial assistance
FII-A foreign institutional investor is an investor or investment fund registered in a country outside of the one in which it is investing. Institutional investors most notably include hedge funds, insurance companies, pension funds and mutual funds. The term is used most commonly in India and refers to outside companies investing in the financial markets of India. The ceiling for overall investment for FIIs is 24 % of paid up capital of the Indian co. and 10 % for NRIs/PIOs. The limit is 20 % in case of PS banks, including the SBI.<br>
slide28. FEMA Current account transactions are divided into 3 schedules in Current Account Transactions Rules:-
Sch I – Prohibited Transactions
Sch II – Transactions requiring prior approval of Government of India
Sch III – Transactions requiring prior approval of RBI
Drawal of foreign exchange is prohibited for –
Transactions specified in Schedule I; or
Travel to Nepal and / or Bhutan; or
Transaction with person resident in Nepal or Bhutan<br>
slide29. Valuation beyond the Companies Act Valuation done under the SEBI Regulations
Listing Obligation & Disclosure Requiement,Reg’15
Issue of Capital & Disclosure Requirement,Reg’09
Substantial acquisition of shares & takeovers,Reg’11
Mutual Fund Regulation,96
Sh.Based Employee Benefit Reg,’14
Valuation under FEMA,17
Valuation under the Income Tax Act,61
Circulars & Orders issued by RBI from time to time
Valuation Under Wealth Tax Act.
Valuation Under the Gift Tax Act.
Valuation Under GST Act.<br>
slide30. Different areas of Valuation Valuation of Equity Shares ,Pref. Shares and Debentures stocks.
Valuation of Bonds (Different types of Bonds and their valuation )
Valuation of Intangibles
Brand Valuation
Valuation for Start-ups & MSMEs
Real estate and property valuation<br>
slide31. Valuation of Shares Valuation of Shares may be necessary under the provision of Wealth Tax Act, Income Tax Act and Companies Act .
For quoted shares market value shall be best method for valuation of shares.
For unquoted shares , average of yields and assets is generally followed for determination of price (NAV).
NAV or the enterprise value divided by the number of shares shall be the value of share.<br>
slide32. Valuation of Bonds Bonds is a promissory notes – issued by the
Government ; - Gilt edged , Treasury Bonds, Municipal Bonds – Not exposed to risk
Sometimes State Bonds are Tax free .
Business ;- Different types of Corporate Bonds – exposed to risk. Par Value of Bonds are generally repaid at future date at some repayment value at Premium .
Bonds interest payment may be termed as Coupon payment – generally paid half yearly .<br>
slide33. Valuation of Bonds In some of cases Bonds coupon rates varies over time – called as floating rate Bonds.
Zero Coupon Bonds – usually no coupon payment ,but issued at a substantial discount .
Some of the Bonds have call provision giving right to call for redemption by the issuer with a premium .
Development Bonds are issued as Tax savings Bonds usually having a lock in period.
Ratings of Bonds are done by the Credit rating Agencies like CRISIL, Care S&P<br>
slide34. Value of Intangibles Intangible asset is identifiable non-monetary asset, without physical substance held for use in the production of goods & Services , for rental or others .
AS 26 recognizes only if it generates future benefit to the enterprise and
Cost of the asset can be measured reliably
AS 10 – Accounting for Fixed Asset only recognizes the purchased goodwill.
Intangible Assets includes Goodwill, Patent, Trademark , etc.<br>
slide35. Brand Valuation Corporate values and earning powers are decided by intangibles and also by the tangible factors .
It is the brand that sells product.
Brand means Name, Sign, Symbols ,designs –to differentiate from the competitors.
Corporate branding means strategic exercise by managerial decisions making , maintaining and monitoring the identity , image and ownership of the corporate entity.
Brand should be considered as asset and amount of money a person prepared to pay for it.<br>
slide36. Valuation for Start-ups Valuing companies early in the life cycle is difficult, partly because of the absence of operating history and partly because most young firms do not make it through these early stages to success.
Valuation of business may be done through DCF method . Difficulties are :
Absence of historical data.
expenses that young companies incur to generate future growth are often mixed with generating current revenues.
The absence of revenues in some cases and how earnings will evolve in future years.<br>
slide37. Derivatives Financial derivatives are used for two main purposes to speculate and to hedge investments.
A derivative is a security with a price that is dependent upon or derived from one or more underlying assets.
The derivative itself is a contract between two or more parties based upon the asset or assets.
Examples of derivatives are Forward, future, options, swaps ,
Its value is determined by fluctuations in the underlying asset.
The most common underlying assets include stocks, bonds, commodities, currencies,. Interest rates and market indexes.<br>
slide38. What is Option ? An option is right to buy or sell a specified quantity of an underlying asset at a fixed price (called a strike price or an exercise price) at or before the expiration date of the option.
Since it is a right and not an obligation, the holder can choose not to exercise the right and allow the option to expire.
There are two types of options - call options (right to buy) and put options (right to sell).
An American option can be exercised at any time prior to its expiration, while a European option can be exercised only at expiration.<br>
slide39. Security Market Cash Market/Spot Market –
Future Market / Forward Market
Swaps -A swap is an over-the-counter derivative contract in which two parties agree to exchange a series of cash flows whereby one party pays a variable series that will be determined by an underlying asset or rate and the other party pays either a variable series determined by a different underlying asset or rate or a fixed series. Examples of Swaps are Interest rate swaps & Currency Rate Swaps.<br>
slide40. Corporate Restructuring Expansion –Amalgamation, Absorption, Tender offer, Asset Acquisition , Joint Venture.
Contraction – Spin off, Equity Carve out, Split off, Divestitures, Asset Sale
Corporate Control – Going Private, Equity Buyback, Anti takeover defenses ,Leveraged buyback<br>
slide41. Ind - AS Business Combination – IND –AS- 103
Financial Instruments – Ind AS- 109
Intangible Assets – Ind AS-38
Property Plant & Machniery –Ind AS- 16
Impairment of Assets- Ind AS 36
Provision for liabilities –Ind AS 37
Fair Value measurement – Ind AS-113
Govt.Grants –Ind AS - 20<br>
slide42. Merger & Acquisition Valuation approaches :
Enterprise Value/EBITDA
Comparable company analysis
Comparable transaction analysis
Discounted cash flow method<br>
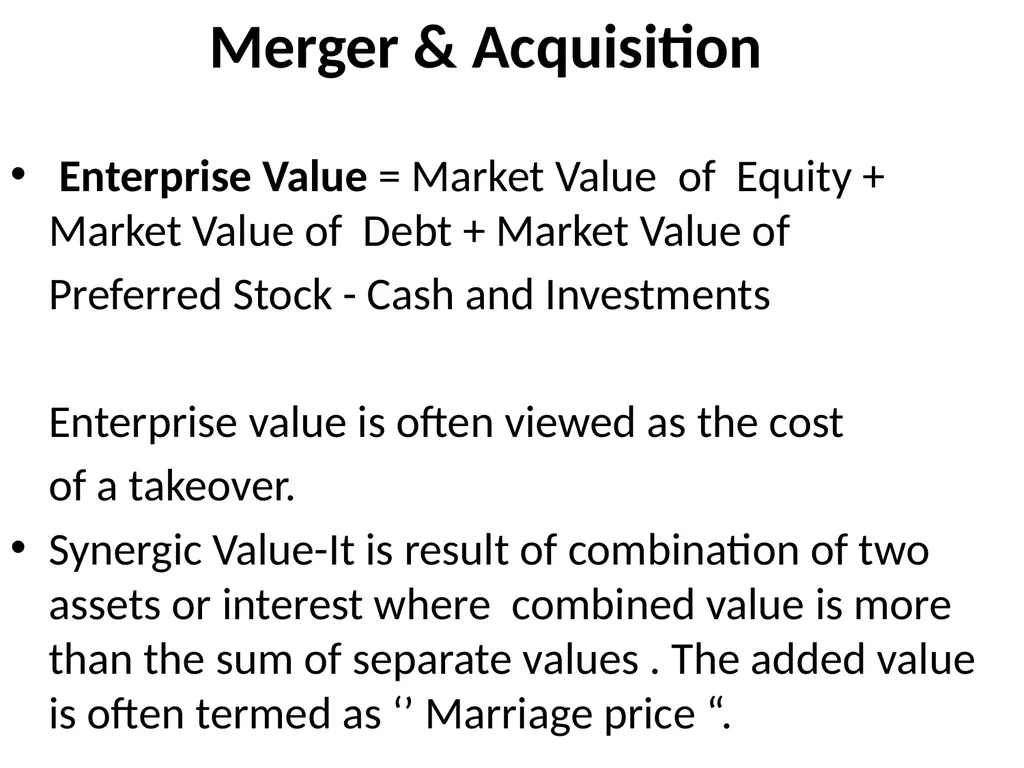
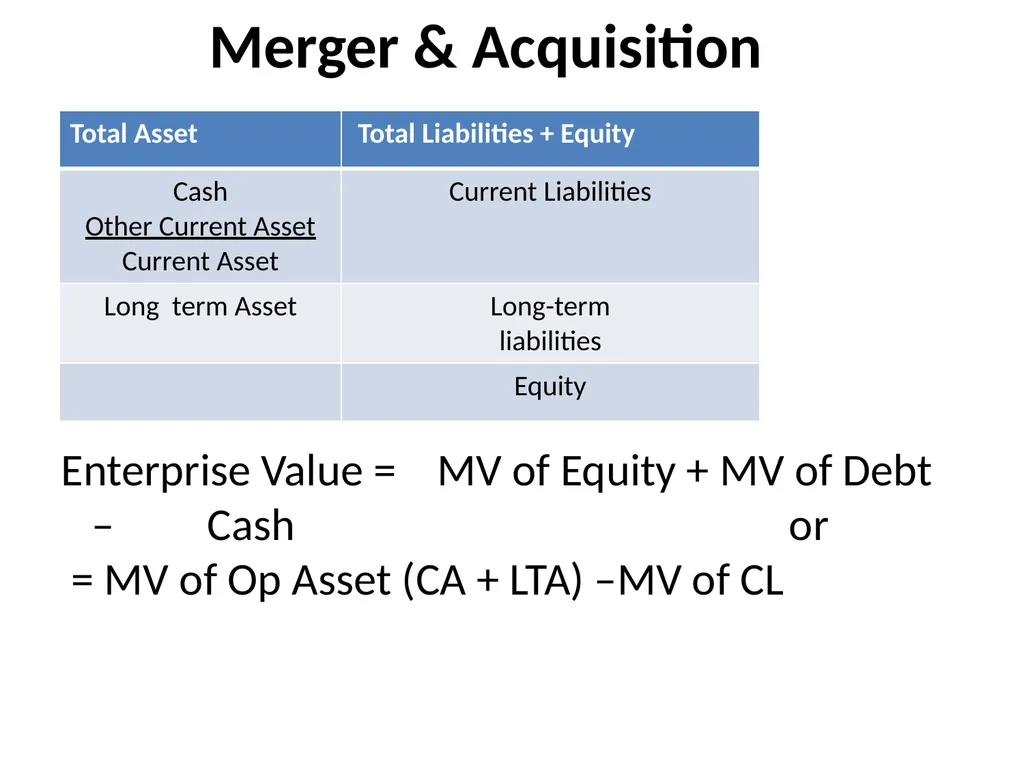
slide43. Merger & Acquisition Enterprise Value = Market Value of Equity + Market Value of Debt + Market Value of
Preferred Stock - Cash and Investments
Enterprise value is often viewed as the cost
of a takeover.
Synergic Value-It is result of combination of two assets or interest where combined value is more than the sum of separate values . The added value is often termed as ‘’ Marriage price “.<br>
slide44. Merger & Acquisition EBITDA
Earnings Before interest, Taxes, Depreciation, and
Amortization, and before non-cash, non reoccurring,non-operating and non-fair- market expenses
M&A:
EBITDA is the “new cash” available for no other purpose than debt-service, taxes and reinvestment
and investor return.
It is a “more reliable” measure of cash profits.<br>
slide45. Merger & Acquisition Enterprise Value = MV of Equity + MV of Debt – Cash or
= MV of Op Asset (CA + LTA) –MV of CL<br>
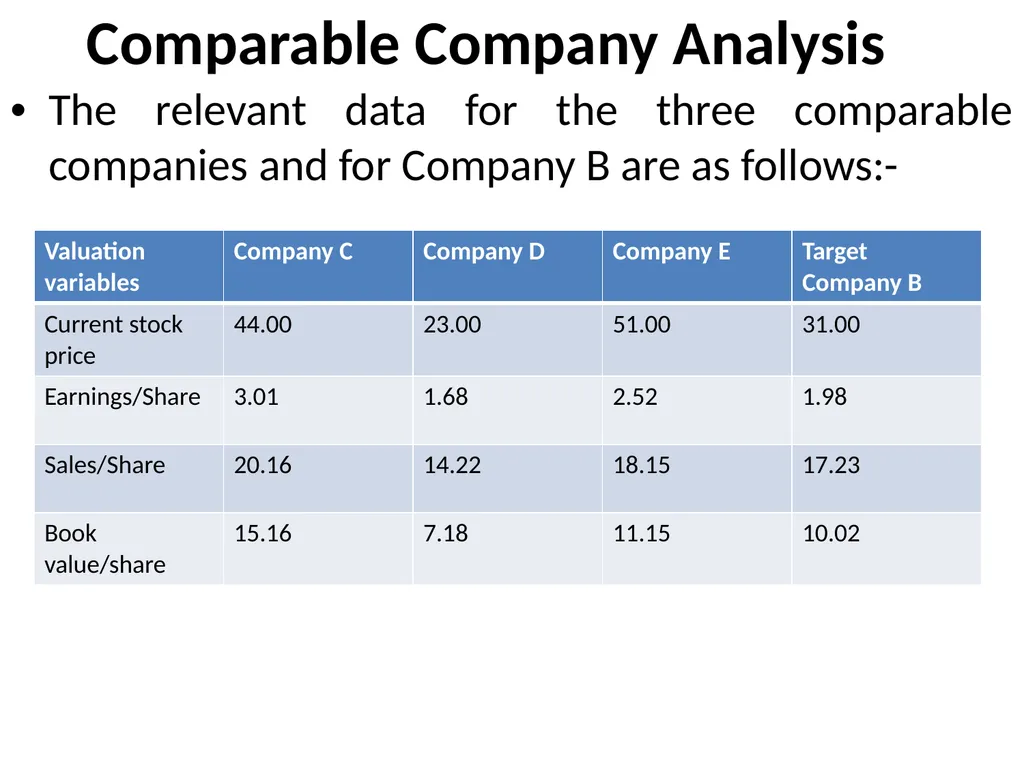
slide46. Comparable Company Analysis The relevant data for the three comparable companies and for Company B are as follows:-<br>
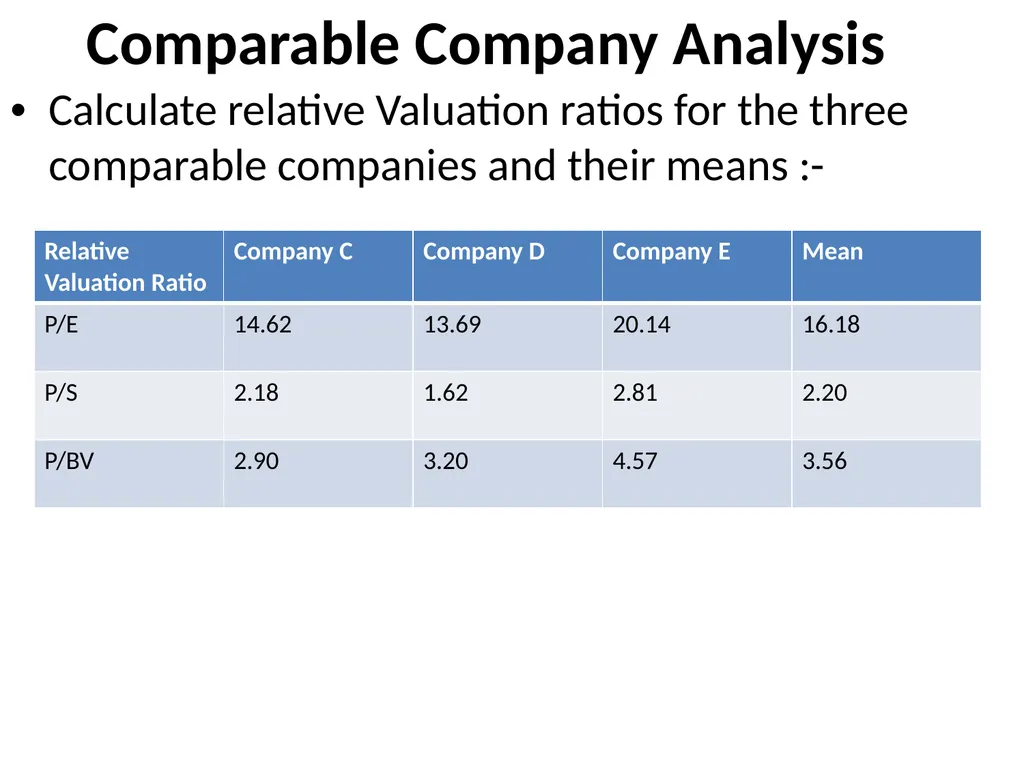
slide47. Comparable Company Analysis Calculate relative Valuation ratios for the three comparable companies and their means :-<br>
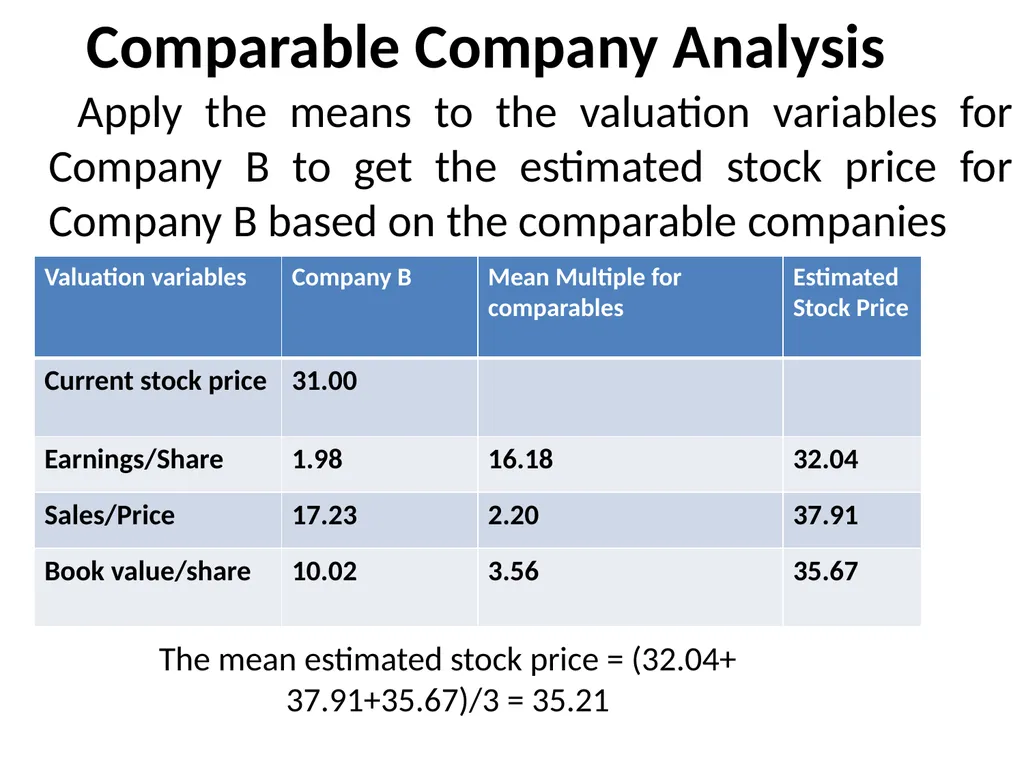
slide48. Comparable Company Analysis Apply the means to the valuation variables for Company B to get the estimated stock price for Company B based on the comparable companies The mean estimated stock price = (32.04+ 37.91+35.67)/3 = 35.21<br>
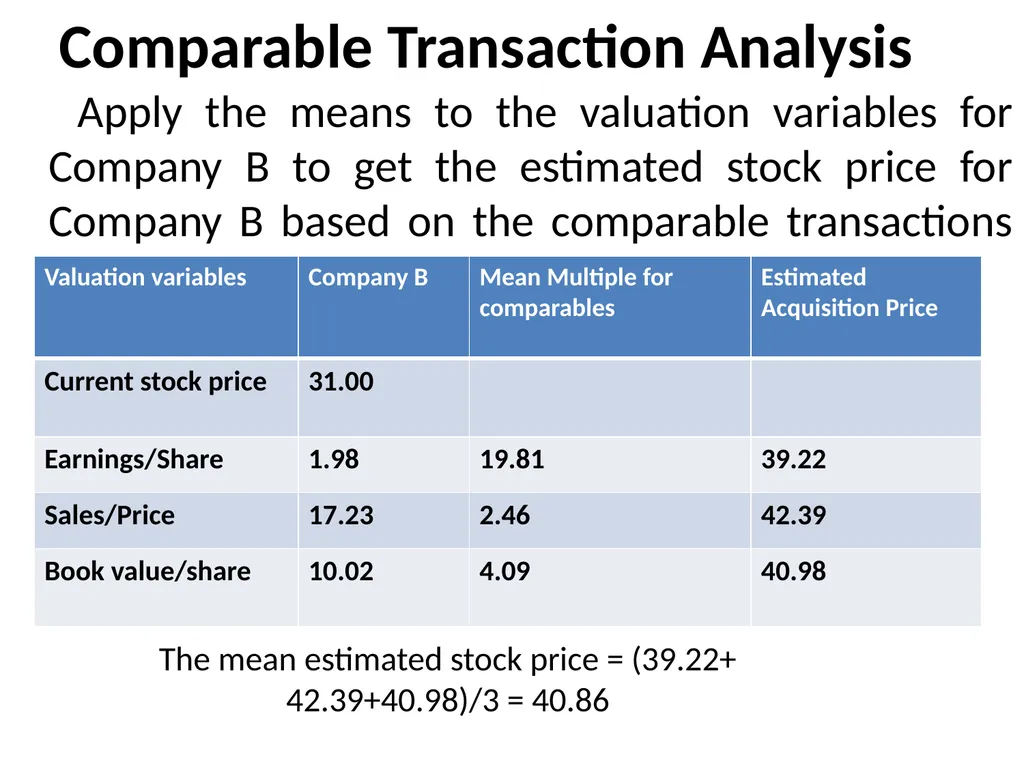
slide49. Comparable Transaction Analysis Apply the means to the valuation variables for Company B to get the estimated stock price for Company B based on the comparable transactions The mean estimated stock price = (39.22+ 42.39+40.98)/3 = 40.86<br>
slide50. Discounted Cash Flow The process for valuing a target company with discounted cash flow analysis requires the following steps:-
Determine which free cash flow model to use for the analysis
Develop pro forma financial estimates
Calculate free cash flows using the pro forma data
Discount free Cash Flow back to the present
Determine the terminal value and discount it back to the present
Add the discounted FCF values to the discounted terminal value<br>
slide51. Methods of Valuation Discounted Cash Flow (INCOME)
Net Present Value
Internal rate of return
EVA method
Comparable Transaction Method (MARKET)
Discounts (Lack of marketability/lack of control)
Replacement Cost Method (COST)
Reproduction methods
Summation method<br>
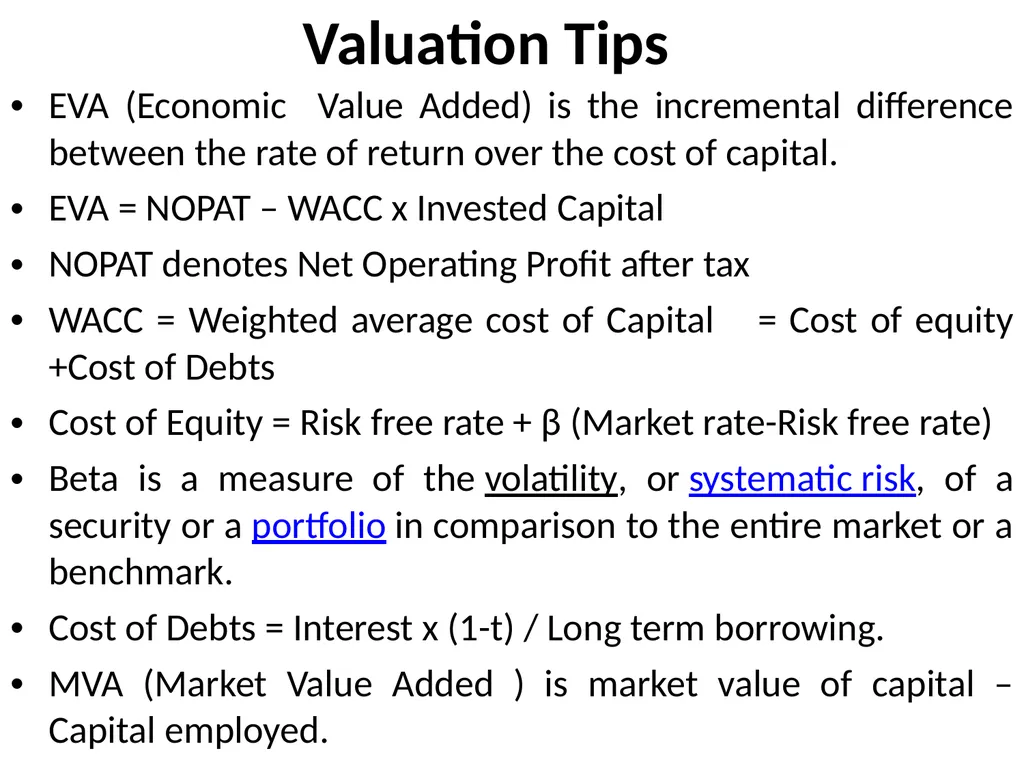
slide52. Valuation Tips EVA (Economic Value Added) is the incremental difference between the rate of return over the cost of capital.
EVA = NOPAT – WACC x Invested Capital
NOPAT denotes Net Operating Profit after tax
WACC = Weighted average cost of Capital = Cost of equity +Cost of Debts
Cost of Equity = Risk free rate + β (Market rate-Risk free rate)
Beta is a measure of the volatility, or systematic risk, of a security or a portfolio in comparison to the entire market or a benchmark.
Cost of Debts = Interest x (1-t) / Long term borrowing.
MVA (Market Value Added ) is market value of capital – Capital employed.<br>
slide53. Valuation Report Registered Valuer obtain information from the subject company for valuation for the class he has to report and also obtain the management information before conducting his assignment .
He shall disclose details of the inputs , calculation , basis , assumption as a part in his report .
Besides ,
i) the background information in respect of the assets,
ii) purpose of valuation
iii) Identity of the valuer & experts involved in the valuation.
iv)date of appointment,valuation date,date of report
v) disclosure of valuer interest or conflicts ,etc
vi)Procedure adopted in valuation, Valuation Standard
vii) Conclusions<br>
slide54. International Valuation Standard It is published in January,2017
There 11 Standards , 5 General and 6 Assets.
General Standard :
IVS-101 –Scope of work
IVS -102 –Investigation & Compliance
IVS-103 – Reporting
IVS-104-Bases of values
IVS 105 – Valuation approaches & Methods
Assets Standards :
IVS- 200 – Business & Business Interest
IVS- 210 – Intangible Assetss
IVS-300- Plant & Machinery
IVS-400- Real Property
IVS-410 -Development Property
IVS 500- Financial Insttruments.<br>
slide55. Basics of Valuation Standard To promote ‘best practices’ and fairness in valuation services
To promote credibility, relevancy & transparency of valuation information.
To enhance quality, consistency, comparability and
uniformity of valuation practice
To enhance reliance on the valuation amongst stakeholder
To improve corporate governance
To improve public confidence in valuation
To improve market efficiency
Enhance market knowledge and understanding<br>
slide56. Valuation Tips EV (Enterprise Value) is the measurement of total value of the market capitalization plus debts less Cash or investment . It is theoretically the takeover valuation price.
Growth rate of the enterprise can be found out by EV/ EBITDA
EBITDA denotes earnings before Interest ,tax, depreciation & amortization.
Other growth rate may be find out by P/E Ratio
i.e., MPS/EPS.
There is a difference between DPS and EPS . It is called retention ratio.<br>
slide57. Examination 50 Hours in house training from the recognized RVO .
Obtain Certificate from the RVO.
Register with the IBBI for examination & enroll for examination by paying fees of Rs 1500 /=
Examination is for 2 hours of 100 marks
Examination process is based on MCQ.
Pass Mark is 60
Can sit as many as you can.
86 questions are 1 mark and 7 are 2 mark.
Negative marking is 0.25 for each wrong answer.<br>
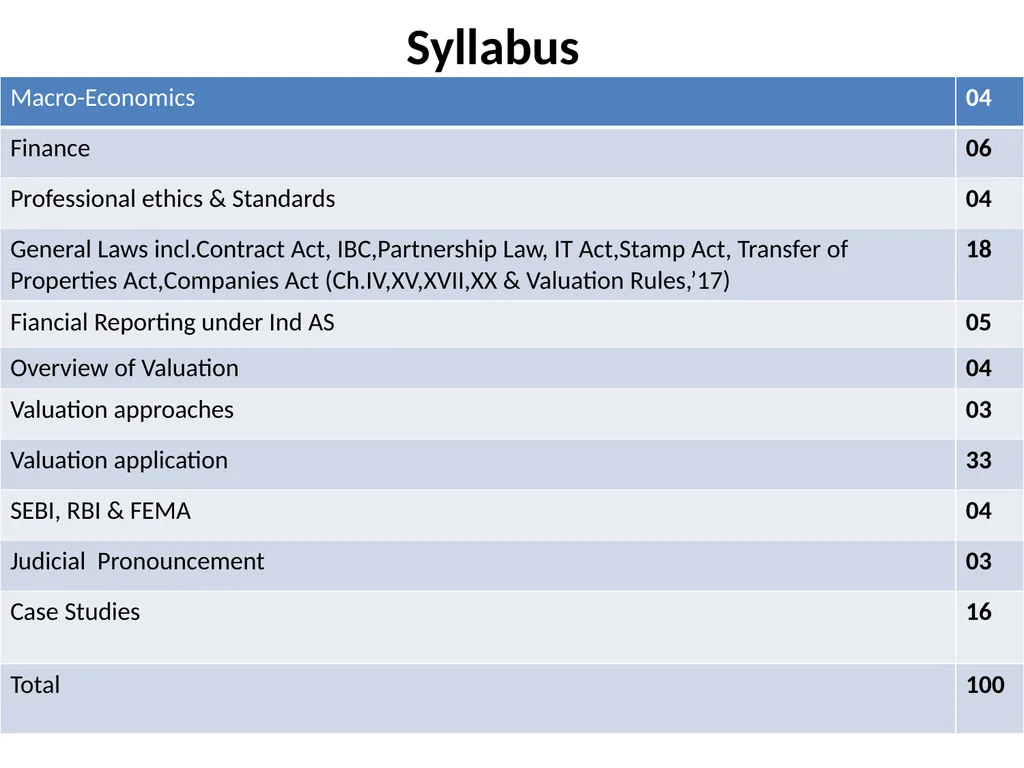
slide58. Syllabus<br>
CMA PRANAB KR.CHAKRABARTY<br>
slide2. VALUATION MEANING As per dictionary meaning- an estimation of the worth of something , especially one carried out by a professional valuer.
International Valuation Standard Council has defined Valuation as :
“ the process of determining the ‘Economic Worth’ of an Asset or Company under certain assumptions and limiting conditions and subject to the data available on the valuation date.<br>
slide3. Valuation Introduction “Some men know the price of everything and the value of nothing “ - Oscar Wilde
“ Appraisers have a value in mind before they start the process and try to back into it”
- Aswath Damaodaran, Jan 14,2009
“ There is a vast difference between understanding something well enough to buy it as opposed to understanding it well enough to sell it.”
- Zig Ziglar, Secrets of Closing the Sale, 1984<br>
slide4. It determine 3 factors :
Cost : Expenditure incurred to produce a commodity having a value - Historical fact.
Price : Additional reward to the producer for the labour and capital involved – Value Consideration
Value : Opinion and varies from purpose to purpose- enjoyment benefit.<br>
slide5. Why Valuation ? To understand the worth of the Business .
For expanding the Business .
To see a baseline value for the business and develop a strategy to improve the profitability of the business and increase the value of the business for an exit strategy.
To evaluate an offer and negotiate a strategic sale of a business .
To determine the annual per share value of an Employee Stock Ownership Plan (ESOP)<br>
slide6. Why Valuation ? To identify the weakness of the business to refocus the operational efforts to improve the profitability and the bottom line .
For Buying and selling and funding for the New Project.
To evaluate the Equity Value .
Financial Reporting Purposes.
Determine the intrinsic value .
Determine the value for Insolvency and Liquidation.
Determine the value for winding up, Merger & Acquisition.<br>
slide7. Areas for Valuation Merger and Acquisition.
Fund raising .
Sale or Reconstruction of the Business.
Issue of Shares , ESOP, Sweat Equity , Buy Back .
Impairment of Assets.
FDI and Foreign Exchange related transaction.
Insolvency and Liquidation Process.
Legal and Statutory obligation.
Insurance Valuation.<br>
slide8. Types of Value Book Value- Value in the Balance Sheet
Market Value – Price at which Buyer & Seller trades.
Fair Market Value – Municipal Valuation, Insurance Industry.
Intrinsic Value – True Value of an Asset both in respect of tangible & intangible factors. It may not be same as current market value .
Extrinsic Value –When option price is greater than the intrinsic value , difference price is called as extrinsic value.
Going concern is always greater than the liquidation value.
Security or Financial Assets.<br>
slide9. Types of values : Assessed Value Investment Value Replacement Value Book Value Liquidation Value Intrinsic Value Synergic Value<br>
slide10. Class of Assets Land & Building.
Plant & Machinery
Security or Financial Assets.<br>
slide11. Land and Building Methods of Valuation of Land :
Land & Building Method ;
Rent Capitalization Method;
Development Method;
Profit Method;
Direct Comparison Method
Methods of Valuation of Building :
Accounts Method ;
Plinth area Rate and Cost Index Method;
Details of item wise Method;
Material and Labour Contract Method;
Comparable Method<br>
slide12. Plant and Machinery Factors Considers for valuation:
Availability of information;
Appropriateness of Method with respect to nature of asset and purpose of valuation should be given emphasis ;
Respective strength and weakness of possible approach & method;
Observable market information in all these methods is preferred ;
Depreciation :
Straight Line ;
Written down Method;<br>
slide13. Approaches Income
Market
Cost .<br>
slide14. Valuation Rules 2017 Under Chapter XVII ,Section 247 of the Companies Act,’13 governs the provisions of valuations and the Registered Valuers .
Valuation Rules,2017 has been notified on 18th October,2017 .
Registered Valuer has to be registered with the authority for carrying out valuation of the class , the valuer been registered .
The valuer shall also be registered with the Registered Valuer Organization of an asset class , the organization been recognized by the authority.<br>
slide15. Valuation Rules in a nutshell Structure – 6 Chapters,21 Rules,5 forms,4 annex.
Registering Authority –IBBI.
Valuer –Passed the Valuation Examination.
RVO – Registered U/s 25 of the Companies Act’56/Section 8 of the Companies Act’13.
Valuation Standard – To follow the International Valuation Standard,2017 , till the standard is formulated by the Central Govt. in consultation with the RVOs.
Valuation Standard as specified by the SEBI/RBI/any other specified authority.<br>
slide16. Areas of Valuation Valuation for further issue of shares
Valuation of Assets involved in arrangement of Non Cash transaction involving Directors .
Valuation of Assets under debt restructuring.
Valuation under scheme of Compromise/Arrangement;
Valuation of Eq. Shares held by the Minority Sh-holding.
Valuation Report to be submitted to the liquidator.
Report of experts for valuation for circulation to creditor/members<br>
slide17. Valuation under the Companies Act Section 62(1)© - Further Issue of Shares – Issue is authorised by the Spl.Resolution & Price is determined by the Regd.Valuer.
Non Cash transaction by the Director shall be approved in AGM and value shall be approved by the Valuer u/s 192(2).
Compromise/arrangement with creditor and members u/s 230(2)(iv) through NCLT on the basis of Valuation Report by Regd Valuer.
Purchase of minority shareholding of 10% or below u/s 236(2) is to be paid on the basis of report of Regd. Valuer<br>
slide18. Valuation under the Companies Act’13 Section 281(1)(a) – Winding up of a Company Valuer report is to be submitted to the NCLT.
Section 305(2) – Voluntary winding up of a company for solvency requires report of the Regd.Valuer.<br>
slide19. SEBI’s regulatory requirement SEBI (ISSUE OF CAPITAL AND DISCLOSURE REQUIREMENTS)
Regulations, 2009
SEBI (LISTING OBLIGATIONS AND DISCLOSURE REQUIREMENTS) REGULATIONS, 2015
SEBI (MUTUAL FUND) REGULATIONS, 1996
SEBI (SHARE BASED EMPLOYEE BENEFITS) REGULATIONS, 2014
SEBI (SUBSTANTIAL ACQUISITION OF SHARES AND TAKEOVERS) REGULATIONS, 2011
SEBI (DELISTING OF EQUITY SHARES) REGULATIONS, 2009<br>
slide20. Other regulatory requirement Under FEMA , valuation is also to be done in respect of Instrument transferred by or to a person resident of India and outside India.
RBI has , from time to time, issued guidelines to the Banks in India.
Companies Act’2013.
ESOP Regulation.<br>
slide21. ICDR - Applicability A public issue;
A rights issue, where the aggregate value of specified securities offered is fifty lakh rupees or more;
A preferential issue;
An issue of bonus shares by a listed issuer;
A qualified institutions placement by a listed issuer;
An issue of Indian Depository Receipts<br>
slide22. Valuation under the ICDR For QIP , Special resolution is wanting in Genl. Meeting U/s 62(1)(c) of the 2013 Act. And also , partly paid-up securities would not be offered and in-principle approval from the stock exchanges.
Exit offer price shall be the volume-weighted average market price of such shares for a period of sixty trading days immediately preceding the relevant date as traded on exchange where the maximum volume of trading in the shares of the issuer are recorded during such period, provided such shares are frequently traded; where not frequently traded, the price determined by the promoters or shareholders having control and the merchant banker taking into account valuation parameters including book value, comparable trading multiples, and such other parameters as are customary for valuation of shares of such issuers.
Where specified securities are issued on a preferential basis to promoters/relatives, for consideration other than cash, valuation be done by an independent qualified valuer.<br>
slide23. Obligation under the LODR Applicability- Securities listed in recognized Exchange
Board of Directors
Meeting of Board- 4 meeting , Gap of two meeting is 120 days.
Compliance Report.
Valuation of Shares to Directors & ESOP
Credit Rating
Committee Including Audit Committee, Risk Management Committee, Stakeholders relationship Committee, Nomination & remuneration committee.
Financial Report – Quarterly , Annual Report.
Website<br>
slide24. Mutual Funds Fund established in the form of Trust. Application by the Sponsor holding 40% of NW . Appoint ARC & operate Schemes.
Valuation shall be NAV of a scheme.
Traded Securities valued at the last quoted closing price on the stock exchange. When traded more than one recognised stock exchange, valued in stock exchange where the security is principally traded.
Valuation principles has been laid down in Reg 43 to 49 . Equity on basis of Capitalization of earnings based on NAV and for Debentures,G’Sec based on Yield to Maturity<br>
slide25. SAST Shall apply to direct and indirect acquisition of shares or voting rights in, or control over target company.
offer for acquiring shares shall be made at a price not lower than price highest of :
Negotiated price ;
Volume-weighted average price paid or payable;
Highest price paid or payable;
volume-weighted average market price of such shares as traded on stock exchange where maximum volume of trading in the shares of target company are recorded.<br>
slide26. Delisting Compulsory delisting- Exchange may by order delist any equity shares of a company on any ground prescribed in rules made under section 21A of Securities Contracts (Regulation) Act, 1956 .
Company may by publication apply to the recognized stock exchange for delisting .
Delisting is not permissible :
Pursuant to Buy back of equity shares by company,
Unless 3 years has elapsed since listing,
Delisting of convertible securities,
Sought to be delisted are outstanding.<br>
slide27. FEMA FDI –Investment through Capital Instrument by Resident outside India in unlisted Indian Co., or 10% or more in post issue paid up equity of listed Indian Co.
Foreign Portfolio Investors – Person residing outside India through capital investment of less than 10% in post issue paid up equity in listed Indian Co and registered in SEBI .
Govt. approval –Approval of different secretariate for industrial assistance
FII-A foreign institutional investor is an investor or investment fund registered in a country outside of the one in which it is investing. Institutional investors most notably include hedge funds, insurance companies, pension funds and mutual funds. The term is used most commonly in India and refers to outside companies investing in the financial markets of India. The ceiling for overall investment for FIIs is 24 % of paid up capital of the Indian co. and 10 % for NRIs/PIOs. The limit is 20 % in case of PS banks, including the SBI.<br>
slide28. FEMA Current account transactions are divided into 3 schedules in Current Account Transactions Rules:-
Sch I – Prohibited Transactions
Sch II – Transactions requiring prior approval of Government of India
Sch III – Transactions requiring prior approval of RBI
Drawal of foreign exchange is prohibited for –
Transactions specified in Schedule I; or
Travel to Nepal and / or Bhutan; or
Transaction with person resident in Nepal or Bhutan<br>
slide29. Valuation beyond the Companies Act Valuation done under the SEBI Regulations
Listing Obligation & Disclosure Requiement,Reg’15
Issue of Capital & Disclosure Requirement,Reg’09
Substantial acquisition of shares & takeovers,Reg’11
Mutual Fund Regulation,96
Sh.Based Employee Benefit Reg,’14
Valuation under FEMA,17
Valuation under the Income Tax Act,61
Circulars & Orders issued by RBI from time to time
Valuation Under Wealth Tax Act.
Valuation Under the Gift Tax Act.
Valuation Under GST Act.<br>
slide30. Different areas of Valuation Valuation of Equity Shares ,Pref. Shares and Debentures stocks.
Valuation of Bonds (Different types of Bonds and their valuation )
Valuation of Intangibles
Brand Valuation
Valuation for Start-ups & MSMEs
Real estate and property valuation<br>
slide31. Valuation of Shares Valuation of Shares may be necessary under the provision of Wealth Tax Act, Income Tax Act and Companies Act .
For quoted shares market value shall be best method for valuation of shares.
For unquoted shares , average of yields and assets is generally followed for determination of price (NAV).
NAV or the enterprise value divided by the number of shares shall be the value of share.<br>
slide32. Valuation of Bonds Bonds is a promissory notes – issued by the
Government ; - Gilt edged , Treasury Bonds, Municipal Bonds – Not exposed to risk
Sometimes State Bonds are Tax free .
Business ;- Different types of Corporate Bonds – exposed to risk. Par Value of Bonds are generally repaid at future date at some repayment value at Premium .
Bonds interest payment may be termed as Coupon payment – generally paid half yearly .<br>
slide33. Valuation of Bonds In some of cases Bonds coupon rates varies over time – called as floating rate Bonds.
Zero Coupon Bonds – usually no coupon payment ,but issued at a substantial discount .
Some of the Bonds have call provision giving right to call for redemption by the issuer with a premium .
Development Bonds are issued as Tax savings Bonds usually having a lock in period.
Ratings of Bonds are done by the Credit rating Agencies like CRISIL, Care S&P<br>
slide34. Value of Intangibles Intangible asset is identifiable non-monetary asset, without physical substance held for use in the production of goods & Services , for rental or others .
AS 26 recognizes only if it generates future benefit to the enterprise and
Cost of the asset can be measured reliably
AS 10 – Accounting for Fixed Asset only recognizes the purchased goodwill.
Intangible Assets includes Goodwill, Patent, Trademark , etc.<br>
slide35. Brand Valuation Corporate values and earning powers are decided by intangibles and also by the tangible factors .
It is the brand that sells product.
Brand means Name, Sign, Symbols ,designs –to differentiate from the competitors.
Corporate branding means strategic exercise by managerial decisions making , maintaining and monitoring the identity , image and ownership of the corporate entity.
Brand should be considered as asset and amount of money a person prepared to pay for it.<br>
slide36. Valuation for Start-ups Valuing companies early in the life cycle is difficult, partly because of the absence of operating history and partly because most young firms do not make it through these early stages to success.
Valuation of business may be done through DCF method . Difficulties are :
Absence of historical data.
expenses that young companies incur to generate future growth are often mixed with generating current revenues.
The absence of revenues in some cases and how earnings will evolve in future years.<br>
slide37. Derivatives Financial derivatives are used for two main purposes to speculate and to hedge investments.
A derivative is a security with a price that is dependent upon or derived from one or more underlying assets.
The derivative itself is a contract between two or more parties based upon the asset or assets.
Examples of derivatives are Forward, future, options, swaps ,
Its value is determined by fluctuations in the underlying asset.
The most common underlying assets include stocks, bonds, commodities, currencies,. Interest rates and market indexes.<br>
slide38. What is Option ? An option is right to buy or sell a specified quantity of an underlying asset at a fixed price (called a strike price or an exercise price) at or before the expiration date of the option.
Since it is a right and not an obligation, the holder can choose not to exercise the right and allow the option to expire.
There are two types of options - call options (right to buy) and put options (right to sell).
An American option can be exercised at any time prior to its expiration, while a European option can be exercised only at expiration.<br>
slide39. Security Market Cash Market/Spot Market –
Future Market / Forward Market
Swaps -A swap is an over-the-counter derivative contract in which two parties agree to exchange a series of cash flows whereby one party pays a variable series that will be determined by an underlying asset or rate and the other party pays either a variable series determined by a different underlying asset or rate or a fixed series. Examples of Swaps are Interest rate swaps & Currency Rate Swaps.<br>
slide40. Corporate Restructuring Expansion –Amalgamation, Absorption, Tender offer, Asset Acquisition , Joint Venture.
Contraction – Spin off, Equity Carve out, Split off, Divestitures, Asset Sale
Corporate Control – Going Private, Equity Buyback, Anti takeover defenses ,Leveraged buyback<br>
slide41. Ind - AS Business Combination – IND –AS- 103
Financial Instruments – Ind AS- 109
Intangible Assets – Ind AS-38
Property Plant & Machniery –Ind AS- 16
Impairment of Assets- Ind AS 36
Provision for liabilities –Ind AS 37
Fair Value measurement – Ind AS-113
Govt.Grants –Ind AS - 20<br>
slide42. Merger & Acquisition Valuation approaches :
Enterprise Value/EBITDA
Comparable company analysis
Comparable transaction analysis
Discounted cash flow method<br>
slide43. Merger & Acquisition Enterprise Value = Market Value of Equity + Market Value of Debt + Market Value of
Preferred Stock - Cash and Investments
Enterprise value is often viewed as the cost
of a takeover.
Synergic Value-It is result of combination of two assets or interest where combined value is more than the sum of separate values . The added value is often termed as ‘’ Marriage price “.<br>
slide44. Merger & Acquisition EBITDA
Earnings Before interest, Taxes, Depreciation, and
Amortization, and before non-cash, non reoccurring,non-operating and non-fair- market expenses
M&A:
EBITDA is the “new cash” available for no other purpose than debt-service, taxes and reinvestment
and investor return.
It is a “more reliable” measure of cash profits.<br>
slide45. Merger & Acquisition Enterprise Value = MV of Equity + MV of Debt – Cash or
= MV of Op Asset (CA + LTA) –MV of CL<br>
slide46. Comparable Company Analysis The relevant data for the three comparable companies and for Company B are as follows:-<br>
slide47. Comparable Company Analysis Calculate relative Valuation ratios for the three comparable companies and their means :-<br>
slide48. Comparable Company Analysis Apply the means to the valuation variables for Company B to get the estimated stock price for Company B based on the comparable companies The mean estimated stock price = (32.04+ 37.91+35.67)/3 = 35.21<br>
slide49. Comparable Transaction Analysis Apply the means to the valuation variables for Company B to get the estimated stock price for Company B based on the comparable transactions The mean estimated stock price = (39.22+ 42.39+40.98)/3 = 40.86<br>
slide50. Discounted Cash Flow The process for valuing a target company with discounted cash flow analysis requires the following steps:-
Determine which free cash flow model to use for the analysis
Develop pro forma financial estimates
Calculate free cash flows using the pro forma data
Discount free Cash Flow back to the present
Determine the terminal value and discount it back to the present
Add the discounted FCF values to the discounted terminal value<br>
slide51. Methods of Valuation Discounted Cash Flow (INCOME)
Net Present Value
Internal rate of return
EVA method
Comparable Transaction Method (MARKET)
Discounts (Lack of marketability/lack of control)
Replacement Cost Method (COST)
Reproduction methods
Summation method<br>
slide52. Valuation Tips EVA (Economic Value Added) is the incremental difference between the rate of return over the cost of capital.
EVA = NOPAT – WACC x Invested Capital
NOPAT denotes Net Operating Profit after tax
WACC = Weighted average cost of Capital = Cost of equity +Cost of Debts
Cost of Equity = Risk free rate + β (Market rate-Risk free rate)
Beta is a measure of the volatility, or systematic risk, of a security or a portfolio in comparison to the entire market or a benchmark.
Cost of Debts = Interest x (1-t) / Long term borrowing.
MVA (Market Value Added ) is market value of capital – Capital employed.<br>
slide53. Valuation Report Registered Valuer obtain information from the subject company for valuation for the class he has to report and also obtain the management information before conducting his assignment .
He shall disclose details of the inputs , calculation , basis , assumption as a part in his report .
Besides ,
i) the background information in respect of the assets,
ii) purpose of valuation
iii) Identity of the valuer & experts involved in the valuation.
iv)date of appointment,valuation date,date of report
v) disclosure of valuer interest or conflicts ,etc
vi)Procedure adopted in valuation, Valuation Standard
vii) Conclusions<br>
slide54. International Valuation Standard It is published in January,2017
There 11 Standards , 5 General and 6 Assets.
General Standard :
IVS-101 –Scope of work
IVS -102 –Investigation & Compliance
IVS-103 – Reporting
IVS-104-Bases of values
IVS 105 – Valuation approaches & Methods
Assets Standards :
IVS- 200 – Business & Business Interest
IVS- 210 – Intangible Assetss
IVS-300- Plant & Machinery
IVS-400- Real Property
IVS-410 -Development Property
IVS 500- Financial Insttruments.<br>
slide55. Basics of Valuation Standard To promote ‘best practices’ and fairness in valuation services
To promote credibility, relevancy & transparency of valuation information.
To enhance quality, consistency, comparability and
uniformity of valuation practice
To enhance reliance on the valuation amongst stakeholder
To improve corporate governance
To improve public confidence in valuation
To improve market efficiency
Enhance market knowledge and understanding<br>
slide56. Valuation Tips EV (Enterprise Value) is the measurement of total value of the market capitalization plus debts less Cash or investment . It is theoretically the takeover valuation price.
Growth rate of the enterprise can be found out by EV/ EBITDA
EBITDA denotes earnings before Interest ,tax, depreciation & amortization.
Other growth rate may be find out by P/E Ratio
i.e., MPS/EPS.
There is a difference between DPS and EPS . It is called retention ratio.<br>
slide57. Examination 50 Hours in house training from the recognized RVO .
Obtain Certificate from the RVO.
Register with the IBBI for examination & enroll for examination by paying fees of Rs 1500 /=
Examination is for 2 hours of 100 marks
Examination process is based on MCQ.
Pass Mark is 60
Can sit as many as you can.
86 questions are 1 mark and 7 are 2 mark.
Negative marking is 0.25 for each wrong answer.<br>
slide58. Syllabus<br>