
CONTROVERSIES UNDER GST V. Raghuraman Senior






Description: CONTROVERSIES UNDER GST V. Raghuraman Senior Advocate ISSUES UNDER INPUT TAX CREDIT 2 AVAILEMENT REVERSAL OF CREDIT 3 SUNCRAFT ENERGY (P) LTD vs ASST. COMMNR 2023 153 taxmann.com 81 (CAL) ISSUE: Non-reflection of suppliers invoice in
Related Topics
Download Presentation
"CONTROVERSIES UNDER GST V. Raghuraman Senior" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. CONTROVERSIES UNDER GST V. Raghuraman
Senior Advocate<br>
slide2. ISSUES UNDER INPUT TAX CREDIT 2<br>
slide3. AVAILEMENT/ REVERSAL OF CREDIT 3<br>
slide4. SUNCRAFT ENERGY (P) LTD vs ASST. COMMNR [2023 153 taxmann.com 81 (CAL)] ISSUE: Non-reflection of supplier’s invoice in GSTR 2A - require reversal of input tax credit by the buyer ?
HELD:
Press release dated 18.10.2018 clarifies that GSTR-2A is for taxpayer facilitation and does not impact the ability of the taxpayer to avail ITC on self-assessment basis.
The department without resorting to any action against the supplier, who is the selling dealer, demand cannot be raised on the buyer. 4<br>
slide5. SUNCRAFT ENERGY (P) LTD vs ASST. COMMNR [2023 153 taxmann.com 81 (CAL)] The tax invoices and the bank statement produced by the buyer to substantiate that price of goods and taxes have been paid to be considered.
It was directed to first proceed against the seller and only in exceptional circumstances as clarified by Board, then and only then action can be initiated against seller.
SLP has been dismissed by the Hon’ble Supreme Court [2023 (157) taxmann.com (352) SC] 5<br>
slide6. Aastha Enterprises vs State of Bihar [2023 (153) TAXMANN.COM 491 (Patna)] ISSUE: Whether the purchasing dealer can be denied input tax credit when selling dealer, who defaulted payment of collected tax to the State?
HELD:
The benefit of claiming credit is one conferred by Statute - if conditions prescribed therein are not complied; no benefit flows to the claimant.
The question of double taxation does not arise - since the claim is denied only when the supplier who collected tax from the purchaser fails to pay it to the Government. 6<br>
slide7. Aastha Enterprises vs State of Bihar [2023 (153) TAXMANN.COM 491 (Patna)] HELD:
Statue has a measure to recover collected tax from the seller – it does not absolve the liability of the taxpayer to satisfy the entire liability to the Government.
The word 'Input Tax Credit’ postulates a situation where the purchasing dealer has a credit in the ledger account maintained by it with the Government. The said credit can only arise when the supplier pays up the tax collected from the purchaser.
Accordingly, credit was denied to the purchasing dealer. 7<br>
slide8. STATE OF KARNATAKA vs ECOM GILL COFFEE TRADING P LTD [2023 (4) CENTAX 223 (SC)] ISSUE: Burden of proof in respect of genuineness of purchases for availing credit.
The respondents had claimed credit on alleged purchases made from the respective dealers.
The Tribunal and High Court allowed the credit, by observing that as the purchasing dealers produced the invoices issued by the respective dealers and in some cases, made the payment through cheques, the Assessing Officer was not justified in denying the credit.
HELD:
Mere claim by dealer that he is a bona fide purchaser is not enough and sufficient to claim credit. 8<br>
slide9. STATE OF KARNATAKA vs ECOM GILL COFFEE TRADING P LTD [2023 (4) CENTAX 223 (SC)] Burden of proving the correctness of credit remains upon the dealer claiming such credit. Such a burden of proof cannot get shifted on the revenue.
Mere production of the invoices or the payment made by cheques is not enough and cannot be said to be discharging the burden of proof cast under section 70 of the KVAT Act.
Purchase transaction was required to be proved by furnishing details viz. name and address of selling dealer, details of vehicle which had delivered goods, payment of freight charges, acknowledgement of taking delivery of goods etc.
Actual physical movement of the goods is the sine qua non for claiming credit. 9<br>
slide10. Malik traders VS state of up [2023 155 taxmann.com 517 (All)] ISSUE: SCN was issued for wrong availment of ITC by the Petitioner.
HELD:
Petitioner has brought on record - tax invoices, e-way bills, GR and payment through banking channel, but no such details such as payment of freight charges, acknowledgement of taking delivery of goods, toll receipts and payment thereof has been provided.
In the absence of these documents, the actual physical movement of goods and genuineness of transportation as well as transaction cannot be established.
Reference made to: Ecom Gill Coffee Trading Pvt Ltd (SC) decision – To say that actual physical movement of goods to be proved. 10<br>
slide11. Henna Medicals VS State Tax Officer [2023 155 taxmann.com 29 (Kerala)] ISSUE: Credit of input tax was denied merely on ground of difference between GSTR 2A and GSTR 3B filed by the Petitioner.
HELD:
Matter was remanded back – To examine the evidence of the petitioner irrespective of the Form GSTR 2A for the petitioner's claim for the input tax credit.
After examination, the assessing officer directed to pass a fresh order.
Reference made to: Diya Agencies v. STO WPC 29769/2023 (Cal HC) and The State of Karnataka v. M/s Ecom Gill Coffee Trading Private Limited 2023 (3) TMI 533 SC. 11<br>
slide12. DENIAL OF CREDIT ON ACCOUNT OF MISMATCH IN GSTR 2A & GSTR 3B Goparaj Gopalakrishnan Pillai vs State Tax Officer [2023 11 Centax 203 (Ker)] – Merely because tax paid is not reflected in GSTR2A would not be sufficient to deny ITC to the buyer. Opportunity to be given to produce evidence to support the claim of ITC by the buyer. 12<br>
slide13. M/s. Gargo Traders VS Joint Commnr of Central tax [2023 151 taxmann.com 270 (CAL)] ISSUE: ITC was denied on ground that supplier was fake and non-existing.
GST registration of the supplier was cancelled with retrospective effect covering the transaction of the petitioner.
HELD: At time of transaction, supplier's name as registered taxable person was already available on Government record and petitioner paid amount on purchased articles as well as tax on same through bank and not in cash.
It cannot be said that there was any failure on petitioner's part in compliance of any obligation required under statute.
Directed the concerned authority to verify the documents on which the petitioner relies upon and grant the relief. 13<br>
slide14. SHRADDHA OVERSEAS P. LTD VS ACST [2023 (3) CENTAX 118 (CAL)] ISSUE: Availment of Input Tax Credit (ITC) without receiving any goods, based on fake documents issued by non-existing dealers was alleged.
HELD: Division bench while remanding the matter, observed that:
To conclude that the dealer is a non-existing dealer, there should be material to show - On the date of transaction, there was no valid registration.
If the cancellation of the registration of the dealer is by way of retrospective cancellation, - Question would be as to whether it would affect the transaction, more particularly when the appellant has been able to show that the payments has been done through banking challans. 14<br>
slide15. Vivo Mobile India (P) ltd VS UOI [2023 155 taxmann.com 324 (All)] ISSUE: Revenue had passed an order opining that Petitioner had availed/utilized excess ITC for the month of Feb & Aug 2020, which is in violation of Rule 36(4) of CGST Rules, 2017.
On the other hand - Petitioner stated that revenue erred in looking at a month-to-month reconciliation of ITC in GSTR 3B vs GSTR 2A. They ought to have looked at that period as a single tax period i.e., cumulatively from Feb 2020 to Aug 2020.
Revenue relied on clause 3(3) of Circular No. 123/42/219-GST dated 11.11.2019 – clarified that the words "on the due date of filing of the returns“ in Rule 36(4) – refer to the date when reconciliation to be made. Whether ITC to be availed based on month-on-month or cumulative reconciliation? 15<br>
slide16. Vivo Mobile India (P) ltd VS UOI [2023 155 taxmann.com 324 (All)] HELD:
The scheme of the Act is to let ITC arise and be availed provisionally, in a continuously moving value addition chain, subject to other conditions including actual payment of tax being eventually proven and remaining undoubted.
Date of filing of GSTR 1 is fixed at 10th of next month – by way of principle it is difficult to accept that ITC could be availed only with reference to that date.
Reference made to Bharti Airtel Ltd (SC) & Suncraft Ltd (Cal HC) – GSTR1 is a necessary step of facilitator. 16<br>
slide17. Vivo Mobile India (P) ltd VS UOI [2023 155 taxmann.com 324 (All)] HELD: Rule 36 (4) and its interpretation:
Rule 36(4) is complete and provides for a functional.
1st Proviso to Rule 36(4) - condition in Rule 36(4) shall apply cumulatively for the period Feb to Aug 2020: Meaning of cumulatively – all additions made, taken together.
The purpose of proviso - grant benefit of ITC late accrued, to transactions completed in the past, by treating Feb to Aug 2020 as one period.
Clarified that Rule 36(4) – necessarily require the computation of eligible ITC on a month-to-month basis, at the same time, a conscious departure was caused by the first proviso for a fixed period February 2020 to August 2020. 17<br>
slide18. VALIDITY OF SECTION 16(4) OF CGST ACT, 2017 18<br>
slide19. Gobinda Construction VS UOI [2023 154 taxmann.com 311(Patna)] ISSUE: Constitutional validity of section 16(4) of the CGST Act has been challenged as violative of Article 14 and 300A of the Constitution.
Alternatively, section 16(4) to be read as procedural requirement and cannot override section 16(1) conditions.
HELD:
ITC is not unconditional - a registered person becomes entitled to ITC only if the requisite conditions stipulated therein are fulfilled.
On close reading of section 16(1) – the provisions of section 16(4) is one of the conditions which makes a registered person entitled to take ITC. 19<br>
slide20. Gobinda Construction VS UOI [2023 154 taxmann.com 311(Patna)] HELD:
Reference made to Godrej & Boyce Mfg. Co. (P.) Ltd. v. CST [1992] 3 SCC 624 & ALD Automotive (P.) Ltd [2018] 99 taxmann.com 202 (SC) - ITC is in the nature of benefit/concession extended to a dealer and the concession can be received by the beneficiary only as per the scheme of the statute.
Section 16(4) to be read as directory – The concession of ITC is dependent on fulfillment of requisite conditions laid down in under various provisions of section 16 including 16(4) thereof.
Section 16(4) is constitutionally valid and not violative of Article 19(1)(g) and 300A of the Constitution. 20<br>
slide21. THIRUMALAKONDA PLYWOODS VS Asst. Commnr [2023 8 Centax 276 (AP)] ISSUE: Constitutional validity of section 16(4) of the CGST Act has been challenged as violative of Article 14 and 300A of the Constitution.
HELD:
Section 16(2): Precisely while section 16 sub-section (2) prescribes the eligibility criteria which is sine qua non for claiming ITC, sub-section (3) and (4) impose conditions or limitation for claiming ITC.
Whether 16(2) overrides the rest of section 16, especially 16(4): Section 16(2) only overrides the provision which enables the ITC i.e., section 16(1). Section 16(2) is not an enabling provision but a restricting provision 21<br>
slide22. THIRUMALAKONDA PLYWOODS VS Asst. Commnr [2023 8 Centax 276 (AP)] HELD:
Section 16(4) being a non-contradictory provision and capable of clear interpretation, will not be overridden by non obstante provision u/s 16(2).
If the legislature has no intention to impose time limitation, there was no necessity to insert a specific provision under section 16(4) and to further intend to override it through section 16(2) which is a futile exercise. 22<br>
slide23. THIRUMALAKONDA PLYWOODS VS Asst. Commnr [2023 8 Centax 276 (AP)] HELD:
Whether section 16(4) violates Article 14, 19(1)(g) & 300A: ITC is a mere concession/rebate/benefit but not a statutory or constitutional right. Imposing conditions including time limitation for availing the said concession will not amount to violation of constitution or any statute.
The operative spheres of Articles 14/19/300A is different from that of Section 16. Hence, no challenge on the ground of constitutional provisions could be made. 23<br>
slide24. BBA Infrastructure Ltd vs Senior Joint Comm of State Tax[2023 157 taxmann.com 345 (Cal)] ISSUE: Availment of ITC beyond the time limit stipulated under Section 16(4) of CGST Act, 2017- ITC was not taken through return but through books of account immediately on receipt of goods and services in terms of first proviso to section 16(2), and section 16(2) has overriding effect on section 16(4) -
HELD:
Section 16(2) does not appear to be a provision which allows Input Tax Credit, rather Section 16(1) is the enabling provision and Section16(2) restricts the credit which is otherwise allowed to the dealers who satisfied the condition.
FOLLWED - Gobinda Construction VS UOI (supra) 24<br>
slide25. Issues on blocking of credit under Rule 86A ITC cannot be blocked solely based on communication of Commissioner (Central Tax) and without any tangible material to form any belief that ITC is fraudulently availed is not sustainable. Decisions rendered in Income Tax Law for the expression ‘reason to believe’ is relevant [See: Parity Infotech Solutions (P) Ltd vs Government of National Capital Territory of Delhi (2023) 7 Centax 169 (Del.)].
Blocking of credit cannot be done by an officer below the rank of Assistant Commissioner. Blocking of credit by any other officer was held to be illegal and contrary to Rule 86A [See: Guru Storage Batteries vs State of Maharashtra (2023) 11 Centax 308 (Bom)]. 25<br>
slide26. Issues on blocking of credit under Rule 86A Electronic credit ledger cannot be blocked for more than one year [See: Raghbir Singh Govt. Contractor vs State of Haryana (2023) 4 Centax 396 (P & H) and TVL. New Royal Traders vs Asst Commnr (2023) 10 Centax 350 (Mad)].
Credit ledger cannot be blocked without assigning any reason for such blocking [See: Vijay Jaiswal vs Asst Commnr (2023) 2 Centax 104 (Cal)]. 26<br>
slide27. Issues under section 17(5) 27<br>
slide28. Issues under section 17(5) ITC on construction services:
Safari Retreats Pvt Ltd (P.) Ltd. vs Chief Commissioner of CGST [2019] 105 taxmann.com 324 (Orissa):
The credit on the input and input services used in construction of shopping mall was allowed to be utilized for payment of GST on renting of such shopping malls.
SLP before the Hon’ble Supreme Court is pending in Chief Commissioner of CGST vs Safari Retreats (P.) Ltd 2019-TIOL-489-SC-GST. All the pleadings are completed, and the judgement is reserved. 28<br>
slide29. Issues under section 17(5) Issues to be addressed in case of Safari:
Section 16 of the CGST Act, 2017 - the terminology used is “used in the course or furtherance of business”. Credit is available when used in course or furtherance of business.
Section 17(1) - business related input tax credits are allowable while credit for other uses is not. Similarly, 17(2) talks of only business credits.
Leasing of immovable property is clearly a taxable supply on which entire chain of input tax credit is available. Since, GST is enshrined on the principles of ‘seamless flow of credit’ – no credit can be denied when supply chain continues. 29<br>
slide30. Issues under section 17(5) Issues to be addressed in case of Safari:
Credit on sale of land and buildings covered under Schedule III are reversed under Section 17(2) and 17 (3) therefore, once the credit is already lost, Section 17(5) cannot be used again to demand reversal of input tax credit once over.
Appropriate meaning to interpret section 17(5): Section 17(5) talks of blocking credits where transactions are covered under Section 17(1) – credits when used for other purposes.
The non obstante clause found in Section 17(5) is to be read as not overriding but in the context - credit is available under Section 16 or 18 when inputs are used for the purpose of business, and if the same is used for “other purposes” credit has to be reversed. 30<br>
slide31. Issues under section 17(5) Usage of term plant and machinery in section 17(5):
Machinery meaning of –
The word ‘machinery’, when used in ordinary language prima facie means some mechanical contrivances which, by themselves or in combination with one or more other mechanical contrivances, by the combined movement and inter-dependent operation of their respective parts generate power, or evoke, modify, apply or direct natural forces with the object in each case of effecting so definite and specific a result. [See: Commissioner of Income Tax Vs Mir Mohammad Ali (1964) 53 ITR 165 (SC)]. 31<br>
slide32. Issues under section 17(5) Plant meaning of –
Plant must be something which is used by the assessee in aid of the object or purpose of the business. It is not only the means of processing the end-product, but it includes the entire operation undertaken for the purpose of obtaining the end-product. Railway sidings were thus treated as ‘plant’. [See: CIT Vs Birla Jute & Industries Ltd (2003) 260 ITR 55 (Cal)]. 32<br>
slide33. Issues under section 17(5) The following has been held to be plant:
Sanitary fittings in the bathrooms in a hotel [See: CIT Vs Taj Mahal Hotel (1971) 82 ITR 44 (SC)].
Building which is used as hotel or cinema theatre is a plant [See: CIT vs Anand Theatres (2000) 244 ITR 192 (SC)].
Generating-station building was so constructed as to be an integral part of its generating system was held to be plant [See: CIT vs Karnataka Power Corporation (2001) 247 ITR 268 (SC)].
Nursing home equipped to enable storage of surgical instruments & bandages was held as plant [See: CIT vs Dr. B. Venkata Rao (2000) 243 ITR 81 (SC)]. 33<br>
slide34. S.R. CONSTRUCTIONS.VS UOI [2023 6 Centax 38 (Tripura)] ISSUE: Petitioner: Petitioner a construction company. They have a works contract agreement with the M/s Hotel Polo Pvt. Ltd. and constructed a hotel at Agartala.
Petitioner availed credit of inputs used for providing works contract services. The said claim of ITC was rejecting – stating that inputs were used for construction of immovable properties and is hit by section 17(5).
HELD: Petitioner has fulfilled all the conditions of work contracts as he is providing work contract services under a contract for construction of building of a Hotel, wherein transfer of property in goods is involved in the execution of such contract. 34<br>
slide35. S.R. CONSTRUCTIONS.VS UOI [2023 6 Centax 38 (Tripura)] HELD: Petitioner has been providing work contract services to the owner of the hotel and not for its own.
For providing works contract of constriction services, Petitioner is entitled to avail credit of goods/services being used for providing such taxable works contract services.
Petitioner do not fall within the definition of section 17(5)(c) of the CGST Act, 2017.
Comment: Even though the hotel constructed remained to be immovable property, credit was never denied, considering that construction was carried not on Petitioner’s own account. 35<br>
slide36. Issues under Section 17(5) ARS STEEL & ALLOY INTERNATIONAL (P) LTD VS STO [2021 127 TAXMANN.COM 787 (MAD)]:
ISSUE: Petitioner manufacturer of MS Billets and Ingots. There was a loss of small portion of the inputs, inherent to the manufacturing process.
Department seeks to reverse a portion of the ITC claimed by the petitioners, proportionate to the loss of the input, referring to the provisions of section 17(5)(h) of the GST Act.
17(5)(h): goods lost, stolen, destroyed, written off or disposed of by way of gift or free samples. 36<br>
slide37. Issues under Section 17(5) ARS STEEL & ALLOY INTERNATIONAL (P) LTD VS STO [2021 127 TAXMANN.COM 787 (MAD)]:
HELD: The situations set out above in clause (h) indicate loss of inputs that are quantifiable and involve external factors or compulsions.
A loss that is occasioned by consumption in the process of manufacture is one which is inherent to the process of manufacture itself and such loss was not contemplated or covered by situations adumbrated under section 17(5)(h). 37<br>
slide38. Issues under Section 17(5) Insertion of new clause – Section 17(5)(fa) vide Finance Act, 2023, w.e.f. 1-10-2023:
(fa) Goods or services or both received by a taxable person, which are used or intended to be used for activities relating to his obligations under corporate social responsibility referred to in section 135 of the Companies Act, 2013 (18 of 2013).
This amendment is effective from 01.10.2023. 38<br>
slide39. Issues under Section 17(5) Insertion of new clause – Section 17(5)(fa) vide Finance Act, 2023, w.e.f. 1-10-2023:
Issues:
For the period prior to 01.10.2023 – Credit can be availed on CSR expenses – Retrospectivity and prospectivity?
Meaning of phrase “activities relating to his obligations under corporate social responsibility” ?
Whether voluntary CSR expenditure is eligible for credit?
What if an individual or firms incurs CSR expenditure? 39<br>
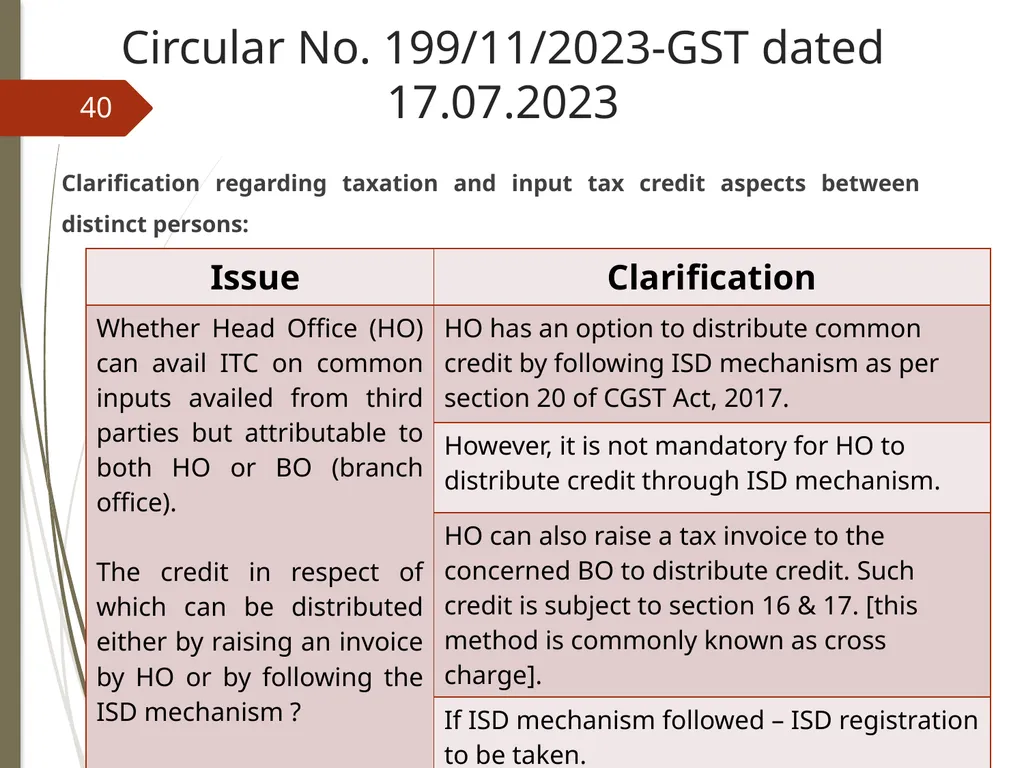
slide40. Circular No. 199/11/2023-GST dated 17.07.2023 Clarification regarding taxation and input tax credit aspects between distinct persons: 40<br>
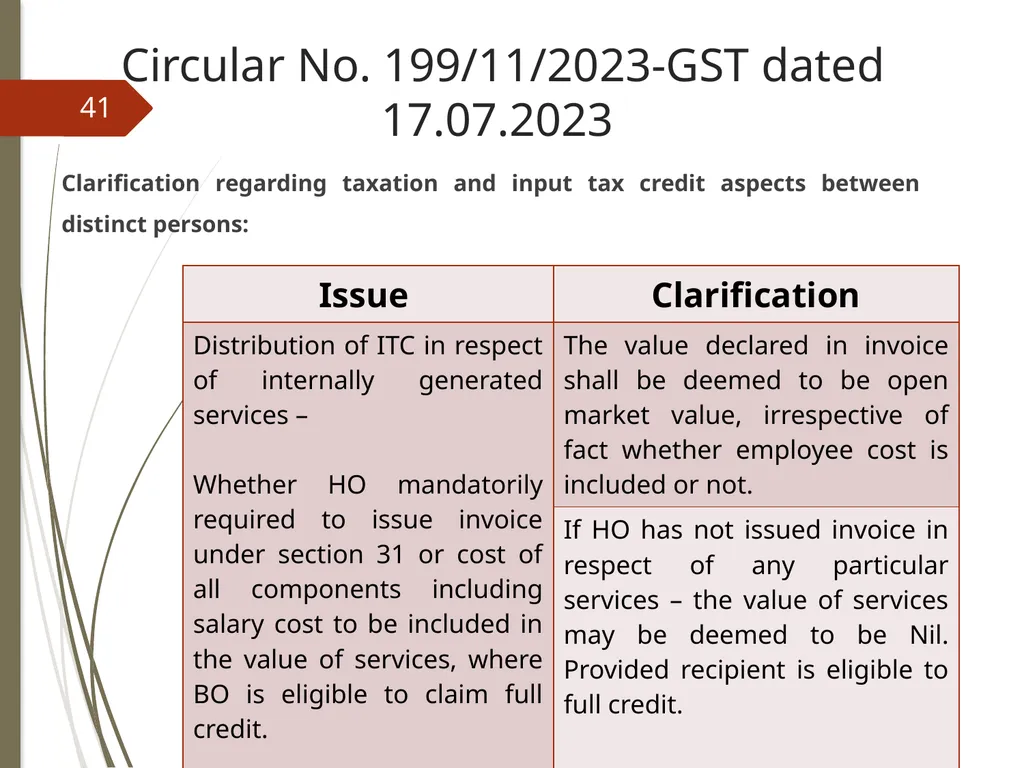
slide41. Circular No. 199/11/2023-GST dated 17.07.2023 Clarification regarding taxation and input tax credit aspects between distinct persons: 41<br>
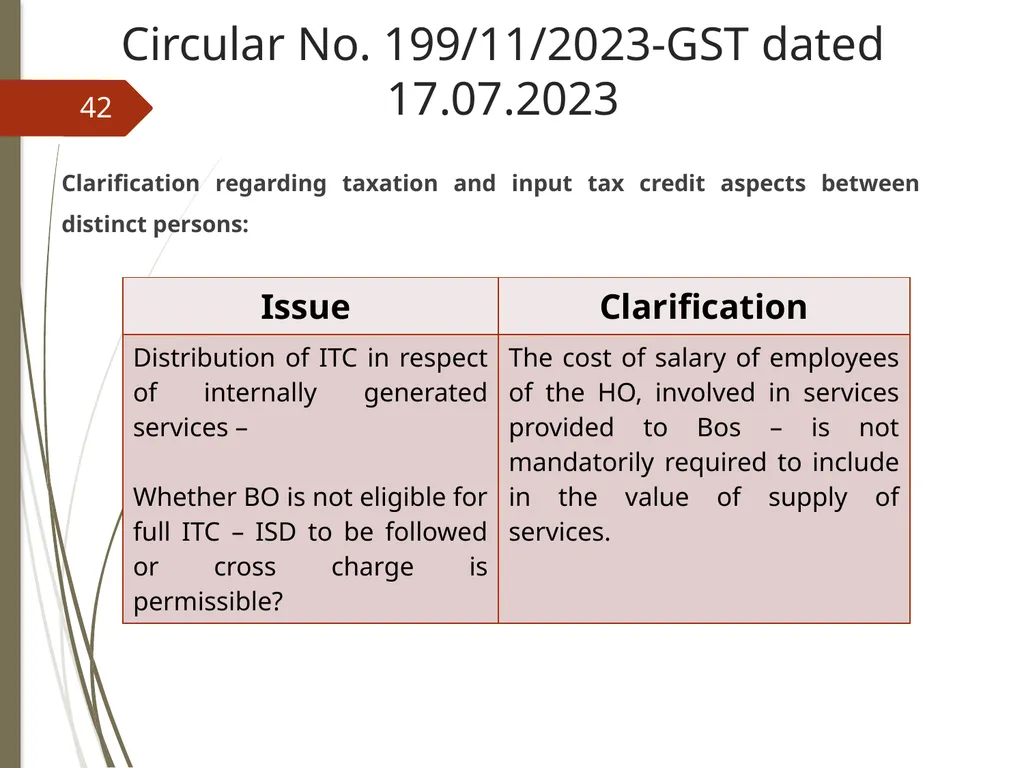
slide42. Circular No. 199/11/2023-GST dated 17.07.2023 Clarification regarding taxation and input tax credit aspects between distinct persons: 42<br>
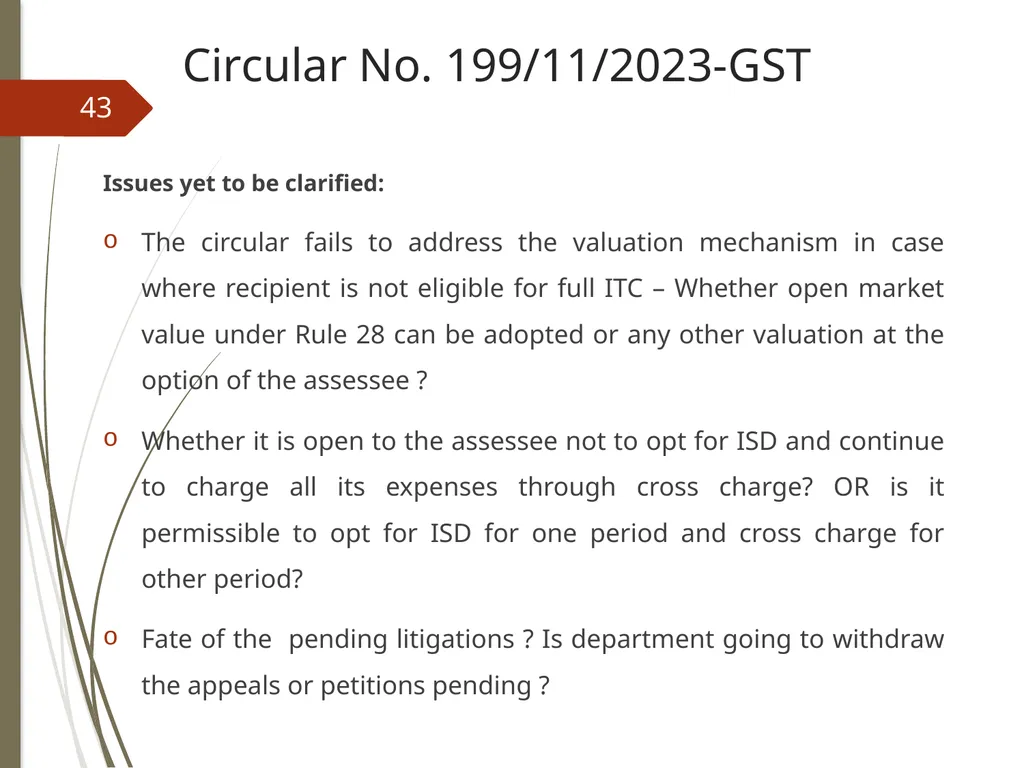
slide43. Circular No. 199/11/2023-GST Issues yet to be clarified:
The circular fails to address the valuation mechanism in case where recipient is not eligible for full ITC – Whether open market value under Rule 28 can be adopted or any other valuation at the option of the assessee ?
Whether it is open to the assessee not to opt for ISD and continue to charge all its expenses through cross charge? OR is it permissible to opt for ISD for one period and cross charge for other period?
Fate of the pending litigations ? Is department going to withdraw the appeals or petitions pending ? 43<br>
slide44. Issues w.r.t. Real Estate Sector 44<br>
slide45. Issues w.r.t. JDA JDA - Construction & handing over of specified number of flats in lieu of developmental rights as Landowners share:
JDA is in the nature of exchange of immovable property and hence does not qualify to be Construction service.
Landowners share under JDA – No purchaser during construction, Supreme court in L&T case held that activity of construction of apartment where there is no purchaser during construction stage would not be a works contract and hence does not qualify to be a service under Para 5(b) of Schedule II.
5(b) would also be not applicable as the building given to owners is not a sale. Further, the consideration for such transfer, i.e. transfer of ownership in land would be made only after completion of construction. 45<br>
slide46. Issues w.r.t. JDA GST implications on Landowners– JDA:
The transfer of developmental rights are in the nature of immovable property and hence does not qualify to be supply.
The grant of developmental right to the developer and permitting the developer to enter / possession of immovable property would not be liable to GST levy under Para 2(a) of Schedule II. 46<br>
slide47. Issues w.r.t. JDA ISSUE: Para 2A under Notification 11/2017-CT(R) – inserted w.e.f., 1.4.2019: valuation of construction of landowners share:
Para 2A provides that value of construction shall be deemed to be equal to Total amount charged for similar apartments in the project from independent buyers (other than landowner), nearest to the date on which such development right or FSI is transferred to promoter,
Less the value of value of land transferred as prescribed in Para 2.
No specific or express provision under CGST Act, 2017 for levy on ‘landowners share’ under JDA – hence legally impermissible to impose levy of tax on Landowner’s share in the hands of the Developer. In view of the absence of statutory provisions of for levy of GST on the landowners share, valuation prescribed in Para 2A could be challenged.
Valuation provision could be challenged on the basis that as there is no service element in JDA between the developer and the landowners, no question of applying valuation provision. 47<br>
slide48. Issues w.r.t. JDA ISSUE: Para 2A – inserted w.e.f., 1.4.2019: valuation of construction of landowners share:
Valuation of landowner's share provided in Circular No.151/2/2012-ST dated 10.02.2012 has been incorporated ‘verbatim’ in Para 2A
It is impossible to obtain value of similar apartments (sold to independent buyers) nearest to date on which development right / FSI was transferred to promoter under JDA – since development rights were transferred at the time of entering JDA, whereas apartments (sold to independent buyers) are constructed after many years.
It is also a well settled principle that the law does not compel a man to do that which he cannot possibly do and the said principle is well expressed in legal maxim “lex non cogit ad impossibilia” is squarely attracted to the facts and circumstances of the present case. 48<br>
slide49. Issues w.r.t. Immovable Property Issue: Entry 5(b) & 6(a) to Schedule II – Construction – validity?
Whether Construction - entry 5(b) of II Schedule would qualify to be supply? Whether Works contract is a supply?
Amendment by Finance Act, 2018 w.e.f., 1.2.2019 - Section 7 is amended with retrospective effect from 1.7.2017 - the entries in Schedule II shall first qualify as service and only then the classification as Service or as Goods would come into play.
There is no deeming clause unlike in erstwhile Service Tax law, to deem the sale of building during construction as service.
Entry 5(b) treats the entire activity of construction as ‘services’ is ultra vires and contradictory to Article 366(29A)(b) which bifurcates the transfer of goods portion from the composite contract and treats the same as deemed sale. 49<br>
slide50. Issues w.r.t. Immovable Property Issue: Omission of CLAUSE (ii) – works contract entry
Omission of Works Contract – Entry 3(ii) – Composite supply of works contract u/s 2(119) is unreasonable and arbitrary hence violative of Article 14 & 19:
Omission makes it mandatory for choose other entries where valuation of total amount has compulsorily included ‘value of land’.
Prior to omission, Developer / Promoter was eligible to opt for clause (ii) of Sl. No. 3 of Notification No. 11/2017-CT (Rate) and pay GST at 18% on Construction agreements.
Whether residual entry 3(xii) could be opted for payment of GST on construction services alone? 50<br>
slide51. Issues w.r.t. Immovable Property Issue: GST on immovable property transactions being unconstitutional lacking legislative competence:
Notification No. 11/2017-CT(R) - Para 2 is made applicable for all ‘Construction Service’ –value of ‘land’ shall be deemed to be 1/3rd of total amount including the amount charged for transfer of land.
Value of land is deemed to be 1/3rd of total amount – which results in levy of GST on land value over and above 1/3rd.
No legislative competence to levy tax on immovable property transactions under Article 246A. Hence, violative of Article 265 of the Constitution
Entries in Entry 3 of Notification read with Entry 5(b) of Schedule II to the CGST Act, 2017 could be challenged as being unconstitutional lacking legislative competence and violative of Article 246A and 265 of the Constitution 51<br>
slide52. Issues w.r.t. Immovable Property Issue: Para 2 of Notification no. 11/2017-CT(R) made applicable to Sl.no. 3 (Construction Services) is illegal & ultra vires S.15
Paragraph 2 of Notification deeming the value of land at one-third of the total amount charged is ultra-vires S.15 of CGST Act – Illegal and Ultra-virus
Alternatively, Paragraph 2 should be read down so as to allow valuation of land on the basis of actual amount received and not at deemed value of one-third of total amount charged.
Hence, Para 2 to be ‘read down’ as not being mandatory and the petitioner is allowed to value the land on the basis of actual amounts received towards the transfer of land / undivided share in the land.
Wipro Ltd. Vs. Asst Collector of Cus & ors [2015 (319) ELT 177 (S.C.)] Munjaal Manishbhai Bhatt vs UOI [2022 (62) GSTL 262 (Guj)], Avigna Properties Pvt Ltd vs State Tax Officer [2023 (7) Centax 203 (Mad)] 52<br>
slide53. Issue w.r.t. reimbursement of GST on account of enhancement of rate 53<br>
slide54. Mas Construction vs Hubballi Dharwad Smart City Ltd 2022 (57) GSTL 230 (Kar) ISSUE: Works Contract awarded in GST regime stipulating payment of Sales Tax/VAT component @ 5% in respect of materials whereas contractor deposited applicable GST
HELD: Contract having been entered into after coming into force of GST and in view of aforesaid clarification which has been approved by Finance Department, contractee required to pay GST after adjusting Sales Tax/VAT referred to in said contract particularly when tax is a statutory liability and contractor would not retain same as profit
Writ Appeal filed before Divisional Bench of the Hon’ble High Court of Karnataka [WA 1427/2021] – interim order dated 07.03.2023 granted 54<br>
slide55. Sri Chandrashekariah Vs State of Karnataka, WP No. 9721 of 2019 ISSUE: Reimbursement of differential tax amount arising out of change in tax regime from VAT to GST where:
“works contract” were entered prior to 01.07.2017 during KVAT regime and works are completed pre-GST but payments are made post-GST or
Contracts entered prior to 01.07.2017 but partly executed pre-GST and balance work executed post-GST or
Contracts for which tenders were invited during KVAT regime and finalised after 01.07.2017 under GST regime
contracts which were invited during KVAT regime under old schedule of rates (SR) but finalised under GST regime 55<br>
slide56. Sri Chandrashekariah Vs State of Karnataka, WP No. 9721 of 2019 HELD: The Hon’ble Court issued the following directions:
Payments received under pre-GST are to be assessed under KVAT
Calculate the balance works to be completed after 01.07.2017
Derive the rate of materials, KVAT items required or used to complete the balance works.
Deduct the "KVAT" amount from those materials and the service tax, if applicable.
Add the applicable "GST" on those items. 56<br>
slide57. Sri Chandrashekariah Vs State of Karnataka, WP No. 9721 of 2019 HELD: The Hon’ble Court issued the following directions:
Input Credit on the materials is to be arrived at and be set off as against the output GST, for those assessed under regular VAT.
Further, the “tax difference” should be calculated on such balance works executed or to be executed after 01.07.2017 separately.
Based on the above calculation, concerned department/authority has to decide whether agreement needs to be changed or not.
Supplementary agreement may be signed with the revised conditions 57<br>
slide58. Back Street Engineers Co-operative Society Ltd vs State of WB [2023 (156) taxmann.com 454 (Cal)] ISSUE: Petitioners were awarded contracts by Government contractees prior to GST implementation but same were executed in GST era - Petitioners received payments from Government contractees without GST
HELD: Government contractees were liable to bear additional tax liability for execution of subsisting Government contracts awarded during pre-GST regime or in post-GST regime without updating Schedule of Rates (SoR) incorporating applicable GST while preparing bill for payment.
Petitioners were to be directed to file representations before Additional Chief Secretary, Finance Department, Government of West Bengal – who shall take final decision 58<br>
slide59. Taxability of Intermediary Services 59<br>
slide60. DHARMENDRA M JANI [2023 (5) CENTAX 201 (BOM)] Issue: Constitutional validity of Section 13(8)(b) of the IGST Act, 2017 which prescribes place of supply of intermediary services to be location of supplier of services
Held: Split View – Matter referred to Third Judge
View expressed by Justice Ujjal Bhuyan
Unconstitutional - Runs completely contrary to very fundamental principle of destination-based consumption tax
Offends Articles 245, 246A, 269A and 286(1)(b) of Constitution
Beyond charging section and creates an artificial deeming fiction
View Expressed by Justice Abhay Ahuja
Constitutional – Prevents the escape of revenue
Supply under consideration is an inter-state supply of service. 60<br>
slide61. DHARMENDRA M JANI [2023 (5) CENTAX 201 (BOM)] – referee judge decision Held: Before the Referee Judge
By Section 13(8)(b) - Place of supply shall be (is deemed to be) the location of supplier of services.
Legal consequence by such deeming combination - A supply of service, of the nature of intermediary services - in the nature of "export of service" defined under Section 2(6) of the IGST Act - becomes an "intra-State" sale falling under the charging provision (Section 9) of the CGST Act and the MGST Act.
Neither CGST, nor SGST recognize tax on export of services - governed within domain of IGST Act
Thus, fiction which is created by section 13(8)(b) would be required to be confined only to provisions of IGST Act, as there is no scope for fiction travelling beyond provisions of IGST Act to CGST and MGST Acts. 61<br>
slide62. GENPACT INDIA (P) LTD VS UOI [2022 (144) TAXMANN.COM (P&H)] Issue: Petitioner - Business Process Outsourcing (BPO) Services entered into a Master Services Sub-Contracting with Genpact International Incorporated (GI). Whether the petitioner qualifies as an intermediary and thus not eligible for refund?
Held: Petitioner was providing services which had been sub-contracted to it by GI
Petitioner had no direct contract with customers of GI. Nothing on record to show that petitioner was liasoning or acting as an "intermediary
Respondent-department had erred in holding petitioner to be in a principal-agent relationship with GI.
Reliance placed on Circular 159/15/2021-GST dated 20.09.2021 – Minimum three parties, Does not supply on his own account – Principal to Principal basis 62<br>
slide63. E&Y LTD VS ADDT COMM, CGST APPEAL-II [2023 (4) CENTAX 440 (DEL)] Issue: Petitioner - provided various professional services to overseas EY Entities in terms of the agreements. Whether the petitioner qualifies as an intermediary and thus not eligible for refund?
Held: Petitioner was providing services to overseas entity and not involved in arranging or facilitating services.
The last limb of section 2(13) of the IGST Act reads as "but does not include a person who supplies such goods or services or both or securities on his own account" - Does not control the definition - Merely restricts the main definition.
There may be services, which may entail outsourcing some constituent part to a third party. But that would not be construed as intermediary services, if the service provider provides services to the recipient on his own account. 63<br>
slide64. OHMI INDUSTRIES ASIA P LTD VS ASST COMM. OF CGST [2023 (6) CENTAX 163 (DEL)] Issue: Petitioner - Petitioner was rendering market research services directly to OHMI, Japan, its overseas entity. Whether the petitioner qualifies as an intermediary and thus not eligible for refund?
Held:
No allegation that it had arranged supply of such services from a third party.
Petitioner was not acting as intermediary in respect of market research services. 64<br>
slide65. BOKS BUSINESS SERVICES VS Commnr of CGST [2023 10 Centax 44 (Del)] ISSUE: ITC claim filed by Petitioner on zero rated supply was rejected on the ground that assessee was as an intermediary and has not made any export of services.
Petitioner providing bookkeeping, payroll, and accounting services through the use of cloud technology to its affiliated entity (incorporated in UK).
HELD: Petitioner is neither facilitating the provision of services by a third entity nor acting as a middleman for procuring services for its affiliate. Petitioner is providing services on principal-to-principal basis.
Reference made to: M/s Ernst And Young Limited v. Additional Commissioner, CGST 2023:DHC:2116-DB and M/s Cube Highways and Transportation Assets Advisor Private Limited v. Assistant Commissioner CGST Division & Ors 2023:DHC:5822-DB.
Directed to process the refund claims of the Petitioner. 65<br>
slide66. Levy of GST on mining lease & royalty 66<br>
slide67. The levy of service tax on the grant of mining lease by a Government against payment of royalty was a subject matter of litigation under Erstwhile Service Tax Regime:
Udaipur Chambers of Commerce and Industry v. UOI 2018 (8) G.S.T.L. 170 (Raj.) and Stay granted in Udaipur Chambers of Commerce and Industry v. UOI 2018 (10) G.S.T.L. J167 (S.C.)].
Gujmin Industry Association vs UOI 2019 (20) G.S.T.L. 11 (Guj.).
The issue that is revolving around the payment of royalty and the tax thereon is that whether payment of royalty paid towards extraction of minerals is in the nature of ‘tax’ and cannot be considered as consideration for service. [See: India Cement Ltd & Others vs State of Tamil Nadu & Others (1990) 1 SCC 12]. This issue is pending before Nine Bench in the case of Mineral Area Development Authority & Others vs Steel Authority of India & Others (2011) 4 SCC 450. 67<br>
slide68. Taxability of secondment contracts 68<br>
slide69. C.C., C.E. & ST Bangalore vs Northern Operating Systems (P) Ltd [2022 (138) taxmann.com 359 (SC)] ISSUE: The overseas entity has a pool of highly skilled employees which are seconded to the assessee. While the employees were under the control of the assessee and worked under its direction, the remuneration was paid by the overseas employer. The overseas entity raised a debit note on the assessee to recover the remuneration.
Whether the overseas entity provided manpower services to the assessee? 69<br>
slide70. C.C., C.E. & ST Bangalore vs Northern Operating Systems (P) Ltd [2022 (138) taxmann.com 359 (SC)] HELD: It was observed that there is no single determinative factor while deciding whether an arrangement is a contract for service or contract of service and applied the test of substance over form
It was opined that the arrangement is a quid pro quo, whereby the assessee has the benefit of experts for a limited period. It was held that the overseas entity was providing manpower recruitment and supply services to the assessee. 70<br>
slide71. Taxability of secondment contracts Based on the decision of the Apex Court, department has issued numerous notices in the GST regime, demanding tax under reverse charge mechanism on secondment of employees.
Points for consideration
Whether employment contracts can be brought to levy of GST ? [Section 7 read with Schedule III]
Aspect of dual employment
Whether any consideration flows from Indian entity to overseas entity? 71<br>
slide72. Taxability of secondment contracts Interim Orders:
Alstom Transport India Ltd vs The State of Karnataka [WP No. 23644/2023]: The petitioner has employed certain expatriates and is paying salary in the Indian currency, and because these employees have maintained their lien with the corresponding overseas company, social security cost is paid. The decision in the case of Northern Operating Systems Pvt. Ltd., is in the peculiarities of that particular case and cannot be applied in distinguishable circumstances. [Reference made in Mitsubishi Electric India Pvt Ltd vs UOI (CWP-25351-2023 P&H)]
United Breweries Ltd vs The Additional Commissioner of Central Tax [WP No. 22959/2023]
Bhoruka Extrusions Pvt Ltd vs ACCT [WP No. 25943/2023 Kar HC]
Biesse India Pvt Ltd vs ACCT [ WP No. 26812/2023 Kar HC] 72<br>
slide73. Taxability of secondment contracts Instruction No. 5/2023-GST dated 13.12.2023
A careful reading of the NOS judgment indicates that Hon’ble Supreme Court’s emphasis is on a nuanced examination based on the unique characteristics of each specific arrangement, rather than relying on any singular test.
The decision of the Hon’ble Supreme Court in the NOS judgment should not be applied mechanically in all the cases. Investigation in each case requires a careful consideration of its distinct factual matrix, including the terms of contract between overseas company and Indian entity, to determine taxability or its extent under GST and applicability of the principles laid down by the Hon’ble Supreme Court’s judgment in NOS case. 73<br>
slide74. Validity of show cause notices issued under Section 73 of CGST Act, 2017? 74<br>
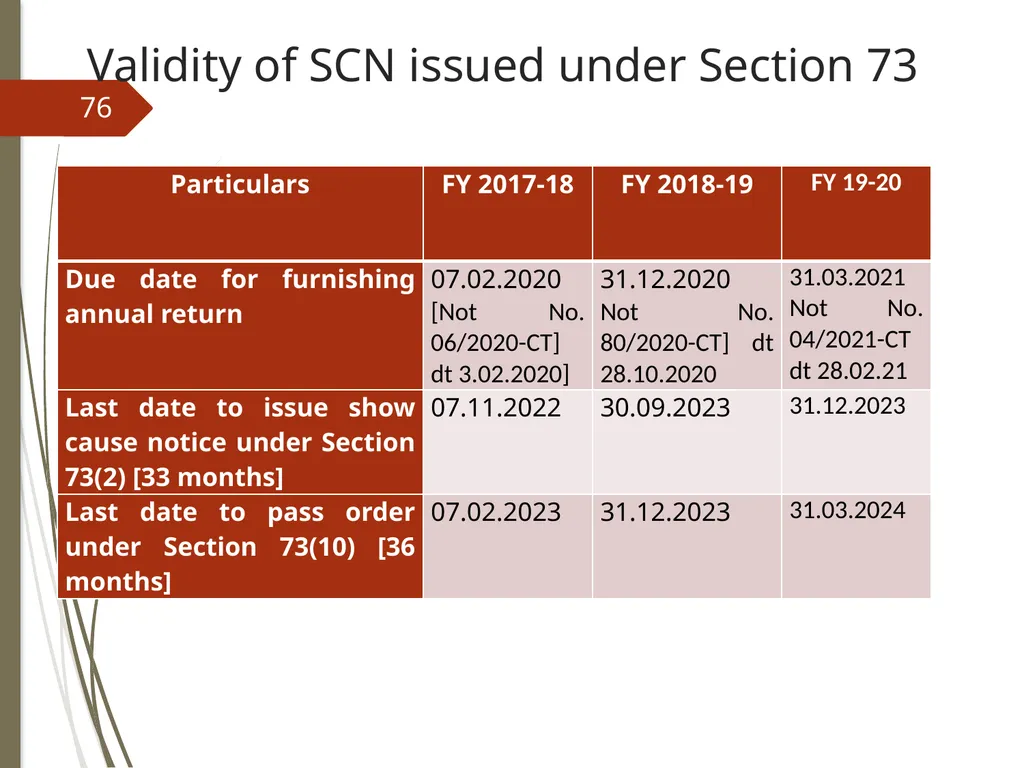
slide75. Validity of SCN issued under Section 73 Section 73(2) - Issuance of show cause notice at least 3 months prior to the time limit specified under sub-section 10 for issuance of order
Section 73(10) – Pass order within three years from the due date for furnishing of annual return for the financial year to which the tax not paid or short paid or input tax credit wrongly availed or utilised relates to or within three years from the date of erroneous refund.
Thus, show cause notice is to be issued within 33 months 75<br>
slide76. Validity of SCN issued under Section 73 76<br>
slide77. Validity of SCN issued under Section 73 Section 168A empowers Government to issue Notifications to extend time limit specified under CGST Act, 2017, which cannot be complied due to force majeure.
Expression “force majeure” means a case of war, epidemic, flood, drought, fire, cyclone, earthquake or any other calamity caused by nature or otherwise affecting the implementation of any of the provisions of this Act. 77<br>
slide78. Validity of SCN issued under Section 73 In exercise of powers of Section 168A
Notification No. 35/2020-CT dated 03.04.2020 and Notification No. 14/2021-CT dated 01.05.2021 were issued from time to time, so as to extend the time limit for issuing show cause notice and passing orders, in view of COVID pandemic
Subsequently, Notification No. 13/2022-CT dated 05.07.2022 was issued to extend the time limit for passing order u/s 73 for FY 2017-18 to 30.9.2023 78<br>
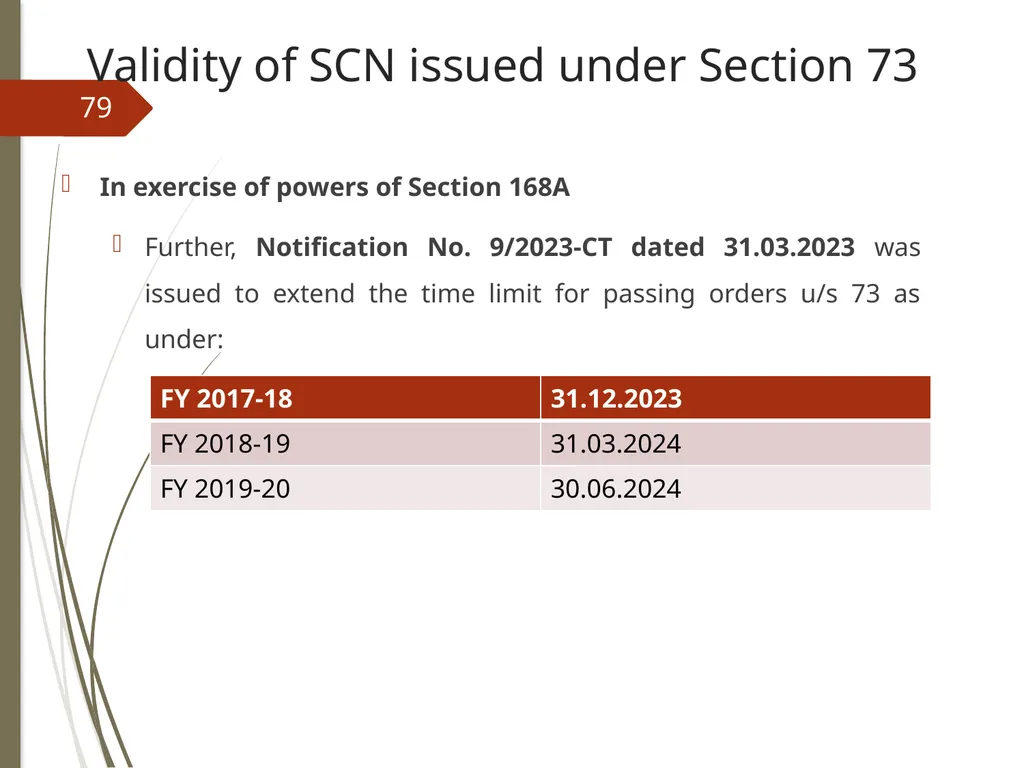
slide79. Validity of SCN issued under Section 73 In exercise of powers of Section 168A
Further, Notification No. 9/2023-CT dated 31.03.2023 was issued to extend the time limit for passing orders u/s 73 as under: 79<br>
slide80. Validity of SCN issued under Section 73 Issues for consideration
Reasons for issuing Notification in 2022 and 2023 under Section 168A, involving force majeure event?
Effect of Supreme Court order for extending limitation period dated 09.05.2022, which sough to exclude the period from 15.03.2020 till 28.02.2022 for the purposes of limitation.
SRSS Agro Pvt Ltd vs UOI [SCA No. 19720/2023]: It is the case of the petitioner that the notification dated 31.03.2023 extending the time limit specified under Section 73 of the Act by virtue of the powers under Section 168A of the Act is unjustified as extension has to be for special circumstances. Notice issued to respondents 80<br>
slide81. DRC-01A: Whether Mandatory or Optional? 81<br>
slide82. Agrometal Vendibles Pvt. Ltd. vs State of Gujarat 2022 (63) G.S.T.L. 212 (Guj.): Issue: This case relates to scrutiny of returns and inconsistencies noticed in taxpayer’s records for year 2019-20. The writ-applicant had received an intimation for tax ascertained as payable, through DRC-01 dated 14-03-2022, instead of Form DRC -01A.
Held: At the stage of an intimation under sub-section (5) of Section 74 in the Form GST DRC-01A, it is Rule 142(1A) which is applicable. There is a vast difference between Rule 142(1)(a) and Rule 142(1A) of the Rules.
Therefore, w.e.f. 15.10.2020, if the department deems fit to issue any intimation of tax ascertained as being payable under sub-section (5) of Section 74 in accordance with the Rule 142(1A) of the Rules, it shall issue notice in the Form GST DRC-01A. 82<br>
slide83. Gulati Enterprises Versus C.B.I. & C. – 2023 (68) G.S.T.L. 237 (Del.) Issue: Whether a pre-show cause consultation notice was required to be mandatorily issued, and is there any non-adherence to Rule 142(1A) in the present case?
Held: The Court held that with effect from 15-10-2020 i.e., after the impugned show cause notice was issued, Rule 142(1A) has undergone a change, inasmuch as the word 'shall' has been replaced with 'may'. The impact of the amendment was not considered, as admittedly the show cause notice was issued prior to 15-10-2020 i.e., on 21-5-2020
Therefore, having regard to the position which obtained prior to 15-10-2020, it was held that pre-show cause notice consultation was mandatory under the unamended Rule 142(1A). 83<br>
slide84. New Morning Star Travels Versus Deputy Commissioner [(2023) 12 Centax 198 (AP) Issue: The assessee was issued DRC-01A intimation by a GST officer for period from July 2017 to 2018-19. Subsequently, the case was transferred to another officer who issued show cause notice under DRC-01 under Section 74(1) for period from 01-07-2017 to 31-03-2021, but no intimation was issued as DRC-01A under Rule 142(1A) for the period after 2018-19
Held: Prior to the amendment - the employment of the word 'shall' in Rule 142(1A) would indicate that the officer shall necessarily follow the procedure prescribed under Rule 142(1A) of the Act, meaning thereby, an intimation of tax shall be issued in terms of Rule 142(1A) at first and if there is no response from the tax payer, then he can issue a show cause notice under section 74(1) of CGST/APGST Act 84<br>
slide85. New Morning Star Travels Versus Deputy Commissioner [(2023) 12 Centax 198 (AP) Held: Rule 142(1A) of CGST Rules, 2017 has been amended by virtue of notification No. 79/2020-CT dt.15-10-2020 and by virtue of the said amendment, the words 'proper officer shall' has been substituted with the words 'proper officer may' as appearing in Rule142(1A). Thus, post amendment, the issuance of intimation under Rule142(1A) is not mandatory, but discretionary on the part of the assessing authority.
Since the tax period related to 1-7-2017 to 31-3-2021 which covers the pre and post amended period of Rule 142(1A), the Respondent ought to have issued tax intimation to the Petitioner under Rule 142(1A) 85<br>
slide86. Recovery of refund without challenging the order 86<br>
slide87. Recovery of refund without challenging the order Ganesh Ores Pvt Ltd vs State of Orissa [2022 (59) GSTL 258 (Ori)] [SLP dismissed – 2022 (59) GSTL 257 (SC)] - There is no restriction that the appeal needs to be filed before issue of SCN in case of the erroneous refunds.
CCE Vs Flock India [2000 (120) ELT 285 (SC)] -where an adjudicating authority has passed an order which is appealable under the statute and the party aggrieved did not choose to exercise the statutory right of filing an appeal it is not open to the party to question the correctness of the order of the adjudicating authority subsequently by filing a claim for refund on the ground that the adjudicating authority had committed an error in passing his order. 87<br>
slide88. Recovery of refund without challenging the order Priya Blue Industries Vs CC (preventive) [2004 (172) ELT 145 (SC)] - A refund claim contrary to an assessment order is not maintainable without the order of assessment having been modified in appeal or reviewed under Section 28 of Customs Act, 1962
ITC Ltd. Vs. CCE [2019-TIOL-481-SC-LB] - Bill of entry being an assessment order, no refund could be claimed unless the said assessment is challenged.
Jairath International Vs UOI [2019-TIOL-2459-HC-P&H-CUS] - Shipping bill is an assessment order and could be challenged under the appeal provisions. Therefore, unless the same is challenged, the shipping bill cannot be modified by way of issue of show cause notice by any authority 88<br>
slide89. Issues on Provisional Attachment 89<br>
slide90. Provisional Attachment Different kinds of issues under Section 83 are:
In many cases, the forming of ‘opinion’ by the proper officer has not been established for provisional attachment under section 83 [See: Radha Krishan Industries v. State of Himachal Pradesh and Others - 2021-TIOL-179-SC-GST]
The order of provisional attachment continues to exist even after one year has elapsed. The Act permits the proper officer to provisionally attach the properties only for one year [See: M/s. Krishna Fashion vs UOI 2022-TIOL-108-HC-DEL-GST] 90<br>
slide91. Provisional Attachment Different kinds of issues under Section 83 are:
The cash credit accounts of the assessees are getting provisionally attached even though in various decisions it is settled that the cash credit accounts cannot be attached for non-existence of debtor-creditor relationship [See: Manish Scrap Traders vs Principal Commissioner 2022-TIOL-54-HC-AHM-GST]
Power to order a provisional attachment of the property of a taxable person including a bank account is draconian in nature [See: Radha Krishan Industries v. State of Himachal Pradesh and Others - 2021-TIOL-179-SC-GST] 91<br>
slide92. Provisional Attachment The provisional attachment under section 83 is permissible only when proceedings under section 62 or 63 or 64 or 67 or 73 or 74 are pending [See: S.S. Offshore (P.) Ltd. vs UOI [2021] 131 taxmann.com 162 (Bombay); Bhavesh Kiritbhai Kalani vs UOI [2021] 127 taxmann.com 199 (Gujarat)]
The bank account of the director of the company was provisionally attached. The ground was that the said company was availing ITC against fake/ineligible invoices. The bank attachment is permissible only in respect of taxable person (who is registered or liable to register) and not against any other person [See: Roshni Sana Jaiswal vs Commnr of Central Taxes [2021] 128 taxmann.com 357 (Delhi)] 92<br>
slide93. Thank You 93<br>
Senior Advocate<br>
slide2. ISSUES UNDER INPUT TAX CREDIT 2<br>
slide3. AVAILEMENT/ REVERSAL OF CREDIT 3<br>
slide4. SUNCRAFT ENERGY (P) LTD vs ASST. COMMNR [2023 153 taxmann.com 81 (CAL)] ISSUE: Non-reflection of supplier’s invoice in GSTR 2A - require reversal of input tax credit by the buyer ?
HELD:
Press release dated 18.10.2018 clarifies that GSTR-2A is for taxpayer facilitation and does not impact the ability of the taxpayer to avail ITC on self-assessment basis.
The department without resorting to any action against the supplier, who is the selling dealer, demand cannot be raised on the buyer. 4<br>
slide5. SUNCRAFT ENERGY (P) LTD vs ASST. COMMNR [2023 153 taxmann.com 81 (CAL)] The tax invoices and the bank statement produced by the buyer to substantiate that price of goods and taxes have been paid to be considered.
It was directed to first proceed against the seller and only in exceptional circumstances as clarified by Board, then and only then action can be initiated against seller.
SLP has been dismissed by the Hon’ble Supreme Court [2023 (157) taxmann.com (352) SC] 5<br>
slide6. Aastha Enterprises vs State of Bihar [2023 (153) TAXMANN.COM 491 (Patna)] ISSUE: Whether the purchasing dealer can be denied input tax credit when selling dealer, who defaulted payment of collected tax to the State?
HELD:
The benefit of claiming credit is one conferred by Statute - if conditions prescribed therein are not complied; no benefit flows to the claimant.
The question of double taxation does not arise - since the claim is denied only when the supplier who collected tax from the purchaser fails to pay it to the Government. 6<br>
slide7. Aastha Enterprises vs State of Bihar [2023 (153) TAXMANN.COM 491 (Patna)] HELD:
Statue has a measure to recover collected tax from the seller – it does not absolve the liability of the taxpayer to satisfy the entire liability to the Government.
The word 'Input Tax Credit’ postulates a situation where the purchasing dealer has a credit in the ledger account maintained by it with the Government. The said credit can only arise when the supplier pays up the tax collected from the purchaser.
Accordingly, credit was denied to the purchasing dealer. 7<br>
slide8. STATE OF KARNATAKA vs ECOM GILL COFFEE TRADING P LTD [2023 (4) CENTAX 223 (SC)] ISSUE: Burden of proof in respect of genuineness of purchases for availing credit.
The respondents had claimed credit on alleged purchases made from the respective dealers.
The Tribunal and High Court allowed the credit, by observing that as the purchasing dealers produced the invoices issued by the respective dealers and in some cases, made the payment through cheques, the Assessing Officer was not justified in denying the credit.
HELD:
Mere claim by dealer that he is a bona fide purchaser is not enough and sufficient to claim credit. 8<br>
slide9. STATE OF KARNATAKA vs ECOM GILL COFFEE TRADING P LTD [2023 (4) CENTAX 223 (SC)] Burden of proving the correctness of credit remains upon the dealer claiming such credit. Such a burden of proof cannot get shifted on the revenue.
Mere production of the invoices or the payment made by cheques is not enough and cannot be said to be discharging the burden of proof cast under section 70 of the KVAT Act.
Purchase transaction was required to be proved by furnishing details viz. name and address of selling dealer, details of vehicle which had delivered goods, payment of freight charges, acknowledgement of taking delivery of goods etc.
Actual physical movement of the goods is the sine qua non for claiming credit. 9<br>
slide10. Malik traders VS state of up [2023 155 taxmann.com 517 (All)] ISSUE: SCN was issued for wrong availment of ITC by the Petitioner.
HELD:
Petitioner has brought on record - tax invoices, e-way bills, GR and payment through banking channel, but no such details such as payment of freight charges, acknowledgement of taking delivery of goods, toll receipts and payment thereof has been provided.
In the absence of these documents, the actual physical movement of goods and genuineness of transportation as well as transaction cannot be established.
Reference made to: Ecom Gill Coffee Trading Pvt Ltd (SC) decision – To say that actual physical movement of goods to be proved. 10<br>
slide11. Henna Medicals VS State Tax Officer [2023 155 taxmann.com 29 (Kerala)] ISSUE: Credit of input tax was denied merely on ground of difference between GSTR 2A and GSTR 3B filed by the Petitioner.
HELD:
Matter was remanded back – To examine the evidence of the petitioner irrespective of the Form GSTR 2A for the petitioner's claim for the input tax credit.
After examination, the assessing officer directed to pass a fresh order.
Reference made to: Diya Agencies v. STO WPC 29769/2023 (Cal HC) and The State of Karnataka v. M/s Ecom Gill Coffee Trading Private Limited 2023 (3) TMI 533 SC. 11<br>
slide12. DENIAL OF CREDIT ON ACCOUNT OF MISMATCH IN GSTR 2A & GSTR 3B Goparaj Gopalakrishnan Pillai vs State Tax Officer [2023 11 Centax 203 (Ker)] – Merely because tax paid is not reflected in GSTR2A would not be sufficient to deny ITC to the buyer. Opportunity to be given to produce evidence to support the claim of ITC by the buyer. 12<br>
slide13. M/s. Gargo Traders VS Joint Commnr of Central tax [2023 151 taxmann.com 270 (CAL)] ISSUE: ITC was denied on ground that supplier was fake and non-existing.
GST registration of the supplier was cancelled with retrospective effect covering the transaction of the petitioner.
HELD: At time of transaction, supplier's name as registered taxable person was already available on Government record and petitioner paid amount on purchased articles as well as tax on same through bank and not in cash.
It cannot be said that there was any failure on petitioner's part in compliance of any obligation required under statute.
Directed the concerned authority to verify the documents on which the petitioner relies upon and grant the relief. 13<br>
slide14. SHRADDHA OVERSEAS P. LTD VS ACST [2023 (3) CENTAX 118 (CAL)] ISSUE: Availment of Input Tax Credit (ITC) without receiving any goods, based on fake documents issued by non-existing dealers was alleged.
HELD: Division bench while remanding the matter, observed that:
To conclude that the dealer is a non-existing dealer, there should be material to show - On the date of transaction, there was no valid registration.
If the cancellation of the registration of the dealer is by way of retrospective cancellation, - Question would be as to whether it would affect the transaction, more particularly when the appellant has been able to show that the payments has been done through banking challans. 14<br>
slide15. Vivo Mobile India (P) ltd VS UOI [2023 155 taxmann.com 324 (All)] ISSUE: Revenue had passed an order opining that Petitioner had availed/utilized excess ITC for the month of Feb & Aug 2020, which is in violation of Rule 36(4) of CGST Rules, 2017.
On the other hand - Petitioner stated that revenue erred in looking at a month-to-month reconciliation of ITC in GSTR 3B vs GSTR 2A. They ought to have looked at that period as a single tax period i.e., cumulatively from Feb 2020 to Aug 2020.
Revenue relied on clause 3(3) of Circular No. 123/42/219-GST dated 11.11.2019 – clarified that the words "on the due date of filing of the returns“ in Rule 36(4) – refer to the date when reconciliation to be made. Whether ITC to be availed based on month-on-month or cumulative reconciliation? 15<br>
slide16. Vivo Mobile India (P) ltd VS UOI [2023 155 taxmann.com 324 (All)] HELD:
The scheme of the Act is to let ITC arise and be availed provisionally, in a continuously moving value addition chain, subject to other conditions including actual payment of tax being eventually proven and remaining undoubted.
Date of filing of GSTR 1 is fixed at 10th of next month – by way of principle it is difficult to accept that ITC could be availed only with reference to that date.
Reference made to Bharti Airtel Ltd (SC) & Suncraft Ltd (Cal HC) – GSTR1 is a necessary step of facilitator. 16<br>
slide17. Vivo Mobile India (P) ltd VS UOI [2023 155 taxmann.com 324 (All)] HELD: Rule 36 (4) and its interpretation:
Rule 36(4) is complete and provides for a functional.
1st Proviso to Rule 36(4) - condition in Rule 36(4) shall apply cumulatively for the period Feb to Aug 2020: Meaning of cumulatively – all additions made, taken together.
The purpose of proviso - grant benefit of ITC late accrued, to transactions completed in the past, by treating Feb to Aug 2020 as one period.
Clarified that Rule 36(4) – necessarily require the computation of eligible ITC on a month-to-month basis, at the same time, a conscious departure was caused by the first proviso for a fixed period February 2020 to August 2020. 17<br>
slide18. VALIDITY OF SECTION 16(4) OF CGST ACT, 2017 18<br>
slide19. Gobinda Construction VS UOI [2023 154 taxmann.com 311(Patna)] ISSUE: Constitutional validity of section 16(4) of the CGST Act has been challenged as violative of Article 14 and 300A of the Constitution.
Alternatively, section 16(4) to be read as procedural requirement and cannot override section 16(1) conditions.
HELD:
ITC is not unconditional - a registered person becomes entitled to ITC only if the requisite conditions stipulated therein are fulfilled.
On close reading of section 16(1) – the provisions of section 16(4) is one of the conditions which makes a registered person entitled to take ITC. 19<br>
slide20. Gobinda Construction VS UOI [2023 154 taxmann.com 311(Patna)] HELD:
Reference made to Godrej & Boyce Mfg. Co. (P.) Ltd. v. CST [1992] 3 SCC 624 & ALD Automotive (P.) Ltd [2018] 99 taxmann.com 202 (SC) - ITC is in the nature of benefit/concession extended to a dealer and the concession can be received by the beneficiary only as per the scheme of the statute.
Section 16(4) to be read as directory – The concession of ITC is dependent on fulfillment of requisite conditions laid down in under various provisions of section 16 including 16(4) thereof.
Section 16(4) is constitutionally valid and not violative of Article 19(1)(g) and 300A of the Constitution. 20<br>
slide21. THIRUMALAKONDA PLYWOODS VS Asst. Commnr [2023 8 Centax 276 (AP)] ISSUE: Constitutional validity of section 16(4) of the CGST Act has been challenged as violative of Article 14 and 300A of the Constitution.
HELD:
Section 16(2): Precisely while section 16 sub-section (2) prescribes the eligibility criteria which is sine qua non for claiming ITC, sub-section (3) and (4) impose conditions or limitation for claiming ITC.
Whether 16(2) overrides the rest of section 16, especially 16(4): Section 16(2) only overrides the provision which enables the ITC i.e., section 16(1). Section 16(2) is not an enabling provision but a restricting provision 21<br>
slide22. THIRUMALAKONDA PLYWOODS VS Asst. Commnr [2023 8 Centax 276 (AP)] HELD:
Section 16(4) being a non-contradictory provision and capable of clear interpretation, will not be overridden by non obstante provision u/s 16(2).
If the legislature has no intention to impose time limitation, there was no necessity to insert a specific provision under section 16(4) and to further intend to override it through section 16(2) which is a futile exercise. 22<br>
slide23. THIRUMALAKONDA PLYWOODS VS Asst. Commnr [2023 8 Centax 276 (AP)] HELD:
Whether section 16(4) violates Article 14, 19(1)(g) & 300A: ITC is a mere concession/rebate/benefit but not a statutory or constitutional right. Imposing conditions including time limitation for availing the said concession will not amount to violation of constitution or any statute.
The operative spheres of Articles 14/19/300A is different from that of Section 16. Hence, no challenge on the ground of constitutional provisions could be made. 23<br>
slide24. BBA Infrastructure Ltd vs Senior Joint Comm of State Tax[2023 157 taxmann.com 345 (Cal)] ISSUE: Availment of ITC beyond the time limit stipulated under Section 16(4) of CGST Act, 2017- ITC was not taken through return but through books of account immediately on receipt of goods and services in terms of first proviso to section 16(2), and section 16(2) has overriding effect on section 16(4) -
HELD:
Section 16(2) does not appear to be a provision which allows Input Tax Credit, rather Section 16(1) is the enabling provision and Section16(2) restricts the credit which is otherwise allowed to the dealers who satisfied the condition.
FOLLWED - Gobinda Construction VS UOI (supra) 24<br>
slide25. Issues on blocking of credit under Rule 86A ITC cannot be blocked solely based on communication of Commissioner (Central Tax) and without any tangible material to form any belief that ITC is fraudulently availed is not sustainable. Decisions rendered in Income Tax Law for the expression ‘reason to believe’ is relevant [See: Parity Infotech Solutions (P) Ltd vs Government of National Capital Territory of Delhi (2023) 7 Centax 169 (Del.)].
Blocking of credit cannot be done by an officer below the rank of Assistant Commissioner. Blocking of credit by any other officer was held to be illegal and contrary to Rule 86A [See: Guru Storage Batteries vs State of Maharashtra (2023) 11 Centax 308 (Bom)]. 25<br>
slide26. Issues on blocking of credit under Rule 86A Electronic credit ledger cannot be blocked for more than one year [See: Raghbir Singh Govt. Contractor vs State of Haryana (2023) 4 Centax 396 (P & H) and TVL. New Royal Traders vs Asst Commnr (2023) 10 Centax 350 (Mad)].
Credit ledger cannot be blocked without assigning any reason for such blocking [See: Vijay Jaiswal vs Asst Commnr (2023) 2 Centax 104 (Cal)]. 26<br>
slide27. Issues under section 17(5) 27<br>
slide28. Issues under section 17(5) ITC on construction services:
Safari Retreats Pvt Ltd (P.) Ltd. vs Chief Commissioner of CGST [2019] 105 taxmann.com 324 (Orissa):
The credit on the input and input services used in construction of shopping mall was allowed to be utilized for payment of GST on renting of such shopping malls.
SLP before the Hon’ble Supreme Court is pending in Chief Commissioner of CGST vs Safari Retreats (P.) Ltd 2019-TIOL-489-SC-GST. All the pleadings are completed, and the judgement is reserved. 28<br>
slide29. Issues under section 17(5) Issues to be addressed in case of Safari:
Section 16 of the CGST Act, 2017 - the terminology used is “used in the course or furtherance of business”. Credit is available when used in course or furtherance of business.
Section 17(1) - business related input tax credits are allowable while credit for other uses is not. Similarly, 17(2) talks of only business credits.
Leasing of immovable property is clearly a taxable supply on which entire chain of input tax credit is available. Since, GST is enshrined on the principles of ‘seamless flow of credit’ – no credit can be denied when supply chain continues. 29<br>
slide30. Issues under section 17(5) Issues to be addressed in case of Safari:
Credit on sale of land and buildings covered under Schedule III are reversed under Section 17(2) and 17 (3) therefore, once the credit is already lost, Section 17(5) cannot be used again to demand reversal of input tax credit once over.
Appropriate meaning to interpret section 17(5): Section 17(5) talks of blocking credits where transactions are covered under Section 17(1) – credits when used for other purposes.
The non obstante clause found in Section 17(5) is to be read as not overriding but in the context - credit is available under Section 16 or 18 when inputs are used for the purpose of business, and if the same is used for “other purposes” credit has to be reversed. 30<br>
slide31. Issues under section 17(5) Usage of term plant and machinery in section 17(5):
Machinery meaning of –
The word ‘machinery’, when used in ordinary language prima facie means some mechanical contrivances which, by themselves or in combination with one or more other mechanical contrivances, by the combined movement and inter-dependent operation of their respective parts generate power, or evoke, modify, apply or direct natural forces with the object in each case of effecting so definite and specific a result. [See: Commissioner of Income Tax Vs Mir Mohammad Ali (1964) 53 ITR 165 (SC)]. 31<br>
slide32. Issues under section 17(5) Plant meaning of –
Plant must be something which is used by the assessee in aid of the object or purpose of the business. It is not only the means of processing the end-product, but it includes the entire operation undertaken for the purpose of obtaining the end-product. Railway sidings were thus treated as ‘plant’. [See: CIT Vs Birla Jute & Industries Ltd (2003) 260 ITR 55 (Cal)]. 32<br>
slide33. Issues under section 17(5) The following has been held to be plant:
Sanitary fittings in the bathrooms in a hotel [See: CIT Vs Taj Mahal Hotel (1971) 82 ITR 44 (SC)].
Building which is used as hotel or cinema theatre is a plant [See: CIT vs Anand Theatres (2000) 244 ITR 192 (SC)].
Generating-station building was so constructed as to be an integral part of its generating system was held to be plant [See: CIT vs Karnataka Power Corporation (2001) 247 ITR 268 (SC)].
Nursing home equipped to enable storage of surgical instruments & bandages was held as plant [See: CIT vs Dr. B. Venkata Rao (2000) 243 ITR 81 (SC)]. 33<br>
slide34. S.R. CONSTRUCTIONS.VS UOI [2023 6 Centax 38 (Tripura)] ISSUE: Petitioner: Petitioner a construction company. They have a works contract agreement with the M/s Hotel Polo Pvt. Ltd. and constructed a hotel at Agartala.
Petitioner availed credit of inputs used for providing works contract services. The said claim of ITC was rejecting – stating that inputs were used for construction of immovable properties and is hit by section 17(5).
HELD: Petitioner has fulfilled all the conditions of work contracts as he is providing work contract services under a contract for construction of building of a Hotel, wherein transfer of property in goods is involved in the execution of such contract. 34<br>
slide35. S.R. CONSTRUCTIONS.VS UOI [2023 6 Centax 38 (Tripura)] HELD: Petitioner has been providing work contract services to the owner of the hotel and not for its own.
For providing works contract of constriction services, Petitioner is entitled to avail credit of goods/services being used for providing such taxable works contract services.
Petitioner do not fall within the definition of section 17(5)(c) of the CGST Act, 2017.
Comment: Even though the hotel constructed remained to be immovable property, credit was never denied, considering that construction was carried not on Petitioner’s own account. 35<br>
slide36. Issues under Section 17(5) ARS STEEL & ALLOY INTERNATIONAL (P) LTD VS STO [2021 127 TAXMANN.COM 787 (MAD)]:
ISSUE: Petitioner manufacturer of MS Billets and Ingots. There was a loss of small portion of the inputs, inherent to the manufacturing process.
Department seeks to reverse a portion of the ITC claimed by the petitioners, proportionate to the loss of the input, referring to the provisions of section 17(5)(h) of the GST Act.
17(5)(h): goods lost, stolen, destroyed, written off or disposed of by way of gift or free samples. 36<br>
slide37. Issues under Section 17(5) ARS STEEL & ALLOY INTERNATIONAL (P) LTD VS STO [2021 127 TAXMANN.COM 787 (MAD)]:
HELD: The situations set out above in clause (h) indicate loss of inputs that are quantifiable and involve external factors or compulsions.
A loss that is occasioned by consumption in the process of manufacture is one which is inherent to the process of manufacture itself and such loss was not contemplated or covered by situations adumbrated under section 17(5)(h). 37<br>
slide38. Issues under Section 17(5) Insertion of new clause – Section 17(5)(fa) vide Finance Act, 2023, w.e.f. 1-10-2023:
(fa) Goods or services or both received by a taxable person, which are used or intended to be used for activities relating to his obligations under corporate social responsibility referred to in section 135 of the Companies Act, 2013 (18 of 2013).
This amendment is effective from 01.10.2023. 38<br>
slide39. Issues under Section 17(5) Insertion of new clause – Section 17(5)(fa) vide Finance Act, 2023, w.e.f. 1-10-2023:
Issues:
For the period prior to 01.10.2023 – Credit can be availed on CSR expenses – Retrospectivity and prospectivity?
Meaning of phrase “activities relating to his obligations under corporate social responsibility” ?
Whether voluntary CSR expenditure is eligible for credit?
What if an individual or firms incurs CSR expenditure? 39<br>
slide40. Circular No. 199/11/2023-GST dated 17.07.2023 Clarification regarding taxation and input tax credit aspects between distinct persons: 40<br>
slide41. Circular No. 199/11/2023-GST dated 17.07.2023 Clarification regarding taxation and input tax credit aspects between distinct persons: 41<br>
slide42. Circular No. 199/11/2023-GST dated 17.07.2023 Clarification regarding taxation and input tax credit aspects between distinct persons: 42<br>
slide43. Circular No. 199/11/2023-GST Issues yet to be clarified:
The circular fails to address the valuation mechanism in case where recipient is not eligible for full ITC – Whether open market value under Rule 28 can be adopted or any other valuation at the option of the assessee ?
Whether it is open to the assessee not to opt for ISD and continue to charge all its expenses through cross charge? OR is it permissible to opt for ISD for one period and cross charge for other period?
Fate of the pending litigations ? Is department going to withdraw the appeals or petitions pending ? 43<br>
slide44. Issues w.r.t. Real Estate Sector 44<br>
slide45. Issues w.r.t. JDA JDA - Construction & handing over of specified number of flats in lieu of developmental rights as Landowners share:
JDA is in the nature of exchange of immovable property and hence does not qualify to be Construction service.
Landowners share under JDA – No purchaser during construction, Supreme court in L&T case held that activity of construction of apartment where there is no purchaser during construction stage would not be a works contract and hence does not qualify to be a service under Para 5(b) of Schedule II.
5(b) would also be not applicable as the building given to owners is not a sale. Further, the consideration for such transfer, i.e. transfer of ownership in land would be made only after completion of construction. 45<br>
slide46. Issues w.r.t. JDA GST implications on Landowners– JDA:
The transfer of developmental rights are in the nature of immovable property and hence does not qualify to be supply.
The grant of developmental right to the developer and permitting the developer to enter / possession of immovable property would not be liable to GST levy under Para 2(a) of Schedule II. 46<br>
slide47. Issues w.r.t. JDA ISSUE: Para 2A under Notification 11/2017-CT(R) – inserted w.e.f., 1.4.2019: valuation of construction of landowners share:
Para 2A provides that value of construction shall be deemed to be equal to Total amount charged for similar apartments in the project from independent buyers (other than landowner), nearest to the date on which such development right or FSI is transferred to promoter,
Less the value of value of land transferred as prescribed in Para 2.
No specific or express provision under CGST Act, 2017 for levy on ‘landowners share’ under JDA – hence legally impermissible to impose levy of tax on Landowner’s share in the hands of the Developer. In view of the absence of statutory provisions of for levy of GST on the landowners share, valuation prescribed in Para 2A could be challenged.
Valuation provision could be challenged on the basis that as there is no service element in JDA between the developer and the landowners, no question of applying valuation provision. 47<br>
slide48. Issues w.r.t. JDA ISSUE: Para 2A – inserted w.e.f., 1.4.2019: valuation of construction of landowners share:
Valuation of landowner's share provided in Circular No.151/2/2012-ST dated 10.02.2012 has been incorporated ‘verbatim’ in Para 2A
It is impossible to obtain value of similar apartments (sold to independent buyers) nearest to date on which development right / FSI was transferred to promoter under JDA – since development rights were transferred at the time of entering JDA, whereas apartments (sold to independent buyers) are constructed after many years.
It is also a well settled principle that the law does not compel a man to do that which he cannot possibly do and the said principle is well expressed in legal maxim “lex non cogit ad impossibilia” is squarely attracted to the facts and circumstances of the present case. 48<br>
slide49. Issues w.r.t. Immovable Property Issue: Entry 5(b) & 6(a) to Schedule II – Construction – validity?
Whether Construction - entry 5(b) of II Schedule would qualify to be supply? Whether Works contract is a supply?
Amendment by Finance Act, 2018 w.e.f., 1.2.2019 - Section 7 is amended with retrospective effect from 1.7.2017 - the entries in Schedule II shall first qualify as service and only then the classification as Service or as Goods would come into play.
There is no deeming clause unlike in erstwhile Service Tax law, to deem the sale of building during construction as service.
Entry 5(b) treats the entire activity of construction as ‘services’ is ultra vires and contradictory to Article 366(29A)(b) which bifurcates the transfer of goods portion from the composite contract and treats the same as deemed sale. 49<br>
slide50. Issues w.r.t. Immovable Property Issue: Omission of CLAUSE (ii) – works contract entry
Omission of Works Contract – Entry 3(ii) – Composite supply of works contract u/s 2(119) is unreasonable and arbitrary hence violative of Article 14 & 19:
Omission makes it mandatory for choose other entries where valuation of total amount has compulsorily included ‘value of land’.
Prior to omission, Developer / Promoter was eligible to opt for clause (ii) of Sl. No. 3 of Notification No. 11/2017-CT (Rate) and pay GST at 18% on Construction agreements.
Whether residual entry 3(xii) could be opted for payment of GST on construction services alone? 50<br>
slide51. Issues w.r.t. Immovable Property Issue: GST on immovable property transactions being unconstitutional lacking legislative competence:
Notification No. 11/2017-CT(R) - Para 2 is made applicable for all ‘Construction Service’ –value of ‘land’ shall be deemed to be 1/3rd of total amount including the amount charged for transfer of land.
Value of land is deemed to be 1/3rd of total amount – which results in levy of GST on land value over and above 1/3rd.
No legislative competence to levy tax on immovable property transactions under Article 246A. Hence, violative of Article 265 of the Constitution
Entries in Entry 3 of Notification read with Entry 5(b) of Schedule II to the CGST Act, 2017 could be challenged as being unconstitutional lacking legislative competence and violative of Article 246A and 265 of the Constitution 51<br>
slide52. Issues w.r.t. Immovable Property Issue: Para 2 of Notification no. 11/2017-CT(R) made applicable to Sl.no. 3 (Construction Services) is illegal & ultra vires S.15
Paragraph 2 of Notification deeming the value of land at one-third of the total amount charged is ultra-vires S.15 of CGST Act – Illegal and Ultra-virus
Alternatively, Paragraph 2 should be read down so as to allow valuation of land on the basis of actual amount received and not at deemed value of one-third of total amount charged.
Hence, Para 2 to be ‘read down’ as not being mandatory and the petitioner is allowed to value the land on the basis of actual amounts received towards the transfer of land / undivided share in the land.
Wipro Ltd. Vs. Asst Collector of Cus & ors [2015 (319) ELT 177 (S.C.)] Munjaal Manishbhai Bhatt vs UOI [2022 (62) GSTL 262 (Guj)], Avigna Properties Pvt Ltd vs State Tax Officer [2023 (7) Centax 203 (Mad)] 52<br>
slide53. Issue w.r.t. reimbursement of GST on account of enhancement of rate 53<br>
slide54. Mas Construction vs Hubballi Dharwad Smart City Ltd 2022 (57) GSTL 230 (Kar) ISSUE: Works Contract awarded in GST regime stipulating payment of Sales Tax/VAT component @ 5% in respect of materials whereas contractor deposited applicable GST
HELD: Contract having been entered into after coming into force of GST and in view of aforesaid clarification which has been approved by Finance Department, contractee required to pay GST after adjusting Sales Tax/VAT referred to in said contract particularly when tax is a statutory liability and contractor would not retain same as profit
Writ Appeal filed before Divisional Bench of the Hon’ble High Court of Karnataka [WA 1427/2021] – interim order dated 07.03.2023 granted 54<br>
slide55. Sri Chandrashekariah Vs State of Karnataka, WP No. 9721 of 2019 ISSUE: Reimbursement of differential tax amount arising out of change in tax regime from VAT to GST where:
“works contract” were entered prior to 01.07.2017 during KVAT regime and works are completed pre-GST but payments are made post-GST or
Contracts entered prior to 01.07.2017 but partly executed pre-GST and balance work executed post-GST or
Contracts for which tenders were invited during KVAT regime and finalised after 01.07.2017 under GST regime
contracts which were invited during KVAT regime under old schedule of rates (SR) but finalised under GST regime 55<br>
slide56. Sri Chandrashekariah Vs State of Karnataka, WP No. 9721 of 2019 HELD: The Hon’ble Court issued the following directions:
Payments received under pre-GST are to be assessed under KVAT
Calculate the balance works to be completed after 01.07.2017
Derive the rate of materials, KVAT items required or used to complete the balance works.
Deduct the "KVAT" amount from those materials and the service tax, if applicable.
Add the applicable "GST" on those items. 56<br>
slide57. Sri Chandrashekariah Vs State of Karnataka, WP No. 9721 of 2019 HELD: The Hon’ble Court issued the following directions:
Input Credit on the materials is to be arrived at and be set off as against the output GST, for those assessed under regular VAT.
Further, the “tax difference” should be calculated on such balance works executed or to be executed after 01.07.2017 separately.
Based on the above calculation, concerned department/authority has to decide whether agreement needs to be changed or not.
Supplementary agreement may be signed with the revised conditions 57<br>
slide58. Back Street Engineers Co-operative Society Ltd vs State of WB [2023 (156) taxmann.com 454 (Cal)] ISSUE: Petitioners were awarded contracts by Government contractees prior to GST implementation but same were executed in GST era - Petitioners received payments from Government contractees without GST
HELD: Government contractees were liable to bear additional tax liability for execution of subsisting Government contracts awarded during pre-GST regime or in post-GST regime without updating Schedule of Rates (SoR) incorporating applicable GST while preparing bill for payment.
Petitioners were to be directed to file representations before Additional Chief Secretary, Finance Department, Government of West Bengal – who shall take final decision 58<br>
slide59. Taxability of Intermediary Services 59<br>
slide60. DHARMENDRA M JANI [2023 (5) CENTAX 201 (BOM)] Issue: Constitutional validity of Section 13(8)(b) of the IGST Act, 2017 which prescribes place of supply of intermediary services to be location of supplier of services
Held: Split View – Matter referred to Third Judge
View expressed by Justice Ujjal Bhuyan
Unconstitutional - Runs completely contrary to very fundamental principle of destination-based consumption tax
Offends Articles 245, 246A, 269A and 286(1)(b) of Constitution
Beyond charging section and creates an artificial deeming fiction
View Expressed by Justice Abhay Ahuja
Constitutional – Prevents the escape of revenue
Supply under consideration is an inter-state supply of service. 60<br>
slide61. DHARMENDRA M JANI [2023 (5) CENTAX 201 (BOM)] – referee judge decision Held: Before the Referee Judge
By Section 13(8)(b) - Place of supply shall be (is deemed to be) the location of supplier of services.
Legal consequence by such deeming combination - A supply of service, of the nature of intermediary services - in the nature of "export of service" defined under Section 2(6) of the IGST Act - becomes an "intra-State" sale falling under the charging provision (Section 9) of the CGST Act and the MGST Act.
Neither CGST, nor SGST recognize tax on export of services - governed within domain of IGST Act
Thus, fiction which is created by section 13(8)(b) would be required to be confined only to provisions of IGST Act, as there is no scope for fiction travelling beyond provisions of IGST Act to CGST and MGST Acts. 61<br>
slide62. GENPACT INDIA (P) LTD VS UOI [2022 (144) TAXMANN.COM (P&H)] Issue: Petitioner - Business Process Outsourcing (BPO) Services entered into a Master Services Sub-Contracting with Genpact International Incorporated (GI). Whether the petitioner qualifies as an intermediary and thus not eligible for refund?
Held: Petitioner was providing services which had been sub-contracted to it by GI
Petitioner had no direct contract with customers of GI. Nothing on record to show that petitioner was liasoning or acting as an "intermediary
Respondent-department had erred in holding petitioner to be in a principal-agent relationship with GI.
Reliance placed on Circular 159/15/2021-GST dated 20.09.2021 – Minimum three parties, Does not supply on his own account – Principal to Principal basis 62<br>
slide63. E&Y LTD VS ADDT COMM, CGST APPEAL-II [2023 (4) CENTAX 440 (DEL)] Issue: Petitioner - provided various professional services to overseas EY Entities in terms of the agreements. Whether the petitioner qualifies as an intermediary and thus not eligible for refund?
Held: Petitioner was providing services to overseas entity and not involved in arranging or facilitating services.
The last limb of section 2(13) of the IGST Act reads as "but does not include a person who supplies such goods or services or both or securities on his own account" - Does not control the definition - Merely restricts the main definition.
There may be services, which may entail outsourcing some constituent part to a third party. But that would not be construed as intermediary services, if the service provider provides services to the recipient on his own account. 63<br>
slide64. OHMI INDUSTRIES ASIA P LTD VS ASST COMM. OF CGST [2023 (6) CENTAX 163 (DEL)] Issue: Petitioner - Petitioner was rendering market research services directly to OHMI, Japan, its overseas entity. Whether the petitioner qualifies as an intermediary and thus not eligible for refund?
Held:
No allegation that it had arranged supply of such services from a third party.
Petitioner was not acting as intermediary in respect of market research services. 64<br>
slide65. BOKS BUSINESS SERVICES VS Commnr of CGST [2023 10 Centax 44 (Del)] ISSUE: ITC claim filed by Petitioner on zero rated supply was rejected on the ground that assessee was as an intermediary and has not made any export of services.
Petitioner providing bookkeeping, payroll, and accounting services through the use of cloud technology to its affiliated entity (incorporated in UK).
HELD: Petitioner is neither facilitating the provision of services by a third entity nor acting as a middleman for procuring services for its affiliate. Petitioner is providing services on principal-to-principal basis.
Reference made to: M/s Ernst And Young Limited v. Additional Commissioner, CGST 2023:DHC:2116-DB and M/s Cube Highways and Transportation Assets Advisor Private Limited v. Assistant Commissioner CGST Division & Ors 2023:DHC:5822-DB.
Directed to process the refund claims of the Petitioner. 65<br>
slide66. Levy of GST on mining lease & royalty 66<br>
slide67. The levy of service tax on the grant of mining lease by a Government against payment of royalty was a subject matter of litigation under Erstwhile Service Tax Regime:
Udaipur Chambers of Commerce and Industry v. UOI 2018 (8) G.S.T.L. 170 (Raj.) and Stay granted in Udaipur Chambers of Commerce and Industry v. UOI 2018 (10) G.S.T.L. J167 (S.C.)].
Gujmin Industry Association vs UOI 2019 (20) G.S.T.L. 11 (Guj.).
The issue that is revolving around the payment of royalty and the tax thereon is that whether payment of royalty paid towards extraction of minerals is in the nature of ‘tax’ and cannot be considered as consideration for service. [See: India Cement Ltd & Others vs State of Tamil Nadu & Others (1990) 1 SCC 12]. This issue is pending before Nine Bench in the case of Mineral Area Development Authority & Others vs Steel Authority of India & Others (2011) 4 SCC 450. 67<br>
slide68. Taxability of secondment contracts 68<br>
slide69. C.C., C.E. & ST Bangalore vs Northern Operating Systems (P) Ltd [2022 (138) taxmann.com 359 (SC)] ISSUE: The overseas entity has a pool of highly skilled employees which are seconded to the assessee. While the employees were under the control of the assessee and worked under its direction, the remuneration was paid by the overseas employer. The overseas entity raised a debit note on the assessee to recover the remuneration.
Whether the overseas entity provided manpower services to the assessee? 69<br>
slide70. C.C., C.E. & ST Bangalore vs Northern Operating Systems (P) Ltd [2022 (138) taxmann.com 359 (SC)] HELD: It was observed that there is no single determinative factor while deciding whether an arrangement is a contract for service or contract of service and applied the test of substance over form
It was opined that the arrangement is a quid pro quo, whereby the assessee has the benefit of experts for a limited period. It was held that the overseas entity was providing manpower recruitment and supply services to the assessee. 70<br>
slide71. Taxability of secondment contracts Based on the decision of the Apex Court, department has issued numerous notices in the GST regime, demanding tax under reverse charge mechanism on secondment of employees.
Points for consideration
Whether employment contracts can be brought to levy of GST ? [Section 7 read with Schedule III]
Aspect of dual employment
Whether any consideration flows from Indian entity to overseas entity? 71<br>
slide72. Taxability of secondment contracts Interim Orders:
Alstom Transport India Ltd vs The State of Karnataka [WP No. 23644/2023]: The petitioner has employed certain expatriates and is paying salary in the Indian currency, and because these employees have maintained their lien with the corresponding overseas company, social security cost is paid. The decision in the case of Northern Operating Systems Pvt. Ltd., is in the peculiarities of that particular case and cannot be applied in distinguishable circumstances. [Reference made in Mitsubishi Electric India Pvt Ltd vs UOI (CWP-25351-2023 P&H)]
United Breweries Ltd vs The Additional Commissioner of Central Tax [WP No. 22959/2023]
Bhoruka Extrusions Pvt Ltd vs ACCT [WP No. 25943/2023 Kar HC]
Biesse India Pvt Ltd vs ACCT [ WP No. 26812/2023 Kar HC] 72<br>
slide73. Taxability of secondment contracts Instruction No. 5/2023-GST dated 13.12.2023
A careful reading of the NOS judgment indicates that Hon’ble Supreme Court’s emphasis is on a nuanced examination based on the unique characteristics of each specific arrangement, rather than relying on any singular test.
The decision of the Hon’ble Supreme Court in the NOS judgment should not be applied mechanically in all the cases. Investigation in each case requires a careful consideration of its distinct factual matrix, including the terms of contract between overseas company and Indian entity, to determine taxability or its extent under GST and applicability of the principles laid down by the Hon’ble Supreme Court’s judgment in NOS case. 73<br>
slide74. Validity of show cause notices issued under Section 73 of CGST Act, 2017? 74<br>
slide75. Validity of SCN issued under Section 73 Section 73(2) - Issuance of show cause notice at least 3 months prior to the time limit specified under sub-section 10 for issuance of order
Section 73(10) – Pass order within three years from the due date for furnishing of annual return for the financial year to which the tax not paid or short paid or input tax credit wrongly availed or utilised relates to or within three years from the date of erroneous refund.
Thus, show cause notice is to be issued within 33 months 75<br>
slide76. Validity of SCN issued under Section 73 76<br>
slide77. Validity of SCN issued under Section 73 Section 168A empowers Government to issue Notifications to extend time limit specified under CGST Act, 2017, which cannot be complied due to force majeure.
Expression “force majeure” means a case of war, epidemic, flood, drought, fire, cyclone, earthquake or any other calamity caused by nature or otherwise affecting the implementation of any of the provisions of this Act. 77<br>
slide78. Validity of SCN issued under Section 73 In exercise of powers of Section 168A
Notification No. 35/2020-CT dated 03.04.2020 and Notification No. 14/2021-CT dated 01.05.2021 were issued from time to time, so as to extend the time limit for issuing show cause notice and passing orders, in view of COVID pandemic
Subsequently, Notification No. 13/2022-CT dated 05.07.2022 was issued to extend the time limit for passing order u/s 73 for FY 2017-18 to 30.9.2023 78<br>
slide79. Validity of SCN issued under Section 73 In exercise of powers of Section 168A
Further, Notification No. 9/2023-CT dated 31.03.2023 was issued to extend the time limit for passing orders u/s 73 as under: 79<br>
slide80. Validity of SCN issued under Section 73 Issues for consideration
Reasons for issuing Notification in 2022 and 2023 under Section 168A, involving force majeure event?
Effect of Supreme Court order for extending limitation period dated 09.05.2022, which sough to exclude the period from 15.03.2020 till 28.02.2022 for the purposes of limitation.
SRSS Agro Pvt Ltd vs UOI [SCA No. 19720/2023]: It is the case of the petitioner that the notification dated 31.03.2023 extending the time limit specified under Section 73 of the Act by virtue of the powers under Section 168A of the Act is unjustified as extension has to be for special circumstances. Notice issued to respondents 80<br>
slide81. DRC-01A: Whether Mandatory or Optional? 81<br>
slide82. Agrometal Vendibles Pvt. Ltd. vs State of Gujarat 2022 (63) G.S.T.L. 212 (Guj.): Issue: This case relates to scrutiny of returns and inconsistencies noticed in taxpayer’s records for year 2019-20. The writ-applicant had received an intimation for tax ascertained as payable, through DRC-01 dated 14-03-2022, instead of Form DRC -01A.
Held: At the stage of an intimation under sub-section (5) of Section 74 in the Form GST DRC-01A, it is Rule 142(1A) which is applicable. There is a vast difference between Rule 142(1)(a) and Rule 142(1A) of the Rules.
Therefore, w.e.f. 15.10.2020, if the department deems fit to issue any intimation of tax ascertained as being payable under sub-section (5) of Section 74 in accordance with the Rule 142(1A) of the Rules, it shall issue notice in the Form GST DRC-01A. 82<br>
slide83. Gulati Enterprises Versus C.B.I. & C. – 2023 (68) G.S.T.L. 237 (Del.) Issue: Whether a pre-show cause consultation notice was required to be mandatorily issued, and is there any non-adherence to Rule 142(1A) in the present case?
Held: The Court held that with effect from 15-10-2020 i.e., after the impugned show cause notice was issued, Rule 142(1A) has undergone a change, inasmuch as the word 'shall' has been replaced with 'may'. The impact of the amendment was not considered, as admittedly the show cause notice was issued prior to 15-10-2020 i.e., on 21-5-2020
Therefore, having regard to the position which obtained prior to 15-10-2020, it was held that pre-show cause notice consultation was mandatory under the unamended Rule 142(1A). 83<br>
slide84. New Morning Star Travels Versus Deputy Commissioner [(2023) 12 Centax 198 (AP) Issue: The assessee was issued DRC-01A intimation by a GST officer for period from July 2017 to 2018-19. Subsequently, the case was transferred to another officer who issued show cause notice under DRC-01 under Section 74(1) for period from 01-07-2017 to 31-03-2021, but no intimation was issued as DRC-01A under Rule 142(1A) for the period after 2018-19
Held: Prior to the amendment - the employment of the word 'shall' in Rule 142(1A) would indicate that the officer shall necessarily follow the procedure prescribed under Rule 142(1A) of the Act, meaning thereby, an intimation of tax shall be issued in terms of Rule 142(1A) at first and if there is no response from the tax payer, then he can issue a show cause notice under section 74(1) of CGST/APGST Act 84<br>
slide85. New Morning Star Travels Versus Deputy Commissioner [(2023) 12 Centax 198 (AP) Held: Rule 142(1A) of CGST Rules, 2017 has been amended by virtue of notification No. 79/2020-CT dt.15-10-2020 and by virtue of the said amendment, the words 'proper officer shall' has been substituted with the words 'proper officer may' as appearing in Rule142(1A). Thus, post amendment, the issuance of intimation under Rule142(1A) is not mandatory, but discretionary on the part of the assessing authority.
Since the tax period related to 1-7-2017 to 31-3-2021 which covers the pre and post amended period of Rule 142(1A), the Respondent ought to have issued tax intimation to the Petitioner under Rule 142(1A) 85<br>
slide86. Recovery of refund without challenging the order 86<br>
slide87. Recovery of refund without challenging the order Ganesh Ores Pvt Ltd vs State of Orissa [2022 (59) GSTL 258 (Ori)] [SLP dismissed – 2022 (59) GSTL 257 (SC)] - There is no restriction that the appeal needs to be filed before issue of SCN in case of the erroneous refunds.
CCE Vs Flock India [2000 (120) ELT 285 (SC)] -where an adjudicating authority has passed an order which is appealable under the statute and the party aggrieved did not choose to exercise the statutory right of filing an appeal it is not open to the party to question the correctness of the order of the adjudicating authority subsequently by filing a claim for refund on the ground that the adjudicating authority had committed an error in passing his order. 87<br>
slide88. Recovery of refund without challenging the order Priya Blue Industries Vs CC (preventive) [2004 (172) ELT 145 (SC)] - A refund claim contrary to an assessment order is not maintainable without the order of assessment having been modified in appeal or reviewed under Section 28 of Customs Act, 1962
ITC Ltd. Vs. CCE [2019-TIOL-481-SC-LB] - Bill of entry being an assessment order, no refund could be claimed unless the said assessment is challenged.
Jairath International Vs UOI [2019-TIOL-2459-HC-P&H-CUS] - Shipping bill is an assessment order and could be challenged under the appeal provisions. Therefore, unless the same is challenged, the shipping bill cannot be modified by way of issue of show cause notice by any authority 88<br>
slide89. Issues on Provisional Attachment 89<br>
slide90. Provisional Attachment Different kinds of issues under Section 83 are:
In many cases, the forming of ‘opinion’ by the proper officer has not been established for provisional attachment under section 83 [See: Radha Krishan Industries v. State of Himachal Pradesh and Others - 2021-TIOL-179-SC-GST]
The order of provisional attachment continues to exist even after one year has elapsed. The Act permits the proper officer to provisionally attach the properties only for one year [See: M/s. Krishna Fashion vs UOI 2022-TIOL-108-HC-DEL-GST] 90<br>
slide91. Provisional Attachment Different kinds of issues under Section 83 are:
The cash credit accounts of the assessees are getting provisionally attached even though in various decisions it is settled that the cash credit accounts cannot be attached for non-existence of debtor-creditor relationship [See: Manish Scrap Traders vs Principal Commissioner 2022-TIOL-54-HC-AHM-GST]
Power to order a provisional attachment of the property of a taxable person including a bank account is draconian in nature [See: Radha Krishan Industries v. State of Himachal Pradesh and Others - 2021-TIOL-179-SC-GST] 91<br>
slide92. Provisional Attachment The provisional attachment under section 83 is permissible only when proceedings under section 62 or 63 or 64 or 67 or 73 or 74 are pending [See: S.S. Offshore (P.) Ltd. vs UOI [2021] 131 taxmann.com 162 (Bombay); Bhavesh Kiritbhai Kalani vs UOI [2021] 127 taxmann.com 199 (Gujarat)]
The bank account of the director of the company was provisionally attached. The ground was that the said company was availing ITC against fake/ineligible invoices. The bank attachment is permissible only in respect of taxable person (who is registered or liable to register) and not against any other person [See: Roshni Sana Jaiswal vs Commnr of Central Taxes [2021] 128 taxmann.com 357 (Delhi)] 92<br>
slide93. Thank You 93<br>