
Corporate Law Amendments & its impact on Statutory
AS
Published · 34 slides · 0 views

1 / 1

Description
Corporate Law Amendments its impact on Statutory Audit Presentation by Gaurav Pingle, Practising Company Secretary Presentation at Karnataka State Chartered Accountants Association Tuesday, 20 April 2021 1 Presentation by CS Gaurav Pingle
Related Topics
Share
Embed code
Download this presentation From Below
"Corporate Law Amendments & its impact on Statutory" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Corporate Law Amendments & its impact on Statutory Audit
Presentation by Gaurav Pingle,
Practising Company Secretary Presentation at Karnataka State Chartered Accountants Association Tuesday, 20 April 2021 1 Presentation by CS Gaurav Pingle<br>
02
Agenda to today’s presentation Amendments to CSR provisions by Cos. (Amendment) Act, 2020
Remuneration to independent directors of Company
Virtual Meetings under companies act, 2013
Key Highlights of Companies (Amendment) Act, 2020
Compliance Calendar Tuesday, 20 April 2021 2 Presentation by CS Gaurav Pingle<br>
Remuneration to independent directors of Company
Virtual Meetings under companies act, 2013
Key Highlights of Companies (Amendment) Act, 2020
Compliance Calendar Tuesday, 20 April 2021 2 Presentation by CS Gaurav Pingle<br>
03
Amendments to csr provisions by companies (amendment) act, 2020 PART I OF THE PRESENTATION Tuesday, 20 April 2021 3 Presentation by CS Gaurav Pingle<br>
04
Meaning of ‘CSR’ – now defined in detail CSR means activities undertaken by Co. in pursuance of its statutory obligation (u/s 135 of the Act) in accordance with the provisions contained in CSR rules, but shall not include the following:
Activities undertaken in pursuance of normal course of business of the company. However, any company engaged in research and development activity of new vaccine, drugs and medical devices in their normal course of business may undertake research and development activity of new vaccine, drugs and medical devices related to COVID-19 for FYs 2020-21, 2021-22, 2022-23 subject to 2 conditions
Any activity undertaken by Co. outside India except for training of Indian sports personnel representing any State or Union territory at national level or India at international level; Tuesday, 20 April 2021 4 Presentation by CS Gaurav Pingle<br>
Activities undertaken in pursuance of normal course of business of the company. However, any company engaged in research and development activity of new vaccine, drugs and medical devices in their normal course of business may undertake research and development activity of new vaccine, drugs and medical devices related to COVID-19 for FYs 2020-21, 2021-22, 2022-23 subject to 2 conditions
Any activity undertaken by Co. outside India except for training of Indian sports personnel representing any State or Union territory at national level or India at international level; Tuesday, 20 April 2021 4 Presentation by CS Gaurav Pingle<br>
05
… CSR means activities undertaken u/s 135 of Cos. Act, shall not include the following: Contribution of any amount directly or indirectly to any political party u/s 182 of Act;
Activities benefitting employees of the Co.;
Activities supported by the Cos. on sponsorship basis for deriving marketing benefits for its products or services;
Activities carried out for fulfilment of any other statutory obligations under any law in force in India. Tuesday, 20 April 2021 5 Presentation by CS Gaurav Pingle<br>
Activities benefitting employees of the Co.;
Activities supported by the Cos. on sponsorship basis for deriving marketing benefits for its products or services;
Activities carried out for fulfilment of any other statutory obligations under any law in force in India. Tuesday, 20 April 2021 5 Presentation by CS Gaurav Pingle<br>
06
CSR Implementation Board shall ensure that CSR activities are undertaken by Co. itself or through:
Co. established u/s 8 of Cos. Act, or a registered public trust or a registered society, registered u/s 12A and 80 G of the Income Tax Act, 1961, established by the Co., either singly or along with any other company, or
Co. established u/s 8 of Cos. Act or a registered trust or a registered society, established by the Central Government or State Government; or
Any entity established under an Act of Parliament or a State legislature; or
Company established u/s 8 of Cos. Act, or Regd. public trust or Regd. Society, Regd. u/s 12A and 80G of the Income Tax Act, 1961, and having an established track record of at least 3 years in undertaking similar activities. Tuesday, 20 April 2021 6 Presentation by CS Gaurav Pingle<br>
Co. established u/s 8 of Cos. Act, or a registered public trust or a registered society, registered u/s 12A and 80 G of the Income Tax Act, 1961, established by the Co., either singly or along with any other company, or
Co. established u/s 8 of Cos. Act or a registered trust or a registered society, established by the Central Government or State Government; or
Any entity established under an Act of Parliament or a State legislature; or
Company established u/s 8 of Cos. Act, or Regd. public trust or Regd. Society, Regd. u/s 12A and 80G of the Income Tax Act, 1961, and having an established track record of at least 3 years in undertaking similar activities. Tuesday, 20 April 2021 6 Presentation by CS Gaurav Pingle<br>
07
… CSR Implementation Every entity who intends to undertake any CSR activity, shall register itself with Central Govt. by filing e-Form CSR-1 electronically with RoC, w.e.f. April 1 2021 (Certification of practicing CA, CS, CWA).
On the submission of e-Form CSR-1 on the portal, a unique CSR Registration Number will be generated. Tuesday, 20 April 2021 7 Presentation by CS Gaurav Pingle<br>
On the submission of e-Form CSR-1 on the portal, a unique CSR Registration Number will be generated. Tuesday, 20 April 2021 7 Presentation by CS Gaurav Pingle<br>
08
Other imp. Aspects of csr amendments Co. may engage international organisations for designing, monitoring and evaluation of the CSR projects or programmes as per its CSR policy as well as for capacity building of their own personnel for CSR;
Co. may also collaborate with other companies for undertaking projects or programmes or CSR activities in such a manner that the CSR committees of respective companies are in a position to report separately on such projects or programmes in accordance with these rules;
Board of Co. shall satisfy itself that funds so disbursed have been utilised for the purposes and in manner as approved by it & CFO or person responsible for financial management shall certify to the effect. Tuesday, 20 April 2021 8 Presentation by CS Gaurav Pingle<br>
Co. may also collaborate with other companies for undertaking projects or programmes or CSR activities in such a manner that the CSR committees of respective companies are in a position to report separately on such projects or programmes in accordance with these rules;
Board of Co. shall satisfy itself that funds so disbursed have been utilised for the purposes and in manner as approved by it & CFO or person responsible for financial management shall certify to the effect. Tuesday, 20 April 2021 8 Presentation by CS Gaurav Pingle<br>
09
‘Administrative overheads’ under CSR provisions ‘Administrative overheads’ means the expenses incurred by the Co. for ‘general management and administration’ of CSR functions in the Co. but shall not include expenses directly incurred for designing, implementation, monitoring, and evaluation of a particular CSR project or programme.
BoD shall ensure that administrative overheads shall not exceed 5% of total CSR expenditure of the company for FY. Tuesday, 20 April 2021 9 Presentation by CS Gaurav Pingle<br>
BoD shall ensure that administrative overheads shall not exceed 5% of total CSR expenditure of the company for FY. Tuesday, 20 April 2021 9 Presentation by CS Gaurav Pingle<br>
10
Ongoing Project Ongoing Project means multi-year project undertaken by Co. in fulfilment of its CSR obligation having timelines not exceeding 3 years excluding the FY in which it was commenced. It shall include such project that was initially not approved as a multi-year project but whose duration has been extended beyond 1 year by the board based on reasonable justification.
In case of ongoing project, the Board of a Company shall monitor the implementation of the project with reference to the approved time lines and year-wise allocation and shall be competent to make modifications, if any, for smooth implementation of the project within the overall permissible time period. Tuesday, 20 April 2021 10 Presentation by CS Gaurav Pingle<br>
In case of ongoing project, the Board of a Company shall monitor the implementation of the project with reference to the approved time lines and year-wise allocation and shall be competent to make modifications, if any, for smooth implementation of the project within the overall permissible time period. Tuesday, 20 April 2021 10 Presentation by CS Gaurav Pingle<br>
11
CSR spending Board of every Co., shall ensure that the Co. spends, in every FY, at least 2% of average net profits of Co. made during 3 immediately preceding FYs, OR where Co. has not completed the period of 3 FYs since its incorporation, during such immediately preceding FYs, in pursuance of its CSR Policy.
Co. shall give preference to the local area and areas around it where it operates, for spending the amount earmarked for CSR activities.
If the Co. fails to spend such amount:
Board shall, in its report, specify the reasons for not spending the amount AND
Unless unspent amount relates to any Ongoing Project, transfer such unspent amount to a Fund specified in Schedule VII, within 6 months of expiry of FY. Tuesday, 20 April 2021 11 Presentation by CS Gaurav Pingle<br>
Co. shall give preference to the local area and areas around it where it operates, for spending the amount earmarked for CSR activities.
If the Co. fails to spend such amount:
Board shall, in its report, specify the reasons for not spending the amount AND
Unless unspent amount relates to any Ongoing Project, transfer such unspent amount to a Fund specified in Schedule VII, within 6 months of expiry of FY. Tuesday, 20 April 2021 11 Presentation by CS Gaurav Pingle<br>
12
… CSR Spending Where a Co. spends an amount in excess of requirement provided u/s 135, such excess amount may be set off against the requirement to spend up to immediate succeeding 3 FYs subject to the conditions that:
Excess amount available for set off shall not include surplus arising out of CSR activities, if any.
Board of directors shall pass a resolution to that effect. Tuesday, 20 April 2021 12 Presentation by CS Gaurav Pingle<br>
Excess amount available for set off shall not include surplus arising out of CSR activities, if any.
Board of directors shall pass a resolution to that effect. Tuesday, 20 April 2021 12 Presentation by CS Gaurav Pingle<br>
13
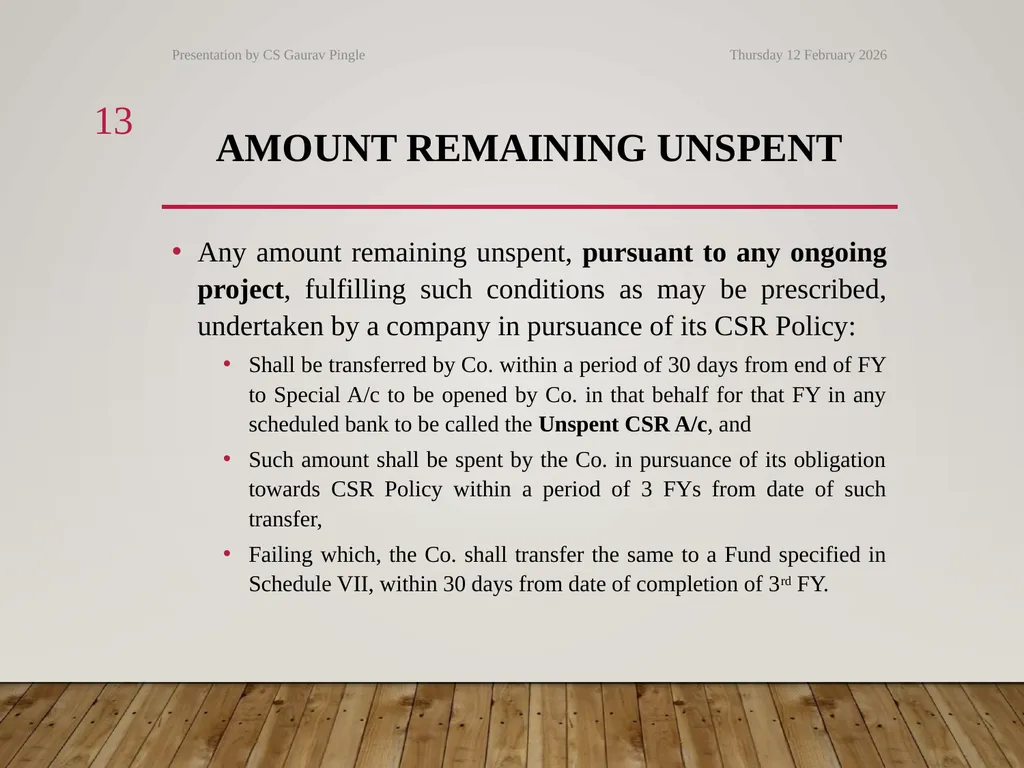
Amount Remaining Unspent Any amount remaining unspent, pursuant to any ongoing project, fulfilling such conditions as may be prescribed, undertaken by a company in pursuance of its CSR Policy:
Shall be transferred by Co. within a period of 30 days from end of FY to Special A/c to be opened by Co. in that behalf for that FY in any scheduled bank to be called the Unspent CSR A/c, and
Such amount shall be spent by the Co. in pursuance of its obligation towards CSR Policy within a period of 3 FYs from date of such transfer,
Failing which, the Co. shall transfer the same to a Fund specified in Schedule VII, within 30 days from date of completion of 3rd FY. Tuesday, 20 April 2021 13 Presentation by CS Gaurav Pingle<br>
Shall be transferred by Co. within a period of 30 days from end of FY to Special A/c to be opened by Co. in that behalf for that FY in any scheduled bank to be called the Unspent CSR A/c, and
Such amount shall be spent by the Co. in pursuance of its obligation towards CSR Policy within a period of 3 FYs from date of such transfer,
Failing which, the Co. shall transfer the same to a Fund specified in Schedule VII, within 30 days from date of completion of 3rd FY. Tuesday, 20 April 2021 13 Presentation by CS Gaurav Pingle<br>
14
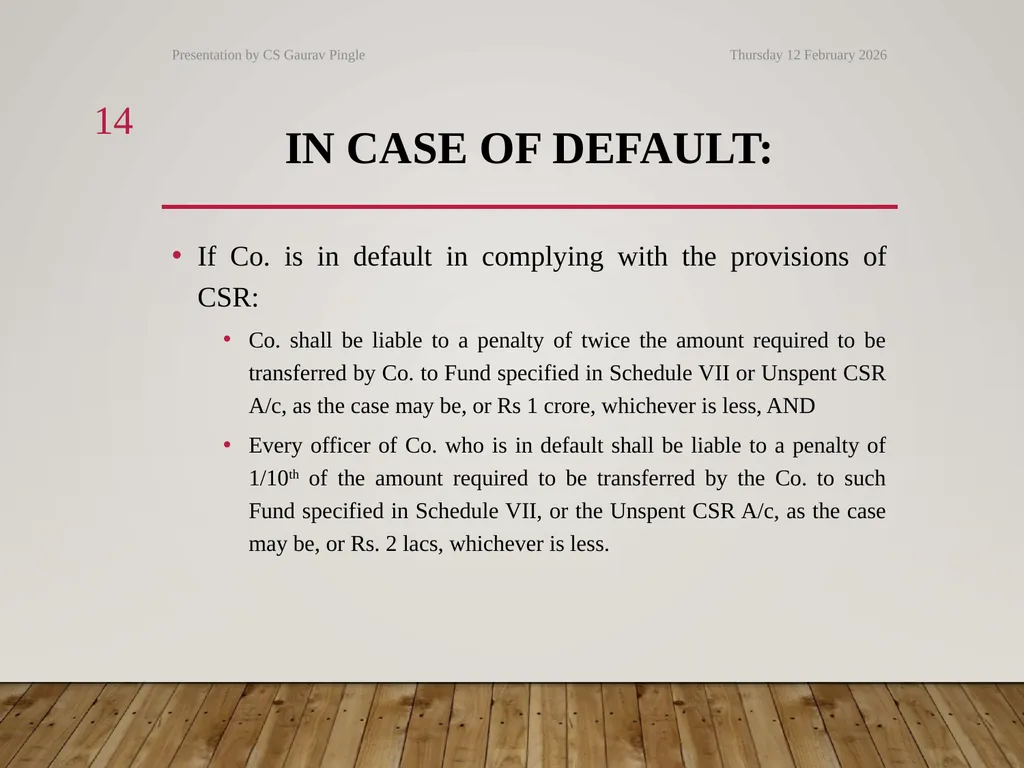
In case of default: If Co. is in default in complying with the provisions of CSR:
Co. shall be liable to a penalty of twice the amount required to be transferred by Co. to Fund specified in Schedule VII or Unspent CSR A/c, as the case may be, or Rs 1 crore, whichever is less, AND
Every officer of Co. who is in default shall be liable to a penalty of 1/10th of the amount required to be transferred by the Co. to such Fund specified in Schedule VII, or the Unspent CSR A/c, as the case may be, or Rs. 2 lacs, whichever is less. Tuesday, 20 April 2021 14 Presentation by CS Gaurav Pingle<br>
Co. shall be liable to a penalty of twice the amount required to be transferred by Co. to Fund specified in Schedule VII or Unspent CSR A/c, as the case may be, or Rs 1 crore, whichever is less, AND
Every officer of Co. who is in default shall be liable to a penalty of 1/10th of the amount required to be transferred by the Co. to such Fund specified in Schedule VII, or the Unspent CSR A/c, as the case may be, or Rs. 2 lacs, whichever is less. Tuesday, 20 April 2021 14 Presentation by CS Gaurav Pingle<br>
15
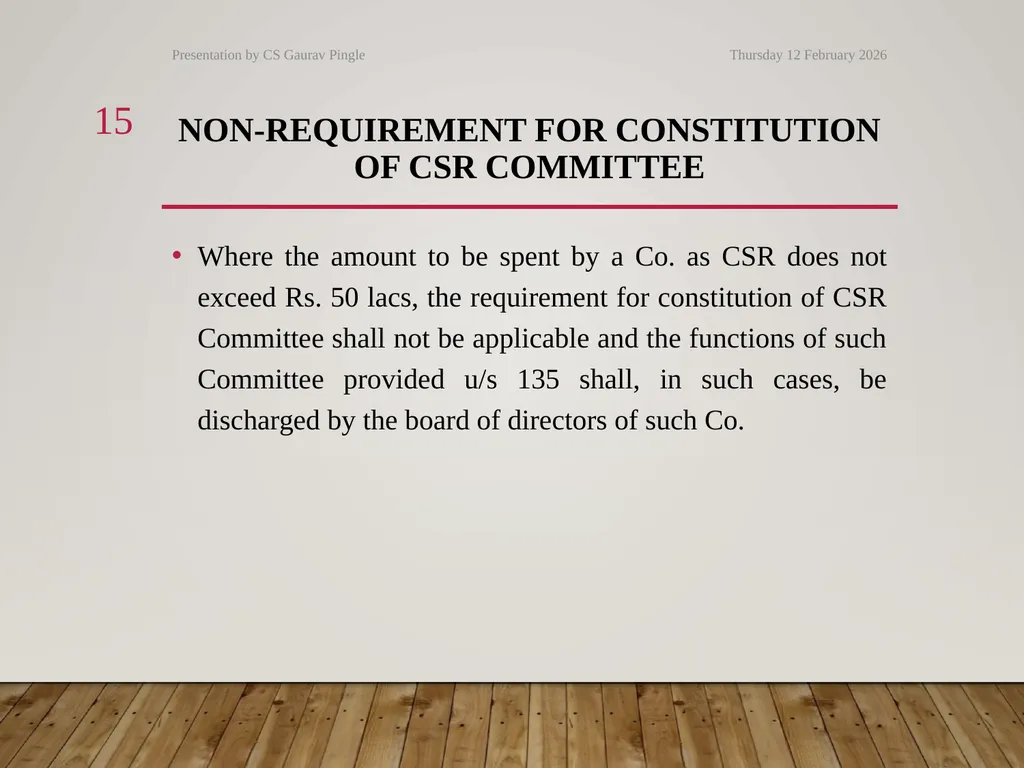
Non-requirement for constitution of CSR Committee Where the amount to be spent by a Co. as CSR does not exceed Rs. 50 lacs, the requirement for constitution of CSR Committee shall not be applicable and the functions of such Committee provided u/s 135 shall, in such cases, be discharged by the board of directors of such Co. Tuesday, 20 April 2021 15 Presentation by CS Gaurav Pingle<br>
16
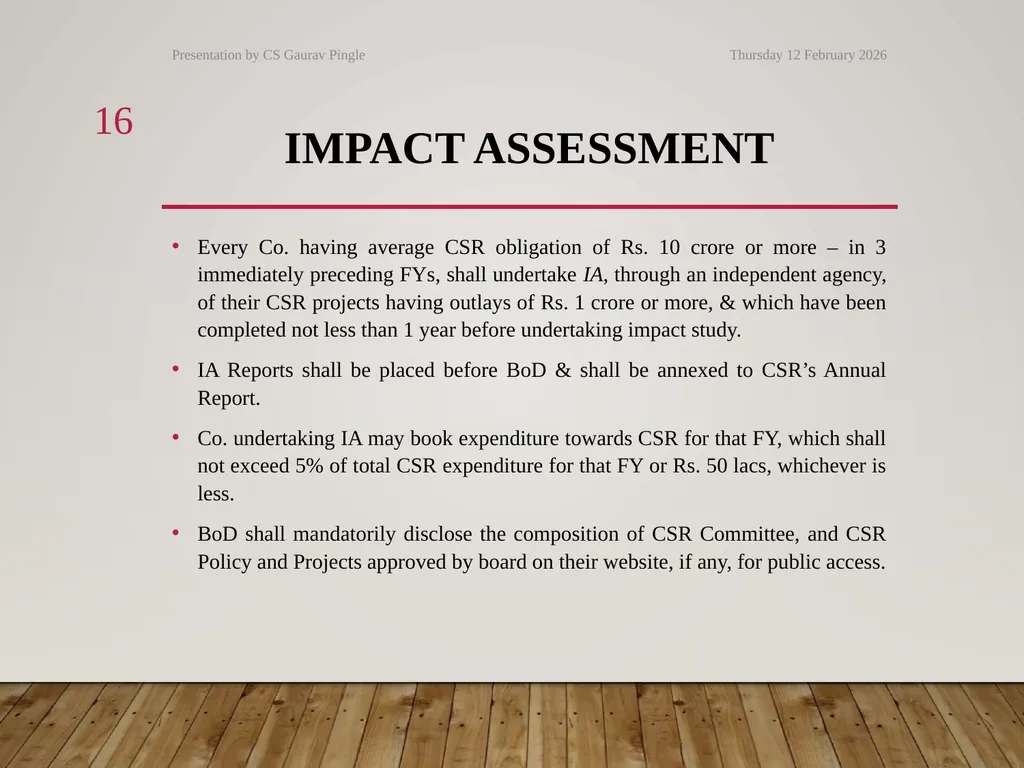
Impact assessment Every Co. having average CSR obligation of Rs. 10 crore or more – in 3 immediately preceding FYs, shall undertake IA, through an independent agency, of their CSR projects having outlays of Rs. 1 crore or more, & which have been completed not less than 1 year before undertaking impact study.
IA Reports shall be placed before BoD & shall be annexed to CSR’s Annual Report.
Co. undertaking IA may book expenditure towards CSR for that FY, which shall not exceed 5% of total CSR expenditure for that FY or Rs. 50 lacs, whichever is less.
BoD shall mandatorily disclose the composition of CSR Committee, and CSR Policy and Projects approved by board on their website, if any, for public access. Tuesday, 20 April 2021 16 Presentation by CS Gaurav Pingle<br>
IA Reports shall be placed before BoD & shall be annexed to CSR’s Annual Report.
Co. undertaking IA may book expenditure towards CSR for that FY, which shall not exceed 5% of total CSR expenditure for that FY or Rs. 50 lacs, whichever is less.
BoD shall mandatorily disclose the composition of CSR Committee, and CSR Policy and Projects approved by board on their website, if any, for public access. Tuesday, 20 April 2021 16 Presentation by CS Gaurav Pingle<br>
17
Remuneration to independent directors PART II OF THE PRESENTATION Tuesday, 20 April 2021 17 Presentation by CS Gaurav Pingle<br>
18
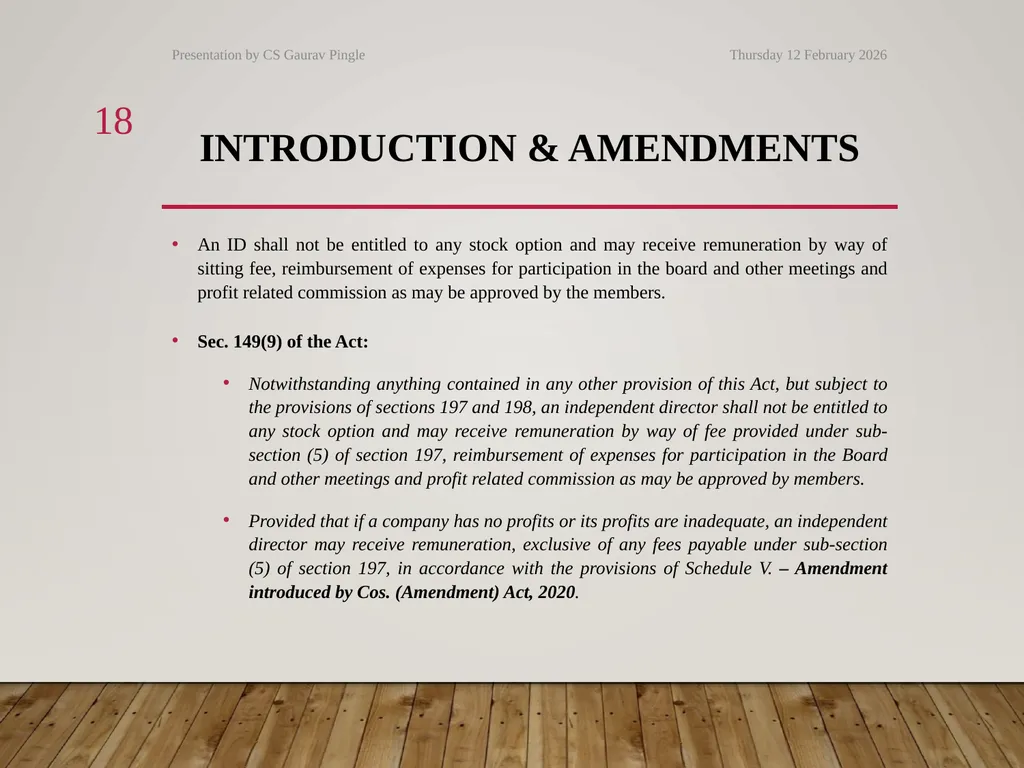
Introduction & amendments An ID shall not be entitled to any stock option and may receive remuneration by way of sitting fee, reimbursement of expenses for participation in the board and other meetings and profit related commission as may be approved by the members.
Sec. 149(9) of the Act:
Notwithstanding anything contained in any other provision of this Act, but subject to the provisions of sections 197 and 198, an independent director shall not be entitled to any stock option and may receive remuneration by way of fee provided under sub-section (5) of section 197, reimbursement of expenses for participation in the Board and other meetings and profit related commission as may be approved by members.
Provided that if a company has no profits or its profits are inadequate, an independent director may receive remuneration, exclusive of any fees payable under sub-section (5) of section 197, in accordance with the provisions of Schedule V. – Amendment introduced by Cos. (Amendment) Act, 2020. Tuesday, 20 April 2021 18 Presentation by CS Gaurav Pingle<br>
Sec. 149(9) of the Act:
Notwithstanding anything contained in any other provision of this Act, but subject to the provisions of sections 197 and 198, an independent director shall not be entitled to any stock option and may receive remuneration by way of fee provided under sub-section (5) of section 197, reimbursement of expenses for participation in the Board and other meetings and profit related commission as may be approved by members.
Provided that if a company has no profits or its profits are inadequate, an independent director may receive remuneration, exclusive of any fees payable under sub-section (5) of section 197, in accordance with the provisions of Schedule V. – Amendment introduced by Cos. (Amendment) Act, 2020. Tuesday, 20 April 2021 18 Presentation by CS Gaurav Pingle<br>
19
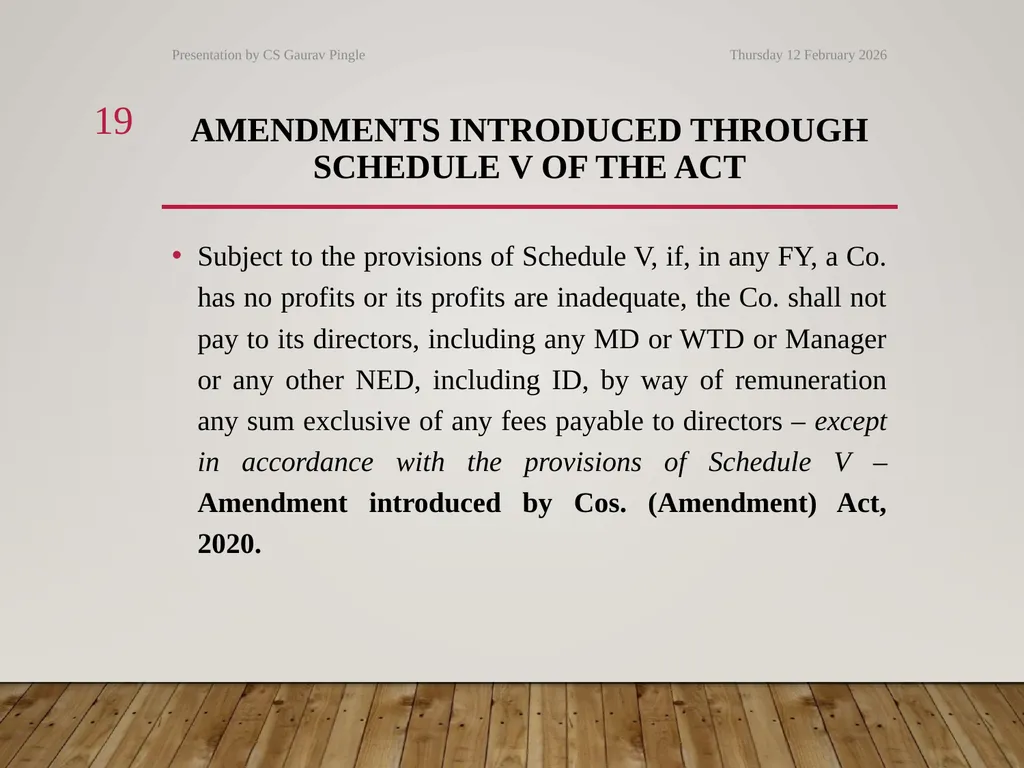
Amendments introduced through Schedule V of the Act Subject to the provisions of Schedule V, if, in any FY, a Co. has no profits or its profits are inadequate, the Co. shall not pay to its directors, including any MD or WTD or Manager or any other NED, including ID, by way of remuneration any sum exclusive of any fees payable to directors – except in accordance with the provisions of Schedule V – Amendment introduced by Cos. (Amendment) Act, 2020. Tuesday, 20 April 2021 19 Presentation by CS Gaurav Pingle<br>
20
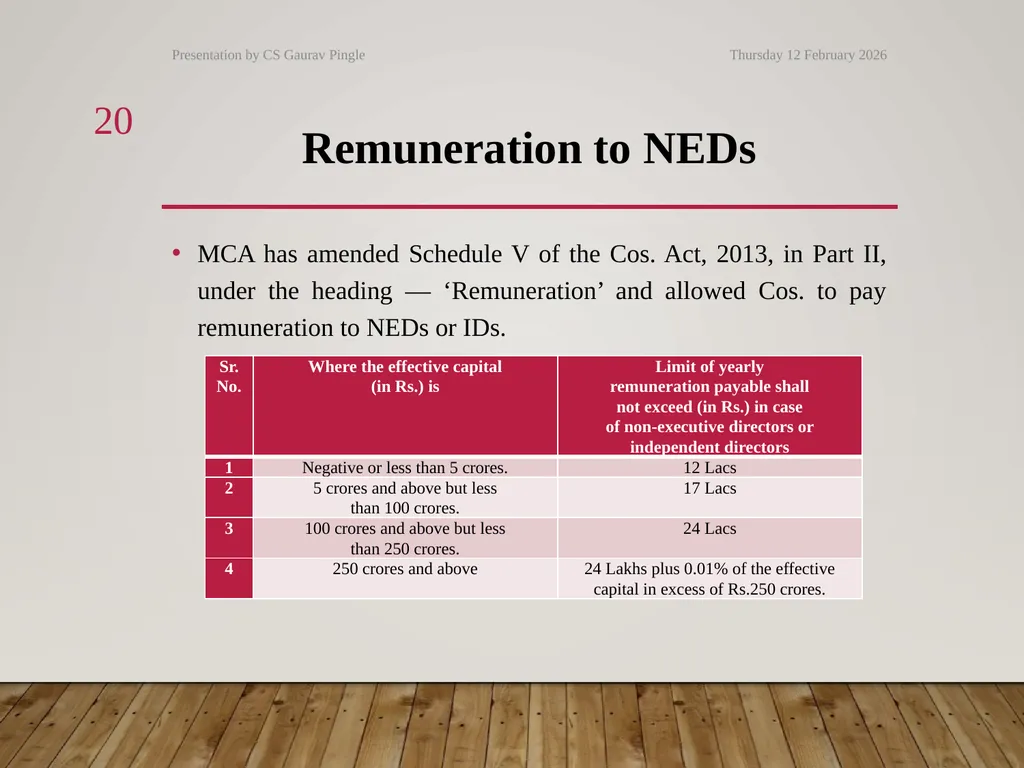
Remuneration to NEDs MCA has amended Schedule V of the Cos. Act, 2013, in Part II, under the heading ― ‘Remuneration’ and allowed Cos. to pay remuneration to NEDs or IDs. Tuesday, 20 April 2021 20 Presentation by CS Gaurav Pingle<br>
21
VIRTUAL MEETINGS UNDER
COMPANIES ACT, 2013 PART III OF THE PRESENTATION Tuesday, 20 April 2021 21 Presentation by CS Gaurav Pingle<br>
22
Board Meetings through Video Conferencing Board meetings to consider the following agenda items can be held through VC without physical presence of quorum till June 30, 2021:
Approval of the Annual Financial Statements;
Approval of the Board’s report;
Approval of the prospectus;
Audit Committee Meetings for consideration of financial statement including consolidated financial statement if any. Tuesday, 20 April 2021 22 Presentation by CS Gaurav Pingle<br>
Approval of the Annual Financial Statements;
Approval of the Board’s report;
Approval of the prospectus;
Audit Committee Meetings for consideration of financial statement including consolidated financial statement if any. Tuesday, 20 April 2021 22 Presentation by CS Gaurav Pingle<br>
23
AGM & EGM through VC AGM can be held through VC till December 31, 2021 – MCA Circular.
EGM can be conducted through VC till June 30, 2021 – MCA Circular.
Notice of Meeting to contain helpline number in case of technical issues
All documents accompanying the notice shall be sent by way of e-mail to all members including auditors
Public notice of the meeting to specially contain the fact that the meeting is being held through VC/OAVM
Cos. which are not required to provide e-voting facility shall have to share an email address with contact number where members may register to participate in the meeting in the public notice. Tuesday, 20 April 2021 23 Presentation by CS Gaurav Pingle<br>
EGM can be conducted through VC till June 30, 2021 – MCA Circular.
Notice of Meeting to contain helpline number in case of technical issues
All documents accompanying the notice shall be sent by way of e-mail to all members including auditors
Public notice of the meeting to specially contain the fact that the meeting is being held through VC/OAVM
Cos. which are not required to provide e-voting facility shall have to share an email address with contact number where members may register to participate in the meeting in the public notice. Tuesday, 20 April 2021 23 Presentation by CS Gaurav Pingle<br>
24
…. AGM & EGM through VC Two way teleconferencing such that participants may be allowed to ask questions to the directors
Transcript / Audio video recording of the proceedings to be ensured
Cos. which are not required to provide e-voting facility to have a designated email address for voting purposes
At least 1 ID (where company has IDs) & Statutory Auditors (or their representative) must mandatorily attend the meeting
Chairman to record his satisfaction in meeting that all efforts under the circumstances have been made to enable members to participate & vote in the meeting. Tuesday, 20 April 2021 24 Presentation by CS Gaurav Pingle<br>
Transcript / Audio video recording of the proceedings to be ensured
Cos. which are not required to provide e-voting facility to have a designated email address for voting purposes
At least 1 ID (where company has IDs) & Statutory Auditors (or their representative) must mandatorily attend the meeting
Chairman to record his satisfaction in meeting that all efforts under the circumstances have been made to enable members to participate & vote in the meeting. Tuesday, 20 April 2021 24 Presentation by CS Gaurav Pingle<br>
25
Key Highlights of Cos. (Amendment) Act, 2020 Compliance related amendments & Decriminalisation of offences
PART Iv OF THE PRESENTATION Tuesday, 20 April 2021 25 Presentation by CS Gaurav Pingle<br>
PART Iv OF THE PRESENTATION Tuesday, 20 April 2021 25 Presentation by CS Gaurav Pingle<br>
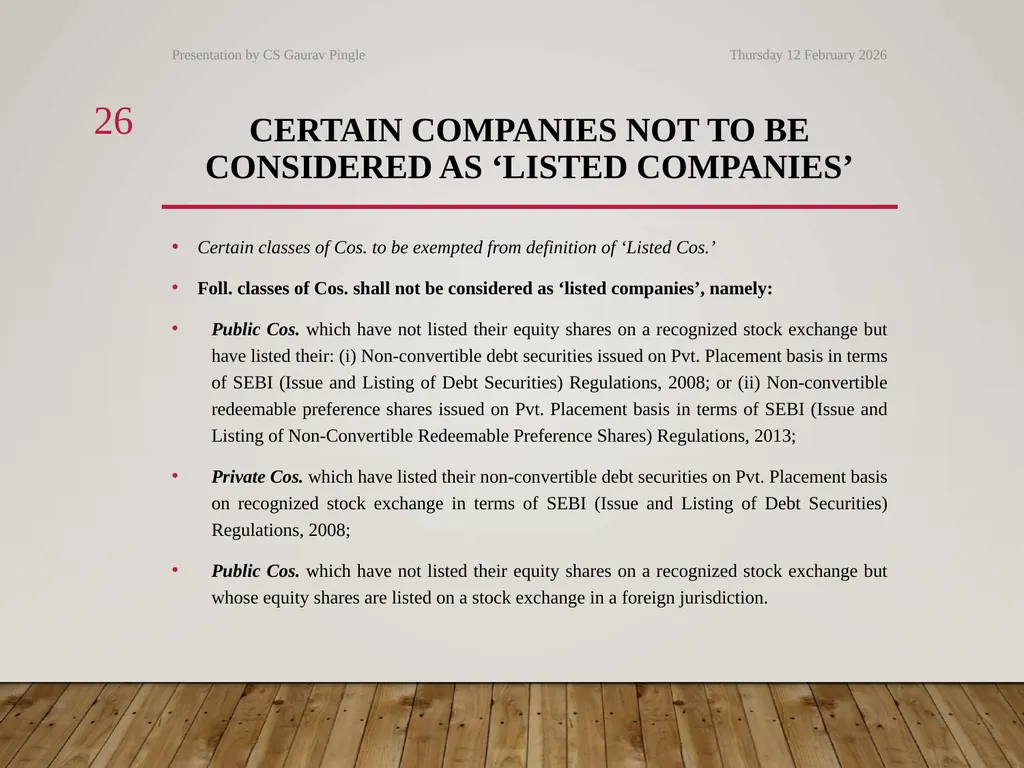
26
Certain companies not to be considered as ‘listed companies’ Certain classes of Cos. to be exempted from definition of ‘Listed Cos.’
Foll. classes of Cos. shall not be considered as ‘listed companies’, namely:
Public Cos. which have not listed their equity shares on a recognized stock exchange but have listed their: (i) Non-convertible debt securities issued on Pvt. Placement basis in terms of SEBI (Issue and Listing of Debt Securities) Regulations, 2008; or (ii) Non-convertible redeemable preference shares issued on Pvt. Placement basis in terms of SEBI (Issue and Listing of Non-Convertible Redeemable Preference Shares) Regulations, 2013;
Private Cos. which have listed their non-convertible debt securities on Pvt. Placement basis on recognized stock exchange in terms of SEBI (Issue and Listing of Debt Securities) Regulations, 2008;
Public Cos. which have not listed their equity shares on a recognized stock exchange but whose equity shares are listed on a stock exchange in a foreign jurisdiction. Tuesday, 20 April 2021 26 Presentation by CS Gaurav Pingle<br>
Foll. classes of Cos. shall not be considered as ‘listed companies’, namely:
Public Cos. which have not listed their equity shares on a recognized stock exchange but have listed their: (i) Non-convertible debt securities issued on Pvt. Placement basis in terms of SEBI (Issue and Listing of Debt Securities) Regulations, 2008; or (ii) Non-convertible redeemable preference shares issued on Pvt. Placement basis in terms of SEBI (Issue and Listing of Non-Convertible Redeemable Preference Shares) Regulations, 2013;
Private Cos. which have listed their non-convertible debt securities on Pvt. Placement basis on recognized stock exchange in terms of SEBI (Issue and Listing of Debt Securities) Regulations, 2008;
Public Cos. which have not listed their equity shares on a recognized stock exchange but whose equity shares are listed on a stock exchange in a foreign jurisdiction. Tuesday, 20 April 2021 26 Presentation by CS Gaurav Pingle<br>
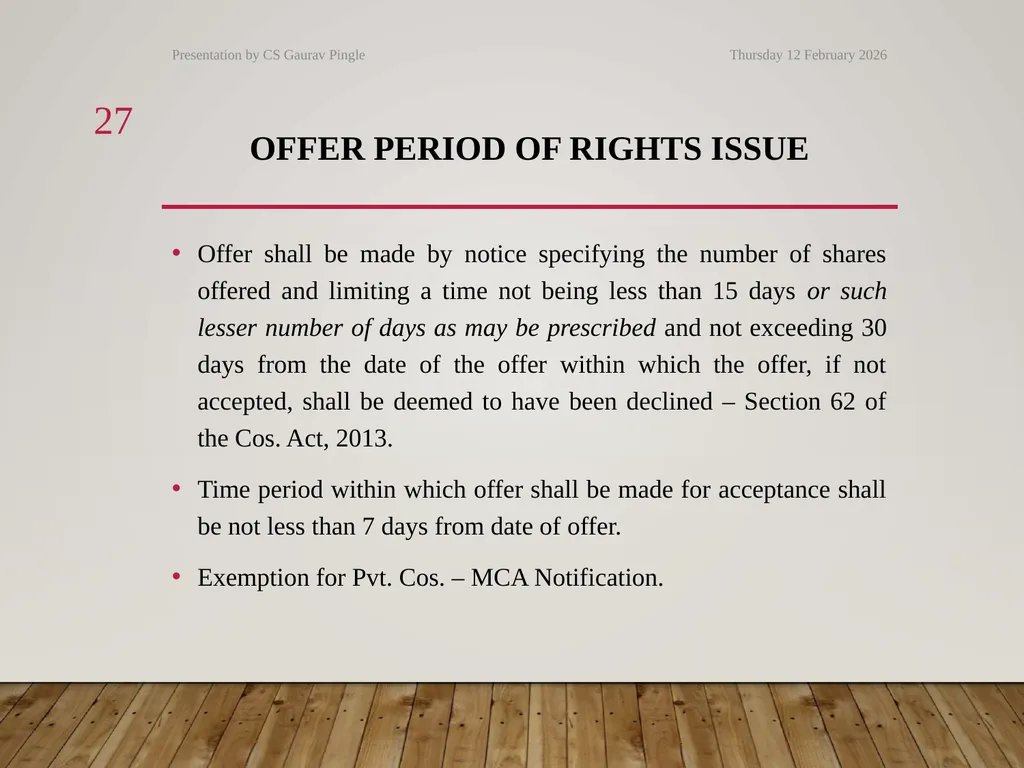
27
OFFER PERIOD OF RIGHTS ISSUE Offer shall be made by notice specifying the number of shares offered and limiting a time not being less than 15 days or such lesser number of days as may be prescribed and not exceeding 30 days from the date of the offer within which the offer, if not accepted, shall be deemed to have been declined – Section 62 of the Cos. Act, 2013.
Time period within which offer shall be made for acceptance shall be not less than 7 days from date of offer.
Exemption for Pvt. Cos. – MCA Notification. Tuesday, 20 April 2021 27 Presentation by CS Gaurav Pingle<br>
Time period within which offer shall be made for acceptance shall be not less than 7 days from date of offer.
Exemption for Pvt. Cos. – MCA Notification. Tuesday, 20 April 2021 27 Presentation by CS Gaurav Pingle<br>
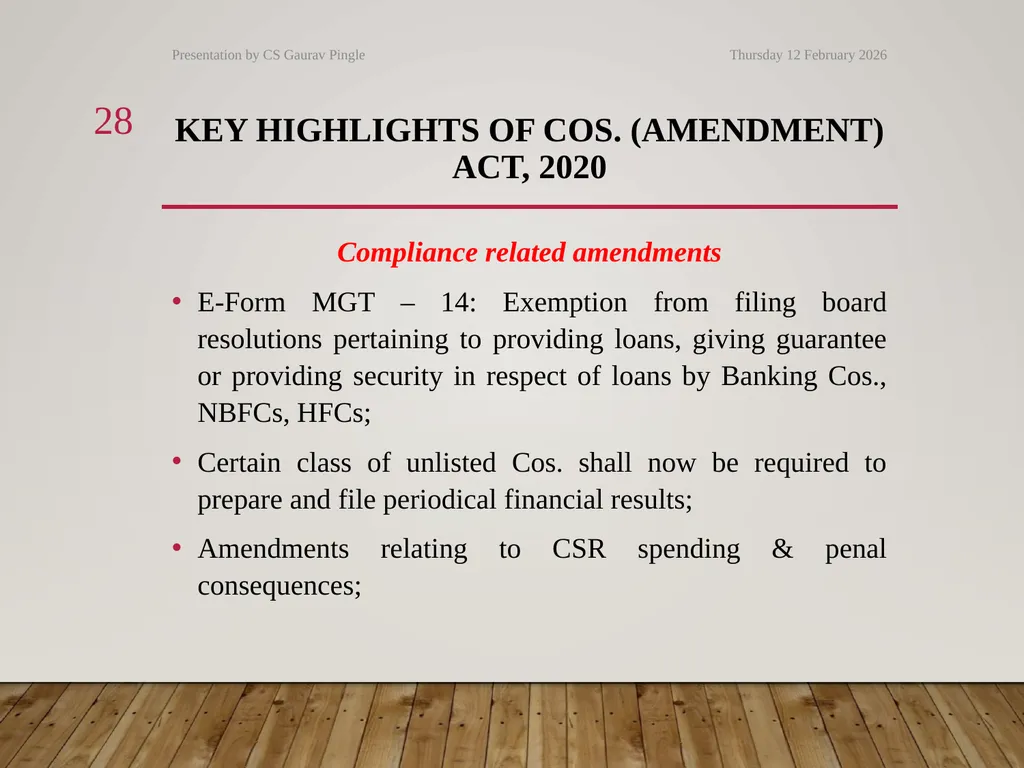
28
Key Highlights of Cos. (Amendment) Act, 2020 Compliance related amendments
E-Form MGT – 14: Exemption from filing board resolutions pertaining to providing loans, giving guarantee or providing security in respect of loans by Banking Cos., NBFCs, HFCs;
Certain class of unlisted Cos. shall now be required to prepare and file periodical financial results;
Amendments relating to CSR spending & penal consequences; Tuesday, 20 April 2021 28 Presentation by CS Gaurav Pingle<br>
E-Form MGT – 14: Exemption from filing board resolutions pertaining to providing loans, giving guarantee or providing security in respect of loans by Banking Cos., NBFCs, HFCs;
Certain class of unlisted Cos. shall now be required to prepare and file periodical financial results;
Amendments relating to CSR spending & penal consequences; Tuesday, 20 April 2021 28 Presentation by CS Gaurav Pingle<br>
29
Compliance calendar – fy 2021 – 2022 Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 29<br>
30
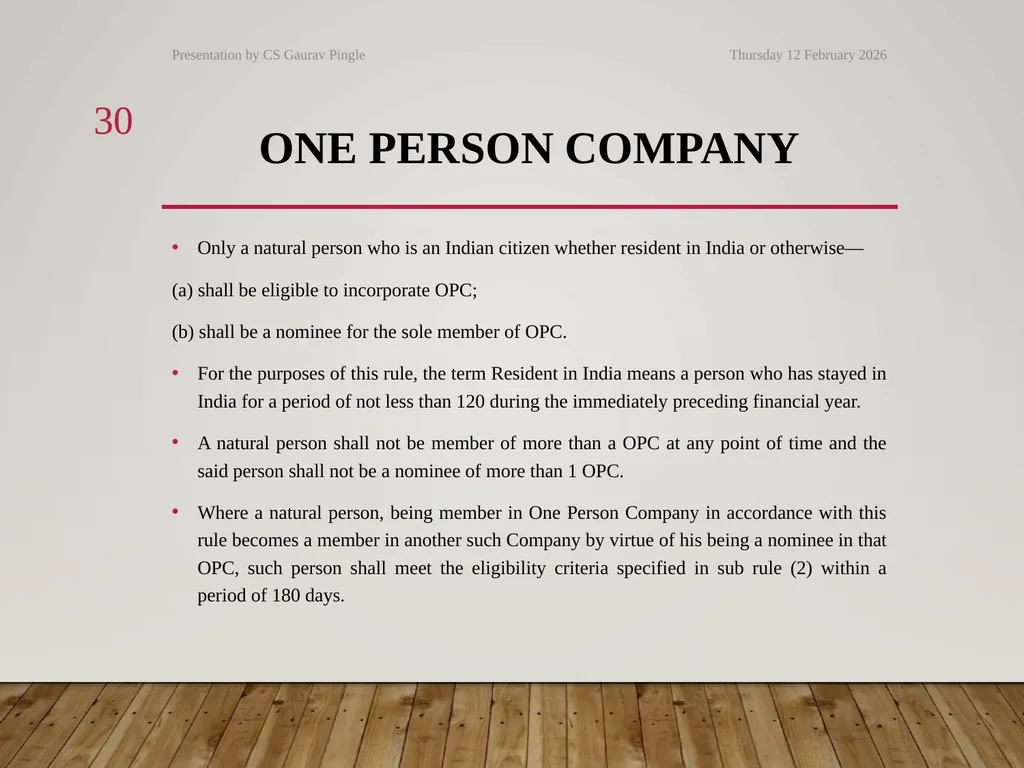
One person company Only a natural person who is an Indian citizen whether resident in India or otherwise—
(a) shall be eligible to incorporate OPC;
(b) shall be a nominee for the sole member of OPC.
For the purposes of this rule, the term Resident in India means a person who has stayed in India for a period of not less than 120 during the immediately preceding financial year.
A natural person shall not be member of more than a OPC at any point of time and the said person shall not be a nominee of more than 1 OPC.
Where a natural person, being member in One Person Company in accordance with this rule becomes a member in another such Company by virtue of his being a nominee in that OPC, such person shall meet the eligibility criteria specified in sub rule (2) within a period of 180 days. Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 30<br>
(a) shall be eligible to incorporate OPC;
(b) shall be a nominee for the sole member of OPC.
For the purposes of this rule, the term Resident in India means a person who has stayed in India for a period of not less than 120 during the immediately preceding financial year.
A natural person shall not be member of more than a OPC at any point of time and the said person shall not be a nominee of more than 1 OPC.
Where a natural person, being member in One Person Company in accordance with this rule becomes a member in another such Company by virtue of his being a nominee in that OPC, such person shall meet the eligibility criteria specified in sub rule (2) within a period of 180 days. Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 30<br>
31
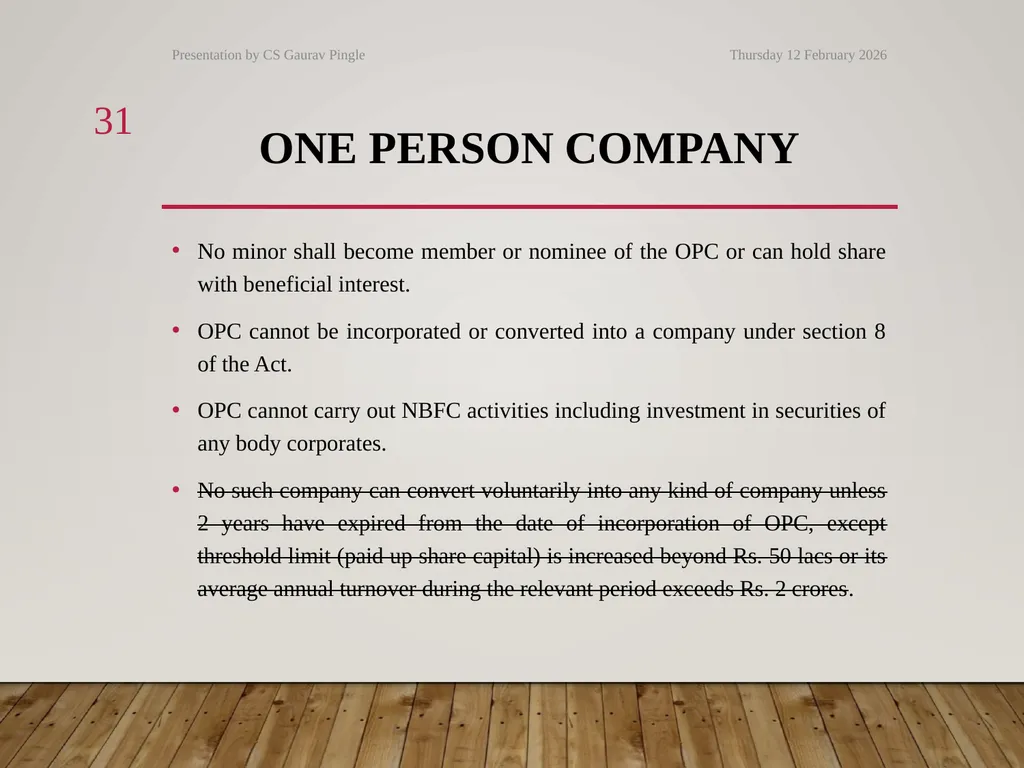
One person company No minor shall become member or nominee of the OPC or can hold share with beneficial interest.
OPC cannot be incorporated or converted into a company under section 8 of the Act.
OPC cannot carry out NBFC activities including investment in securities of any body corporates.
No such company can convert voluntarily into any kind of company unless 2 years have expired from the date of incorporation of OPC, except threshold limit (paid up share capital) is increased beyond Rs. 50 lacs or its average annual turnover during the relevant period exceeds Rs. 2 crores. Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 31<br>
OPC cannot be incorporated or converted into a company under section 8 of the Act.
OPC cannot carry out NBFC activities including investment in securities of any body corporates.
No such company can convert voluntarily into any kind of company unless 2 years have expired from the date of incorporation of OPC, except threshold limit (paid up share capital) is increased beyond Rs. 50 lacs or its average annual turnover during the relevant period exceeds Rs. 2 crores. Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 31<br>
32
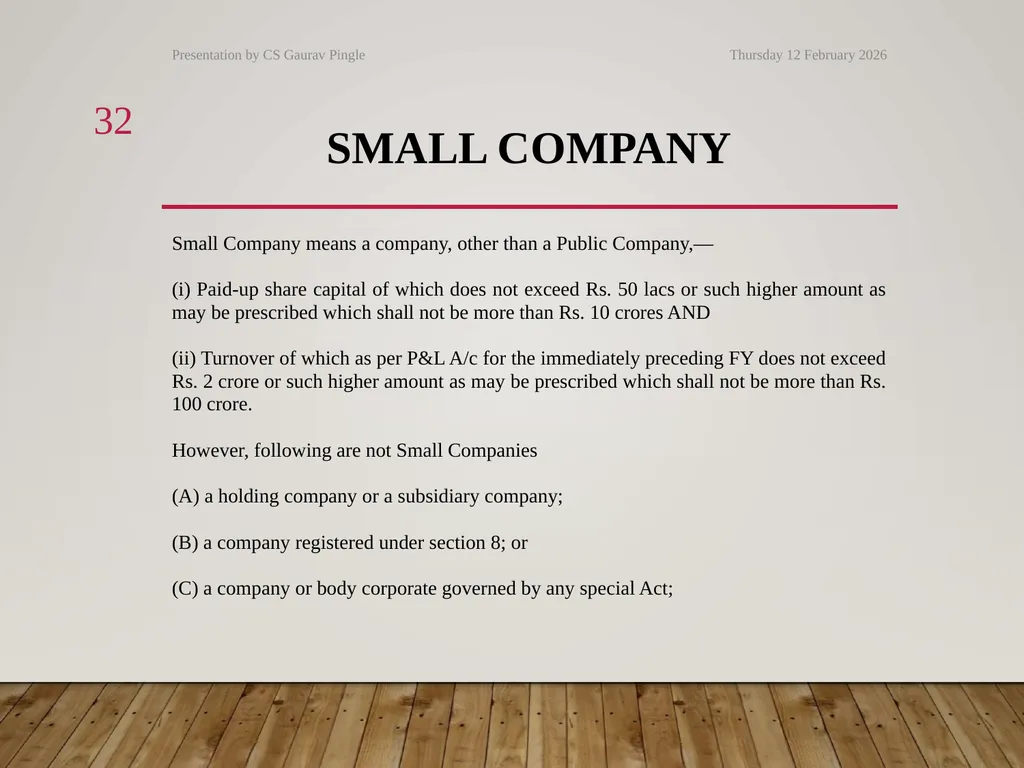
SMALL COMPANY Small Company means a company, other than a Public Company,—
(i) Paid-up share capital of which does not exceed Rs. 50 lacs or such higher amount as may be prescribed which shall not be more than Rs. 10 crores AND
(ii) Turnover of which as per P&L A/c for the immediately preceding FY does not exceed Rs. 2 crore or such higher amount as may be prescribed which shall not be more than Rs. 100 crore.
However, following are not Small Companies
(A) a holding company or a subsidiary company;
(B) a company registered under section 8; or
(C) a company or body corporate governed by any special Act; Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 32<br>
(i) Paid-up share capital of which does not exceed Rs. 50 lacs or such higher amount as may be prescribed which shall not be more than Rs. 10 crores AND
(ii) Turnover of which as per P&L A/c for the immediately preceding FY does not exceed Rs. 2 crore or such higher amount as may be prescribed which shall not be more than Rs. 100 crore.
However, following are not Small Companies
(A) a holding company or a subsidiary company;
(B) a company registered under section 8; or
(C) a company or body corporate governed by any special Act; Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 32<br>
33
QUESTION & ANSWER SESSION Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 33<br>
34
Thank you Thank you members for active participation!
CS GAURAV PINGLE
(E) gp@csgauravpingle.com
(W) www.csgauravpingle.com
(M)+91 9975565713 Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 34<br>
CS GAURAV PINGLE
(E) gp@csgauravpingle.com
(W) www.csgauravpingle.com
(M)+91 9975565713 Tuesday, 20 April 2021 Presentation by CS Gaurav Pingle 34<br>