
DeFi: Hope or Hype? Quite a bit for regulators to

Description: DeFi: Hope or Hype? Quite a bit for regulators to think about. Cryptocurrencies Institutional Interest Spot and Futures ETFsETPs Regulators have focused on trading venues, Market power in creating and processing the underlying is also
Related Topics
Download Presentation
"DeFi: Hope or Hype? Quite a bit for regulators to" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. DeFi: Hope or Hype? Quite a bit for regulators to think about.<br>
slide2. Cryptocurrencies Institutional Interest
Spot and Futures ETFs/ETPs
Regulators have focused on trading venues,
Market power in creating and processing the underlying is also relevant
Regulations designed for Traditional Finance are not adapted to DeFi 11/15/24 The Future of Finance<br>
slide3. Stablecoins Backed by liquid assets off-chain or cryptocurrencies on-chain
Sky or Tether
Total: about $ 179 bn
Largest is Tether: About 70% 11/15/24 The Future of Finance<br>
slide4. Blockchain data on daily “simple” transactions 11/15/24 The Future of Finance<br>
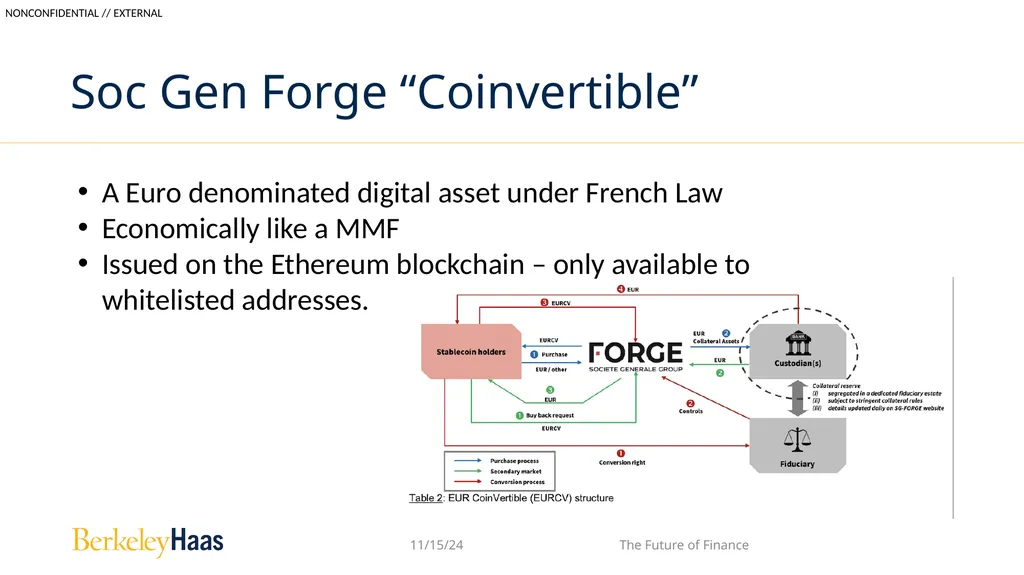
slide5. Soc Gen Forge “Coinvertible” A Euro denominated digital asset under French Law
Economically like a MMF
Issued on the Ethereum blockchain – only available to whitelisted addresses. 11/15/24 The Future of Finance<br>
slide6. Wyoming Stablecoin Anticipated launch in 2025
Backed by US Gov’t bills held in trust
Anticipate US-wide use 11/15/24 The Future of Finance<br>
slide7. Regulatory Questions Cheaper payment rails may lead customers to eschew banks
Changes in deposits and flows due to changes in the payment system can have real effects as they affect banks’ incentives to produce inside money/loans
Changes in the type of deposits at banks can affect stability if they become more “sticky.” 11/15/24 The Future of Finance<br>
slide8. Optimal Regulatory Response Not obvious that a central planner wants the same institution to process payments and to make loans.
Because of network effects, competition in payments is difficult.
Stablecoins are a plausible substitute for card networks --> encourage competition? 11/15/24 The Future of Finance<br>
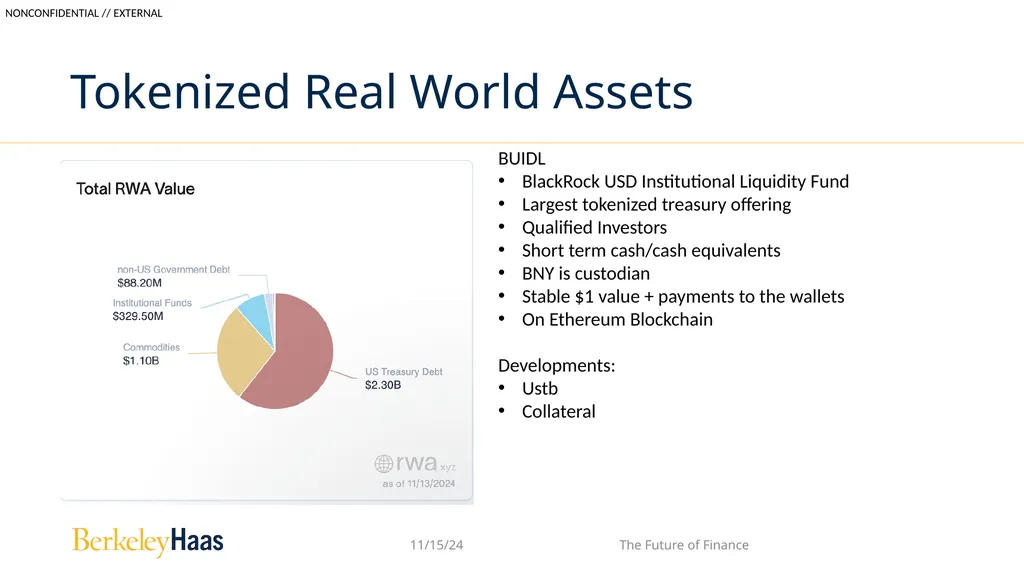
slide9. Tokenized Real World Assets BUIDL
BlackRock USD Institutional Liquidity Fund
Largest tokenized treasury offering
Qualified Investors
Short term cash/cash equivalents
BNY is custodian
Stable $1 value + payments to the wallets
On Ethereum Blockchain
Developments:
Ustb
Collateral 11/15/24 The Future of Finance<br>
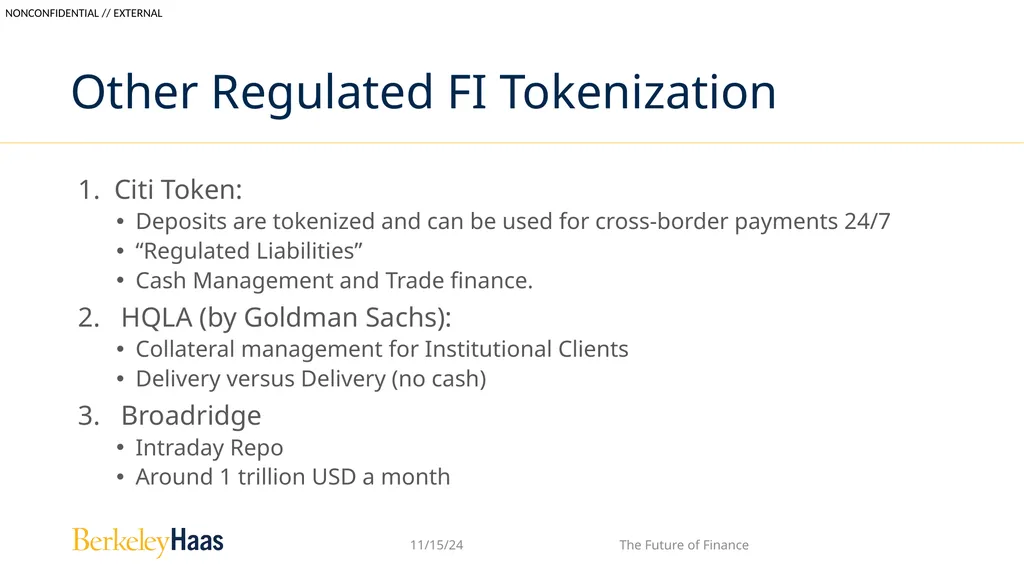
slide10. Other Regulated FI Tokenization 1. Citi Token:
Deposits are tokenized and can be used for cross-border payments 24/7
“Regulated Liabilities”
Cash Management and Trade finance.
2. HQLA (by Goldman Sachs):
Collateral management for Institutional Clients
Delivery versus Delivery (no cash)
Broadridge
Intraday Repo
Around 1 trillion USD a month 11/15/24 The Future of Finance<br>
slide11. Benefits of Tokenization Allows fractionalization.
Increased participation
May increase secondary market liquidity 11/15/24 The Future of Finance<br>
slide12. Tokenization and settlement Makes it easier to switch and use collateral
Possible to do direct collateral swaps
Less volume in markets and price discovery
Precise settlement (less pre-funding)
Align technological transfer with title transfer (no fails) 11/15/24 The Future of Finance<br>
slide13. Optimal Regulatory Response Tokenization makes illiquid collateral more liquid
Moves liquidity risk from institutions to markets.
We do not have a framework to measure this.
Faster settlement means it is unclear who holds risk at any time.
Current regulation based on slower markets. 11/15/24 The Future of Finance<br>
slide14. Technological Innovation New ways of transferring value and ownership
New ways of trading, clearing and settlement.
Is the economic intent of legacy regulations correctly translated to the new technological innovations? 11/15/24 The Future of Finance<br>
slide2. Cryptocurrencies Institutional Interest
Spot and Futures ETFs/ETPs
Regulators have focused on trading venues,
Market power in creating and processing the underlying is also relevant
Regulations designed for Traditional Finance are not adapted to DeFi 11/15/24 The Future of Finance<br>
slide3. Stablecoins Backed by liquid assets off-chain or cryptocurrencies on-chain
Sky or Tether
Total: about $ 179 bn
Largest is Tether: About 70% 11/15/24 The Future of Finance<br>
slide4. Blockchain data on daily “simple” transactions 11/15/24 The Future of Finance<br>
slide5. Soc Gen Forge “Coinvertible” A Euro denominated digital asset under French Law
Economically like a MMF
Issued on the Ethereum blockchain – only available to whitelisted addresses. 11/15/24 The Future of Finance<br>
slide6. Wyoming Stablecoin Anticipated launch in 2025
Backed by US Gov’t bills held in trust
Anticipate US-wide use 11/15/24 The Future of Finance<br>
slide7. Regulatory Questions Cheaper payment rails may lead customers to eschew banks
Changes in deposits and flows due to changes in the payment system can have real effects as they affect banks’ incentives to produce inside money/loans
Changes in the type of deposits at banks can affect stability if they become more “sticky.” 11/15/24 The Future of Finance<br>
slide8. Optimal Regulatory Response Not obvious that a central planner wants the same institution to process payments and to make loans.
Because of network effects, competition in payments is difficult.
Stablecoins are a plausible substitute for card networks --> encourage competition? 11/15/24 The Future of Finance<br>
slide9. Tokenized Real World Assets BUIDL
BlackRock USD Institutional Liquidity Fund
Largest tokenized treasury offering
Qualified Investors
Short term cash/cash equivalents
BNY is custodian
Stable $1 value + payments to the wallets
On Ethereum Blockchain
Developments:
Ustb
Collateral 11/15/24 The Future of Finance<br>
slide10. Other Regulated FI Tokenization 1. Citi Token:
Deposits are tokenized and can be used for cross-border payments 24/7
“Regulated Liabilities”
Cash Management and Trade finance.
2. HQLA (by Goldman Sachs):
Collateral management for Institutional Clients
Delivery versus Delivery (no cash)
Broadridge
Intraday Repo
Around 1 trillion USD a month 11/15/24 The Future of Finance<br>
slide11. Benefits of Tokenization Allows fractionalization.
Increased participation
May increase secondary market liquidity 11/15/24 The Future of Finance<br>
slide12. Tokenization and settlement Makes it easier to switch and use collateral
Possible to do direct collateral swaps
Less volume in markets and price discovery
Precise settlement (less pre-funding)
Align technological transfer with title transfer (no fails) 11/15/24 The Future of Finance<br>
slide13. Optimal Regulatory Response Tokenization makes illiquid collateral more liquid
Moves liquidity risk from institutions to markets.
We do not have a framework to measure this.
Faster settlement means it is unclear who holds risk at any time.
Current regulation based on slower markets. 11/15/24 The Future of Finance<br>
slide14. Technological Innovation New ways of transferring value and ownership
New ways of trading, clearing and settlement.
Is the economic intent of legacy regulations correctly translated to the new technological innovations? 11/15/24 The Future of Finance<br>