
Edmonton’s Energy Transition Plan Clean Energy
EM
Published · 17 slides · 0 views

1 / 1

Description
Edmontons Energy Transition Plan Clean Energy Financing: Briefing Note 21 October 2013 RICHARD BOYD Numerous reports by government, non-profits, and private businesses have surveyed approaches for funding clean energy (energy efficiency
Related Topics
Download this presentation From Below
"Edmonton’s Energy Transition Plan Clean Energy" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Share
Embed code
Presentation Transcript
01
Edmonton’s Energy Transition Plan
Clean Energy Financing: Briefing Note
21 October 2013
RICHARD BOYD<br>
02
Numerous reports by government, non-profits, and private businesses have surveyed approaches for funding clean energy (energy efficiency and renewable energy) programs and projects, including C3’s Energy Efficiency Funding and Administration Options for Alberta. The purpose of this note is not to provide another scan of the full spectrum of available approaches, but rather to focus on innovative solutions that have recently gained traction in the USA, and that are in use, or are being considered for use, in a Canadian context.
Recent innovations in clean energy financing have developed business models that simultaneously address many recognized market barriers, including the first-time cost barrier, and that encourage the adoption of cutting-edge technologies and deep improvements in energy efficiency. These financing strategies also provide scalable solutions, and are designed to use limited public funds to mobilize, leverage, and support investment in clean energy by private financial institutions (FIs). Leverage ratios of 4:1 (young programs) to 20:1 (mature programs) have been observed in the USA. In the latter case, $3 million of public grant capital can be turned into $60 million of private lending capital. The path to adequate and sustainable funding of clean energy programs and projects, requires a shift from the traditional publicly grant-funded world of rebates, towards innovative financing programs that use public funds to mobilize large amounts of private capital. Given this basic premise, we provide a high-level overview of three innovative, scalable clean energy financing models that exhibit great promise, namely:
Property assessed (Local Improvement Charge) programs;
Energy savings agreement programs; and
On-bill tariff repayment programs.
A typical financing program – applicable to residential, commercial, and industrial clean energy projects – consists of up to five major elements: a source(s) of program funds (e.g., private debt or equity, public grants or loans); an administrator(s); a repayment vehicle (e.g., monthly credit bill, on-bill tariff, property tax assessment, service fee); credit enhancements (e.g., loan loss reserve fund, subordinate debt structure, loan guarantee); and security (e.g., utility meter, property tax-lien, equipment). For each of the three program models, we provide a brief description of the underlying model (encompassing each of these elements), list key strengths and weaknesses, and highlight the roles for the City of Edmonton (COE) and the Government of Alberta (GOA).
Before looking at the three models for clean energy financing, we first outline the main characteristics of cost-effective, self-sustaining financing programs. The chosen models must reflect these characteristics. Introduction<br>
Recent innovations in clean energy financing have developed business models that simultaneously address many recognized market barriers, including the first-time cost barrier, and that encourage the adoption of cutting-edge technologies and deep improvements in energy efficiency. These financing strategies also provide scalable solutions, and are designed to use limited public funds to mobilize, leverage, and support investment in clean energy by private financial institutions (FIs). Leverage ratios of 4:1 (young programs) to 20:1 (mature programs) have been observed in the USA. In the latter case, $3 million of public grant capital can be turned into $60 million of private lending capital. The path to adequate and sustainable funding of clean energy programs and projects, requires a shift from the traditional publicly grant-funded world of rebates, towards innovative financing programs that use public funds to mobilize large amounts of private capital. Given this basic premise, we provide a high-level overview of three innovative, scalable clean energy financing models that exhibit great promise, namely:
Property assessed (Local Improvement Charge) programs;
Energy savings agreement programs; and
On-bill tariff repayment programs.
A typical financing program – applicable to residential, commercial, and industrial clean energy projects – consists of up to five major elements: a source(s) of program funds (e.g., private debt or equity, public grants or loans); an administrator(s); a repayment vehicle (e.g., monthly credit bill, on-bill tariff, property tax assessment, service fee); credit enhancements (e.g., loan loss reserve fund, subordinate debt structure, loan guarantee); and security (e.g., utility meter, property tax-lien, equipment). For each of the three program models, we provide a brief description of the underlying model (encompassing each of these elements), list key strengths and weaknesses, and highlight the roles for the City of Edmonton (COE) and the Government of Alberta (GOA).
Before looking at the three models for clean energy financing, we first outline the main characteristics of cost-effective, self-sustaining financing programs. The chosen models must reflect these characteristics. Introduction<br>
03
Self-sustainability
For a clean energy financing program to be self-sustaining, public funds should be used to mobilize, leverage, and support participation by private financial institutions, both primary lenders that provide loan capital directly to households and businesses or indirectly via the program administrator, and investors (in the secondary market) that purchase portfolios of loans from the primary lenders. To these ends, a clean energy financing program should:
Prove clean energy finance as a viable business line for private financial institutions; and
Develop a secondary market for portfolios of clean energy loans.
1. Make the business case to primary lenders
The path to self-sustainability requires private financial institutions to perceive clean energy financing as profitable, creditworthy, and a sizeable business line. For only then will public funds successfully mobilize and leverage private capital. Potential partner financial institutions will want to know:
The size of individual loans to households and businesses (and hence transaction costs);
The likely total size (total deal flow) of the financing program;
The credit characteristics of the target market;
Who bears what risks;
The size and structure of available credit enhancements (e.g., loan loss reserve funds (LRF), subordinate debt structures, loan guarantees, interest rate buy-downs, etc.);
The administrator’s expectations for interest rates and loan terms; and
Responsibilities and expectations for loan servicing and origination. Keys to effective, self-sustaining financing programs<br>
For a clean energy financing program to be self-sustaining, public funds should be used to mobilize, leverage, and support participation by private financial institutions, both primary lenders that provide loan capital directly to households and businesses or indirectly via the program administrator, and investors (in the secondary market) that purchase portfolios of loans from the primary lenders. To these ends, a clean energy financing program should:
Prove clean energy finance as a viable business line for private financial institutions; and
Develop a secondary market for portfolios of clean energy loans.
1. Make the business case to primary lenders
The path to self-sustainability requires private financial institutions to perceive clean energy financing as profitable, creditworthy, and a sizeable business line. For only then will public funds successfully mobilize and leverage private capital. Potential partner financial institutions will want to know:
The size of individual loans to households and businesses (and hence transaction costs);
The likely total size (total deal flow) of the financing program;
The credit characteristics of the target market;
Who bears what risks;
The size and structure of available credit enhancements (e.g., loan loss reserve funds (LRF), subordinate debt structures, loan guarantees, interest rate buy-downs, etc.);
The administrator’s expectations for interest rates and loan terms; and
Responsibilities and expectations for loan servicing and origination. Keys to effective, self-sustaining financing programs<br>
04
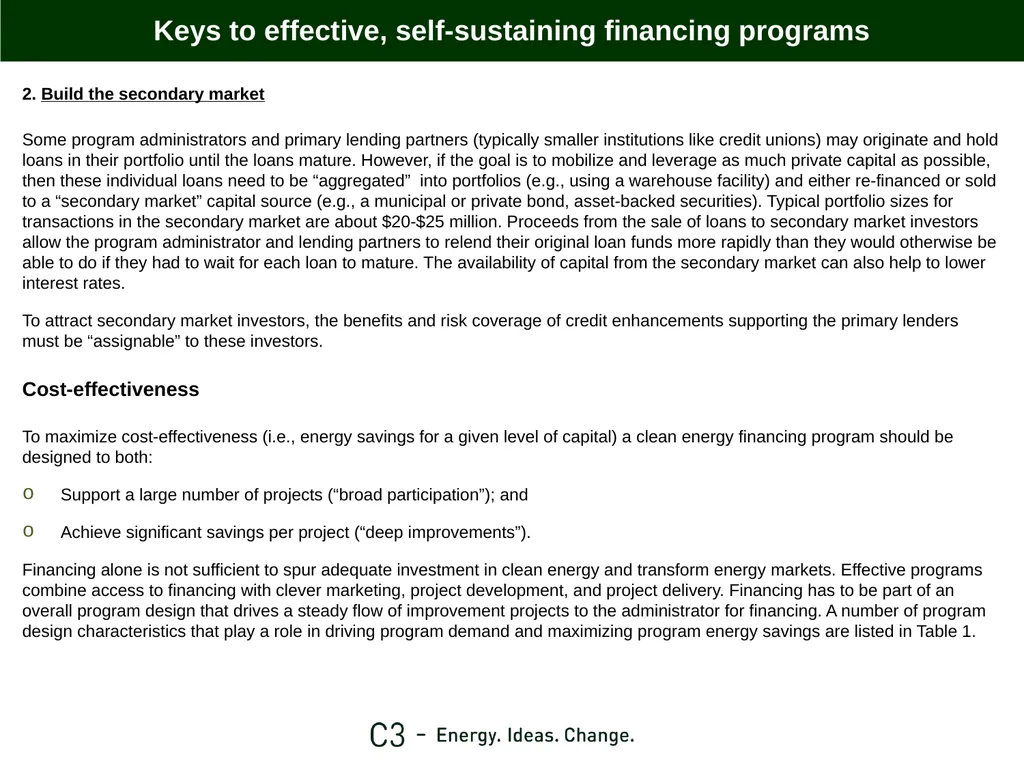
2. Build the secondary market
Some program administrators and primary lending partners (typically smaller institutions like credit unions) may originate and hold loans in their portfolio until the loans mature. However, if the goal is to mobilize and leverage as much private capital as possible, then these individual loans need to be “aggregated” into portfolios (e.g., using a warehouse facility) and either re-financed or sold to a “secondary market” capital source (e.g., a municipal or private bond, asset-backed securities). Typical portfolio sizes for transactions in the secondary market are about $20-$25 million. Proceeds from the sale of loans to secondary market investors allow the program administrator and lending partners to relend their original loan funds more rapidly than they would otherwise be able to do if they had to wait for each loan to mature. The availability of capital from the secondary market can also help to lower interest rates.
To attract secondary market investors, the benefits and risk coverage of credit enhancements supporting the primary lenders must be “assignable” to these investors.
Cost-effectiveness
To maximize cost-effectiveness (i.e., energy savings for a given level of capital) a clean energy financing program should be designed to both:
Support a large number of projects (“broad participation”); and
Achieve significant savings per project (“deep improvements”).
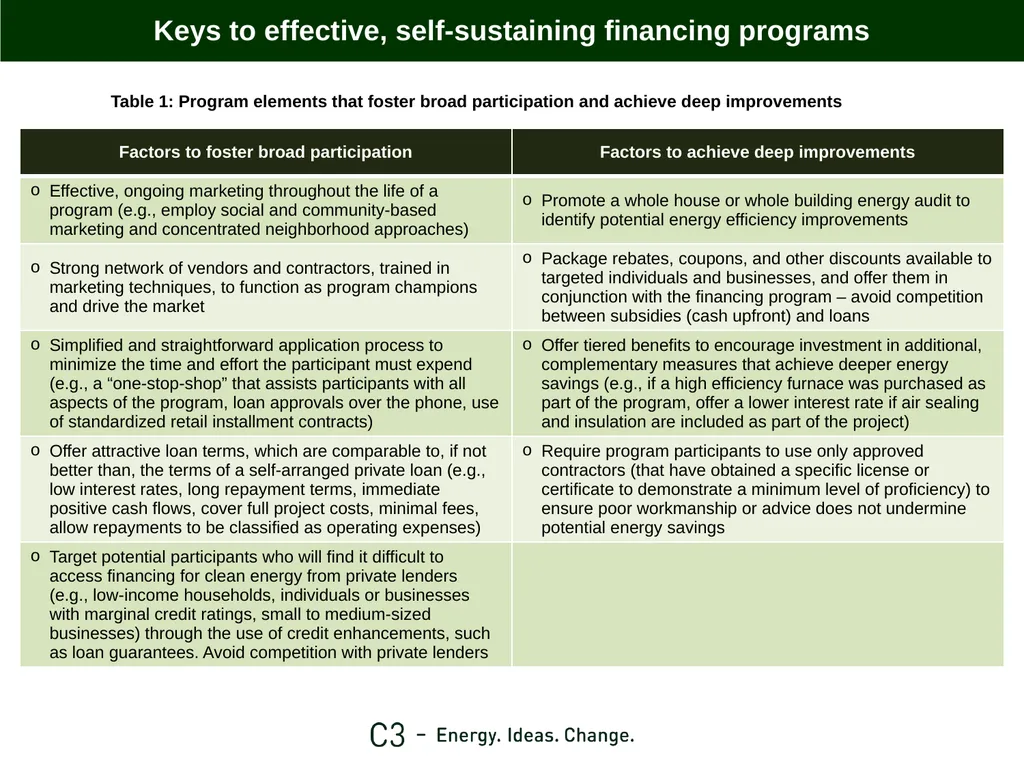
Financing alone is not sufficient to spur adequate investment in clean energy and transform energy markets. Effective programs combine access to financing with clever marketing, project development, and project delivery. Financing has to be part of an overall program design that drives a steady flow of improvement projects to the administrator for financing. A number of program design characteristics that play a role in driving program demand and maximizing program energy savings are listed in Table 1. Keys to effective, self-sustaining financing programs<br>
Some program administrators and primary lending partners (typically smaller institutions like credit unions) may originate and hold loans in their portfolio until the loans mature. However, if the goal is to mobilize and leverage as much private capital as possible, then these individual loans need to be “aggregated” into portfolios (e.g., using a warehouse facility) and either re-financed or sold to a “secondary market” capital source (e.g., a municipal or private bond, asset-backed securities). Typical portfolio sizes for transactions in the secondary market are about $20-$25 million. Proceeds from the sale of loans to secondary market investors allow the program administrator and lending partners to relend their original loan funds more rapidly than they would otherwise be able to do if they had to wait for each loan to mature. The availability of capital from the secondary market can also help to lower interest rates.
To attract secondary market investors, the benefits and risk coverage of credit enhancements supporting the primary lenders must be “assignable” to these investors.
Cost-effectiveness
To maximize cost-effectiveness (i.e., energy savings for a given level of capital) a clean energy financing program should be designed to both:
Support a large number of projects (“broad participation”); and
Achieve significant savings per project (“deep improvements”).
Financing alone is not sufficient to spur adequate investment in clean energy and transform energy markets. Effective programs combine access to financing with clever marketing, project development, and project delivery. Financing has to be part of an overall program design that drives a steady flow of improvement projects to the administrator for financing. A number of program design characteristics that play a role in driving program demand and maximizing program energy savings are listed in Table 1. Keys to effective, self-sustaining financing programs<br>
05
Keys to effective, self-sustaining financing programs Table 1: Program elements that foster broad participation and achieve deep improvements<br>
06
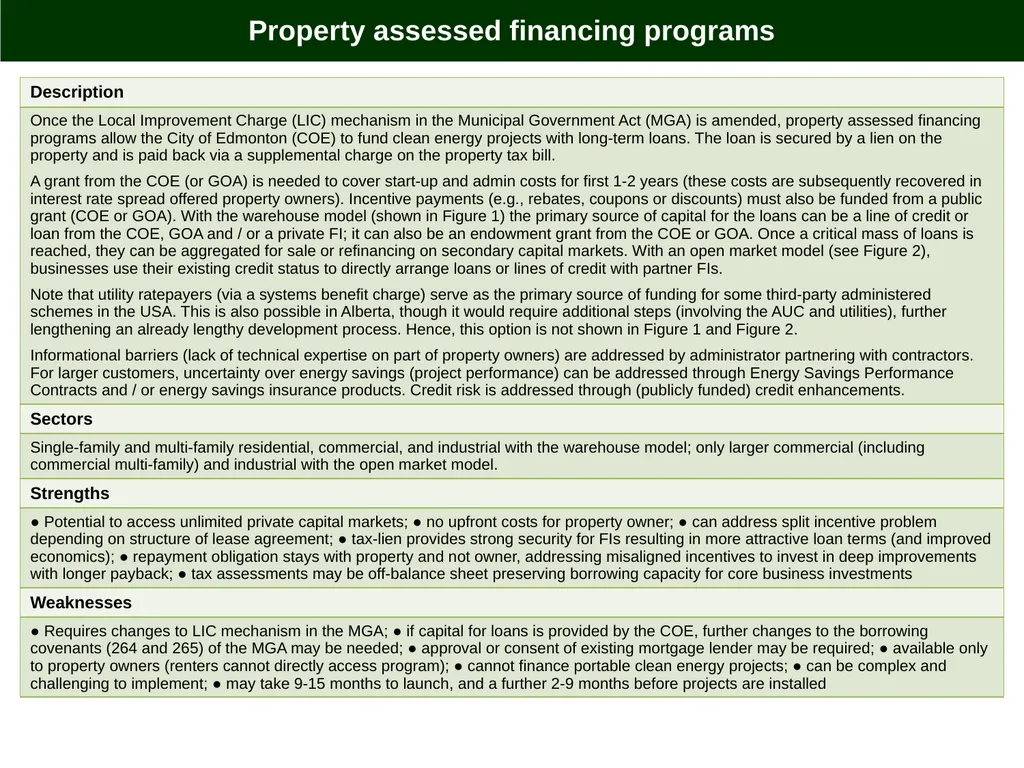
Property assessed financing programs<br>
07
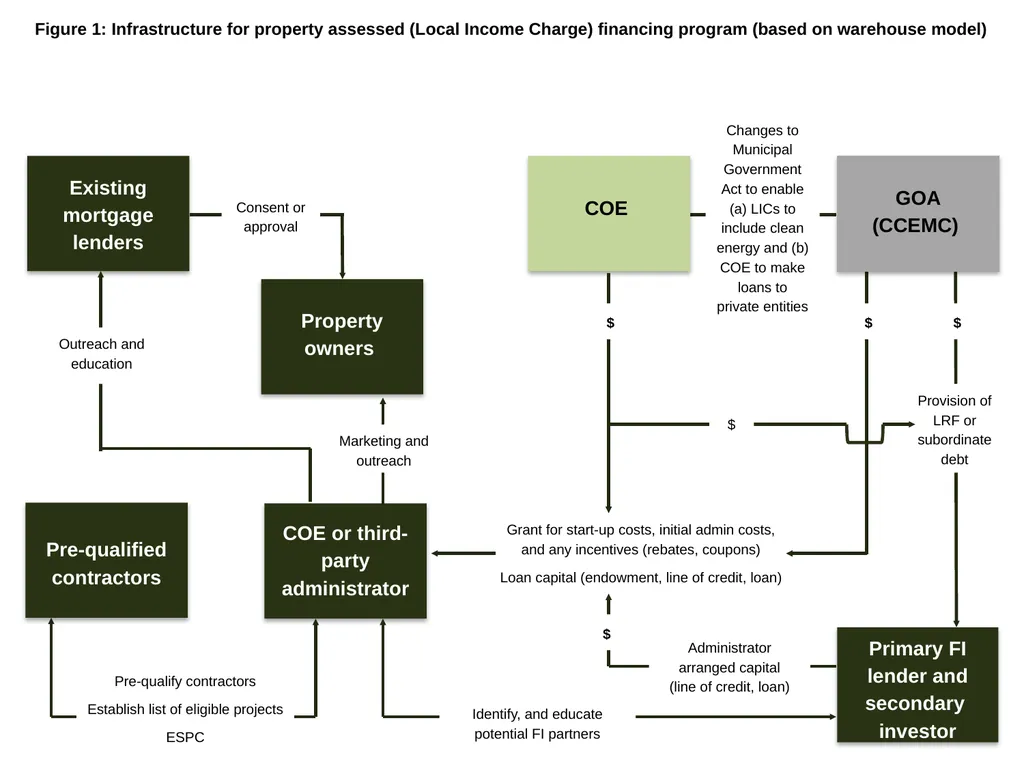
Primary FI lender and secondary investor COE or third-party administrator COE Pre-qualified contractors Provision of LRF or subordinate debt Changes to Municipal Government Act to enable (a) LICs to include clean energy and (b) COE to make loans to private entities GOA
(CCEMC) Identify, and educate potential FI partners Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons)
Loan capital (endowment, line of credit, loan) Property owners Marketing and outreach Administrator arranged capital
(line of credit, loan) $ $ $ Figure 1: Infrastructure for property assessed (Local Income Charge) financing program (based on warehouse model) $ Existing mortgage lenders Consent or approval $ Outreach and education Pre-qualify contractors
Establish list of eligible projects
ESPC<br>
(CCEMC) Identify, and educate potential FI partners Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons)
Loan capital (endowment, line of credit, loan) Property owners Marketing and outreach Administrator arranged capital
(line of credit, loan) $ $ $ Figure 1: Infrastructure for property assessed (Local Income Charge) financing program (based on warehouse model) $ Existing mortgage lenders Consent or approval $ Outreach and education Pre-qualify contractors
Establish list of eligible projects
ESPC<br>
08
Marketing and outreach Pre-qualified contractors COE or third-party administrator Property owners GOA
(CCEMC) COE Primary FI lender and secondary investor Pre-qualify contractors
Establish list of eligible projects
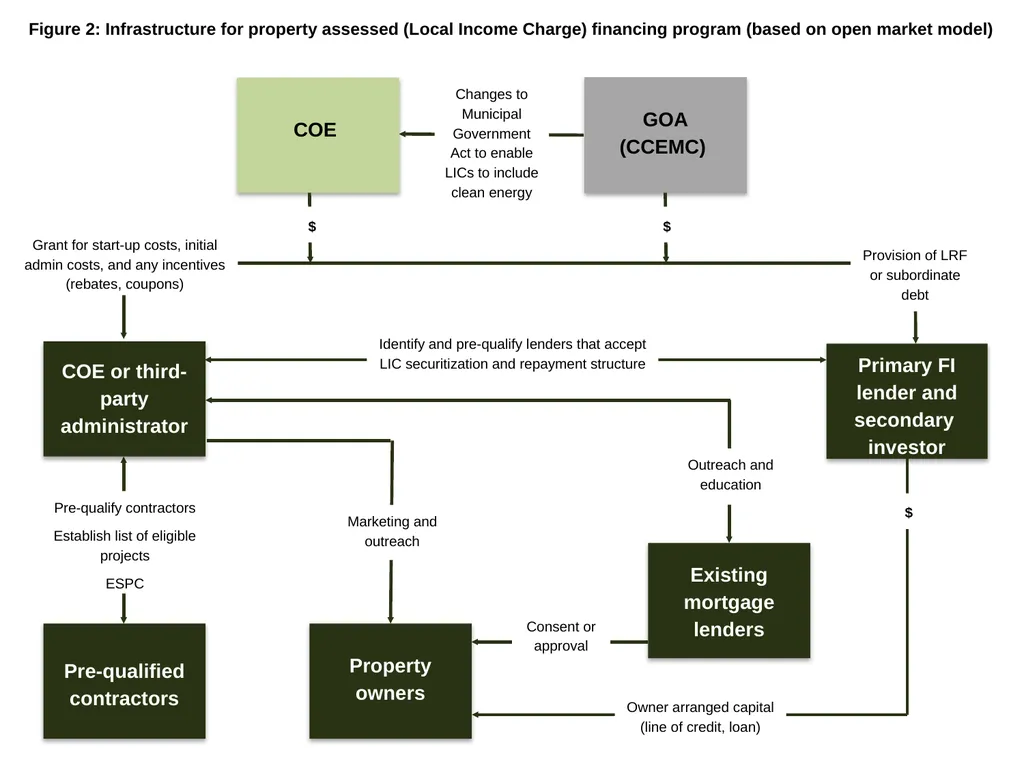
ESPC Changes to Municipal Government Act to enable LICs to include clean energy Figure 2: Infrastructure for property assessed (Local Income Charge) financing program (based on open market model) Existing mortgage lenders Consent or approval Outreach and education Identify and pre-qualify lenders that accept LIC securitization and repayment structure Provision of LRF or subordinate debt $ Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons) $ Owner arranged capital
(line of credit, loan) $<br>
(CCEMC) COE Primary FI lender and secondary investor Pre-qualify contractors
Establish list of eligible projects
ESPC Changes to Municipal Government Act to enable LICs to include clean energy Figure 2: Infrastructure for property assessed (Local Income Charge) financing program (based on open market model) Existing mortgage lenders Consent or approval Outreach and education Identify and pre-qualify lenders that accept LIC securitization and repayment structure Provision of LRF or subordinate debt $ Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons) $ Owner arranged capital
(line of credit, loan) $<br>
09
Energy savings agreement financing program<br>
10
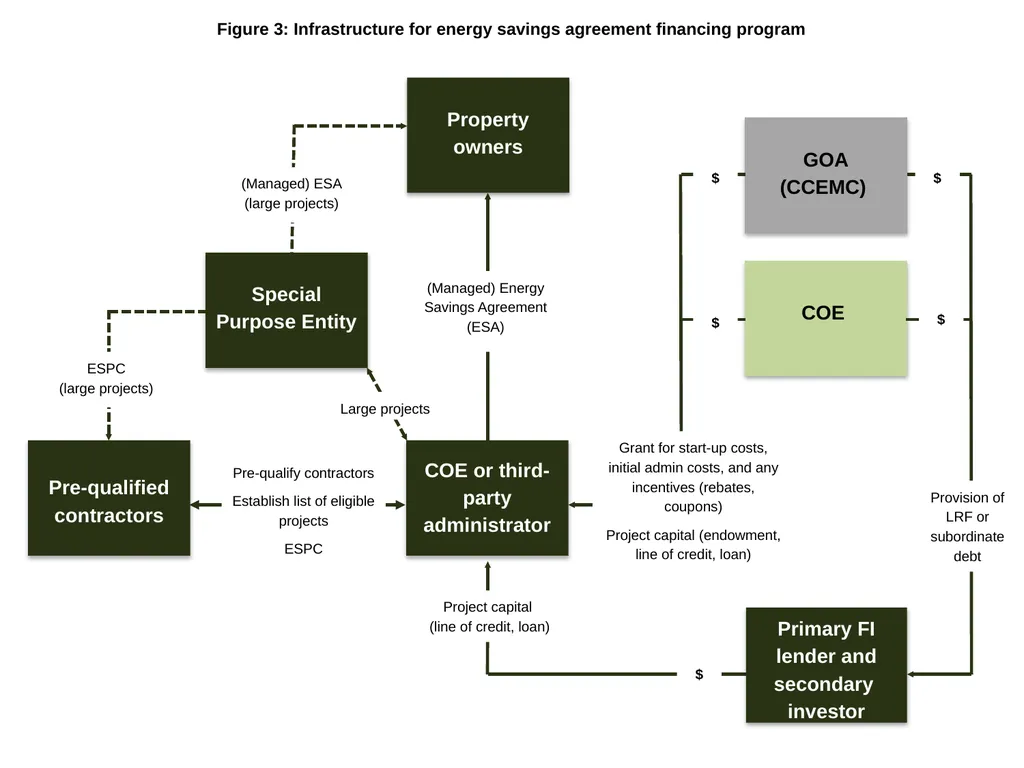
Figure 3: Infrastructure for energy savings agreement financing program Pre-qualify contractors
Establish list of eligible projects
ESPC Pre-qualified contractors Property owners COE or third-party administrator Primary FI lender and secondary investor GOA
(CCEMC) COE (Managed) Energy Savings Agreement (ESA) Special Purpose Entity Project capital
(line of credit, loan) $ ESPC
(large projects) (Managed) ESA
(large projects) Large projects $ Provision of LRF or subordinate debt Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons)
Project capital (endowment, line of credit, loan) $ $ $<br>
Establish list of eligible projects
ESPC Pre-qualified contractors Property owners COE or third-party administrator Primary FI lender and secondary investor GOA
(CCEMC) COE (Managed) Energy Savings Agreement (ESA) Special Purpose Entity Project capital
(line of credit, loan) $ ESPC
(large projects) (Managed) ESA
(large projects) Large projects $ Provision of LRF or subordinate debt Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons)
Project capital (endowment, line of credit, loan) $ $ $<br>
11
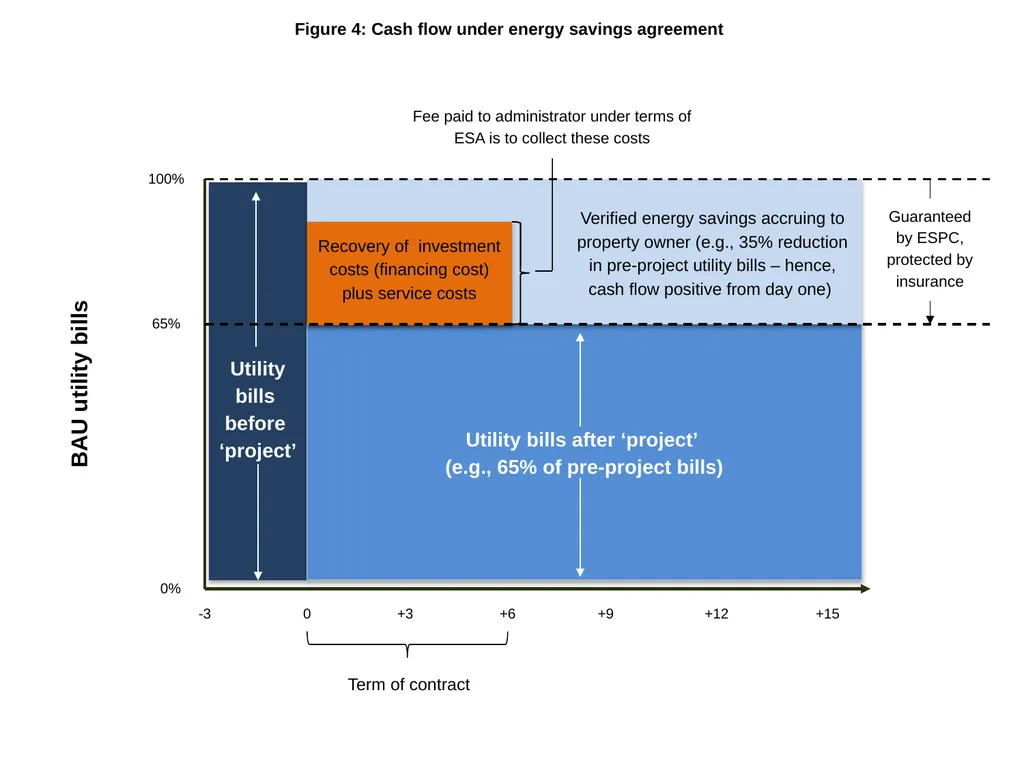
BAU utility bills -3 0 +3 +6 +9 +12 +15 0% 100% 65% Utility bills before ‘project’ Utility bills after ‘project’
(e.g., 65% of pre-project bills) Verified energy savings accruing to property owner (e.g., 35% reduction in pre-project utility bills – hence, cash flow positive from day one) Recovery of investment costs (financing cost) plus service costs Term of contract Guaranteed by ESPC, protected by insurance Fee paid to administrator under terms of ESA is to collect these costs Figure 4: Cash flow under energy savings agreement<br>
(e.g., 65% of pre-project bills) Verified energy savings accruing to property owner (e.g., 35% reduction in pre-project utility bills – hence, cash flow positive from day one) Recovery of investment costs (financing cost) plus service costs Term of contract Guaranteed by ESPC, protected by insurance Fee paid to administrator under terms of ESA is to collect these costs Figure 4: Cash flow under energy savings agreement<br>
12
On-bill tariff repayment financing program<br>
13
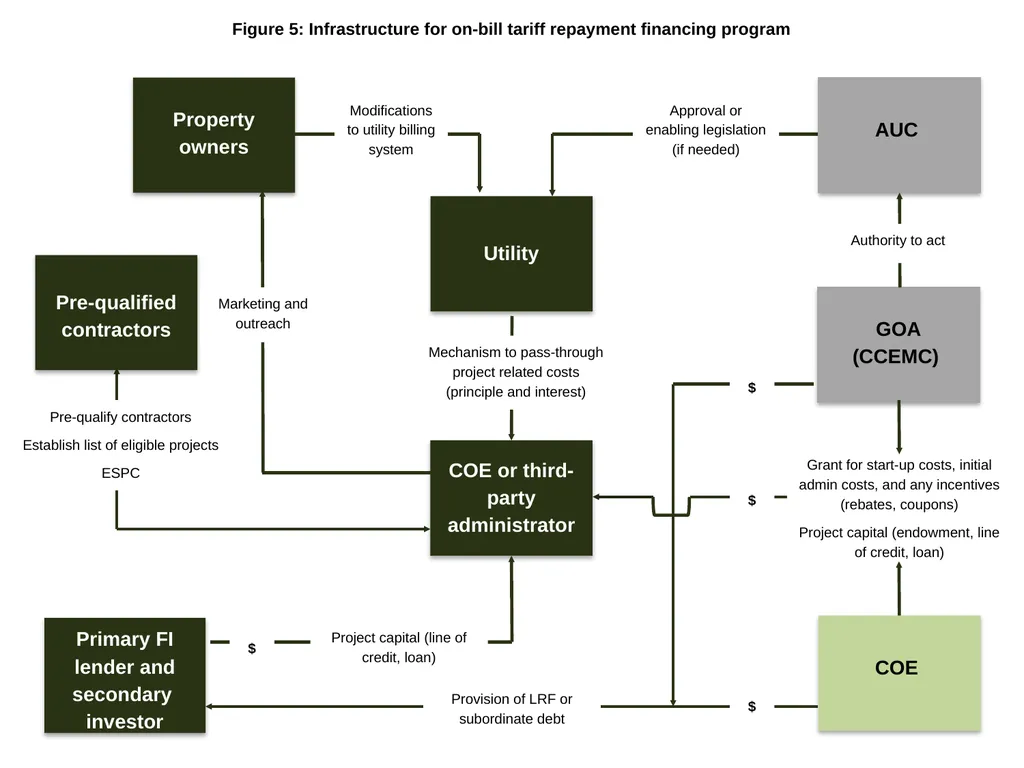
Approval or enabling legislation (if needed) COE or third-party administrator Utility Pre-qualified contractors Primary FI lender and secondary investor GOA
(CCEMC) AUC Property owners Figure 5: Infrastructure for on-bill tariff repayment financing program COE Mechanism to pass-through project related costs (principle and interest) Marketing and outreach Authority to act Modifications to utility billing system Provision of LRF or subordinate debt Project capital (line of credit, loan) Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons)
Project capital (endowment, line of credit, loan) $ $ $ $ Pre-qualify contractors
Establish list of eligible projects
ESPC<br>
(CCEMC) AUC Property owners Figure 5: Infrastructure for on-bill tariff repayment financing program COE Mechanism to pass-through project related costs (principle and interest) Marketing and outreach Authority to act Modifications to utility billing system Provision of LRF or subordinate debt Project capital (line of credit, loan) Grant for start-up costs, initial admin costs, and any incentives (rebates, coupons)
Project capital (endowment, line of credit, loan) $ $ $ $ Pre-qualify contractors
Establish list of eligible projects
ESPC<br>
14
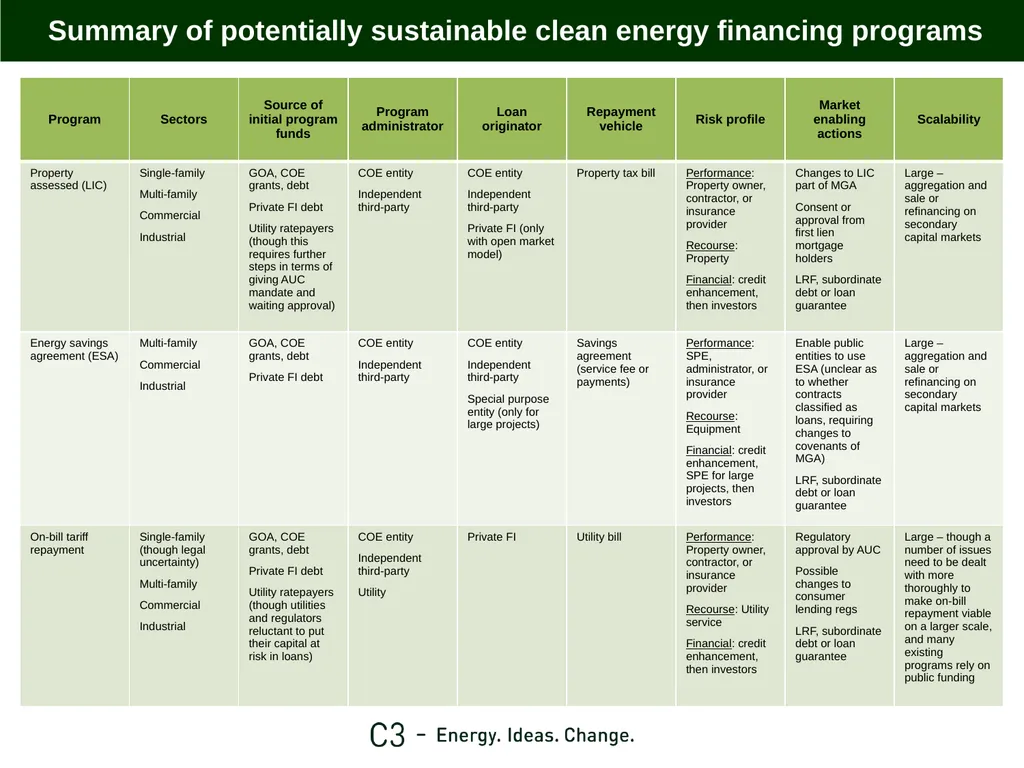
Summary of potentially sustainable clean energy financing programs<br>
15
Dr Richard Boyd
Senior Economist, Research and Analysis
Email: rboyd@c-3.ca
Direct 403.517.2702 Contact details<br>
Senior Economist, Research and Analysis
Email: rboyd@c-3.ca
Direct 403.517.2702 Contact details<br>