Extended Auditors Reports and Audit Quality: A Textual Analysis Penny Zhang Greg Shailer Background Motivation Regulatory Background FRC (reporting periods ending on or after 30th Sep, 2013, for entities that report on application of the
"Extended Auditor's Reports and Audit Quality: A" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
Extended Auditor's Reports and Audit Quality: A Textual Analysis Penny Zhang
Greg Shailer<br>
02
Background & Motivation Regulatory Background
FRC (reporting periods ending on or after 30th Sep, 2013, for entities that report on application of the UK Corporate Governance Code)
PCAOB, IAASB, and EC
Disclose the most significant audit matters in that year’s financial statement audit, using non-standardised language.
These enhanced reporting standards are intended to make audit reports more transparent as they induce differentiations among auditor reports (PCAOB 2016). 2<br>
03
Background & Motivation The use of tailored, non-standardized language when discussing material risks of the audited entity is key to achieving the objectives of EARs (FRC, 2013; IAASB, 2013; PCAOB, 2013)
We examine how the use of standardized disclosures in EARs relates to audit quality at the engagement level (after adjusting for the industry-based comparability effects) 3<br>
04
Research Approach Textual similarities of EARs are expected to be negatively associated with audit quality
Generic disclosures may be intentionally chosen by auditors to reduce transparency
Standardized language may be a consequence of deficiencies in audit effort or competence 4<br>
05
Research Approach The UK’s first three implementation years (from 30/09/2013 to 30/09/2016)
The textual similarities of EARs are measured using the Vector Space Model (VSM).
Mean scores of that EAR relative to each of the other EARs issued by the same audit firm in each year.
KAM sub-sections & full EARs 5<br>
06
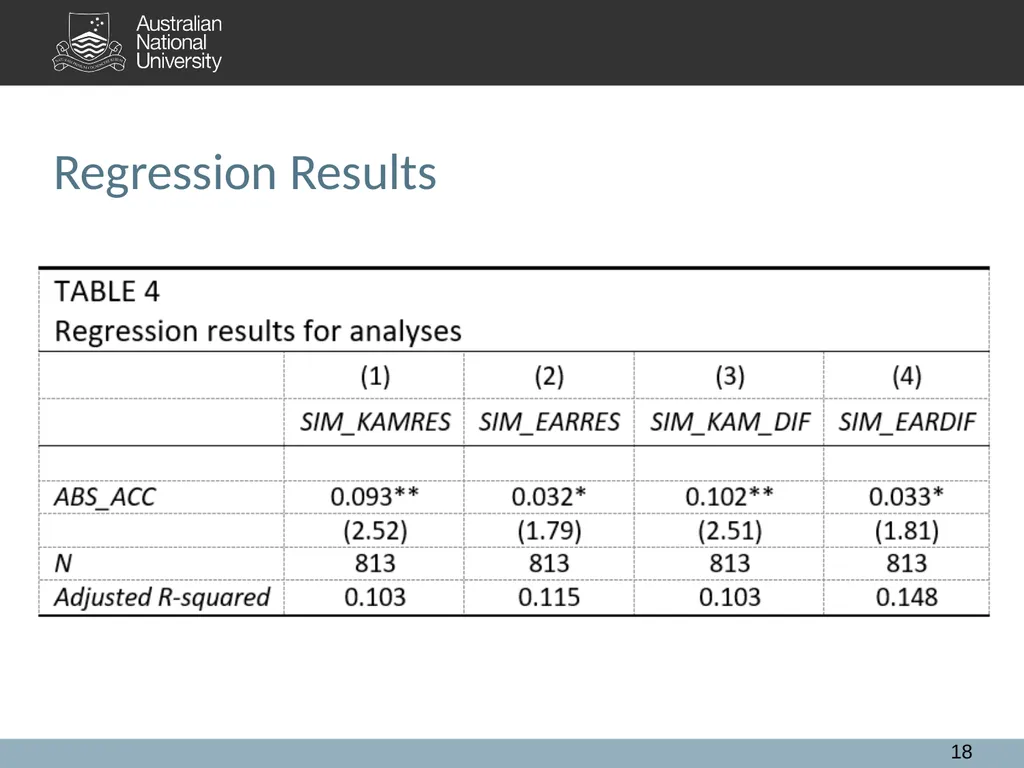
Findings EAR similarity scores are negatively associated with audit quality, measured as abnormal accruals and abnormal audit fees.
The relation is more significant when examining KAM sub-sections, compared to the analysis of full EARs.
Our results suggest that, on average, engagements with higher audit quality result in more transparent EARs. 6<br>
07
Related Studies of EARs AUDIT QUALITY
Gutierrez et al. (2018)
Non-significant result
Reid et al. (2018)
The absolute abnormal accruals and the likelihood of just meeting or beating analyst forecasts were improved following the implementation of EARs.
TEXTUAL ANALYSIS
Smith (2017)
Auditors with industry expertise, from Big4 accounting firms and larger offices produce more readable EARs. 7<br>
08
Related Studies on Report Transparency Managers choose to provide less transparent disclosures to reduce the detection of their earnings management
Accruals-based earnings management is negatively associated with
Corporate disclosure quality (Lobo & Zhou 2001)
Specific accrual-related disclosure transparency (Cassell et al. 2015) 8<br>
09
Hypothesis Development Reports that use more standardised language and so convey less firm-specific information are with lower disclosure transparency.
Preparers prefer less transparency to avoid revealing the quality of the underlying performance (Cassell et al. 2015; Hunton et al. 2006; Tucker 2015)
Auditors may seek to avoid transparency for engagements that have lower audit quality by using more standardised EARs. 9<br>
10
Similarities across EARs may arise from deficiencies in auditors’ effort or competence.
If an auditor pays insufficient attention to, or has insufficient understanding of entity-specific issues
Hypothesis: Textual similarity in extended auditor’s reports is negatively associated with audit quality. 10 Hypothesis Development<br>
11
Measurement of EAR Similarities 11<br>
12
Measurement of EAR similarities KAM Similarityi,j score and EAR Similarityi,j score are computed for each pair of companies in an audit firm’s portfolio in a given year
Base SIM score is the average of its relevant Similarity scores in relation to all other (n-1) companies in the same audit firm (of n companies) in a given year 12<br>
13
Adjust for industry-based comparability effects
“Unlike things look alike” vs “Like things look alike”
Ind SIMKAM and Ind SIMEAR adjustments applied to each company’s Base SIMKAM or Base SIMEAR is calculated using the same procedure
The defined set of documents - Auditor-industry-year 13 Adjustments for Base Similarity Scores<br>
14
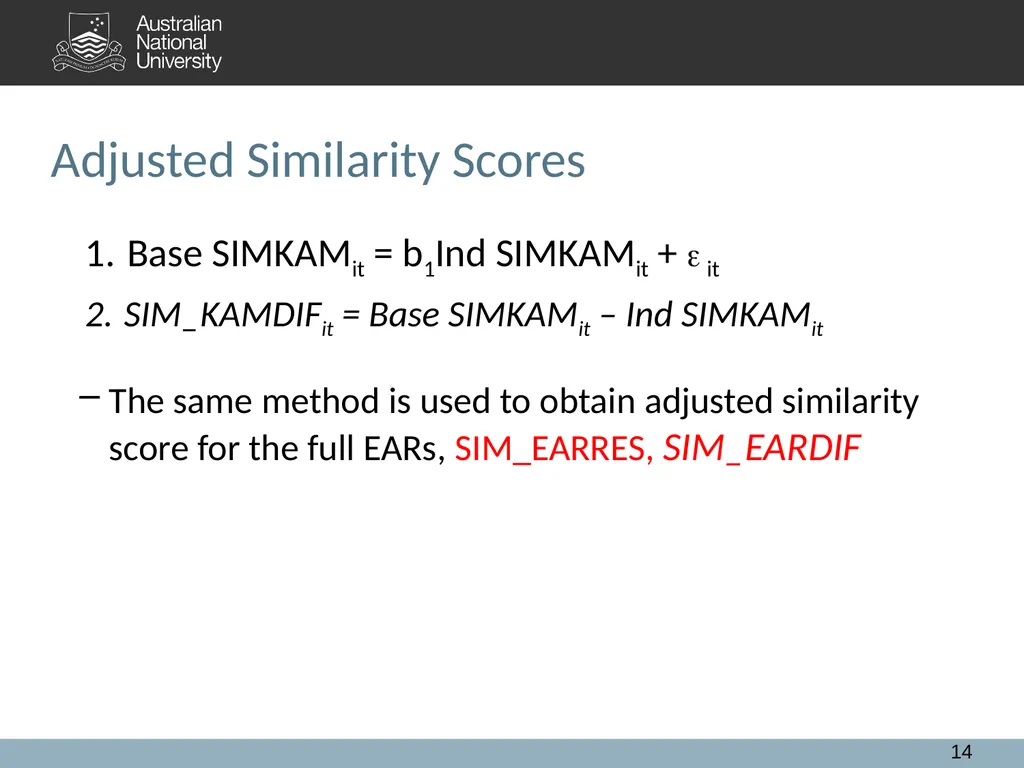
Base SIMKAMit = b1Ind SIMKAMit + it
SIM_KAMDIFit = Base SIMKAMit – Ind SIMKAMit
The same method is used to obtain adjusted similarity score for the full EARs, SIM_EARRES, SIM_EARDIF 14 Adjusted Similarity Scores<br>
15
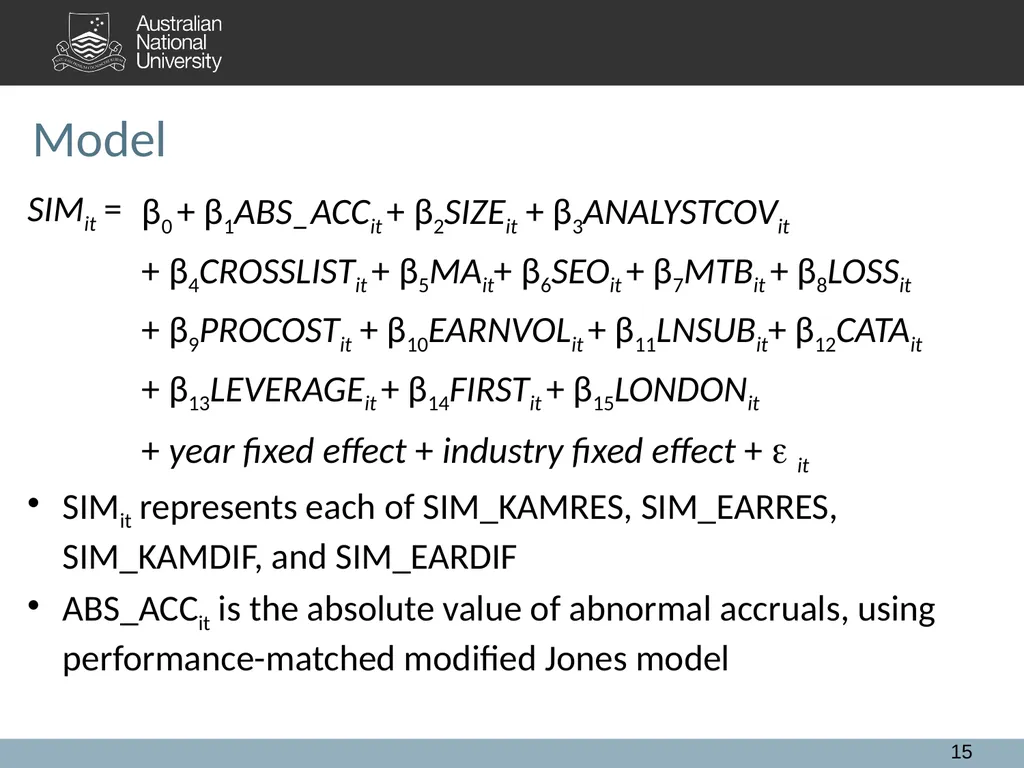
Model 15 SIMit =
SIMit represents each of SIM_KAMRES, SIM_EARRES, SIM_KAMDIF, and SIM_EARDIF
ABS_ACCit is the absolute value of abnormal accruals, using performance-matched modified Jones model β0 + β1ABS_ACCit + β2SIZEit + β3ANALYSTCOVit
+ β4CROSSLISTit + β5MAit+ β6SEOit + β7MTBit + β8LOSSit
+ β9PROCOSTit + β10EARNVOLit + β11LNSUBit+ β12CATAit
+ β13LEVERAGEit + β14FIRSTit + β15LONDONit
+ year fixed effect + industry fixed effect + it<br>
16
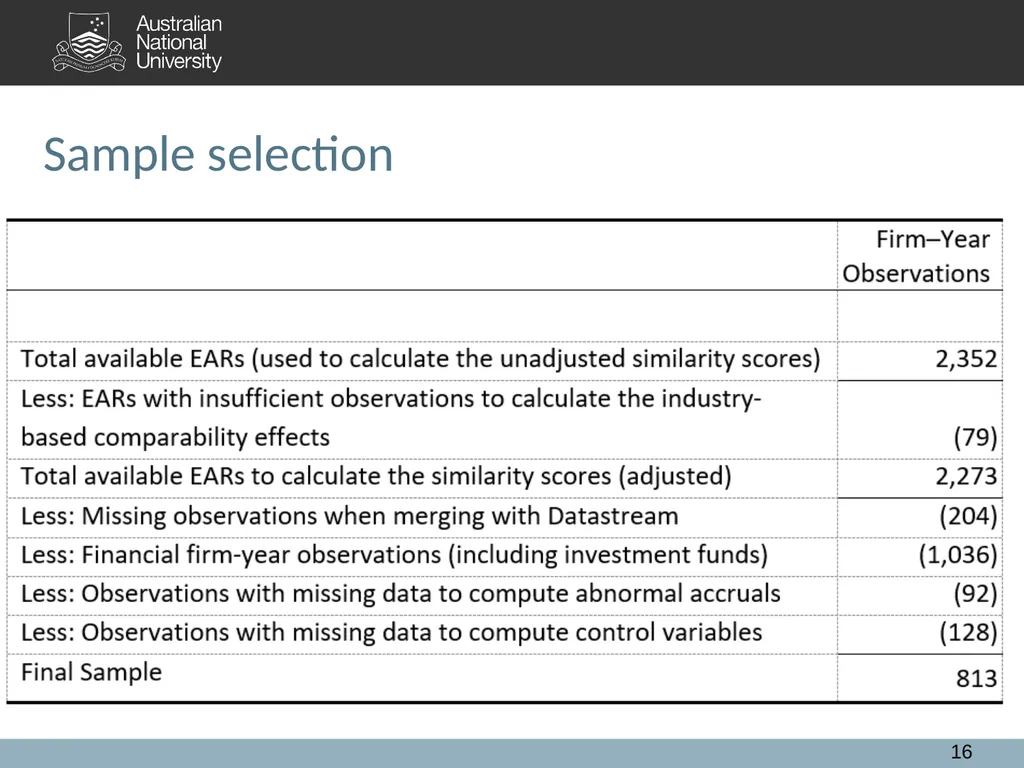
16 Sample selection<br>
17
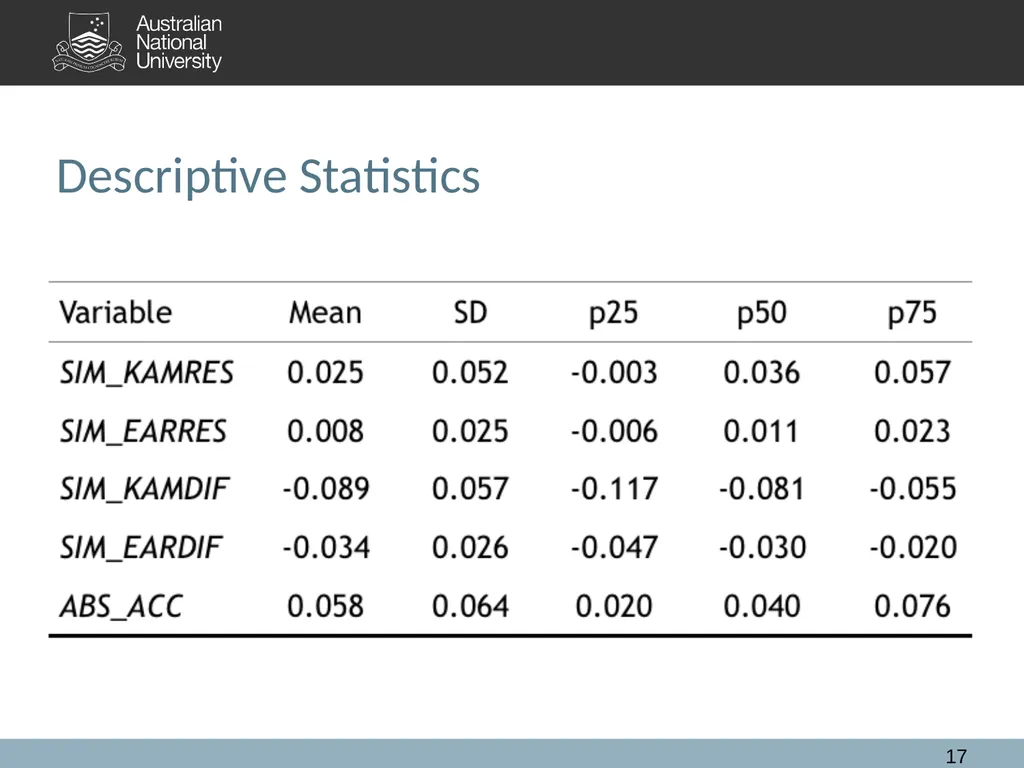
Descriptive Statistics 17<br>
18
18 Regression Results<br>
19
Robustness Tests Alternative Measures of EAR Similarity TF-IDF
IDF is computed as log(N/nm)
where N is the number of total documents included in the sample and n is the number of documents containing word m.
TF-IDF weighting gives larger weights to words used less frequently in the collection of EARs, and lesser weights to common words 19<br>
20
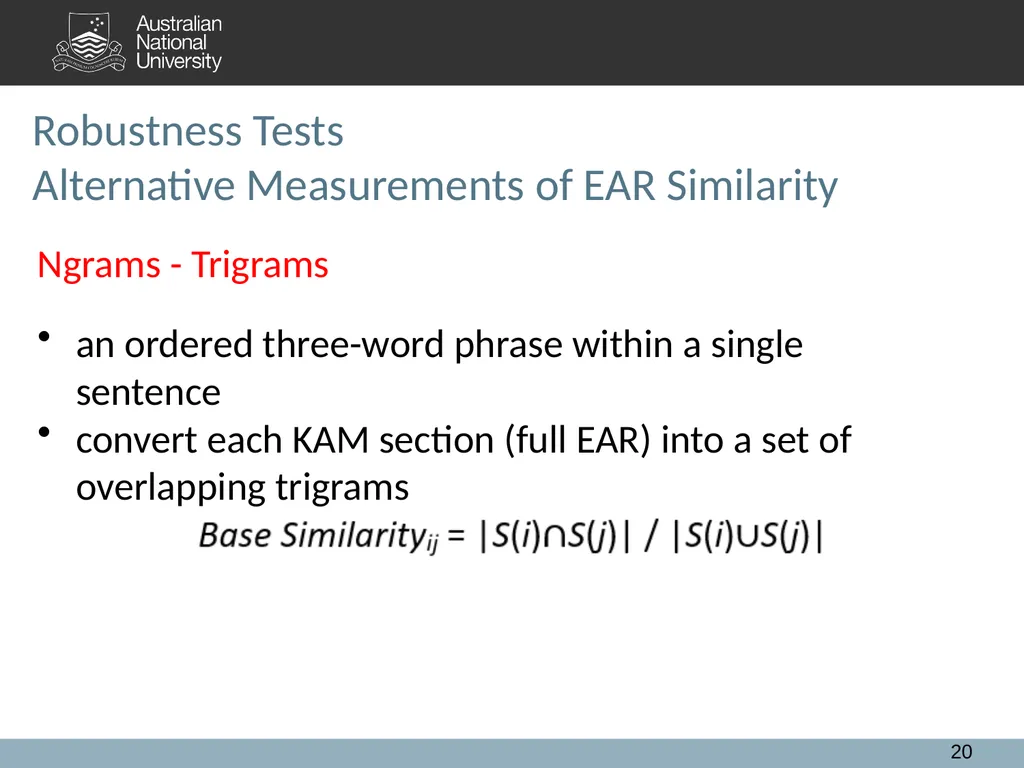
Ngrams - Trigrams
an ordered three-word phrase within a single sentence
convert each KAM section (full EAR) into a set of overlapping trigrams 20 Robustness Tests Alternative Measurements of EAR Similarity<br>
21
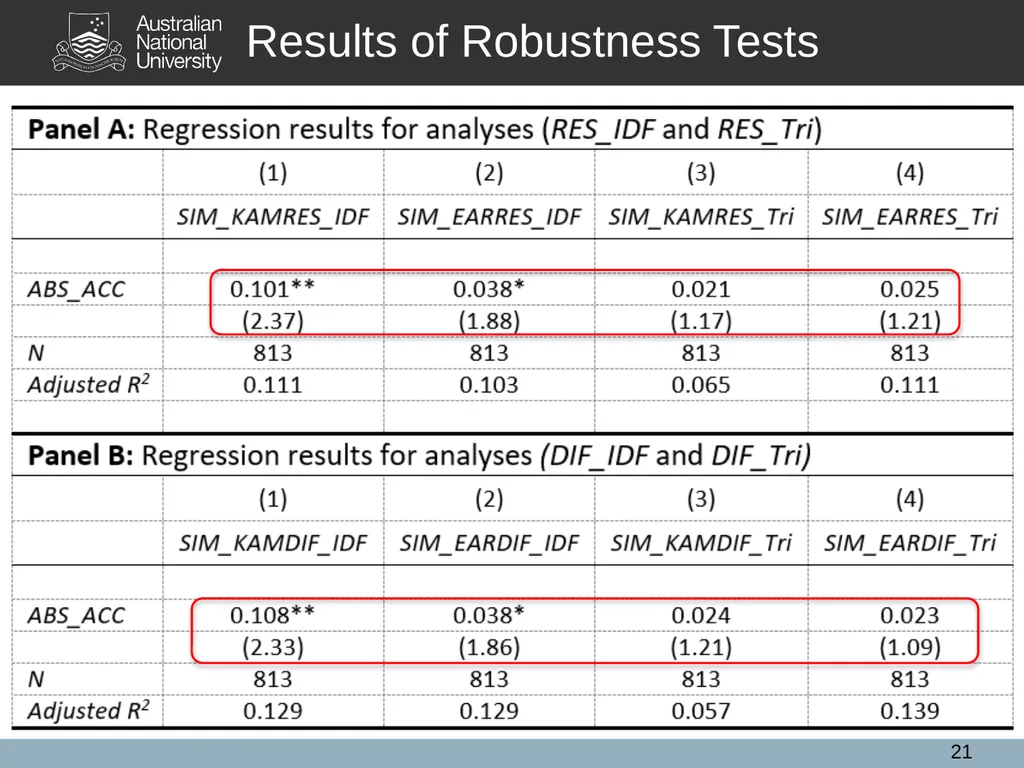
21 Results of Robustness Tests<br>
22
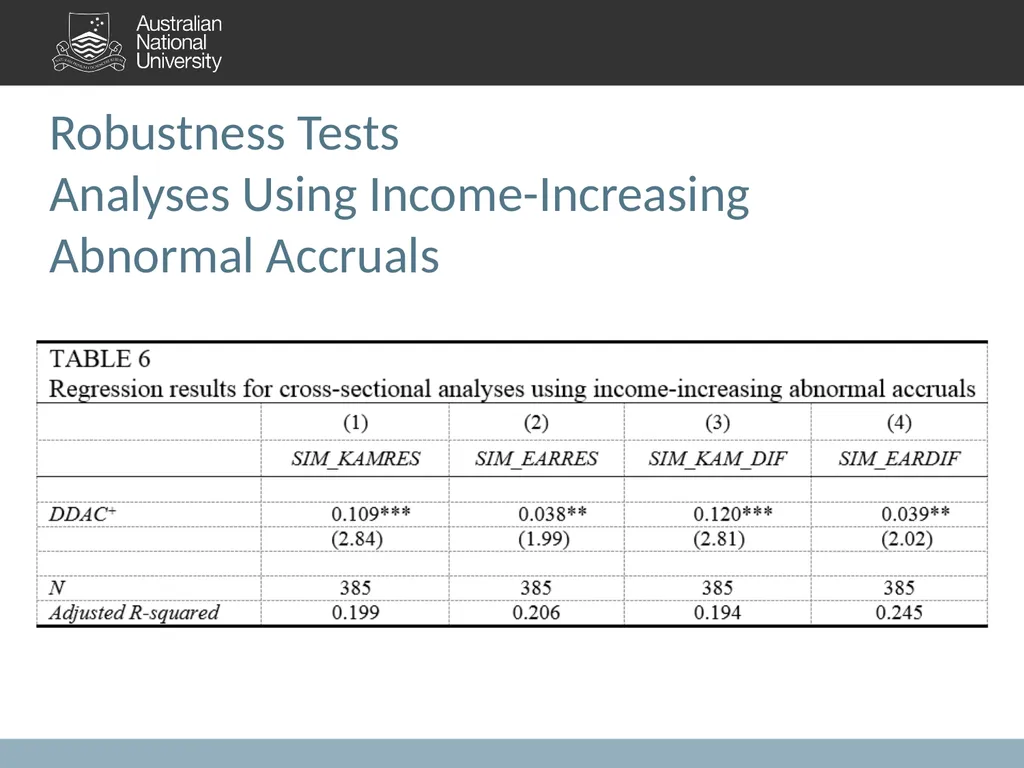
Robustness Tests Analyses Using Income-Increasing Abnormal Accruals<br>
23
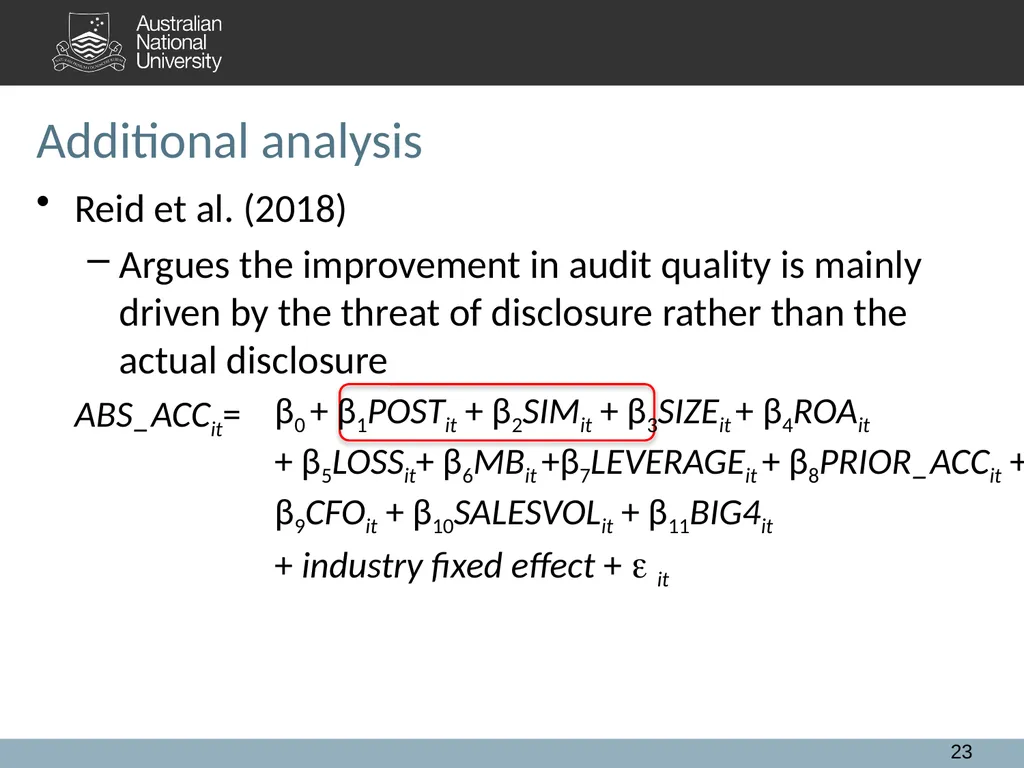
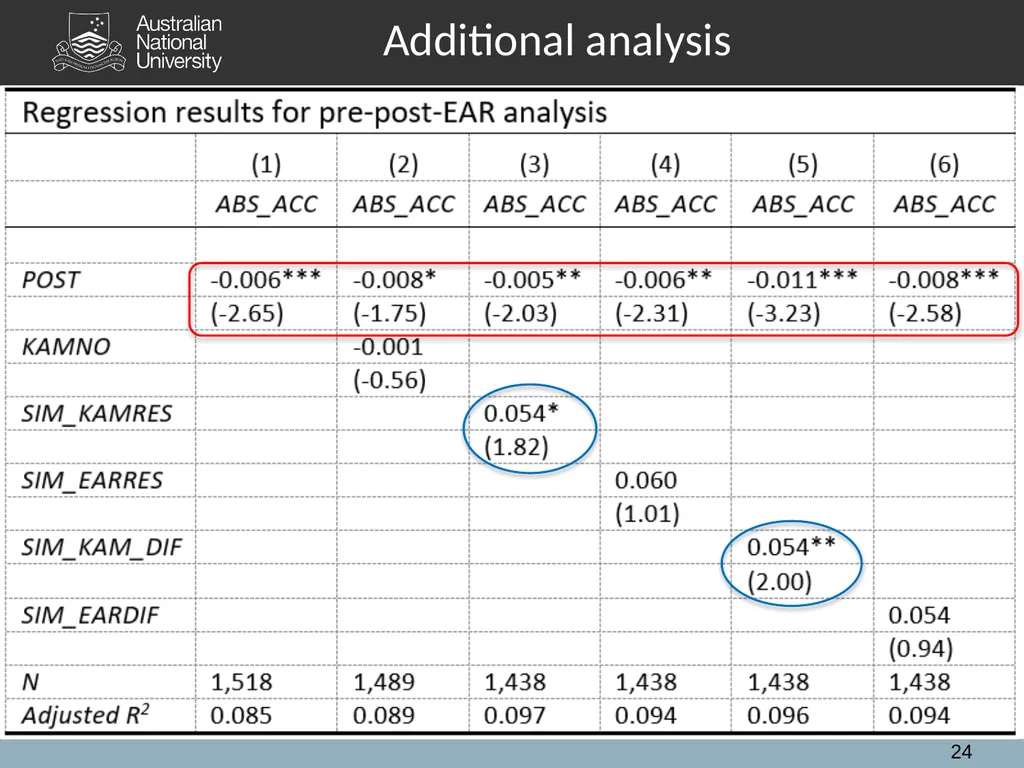
Additional analysis Reid et al. (2018)
Argues the improvement in audit quality is mainly driven by the threat of disclosure rather than the actual disclosure
ABS_ACCit= 23 β0 + β1POSTit + β2SIMit + β3SIZEit + β4ROAit
+ β5LOSSit+ β6MBit +β7LEVERAGEit + β8PRIOR_ACCit + β9CFOit + β10SALESVOLit + β11BIG4it
+ industry fixed effect + it<br>
24
Additional analysis 24<br>
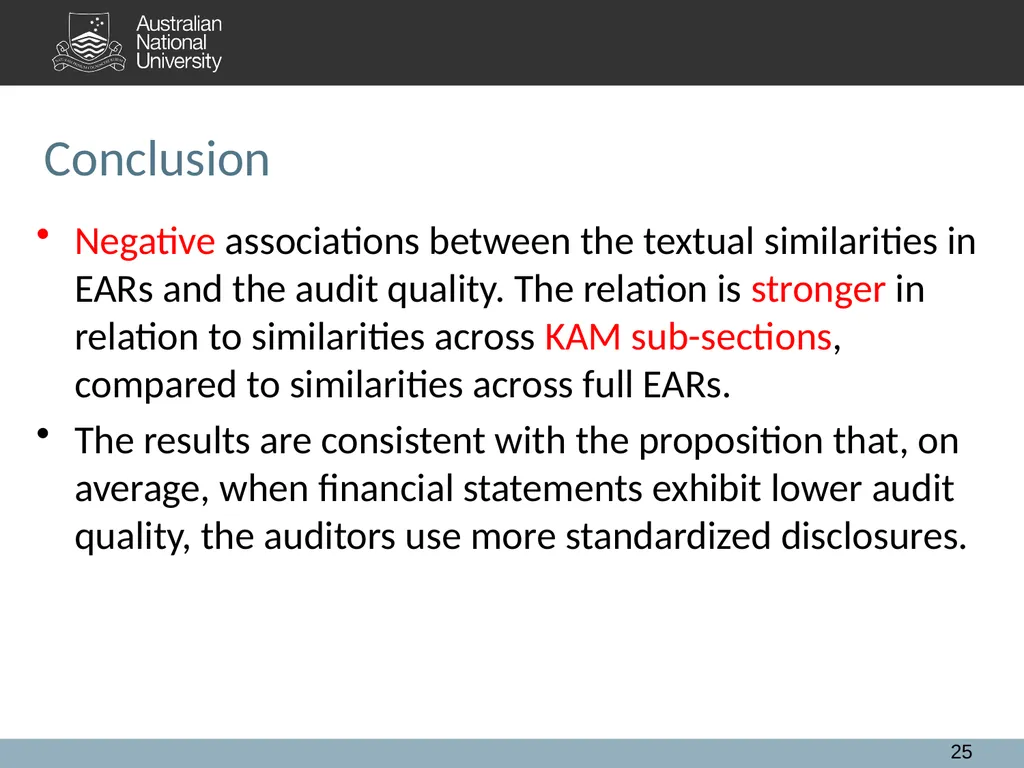
25
Conclusion Negative associations between the textual similarities in EARs and the audit quality. The relation is stronger in relation to similarities across KAM sub-sections, compared to similarities across full EARs.
The results are consistent with the proposition that, on average, when financial statements exhibit lower audit quality, the auditors use more standardized disclosures. 25<br>
26
Contributions Policy Development
Standard setters in other jurisdictions better understand the potential impact of the revised auditing standard.
Audit Research Literature
Extends the textual analysis literature to audit reports
Differences in auditors’ reporting behaviours and relate these to differences in audit quality across engagements. 26<br>
27
Conclusion Whether the observed relation is a consequence of auditors intentionally reducing transparency, auditor effort or competence, or yet to be discovered factors requires further research.
Whether this applies to later adopters of EARs also requires further research. 27<br>