
Financial Statements Literacy September 19, 2018

Description: Financial Statements Literacy September 19, 2018 Financial Audit and Review Services Tax Services SOX Compliance and Internal Controls Employee Benefit Plan Audit Services IT Risk Compliance Advisory Holtzman Partners LLP Agenda Financial
Related Topics
Download Presentation
"Financial Statements Literacy September 19, 2018" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Financial Statements Literacy
September 19, 2018<br>
slide2. Financial Audit and Review Services
Tax Services
SOX Compliance and Internal Controls
Employee Benefit Plan Audit Services
IT Risk & Compliance
Advisory Holtzman Partners LLP<br>
slide3. Agenda Financial Statement Overview
Financial Statement Analysis
Financial Statement Ratios and Other Performance Measures
Upcoming changes to Not-for-Profit Accounting
Auditor Involvement<br>
slide4. Financial Statement Overview<br>
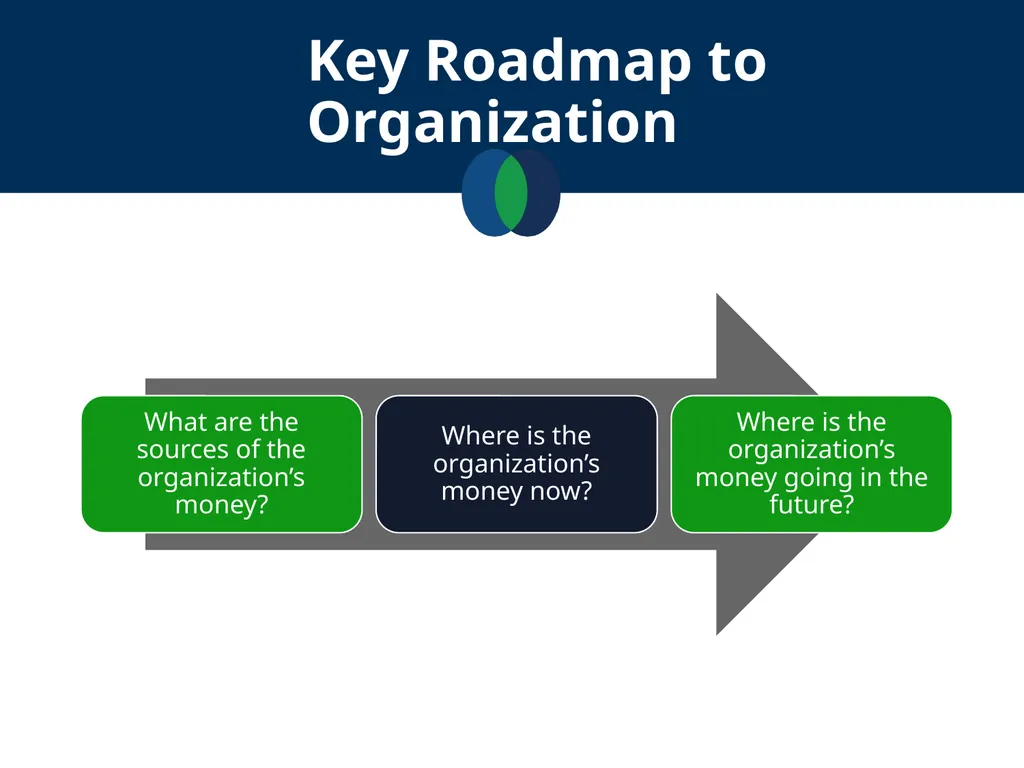
slide5. Key Roadmap to Organization<br>
slide6. Primary Financial Statements Basic financial statements:
Statement of Net Assets
Statement of Activities
Statement of Cash Flows<br>
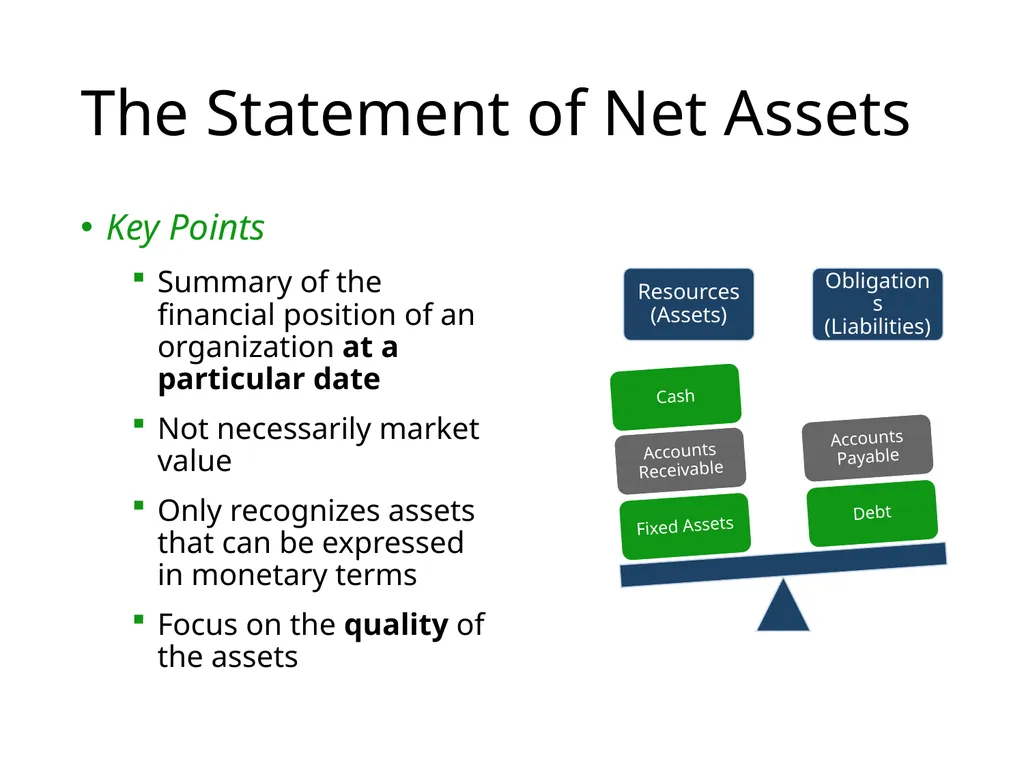
slide7. The Statement of Net Assets Key Points
Summary of the financial position of an organization at a particular date
Not necessarily market value
Only recognizes assets that can be expressed in monetary terms
Focus on the quality of the assets<br>
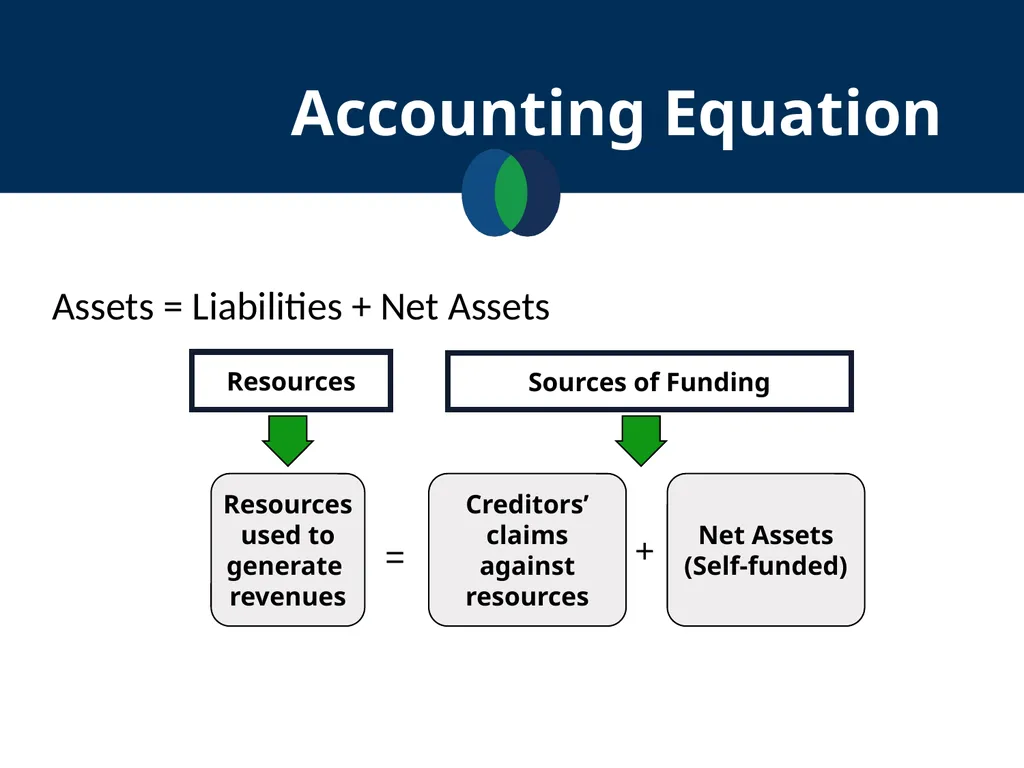
slide8. Accounting Equation Assets = Liabilities + Net Assets Sources of Funding Creditors’
claims
against
resources = + Net Assets
(Self-funded) Resources Resources
used to
generate
revenues<br>
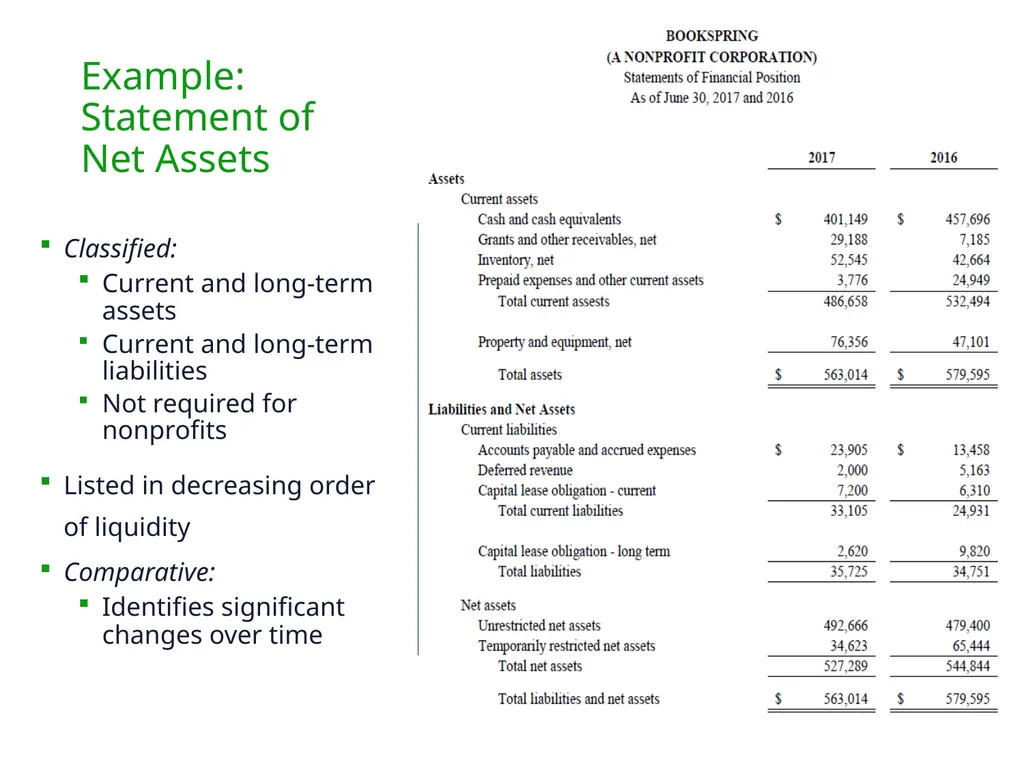
slide9. Example: Statement of Net Assets Classified:
Current and long-term assets
Current and long-term liabilities
Not required for nonprofits
Listed in decreasing order of liquidity
Comparative:
Identifies significant changes over time<br>
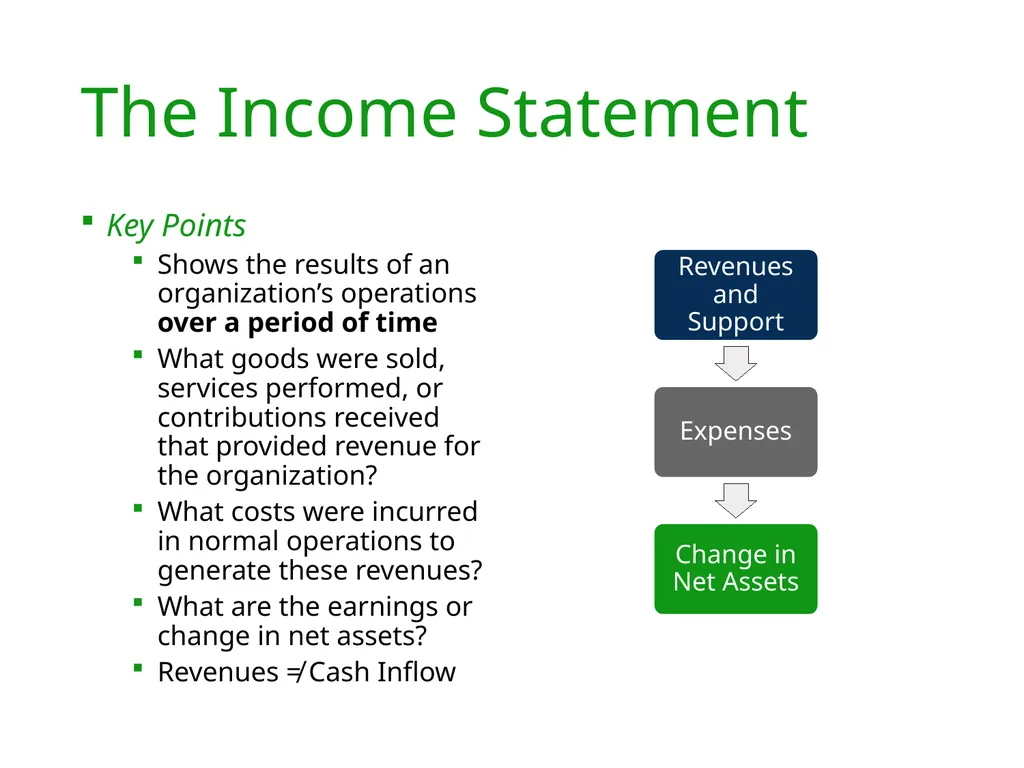
slide10. The Income Statement Key Points
Shows the results of an organization’s operations over a period of time
What goods were sold, services performed, or contributions received that provided revenue for the organization?
What costs were incurred in normal operations to generate these revenues?
What are the earnings or change in net assets?
Revenues ≠ Cash Inflow<br>
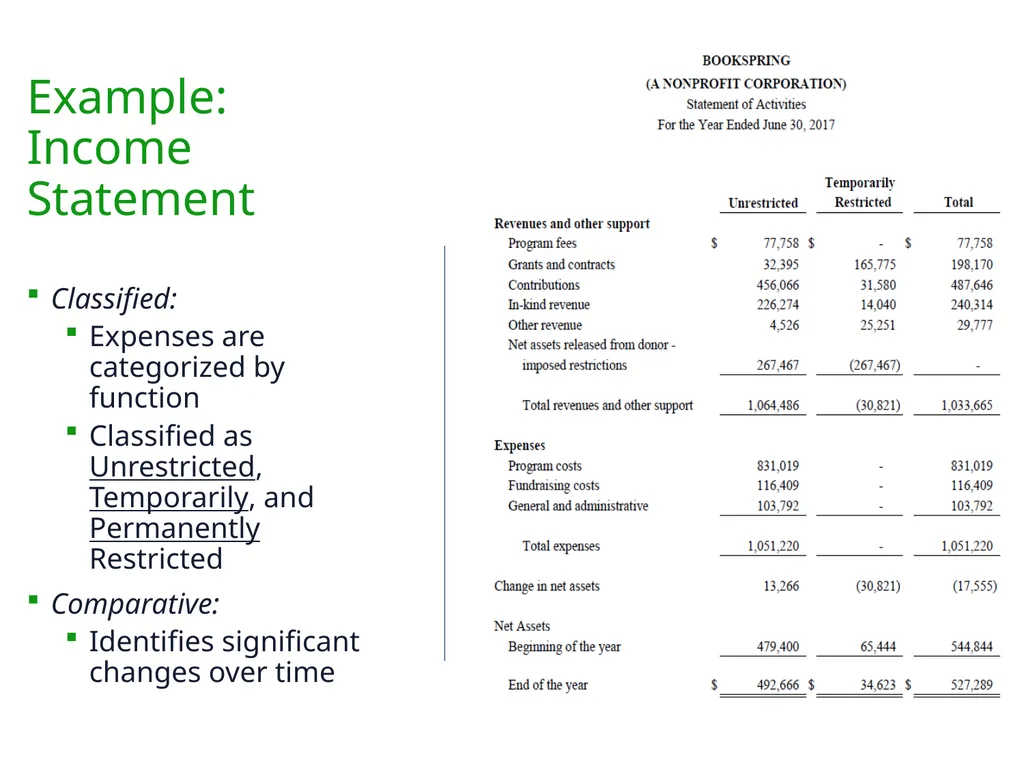
slide11. Example: Income Statement Classified:
Expenses are categorized by function
Classified as Unrestricted, Temporarily, and Permanently Restricted
Comparative:
Identifies significant changes over time<br>
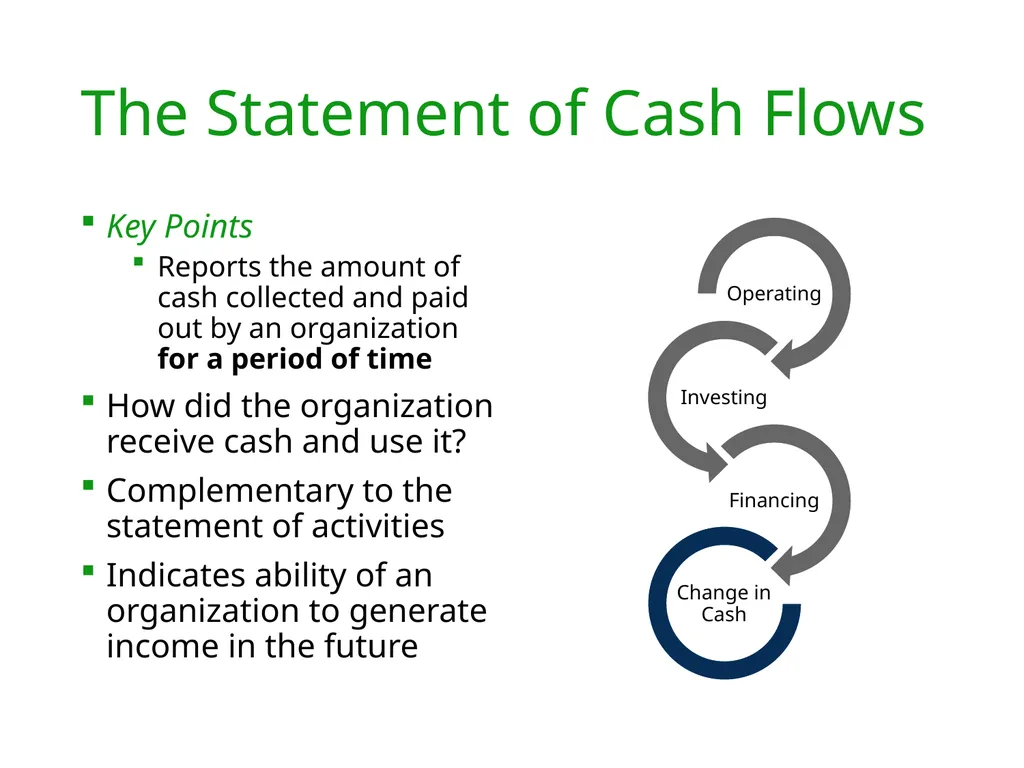
slide12. The Statement of Cash Flows Key Points
Reports the amount of cash collected and paid out by an organization for a period of time
How did the organization receive cash and use it?
Complementary to the statement of activities
Indicates ability of an organization to generate income in the future<br>
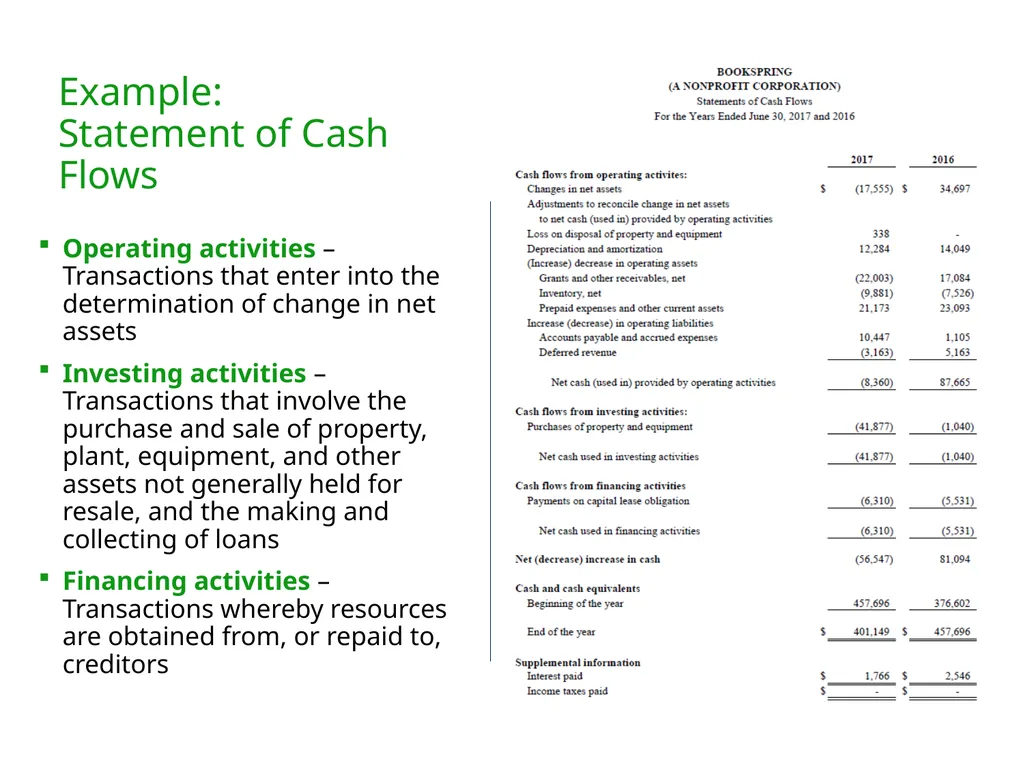
slide13. Example: Statement of Cash Flows Operating activities – Transactions that enter into the determination of change in net assets
Investing activities – Transactions that involve the purchase and sale of property, plant, equipment, and other assets not generally held for resale, and the making and collecting of loans
Financing activities – Transactions whereby resources are obtained from, or repaid to, creditors<br>
slide14. Statement of Functional Expenses Key Points
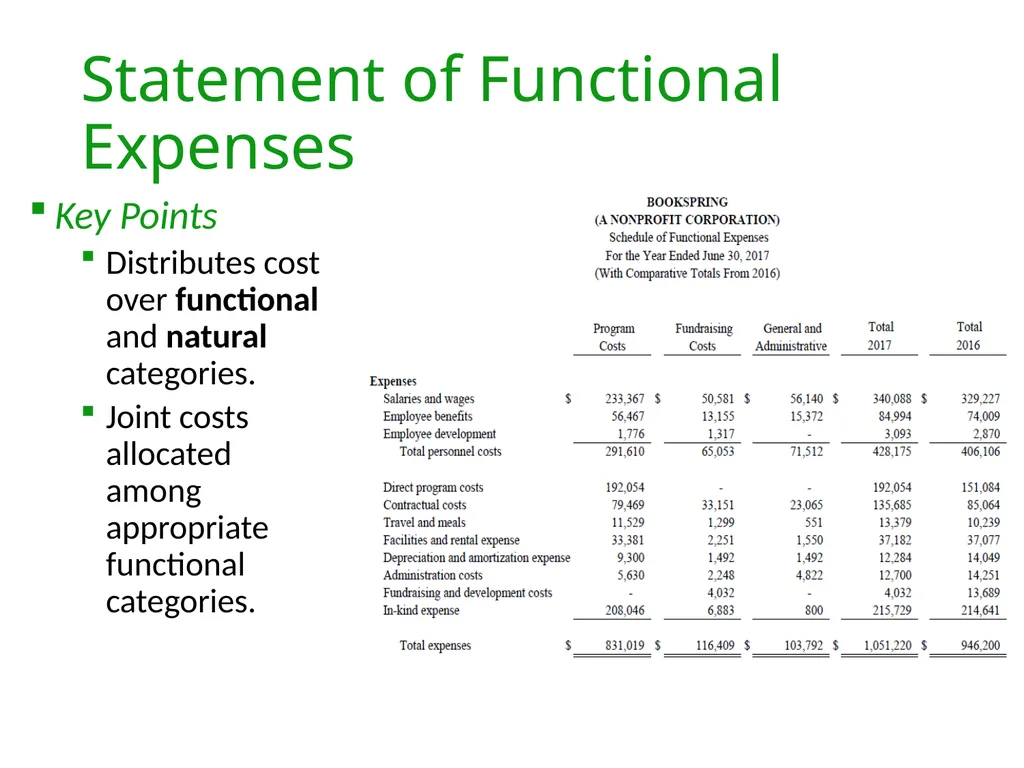
Distributes cost over functional and natural categories.
Joint costs allocated among appropriate functional categories.<br>
slide15. Notes to the Financial Statements Disclosure of important information that is not shown on the face of the financial statements
Additional information behind the summary totals
Supplementary information required by the FASB<br>
slide16. Financial Statement Analysis<br>
slide17. Financial Statement Preparation Organizations require periodic, timely reporting
U.S. GAAP most common method of accounting
Financial Accounting Standards Board (FASB) continually monitors and updates GAAP GAAP = Generally Accepted Accounting Principles<br>
slide18. Be Aware! Different accounting methods often produce radically different results
U.S. GAAP vs. IFRS
Accrual Basis vs. Cash Basis
Governmental Accounting Standards IFRS = International Financial Reporting Standards<br>
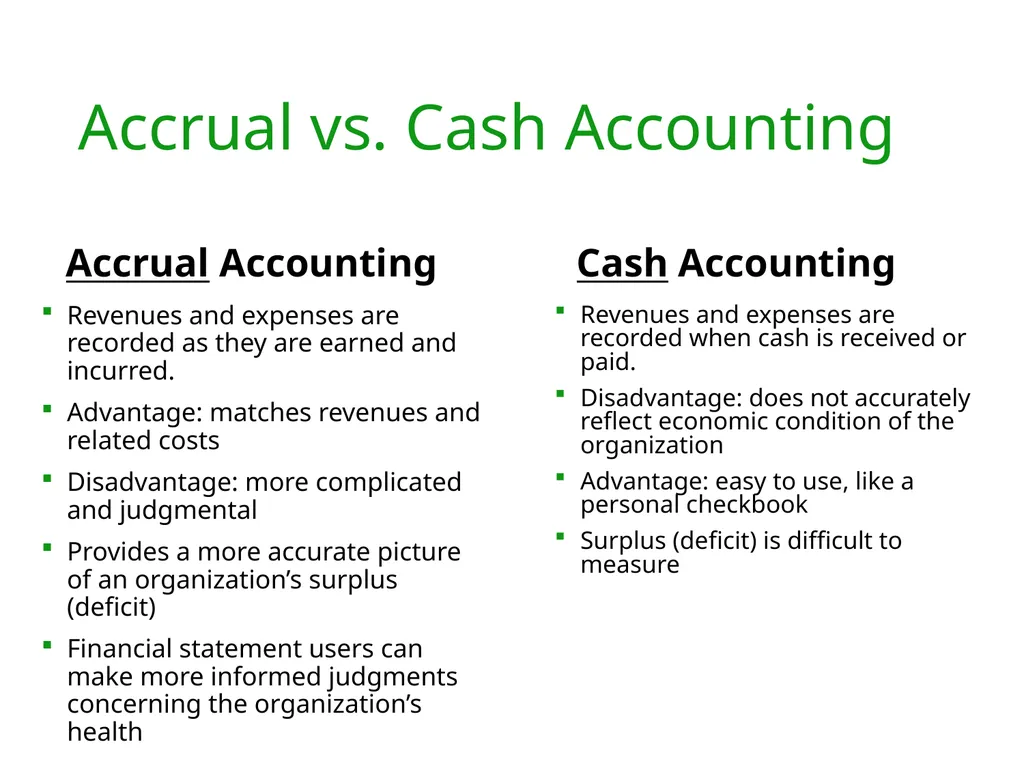
slide19. Accrual vs. Cash Accounting Accrual Accounting Revenues and expenses are recorded as they are earned and incurred.
Advantage: matches revenues and related costs
Disadvantage: more complicated and judgmental
Provides a more accurate picture of an organization’s surplus (deficit)
Financial statement users can make more informed judgments concerning the organization’s health Cash Accounting Revenues and expenses are recorded when cash is received or paid.
Disadvantage: does not accurately reflect economic condition of the organization
Advantage: easy to use, like a personal checkbook
Surplus (deficit) is difficult to measure<br>
slide20. Financial Statement Ratios and Other Performance Measures<br>
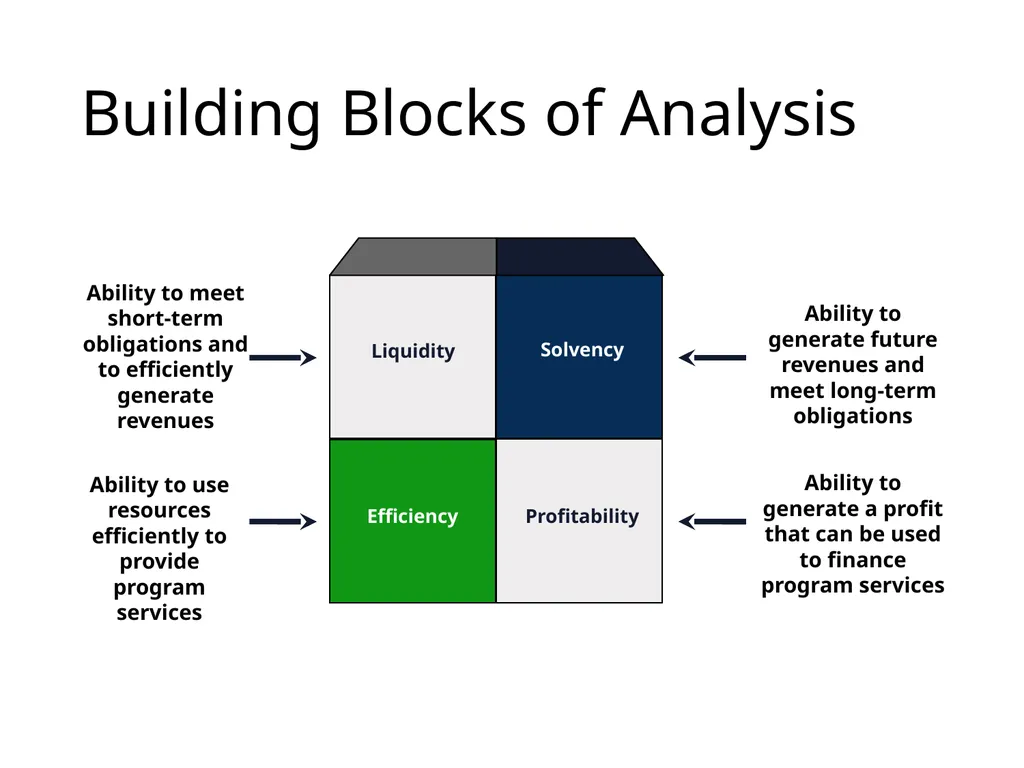
slide21. Profitability Ability to meet short-term obligations and to efficiently generate revenues Ability to generate future revenues and meet long-term obligations Ability to generate a profit that can be used to finance program services Ability to use resources efficiently to provide program services Building Blocks of Analysis<br>
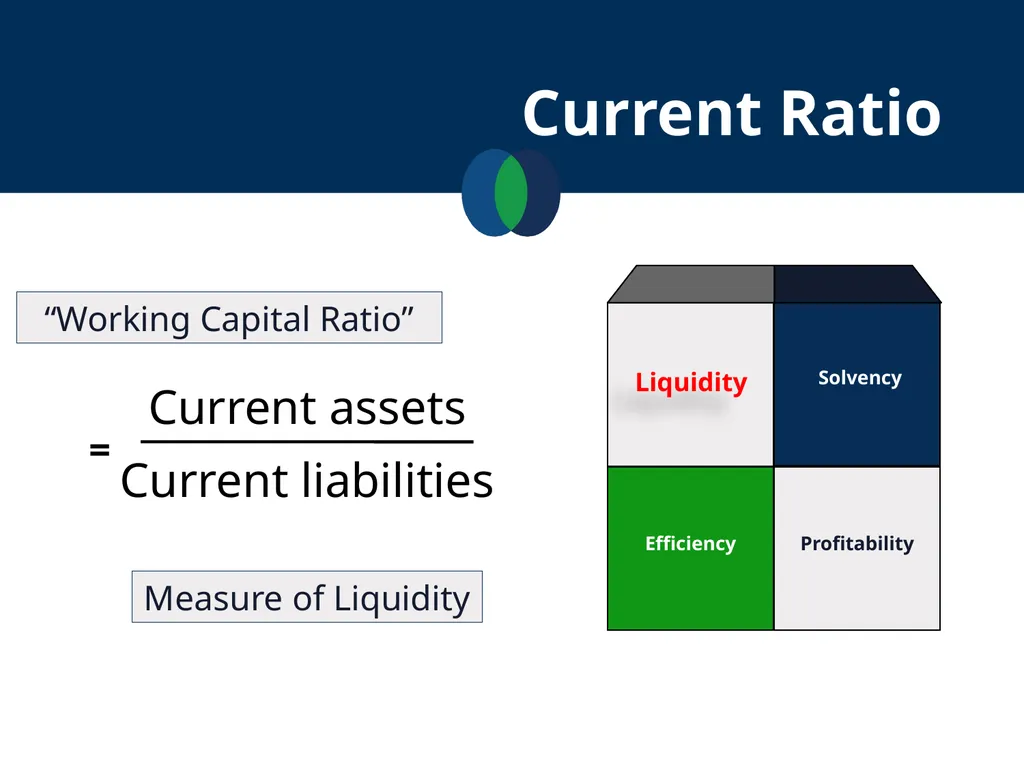
slide22. Current Ratio Measure of Liquidity “Working Capital Ratio” Profitability<br>
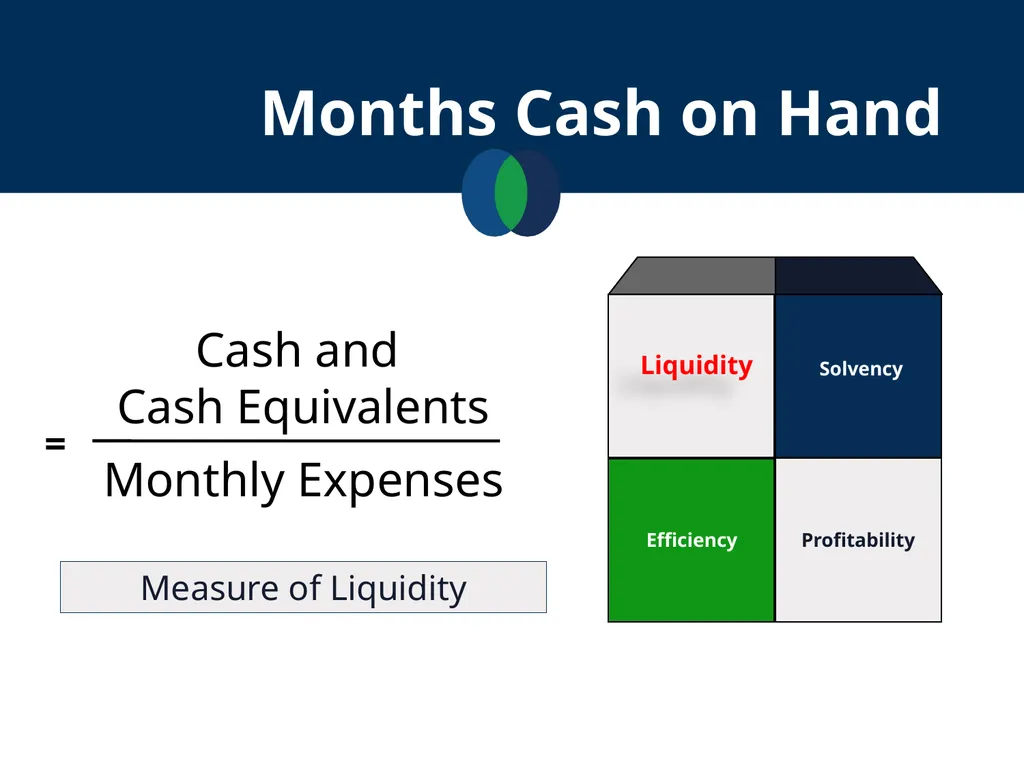
slide23. Months Cash on Hand Measure of Liquidity Profitability Liquidity<br>
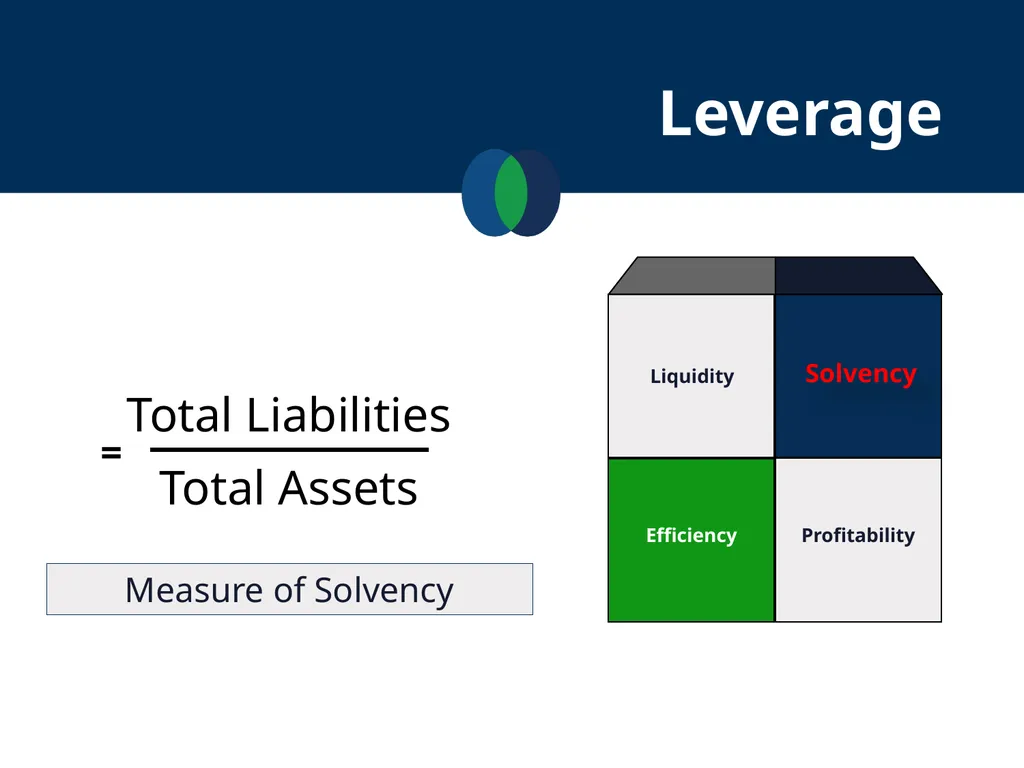
slide24. Leverage Measure of Solvency Profitability<br>
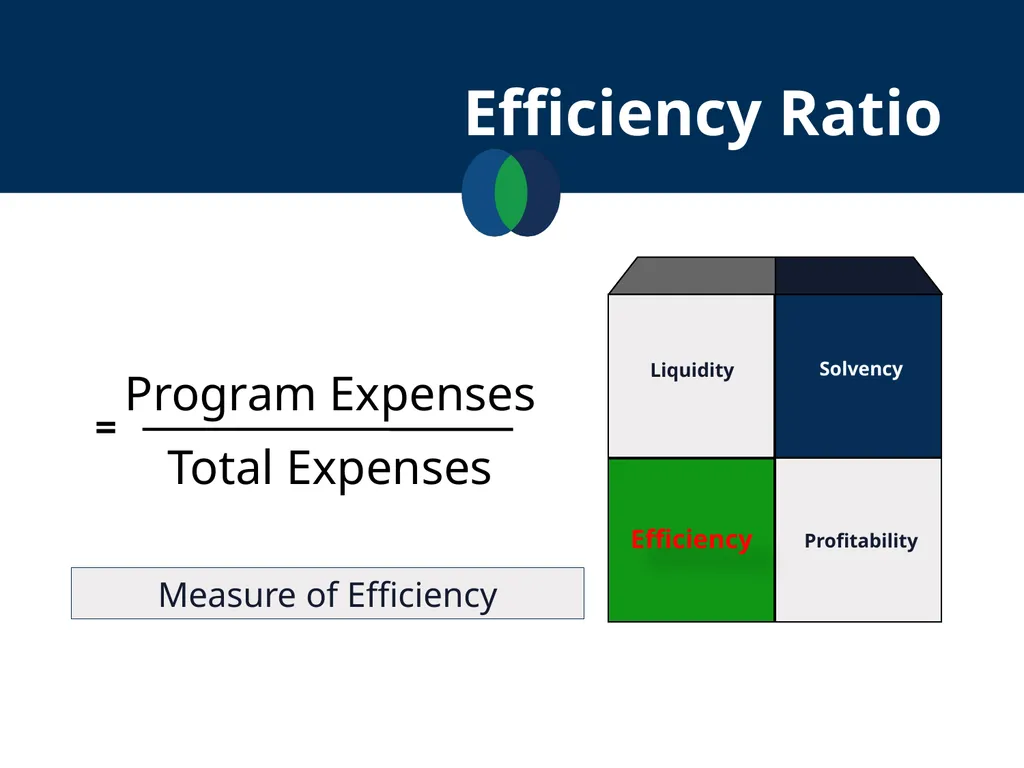
slide25. Efficiency Ratio Profitability Measure of Efficiency<br>
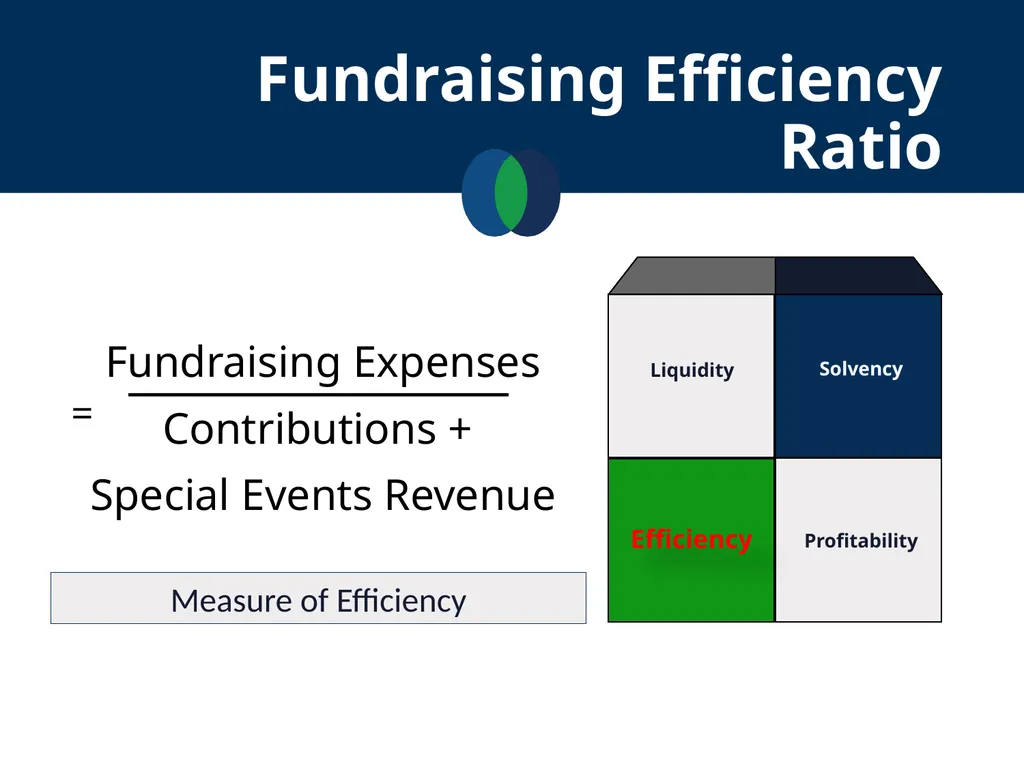
slide26. Fundraising Efficiency Ratio Profitability Measure of Efficiency<br>
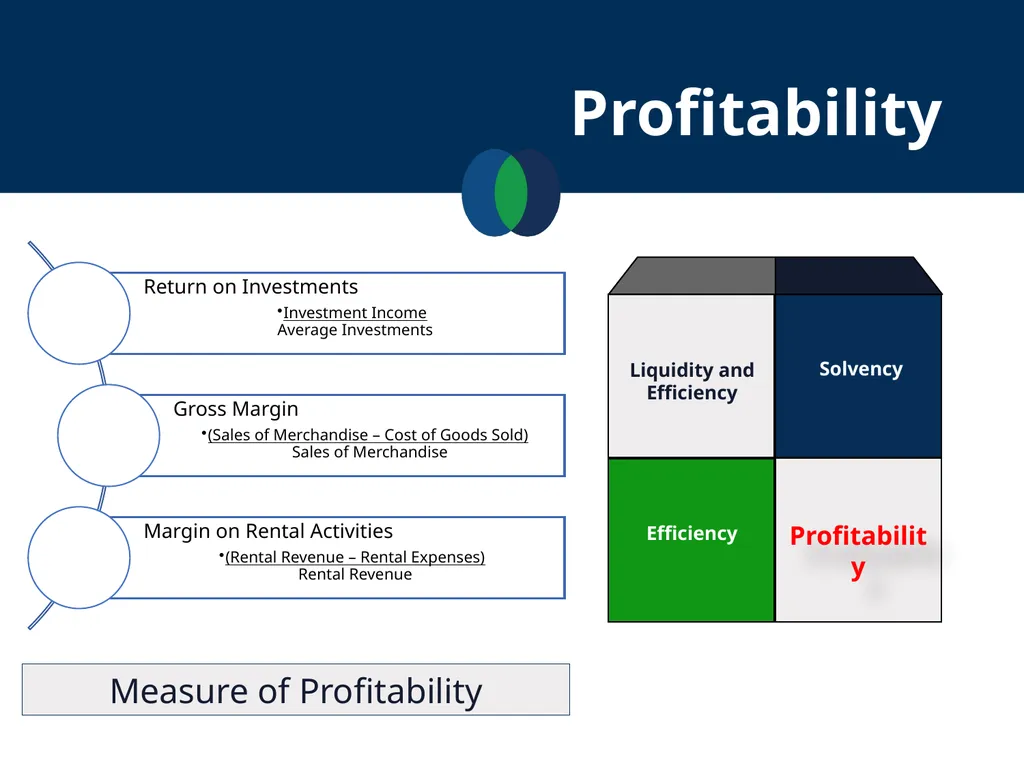
slide27. Profitability Profitability Measure of Profitability Efficiency<br>
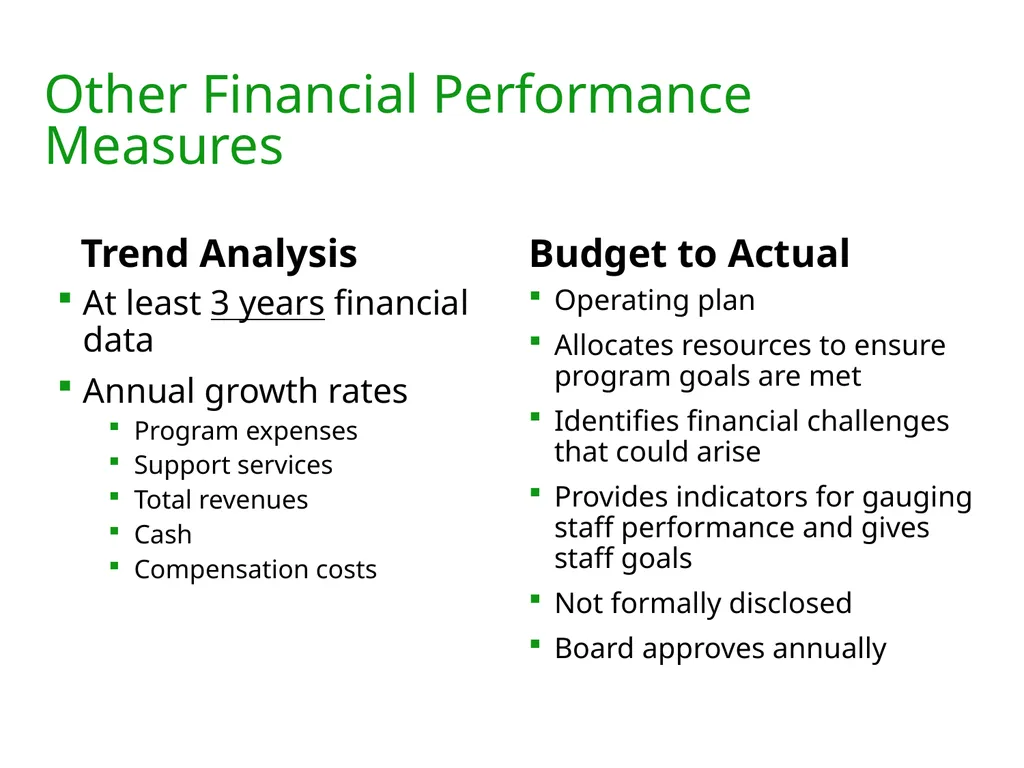
slide28. Other Financial Performance Measures Trend Analysis At least 3 years financial data
Annual growth rates
Program expenses
Support services
Total revenues
Cash
Compensation costs Budget to Actual Operating plan
Allocates resources to ensure program goals are met
Identifies financial challenges that could arise
Provides indicators for gauging staff performance and gives staff goals
Not formally disclosed
Board approves annually<br>
slide29. Upcoming Changes to Not-for-Profit Accounting<br>
slide30. Not-for-Profit Accounting Changes Efficiency ASU 2016-14, Presentation of Financial Statements of Not-for-Profit Entities
Issued August 2016
First overhaul of NFP financial presentation since early ‘90s (SFAS 115/116)
Applies to all NFPs including business-oriented health care entities
Effective: Annual financial statements issued for fiscal years beginning after December 15, 2017 (early adoption permitted)<br>
slide31. Not-for-Profit Accounting Changes Efficiency Net asset classes reduced from three to two
New liquidity and availability disclosures required
All NFPs must report expenses by nature and function in one place, and describe methods used to allocate among functional categories
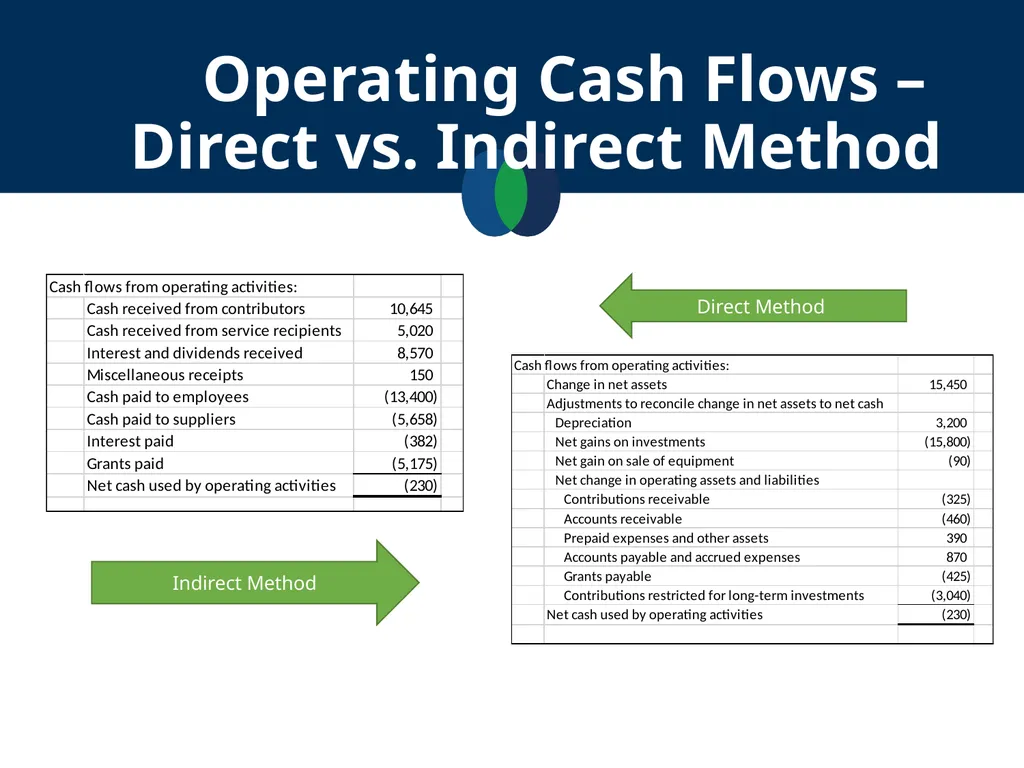
Use of direct method in SOCF eliminates reconciliation of change in net assets to cash flows from (used for) operating activities<br>
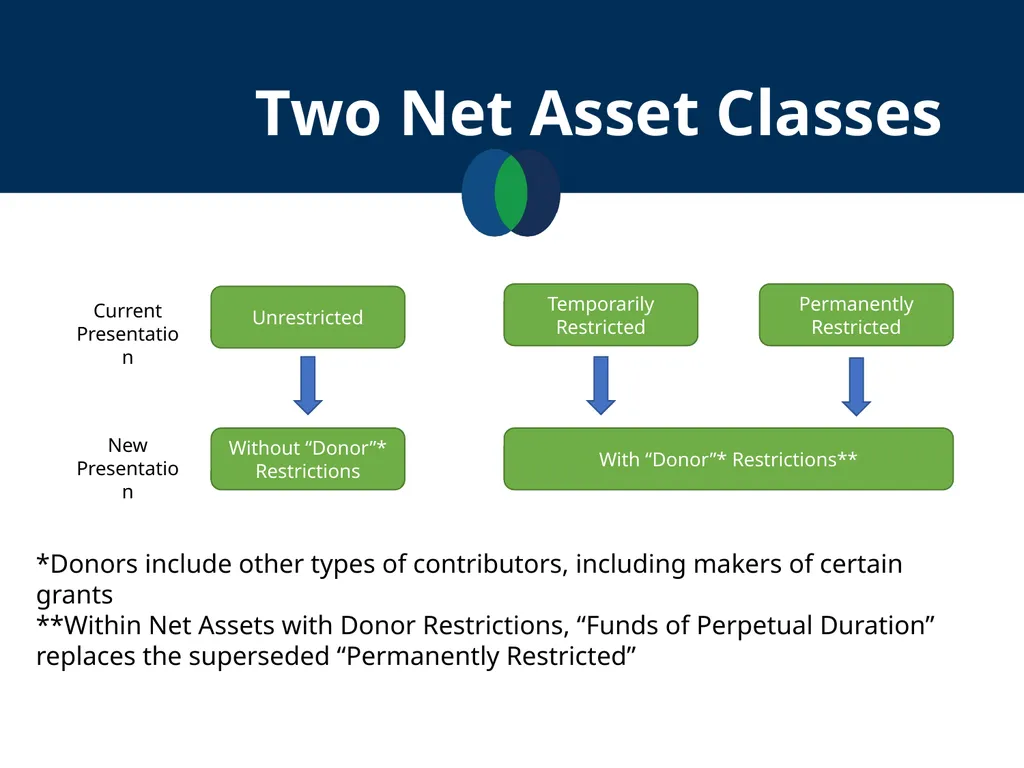
slide32. Two Net Asset Classes Unrestricted Temporarily Restricted Permanently Restricted Current Presentation Without “Donor”* Restrictions With “Donor”* Restrictions** New Presentation *Donors include other types of contributors, including makers of certain grants
**Within Net Assets with Donor Restrictions, “Funds of Perpetual Duration” replaces the superseded “Permanently Restricted”<br>
slide33. Operating Cash Flows – Direct vs. Indirect Method Indirect Method Direct Method<br>
slide34. Auditor Involvement<br>
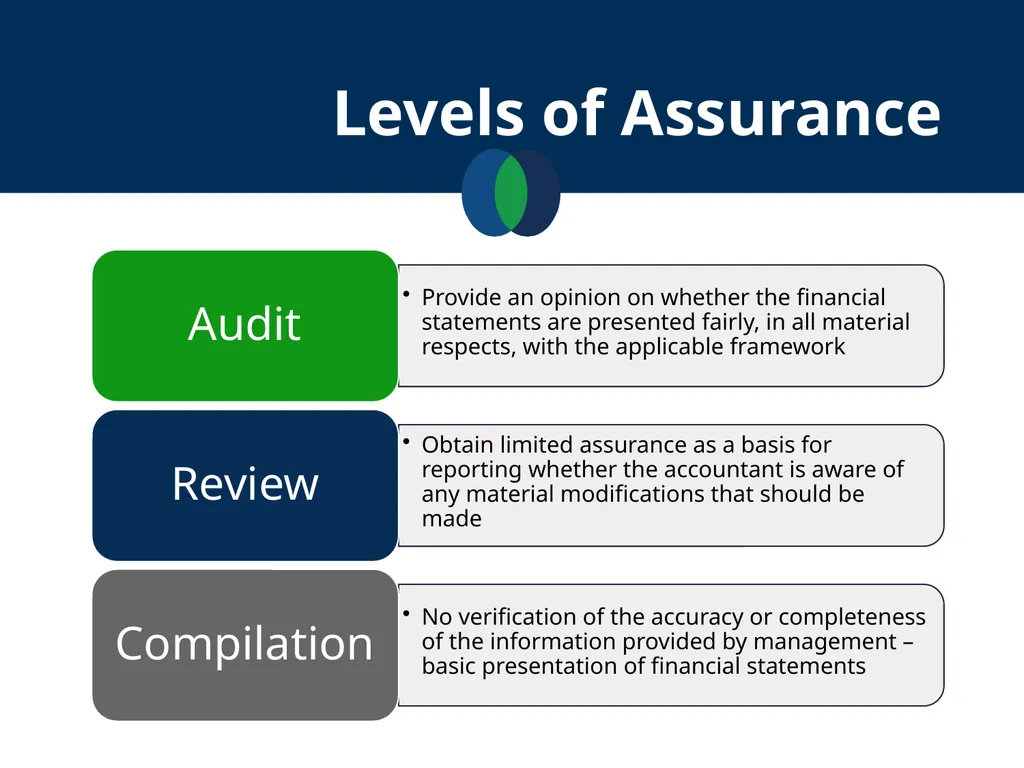
slide35. Levels of Assurance<br>
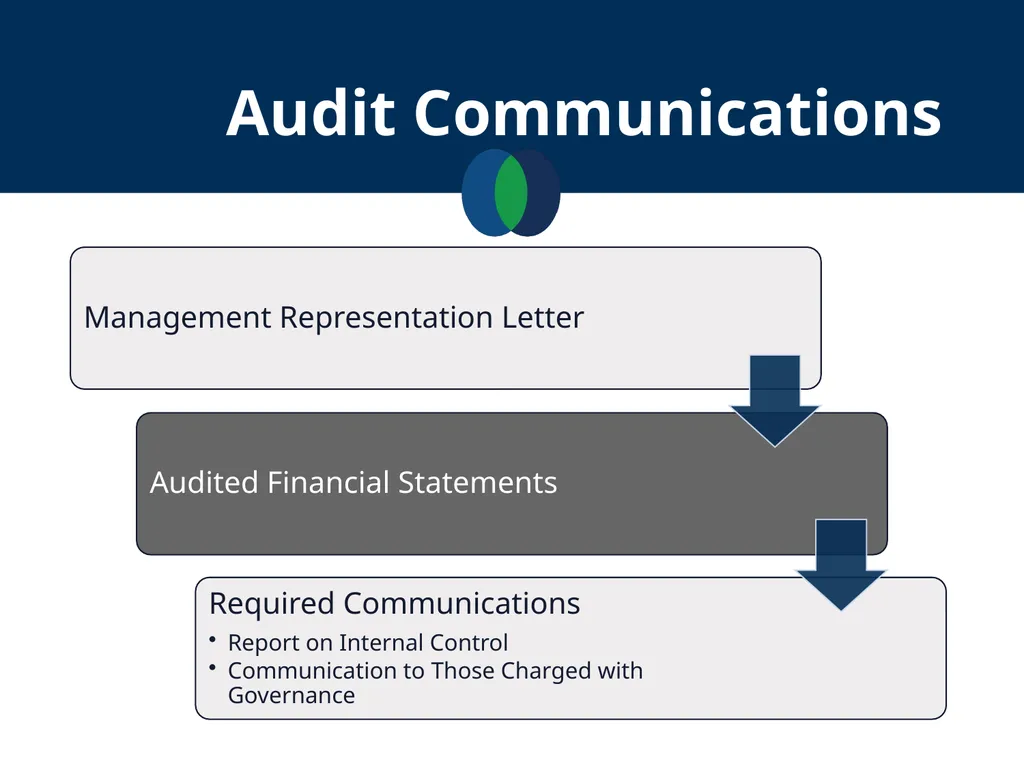
slide36. Audit Communications<br>
slide37. Common Landmines Financial statements can provide a wealth of information about an organization, but understand the context of what you are reviewing:
—What is the basis of accounting?
—What levels of assurance can be placed on the information?
—What assurance does an audit not provide?<br>
slide38. Contact information: jillian.bergman@holtzmanpartners.com (512) 610-7216<br>
slide2. Financial Audit and Review Services
Tax Services
SOX Compliance and Internal Controls
Employee Benefit Plan Audit Services
IT Risk & Compliance
Advisory Holtzman Partners LLP<br>
slide3. Agenda Financial Statement Overview
Financial Statement Analysis
Financial Statement Ratios and Other Performance Measures
Upcoming changes to Not-for-Profit Accounting
Auditor Involvement<br>
slide4. Financial Statement Overview<br>
slide5. Key Roadmap to Organization<br>
slide6. Primary Financial Statements Basic financial statements:
Statement of Net Assets
Statement of Activities
Statement of Cash Flows<br>
slide7. The Statement of Net Assets Key Points
Summary of the financial position of an organization at a particular date
Not necessarily market value
Only recognizes assets that can be expressed in monetary terms
Focus on the quality of the assets<br>
slide8. Accounting Equation Assets = Liabilities + Net Assets Sources of Funding Creditors’
claims
against
resources = + Net Assets
(Self-funded) Resources Resources
used to
generate
revenues<br>
slide9. Example: Statement of Net Assets Classified:
Current and long-term assets
Current and long-term liabilities
Not required for nonprofits
Listed in decreasing order of liquidity
Comparative:
Identifies significant changes over time<br>
slide10. The Income Statement Key Points
Shows the results of an organization’s operations over a period of time
What goods were sold, services performed, or contributions received that provided revenue for the organization?
What costs were incurred in normal operations to generate these revenues?
What are the earnings or change in net assets?
Revenues ≠ Cash Inflow<br>
slide11. Example: Income Statement Classified:
Expenses are categorized by function
Classified as Unrestricted, Temporarily, and Permanently Restricted
Comparative:
Identifies significant changes over time<br>
slide12. The Statement of Cash Flows Key Points
Reports the amount of cash collected and paid out by an organization for a period of time
How did the organization receive cash and use it?
Complementary to the statement of activities
Indicates ability of an organization to generate income in the future<br>
slide13. Example: Statement of Cash Flows Operating activities – Transactions that enter into the determination of change in net assets
Investing activities – Transactions that involve the purchase and sale of property, plant, equipment, and other assets not generally held for resale, and the making and collecting of loans
Financing activities – Transactions whereby resources are obtained from, or repaid to, creditors<br>
slide14. Statement of Functional Expenses Key Points
Distributes cost over functional and natural categories.
Joint costs allocated among appropriate functional categories.<br>
slide15. Notes to the Financial Statements Disclosure of important information that is not shown on the face of the financial statements
Additional information behind the summary totals
Supplementary information required by the FASB<br>
slide16. Financial Statement Analysis<br>
slide17. Financial Statement Preparation Organizations require periodic, timely reporting
U.S. GAAP most common method of accounting
Financial Accounting Standards Board (FASB) continually monitors and updates GAAP GAAP = Generally Accepted Accounting Principles<br>
slide18. Be Aware! Different accounting methods often produce radically different results
U.S. GAAP vs. IFRS
Accrual Basis vs. Cash Basis
Governmental Accounting Standards IFRS = International Financial Reporting Standards<br>
slide19. Accrual vs. Cash Accounting Accrual Accounting Revenues and expenses are recorded as they are earned and incurred.
Advantage: matches revenues and related costs
Disadvantage: more complicated and judgmental
Provides a more accurate picture of an organization’s surplus (deficit)
Financial statement users can make more informed judgments concerning the organization’s health Cash Accounting Revenues and expenses are recorded when cash is received or paid.
Disadvantage: does not accurately reflect economic condition of the organization
Advantage: easy to use, like a personal checkbook
Surplus (deficit) is difficult to measure<br>
slide20. Financial Statement Ratios and Other Performance Measures<br>
slide21. Profitability Ability to meet short-term obligations and to efficiently generate revenues Ability to generate future revenues and meet long-term obligations Ability to generate a profit that can be used to finance program services Ability to use resources efficiently to provide program services Building Blocks of Analysis<br>
slide22. Current Ratio Measure of Liquidity “Working Capital Ratio” Profitability<br>
slide23. Months Cash on Hand Measure of Liquidity Profitability Liquidity<br>
slide24. Leverage Measure of Solvency Profitability<br>
slide25. Efficiency Ratio Profitability Measure of Efficiency<br>
slide26. Fundraising Efficiency Ratio Profitability Measure of Efficiency<br>
slide27. Profitability Profitability Measure of Profitability Efficiency<br>
slide28. Other Financial Performance Measures Trend Analysis At least 3 years financial data
Annual growth rates
Program expenses
Support services
Total revenues
Cash
Compensation costs Budget to Actual Operating plan
Allocates resources to ensure program goals are met
Identifies financial challenges that could arise
Provides indicators for gauging staff performance and gives staff goals
Not formally disclosed
Board approves annually<br>
slide29. Upcoming Changes to Not-for-Profit Accounting<br>
slide30. Not-for-Profit Accounting Changes Efficiency ASU 2016-14, Presentation of Financial Statements of Not-for-Profit Entities
Issued August 2016
First overhaul of NFP financial presentation since early ‘90s (SFAS 115/116)
Applies to all NFPs including business-oriented health care entities
Effective: Annual financial statements issued for fiscal years beginning after December 15, 2017 (early adoption permitted)<br>
slide31. Not-for-Profit Accounting Changes Efficiency Net asset classes reduced from three to two
New liquidity and availability disclosures required
All NFPs must report expenses by nature and function in one place, and describe methods used to allocate among functional categories
Use of direct method in SOCF eliminates reconciliation of change in net assets to cash flows from (used for) operating activities<br>
slide32. Two Net Asset Classes Unrestricted Temporarily Restricted Permanently Restricted Current Presentation Without “Donor”* Restrictions With “Donor”* Restrictions** New Presentation *Donors include other types of contributors, including makers of certain grants
**Within Net Assets with Donor Restrictions, “Funds of Perpetual Duration” replaces the superseded “Permanently Restricted”<br>
slide33. Operating Cash Flows – Direct vs. Indirect Method Indirect Method Direct Method<br>
slide34. Auditor Involvement<br>
slide35. Levels of Assurance<br>
slide36. Audit Communications<br>
slide37. Common Landmines Financial statements can provide a wealth of information about an organization, but understand the context of what you are reviewing:
—What is the basis of accounting?
—What levels of assurance can be placed on the information?
—What assurance does an audit not provide?<br>
slide38. Contact information: jillian.bergman@holtzmanpartners.com (512) 610-7216<br>