
GST Outreach for Trade and Taxpayers Changes
TD
Published · 51 slides · 0 views

1 / 1
Description
GST Outreach for Trade and Taxpayers Changes brought upon by 47th GST Council Meeting By : CGST Delhi Zone INDEX Trade Facilitation Measures Easing Compliances Clarifications Exemption Withdrawals Rate Rationalization E-invoicing Trade
Related Topics
Share
Embed code
Download this presentation From Below
"GST Outreach for Trade and Taxpayers Changes" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
GST Outreach for Trade and Taxpayers Changes brought upon by 47th GST Council Meeting
By :
CGST Delhi Zone<br>
By :
CGST Delhi Zone<br>
02
INDEX Trade Facilitation Measures
Easing Compliances
Clarifications
Exemption Withdrawals
Rate Rationalization
E-invoicing<br>
Easing Compliances
Clarifications
Exemption Withdrawals
Rate Rationalization
E-invoicing<br>
03
Trade Facilitation Measures 47th GST Council Meeting<br>
04
Measures for Trade Facilitation
The scheme would be tentatively implemented with effect from 01.01.2023 For small taxpayers undertaking supplies through E-commerce Operators (In-principal approval):
1. Waiver of requirement of mandatory registration under Section 24(ix) for person supplying goods through ECOs, subject to certain conditions, such as-
the aggregate turnover on all India basis does not exceed the turnover specified under section 22(1) of the CGST Act and notifications issued thereunder.
the person is not making any inter-State taxable supply
2. Composition taxpayers would be allowed to make intra-State supply through e-commerce operators subject to certain conditions.<br>
1. Waiver of requirement of mandatory registration under Section 24(ix) for person supplying goods through ECOs, subject to certain conditions, such as-
the aggregate turnover on all India basis does not exceed the turnover specified under section 22(1) of the CGST Act and notifications issued thereunder.
the person is not making any inter-State taxable supply
2. Composition taxpayers would be allowed to make intra-State supply through e-commerce operators subject to certain conditions.<br>
05
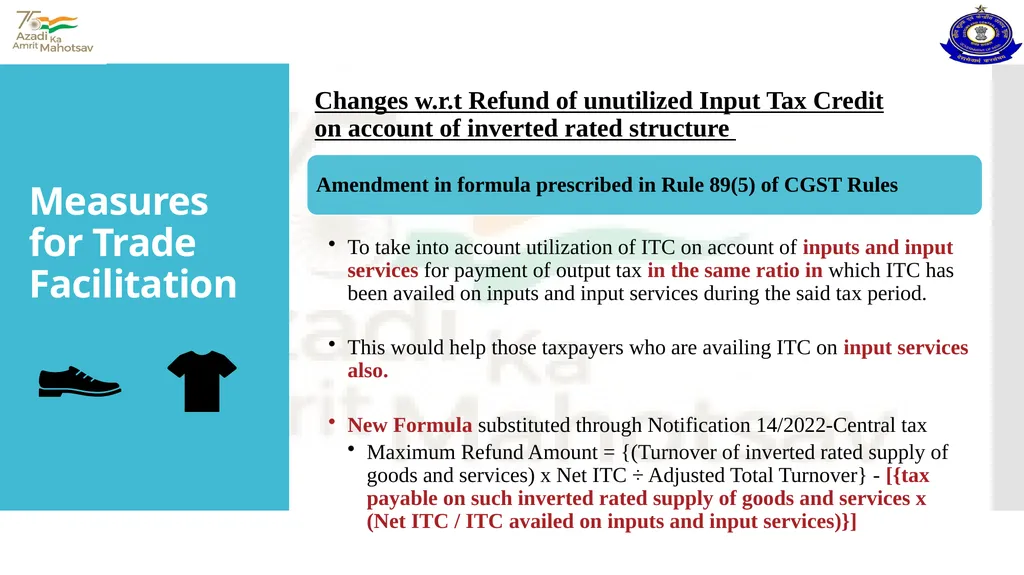
Measures for Trade Facilitation Changes w.r.t Refund of unutilized Input Tax Credit on account of inverted rated structure<br>
06
Refund of unutilized Input Tax Credit on account of inverted rated structure<br>
07
Interest on delayed payment of tax ITC wrongly availed shall be construed to have been utilized, when the balance in the electronic credit ledger falls below the amount of input tax credit wrongly availed.
The date of utilization of such input tax credit shall be taken to be
(a) the date on which the return is due to be furnished or the actual date of filing of the said return, whichever is earlier on account of payment of tax through the said return; or
b) the date of debit in the electronic credit ledger when the balance in the electronic credit ledger falls below the amount of input tax credit wrongly availed, in all other cases.<br>
The date of utilization of such input tax credit shall be taken to be
(a) the date on which the return is due to be furnished or the actual date of filing of the said return, whichever is earlier on account of payment of tax through the said return; or
b) the date of debit in the electronic credit ledger when the balance in the electronic credit ledger falls below the amount of input tax credit wrongly availed, in all other cases.<br>
08
Refund of unutilized Input Tax Credit on account of Export of Electricity
Circular No. 175/07/2022-GST Necessity of the Amendment:
Problem being faced by power generating units in filing of refund of unutilised Input Tax Credit (ITC) on account of export of electricity.
Changes through Notification and Circular:
Clause(ba) has been inserted in sub-rule (2) of rule 89 and a Statement 3B has been inserted in FORM GST RFD-01of the CGST Rules, 2017 vide notification No. 14/2022-CT dated 5thJuly, 2022.
The applicant would be required to file the application for refund under “Any Other” category electronically in FORM GST RFD-01, on the portal. In remark column of the application, the taxpayer would enter “Export of electricity-without payment of tax (accumulated ITC)<br>
Problem being faced by power generating units in filing of refund of unutilised Input Tax Credit (ITC) on account of export of electricity.
Changes through Notification and Circular:
Clause(ba) has been inserted in sub-rule (2) of rule 89 and a Statement 3B has been inserted in FORM GST RFD-01of the CGST Rules, 2017 vide notification No. 14/2022-CT dated 5thJuly, 2022.
The applicant would be required to file the application for refund under “Any Other” category electronically in FORM GST RFD-01, on the portal. In remark column of the application, the taxpayer would enter “Export of electricity-without payment of tax (accumulated ITC)<br>
09
Refund of unutilized Input Tax Credit on account of Export of Electricity
Circular No. 175/07/2022-GST The applicant would be required to furnish/upload
Details in Statement 3B of FORM GST RFD-01(in pdf format)
Required to upload the copy of statement of scheduled energy for electricity exported by the Generation Plants(in format attached as Annexure-I), for the period for which refund has been claimed and the copy of the relevant agreement(s) detailing the tariff per unit for the electricity exported.
Details of calculation of the refund amount in Statement -3A of FORM GST RFD-01 by uploading the same in pdf format along with refund application in FORM GST RFD-01.<br>
Details in Statement 3B of FORM GST RFD-01(in pdf format)
Required to upload the copy of statement of scheduled energy for electricity exported by the Generation Plants(in format attached as Annexure-I), for the period for which refund has been claimed and the copy of the relevant agreement(s) detailing the tariff per unit for the electricity exported.
Details of calculation of the refund amount in Statement -3A of FORM GST RFD-01 by uploading the same in pdf format along with refund application in FORM GST RFD-01.<br>
10
Easing Compliance 47th GST Council Meeting<br>
11
Easing Compliance
Notification 9/2022 Central Tax Dt. 05.07.2022<br>
12
As per Rule 96(10) IGST Refund not eligible, if at time of procurement the benefit of following notification is availed.
Notification No. 48/2017 – CT (Deemed Exports other than receipt of capital goods under EOU scheme)
Notification No. 40/2017 – CT (R) (Merchant Exports)
Notification No. 78 & 79/2017 – Customs (Certain Concessional Imports)
In case refund has been availed in contravention of rule 96(10) or erroneous refund of accumulated ITC then such refund has to be paid back by the refund claimant, however, without any facility for re-crediting of ITC used in paying IGST on Exports
To facilitate re-credit Form PMT-03A introduced. Re-credit of ITC after recovery of erroneous refund Notification 14/2022 Central Tax Dt. 05.07.2022.<br>
Notification No. 48/2017 – CT (Deemed Exports other than receipt of capital goods under EOU scheme)
Notification No. 40/2017 – CT (R) (Merchant Exports)
Notification No. 78 & 79/2017 – Customs (Certain Concessional Imports)
In case refund has been availed in contravention of rule 96(10) or erroneous refund of accumulated ITC then such refund has to be paid back by the refund claimant, however, without any facility for re-crediting of ITC used in paying IGST on Exports
To facilitate re-credit Form PMT-03A introduced. Re-credit of ITC after recovery of erroneous refund Notification 14/2022 Central Tax Dt. 05.07.2022.<br>
13
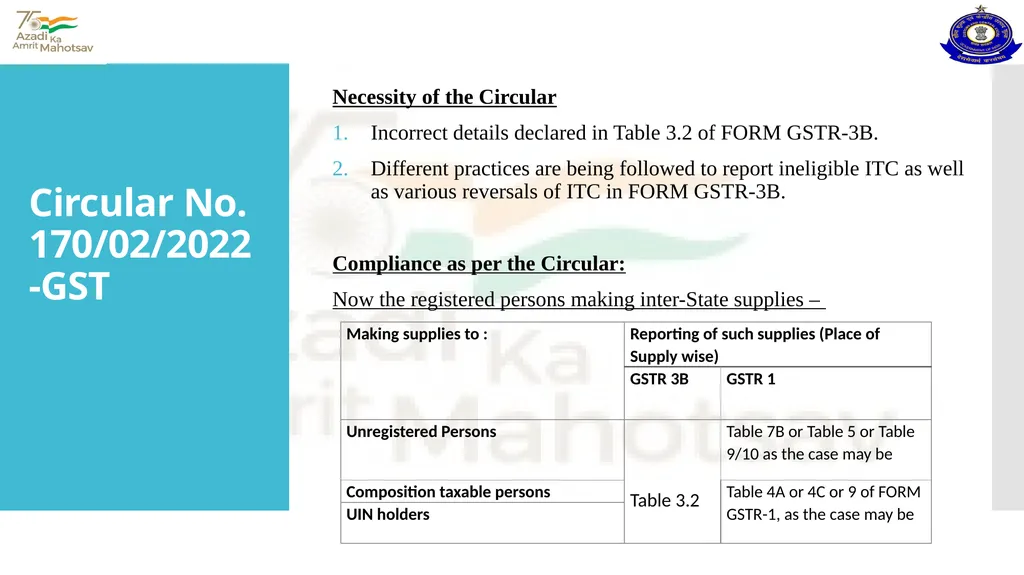
Circular No. 170/02/2022-GST Necessity of the Circular
Incorrect details declared in Table 3.2 of FORM GSTR-3B.
Different practices are being followed to report ineligible ITC as well as various reversals of ITC in FORM GSTR-3B.
Compliance as per the Circular:
Now the registered persons making inter-State supplies –<br>
Incorrect details declared in Table 3.2 of FORM GSTR-3B.
Different practices are being followed to report ineligible ITC as well as various reversals of ITC in FORM GSTR-3B.
Compliance as per the Circular:
Now the registered persons making inter-State supplies –<br>
14
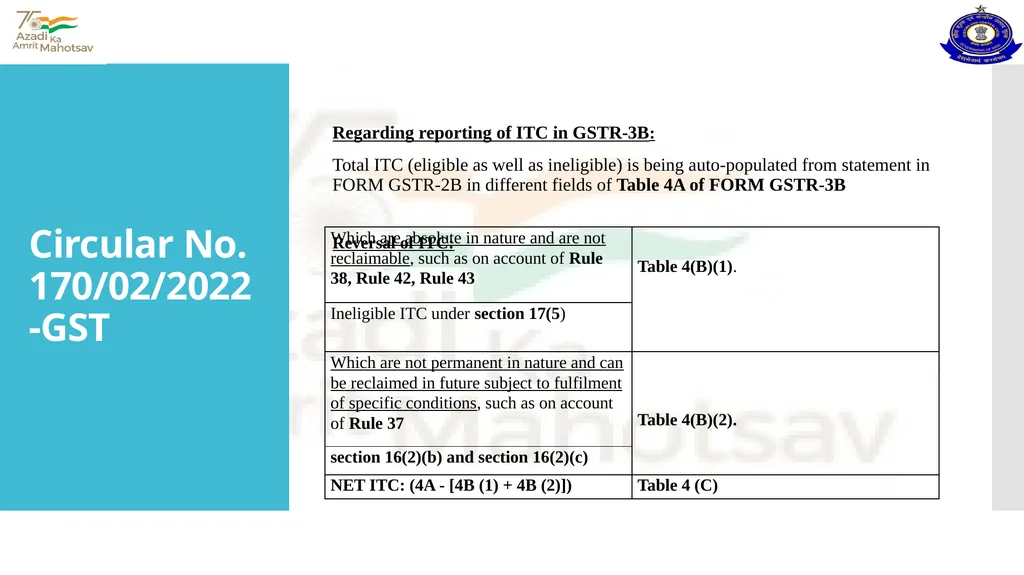
Circular No. 170/02/2022-GST Regarding reporting of ITC in GSTR-3B:
Total ITC (eligible as well as ineligible) is being auto-populated from statement in FORM GSTR-2B in different fields of Table 4A of FORM GSTR-3B
Reversal of ITC:<br>
Total ITC (eligible as well as ineligible) is being auto-populated from statement in FORM GSTR-2B in different fields of Table 4A of FORM GSTR-3B
Reversal of ITC:<br>
15
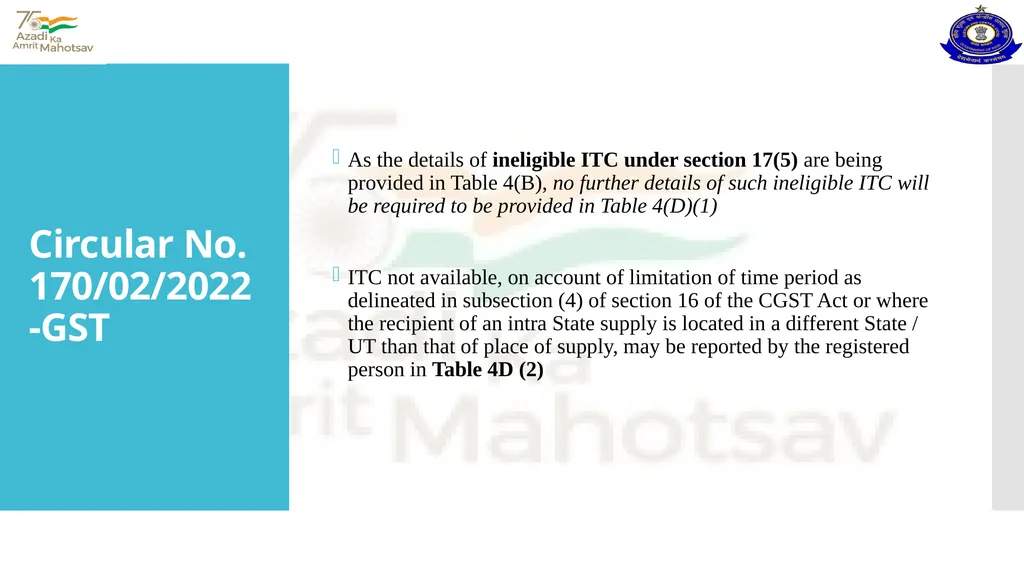
Circular No. 170/02/2022-GST As the details of ineligible ITC under section 17(5) are being provided in Table 4(B), no further details of such ineligible ITC will be required to be provided in Table 4(D)(1)
ITC not available, on account of limitation of time period as delineated in subsection (4) of section 16 of the CGST Act or where the recipient of an intra State supply is located in a different State / UT than that of place of supply, may be reported by the registered person in Table 4D (2)<br>
ITC not available, on account of limitation of time period as delineated in subsection (4) of section 16 of the CGST Act or where the recipient of an intra State supply is located in a different State / UT than that of place of supply, may be reported by the registered person in Table 4D (2)<br>
16
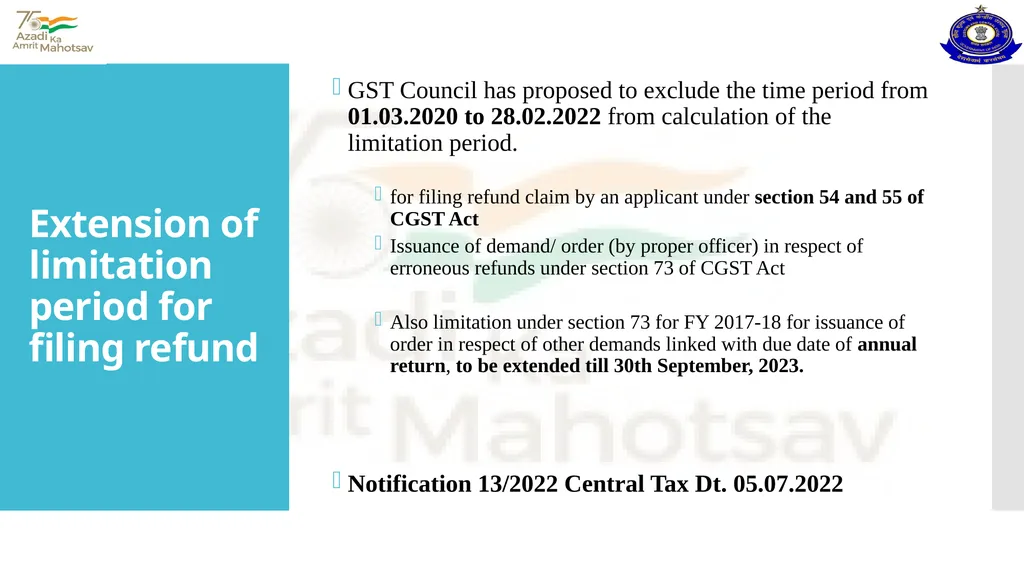
Extension of limitation period for filing refund GST Council has proposed to exclude the time period from 01.03.2020 to 28.02.2022 from calculation of the limitation period.
for filing refund claim by an applicant under section 54 and 55 of CGST Act
Issuance of demand/ order (by proper officer) in respect of erroneous refunds under section 73 of CGST Act
Also limitation under section 73 for FY 2017-18 for issuance of order in respect of other demands linked with due date of annual return, to be extended till 30th September, 2023.
Notification 13/2022 Central Tax Dt. 05.07.2022<br>
for filing refund claim by an applicant under section 54 and 55 of CGST Act
Issuance of demand/ order (by proper officer) in respect of erroneous refunds under section 73 of CGST Act
Also limitation under section 73 for FY 2017-18 for issuance of order in respect of other demands linked with due date of annual return, to be extended till 30th September, 2023.
Notification 13/2022 Central Tax Dt. 05.07.2022<br>
17
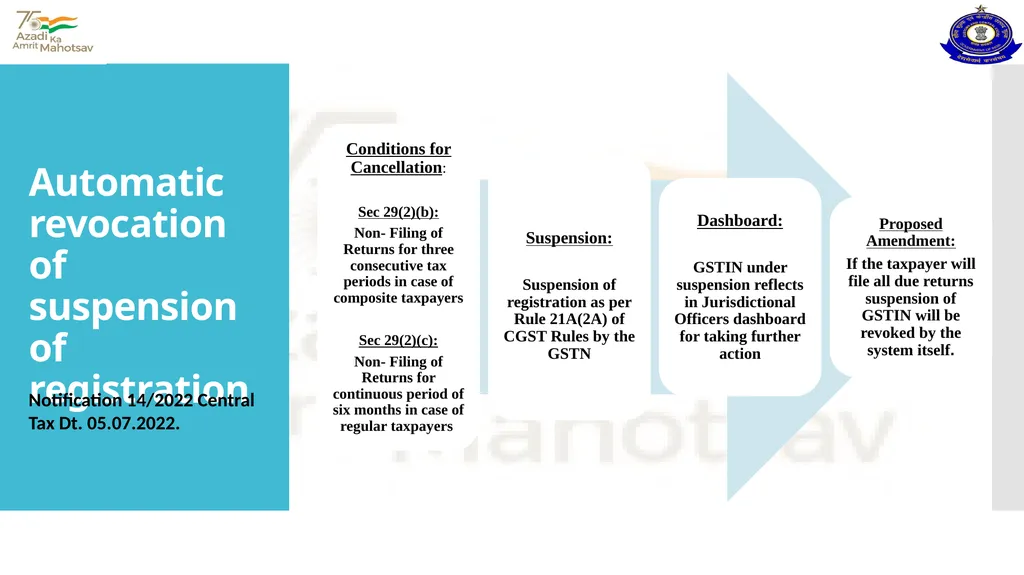
Automatic revocation of suspension of registration Notification 14/2022 Central Tax Dt. 05.07.2022.<br>
18
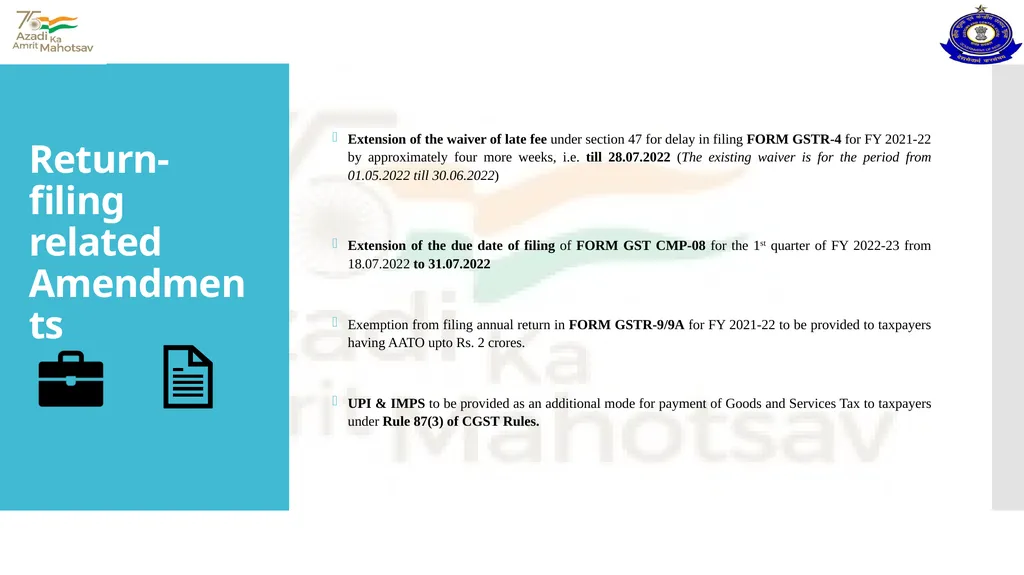
Return-filing related Amendments Extension of the waiver of late fee under section 47 for delay in filing FORM GSTR-4 for FY 2021-22 by approximately four more weeks, i.e. till 28.07.2022 (The existing waiver is for the period from 01.05.2022 till 30.06.2022)
Extension of the due date of filing of FORM GST CMP-08 for the 1st quarter of FY 2022-23 from 18.07.2022 to 31.07.2022
Exemption from filing annual return in FORM GSTR-9/9A for FY 2021-22 to be provided to taxpayers having AATO upto Rs. 2 crores.
UPI & IMPS to be provided as an additional mode for payment of Goods and Services Tax to taxpayers under Rule 87(3) of CGST Rules.<br>
Extension of the due date of filing of FORM GST CMP-08 for the 1st quarter of FY 2022-23 from 18.07.2022 to 31.07.2022
Exemption from filing annual return in FORM GSTR-9/9A for FY 2021-22 to be provided to taxpayers having AATO upto Rs. 2 crores.
UPI & IMPS to be provided as an additional mode for payment of Goods and Services Tax to taxpayers under Rule 87(3) of CGST Rules.<br>
19
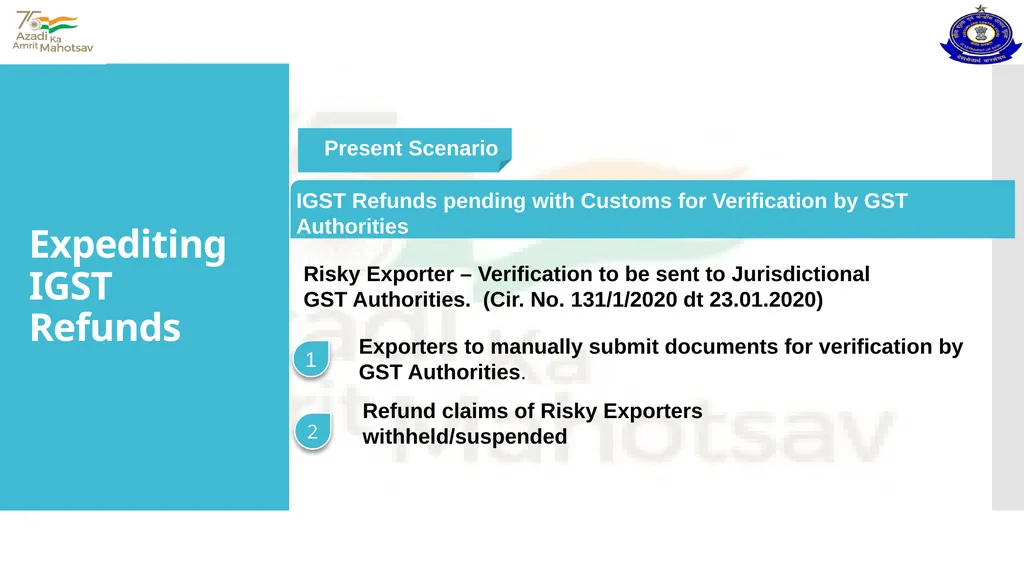
Expediting IGST Refunds Present Scenario 1 Exporters to manually submit documents for verification by GST Authorities. Risky Exporter – Verification to be sent to Jurisdictional GST Authorities. (Cir. No. 131/1/2020 dt 23.01.2020) IGST Refunds pending with Customs for Verification by GST Authorities 2 Refund claims of Risky Exporters withheld/suspended<br>
20
Expediting IGST Refunds Cir. No. 131/1/2020 Amendment to Rule 96 Transmission of such IGST refund claims on the portal in a system generated FORM GST RFD-01 to the jurisdictional GST authorities for processing Proposed Amendment of Rule 96 for handling pending Refund Claims Notification 14/2022 Central Tax Dt. 05.07.2022.<br>
21
Clarifications 47th GST Council Meeting<br>
22
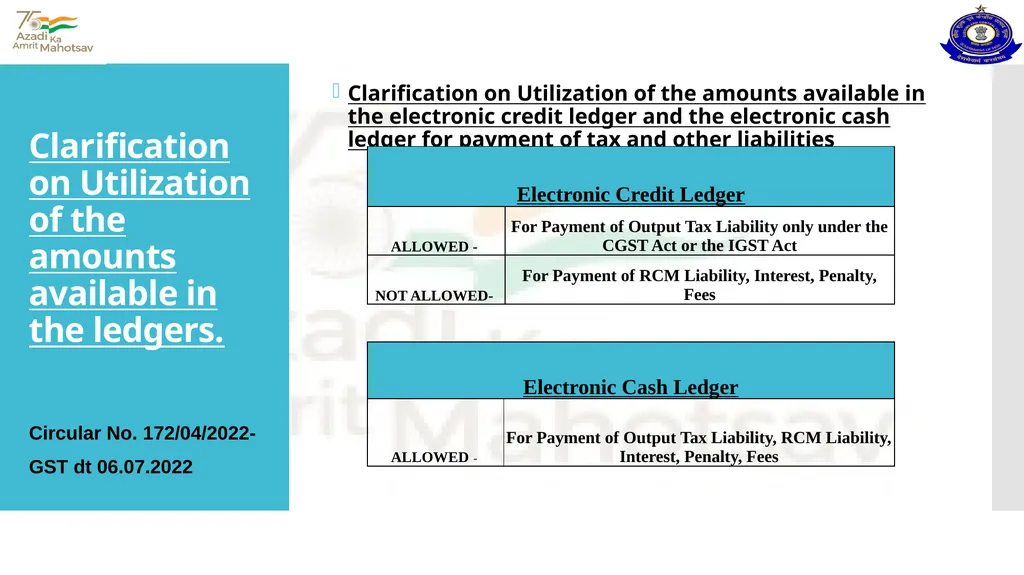
Clarification on Utilization of the amounts available in the ledgers.
Circular No. 172/04/2022-GST dt 06.07.2022 Clarification on Utilization of the amounts available in the electronic credit ledger and the electronic cash ledger for payment of tax and other liabilities<br>
23
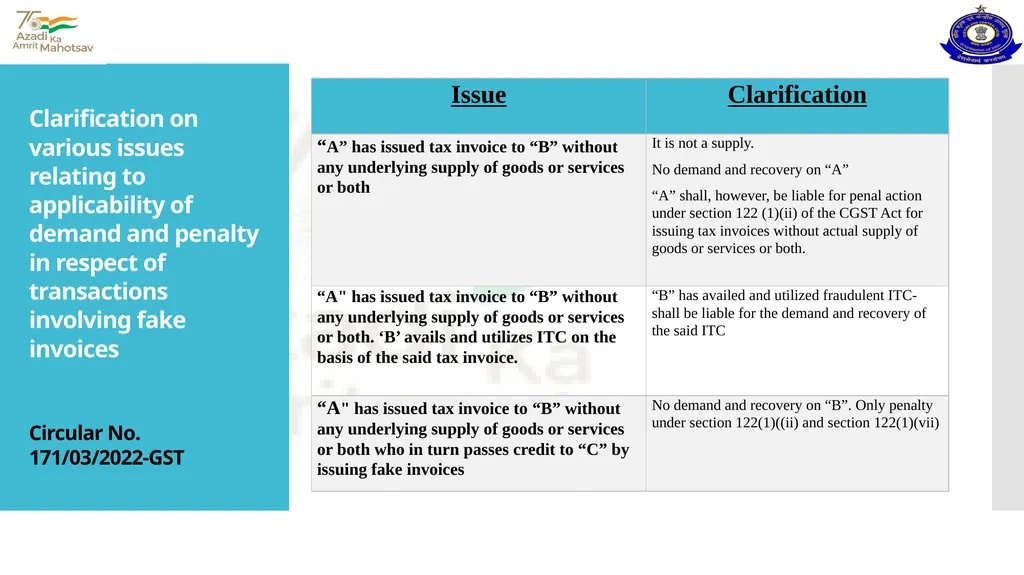
Clarification on various issues relating to applicability of demand and penalty in respect of transactions involving fake invoices
Circular No. 171/03/2022-GST<br>
24
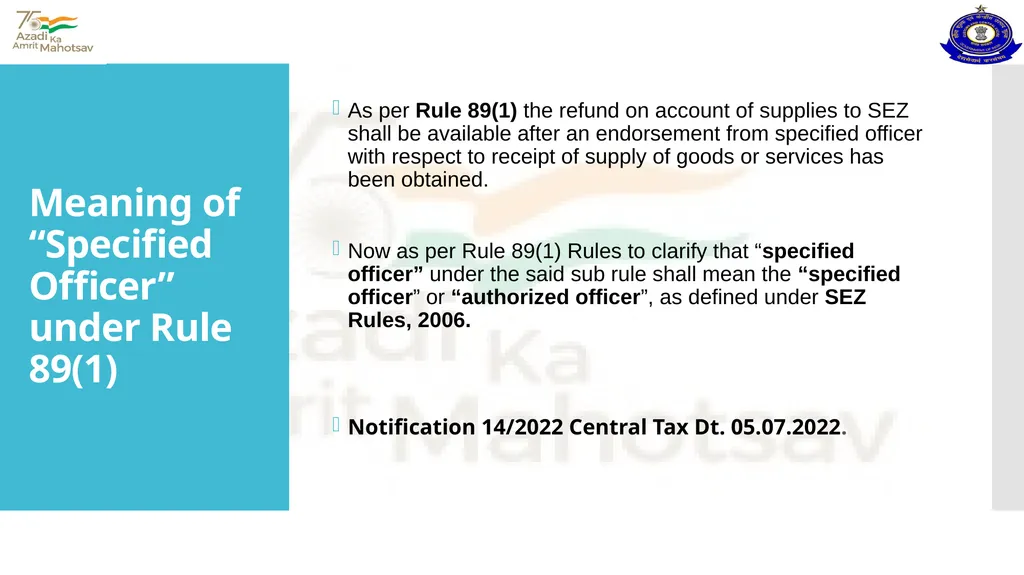
Meaning of “Specified Officer” under Rule 89(1) As per Rule 89(1) the refund on account of supplies to SEZ shall be available after an endorsement from specified officer with respect to receipt of supply of goods or services has been obtained.
Now as per Rule 89(1) Rules to clarify that “specified officer” under the said sub rule shall mean the “specified officer” or “authorized officer”, as defined under SEZ Rules, 2006.
Notification 14/2022 Central Tax Dt. 05.07.2022.<br>
Now as per Rule 89(1) Rules to clarify that “specified officer” under the said sub rule shall mean the “specified officer” or “authorized officer”, as defined under SEZ Rules, 2006.
Notification 14/2022 Central Tax Dt. 05.07.2022.<br>
25
Clarification on the issue of perquisites provided by employer to the employees as per contractual agreement
Circular No. 172/04/2022-GST dt 06.07.2022 Issue:
Whether various perquisites provided by the employer to its employees in terms of contractual agreement entered into between the employer and the employee are liable for GST?
Clarification:
Perquisites provided by the employer to the employee in terms of contractual agreement entered into between the employer and the employee, will not be subjected to GST when the same are provided in terms of the contract between the employer and employee.<br>
Whether various perquisites provided by the employer to its employees in terms of contractual agreement entered into between the employer and the employee are liable for GST?
Clarification:
Perquisites provided by the employer to the employee in terms of contractual agreement entered into between the employer and the employee, will not be subjected to GST when the same are provided in terms of the contract between the employer and employee.<br>
26
WITHDRAWAL OF EXEMPTIONS 47th GST Council Meeting<br>
27
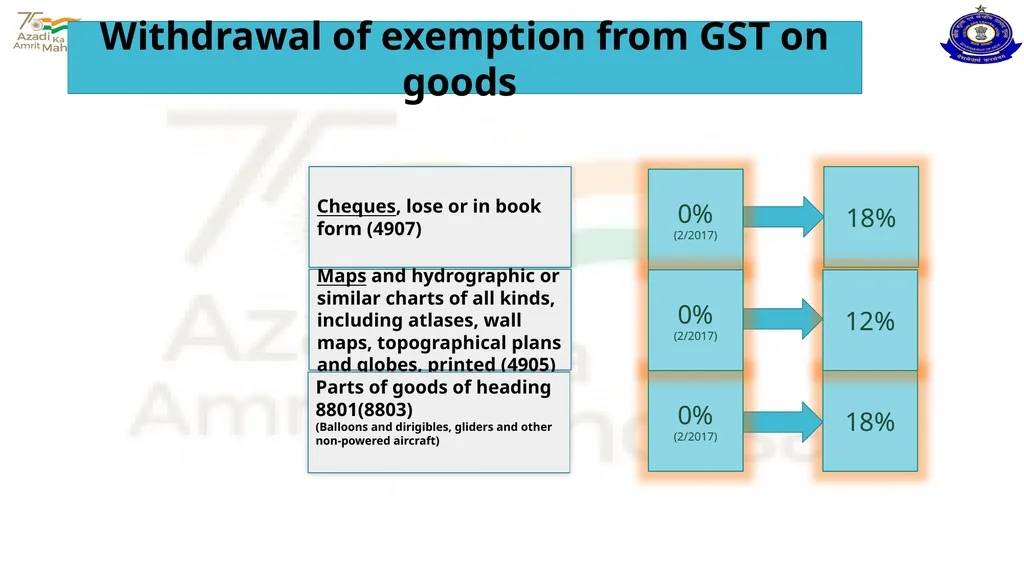
Cheques, lose or in book form (4907) Maps and hydrographic or similar charts of all kinds, including atlases, wall maps, topographical plans and globes, printed (4905) Parts of goods of heading 8801(8803)
(Balloons and dirigibles, gliders and other non-powered aircraft) 18% 18% 12% Withdrawal of exemption from GST on goods 0%
(2/2017) 0%
(2/2017) 0%
(2/2017)<br>
(Balloons and dirigibles, gliders and other non-powered aircraft) 18% 18% 12% Withdrawal of exemption from GST on goods 0%
(2/2017) 0%
(2/2017) 0%
(2/2017)<br>
28
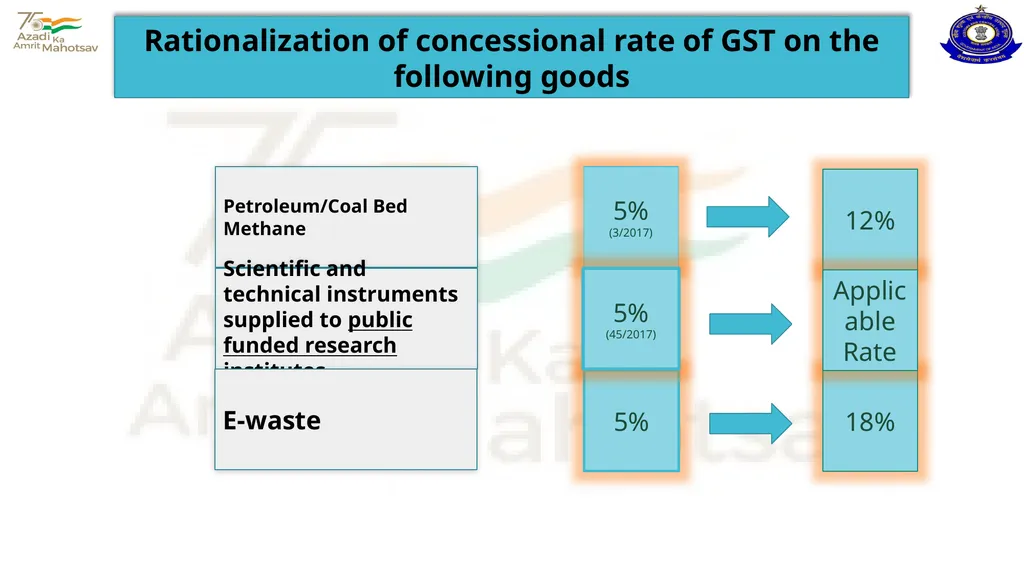
Petroleum/Coal Bed Methane Scientific and technical instruments supplied to public funded research institutes E-waste 12% 18% Applicable Rate Rationalization of concessional rate of GST on the following goods 5%
(3/2017) 5% 5%
(45/2017)<br>
(3/2017) 5% 5%
(45/2017)<br>
29
Rationalization of Exemption on Services
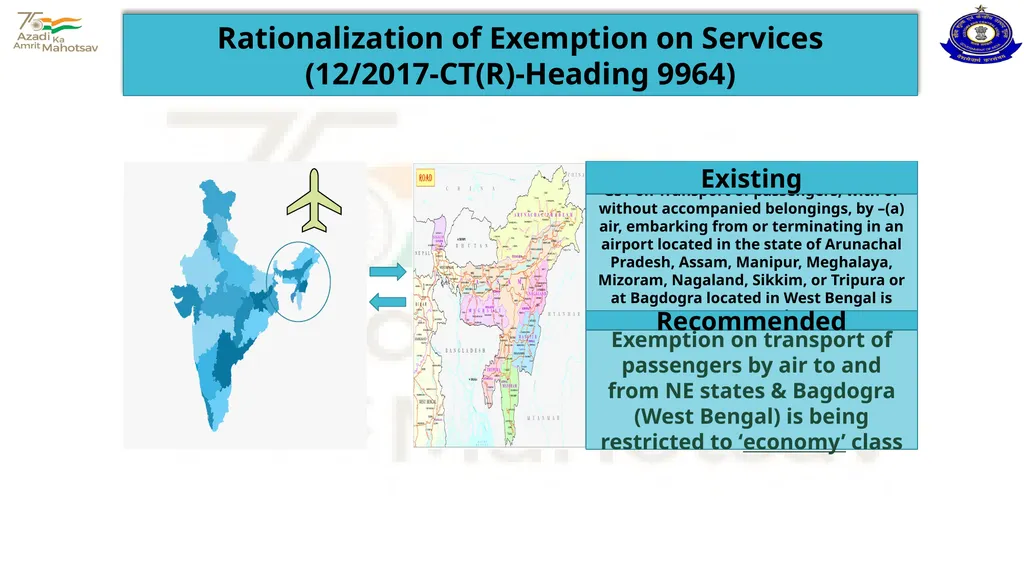
(12/2017-CT(R)-Heading 9964) GST on Transport of passengers, with or without accompanied belongings, by –(a) air, embarking from or terminating in an airport located in the state of Arunachal Pradesh, Assam, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, or Tripura or at Bagdogra located in West Bengal is exempted Exemption on transport of passengers by air to and from NE states & Bagdogra (West Bengal) is being restricted to ‘economy’ class Existing Recommended<br>
(12/2017-CT(R)-Heading 9964) GST on Transport of passengers, with or without accompanied belongings, by –(a) air, embarking from or terminating in an airport located in the state of Arunachal Pradesh, Assam, Manipur, Meghalaya, Mizoram, Nagaland, Sikkim, or Tripura or at Bagdogra located in West Bengal is exempted Exemption on transport of passengers by air to and from NE states & Bagdogra (West Bengal) is being restricted to ‘economy’ class Existing Recommended<br>
30
Withdrawal of Exemption on Services
(12/2017-Central Tax (Rate) Heading 9971) Services provided by RBI, IRDA, GSTN, SEBI,FSSAI<br>
(12/2017-Central Tax (Rate) Heading 9971) Services provided by RBI, IRDA, GSTN, SEBI,FSSAI<br>
31
Withdrawal of Exemption on Services (Notification 01/2018 amending 11/2017 CGST-Rate, Serial No.24(i)(i)(h) , Heading 9986) Nil rate of GST on Support services to agriculture, forestry, fishing, animal husbandry.
Explanation. –“Support services to agriculture, forestry, fishing, animal husbandry” mean -(i) Services relating to cultivation of plants and rearing of all life forms of animals, except the rearing of horses, for food, fibre, fuel, raw material or other similar products or agricultural produce by way of—
h) services by way of fumigation in a warehouse of agricultural produce. Withdrawal of exemption of GST on Support services to agriculture, forestry, fishing, animal husbandry.
Explanation. –“Support services to agriculture, forestry, fishing, animal husbandry” mean -(i) Services relating to cultivation of plants and rearing of all life forms of animals, except the rearing of horses, for food, fibre, fuel, raw material or other similar products or agricultural produce by way of—
h) services by way of fumigation in a warehouse of agricultural produce. EXISTING RECOMMENDATION<br>
Explanation. –“Support services to agriculture, forestry, fishing, animal husbandry” mean -(i) Services relating to cultivation of plants and rearing of all life forms of animals, except the rearing of horses, for food, fibre, fuel, raw material or other similar products or agricultural produce by way of—
h) services by way of fumigation in a warehouse of agricultural produce. Withdrawal of exemption of GST on Support services to agriculture, forestry, fishing, animal husbandry.
Explanation. –“Support services to agriculture, forestry, fishing, animal husbandry” mean -(i) Services relating to cultivation of plants and rearing of all life forms of animals, except the rearing of horses, for food, fibre, fuel, raw material or other similar products or agricultural produce by way of—
h) services by way of fumigation in a warehouse of agricultural produce. EXISTING RECOMMENDATION<br>
32
Withdrawal of Exemption on Services (Notification 12/2017 CGST-Rate, Serial No.12, Heading 9963 or 9972) Nil rate of GST on Services by way of renting of residential dwelling for use as residence. Withdrawal of exemption of GST on renting of residential dwelling to business entities (registered persons). EXISTING RECOMMENDATION<br>
33
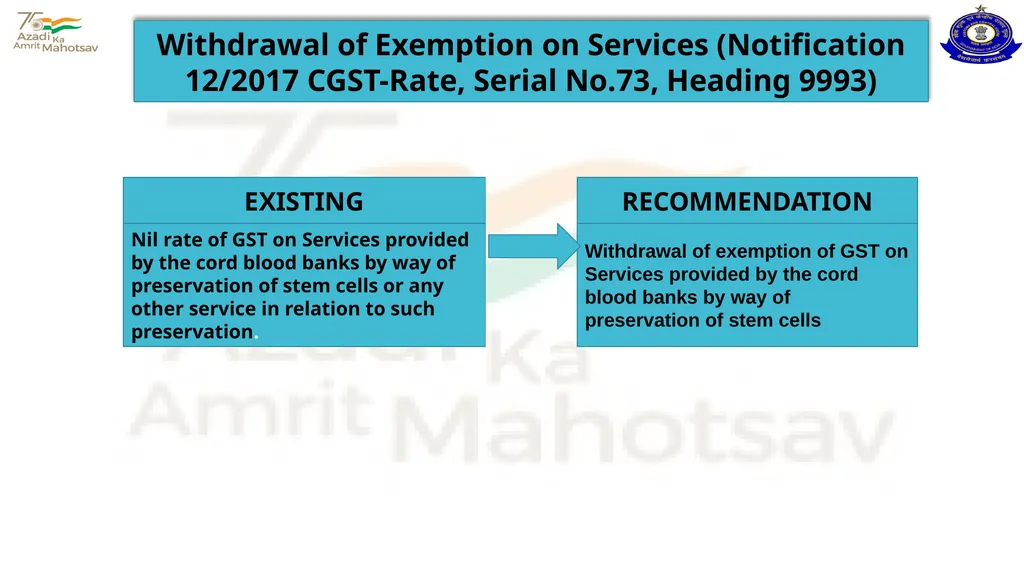
Withdrawal of Exemption on Services (Notification 12/2017 CGST-Rate, Serial No.73, Heading 9993) Nil rate of GST on Services provided by the cord blood banks by way of preservation of stem cells or any other service in relation to such preservation. Withdrawal of exemption of GST on Services provided by the cord blood banks by way of preservation of stem cells EXISTING RECOMMENDATION<br>
34
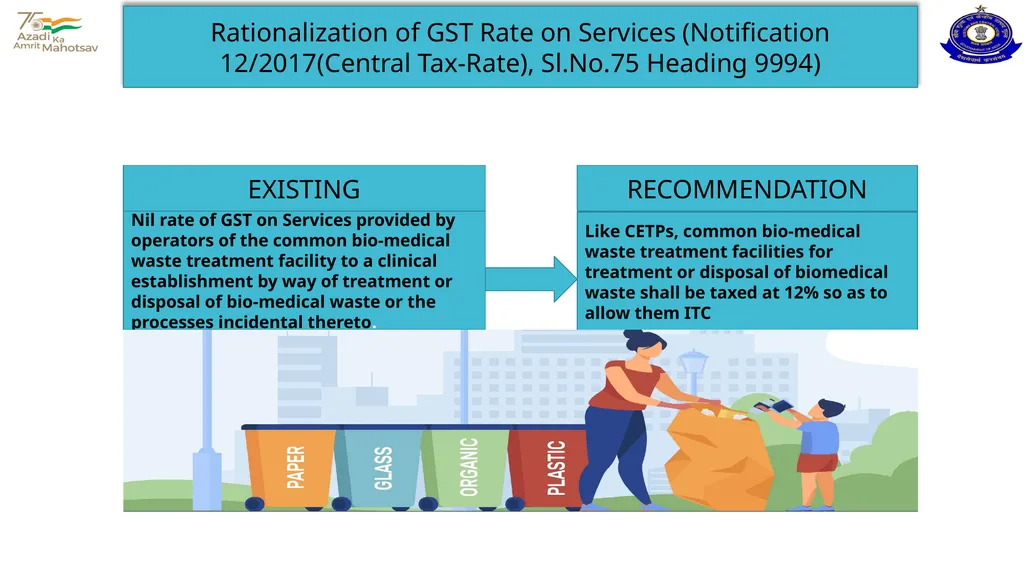
Rationalization of GST Rate on Services (Notification 12/2017(Central Tax-Rate), Sl.No.75 Heading 9994) Nil rate of GST on Services provided by operators of the common bio-medical waste treatment facility to a clinical establishment by way of treatment or disposal of bio-medical waste or the processes incidental thereto. Like CETPs, common bio-medical waste treatment facilities for treatment or disposal of biomedical waste shall be taxed at 12% so as to allow them ITC EXISTING RECOMMENDATION<br>
35
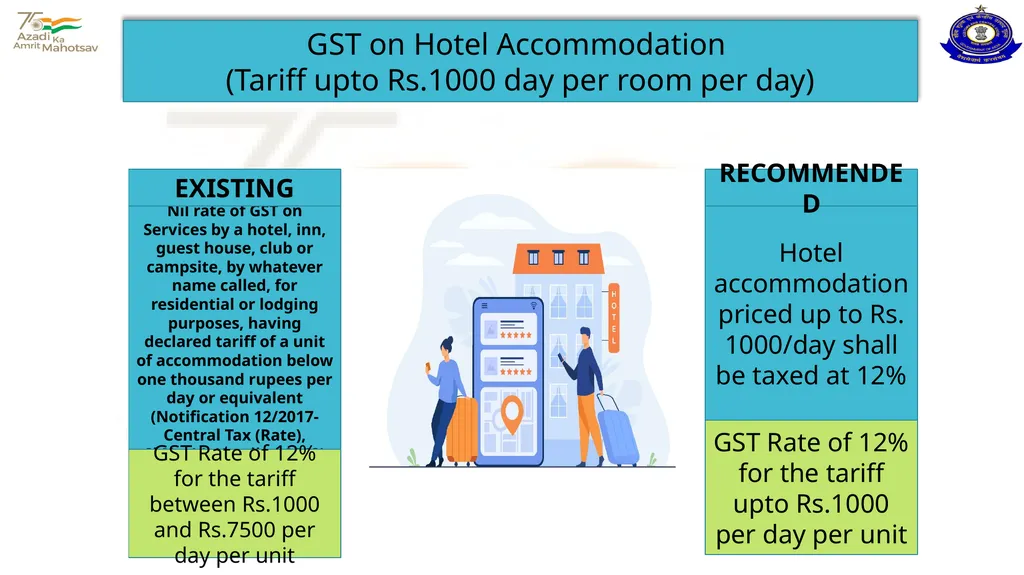
GST on Hotel Accommodation
(Tariff upto Rs.1000 day per room per day) Nil rate of GST on Services by a hotel, inn, guest house, club or campsite, by whatever name called, for residential or lodging purposes, having declared tariff of a unit of accommodation below one thousand rupees per day or equivalent (Notification 12/2017- Central Tax (Rate), Sl.No.14, Heading 9963) Hotel accommodation priced up to Rs. 1000/day shall be taxed at 12% EXISTING RECOMMENDED GST Rate of 12% for the tariff between Rs.1000 and Rs.7500 per day per unit GST Rate of 12% for the tariff upto Rs.1000 per day per unit<br>
(Tariff upto Rs.1000 day per room per day) Nil rate of GST on Services by a hotel, inn, guest house, club or campsite, by whatever name called, for residential or lodging purposes, having declared tariff of a unit of accommodation below one thousand rupees per day or equivalent (Notification 12/2017- Central Tax (Rate), Sl.No.14, Heading 9963) Hotel accommodation priced up to Rs. 1000/day shall be taxed at 12% EXISTING RECOMMENDED GST Rate of 12% for the tariff between Rs.1000 and Rs.7500 per day per unit GST Rate of 12% for the tariff upto Rs.1000 per day per unit<br>
36
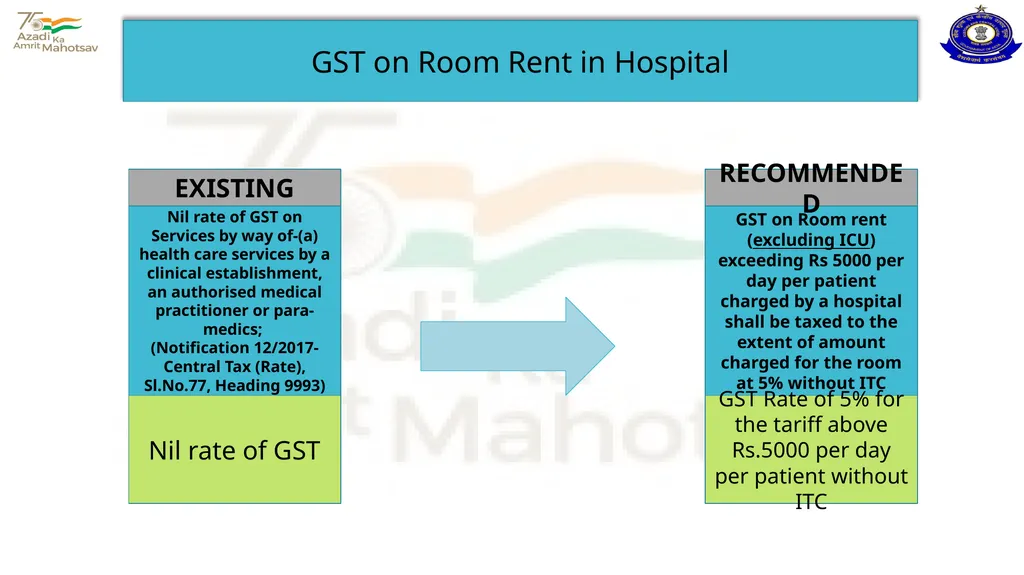
GST on Room Rent in Hospital Nil rate of GST on Services by way of-(a) health care services by a clinical establishment, an authorised medical practitioner or para-medics;
(Notification 12/2017- Central Tax (Rate), Sl.No.77, Heading 9993) GST on Room rent (excluding ICU) exceeding Rs 5000 per day per patient charged by a hospital shall be taxed to the extent of amount charged for the room at 5% without ITC EXISTING RECOMMENDED Nil rate of GST GST Rate of 5% for the tariff above Rs.5000 per day per patient without ITC<br>
(Notification 12/2017- Central Tax (Rate), Sl.No.77, Heading 9993) GST on Room rent (excluding ICU) exceeding Rs 5000 per day per patient charged by a hospital shall be taxed to the extent of amount charged for the room at 5% without ITC EXISTING RECOMMENDED Nil rate of GST GST Rate of 5% for the tariff above Rs.5000 per day per patient without ITC<br>
37
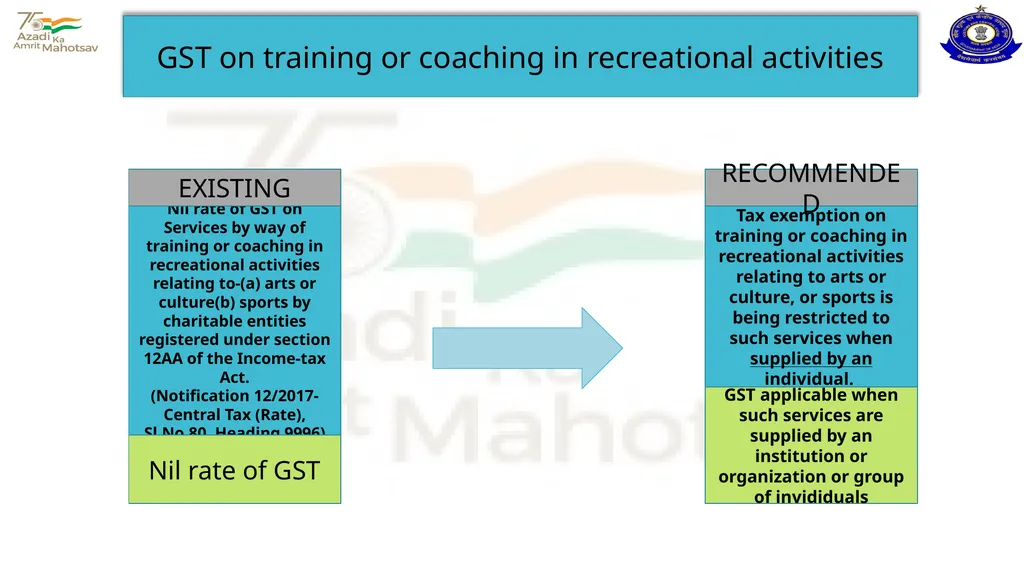
GST on training or coaching in recreational activities Nil rate of GST on Services by way of training or coaching in recreational activities relating to-(a) arts or culture(b) sports by charitable entities registered under section 12AA of the Income-tax Act.
(Notification 12/2017- Central Tax (Rate), Sl.No.80, Heading 9996) Tax exemption on training or coaching in recreational activities relating to arts or culture, or sports is being restricted to such services when supplied by an individual. EXISTING RECOMMENDED Nil rate of GST GST applicable when such services are supplied by an institution or organization or group of invididuals<br>
(Notification 12/2017- Central Tax (Rate), Sl.No.80, Heading 9996) Tax exemption on training or coaching in recreational activities relating to arts or culture, or sports is being restricted to such services when supplied by an individual. EXISTING RECOMMENDED Nil rate of GST GST applicable when such services are supplied by an institution or organization or group of invididuals<br>
38
Rate Rationalization 47th GST Council Meeting<br>
39
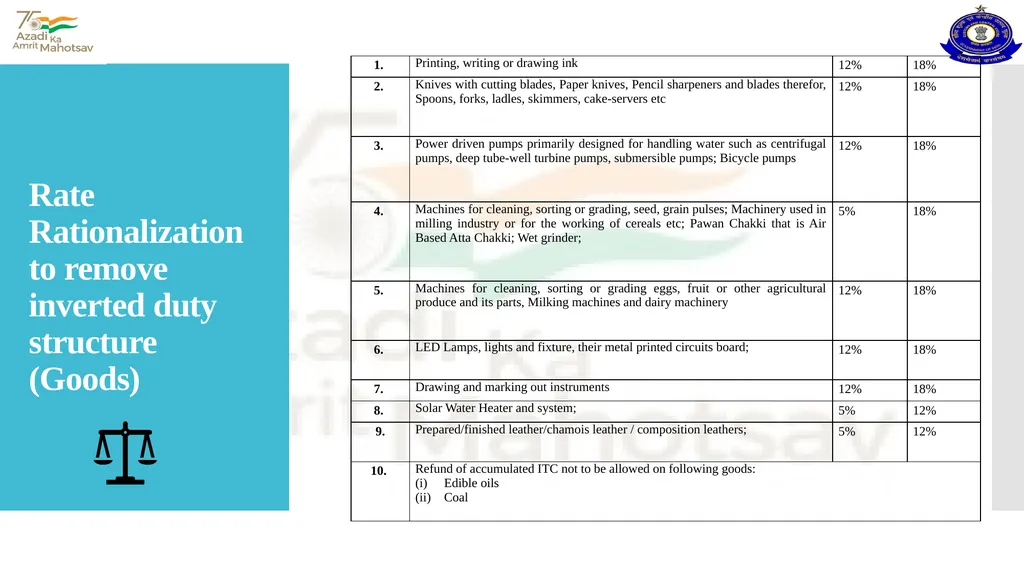
Rate Rationalization to remove inverted duty structure (Goods)<br>
40
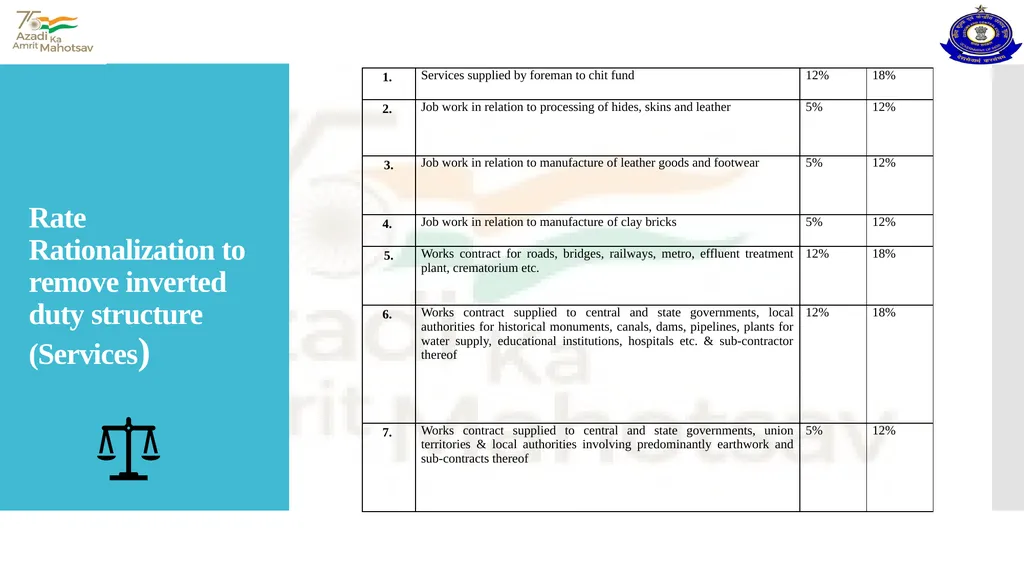
Rate Rationalization to remove inverted duty structure (Services)<br>
41
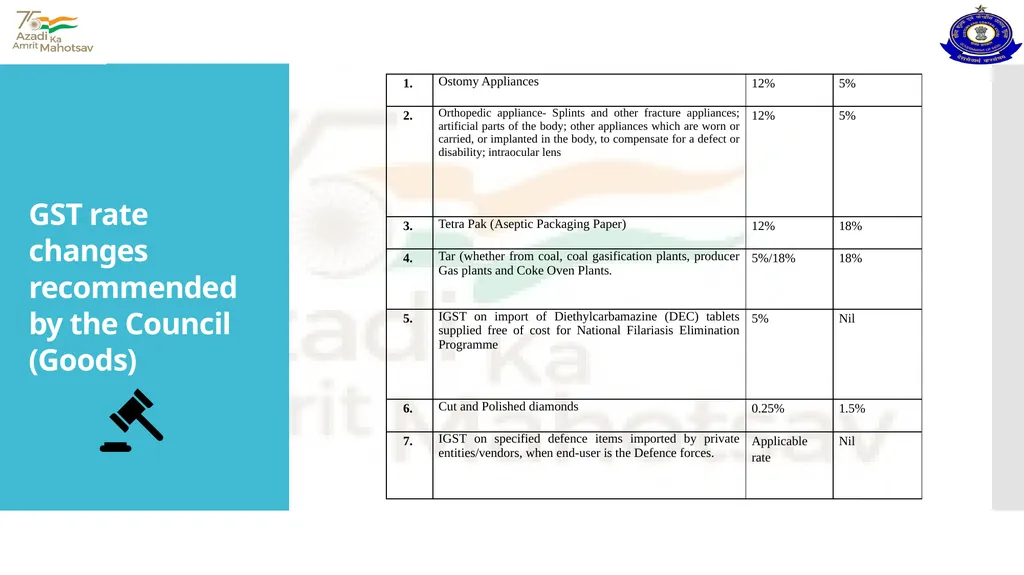
GST rate changes recommended by the Council
(Goods)<br>
42
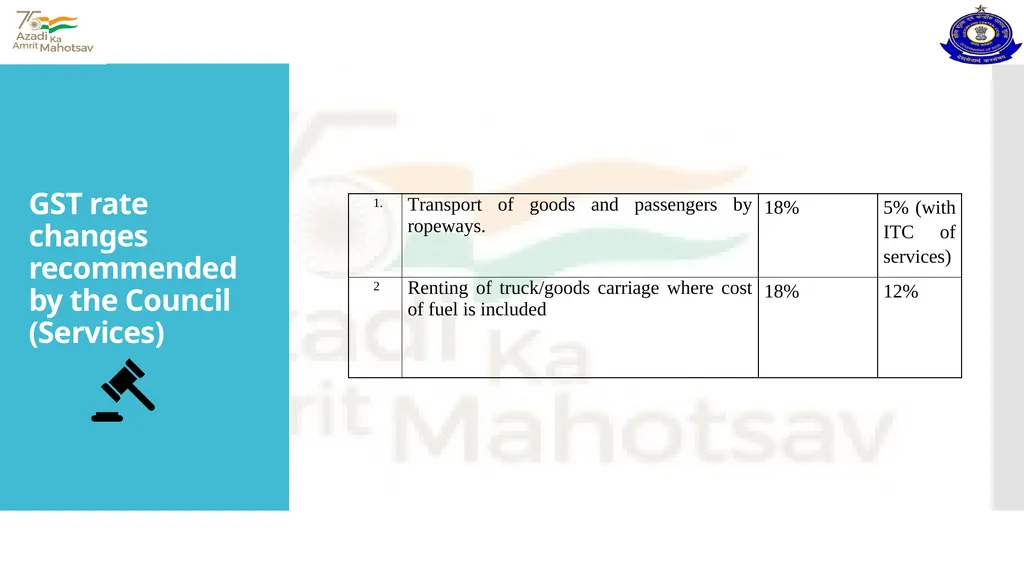
GST rate changes recommended by the Council (Services)<br>
43
Clarification on GST rate
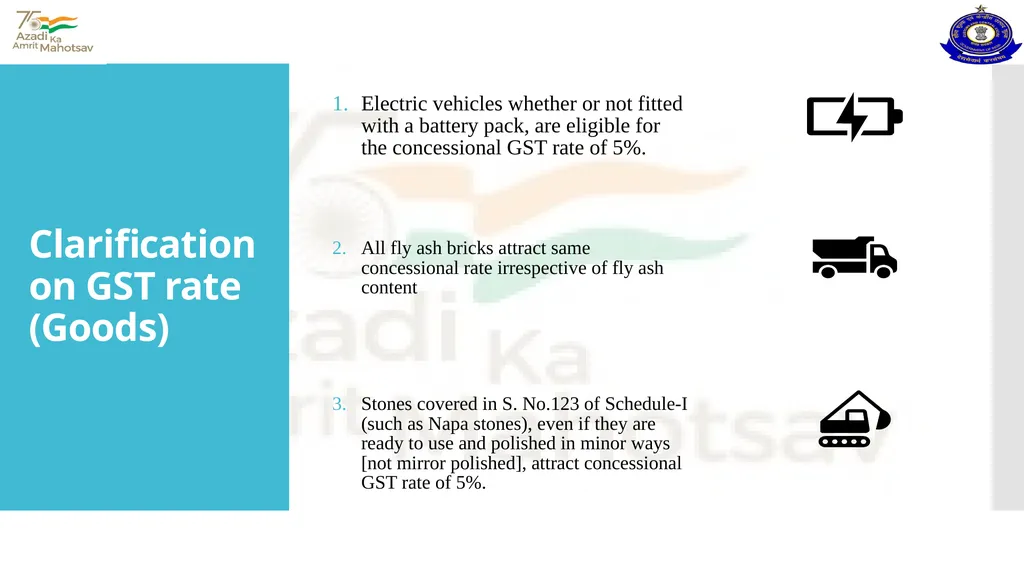
(Goods) Electric vehicles whether or not fitted with a battery pack, are eligible for the concessional GST rate of 5%.
All fly ash bricks attract same concessional rate irrespective of fly ash content
Stones covered in S. No.123 of Schedule-I (such as Napa stones), even if they are ready to use and polished in minor ways [not mirror polished], attract concessional GST rate of 5%.<br>
All fly ash bricks attract same concessional rate irrespective of fly ash content
Stones covered in S. No.123 of Schedule-I (such as Napa stones), even if they are ready to use and polished in minor ways [not mirror polished], attract concessional GST rate of 5%.<br>
44
Clarification on GST rate
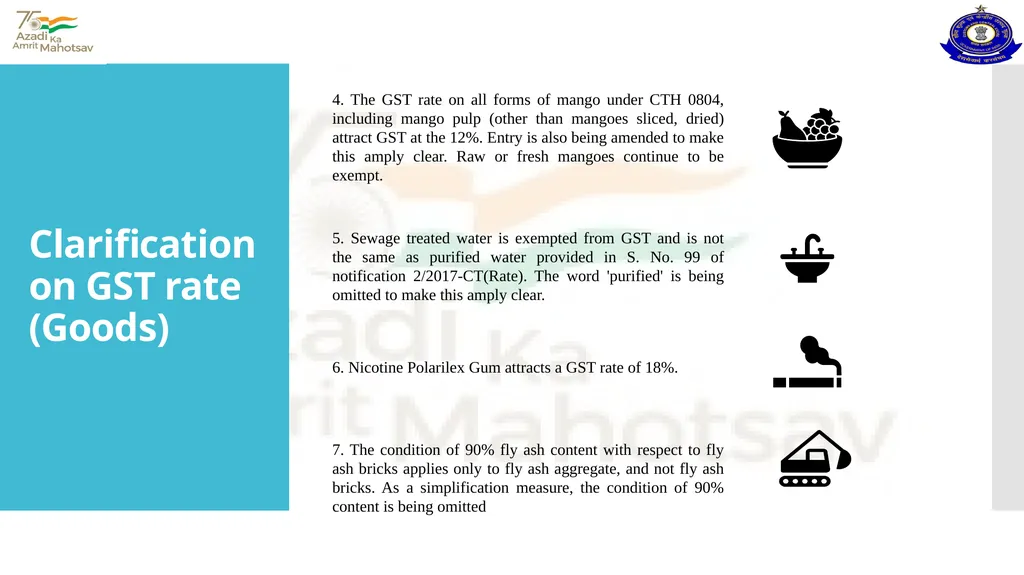
(Goods) 4. The GST rate on all forms of mango under CTH 0804, including mango pulp (other than mangoes sliced, dried) attract GST at the 12%. Entry is also being amended to make this amply clear. Raw or fresh mangoes continue to be exempt.
5. Sewage treated water is exempted from GST and is not the same as purified water provided in S. No. 99 of notification 2/2017-CT(Rate). The word 'purified' is being omitted to make this amply clear.
6. Nicotine Polarilex Gum attracts a GST rate of 18%.
7. The condition of 90% fly ash content with respect to fly ash bricks applies only to fly ash aggregate, and not fly ash bricks. As a simplification measure, the condition of 90% content is being omitted<br>
5. Sewage treated water is exempted from GST and is not the same as purified water provided in S. No. 99 of notification 2/2017-CT(Rate). The word 'purified' is being omitted to make this amply clear.
6. Nicotine Polarilex Gum attracts a GST rate of 18%.
7. The condition of 90% fly ash content with respect to fly ash bricks applies only to fly ash aggregate, and not fly ash bricks. As a simplification measure, the condition of 90% content is being omitted<br>
45
Clarification on GST rate
(Services) 1. Due to ambiguity in GST rates on supply of ice-cream by ice-cream parlours, GST charged @ 5% without ITC on the same during the period 1.07.2017 to 5.10.2021 shall be regularized to avoid unnecessary litigation.
2. Application fee charged for entrance or for issuance of eligibility certificate for admission or issuance of migration certificate by universities is exempt from GST.
3.Ginned or baled fibres is covered in entry 24B of notification No. 12/2017- Central Tax (Rate) dated 28.06.2017 in the category of raw vegetable fibres. The exemption under this entry is being rationalized<br>
2. Application fee charged for entrance or for issuance of eligibility certificate for admission or issuance of migration certificate by universities is exempt from GST.
3.Ginned or baled fibres is covered in entry 24B of notification No. 12/2017- Central Tax (Rate) dated 28.06.2017 in the category of raw vegetable fibres. The exemption under this entry is being rationalized<br>
46
Clarification on GST rate
(Services) 4. Services associated with transit cargo both to and from Nepal and Bhutan are covered by exemption under entry 9B of notification No. 12/2017-CT(R) dated 28.06.2017.
5. Activity of selling of space for advertisement in souvenirs published in the form of books is eligible for concessional GST at 5%.
6. Renting of vehicle with operator for transportation of goods on time basis is classifiable under Heading 9966 (rental services of transport vehicles with operators) and attracts GST at 18%.GST on such renting where cost of fuel is included in the consideration charged is being prescribed at 12%.<br>
5. Activity of selling of space for advertisement in souvenirs published in the form of books is eligible for concessional GST at 5%.
6. Renting of vehicle with operator for transportation of goods on time basis is classifiable under Heading 9966 (rental services of transport vehicles with operators) and attracts GST at 18%.GST on such renting where cost of fuel is included in the consideration charged is being prescribed at 12%.<br>
47
Clarification on GST rate
(Services) 7. Allowing choice of location of a plot is part of supply of long term lease of plot of land. Therefore, location charge or preferential location charges (PLC) are part of consideration charged for long term lease of land and shall get the same treatment under GST.
8. Services provided by the guest anchors to TV channels in lieu of honorarium attract GST.
9. Additional fee collected in the form of higher toll charges from vehicles not having Fastag is essentially payment of toll for allowing access to roads or bridges to such vehicles and shall be given the same tax treatment as given to toll charges.<br>
8. Services provided by the guest anchors to TV channels in lieu of honorarium attract GST.
9. Additional fee collected in the form of higher toll charges from vehicles not having Fastag is essentially payment of toll for allowing access to roads or bridges to such vehicles and shall be given the same tax treatment as given to toll charges.<br>
48
Clarification on GST rate
(Services) 10.Services in form of Assisted Reproductive Technology (ART)/ In vitro fertilization (IVF) are covered under the definition of health care services for the purpose of exemption under GST.
11.. Sale of land after leveling, laying down of drainage lines etc. is sale of land and does not attract GST.
12. Renting of motor vehicles for transport of passengers to a body corporate for a period (time) is taxable in the hands of body corporate under RCM.
13. The expression ‘public transport’ used in the exemption entry at SI No. 17(d) of notification No. 12/2017-CT(R), which exempts transport of passengers by public transport other than predominantly for tourism purpose, in a vessel between places located in India, means thatsuch transport should be open to public for point to point transport [e.g. such transport in Andaman and Nicobar islands].<br>
11.. Sale of land after leveling, laying down of drainage lines etc. is sale of land and does not attract GST.
12. Renting of motor vehicles for transport of passengers to a body corporate for a period (time) is taxable in the hands of body corporate under RCM.
13. The expression ‘public transport’ used in the exemption entry at SI No. 17(d) of notification No. 12/2017-CT(R), which exempts transport of passengers by public transport other than predominantly for tourism purpose, in a vessel between places located in India, means thatsuch transport should be open to public for point to point transport [e.g. such transport in Andaman and Nicobar islands].<br>
49
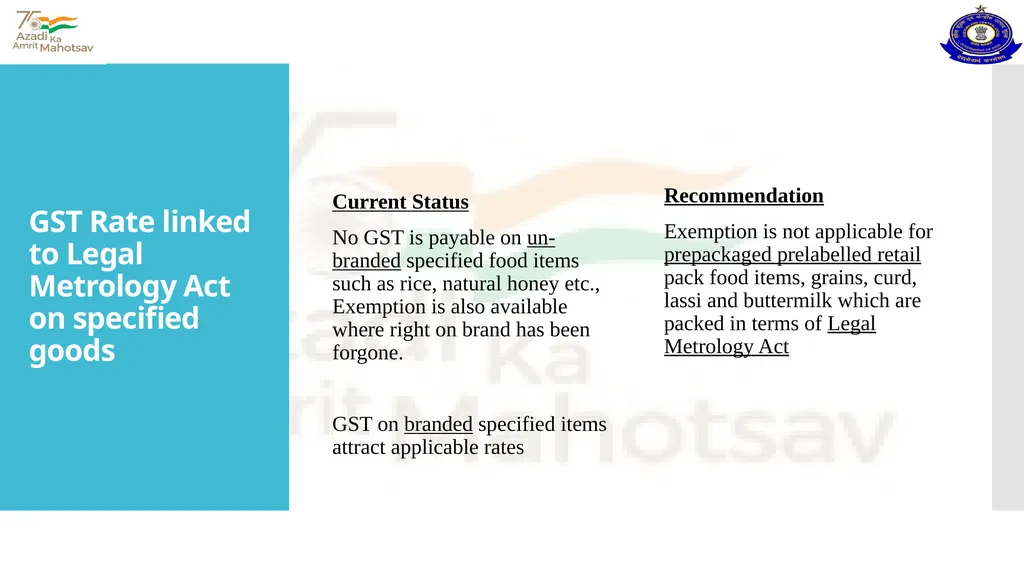
GST Rate linked to Legal Metrology Act on specified goods Current Status
No GST is payable on un-branded specified food items such as rice, natural honey etc., Exemption is also available where right on brand has been forgone.
GST on branded specified items attract applicable rates Recommendation
Exemption is not applicable for prepackaged prelabelled retail pack food items, grains, curd, lassi and buttermilk which are packed in terms of Legal Metrology Act<br>
No GST is payable on un-branded specified food items such as rice, natural honey etc., Exemption is also available where right on brand has been forgone.
GST on branded specified items attract applicable rates Recommendation
Exemption is not applicable for prepackaged prelabelled retail pack food items, grains, curd, lassi and buttermilk which are packed in terms of Legal Metrology Act<br>
50
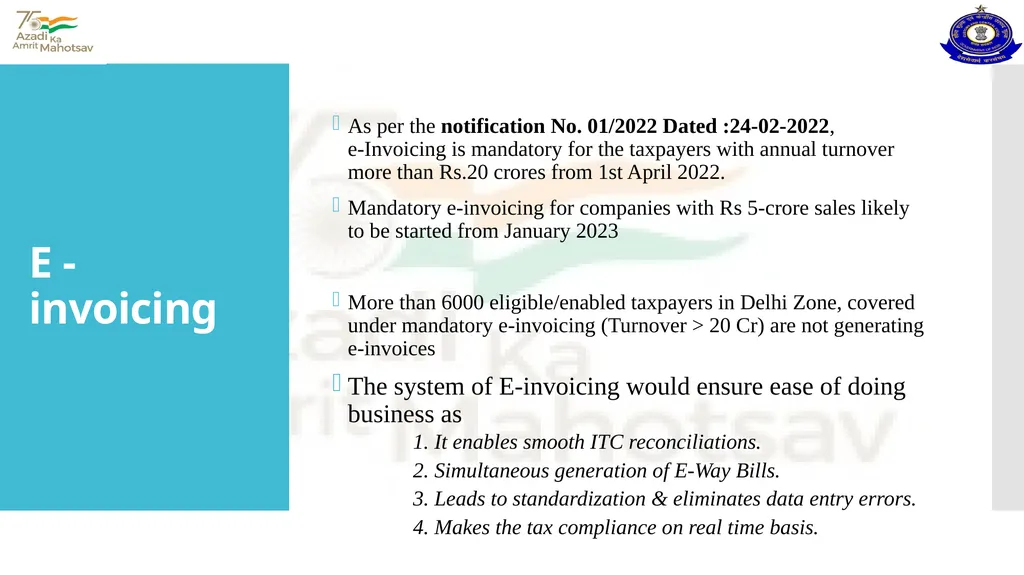
E -invoicing As per the notification No. 01/2022 Dated :24-02-2022, e-Invoicing is mandatory for the taxpayers with annual turnover more than Rs.20 crores from 1st April 2022.
Mandatory e-invoicing for companies with Rs 5-crore sales likely to be started from January 2023
More than 6000 eligible/enabled taxpayers in Delhi Zone, covered under mandatory e-invoicing (Turnover > 20 Cr) are not generating e-invoices
The system of E-invoicing would ensure ease of doing business as
1. It enables smooth ITC reconciliations.
2. Simultaneous generation of E-Way Bills.
3. Leads to standardization & eliminates data entry errors.
4. Makes the tax compliance on real time basis.<br>
Mandatory e-invoicing for companies with Rs 5-crore sales likely to be started from January 2023
More than 6000 eligible/enabled taxpayers in Delhi Zone, covered under mandatory e-invoicing (Turnover > 20 Cr) are not generating e-invoices
The system of E-invoicing would ensure ease of doing business as
1. It enables smooth ITC reconciliations.
2. Simultaneous generation of E-Way Bills.
3. Leads to standardization & eliminates data entry errors.
4. Makes the tax compliance on real time basis.<br>
51
THANK YOU<br>