
© Institute for Fiscal Studies The wealth and


Description: Institute for Fiscal Studies The wealth and saving of UK families on the eve of the crisis Thomas F. Crossley and Cormac ODea Institute for Fiscal Studies Institute for Fiscal Studies IFS Retirement Saving Consortium Association of
Related Topics
Download Presentation
"© Institute for Fiscal Studies The wealth and" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. © Institute for Fiscal Studies The wealth and saving of UK families on the eve of the crisis Thomas F. Crossley and Cormac O’Dea
Institute for Fiscal Studies<br>
slide2. © Institute for Fiscal Studies IFS Retirement Saving Consortium Association of British Insurers
Bank of England
Barclays
Chartered Institute of Personnel and Development
Department for Work and Pensions
Financial Services Authority HM Revenue and Customs
HM Treasury
Investment Management Association
Pensions Regulator
Personal Accounts Delivery Authority
Scottish Widows
The Actuarial Profession<br>
slide3. © Institute for Fiscal Studies Motivation for this research: Where to look to study Household Saving? Most high profile measure of Household Saving is the ONS Household Saving Ratio, released quarterly.
This is a measure of the total saving undertaken in the economy<br>
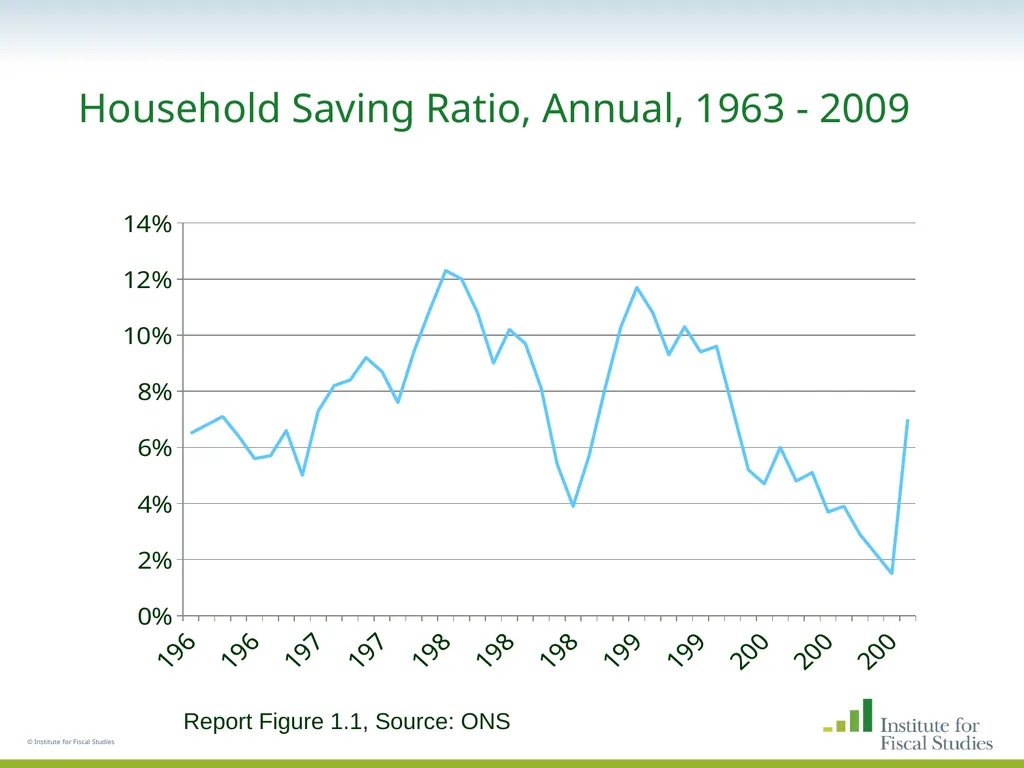
slide4. © Institute for Fiscal Studies Household Saving Ratio, Annual, 1963 - 2009 Report Figure 1.1, Source: ONS<br>
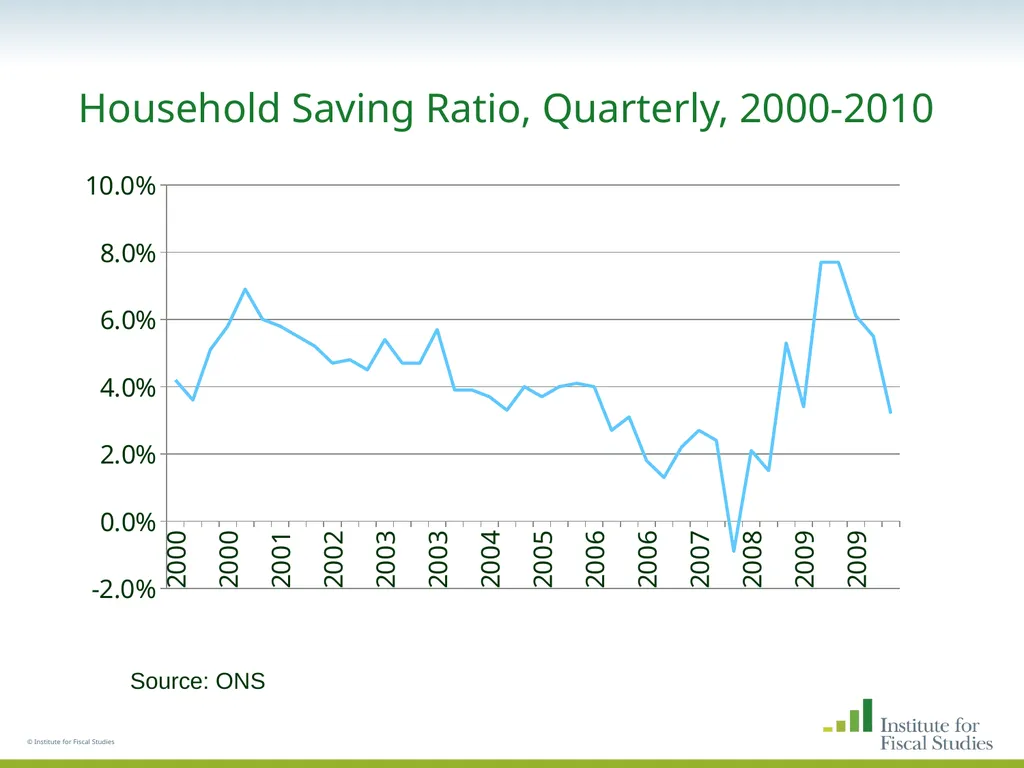
slide5. © Institute for Fiscal Studies Household Saving Ratio, Quarterly, 2000-2010 Source: ONS<br>
slide6. © Institute for Fiscal Studies Household Saving Ratio The most high profile measure of Household Saving is the ONS Household Saving Ratio, released quarterly.
This is a measure of the total saving undertaken in the economy
A useful summary of the total volume of saving being done in the economy.
But we would caution against relying on it for questions related to the adequacy of wealth for retirement
It is dominated by the saving of the those with the greatest income.
Contains limited information about trends in saving among those with low and middle incomes.
An economy-wide average: contains no information on distributional questions such as who saves and who doesn’t.
Measured with a great deal of uncertainty
Calculated as the difference between two large aggregates, themselves measured with error.<br>
slide7. Can we look at household saving using microdata? © Institute for Fiscal Studies<br>
slide8. © Institute for Fiscal Studies In the report, using the British Household Panel Survey, we calculate two measures of wealth... Liquid Financial Wealth
Balances in savings accounts plus bonds/equities less non-mortgage debt
Financial and Housing Wealth
Liquid Financial Wealth plus value of housing less outstanding mortgage debt
Use these measures to:
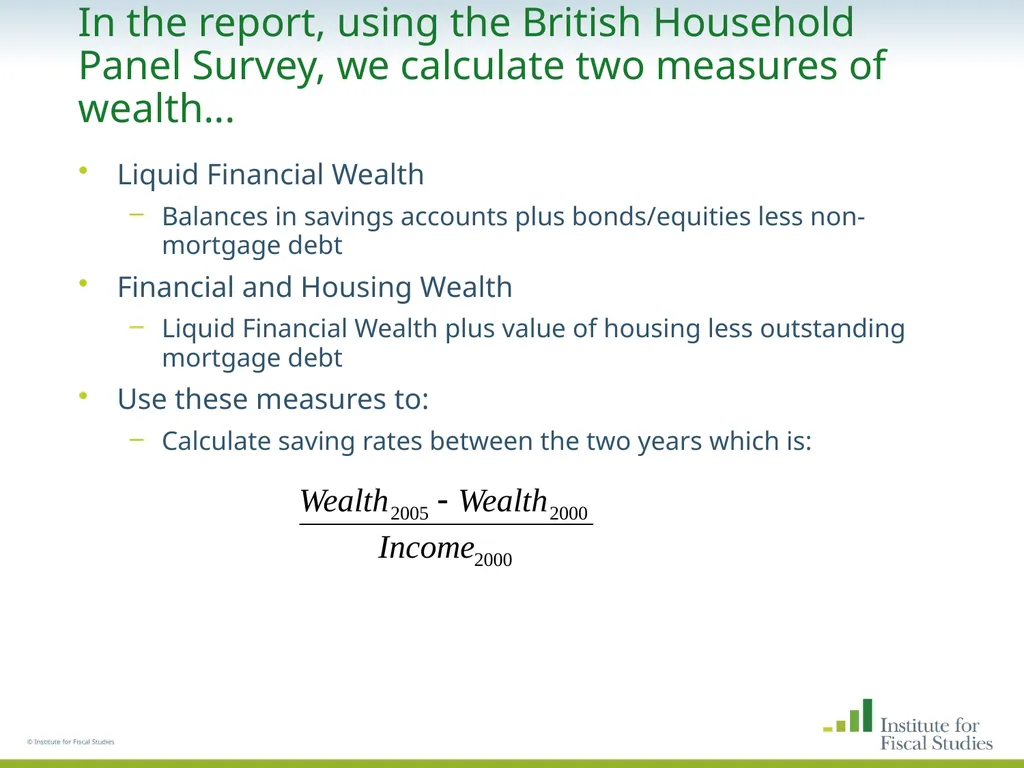
Calculate saving rates between the two years which is:<br>
slide9. © Institute for Fiscal Studies In the report, using the British Household Panel Survey, we calculate two measures of wealth... Liquid Financial Wealth
Balances in savings accounts plus bonds/equities less non-mortgage debt
Financial and Housing Wealth
Liquid Financial Wealth plus value of housing less outstanding mortgage debt
Use these measures to:
Calculate saving rates between the two years which is:<br>
slide10. ...and summarise the distribution of wealth and saving according to household type We define family groups according to:
Age, Income, Family Type, Housing Tenure, Pension Payments
Summarise the distribution of wealth and saving for each group
Family level analysis
A family is defined as a single adult or couple with any dependent children
What important assets are we missing from the data?
Cash and current account balances
Pension Wealth © Institute for Fiscal Studies<br>
slide11. © Institute for Fiscal Studies The rest of this presentation.... Summary of wealth distribution in 2005
Illustrate patterns by age, income
Summary of saving behaviour between 2000 and 2005
Again, illustrate patterns by age, income
Dramatic differences in saving rate depending on whether changes in housing equity are included in saving or not<br>
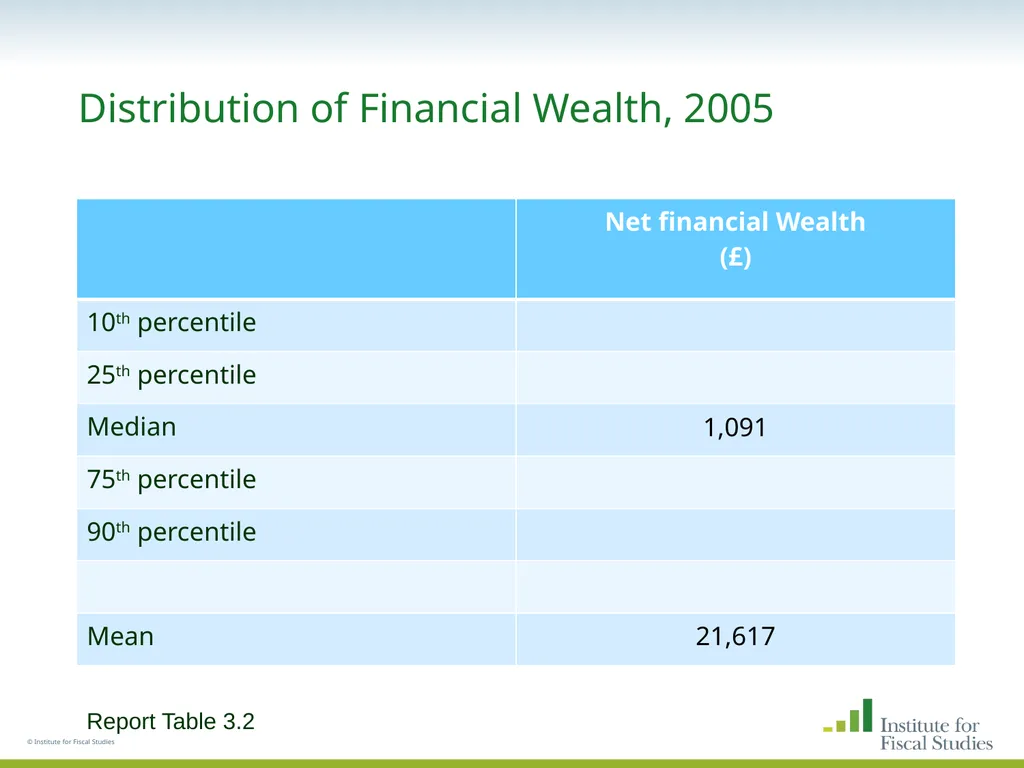
slide12. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies Report Table 3.2<br>
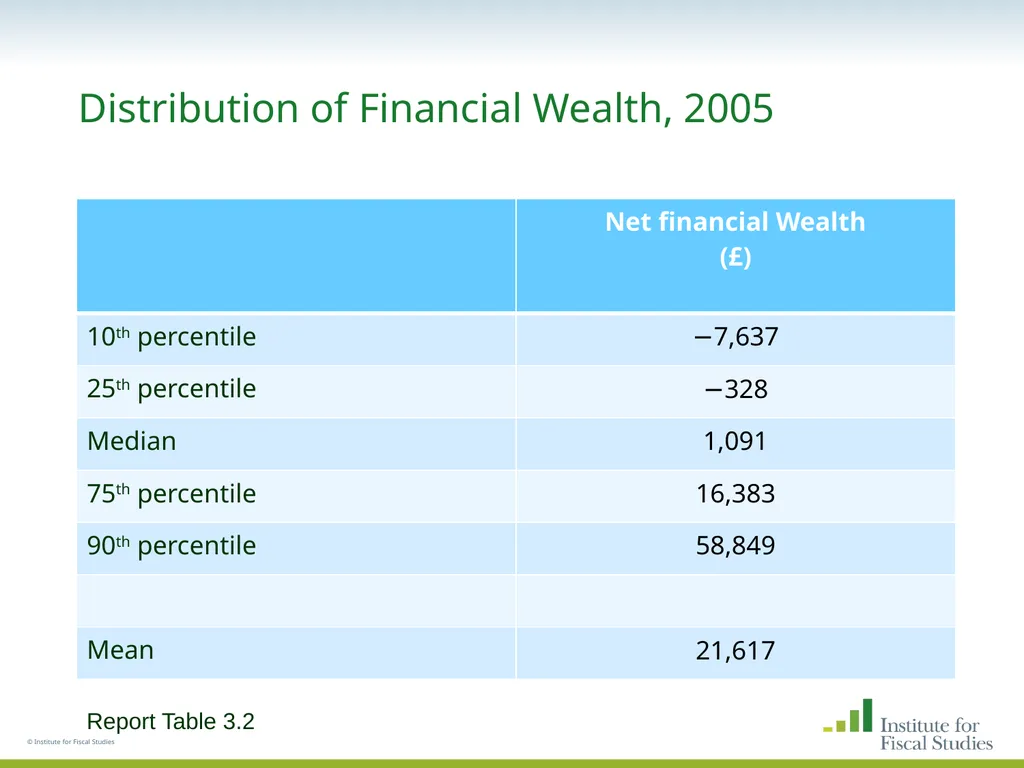
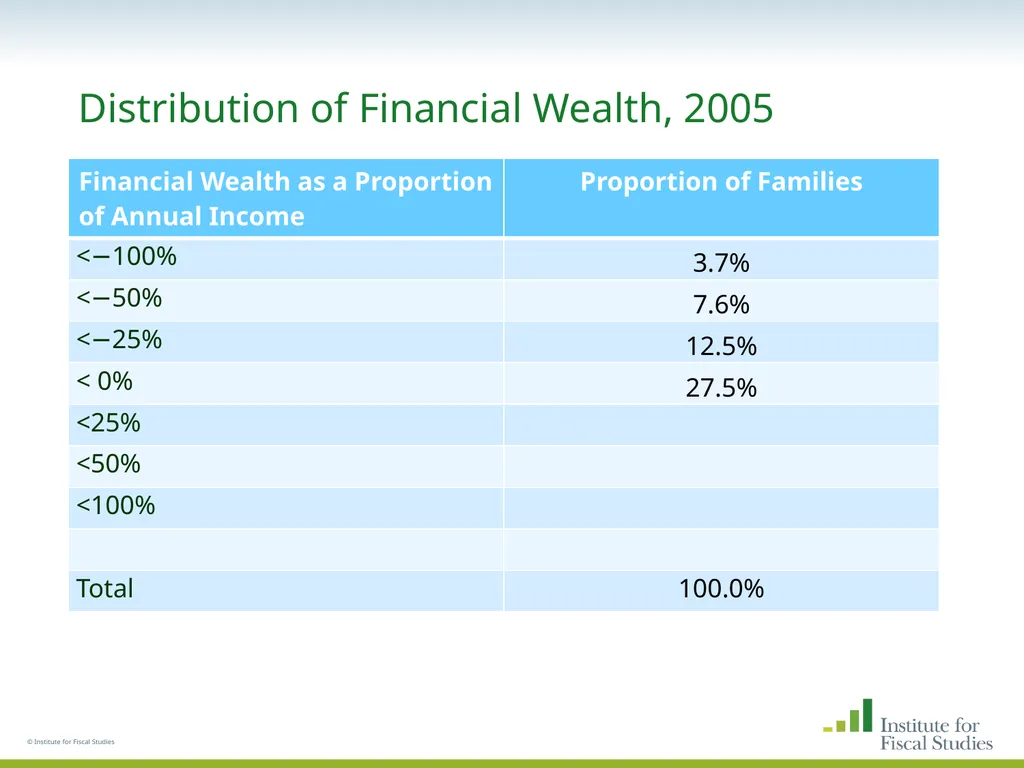
slide13. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies Report Table 3.2<br>
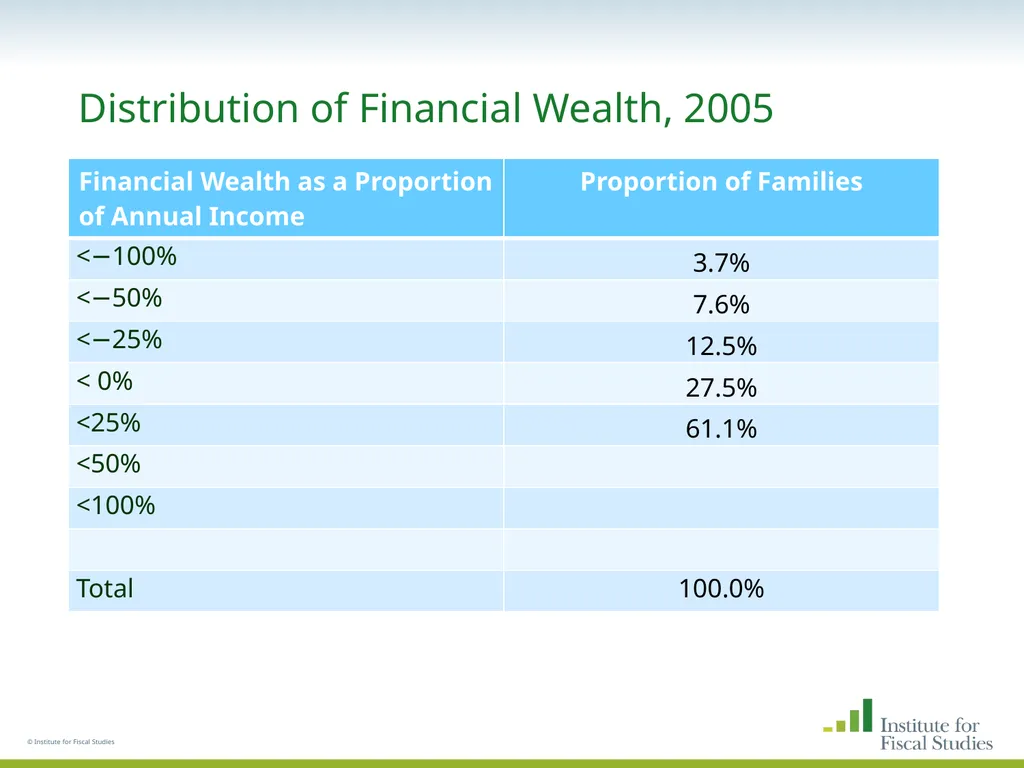
slide14. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
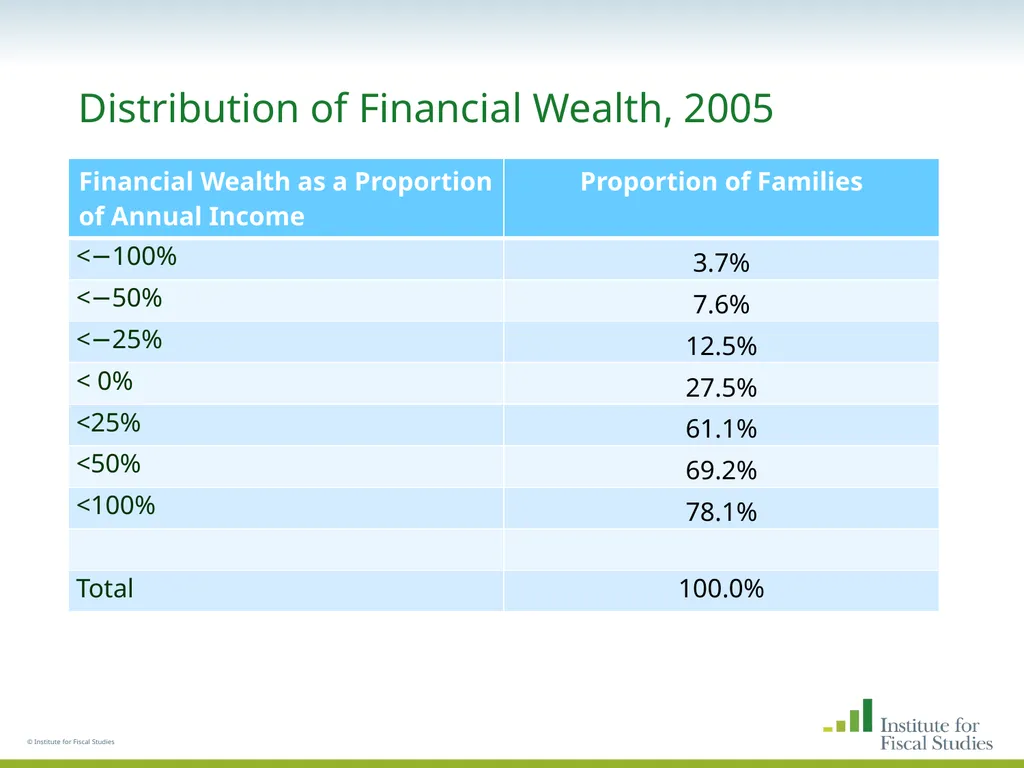
slide15. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
slide16. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
slide17. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
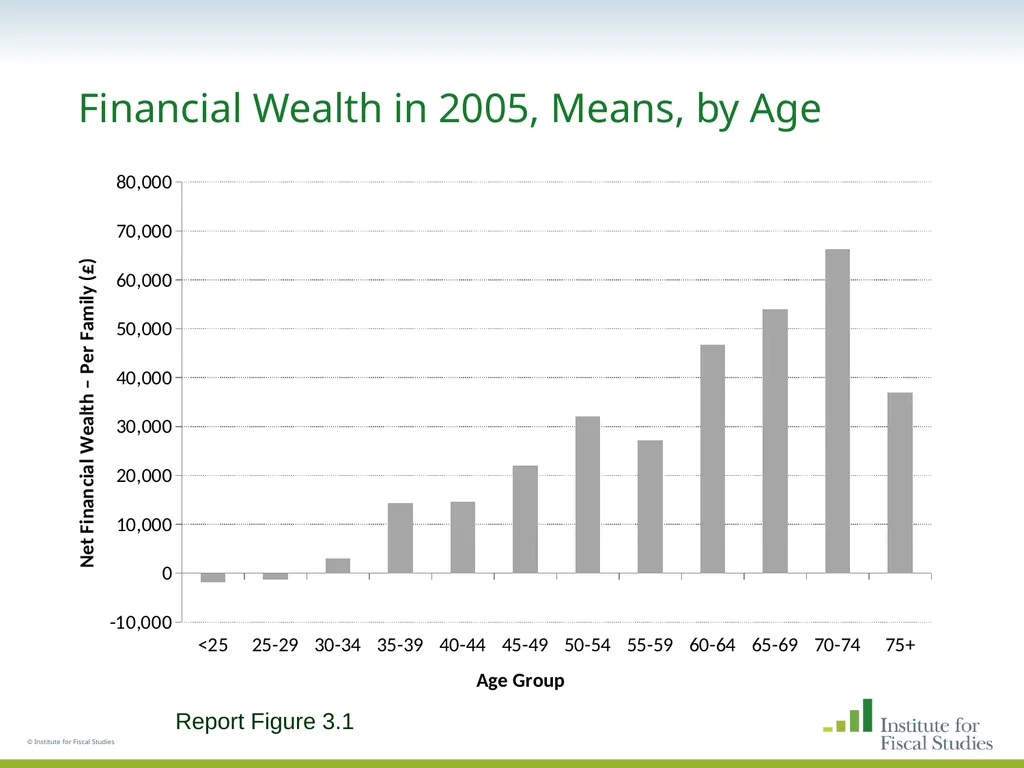
slide18. Financial Wealth in 2005, Means, by Age © Institute for Fiscal Studies Report Figure 3.1<br>
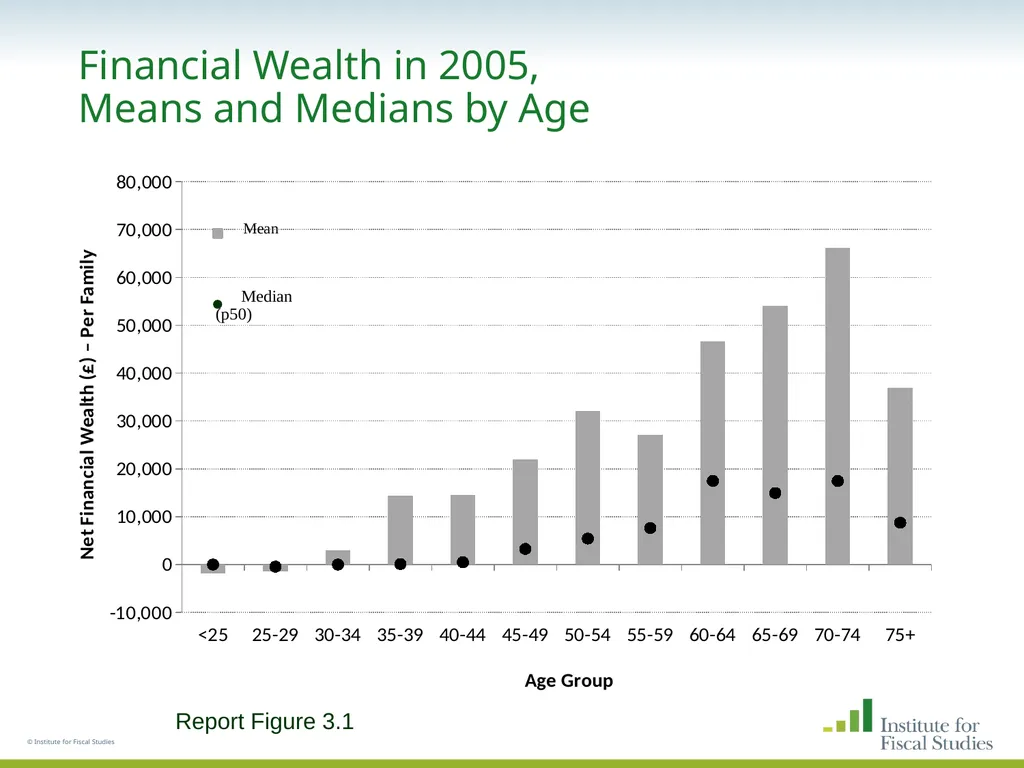
slide19. Financial Wealth in 2005, Means and Medians by Age © Institute for Fiscal Studies Report Figure 3.1<br>
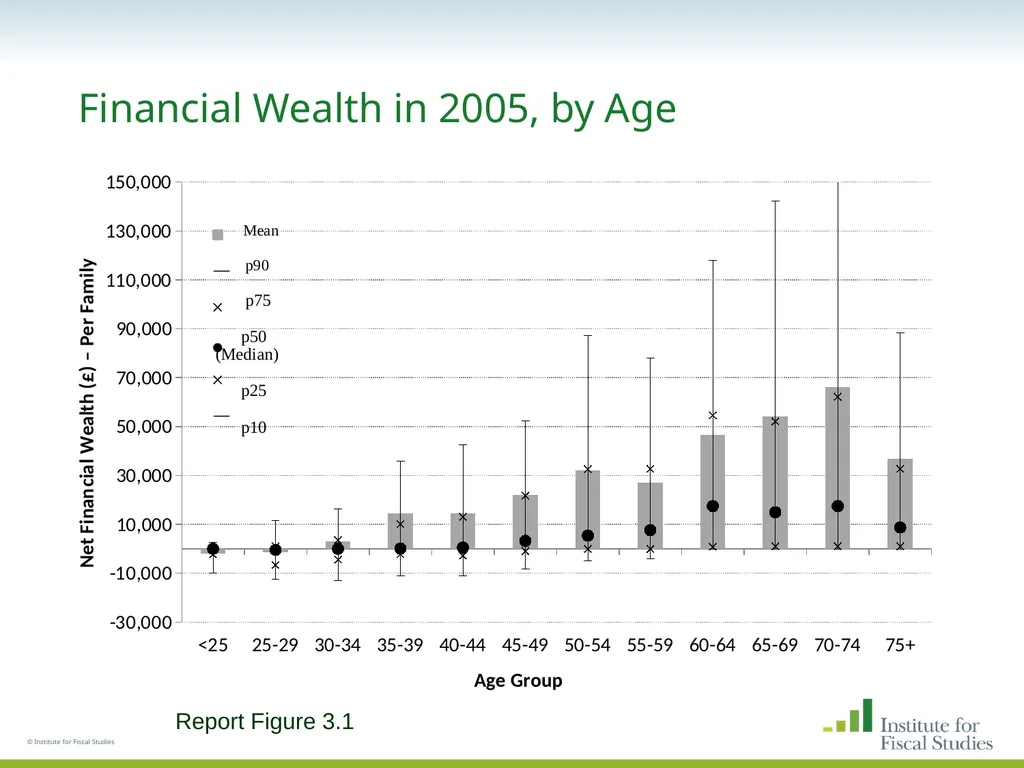
slide20. Financial Wealth in 2005, by Age © Institute for Fiscal Studies Report Figure 3.1<br>
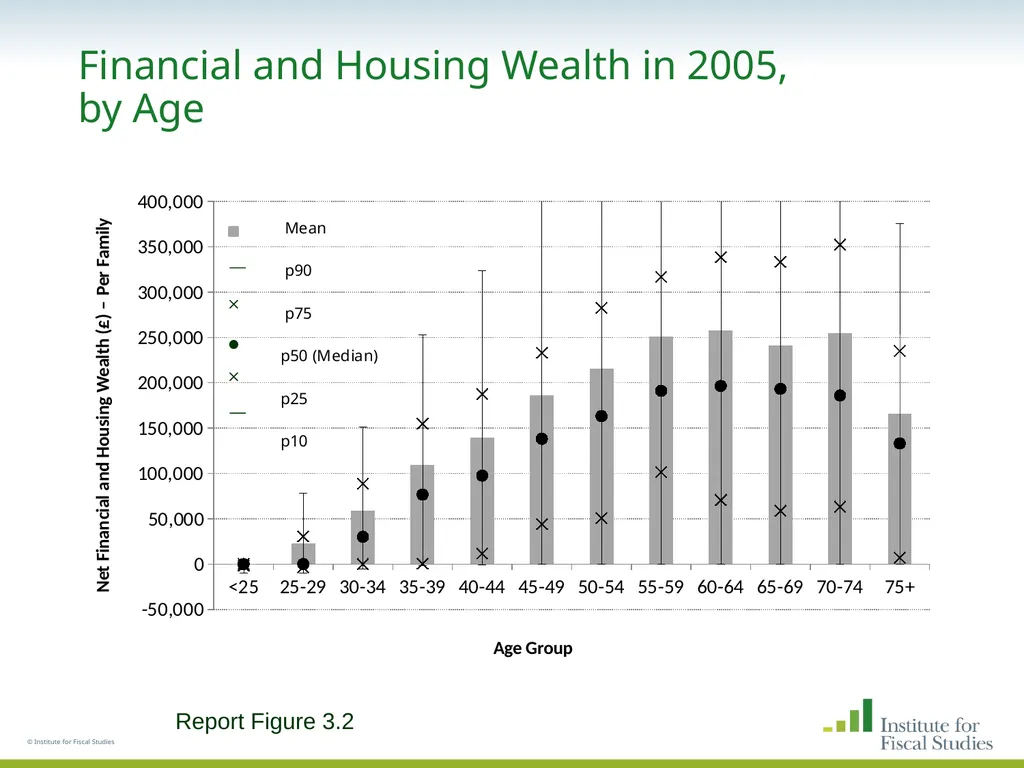
slide21. Financial and Housing Wealth in 2005, by Age © Institute for Fiscal Studies Report Figure 3.2<br>
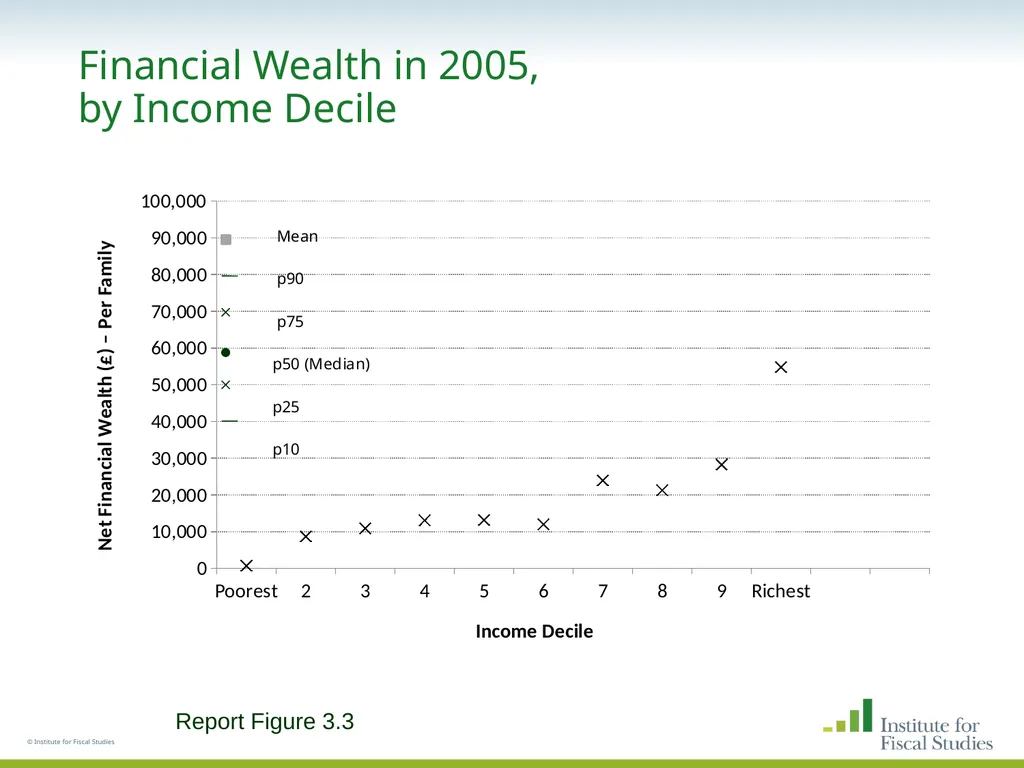
slide22. Financial Wealth in 2005, by Income Decile © Institute for Fiscal Studies Report Figure 3.3<br>
slide23. What happened to the wealth distribution between 2000 and 2005? © Institute for Fiscal Studies<br>
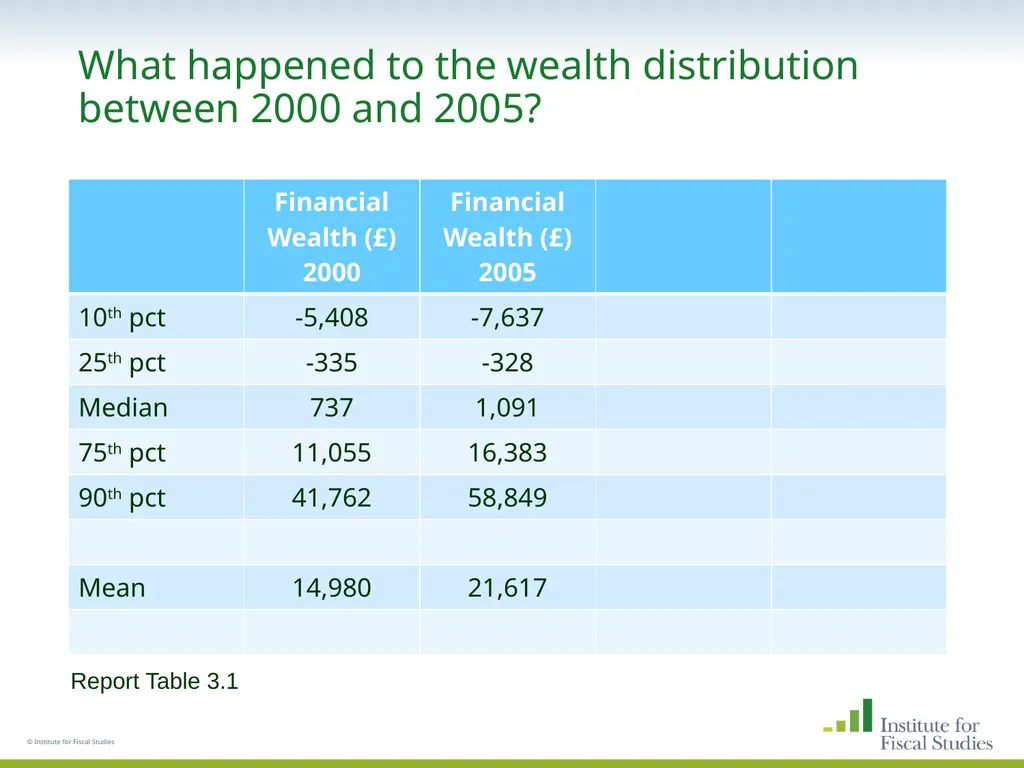
slide24. What happened to the wealth distribution between 2000 and 2005? © Institute for Fiscal Studies Report Table 3.1<br>
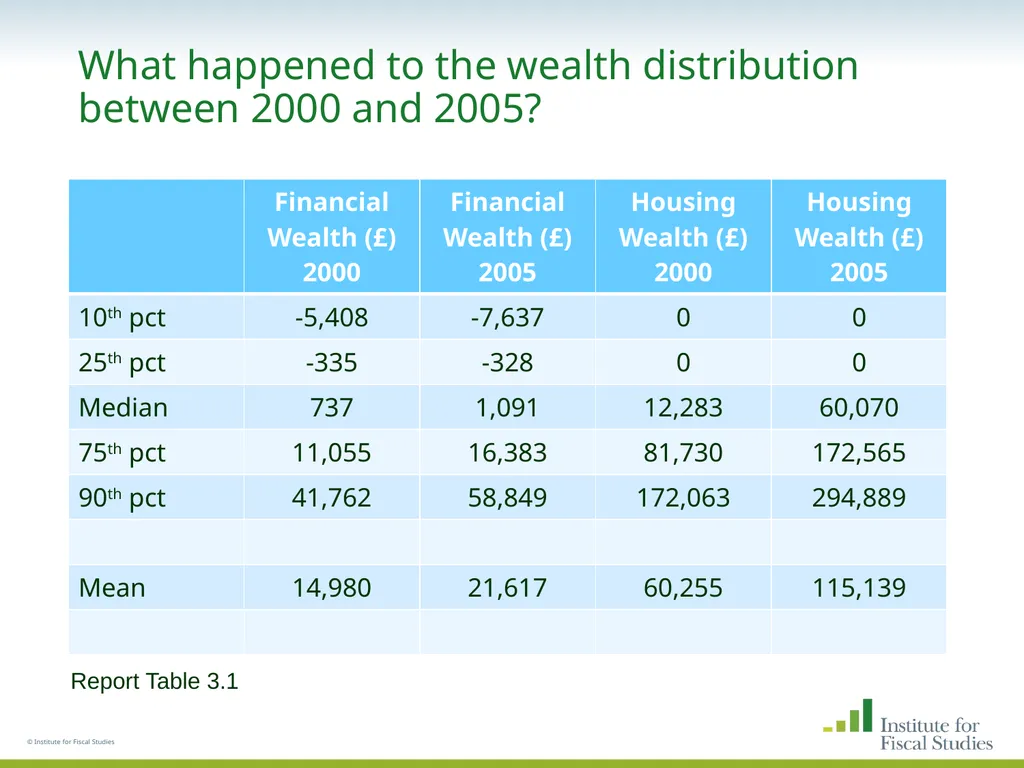
slide25. What happened to the wealth distribution between 2000 and 2005? © Institute for Fiscal Studies Report Table 3.1<br>
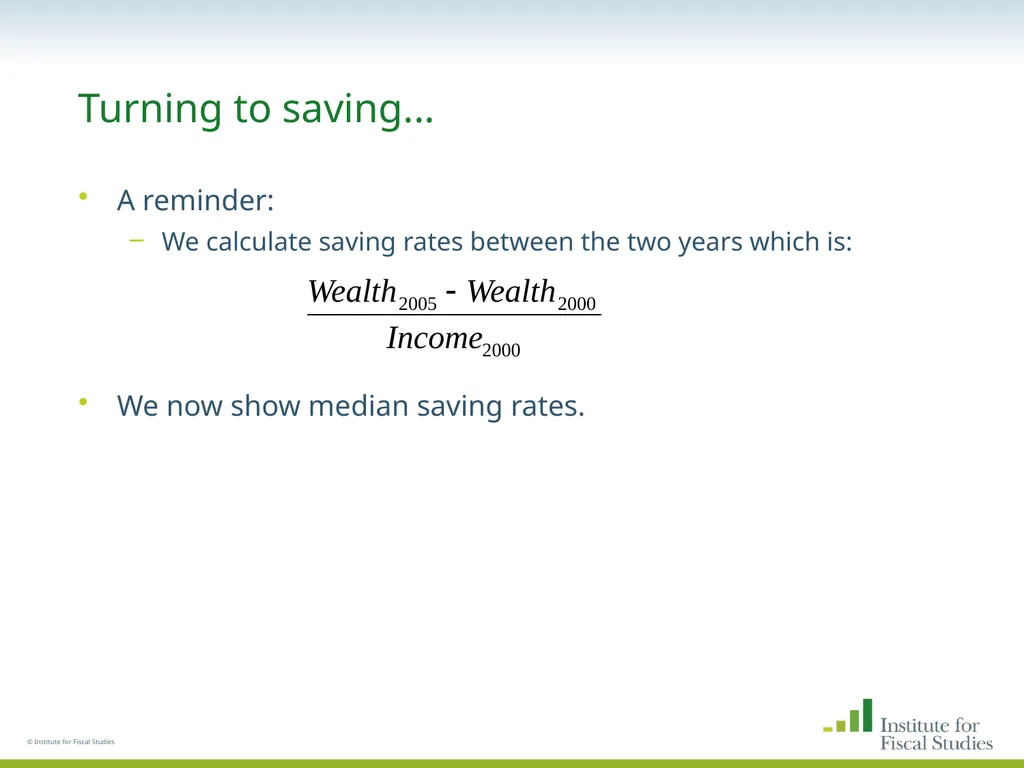
slide26. Turning to saving... A reminder:
We calculate saving rates between the two years which is:
We now show median saving rates. © Institute for Fiscal Studies<br>
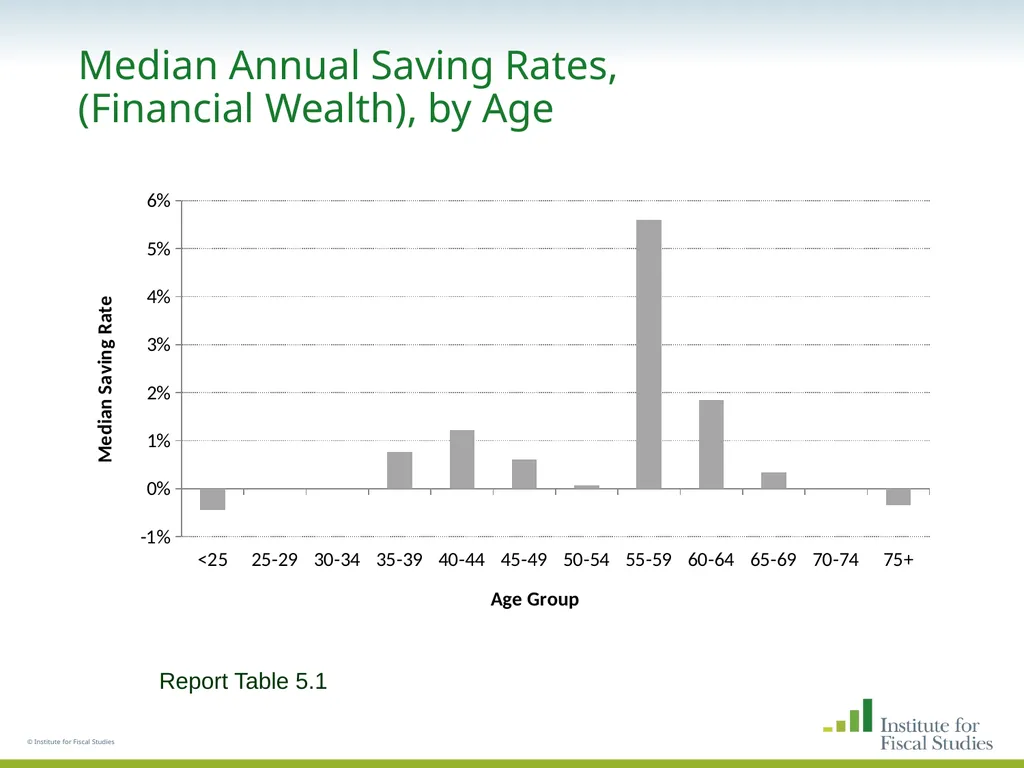
slide27. Median Annual Saving Rates, (Financial Wealth), by Age © Institute for Fiscal Studies Report Table 5.1<br>
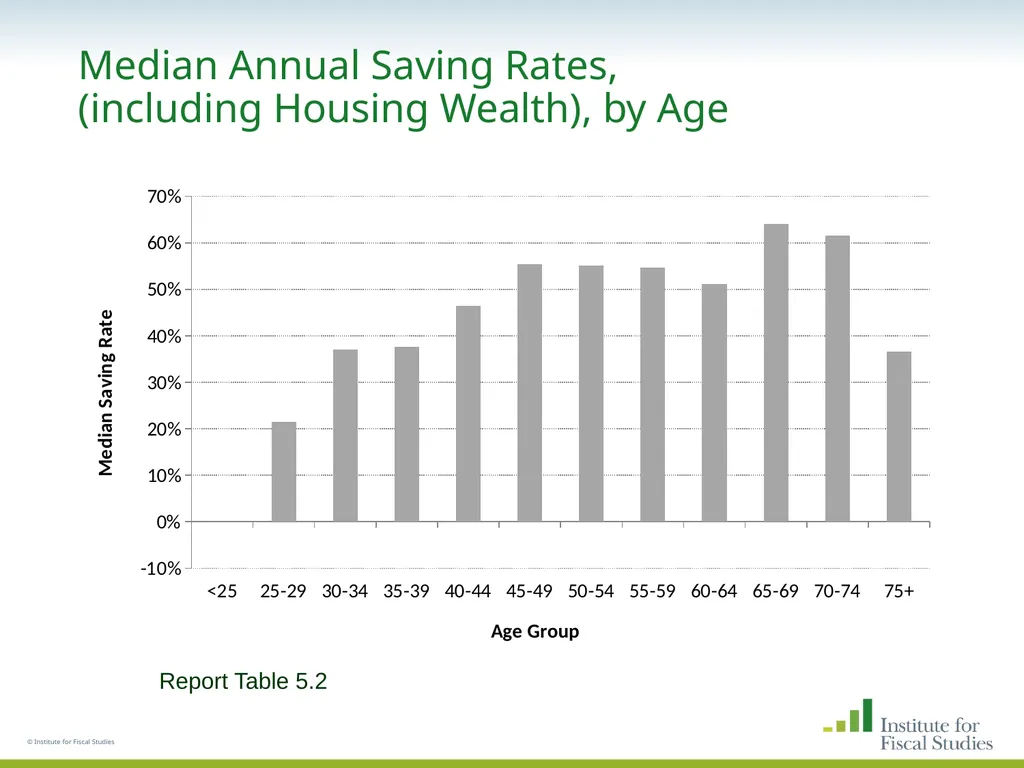
slide28. Median Annual Saving Rates, (including Housing Wealth), by Age © Institute for Fiscal Studies Report Table 5.2<br>
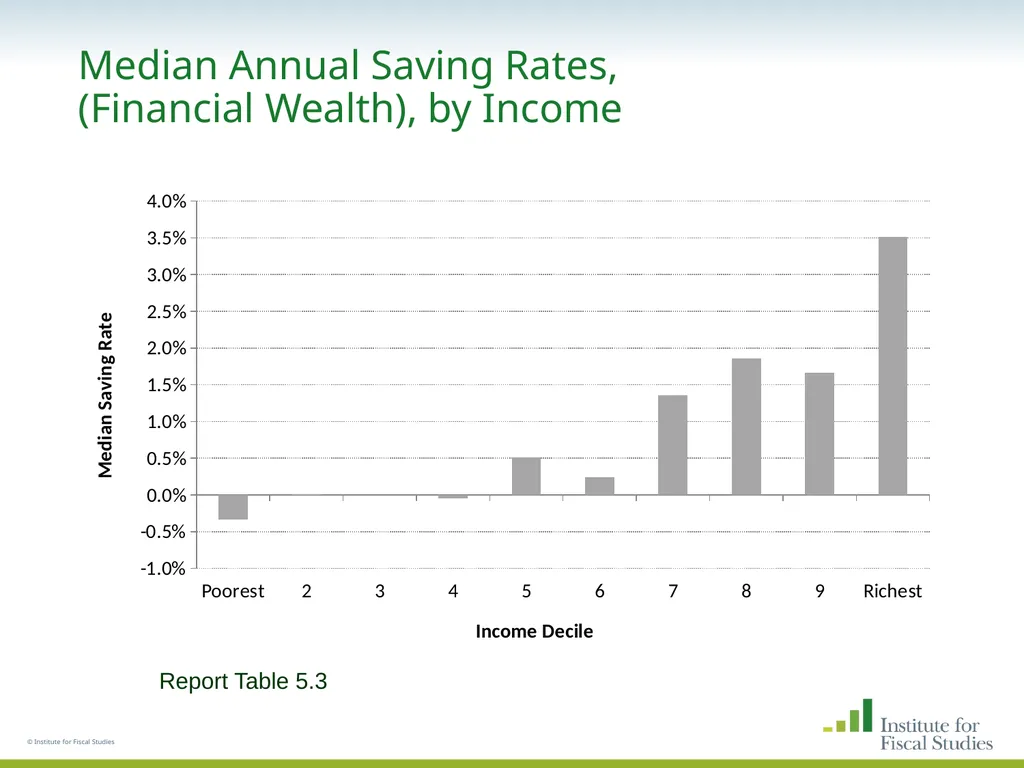
slide29. Median Annual Saving Rates, (Financial Wealth), by Income © Institute for Fiscal Studies Report Table 5.3<br>
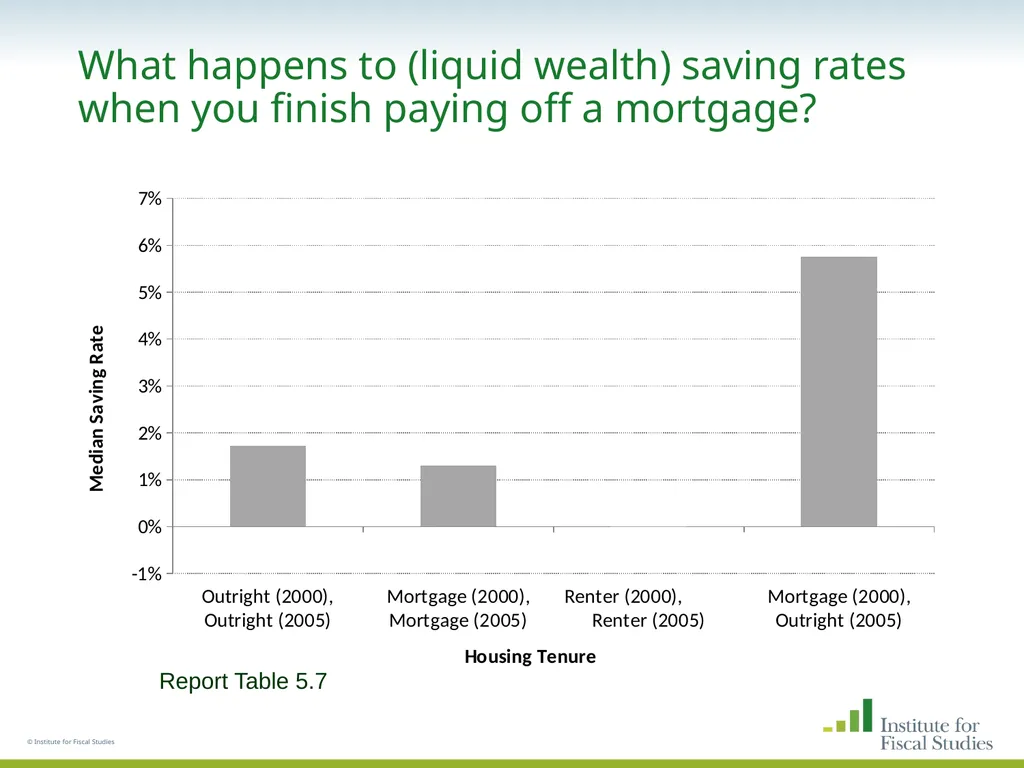
slide30. What happens to (liquid wealth) saving rates when you finish paying off a mortgage? © Institute for Fiscal Studies Report Table 5.7<br>
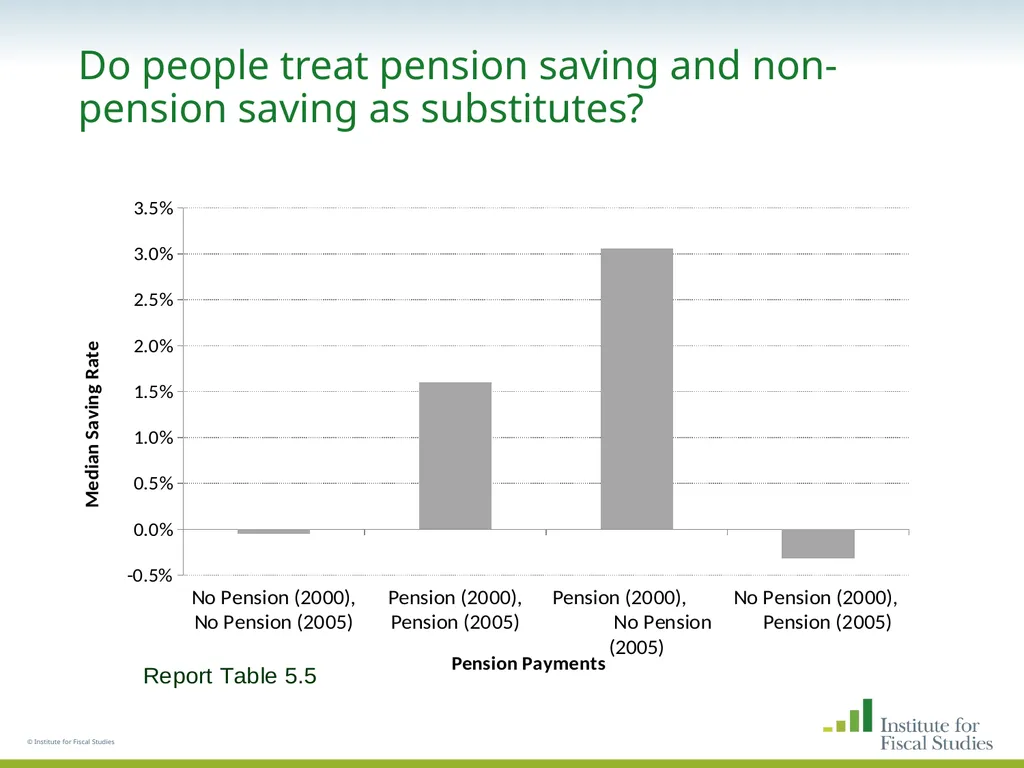
slide31. Do people treat pension saving and non-pension saving as substitutes? © Institute for Fiscal Studies<br>
slide32. Summary – Wealth Distribution Wealth is distributed unequally throughout the population
In 2005, many families had no or little liquid wealth
Mean wealth is substantially higher than median wealth
Median financial wealth was very close to zero (<£500) for families headed by anyone under the age 45.
The patterns according to socio-economic characteristics are largely as expected:
Financial wealth rises with age (except at the very oldest ages)
Financial wealth rises with current income © Institute for Fiscal Studies<br>
slide33. Summary – Liquid Saving 2000 to 2005 There was very little net saving of liquid financial wealth between the two years:
Real median family wealth increased from approx. £750 to approx. £1,100.
Passive accumulation of increases in housing equity swamped accumulation of more liquid forms of wealth.
Saving in terms of liquid wealth between 2000 and 2005 was highest for those aged between 55 and 59.
Younger and poorer families had particularly low rates of saving between 2000 and 2005. © Institute for Fiscal Studies<br>
slide34. Other related research underway or planned at the IFS... What has been the effect of the financial crisis on household wealth and saving?
Distribution of retirement resources among the oldest households (updating of previous work that summarised the distribution in 2002)
Estimation of discount rates implied by earnings histories and wealth data
To what extent is private pension coverage affected by up-front financial incentives to save? © Institute for Fiscal Studies<br>
slide35. © Institute for Fiscal Studies The wealth and saving of UK families on the eve of the crisis Thomas F. Crossley
Cormac O’Dea<br>
Institute for Fiscal Studies<br>
slide2. © Institute for Fiscal Studies IFS Retirement Saving Consortium Association of British Insurers
Bank of England
Barclays
Chartered Institute of Personnel and Development
Department for Work and Pensions
Financial Services Authority HM Revenue and Customs
HM Treasury
Investment Management Association
Pensions Regulator
Personal Accounts Delivery Authority
Scottish Widows
The Actuarial Profession<br>
slide3. © Institute for Fiscal Studies Motivation for this research: Where to look to study Household Saving? Most high profile measure of Household Saving is the ONS Household Saving Ratio, released quarterly.
This is a measure of the total saving undertaken in the economy<br>
slide4. © Institute for Fiscal Studies Household Saving Ratio, Annual, 1963 - 2009 Report Figure 1.1, Source: ONS<br>
slide5. © Institute for Fiscal Studies Household Saving Ratio, Quarterly, 2000-2010 Source: ONS<br>
slide6. © Institute for Fiscal Studies Household Saving Ratio The most high profile measure of Household Saving is the ONS Household Saving Ratio, released quarterly.
This is a measure of the total saving undertaken in the economy
A useful summary of the total volume of saving being done in the economy.
But we would caution against relying on it for questions related to the adequacy of wealth for retirement
It is dominated by the saving of the those with the greatest income.
Contains limited information about trends in saving among those with low and middle incomes.
An economy-wide average: contains no information on distributional questions such as who saves and who doesn’t.
Measured with a great deal of uncertainty
Calculated as the difference between two large aggregates, themselves measured with error.<br>
slide7. Can we look at household saving using microdata? © Institute for Fiscal Studies<br>
slide8. © Institute for Fiscal Studies In the report, using the British Household Panel Survey, we calculate two measures of wealth... Liquid Financial Wealth
Balances in savings accounts plus bonds/equities less non-mortgage debt
Financial and Housing Wealth
Liquid Financial Wealth plus value of housing less outstanding mortgage debt
Use these measures to:
Calculate saving rates between the two years which is:<br>
slide9. © Institute for Fiscal Studies In the report, using the British Household Panel Survey, we calculate two measures of wealth... Liquid Financial Wealth
Balances in savings accounts plus bonds/equities less non-mortgage debt
Financial and Housing Wealth
Liquid Financial Wealth plus value of housing less outstanding mortgage debt
Use these measures to:
Calculate saving rates between the two years which is:<br>
slide10. ...and summarise the distribution of wealth and saving according to household type We define family groups according to:
Age, Income, Family Type, Housing Tenure, Pension Payments
Summarise the distribution of wealth and saving for each group
Family level analysis
A family is defined as a single adult or couple with any dependent children
What important assets are we missing from the data?
Cash and current account balances
Pension Wealth © Institute for Fiscal Studies<br>
slide11. © Institute for Fiscal Studies The rest of this presentation.... Summary of wealth distribution in 2005
Illustrate patterns by age, income
Summary of saving behaviour between 2000 and 2005
Again, illustrate patterns by age, income
Dramatic differences in saving rate depending on whether changes in housing equity are included in saving or not<br>
slide12. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies Report Table 3.2<br>
slide13. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies Report Table 3.2<br>
slide14. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
slide15. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
slide16. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
slide17. Distribution of Financial Wealth, 2005 © Institute for Fiscal Studies<br>
slide18. Financial Wealth in 2005, Means, by Age © Institute for Fiscal Studies Report Figure 3.1<br>
slide19. Financial Wealth in 2005, Means and Medians by Age © Institute for Fiscal Studies Report Figure 3.1<br>
slide20. Financial Wealth in 2005, by Age © Institute for Fiscal Studies Report Figure 3.1<br>
slide21. Financial and Housing Wealth in 2005, by Age © Institute for Fiscal Studies Report Figure 3.2<br>
slide22. Financial Wealth in 2005, by Income Decile © Institute for Fiscal Studies Report Figure 3.3<br>
slide23. What happened to the wealth distribution between 2000 and 2005? © Institute for Fiscal Studies<br>
slide24. What happened to the wealth distribution between 2000 and 2005? © Institute for Fiscal Studies Report Table 3.1<br>
slide25. What happened to the wealth distribution between 2000 and 2005? © Institute for Fiscal Studies Report Table 3.1<br>
slide26. Turning to saving... A reminder:
We calculate saving rates between the two years which is:
We now show median saving rates. © Institute for Fiscal Studies<br>
slide27. Median Annual Saving Rates, (Financial Wealth), by Age © Institute for Fiscal Studies Report Table 5.1<br>
slide28. Median Annual Saving Rates, (including Housing Wealth), by Age © Institute for Fiscal Studies Report Table 5.2<br>
slide29. Median Annual Saving Rates, (Financial Wealth), by Income © Institute for Fiscal Studies Report Table 5.3<br>
slide30. What happens to (liquid wealth) saving rates when you finish paying off a mortgage? © Institute for Fiscal Studies Report Table 5.7<br>
slide31. Do people treat pension saving and non-pension saving as substitutes? © Institute for Fiscal Studies<br>
slide32. Summary – Wealth Distribution Wealth is distributed unequally throughout the population
In 2005, many families had no or little liquid wealth
Mean wealth is substantially higher than median wealth
Median financial wealth was very close to zero (<£500) for families headed by anyone under the age 45.
The patterns according to socio-economic characteristics are largely as expected:
Financial wealth rises with age (except at the very oldest ages)
Financial wealth rises with current income © Institute for Fiscal Studies<br>
slide33. Summary – Liquid Saving 2000 to 2005 There was very little net saving of liquid financial wealth between the two years:
Real median family wealth increased from approx. £750 to approx. £1,100.
Passive accumulation of increases in housing equity swamped accumulation of more liquid forms of wealth.
Saving in terms of liquid wealth between 2000 and 2005 was highest for those aged between 55 and 59.
Younger and poorer families had particularly low rates of saving between 2000 and 2005. © Institute for Fiscal Studies<br>
slide34. Other related research underway or planned at the IFS... What has been the effect of the financial crisis on household wealth and saving?
Distribution of retirement resources among the oldest households (updating of previous work that summarised the distribution in 2002)
Estimation of discount rates implied by earnings histories and wealth data
To what extent is private pension coverage affected by up-front financial incentives to save? © Institute for Fiscal Studies<br>
slide35. © Institute for Fiscal Studies The wealth and saving of UK families on the eve of the crisis Thomas F. Crossley
Cormac O’Dea<br>