
International Economics Tenth Edition Exchange

Description: International Economics Tenth Edition Exchange Rate Determination Dominick Salvatore John Wiley Sons, Inc. Salvatore: International Economics, 11th Edition 2013 John Wiley Sons, Inc. CHAPTER F I F T E E N 15 Learning Goals: Understand
Related Topics
Download Presentation
"International Economics Tenth Edition Exchange" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. International Economics
Tenth Edition Exchange Rate Determination
Dominick Salvatore
John Wiley & Sons, Inc. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. CHAPTER F I F T E E N 15<br>
slide2. Learning Goals: Understand the purchasing power parity theory and why it does not work in the short run
Understand how the monetary and the portfolio balance models of the exchange rate work
Understand the causes of exchange rate overshooting
Understand why exchange rates are so difficult to forecast Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide3. Introduction Since floating rates began in 1973, international financial flows are now larger than trade flows, shifting the focus to monetary theories of exchange rates.
Monetary exchange rate theories view the exchange rate as a purely financial phenomenon, and tend to explain exchange rate volatility and disequilibria in the short run. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
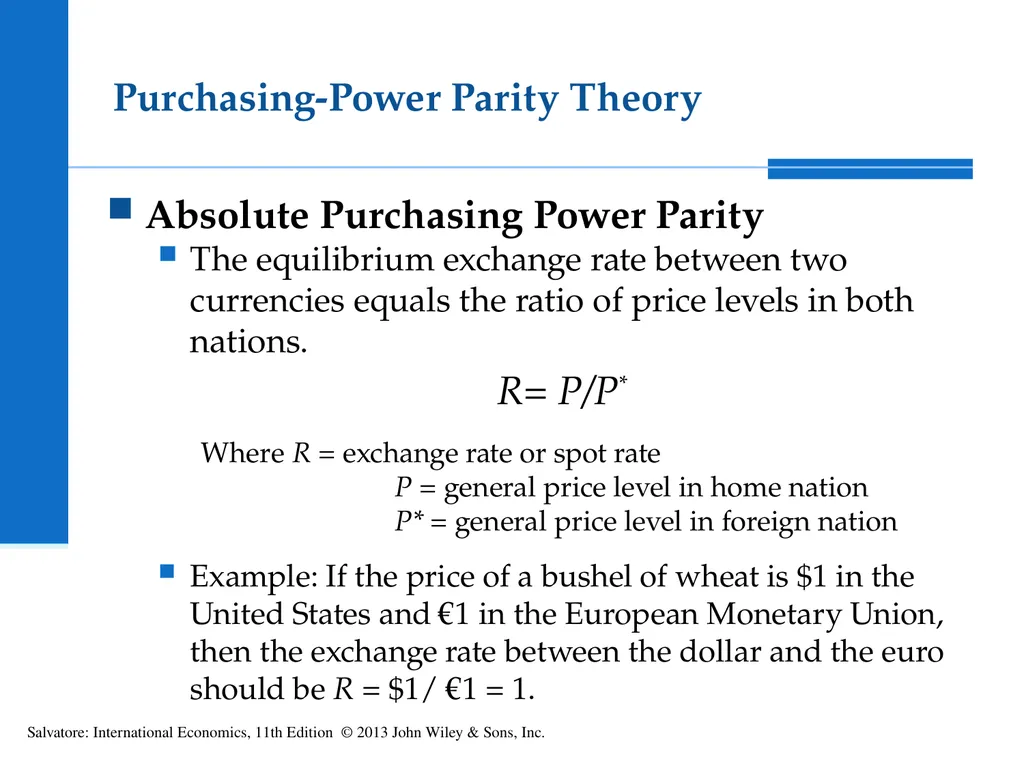
slide4. Purchasing-Power Parity Theory Absolute Purchasing Power Parity
The equilibrium exchange rate between two currencies equals the ratio of price levels in both nations.
R= P/P*
Where R = exchange rate or spot rate
P = general price level in home nation
P* = general price level in foreign nation
Example: If the price of a bushel of wheat is $1 in the United States and €1 in the European Monetary Union, then the exchange rate between the dollar and the euro should be R = $1/ €1 = 1. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide5. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. The law of one price
A given commodity should have the same price (so that the purchasing power of the two currencies is at parity) in both countries when expressed in terms of the same currency.
Caused by commodity arbitrage.<br>
slide6. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Absolute PPP theory can be misleading because:
Appears to give exchange rate that equilibrates trade in goods and services while ignoring capital account.
At exchange rate that equilibrates trade in goods and services, capital inflows would produce surplus in balance of payments, while capital outflows would lead to deficits.<br>
slide7. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Absolute PPP theory can be misleading because:
Will not even give exchange rate that equilibrates trade in goods and services because of existence of nontraded goods.
International trade tends to equalize prices of traded goods and services, not nontraded goods.<br>
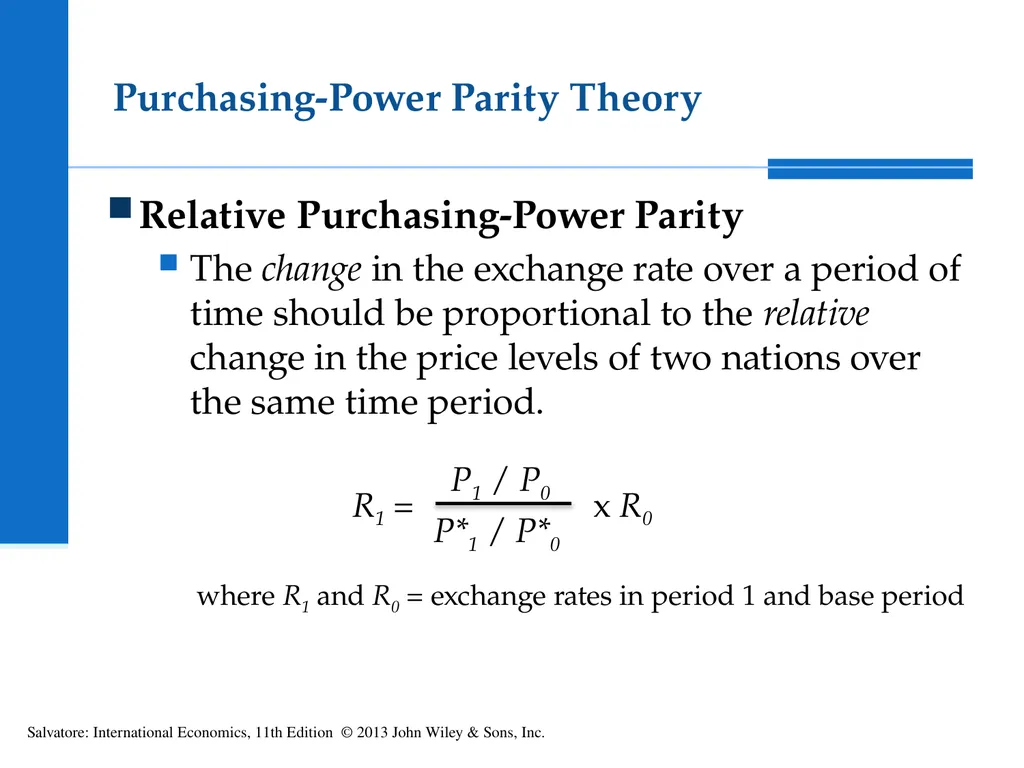
slide8. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Relative Purchasing-Power Parity
The change in the exchange rate over a period of time should be proportional to the relative change in the price levels of two nations over the same time period. where R1 and R0 = exchange rates in period 1 and base period<br>
slide9. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Relative Purchasing-Power Parity
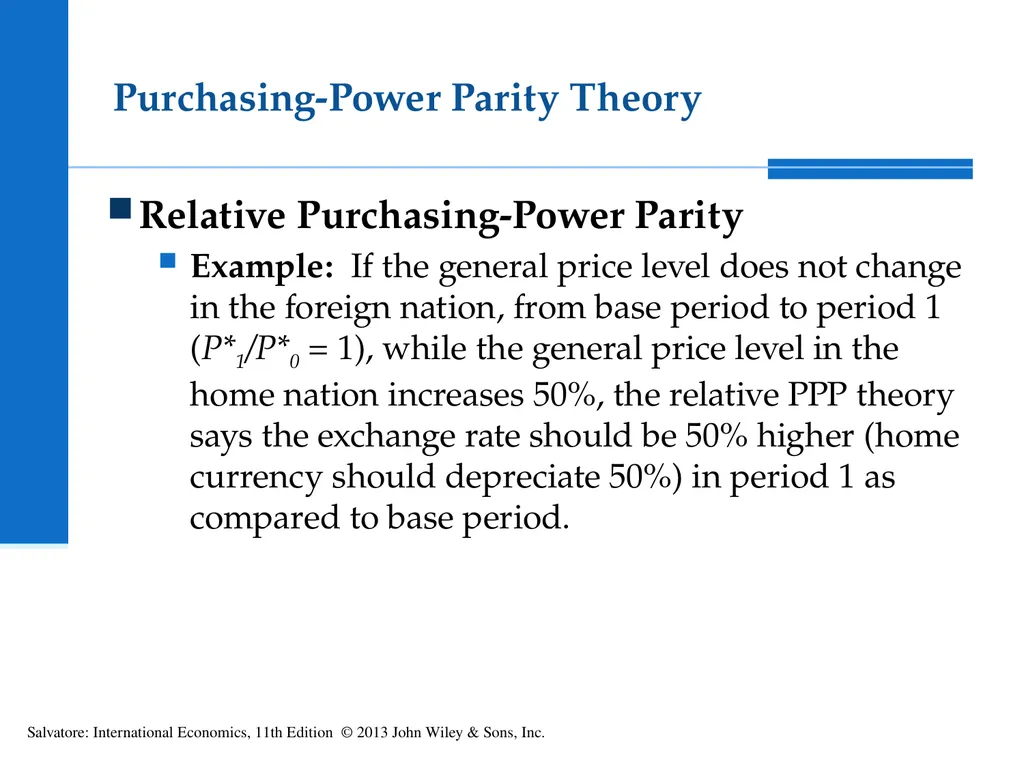
Example: If the general price level does not change in the foreign nation, from base period to period 1 (P*1/P*0 = 1), while the general price level in the home nation increases 50%, the relative PPP theory says the exchange rate should be 50% higher (home currency should depreciate 50%) in period 1 as compared to base period.<br>
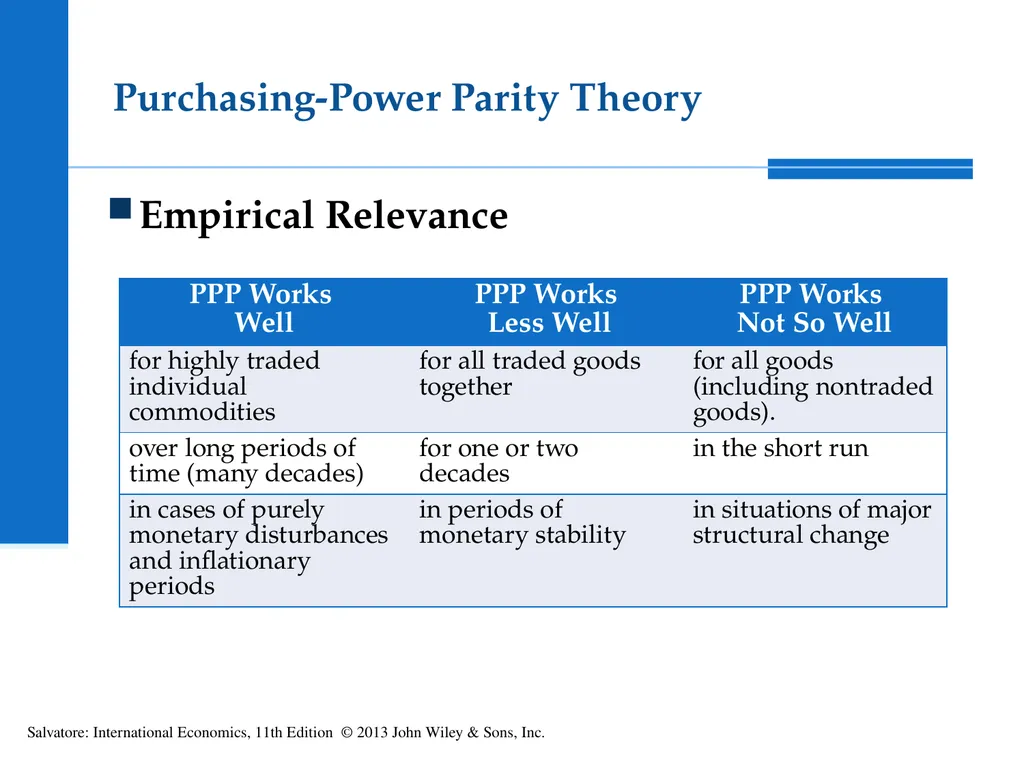
slide10. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Empirical Relevance<br>
slide11. Monetary Approach to the Balance of Payments and Exchange Rates The monetary approach to the balance of payments views the balance of payments as a monetary phenomenon.
Money plays crucial role in the long run as both a disturbance and an adjustment. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
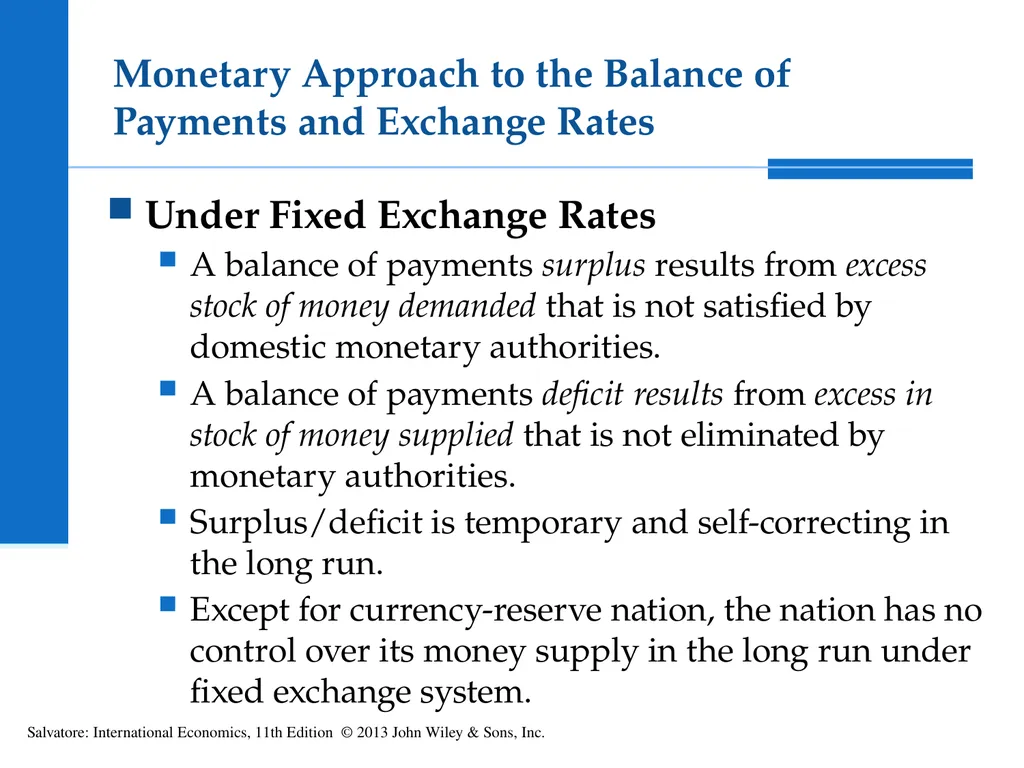
slide12. Monetary Approach to the Balance of Payments and Exchange Rates Under Fixed Exchange Rates
A balance of payments surplus results from excess stock of money demanded that is not satisfied by domestic monetary authorities.
A balance of payments deficit results from excess in stock of money supplied that is not eliminated by monetary authorities.
Surplus/deficit is temporary and self-correcting in the long run.
Except for currency-reserve nation, the nation has no control over its money supply in the long run under fixed exchange system. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide13. Monetary Approach to the Balance of Payments and Exchange Rates Under Flexible Exchange Rates
Balance of payments disequilibria are immediately corrected by automatic changes in exchange rates without international flow of money or reserves.
Nation retains dominant control over its money supply and monetary policy.
Adjustment occurs as result of the change in domestic prices accompanying the change in exchange rate. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
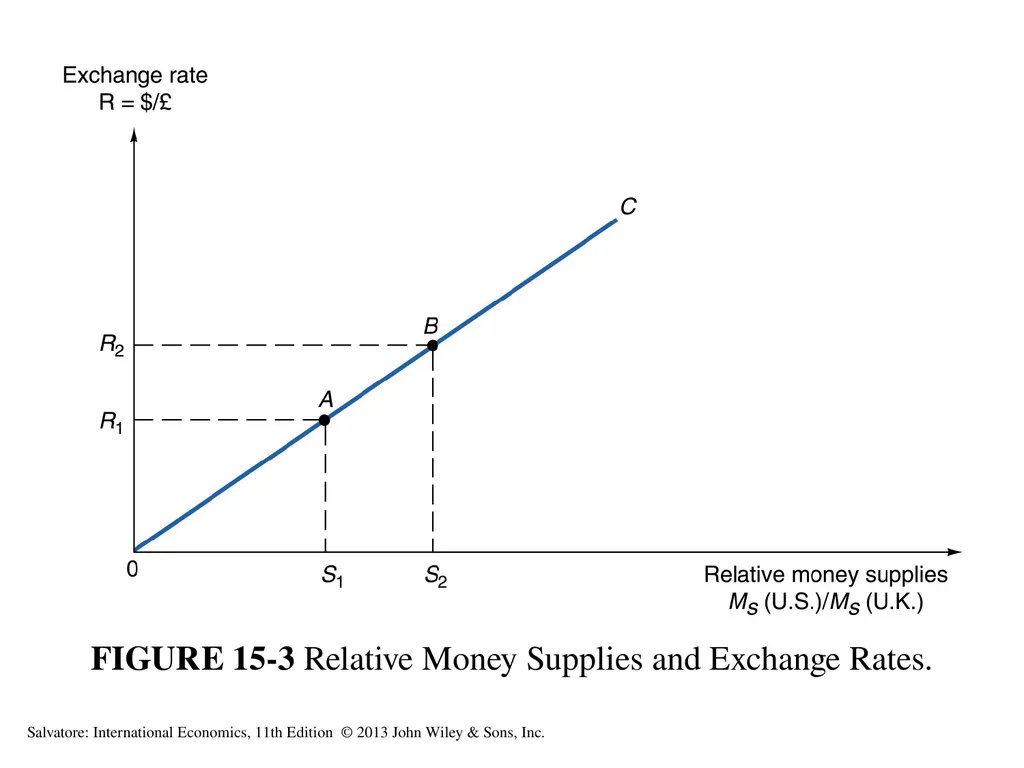
slide14. FIGURE 15-3 Relative Money Supplies and Exchange Rates. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
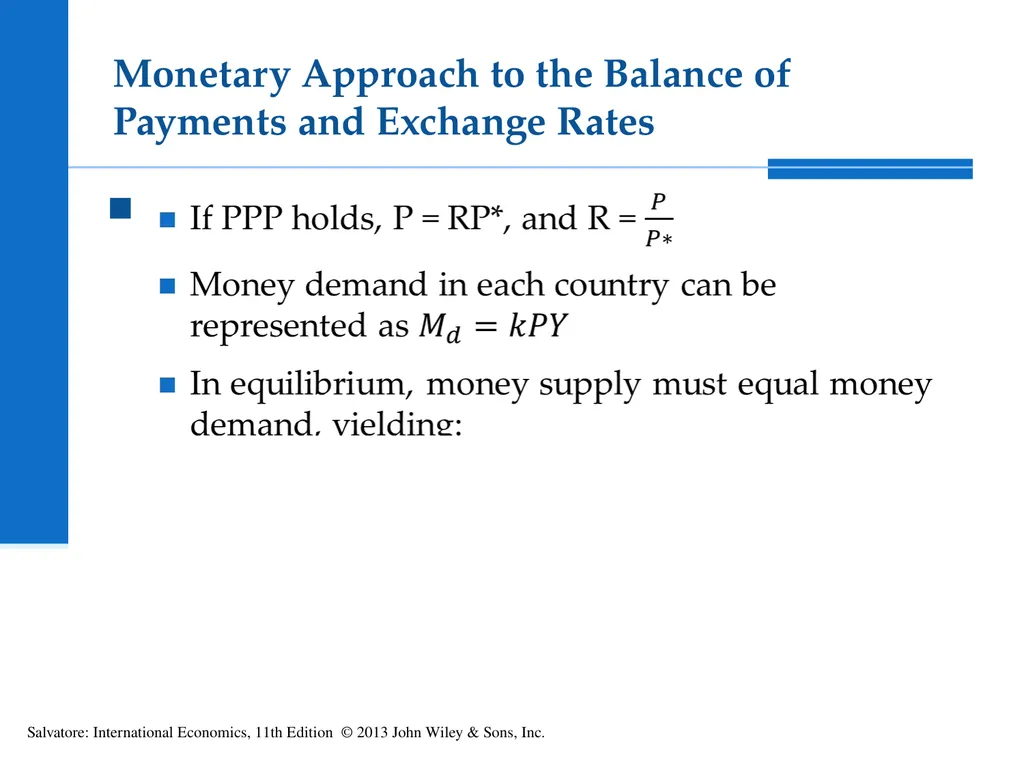
slide15. Monetary Approach to the Balance of Payments and Exchange Rates Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide16. Portfolio Balance Model and Exchange Rates Portfolio Balance Approach
The exchange rate is determined in the process of equilibrating or balancing the stock or total demand and supply of financial assets (of which money is only one) in each country.
Regarded as a more realistic and satisfactory version of the monetary approach. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide17. Portfolio Balance Model and Exchange Rates Expectations, Interest Differentials, and Exchange Rates
The exchange rate is determined not only by the relative growth of money supply and money demand but also by inflation expectations and expected changes.
As long as domestic and foreign bonds are assumed to be perfect substitutes, (i-i*) = EA, where EA is the expected appreciation of the foreign currency. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide18. Portfolio Balance Model and Exchange Rates Portfolio Balance Approach
If investors demand more of a foreign asset, either because of higher relative foreign interest rates or increased wealth, demand for foreign currency will increase, depreciating domestic currency.
If investors sell foreign assets, either because of lower relative foreign interest rates or decreased wealth, supply of foreign currency will increase, appreciating domestic currency. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide19. Portfolio Balance Model and Exchange Rates Portfolio Balance Approach
Domestic and foreign bonds are assumed to be imperfect substitutes; domestic investors require a higher return to compensate for the risk of holding foreign bonds.
Stock model rather than a flow model.
The exchange rate is determined in the process of reaching equilibrium in each financial market. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
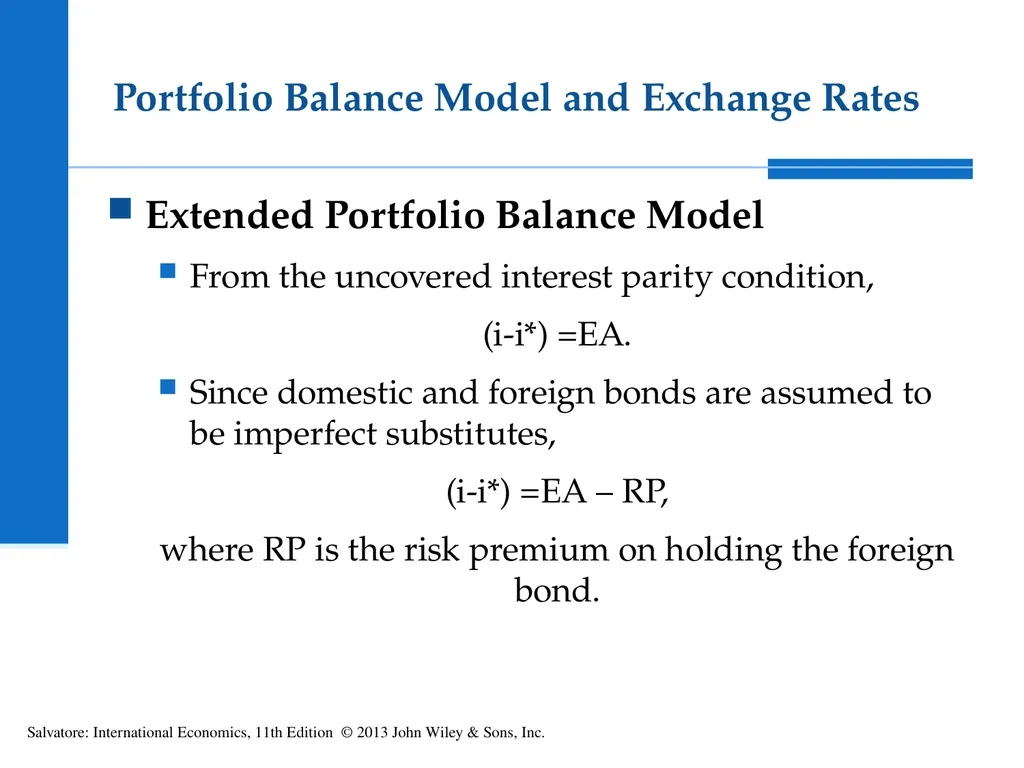
slide20. Portfolio Balance Model and Exchange Rates Extended Portfolio Balance Model
From the uncovered interest parity condition,
(i-i*) =EA.
Since domestic and foreign bonds are assumed to be imperfect substitutes,
(i-i*) =EA – RP,
where RP is the risk premium on holding the foreign bond. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide21. Portfolio Balance Model and Exchange Rates Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
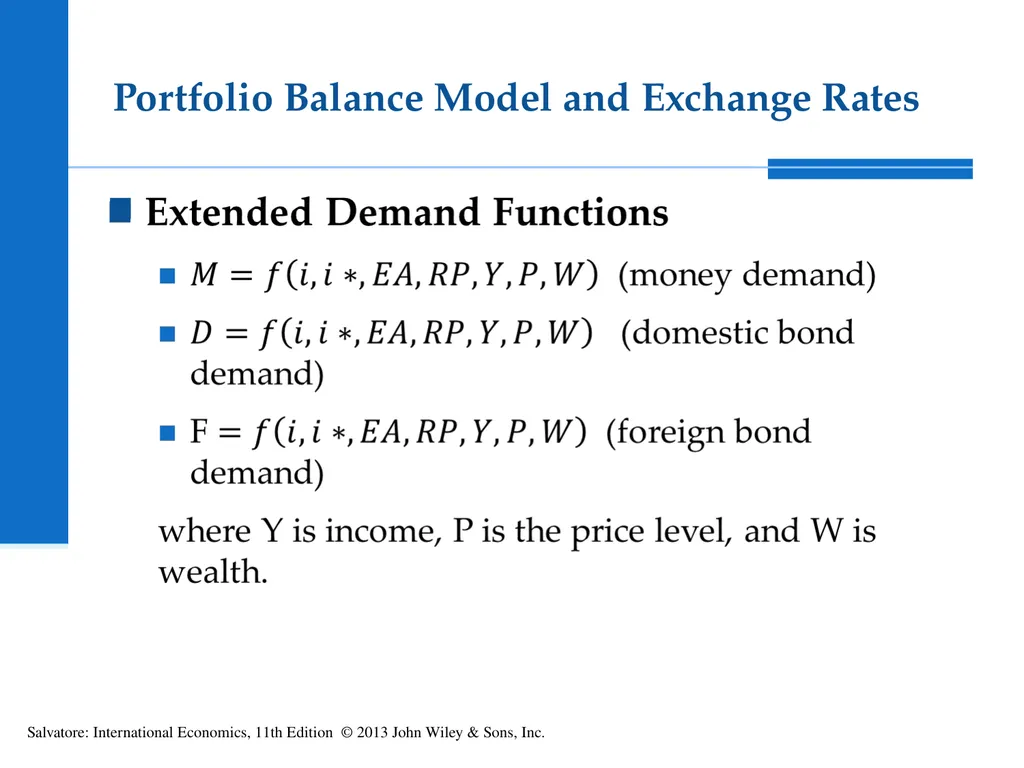
slide22. Portfolio Balance Model and Exchange Rates Extended Demand Functions
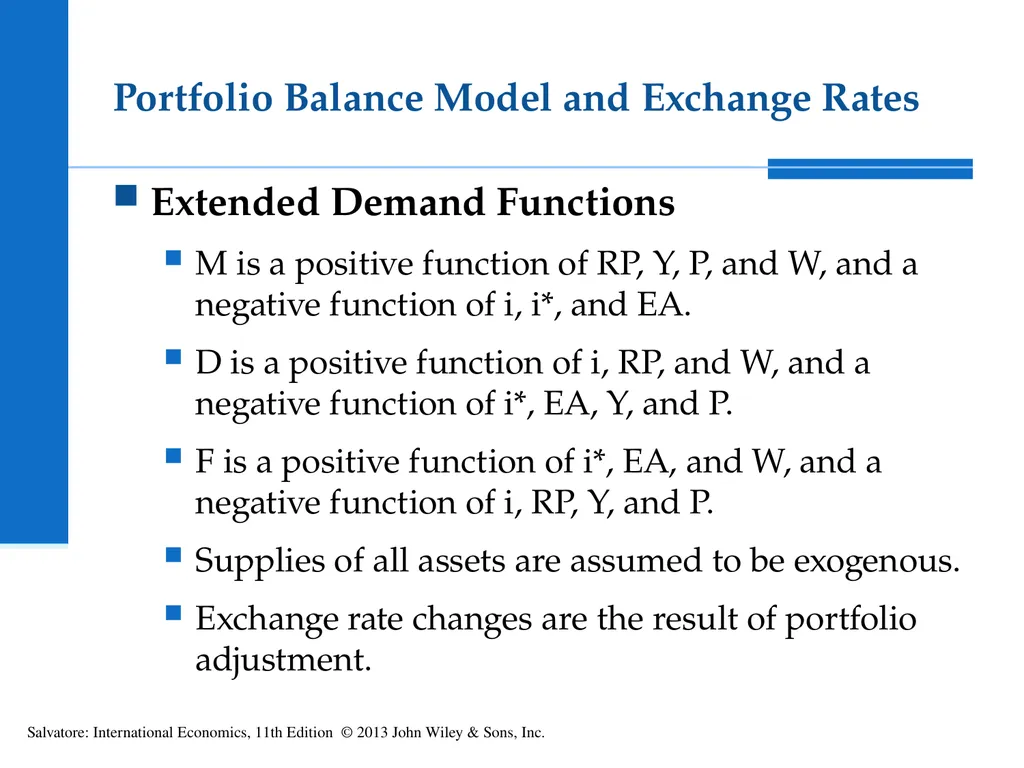
M is a positive function of RP, Y, P, and W, and a negative function of i, i*, and EA.
D is a positive function of i, RP, and W, and a negative function of i*, EA, Y, and P.
F is a positive function of i*, EA, and W, and a negative function of i, RP, Y, and P.
Supplies of all assets are assumed to be exogenous.
Exchange rate changes are the result of portfolio adjustment. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
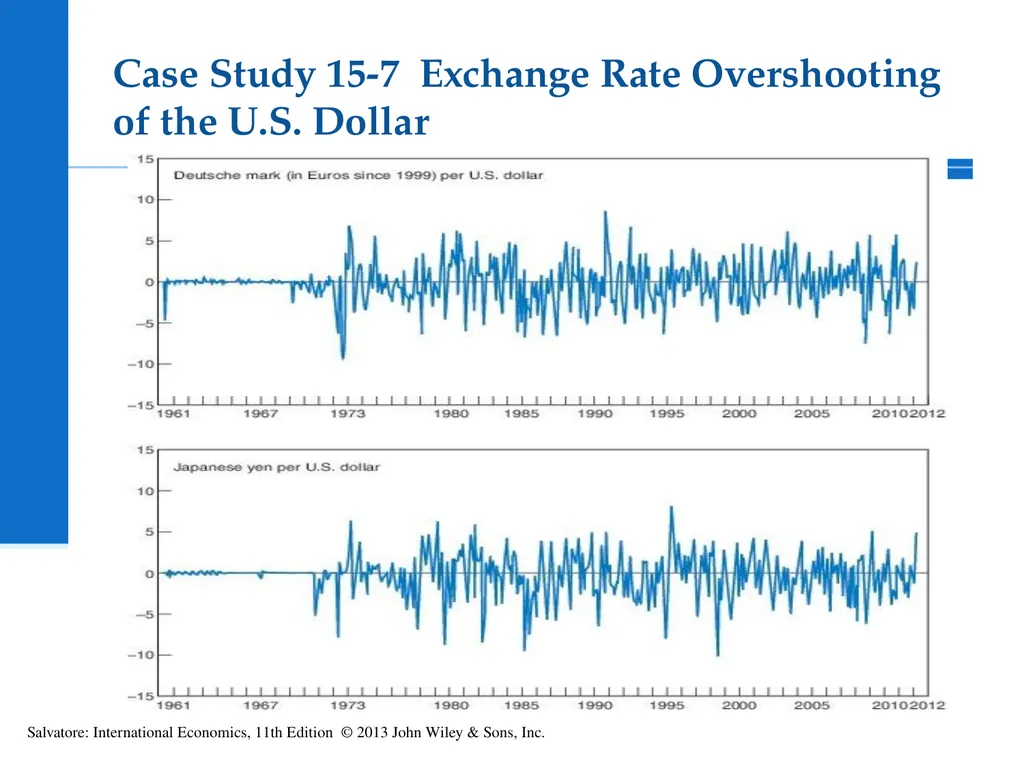
slide23. Exchange Rate Dynamics Exchange Rate Overshooting
Stock adjustments in financial assets are usually much larger and quicker to occur than adjustments in trade flows.
Most of the burden of adjustments in exchange rates comes from financial markets in short run.
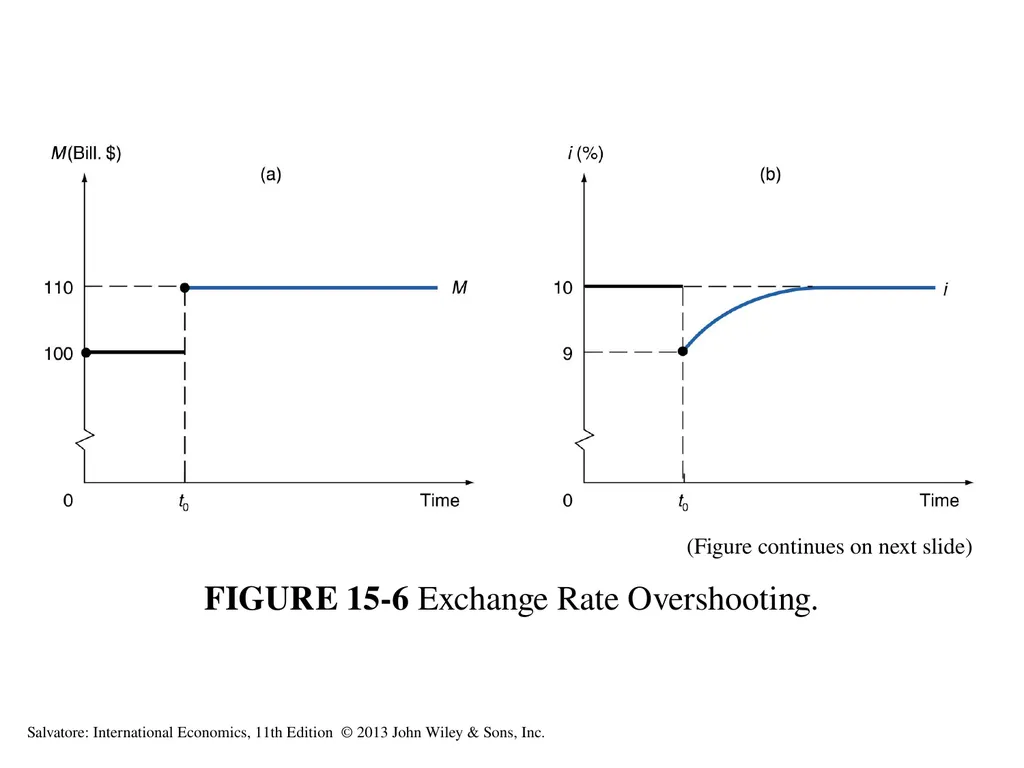
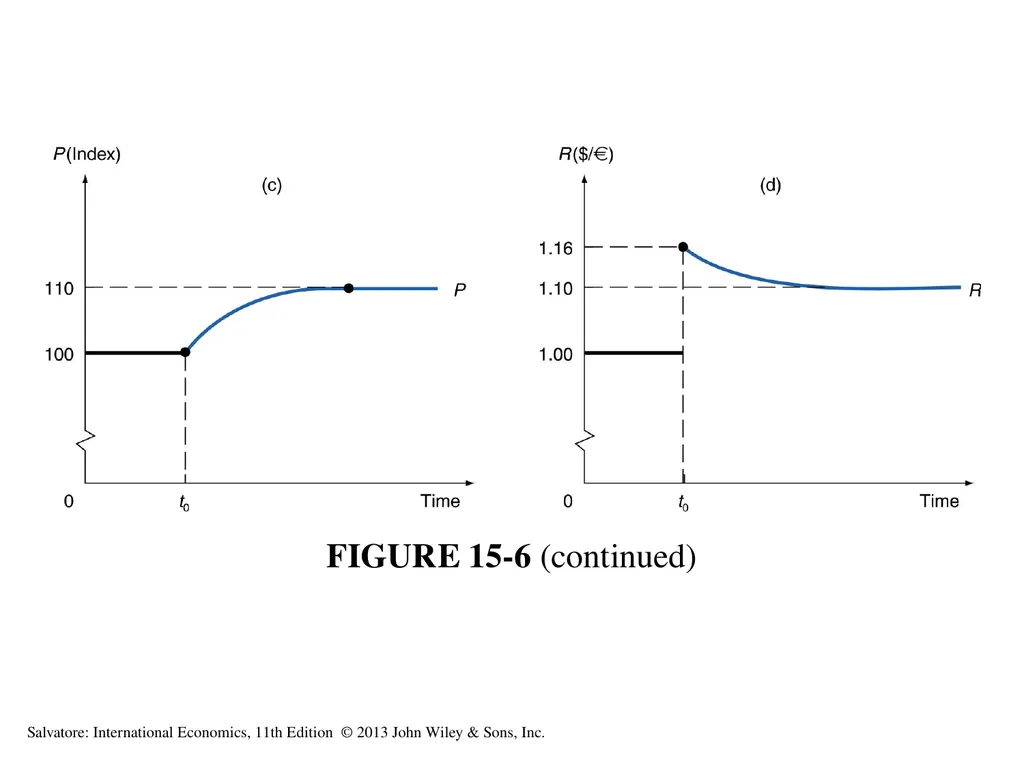
Thus, exchange rate must overshoot or bypass its long run equilibrium level for equilibrium to be quickly reestablished in financial markets. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide24. FIGURE 15-6 Exchange Rate Overshooting. (Figure continues on next slide) Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide25. FIGURE 15-6 (continued) Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide26. Empirical Tests of the Monetary and Portfolio Balance Models and Exchange Rate Forecasting Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Models of exchange rates have not been very successful at predicting future exchange rates.
Reasons:
Exchange rates are highly influenced by new information.
Expectations in exchange rate markets tend to be self-fulfilling (at least in the short-run).
This may lead to speculative bubbles, generate movements in the market contrary to what is expected by theory.<br>
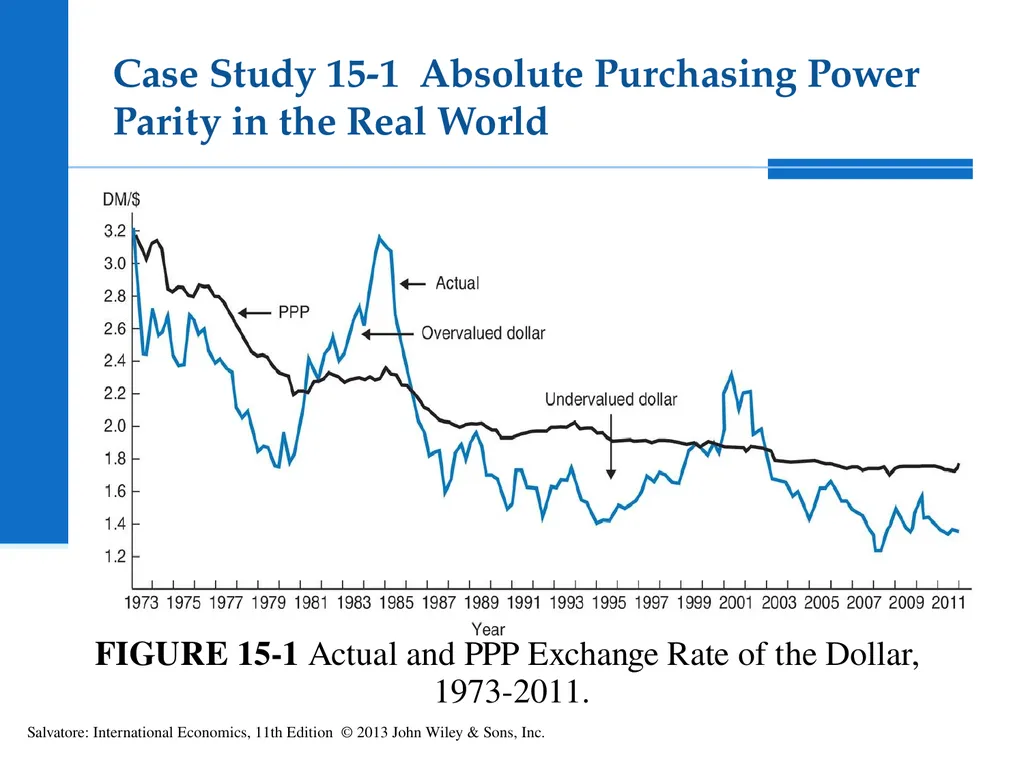
slide27. Case Study 15-1 Absolute Purchasing Power Parity in the Real World Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-1 Actual and PPP Exchange Rate of the Dollar,
1973-2011.<br>
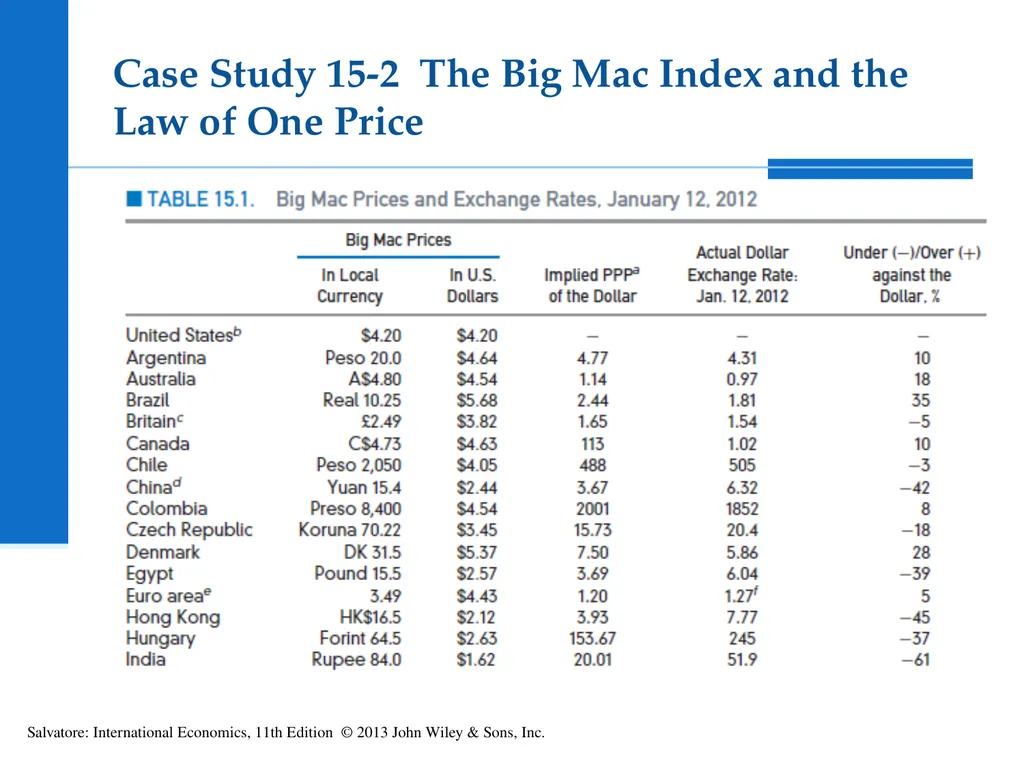
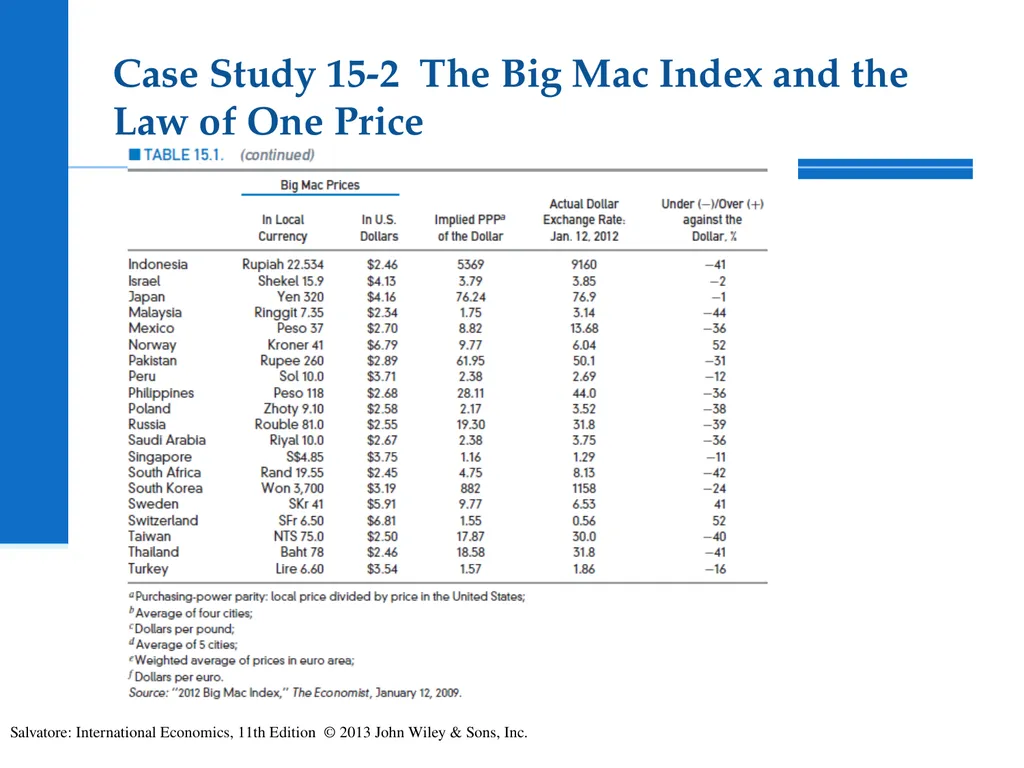
slide28. Case Study 15-2 The Big Mac Index and the Law of One Price Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide29. Case Study 15-2 The Big Mac Index and the Law of One Price Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
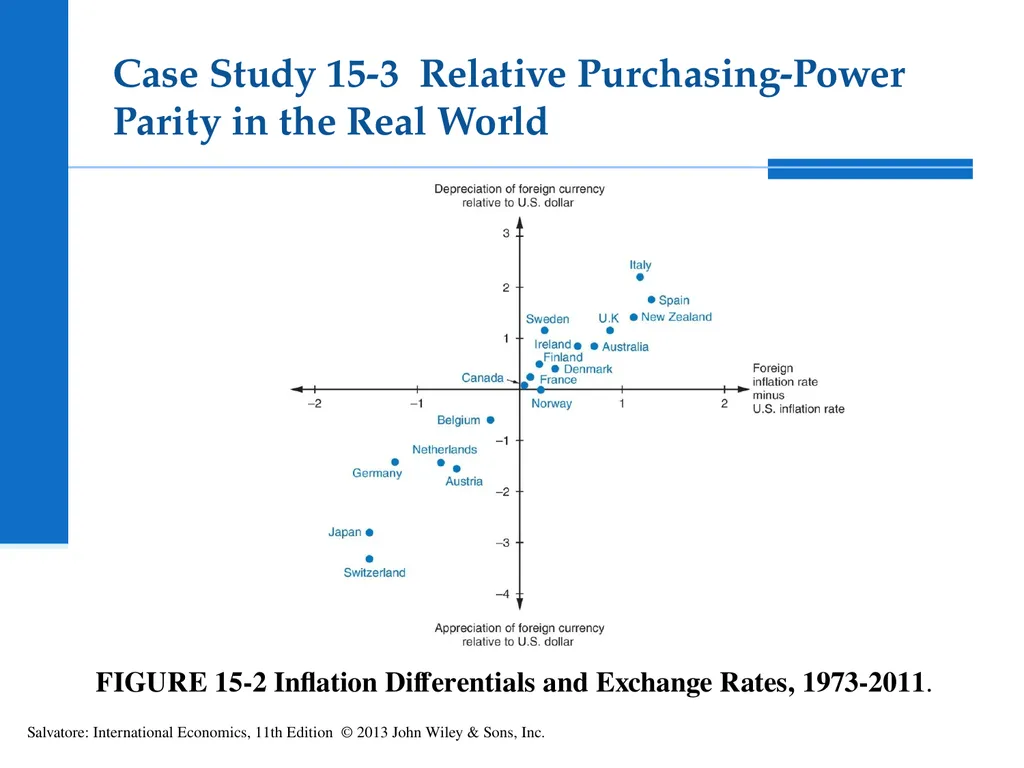
slide30. Case Study 15-3 Relative Purchasing-Power Parity in the Real World Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-2 Inflation Differentials and Exchange Rates, 1973-2011.<br>
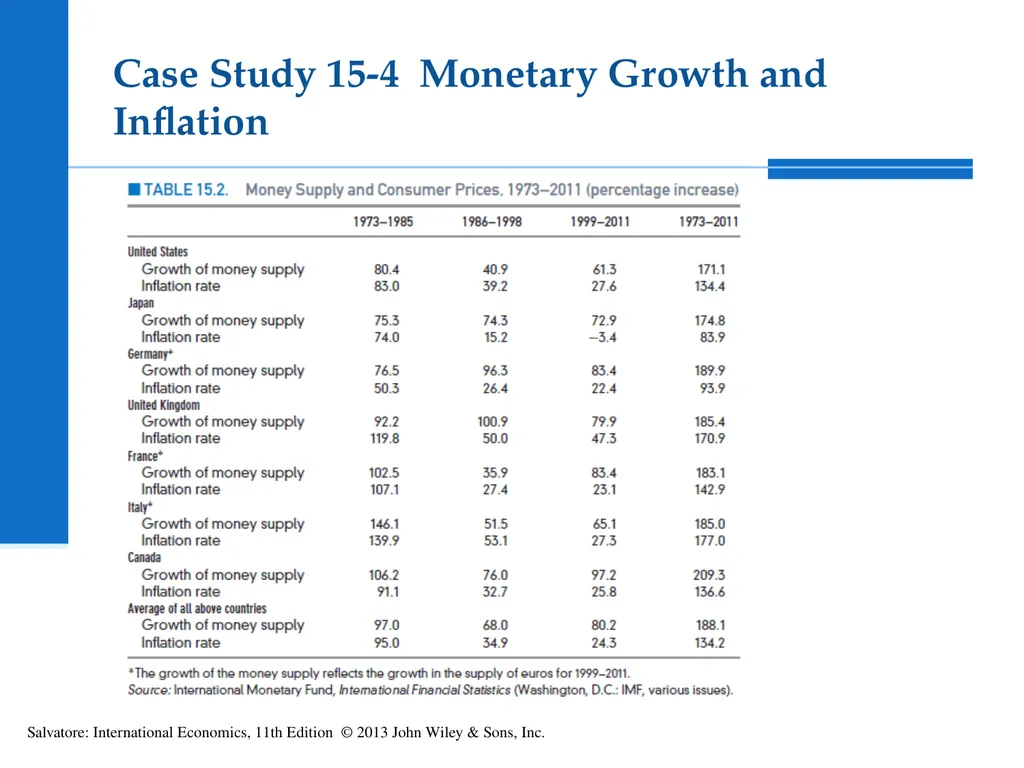
slide31. Case Study 15-4 Monetary Growth and Inflation Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
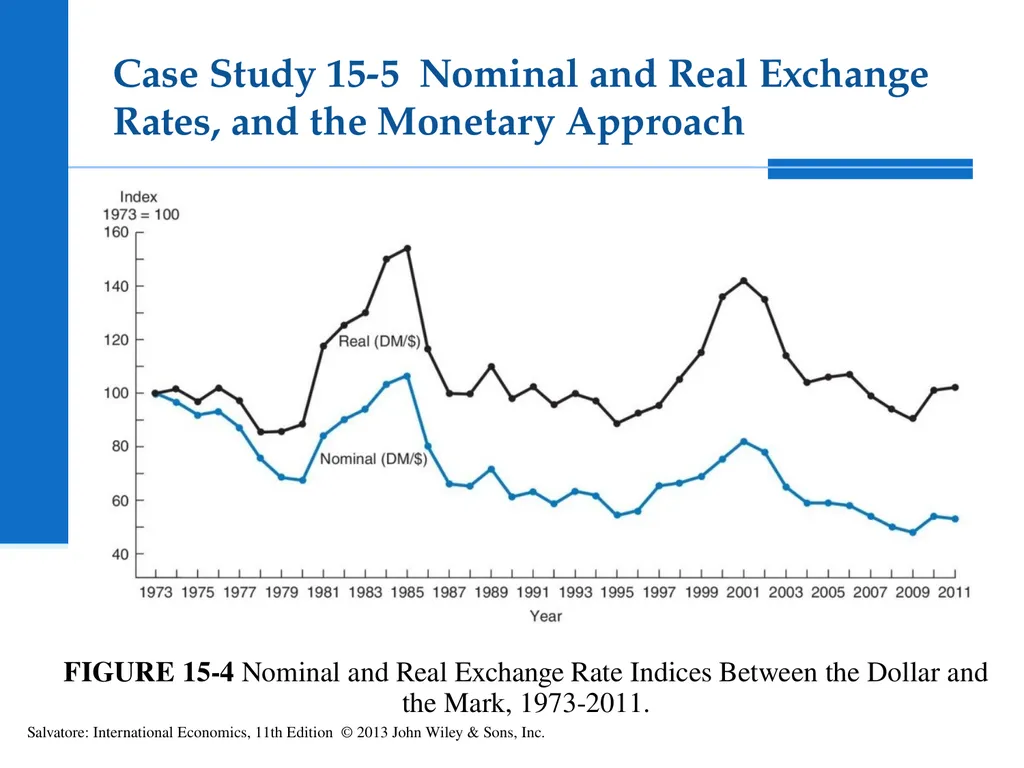
slide32. Case Study 15-5 Nominal and Real Exchange Rates, and the Monetary Approach Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-4 Nominal and Real Exchange Rate Indices Between the Dollar and the Mark, 1973-2011.<br>
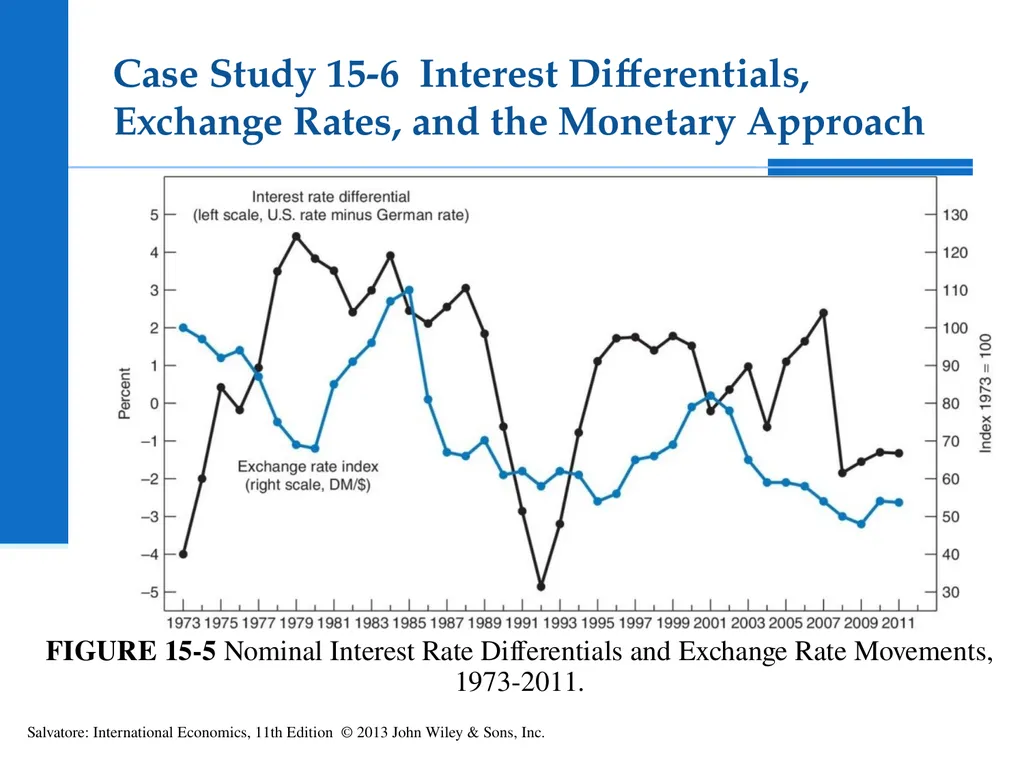
slide33. Case Study 15-6 Interest Differentials, Exchange Rates, and the Monetary Approach Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-5 Nominal Interest Rate Differentials and Exchange Rate Movements, 1973-2011.<br>
slide34. Case Study 15-7 Exchange Rate Overshooting of the U.S. Dollar Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
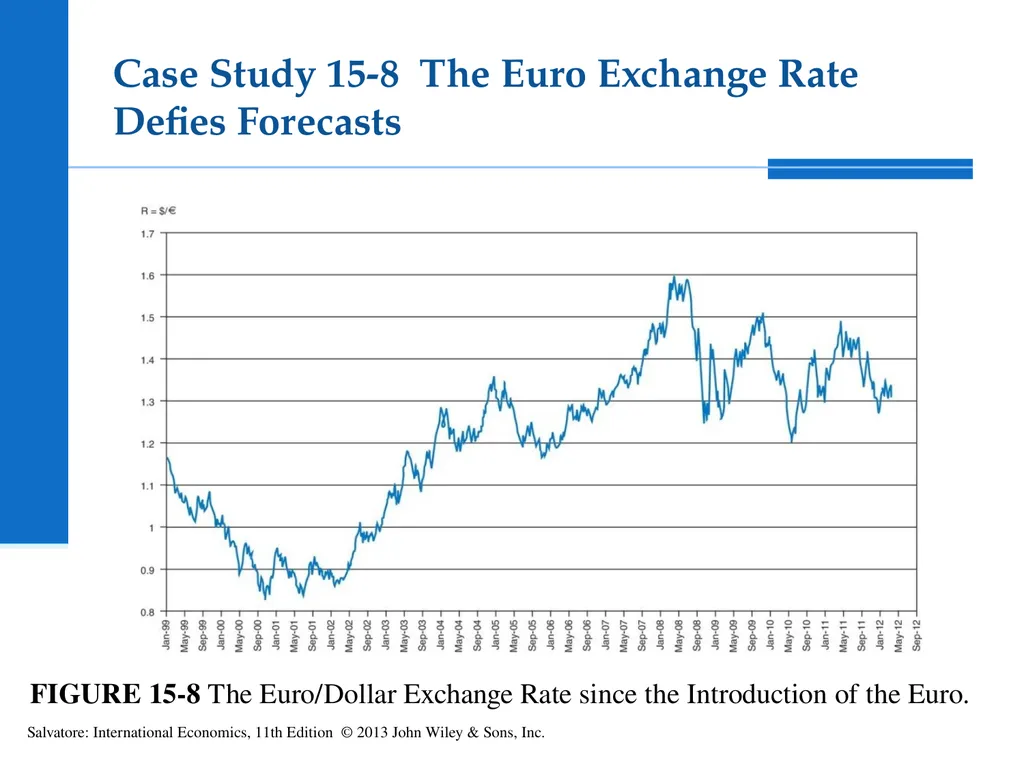
slide35. Case Study 15-8 The Euro Exchange Rate Defies Forecasts Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-8 The Euro/Dollar Exchange Rate since the Introduction of the Euro.<br>
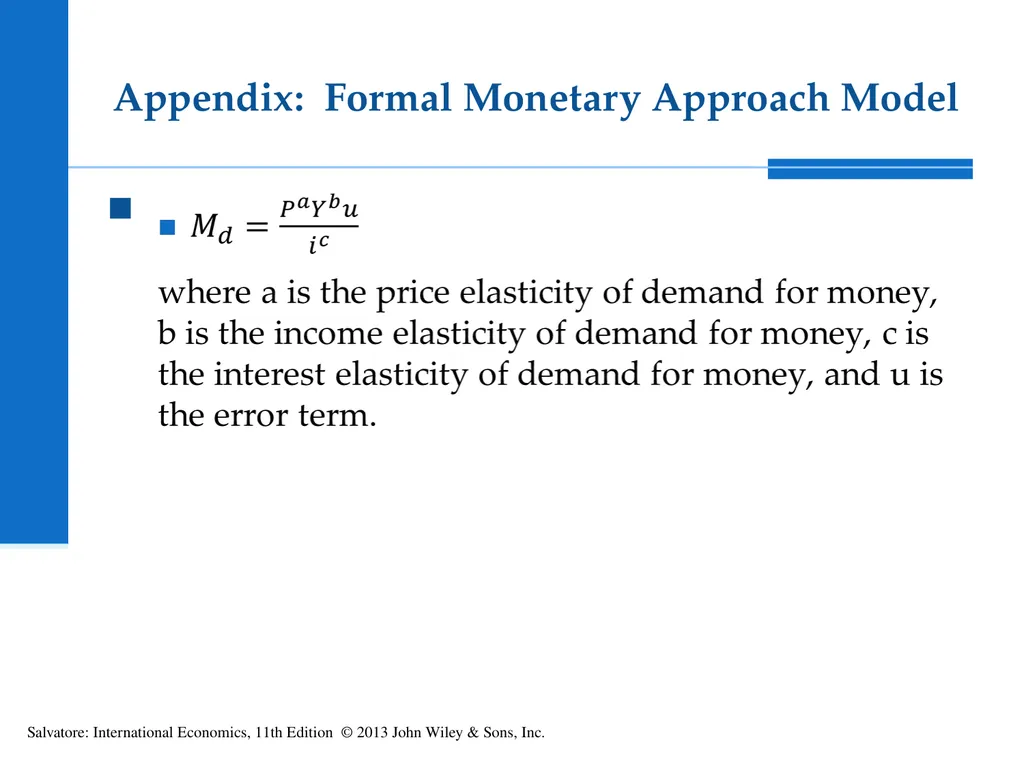
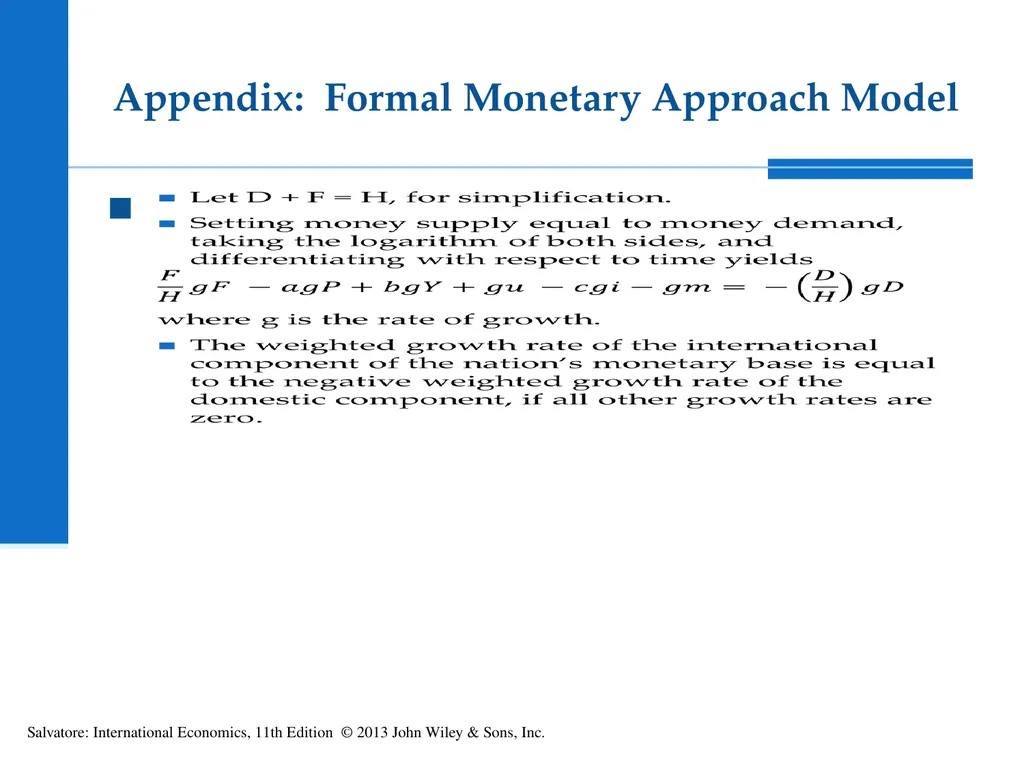
slide36. Appendix: Formal Monetary Approach Model Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide37. Appendix: Formal Monetary Approach Model Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
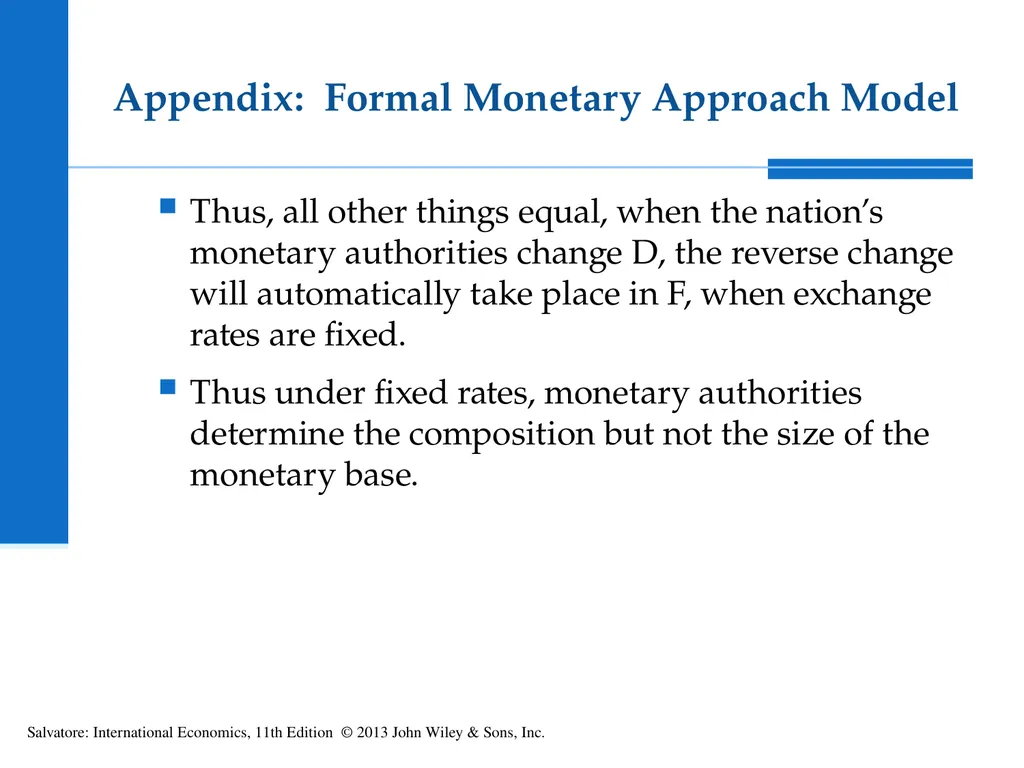
slide38. Appendix: Formal Monetary Approach Model Thus, all other things equal, when the nation’s monetary authorities change D, the reverse change will automatically take place in F, when exchange rates are fixed.
Thus under fixed rates, monetary authorities determine the composition but not the size of the monetary base. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
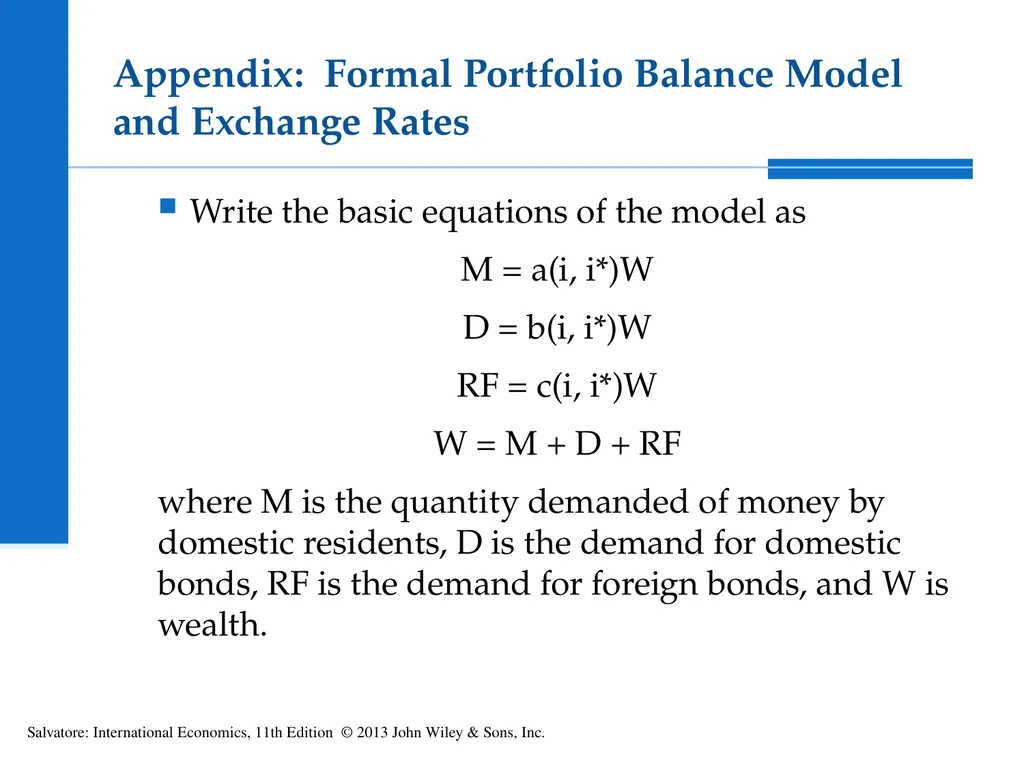
slide39. Appendix: Formal Portfolio Balance Model and Exchange Rates Write the basic equations of the model as
M = a(i, i*)W
D = b(i, i*)W
RF = c(i, i*)W
W = M + D + RF
where M is the quantity demanded of money by domestic residents, D is the demand for domestic bonds, RF is the demand for foreign bonds, and W is wealth. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
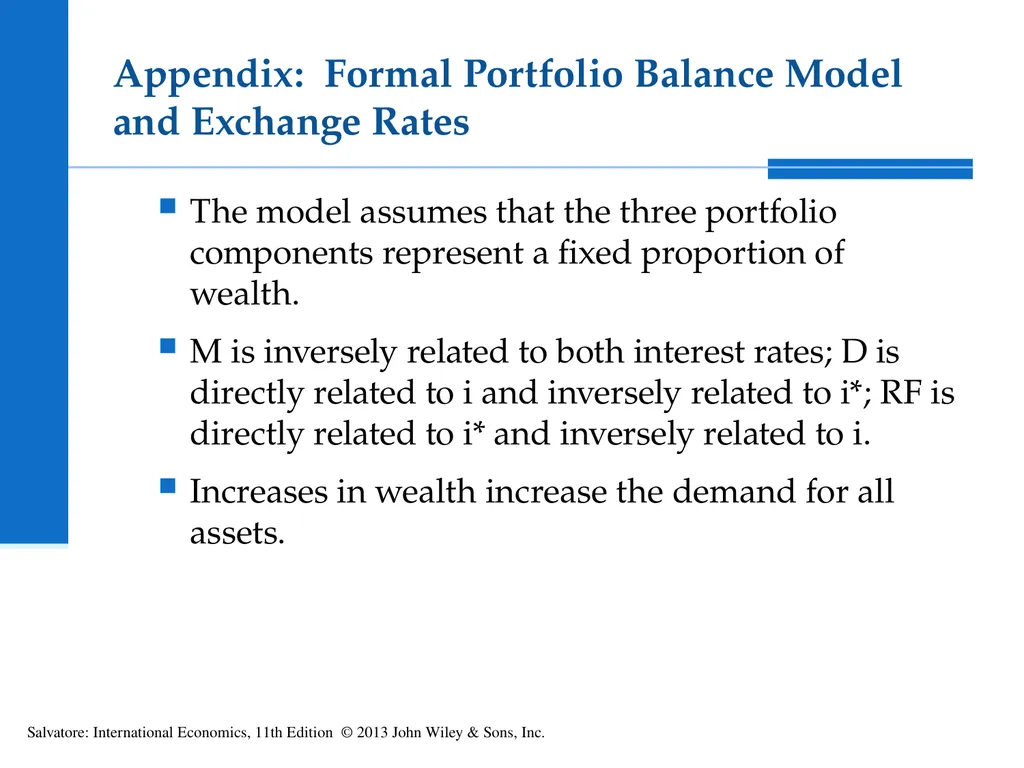
slide40. Appendix: Formal Portfolio Balance Model and Exchange Rates The model assumes that the three portfolio components represent a fixed proportion of wealth.
M is inversely related to both interest rates; D is directly related to i and inversely related to i*; RF is directly related to i* and inversely related to i.
Increases in wealth increase the demand for all assets. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
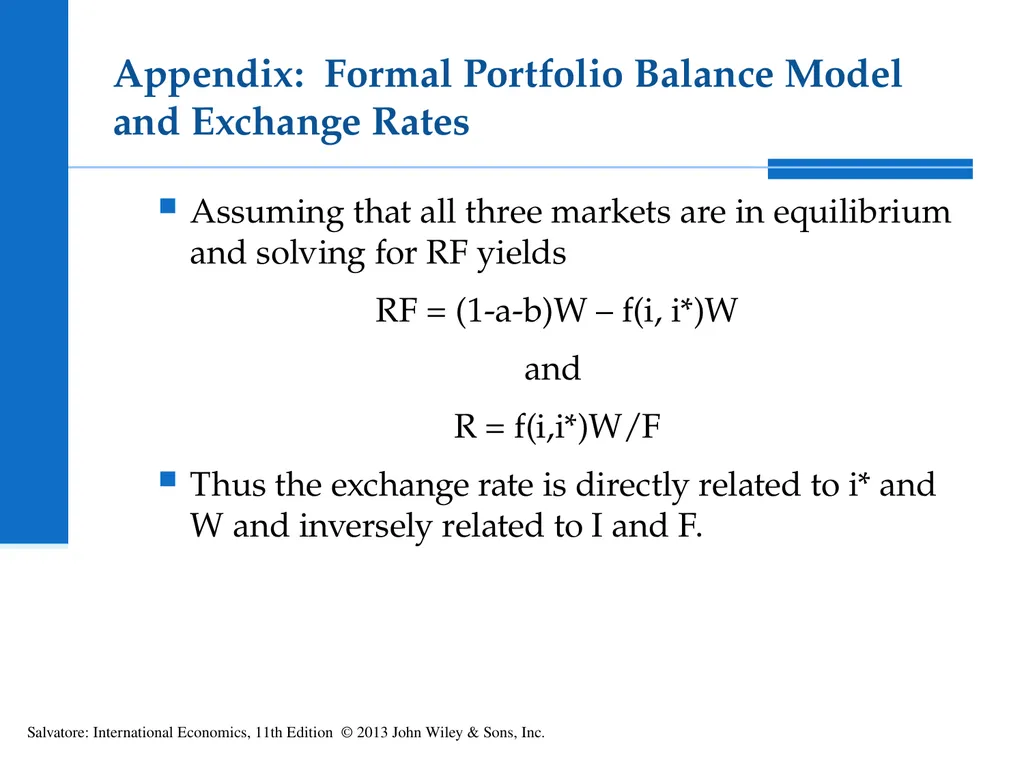
slide41. Appendix: Formal Portfolio Balance Model and Exchange Rates Assuming that all three markets are in equilibrium and solving for RF yields
RF = (1-a-b)W – f(i, i*)W
and
R = f(i,i*)W/F
Thus the exchange rate is directly related to i* and W and inversely related to I and F. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide42. Copyright 2013 John Wiley & Sons, Inc.
All rights reserved. Reproduction or translation of this work beyond that permitted in section 117 of the 1976 United States Copyright Act without express permission of the copyright owner is unlawful. Request for further information should be addressed to the Permissions Department, John Wiley & Sons, Inc. The purchaser may make back-up copies for his/her own use only and not for distribution or resale. The Publisher assumes no responsibility for errors, omissions, or damages caused by the use of these programs or from the use of the information herein. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
Dominick Salvatore
John Wiley & Sons, Inc. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. CHAPTER F I F T E E N 15<br>
slide2. Learning Goals: Understand the purchasing power parity theory and why it does not work in the short run
Understand how the monetary and the portfolio balance models of the exchange rate work
Understand the causes of exchange rate overshooting
Understand why exchange rates are so difficult to forecast Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide3. Introduction Since floating rates began in 1973, international financial flows are now larger than trade flows, shifting the focus to monetary theories of exchange rates.
Monetary exchange rate theories view the exchange rate as a purely financial phenomenon, and tend to explain exchange rate volatility and disequilibria in the short run. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide4. Purchasing-Power Parity Theory Absolute Purchasing Power Parity
The equilibrium exchange rate between two currencies equals the ratio of price levels in both nations.
R= P/P*
Where R = exchange rate or spot rate
P = general price level in home nation
P* = general price level in foreign nation
Example: If the price of a bushel of wheat is $1 in the United States and €1 in the European Monetary Union, then the exchange rate between the dollar and the euro should be R = $1/ €1 = 1. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide5. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. The law of one price
A given commodity should have the same price (so that the purchasing power of the two currencies is at parity) in both countries when expressed in terms of the same currency.
Caused by commodity arbitrage.<br>
slide6. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Absolute PPP theory can be misleading because:
Appears to give exchange rate that equilibrates trade in goods and services while ignoring capital account.
At exchange rate that equilibrates trade in goods and services, capital inflows would produce surplus in balance of payments, while capital outflows would lead to deficits.<br>
slide7. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Absolute PPP theory can be misleading because:
Will not even give exchange rate that equilibrates trade in goods and services because of existence of nontraded goods.
International trade tends to equalize prices of traded goods and services, not nontraded goods.<br>
slide8. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Relative Purchasing-Power Parity
The change in the exchange rate over a period of time should be proportional to the relative change in the price levels of two nations over the same time period. where R1 and R0 = exchange rates in period 1 and base period<br>
slide9. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Relative Purchasing-Power Parity
Example: If the general price level does not change in the foreign nation, from base period to period 1 (P*1/P*0 = 1), while the general price level in the home nation increases 50%, the relative PPP theory says the exchange rate should be 50% higher (home currency should depreciate 50%) in period 1 as compared to base period.<br>
slide10. Purchasing-Power Parity Theory Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Empirical Relevance<br>
slide11. Monetary Approach to the Balance of Payments and Exchange Rates The monetary approach to the balance of payments views the balance of payments as a monetary phenomenon.
Money plays crucial role in the long run as both a disturbance and an adjustment. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide12. Monetary Approach to the Balance of Payments and Exchange Rates Under Fixed Exchange Rates
A balance of payments surplus results from excess stock of money demanded that is not satisfied by domestic monetary authorities.
A balance of payments deficit results from excess in stock of money supplied that is not eliminated by monetary authorities.
Surplus/deficit is temporary and self-correcting in the long run.
Except for currency-reserve nation, the nation has no control over its money supply in the long run under fixed exchange system. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide13. Monetary Approach to the Balance of Payments and Exchange Rates Under Flexible Exchange Rates
Balance of payments disequilibria are immediately corrected by automatic changes in exchange rates without international flow of money or reserves.
Nation retains dominant control over its money supply and monetary policy.
Adjustment occurs as result of the change in domestic prices accompanying the change in exchange rate. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide14. FIGURE 15-3 Relative Money Supplies and Exchange Rates. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide15. Monetary Approach to the Balance of Payments and Exchange Rates Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide16. Portfolio Balance Model and Exchange Rates Portfolio Balance Approach
The exchange rate is determined in the process of equilibrating or balancing the stock or total demand and supply of financial assets (of which money is only one) in each country.
Regarded as a more realistic and satisfactory version of the monetary approach. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide17. Portfolio Balance Model and Exchange Rates Expectations, Interest Differentials, and Exchange Rates
The exchange rate is determined not only by the relative growth of money supply and money demand but also by inflation expectations and expected changes.
As long as domestic and foreign bonds are assumed to be perfect substitutes, (i-i*) = EA, where EA is the expected appreciation of the foreign currency. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide18. Portfolio Balance Model and Exchange Rates Portfolio Balance Approach
If investors demand more of a foreign asset, either because of higher relative foreign interest rates or increased wealth, demand for foreign currency will increase, depreciating domestic currency.
If investors sell foreign assets, either because of lower relative foreign interest rates or decreased wealth, supply of foreign currency will increase, appreciating domestic currency. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide19. Portfolio Balance Model and Exchange Rates Portfolio Balance Approach
Domestic and foreign bonds are assumed to be imperfect substitutes; domestic investors require a higher return to compensate for the risk of holding foreign bonds.
Stock model rather than a flow model.
The exchange rate is determined in the process of reaching equilibrium in each financial market. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide20. Portfolio Balance Model and Exchange Rates Extended Portfolio Balance Model
From the uncovered interest parity condition,
(i-i*) =EA.
Since domestic and foreign bonds are assumed to be imperfect substitutes,
(i-i*) =EA – RP,
where RP is the risk premium on holding the foreign bond. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide21. Portfolio Balance Model and Exchange Rates Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide22. Portfolio Balance Model and Exchange Rates Extended Demand Functions
M is a positive function of RP, Y, P, and W, and a negative function of i, i*, and EA.
D is a positive function of i, RP, and W, and a negative function of i*, EA, Y, and P.
F is a positive function of i*, EA, and W, and a negative function of i, RP, Y, and P.
Supplies of all assets are assumed to be exogenous.
Exchange rate changes are the result of portfolio adjustment. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide23. Exchange Rate Dynamics Exchange Rate Overshooting
Stock adjustments in financial assets are usually much larger and quicker to occur than adjustments in trade flows.
Most of the burden of adjustments in exchange rates comes from financial markets in short run.
Thus, exchange rate must overshoot or bypass its long run equilibrium level for equilibrium to be quickly reestablished in financial markets. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide24. FIGURE 15-6 Exchange Rate Overshooting. (Figure continues on next slide) Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide25. FIGURE 15-6 (continued) Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide26. Empirical Tests of the Monetary and Portfolio Balance Models and Exchange Rate Forecasting Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. Models of exchange rates have not been very successful at predicting future exchange rates.
Reasons:
Exchange rates are highly influenced by new information.
Expectations in exchange rate markets tend to be self-fulfilling (at least in the short-run).
This may lead to speculative bubbles, generate movements in the market contrary to what is expected by theory.<br>
slide27. Case Study 15-1 Absolute Purchasing Power Parity in the Real World Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-1 Actual and PPP Exchange Rate of the Dollar,
1973-2011.<br>
slide28. Case Study 15-2 The Big Mac Index and the Law of One Price Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide29. Case Study 15-2 The Big Mac Index and the Law of One Price Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide30. Case Study 15-3 Relative Purchasing-Power Parity in the Real World Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-2 Inflation Differentials and Exchange Rates, 1973-2011.<br>
slide31. Case Study 15-4 Monetary Growth and Inflation Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide32. Case Study 15-5 Nominal and Real Exchange Rates, and the Monetary Approach Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-4 Nominal and Real Exchange Rate Indices Between the Dollar and the Mark, 1973-2011.<br>
slide33. Case Study 15-6 Interest Differentials, Exchange Rates, and the Monetary Approach Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-5 Nominal Interest Rate Differentials and Exchange Rate Movements, 1973-2011.<br>
slide34. Case Study 15-7 Exchange Rate Overshooting of the U.S. Dollar Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide35. Case Study 15-8 The Euro Exchange Rate Defies Forecasts Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc. FIGURE 15-8 The Euro/Dollar Exchange Rate since the Introduction of the Euro.<br>
slide36. Appendix: Formal Monetary Approach Model Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide37. Appendix: Formal Monetary Approach Model Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide38. Appendix: Formal Monetary Approach Model Thus, all other things equal, when the nation’s monetary authorities change D, the reverse change will automatically take place in F, when exchange rates are fixed.
Thus under fixed rates, monetary authorities determine the composition but not the size of the monetary base. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide39. Appendix: Formal Portfolio Balance Model and Exchange Rates Write the basic equations of the model as
M = a(i, i*)W
D = b(i, i*)W
RF = c(i, i*)W
W = M + D + RF
where M is the quantity demanded of money by domestic residents, D is the demand for domestic bonds, RF is the demand for foreign bonds, and W is wealth. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide40. Appendix: Formal Portfolio Balance Model and Exchange Rates The model assumes that the three portfolio components represent a fixed proportion of wealth.
M is inversely related to both interest rates; D is directly related to i and inversely related to i*; RF is directly related to i* and inversely related to i.
Increases in wealth increase the demand for all assets. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide41. Appendix: Formal Portfolio Balance Model and Exchange Rates Assuming that all three markets are in equilibrium and solving for RF yields
RF = (1-a-b)W – f(i, i*)W
and
R = f(i,i*)W/F
Thus the exchange rate is directly related to i* and W and inversely related to I and F. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>
slide42. Copyright 2013 John Wiley & Sons, Inc.
All rights reserved. Reproduction or translation of this work beyond that permitted in section 117 of the 1976 United States Copyright Act without express permission of the copyright owner is unlawful. Request for further information should be addressed to the Permissions Department, John Wiley & Sons, Inc. The purchaser may make back-up copies for his/her own use only and not for distribution or resale. The Publisher assumes no responsibility for errors, omissions, or damages caused by the use of these programs or from the use of the information herein. Salvatore: International Economics, 11th Edition © 2013 John Wiley & Sons, Inc.<br>