
Introduction to Business Accounting and Finance

Description: Introduction to Business Accounting and Finance Module Learning Outcomes Recognize sound accounting practices, and use financial statements and accounting principles to make informed judgements about an organizations financial health 16.1:
Related Topics
Download Presentation
"Introduction to Business Accounting and Finance" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Introduction to Business Accounting and Finance<br>
slide2. Module Learning Outcomes Recognize sound accounting practices, and use financial statements and accounting principles to make informed judgements about an organization’s financial health
16.1: Define accounting, and explain its role as a form of business communication
16.2: Identify key financial statements and their components, and explain the primary use of each type of payment
16.3: Calculate the break-even point, where profit will be equal to $0, using information from financial statements
16.4: Use financial statements to calculate basic financial ratios to measure the profitability and health of a business
16.5: Discuss the importance of ethical practices in accounting and the implications of unethical behavior<br>
slide3. Accounting in Business<br>
slide4. Learning Outcomes: Accounting in Business 16.1: Define accounting, and explain its role as a form of business communication
16.1.1: Explain the role of accounting as a form of business communication
16.1.2: Identify the users and uses of financial accounting
16.1.3: Identify the users and uses of managerial accounting<br>
slide5. Class Discussion: Why Accounting?<br>
slide6. Understanding Accounting in Business Accounting is the measurement and communication process used to report on the activities of profit-seeking business organizations. It is the language of business.
Accounting represents all of the financial transactions of a business in a format that can be interpreted and understood by both internal and external stakeholders.<br>
slide7. Internal and External Users Users of accounting information are separated into two groups, internal and external.
Internal users are the people within a business organization who use accounting information. For example, the human resource department needs to have information about how profitable the business is in order to set salaries and benefits. Likewise, production managers need to know if the business is doing well enough to afford to replace worn-out machinery or pay overtime to production workers.
External users are people outside the business entity that use accounting information. These external users include potential investors, the Internal Revenue Service, banks and finance companies, as well as local taxing authorities.<br>
slide8. Uses of Financial Accounting Financial accounting information appears on financial statements that are intended primarily for external use. Financial accounting relates to the company as a whole.
Stockholders and creditors are two outside parties who need financial accounting information. These two parties make decisions pertaining to the entire company, such as whether to increase their investment in the company or to extend credit to the company.<br>
slide9. GAAP and Tax Accounting Financial accountants adhere to set of rules called Generally Accepted Accounting Principles (GAAP): a uniform set of accounting rules that allow users to compare the financial statements issued by one company to those of another company in the same industry.
Tax accounting information includes financial accounting information, written and presented in the tax code of the government. Tax accounting focuses on compliance with tax code and presenting the profit and loss story of a business to minimize its tax liability.<br>
slide10. Uses of Managerial Accounting Managerial accounting information is for internal use and provides special information for the managers of a company.
The information managers use may range from broad, long-range planning data to detailed explanations of why actual costs varied from cost estimates. Managerial accounting is more concerned with forward looking projections and making decisions that will affect the future of the organization, than in the historical recording and compliance aspects of the financial accountants.<br>
slide11. Bookkeeping vs. Accounting Accounting is often confused with bookkeeping.
Bookkeeping is a mechanical process that records the routine economic activities of a business.
Accounting includes bookkeeping, but it goes further to analyze and interpret financial information, prepare financial statements, conduct audits, design accounting systems, prepare special business and financial studies, prepare forecasts and budgets, and provide tax services.<br>
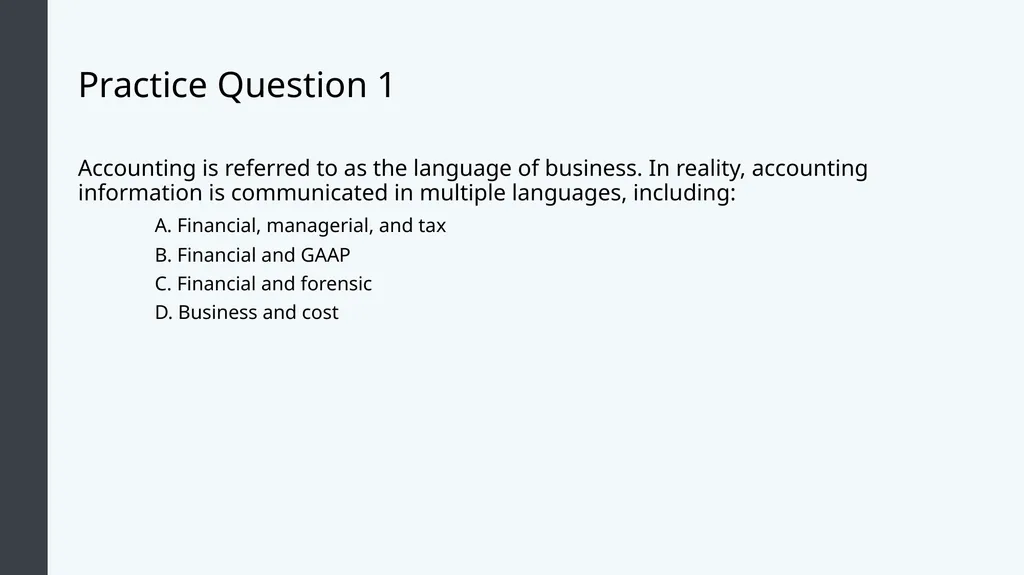
slide12. Practice Question 1 Accounting is referred to as the language of business. In reality, accounting information is communicated in multiple languages, including:
A. Financial, managerial, and tax
B. Financial and GAAP
C. Financial and forensic
D. Business and cost<br>
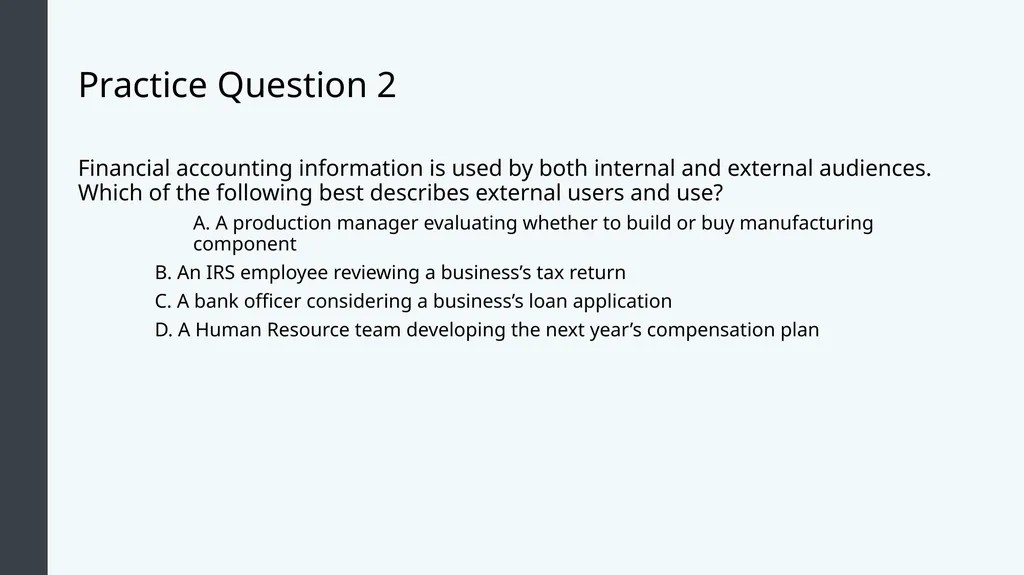
slide13. Practice Question 2 Financial accounting information is used by both internal and external audiences. Which of the following best describes external users and use?
A. A production manager evaluating whether to build or buy manufacturing component
B. An IRS employee reviewing a business’s tax return
C. A bank officer considering a business’s loan application
D. A Human Resource team developing the next year’s compensation plan<br>
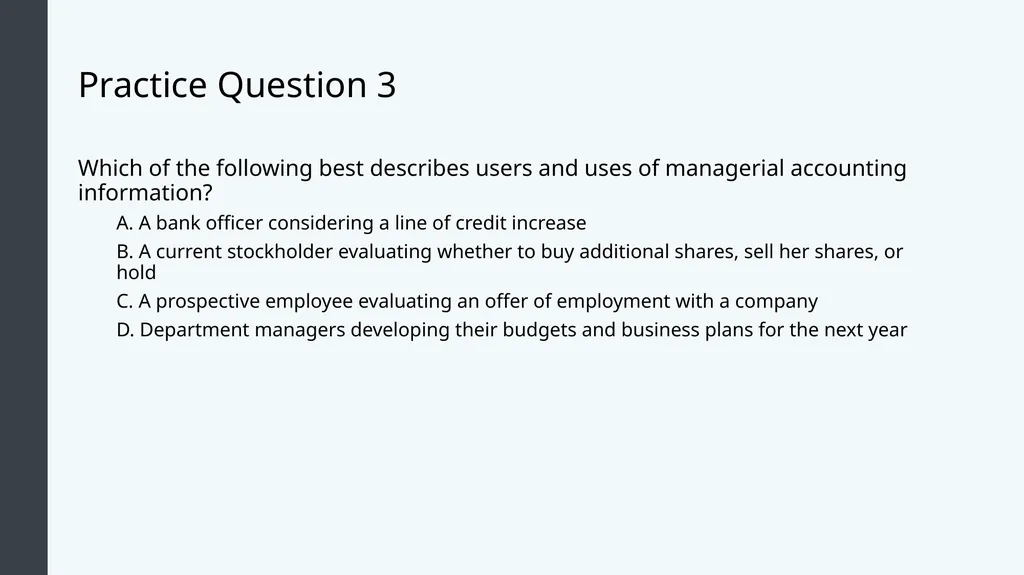
slide14. Practice Question 3 Which of the following best describes users and uses of managerial accounting information?
A. A bank officer considering a line of credit increase
B. A current stockholder evaluating whether to buy additional shares, sell her shares, or hold
C. A prospective employee evaluating an offer of employment with a company
D. Department managers developing their budgets and business plans for the next year<br>
slide15. Key Financial Statements<br>
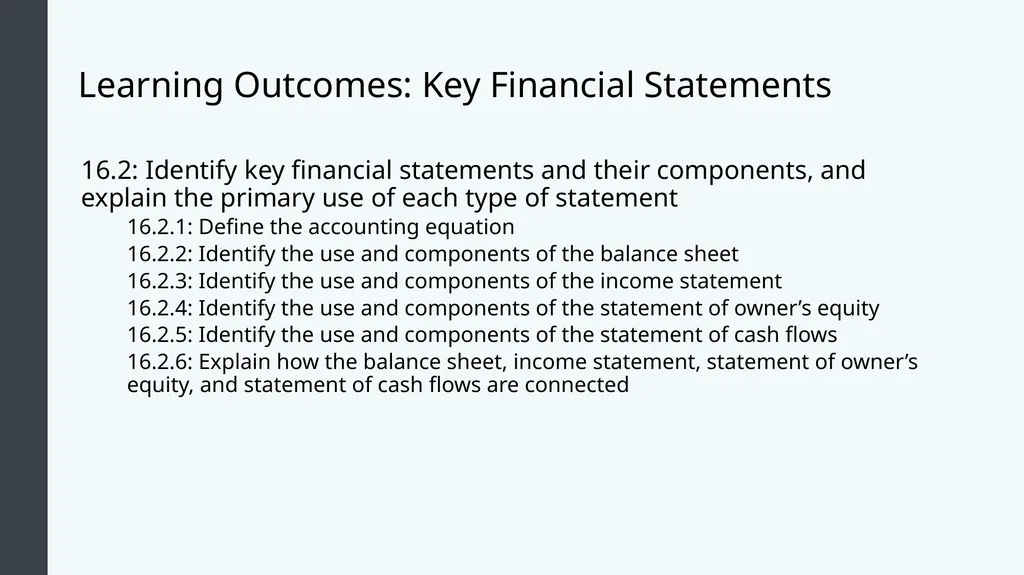
slide16. Learning Outcomes: Key Financial Statements 16.2: Identify key financial statements and their components, and explain the primary use of each type of statement
16.2.1: Define the accounting equation
16.2.2: Identify the use and components of the balance sheet
16.2.3: Identify the use and components of the income statement
16.2.4: Identify the use and components of the statement of owner’s equity
16.2.5: Identify the use and components of the statement of cash flows
16.2.6: Explain how the balance sheet, income statement, statement of owner’s equity, and statement of cash flows are connected<br>
slide17. Understanding Key Financial Statements Financial statements are the means by which companies communicate their story. Together these statements represent the profitability and financial strength of a company.
Key Financial Statements include:
Income statement: reflects a company’s profitability
Statement of owner's equity: shows the change in retained earnings between the beginning and end of a period
Balance sheet: reflects a company’s solvency and financial position
Statement of cash flows: shows the cash inflows and outflows for a company during a period of time<br>
slide18. The Accounting Equation Three terms used in the accounting equation:
Asset: An asset is an economic resource that can be tangible or intangible. Assets represent value that can be converted into cash. They can include cash, vehicles, buildings, equipment, patents, and debts owed to the company.
Liability: future sacrifices of economic benefits that the entity is obliged to make to other entities as a result of past transactions or other past events. Liability can include loans, monies owed to a supplier or creditor that the business will use assets to settle.
Equity: the difference between the value of the assets and the amount of the liabilities of something owned. Owner’s equity consists of the net assets of an entity (net assets = total assets - total liability)
The Accounting Equation: Assets - Liability = Owner’s or Shareholder’s Equity<br>
slide19. Income Statement Also called “earnings statement” or “profit and loss statement”
First financial statement prepared because it provides information for the remaining 3 statements
Provides information about the profitability of a stated period of time
Made up of 3 types of accounts:
1. Revenue: inflows of cash resulting from the sale of products or the rendering of services to customers
2. Expenses: costs incurred to produce revenues
3. Net Income (Revenues - Expenses = Net Income)<br>
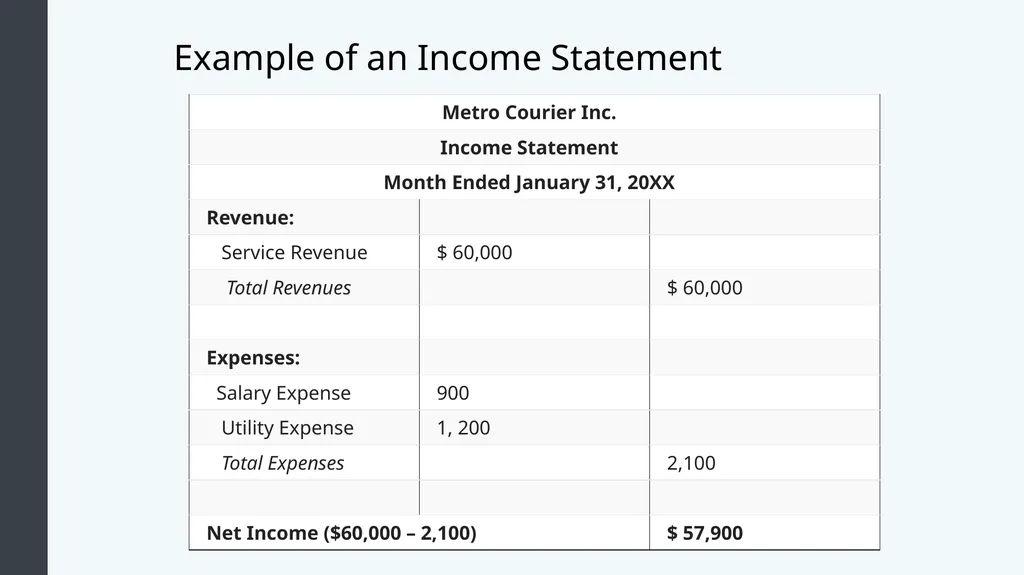
slide20. Example of an Income Statement<br>
slide21. Statement of Owner’s Equity Explains the changes in retained earnings between two balance sheet dates
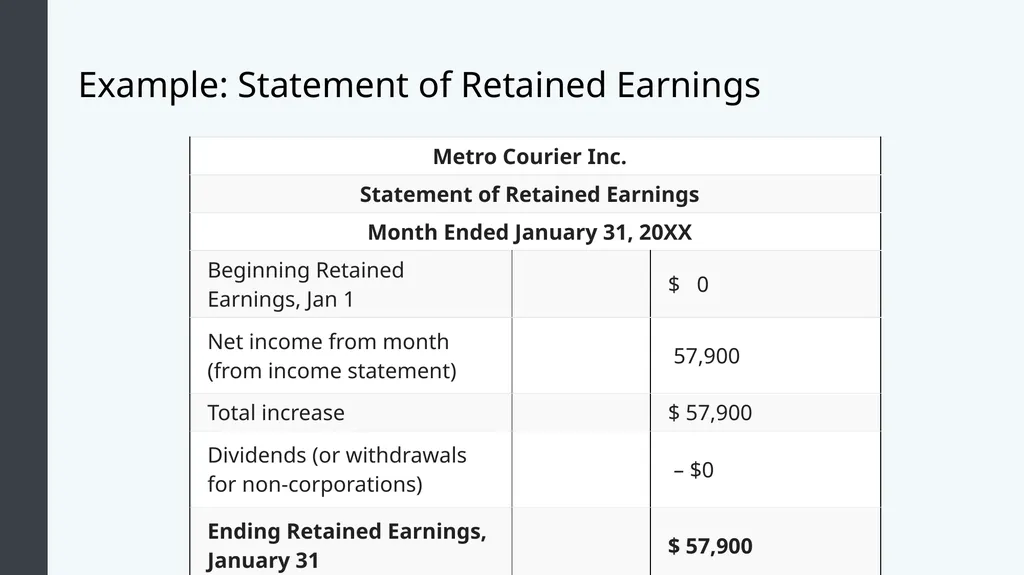
We start with beginning retained earnings (in our example, the business began in January, so we start with a zero balance) and add any net income (or subtract net loss) from the income statement. Next, we subtract any dividends declared (or any owner withdrawals in a partnership or sole-proprietor) to get the ending balance in retained earnings (or capital for non-corporations)<br>
slide22. Example: Statement of Retained Earnings<br>
slide23. Balance Sheets Provides a snapshot of company’s financial position at a particular moment in time. That specific moment is the close of business on the date of the balance sheet.
Lists a company’s:
Assets
Liabilities
Equity
The Accounting Equation
Assets – Liabilities = Owner’s or Shareholders’ Equity<br>
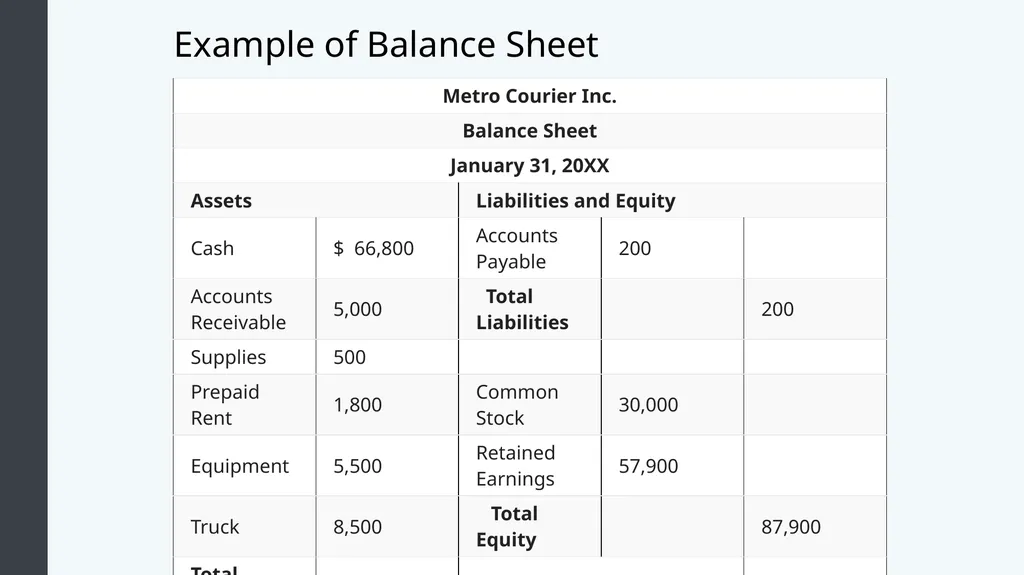
slide24. Example of Balance Sheet<br>
slide25. Statement of Cash Flow Reports the cash receipts and cash disbursements during an accounting period
Reports effects on cash of a company’s:
Operating activities
Investing activities
Financing activities
Includes both cash and cash equivalents (ex. investments)<br>
slide26. Operating Activities: Cash Inflows Cash inflows from operating activities include:
Cash from sales of goods or services
Interest received from making loans
Dividends received from investments in equity securities
Cash received from the sale of trading securities
Other cash receipts that do not arise from transactions defined as investing or financing activities<br>
slide27. Operating Activities: Cash Outflows Cash outflows for operating activities include payments to:
Acquire inventory
Suppliers and employees for other goods or services
Lenders and other creditors for interest
Purchase trading securities
All other cash payments that do not arise from transactions defined as investing or financing activities<br>
slide28. Investing Activities Cash inflows from investing activities include:
Sale of property, plant, and equipment
Sale of available-for-sale and held-to-maturity securities
Collection of long-term loans made to others
Cash outflows for investing activities include:
Purchase of property, plant, and equipment
Purchase of available-for-sale and held-to-maturity securities
Long-term loans to others<br>
slide29. Financing Activities Cash inflows from financing activities include:
Cash received from issuing capital stock and bonds, mortgages, and notes, and from other short- or long-term borrowing
Cash outflows for financing activities include:
Payments of cash dividends or other distributions to owners (including cash paid to purchase treasury stock) and repayments of amounts borrowed<br>
slide30. The Break-Even Point<br>
slide31. Learning Outcomes: The Break-Even Point 16.3: Calculate the break-even point, where profit will be equal to $0, using information from financial statements
16.3.1: Define the break-even point
16.3.2: Differentiate between fixed and variable costs
16.3.3: Calculate the break-even point
16.3.4: Calculate the contribution margin
16.3.5: Calculate the contribution margin ratio
16.3.6: Calculate the margin of safety<br>
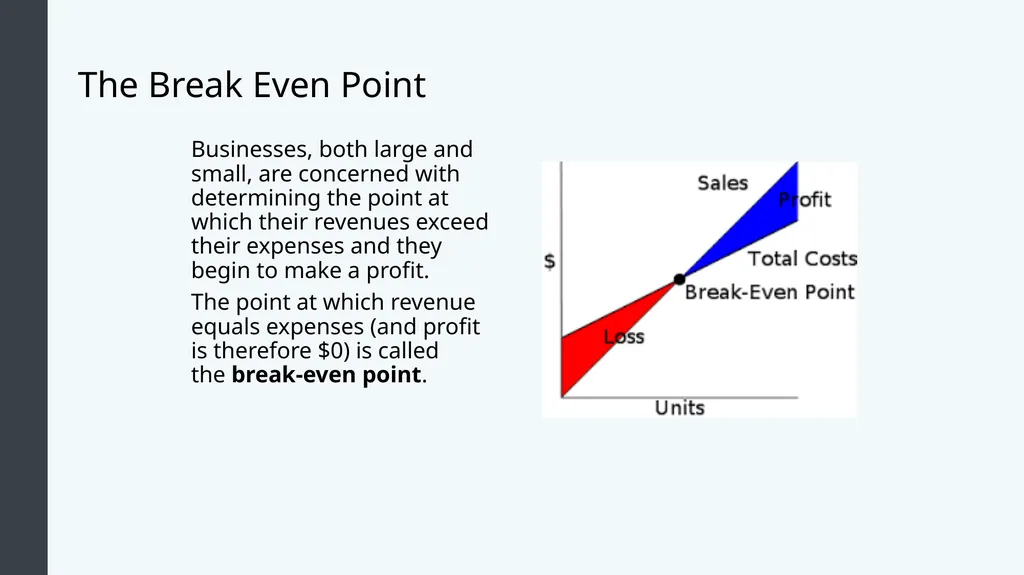
slide32. The Break Even Point Businesses, both large and small, are concerned with determining the point at which their revenues exceed their expenses and they begin to make a profit.
The point at which revenue equals expenses (and profit is therefore $0) is called the break-even point.<br>
slide33. Difference Between Fixed and Variable Costs Fixed costs are expenses that are not dependent on the amount of goods or services produced by the business.
Examples: salaries or rents paid per month
Variable Costs are volume related and are paid per quantity or unit produced.
Examples: gas or tires for a car<br>
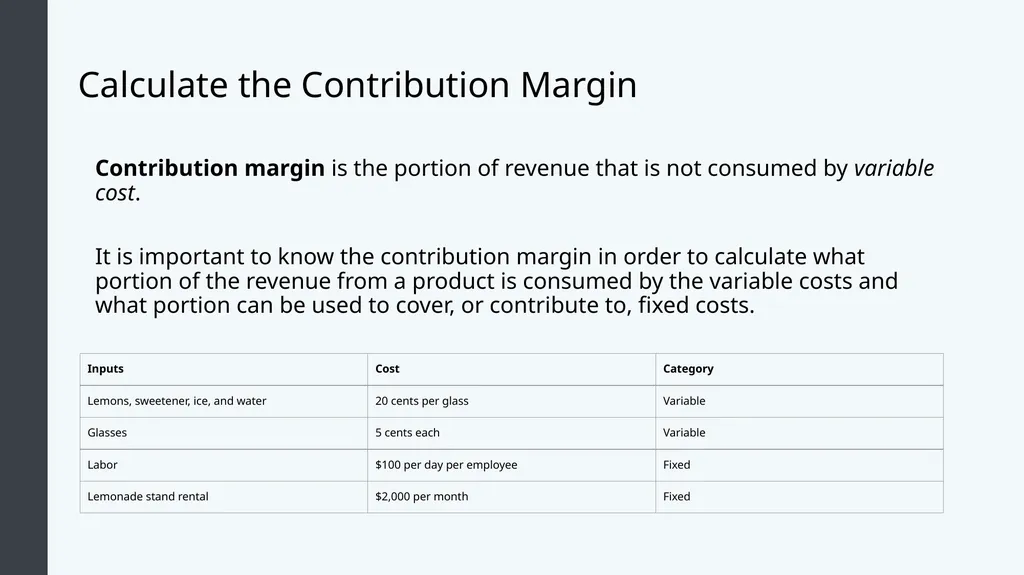
slide34. Calculate the Contribution Margin Contribution margin is the portion of revenue that is not consumed by variable cost.
It is important to know the contribution margin in order to calculate what portion of the revenue from a product is consumed by the variable costs and what portion can be used to cover, or contribute to, fixed costs.<br>
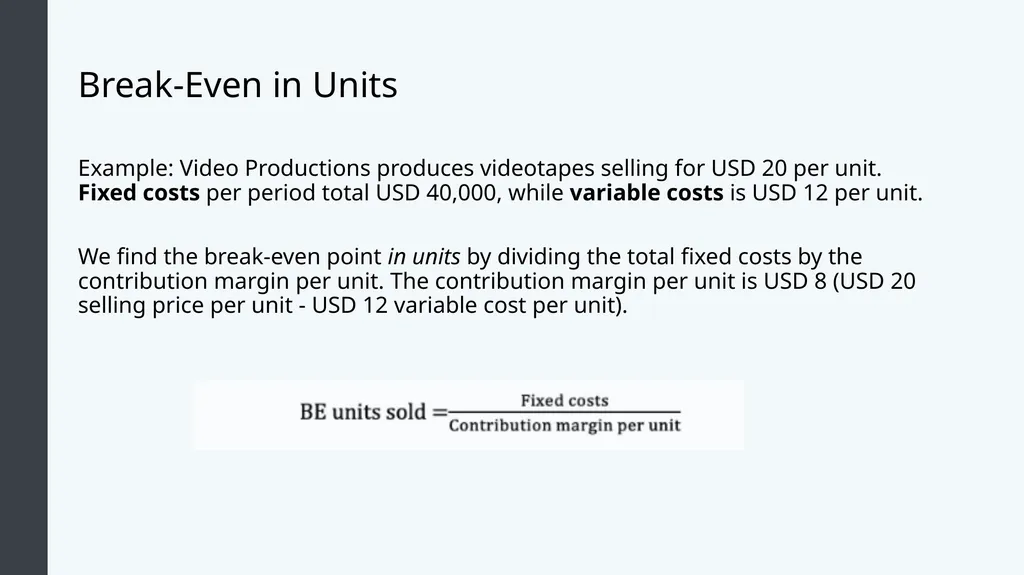
slide35. Break-Even in Units Example: Video Productions produces videotapes selling for USD 20 per unit. Fixed costs per period total USD 40,000, while variable costs is USD 12 per unit.
We find the break-even point in units by dividing the total fixed costs by the contribution margin per unit. The contribution margin per unit is USD 8 (USD 20 selling price per unit - USD 12 variable cost per unit).<br>
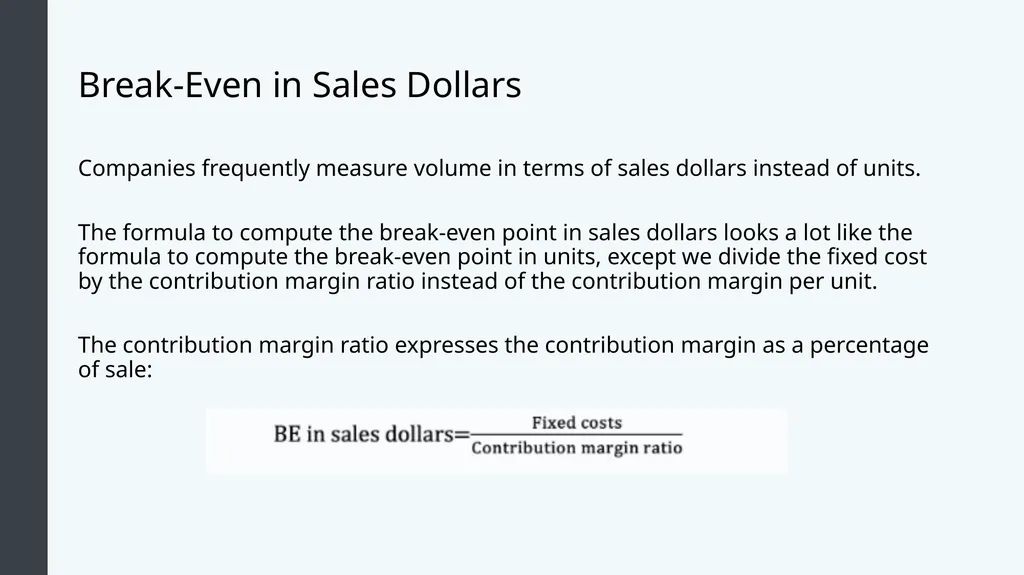
slide36. Break-Even in Sales Dollars Companies frequently measure volume in terms of sales dollars instead of units.
The formula to compute the break-even point in sales dollars looks a lot like the formula to compute the break-even point in units, except we divide the fixed cost by the contribution margin ratio instead of the contribution margin per unit.
The contribution margin ratio expresses the contribution margin as a percentage of sale:<br>
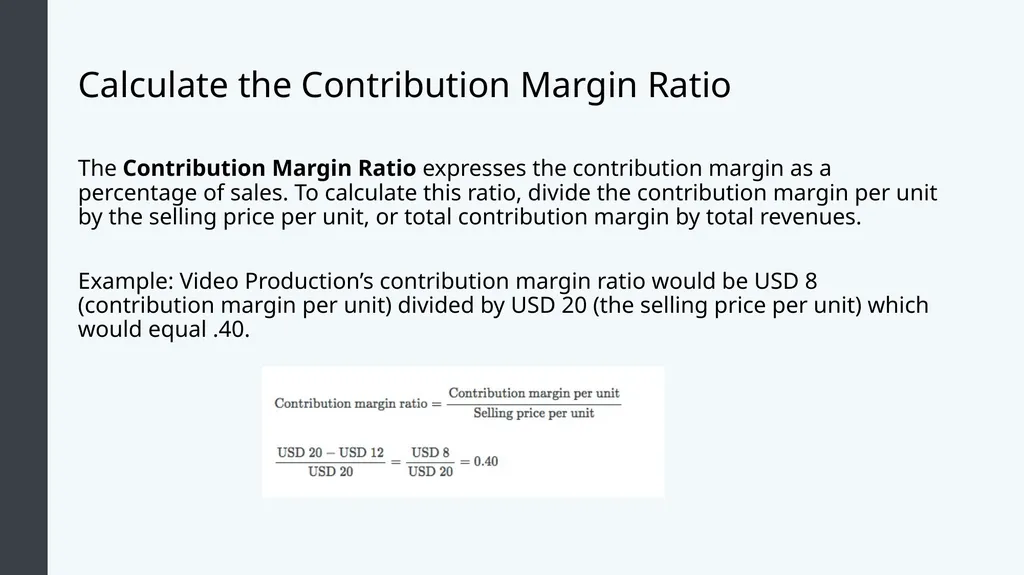
slide37. Calculate the Contribution Margin Ratio The Contribution Margin Ratio expresses the contribution margin as a percentage of sales. To calculate this ratio, divide the contribution margin per unit by the selling price per unit, or total contribution margin by total revenues.
Example: Video Production’s contribution margin ratio would be USD 8 (contribution margin per unit) divided by USD 20 (the selling price per unit) which would equal .40.<br>
slide38. Margin of Safety If a company’s current sales are more than its break-even point, it has a margin of safety equal to current sales minus break-even sales.
The margin of safety is the amount by which sales can decrease before the company incurs a loss.
Margin of safety = Current Sales - Break-even sales
Example: Margin of safety = USD 120,000 - USD 100,000 when Video Productions has sales of USD 120,000 and its break-even sales are USE 100,000<br>
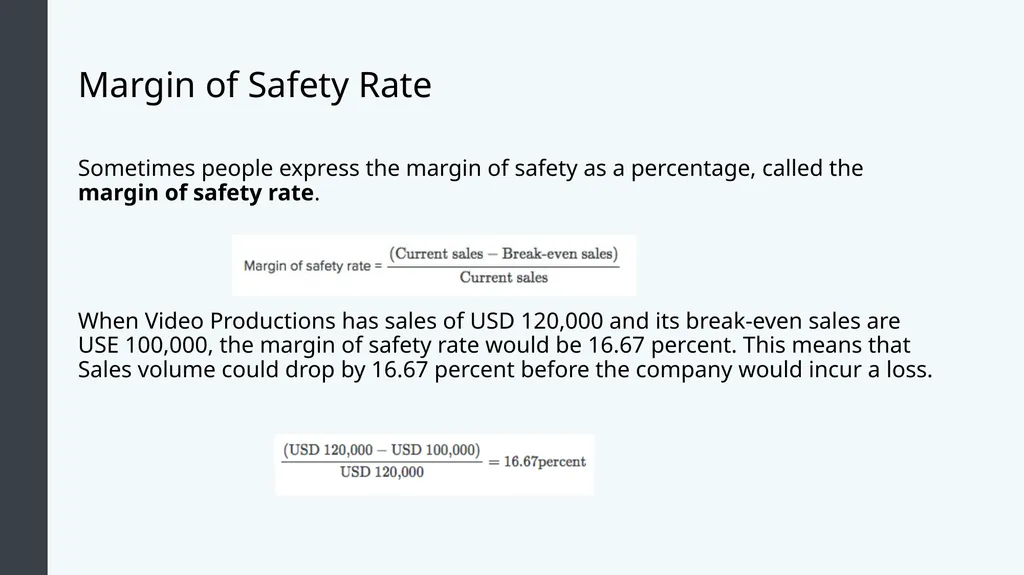
slide39. Margin of Safety Rate Sometimes people express the margin of safety as a percentage, called the margin of safety rate.
When Video Productions has sales of USD 120,000 and its break-even sales are USE 100,000, the margin of safety rate would be 16.67 percent. This means that Sales volume could drop by 16.67 percent before the company would incur a loss.<br>
slide40. Financial Ratios<br>
slide41. Learning Outcomes: Financial Ratios 16.4: Use financial statements to calculate basic financial ratios to measure the profitability and health of a business
16.4.1: Explain how financial ratios are used
16.4.2: Calculate the current ratio using information from financial statements
16.4.3: Calculate the acid-test (quick) ratio using information from financial statements
16.4.4: Calculate inventory turnover using information form financial statements<br>
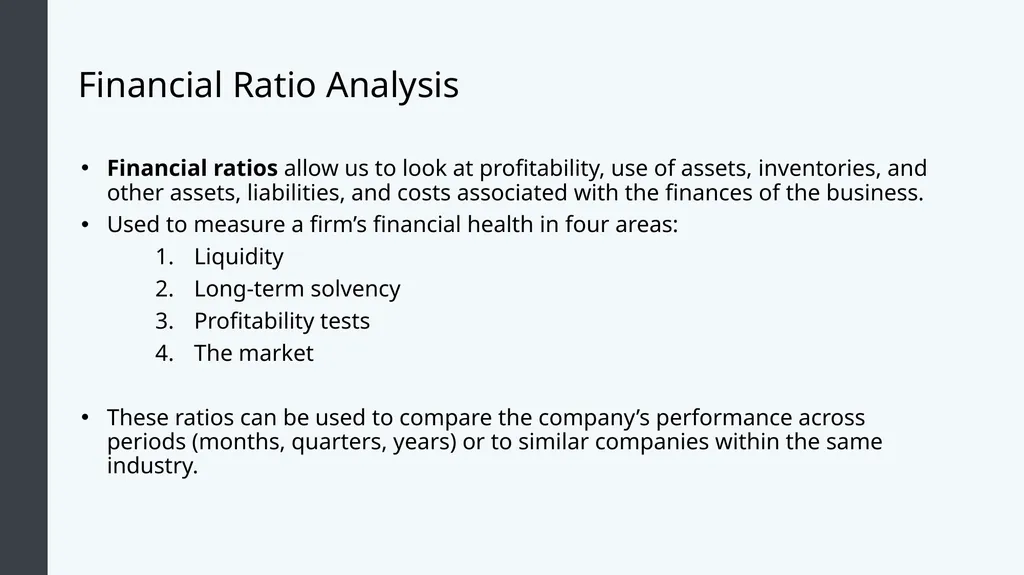
slide42. Financial Ratio Analysis Financial ratios allow us to look at profitability, use of assets, inventories, and other assets, liabilities, and costs associated with the finances of the business.
Used to measure a firm’s financial health in four areas:
Liquidity
Long-term solvency
Profitability tests
The market
These ratios can be used to compare the company’s performance across periods (months, quarters, years) or to similar companies within the same industry.<br>
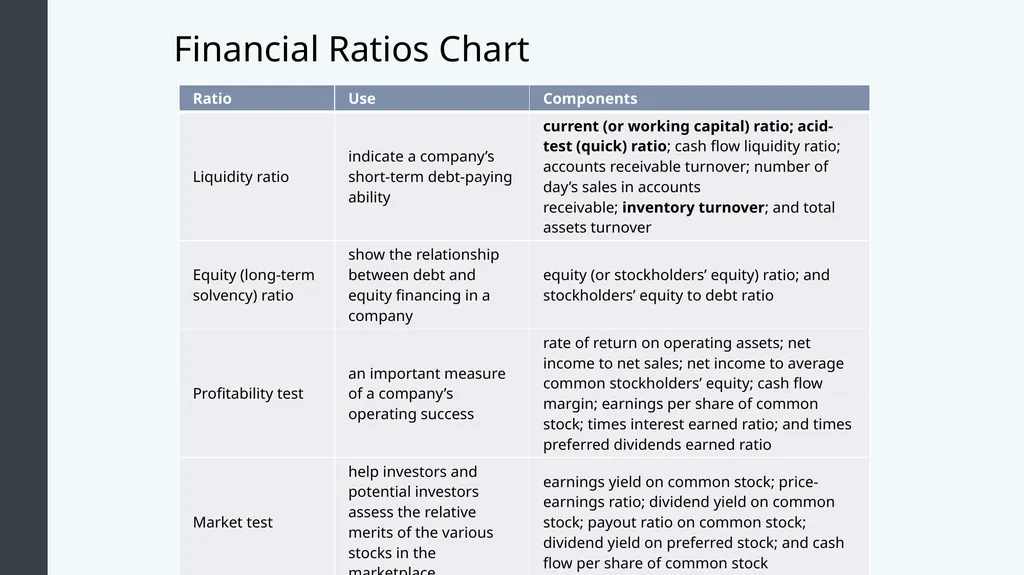
slide43. Financial Ratios Chart<br>
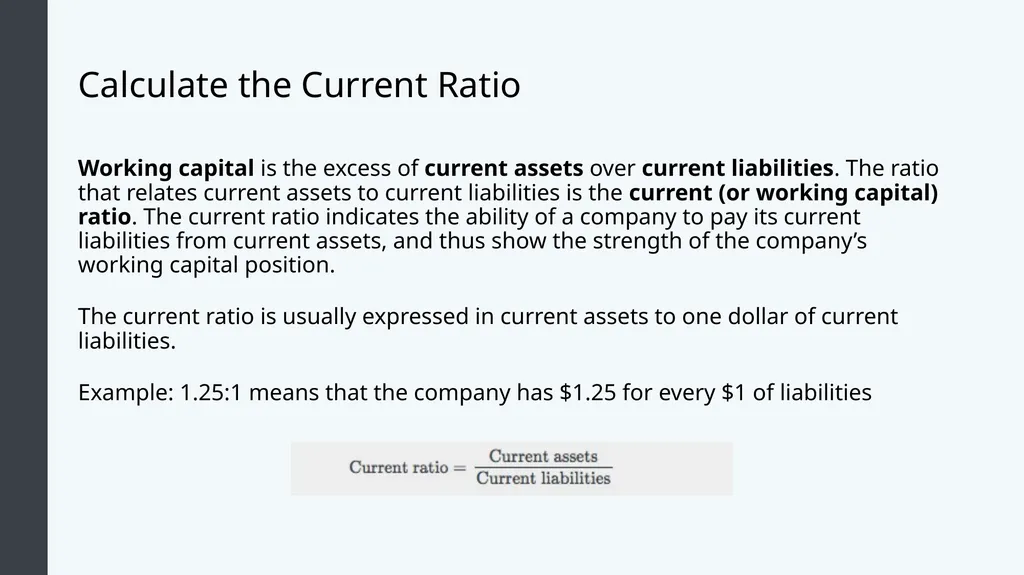
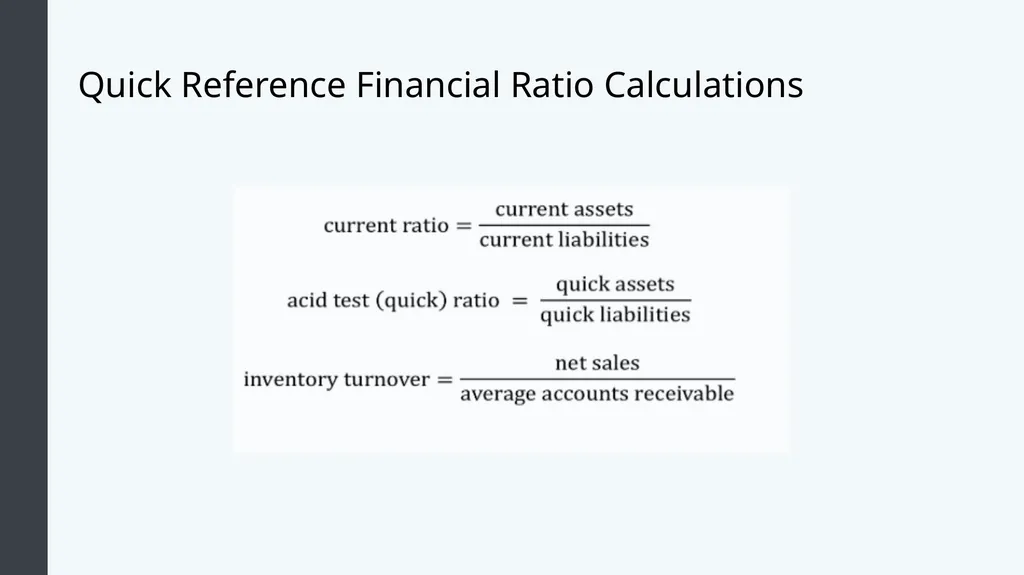
slide44. Calculate the Current Ratio Working capital is the excess of current assets over current liabilities. The ratio that relates current assets to current liabilities is the current (or working capital) ratio. The current ratio indicates the ability of a company to pay its current liabilities from current assets, and thus show the strength of the company’s working capital position.
The current ratio is usually expressed in current assets to one dollar of current liabilities.
Example: 1.25:1 means that the company has $1.25 for every $1 of liabilities<br>
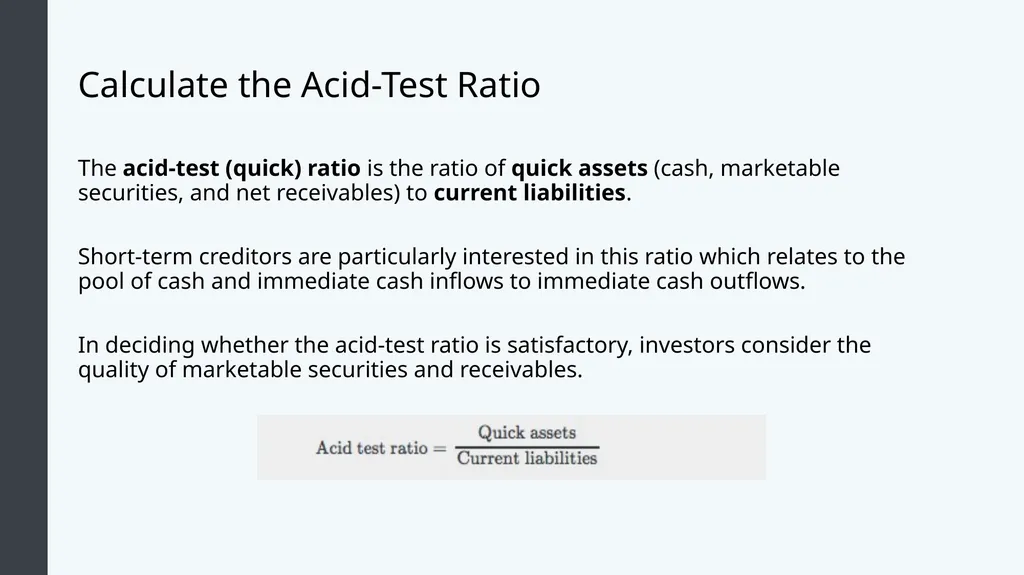
slide45. Calculate the Acid-Test Ratio The acid-test (quick) ratio is the ratio of quick assets (cash, marketable securities, and net receivables) to current liabilities.
Short-term creditors are particularly interested in this ratio which relates to the pool of cash and immediate cash inflows to immediate cash outflows.
In deciding whether the acid-test ratio is satisfactory, investors consider the quality of marketable securities and receivables.<br>
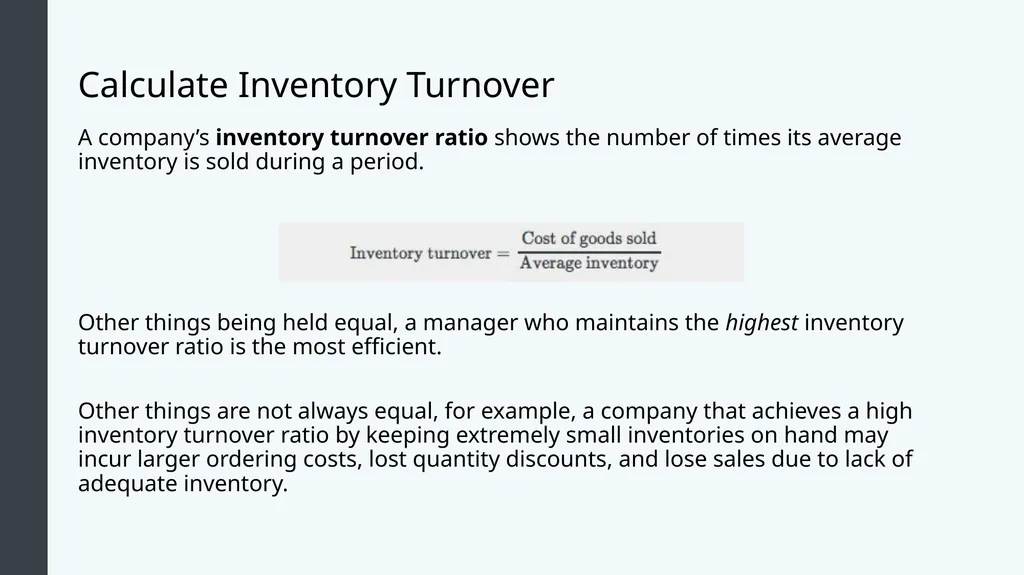
slide46. Calculate Inventory Turnover A company’s inventory turnover ratio shows the number of times its average inventory is sold during a period.
Other things being held equal, a manager who maintains the highest inventory turnover ratio is the most efficient.
Other things are not always equal, for example, a company that achieves a high inventory turnover ratio by keeping extremely small inventories on hand may incur larger ordering costs, lost quantity discounts, and lose sales due to lack of adequate inventory.<br>
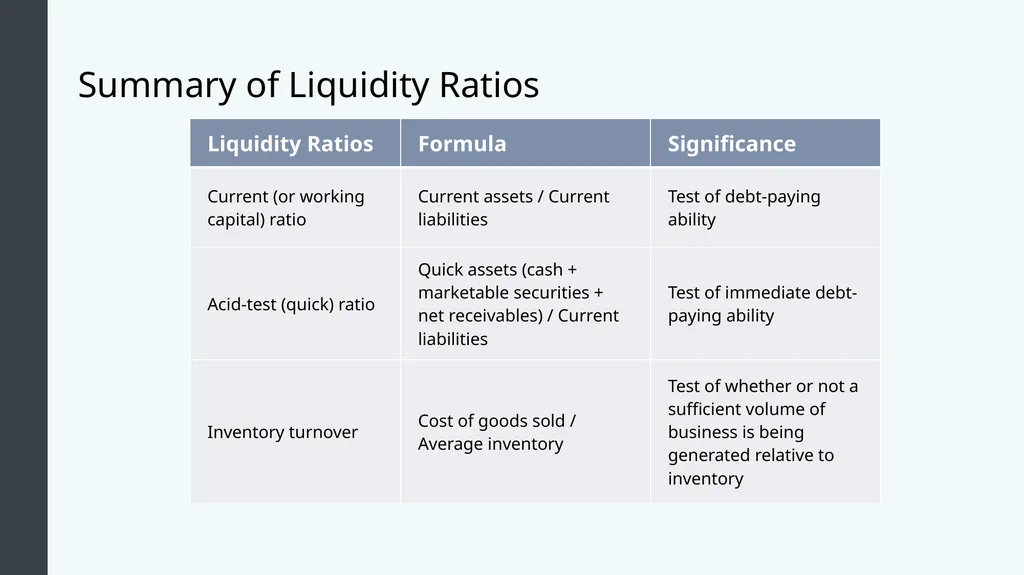
slide47. Summary of Liquidity Ratios<br>
slide48. Interpretation and Use of Ratios Standing alone, a single financial ratio may not be informative. Investors gain a greater insight by computing and analyzing several related ratios for a company.
Analysts must be sure their comparisons are valid, especially if those comparisons are from different time periods.
Analysts must consider many items including:
Business conditions
Important events that may have a large impact on a ratio
The seasonal nature of some businesses<br>
slide49. Quick Reference Financial Ratio Calculations<br>
slide50. Practice Question 5 Financial ratios allow a business, potential creditor, or investor to:
A. conduct a manager’s performance review
B. compare the performance of unrelated business
C. determine the health of a company individually and relate to similar businesses or alternative investment options
D. evaluate market conditions<br>
slide51. Practice Question 6 The current ratio is a liquidity ratio that serves as an indicator of a company’s short-term debt-paying ability. Let’s assume your belt company’s month-end balance sheet lists $2,000 in current assets, $5,000 in total assets, $500 in current liabilities and $1,000 in total liabilities. What is your current ratio?
A. 4
B. 5
C. 4:1
D. $5:$1<br>
slide52. Practice Question 7 The acid-test is another liquidity ratio that is of particular interest to those who are considering a business’ request for a short-term loan or credit. Let’s say your $2,000 current asset balance includes $200 in cash, $500 in accounts receivable (net), $300 in a money market account, $700 in supplies and $300 in prepaid insurance. Your current liabilities are $500. What is your current ratio?
A. 2:1
B. 3.4:1
C. 4:1
D. 2<br>
slide53. Practice Question 8 A company’s inventory turnover ratio shows the number of times its average inventory is sold during a period, where a higher inventory turnover is generally considered to be better. Pulling a COGS of $5,000 from the income statement and calculating average inventory of $300 based on January 1 and December 31 balance sheet data, what is the inventory turnover?
A. 6%
B. 6
C. 16.67
D. 17%<br>
slide54. Class Discussion: Accounting and Life Now we’ve learned and practiced some basic accounting principles and calculations: the accounting equation, balance sheet, income statement. owner’s equity, cash flows, break even, contribution margin, margin of safety, and financial ratios.
Discuss as a large group how accounting practices could help you in your personal life even if you are not a CPA.<br>
slide55. Ethical Practices in Accounting<br>
slide56. Learning Outcomes: Ethical Practices in Accounting 16.5: Discuss the importance of ethical practices in accounting and the implications of unethical behavior
16.5.1: Discuss the consequences of unethical practices in the accounting profession
16.5.2: Discuss the impact of the Sarbanes-Oxley Act on accounting practices<br>
slide57. Consequences of Unethical Behavior in Accounting Unethical financial reporting has cost taxpayers billions of dollars, employees their jobs, and the accounting profession its untarnished reputation.
The American Institute of Public Accountants (AIPA) has its own Code of Professional Conduct that prescribes the ethical conduct members should strive to achieve which include the following guidance:
Recognize and consider all relevant facts and circumstances, including applicable rules, laws or regulations,
Consider the ethical issues involved,
Consider established internal procedures, and then
Formulate alternative courses of action.
After weighing the consequences of each course of action, you select the best course of action based on your own judgment.<br>
slide58. Sarbanes-Oxley (SOX) In 2002 the Sarbanes-Oxley Act (SOX) went into effect. This law is one of the most extensive pieces of business legislation passed by Congress.
Attempts to foster ethical behavior in business accounting
Top management must individually certify the accuracy of financial information
Increased severity of penalties for fraudulent financial activity and altering or destroying key audit documents
Increased the oversight role of boards of directors and the independence of outside auditors
Has improved investor confidence and made financial statements more accurate and reliable
Restricts the scope of non-auditing work and auditor may perform for a client<br>
slide59. Quick Review What is accounting? What is its role as a form of business communication?
What are key financial statements and their components, and what is the primary use of each type of statement?
How do you calculate the break-even point, where profit will be equal to $0, using information from financial statements?
How do you use financial statements to calculate basic financial ratios to measure the profitability and health of a business?
Why are ethical practices in accounting important? What are the implications of unethical behavior?<br>
slide2. Module Learning Outcomes Recognize sound accounting practices, and use financial statements and accounting principles to make informed judgements about an organization’s financial health
16.1: Define accounting, and explain its role as a form of business communication
16.2: Identify key financial statements and their components, and explain the primary use of each type of payment
16.3: Calculate the break-even point, where profit will be equal to $0, using information from financial statements
16.4: Use financial statements to calculate basic financial ratios to measure the profitability and health of a business
16.5: Discuss the importance of ethical practices in accounting and the implications of unethical behavior<br>
slide3. Accounting in Business<br>
slide4. Learning Outcomes: Accounting in Business 16.1: Define accounting, and explain its role as a form of business communication
16.1.1: Explain the role of accounting as a form of business communication
16.1.2: Identify the users and uses of financial accounting
16.1.3: Identify the users and uses of managerial accounting<br>
slide5. Class Discussion: Why Accounting?<br>
slide6. Understanding Accounting in Business Accounting is the measurement and communication process used to report on the activities of profit-seeking business organizations. It is the language of business.
Accounting represents all of the financial transactions of a business in a format that can be interpreted and understood by both internal and external stakeholders.<br>
slide7. Internal and External Users Users of accounting information are separated into two groups, internal and external.
Internal users are the people within a business organization who use accounting information. For example, the human resource department needs to have information about how profitable the business is in order to set salaries and benefits. Likewise, production managers need to know if the business is doing well enough to afford to replace worn-out machinery or pay overtime to production workers.
External users are people outside the business entity that use accounting information. These external users include potential investors, the Internal Revenue Service, banks and finance companies, as well as local taxing authorities.<br>
slide8. Uses of Financial Accounting Financial accounting information appears on financial statements that are intended primarily for external use. Financial accounting relates to the company as a whole.
Stockholders and creditors are two outside parties who need financial accounting information. These two parties make decisions pertaining to the entire company, such as whether to increase their investment in the company or to extend credit to the company.<br>
slide9. GAAP and Tax Accounting Financial accountants adhere to set of rules called Generally Accepted Accounting Principles (GAAP): a uniform set of accounting rules that allow users to compare the financial statements issued by one company to those of another company in the same industry.
Tax accounting information includes financial accounting information, written and presented in the tax code of the government. Tax accounting focuses on compliance with tax code and presenting the profit and loss story of a business to minimize its tax liability.<br>
slide10. Uses of Managerial Accounting Managerial accounting information is for internal use and provides special information for the managers of a company.
The information managers use may range from broad, long-range planning data to detailed explanations of why actual costs varied from cost estimates. Managerial accounting is more concerned with forward looking projections and making decisions that will affect the future of the organization, than in the historical recording and compliance aspects of the financial accountants.<br>
slide11. Bookkeeping vs. Accounting Accounting is often confused with bookkeeping.
Bookkeeping is a mechanical process that records the routine economic activities of a business.
Accounting includes bookkeeping, but it goes further to analyze and interpret financial information, prepare financial statements, conduct audits, design accounting systems, prepare special business and financial studies, prepare forecasts and budgets, and provide tax services.<br>
slide12. Practice Question 1 Accounting is referred to as the language of business. In reality, accounting information is communicated in multiple languages, including:
A. Financial, managerial, and tax
B. Financial and GAAP
C. Financial and forensic
D. Business and cost<br>
slide13. Practice Question 2 Financial accounting information is used by both internal and external audiences. Which of the following best describes external users and use?
A. A production manager evaluating whether to build or buy manufacturing component
B. An IRS employee reviewing a business’s tax return
C. A bank officer considering a business’s loan application
D. A Human Resource team developing the next year’s compensation plan<br>
slide14. Practice Question 3 Which of the following best describes users and uses of managerial accounting information?
A. A bank officer considering a line of credit increase
B. A current stockholder evaluating whether to buy additional shares, sell her shares, or hold
C. A prospective employee evaluating an offer of employment with a company
D. Department managers developing their budgets and business plans for the next year<br>
slide15. Key Financial Statements<br>
slide16. Learning Outcomes: Key Financial Statements 16.2: Identify key financial statements and their components, and explain the primary use of each type of statement
16.2.1: Define the accounting equation
16.2.2: Identify the use and components of the balance sheet
16.2.3: Identify the use and components of the income statement
16.2.4: Identify the use and components of the statement of owner’s equity
16.2.5: Identify the use and components of the statement of cash flows
16.2.6: Explain how the balance sheet, income statement, statement of owner’s equity, and statement of cash flows are connected<br>
slide17. Understanding Key Financial Statements Financial statements are the means by which companies communicate their story. Together these statements represent the profitability and financial strength of a company.
Key Financial Statements include:
Income statement: reflects a company’s profitability
Statement of owner's equity: shows the change in retained earnings between the beginning and end of a period
Balance sheet: reflects a company’s solvency and financial position
Statement of cash flows: shows the cash inflows and outflows for a company during a period of time<br>
slide18. The Accounting Equation Three terms used in the accounting equation:
Asset: An asset is an economic resource that can be tangible or intangible. Assets represent value that can be converted into cash. They can include cash, vehicles, buildings, equipment, patents, and debts owed to the company.
Liability: future sacrifices of economic benefits that the entity is obliged to make to other entities as a result of past transactions or other past events. Liability can include loans, monies owed to a supplier or creditor that the business will use assets to settle.
Equity: the difference between the value of the assets and the amount of the liabilities of something owned. Owner’s equity consists of the net assets of an entity (net assets = total assets - total liability)
The Accounting Equation: Assets - Liability = Owner’s or Shareholder’s Equity<br>
slide19. Income Statement Also called “earnings statement” or “profit and loss statement”
First financial statement prepared because it provides information for the remaining 3 statements
Provides information about the profitability of a stated period of time
Made up of 3 types of accounts:
1. Revenue: inflows of cash resulting from the sale of products or the rendering of services to customers
2. Expenses: costs incurred to produce revenues
3. Net Income (Revenues - Expenses = Net Income)<br>
slide20. Example of an Income Statement<br>
slide21. Statement of Owner’s Equity Explains the changes in retained earnings between two balance sheet dates
We start with beginning retained earnings (in our example, the business began in January, so we start with a zero balance) and add any net income (or subtract net loss) from the income statement. Next, we subtract any dividends declared (or any owner withdrawals in a partnership or sole-proprietor) to get the ending balance in retained earnings (or capital for non-corporations)<br>
slide22. Example: Statement of Retained Earnings<br>
slide23. Balance Sheets Provides a snapshot of company’s financial position at a particular moment in time. That specific moment is the close of business on the date of the balance sheet.
Lists a company’s:
Assets
Liabilities
Equity
The Accounting Equation
Assets – Liabilities = Owner’s or Shareholders’ Equity<br>
slide24. Example of Balance Sheet<br>
slide25. Statement of Cash Flow Reports the cash receipts and cash disbursements during an accounting period
Reports effects on cash of a company’s:
Operating activities
Investing activities
Financing activities
Includes both cash and cash equivalents (ex. investments)<br>
slide26. Operating Activities: Cash Inflows Cash inflows from operating activities include:
Cash from sales of goods or services
Interest received from making loans
Dividends received from investments in equity securities
Cash received from the sale of trading securities
Other cash receipts that do not arise from transactions defined as investing or financing activities<br>
slide27. Operating Activities: Cash Outflows Cash outflows for operating activities include payments to:
Acquire inventory
Suppliers and employees for other goods or services
Lenders and other creditors for interest
Purchase trading securities
All other cash payments that do not arise from transactions defined as investing or financing activities<br>
slide28. Investing Activities Cash inflows from investing activities include:
Sale of property, plant, and equipment
Sale of available-for-sale and held-to-maturity securities
Collection of long-term loans made to others
Cash outflows for investing activities include:
Purchase of property, plant, and equipment
Purchase of available-for-sale and held-to-maturity securities
Long-term loans to others<br>
slide29. Financing Activities Cash inflows from financing activities include:
Cash received from issuing capital stock and bonds, mortgages, and notes, and from other short- or long-term borrowing
Cash outflows for financing activities include:
Payments of cash dividends or other distributions to owners (including cash paid to purchase treasury stock) and repayments of amounts borrowed<br>
slide30. The Break-Even Point<br>
slide31. Learning Outcomes: The Break-Even Point 16.3: Calculate the break-even point, where profit will be equal to $0, using information from financial statements
16.3.1: Define the break-even point
16.3.2: Differentiate between fixed and variable costs
16.3.3: Calculate the break-even point
16.3.4: Calculate the contribution margin
16.3.5: Calculate the contribution margin ratio
16.3.6: Calculate the margin of safety<br>
slide32. The Break Even Point Businesses, both large and small, are concerned with determining the point at which their revenues exceed their expenses and they begin to make a profit.
The point at which revenue equals expenses (and profit is therefore $0) is called the break-even point.<br>
slide33. Difference Between Fixed and Variable Costs Fixed costs are expenses that are not dependent on the amount of goods or services produced by the business.
Examples: salaries or rents paid per month
Variable Costs are volume related and are paid per quantity or unit produced.
Examples: gas or tires for a car<br>
slide34. Calculate the Contribution Margin Contribution margin is the portion of revenue that is not consumed by variable cost.
It is important to know the contribution margin in order to calculate what portion of the revenue from a product is consumed by the variable costs and what portion can be used to cover, or contribute to, fixed costs.<br>
slide35. Break-Even in Units Example: Video Productions produces videotapes selling for USD 20 per unit. Fixed costs per period total USD 40,000, while variable costs is USD 12 per unit.
We find the break-even point in units by dividing the total fixed costs by the contribution margin per unit. The contribution margin per unit is USD 8 (USD 20 selling price per unit - USD 12 variable cost per unit).<br>
slide36. Break-Even in Sales Dollars Companies frequently measure volume in terms of sales dollars instead of units.
The formula to compute the break-even point in sales dollars looks a lot like the formula to compute the break-even point in units, except we divide the fixed cost by the contribution margin ratio instead of the contribution margin per unit.
The contribution margin ratio expresses the contribution margin as a percentage of sale:<br>
slide37. Calculate the Contribution Margin Ratio The Contribution Margin Ratio expresses the contribution margin as a percentage of sales. To calculate this ratio, divide the contribution margin per unit by the selling price per unit, or total contribution margin by total revenues.
Example: Video Production’s contribution margin ratio would be USD 8 (contribution margin per unit) divided by USD 20 (the selling price per unit) which would equal .40.<br>
slide38. Margin of Safety If a company’s current sales are more than its break-even point, it has a margin of safety equal to current sales minus break-even sales.
The margin of safety is the amount by which sales can decrease before the company incurs a loss.
Margin of safety = Current Sales - Break-even sales
Example: Margin of safety = USD 120,000 - USD 100,000 when Video Productions has sales of USD 120,000 and its break-even sales are USE 100,000<br>
slide39. Margin of Safety Rate Sometimes people express the margin of safety as a percentage, called the margin of safety rate.
When Video Productions has sales of USD 120,000 and its break-even sales are USE 100,000, the margin of safety rate would be 16.67 percent. This means that Sales volume could drop by 16.67 percent before the company would incur a loss.<br>
slide40. Financial Ratios<br>
slide41. Learning Outcomes: Financial Ratios 16.4: Use financial statements to calculate basic financial ratios to measure the profitability and health of a business
16.4.1: Explain how financial ratios are used
16.4.2: Calculate the current ratio using information from financial statements
16.4.3: Calculate the acid-test (quick) ratio using information from financial statements
16.4.4: Calculate inventory turnover using information form financial statements<br>
slide42. Financial Ratio Analysis Financial ratios allow us to look at profitability, use of assets, inventories, and other assets, liabilities, and costs associated with the finances of the business.
Used to measure a firm’s financial health in four areas:
Liquidity
Long-term solvency
Profitability tests
The market
These ratios can be used to compare the company’s performance across periods (months, quarters, years) or to similar companies within the same industry.<br>
slide43. Financial Ratios Chart<br>
slide44. Calculate the Current Ratio Working capital is the excess of current assets over current liabilities. The ratio that relates current assets to current liabilities is the current (or working capital) ratio. The current ratio indicates the ability of a company to pay its current liabilities from current assets, and thus show the strength of the company’s working capital position.
The current ratio is usually expressed in current assets to one dollar of current liabilities.
Example: 1.25:1 means that the company has $1.25 for every $1 of liabilities<br>
slide45. Calculate the Acid-Test Ratio The acid-test (quick) ratio is the ratio of quick assets (cash, marketable securities, and net receivables) to current liabilities.
Short-term creditors are particularly interested in this ratio which relates to the pool of cash and immediate cash inflows to immediate cash outflows.
In deciding whether the acid-test ratio is satisfactory, investors consider the quality of marketable securities and receivables.<br>
slide46. Calculate Inventory Turnover A company’s inventory turnover ratio shows the number of times its average inventory is sold during a period.
Other things being held equal, a manager who maintains the highest inventory turnover ratio is the most efficient.
Other things are not always equal, for example, a company that achieves a high inventory turnover ratio by keeping extremely small inventories on hand may incur larger ordering costs, lost quantity discounts, and lose sales due to lack of adequate inventory.<br>
slide47. Summary of Liquidity Ratios<br>
slide48. Interpretation and Use of Ratios Standing alone, a single financial ratio may not be informative. Investors gain a greater insight by computing and analyzing several related ratios for a company.
Analysts must be sure their comparisons are valid, especially if those comparisons are from different time periods.
Analysts must consider many items including:
Business conditions
Important events that may have a large impact on a ratio
The seasonal nature of some businesses<br>
slide49. Quick Reference Financial Ratio Calculations<br>
slide50. Practice Question 5 Financial ratios allow a business, potential creditor, or investor to:
A. conduct a manager’s performance review
B. compare the performance of unrelated business
C. determine the health of a company individually and relate to similar businesses or alternative investment options
D. evaluate market conditions<br>
slide51. Practice Question 6 The current ratio is a liquidity ratio that serves as an indicator of a company’s short-term debt-paying ability. Let’s assume your belt company’s month-end balance sheet lists $2,000 in current assets, $5,000 in total assets, $500 in current liabilities and $1,000 in total liabilities. What is your current ratio?
A. 4
B. 5
C. 4:1
D. $5:$1<br>
slide52. Practice Question 7 The acid-test is another liquidity ratio that is of particular interest to those who are considering a business’ request for a short-term loan or credit. Let’s say your $2,000 current asset balance includes $200 in cash, $500 in accounts receivable (net), $300 in a money market account, $700 in supplies and $300 in prepaid insurance. Your current liabilities are $500. What is your current ratio?
A. 2:1
B. 3.4:1
C. 4:1
D. 2<br>
slide53. Practice Question 8 A company’s inventory turnover ratio shows the number of times its average inventory is sold during a period, where a higher inventory turnover is generally considered to be better. Pulling a COGS of $5,000 from the income statement and calculating average inventory of $300 based on January 1 and December 31 balance sheet data, what is the inventory turnover?
A. 6%
B. 6
C. 16.67
D. 17%<br>
slide54. Class Discussion: Accounting and Life Now we’ve learned and practiced some basic accounting principles and calculations: the accounting equation, balance sheet, income statement. owner’s equity, cash flows, break even, contribution margin, margin of safety, and financial ratios.
Discuss as a large group how accounting practices could help you in your personal life even if you are not a CPA.<br>
slide55. Ethical Practices in Accounting<br>
slide56. Learning Outcomes: Ethical Practices in Accounting 16.5: Discuss the importance of ethical practices in accounting and the implications of unethical behavior
16.5.1: Discuss the consequences of unethical practices in the accounting profession
16.5.2: Discuss the impact of the Sarbanes-Oxley Act on accounting practices<br>
slide57. Consequences of Unethical Behavior in Accounting Unethical financial reporting has cost taxpayers billions of dollars, employees their jobs, and the accounting profession its untarnished reputation.
The American Institute of Public Accountants (AIPA) has its own Code of Professional Conduct that prescribes the ethical conduct members should strive to achieve which include the following guidance:
Recognize and consider all relevant facts and circumstances, including applicable rules, laws or regulations,
Consider the ethical issues involved,
Consider established internal procedures, and then
Formulate alternative courses of action.
After weighing the consequences of each course of action, you select the best course of action based on your own judgment.<br>
slide58. Sarbanes-Oxley (SOX) In 2002 the Sarbanes-Oxley Act (SOX) went into effect. This law is one of the most extensive pieces of business legislation passed by Congress.
Attempts to foster ethical behavior in business accounting
Top management must individually certify the accuracy of financial information
Increased severity of penalties for fraudulent financial activity and altering or destroying key audit documents
Increased the oversight role of boards of directors and the independence of outside auditors
Has improved investor confidence and made financial statements more accurate and reliable
Restricts the scope of non-auditing work and auditor may perform for a client<br>
slide59. Quick Review What is accounting? What is its role as a form of business communication?
What are key financial statements and their components, and what is the primary use of each type of statement?
How do you calculate the break-even point, where profit will be equal to $0, using information from financial statements?
How do you use financial statements to calculate basic financial ratios to measure the profitability and health of a business?
Why are ethical practices in accounting important? What are the implications of unethical behavior?<br>