
M&A and Investment Banking Lecture 4.1 – M&A


Description: MA and Investment Banking Lecture 4.1 MA Tactics 1 MA Tactics Art or Science? Hostile Shareholder Activism 2 MA Tactics Hostile MA 3 Hostile MA Hostile MA is really only possible in public MA situations As a bidder in a private
Related Topics
Download Presentation
"M&A and Investment Banking Lecture 4.1 – M&A" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. M&A and Investment Banking Lecture 4.1 – M&A Tactics 1<br>
slide2. M&A Tactics Art or Science?
Hostile
Shareholder Activism 2<br>
slide3. M&A Tactics Hostile M&A 3<br>
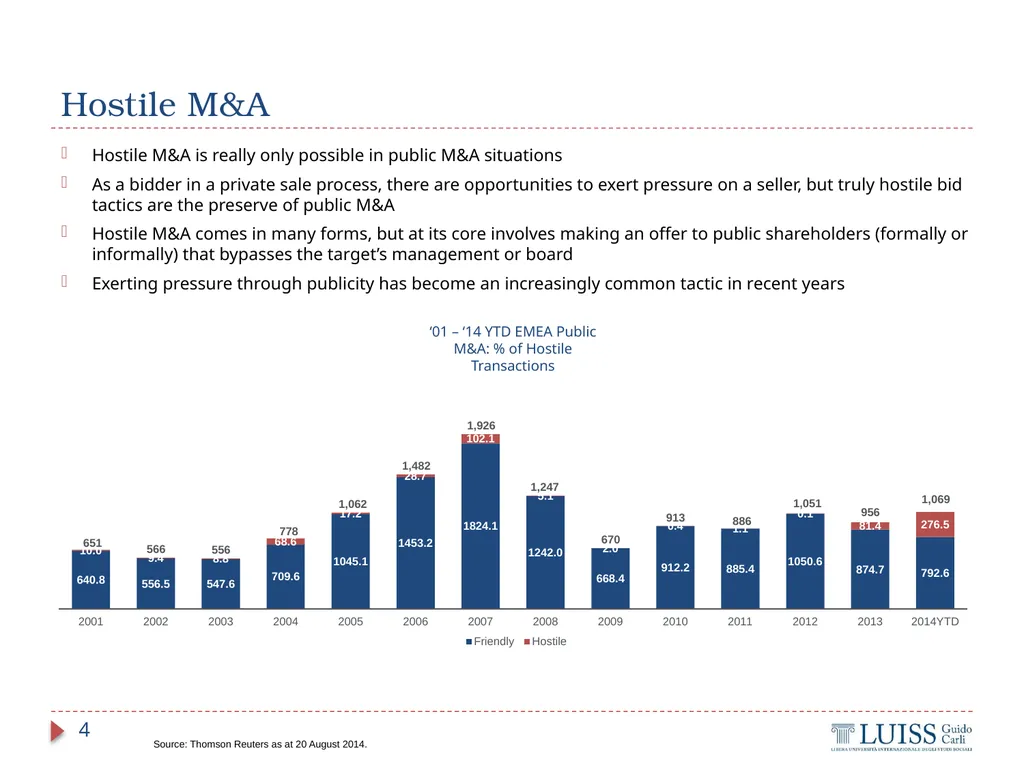
slide4. Hostile M&A Hostile M&A is really only possible in public M&A situations
As a bidder in a private sale process, there are opportunities to exert pressure on a seller, but truly hostile bid tactics are the preserve of public M&A
Hostile M&A comes in many forms, but at its core involves making an offer to public shareholders (formally or informally) that bypasses the target’s management or board
Exerting pressure through publicity has become an increasingly common tactic in recent years 4 Source: Thomson Reuters as at 20 August 2014. ‘01 – ‘14 YTD EMEA Public M&A: % of Hostile Transactions<br>
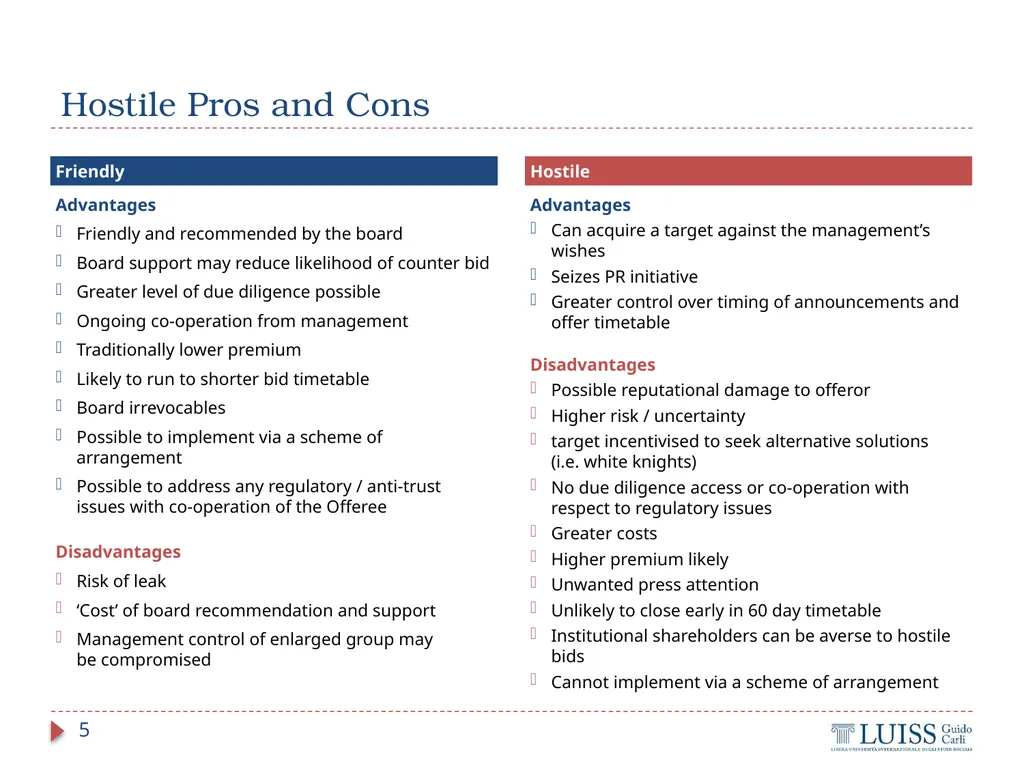
slide5. Hostile Pros and Cons Hostile Advantages
Can acquire a target against the management’s wishes
Seizes PR initiative
Greater control over timing of announcements and offer timetable
Disadvantages
Possible reputational damage to offeror
Higher risk / uncertainty
target incentivised to seek alternative solutions (i.e. white knights)
No due diligence access or co-operation with respect to regulatory issues
Greater costs
Higher premium likely
Unwanted press attention
Unlikely to close early in 60 day timetable
Institutional shareholders can be averse to hostile bids
Cannot implement via a scheme of arrangement Friendly Advantages
Friendly and recommended by the board
Board support may reduce likelihood of counter bid
Greater level of due diligence possible
Ongoing co-operation from management
Traditionally lower premium
Likely to run to shorter bid timetable
Board irrevocables
Possible to implement via a scheme of arrangement
Possible to address any regulatory / anti-trust issues with co-operation of the Offeree
Disadvantages
Risk of leak
‘Cost’ of board recommendation and support
Management control of enlarged group may be compromised 5<br>
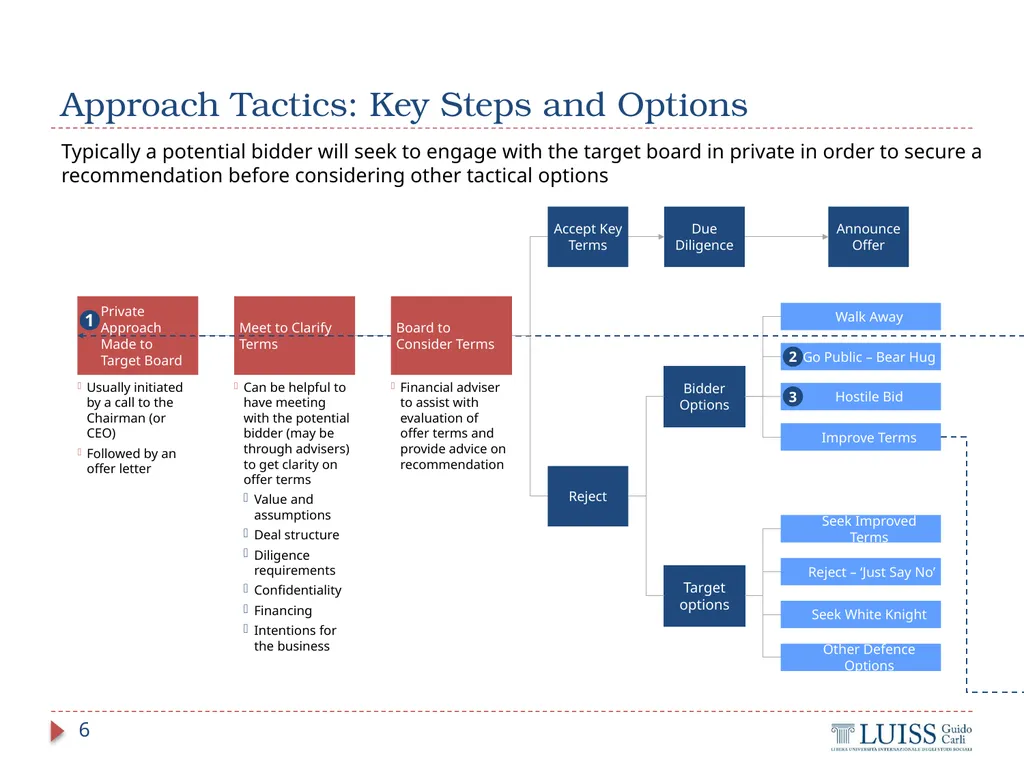
slide6. Usually initiated by a call to the Chairman (or CEO)
Followed by an offer letter Can be helpful to have meeting with the potential bidder (may be through advisers) to get clarity on offer terms
Value and assumptions
Deal structure
Diligence requirements
Confidentiality
Financing
Intentions for the business Financial adviser to assist with evaluation of offer terms and provide advice on recommendation Private Approach Made to Target Board Meet to Clarify Terms Announce Offer Reject Bidder Options Target options Board to Consider Terms Accept Key Terms Due Diligence Walk Away Go Public – Bear Hug Hostile Bid Improve Terms Reject – ‘Just Say No’ Seek White Knight Other Defence Options Seek Improved Terms 1 2 3 Typically a potential bidder will seek to engage with the target board in private in order to secure a recommendation before considering other tactical options Approach Tactics: Key Steps and Options 6<br>
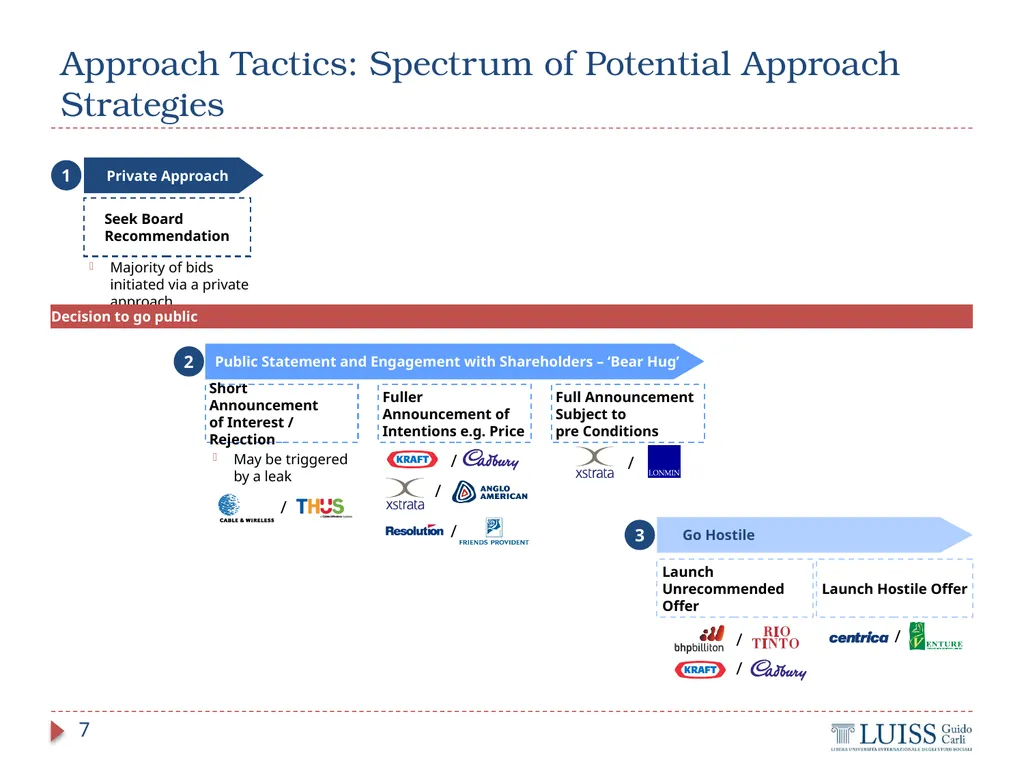
slide7. Private Approach Seek Board Recommendation Public Statement and Engagement with Shareholders – ‘Bear Hug’ Short Announcement
of Interest / Rejection Fuller
Announcement of Intentions e.g. Price Full Announcement Subject to
pre Conditions Majority of bids initiated via a private approach 1 Go Hostile Launch Unrecommended Offer Launch Hostile Offer 3 / / Decision to go public 2 Approach Tactics: Spectrum of Potential Approach Strategies 7 /<br>
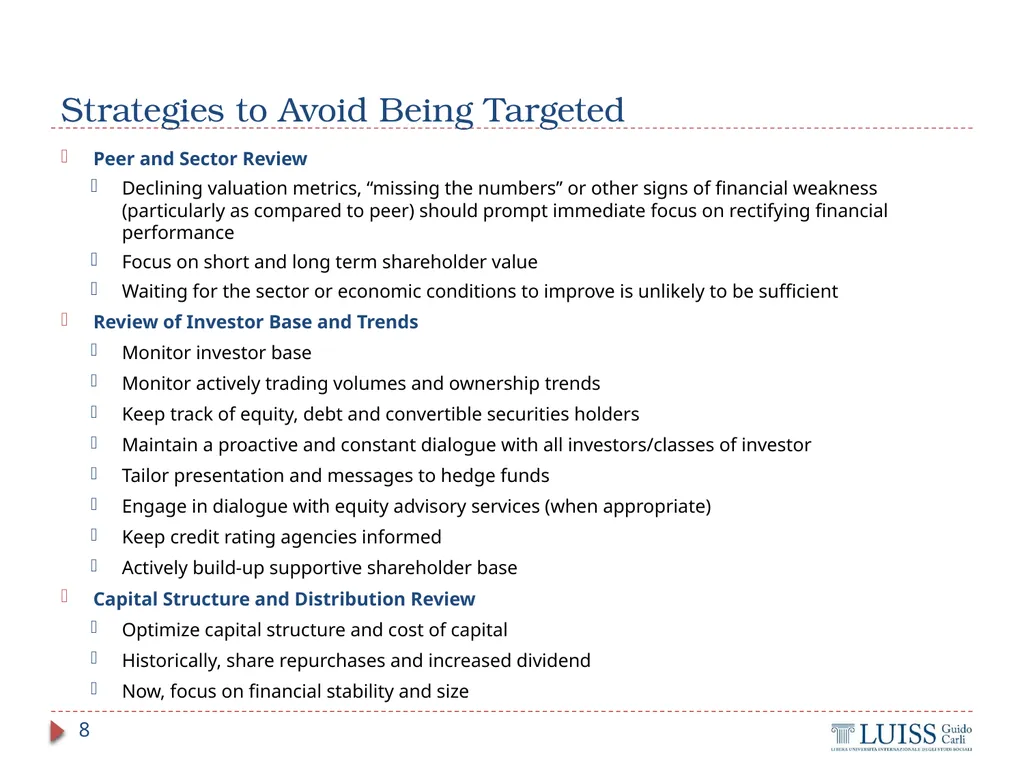
slide8. Strategies to Avoid Being Targeted Peer and Sector Review
Declining valuation metrics, “missing the numbers” or other signs of financial weakness (particularly as compared to peer) should prompt immediate focus on rectifying financial performance
Focus on short and long term shareholder value
Waiting for the sector or economic conditions to improve is unlikely to be sufficient
Review of Investor Base and Trends
Monitor investor base
Monitor actively trading volumes and ownership trends
Keep track of equity, debt and convertible securities holders
Maintain a proactive and constant dialogue with all investors/classes of investor
Tailor presentation and messages to hedge funds
Engage in dialogue with equity advisory services (when appropriate)
Keep credit rating agencies informed
Actively build-up supportive shareholder base
Capital Structure and Distribution Review
Optimize capital structure and cost of capital
Historically, share repurchases and increased dividend
Now, focus on financial stability and size 8<br>
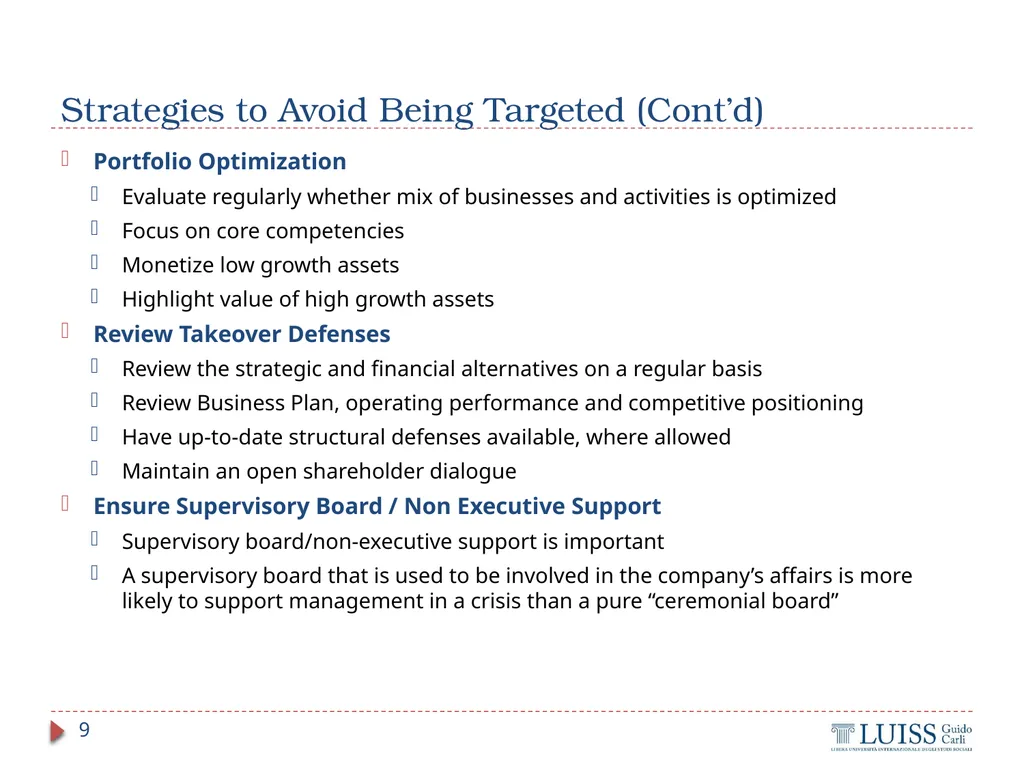
slide9. Strategies to Avoid Being Targeted (Cont’d) Portfolio Optimization
Evaluate regularly whether mix of businesses and activities is optimized
Focus on core competencies
Monetize low growth assets
Highlight value of high growth assets
Review Takeover Defenses
Review the strategic and financial alternatives on a regular basis
Review Business Plan, operating performance and competitive positioning
Have up-to-date structural defenses available, where allowed
Maintain an open shareholder dialogue
Ensure Supervisory Board / Non Executive Support
Supervisory board/non-executive support is important
A supervisory board that is used to be involved in the company’s affairs is more likely to support management in a crisis than a pure “ceremonial board” 9<br>
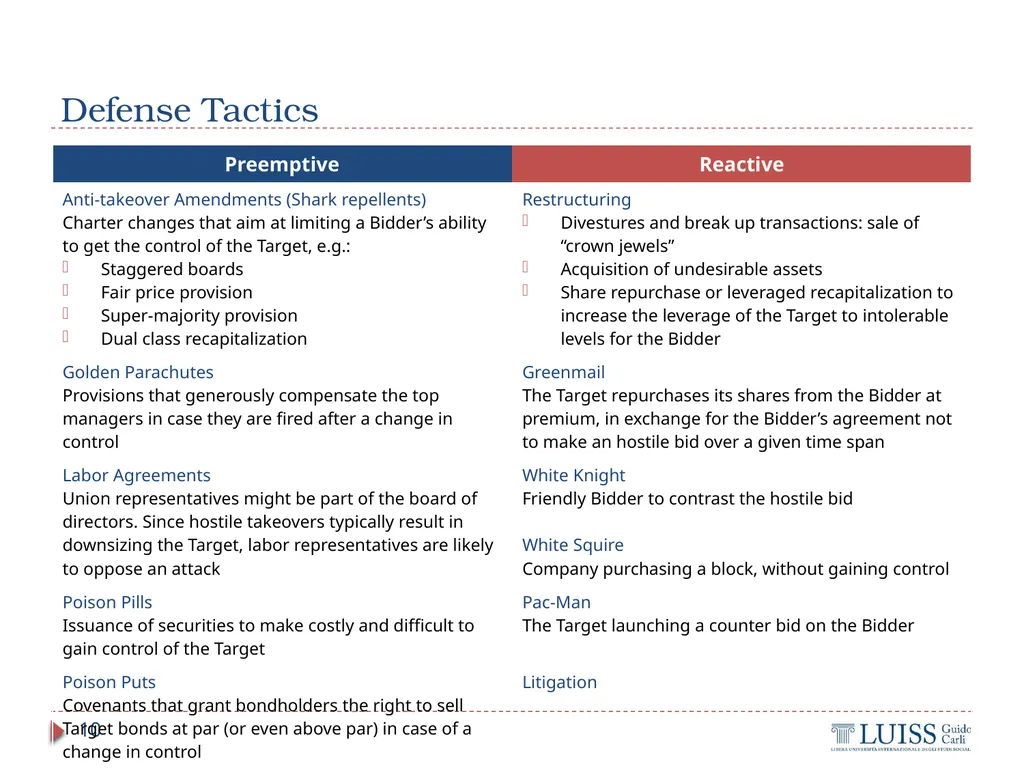
slide10. Defense Tactics 10<br>
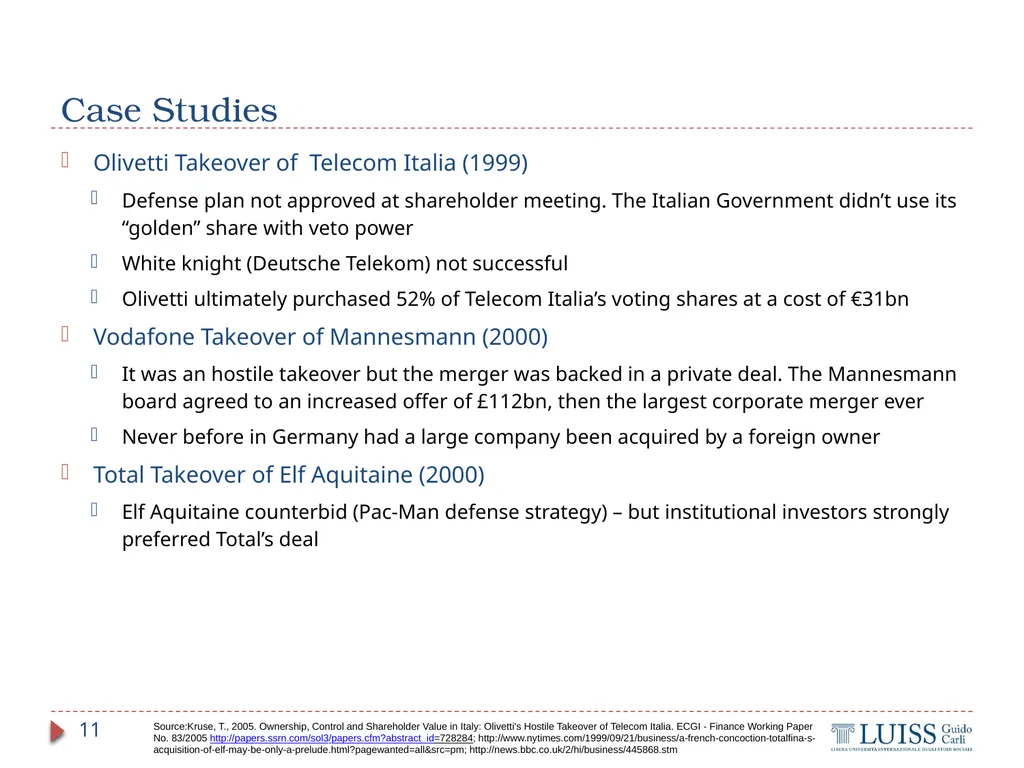
slide11. Case Studies Olivetti Takeover of Telecom Italia (1999)
Defense plan not approved at shareholder meeting. The Italian Government didn’t use its “golden” share with veto power
White knight (Deutsche Telekom) not successful
Olivetti ultimately purchased 52% of Telecom Italia’s voting shares at a cost of €31bn
Vodafone Takeover of Mannesmann (2000)
It was an hostile takeover but the merger was backed in a private deal. The Mannesmann board agreed to an increased offer of £112bn, then the largest corporate merger ever
Never before in Germany had a large company been acquired by a foreign owner
Total Takeover of Elf Aquitaine (2000)
Elf Aquitaine counterbid (Pac-Man defense strategy) – but institutional investors strongly preferred Total’s deal 11 Source:Kruse, T., 2005. Ownership, Control and Shareholder Value in Italy: Olivetti's Hostile Takeover of Telecom Italia. ECGI - Finance Working Paper No. 83/2005 http://papers.ssrn.com/sol3/papers.cfm?abstract_id=728284; http://www.nytimes.com/1999/09/21/business/a-french-concoction-totalfina-s-acquisition-of-elf-may-be-only-a-prelude.html?pagewanted=all&src=pm; http://news.bbc.co.uk/2/hi/business/445868.stm<br>
slide12. M&A Tactics Shareholder Activism 12<br>
slide13. Hostile - Shareholder Activism Shareholder Activism: a way in which shareholders can assert their power as owners of the company to influence its behavior
Source of monitoring of managers and/or blockholders (principal-agent relationship)
Shareholder Activist: a shareholder who attempts to use his or her rights as a shareholder of a publicly-traded corporation to bring about social change 13<br>
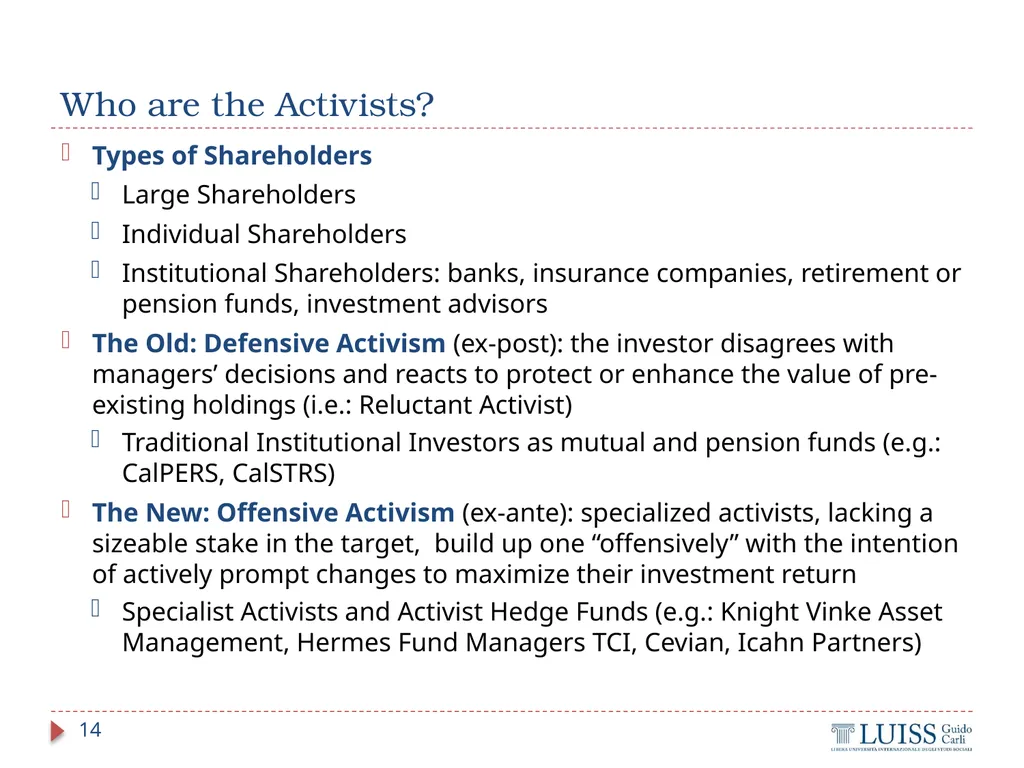
slide14. Who are the Activists? Types of Shareholders
Large Shareholders
Individual Shareholders
Institutional Shareholders: banks, insurance companies, retirement or pension funds, investment advisors
The Old: Defensive Activism (ex-post): the investor disagrees with managers’ decisions and reacts to protect or enhance the value of pre-existing holdings (i.e.: Reluctant Activist)
Traditional Institutional Investors as mutual and pension funds (e.g.: CalPERS, CalSTRS)
The New: Offensive Activism (ex-ante): specialized activists, lacking a sizeable stake in the target, build up one “offensively” with the intention of actively prompt changes to maximize their investment return
Specialist Activists and Activist Hedge Funds (e.g.: Knight Vinke Asset Management, Hermes Fund Managers TCI, Cevian, Icahn Partners) 14<br>
slide15. Can activism deliver over the long-term? Total Return S&P Index vs. Selected 2005 Activism Portfolio Does This Graph Imply that Activism Will be Less Successful When There is Less Liquidity? Credit Crunch Begins Lehman/AIG 116.6 102.1 15 Source: Institutional Shareholder Services (ISS) data as of 22 June 2010; includes 41 activist situations tracked by ISS in 2005<br>
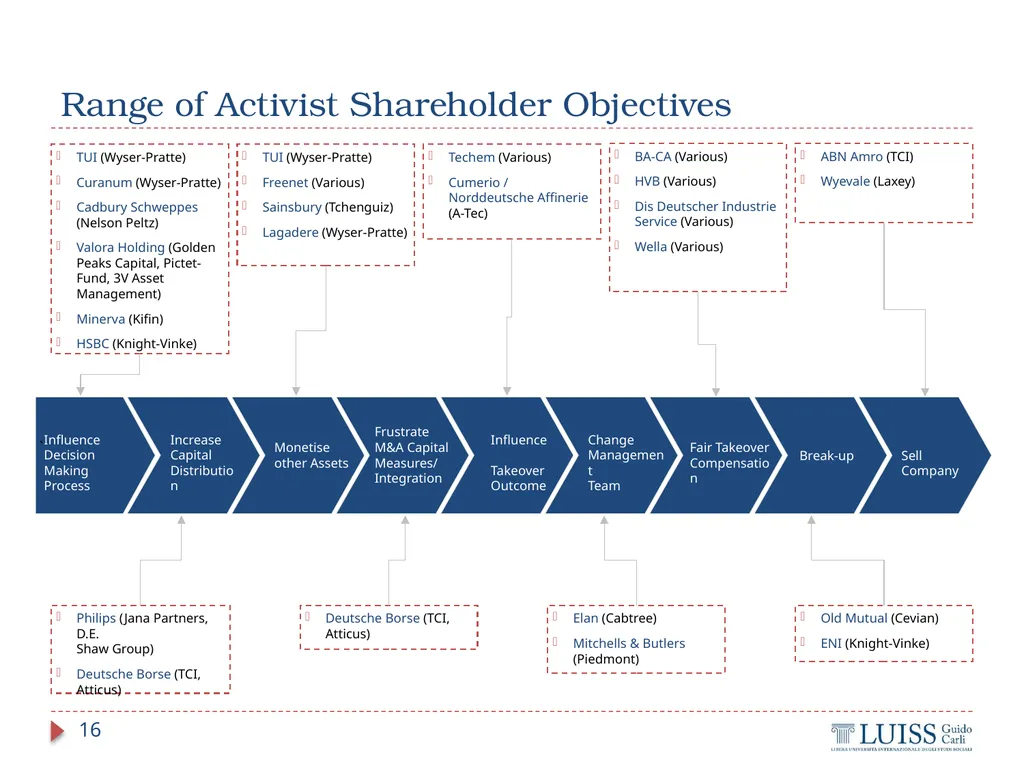
slide16. ` Range of Activist Shareholder Objectives TUI (Wyser-Pratte)
Curanum (Wyser-Pratte)
Cadbury Schweppes (Nelson Peltz)
Valora Holding (Golden Peaks Capital, Pictet-Fund, 3V Asset Management)
Minerva (Kifin)
HSBC (Knight-Vinke) TUI (Wyser-Pratte)
Freenet (Various)
Sainsbury (Tchenguiz)
Lagadere (Wyser-Pratte) Techem (Various)
Cumerio / Norddeutsche Affinerie (A-Tec) ABN Amro (TCI)
Wyevale (Laxey) Philips (Jana Partners, D.E. Shaw Group)
Deutsche Borse (TCI, Atticus) Deutsche Borse (TCI, Atticus) BA-CA (Various)
HVB (Various)
Dis Deutscher Industrie Service (Various)
Wella (Various) Monetise other Assets Frustrate M&A Capital Measures/ Integration Influence Takeover Outcome Fair Takeover Compensation Sell Company Change Management Team Break-up Old Mutual (Cevian)
ENI (Knight-Vinke) Elan (Cabtree)
Mitchells & Butlers (Piedmont) 16 Increase Capital Distribution Influence Decision Making Process<br>
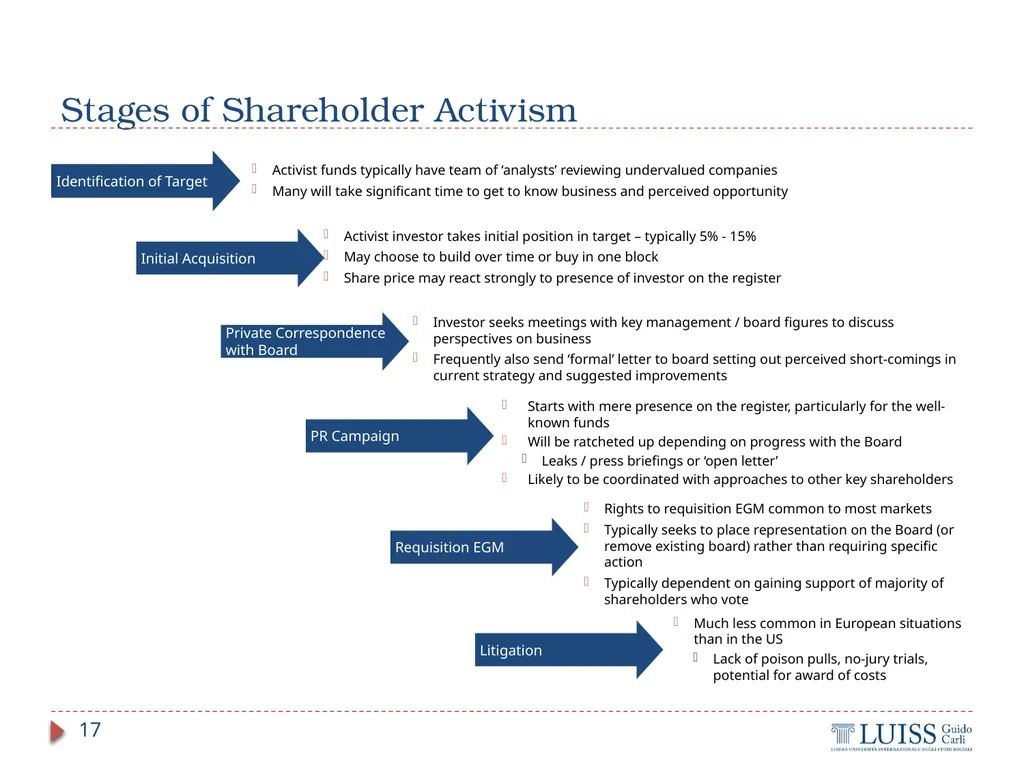
slide17. Stages of Shareholder Activism Private Correspondence with Board Activist funds typically have team of ‘analysts’ reviewing undervalued companies
Many will take significant time to get to know business and perceived opportunity Initial Acquisition PR Campaign Requisition EGM Litigation Identification of Target Activist investor takes initial position in target – typically 5% - 15%
May choose to build over time or buy in one block
Share price may react strongly to presence of investor on the register Investor seeks meetings with key management / board figures to discuss perspectives on business
Frequently also send ‘formal’ letter to board setting out perceived short-comings in current strategy and suggested improvements Starts with mere presence on the register, particularly for the well-known funds
Will be ratcheted up depending on progress with the Board
Leaks / press briefings or ‘open letter’
Likely to be coordinated with approaches to other key shareholders Rights to requisition EGM common to most markets
Typically seeks to place representation on the Board (or remove existing board) rather than requiring specific action
Typically dependent on gaining support of majority of shareholders who vote Much less common in European situations than in the US
Lack of poison pulls, no-jury trials, potential for award of costs 17<br>
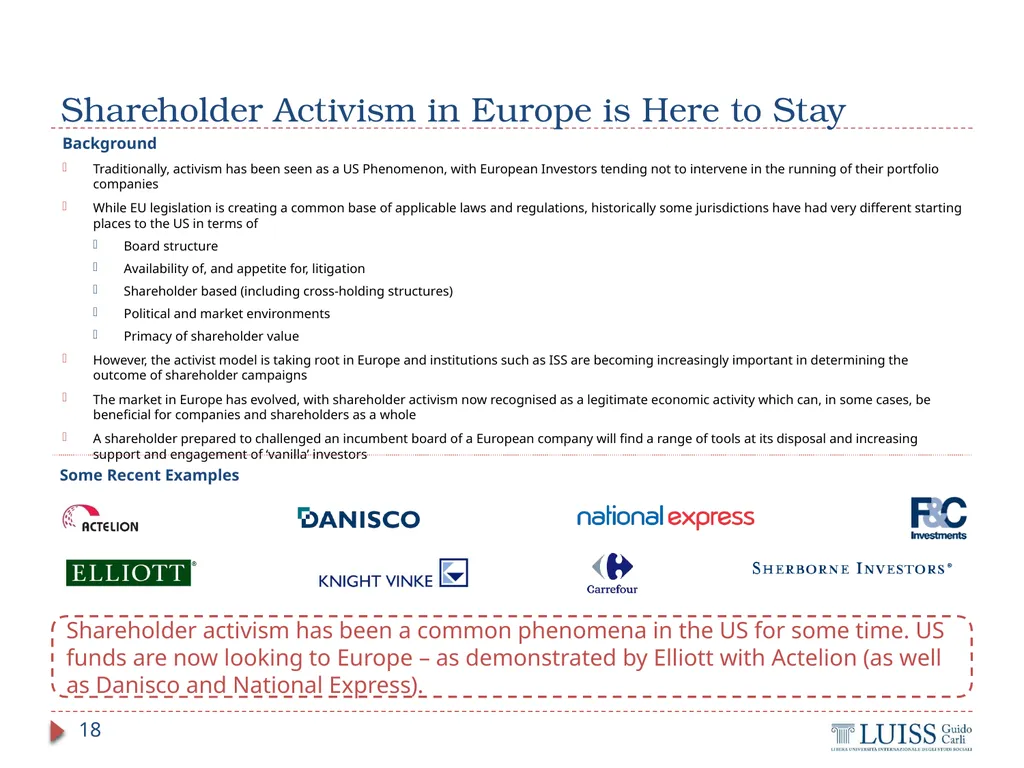
slide18. Shareholder Activism in Europe is Here to Stay 18 Background
Traditionally, activism has been seen as a US Phenomenon, with European Investors tending not to intervene in the running of their portfolio companies
While EU legislation is creating a common base of applicable laws and regulations, historically some jurisdictions have had very different starting places to the US in terms of
Board structure
Availability of, and appetite for, litigation
Shareholder based (including cross-holding structures)
Political and market environments
Primacy of shareholder value
However, the activist model is taking root in Europe and institutions such as ISS are becoming increasingly important in determining the outcome of shareholder campaigns
The market in Europe has evolved, with shareholder activism now recognised as a legitimate economic activity which can, in some cases, be beneficial for companies and shareholders as a whole
A shareholder prepared to challenged an incumbent board of a European company will find a range of tools at its disposal and increasing support and engagement of ‘vanilla’ investors Some Recent Examples Shareholder activism has been a common phenomena in the US for some time. US funds are now looking to Europe – as demonstrated by Elliott with Actelion (as well as Danisco and National Express).<br>
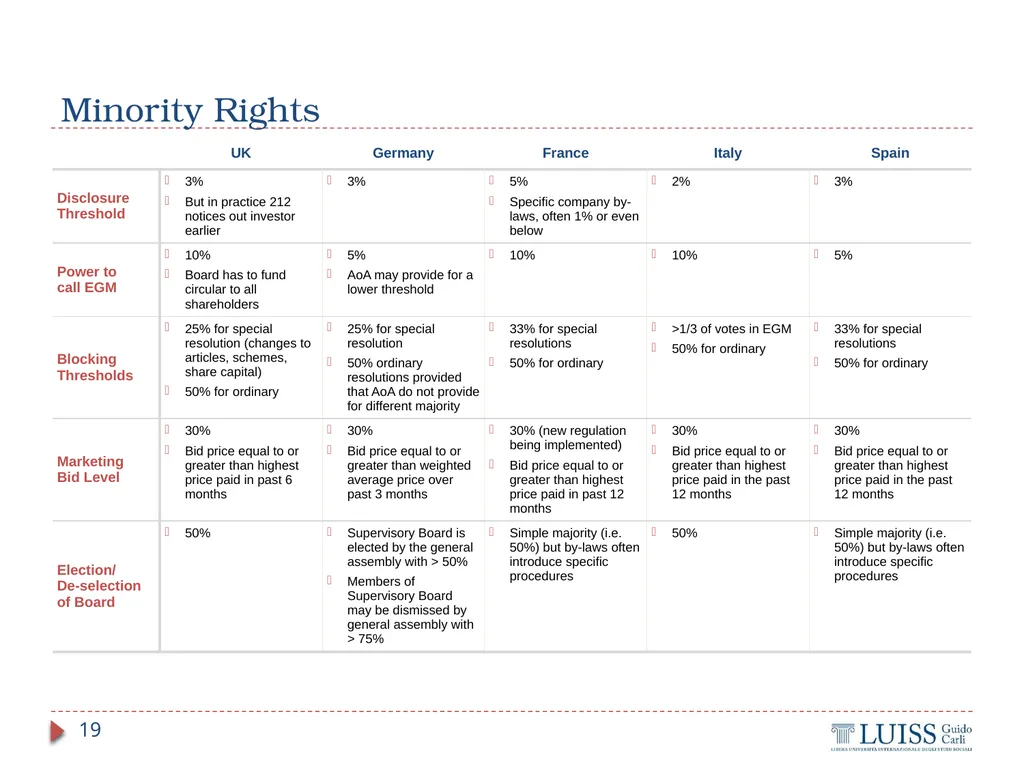
slide19. Minority Rights 19<br>
slide20. M&A and Investment Banking Lesson 4.2 – Contract Negotiation 20<br>
slide21. Contract Negotiation Sales and Purchase Agreement
Due Diligence Process 21<br>
slide22. Contract Negotiation Sales and Purchase Agreement 22<br>
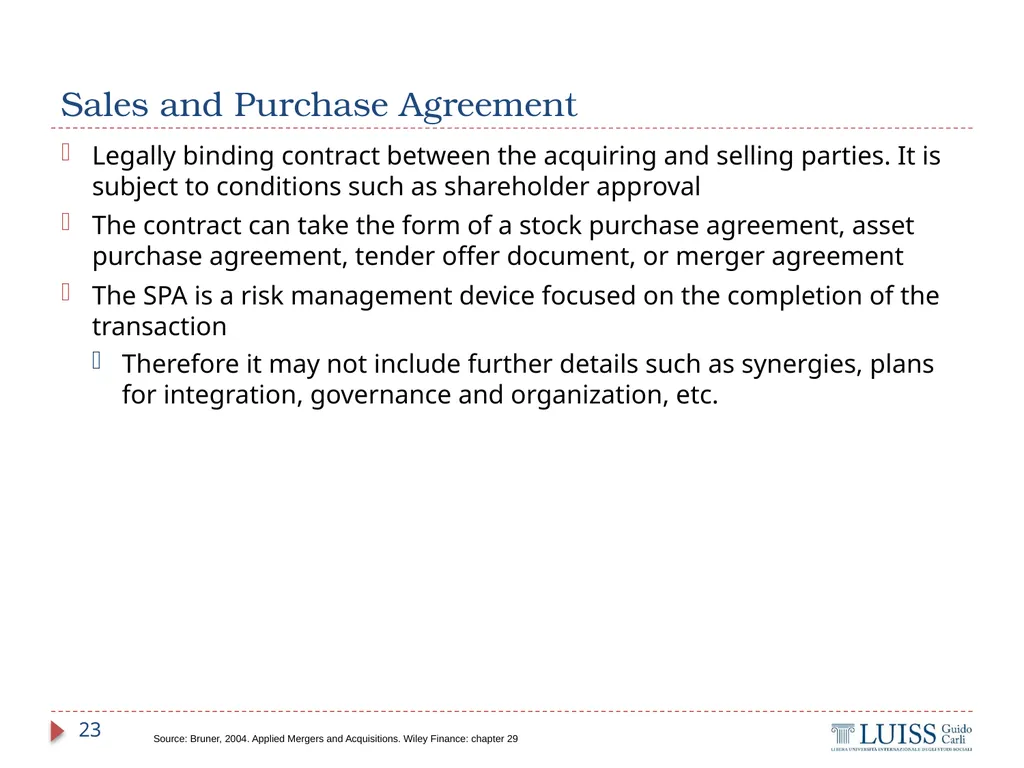
slide23. Sales and Purchase Agreement Legally binding contract between the acquiring and selling parties. It is subject to conditions such as shareholder approval
The contract can take the form of a stock purchase agreement, asset purchase agreement, tender offer document, or merger agreement
The SPA is a risk management device focused on the completion of the transaction
Therefore it may not include further details such as synergies, plans for integration, governance and organization, etc. 23 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
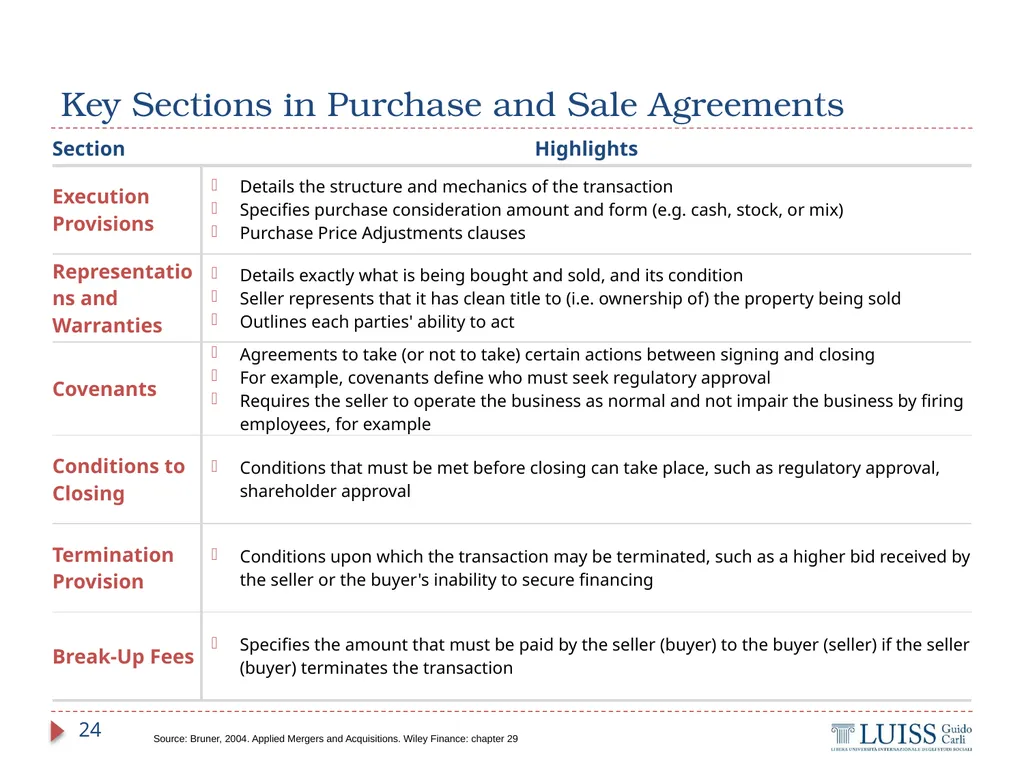
slide24. Key Sections in Purchase and Sale Agreements 24 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
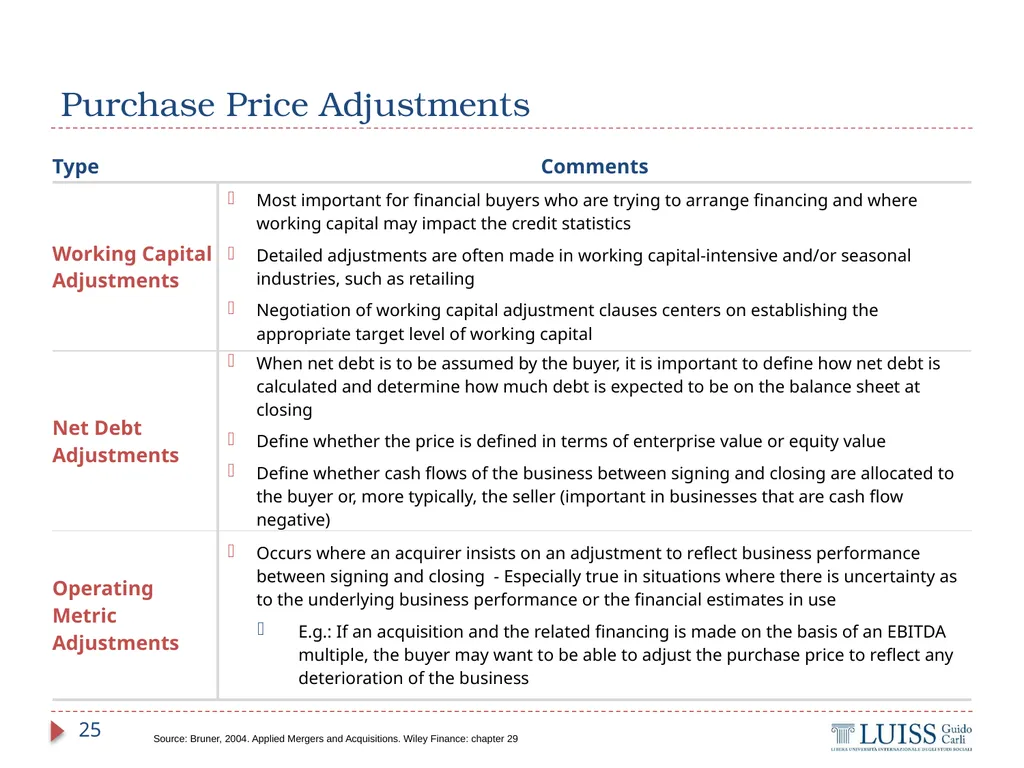
slide25. Purchase Price Adjustments 25 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
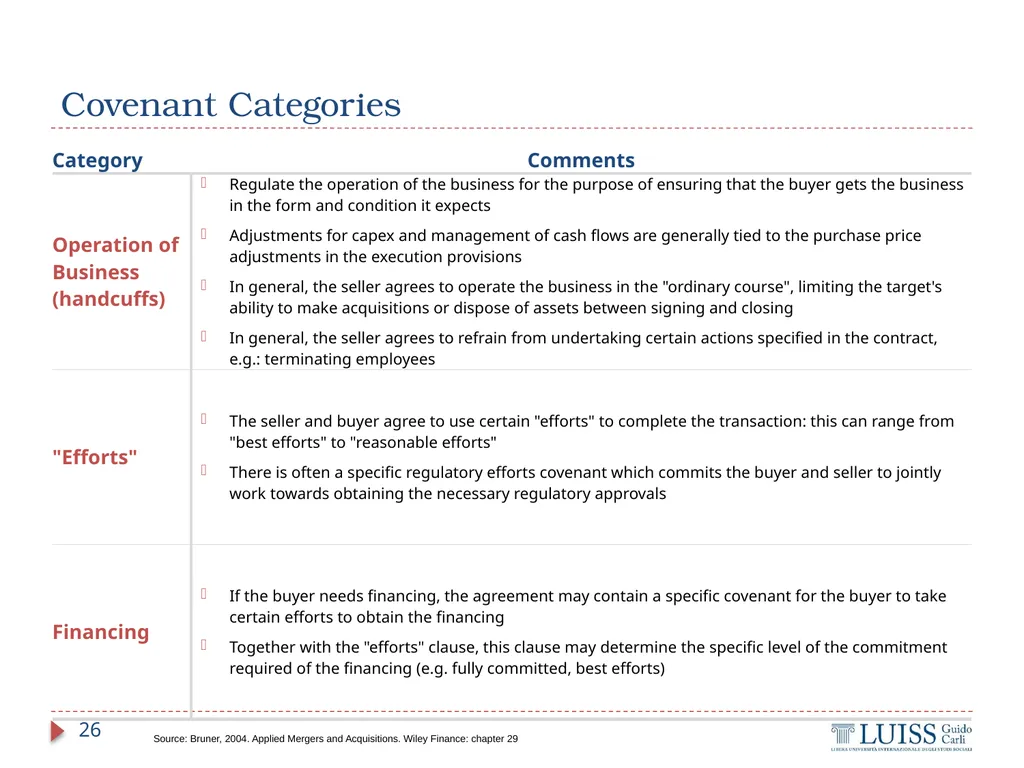
slide26. Covenant Categories 26 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
slide27. Contract Negotiation Due Diligence Process 27<br>
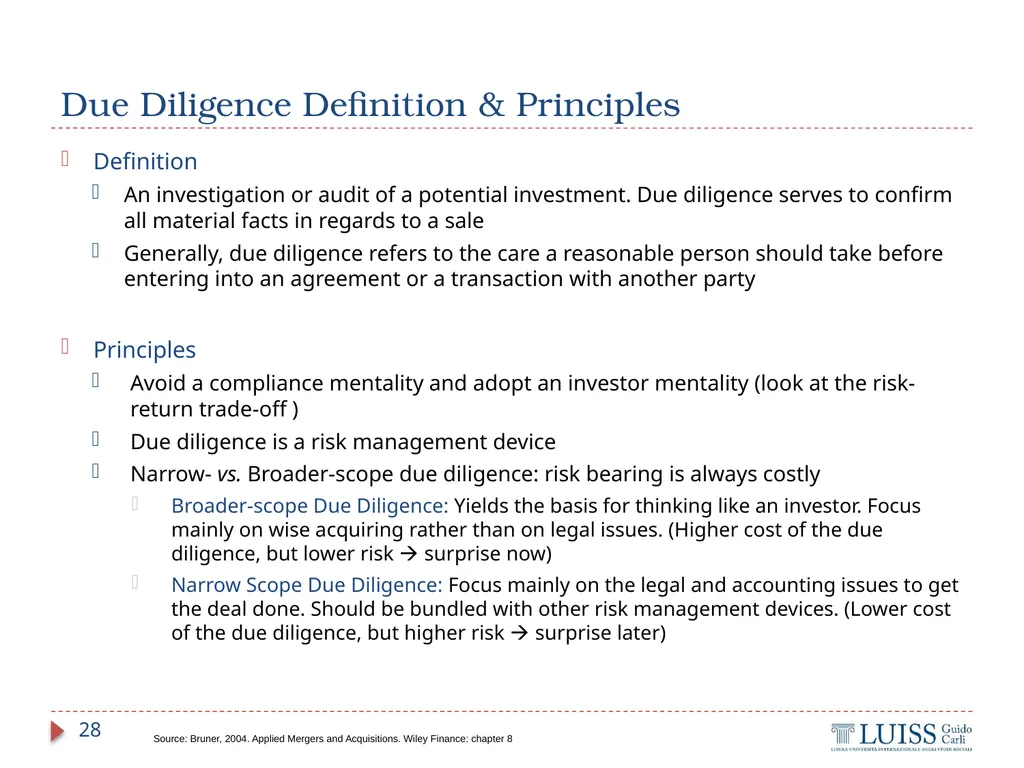
slide28. Due Diligence Definition & Principles Definition
An investigation or audit of a potential investment. Due diligence serves to confirm all material facts in regards to a sale
Generally, due diligence refers to the care a reasonable person should take before entering into an agreement or a transaction with another party
Principles
Avoid a compliance mentality and adopt an investor mentality (look at the risk-return trade-off )
Due diligence is a risk management device
Narrow- vs. Broader-scope due diligence: risk bearing is always costly
Broader-scope Due Diligence: Yields the basis for thinking like an investor. Focus mainly on wise acquiring rather than on legal issues. (Higher cost of the due diligence, but lower risk surprise now)
Narrow Scope Due Diligence: Focus mainly on the legal and accounting issues to get the deal done. Should be bundled with other risk management devices. (Lower cost of the due diligence, but higher risk surprise later) 28 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
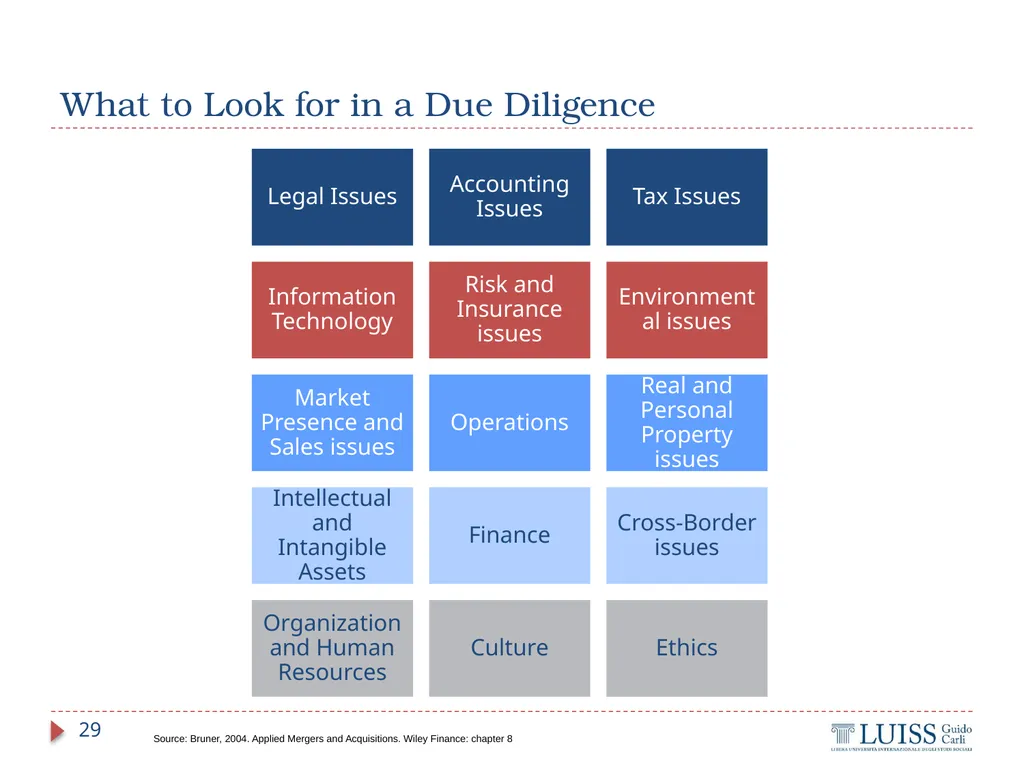
slide29. What to Look for in a Due Diligence Legal Issues Accounting Issues Tax Issues Information Technology Risk and Insurance issues Environmental issues Market Presence and Sales issues Operations Real and Personal Property issues Intellectual and Intangible Assets Finance Cross-Border issues Organization and Human Resources Culture Ethics 29 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
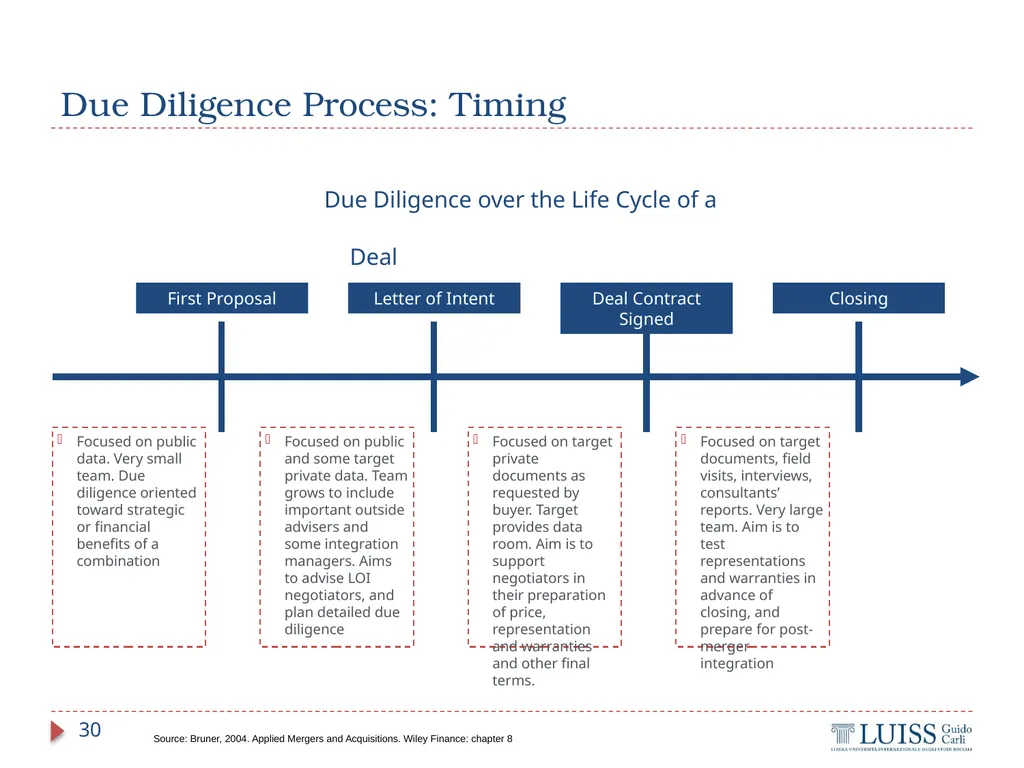
slide30. Due Diligence Process: Timing Due Diligence over the Life Cycle of a Deal 30 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8 Focused on public data. Very small team. Due diligence oriented toward strategic or financial benefits of a combination Focused on public and some target private data. Team grows to include important outside advisers and some integration managers. Aims to advise LOI negotiators, and plan detailed due diligence Focused on target private documents as requested by buyer. Target provides data room. Aim is to support negotiators in their preparation of price, representation and warranties and other final terms. Focused on target documents, field visits, interviews, consultants’ reports. Very large team. Aim is to test representations and warranties in advance of closing, and prepare for post-merger integration First Proposal Letter of Intent Deal Contract Signed Closing<br>
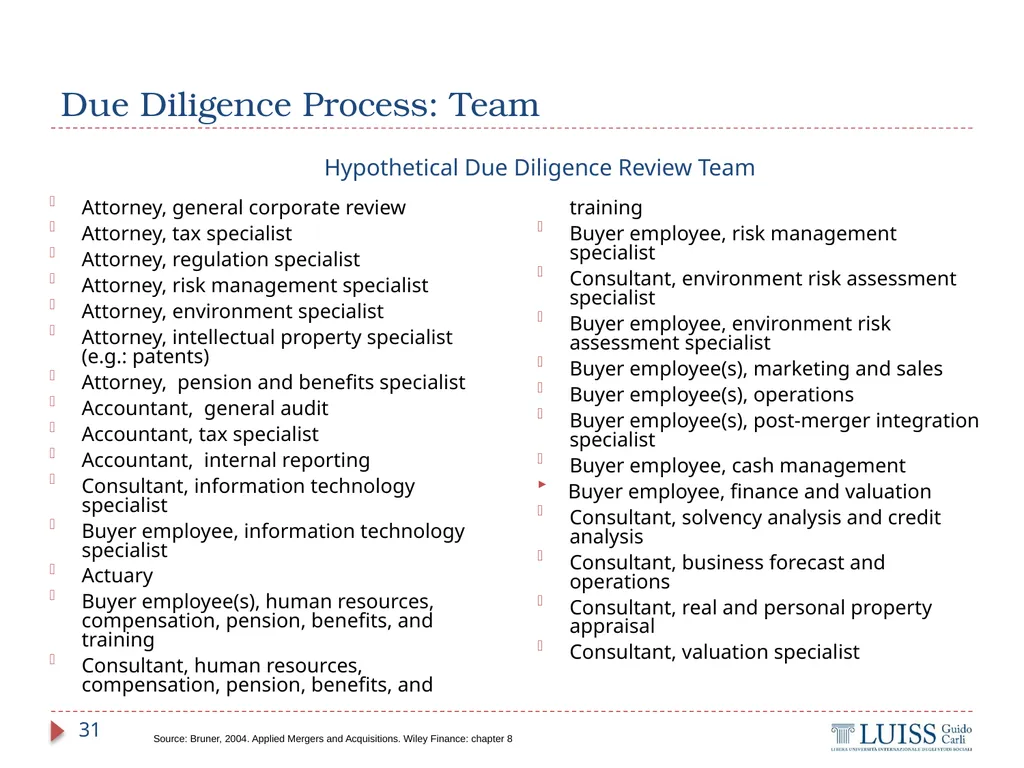
slide31. Due Diligence Process: Team Attorney, general corporate review
Attorney, tax specialist
Attorney, regulation specialist
Attorney, risk management specialist
Attorney, environment specialist
Attorney, intellectual property specialist (e.g.: patents)
Attorney, pension and benefits specialist
Accountant, general audit
Accountant, tax specialist
Accountant, internal reporting
Consultant, information technology specialist
Buyer employee, information technology specialist
Actuary
Buyer employee(s), human resources, compensation, pension, benefits, and training
Consultant, human resources, compensation, pension, benefits, and training
Buyer employee, risk management specialist
Consultant, environment risk assessment specialist
Buyer employee, environment risk assessment specialist
Buyer employee(s), marketing and sales
Buyer employee(s), operations
Buyer employee(s), post-merger integration specialist
Buyer employee, cash management
Buyer employee, finance and valuation
Consultant, solvency analysis and credit analysis
Consultant, business forecast and operations
Consultant, real and personal property appraisal
Consultant, valuation specialist Hypothetical Due Diligence Review Team 31 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
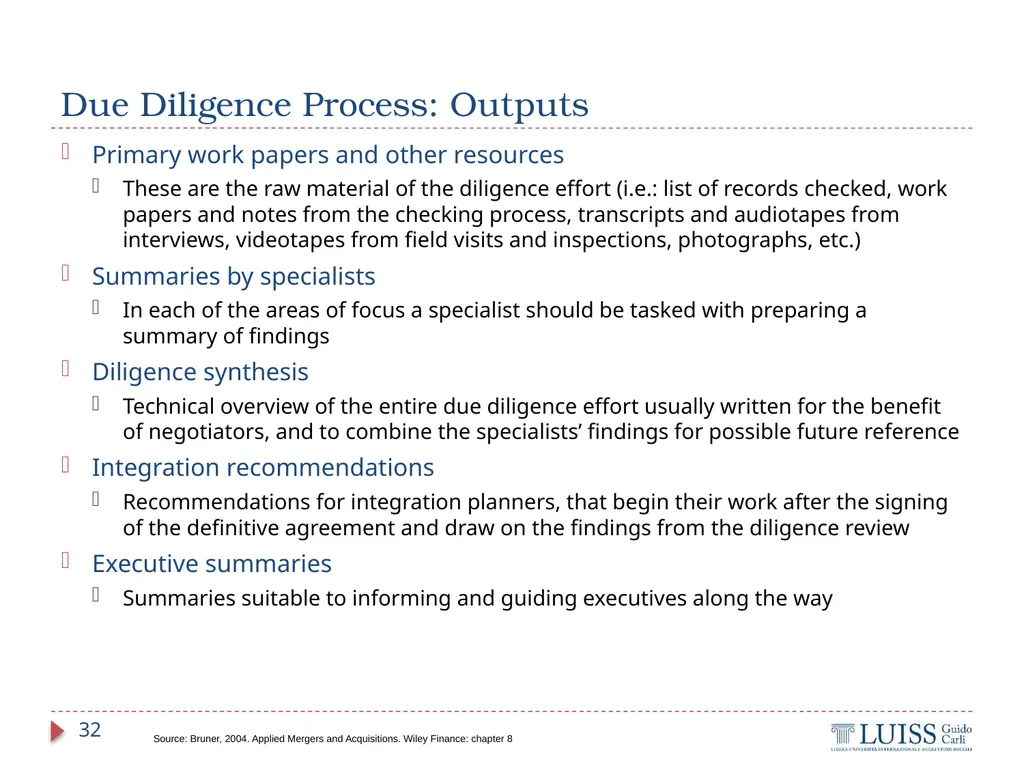
slide32. Due Diligence Process: Outputs Primary work papers and other resources
These are the raw material of the diligence effort (i.e.: list of records checked, work papers and notes from the checking process, transcripts and audiotapes from interviews, videotapes from field visits and inspections, photographs, etc.)
Summaries by specialists
In each of the areas of focus a specialist should be tasked with preparing a summary of findings
Diligence synthesis
Technical overview of the entire due diligence effort usually written for the benefit of negotiators, and to combine the specialists’ findings for possible future reference
Integration recommendations
Recommendations for integration planners, that begin their work after the signing of the definitive agreement and draw on the findings from the diligence review
Executive summaries
Summaries suitable to informing and guiding executives along the way 32 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
slide33. References Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapters 8, 29, 30, 32-34
Fleuriet, 2008. Investment banking explained, McGraw-Hill: chapter 14
Iannotta, G., 2010. Investment Banking, Springer-Verlag Berlin Heidelberg: chapter 9
Kruse, T., 2005. Ownership, Control and Shareholder Value in Italy: Olivetti's Hostile Takeover of Telecom Italia. ECGI - Finance Working Paper No. 83/2005
Miller, E.L.J., 2008. Mergers and Acquisitions: A Step-by-Step Legal and Practical Guide. Wiley: chapter 2 33<br>
slide2. M&A Tactics Art or Science?
Hostile
Shareholder Activism 2<br>
slide3. M&A Tactics Hostile M&A 3<br>
slide4. Hostile M&A Hostile M&A is really only possible in public M&A situations
As a bidder in a private sale process, there are opportunities to exert pressure on a seller, but truly hostile bid tactics are the preserve of public M&A
Hostile M&A comes in many forms, but at its core involves making an offer to public shareholders (formally or informally) that bypasses the target’s management or board
Exerting pressure through publicity has become an increasingly common tactic in recent years 4 Source: Thomson Reuters as at 20 August 2014. ‘01 – ‘14 YTD EMEA Public M&A: % of Hostile Transactions<br>
slide5. Hostile Pros and Cons Hostile Advantages
Can acquire a target against the management’s wishes
Seizes PR initiative
Greater control over timing of announcements and offer timetable
Disadvantages
Possible reputational damage to offeror
Higher risk / uncertainty
target incentivised to seek alternative solutions (i.e. white knights)
No due diligence access or co-operation with respect to regulatory issues
Greater costs
Higher premium likely
Unwanted press attention
Unlikely to close early in 60 day timetable
Institutional shareholders can be averse to hostile bids
Cannot implement via a scheme of arrangement Friendly Advantages
Friendly and recommended by the board
Board support may reduce likelihood of counter bid
Greater level of due diligence possible
Ongoing co-operation from management
Traditionally lower premium
Likely to run to shorter bid timetable
Board irrevocables
Possible to implement via a scheme of arrangement
Possible to address any regulatory / anti-trust issues with co-operation of the Offeree
Disadvantages
Risk of leak
‘Cost’ of board recommendation and support
Management control of enlarged group may be compromised 5<br>
slide6. Usually initiated by a call to the Chairman (or CEO)
Followed by an offer letter Can be helpful to have meeting with the potential bidder (may be through advisers) to get clarity on offer terms
Value and assumptions
Deal structure
Diligence requirements
Confidentiality
Financing
Intentions for the business Financial adviser to assist with evaluation of offer terms and provide advice on recommendation Private Approach Made to Target Board Meet to Clarify Terms Announce Offer Reject Bidder Options Target options Board to Consider Terms Accept Key Terms Due Diligence Walk Away Go Public – Bear Hug Hostile Bid Improve Terms Reject – ‘Just Say No’ Seek White Knight Other Defence Options Seek Improved Terms 1 2 3 Typically a potential bidder will seek to engage with the target board in private in order to secure a recommendation before considering other tactical options Approach Tactics: Key Steps and Options 6<br>
slide7. Private Approach Seek Board Recommendation Public Statement and Engagement with Shareholders – ‘Bear Hug’ Short Announcement
of Interest / Rejection Fuller
Announcement of Intentions e.g. Price Full Announcement Subject to
pre Conditions Majority of bids initiated via a private approach 1 Go Hostile Launch Unrecommended Offer Launch Hostile Offer 3 / / Decision to go public 2 Approach Tactics: Spectrum of Potential Approach Strategies 7 /<br>
slide8. Strategies to Avoid Being Targeted Peer and Sector Review
Declining valuation metrics, “missing the numbers” or other signs of financial weakness (particularly as compared to peer) should prompt immediate focus on rectifying financial performance
Focus on short and long term shareholder value
Waiting for the sector or economic conditions to improve is unlikely to be sufficient
Review of Investor Base and Trends
Monitor investor base
Monitor actively trading volumes and ownership trends
Keep track of equity, debt and convertible securities holders
Maintain a proactive and constant dialogue with all investors/classes of investor
Tailor presentation and messages to hedge funds
Engage in dialogue with equity advisory services (when appropriate)
Keep credit rating agencies informed
Actively build-up supportive shareholder base
Capital Structure and Distribution Review
Optimize capital structure and cost of capital
Historically, share repurchases and increased dividend
Now, focus on financial stability and size 8<br>
slide9. Strategies to Avoid Being Targeted (Cont’d) Portfolio Optimization
Evaluate regularly whether mix of businesses and activities is optimized
Focus on core competencies
Monetize low growth assets
Highlight value of high growth assets
Review Takeover Defenses
Review the strategic and financial alternatives on a regular basis
Review Business Plan, operating performance and competitive positioning
Have up-to-date structural defenses available, where allowed
Maintain an open shareholder dialogue
Ensure Supervisory Board / Non Executive Support
Supervisory board/non-executive support is important
A supervisory board that is used to be involved in the company’s affairs is more likely to support management in a crisis than a pure “ceremonial board” 9<br>
slide10. Defense Tactics 10<br>
slide11. Case Studies Olivetti Takeover of Telecom Italia (1999)
Defense plan not approved at shareholder meeting. The Italian Government didn’t use its “golden” share with veto power
White knight (Deutsche Telekom) not successful
Olivetti ultimately purchased 52% of Telecom Italia’s voting shares at a cost of €31bn
Vodafone Takeover of Mannesmann (2000)
It was an hostile takeover but the merger was backed in a private deal. The Mannesmann board agreed to an increased offer of £112bn, then the largest corporate merger ever
Never before in Germany had a large company been acquired by a foreign owner
Total Takeover of Elf Aquitaine (2000)
Elf Aquitaine counterbid (Pac-Man defense strategy) – but institutional investors strongly preferred Total’s deal 11 Source:Kruse, T., 2005. Ownership, Control and Shareholder Value in Italy: Olivetti's Hostile Takeover of Telecom Italia. ECGI - Finance Working Paper No. 83/2005 http://papers.ssrn.com/sol3/papers.cfm?abstract_id=728284; http://www.nytimes.com/1999/09/21/business/a-french-concoction-totalfina-s-acquisition-of-elf-may-be-only-a-prelude.html?pagewanted=all&src=pm; http://news.bbc.co.uk/2/hi/business/445868.stm<br>
slide12. M&A Tactics Shareholder Activism 12<br>
slide13. Hostile - Shareholder Activism Shareholder Activism: a way in which shareholders can assert their power as owners of the company to influence its behavior
Source of monitoring of managers and/or blockholders (principal-agent relationship)
Shareholder Activist: a shareholder who attempts to use his or her rights as a shareholder of a publicly-traded corporation to bring about social change 13<br>
slide14. Who are the Activists? Types of Shareholders
Large Shareholders
Individual Shareholders
Institutional Shareholders: banks, insurance companies, retirement or pension funds, investment advisors
The Old: Defensive Activism (ex-post): the investor disagrees with managers’ decisions and reacts to protect or enhance the value of pre-existing holdings (i.e.: Reluctant Activist)
Traditional Institutional Investors as mutual and pension funds (e.g.: CalPERS, CalSTRS)
The New: Offensive Activism (ex-ante): specialized activists, lacking a sizeable stake in the target, build up one “offensively” with the intention of actively prompt changes to maximize their investment return
Specialist Activists and Activist Hedge Funds (e.g.: Knight Vinke Asset Management, Hermes Fund Managers TCI, Cevian, Icahn Partners) 14<br>
slide15. Can activism deliver over the long-term? Total Return S&P Index vs. Selected 2005 Activism Portfolio Does This Graph Imply that Activism Will be Less Successful When There is Less Liquidity? Credit Crunch Begins Lehman/AIG 116.6 102.1 15 Source: Institutional Shareholder Services (ISS) data as of 22 June 2010; includes 41 activist situations tracked by ISS in 2005<br>
slide16. ` Range of Activist Shareholder Objectives TUI (Wyser-Pratte)
Curanum (Wyser-Pratte)
Cadbury Schweppes (Nelson Peltz)
Valora Holding (Golden Peaks Capital, Pictet-Fund, 3V Asset Management)
Minerva (Kifin)
HSBC (Knight-Vinke) TUI (Wyser-Pratte)
Freenet (Various)
Sainsbury (Tchenguiz)
Lagadere (Wyser-Pratte) Techem (Various)
Cumerio / Norddeutsche Affinerie (A-Tec) ABN Amro (TCI)
Wyevale (Laxey) Philips (Jana Partners, D.E. Shaw Group)
Deutsche Borse (TCI, Atticus) Deutsche Borse (TCI, Atticus) BA-CA (Various)
HVB (Various)
Dis Deutscher Industrie Service (Various)
Wella (Various) Monetise other Assets Frustrate M&A Capital Measures/ Integration Influence Takeover Outcome Fair Takeover Compensation Sell Company Change Management Team Break-up Old Mutual (Cevian)
ENI (Knight-Vinke) Elan (Cabtree)
Mitchells & Butlers (Piedmont) 16 Increase Capital Distribution Influence Decision Making Process<br>
slide17. Stages of Shareholder Activism Private Correspondence with Board Activist funds typically have team of ‘analysts’ reviewing undervalued companies
Many will take significant time to get to know business and perceived opportunity Initial Acquisition PR Campaign Requisition EGM Litigation Identification of Target Activist investor takes initial position in target – typically 5% - 15%
May choose to build over time or buy in one block
Share price may react strongly to presence of investor on the register Investor seeks meetings with key management / board figures to discuss perspectives on business
Frequently also send ‘formal’ letter to board setting out perceived short-comings in current strategy and suggested improvements Starts with mere presence on the register, particularly for the well-known funds
Will be ratcheted up depending on progress with the Board
Leaks / press briefings or ‘open letter’
Likely to be coordinated with approaches to other key shareholders Rights to requisition EGM common to most markets
Typically seeks to place representation on the Board (or remove existing board) rather than requiring specific action
Typically dependent on gaining support of majority of shareholders who vote Much less common in European situations than in the US
Lack of poison pulls, no-jury trials, potential for award of costs 17<br>
slide18. Shareholder Activism in Europe is Here to Stay 18 Background
Traditionally, activism has been seen as a US Phenomenon, with European Investors tending not to intervene in the running of their portfolio companies
While EU legislation is creating a common base of applicable laws and regulations, historically some jurisdictions have had very different starting places to the US in terms of
Board structure
Availability of, and appetite for, litigation
Shareholder based (including cross-holding structures)
Political and market environments
Primacy of shareholder value
However, the activist model is taking root in Europe and institutions such as ISS are becoming increasingly important in determining the outcome of shareholder campaigns
The market in Europe has evolved, with shareholder activism now recognised as a legitimate economic activity which can, in some cases, be beneficial for companies and shareholders as a whole
A shareholder prepared to challenged an incumbent board of a European company will find a range of tools at its disposal and increasing support and engagement of ‘vanilla’ investors Some Recent Examples Shareholder activism has been a common phenomena in the US for some time. US funds are now looking to Europe – as demonstrated by Elliott with Actelion (as well as Danisco and National Express).<br>
slide19. Minority Rights 19<br>
slide20. M&A and Investment Banking Lesson 4.2 – Contract Negotiation 20<br>
slide21. Contract Negotiation Sales and Purchase Agreement
Due Diligence Process 21<br>
slide22. Contract Negotiation Sales and Purchase Agreement 22<br>
slide23. Sales and Purchase Agreement Legally binding contract between the acquiring and selling parties. It is subject to conditions such as shareholder approval
The contract can take the form of a stock purchase agreement, asset purchase agreement, tender offer document, or merger agreement
The SPA is a risk management device focused on the completion of the transaction
Therefore it may not include further details such as synergies, plans for integration, governance and organization, etc. 23 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
slide24. Key Sections in Purchase and Sale Agreements 24 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
slide25. Purchase Price Adjustments 25 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
slide26. Covenant Categories 26 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 29<br>
slide27. Contract Negotiation Due Diligence Process 27<br>
slide28. Due Diligence Definition & Principles Definition
An investigation or audit of a potential investment. Due diligence serves to confirm all material facts in regards to a sale
Generally, due diligence refers to the care a reasonable person should take before entering into an agreement or a transaction with another party
Principles
Avoid a compliance mentality and adopt an investor mentality (look at the risk-return trade-off )
Due diligence is a risk management device
Narrow- vs. Broader-scope due diligence: risk bearing is always costly
Broader-scope Due Diligence: Yields the basis for thinking like an investor. Focus mainly on wise acquiring rather than on legal issues. (Higher cost of the due diligence, but lower risk surprise now)
Narrow Scope Due Diligence: Focus mainly on the legal and accounting issues to get the deal done. Should be bundled with other risk management devices. (Lower cost of the due diligence, but higher risk surprise later) 28 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
slide29. What to Look for in a Due Diligence Legal Issues Accounting Issues Tax Issues Information Technology Risk and Insurance issues Environmental issues Market Presence and Sales issues Operations Real and Personal Property issues Intellectual and Intangible Assets Finance Cross-Border issues Organization and Human Resources Culture Ethics 29 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
slide30. Due Diligence Process: Timing Due Diligence over the Life Cycle of a Deal 30 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8 Focused on public data. Very small team. Due diligence oriented toward strategic or financial benefits of a combination Focused on public and some target private data. Team grows to include important outside advisers and some integration managers. Aims to advise LOI negotiators, and plan detailed due diligence Focused on target private documents as requested by buyer. Target provides data room. Aim is to support negotiators in their preparation of price, representation and warranties and other final terms. Focused on target documents, field visits, interviews, consultants’ reports. Very large team. Aim is to test representations and warranties in advance of closing, and prepare for post-merger integration First Proposal Letter of Intent Deal Contract Signed Closing<br>
slide31. Due Diligence Process: Team Attorney, general corporate review
Attorney, tax specialist
Attorney, regulation specialist
Attorney, risk management specialist
Attorney, environment specialist
Attorney, intellectual property specialist (e.g.: patents)
Attorney, pension and benefits specialist
Accountant, general audit
Accountant, tax specialist
Accountant, internal reporting
Consultant, information technology specialist
Buyer employee, information technology specialist
Actuary
Buyer employee(s), human resources, compensation, pension, benefits, and training
Consultant, human resources, compensation, pension, benefits, and training
Buyer employee, risk management specialist
Consultant, environment risk assessment specialist
Buyer employee, environment risk assessment specialist
Buyer employee(s), marketing and sales
Buyer employee(s), operations
Buyer employee(s), post-merger integration specialist
Buyer employee, cash management
Buyer employee, finance and valuation
Consultant, solvency analysis and credit analysis
Consultant, business forecast and operations
Consultant, real and personal property appraisal
Consultant, valuation specialist Hypothetical Due Diligence Review Team 31 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
slide32. Due Diligence Process: Outputs Primary work papers and other resources
These are the raw material of the diligence effort (i.e.: list of records checked, work papers and notes from the checking process, transcripts and audiotapes from interviews, videotapes from field visits and inspections, photographs, etc.)
Summaries by specialists
In each of the areas of focus a specialist should be tasked with preparing a summary of findings
Diligence synthesis
Technical overview of the entire due diligence effort usually written for the benefit of negotiators, and to combine the specialists’ findings for possible future reference
Integration recommendations
Recommendations for integration planners, that begin their work after the signing of the definitive agreement and draw on the findings from the diligence review
Executive summaries
Summaries suitable to informing and guiding executives along the way 32 Source: Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapter 8<br>
slide33. References Bruner, 2004. Applied Mergers and Acquisitions. Wiley Finance: chapters 8, 29, 30, 32-34
Fleuriet, 2008. Investment banking explained, McGraw-Hill: chapter 14
Iannotta, G., 2010. Investment Banking, Springer-Verlag Berlin Heidelberg: chapter 9
Kruse, T., 2005. Ownership, Control and Shareholder Value in Italy: Olivetti's Hostile Takeover of Telecom Italia. ECGI - Finance Working Paper No. 83/2005
Miller, E.L.J., 2008. Mergers and Acquisitions: A Step-by-Step Legal and Practical Guide. Wiley: chapter 2 33<br>