03
The Integrated Management Consultancy approach tackles all aspects of the Companies running, i.e., thorough planning, account outsourcing, practicality, transactional services and compliance outsourcing. 3 Akshit Bhatia | Parshotam & Associates<br>
04
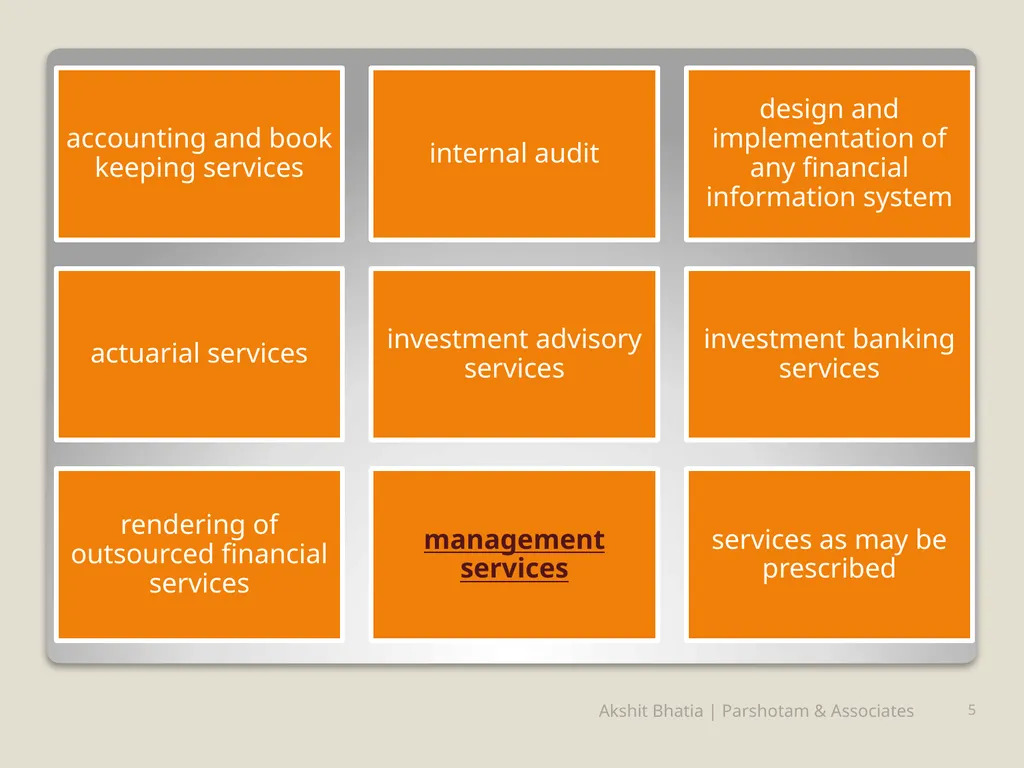
Services not to be rendered by the auditor Section 144 provides that an auditor shall provide to the company only such services those are approved by the Board of Directors or the audit committee, as the case may be but shall not include the following services rendered “directly or indirectly” to the company or its holding company or subsidiary company, namely:— 4 Akshit Bhatia | Parshotam & Associates<br>
05
5 Akshit Bhatia | Parshotam & Associates<br>
06
Disqualification of Auditor u/s 141 of companies act 2013 Section 144(h) has restricted the statutory auditors to provide “management services” but has not explained the meaning and scope of this expression even till date.
Any person acting as Statutory auditor of the company rendering services under section 144 read with section 141(3)(i) shall vacate his office under section 141(4) and that vacancy will be treated as a casual vacancy under section 139(8). 6 Akshit Bhatia | Parshotam & Associates<br>
07
Time allowed to leave the restricted services by the auditors It may be noted that an auditor or the audit firm who or which has been performing any non audit services on or before the commencement of this act shall comply with the provision of this section before the closure of the financial year after the date of such commencement. 7 Akshit Bhatia | Parshotam & Associates<br>
08
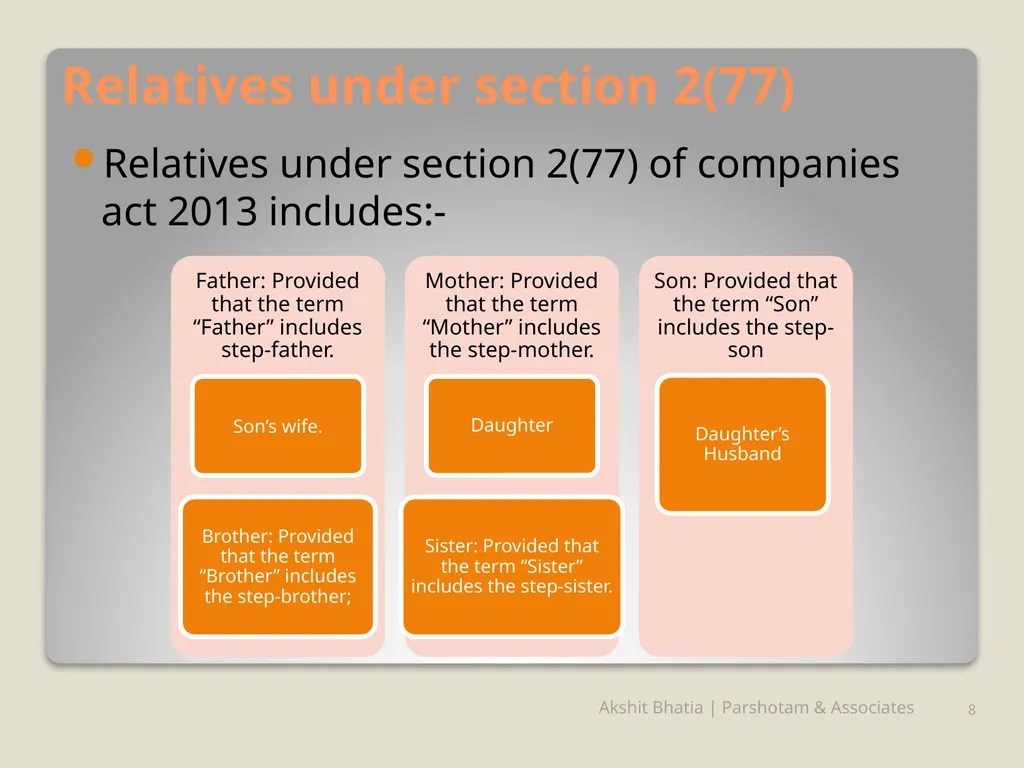
Relatives under section 2(77) Relatives under section 2(77) of companies act 2013 includes:- 8 Akshit Bhatia | Parshotam & Associates<br>
09
Example Mr. X, a practicing CA is appointed as a ‘Tax Consultant’ of ABC Ltd in which his father is a Managing Director.
Solution- A CA appointed as an auditor of a company, should ensure the independence in respect of his appointment. In this case Mr. X is a Tax Consultant and not a Statutory Auditor or Tax Auditor of ABC Ltd, hence he is not subject to the above requirements. 9 Akshit Bhatia | Parshotam & Associates<br>
10
Regulatory framework Guidance Note on independence states that the auditor should be straight-forward, honest and sincere in his approach to his professional work.
It further states that auditor should be independent in its objectivity. Further there are some threats to independency of auditor are stated by this framework.
Lets see if auditor provides any services other than audit, how these threats may occur. 10 Akshit Bhatia | Parshotam & Associates<br>
11
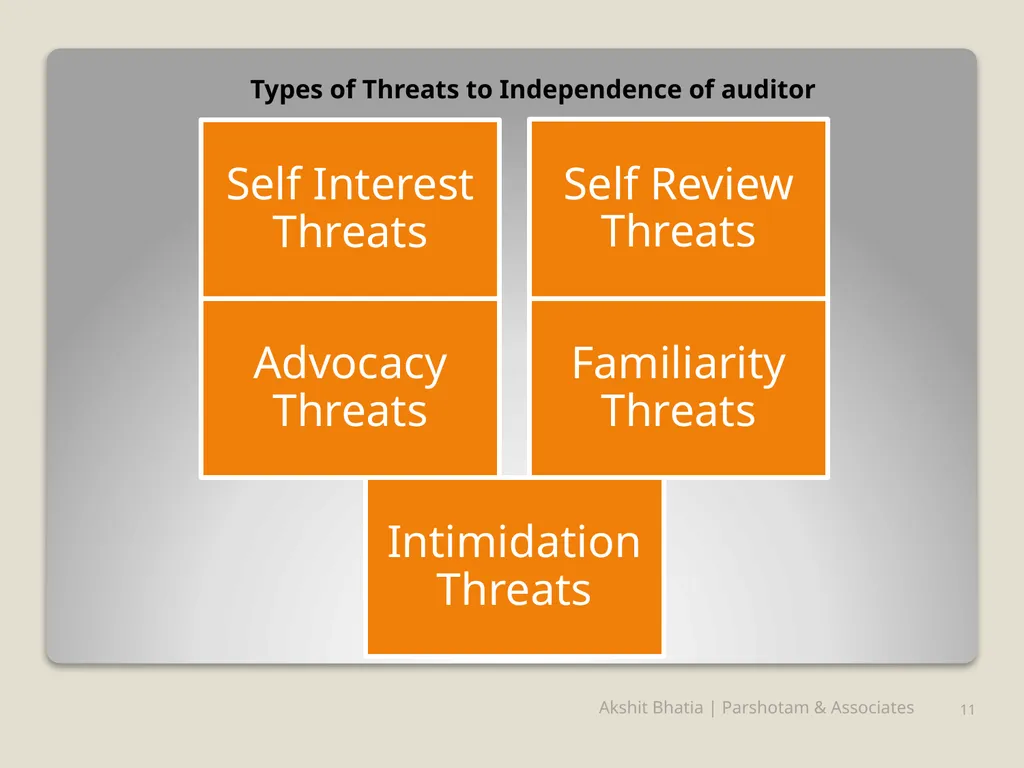
Types of Threats to Independence of auditor 11 Akshit Bhatia | Parshotam & Associates<br>
12
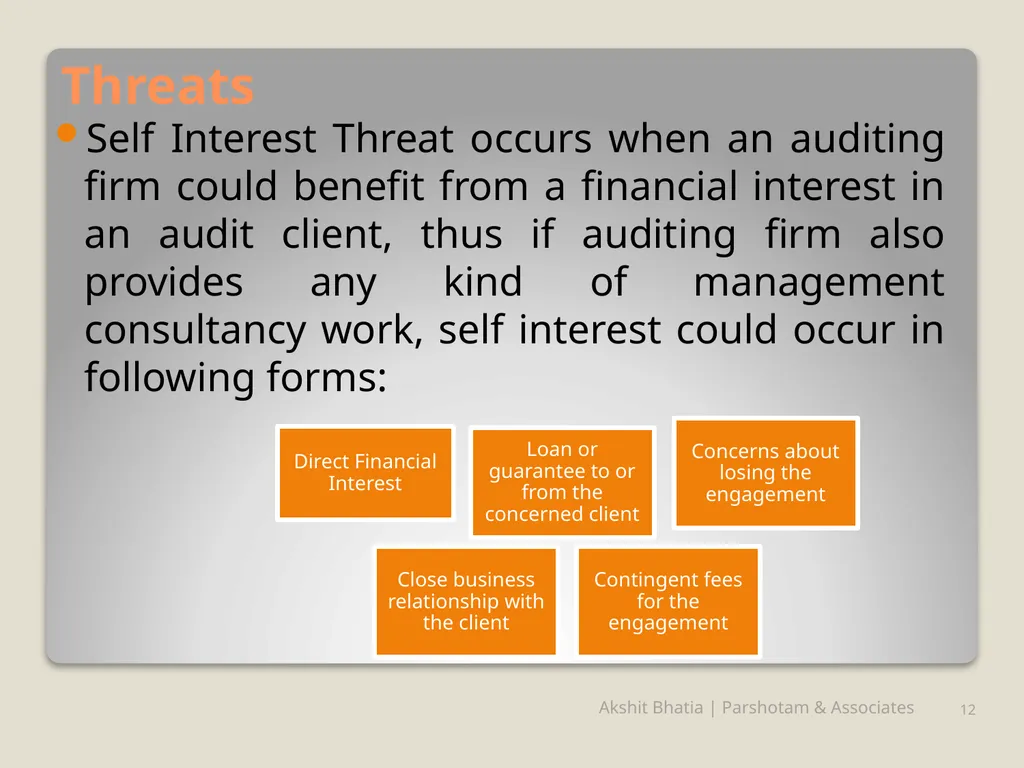
Threats Self Interest Threat occurs when an auditing firm could benefit from a financial interest in an audit client, thus if auditing firm also provides any kind of management consultancy work, self interest could occur in following forms: 12 Akshit Bhatia | Parshotam & Associates<br>
13
Self Review Threats occurs when work is performed or assisted by the person, who has the responsibility to review the same work. One of the instances where such threat come into play is : when auditors perform services that are themselves subject matters of audit.
Thus if auditor provides any type of management consultancy service it exposes the Self review threat 13 Akshit Bhatia | Parshotam & Associates<br>
14
Advocacy Threats are those threats which occur when the auditor promotes, or is perceived to promote, a client’s opinion to a point where people may believe that objectivity is getting compromised, e.g. when an auditor deals with shares or securities of the audited company, or becomes the client’s advocate in litigation and third party disputes, thus management consultancy if any provided by auditor exposes this threat. 14 Akshit Bhatia | Parshotam & Associates<br>
15
Familiarity threats are self-evident, and occur when auditors form relationships with the client where they end up being too sympathetic to the client’s interests. 15 Akshit Bhatia | Parshotam & Associates<br>
16
Intimidation threats, which occur when auditors are deterred from acting objectively with an adequate degree of professional skepticism. It can occur if other services are also provided by the auditor and thus auditor may skip the review of controls applied by auditor in capacity of consultant. 16 Akshit Bhatia | Parshotam & Associates<br>
17
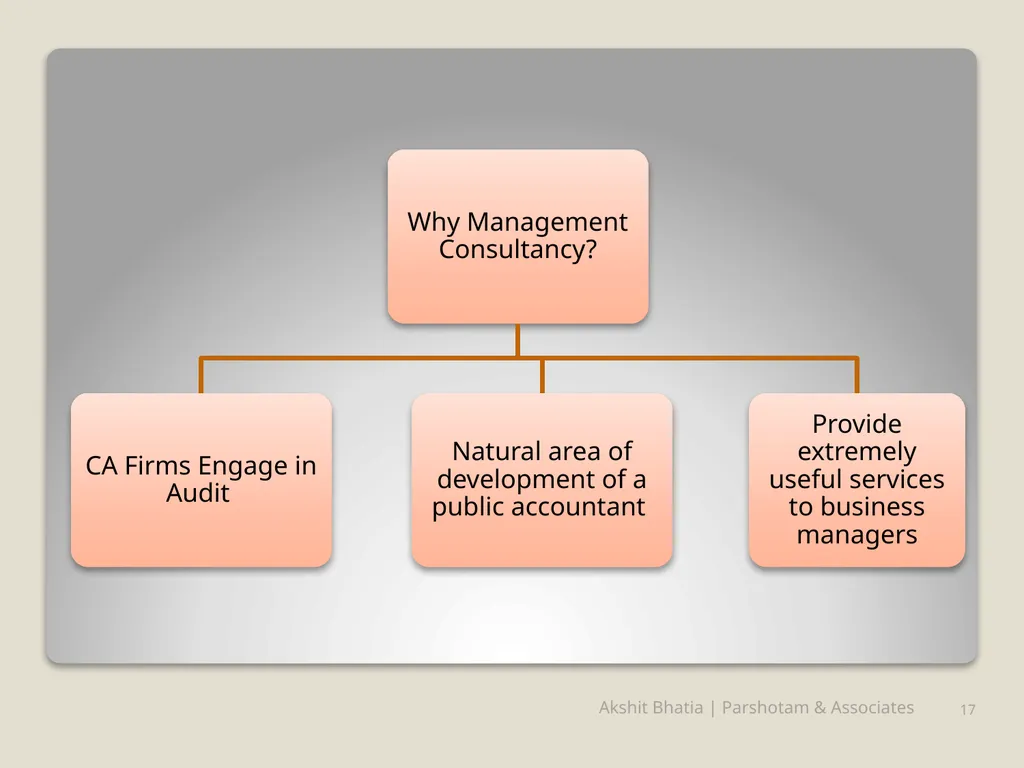
17 Akshit Bhatia | Parshotam & Associates<br>
18
Why a chartered accountant for management consultancy services? A CA is equipped with conceptual & practical knowledge of various subjects like Accounts, Finance, Taxation, Costing, Industry, Business & Company Laws, Capital Market, International Market & Laws, IT. 18 Akshit Bhatia | Parshotam & Associates<br>
19
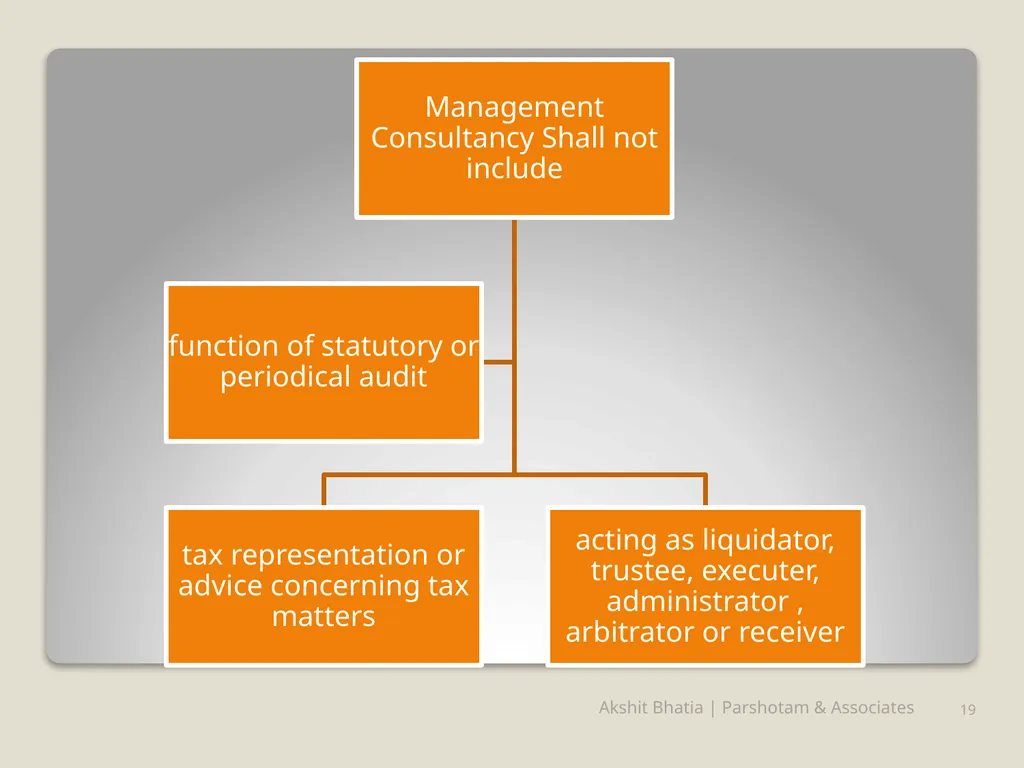
19 Akshit Bhatia | Parshotam & Associates<br>
20
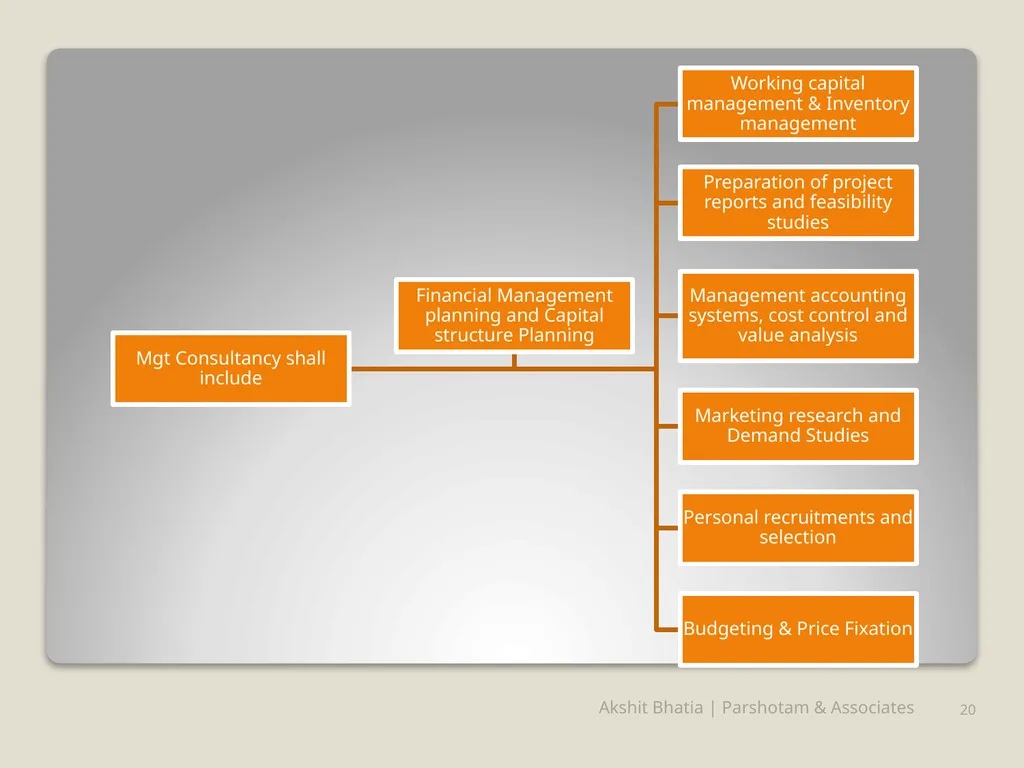
20 Akshit Bhatia | Parshotam & Associates<br>
21
Legislative Intent The Management services should be defined as services such as valuation, due diligence, special audit which could have bearing impact on the audit services may be prohibited. 21 Akshit Bhatia | Parshotam & Associates<br>
22
Punishment for non-compliance Any contravention under this section by the auditor than he shall be punishable with fine of not less than 25 thousand rupees which may extend to 5 lakh rupees.
Any willful default by the auditor then he shall be punishable with imprisonment for a term which extend to one year and fine which shall not be less than one lakh and 22 Akshit Bhatia | Parshotam & Associates<br>
23
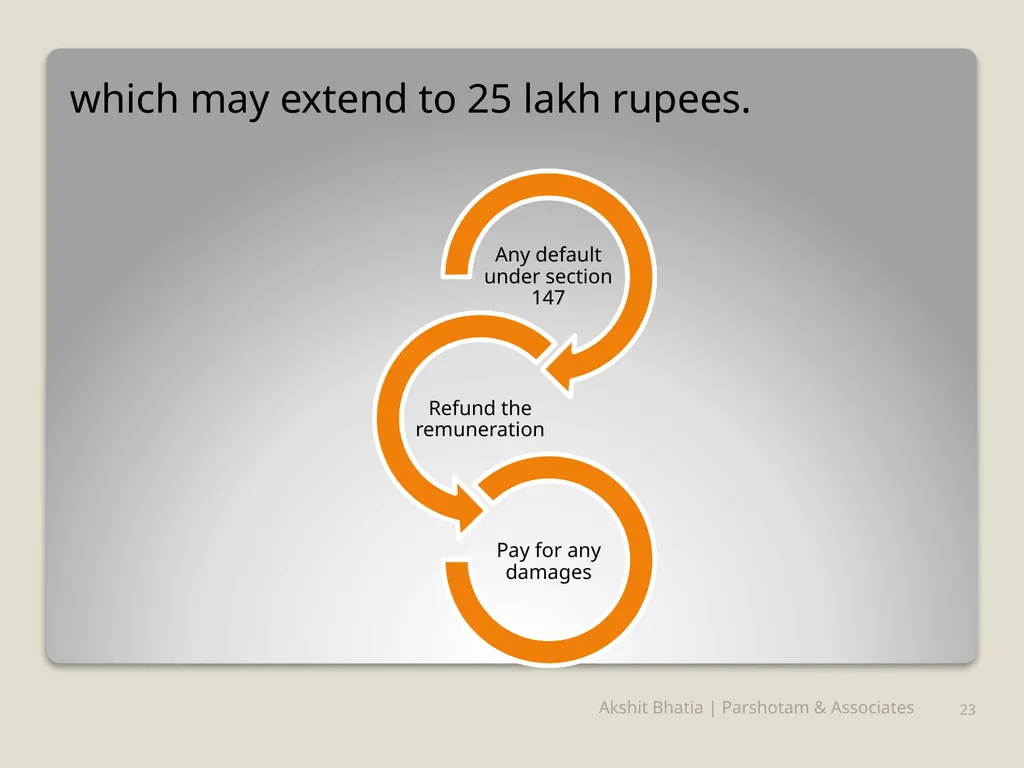
which may extend to 25 lakh rupees. 23 Akshit Bhatia | Parshotam & Associates<br>
24
Conclusion Management services means any services as may be provided in relation to the management or administration of the company.
Simply giving options/ setting out alternatives, without making a recommendation should be permitted as long as these recommendations/ options do not relate to any decisions pertaining to the way the business of auditee company is being run and does not constitute management consulting.
It seems that financial due diligence and tax services does not fall within the scope of prohibited services to the extent these are not management services.
The Act prohibits investment advisory and investment banking services but there is no prohibition for valuation services. However, if the valuation is for giving opinion on whether or not to invest in the company, to acquire the company, it may fall within management services. 24 Akshit Bhatia | Parshotam & Associates<br>
25
THANK YOU 25 Akshit Bhatia | Parshotam & Associates<br>