
Marketing of Deposits Marketing definition :- Is

Description: Marketing of Deposits Marketing definition :- Is the process of creating interest in the potential customers clients in your products and or services. Dr . Philip Kotlar Father of Marketing the science art of exploring , creating
Related Topics
Download Presentation
"Marketing of Deposits Marketing definition :- Is" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Marketing of Deposits Marketing definition :-
Is the process of creating interest in the potential customers & clients in your product/s and or services.
Dr . Philip Kotlar – Father of Marketing
“ the science & art of exploring , creating and delivering value to satisfy the needs of a target market at a profit.”
Marketing identifies unfulfilled needs & desires.
It defines measures & quantifies the size of the identified market & the profit potential.<br>
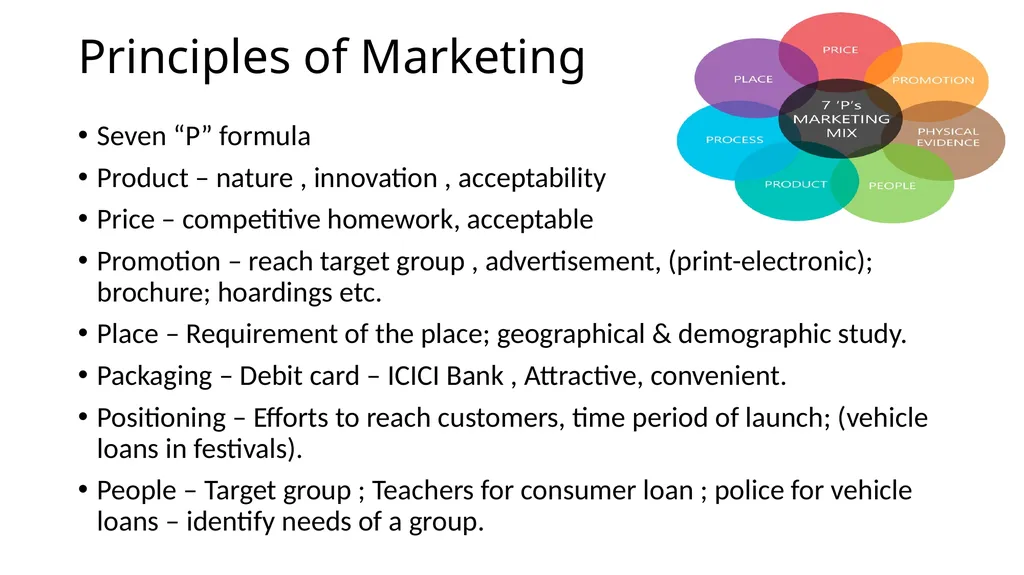
slide2. Principles of Marketing Seven “P” formula
Product – nature , innovation , acceptability
Price – competitive homework, acceptable
Promotion – reach target group , advertisement, (print-electronic); brochure; hoardings etc.
Place – Requirement of the place; geographical & demographic study.
Packaging – Debit card – ICICI Bank , Attractive, convenient.
Positioning – Efforts to reach customers, time period of launch; (vehicle loans in festivals).
People – Target group ; Teachers for consumer loan ; police for vehicle loans – identify needs of a group.<br>
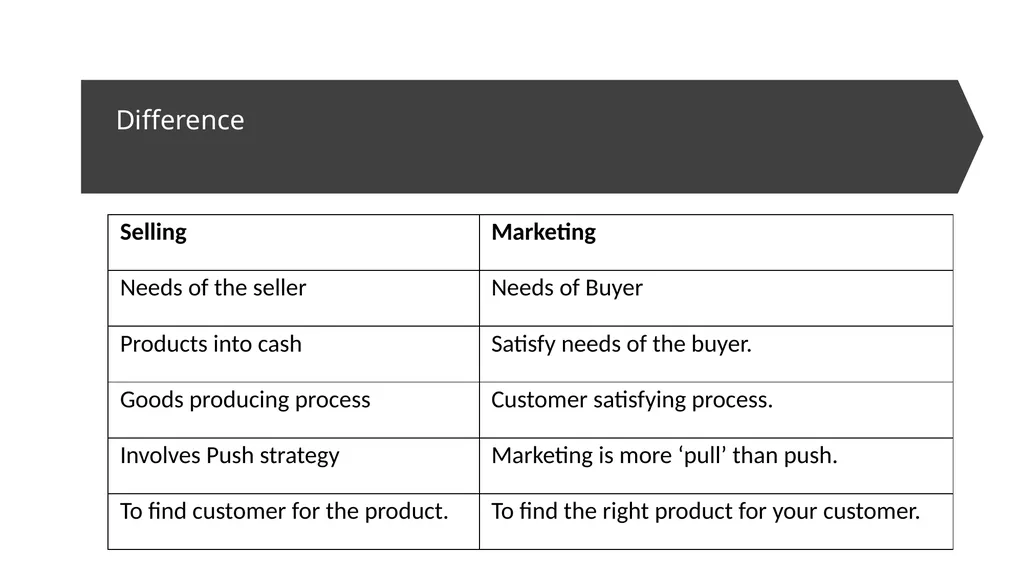
slide3. Difference<br>
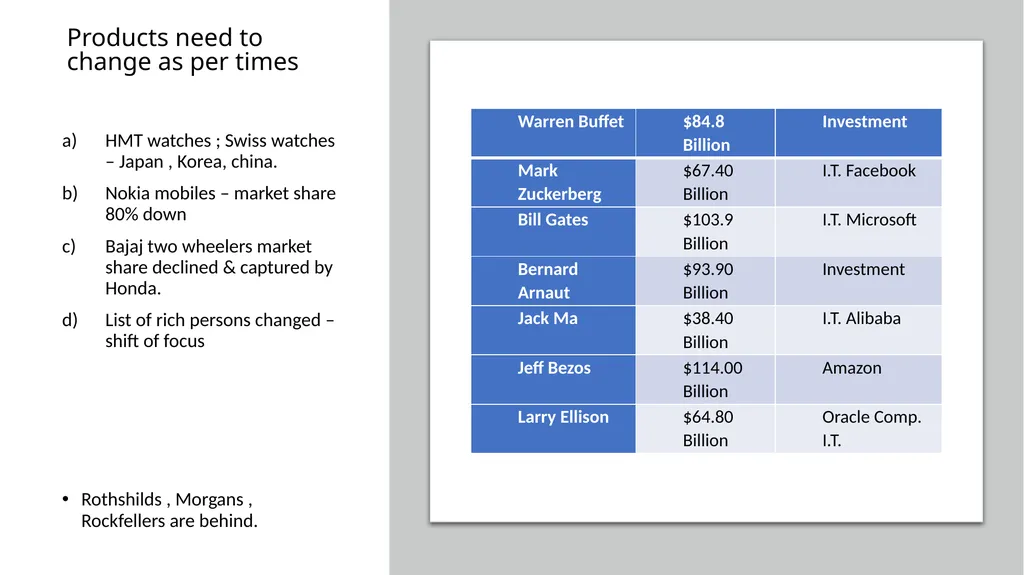
slide4. Products need to change as per times HMT watches ; Swiss watches – Japan , Korea, china.
Nokia mobiles – market share 80% down
Bajaj two wheelers market share declined & captured by Honda.
List of rich persons changed – shift of focus
Rothshilds , Morgans , Rockfellers are behind.<br>
slide5. Marketing in Banking Helping customer/s to open &operate accounts ; making transfers, availing various loans, forex requirements etc.
Marketing in Banks aims at –
Acquiring, Retaining & Growing Customers.
Customer as human being have needs, wants, demands and desires . To start with we should understand these needs.
Mobile and Net Banking becoming most popular.<br>
slide6. Relationship managers Create a customer base. High value customers.
All their requirements – door step service.
Account opening – scanning of KYC documents photo , signature – need not go to branch.
Debit card ; Credit card; Investment plans, personal loans; Travels-forex; everything is taken care.
Payment of utility bills – online.<br>
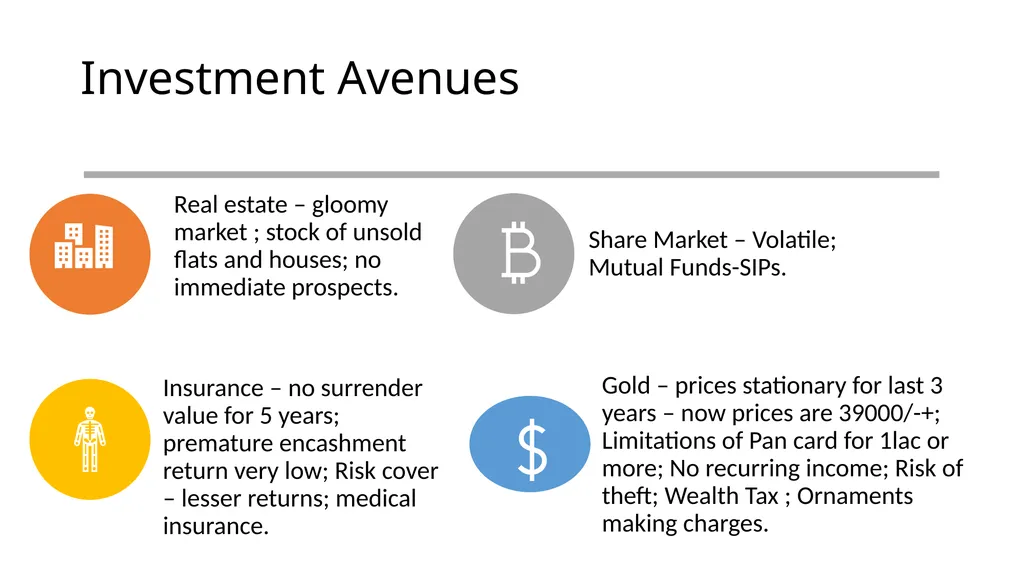
slide7. Investment Avenues<br>
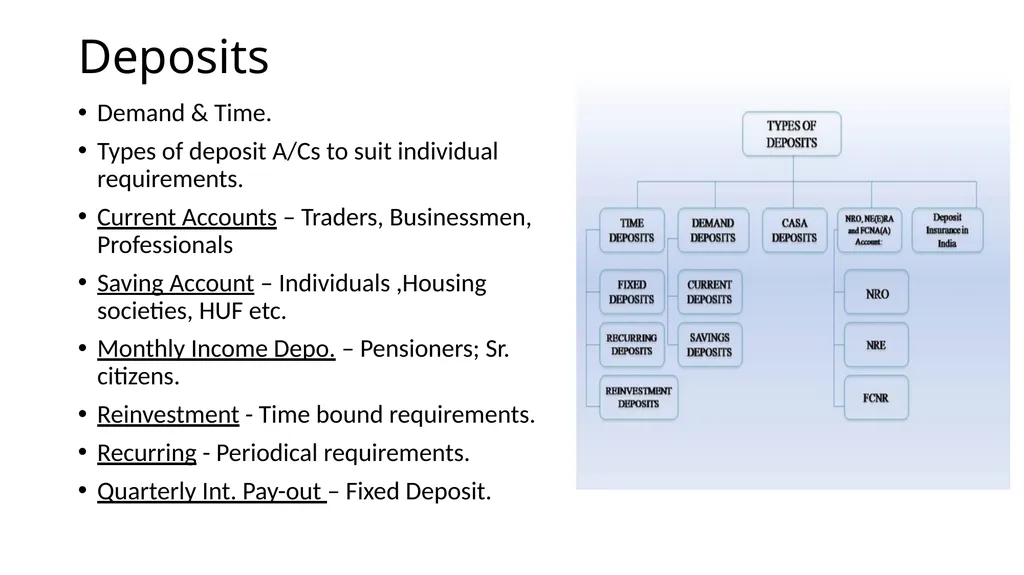
slide8. Deposits Demand & Time.
Types of deposit A/Cs to suit individual requirements.
Current Accounts – Traders, Businessmen, Professionals
Saving Account – Individuals ,Housing societies, HUF etc.
Monthly Income Depo. – Pensioners; Sr. citizens.
Reinvestment - Time bound requirements.
Recurring - Periodical requirements.
Quarterly Int. Pay-out – Fixed Deposit.<br>
slide9. Strengths of Deposits Premature encashment
Loan up to 90% of deposit.
Overdraft against deposit.
Age old popular investment.
Fixed contracted Interest Rate.
Any period from 7 days to 10 years.
HCs and B.Gs can be availed – Margin.
DICGC Cover up to 1 lac.<br>
slide10. Challenges in Marketing Deposits Competitive rate of interest
Deposits out of savings A/C.
TDS- on int. pay out 10000/-plus.
Form 15H &15-G.
Competition of SIP.
Co-op. Banks – Risk element.<br>
slide11. Marketing CASA Deposits Demand Deposits in nature.
Financial strength depends on % of CASA.
Higher the % better is the profitability.
CASA deposits affect Net Interest Margin (NIM).
Special efforts required for CASA.
Door to Door campaigning-
Package to salary earners-
Current A/C – No cheque book charges, Remittance at par Debit card – email A/C statement.
Selected CASA accounts Accident Insurance
Increase in % of CASA – cost of funds decreases profitability increases – 0
Competitive lending rates possible.<br>
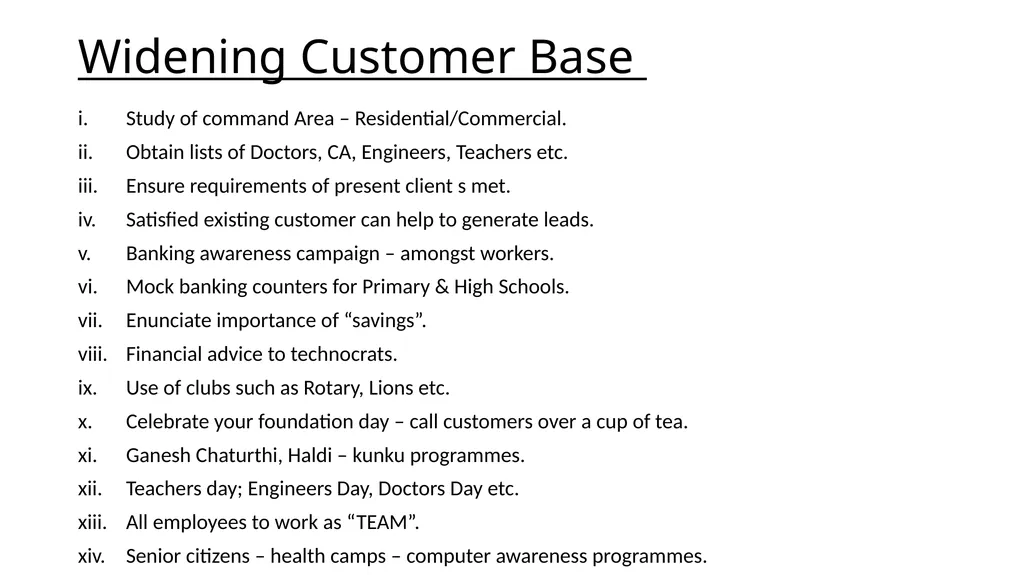
slide12. Widening Customer Base Study of command Area – Residential/Commercial.
Obtain lists of Doctors, CA, Engineers, Teachers etc.
Ensure requirements of present client s met.
Satisfied existing customer can help to generate leads.
Banking awareness campaign – amongst workers.
Mock banking counters for Primary & High Schools.
Enunciate importance of “savings”.
Financial advice to technocrats.
Use of clubs such as Rotary, Lions etc.
Celebrate your foundation day – call customers over a cup of tea.
Ganesh Chaturthi, Haldi – kunku programmes.
Teachers day; Engineers Day, Doctors Day etc.
All employees to work as “TEAM”.
Senior citizens – health camps – computer awareness programmes.<br>
slide13. Self Help Groups a) National priority – Urban – Semi urban – Villagers.
b) Minimum 10 women to form group.
c) Choose – Secretary; Chairman, Treasurer.
d) Develop Savings habit – get togethers.
e) Develop market for their products.
f) Exhibitions can be arranged at regular intervals.
g) Scheme of Financing – Marketing – Education – Training be approved by NABARD.
h) Expenses for training, Exhibitions etc. are compensated by NABARD.
i) Sizable CASA – Good advances – Excellent Recovery.
j) Low Costing Housing Loans.<br>
slide14. Know your Bank Financially Sound – Well Managed – FSWM Bank
Net worth of the Bank – positive
CRAR- Capital to Risk Asset Ratio 10% +
NPAs – Gross more relevant than Net NPAs – lessthan 7%.
Profit / Earnings – Last 3 years.
No defaults in CRR & SLR.
Sound internal control system – 2 professional Directors on board
CAMELS Rating – Capital Adequacy, Asset Quality, Management, Earnings, Liquidity & systems.
RBI Inspection Grade.
FSWM - On site / off site ATMs
Branch expansion,
Extension- area of operation
Shifting of premises etc.
Keep latest information regarding deposits & lending rates.<br>
slide15. Loan Products Clean Loan Shareholder
50,000 to 5,00,000
Easy process – Quick disbursement.
reasonable Rate of Interest.
Sanctioning Power to Branch Manager.
Compare with Pvt. Sector / Nationalized Bank.
Most powerful product with good return.<br>
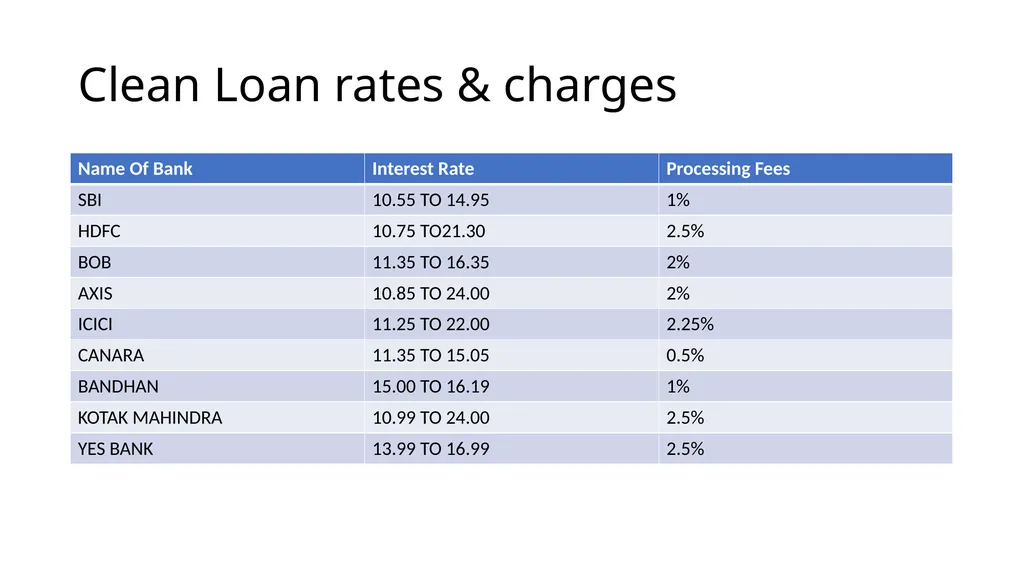
slide16. Clean Loan rates & charges<br>
slide17. Vehicle Loans Applicant (most) known to the Bank.
½ page loan application.
Simple, Easy & quick appraisal.
Reasonable Processing Charges.
Bulk/ Group Financing.
Police, Government Employees, Pvt. Companies Etc.
Disbursement with Function.<br>
slide18. Consortium Lending Requirement beyond Exposure Limit.
More than one bank to finance.
Single window document.
Retaining High Value Borrowers.
Group Accounts- Salaries etc.
Documentation on IBA sight.
Lead Bank undertakes appraisal.
Lead Bank executes documents
D.P. is communicated by Lead Bank.
Quaterly Review Meeting.<br>
Is the process of creating interest in the potential customers & clients in your product/s and or services.
Dr . Philip Kotlar – Father of Marketing
“ the science & art of exploring , creating and delivering value to satisfy the needs of a target market at a profit.”
Marketing identifies unfulfilled needs & desires.
It defines measures & quantifies the size of the identified market & the profit potential.<br>
slide2. Principles of Marketing Seven “P” formula
Product – nature , innovation , acceptability
Price – competitive homework, acceptable
Promotion – reach target group , advertisement, (print-electronic); brochure; hoardings etc.
Place – Requirement of the place; geographical & demographic study.
Packaging – Debit card – ICICI Bank , Attractive, convenient.
Positioning – Efforts to reach customers, time period of launch; (vehicle loans in festivals).
People – Target group ; Teachers for consumer loan ; police for vehicle loans – identify needs of a group.<br>
slide3. Difference<br>
slide4. Products need to change as per times HMT watches ; Swiss watches – Japan , Korea, china.
Nokia mobiles – market share 80% down
Bajaj two wheelers market share declined & captured by Honda.
List of rich persons changed – shift of focus
Rothshilds , Morgans , Rockfellers are behind.<br>
slide5. Marketing in Banking Helping customer/s to open &operate accounts ; making transfers, availing various loans, forex requirements etc.
Marketing in Banks aims at –
Acquiring, Retaining & Growing Customers.
Customer as human being have needs, wants, demands and desires . To start with we should understand these needs.
Mobile and Net Banking becoming most popular.<br>
slide6. Relationship managers Create a customer base. High value customers.
All their requirements – door step service.
Account opening – scanning of KYC documents photo , signature – need not go to branch.
Debit card ; Credit card; Investment plans, personal loans; Travels-forex; everything is taken care.
Payment of utility bills – online.<br>
slide7. Investment Avenues<br>
slide8. Deposits Demand & Time.
Types of deposit A/Cs to suit individual requirements.
Current Accounts – Traders, Businessmen, Professionals
Saving Account – Individuals ,Housing societies, HUF etc.
Monthly Income Depo. – Pensioners; Sr. citizens.
Reinvestment - Time bound requirements.
Recurring - Periodical requirements.
Quarterly Int. Pay-out – Fixed Deposit.<br>
slide9. Strengths of Deposits Premature encashment
Loan up to 90% of deposit.
Overdraft against deposit.
Age old popular investment.
Fixed contracted Interest Rate.
Any period from 7 days to 10 years.
HCs and B.Gs can be availed – Margin.
DICGC Cover up to 1 lac.<br>
slide10. Challenges in Marketing Deposits Competitive rate of interest
Deposits out of savings A/C.
TDS- on int. pay out 10000/-plus.
Form 15H &15-G.
Competition of SIP.
Co-op. Banks – Risk element.<br>
slide11. Marketing CASA Deposits Demand Deposits in nature.
Financial strength depends on % of CASA.
Higher the % better is the profitability.
CASA deposits affect Net Interest Margin (NIM).
Special efforts required for CASA.
Door to Door campaigning-
Package to salary earners-
Current A/C – No cheque book charges, Remittance at par Debit card – email A/C statement.
Selected CASA accounts Accident Insurance
Increase in % of CASA – cost of funds decreases profitability increases – 0
Competitive lending rates possible.<br>
slide12. Widening Customer Base Study of command Area – Residential/Commercial.
Obtain lists of Doctors, CA, Engineers, Teachers etc.
Ensure requirements of present client s met.
Satisfied existing customer can help to generate leads.
Banking awareness campaign – amongst workers.
Mock banking counters for Primary & High Schools.
Enunciate importance of “savings”.
Financial advice to technocrats.
Use of clubs such as Rotary, Lions etc.
Celebrate your foundation day – call customers over a cup of tea.
Ganesh Chaturthi, Haldi – kunku programmes.
Teachers day; Engineers Day, Doctors Day etc.
All employees to work as “TEAM”.
Senior citizens – health camps – computer awareness programmes.<br>
slide13. Self Help Groups a) National priority – Urban – Semi urban – Villagers.
b) Minimum 10 women to form group.
c) Choose – Secretary; Chairman, Treasurer.
d) Develop Savings habit – get togethers.
e) Develop market for their products.
f) Exhibitions can be arranged at regular intervals.
g) Scheme of Financing – Marketing – Education – Training be approved by NABARD.
h) Expenses for training, Exhibitions etc. are compensated by NABARD.
i) Sizable CASA – Good advances – Excellent Recovery.
j) Low Costing Housing Loans.<br>
slide14. Know your Bank Financially Sound – Well Managed – FSWM Bank
Net worth of the Bank – positive
CRAR- Capital to Risk Asset Ratio 10% +
NPAs – Gross more relevant than Net NPAs – lessthan 7%.
Profit / Earnings – Last 3 years.
No defaults in CRR & SLR.
Sound internal control system – 2 professional Directors on board
CAMELS Rating – Capital Adequacy, Asset Quality, Management, Earnings, Liquidity & systems.
RBI Inspection Grade.
FSWM - On site / off site ATMs
Branch expansion,
Extension- area of operation
Shifting of premises etc.
Keep latest information regarding deposits & lending rates.<br>
slide15. Loan Products Clean Loan Shareholder
50,000 to 5,00,000
Easy process – Quick disbursement.
reasonable Rate of Interest.
Sanctioning Power to Branch Manager.
Compare with Pvt. Sector / Nationalized Bank.
Most powerful product with good return.<br>
slide16. Clean Loan rates & charges<br>
slide17. Vehicle Loans Applicant (most) known to the Bank.
½ page loan application.
Simple, Easy & quick appraisal.
Reasonable Processing Charges.
Bulk/ Group Financing.
Police, Government Employees, Pvt. Companies Etc.
Disbursement with Function.<br>
slide18. Consortium Lending Requirement beyond Exposure Limit.
More than one bank to finance.
Single window document.
Retaining High Value Borrowers.
Group Accounts- Salaries etc.
Documentation on IBA sight.
Lead Bank undertakes appraisal.
Lead Bank executes documents
D.P. is communicated by Lead Bank.
Quaterly Review Meeting.<br>