
NCPERS presents Financial Economics and the

Description: NCPERS presents Financial Economics and the Management of Public Pension Plans: A Critical Response Paul Angelo, FSA, FCA, MAAA Senior Vice President Actuary, Segal Consulting September 27, 2017 Sherry S. Chan, FSA, FCA, MAAA Chief
Related Topics
Download Presentation
"NCPERS presents Financial Economics and the" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. NCPERS presents
Financial Economics and the Management of Public Pension Plans:
A Critical Response Paul Angelo, FSA, FCA, MAAA Senior Vice President & Actuary, Segal Consulting September 27, 2017 Sherry S. Chan, FSA, FCA, MAAA Chief Actuary, New York City Office of the Actuary 5485051v3<br>
slide2. The Market Pricing Controversy Ongoing controversy on how to value pension obligations for public sector pension plans
The Level Cost Model
Discount rate: expected return on assets
Cost method: level cost based on projected benefits
Based on established funding practices
See Conference of Consulting Actuaries “White Paper” on Funding Policy
The Market Pricing Model (“MV ABO”, aka MVL, “economic value”)
Discount rate: market yields on low risk bonds (MV)
Bonds with default risk comparable to the public pension promise
Cost method: increasing cost based on accrued benefits (ABO)
Based on “financial economics” (FE)
“Understanding the Valuation of Public Pension Liabilities: Expected Cost versus Market Price”
Society of Actuaries “In the Public Interest” newsletter, Jan. 2016 2<br>
slide3. Terminology is part of the controversy Cost, liability, obligation and value: framework for discussion
First, there’s the (unquantified) concept of “cost vs benefit”
The “cost” is the hurt on the taxpayer to provide a good thing (retirement security) to the employee
Then, “Cost” is the quantified amount incurred in a period
“Liability” is the Cost accrued to date (one determines the other)
“Obligation” quantifies the promise to date (e.g., FASB’s ABO)
Depending on purpose, the Obligation value could be the Liability
If so, then the periodic Cost is the change in the Obligation
“Value” retains several meanings, both as verb and noun! 3<br>
slide4. Terminology is part of the controversy Market Pricing proponents assert that “the cost” is that determined under the market pricing model
Starts with MV ABO as liability (hence “MVL)
Then the periodic cost is ∆ MV ABO (change in MV ABO)
In contrast, the Level Cost Model reverses the order
Starts with an allocation of periodic Normal Costs (NC) with the same actuarial present value as the member’s projected benefit
Consistent with the periodic nature of the pension benefit
Then the accrued liability is ∑ NC (sum of individual NCs)
Under Actuarial Standards of Practice (ASOPs) 4 and 27, the basis for measurement of both cost and liability depends on the purpose of the measurement 4<br>
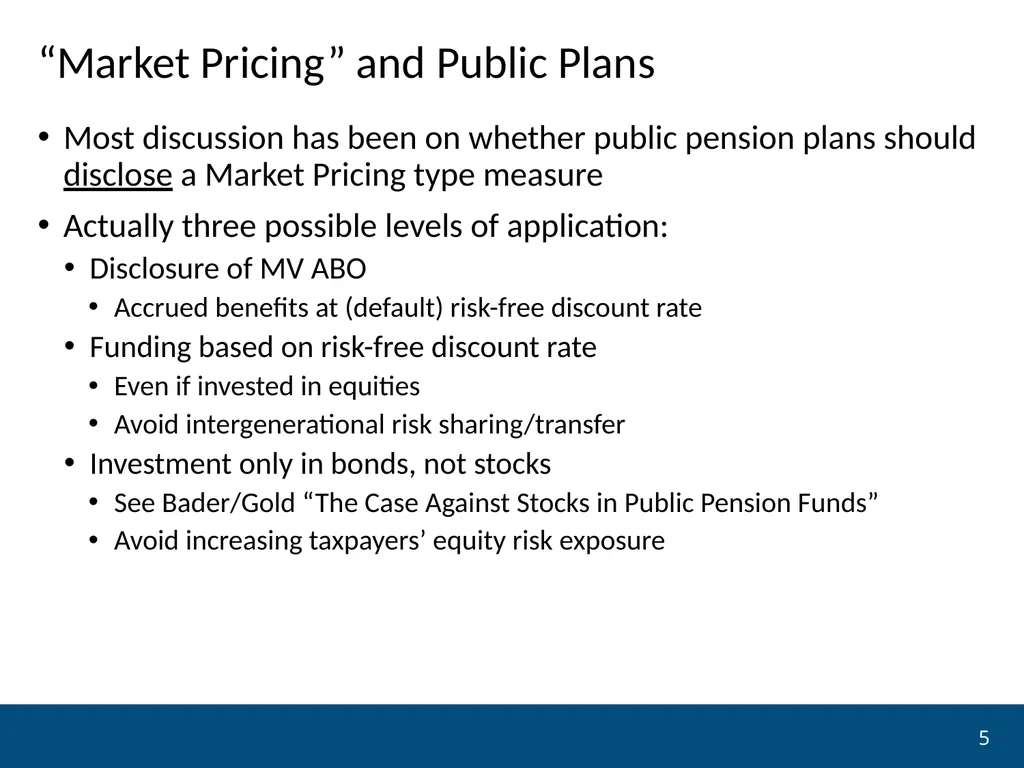
slide5. “Market Pricing” and Public Plans Most discussion has been on whether public pension plans should disclose a Market Pricing type measure
Actually three possible levels of application:
Disclosure of MV ABO
Accrued benefits at (default) risk-free discount rate
Funding based on risk-free discount rate
Even if invested in equities
Avoid intergenerational risk sharing/transfer
Investment only in bonds, not stocks
See Bader/Gold “The Case Against Stocks in Public Pension Funds”
Avoid increasing taxpayers’ equity risk exposure 5<br>
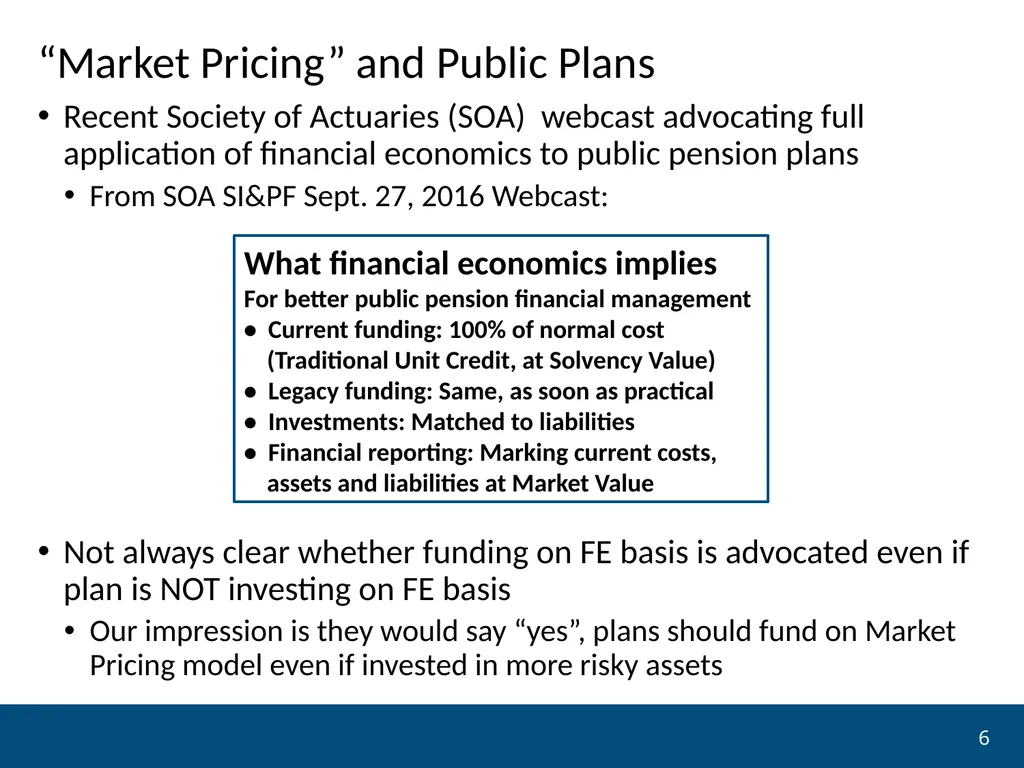
slide6. “Market Pricing” and Public Plans Recent Society of Actuaries (SOA) webcast advocating full application of financial economics to public pension plans
From SOA SI&PF Sept. 27, 2016 Webcast:
Not always clear whether funding on FE basis is advocated even if plan is NOT investing on FE basis
Our impression is they would say “yes”, plans should fund on Market Pricing model even if invested in more risky assets 6 What financial economics implies
For better public pension financial management
• Current funding: 100% of normal cost (Traditional Unit Credit, at Solvency Value)
• Legacy funding: Same, as soon as practical
• Investments: Matched to liabilities
• Financial reporting: Marking current costs, assets and liabilities at Market Value<br>
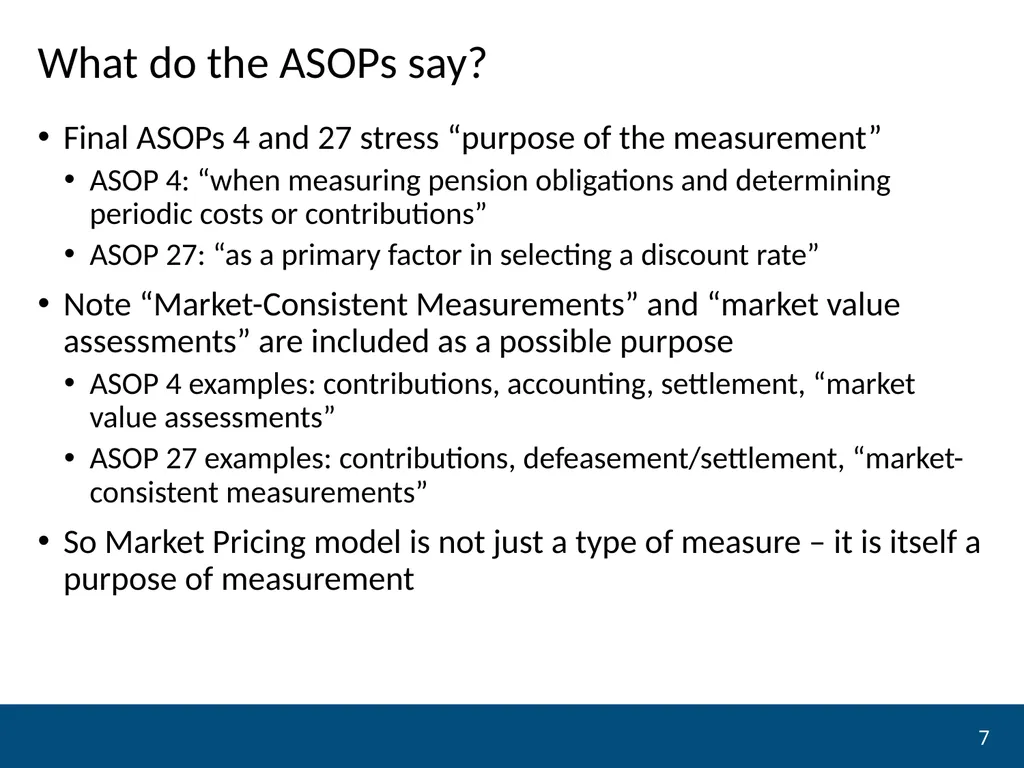
slide7. What do the ASOPs say? Final ASOPs 4 and 27 stress “purpose of the measurement”
ASOP 4: “when measuring pension obligations and determining periodic costs or contributions”
ASOP 27: “as a primary factor in selecting a discount rate”
Note “Market-Consistent Measurements” and “market value assessments” are included as a possible purpose
ASOP 4 examples: contributions, accounting, settlement, “market value assessments”
ASOP 27 examples: contributions, defeasement/settlement, “market-consistent measurements”
So Market Pricing model is not just a type of measure – it is itself a purpose of measurement 7<br>
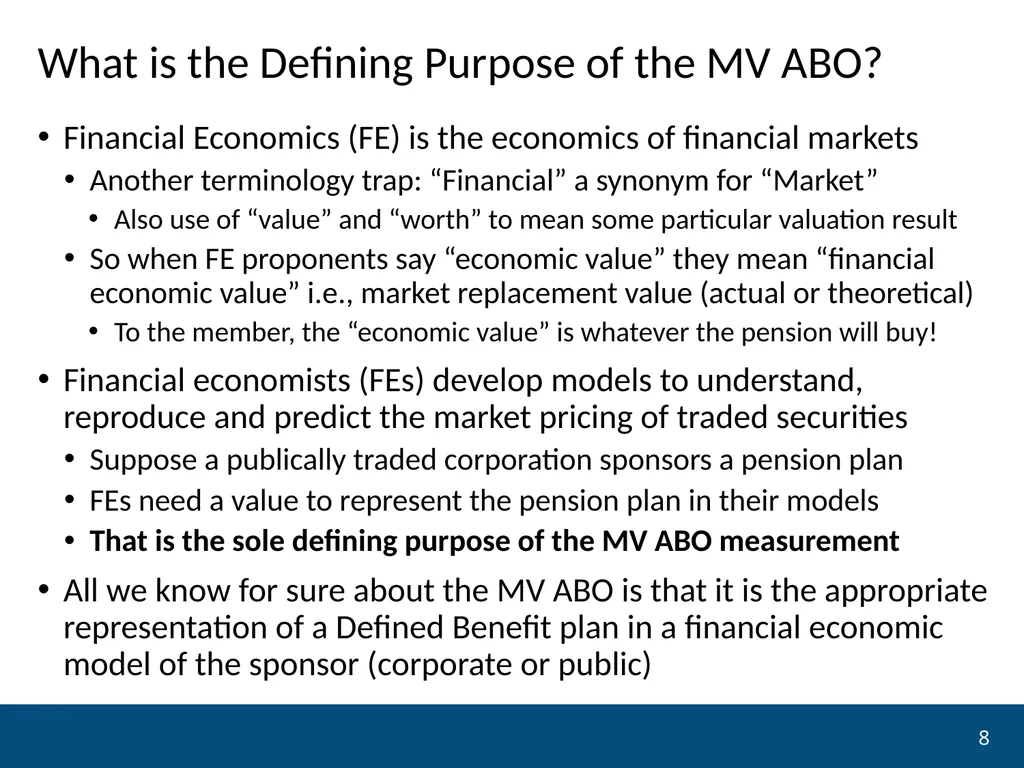
slide8. What is the Defining Purpose of the MV ABO? Financial Economics (FE) is the economics of financial markets
Another terminology trap: “Financial” a synonym for “Market”
Also use of “value” and “worth” to mean some particular valuation result
So when FE proponents say “economic value” they mean “financial economic value” i.e., market replacement value (actual or theoretical)
To the member, the “economic value” is whatever the pension will buy!
Financial economists (FEs) develop models to understand, reproduce and predict the market pricing of traded securities
Suppose a publically traded corporation sponsors a pension plan
FEs need a value to represent the pension plan in their models
That is the sole defining purpose of the MV ABO measurement
All we know for sure about the MV ABO is that it is the appropriate representation of a Defined Benefit plan in a financial economic model of the sponsor (corporate or public) 8<br>
slide9. Brief History of Market Pricing Model for Corporate Pension Plans Originally, ERISA minimum funding was only level-cost model
IRC Sec. 412, from 1976 to 1987
Market pricing for corporate plans arrives in1987
“Current Liability” under OBRA 1987 for funding
Also “ABO” under FAS 87 for expensing
Clearly intended as a settlement measure of accrued benefits
For funding, dual regime lasts for 20 years
With RPA 1994, market pricing model starts to take over
In 2003, “the Great Controversy” (SOA Vancouver) advocated strict market pricing for corporate pension funding
Finally, PPA 2006 eliminates level cost funding for corporates
Target Liability is a strict MV ABO (discount rate relaxed in 2012)
Corporate “Pension Actuary’s Guide to FE” published 9<br>
slide10. Market focus: corporate vs public FE’s market focus is appropriate for corporations
A stock corporation exists solely to maximize its stock’s market price
Everything, including its pensions, must be considered as reducible to a market derived value and managed based on that market value.
Public sector linkage to the market is less direct
Agencies and pension plans participate in the markets
The purpose of public agencies and pension plans cannot be reduced to a single market defined measure
Corporations are “of” the market, while public agencies and plans are only “in” the market.
FE principles do not incorporate this difference
FE conclusions provide information about all stock corporations, not about all pension plans 10<br>
slide11. Evaluating the Market Pricing Model as a Basis for Funding Public Pension Plans Consider what it means to use the Market Pricing model to measure the ongoing cost of a pension plan
Focus on funding but discussion also applies to disclosure
Start with the cost allocation method: Traditional Unit Credit (TUC)
Accrued Liability = PV of accrued benefits (MV ABO)
Normal Cost = Change in PV of accrued benefits (∆ MV ABO)
Well known flaws in TUC/PVAB/ABO method for allocating costs
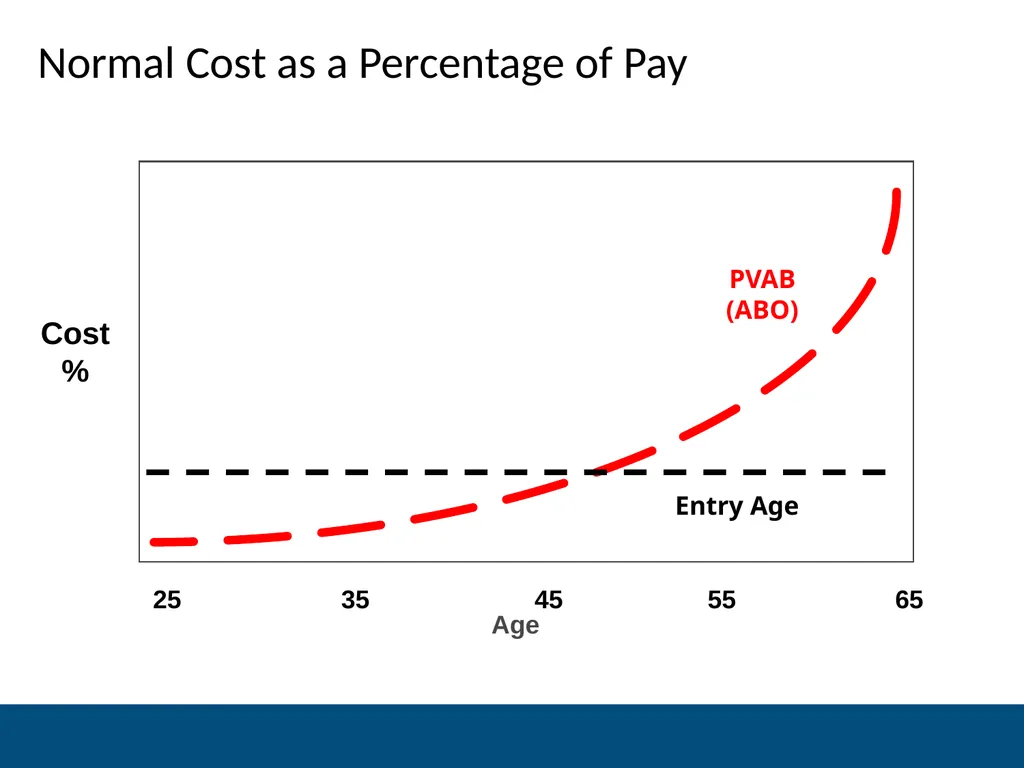
Back-loaded cost allocation, sharply increasing individual normal costs
Cost spikes at eligibility for retirement
Demographically unstable aggregate normal cost
Even for corporate plans, TUC was illegal for final pay plans
Except as a settlement value 11<br>
slide12. Normal Cost as a Percentage of Pay<br>
slide13. Evaluating Market Pricing: TUC/ABO Cost Method Under FE theory, the pension plan is a transfer of wealth
Amount of annual wealth transfer is ∆ MV ABO
∆ MV ABO is part of members annual compensation
For a career participant in later years of service, this ∆ MV ABO (i.e., TUC Normal Cost) should be the employees entire incremental compensation – so no pay increases (or even pay)
Source: GASB Financial Reporting Task Force, December 2, 2009
This untenable conclusion led GASB to adopt the Level Cost model (Entry Age method) for financial reporting
See GASB Statement 68 “Basis of Conclusions”, §256 on cost allocation
The policy objective of an equitable cost allocation over a career requires a more sophisticated model than simple benefit accrual 13<br>
slide14. Evaluating Market Pricing: “Risk Free” Discount Rate Overcharges current taxpayers and members on an expected value basis (assuming plan NOT invested on FE basis)
Violates intergenerational equity
Member rates never reflect equity returns, even when realized
Excludes expected savings from intergenerational risk sharing
This led GASB to adopt the Level Cost model (expected return discount rate) for financial reporting
See GASB Statement 68, §§227-228 on discount rate
The policy objective of an equitable cost allocation over generations requires a more sophisticated model than simply observing bond yields 14<br>
slide15. What About the Equity Risk? Intergenerational risk sharing or pooling does entail the risk of intergenerational transfers of gains or losses
FE looks only at risk of shifting losses forward
Risks and advantages are shared by all generations
Taxpayers assign equity investing role to public plans
E.g., California 1966 (25% equities), 1984 (“prudent man” rule)
FE replaces risk management with risk aversion
This comes at a high price to the taxpayers
FE does not balance the costs and benefits of accepting that risk across generations 15<br>
slide16. Equity Investment for Retirement Plans FE principles conclude pension plans should not invest in equities.
Match riskiness of assets to (low) riskiness of benefit promise
Avoid increasing taxpayer/shareholder equity risk exposure
Equity investing OK for individual retirement planning
How should the retirement function participate in the economy?
As an owner (through equities) or only as a lender (through bonds)
Answer: as an owner, whether individually or collectively
E.g., California 1966 (25% equities), 1984 (“prudent man” rule)
Public pension plans allow pooling of risk, both demographic and economic
Provides a more economically efficient vehicle for converting taxpayer dollars into retirement security for public employees 16<br>
slide17. Limitations of Financial Economic Principles For public agencies there are relevant principles, objectives and policy considerations beyond those reflected in the FE model
They lead to a level cost allocation method and an expected return discount rate, both for funding and financial reporting
For example, see GASB Statement 68 “Basis of Conclusions”
Paragraph 256 on cost allocation
Paragraphs 227-228 on discount rate
Similarly, for funding see CCA PPC Funding Policies and Practices “White Paper”
Balance between demographic matching and volatility management
The financial economic model and its MV ABO measure are insufficient to represent the more complicated policy objectives of public pension plans 17<br>
slide18. Limitations of Financial Economic Principles FE principles were developed for the purpose of determining a value consistent with the financial economic model
Those principles lead to MV ABO as the appropriate measure
FE proponents then assert these principles are appropriate and sufficient for other purposes, i.e., funding a public pension plan
Fails to acknowledge the limitations of their defining purpose
FE proponents show that FE principles lead to MV ABO as appropriate measure for public pension plans, including disclosure, funding and investing
That is because market economic principles always lead to a market pricing measure 18<br>
slide19. Report of the Actuarial Standards Board’s Pension Task Force (PTF) -- Feb. 29, 2016 PTF believes that a “market-based alternative liability measurement” should be calculated and disclosed for all valuations of pension plans for funding purposes, because:
It may be misleading to show traditional values by themselves.
Market-based alternative liability provides a reasonable measure of the cost of reducing the risk that the traditional measurement will be insufficient for the underlying obligation
Provides important information about risk.
Encourage better decisions regarding the financing of the plan.
Will help advance the actuarial profession.
Not implying that such a measure is “the one true answer”
Would show an important alternative view of pension finance 19<br>
slide20. ASB Pension Task Force “Suggestions” The PTF suggests that an alternative liability measure based on “solvency value” be calculated and disclosed for all valuations of pension plans done for funding purposes.
Estimate of the cost to defease all liabilities accrued under the plan in the marketplace, presuming that capacity is available
Assets needed to fully secure promises to members
Understanding of risks to members’ benefits
Information about the amount of investment risk being taken
An acceptable proxy for this measurement would be
Present value of accrued benefits (i.e., unit credit method)
U.S. Treasury rates as discount rate
other assumptions according to ASOP Nos. 27 and 35.
Avoid the term “market value of liabilities”! 20<br>
slide21. Defeasement/settlement value as measure of risk Terminology: common meaning of “solvency” is not the same as what it means within FE theory
So a better term is “defeasement” or “settlement” value
ASB PTF says disclosure of a market-based liability measurement:
provides a measure of the cost of reducing the risk that the traditional actuarial liability measurement will be insufficient collateral for the underlying obligation,
provides information about the amount of investment risk being taken by the plan. In particular, it can show the amount of investment income in excess of that provided by low-risk investments that the principal expects to receive
But settlement value does not measure the possible consequences of investment risk, only the cost to eliminate that risk
Quantifies risk aversion, not risk management 21<br>
slide22. Risk of Misuse of Market Pricing Disclosure Market pricing proponents have a well-established practice of describing MV ABO as the only true measure of pension cost
Proponents of other measures are either ignorant or deceitful
One recent example: David Crane, “It’s the Lie That Gets You” [medium.com, March 4, 2017] 22 Notice how CalPERS is choosing to value liabilities at the same rate as it expects to earn on assets. …
As Nixon said, it’s the lie that gets you. CalPERS’s lies harm citizens.
By linking discount rates to investment return assumptions, CalPERS and its sister pension fund, CalSTRS, are being untruthful. The lies get exposed when citizens get hit with pension deficits.<br>
slide23. Actuarial Code of Conduct – Precept 8 PRECEPT 8. An Actuary who performs Actuarial Services shall take reasonable steps to ensure that such services are not used to mislead other parties.
ANNOTATION 8-1. An Actuarial Communication prepared by an Actuary may be used by another party in a way that may influence the actions of a third party. The Actuary should recognize the risks of misquotation, misinterpretation, or other misuse of the Actuarial Communication and should therefore take reasonable steps to present the Actuarial Communication clearly and fairly and to include, as appropriate, limitations on the distribution and utilization of the Actuarial Communication.
What if no amount of clearly presented “limitations on utilization” will prevent the Solvency Value from being (mis)interpreted to other parties as the “true cost” of the benefit? 23<br>
slide24. Summary comment on lower discount rates for public pension valuations Two very different arguments for lowering the discount rate
Market Pricing Model: discount rate should be based on current (very low) “risk-free” interest rates
Independent of asset allocation or expected return on assets!
Based on financial economics and “market pricing” model
Level Cost Model: discount rate should be based on a lower expected return on assets
Still based on asset allocation and “level cost” model, but less optimistic
Reflects lower inflation expectations, lower bond returns, etc.
This is an essential part of any review of assumptions
Arguments for lower discount rate often confuse the two
Stakeholders deserve clarity: more conservative expected earnings or valuing pensions like low-risk bonds 24<br>
slide25. Links to related resources “Understanding the Valuation of Public Pension Liabilities: Expected Cost versus Market Price”
Society of Actuaries Social Insurance and Public Finance Section newsletter “In the Public Interest”, Issue 12, January 2016
https://www.soa.org/sections/social-ins-pub-fin/social-ins-pub-fin-newsletter/
Actuarial Funding Policies and Practices for Public Pension Plans
Conference of Consulting Actuaries Public Plans Community “White Paper” issued October 2014
http://www.ccactuaries.org/Portals/0/pdf/CCA_PPC_White_Paper_on_Public_Pension_Funding_Policy.pdf<br>
slide26. DISCUSSION<br>
slide27. Reference: GASB Statement 68 Basis for Conclusions, Paragraphs 227-228 on Discount Rate
227. The Board concluded that this approach, which first considers the long-term expected rate of return on pension plan investments, appropriately reflects the environment in which governmental employers incur an obligation for pensions, accumulate assets in a dedicated trust to satisfy that obligation, and ultimately discharge that obligation through the payment of benefits to retirees from accumulated, dedicated assets. Pension obligations are incurred over the career of an employee, and the employer’s relationship to the employee and the benefit obligation extends through many periods, including periods subsequent to the retirement date. In addition, governmental employers and the pension plans through which they accumulate and manage assets and provide pensions are long-lived entities. The Board believes that discounting using the long-term expected rate of return on pension plan investments, when pension plan assets are expected to be invested using a strategy to achieve that return, reflects the long-term nature of the employer’s pension liability. 27<br>
slide28. Reference: GASB Statement 68 Basis for Conclusions, Paragraphs 227-228 on Discount Rate
228. The Board believes that the approach required by this Statement—which incorporates projections of future cash inflows from pension plan investment earnings into the measurement of service cost and the total pension liability—is consistent with its views related to the projection of benefit payments, in which all reasonably anticipated future events are incorporated into the estimate of the total obligation that will be incurred by the employer over the course of an employee’s career. The amounts that are projected to be provided by pension plan investment earnings represent a reduction in the employer’s expected sacrifice of resources to satisfy the obligation for pensions. Therefore, if the potentially significant effect of pension plan investment earnings is not considered in the measurement of the pension liability, the Board believes that amounts recognized by the employer, including the employer’s cost of services associated with pensions as they are earned, potentially would be misstated and would fail to provide information appropriate for use in assessing the degree to which interperiod equity is achieved. 28<br>
slide29. Reference: GASB Statement 68 Basis for Conclusions, Paragraph 256 on Attribution Method
256. Respondents that supported the use of the unit credit or projected unit credit actuarial cost method generally believe that the application of one of those methods results in a pattern of service costs that is more consistent with the pattern in which an obligation for benefits is incurred by the employers than the service cost pattern that results from use of the entry age actuarial cost method. Some respondents also suggested that use of the entry age actuarial cost method for accounting purposes might result in measures that impede decision-making because the service cost that results in each period does not reflect the full effects of decisions with respect to salary changes in the periods in which those decisions are made. These respondents generally believe that the benefit terms themselves should be applied on a period-by-period basis to determine the amount of service cost to attribute to each period. Some respondents that supported the use of a projected unit credit approach believe that the total pension liability measure that results from application of that cost method would more closely meet the definition of a liability in Concepts Statement 4—that is, a present obligation to sacrifice resources—because that method could be defined to be applied in such a way as to more closely reflect the specific benefit accrual patterns identified in the benefit terms than would the entry age method. 29<br>
slide30. Reference: GASB Statement 68 Basis for Conclusions, Paragraph 256 on Attribution Method
256 (continued). On these points, the Board notes that the distinction between the projected unit credit method and the entry age method is a matter of degree because, as traditionally applied, both approaches incorporate expectations of future events. However, when viewed within the context of a long-term career relationship, the Board believes that a portion of any incremental value explicitly associated with future exchanges under the benefit terms implicitly is associated with past periods of service. This is because exchanges earlier in an employee’s career are necessary to have exchanges later in the employee’s career. The Board believes that the implicit value of each exchange represents a present obligation of the employer within the context of the expected career-long relationship. Consistent with this view, the Board also believes that for accounting and financial reporting purposes, the different periods of an employee’s career generally should be viewed as contributing equally to the ultimate benefits that will be provided to that employee. 30<br>
slide2. The Market Pricing Controversy Ongoing controversy on how to value pension obligations for public sector pension plans
The Level Cost Model
Discount rate: expected return on assets
Cost method: level cost based on projected benefits
Based on established funding practices
See Conference of Consulting Actuaries “White Paper” on Funding Policy
The Market Pricing Model (“MV ABO”, aka MVL, “economic value”)
Discount rate: market yields on low risk bonds (MV)
Bonds with default risk comparable to the public pension promise
Cost method: increasing cost based on accrued benefits (ABO)
Based on “financial economics” (FE)
“Understanding the Valuation of Public Pension Liabilities: Expected Cost versus Market Price”
Society of Actuaries “In the Public Interest” newsletter, Jan. 2016 2<br>
slide3. Terminology is part of the controversy Cost, liability, obligation and value: framework for discussion
First, there’s the (unquantified) concept of “cost vs benefit”
The “cost” is the hurt on the taxpayer to provide a good thing (retirement security) to the employee
Then, “Cost” is the quantified amount incurred in a period
“Liability” is the Cost accrued to date (one determines the other)
“Obligation” quantifies the promise to date (e.g., FASB’s ABO)
Depending on purpose, the Obligation value could be the Liability
If so, then the periodic Cost is the change in the Obligation
“Value” retains several meanings, both as verb and noun! 3<br>
slide4. Terminology is part of the controversy Market Pricing proponents assert that “the cost” is that determined under the market pricing model
Starts with MV ABO as liability (hence “MVL)
Then the periodic cost is ∆ MV ABO (change in MV ABO)
In contrast, the Level Cost Model reverses the order
Starts with an allocation of periodic Normal Costs (NC) with the same actuarial present value as the member’s projected benefit
Consistent with the periodic nature of the pension benefit
Then the accrued liability is ∑ NC (sum of individual NCs)
Under Actuarial Standards of Practice (ASOPs) 4 and 27, the basis for measurement of both cost and liability depends on the purpose of the measurement 4<br>
slide5. “Market Pricing” and Public Plans Most discussion has been on whether public pension plans should disclose a Market Pricing type measure
Actually three possible levels of application:
Disclosure of MV ABO
Accrued benefits at (default) risk-free discount rate
Funding based on risk-free discount rate
Even if invested in equities
Avoid intergenerational risk sharing/transfer
Investment only in bonds, not stocks
See Bader/Gold “The Case Against Stocks in Public Pension Funds”
Avoid increasing taxpayers’ equity risk exposure 5<br>
slide6. “Market Pricing” and Public Plans Recent Society of Actuaries (SOA) webcast advocating full application of financial economics to public pension plans
From SOA SI&PF Sept. 27, 2016 Webcast:
Not always clear whether funding on FE basis is advocated even if plan is NOT investing on FE basis
Our impression is they would say “yes”, plans should fund on Market Pricing model even if invested in more risky assets 6 What financial economics implies
For better public pension financial management
• Current funding: 100% of normal cost (Traditional Unit Credit, at Solvency Value)
• Legacy funding: Same, as soon as practical
• Investments: Matched to liabilities
• Financial reporting: Marking current costs, assets and liabilities at Market Value<br>
slide7. What do the ASOPs say? Final ASOPs 4 and 27 stress “purpose of the measurement”
ASOP 4: “when measuring pension obligations and determining periodic costs or contributions”
ASOP 27: “as a primary factor in selecting a discount rate”
Note “Market-Consistent Measurements” and “market value assessments” are included as a possible purpose
ASOP 4 examples: contributions, accounting, settlement, “market value assessments”
ASOP 27 examples: contributions, defeasement/settlement, “market-consistent measurements”
So Market Pricing model is not just a type of measure – it is itself a purpose of measurement 7<br>
slide8. What is the Defining Purpose of the MV ABO? Financial Economics (FE) is the economics of financial markets
Another terminology trap: “Financial” a synonym for “Market”
Also use of “value” and “worth” to mean some particular valuation result
So when FE proponents say “economic value” they mean “financial economic value” i.e., market replacement value (actual or theoretical)
To the member, the “economic value” is whatever the pension will buy!
Financial economists (FEs) develop models to understand, reproduce and predict the market pricing of traded securities
Suppose a publically traded corporation sponsors a pension plan
FEs need a value to represent the pension plan in their models
That is the sole defining purpose of the MV ABO measurement
All we know for sure about the MV ABO is that it is the appropriate representation of a Defined Benefit plan in a financial economic model of the sponsor (corporate or public) 8<br>
slide9. Brief History of Market Pricing Model for Corporate Pension Plans Originally, ERISA minimum funding was only level-cost model
IRC Sec. 412, from 1976 to 1987
Market pricing for corporate plans arrives in1987
“Current Liability” under OBRA 1987 for funding
Also “ABO” under FAS 87 for expensing
Clearly intended as a settlement measure of accrued benefits
For funding, dual regime lasts for 20 years
With RPA 1994, market pricing model starts to take over
In 2003, “the Great Controversy” (SOA Vancouver) advocated strict market pricing for corporate pension funding
Finally, PPA 2006 eliminates level cost funding for corporates
Target Liability is a strict MV ABO (discount rate relaxed in 2012)
Corporate “Pension Actuary’s Guide to FE” published 9<br>
slide10. Market focus: corporate vs public FE’s market focus is appropriate for corporations
A stock corporation exists solely to maximize its stock’s market price
Everything, including its pensions, must be considered as reducible to a market derived value and managed based on that market value.
Public sector linkage to the market is less direct
Agencies and pension plans participate in the markets
The purpose of public agencies and pension plans cannot be reduced to a single market defined measure
Corporations are “of” the market, while public agencies and plans are only “in” the market.
FE principles do not incorporate this difference
FE conclusions provide information about all stock corporations, not about all pension plans 10<br>
slide11. Evaluating the Market Pricing Model as a Basis for Funding Public Pension Plans Consider what it means to use the Market Pricing model to measure the ongoing cost of a pension plan
Focus on funding but discussion also applies to disclosure
Start with the cost allocation method: Traditional Unit Credit (TUC)
Accrued Liability = PV of accrued benefits (MV ABO)
Normal Cost = Change in PV of accrued benefits (∆ MV ABO)
Well known flaws in TUC/PVAB/ABO method for allocating costs
Back-loaded cost allocation, sharply increasing individual normal costs
Cost spikes at eligibility for retirement
Demographically unstable aggregate normal cost
Even for corporate plans, TUC was illegal for final pay plans
Except as a settlement value 11<br>
slide12. Normal Cost as a Percentage of Pay<br>
slide13. Evaluating Market Pricing: TUC/ABO Cost Method Under FE theory, the pension plan is a transfer of wealth
Amount of annual wealth transfer is ∆ MV ABO
∆ MV ABO is part of members annual compensation
For a career participant in later years of service, this ∆ MV ABO (i.e., TUC Normal Cost) should be the employees entire incremental compensation – so no pay increases (or even pay)
Source: GASB Financial Reporting Task Force, December 2, 2009
This untenable conclusion led GASB to adopt the Level Cost model (Entry Age method) for financial reporting
See GASB Statement 68 “Basis of Conclusions”, §256 on cost allocation
The policy objective of an equitable cost allocation over a career requires a more sophisticated model than simple benefit accrual 13<br>
slide14. Evaluating Market Pricing: “Risk Free” Discount Rate Overcharges current taxpayers and members on an expected value basis (assuming plan NOT invested on FE basis)
Violates intergenerational equity
Member rates never reflect equity returns, even when realized
Excludes expected savings from intergenerational risk sharing
This led GASB to adopt the Level Cost model (expected return discount rate) for financial reporting
See GASB Statement 68, §§227-228 on discount rate
The policy objective of an equitable cost allocation over generations requires a more sophisticated model than simply observing bond yields 14<br>
slide15. What About the Equity Risk? Intergenerational risk sharing or pooling does entail the risk of intergenerational transfers of gains or losses
FE looks only at risk of shifting losses forward
Risks and advantages are shared by all generations
Taxpayers assign equity investing role to public plans
E.g., California 1966 (25% equities), 1984 (“prudent man” rule)
FE replaces risk management with risk aversion
This comes at a high price to the taxpayers
FE does not balance the costs and benefits of accepting that risk across generations 15<br>
slide16. Equity Investment for Retirement Plans FE principles conclude pension plans should not invest in equities.
Match riskiness of assets to (low) riskiness of benefit promise
Avoid increasing taxpayer/shareholder equity risk exposure
Equity investing OK for individual retirement planning
How should the retirement function participate in the economy?
As an owner (through equities) or only as a lender (through bonds)
Answer: as an owner, whether individually or collectively
E.g., California 1966 (25% equities), 1984 (“prudent man” rule)
Public pension plans allow pooling of risk, both demographic and economic
Provides a more economically efficient vehicle for converting taxpayer dollars into retirement security for public employees 16<br>
slide17. Limitations of Financial Economic Principles For public agencies there are relevant principles, objectives and policy considerations beyond those reflected in the FE model
They lead to a level cost allocation method and an expected return discount rate, both for funding and financial reporting
For example, see GASB Statement 68 “Basis of Conclusions”
Paragraph 256 on cost allocation
Paragraphs 227-228 on discount rate
Similarly, for funding see CCA PPC Funding Policies and Practices “White Paper”
Balance between demographic matching and volatility management
The financial economic model and its MV ABO measure are insufficient to represent the more complicated policy objectives of public pension plans 17<br>
slide18. Limitations of Financial Economic Principles FE principles were developed for the purpose of determining a value consistent with the financial economic model
Those principles lead to MV ABO as the appropriate measure
FE proponents then assert these principles are appropriate and sufficient for other purposes, i.e., funding a public pension plan
Fails to acknowledge the limitations of their defining purpose
FE proponents show that FE principles lead to MV ABO as appropriate measure for public pension plans, including disclosure, funding and investing
That is because market economic principles always lead to a market pricing measure 18<br>
slide19. Report of the Actuarial Standards Board’s Pension Task Force (PTF) -- Feb. 29, 2016 PTF believes that a “market-based alternative liability measurement” should be calculated and disclosed for all valuations of pension plans for funding purposes, because:
It may be misleading to show traditional values by themselves.
Market-based alternative liability provides a reasonable measure of the cost of reducing the risk that the traditional measurement will be insufficient for the underlying obligation
Provides important information about risk.
Encourage better decisions regarding the financing of the plan.
Will help advance the actuarial profession.
Not implying that such a measure is “the one true answer”
Would show an important alternative view of pension finance 19<br>
slide20. ASB Pension Task Force “Suggestions” The PTF suggests that an alternative liability measure based on “solvency value” be calculated and disclosed for all valuations of pension plans done for funding purposes.
Estimate of the cost to defease all liabilities accrued under the plan in the marketplace, presuming that capacity is available
Assets needed to fully secure promises to members
Understanding of risks to members’ benefits
Information about the amount of investment risk being taken
An acceptable proxy for this measurement would be
Present value of accrued benefits (i.e., unit credit method)
U.S. Treasury rates as discount rate
other assumptions according to ASOP Nos. 27 and 35.
Avoid the term “market value of liabilities”! 20<br>
slide21. Defeasement/settlement value as measure of risk Terminology: common meaning of “solvency” is not the same as what it means within FE theory
So a better term is “defeasement” or “settlement” value
ASB PTF says disclosure of a market-based liability measurement:
provides a measure of the cost of reducing the risk that the traditional actuarial liability measurement will be insufficient collateral for the underlying obligation,
provides information about the amount of investment risk being taken by the plan. In particular, it can show the amount of investment income in excess of that provided by low-risk investments that the principal expects to receive
But settlement value does not measure the possible consequences of investment risk, only the cost to eliminate that risk
Quantifies risk aversion, not risk management 21<br>
slide22. Risk of Misuse of Market Pricing Disclosure Market pricing proponents have a well-established practice of describing MV ABO as the only true measure of pension cost
Proponents of other measures are either ignorant or deceitful
One recent example: David Crane, “It’s the Lie That Gets You” [medium.com, March 4, 2017] 22 Notice how CalPERS is choosing to value liabilities at the same rate as it expects to earn on assets. …
As Nixon said, it’s the lie that gets you. CalPERS’s lies harm citizens.
By linking discount rates to investment return assumptions, CalPERS and its sister pension fund, CalSTRS, are being untruthful. The lies get exposed when citizens get hit with pension deficits.<br>
slide23. Actuarial Code of Conduct – Precept 8 PRECEPT 8. An Actuary who performs Actuarial Services shall take reasonable steps to ensure that such services are not used to mislead other parties.
ANNOTATION 8-1. An Actuarial Communication prepared by an Actuary may be used by another party in a way that may influence the actions of a third party. The Actuary should recognize the risks of misquotation, misinterpretation, or other misuse of the Actuarial Communication and should therefore take reasonable steps to present the Actuarial Communication clearly and fairly and to include, as appropriate, limitations on the distribution and utilization of the Actuarial Communication.
What if no amount of clearly presented “limitations on utilization” will prevent the Solvency Value from being (mis)interpreted to other parties as the “true cost” of the benefit? 23<br>
slide24. Summary comment on lower discount rates for public pension valuations Two very different arguments for lowering the discount rate
Market Pricing Model: discount rate should be based on current (very low) “risk-free” interest rates
Independent of asset allocation or expected return on assets!
Based on financial economics and “market pricing” model
Level Cost Model: discount rate should be based on a lower expected return on assets
Still based on asset allocation and “level cost” model, but less optimistic
Reflects lower inflation expectations, lower bond returns, etc.
This is an essential part of any review of assumptions
Arguments for lower discount rate often confuse the two
Stakeholders deserve clarity: more conservative expected earnings or valuing pensions like low-risk bonds 24<br>
slide25. Links to related resources “Understanding the Valuation of Public Pension Liabilities: Expected Cost versus Market Price”
Society of Actuaries Social Insurance and Public Finance Section newsletter “In the Public Interest”, Issue 12, January 2016
https://www.soa.org/sections/social-ins-pub-fin/social-ins-pub-fin-newsletter/
Actuarial Funding Policies and Practices for Public Pension Plans
Conference of Consulting Actuaries Public Plans Community “White Paper” issued October 2014
http://www.ccactuaries.org/Portals/0/pdf/CCA_PPC_White_Paper_on_Public_Pension_Funding_Policy.pdf<br>
slide26. DISCUSSION<br>
slide27. Reference: GASB Statement 68 Basis for Conclusions, Paragraphs 227-228 on Discount Rate
227. The Board concluded that this approach, which first considers the long-term expected rate of return on pension plan investments, appropriately reflects the environment in which governmental employers incur an obligation for pensions, accumulate assets in a dedicated trust to satisfy that obligation, and ultimately discharge that obligation through the payment of benefits to retirees from accumulated, dedicated assets. Pension obligations are incurred over the career of an employee, and the employer’s relationship to the employee and the benefit obligation extends through many periods, including periods subsequent to the retirement date. In addition, governmental employers and the pension plans through which they accumulate and manage assets and provide pensions are long-lived entities. The Board believes that discounting using the long-term expected rate of return on pension plan investments, when pension plan assets are expected to be invested using a strategy to achieve that return, reflects the long-term nature of the employer’s pension liability. 27<br>
slide28. Reference: GASB Statement 68 Basis for Conclusions, Paragraphs 227-228 on Discount Rate
228. The Board believes that the approach required by this Statement—which incorporates projections of future cash inflows from pension plan investment earnings into the measurement of service cost and the total pension liability—is consistent with its views related to the projection of benefit payments, in which all reasonably anticipated future events are incorporated into the estimate of the total obligation that will be incurred by the employer over the course of an employee’s career. The amounts that are projected to be provided by pension plan investment earnings represent a reduction in the employer’s expected sacrifice of resources to satisfy the obligation for pensions. Therefore, if the potentially significant effect of pension plan investment earnings is not considered in the measurement of the pension liability, the Board believes that amounts recognized by the employer, including the employer’s cost of services associated with pensions as they are earned, potentially would be misstated and would fail to provide information appropriate for use in assessing the degree to which interperiod equity is achieved. 28<br>
slide29. Reference: GASB Statement 68 Basis for Conclusions, Paragraph 256 on Attribution Method
256. Respondents that supported the use of the unit credit or projected unit credit actuarial cost method generally believe that the application of one of those methods results in a pattern of service costs that is more consistent with the pattern in which an obligation for benefits is incurred by the employers than the service cost pattern that results from use of the entry age actuarial cost method. Some respondents also suggested that use of the entry age actuarial cost method for accounting purposes might result in measures that impede decision-making because the service cost that results in each period does not reflect the full effects of decisions with respect to salary changes in the periods in which those decisions are made. These respondents generally believe that the benefit terms themselves should be applied on a period-by-period basis to determine the amount of service cost to attribute to each period. Some respondents that supported the use of a projected unit credit approach believe that the total pension liability measure that results from application of that cost method would more closely meet the definition of a liability in Concepts Statement 4—that is, a present obligation to sacrifice resources—because that method could be defined to be applied in such a way as to more closely reflect the specific benefit accrual patterns identified in the benefit terms than would the entry age method. 29<br>
slide30. Reference: GASB Statement 68 Basis for Conclusions, Paragraph 256 on Attribution Method
256 (continued). On these points, the Board notes that the distinction between the projected unit credit method and the entry age method is a matter of degree because, as traditionally applied, both approaches incorporate expectations of future events. However, when viewed within the context of a long-term career relationship, the Board believes that a portion of any incremental value explicitly associated with future exchanges under the benefit terms implicitly is associated with past periods of service. This is because exchanges earlier in an employee’s career are necessary to have exchanges later in the employee’s career. The Board believes that the implicit value of each exchange represents a present obligation of the employer within the context of the expected career-long relationship. Consistent with this view, the Board also believes that for accounting and financial reporting purposes, the different periods of an employee’s career generally should be viewed as contributing equally to the ultimate benefits that will be provided to that employee. 30<br>