
Options, Futures, and Other Derivatives 6th

Description: Options, Futures, and Other Derivatives 6th Edition, Copyright John C. Hull 2005 6.1 Interest Rate Futures Chapter 6 Options, Futures, and Other Derivatives 6th Edition, Copyright John C. Hull 2005 6.2 Day Count Conventions in the U.S.
Related Topics
Download Presentation
"Options, Futures, and Other Derivatives 6th" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.1 Interest Rate Futures Chapter 6<br>
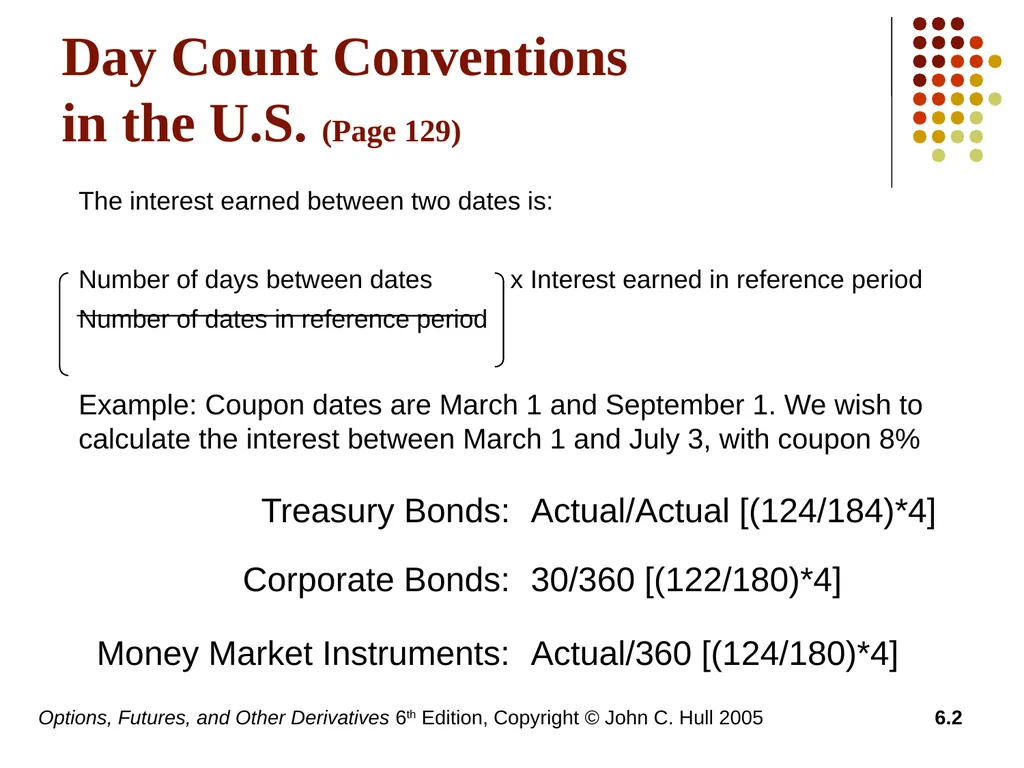
slide2. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.2 Day Count Conventions in the U.S. (Page 129) The interest earned between two dates is:
Number of days between dates x Interest earned in reference period
Number of dates in reference period
Example: Coupon dates are March 1 and September 1. We wish to calculate the interest between March 1 and July 3, with coupon 8%<br>
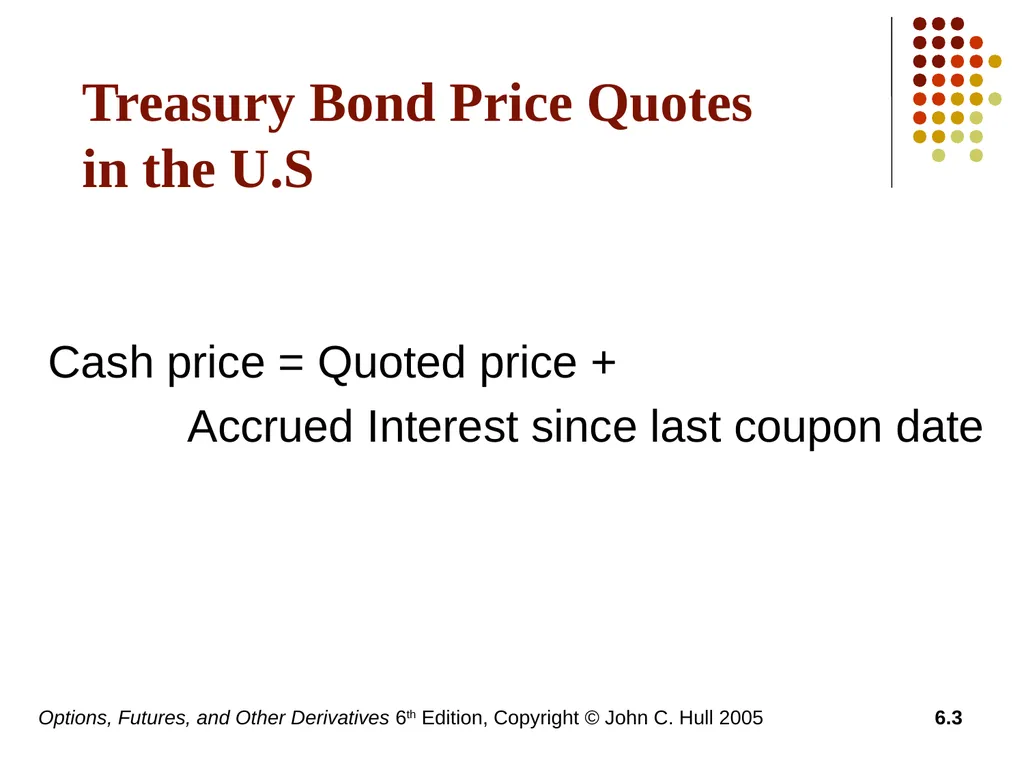
slide3. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.3 Treasury Bond Price Quotes in the U.S Cash price = Quoted price +
Accrued Interest since last coupon date<br>
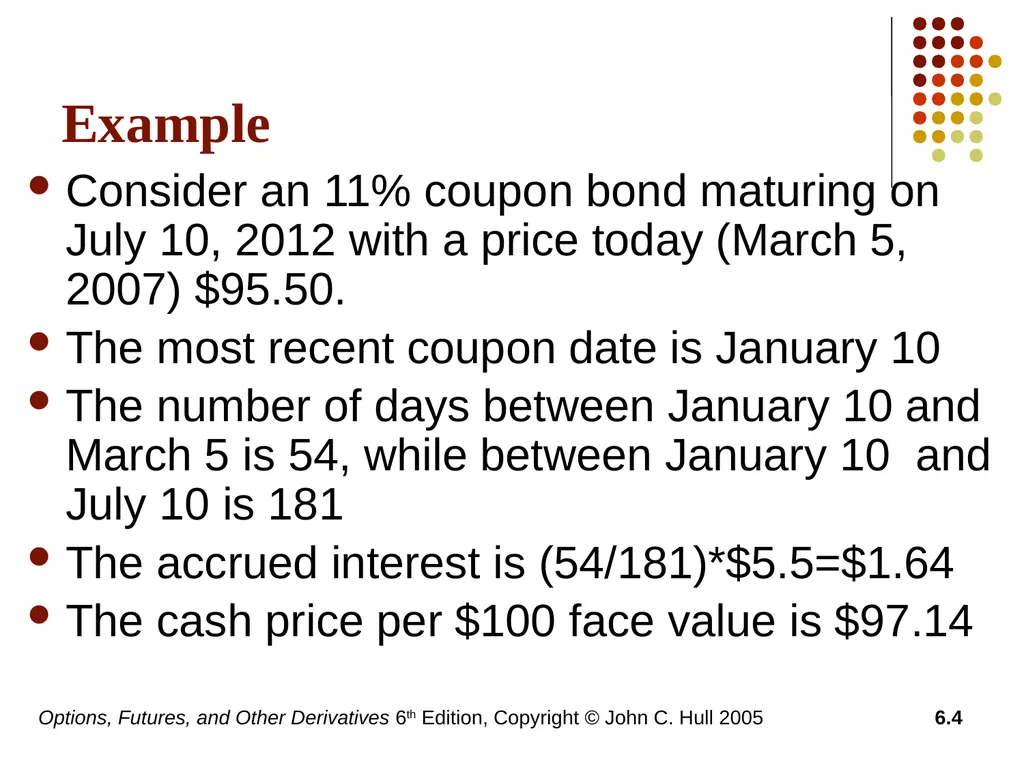
slide4. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.4 Example Consider an 11% coupon bond maturing on July 10, 2012 with a price today (March 5, 2007) $95.50.
The most recent coupon date is January 10
The number of days between January 10 and March 5 is 54, while between January 10 and July 10 is 181
The accrued interest is (54/181)*$5.5=$1.64
The cash price per $100 face value is $97.14<br>
slide5. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.5 Treasury Bond Futures Pages 133-137 The delivery is any government bond with more than 15 years to maturity, which is not callable within 15 years
Cash price received by party with short position =
Most Recent Settlement Price × Conversion factor + Accrued interest<br>
slide6. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.6 Example Settlement price of bond delivered = 90.00
Conversion factor = 1.3800
Accrued interest on bond =3.00
Price received for bond is (1.3800×90.00)+3.00 = $127.20
per $100 of principal
The party with the short position in one contract would deliver bonds with a face value of $100.000 and receive $127.20.<br>
slide7. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.7 Conversion Factor The conversion factor for a bond is approximately equal to the value of the bond on the assumption that the yield curve is flat at 6% with semiannual compounding<br>
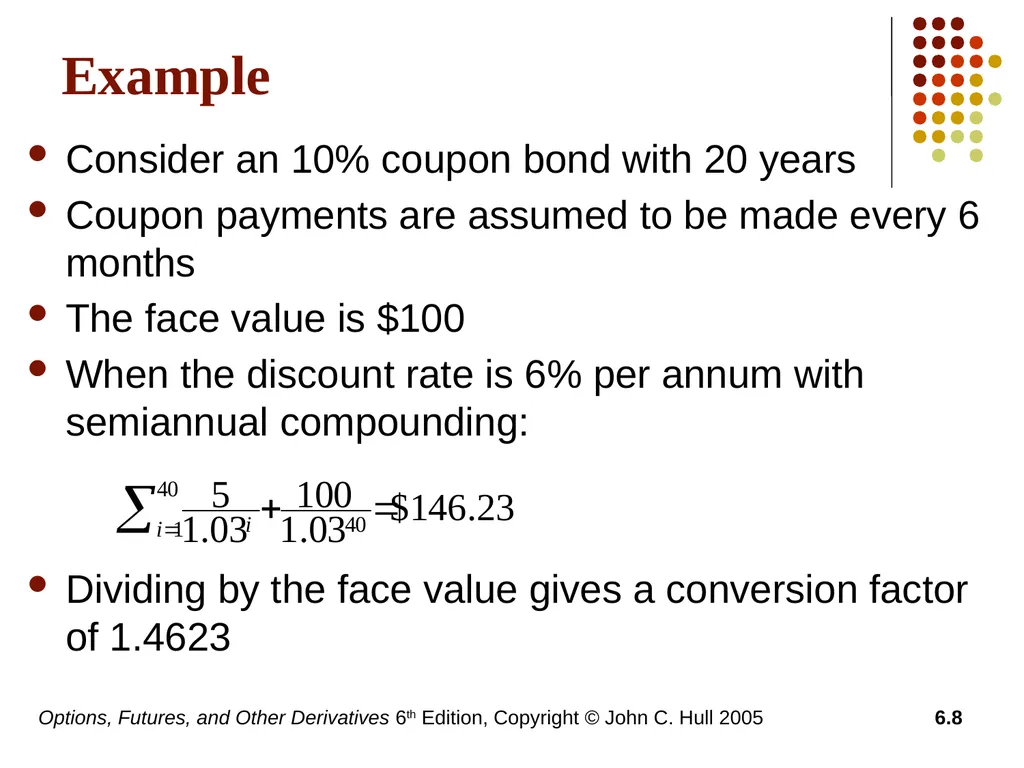
slide8. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.8 Example Consider an 10% coupon bond with 20 years
Coupon payments are assumed to be made every 6 months
The face value is $100
When the discount rate is 6% per annum with semiannual compounding:
Dividing by the face value gives a conversion factor of 1.4623<br>
slide9. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.9 Cheapest-to-deliver bond Any of a range of eligible bonds can be delivered
The party with the short position receives:
Settlement Price × Conversion factor + Accrued interest
The cost of purchasing a bond is
Quoted bond price+Accrued Interest
The cheapest-to-deliver bond is the one for which
Quoted bond price-(Settlement Price × Conversion factor) is least.<br>
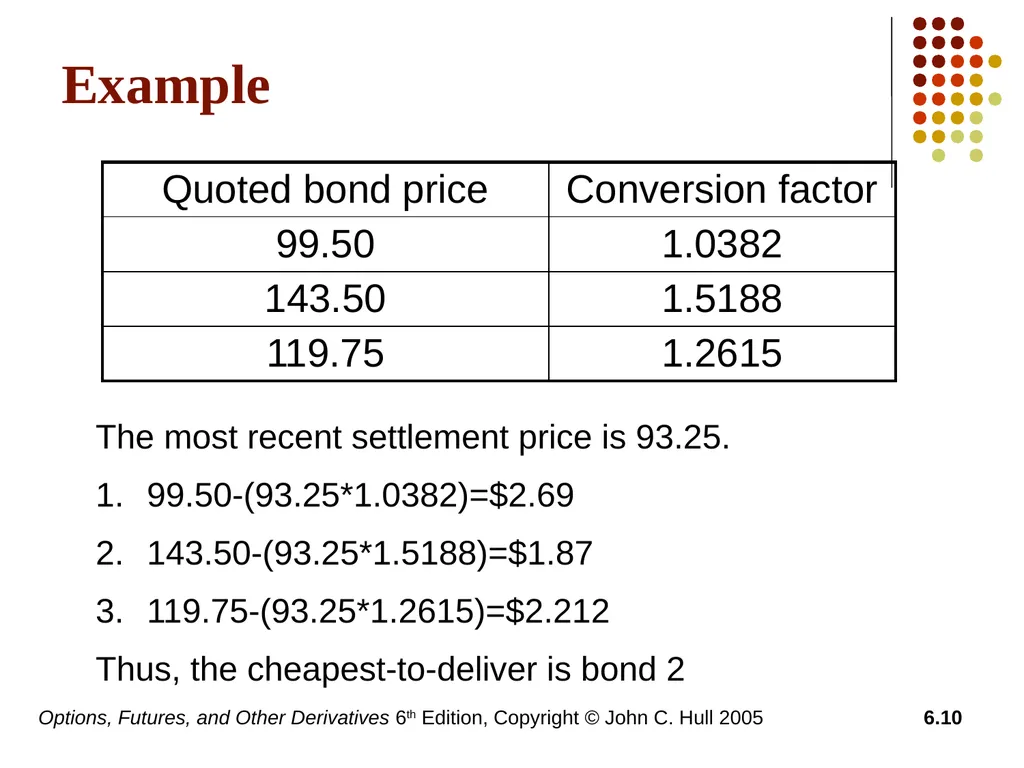
slide10. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.10 Example The most recent settlement price is 93.25.
99.50-(93.25*1.0382)=$2.69
143.50-(93.25*1.5188)=$1.87
119.75-(93.25*1.2615)=$2.212
Thus, the cheapest-to-deliver is bond 2<br>
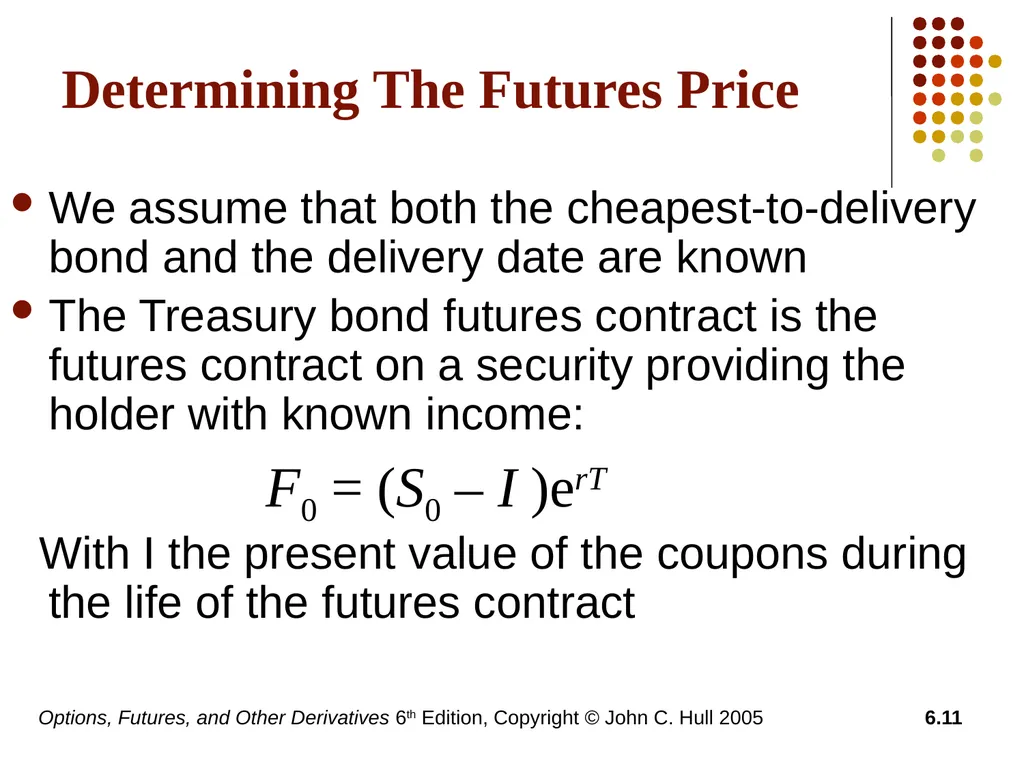
slide11. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.11 Determining The Futures Price We assume that both the cheapest-to-delivery bond and the delivery date are known
The Treasury bond futures contract is the futures contract on a security providing the holder with known income:
F0 = (S0 – I )erT
With I the present value of the coupons during the life of the futures contract<br>
slide12. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.12 Example The cheapest-to-deliver is a 12% coupon bond with a conversion factor of 1.400
The delivery will take place in 270 days.
Last coupon date was 60 days ago
Next coupon date is in 122 days, and the coupon date thereafter is in 35 days
The term structure is flat, the interest rate is 10%
The current quoted bond price is $120<br>
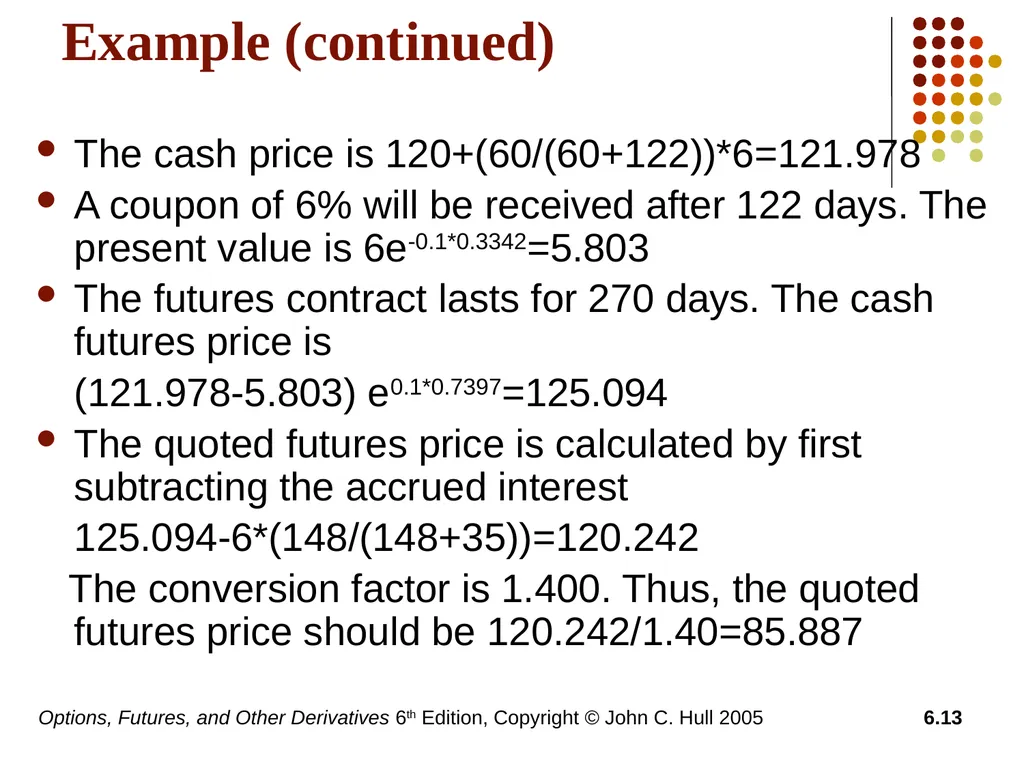
slide13. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.13 Example (continued) The cash price is 120+(60/(60+122))*6=121.978
A coupon of 6% will be received after 122 days. The present value is 6e-0.1*0.3342=5.803
The futures contract lasts for 270 days. The cash futures price is
(121.978-5.803) e0.1*0.7397=125.094
The quoted futures price is calculated by first subtracting the accrued interest
125.094-6*(148/(148+35))=120.242
The conversion factor is 1.400. Thus, the quoted futures price should be 120.242/1.40=85.887<br>
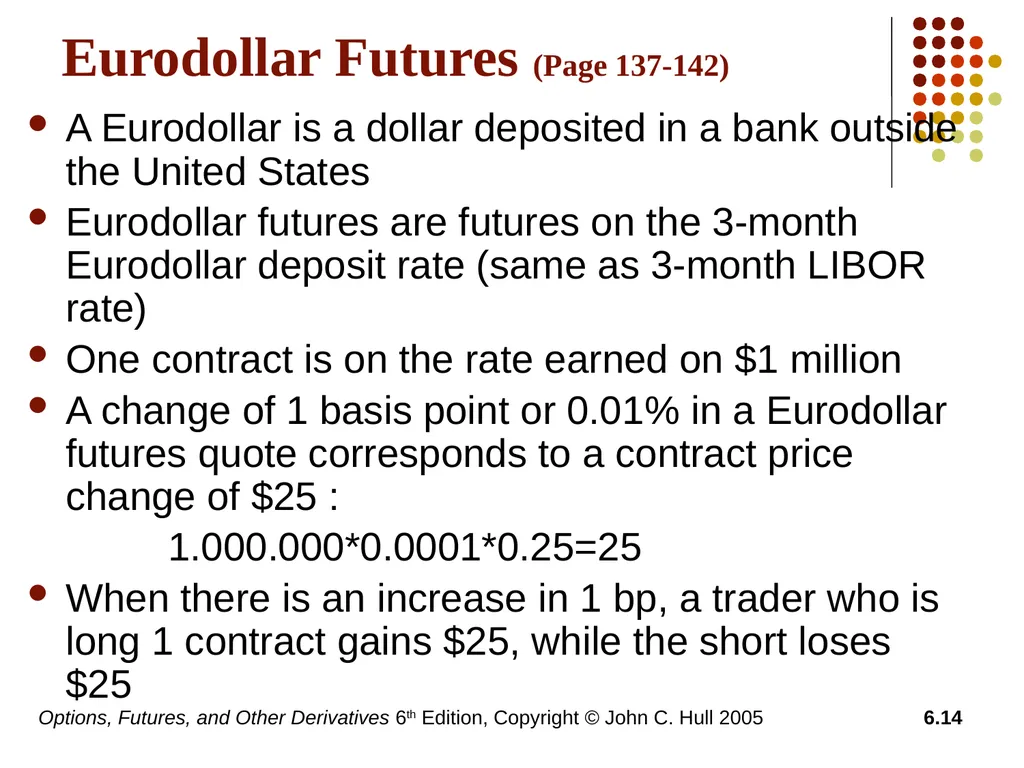
slide14. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.14 A Eurodollar is a dollar deposited in a bank outside the United States
Eurodollar futures are futures on the 3-month Eurodollar deposit rate (same as 3-month LIBOR rate)
One contract is on the rate earned on $1 million
A change of 1 basis point or 0.01% in a Eurodollar futures quote corresponds to a contract price change of $25 :
1.000.000*0.0001*0.25=25
When there is an increase in 1 bp, a trader who is long 1 contract gains $25, while the short loses $25 Eurodollar Futures (Page 137-142)<br>
slide15. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.15 Eurodollar Futures continued A Eurodollar futures contract is settled in cash
When it expires (on the third Wednesday of the delivery month) the final settlement price is 100 minus the actual three month deposit rate:
100 - R<br>
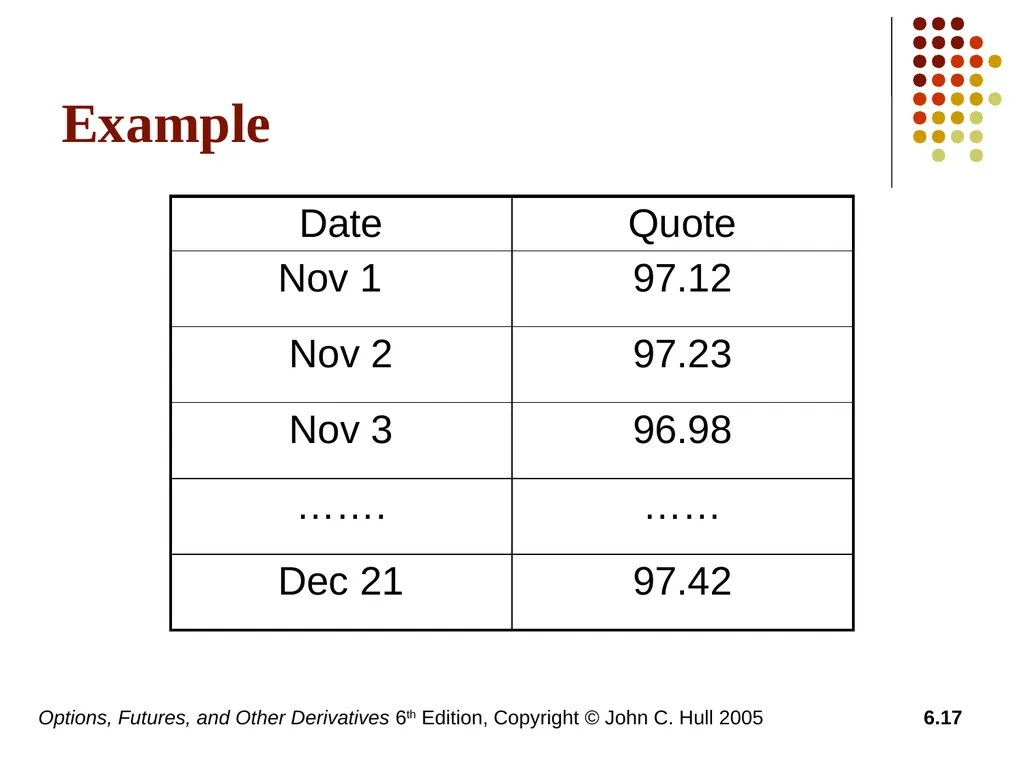
slide16. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.16 Example Suppose you buy (take a long position in) a contract on November 1
The contract expires on December 21
The prices are as shown
How much do you gain or lose a) on the first day, b) on the second day, c) over the whole time until expiration?<br>
slide17. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.17 Example<br>
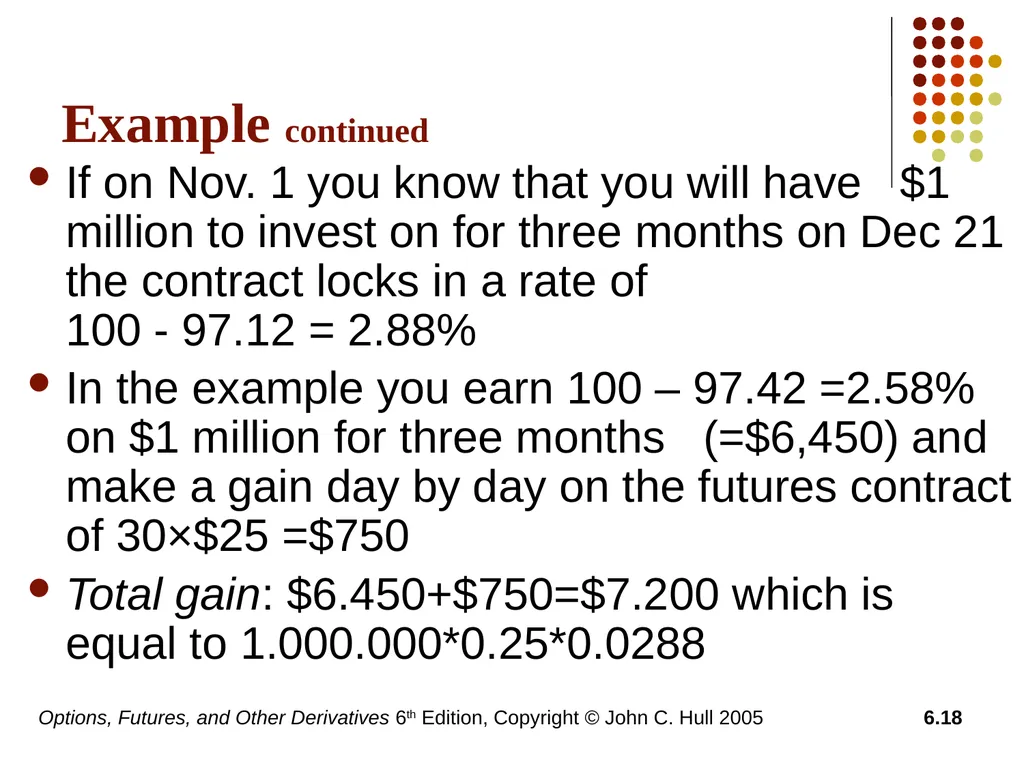
slide18. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.18 Example continued If on Nov. 1 you know that you will have $1 million to invest on for three months on Dec 21 the contract locks in a rate of 100 - 97.12 = 2.88%
In the example you earn 100 – 97.42 =2.58% on $1 million for three months (=$6,450) and make a gain day by day on the futures contract of 30×$25 =$750
Total gain: $6.450+$750=$7.200 which is equal to 1.000.000*0.25*0.0288<br>
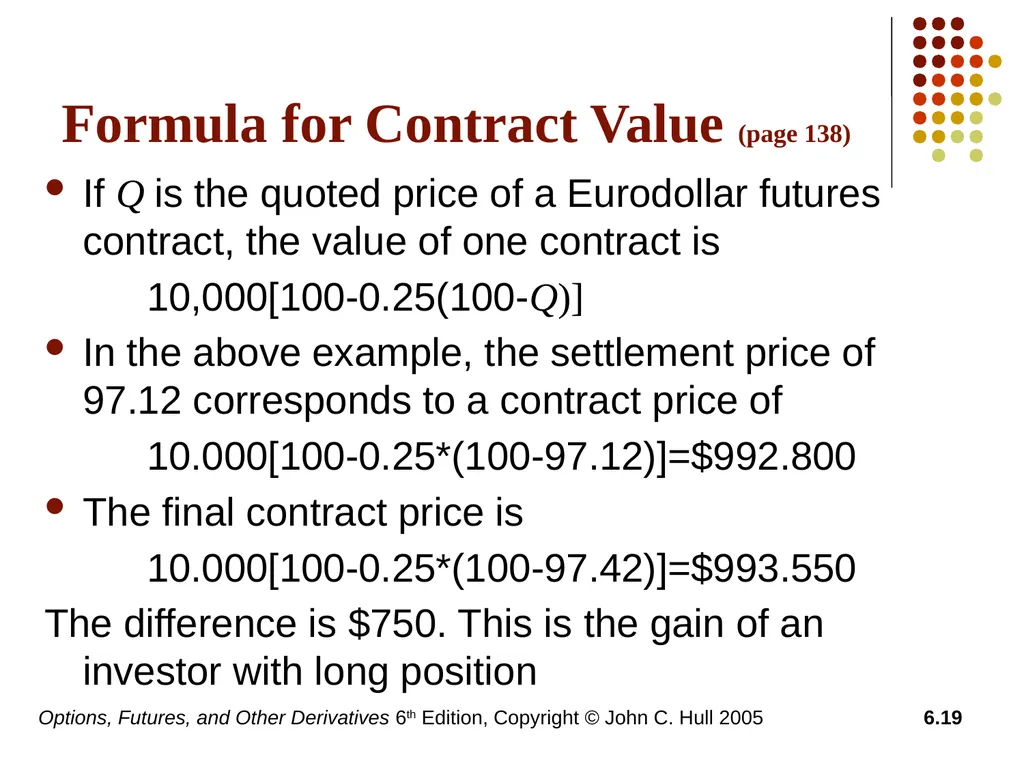
slide19. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.19 Formula for Contract Value (page 138) If Q is the quoted price of a Eurodollar futures contract, the value of one contract is
10,000[100-0.25(100-Q)]
In the above example, the settlement price of 97.12 corresponds to a contract price of
10.000[100-0.25*(100-97.12)]=$992.800
The final contract price is
10.000[100-0.25*(100-97.42)]=$993.550
The difference is $750. This is the gain of an investor with long position<br>
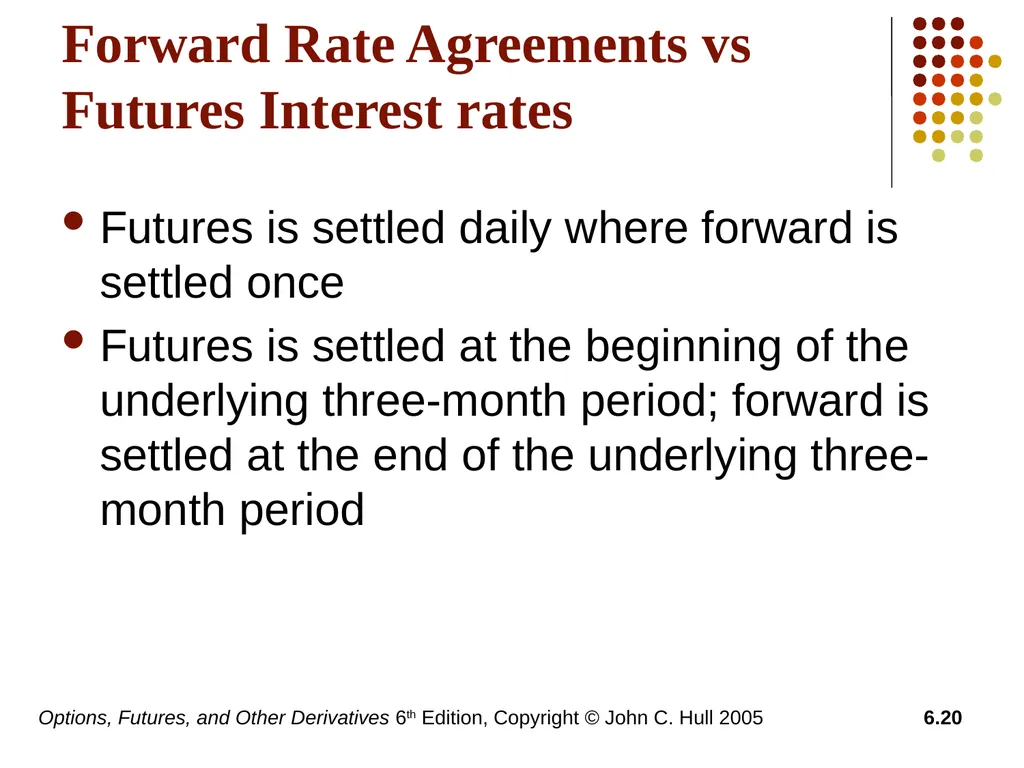
slide20. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.20 Forward Rate Agreements vs Futures Interest rates Futures is settled daily where forward is settled once
Futures is settled at the beginning of the underlying three-month period; forward is settled at the end of the underlying three- month period<br>
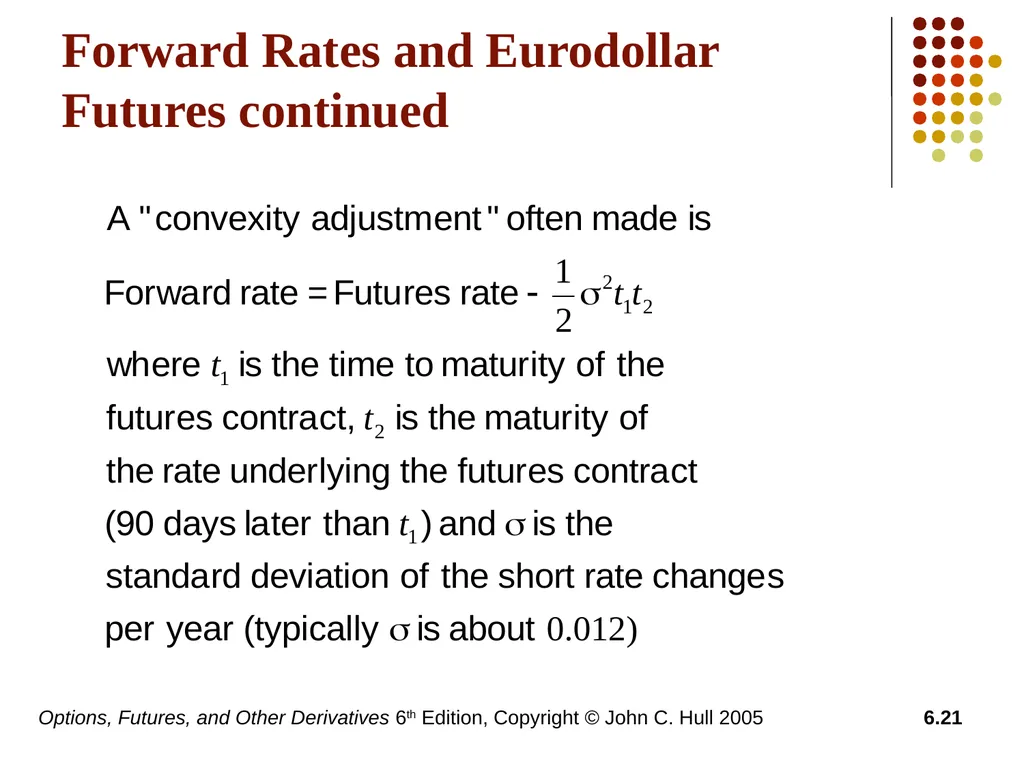
slide21. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.21 Forward Rates and Eurodollar Futures continued<br>
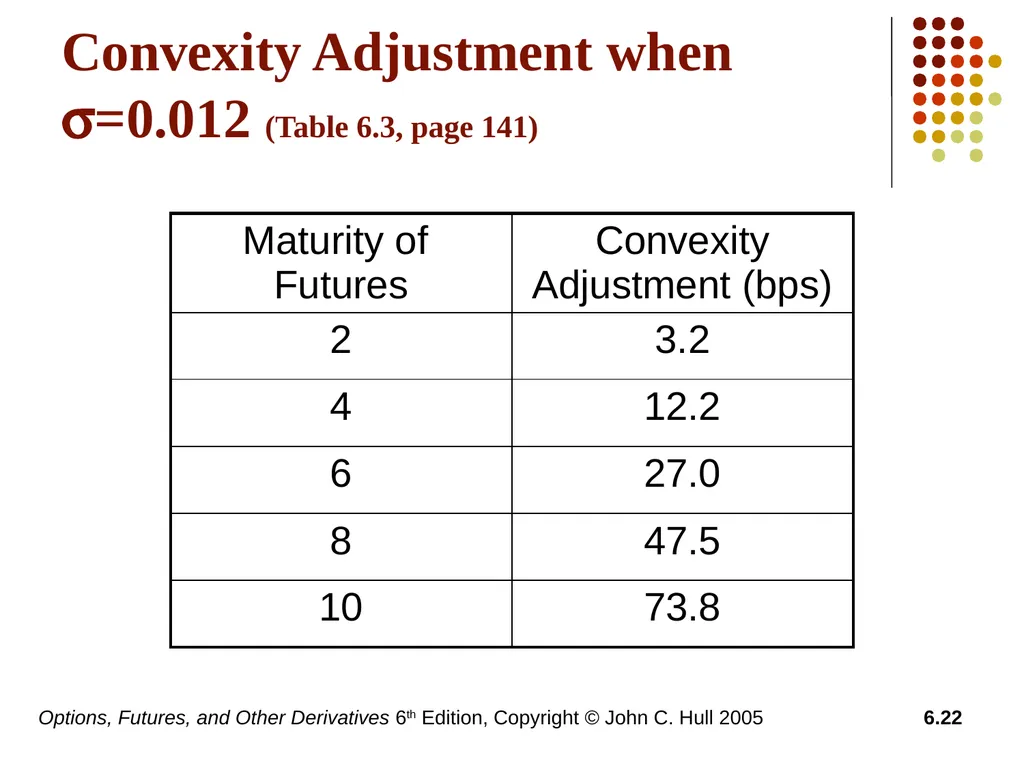
slide22. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.22 Convexity Adjustment when s=0.012 (Table 6.3, page 141)<br>
slide23. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.23 Extending the LIBOR Zero Curve LIBOR deposit rates define the LIBOR zero curve out to one year
Eurodollar futures can be used to determine forward rates (using the convexity adjustment) and the forward rates can then be used to bootstrap the zero curve<br>
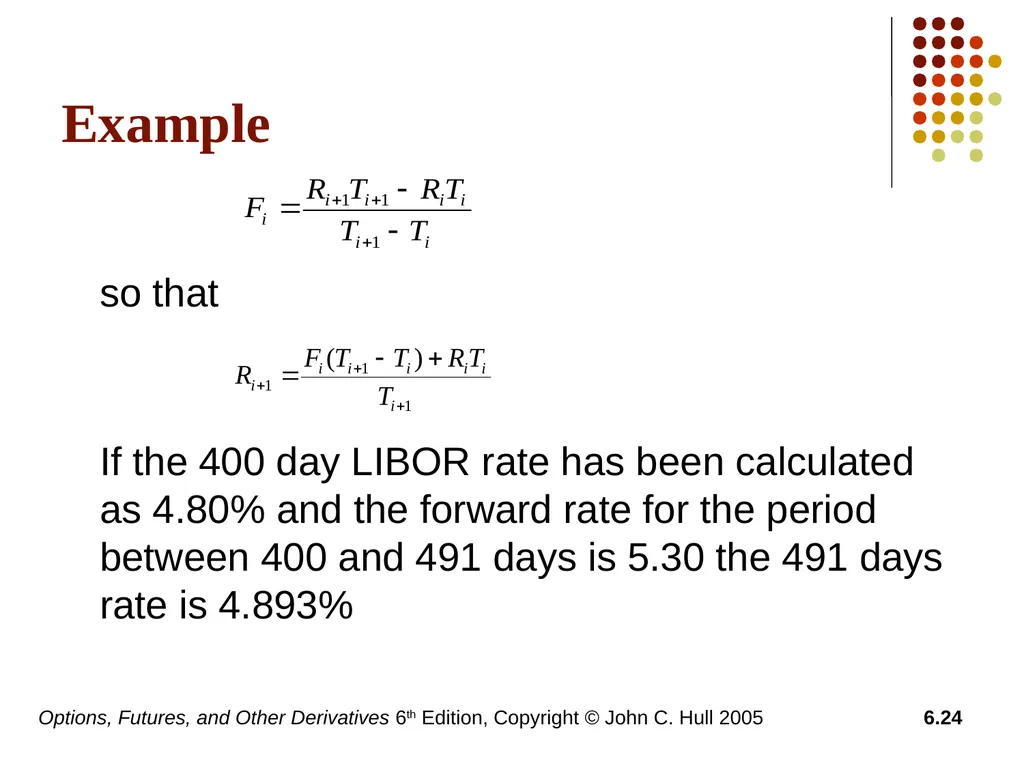
slide24. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.24 Example so that
If the 400 day LIBOR rate has been calculated as 4.80% and the forward rate for the period between 400 and 491 days is 5.30 the 491 days rate is 4.893%<br>
slide25. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.25 Duration Matching This involves hedging against interest rate risk by matching the durations of assets and liabilities
It provides protection against small parallel shifts in the zero curve<br>
slide26. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.26 Use of Eurodollar Futures One contract locks in an interest rate on $1 million for a future 3-month period
How many contracts are necessary to lock in an interest rate for a future six month period?<br>
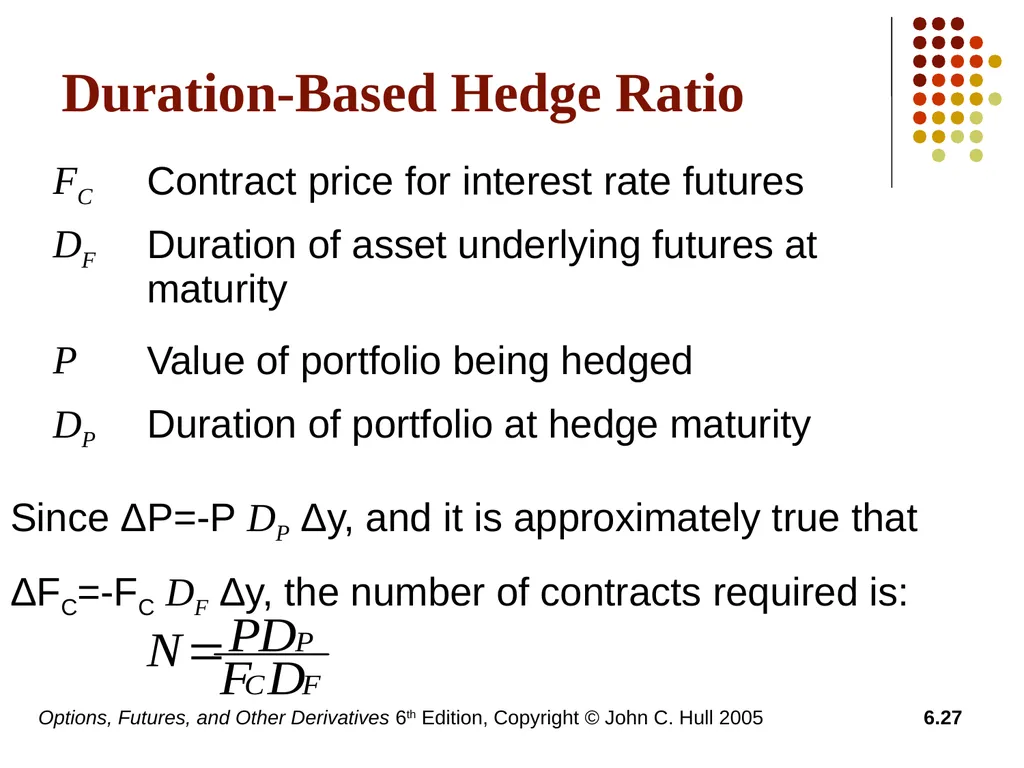
slide27. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.27 Duration-Based Hedge Ratio Since ΔP=-P DP Δy, and it is approximately true that
ΔFC=-FC DF Δy, the number of contracts required is:<br>
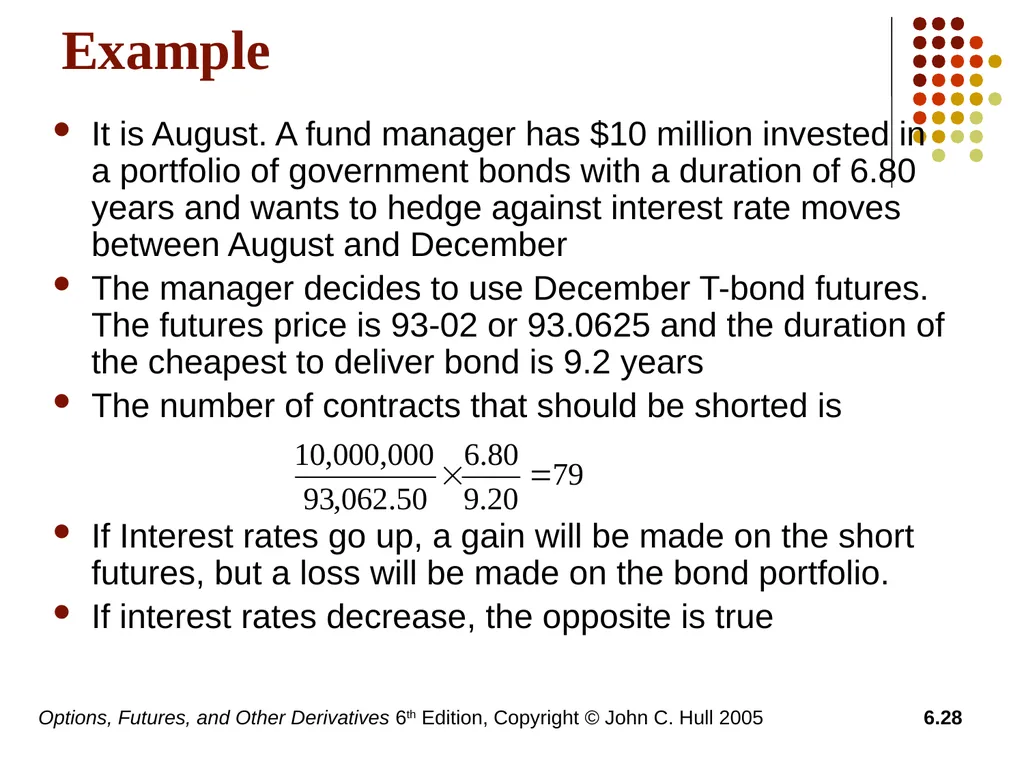
slide28. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.28 Example It is August. A fund manager has $10 million invested in a portfolio of government bonds with a duration of 6.80 years and wants to hedge against interest rate moves between August and December
The manager decides to use December T-bond futures. The futures price is 93-02 or 93.0625 and the duration of the cheapest to deliver bond is 9.2 years
The number of contracts that should be shorted is
If Interest rates go up, a gain will be made on the short futures, but a loss will be made on the bond portfolio.
If interest rates decrease, the opposite is true<br>
slide29. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.29 Limitations of Duration-Based Hedging Assumes that only parallel shift in yield curve take place
Assumes that yield curve changes are small<br>
slide2. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.2 Day Count Conventions in the U.S. (Page 129) The interest earned between two dates is:
Number of days between dates x Interest earned in reference period
Number of dates in reference period
Example: Coupon dates are March 1 and September 1. We wish to calculate the interest between March 1 and July 3, with coupon 8%<br>
slide3. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.3 Treasury Bond Price Quotes in the U.S Cash price = Quoted price +
Accrued Interest since last coupon date<br>
slide4. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.4 Example Consider an 11% coupon bond maturing on July 10, 2012 with a price today (March 5, 2007) $95.50.
The most recent coupon date is January 10
The number of days between January 10 and March 5 is 54, while between January 10 and July 10 is 181
The accrued interest is (54/181)*$5.5=$1.64
The cash price per $100 face value is $97.14<br>
slide5. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.5 Treasury Bond Futures Pages 133-137 The delivery is any government bond with more than 15 years to maturity, which is not callable within 15 years
Cash price received by party with short position =
Most Recent Settlement Price × Conversion factor + Accrued interest<br>
slide6. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.6 Example Settlement price of bond delivered = 90.00
Conversion factor = 1.3800
Accrued interest on bond =3.00
Price received for bond is (1.3800×90.00)+3.00 = $127.20
per $100 of principal
The party with the short position in one contract would deliver bonds with a face value of $100.000 and receive $127.20.<br>
slide7. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.7 Conversion Factor The conversion factor for a bond is approximately equal to the value of the bond on the assumption that the yield curve is flat at 6% with semiannual compounding<br>
slide8. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.8 Example Consider an 10% coupon bond with 20 years
Coupon payments are assumed to be made every 6 months
The face value is $100
When the discount rate is 6% per annum with semiannual compounding:
Dividing by the face value gives a conversion factor of 1.4623<br>
slide9. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.9 Cheapest-to-deliver bond Any of a range of eligible bonds can be delivered
The party with the short position receives:
Settlement Price × Conversion factor + Accrued interest
The cost of purchasing a bond is
Quoted bond price+Accrued Interest
The cheapest-to-deliver bond is the one for which
Quoted bond price-(Settlement Price × Conversion factor) is least.<br>
slide10. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.10 Example The most recent settlement price is 93.25.
99.50-(93.25*1.0382)=$2.69
143.50-(93.25*1.5188)=$1.87
119.75-(93.25*1.2615)=$2.212
Thus, the cheapest-to-deliver is bond 2<br>
slide11. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.11 Determining The Futures Price We assume that both the cheapest-to-delivery bond and the delivery date are known
The Treasury bond futures contract is the futures contract on a security providing the holder with known income:
F0 = (S0 – I )erT
With I the present value of the coupons during the life of the futures contract<br>
slide12. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.12 Example The cheapest-to-deliver is a 12% coupon bond with a conversion factor of 1.400
The delivery will take place in 270 days.
Last coupon date was 60 days ago
Next coupon date is in 122 days, and the coupon date thereafter is in 35 days
The term structure is flat, the interest rate is 10%
The current quoted bond price is $120<br>
slide13. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.13 Example (continued) The cash price is 120+(60/(60+122))*6=121.978
A coupon of 6% will be received after 122 days. The present value is 6e-0.1*0.3342=5.803
The futures contract lasts for 270 days. The cash futures price is
(121.978-5.803) e0.1*0.7397=125.094
The quoted futures price is calculated by first subtracting the accrued interest
125.094-6*(148/(148+35))=120.242
The conversion factor is 1.400. Thus, the quoted futures price should be 120.242/1.40=85.887<br>
slide14. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.14 A Eurodollar is a dollar deposited in a bank outside the United States
Eurodollar futures are futures on the 3-month Eurodollar deposit rate (same as 3-month LIBOR rate)
One contract is on the rate earned on $1 million
A change of 1 basis point or 0.01% in a Eurodollar futures quote corresponds to a contract price change of $25 :
1.000.000*0.0001*0.25=25
When there is an increase in 1 bp, a trader who is long 1 contract gains $25, while the short loses $25 Eurodollar Futures (Page 137-142)<br>
slide15. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.15 Eurodollar Futures continued A Eurodollar futures contract is settled in cash
When it expires (on the third Wednesday of the delivery month) the final settlement price is 100 minus the actual three month deposit rate:
100 - R<br>
slide16. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.16 Example Suppose you buy (take a long position in) a contract on November 1
The contract expires on December 21
The prices are as shown
How much do you gain or lose a) on the first day, b) on the second day, c) over the whole time until expiration?<br>
slide17. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.17 Example<br>
slide18. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.18 Example continued If on Nov. 1 you know that you will have $1 million to invest on for three months on Dec 21 the contract locks in a rate of 100 - 97.12 = 2.88%
In the example you earn 100 – 97.42 =2.58% on $1 million for three months (=$6,450) and make a gain day by day on the futures contract of 30×$25 =$750
Total gain: $6.450+$750=$7.200 which is equal to 1.000.000*0.25*0.0288<br>
slide19. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.19 Formula for Contract Value (page 138) If Q is the quoted price of a Eurodollar futures contract, the value of one contract is
10,000[100-0.25(100-Q)]
In the above example, the settlement price of 97.12 corresponds to a contract price of
10.000[100-0.25*(100-97.12)]=$992.800
The final contract price is
10.000[100-0.25*(100-97.42)]=$993.550
The difference is $750. This is the gain of an investor with long position<br>
slide20. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.20 Forward Rate Agreements vs Futures Interest rates Futures is settled daily where forward is settled once
Futures is settled at the beginning of the underlying three-month period; forward is settled at the end of the underlying three- month period<br>
slide21. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.21 Forward Rates and Eurodollar Futures continued<br>
slide22. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.22 Convexity Adjustment when s=0.012 (Table 6.3, page 141)<br>
slide23. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.23 Extending the LIBOR Zero Curve LIBOR deposit rates define the LIBOR zero curve out to one year
Eurodollar futures can be used to determine forward rates (using the convexity adjustment) and the forward rates can then be used to bootstrap the zero curve<br>
slide24. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.24 Example so that
If the 400 day LIBOR rate has been calculated as 4.80% and the forward rate for the period between 400 and 491 days is 5.30 the 491 days rate is 4.893%<br>
slide25. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.25 Duration Matching This involves hedging against interest rate risk by matching the durations of assets and liabilities
It provides protection against small parallel shifts in the zero curve<br>
slide26. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.26 Use of Eurodollar Futures One contract locks in an interest rate on $1 million for a future 3-month period
How many contracts are necessary to lock in an interest rate for a future six month period?<br>
slide27. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.27 Duration-Based Hedge Ratio Since ΔP=-P DP Δy, and it is approximately true that
ΔFC=-FC DF Δy, the number of contracts required is:<br>
slide28. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.28 Example It is August. A fund manager has $10 million invested in a portfolio of government bonds with a duration of 6.80 years and wants to hedge against interest rate moves between August and December
The manager decides to use December T-bond futures. The futures price is 93-02 or 93.0625 and the duration of the cheapest to deliver bond is 9.2 years
The number of contracts that should be shorted is
If Interest rates go up, a gain will be made on the short futures, but a loss will be made on the bond portfolio.
If interest rates decrease, the opposite is true<br>
slide29. Options, Futures, and Other Derivatives 6th Edition, Copyright © John C. Hull 2005 6.29 Limitations of Duration-Based Hedging Assumes that only parallel shift in yield curve take place
Assumes that yield curve changes are small<br>