
OVERVIEW OF THE NEW SYLLABUS EFFECTIVE NOVEMBER


Description: OVERVIEW OF THE NEW SYLLABUS EFFECTIVE NOVEMBER 2025 GENERAL INFORMATION A 15-Subjects structure is retained in the new syllabus Each subject syllabus contains the following content: Prior knowledge where applicable Ethics Method of
Related Topics
Download Presentation
"OVERVIEW OF THE NEW SYLLABUS EFFECTIVE NOVEMBER" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. OVERVIEW OF THE NEW SYLLABUS EFFECTIVE NOVEMBER 2025<br>
slide2. GENERAL INFORMATION A 15-Subjects structure is retained in the new syllabus
Each subject syllabus contains the following content:
Prior knowledge – where applicable
Ethics
Method of assessment and Topic weighting
Ethics and professional scepticism
Specification grid.<br>
slide3. New paradigm in the new syllabus review Major Structural Review of the syllabus every 3years with annual update
Incorporation of IFAC International Sustainability Standards Board’s (ISSB’s) new standards
Sustainability reporting, sustainable and responsible finance
Soft skills increasingly required by the accountant to effectively perform
Latest development on Initial Professional Development (IPD) of Professional Accounting Organisations (PAOs) to incorporate International Education Standards (IES) 1- 5: International Panel on Accounting Education (IPAE) of IFAC.
Local developments
Finance Act 2020, 2021, 2022, 2023
Petroleum Industry Act (PIA), 2021<br>
slide4. New incorporations into the new syllabus Skills sets required by Chartered accountants to cope with technological disruptions in a digital age and prepare future ready accountants.
Sustainability reporting, sustainable and responsible finance.
Soft skills required by accountants to operate in the 21st century.
Provisions of the Petroleum Industry Act (PIA), 2021
Changes occasioned by the Finance Act, 20120, 2021, 2022, and 2023.
Reflect the proper accountability and more efficient public financial management called for by the ICAN Accountability Index<br>
slide5. Structural changes At Foundation Level:
Management Information is replaced with Management Accounting
Business, Management and Finance is renamed Business Environment,to reflect the new contents (Finance aspect is taken to Financial Management at Skills, while Economic section is expanded)
Business Law is changed to Corporate and Business Law<br>
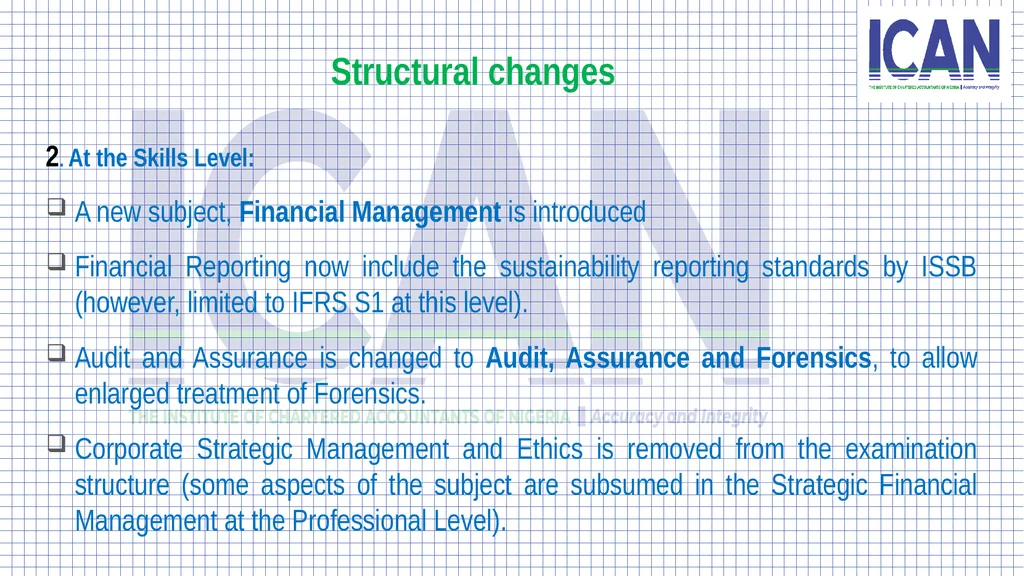
slide6. Structural changes 2. At the Skills Level:
A new subject, Financial Management is introduced
Financial Reporting now include the sustainability reporting standards by ISSB (however, limited to IFRS S1 at this level).
Audit and Assurance is changed to Audit, Assurance and Forensics, to allow enlarged treatment of Forensics.
Corporate Strategic Management and Ethics is removed from the examination structure (some aspects of the subject are subsumed in the Strategic Financial Management at the Professional Level).<br>
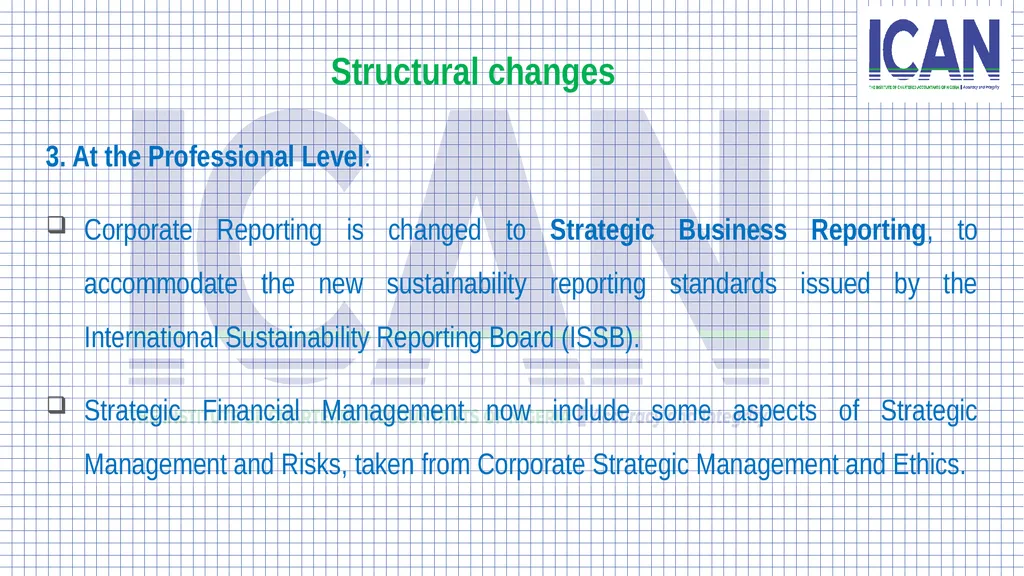
slide7. Structural changes 3. At the Professional Level:
Corporate Reporting is changed to Strategic Business Reporting, to accommodate the new sustainability reporting standards issued by the International Sustainability Reporting Board (ISSB).
Strategic Financial Management now include some aspects of Strategic Management and Risks, taken from Corporate Strategic Management and Ethics.<br>
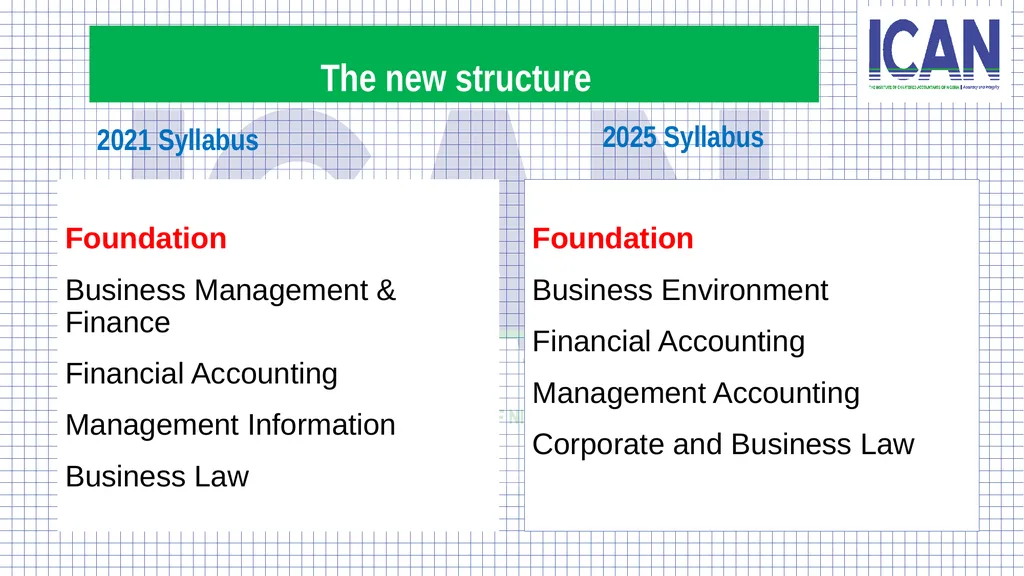
slide8. The new structure 2021 Syllabus 2021 llabus
Foundation
Business Management & Finance
Financial Accounting
Management Information
Business Law 2025 Syllabus 2024 Syllabus
Foundation
Business Environment
Financial Accounting
Management Accounting
Corporate and Business Law<br>
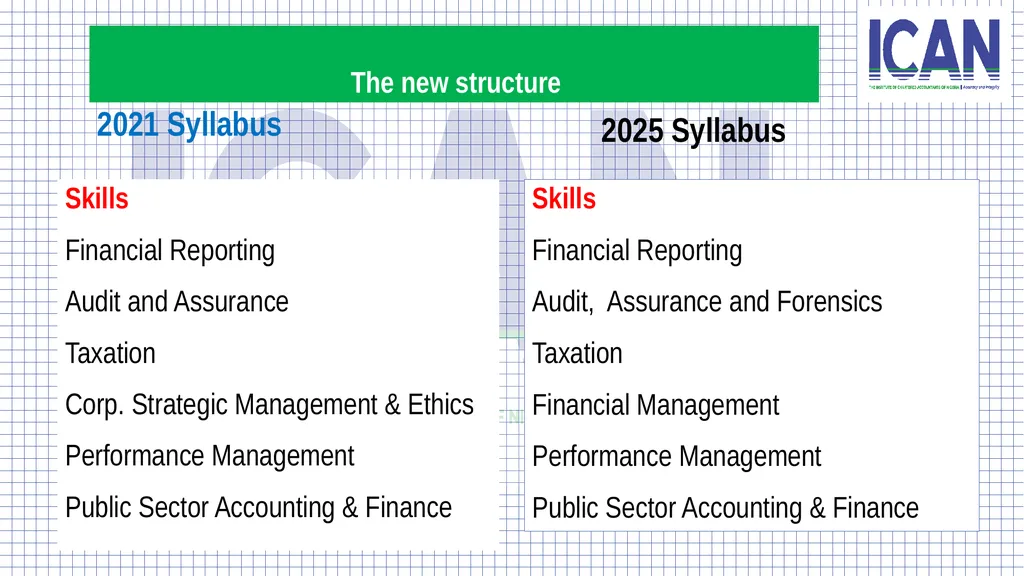
slide9. The new structure 2021 Syllabus Skills
Financial Reporting
Audit and Assurance
Taxation
Corp. Strategic Management & Ethics
Performance Management
Public Sector Accounting & Finance 2025 Syllabus Skills
Financial Reporting
Audit, Assurance and Forensics
Taxation
Financial Management
Performance Management
Public Sector Accounting & Finance<br>
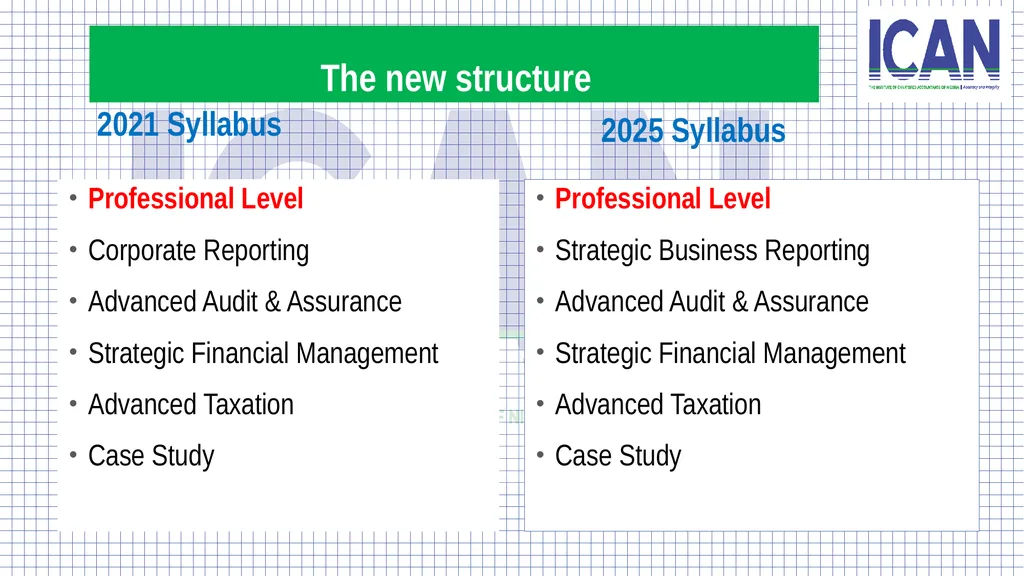
slide10. The new structure 2021 Syllabus Professional Level
Corporate Reporting
Advanced Audit & Assurance
Strategic Financial Management
Advanced Taxation
Case Study 2025 Syllabus Professional Level
Strategic Business Reporting
Advanced Audit & Assurance
Strategic Financial Management
Advanced Taxation
Case Study<br>
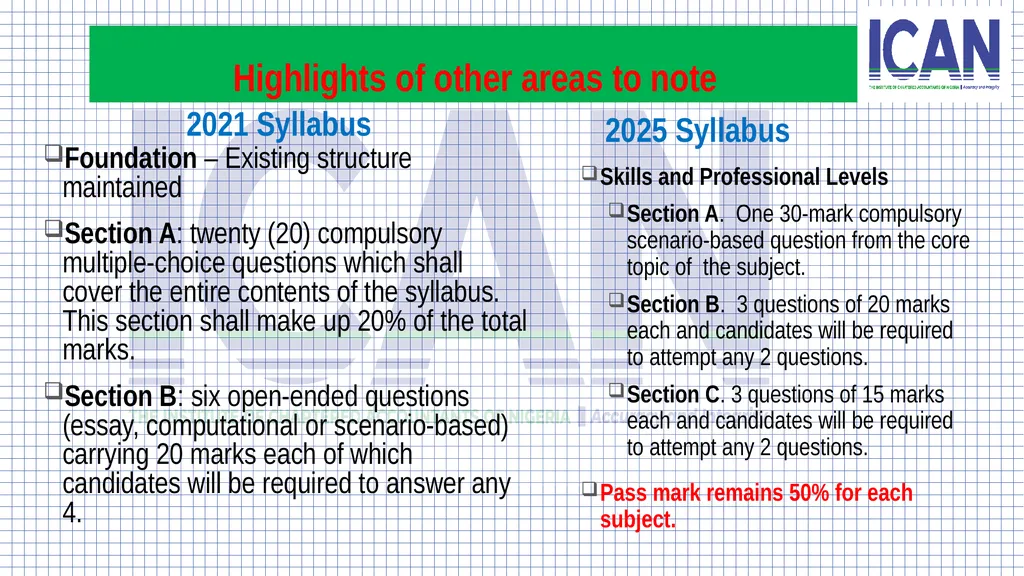
slide11. Highlights of other areas to note 2021 Syllabus 2025 Syllabus Foundation – Existing structure maintained
Section A: twenty (20) compulsory multiple-choice questions which shall cover the entire contents of the syllabus. This section shall make up 20% of the total marks.
Section B: six open-ended questions (essay, computational or scenario-based) carrying 20 marks each of which candidates will be required to answer any 4. Skills and Professional Levels
Section A. One 30-mark compulsory scenario-based question from the core topic of the subject.
Section B. 3 questions of 20 marks each and candidates will be required to attempt any 2 questions.
Section C. 3 questions of 15 marks each and candidates will be required to attempt any 2 questions.
Pass mark remains 50% for each subject.<br>
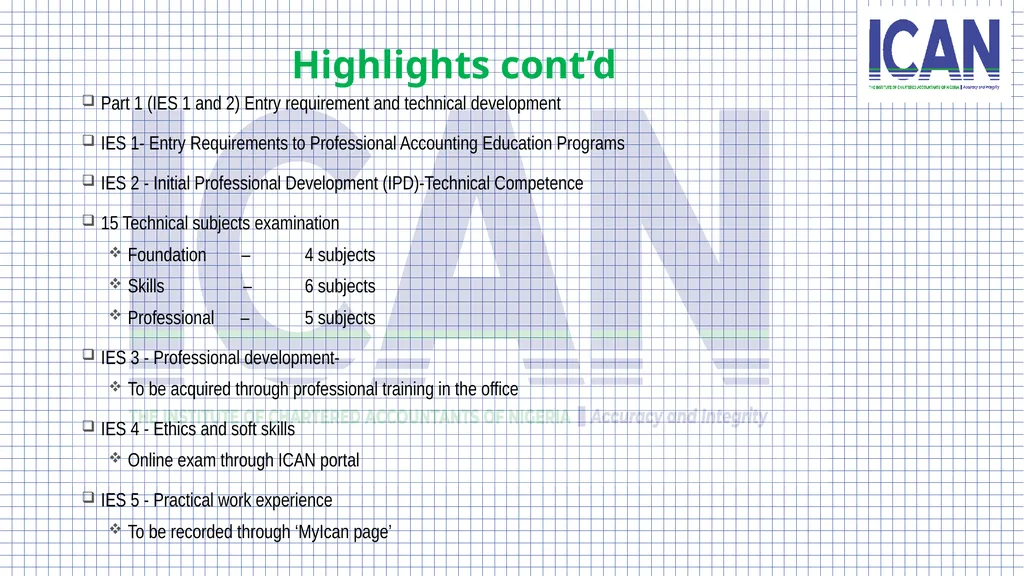
slide12. Highlights cont’d Part 1 (IES 1 and 2) Entry requirement and technical development
IES 1- Entry Requirements to Professional Accounting Education Programs
IES 2 - Initial Professional Development (IPD)-Technical Competence
15 Technical subjects examination
Foundation – 4 subjects
Skills – 6 subjects
Professional – 5 subjects
IES 3 - Professional development-
To be acquired through professional training in the office
IES 4 - Ethics and soft skills
Online exam through ICAN portal
IES 5 - Practical work experience
To be recorded through ‘MyIcan page’<br>
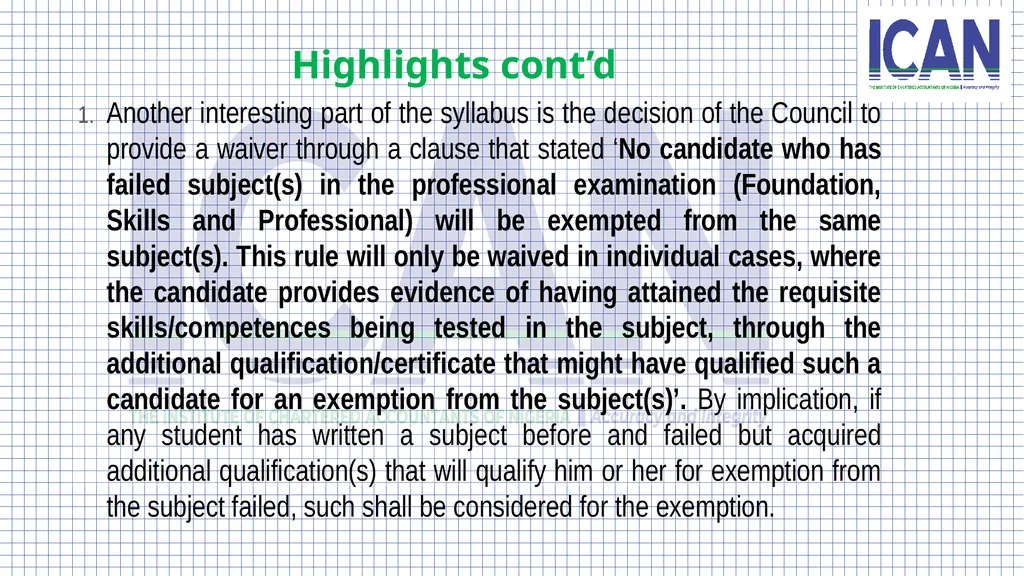
slide13. Highlights cont’d Another interesting part of the syllabus is the decision of the Council to provide a waiver through a clause that stated ‘No candidate who has failed subject(s) in the professional examination (Foundation, Skills and Professional) will be exempted from the same subject(s). This rule will only be waived in individual cases, where the candidate provides evidence of having attained the requisite skills/competences being tested in the subject, through the additional qualification/certificate that might have qualified such a candidate for an exemption from the subject(s)’. By implication, if any student has written a subject before and failed but acquired additional qualification(s) that will qualify him or her for exemption from the subject failed, such shall be considered for the exemption.<br>
slide14. Thank you for your attention!<br>
slide2. GENERAL INFORMATION A 15-Subjects structure is retained in the new syllabus
Each subject syllabus contains the following content:
Prior knowledge – where applicable
Ethics
Method of assessment and Topic weighting
Ethics and professional scepticism
Specification grid.<br>
slide3. New paradigm in the new syllabus review Major Structural Review of the syllabus every 3years with annual update
Incorporation of IFAC International Sustainability Standards Board’s (ISSB’s) new standards
Sustainability reporting, sustainable and responsible finance
Soft skills increasingly required by the accountant to effectively perform
Latest development on Initial Professional Development (IPD) of Professional Accounting Organisations (PAOs) to incorporate International Education Standards (IES) 1- 5: International Panel on Accounting Education (IPAE) of IFAC.
Local developments
Finance Act 2020, 2021, 2022, 2023
Petroleum Industry Act (PIA), 2021<br>
slide4. New incorporations into the new syllabus Skills sets required by Chartered accountants to cope with technological disruptions in a digital age and prepare future ready accountants.
Sustainability reporting, sustainable and responsible finance.
Soft skills required by accountants to operate in the 21st century.
Provisions of the Petroleum Industry Act (PIA), 2021
Changes occasioned by the Finance Act, 20120, 2021, 2022, and 2023.
Reflect the proper accountability and more efficient public financial management called for by the ICAN Accountability Index<br>
slide5. Structural changes At Foundation Level:
Management Information is replaced with Management Accounting
Business, Management and Finance is renamed Business Environment,to reflect the new contents (Finance aspect is taken to Financial Management at Skills, while Economic section is expanded)
Business Law is changed to Corporate and Business Law<br>
slide6. Structural changes 2. At the Skills Level:
A new subject, Financial Management is introduced
Financial Reporting now include the sustainability reporting standards by ISSB (however, limited to IFRS S1 at this level).
Audit and Assurance is changed to Audit, Assurance and Forensics, to allow enlarged treatment of Forensics.
Corporate Strategic Management and Ethics is removed from the examination structure (some aspects of the subject are subsumed in the Strategic Financial Management at the Professional Level).<br>
slide7. Structural changes 3. At the Professional Level:
Corporate Reporting is changed to Strategic Business Reporting, to accommodate the new sustainability reporting standards issued by the International Sustainability Reporting Board (ISSB).
Strategic Financial Management now include some aspects of Strategic Management and Risks, taken from Corporate Strategic Management and Ethics.<br>
slide8. The new structure 2021 Syllabus 2021 llabus
Foundation
Business Management & Finance
Financial Accounting
Management Information
Business Law 2025 Syllabus 2024 Syllabus
Foundation
Business Environment
Financial Accounting
Management Accounting
Corporate and Business Law<br>
slide9. The new structure 2021 Syllabus Skills
Financial Reporting
Audit and Assurance
Taxation
Corp. Strategic Management & Ethics
Performance Management
Public Sector Accounting & Finance 2025 Syllabus Skills
Financial Reporting
Audit, Assurance and Forensics
Taxation
Financial Management
Performance Management
Public Sector Accounting & Finance<br>
slide10. The new structure 2021 Syllabus Professional Level
Corporate Reporting
Advanced Audit & Assurance
Strategic Financial Management
Advanced Taxation
Case Study 2025 Syllabus Professional Level
Strategic Business Reporting
Advanced Audit & Assurance
Strategic Financial Management
Advanced Taxation
Case Study<br>
slide11. Highlights of other areas to note 2021 Syllabus 2025 Syllabus Foundation – Existing structure maintained
Section A: twenty (20) compulsory multiple-choice questions which shall cover the entire contents of the syllabus. This section shall make up 20% of the total marks.
Section B: six open-ended questions (essay, computational or scenario-based) carrying 20 marks each of which candidates will be required to answer any 4. Skills and Professional Levels
Section A. One 30-mark compulsory scenario-based question from the core topic of the subject.
Section B. 3 questions of 20 marks each and candidates will be required to attempt any 2 questions.
Section C. 3 questions of 15 marks each and candidates will be required to attempt any 2 questions.
Pass mark remains 50% for each subject.<br>
slide12. Highlights cont’d Part 1 (IES 1 and 2) Entry requirement and technical development
IES 1- Entry Requirements to Professional Accounting Education Programs
IES 2 - Initial Professional Development (IPD)-Technical Competence
15 Technical subjects examination
Foundation – 4 subjects
Skills – 6 subjects
Professional – 5 subjects
IES 3 - Professional development-
To be acquired through professional training in the office
IES 4 - Ethics and soft skills
Online exam through ICAN portal
IES 5 - Practical work experience
To be recorded through ‘MyIcan page’<br>
slide13. Highlights cont’d Another interesting part of the syllabus is the decision of the Council to provide a waiver through a clause that stated ‘No candidate who has failed subject(s) in the professional examination (Foundation, Skills and Professional) will be exempted from the same subject(s). This rule will only be waived in individual cases, where the candidate provides evidence of having attained the requisite skills/competences being tested in the subject, through the additional qualification/certificate that might have qualified such a candidate for an exemption from the subject(s)’. By implication, if any student has written a subject before and failed but acquired additional qualification(s) that will qualify him or her for exemption from the subject failed, such shall be considered for the exemption.<br>
slide14. Thank you for your attention!<br>