
Personal Finance: “30” Thoughts David Laibson


Description: Personal Finance: 30 Thoughts David Laibson Lowell House Harvard College Cambridge, MA 02138 April 23, 2023 Disclaimer This is not legal advice. This is not investment advice. This is only education. Start with saving During periods of
Related Topics
Download Presentation
"Personal Finance: “30” Thoughts David Laibson" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Personal Finance: “30” Thoughts David Laibson
Lowell House Harvard College | Cambridge, MA 02138 April 23, 2023<br>
slide2. Disclaimer This is not legal advice.
This is not investment advice.
This is only education.<br>
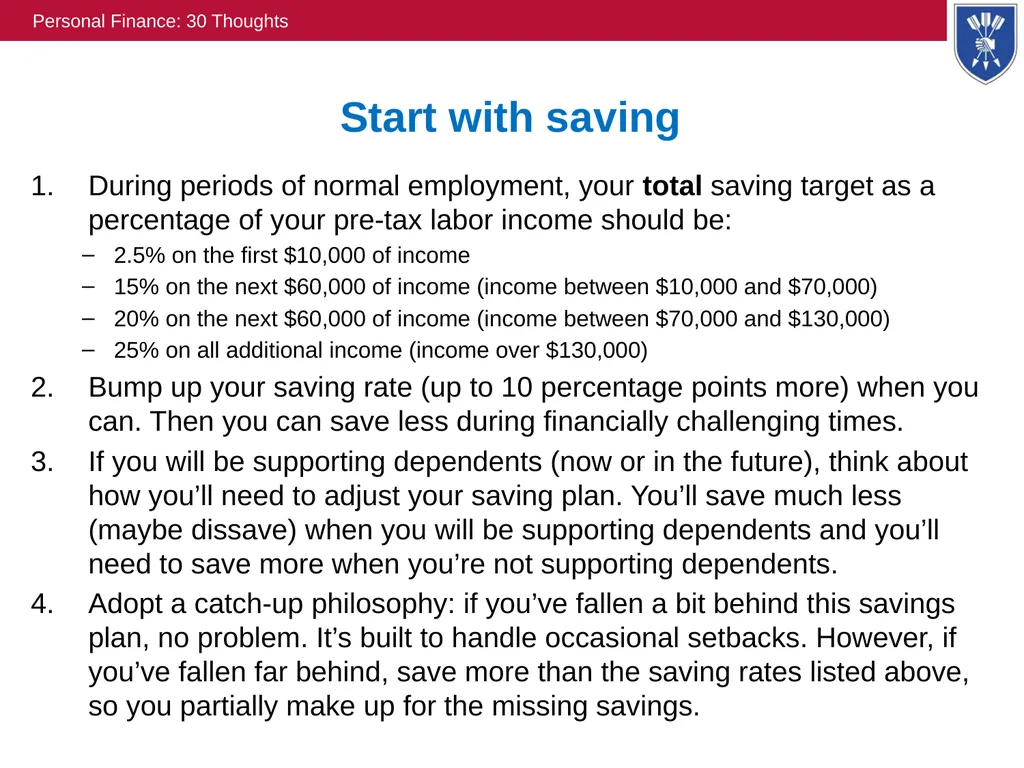
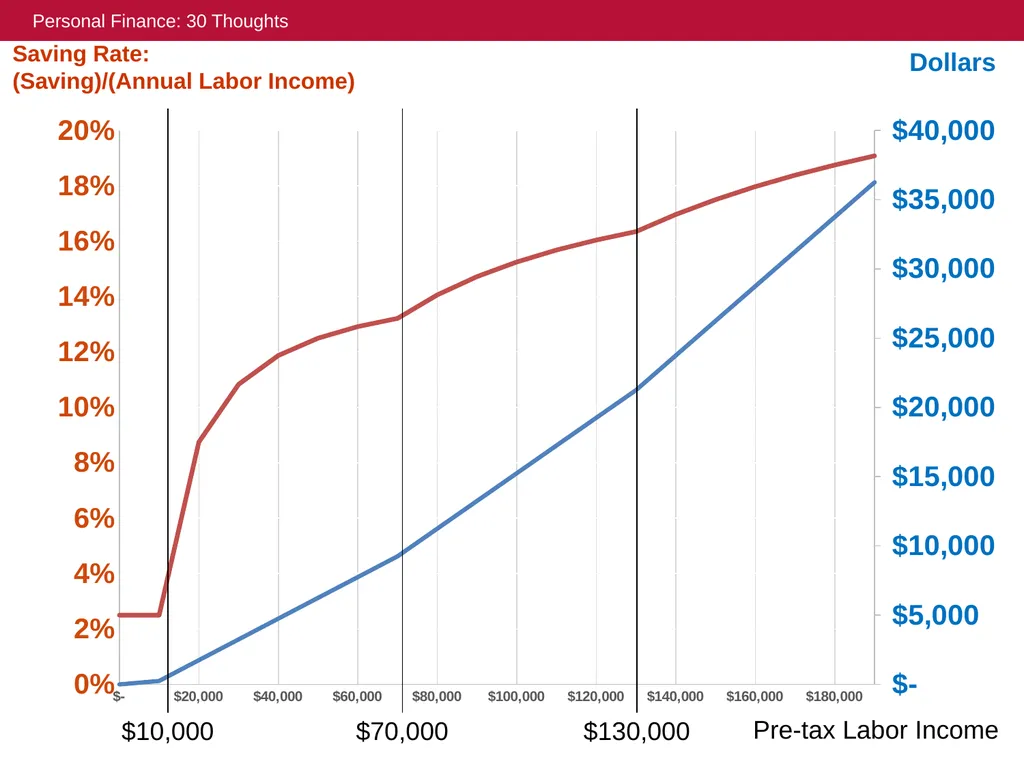
slide3. Start with saving During periods of normal employment, your total saving target as a percentage of your pre-tax labor income should be:
2.5% on the first $10,000 of income
15% on the next $60,000 of income (income between $10,000 and $70,000)
20% on the next $60,000 of income (income between $70,000 and $130,000)
25% on all additional income (income over $130,000)
Bump up your saving rate (up to 10 percentage points more) when you can. Then you can save less during financially challenging times.
If you will be supporting dependents (now or in the future), think about how you’ll need to adjust your saving plan. You’ll save much less (maybe dissave) when you will be supporting dependents and you’ll need to save more when you’re not supporting dependents.
Adopt a catch-up philosophy: if you’ve fallen a bit behind this savings plan, no problem. It’s built to handle occasional setbacks. However, if you’ve fallen far behind, save more than the saving rates listed above, so you partially make up for the missing savings. Personal Finance: 30 Thoughts<br>
slide4. Saving Rate:
(Saving)/(Annual Labor Income) Dollars Pre-tax Labor Income $10,000 $70,000 $130,000 Personal Finance: 30 Thoughts<br>
slide5. What counts toward this saving target? Your contributions to your employer’s retirement savings program (multiply by 1.5 if this is a Roth account).
Your employer’s “matching” contributions.
Principal payments on your mortgage (but not interest payments).
Net contributions to your “rainy day” savings account. Personal Finance: 30 Thoughts<br>
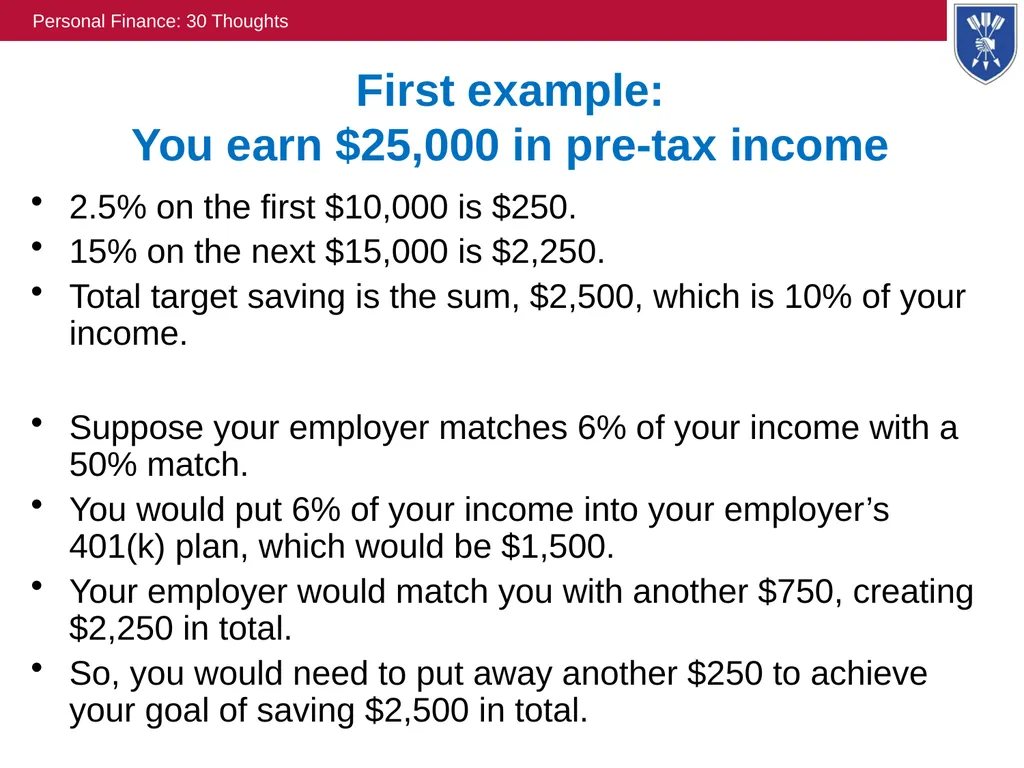
slide6. First example: You earn $25,000 in pre-tax income 2.5% on the first $10,000 is $250.
15% on the next $15,000 is $2,250.
Total target saving is the sum, $2,500, which is 10% of your income.
Suppose your employer matches 6% of your income with a 50% match.
You would put 6% of your income into your employer’s 401(k) plan, which would be $1,500.
Your employer would match you with another $750, creating $2,250 in total.
So, you would need to put away another $250 to achieve your goal of saving $2,500 in total. Personal Finance: 30 Thoughts<br>
slide7. Suppose you earn $75,000 in pre-tax income 2.5% on the first $10,000 is $250.
15% on the next $60,000 is $9,000.
20% on the next $5,000 is $1,000.
Total target saving is the sum, $10,250, which is 13.7% of your income.
Suppose your employer matches 6% of your income with a 50% match.
You would put 6% of your income into your employer’s 401(k) plan, which would be $4,500.
Your employer would match you with another $2,250, creating $6,750 in total.
So, you would need to put away another $3,500 to achieve your goal of saving $10,250. Personal Finance: 30 Thoughts<br>
slide8. Saving (continued) Prioritize saving/debt categories:
Priority Group 1 (highest priority)
Pay the minimum balance on your credit cards
Get full savers credit (if eligible)
Get full retirement savings match from employer (if match offered)
Pay your rent or mortgage bill
Priority Group 2
Pay your credit card bills in full (starting with highest interest cards)
Priority Group 3 (lowest priority)
Create a rainy-day fund equal to 1/4 of your normal post-tax annual labor income (hold in a money market account)
Build up a down-payment for buying a house (20% of home value – hold in a money market account)
Save more in a 401(k), 403(b), IRA, or some other defined contribution retirement account Personal Finance: 30 Thoughts<br>
slide9. Two kinds of investment funds Passively managed investments: buy-and-hold the index of all stocks (close to zero fee).
Actively managed investments: trade to try to beat the index of all stocks (high fee). Personal Finance: 30 Thoughts<br>
slide10. It’s almost impossible to reliably beat the market and it is easy to underperform the market In most years, a majority of actively managed investment funds underperform (low-fee) index funds.
Over the long-run, almost all actively managed investment funds underperform (low-fee) index funds.
Even asset managers that do much better than index funds in year t, tend to do no better than index funds in year t+1.
Suppose performance is pure chance, you would expect 2,500 mutual funds out of 10,000 to outperform index funds two years in a row: (1/2)(1/2) = (1/4).
Easy to misread “strong historical performance” as skill. Luck seems to generate almost all long-run out-performance.
The only thing that is robustly predictable from year to year is the asset management fee.
You should focus on minimizing fees by holding index funds. Information about “good” investments is already “priced in.” Personal Finance: 30 Thoughts<br>
slide11. Investing Invest retirement savings in a passive (i.e., indexed) target date fund – sometimes called a lifecycle fund. It should have an expense ratio of less than 20 basis points and no loads.
Don’t try to time/play the market.
Invest other savings in a money market fund that has an expense ratio of less than 20 basis points.
If you work with a financial planner, make certain that they are a fiduciary. Find out what fees they are charging you. (But keep in mind, that you likely don’t need a financial planner, if you follow the free advice listed here.) Personal Finance: 30 Thoughts<br>
slide12. Debt Use a credit card that gives you at least 1% cash back (preferably 2%), or an equivalent value in points or miles.
Maximize your FICO score by (i) becoming an “authorized user” on a “high”-FICO account, (ii) getting your own credit card after you turn 18 (co-signers?), (iii) having 2-3 credit cards, (iv) using a small fraction of your total credit line (even if you pay in full each month), (v) minimizing “hard inquiries” (from credit applications) and (vi) paying bills on time. Monitor your credit and credit score by downloading your annual free credit reports from all three credit bureaus: Equifax, Experian, TransUnion.
Try to avoid credit card debt. Almost never use payday loans. (Your rainy-day fund – above – will enable you to mostly avoid credit card and payday debt.)
When you buy a car, use up half of your rainy-day fund, and then borrow the rest of the money you need with an auto-loan.
Buy a home with a 20% down-payment (wait to do this until you live in a place where you expect to stay for at least 7 years).
If mortgage interest rates fall by 2 percentage points from your origination rate, refinance your mortgage.* Avoid cash-outs. Personal Finance: 30 Thoughts *For an exact formula for optimal mortgage refinancing, see Agarwal, S., Driscoll, J. C., & Laibson, D. I. 2013. Optimal Mortgage Refinancing: A Closed‐Form Solution. Journal of Money, Credit and Banking, 45(4), 591-622.<br>
slide13. Misc. Buy health insurance, automobile insurance, home-owner’s insurance and disability insurance (the last one is typically obtained from your employer as a group plan). Don’t buy other insurance, especially not extended warranties. Buy life insurance only if you support someone else with your earnings or time.
Ask for discounts. Ask for the best price. Ask if anyone else is paying a price lower than the price you are paying. Shop around. Weaponize competition to your advantage and to the disadvantage of the firms selling you stuff.
Obtain commission discounts when you work with real estate brokers. If they won’t give you a discount, find another real estate broker. (If they tell you discounts are illegal, look up the statute.)
Before you have kids (if you are going to have kids), create an estate plan including, durable power of attorney, will, living will, healthy care proxy. Personal Finance: 30 Thoughts<br>
slide14. Behavioral Financial things will go worse than you think (on average).
There are known unknowns and unknown unknowns. Think more about both of these categories. Discuss with friends, family, trusted advisors, etc…
Your financial services providers know the mistakes you are making and are probably going to exploit them.
You will underperform relative to your own good intentions (e.g., procrastinate signing up for your employer’s 401(k) plan). Commit your actions ahead of time to overcome this propensity.
The only way to be good at something is either to be highly experienced, or to have someone with lots of experience helping you (with aligned interests).
Look for providers with a long and strong reputation for acting in the interests of their customers.
Try to keep the big picture in mind to avoid worrying about small loses (and thereby letting loss aversion rule/ruin your life). Personal Finance: 30 Thoughts<br>
slide15. Retirement Remember that long-term care is expensive and is not covered by Medicare. If reasonable, keep savings set aside for this expense (ballpark cost is $100,000 per year per person). If you run out of money, Medicaid will cover a far less comfortable version of long-term care.
When you retire, withdraw your (annual) required minimum distribution (RMD) from your retirement savings plan and consume the (after-tax) value of those withdrawals along with your other annuity payments (e.g., Social Security). Personal Finance: 30 Thoughts<br>
slide16. Meta-cognition The financial world is constantly changing. You’ll need to continuously update your financial strategy as new products, regulations, and challenges emerge.
Ignore all of this advice.
The advice you just received is oversimplified (which also makes it more actionable).
Be skeptical of anyone offering financial advice. Personal Finance: 30 Thoughts<br>
slide17. If you want a copy of this slide deck… Look for a bacch-talk announcement this week with a link.<br>
Lowell House Harvard College | Cambridge, MA 02138 April 23, 2023<br>
slide2. Disclaimer This is not legal advice.
This is not investment advice.
This is only education.<br>
slide3. Start with saving During periods of normal employment, your total saving target as a percentage of your pre-tax labor income should be:
2.5% on the first $10,000 of income
15% on the next $60,000 of income (income between $10,000 and $70,000)
20% on the next $60,000 of income (income between $70,000 and $130,000)
25% on all additional income (income over $130,000)
Bump up your saving rate (up to 10 percentage points more) when you can. Then you can save less during financially challenging times.
If you will be supporting dependents (now or in the future), think about how you’ll need to adjust your saving plan. You’ll save much less (maybe dissave) when you will be supporting dependents and you’ll need to save more when you’re not supporting dependents.
Adopt a catch-up philosophy: if you’ve fallen a bit behind this savings plan, no problem. It’s built to handle occasional setbacks. However, if you’ve fallen far behind, save more than the saving rates listed above, so you partially make up for the missing savings. Personal Finance: 30 Thoughts<br>
slide4. Saving Rate:
(Saving)/(Annual Labor Income) Dollars Pre-tax Labor Income $10,000 $70,000 $130,000 Personal Finance: 30 Thoughts<br>
slide5. What counts toward this saving target? Your contributions to your employer’s retirement savings program (multiply by 1.5 if this is a Roth account).
Your employer’s “matching” contributions.
Principal payments on your mortgage (but not interest payments).
Net contributions to your “rainy day” savings account. Personal Finance: 30 Thoughts<br>
slide6. First example: You earn $25,000 in pre-tax income 2.5% on the first $10,000 is $250.
15% on the next $15,000 is $2,250.
Total target saving is the sum, $2,500, which is 10% of your income.
Suppose your employer matches 6% of your income with a 50% match.
You would put 6% of your income into your employer’s 401(k) plan, which would be $1,500.
Your employer would match you with another $750, creating $2,250 in total.
So, you would need to put away another $250 to achieve your goal of saving $2,500 in total. Personal Finance: 30 Thoughts<br>
slide7. Suppose you earn $75,000 in pre-tax income 2.5% on the first $10,000 is $250.
15% on the next $60,000 is $9,000.
20% on the next $5,000 is $1,000.
Total target saving is the sum, $10,250, which is 13.7% of your income.
Suppose your employer matches 6% of your income with a 50% match.
You would put 6% of your income into your employer’s 401(k) plan, which would be $4,500.
Your employer would match you with another $2,250, creating $6,750 in total.
So, you would need to put away another $3,500 to achieve your goal of saving $10,250. Personal Finance: 30 Thoughts<br>
slide8. Saving (continued) Prioritize saving/debt categories:
Priority Group 1 (highest priority)
Pay the minimum balance on your credit cards
Get full savers credit (if eligible)
Get full retirement savings match from employer (if match offered)
Pay your rent or mortgage bill
Priority Group 2
Pay your credit card bills in full (starting with highest interest cards)
Priority Group 3 (lowest priority)
Create a rainy-day fund equal to 1/4 of your normal post-tax annual labor income (hold in a money market account)
Build up a down-payment for buying a house (20% of home value – hold in a money market account)
Save more in a 401(k), 403(b), IRA, or some other defined contribution retirement account Personal Finance: 30 Thoughts<br>
slide9. Two kinds of investment funds Passively managed investments: buy-and-hold the index of all stocks (close to zero fee).
Actively managed investments: trade to try to beat the index of all stocks (high fee). Personal Finance: 30 Thoughts<br>
slide10. It’s almost impossible to reliably beat the market and it is easy to underperform the market In most years, a majority of actively managed investment funds underperform (low-fee) index funds.
Over the long-run, almost all actively managed investment funds underperform (low-fee) index funds.
Even asset managers that do much better than index funds in year t, tend to do no better than index funds in year t+1.
Suppose performance is pure chance, you would expect 2,500 mutual funds out of 10,000 to outperform index funds two years in a row: (1/2)(1/2) = (1/4).
Easy to misread “strong historical performance” as skill. Luck seems to generate almost all long-run out-performance.
The only thing that is robustly predictable from year to year is the asset management fee.
You should focus on minimizing fees by holding index funds. Information about “good” investments is already “priced in.” Personal Finance: 30 Thoughts<br>
slide11. Investing Invest retirement savings in a passive (i.e., indexed) target date fund – sometimes called a lifecycle fund. It should have an expense ratio of less than 20 basis points and no loads.
Don’t try to time/play the market.
Invest other savings in a money market fund that has an expense ratio of less than 20 basis points.
If you work with a financial planner, make certain that they are a fiduciary. Find out what fees they are charging you. (But keep in mind, that you likely don’t need a financial planner, if you follow the free advice listed here.) Personal Finance: 30 Thoughts<br>
slide12. Debt Use a credit card that gives you at least 1% cash back (preferably 2%), or an equivalent value in points or miles.
Maximize your FICO score by (i) becoming an “authorized user” on a “high”-FICO account, (ii) getting your own credit card after you turn 18 (co-signers?), (iii) having 2-3 credit cards, (iv) using a small fraction of your total credit line (even if you pay in full each month), (v) minimizing “hard inquiries” (from credit applications) and (vi) paying bills on time. Monitor your credit and credit score by downloading your annual free credit reports from all three credit bureaus: Equifax, Experian, TransUnion.
Try to avoid credit card debt. Almost never use payday loans. (Your rainy-day fund – above – will enable you to mostly avoid credit card and payday debt.)
When you buy a car, use up half of your rainy-day fund, and then borrow the rest of the money you need with an auto-loan.
Buy a home with a 20% down-payment (wait to do this until you live in a place where you expect to stay for at least 7 years).
If mortgage interest rates fall by 2 percentage points from your origination rate, refinance your mortgage.* Avoid cash-outs. Personal Finance: 30 Thoughts *For an exact formula for optimal mortgage refinancing, see Agarwal, S., Driscoll, J. C., & Laibson, D. I. 2013. Optimal Mortgage Refinancing: A Closed‐Form Solution. Journal of Money, Credit and Banking, 45(4), 591-622.<br>
slide13. Misc. Buy health insurance, automobile insurance, home-owner’s insurance and disability insurance (the last one is typically obtained from your employer as a group plan). Don’t buy other insurance, especially not extended warranties. Buy life insurance only if you support someone else with your earnings or time.
Ask for discounts. Ask for the best price. Ask if anyone else is paying a price lower than the price you are paying. Shop around. Weaponize competition to your advantage and to the disadvantage of the firms selling you stuff.
Obtain commission discounts when you work with real estate brokers. If they won’t give you a discount, find another real estate broker. (If they tell you discounts are illegal, look up the statute.)
Before you have kids (if you are going to have kids), create an estate plan including, durable power of attorney, will, living will, healthy care proxy. Personal Finance: 30 Thoughts<br>
slide14. Behavioral Financial things will go worse than you think (on average).
There are known unknowns and unknown unknowns. Think more about both of these categories. Discuss with friends, family, trusted advisors, etc…
Your financial services providers know the mistakes you are making and are probably going to exploit them.
You will underperform relative to your own good intentions (e.g., procrastinate signing up for your employer’s 401(k) plan). Commit your actions ahead of time to overcome this propensity.
The only way to be good at something is either to be highly experienced, or to have someone with lots of experience helping you (with aligned interests).
Look for providers with a long and strong reputation for acting in the interests of their customers.
Try to keep the big picture in mind to avoid worrying about small loses (and thereby letting loss aversion rule/ruin your life). Personal Finance: 30 Thoughts<br>
slide15. Retirement Remember that long-term care is expensive and is not covered by Medicare. If reasonable, keep savings set aside for this expense (ballpark cost is $100,000 per year per person). If you run out of money, Medicaid will cover a far less comfortable version of long-term care.
When you retire, withdraw your (annual) required minimum distribution (RMD) from your retirement savings plan and consume the (after-tax) value of those withdrawals along with your other annuity payments (e.g., Social Security). Personal Finance: 30 Thoughts<br>
slide16. Meta-cognition The financial world is constantly changing. You’ll need to continuously update your financial strategy as new products, regulations, and challenges emerge.
Ignore all of this advice.
The advice you just received is oversimplified (which also makes it more actionable).
Be skeptical of anyone offering financial advice. Personal Finance: 30 Thoughts<br>
slide17. If you want a copy of this slide deck… Look for a bacch-talk announcement this week with a link.<br>