
PGDBFS 103 International Financial Accounting and





Description: PGDBFS 103 International Financial Accounting and Policy (IFAP) International Financial Reporting Standards INTERNATIONAL FINANCIAL REPORTING STANDARDS (IFRSs) IFRSs are the set of most commonly adopted generally accepted accounting
Related Topics
Download Presentation
"PGDBFS 103 International Financial Accounting and" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. PGDBFS 103 International Financial Accounting and Policy (IFAP) International Financial Reporting Standards<br>
slide2. INTERNATIONAL FINANCIAL REPORTING STANDARDS (IFRSs) IFRSs are the set of most commonly adopted generally accepted accounting principles worldwide.
This module describes and demonstrates the requirements of selected IFRSs and also makes comparison to US GAAPs to indicate differences and similarities.
The type of differences between US GAAPs and IFRS will include: definition differences, recognition differences, measurement differences, alternative accounting treatments available, lack of requirements or guidance, presentation differences, disclosure differences<br>
slide3. IAS 2 - Inventories Recognition: An entity should initially recognise inventory when it has control of the inventory, expects it to provide future economic benefits, and the cost of the inventory can be measured reliably.
Measurement: Initial measurement of inventories should be at cost. After initial recognition, inventories should be measured at the lower of cost and net realisable value.
Definition of “Cost” - Cost is defined as all costs of purchase, costs of conversion and other costs incurred in bringing the inventories to their present location and condition.
Cost excludes: administrative overheads, abnormal losses, storage costs, selling costs
US GAAP vs IFRS
LIFO is only allowed under US GAAP
Reversal of inventory write downs prohibited under US GAAP. IFRS allows up to the original write down.<br>
slide4. IAS 16 – Property, plant and equipment Recognition: When it is probable that future economic benefits associated with the item will flow to the entity; and the cost of the item can be measured reliably.
Measurement: initially measured at cost.
Cost - costs of acquiring or constructing the asset and costs incurred subsequently to add to or replace part of the asset.
The purchase price
Directly attributable costs
costs of dismantling and removing the item and restoring the site
Borrowing costs on qualifying assets.
Subsequent measurement
US GAAP – cost model
IFRS – cost model / revaluation model
US GAAP vs IFRS
IFRS – component depreciation / annual review of residual value and life
US GAAP – no component depreciation / no explicit requirement for an annual review of residual values.<br>
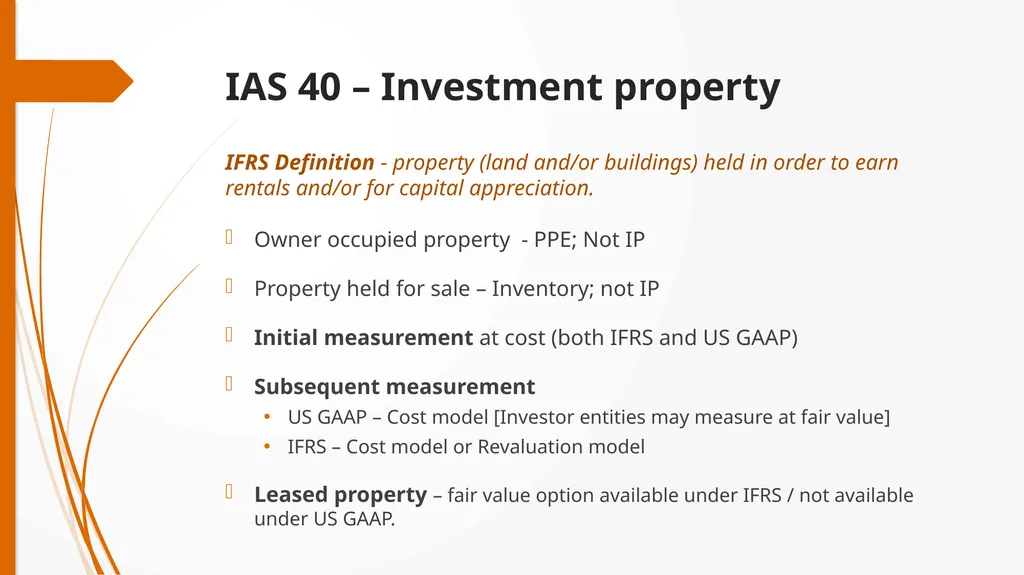
slide5. IAS 40 – Investment property IFRS Definition - property (land and/or buildings) held in order to earn rentals and/or for capital appreciation.
Owner occupied property - PPE; Not IP
Property held for sale – Inventory; not IP
Initial measurement at cost (both IFRS and US GAAP)
Subsequent measurement
US GAAP – Cost model [Investor entities may measure at fair value]
IFRS – Cost model or Revaluation model
Leased property – fair value option available under IFRS / not available under US GAAP.<br>
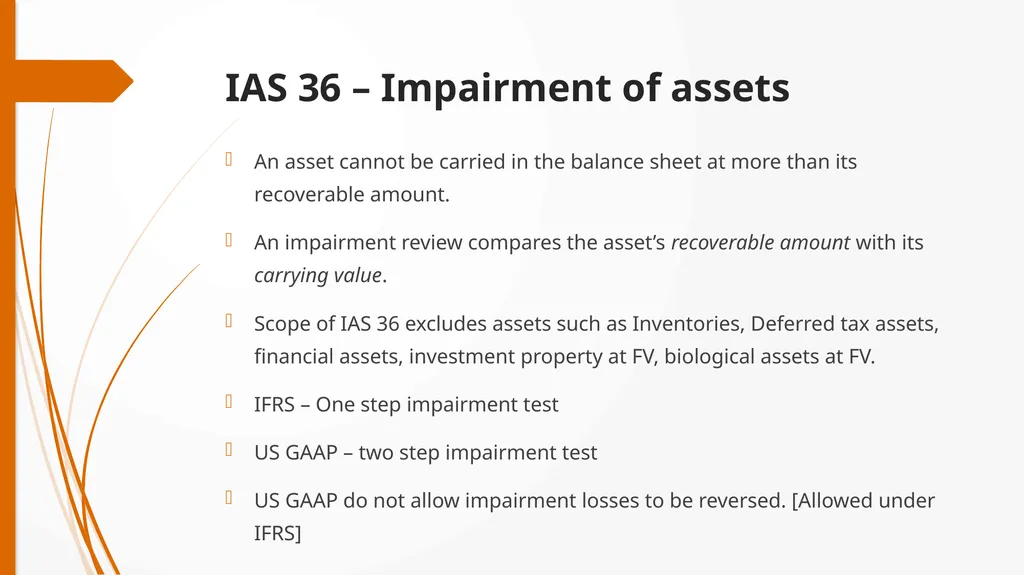
slide6. IAS 36 – Impairment of assets An asset cannot be carried in the balance sheet at more than its recoverable amount.
An impairment review compares the asset’s recoverable amount with its carrying value.
Scope of IAS 36 excludes assets such as Inventories, Deferred tax assets, financial assets, investment property at FV, biological assets at FV.
IFRS – One step impairment test
US GAAP – two step impairment test
US GAAP do not allow impairment losses to be reversed. [Allowed under IFRS]<br>
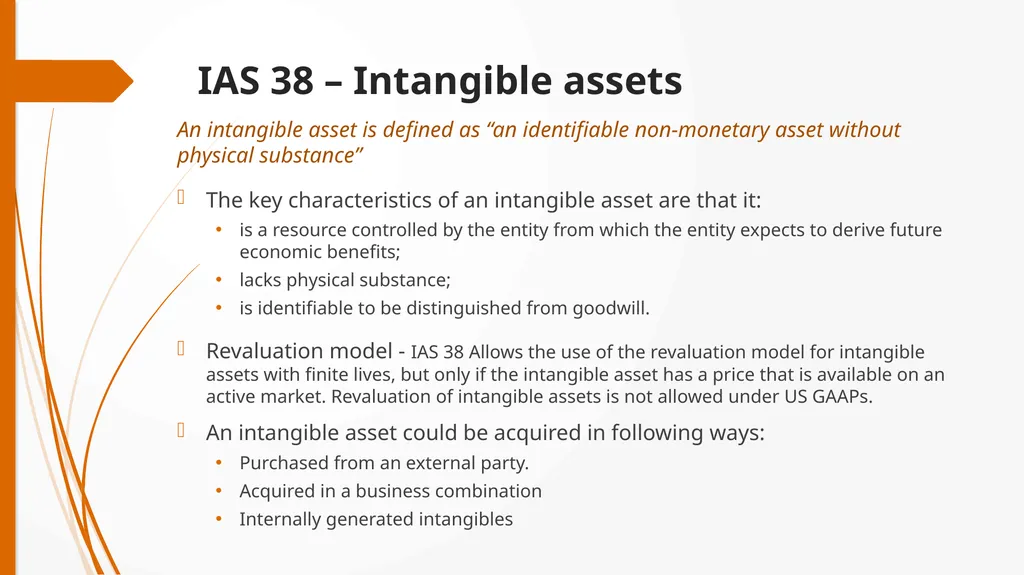
slide7. IAS 38 – Intangible assets An intangible asset is defined as “an identifiable non-monetary asset without physical substance”
The key characteristics of an intangible asset are that it:
is a resource controlled by the entity from which the entity expects to derive future economic benefits;
lacks physical substance;
is identifiable to be distinguished from goodwill.
Revaluation model - IAS 38 Allows the use of the revaluation model for intangible assets with finite lives, but only if the intangible asset has a price that is available on an active market. Revaluation of intangible assets is not allowed under US GAAPs.
An intangible asset could be acquired in following ways:
Purchased from an external party.
Acquired in a business combination
Internally generated intangibles<br>
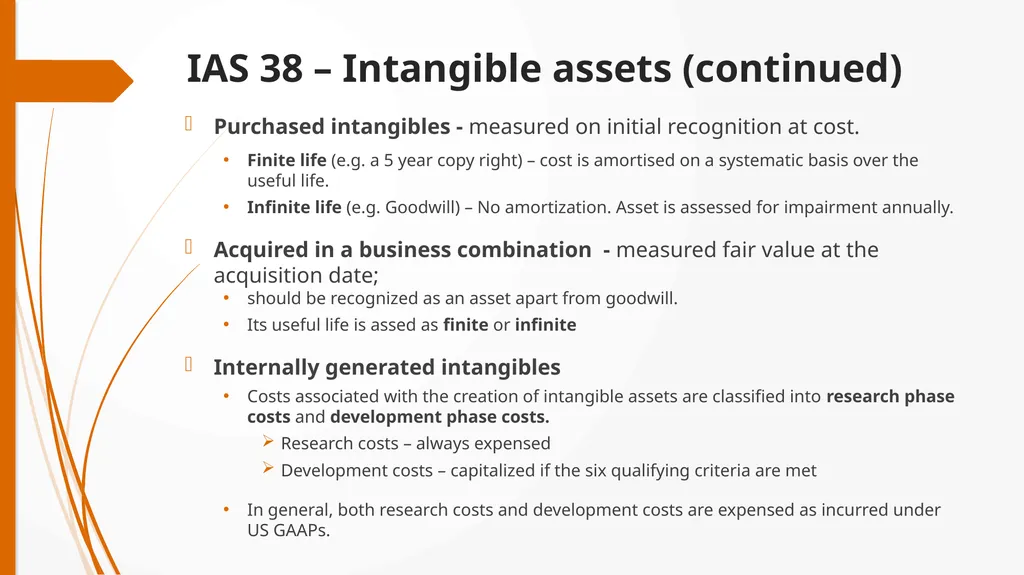
slide8. IAS 38 – Intangible assets (continued) Purchased intangibles - measured on initial recognition at cost.
Finite life (e.g. a 5 year copy right) – cost is amortised on a systematic basis over the useful life.
Infinite life (e.g. Goodwill) – No amortization. Asset is assessed for impairment annually.
Acquired in a business combination - measured fair value at the acquisition date;
should be recognized as an asset apart from goodwill.
Its useful life is assed as finite or infinite
Internally generated intangibles
Costs associated with the creation of intangible assets are classified into research phase costs and development phase costs.
Research costs – always expensed
Development costs – capitalized if the six qualifying criteria are met
In general, both research costs and development costs are expensed as incurred under US GAAPs.<br>
slide9. IAS 23 – Borrowing costs Prior to the revision of IAS 23, it provided two methods of accounting for borrowing costs.
Benchmark treatment: expense all borrowing costs in the period incurred.
Allowed alternative treatment: capitalize borrowing costs to the extent they are attributable to the acquisition, construction or production of a qualifying asset; other borrowing costs are expensed as incurred.
Adoption of the benchmark treatment was not acceptable under US GAAP. Under the IASB-FASB convergence project, IAS 27 was revised in 2007, whereby the benchmark treatment was eliminated.
Borrowing costs under IFRS are broader and can include more components than interest costs under US GAAP. E.g. IAS 23 specifically includes foreign exchange gains/losses on foreign currency borrowings.<br>
slide10. IAS 17 - Leases A lease is defined as an agreement whereby the lessor conveys to the lessee in return for a payment or series of payments the right to use an asset for an agreed period of time.
All leases must be classified as either finance leases or operating leases.
A finance lease is defined as “... a lease that transfers substantially all the risks and rewards incidental to ownership of an asset”. Thus, a finance lease is an arrangement that has the substance of a financing transaction for the lessee to acquire effective economic ownership of an asset.
An operating lease is “... a lease other than a finance lease”.
The classification is based on the extent to which risks and rewards incidental to ownership of a leased asset lie with the lessor or the lessee.<br>
slide11. IAS 17 – Leases (continued) Finance lease indicators:
The lease transfers ownership of the asset to the lessee by the end of the lease term.
The lessee has the option to purchase the asset at a bargain price.
The lease term is for the major part of the economic life of the asset.
At the inception, the present value of the minimum lease payments amounts to at least substantially all of the fair value of the leased asset.
The leased assets are of a specialised nature such that only the lessee can use them without major modifications being made.
The following situations, individually or in combination, also could also lead to a finance lease classification:
If the lessee can cancel the lease, the lessor’s losses associated with the cancellation are borne by the lessee.
Gains or losses from the fluctuation in the residual’s fair value fall to the lessee.
The lessee has the ability to continue the lease for a secondary period at a rent that is substantially lower than market rent.<br>
slide12. IAS 17 – Leases (continued) Accounting for finance leases
Leased assets and leased liabilities are presented separately and gross in the balance sheet.
the sum to be recognized : lower of the fair value of the leased asset and the present value of the minimum lease payments.
Discount factor is the interest rate implicit in the lease; or Lessee’s incremental borrowing rate
An asset leased under a finance lease should be depreciated over the shorter of the lease term and its useful life.
Accounting for operating leases
Operating leases should not be capitalised
Lease payments made under operating leases should be recognised as an expense on a straight-line basis over the lease term.<br>
slide13. IAS 17 – Leases (continued) Accounting for sale and leaseback transactions - Finance leasebacks
A finance leaseback is essentially a financing operation for the seller.
The seller/lessee never disposes of the risks and rewards of ownership of the asset.
Should not recognise a profit or loss on the sale.
Any apparent profit (that is, the difference between the sale price and the previous carrying value) should be deferred and amortised over the lease term.
Operating leases – Disclosures
Lessees shall make the following disclosures for operating leases:
The total of future minimum lease payments under non-cancellable operating leases for each of the following periods:
not later than one year;
later than one year and not later than five years;
later than five years.
US GAAPS require disclosure of the amount to be paid in each of the next 5 years (year 1 to 5) by year, as well as the amount to be paid later than 5 years as a single amount.<br>
slide14. IAS 17 – Leases (continued) IASB / FASB Convergence project
The IASB published IFRS 16 Leases in January 2016 with an effective date of 1 January 2019.
The new standard requires lessees to recognise nearly all leases on the balance sheet which will reflect their right to use an asset for a period of time and the associated liability for payments.
lessees will be greatly affected by the new leases standard. The lessors’ accounting largely remains unchanged
exempted short term leases and low value asset leases
The new standard will affect virtually all commonly used financial ratios and performance metrics<br>
slide15. IFRS 16 – Leases Para 9:At inception of a contract, an entity shall assess whether the contract is, or contains, a lease. A contract is, or contains, a lease if the contract conveys the right to control the use of an identified asset for a period of time in exchange for consideration. Paragraphs B9–B31 set out guidance on the assessment of whether a contract is, or contains, a lease.
B9 : To assess whether a contract conveys the right to control the use of an identified asset (see paragraphs B13–B20) for a period of time, an entity shall assess whether, throughout the period of use, the customer has both of the following:
(a) the right to obtain substantially all of the economic benefits from use of the identified asset (as described in paragraphs B21–B23); and
(b) the right to direct the use of the identified asset (as described in paragraphs B24–B30).<br>
slide16. Covid-19-related Rent Concessions – Amendment to IFRS 16 Key requirements
Optional practical expedient to IFRS 16 Leases.
It allows lessees not to account for rent concessions as a lease modification if they are a direct consequence of Covid-19 and only if all the following conditions are met;
the revised consideration is substantially the same or less than the original consideration;
the reduction in lease payments relates to payments due on or before 30 June 2021; and
no other substantive changes have been made to the terms of the lease 16<br>
slide17. Covid-19-related Rent Concessions – Amendment to IFRS 16 Key requirements 17<br>
slide18. Covid-19-related Rent Concessions – Amendment to IFRS 16 Accounting for a lease modification – Application of modification due to Covid-19 18<br>
slide19. Covid-19-related Rent Concessions – Amendment to IFRS 16 Key requirements 19<br>
slide20. Covid-19-related Rent Concessions – Amendment to IFRS 16 20 Example disclosures if lessee elects to apply the practical expedients
Rent concessions
The Group negotiated rent concessions with its landlords for the majority of its retail store leases as a result of the severe impact of the COVID-19 pandemic during the year. The Group also negotiated rent concessions for certain of its leases of distribution vehicles. The Group applied the practical expedient for COVID-19-related rent concessions consistently to eligible rent concessions relating to its retail store leases. The Group continues to account for rent concessions relating to its distribution vehicle leases under other applicable guidance in IFRS 16.
The amount recognised in profit or loss for the reporting period to reflect changes in lease payments arising from rent concessions to which the Group has applied the practical expedient for COVID-19-related rent concessions is CU 500 thousand (2019: nil).<br>
slide21. Covid-19-related Rent Concessions – Amendment to IFRS 16 21 Example 1 At 31 March 2020 a lessee has a lease liability. The lease contract requires monthly lease payment of CU100. The analysis below sets out the accounting for the lease liability in different scenarios. In all scenarios rent concession occur as a direct consequence of the COVID-19 pandemic.<br>
slide22. Covid-19-related Rent Concessions- Amendment to IFRS 16 Accounting treatment
No lease payments from Apr- Jun
April to June Identifying Negative variable lease payment Dr. Lease liability CU 300 Cr. P&L CU 300
Accrued Interest Dr. Interest expense Cr. Lease liability July to September
Dr. Lease liability CU 300
Cr. Cash CU 300
Dr. Interest expense
Cr. Lease liability 22 Scenario 1 Forgiveness of lease payments from April- June, and no change from July -Sep<br>
slide23. Deferred lease payments (from April- June).
Accounting treatment
April to June
No lease payments from April- June
Accrued Interest.
Dr. Interest expense
Cr. Lease liability Deferred payments shall pay from July- Sept by CU 300
July to Sept
Dr. lease liability CU 600
Cr. Cash CU 600
Accrued Interest.
Dr. Interest expense
Cr. Lease liability 23 Scenario 2 Covid-19-related Rent Concessions- Amendment to IFRS 16<br>
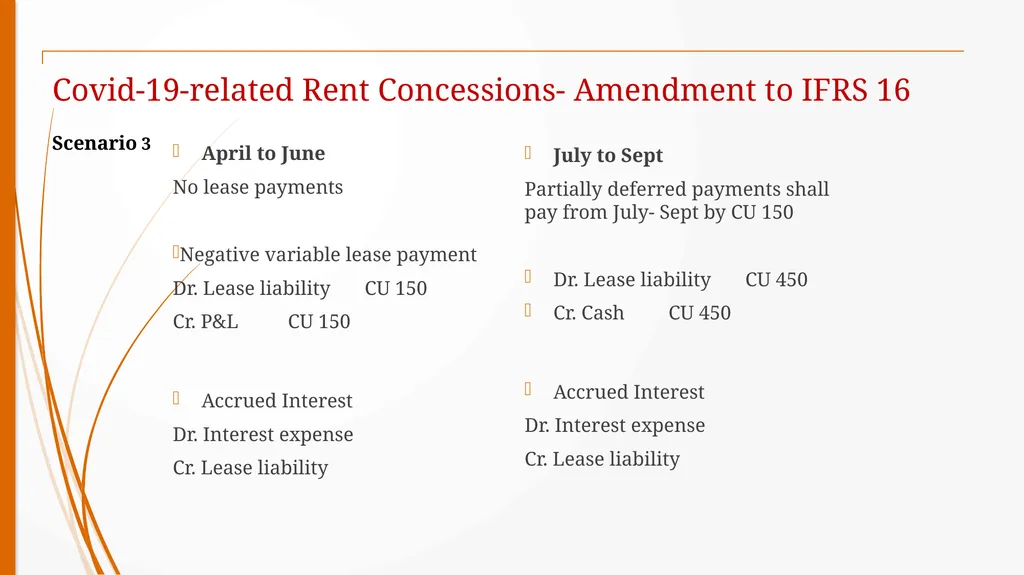
slide24. April to June
No lease payments
Negative variable lease payment
Dr. Lease liability CU 150
Cr. P&L CU 150
Accrued Interest
Dr. Interest expense
Cr. Lease liability July to Sept
Partially deferred payments shall pay from July- Sept by CU 150
Dr. Lease liability CU 450
Cr. Cash CU 450
Accrued Interest
Dr. Interest expense
Cr. Lease liability 24 Covid-19-related Rent Concessions- Amendment to IFRS 16 Scenario 3<br>
slide25. Covid-19-related Rent Concessions- Amendment to IFRS 16 Scenario 4 Rebate provided by lessor (from April- June) April to June
Lessee already paid CU 300 for Apr- Jun, lessor agreed to refund
Dr. Lease liability /Receivable/Cash CU 300
Cr. P&L CU 300
Accrued Interest.
Dr. Interest expense
Cr. Lease liability July to Sept
Dr. lease liability CU 300
Cr. Cash CU 300
Accrued Interest.
Dr. Interest expense
Cr. Lease liability 25<br>
slide26. Covid-19-related Rent Concessions- Amendment to IFRS 16 Scenario 5 Three months rent holiday by lessor (from April- June) April to June
Accrued Interest.
Dr. Interest expense
Cr. Lease liability
Lessee doesn’t have to apply para 40, If the lessee elects the practical expedient, the lessee doesn’t remeasure the lease liability using a revised discount rate but remeasures the lease liability using unchanged discount rate. No adjustment to the ROU. ROU will be depreciated prospectively over the longer lease term 26<br>
slide27. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 2 Lessee X enters into a 20-year lease of office space with Lessor Y. The annual lease payments are 150,000 payable in arrears and X’s incremental borrowing rate at commencement of the lease is 5%. X does not provide any residual value guarantee. There are no initial direct costs, lease incentives or other payments between X and Y.
Therefore, X initially recognises the lease liability and right-of-use asset at CU 1,869,332 each.
At the end of Year 10, due to the Covid pandemic, X and Y agree to reduce the lease payments to CU 100,000 payable in arrears which is due on 30 June 2020 till the end of the lease term. At this date, the lease liability is CU 1,158,260, the right-of-use asset is CU 934,666 and X’s incremental borrowing rate is 6% (assume that the interest rate implicit in the lease cannot be readily determined). 27<br>
slide28. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 2 Continued In this example, the entire rent concession would fail the 2nd criterion of “reduction in lease payments relates to payments due on or before 30 June 2021” and due that practical expedient would be unavailable.
Rent concessions are not permitted to be ‘sub-divided’ into a portion that satisfies the criterion (i.e. 30 June 2020 – 30 June 2021) and a portion that does not satisfy the criterion (1 July 2021 – end of the lease term). The criterion is assessed for the rent concession in its entirety.
Therefore, this should be accounted as a lease modification. 28<br>
slide29. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 2 Continued The modification does not grant X an additional right of use and therefore cannot be accounted for as a separate lease.
X remeasures the lease liability at CU 736,009 based on: – annual lease payments payable in arrears of 100,000; – a remaining lease term of 10 years; and – a revised incremental borrowing rate of 6%.
CU 100,000/1.06 + CU 100,000/1.062 + CU 100,000/1.063 +………. CU 100,000/1.069 + CU 100,000/1.0610= CU 736,009
X recognises the difference between the carrying amount of the lease liability before the modification (CU 1,158,260) and the carrying amount of the modified lease liability (CU 736,009) of CU 422,251 as an adjustment to the right-of-use asset. 29<br>
slide30. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 A lessee enters into a lease for 5,000 square metres of office space for 10 years. The lease payments are fixed at CU 50,000 per annum. After five years, due to the Covid pandemic, the parties amend the contract to reduce the office space by 2,500 square metres. From year 6 onwards (till the end of the lease term), i.e. rent due from 30 June 2020, the annual lease payments will be CU 30,000. At the beginning of year 6, the lessee’s incremental borrowing rate is 5% (assume that the rate implicit in the lease at that date is not readily determinable).
The carrying amounts of the lease liability and right-of-use asset before modification are as follows:
Right-of-use asset CU 184,002
Lease liability CU 210,618
. 30<br>
slide31. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 Continued In this example,
In addition to the rent concession, space also has been reduced.
This would be a substantive change to other terms and conditions, and therefore criteria 3 is not met.
The practical expedient would be unavailable for that rent concession 31<br>
slide32. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 Continued The value of the lease liability after the modification is CU 129,884
(= CU 30,000/1.05 + CU 30,000/1.052 + CU 30,000/1.053 + CU 30,000/1.054 + CU 30,000/1.055).
In a first step, the right-of-use asset and the lease liability are reduced by 50%, because the original office space is reduced by 50%. The difference between these two amounts is recognised as a gain in profit or loss:
50% of carrying amount before modification
Lease liability = CU 210,618/2= CU 105,309
Right of use asset = CU 184,002/2= CU 92,001
Dr. Lease liability CU 105,309
Cr. Right-of-use asset CU 92,001
Cr. Gain CU 13,308 32<br>
slide33. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 Continued In a second step, the right-of-use asset has to be adjusted to reflect the updated discount rate and the change in the consideration. Accordingly, the difference between the remaining lease liability (CU 105,309) and the modified lease liability (CU 129,884) is recognised as an adjustment to the right-of-use asset:
Dr. Right-of-use asset CU 24,575
Cr. Lease liability CU 24,575 33<br>
slide34. Covid-19-related Rent Concessions- Amendment to IFRS 16 Impact
The amendment to IFRS 16 simplifies the accounting requirement for lessees.
A lessee is still required to assess each rent concession against the criteria established by the practical expedient.
The practical expedient is not available for lessor. 34<br>
slide35. Disclosure and presentation standards<br>
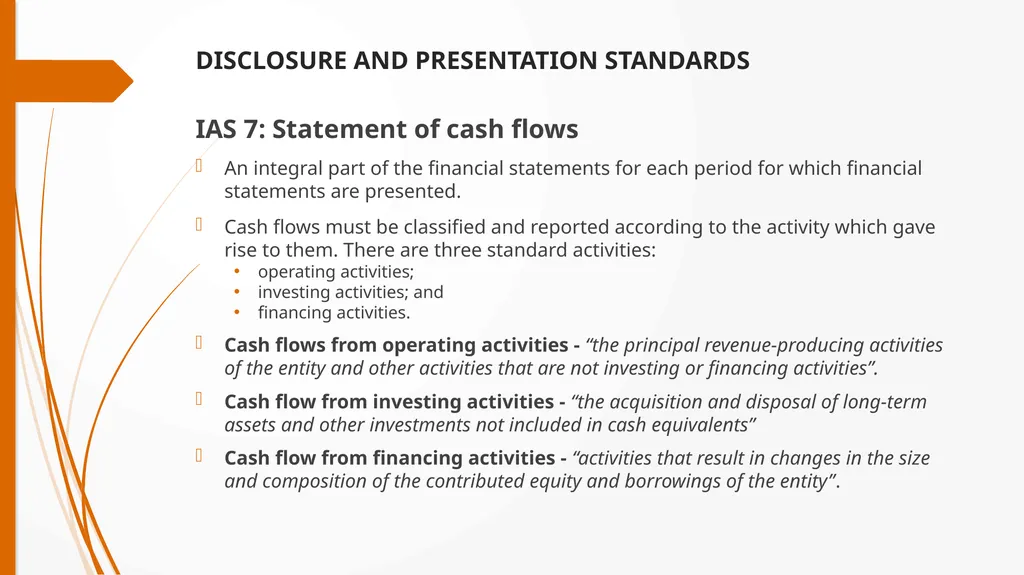
slide36. Disclosure and presentation standards IAS 7: Statement of cash flows
An integral part of the financial statements for each period for which financial statements are presented.
Cash flows must be classified and reported according to the activity which gave rise to them. There are three standard activities:
operating activities;
investing activities; and
financing activities.
Cash flows from operating activities - “the principal revenue-producing activities of the entity and other activities that are not investing or financing activities”.
Cash flow from investing activities - “the acquisition and disposal of long-term assets and other investments not included in cash equivalents”
Cash flow from financing activities - “activities that result in changes in the size and composition of the contributed equity and borrowings of the entity”.<br>
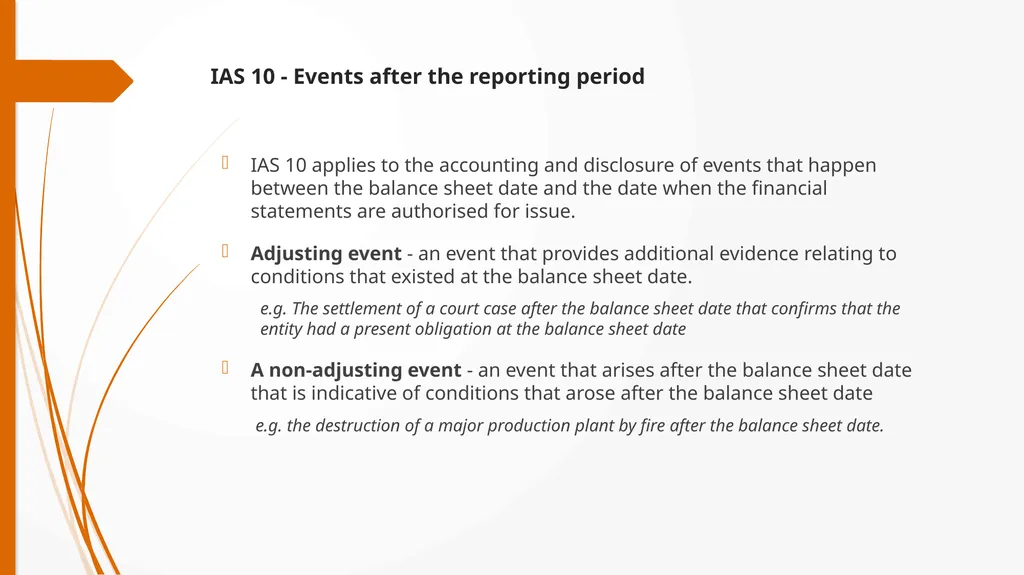
slide37. IAS 10 - Events after the reporting period IAS 10 applies to the accounting and disclosure of events that happen between the balance sheet date and the date when the financial statements are authorised for issue.
Adjusting event - an event that provides additional evidence relating to conditions that existed at the balance sheet date.
e.g. The settlement of a court case after the balance sheet date that confirms that the entity had a present obligation at the balance sheet date
A non-adjusting event - an event that arises after the balance sheet date that is indicative of conditions that arose after the balance sheet date
e.g. the destruction of a major production plant by fire after the balance sheet date.<br>
slide38. IAS 24 - Related party disclosures IAS 24’s objective is to ensure that financial statements contain the disclosures necessary to draw attention to the possibility that the reported financial position and results might have been affected by the existence of related parties and by transactions and outstanding balances, including commitments, with them.
‘Related parties’ of an entity includes:
Persons with control or joint control over the reporting entity;
Persons with significant influence over the reporting entity; or
Members of the key management personnel of the reporting entity or of a parent of the reporting entity.
Members of the same group (e.g. fellow subsidiaries of a group)
Required disclosures include
Names and the nature of the relationship with related parties
Amount of transactions with related parties.
Balances outstanding at year-end from related parties
Key management remuneration<br>
slide39. IAS 33 - Earnings per share Basic EPS = Profit or loss / weighted Average number of shares
IAS 33 applies to the following entities:
Those whose ordinary shares are traded in a public market.
Those that file, or are in the process of filing, financial statements with a securities commission or other regulatory body for the purpose of issuing ordinary shares in a public market.
Widely used to gauge an entity’s profitability and to value its shares.
Diluted Earnings per share - Profit or loss / (weighted Average number of shares +All dilutive potential ordinary shares)<br>
slide40. IFRS 8 Operating segments Enables users to evaluate results of segments
IFRS 8 applies to the following entities:
Those whose ordinary shares are traded in a public market.
Those who are in the process of issuing ordinary shares in a public market.
An operating segment is defined as a component of an entity:
that engages in business activities from which it could earn revenues and incur expenses;
whose operating results reviewed by the entity’s CODM (Chief Operating Decision Maker) to make decisions about resources to be allocated to the segment and assess its performance; and
for which discrete financial information is available.
Specified amounts that should be disclosed:
Revenues from external customers; inter-segment revenue; interest revenue; interest expense; depreciation and amortisation; income tax expense or income; and material non-cash items other than depreciation and amortisation<br>
slide2. INTERNATIONAL FINANCIAL REPORTING STANDARDS (IFRSs) IFRSs are the set of most commonly adopted generally accepted accounting principles worldwide.
This module describes and demonstrates the requirements of selected IFRSs and also makes comparison to US GAAPs to indicate differences and similarities.
The type of differences between US GAAPs and IFRS will include: definition differences, recognition differences, measurement differences, alternative accounting treatments available, lack of requirements or guidance, presentation differences, disclosure differences<br>
slide3. IAS 2 - Inventories Recognition: An entity should initially recognise inventory when it has control of the inventory, expects it to provide future economic benefits, and the cost of the inventory can be measured reliably.
Measurement: Initial measurement of inventories should be at cost. After initial recognition, inventories should be measured at the lower of cost and net realisable value.
Definition of “Cost” - Cost is defined as all costs of purchase, costs of conversion and other costs incurred in bringing the inventories to their present location and condition.
Cost excludes: administrative overheads, abnormal losses, storage costs, selling costs
US GAAP vs IFRS
LIFO is only allowed under US GAAP
Reversal of inventory write downs prohibited under US GAAP. IFRS allows up to the original write down.<br>
slide4. IAS 16 – Property, plant and equipment Recognition: When it is probable that future economic benefits associated with the item will flow to the entity; and the cost of the item can be measured reliably.
Measurement: initially measured at cost.
Cost - costs of acquiring or constructing the asset and costs incurred subsequently to add to or replace part of the asset.
The purchase price
Directly attributable costs
costs of dismantling and removing the item and restoring the site
Borrowing costs on qualifying assets.
Subsequent measurement
US GAAP – cost model
IFRS – cost model / revaluation model
US GAAP vs IFRS
IFRS – component depreciation / annual review of residual value and life
US GAAP – no component depreciation / no explicit requirement for an annual review of residual values.<br>
slide5. IAS 40 – Investment property IFRS Definition - property (land and/or buildings) held in order to earn rentals and/or for capital appreciation.
Owner occupied property - PPE; Not IP
Property held for sale – Inventory; not IP
Initial measurement at cost (both IFRS and US GAAP)
Subsequent measurement
US GAAP – Cost model [Investor entities may measure at fair value]
IFRS – Cost model or Revaluation model
Leased property – fair value option available under IFRS / not available under US GAAP.<br>
slide6. IAS 36 – Impairment of assets An asset cannot be carried in the balance sheet at more than its recoverable amount.
An impairment review compares the asset’s recoverable amount with its carrying value.
Scope of IAS 36 excludes assets such as Inventories, Deferred tax assets, financial assets, investment property at FV, biological assets at FV.
IFRS – One step impairment test
US GAAP – two step impairment test
US GAAP do not allow impairment losses to be reversed. [Allowed under IFRS]<br>
slide7. IAS 38 – Intangible assets An intangible asset is defined as “an identifiable non-monetary asset without physical substance”
The key characteristics of an intangible asset are that it:
is a resource controlled by the entity from which the entity expects to derive future economic benefits;
lacks physical substance;
is identifiable to be distinguished from goodwill.
Revaluation model - IAS 38 Allows the use of the revaluation model for intangible assets with finite lives, but only if the intangible asset has a price that is available on an active market. Revaluation of intangible assets is not allowed under US GAAPs.
An intangible asset could be acquired in following ways:
Purchased from an external party.
Acquired in a business combination
Internally generated intangibles<br>
slide8. IAS 38 – Intangible assets (continued) Purchased intangibles - measured on initial recognition at cost.
Finite life (e.g. a 5 year copy right) – cost is amortised on a systematic basis over the useful life.
Infinite life (e.g. Goodwill) – No amortization. Asset is assessed for impairment annually.
Acquired in a business combination - measured fair value at the acquisition date;
should be recognized as an asset apart from goodwill.
Its useful life is assed as finite or infinite
Internally generated intangibles
Costs associated with the creation of intangible assets are classified into research phase costs and development phase costs.
Research costs – always expensed
Development costs – capitalized if the six qualifying criteria are met
In general, both research costs and development costs are expensed as incurred under US GAAPs.<br>
slide9. IAS 23 – Borrowing costs Prior to the revision of IAS 23, it provided two methods of accounting for borrowing costs.
Benchmark treatment: expense all borrowing costs in the period incurred.
Allowed alternative treatment: capitalize borrowing costs to the extent they are attributable to the acquisition, construction or production of a qualifying asset; other borrowing costs are expensed as incurred.
Adoption of the benchmark treatment was not acceptable under US GAAP. Under the IASB-FASB convergence project, IAS 27 was revised in 2007, whereby the benchmark treatment was eliminated.
Borrowing costs under IFRS are broader and can include more components than interest costs under US GAAP. E.g. IAS 23 specifically includes foreign exchange gains/losses on foreign currency borrowings.<br>
slide10. IAS 17 - Leases A lease is defined as an agreement whereby the lessor conveys to the lessee in return for a payment or series of payments the right to use an asset for an agreed period of time.
All leases must be classified as either finance leases or operating leases.
A finance lease is defined as “... a lease that transfers substantially all the risks and rewards incidental to ownership of an asset”. Thus, a finance lease is an arrangement that has the substance of a financing transaction for the lessee to acquire effective economic ownership of an asset.
An operating lease is “... a lease other than a finance lease”.
The classification is based on the extent to which risks and rewards incidental to ownership of a leased asset lie with the lessor or the lessee.<br>
slide11. IAS 17 – Leases (continued) Finance lease indicators:
The lease transfers ownership of the asset to the lessee by the end of the lease term.
The lessee has the option to purchase the asset at a bargain price.
The lease term is for the major part of the economic life of the asset.
At the inception, the present value of the minimum lease payments amounts to at least substantially all of the fair value of the leased asset.
The leased assets are of a specialised nature such that only the lessee can use them without major modifications being made.
The following situations, individually or in combination, also could also lead to a finance lease classification:
If the lessee can cancel the lease, the lessor’s losses associated with the cancellation are borne by the lessee.
Gains or losses from the fluctuation in the residual’s fair value fall to the lessee.
The lessee has the ability to continue the lease for a secondary period at a rent that is substantially lower than market rent.<br>
slide12. IAS 17 – Leases (continued) Accounting for finance leases
Leased assets and leased liabilities are presented separately and gross in the balance sheet.
the sum to be recognized : lower of the fair value of the leased asset and the present value of the minimum lease payments.
Discount factor is the interest rate implicit in the lease; or Lessee’s incremental borrowing rate
An asset leased under a finance lease should be depreciated over the shorter of the lease term and its useful life.
Accounting for operating leases
Operating leases should not be capitalised
Lease payments made under operating leases should be recognised as an expense on a straight-line basis over the lease term.<br>
slide13. IAS 17 – Leases (continued) Accounting for sale and leaseback transactions - Finance leasebacks
A finance leaseback is essentially a financing operation for the seller.
The seller/lessee never disposes of the risks and rewards of ownership of the asset.
Should not recognise a profit or loss on the sale.
Any apparent profit (that is, the difference between the sale price and the previous carrying value) should be deferred and amortised over the lease term.
Operating leases – Disclosures
Lessees shall make the following disclosures for operating leases:
The total of future minimum lease payments under non-cancellable operating leases for each of the following periods:
not later than one year;
later than one year and not later than five years;
later than five years.
US GAAPS require disclosure of the amount to be paid in each of the next 5 years (year 1 to 5) by year, as well as the amount to be paid later than 5 years as a single amount.<br>
slide14. IAS 17 – Leases (continued) IASB / FASB Convergence project
The IASB published IFRS 16 Leases in January 2016 with an effective date of 1 January 2019.
The new standard requires lessees to recognise nearly all leases on the balance sheet which will reflect their right to use an asset for a period of time and the associated liability for payments.
lessees will be greatly affected by the new leases standard. The lessors’ accounting largely remains unchanged
exempted short term leases and low value asset leases
The new standard will affect virtually all commonly used financial ratios and performance metrics<br>
slide15. IFRS 16 – Leases Para 9:At inception of a contract, an entity shall assess whether the contract is, or contains, a lease. A contract is, or contains, a lease if the contract conveys the right to control the use of an identified asset for a period of time in exchange for consideration. Paragraphs B9–B31 set out guidance on the assessment of whether a contract is, or contains, a lease.
B9 : To assess whether a contract conveys the right to control the use of an identified asset (see paragraphs B13–B20) for a period of time, an entity shall assess whether, throughout the period of use, the customer has both of the following:
(a) the right to obtain substantially all of the economic benefits from use of the identified asset (as described in paragraphs B21–B23); and
(b) the right to direct the use of the identified asset (as described in paragraphs B24–B30).<br>
slide16. Covid-19-related Rent Concessions – Amendment to IFRS 16 Key requirements
Optional practical expedient to IFRS 16 Leases.
It allows lessees not to account for rent concessions as a lease modification if they are a direct consequence of Covid-19 and only if all the following conditions are met;
the revised consideration is substantially the same or less than the original consideration;
the reduction in lease payments relates to payments due on or before 30 June 2021; and
no other substantive changes have been made to the terms of the lease 16<br>
slide17. Covid-19-related Rent Concessions – Amendment to IFRS 16 Key requirements 17<br>
slide18. Covid-19-related Rent Concessions – Amendment to IFRS 16 Accounting for a lease modification – Application of modification due to Covid-19 18<br>
slide19. Covid-19-related Rent Concessions – Amendment to IFRS 16 Key requirements 19<br>
slide20. Covid-19-related Rent Concessions – Amendment to IFRS 16 20 Example disclosures if lessee elects to apply the practical expedients
Rent concessions
The Group negotiated rent concessions with its landlords for the majority of its retail store leases as a result of the severe impact of the COVID-19 pandemic during the year. The Group also negotiated rent concessions for certain of its leases of distribution vehicles. The Group applied the practical expedient for COVID-19-related rent concessions consistently to eligible rent concessions relating to its retail store leases. The Group continues to account for rent concessions relating to its distribution vehicle leases under other applicable guidance in IFRS 16.
The amount recognised in profit or loss for the reporting period to reflect changes in lease payments arising from rent concessions to which the Group has applied the practical expedient for COVID-19-related rent concessions is CU 500 thousand (2019: nil).<br>
slide21. Covid-19-related Rent Concessions – Amendment to IFRS 16 21 Example 1 At 31 March 2020 a lessee has a lease liability. The lease contract requires monthly lease payment of CU100. The analysis below sets out the accounting for the lease liability in different scenarios. In all scenarios rent concession occur as a direct consequence of the COVID-19 pandemic.<br>
slide22. Covid-19-related Rent Concessions- Amendment to IFRS 16 Accounting treatment
No lease payments from Apr- Jun
April to June Identifying Negative variable lease payment Dr. Lease liability CU 300 Cr. P&L CU 300
Accrued Interest Dr. Interest expense Cr. Lease liability July to September
Dr. Lease liability CU 300
Cr. Cash CU 300
Dr. Interest expense
Cr. Lease liability 22 Scenario 1 Forgiveness of lease payments from April- June, and no change from July -Sep<br>
slide23. Deferred lease payments (from April- June).
Accounting treatment
April to June
No lease payments from April- June
Accrued Interest.
Dr. Interest expense
Cr. Lease liability Deferred payments shall pay from July- Sept by CU 300
July to Sept
Dr. lease liability CU 600
Cr. Cash CU 600
Accrued Interest.
Dr. Interest expense
Cr. Lease liability 23 Scenario 2 Covid-19-related Rent Concessions- Amendment to IFRS 16<br>
slide24. April to June
No lease payments
Negative variable lease payment
Dr. Lease liability CU 150
Cr. P&L CU 150
Accrued Interest
Dr. Interest expense
Cr. Lease liability July to Sept
Partially deferred payments shall pay from July- Sept by CU 150
Dr. Lease liability CU 450
Cr. Cash CU 450
Accrued Interest
Dr. Interest expense
Cr. Lease liability 24 Covid-19-related Rent Concessions- Amendment to IFRS 16 Scenario 3<br>
slide25. Covid-19-related Rent Concessions- Amendment to IFRS 16 Scenario 4 Rebate provided by lessor (from April- June) April to June
Lessee already paid CU 300 for Apr- Jun, lessor agreed to refund
Dr. Lease liability /Receivable/Cash CU 300
Cr. P&L CU 300
Accrued Interest.
Dr. Interest expense
Cr. Lease liability July to Sept
Dr. lease liability CU 300
Cr. Cash CU 300
Accrued Interest.
Dr. Interest expense
Cr. Lease liability 25<br>
slide26. Covid-19-related Rent Concessions- Amendment to IFRS 16 Scenario 5 Three months rent holiday by lessor (from April- June) April to June
Accrued Interest.
Dr. Interest expense
Cr. Lease liability
Lessee doesn’t have to apply para 40, If the lessee elects the practical expedient, the lessee doesn’t remeasure the lease liability using a revised discount rate but remeasures the lease liability using unchanged discount rate. No adjustment to the ROU. ROU will be depreciated prospectively over the longer lease term 26<br>
slide27. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 2 Lessee X enters into a 20-year lease of office space with Lessor Y. The annual lease payments are 150,000 payable in arrears and X’s incremental borrowing rate at commencement of the lease is 5%. X does not provide any residual value guarantee. There are no initial direct costs, lease incentives or other payments between X and Y.
Therefore, X initially recognises the lease liability and right-of-use asset at CU 1,869,332 each.
At the end of Year 10, due to the Covid pandemic, X and Y agree to reduce the lease payments to CU 100,000 payable in arrears which is due on 30 June 2020 till the end of the lease term. At this date, the lease liability is CU 1,158,260, the right-of-use asset is CU 934,666 and X’s incremental borrowing rate is 6% (assume that the interest rate implicit in the lease cannot be readily determined). 27<br>
slide28. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 2 Continued In this example, the entire rent concession would fail the 2nd criterion of “reduction in lease payments relates to payments due on or before 30 June 2021” and due that practical expedient would be unavailable.
Rent concessions are not permitted to be ‘sub-divided’ into a portion that satisfies the criterion (i.e. 30 June 2020 – 30 June 2021) and a portion that does not satisfy the criterion (1 July 2021 – end of the lease term). The criterion is assessed for the rent concession in its entirety.
Therefore, this should be accounted as a lease modification. 28<br>
slide29. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 2 Continued The modification does not grant X an additional right of use and therefore cannot be accounted for as a separate lease.
X remeasures the lease liability at CU 736,009 based on: – annual lease payments payable in arrears of 100,000; – a remaining lease term of 10 years; and – a revised incremental borrowing rate of 6%.
CU 100,000/1.06 + CU 100,000/1.062 + CU 100,000/1.063 +………. CU 100,000/1.069 + CU 100,000/1.0610= CU 736,009
X recognises the difference between the carrying amount of the lease liability before the modification (CU 1,158,260) and the carrying amount of the modified lease liability (CU 736,009) of CU 422,251 as an adjustment to the right-of-use asset. 29<br>
slide30. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 A lessee enters into a lease for 5,000 square metres of office space for 10 years. The lease payments are fixed at CU 50,000 per annum. After five years, due to the Covid pandemic, the parties amend the contract to reduce the office space by 2,500 square metres. From year 6 onwards (till the end of the lease term), i.e. rent due from 30 June 2020, the annual lease payments will be CU 30,000. At the beginning of year 6, the lessee’s incremental borrowing rate is 5% (assume that the rate implicit in the lease at that date is not readily determinable).
The carrying amounts of the lease liability and right-of-use asset before modification are as follows:
Right-of-use asset CU 184,002
Lease liability CU 210,618
. 30<br>
slide31. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 Continued In this example,
In addition to the rent concession, space also has been reduced.
This would be a substantive change to other terms and conditions, and therefore criteria 3 is not met.
The practical expedient would be unavailable for that rent concession 31<br>
slide32. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 Continued The value of the lease liability after the modification is CU 129,884
(= CU 30,000/1.05 + CU 30,000/1.052 + CU 30,000/1.053 + CU 30,000/1.054 + CU 30,000/1.055).
In a first step, the right-of-use asset and the lease liability are reduced by 50%, because the original office space is reduced by 50%. The difference between these two amounts is recognised as a gain in profit or loss:
50% of carrying amount before modification
Lease liability = CU 210,618/2= CU 105,309
Right of use asset = CU 184,002/2= CU 92,001
Dr. Lease liability CU 105,309
Cr. Right-of-use asset CU 92,001
Cr. Gain CU 13,308 32<br>
slide33. Covid-19-related Rent Concessions- Amendment to IFRS 16 Example- 3 Continued In a second step, the right-of-use asset has to be adjusted to reflect the updated discount rate and the change in the consideration. Accordingly, the difference between the remaining lease liability (CU 105,309) and the modified lease liability (CU 129,884) is recognised as an adjustment to the right-of-use asset:
Dr. Right-of-use asset CU 24,575
Cr. Lease liability CU 24,575 33<br>
slide34. Covid-19-related Rent Concessions- Amendment to IFRS 16 Impact
The amendment to IFRS 16 simplifies the accounting requirement for lessees.
A lessee is still required to assess each rent concession against the criteria established by the practical expedient.
The practical expedient is not available for lessor. 34<br>
slide35. Disclosure and presentation standards<br>
slide36. Disclosure and presentation standards IAS 7: Statement of cash flows
An integral part of the financial statements for each period for which financial statements are presented.
Cash flows must be classified and reported according to the activity which gave rise to them. There are three standard activities:
operating activities;
investing activities; and
financing activities.
Cash flows from operating activities - “the principal revenue-producing activities of the entity and other activities that are not investing or financing activities”.
Cash flow from investing activities - “the acquisition and disposal of long-term assets and other investments not included in cash equivalents”
Cash flow from financing activities - “activities that result in changes in the size and composition of the contributed equity and borrowings of the entity”.<br>
slide37. IAS 10 - Events after the reporting period IAS 10 applies to the accounting and disclosure of events that happen between the balance sheet date and the date when the financial statements are authorised for issue.
Adjusting event - an event that provides additional evidence relating to conditions that existed at the balance sheet date.
e.g. The settlement of a court case after the balance sheet date that confirms that the entity had a present obligation at the balance sheet date
A non-adjusting event - an event that arises after the balance sheet date that is indicative of conditions that arose after the balance sheet date
e.g. the destruction of a major production plant by fire after the balance sheet date.<br>
slide38. IAS 24 - Related party disclosures IAS 24’s objective is to ensure that financial statements contain the disclosures necessary to draw attention to the possibility that the reported financial position and results might have been affected by the existence of related parties and by transactions and outstanding balances, including commitments, with them.
‘Related parties’ of an entity includes:
Persons with control or joint control over the reporting entity;
Persons with significant influence over the reporting entity; or
Members of the key management personnel of the reporting entity or of a parent of the reporting entity.
Members of the same group (e.g. fellow subsidiaries of a group)
Required disclosures include
Names and the nature of the relationship with related parties
Amount of transactions with related parties.
Balances outstanding at year-end from related parties
Key management remuneration<br>
slide39. IAS 33 - Earnings per share Basic EPS = Profit or loss / weighted Average number of shares
IAS 33 applies to the following entities:
Those whose ordinary shares are traded in a public market.
Those that file, or are in the process of filing, financial statements with a securities commission or other regulatory body for the purpose of issuing ordinary shares in a public market.
Widely used to gauge an entity’s profitability and to value its shares.
Diluted Earnings per share - Profit or loss / (weighted Average number of shares +All dilutive potential ordinary shares)<br>
slide40. IFRS 8 Operating segments Enables users to evaluate results of segments
IFRS 8 applies to the following entities:
Those whose ordinary shares are traded in a public market.
Those who are in the process of issuing ordinary shares in a public market.
An operating segment is defined as a component of an entity:
that engages in business activities from which it could earn revenues and incur expenses;
whose operating results reviewed by the entity’s CODM (Chief Operating Decision Maker) to make decisions about resources to be allocated to the segment and assess its performance; and
for which discrete financial information is available.
Specified amounts that should be disclosed:
Revenues from external customers; inter-segment revenue; interest revenue; interest expense; depreciation and amortisation; income tax expense or income; and material non-cash items other than depreciation and amortisation<br>