
Public Financial Disclosure Guide Changes in
Description: Public Financial Disclosure Guide Changes in Reporting Requirements and Review Standards May 12, 2016 Positions Filers need not report an unpaid position with an advisory committee for a state or local government, unless the filer had
Related Topics
Download Presentation
"Public Financial Disclosure Guide Changes in" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Public Financial Disclosure Guide Changes in Reporting Requirements
and Review Standards
May 12, 2016<br>
slide2. Positions Filers need not report an unpaid position with an advisory committee for a state or local government, unless the filer had fiduciary duties or was otherwise treated as an employee.
The Guide includes several FAQs regarding whether certain types of service results in a reportable positions.<br>
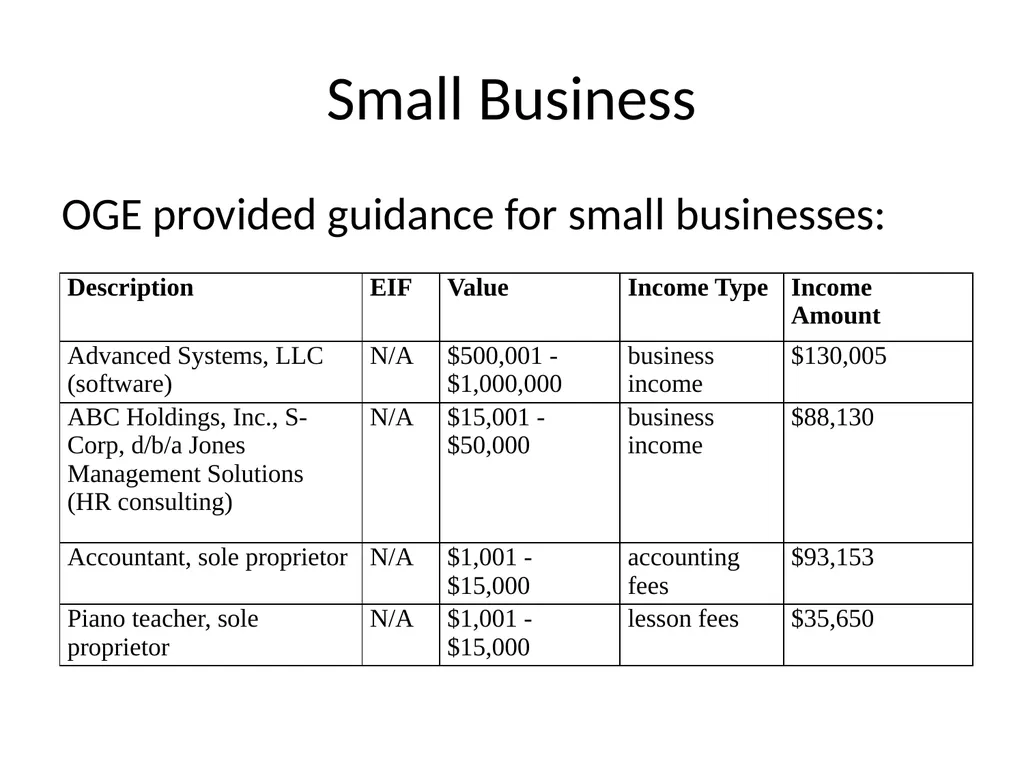
slide3. Small Business OGE provided guidance for small businesses:<br>
slide4. Business Assets and Liabilities You are not required to report assets and liabilities of a trade or business, unless those interests are unrelated to the operations of the business.
What constitutes “unrelated” will vary based on the specific circumstances; however, the following general guidelines apply:
Publicly traded corporations: Assets and liabilities of a publicly traded corporation are deemed to be related to the operations of the business for purposes of financial disclosure. Consequently, one need not perform any further test with respect to such interests.
Businesses that are not publicly traded: One needs to consider factors such as the type of asset or liability and its relationship to the economic activity conducted by the business.
No one factor is necessarily dispositive; however, in many cases, the type of asset itself will demonstrate a nexus between the asset and operations of the business, which removes the need for further analysis. For example, in OGE’s experience, a filer would not need to itemize office furniture, equipment, supplies, inventory, accounts receivable, accounts payable, working capital funds, real estate used in the operations of the business, or any mortgages on such real estate.<br>
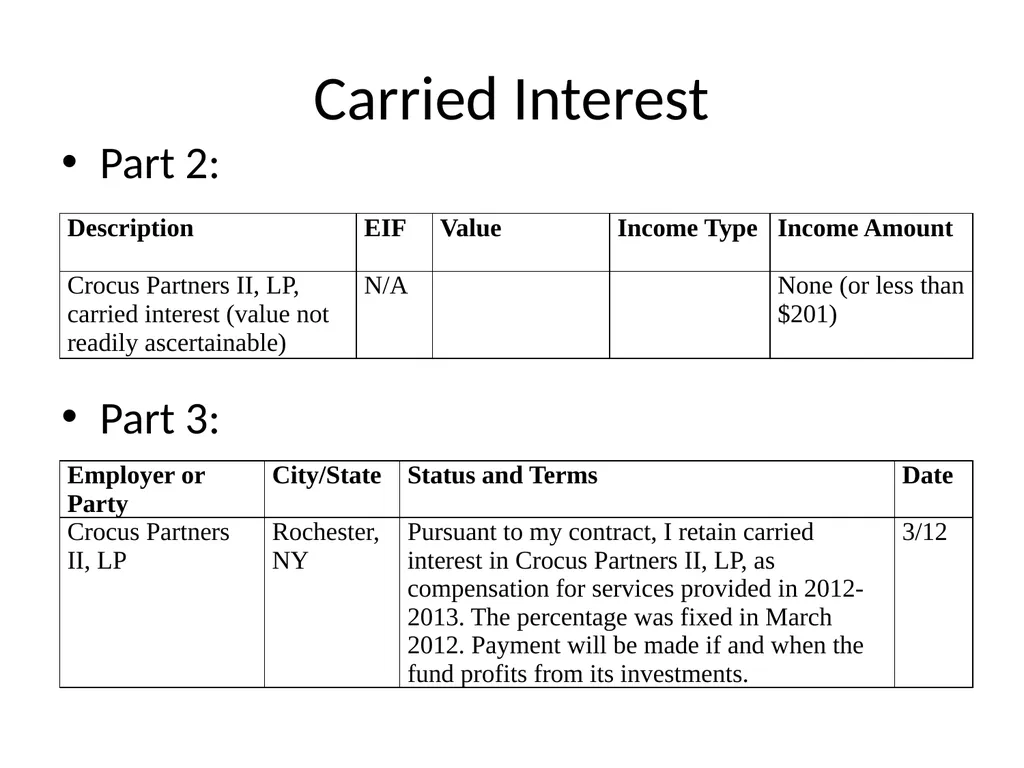
slide5. Carried Interest Part 2:
Part 3:<br>
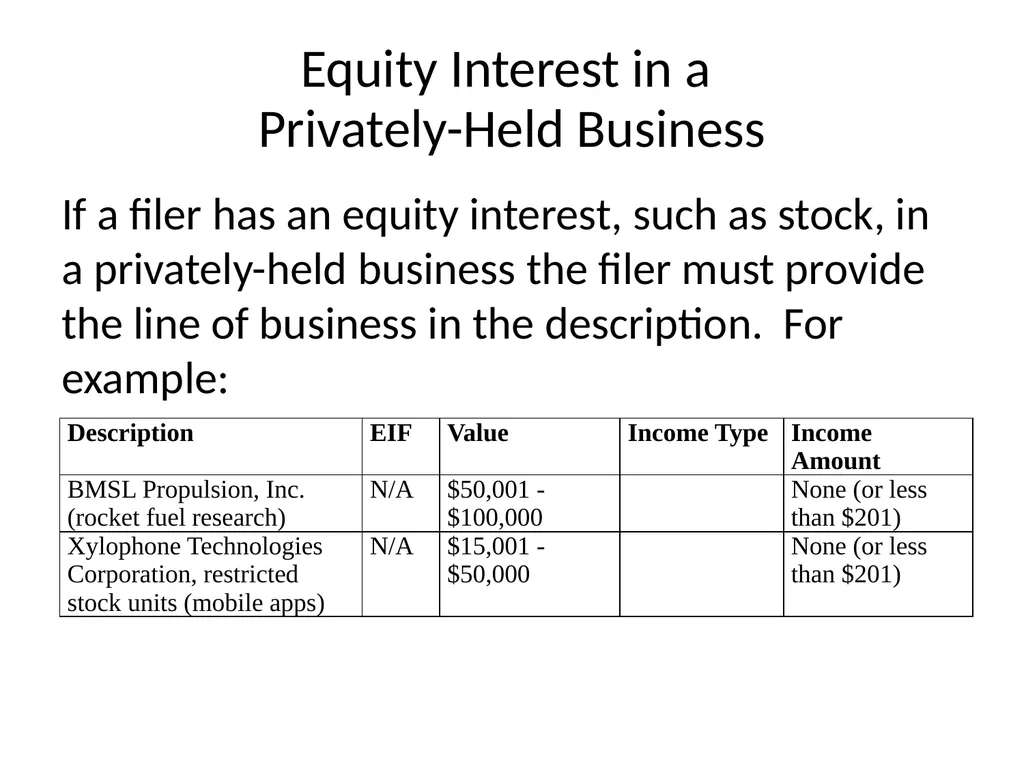
slide6. Equity Interest in a Privately-Held Business If a filer has an equity interest, such as stock, in a privately-held business the filer must provide the line of business in the description. For example:<br>
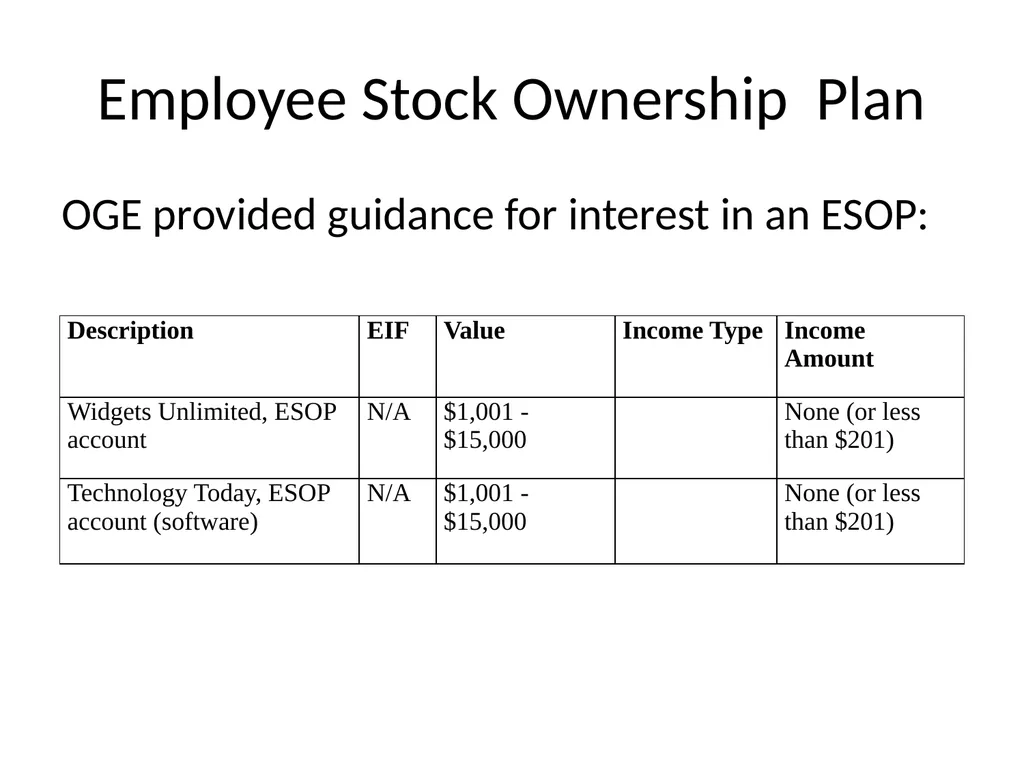
slide7. Employee Stock Ownership Plan OGE provided guidance for interest in an ESOP:<br>
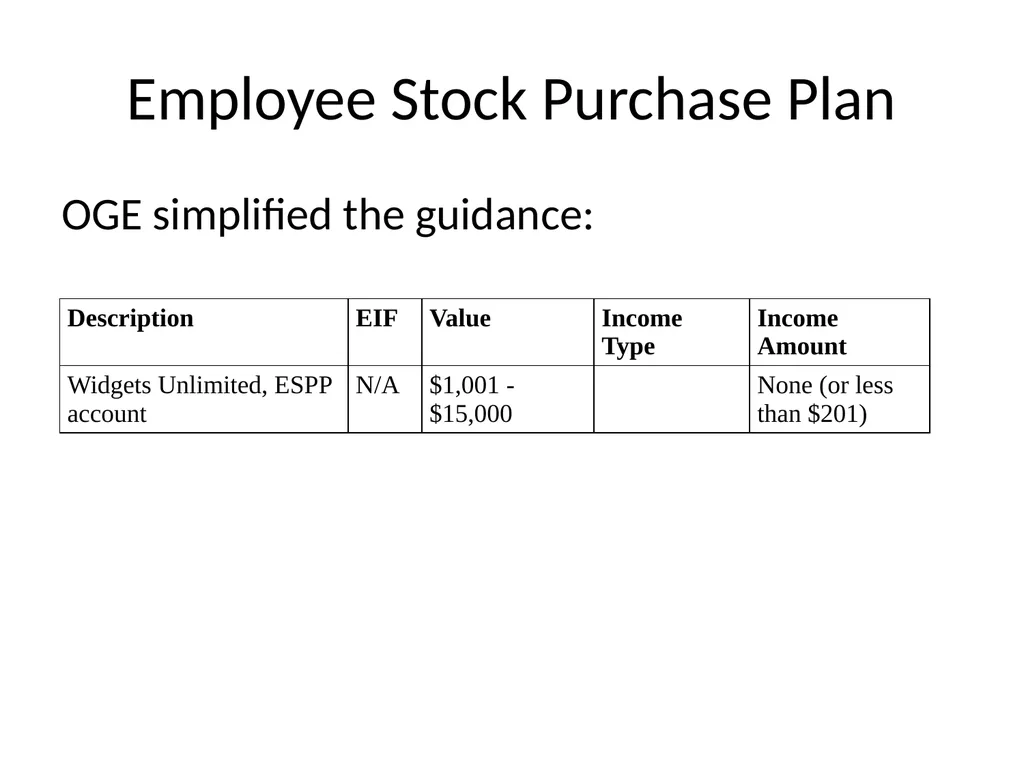
slide8. Employee Stock Purchase Plan OGE simplified the guidance:<br>
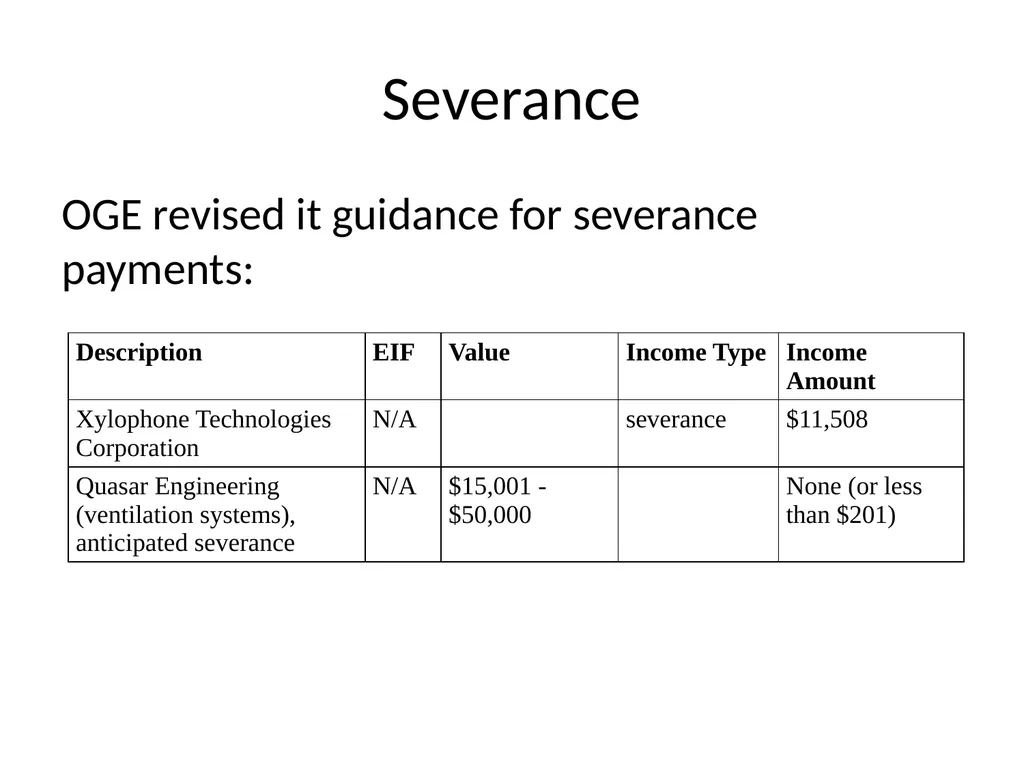
slide9. Severance OGE revised it guidance for severance payments:<br>
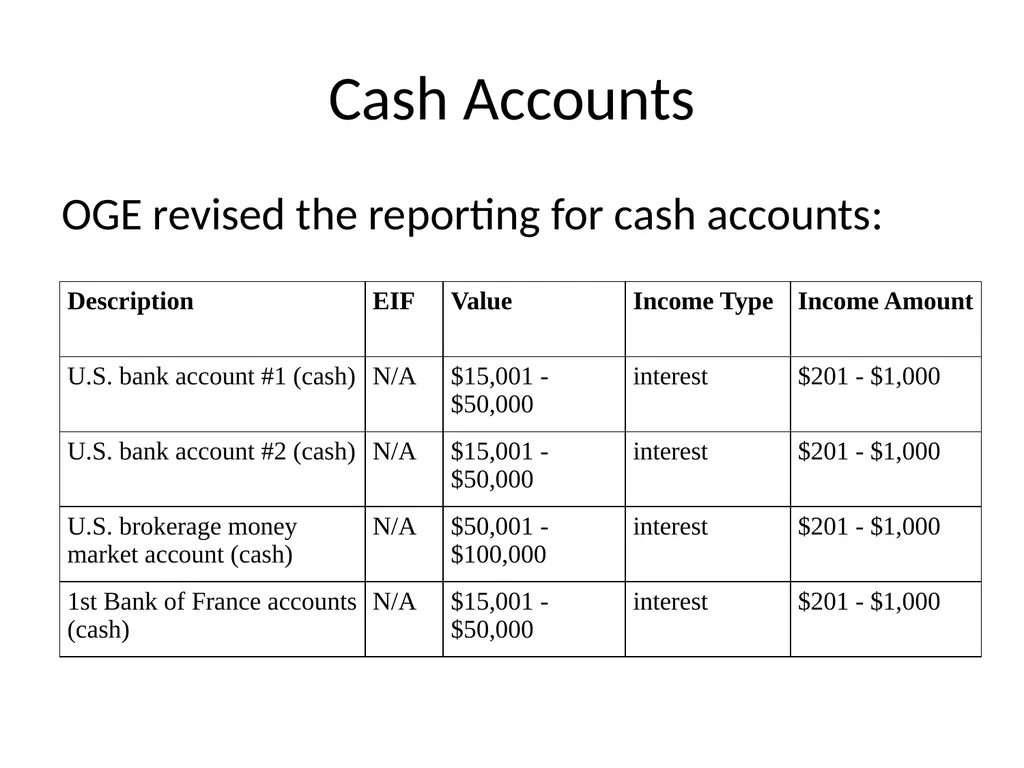
slide10. Cash Accounts OGE revised the reporting for cash accounts:<br>
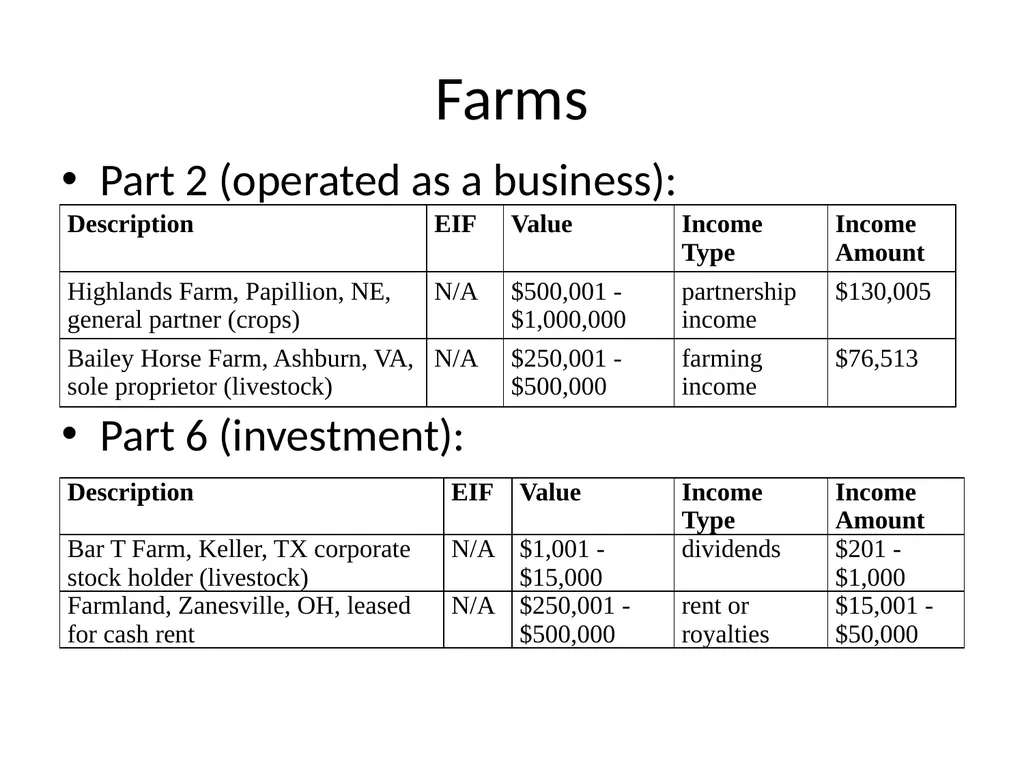
slide11. Farms Part 2 (operated as a business):
Part 6 (investment):<br>
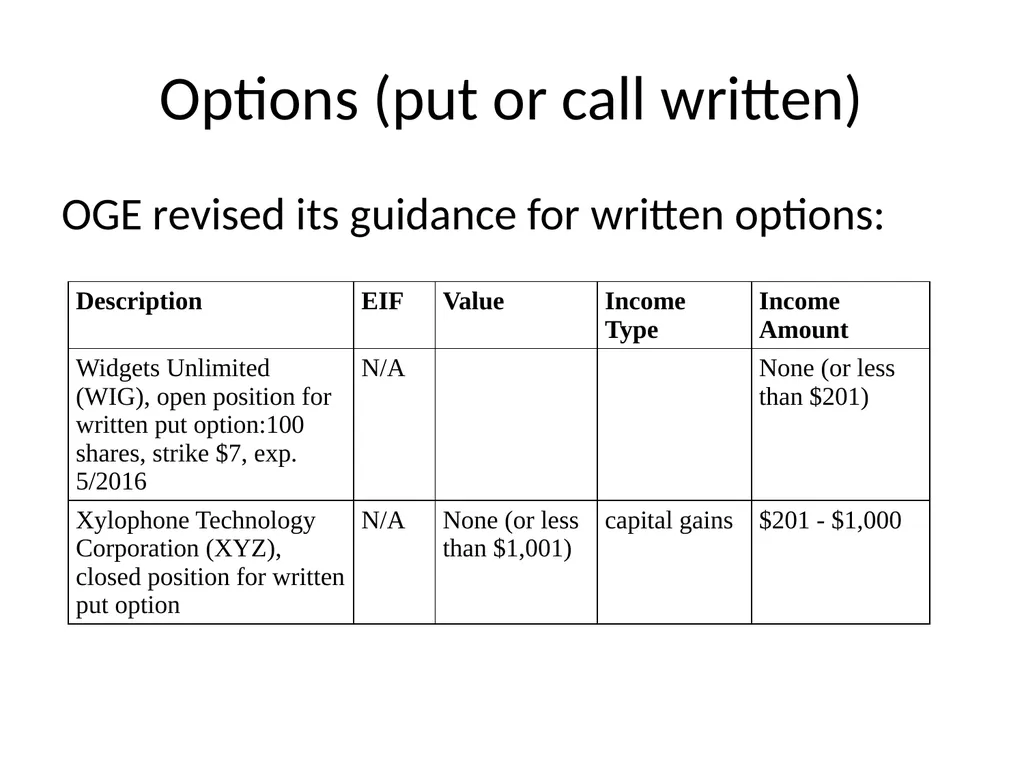
slide12. Options (put or call written) OGE revised its guidance for written options:<br>
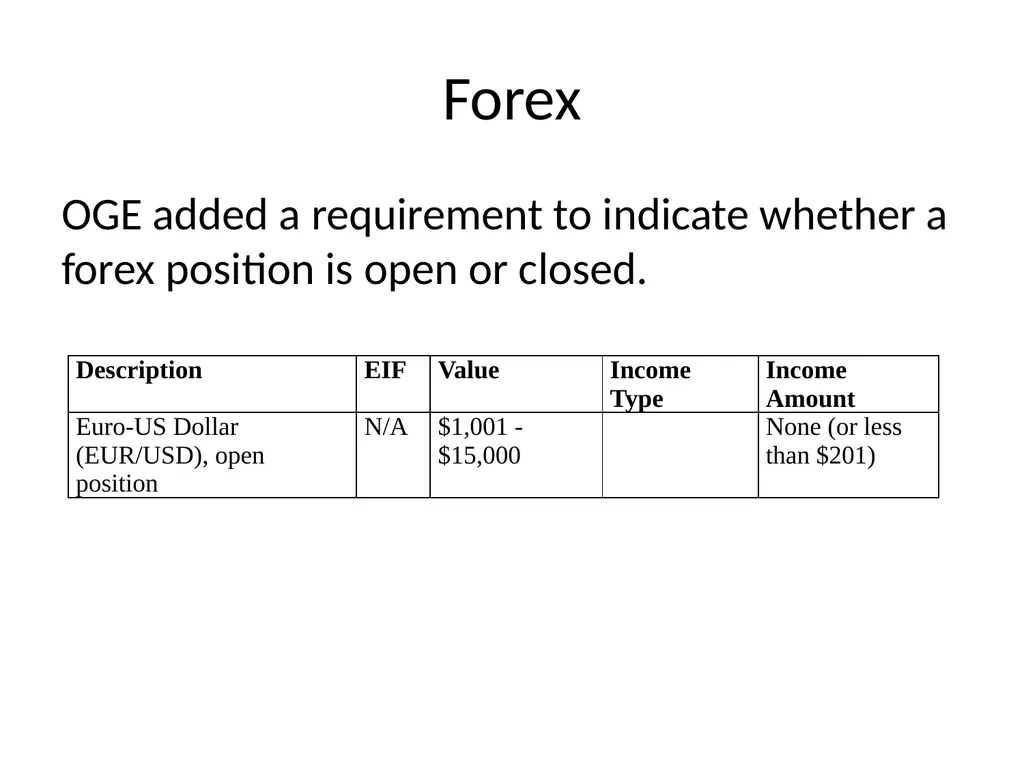
slide13. Forex OGE added a requirement to indicate whether a forex position is open or closed.<br>
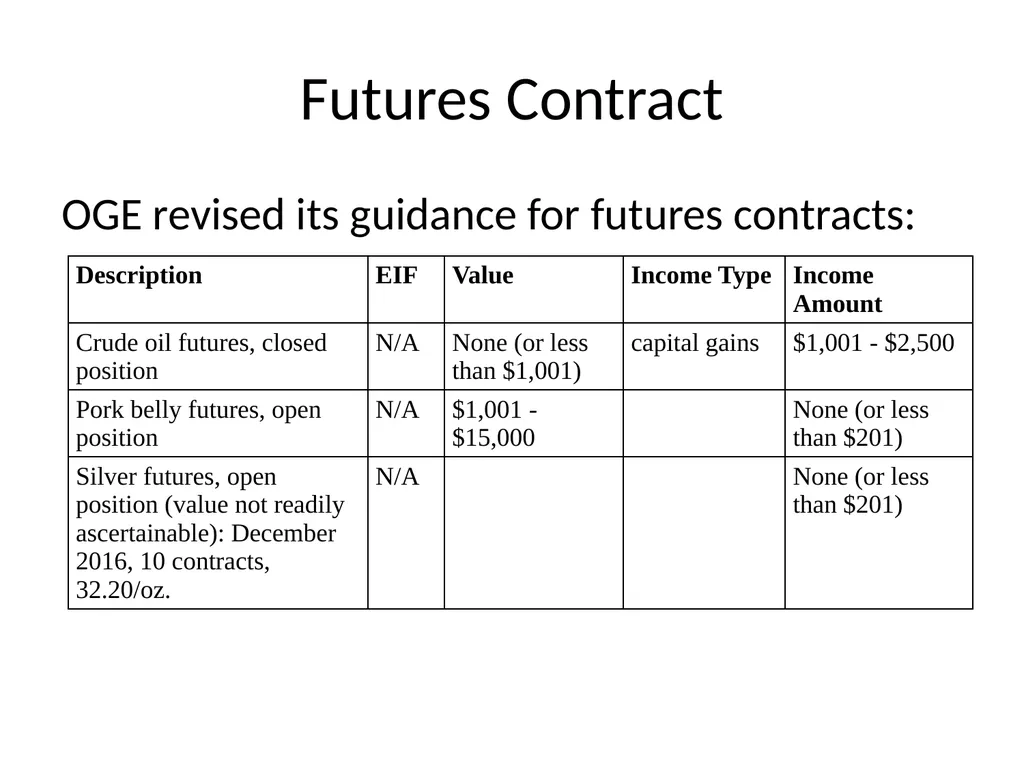
slide14. Futures Contract OGE revised its guidance for futures contracts:<br>
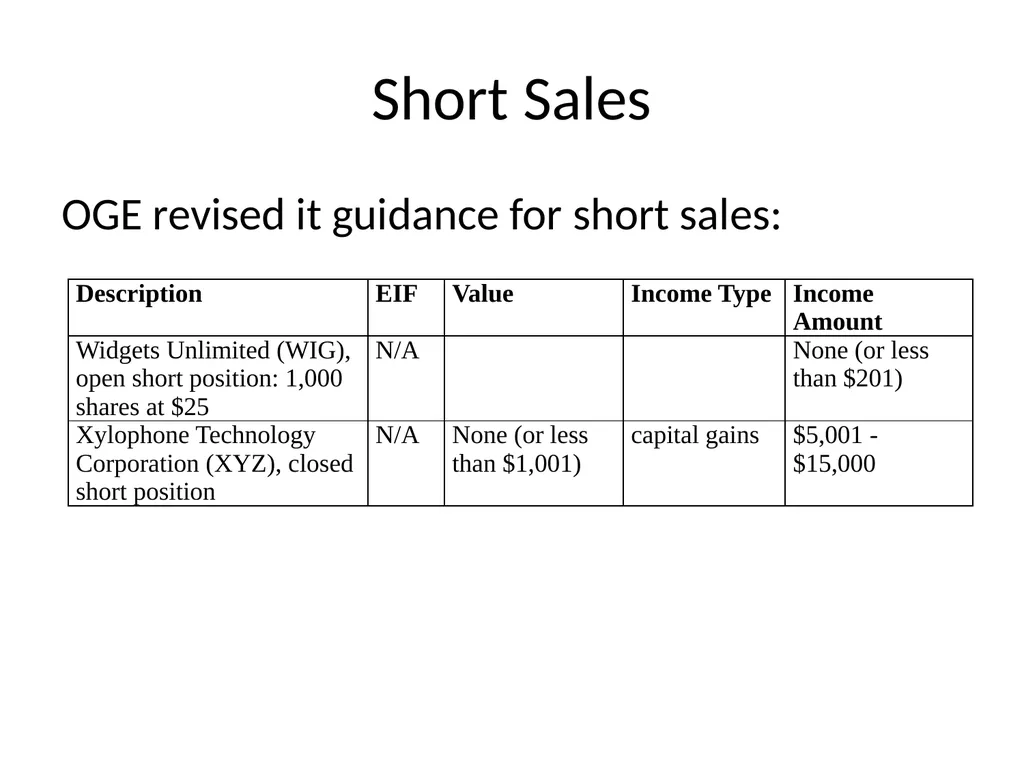
slide15. Short Sales OGE revised it guidance for short sales:<br>
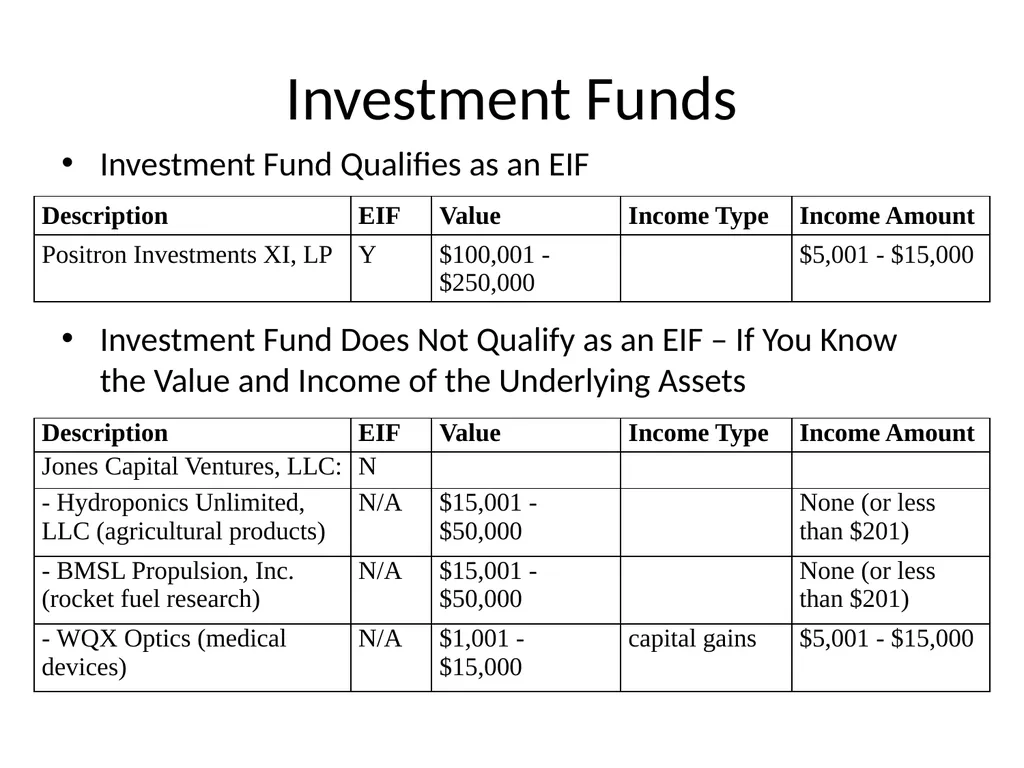
slide16. Investment Funds Investment Fund Qualifies as an EIF
Investment Fund Does Not Qualify as an EIF – If You Know the Value and Income of the Underlying Assets<br>
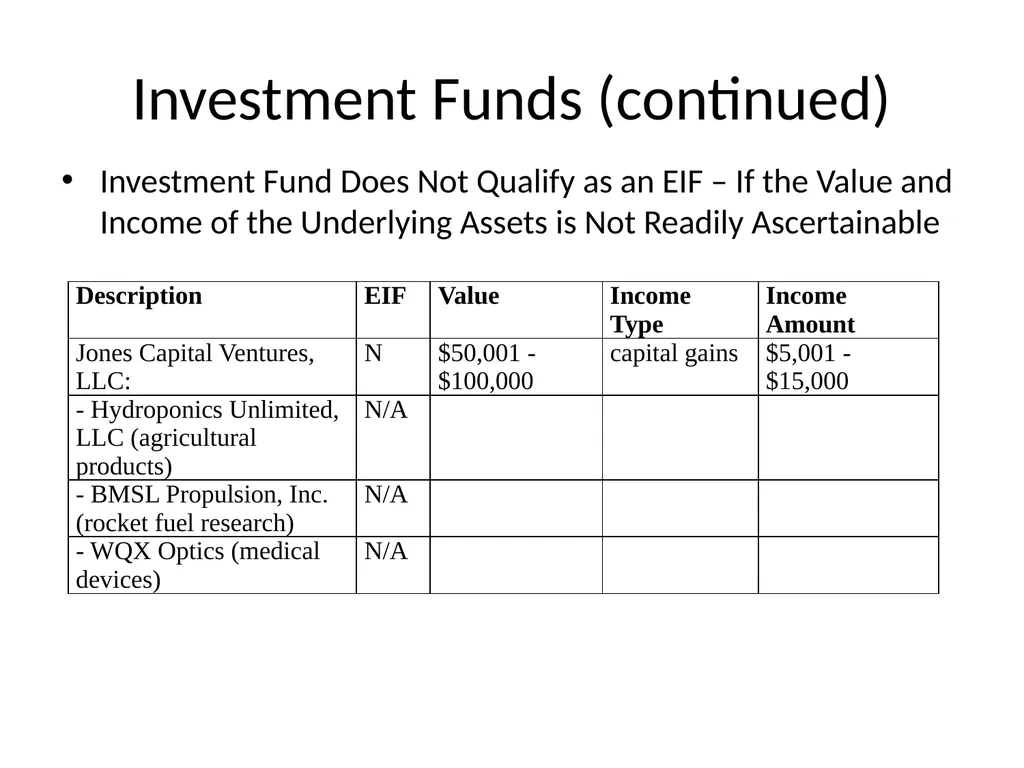
slide17. Investment Funds (continued) Investment Fund Does Not Qualify as an EIF – If the Value and Income of the Underlying Assets is Not Readily Ascertainable<br>
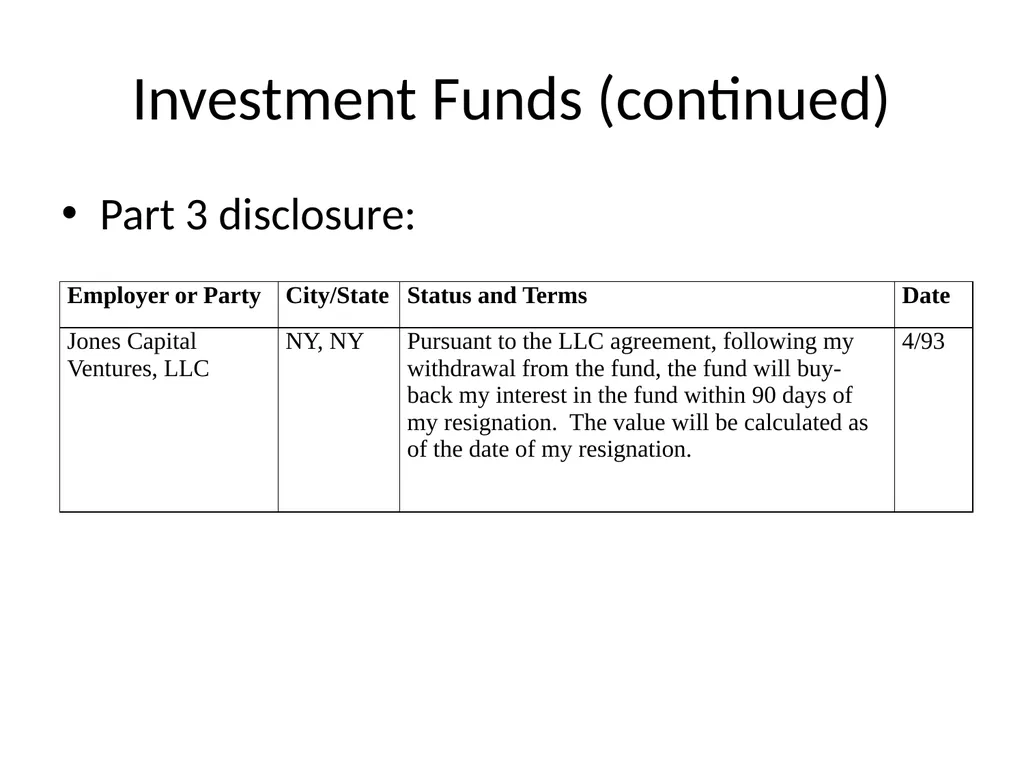
slide18. Investment Funds (continued) Part 3 disclosure:<br>
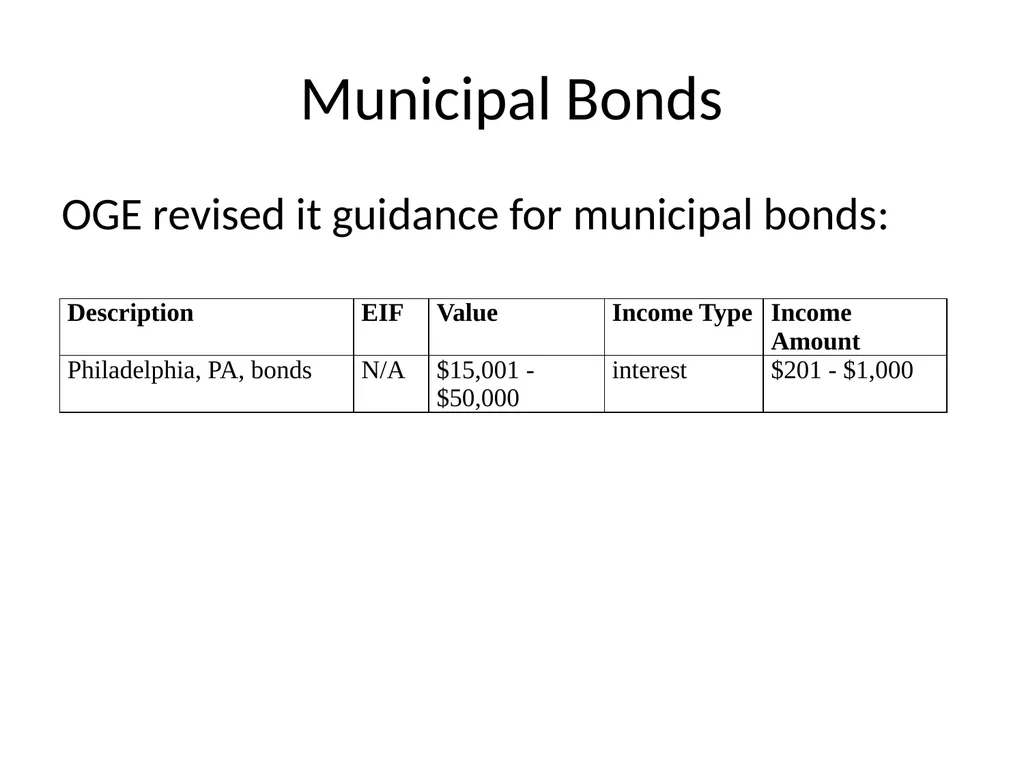
slide19. Municipal Bonds OGE revised it guidance for municipal bonds:<br>
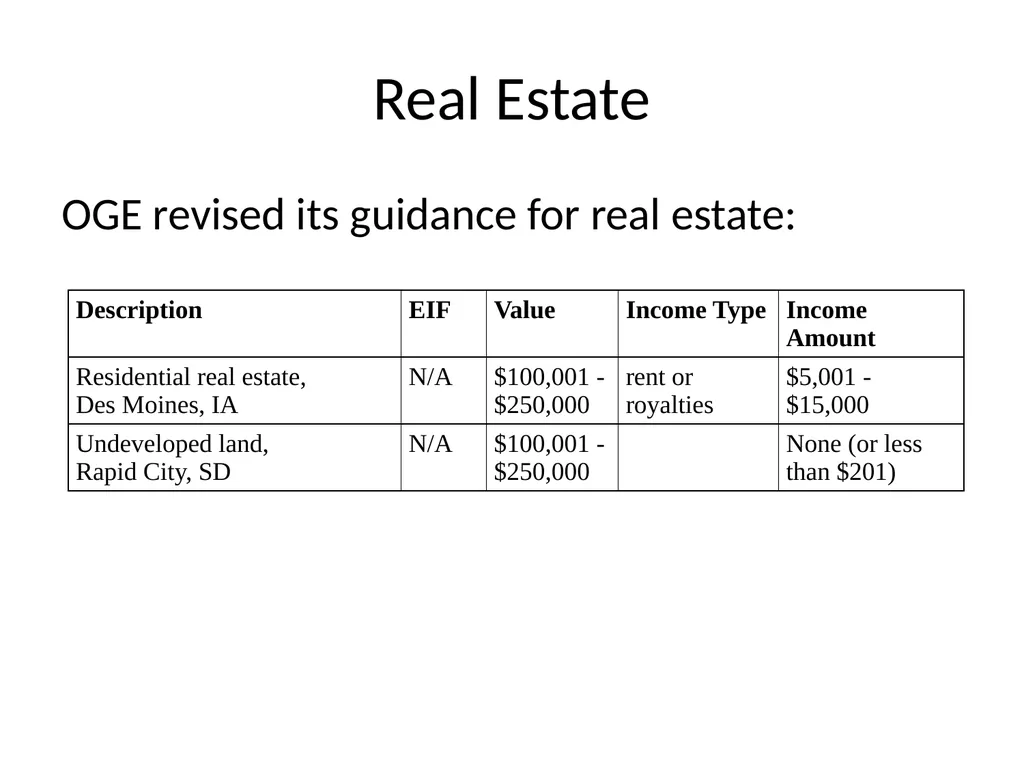
slide20. Real Estate OGE revised its guidance for real estate:<br>
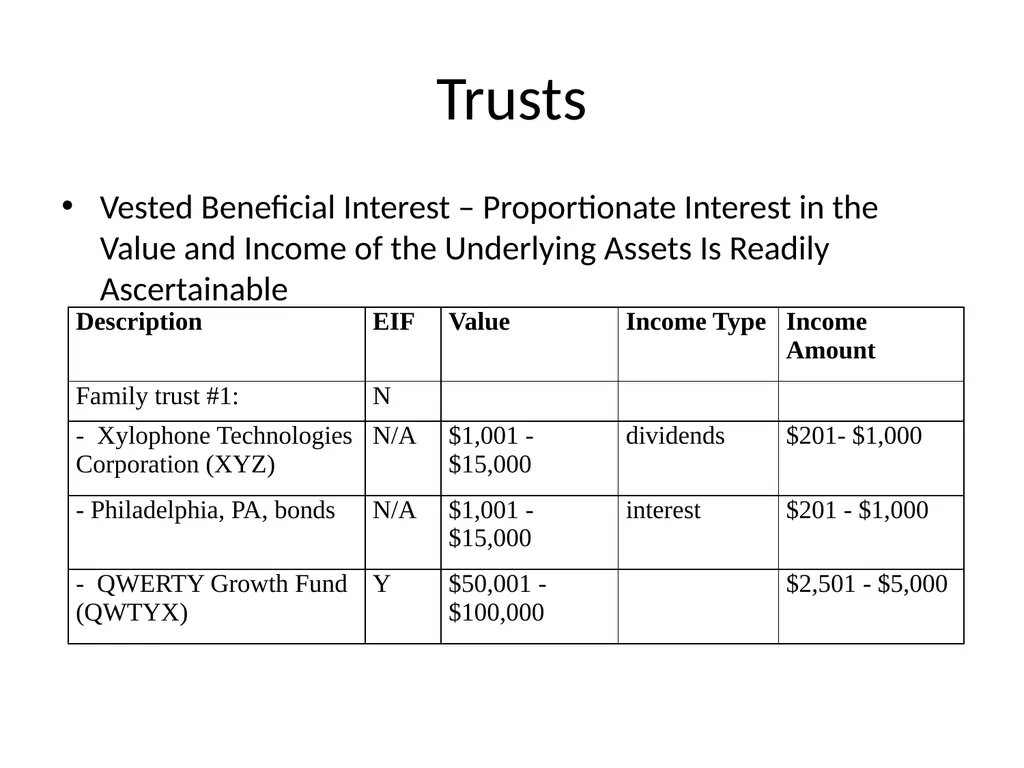
slide21. Trusts Vested Beneficial Interest – Proportionate Interest in the Value and Income of the Underlying Assets Is Readily Ascertainable<br>
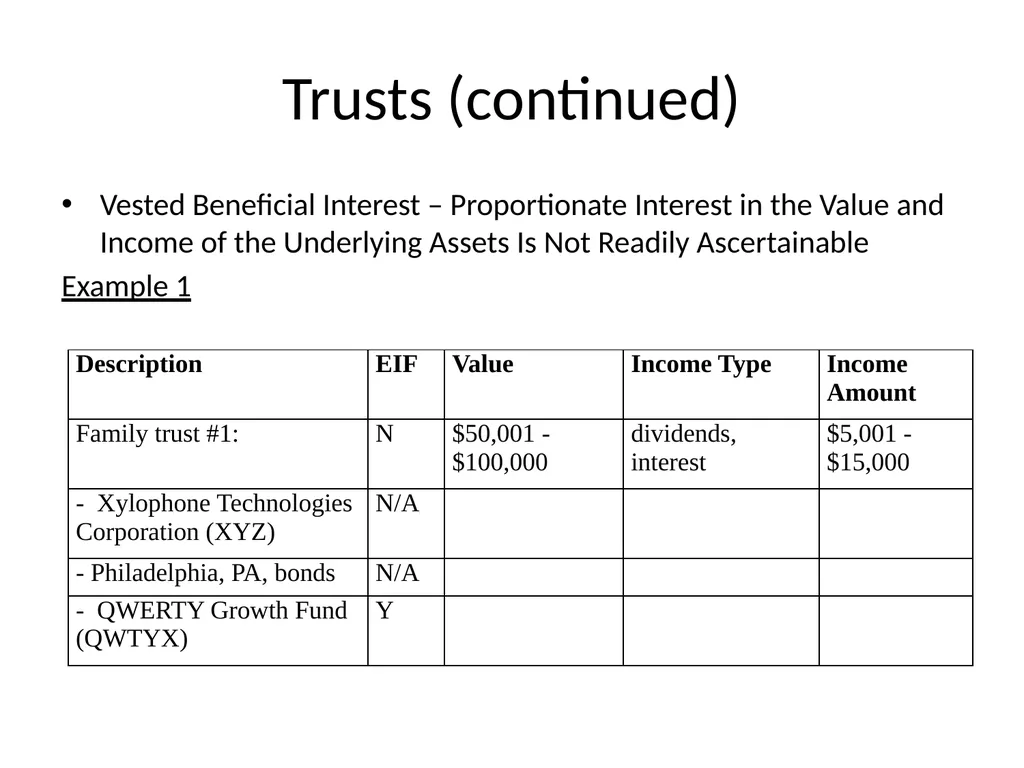
slide22. Trusts (continued) Vested Beneficial Interest – Proportionate Interest in the Value and Income of the Underlying Assets Is Not Readily Ascertainable
Example 1<br>
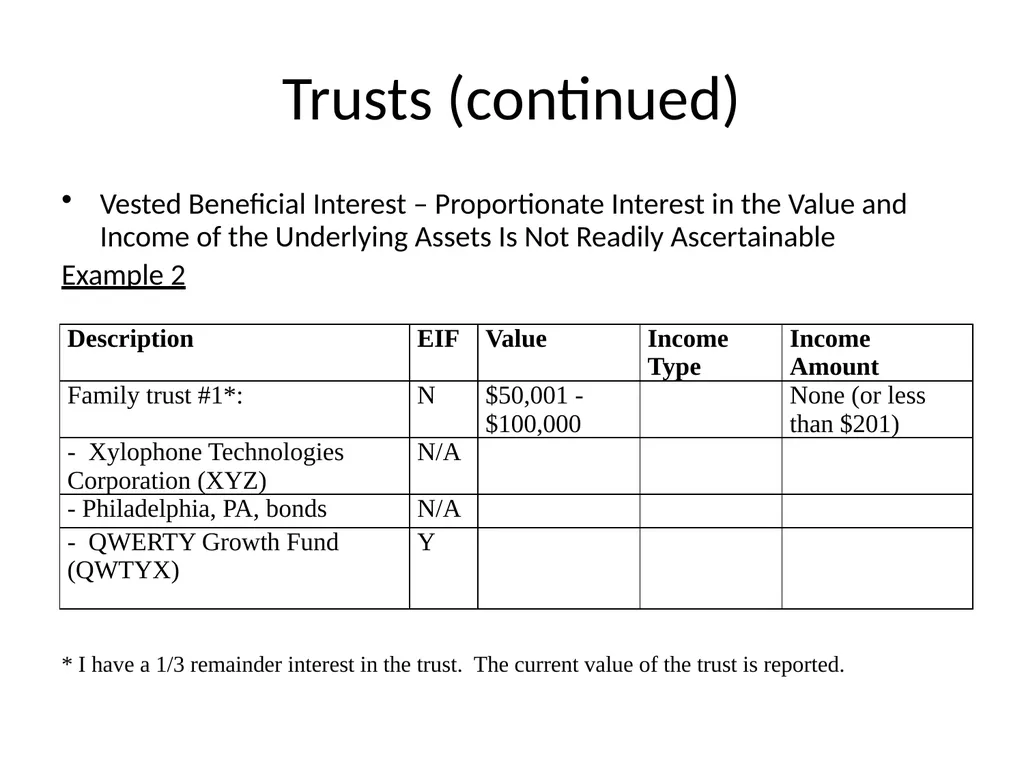
slide23. Trusts (continued) Vested Beneficial Interest – Proportionate Interest in the Value and Income of the Underlying Assets Is Not Readily Ascertainable
Example 2
* I have a 1/3 remainder interest in the trust. The current value of the trust is reported.<br>
slide24. Confidential Clients In certain rare cases , filers need not publicly disclose the identity of confidential clients on Part 4 of the report.
In those cases, specify the reason(s) why confidential clients have not been disclosed. For each reason specified,
indicate the number of confidential clients that have not been disclosed and
indicate how many clients are entities and how many are individuals
For example: 2 confidential clients are not disclosed because they are subject to non-public investigations = 1 partnership and 1 individual.<br>
slide25. Transactions A filer does not need to incorporate 278-Ts into an annual or termination report unless required by the agency.
OGE removed the requirement that a filer indicate that a sale was made pursuant to a Certificate of Divestiture.
A filer may provide a general description of transaction dates for transactions not subject to 278-T reporting (e.g. monthly or multiple).<br>
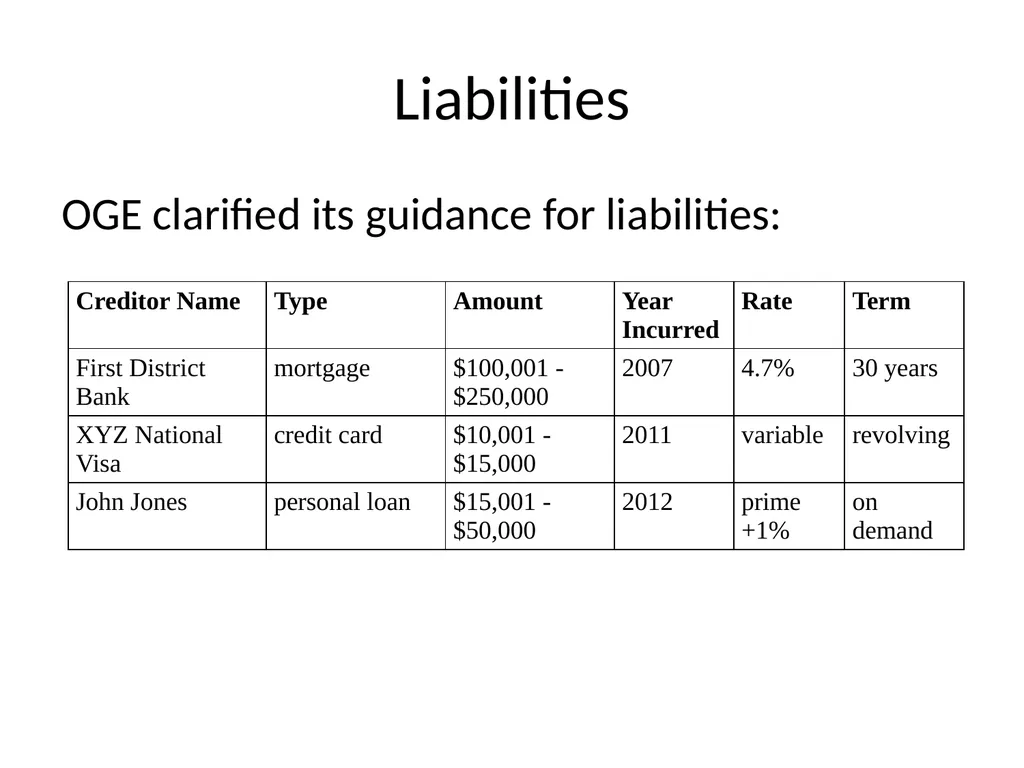
slide26. Liabilities OGE clarified its guidance for liabilities:<br>
slide27. Programmatic Guidance Clarifications Extensions
Record Retention for 278-Ts
Release of Reports
Review time frames, assumptions, and annotations<br>
slide28. Thank You<br>
and Review Standards
May 12, 2016<br>
slide2. Positions Filers need not report an unpaid position with an advisory committee for a state or local government, unless the filer had fiduciary duties or was otherwise treated as an employee.
The Guide includes several FAQs regarding whether certain types of service results in a reportable positions.<br>
slide3. Small Business OGE provided guidance for small businesses:<br>
slide4. Business Assets and Liabilities You are not required to report assets and liabilities of a trade or business, unless those interests are unrelated to the operations of the business.
What constitutes “unrelated” will vary based on the specific circumstances; however, the following general guidelines apply:
Publicly traded corporations: Assets and liabilities of a publicly traded corporation are deemed to be related to the operations of the business for purposes of financial disclosure. Consequently, one need not perform any further test with respect to such interests.
Businesses that are not publicly traded: One needs to consider factors such as the type of asset or liability and its relationship to the economic activity conducted by the business.
No one factor is necessarily dispositive; however, in many cases, the type of asset itself will demonstrate a nexus between the asset and operations of the business, which removes the need for further analysis. For example, in OGE’s experience, a filer would not need to itemize office furniture, equipment, supplies, inventory, accounts receivable, accounts payable, working capital funds, real estate used in the operations of the business, or any mortgages on such real estate.<br>
slide5. Carried Interest Part 2:
Part 3:<br>
slide6. Equity Interest in a Privately-Held Business If a filer has an equity interest, such as stock, in a privately-held business the filer must provide the line of business in the description. For example:<br>
slide7. Employee Stock Ownership Plan OGE provided guidance for interest in an ESOP:<br>
slide8. Employee Stock Purchase Plan OGE simplified the guidance:<br>
slide9. Severance OGE revised it guidance for severance payments:<br>
slide10. Cash Accounts OGE revised the reporting for cash accounts:<br>
slide11. Farms Part 2 (operated as a business):
Part 6 (investment):<br>
slide12. Options (put or call written) OGE revised its guidance for written options:<br>
slide13. Forex OGE added a requirement to indicate whether a forex position is open or closed.<br>
slide14. Futures Contract OGE revised its guidance for futures contracts:<br>
slide15. Short Sales OGE revised it guidance for short sales:<br>
slide16. Investment Funds Investment Fund Qualifies as an EIF
Investment Fund Does Not Qualify as an EIF – If You Know the Value and Income of the Underlying Assets<br>
slide17. Investment Funds (continued) Investment Fund Does Not Qualify as an EIF – If the Value and Income of the Underlying Assets is Not Readily Ascertainable<br>
slide18. Investment Funds (continued) Part 3 disclosure:<br>
slide19. Municipal Bonds OGE revised it guidance for municipal bonds:<br>
slide20. Real Estate OGE revised its guidance for real estate:<br>
slide21. Trusts Vested Beneficial Interest – Proportionate Interest in the Value and Income of the Underlying Assets Is Readily Ascertainable<br>
slide22. Trusts (continued) Vested Beneficial Interest – Proportionate Interest in the Value and Income of the Underlying Assets Is Not Readily Ascertainable
Example 1<br>
slide23. Trusts (continued) Vested Beneficial Interest – Proportionate Interest in the Value and Income of the Underlying Assets Is Not Readily Ascertainable
Example 2
* I have a 1/3 remainder interest in the trust. The current value of the trust is reported.<br>
slide24. Confidential Clients In certain rare cases , filers need not publicly disclose the identity of confidential clients on Part 4 of the report.
In those cases, specify the reason(s) why confidential clients have not been disclosed. For each reason specified,
indicate the number of confidential clients that have not been disclosed and
indicate how many clients are entities and how many are individuals
For example: 2 confidential clients are not disclosed because they are subject to non-public investigations = 1 partnership and 1 individual.<br>
slide25. Transactions A filer does not need to incorporate 278-Ts into an annual or termination report unless required by the agency.
OGE removed the requirement that a filer indicate that a sale was made pursuant to a Certificate of Divestiture.
A filer may provide a general description of transaction dates for transactions not subject to 278-T reporting (e.g. monthly or multiple).<br>
slide26. Liabilities OGE clarified its guidance for liabilities:<br>
slide27. Programmatic Guidance Clarifications Extensions
Record Retention for 278-Ts
Release of Reports
Review time frames, assumptions, and annotations<br>
slide28. Thank You<br>