Relationship between Internal Audit, MPAC and Audit Committee IMFO Annual Conference 2016 at Durban ICC, 04 October 2016 Presented by: Makhosandile Kwaza Agenda Introduction Role of the municipal council Council committees Difference
"Relationship between Internal Audit, MPAC and" is the property of its rightful owner. Permission is granted to
download and print the materials on this website for personal, non-commercial use only, and to display it
on your personal computer provided you do not modify the materials and that you retain all copyright
notices contained in the materials. By downloading content from our website, you accept the terms of this
agreement.
Presentation Transcript
01
Relationship between Internal Audit, MPAC and Audit Committee IMFO Annual Conference 2016 at Durban ICC, 04 October 2016
Presented by: Makhosandile Kwaza<br>
02
Agenda Introduction
Role of the municipal council
Council committees
Difference between Audit Committee and MPAC<br>
03
Introduction (1) 40. Government of the Republic.—
(l) In the Republic, government is constituted as national, provincial and local spheres of government which are distinctive, interdependent and interrelated.<br>
04
Introduction (2) 151. Status of municipalities -:
The local sphere of government consists of municipalities, which must be established for the whole of the territory of the Republic.
The executive and legislative authority of a municipality is vested in its Municipal Council.
A municipality has the right to govern, on its own initiative, the local government affairs of its community, subject to national and provincial legislation, as provided for in the Constitution,
The national or a provincial government may not compromise or impede a municipality’s ability or right to exercise its powers or perform its functions.<br>
05
Principle of separation of powers Constitution gives expression to the principle of separation of powers by recognising the functional independence of the three branches of government (executive, legislature and judiciary).
In the local government the independence between the executive and legislature is not exist.
Same councillors who are executive members become part of legislative in the council.<br>
06
Oversight report on annual report Section 129 of the MFMA – published
Section 129(4) of the MFMA only provides for the issuance of guidance on the manner in which municipal councils should consider annual reports and conduct public hearings.
Does the council need to still appoint the committee to prepare the oversight report or is that the function of MPAC.
Perhaps the terms of reference for MPAC should also give mandate to MPAC to perform this function.<br>
07
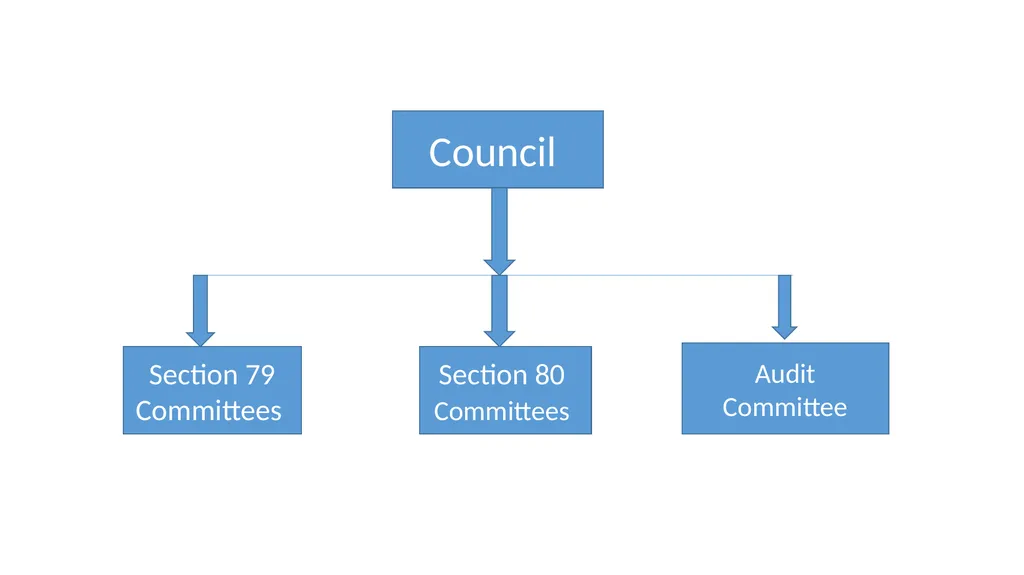
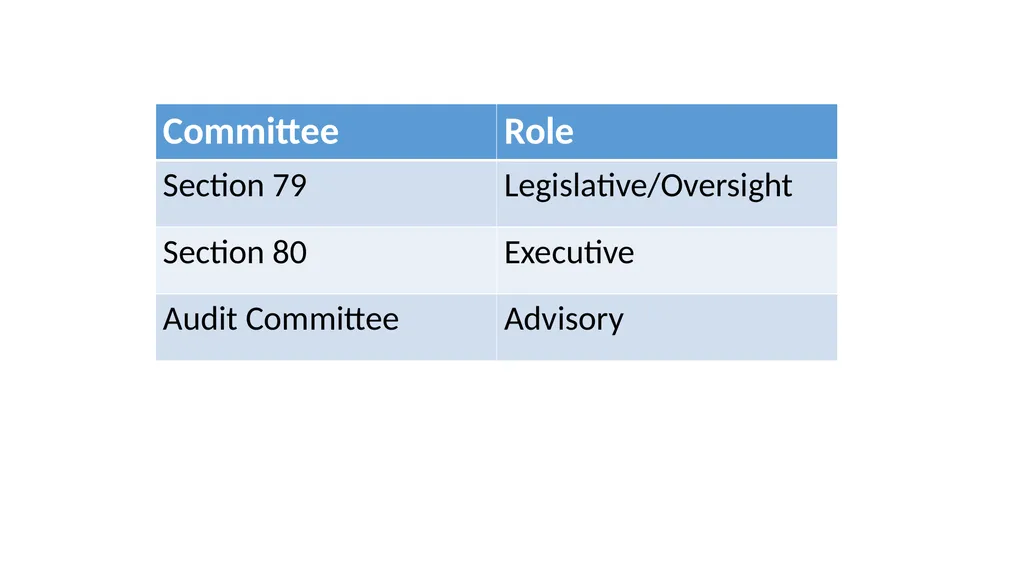
Council Section 79
Committees Section 80
Committees Audit Committee<br>
08
Topic Relationship between:
Internal Audit;
Audit Committee; and
Municipal Public Accounts Committee (MPAC)<br>
09
Internal Audit Internal auditing is an independent, objective assurance and consulting activity designed to add value and improve an organization’s operations.
It helps an organization accomplish its objectives by bringing a systematic, disciplined approach to evaluate and improve the effectiveness of risk management, control, and governance processes.
Established in terms of s 165 of the MFMA
Prepare a risk based IA plan<br>
10
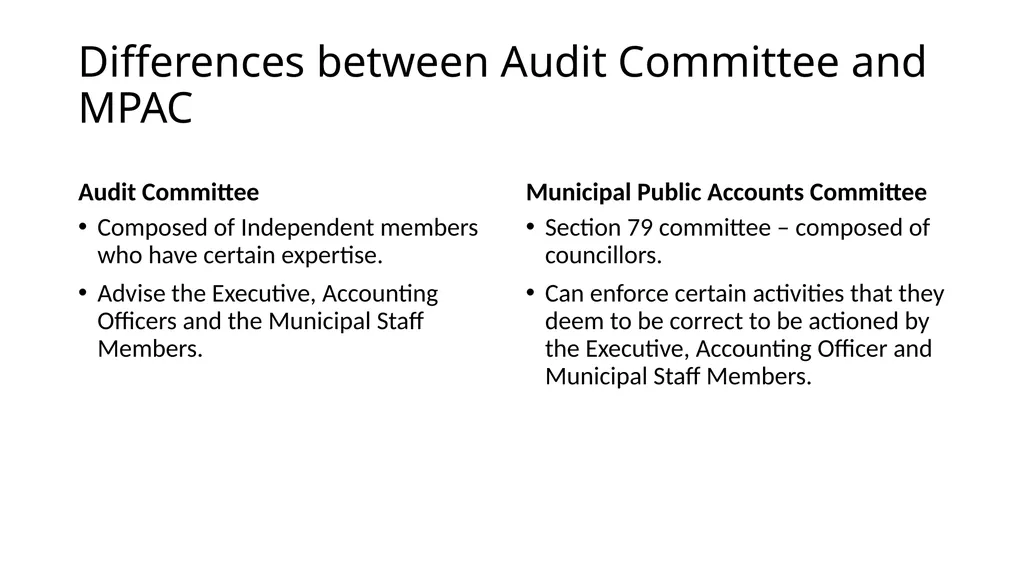
Differences between Audit Committee and MPAC Audit Committee Composed of Independent members who have certain expertise.
Advise the Executive, Accounting Officers and the Municipal Staff Members. Municipal Public Accounts Committee Section 79 committee – composed of councillors.
Can enforce certain activities that they deem to be correct to be actioned by the Executive, Accounting Officer and Municipal Staff Members.<br>
11
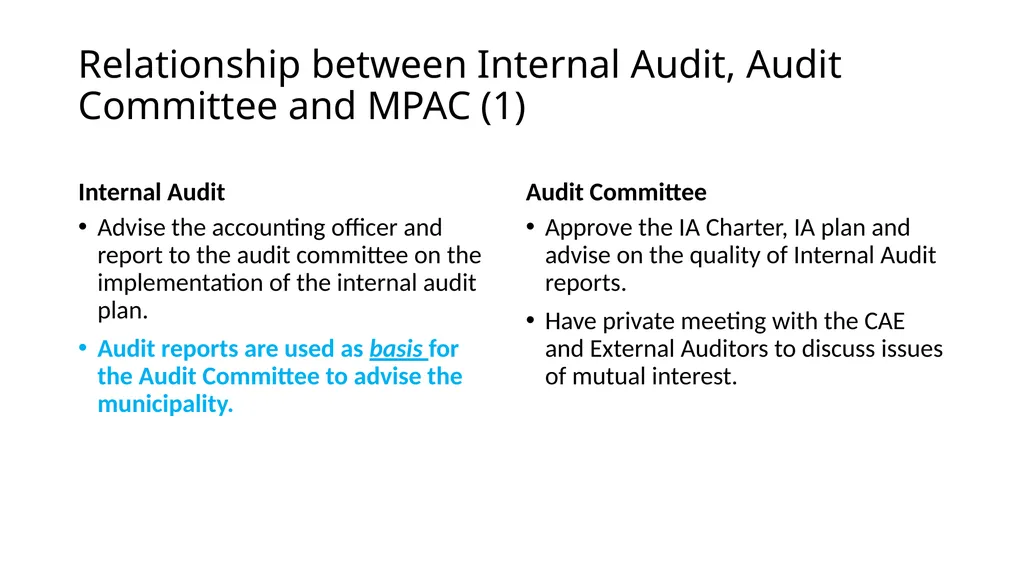
Relationship between Internal Audit, Audit Committee and MPAC (1) Internal Audit Advise the accounting officer and report to the audit committee on the implementation of the internal audit plan.
Audit reports are used as basis for the Audit Committee to advise the municipality. Audit Committee Approve the IA Charter, IA plan and advise on the quality of Internal Audit reports.
Have private meeting with the CAE and External Auditors to discuss issues of mutual interest.<br>
12
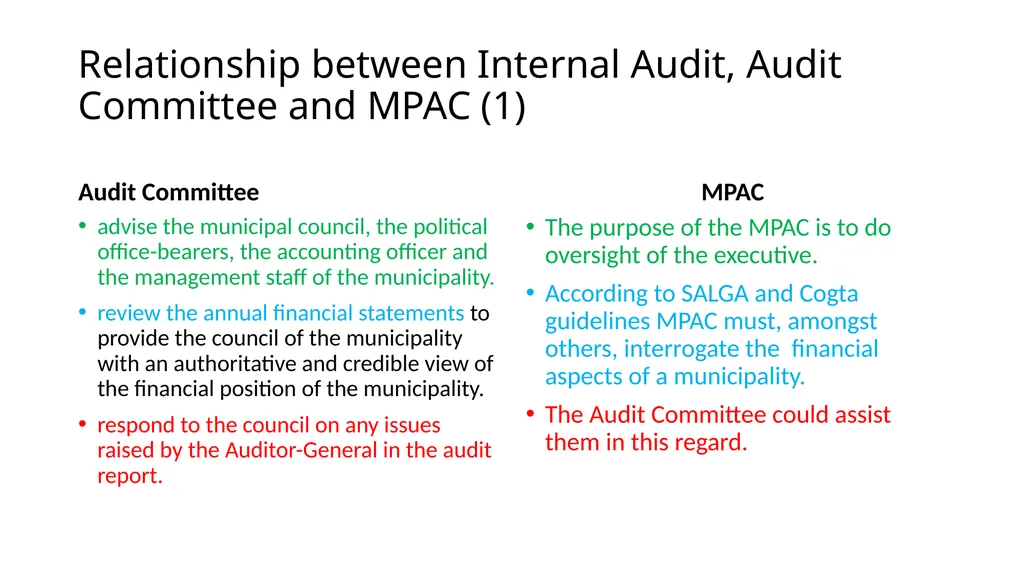
Relationship between Internal Audit, Audit Committee and MPAC (1) Audit Committee advise the municipal council, the political office-bearers, the accounting officer and the management staff of the municipality.
review the annual financial statements to provide the council of the municipality with an authoritative and credible view of the financial position of the municipality.
respond to the council on any issues raised by the Auditor-General in the audit report. MPAC The purpose of the MPAC is to do oversight of the executive.
According to SALGA and Cogta guidelines MPAC must, amongst others, interrogate the financial aspects of a municipality.
The Audit Committee could assist them in this regard.<br>