
Reports of Value’s Death May Be Greatly

Description: Reports of Values Death May Be Greatly Exaggerated Campbell R. Harvey Duke University and NBER (Joint work in progress with Rob Arnott, Vitali Kalesnik, and Juhani Linnainmaa) November 2019 PRELIMINARY NOT FOR DISTRIBUTION Why has value
Related Topics
Download Presentation
"Reports of Value’s Death May Be Greatly" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Reports of Value’s Death May Be Greatly Exaggerated Campbell R. Harvey
Duke University and NBER
(Joint work in progress with Rob Arnott, Vitali Kalesnik, and Juhani Linnainmaa) November 2019 PRELIMINARY
NOT FOR DISTRIBUTION<br>
slide2. Why has value underperformed growth? Did crowding reduce expected returns?
Different economic regime?
Different interest rate regime?
Less relative mean reversion?
Is value mismeasured?
Value has lagged because it has become cheaper? 2<br>
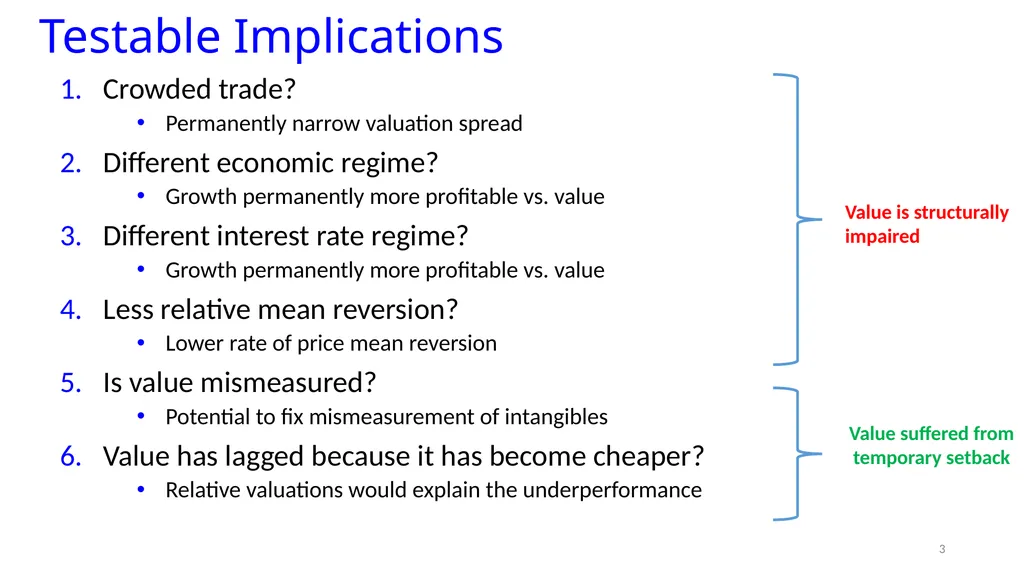
slide3. Testable Implications Crowded trade?
Permanently narrow valuation spread
Different economic regime?
Growth permanently more profitable vs. value
Different interest rate regime?
Growth permanently more profitable vs. value
Less relative mean reversion?
Lower rate of price mean reversion
Is value mismeasured?
Potential to fix mismeasurement of intangibles
Value has lagged because it has become cheaper?
Relative valuations would explain the underperformance 3<br>
slide4. Diagnosing Value<br>
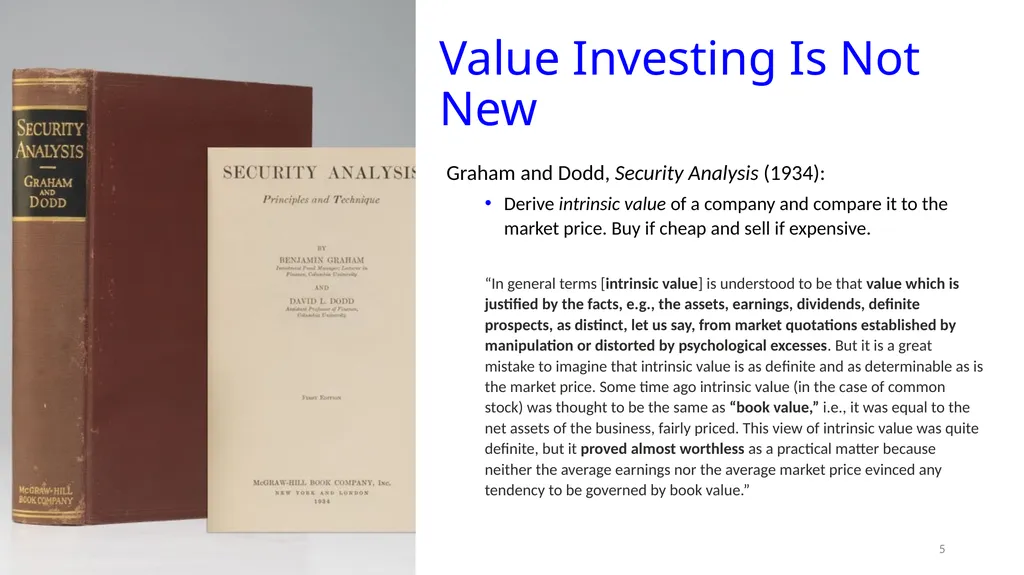
slide5. Value Investing Is Not New 5 Graham and Dodd, Security Analysis (1934):
Derive intrinsic value of a company and compare it to the market price. Buy if cheap and sell if expensive.
“In general terms [intrinsic value] is understood to be that value which is justified by the facts, e.g., the assets, earnings, dividends, definite prospects, as distinct, let us say, from market quotations established by manipulation or distorted by psychological excesses. But it is a great mistake to imagine that intrinsic value is as definite and as determinable as is the market price. Some time ago intrinsic value (in the case of common stock) was thought to be the same as “book value,” i.e., it was equal to the net assets of the business, fairly priced. This view of intrinsic value was quite definite, but it proved almost worthless as a practical matter because neither the average earnings nor the average market price evinced any tendency to be governed by book value.”<br>
slide6. Academic Origins of Value Basu (1977) — First academic evidence of superior performance of value strategies
Stocks with low P/E (value) outperform stocks with high P/E (growth).
Fama and French (1992) — Risk-based theory of value
P/B becomes a standard academic definition of value.
Lakonishok, Shleifer, and Vishny (1994) — Mispricing theory of value 6<br>
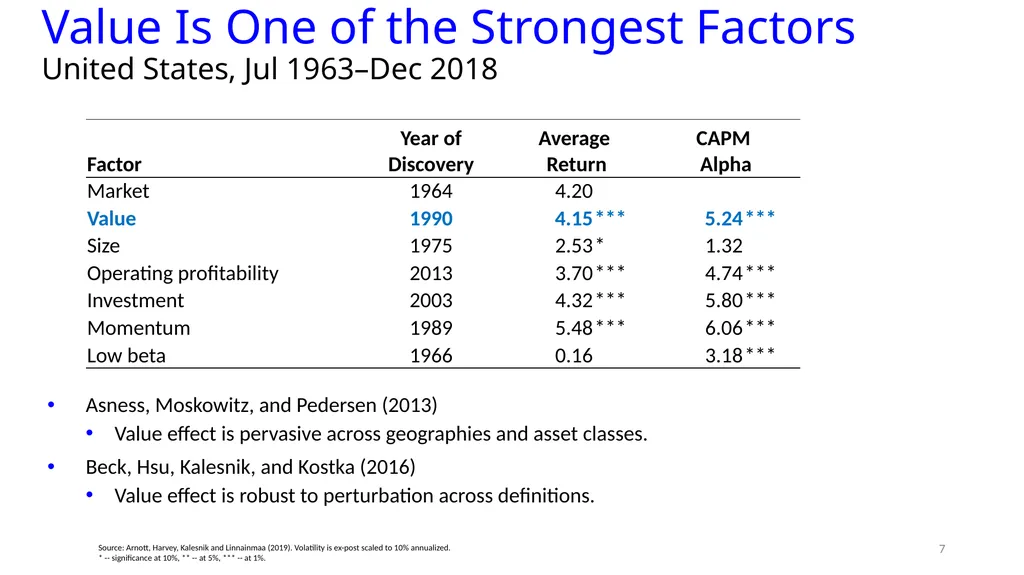
slide7. Value Is One of the Strongest Factors United States, Jul 1963–Dec 2018 Asness, Moskowitz, and Pedersen (2013)
Value effect is pervasive across geographies and asset classes.
Beck, Hsu, Kalesnik, and Kostka (2016)
Value effect is robust to perturbation across definitions. 7 Source: Arnott, Harvey, Kalesnik and Linnainmaa (2019). Volatility is ex-post scaled to 10% annualized.
* -- significance at 10%, ** -- at 5%, *** -- at 1%.<br>
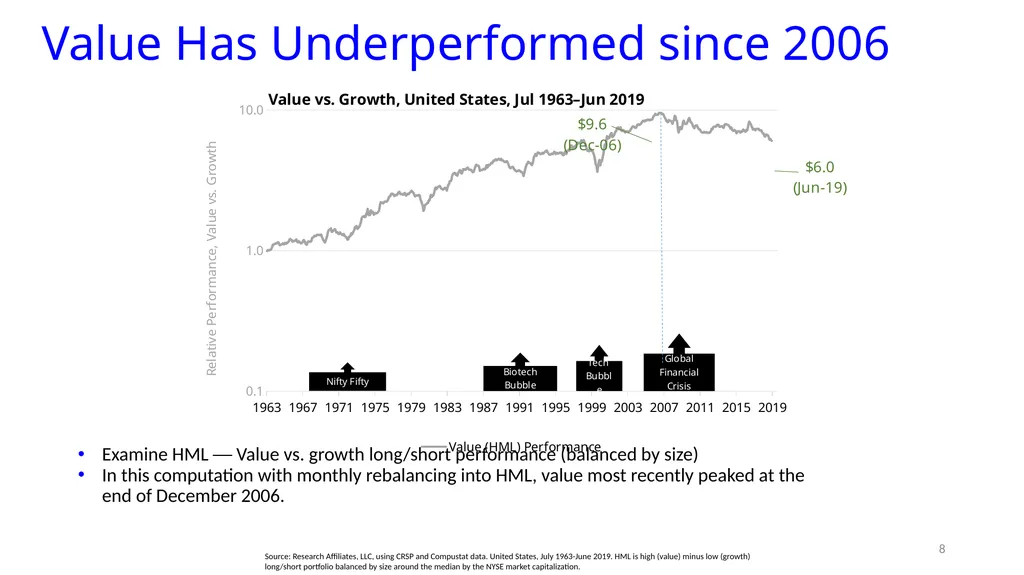
slide8. Value Has Underperformed since 2006 Examine HML — Value vs. growth long/short performance (balanced by size)
In this computation with monthly rebalancing into HML, value most recently peaked at the end of December 2006. 8 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. HML is high (value) minus low (growth) long/short portfolio balanced by size around the median by the NYSE market capitalization.<br>
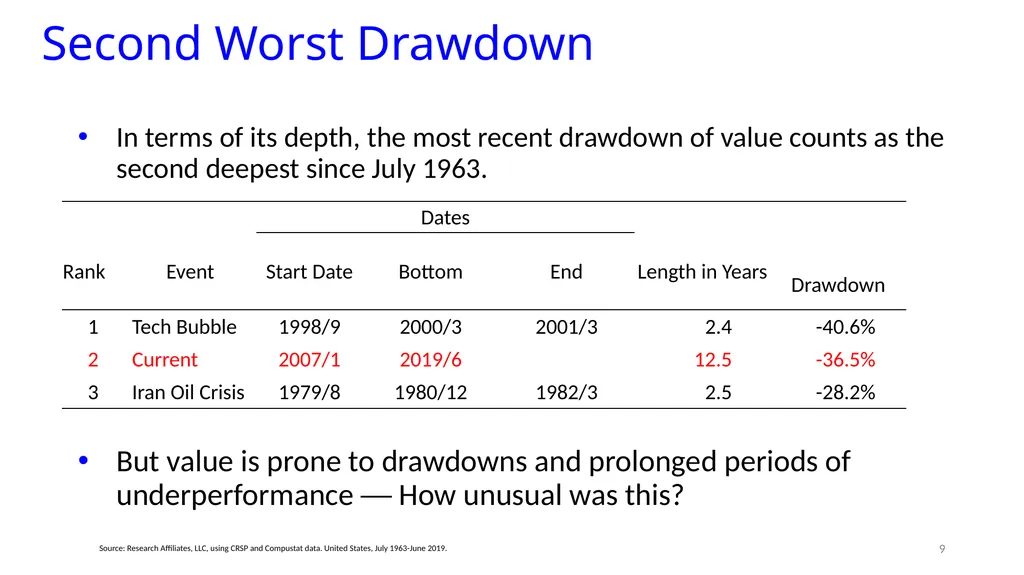
slide9. Second Worst Drawdown In terms of its depth, the most recent drawdown of value counts as the second deepest since July 1963.
But value is prone to drawdowns and prolonged periods of underperformance — How unusual was this? 9 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide10. Estimated Probability of a Drawdown Use the “Alice in Factorland” bootstrapping methodology to assess the likelihood of the drawdown that started in 2007.
Take the long/short return sample period up to December 2006.
Draw returns from this sample in six-month blocks.
Create a sample that matches the length of the actual total sample from July 1963 through June 2019.
For each simulated sample, record the size of the second-largest drawdown.
Draw 200,000 simulated samples.
We take the second-largest drawdown to be consistent with the actual data.
Drawdowns ranked by magnitude are order statistics. 10<br>
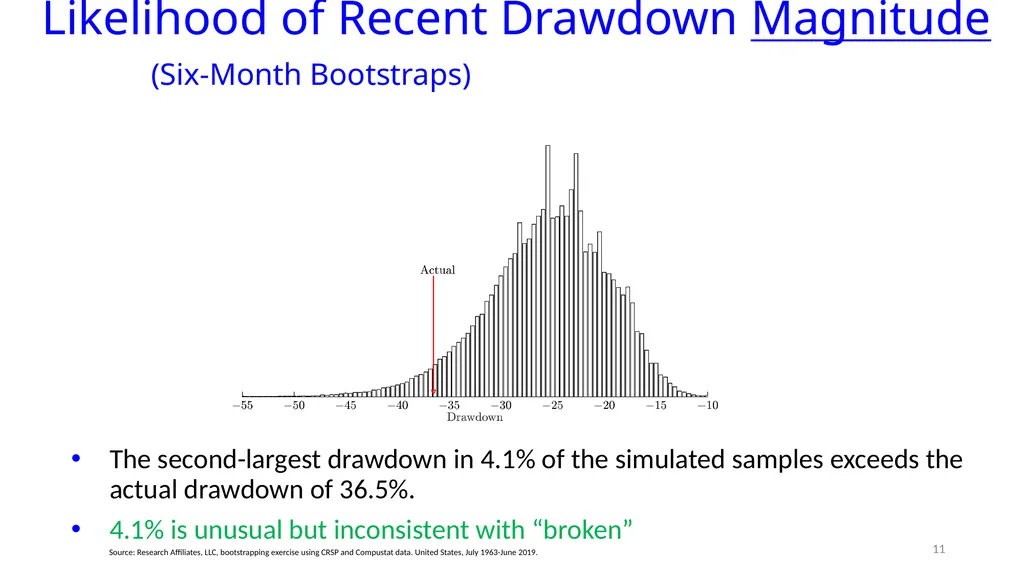
slide11. Likelihood of Recent Drawdown Magnitude (Six-Month Bootstraps) The second-largest drawdown in 4.1% of the simulated samples exceeds the actual drawdown of 36.5%.
4.1% is unusual but inconsistent with “broken” 11 Source: Research Affiliates, LLC, bootstrapping exercise using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide12. Drawdown Duration In terms of its depth, the most recent drawdown of value is, by far, the longest duration since July 1963.
But value is prone to drawdowns and prolonged periods of underperformance — How unusual was this? 12 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide13. Estimated Probability of a Drawdown Use the “Alice in Factorland” bootstrapping methodology to assess the likelihood of the drawdown that started in 2007.
Take the long/short return sample period up to December 2006.
Draw returns from this sample in six-month, two- and five-year blocks.
Create a sample that matches the length of the actual total sample from July 1963 through June 2019.
For each simulated sample, record the length of the longest drawdown.
Draw 200,000 simulated samples.
We take the longest drawdowns. 13<br>
slide14. Likelihood of Recent Drawdown Duration (Six-Month Bootstraps) In 23% of the simulated samples, the longest period of underperformance lasts longer than the 12.5 years we are experiencing now.
The duration of the recent drawdown within the norm. 14 Source: Research Affiliates, LLC, bootstrapping exercise using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide15. Likelihood of Recent Drawdown Duration (Five-Year Bootstraps) In 6% of the simulated samples, the longest period of underperformance lasts longer than the 12.5 years we are experiencing now. Usually value performance mean reverts very fast—not this time!
Unusual, but not consistent with “broken” 15 Source: Research Affiliates, LLC, bootstrapping exercise using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide16. Is the Value Engine Broken? 16<br>
slide17. Value Engine Components Value minus growth driven by revaluation as well as two structural components:
Migration
Profitability differences 17<br>
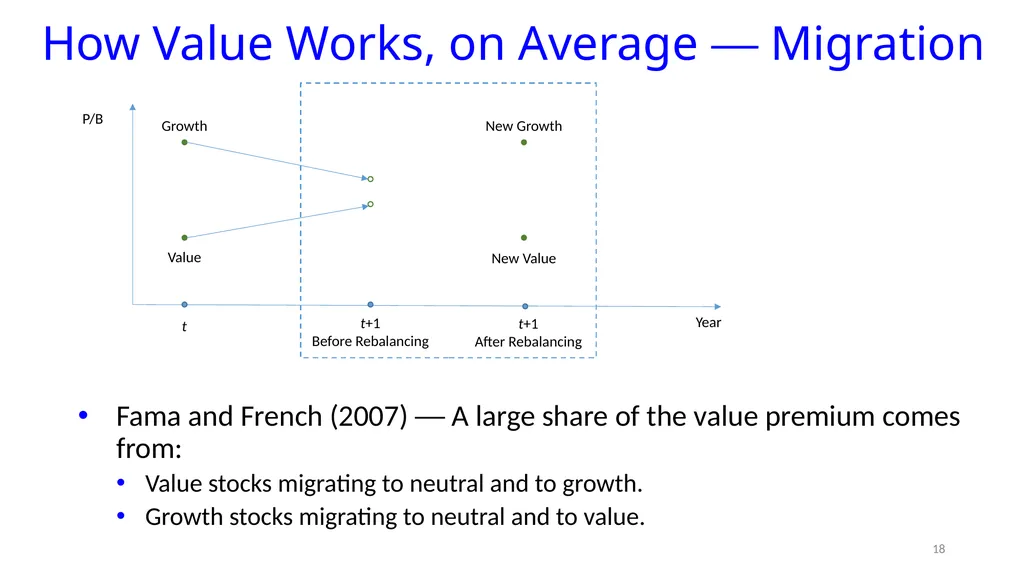
slide18. How Value Works, on Average — Migration Fama and French (2007) — A large share of the value premium comes from:
Value stocks migrating to neutral and to growth.
Growth stocks migrating to neutral and to value. 18 Growth Value Year t t+1
Before Rebalancing t+1
After Rebalancing New Growth New Value P/B<br>
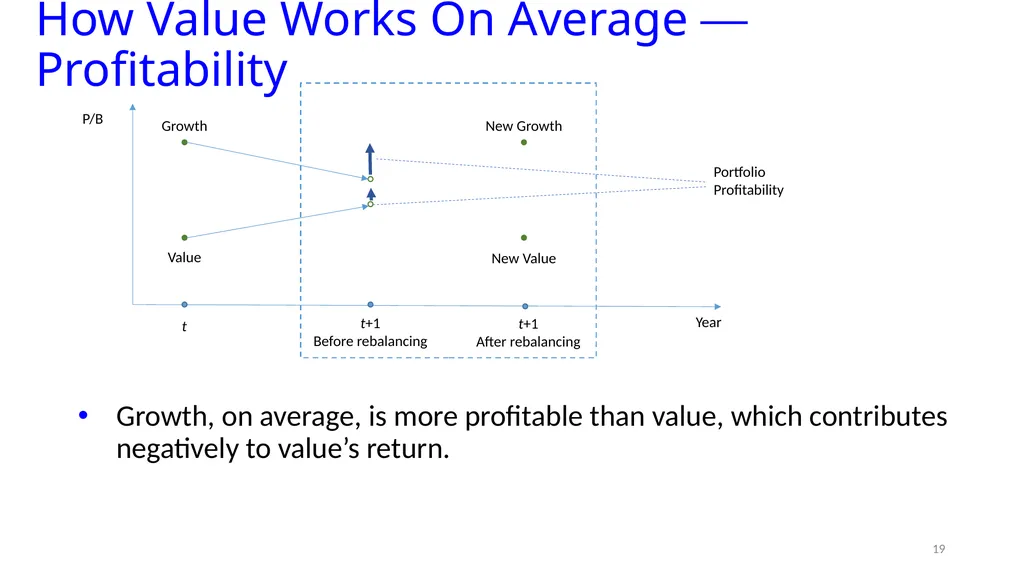
slide19. How Value Works On Average — Profitability Growth, on average, is more profitable than value, which contributes negatively to value’s return. 19 Growth Value Year t t+1
Before rebalancing t+1
After rebalancing New Growth New Value P/B<br>
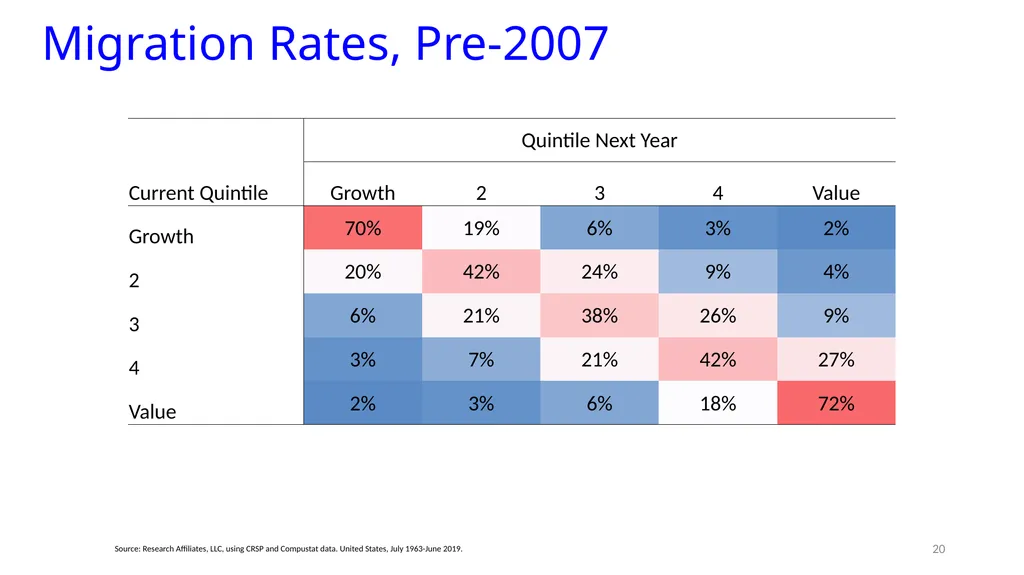
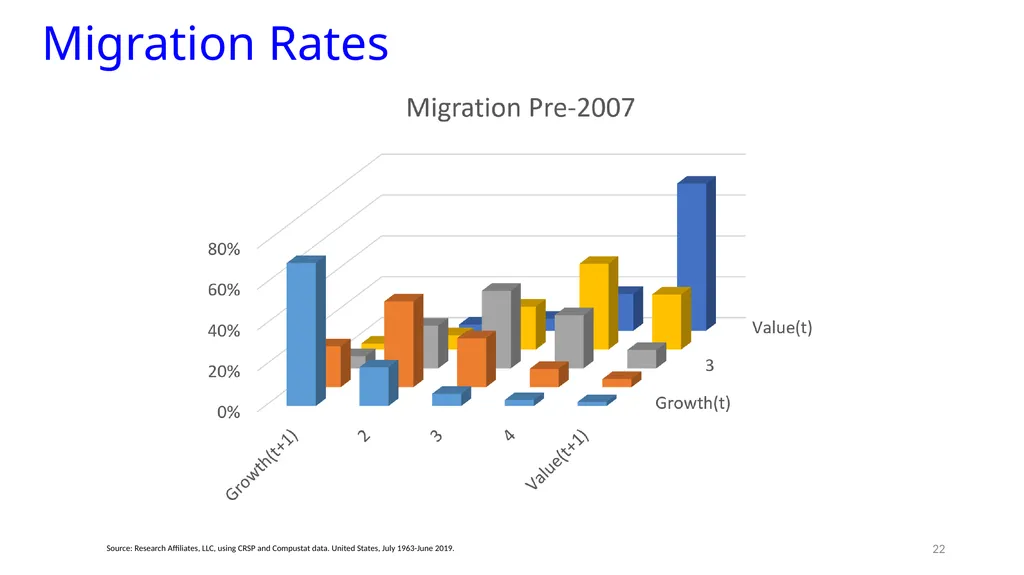
slide20. Migration Rates, Pre-2007 20 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
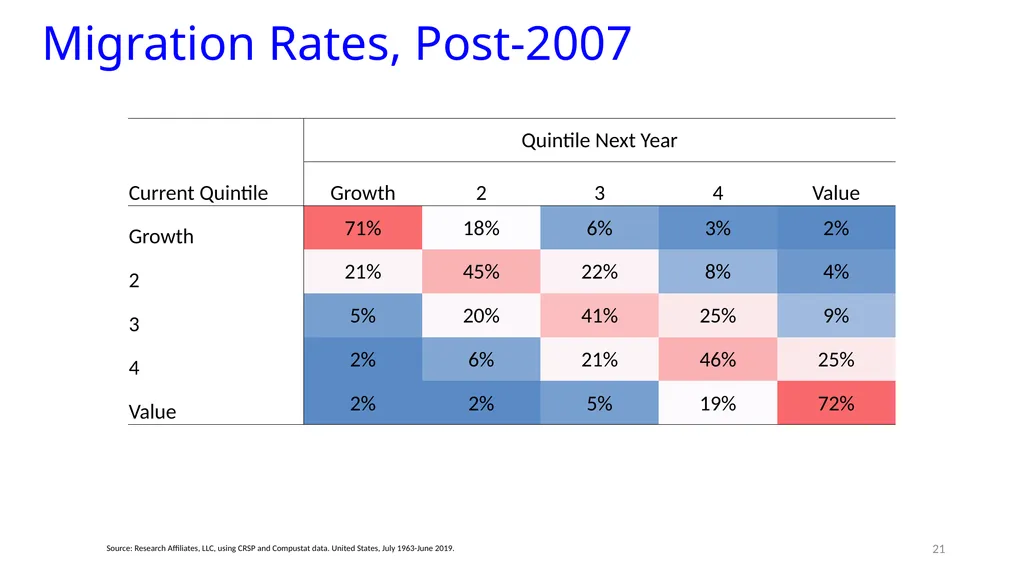
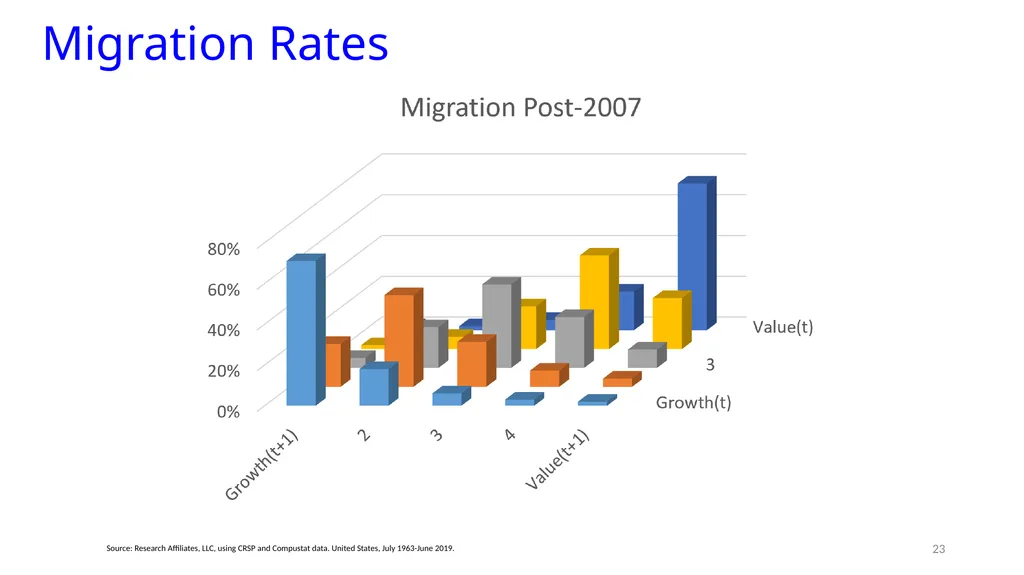
slide21. Migration Rates, Post-2007 21 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide22. Migration Rates 22 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide23. Migration Rates 23 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
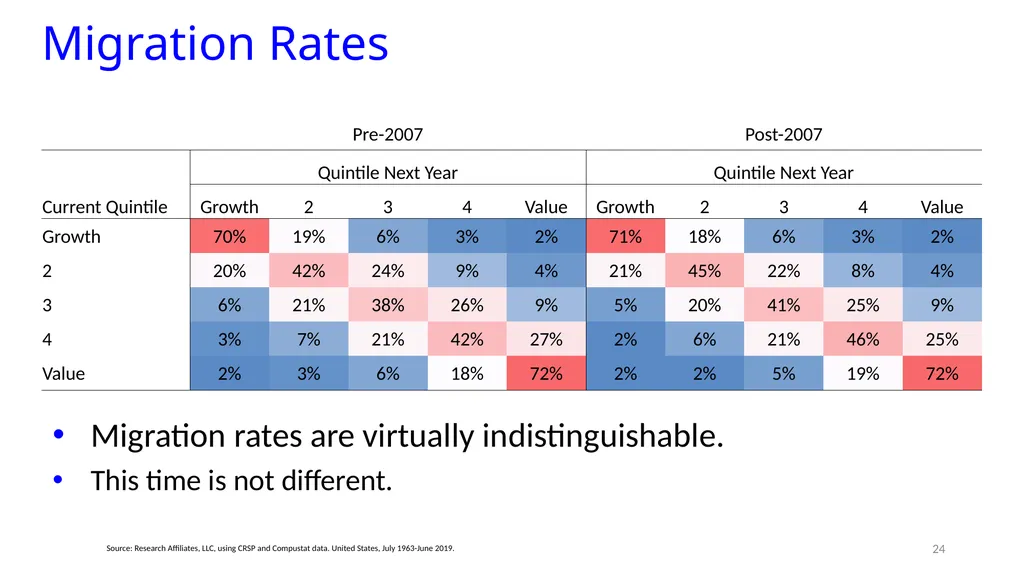
slide24. Migration Rates Migration rates are virtually indistinguishable.
This time is not different. 24 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
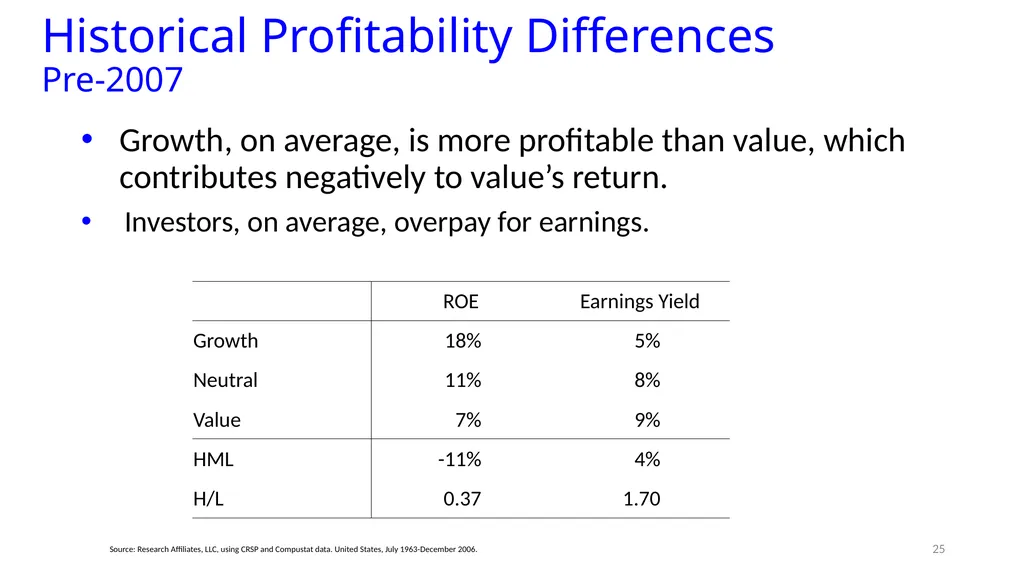
slide25. Historical Profitability Differences Pre-2007 Growth, on average, is more profitable than value, which contributes negatively to value’s return.
Investors, on average, overpay for earnings. 25 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-December 2006.<br>
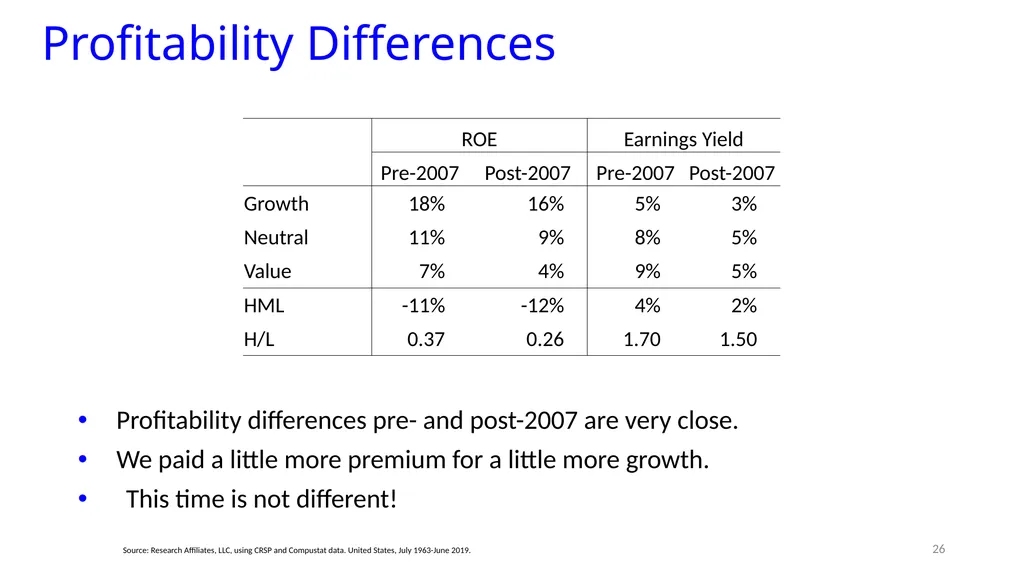
slide26. Profitability Differences Profitability differences pre- and post-2007 are very close.
We paid a little more premium for a little more growth.
This time is not different! 26 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide27. How Big Was Revaluation Alpha Post-2007?<br>
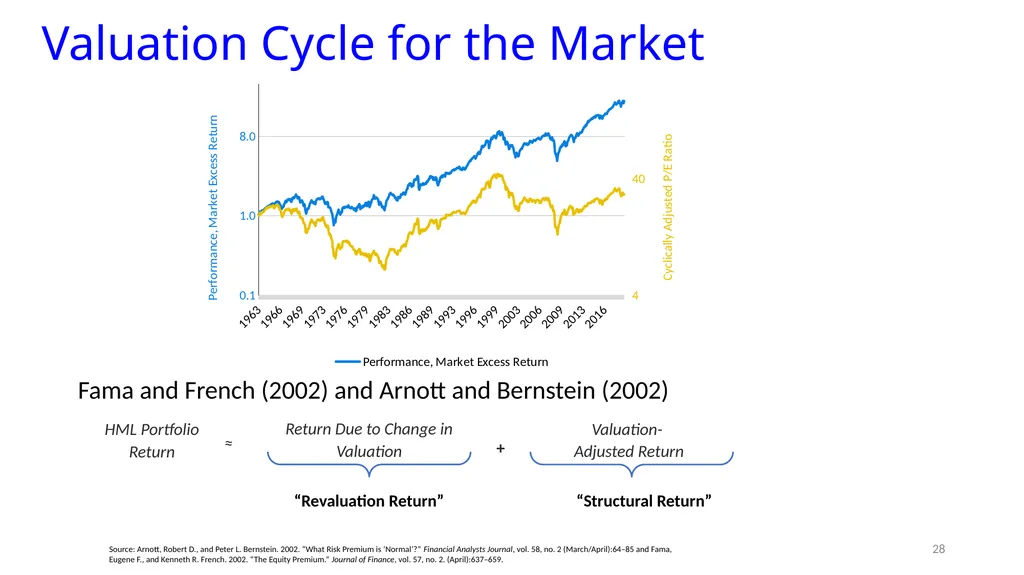
slide28. Valuation Cycle for the Market Fama and French (2002) and Arnott and Bernstein (2002) 28 Source: Arnott, Robert D., and Peter L. Bernstein. 2002. “What Risk Premium is ‘Normal’?” Financial Analysts Journal, vol. 58, no. 2 (March/April):64–85 and Fama, Eugene F., and Kenneth R. French. 2002. “The Equity Premium.” Journal of Finance, vol. 57, no. 2. (April):637–659.<br>
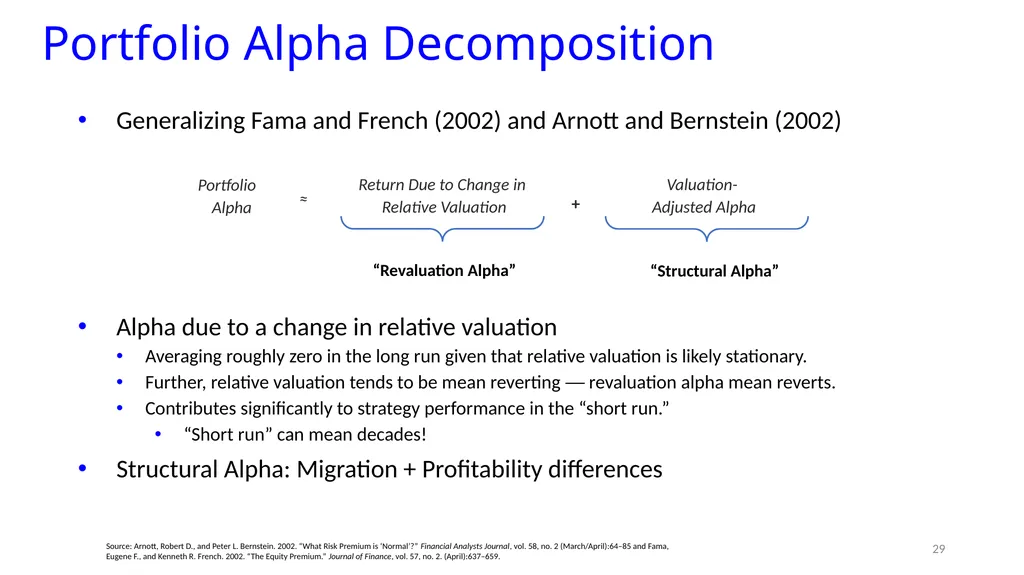
slide29. Portfolio Alpha Decomposition Generalizing Fama and French (2002) and Arnott and Bernstein (2002)
Alpha due to a change in relative valuation
Averaging roughly zero in the long run given that relative valuation is likely stationary.
Further, relative valuation tends to be mean reverting — revaluation alpha mean reverts.
Contributes significantly to strategy performance in the “short run.”
“Short run” can mean decades!
Structural Alpha: Migration + Profitability differences 29 Source: Arnott, Robert D., and Peter L. Bernstein. 2002. “What Risk Premium is ‘Normal’?” Financial Analysts Journal, vol. 58, no. 2 (March/April):64–85 and Fama, Eugene F., and Kenneth R. French. 2002. “The Equity Premium.” Journal of Finance, vol. 57, no. 2. (April):637–659.<br>
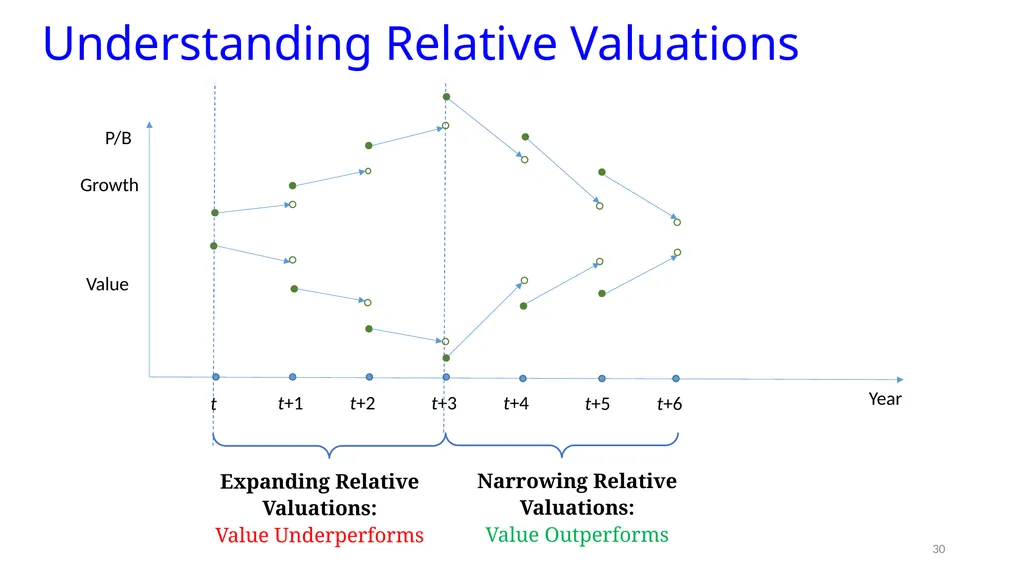
slide30. Understanding Relative Valuations 30<br>
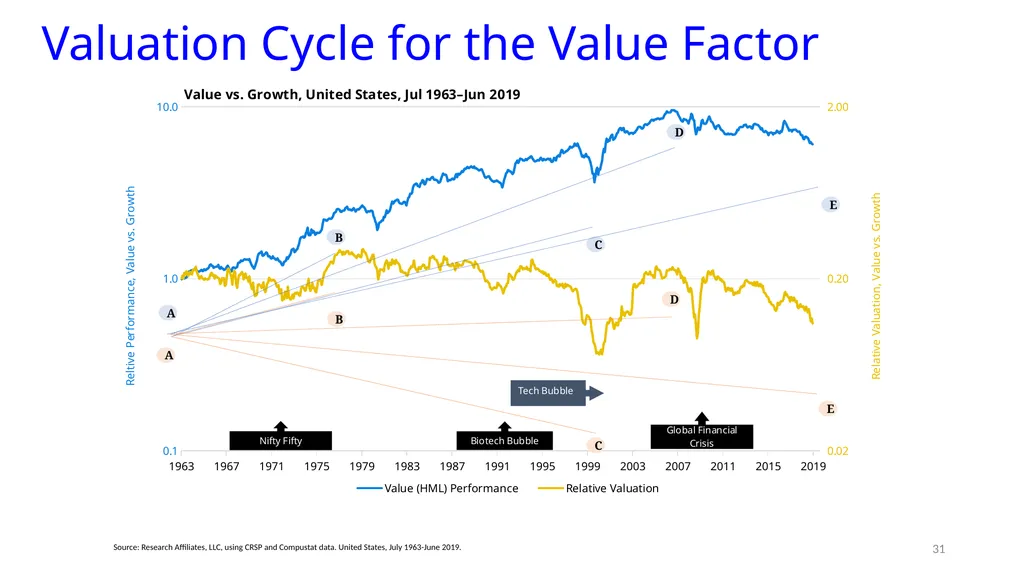
slide31. Valuation Cycle for the Value Factor 31 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
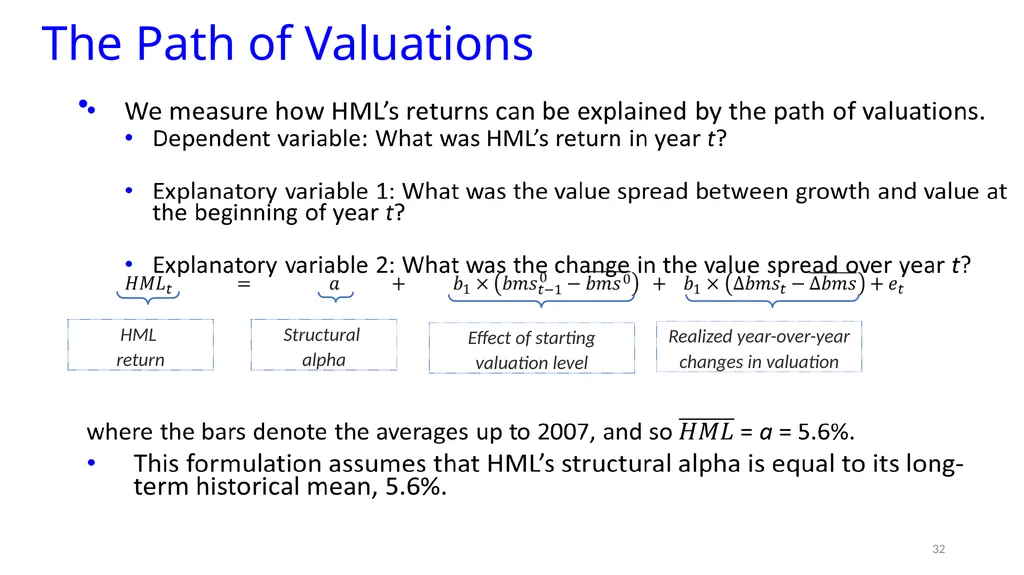
slide32. The Path of Valuations 32<br>
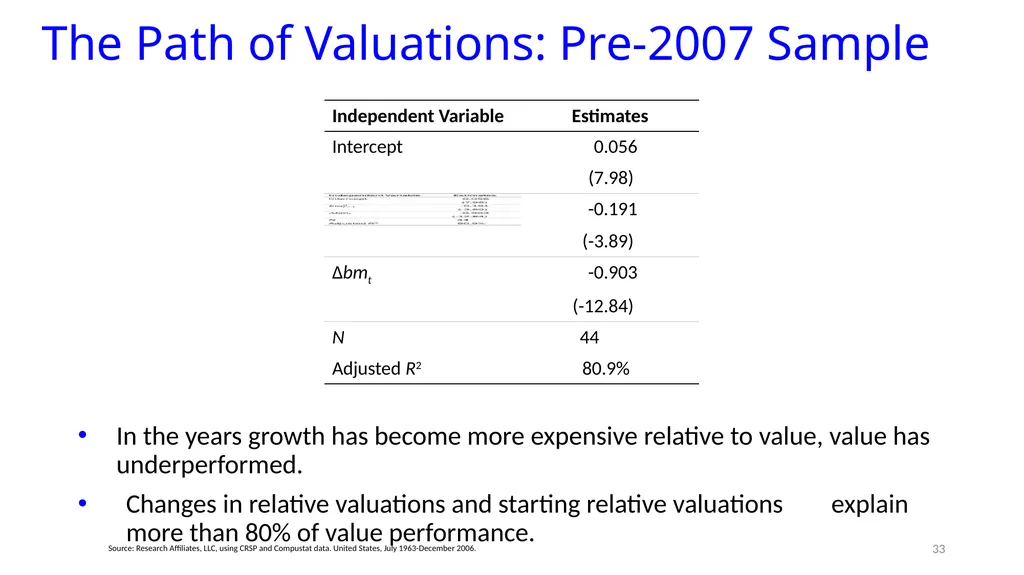
slide33. The Path of Valuations: Pre-2007 Sample In the years growth has become more expensive relative to value, value has underperformed.
Changes in relative valuations and starting relative valuations explain more than 80% of value performance. 33 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-December 2006.<br>
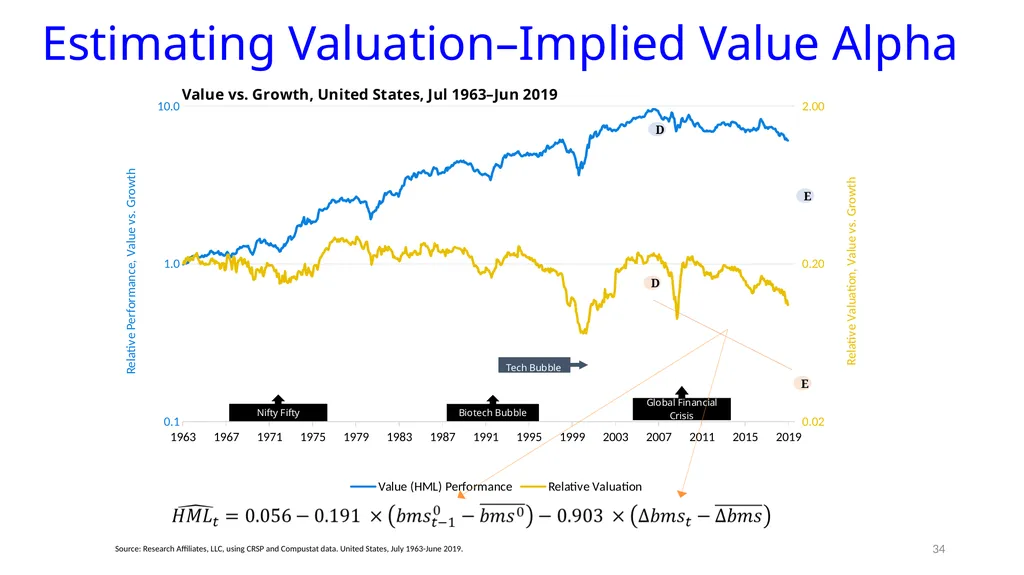
slide34. Estimating Valuation–Implied Value Alpha 34 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
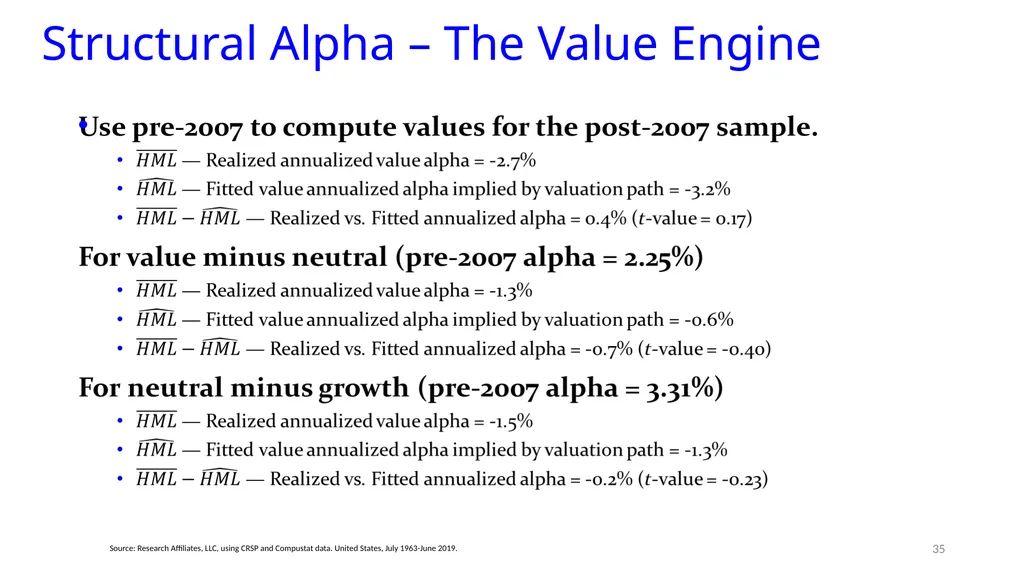
slide35. Structural Alpha – The Value Engine 35 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
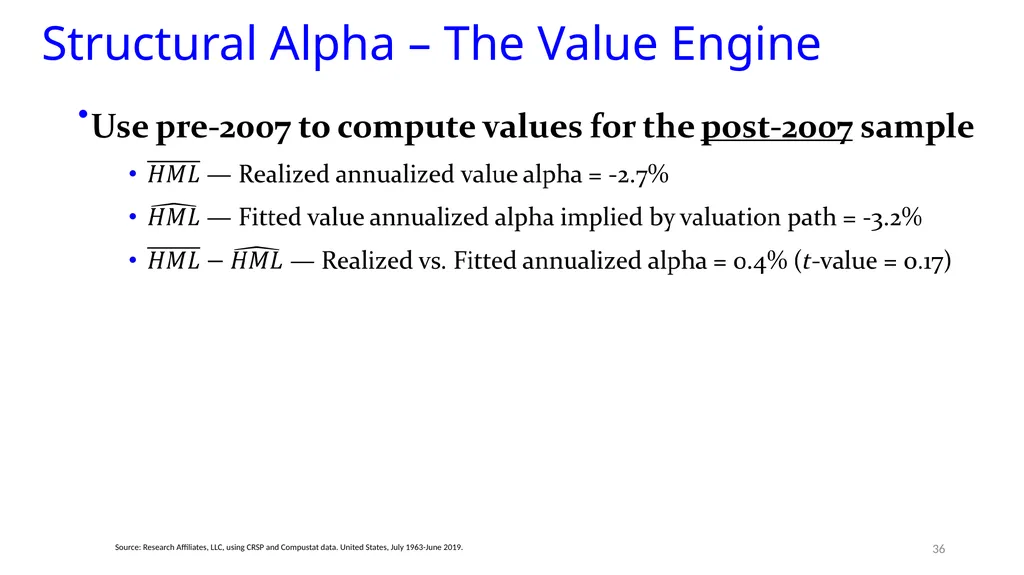
slide36. Structural Alpha – The Value Engine 36 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide37. Structural Alpha – The Value Engine Starting valuation: one of the narrowest in history (19.5th percentile)
Ending valuation: one of the widest in history (95.8th percentile)
It was wider only during the dot-com bubble (2000) and GFC (2009).
The association between changes in valuations and HML in the pre-2007 sample substantially explains why value has underperformed post-2007.
Post-2007 return can be fully attributed to revaluation. 37 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
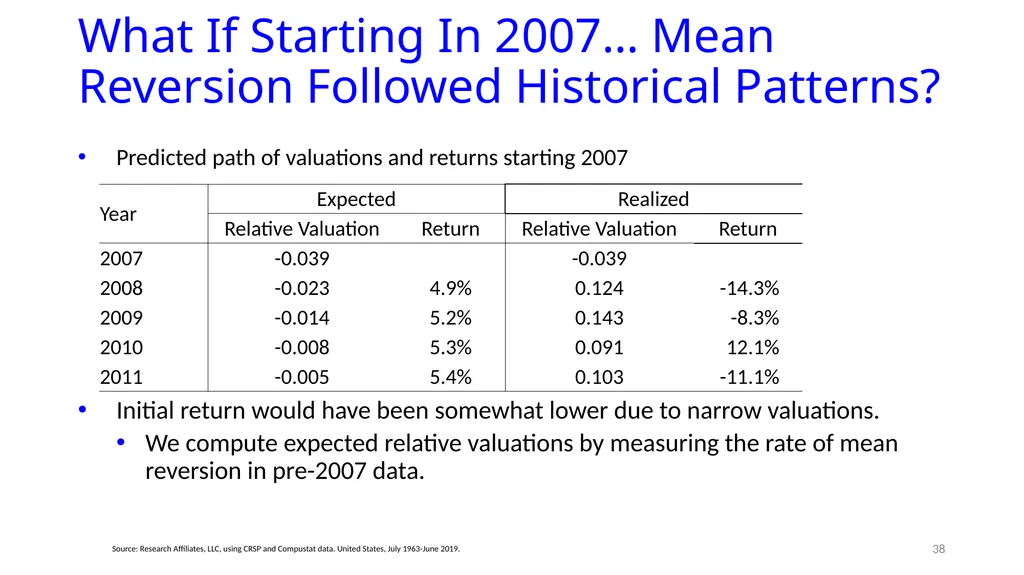
slide38. What If Starting In 2007… Mean Reversion Followed Historical Patterns? Predicted path of valuations and returns starting 2007
Initial return would have been somewhat lower due to narrow valuations.
We compute expected relative valuations by measuring the rate of mean reversion in pre-2007 data. 38 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
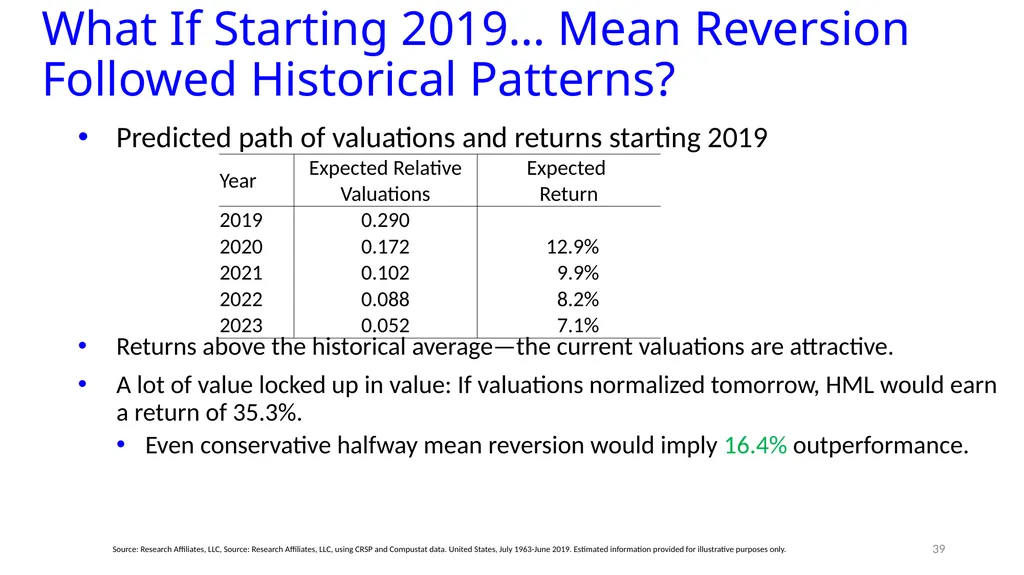
slide39. What If Starting 2019… Mean Reversion Followed Historical Patterns? Predicted path of valuations and returns starting 2019
Returns above the historical average—the current valuations are attractive.
A lot of value locked up in value: If valuations normalized tomorrow, HML would earn a return of 35.3%.
Even conservative halfway mean reversion would imply 16.4% outperformance. 39 Source: Research Affiliates, LLC, Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide40. How Much Mean Reversion is Necessary for Value to Outperform Growth? A modest mean reversion from the 95.8th percentile to the 93.6th percentile implies value breakeven with growth. 40 Source: Research Affiliates, LLC, Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide41. How This Time Was Different<br>
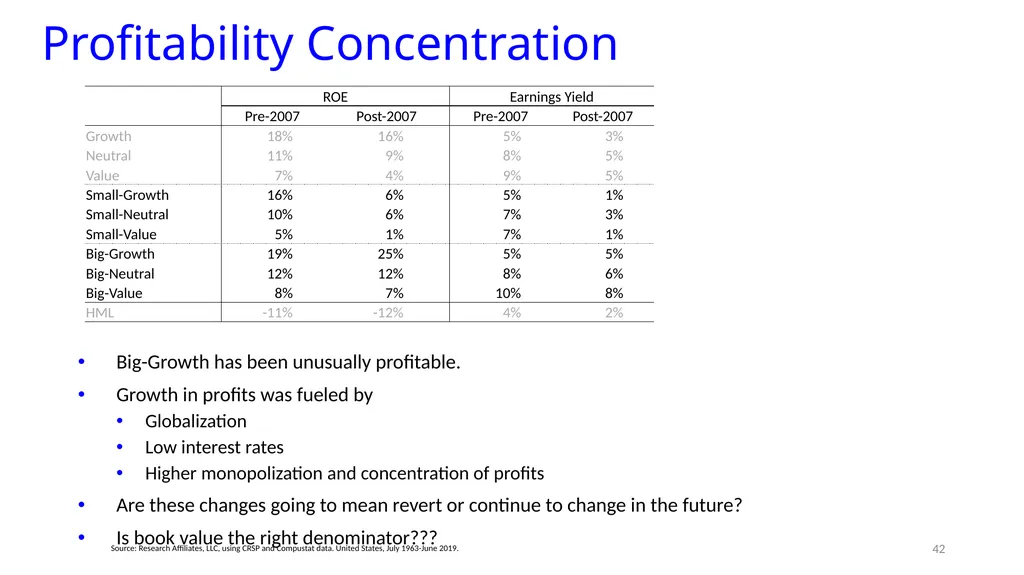
slide42. Profitability Concentration Big-Growth has been unusually profitable.
Growth in profits was fueled by
Globalization
Low interest rates
Higher monopolization and concentration of profits
Are these changes going to mean revert or continue to change in the future?
Is book value the right denominator??? 42 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
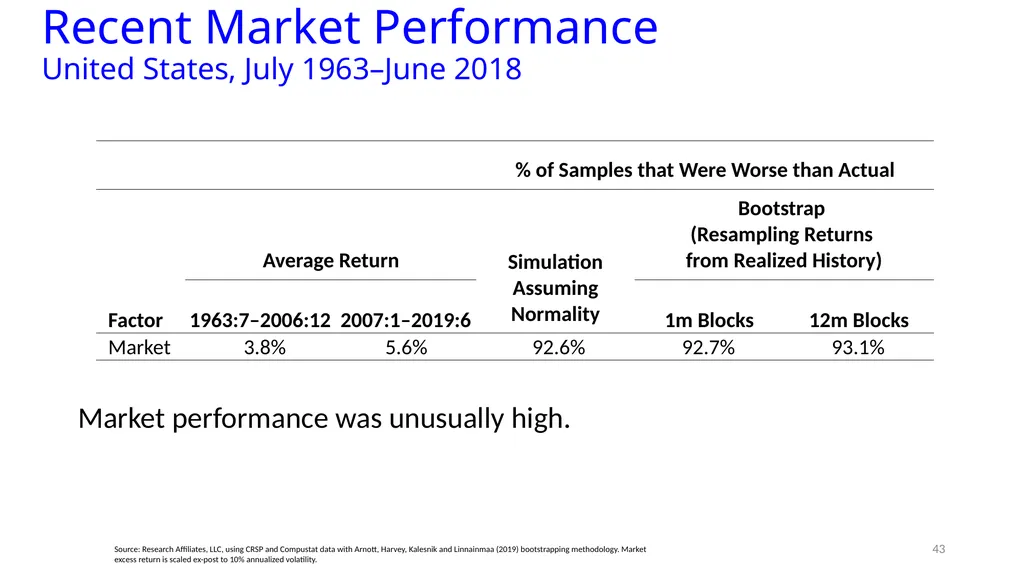
slide43. Recent Market Performance United States, July 1963–June 2018 Market performance was unusually high. 43 Source: Research Affiliates, LLC, using CRSP and Compustat data with Arnott, Harvey, Kalesnik and Linnainmaa (2019) bootstrapping methodology. Market excess return is scaled ex-post to 10% annualized volatility.<br>
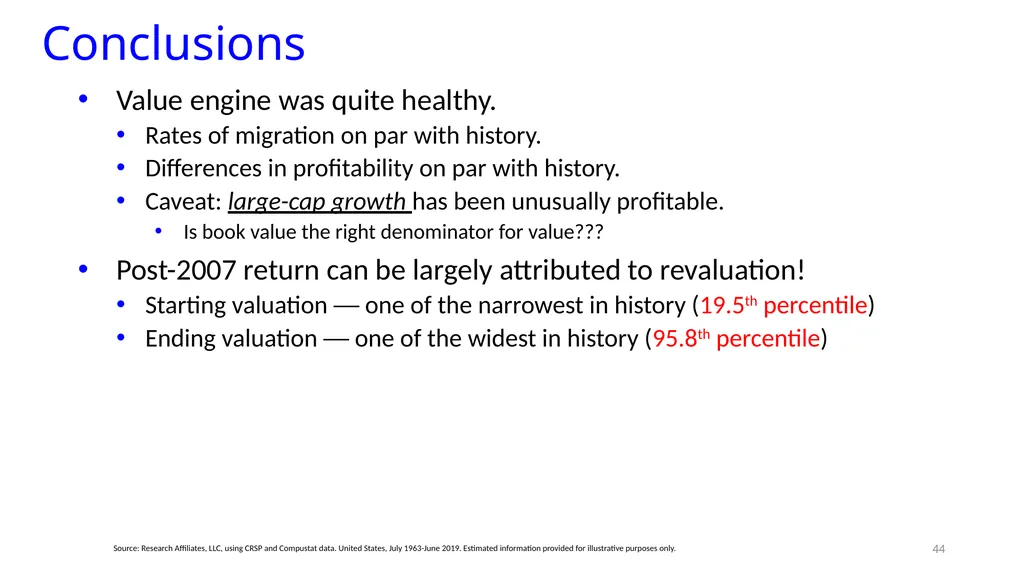
slide44. Conclusions Value engine was quite healthy.
Rates of migration on par with history.
Differences in profitability on par with history.
Caveat: large-cap growth has been unusually profitable.
Is book value the right denominator for value???
Post-2007 return can be largely attributed to revaluation!
Starting valuation — one of the narrowest in history (19.5th percentile)
Ending valuation — one of the widest in history (95.8th percentile) 44 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide45. Conclusions Do we have a growth bubble?
If valuations were to mean-revert today, value will outperform growth by 35.3%.
Even halfway mean reversion would imply 16.4% outperformance!
A modest mean reversion from 95.8th to 93.6th percentile implies value breakeven with growth 45 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide46. Supplementary Material<br>
slide47. Value Mismeasurement Investments in intangible assets such as research and development, unpatented technology, trademarks, software and client relationships are increasingly important as the U.S. evolves from a manufacturing economy to a service-oriented economy.
Accounting systems developed over 100 years ago treat intangibles as expenses rather than valuable long-term investments.
This is the reason that the notion of book value is increasingly irrelevant (intangible expenses are deducted from book value). 47<br>
slide48. Value Mismeasurement Implications:
Many “growth” stocks are misclassified and should be neutral or value
Similarly, some “value” stocks are misclassified 48<br>
slide49. Value Mismeasurement Repairs:
Capitalize the intangibles and adjust the book value*
Use alternative measures of value 49 *See Lev and Srivastava (2019)<br>
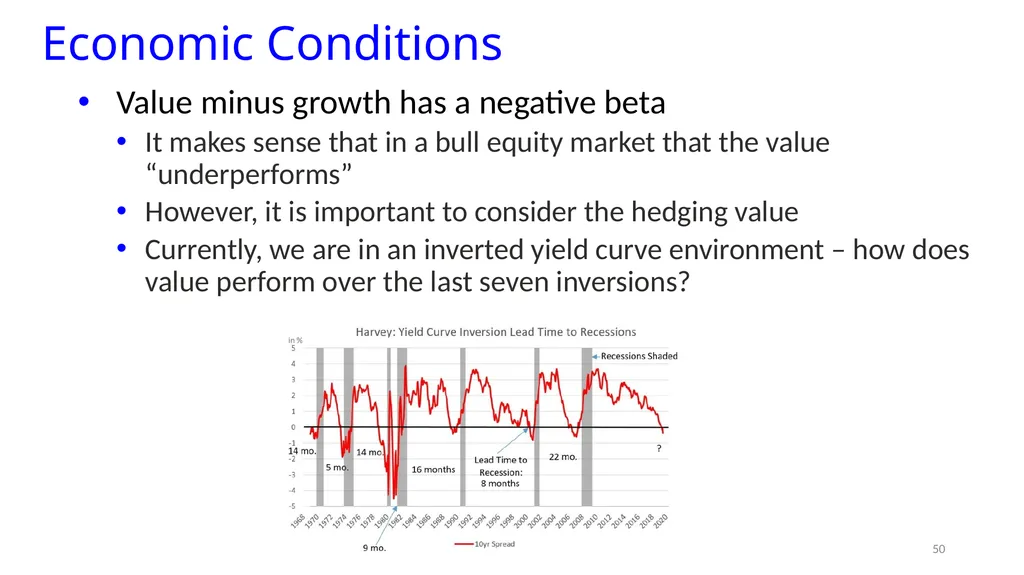
slide50. Economic Conditions Value minus growth has a negative beta
It makes sense that in a bull equity market that the value “underperforms”
However, it is important to consider the hedging value
Currently, we are in an inverted yield curve environment – how does value perform over the last seven inversions? 50<br>
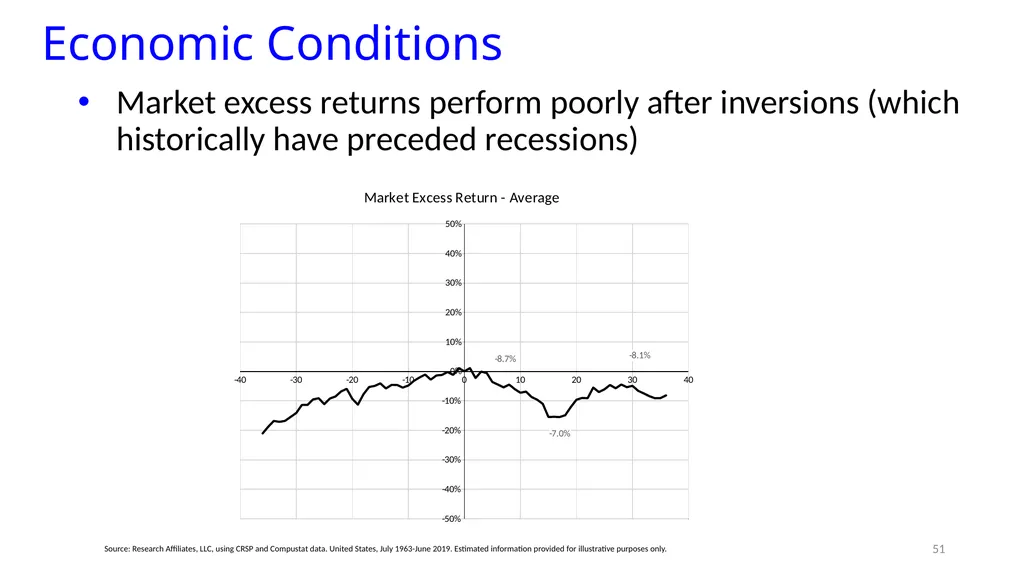
slide51. Economic Conditions Market excess returns perform poorly after inversions (which historically have preceded recessions) 51 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
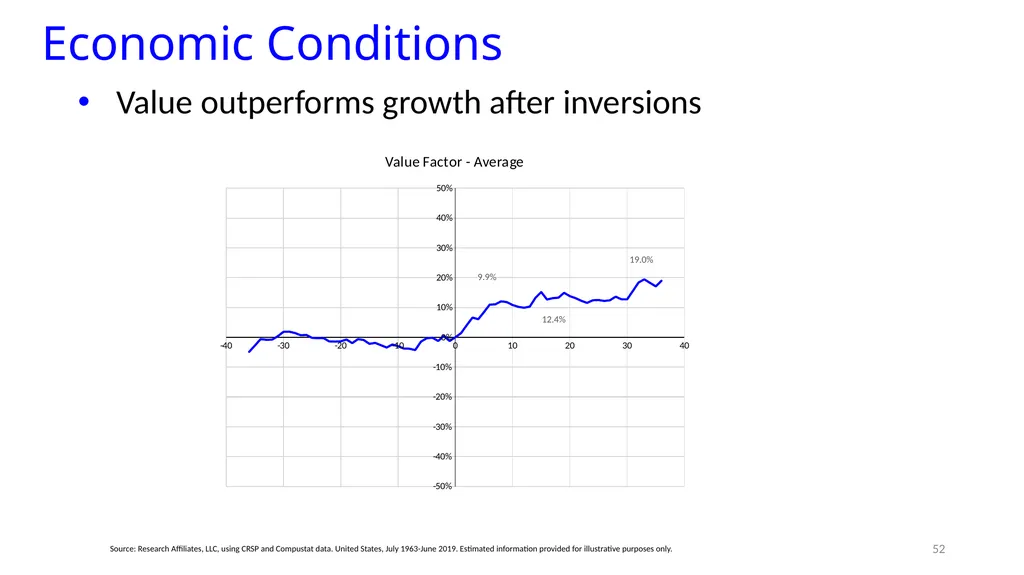
slide52. Economic Conditions Value outperforms growth after inversions 52 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide53. Economic Conditions Over 50% of U.S. CFOs believe that low long-term interest rates are bad for the economy according to the Duke-CFO Survey
CFOs see historic low interest rates favoring firms with market power
FANMAG stocks have market power and have accounted for the bulk of the S&P 500 performance. 53 www.cfosurvey.org<br>
slide54. Economic Conditions Are the duopolies sustainable?
Google and Facebook in Advertising
AWS and Azure in the Cloud
Android and iOS in mobile OS
Google and Amazon in consumer AI (personal assistants)
Walmart and Amazon in retail
Amazon and Apple as ecosystems of bundled consumer subscription lifestyles. 54 See https://medium.com/futuresin/rip-decentralization-ae2d13417da7<br>
Duke University and NBER
(Joint work in progress with Rob Arnott, Vitali Kalesnik, and Juhani Linnainmaa) November 2019 PRELIMINARY
NOT FOR DISTRIBUTION<br>
slide2. Why has value underperformed growth? Did crowding reduce expected returns?
Different economic regime?
Different interest rate regime?
Less relative mean reversion?
Is value mismeasured?
Value has lagged because it has become cheaper? 2<br>
slide3. Testable Implications Crowded trade?
Permanently narrow valuation spread
Different economic regime?
Growth permanently more profitable vs. value
Different interest rate regime?
Growth permanently more profitable vs. value
Less relative mean reversion?
Lower rate of price mean reversion
Is value mismeasured?
Potential to fix mismeasurement of intangibles
Value has lagged because it has become cheaper?
Relative valuations would explain the underperformance 3<br>
slide4. Diagnosing Value<br>
slide5. Value Investing Is Not New 5 Graham and Dodd, Security Analysis (1934):
Derive intrinsic value of a company and compare it to the market price. Buy if cheap and sell if expensive.
“In general terms [intrinsic value] is understood to be that value which is justified by the facts, e.g., the assets, earnings, dividends, definite prospects, as distinct, let us say, from market quotations established by manipulation or distorted by psychological excesses. But it is a great mistake to imagine that intrinsic value is as definite and as determinable as is the market price. Some time ago intrinsic value (in the case of common stock) was thought to be the same as “book value,” i.e., it was equal to the net assets of the business, fairly priced. This view of intrinsic value was quite definite, but it proved almost worthless as a practical matter because neither the average earnings nor the average market price evinced any tendency to be governed by book value.”<br>
slide6. Academic Origins of Value Basu (1977) — First academic evidence of superior performance of value strategies
Stocks with low P/E (value) outperform stocks with high P/E (growth).
Fama and French (1992) — Risk-based theory of value
P/B becomes a standard academic definition of value.
Lakonishok, Shleifer, and Vishny (1994) — Mispricing theory of value 6<br>
slide7. Value Is One of the Strongest Factors United States, Jul 1963–Dec 2018 Asness, Moskowitz, and Pedersen (2013)
Value effect is pervasive across geographies and asset classes.
Beck, Hsu, Kalesnik, and Kostka (2016)
Value effect is robust to perturbation across definitions. 7 Source: Arnott, Harvey, Kalesnik and Linnainmaa (2019). Volatility is ex-post scaled to 10% annualized.
* -- significance at 10%, ** -- at 5%, *** -- at 1%.<br>
slide8. Value Has Underperformed since 2006 Examine HML — Value vs. growth long/short performance (balanced by size)
In this computation with monthly rebalancing into HML, value most recently peaked at the end of December 2006. 8 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. HML is high (value) minus low (growth) long/short portfolio balanced by size around the median by the NYSE market capitalization.<br>
slide9. Second Worst Drawdown In terms of its depth, the most recent drawdown of value counts as the second deepest since July 1963.
But value is prone to drawdowns and prolonged periods of underperformance — How unusual was this? 9 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide10. Estimated Probability of a Drawdown Use the “Alice in Factorland” bootstrapping methodology to assess the likelihood of the drawdown that started in 2007.
Take the long/short return sample period up to December 2006.
Draw returns from this sample in six-month blocks.
Create a sample that matches the length of the actual total sample from July 1963 through June 2019.
For each simulated sample, record the size of the second-largest drawdown.
Draw 200,000 simulated samples.
We take the second-largest drawdown to be consistent with the actual data.
Drawdowns ranked by magnitude are order statistics. 10<br>
slide11. Likelihood of Recent Drawdown Magnitude (Six-Month Bootstraps) The second-largest drawdown in 4.1% of the simulated samples exceeds the actual drawdown of 36.5%.
4.1% is unusual but inconsistent with “broken” 11 Source: Research Affiliates, LLC, bootstrapping exercise using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide12. Drawdown Duration In terms of its depth, the most recent drawdown of value is, by far, the longest duration since July 1963.
But value is prone to drawdowns and prolonged periods of underperformance — How unusual was this? 12 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide13. Estimated Probability of a Drawdown Use the “Alice in Factorland” bootstrapping methodology to assess the likelihood of the drawdown that started in 2007.
Take the long/short return sample period up to December 2006.
Draw returns from this sample in six-month, two- and five-year blocks.
Create a sample that matches the length of the actual total sample from July 1963 through June 2019.
For each simulated sample, record the length of the longest drawdown.
Draw 200,000 simulated samples.
We take the longest drawdowns. 13<br>
slide14. Likelihood of Recent Drawdown Duration (Six-Month Bootstraps) In 23% of the simulated samples, the longest period of underperformance lasts longer than the 12.5 years we are experiencing now.
The duration of the recent drawdown within the norm. 14 Source: Research Affiliates, LLC, bootstrapping exercise using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide15. Likelihood of Recent Drawdown Duration (Five-Year Bootstraps) In 6% of the simulated samples, the longest period of underperformance lasts longer than the 12.5 years we are experiencing now. Usually value performance mean reverts very fast—not this time!
Unusual, but not consistent with “broken” 15 Source: Research Affiliates, LLC, bootstrapping exercise using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide16. Is the Value Engine Broken? 16<br>
slide17. Value Engine Components Value minus growth driven by revaluation as well as two structural components:
Migration
Profitability differences 17<br>
slide18. How Value Works, on Average — Migration Fama and French (2007) — A large share of the value premium comes from:
Value stocks migrating to neutral and to growth.
Growth stocks migrating to neutral and to value. 18 Growth Value Year t t+1
Before Rebalancing t+1
After Rebalancing New Growth New Value P/B<br>
slide19. How Value Works On Average — Profitability Growth, on average, is more profitable than value, which contributes negatively to value’s return. 19 Growth Value Year t t+1
Before rebalancing t+1
After rebalancing New Growth New Value P/B<br>
slide20. Migration Rates, Pre-2007 20 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide21. Migration Rates, Post-2007 21 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide22. Migration Rates 22 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide23. Migration Rates 23 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide24. Migration Rates Migration rates are virtually indistinguishable.
This time is not different. 24 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide25. Historical Profitability Differences Pre-2007 Growth, on average, is more profitable than value, which contributes negatively to value’s return.
Investors, on average, overpay for earnings. 25 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-December 2006.<br>
slide26. Profitability Differences Profitability differences pre- and post-2007 are very close.
We paid a little more premium for a little more growth.
This time is not different! 26 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide27. How Big Was Revaluation Alpha Post-2007?<br>
slide28. Valuation Cycle for the Market Fama and French (2002) and Arnott and Bernstein (2002) 28 Source: Arnott, Robert D., and Peter L. Bernstein. 2002. “What Risk Premium is ‘Normal’?” Financial Analysts Journal, vol. 58, no. 2 (March/April):64–85 and Fama, Eugene F., and Kenneth R. French. 2002. “The Equity Premium.” Journal of Finance, vol. 57, no. 2. (April):637–659.<br>
slide29. Portfolio Alpha Decomposition Generalizing Fama and French (2002) and Arnott and Bernstein (2002)
Alpha due to a change in relative valuation
Averaging roughly zero in the long run given that relative valuation is likely stationary.
Further, relative valuation tends to be mean reverting — revaluation alpha mean reverts.
Contributes significantly to strategy performance in the “short run.”
“Short run” can mean decades!
Structural Alpha: Migration + Profitability differences 29 Source: Arnott, Robert D., and Peter L. Bernstein. 2002. “What Risk Premium is ‘Normal’?” Financial Analysts Journal, vol. 58, no. 2 (March/April):64–85 and Fama, Eugene F., and Kenneth R. French. 2002. “The Equity Premium.” Journal of Finance, vol. 57, no. 2. (April):637–659.<br>
slide30. Understanding Relative Valuations 30<br>
slide31. Valuation Cycle for the Value Factor 31 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide32. The Path of Valuations 32<br>
slide33. The Path of Valuations: Pre-2007 Sample In the years growth has become more expensive relative to value, value has underperformed.
Changes in relative valuations and starting relative valuations explain more than 80% of value performance. 33 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-December 2006.<br>
slide34. Estimating Valuation–Implied Value Alpha 34 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide35. Structural Alpha – The Value Engine 35 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide36. Structural Alpha – The Value Engine 36 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide37. Structural Alpha – The Value Engine Starting valuation: one of the narrowest in history (19.5th percentile)
Ending valuation: one of the widest in history (95.8th percentile)
It was wider only during the dot-com bubble (2000) and GFC (2009).
The association between changes in valuations and HML in the pre-2007 sample substantially explains why value has underperformed post-2007.
Post-2007 return can be fully attributed to revaluation. 37 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide38. What If Starting In 2007… Mean Reversion Followed Historical Patterns? Predicted path of valuations and returns starting 2007
Initial return would have been somewhat lower due to narrow valuations.
We compute expected relative valuations by measuring the rate of mean reversion in pre-2007 data. 38 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide39. What If Starting 2019… Mean Reversion Followed Historical Patterns? Predicted path of valuations and returns starting 2019
Returns above the historical average—the current valuations are attractive.
A lot of value locked up in value: If valuations normalized tomorrow, HML would earn a return of 35.3%.
Even conservative halfway mean reversion would imply 16.4% outperformance. 39 Source: Research Affiliates, LLC, Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide40. How Much Mean Reversion is Necessary for Value to Outperform Growth? A modest mean reversion from the 95.8th percentile to the 93.6th percentile implies value breakeven with growth. 40 Source: Research Affiliates, LLC, Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide41. How This Time Was Different<br>
slide42. Profitability Concentration Big-Growth has been unusually profitable.
Growth in profits was fueled by
Globalization
Low interest rates
Higher monopolization and concentration of profits
Are these changes going to mean revert or continue to change in the future?
Is book value the right denominator??? 42 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019.<br>
slide43. Recent Market Performance United States, July 1963–June 2018 Market performance was unusually high. 43 Source: Research Affiliates, LLC, using CRSP and Compustat data with Arnott, Harvey, Kalesnik and Linnainmaa (2019) bootstrapping methodology. Market excess return is scaled ex-post to 10% annualized volatility.<br>
slide44. Conclusions Value engine was quite healthy.
Rates of migration on par with history.
Differences in profitability on par with history.
Caveat: large-cap growth has been unusually profitable.
Is book value the right denominator for value???
Post-2007 return can be largely attributed to revaluation!
Starting valuation — one of the narrowest in history (19.5th percentile)
Ending valuation — one of the widest in history (95.8th percentile) 44 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide45. Conclusions Do we have a growth bubble?
If valuations were to mean-revert today, value will outperform growth by 35.3%.
Even halfway mean reversion would imply 16.4% outperformance!
A modest mean reversion from 95.8th to 93.6th percentile implies value breakeven with growth 45 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide46. Supplementary Material<br>
slide47. Value Mismeasurement Investments in intangible assets such as research and development, unpatented technology, trademarks, software and client relationships are increasingly important as the U.S. evolves from a manufacturing economy to a service-oriented economy.
Accounting systems developed over 100 years ago treat intangibles as expenses rather than valuable long-term investments.
This is the reason that the notion of book value is increasingly irrelevant (intangible expenses are deducted from book value). 47<br>
slide48. Value Mismeasurement Implications:
Many “growth” stocks are misclassified and should be neutral or value
Similarly, some “value” stocks are misclassified 48<br>
slide49. Value Mismeasurement Repairs:
Capitalize the intangibles and adjust the book value*
Use alternative measures of value 49 *See Lev and Srivastava (2019)<br>
slide50. Economic Conditions Value minus growth has a negative beta
It makes sense that in a bull equity market that the value “underperforms”
However, it is important to consider the hedging value
Currently, we are in an inverted yield curve environment – how does value perform over the last seven inversions? 50<br>
slide51. Economic Conditions Market excess returns perform poorly after inversions (which historically have preceded recessions) 51 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide52. Economic Conditions Value outperforms growth after inversions 52 Source: Research Affiliates, LLC, using CRSP and Compustat data. United States, July 1963-June 2019. Estimated information provided for illustrative purposes only.<br>
slide53. Economic Conditions Over 50% of U.S. CFOs believe that low long-term interest rates are bad for the economy according to the Duke-CFO Survey
CFOs see historic low interest rates favoring firms with market power
FANMAG stocks have market power and have accounted for the bulk of the S&P 500 performance. 53 www.cfosurvey.org<br>
slide54. Economic Conditions Are the duopolies sustainable?
Google and Facebook in Advertising
AWS and Azure in the Cloud
Android and iOS in mobile OS
Google and Amazon in consumer AI (personal assistants)
Walmart and Amazon in retail
Amazon and Apple as ecosystems of bundled consumer subscription lifestyles. 54 See https://medium.com/futuresin/rip-decentralization-ae2d13417da7<br>