
Response to public hearings MARCH 2022 1 List of






Description: Response to public hearings MARCH 2022 1 List of organisations that made submissions Parliament Budget Office (PBO) Financial and Fiscal Commission (FFC) Fiscal Cliff Study Group South African Institute of Chartered Accountants (SAICA) PWC
Related Topics
Download Presentation
"Response to public hearings MARCH 2022 1 List of" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Response to public hearings MARCH 2022 1<br>
slide2. List of organisations that made submissions Parliament Budget Office (PBO)
Financial and Fiscal Commission (FFC)
Fiscal Cliff Study Group
South African Institute of Chartered Accountants (SAICA)
PWC
South African Institute of Taxation (SAIT)
Amandla.Mobi
Congress of South African Trade Unions (COSATU)
Financial and Fiscal Commission (FFC)
Healthy Living Alliance (HEALA)
1 Road consulting
South African Breweries (SAB)
Women on Farms Project
Institute for Economic Justice (IEJ)<br>
slide3. Main responses Economic growth and reforms: Fiscal policy alone cannot solve the problems of inequality, poverty and unemployment. Inclusive growth and economic reforms are essential.
Revenue and tax proposals: Several responses are noted.
Expenditure: No further budget reductions were announced in the 2022 Budget. The 2020 Budget allows increases in critical spending areas using a portion of revenue improvements.
Fiscal resilience and debt sustainability: Ever increasing debt and debt service cost crowds out the space to spend on critical priority areas.
Other matters raised:
SOCs: Significant reforms are necessary to improve efficiency of SOCs so that they are not a fiscal burden to the country and serve the people of South Africa in an effective way.
Corruption: NT has implemented several new measures to support the fight against corruption in government.
Public participation platforms: NT is continuously looking into new ways to make the budget more consultative, transparent and accessible.
Business support measures: More regulatory measures (than loan guarantee measures) were taken-up for the loan guarantee scheme which ended in July 2021. An additional loan guarantee scheme is initiated in the new year.<br>
slide4. Inclusive growth and structural reforms are critical Structural constraints have reduced potential growth for the past decade and remain an impediment to the recovery. The economic effects of the pandemic (lost jobs and delayed investments) were exacerbated by inadequate electricity supply, with the highest levels of load-shedding to date.
Reducing regulatory constraints, providing effective services, and coordinating and sequencing economic interventions will bolster public and private investment, which will, in turn, increase resilience and support economic transformation.
Reforms are needed to promote growth and employment. These reforms include:
Stimulate demand through investment in infrastructure, complemented by employment programmes and social transfers that will boost household consumption.
Modernising network industries will support an increase in the economy’s productive capacity
Boost electricity production
Reduce the cost of doing business.
The 2021 MTBPS detailed notable progress on structural reforms through Operation Vulindlela. Work is underway to expedite the approvals required to register embedded electricity generation plants, complete the analogue to digital migration and auction spectrum, and clear the backlog of water-use licences.
Post-COVID-19 recovery strategies include stimulating the economy through public employment programmes and tax incentives, while implementing reforms to ease the skill constraints and make it easier to do business. Labour-intensive, export-orientated sectors are receiving additional support.
Fiscal policy may only affect economic growth to a certain extent. Structural reforms are imperative to accelerate economic growth needed to reduce poverty and unemployment while also increasing investment.<br>
slide5. Main fiscal policy issues Over the past few years there has been a disconnect between government spending and economic growth. Higher spending should be accompanied by inclusive economic growth.
Despite measures aimed at controlling expenditure growth, the funding for the social wage has been protected to ensure that necessary goods and services are provided to those who are in need.
The decision not to implement the final leg of the 2018 wage agreement, together with other measures to reduce average wage costs have improved the wage trajectory. Government is firmly committed to the compensation ceiling as announced in the budget.
No further budget reductions were announced in the 2022 Budget. Instead, additional spending in critical spending areas were made using a portion of revenue improvements.
Despite projections to reach a primary surplus by 2023/24, debt is high. Each year, a budget deficit adds to debt, increasing debt-service cost, limiting our capacity to spend more – this cannot continue indefinitely. 5<br>
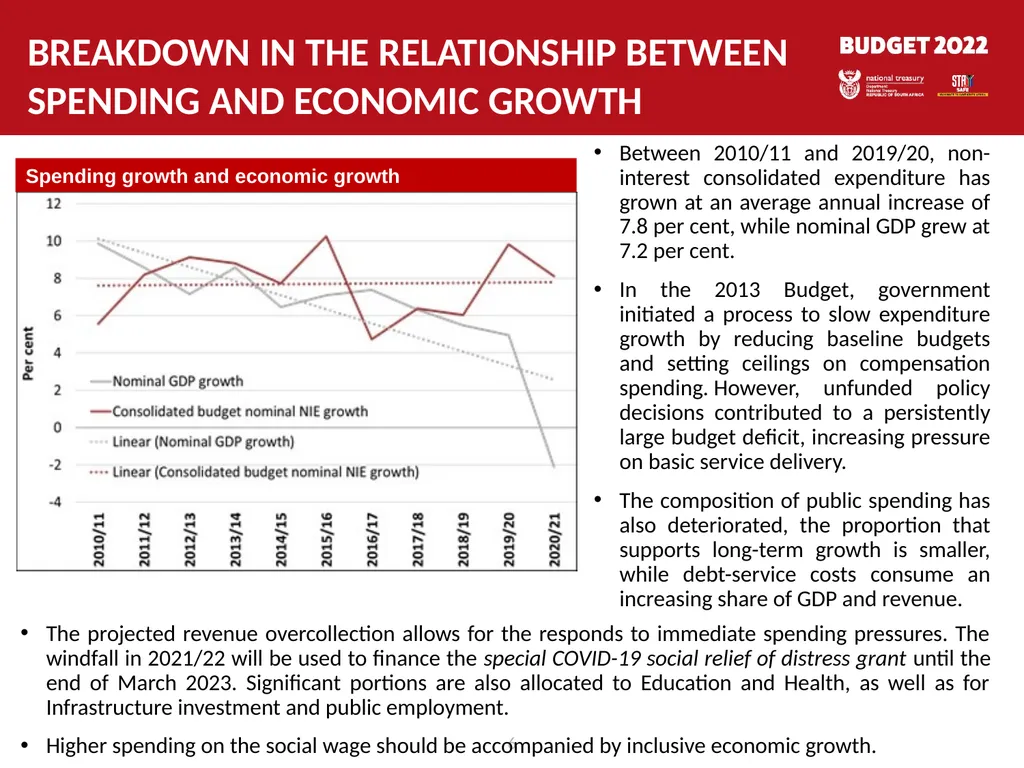
slide6. BREAKDOWN IN THE Relationship between spending and economic growth The projected revenue overcollection allows for the responds to immediate spending pressures. The windfall in 2021/22 will be used to finance the special COVID-19 social relief of distress grant until the end of March 2023. Significant portions are also allocated to Education and Health, as well as for Infrastructure investment and public employment.
Higher spending on the social wage should be accompanied by inclusive economic growth. 6 Spending growth and economic growth Between 2010/11 and 2019/20, non-interest consolidated expenditure has grown at an average annual increase of 7.8 per cent, while nominal GDP grew at 7.2 per cent.
In the 2013 Budget, government initiated a process to slow expenditure growth by reducing baseline budgets and setting ceilings on compensation spending. However, unfunded policy decisions contributed to a persistently large budget deficit, increasing pressure on basic service delivery.
The composition of public spending has also deteriorated, the proportion that supports long-term growth is smaller, while debt-service costs consume an increasing share of GDP and revenue.<br>
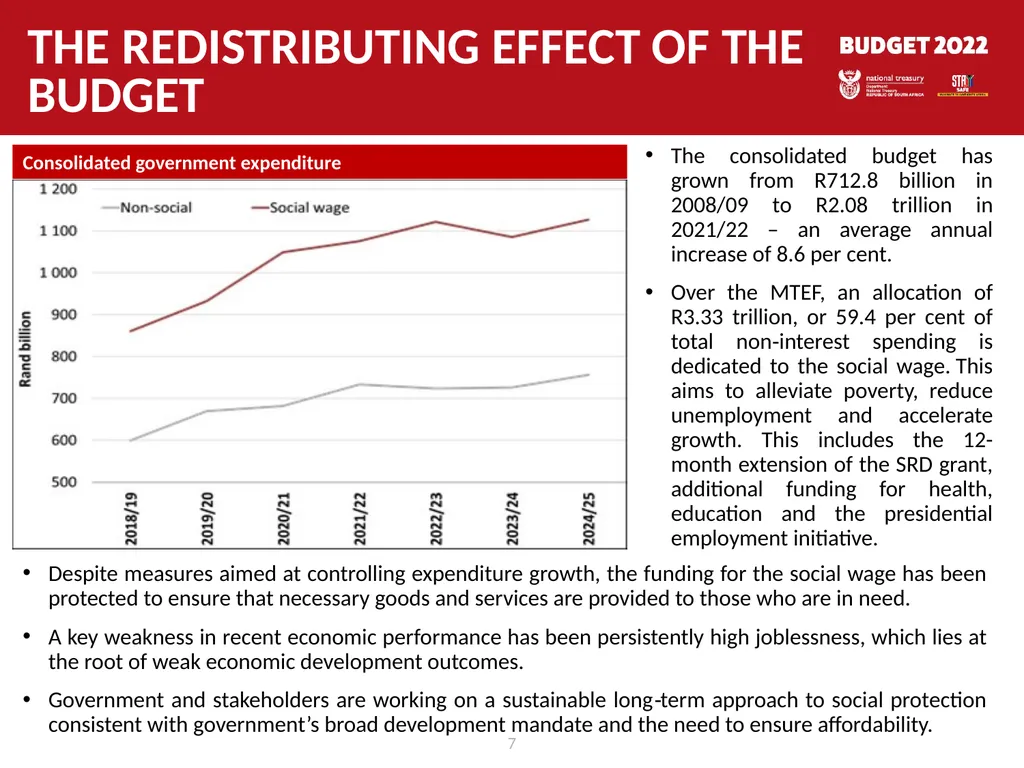
slide7. The redistributing effect of the budget 7 The consolidated budget has grown from R712.8 billion in 2008/09 to R2.08 trillion in 2021/22 – an average annual increase of 8.6 per cent.
Over the MTEF, an allocation of R3.33 trillion, or 59.4 per cent of total non‐interest spending is dedicated to the social wage. This aims to alleviate poverty, reduce unemployment and accelerate growth. This includes the 12-month extension of the SRD grant, additional funding for health, education and the presidential employment initiative. Consolidated government expenditure Despite measures aimed at controlling expenditure growth, the funding for the social wage has been protected to ensure that necessary goods and services are provided to those who are in need.
A key weakness in recent economic performance has been persistently high joblessness, which lies at the root of weak economic development outcomes.
Government and stakeholders are working on a sustainable long‐term approach to social protection consistent with government’s broad development mandate and the need to ensure affordability.<br>
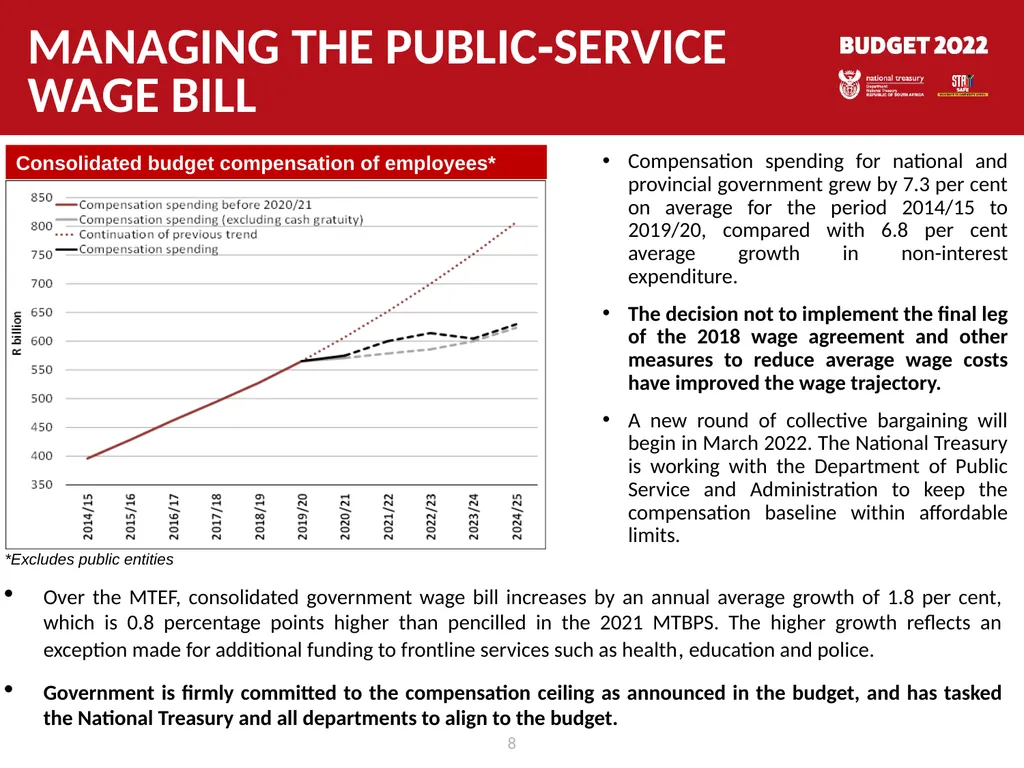
slide8. Managing the public‐service wage bill Compensation spending for national and provincial government grew by 7.3 per cent on average for the period 2014/15 to 2019/20, compared with 6.8 per cent average growth in non-interest expenditure.
The decision not to implement the final leg of the 2018 wage agreement and other measures to reduce average wage costs have improved the wage trajectory.
A new round of collective bargaining will begin in March 2022. The National Treasury is working with the Department of Public Service and Administration to keep the compensation baseline within affordable limits. 8 Over the MTEF, consolidated government wage bill increases by an annual average growth of 1.8 per cent, which is 0.8 percentage points higher than pencilled in the 2021 MTBPS. The higher growth reflects an exception made for additional funding to frontline services such as health, education and police.
Government is firmly committed to the compensation ceiling as announced in the budget, and has tasked the National Treasury and all departments to align to the budget. Consolidated budget compensation of employees* *Excludes public entities<br>
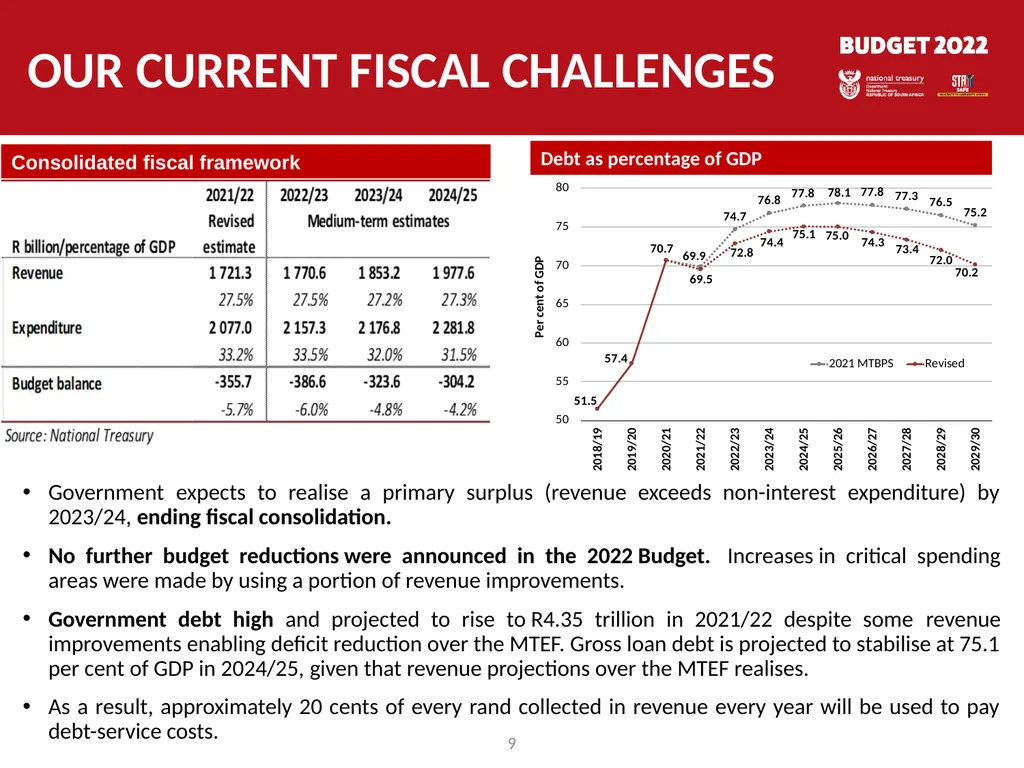
slide9. Our current fiscal challenges Government expects to realise a primary surplus (revenue exceeds non-interest expenditure) by 2023/24, ending fiscal consolidation.
No further budget reductions were announced in the 2022 Budget. Increases in critical spending areas were made by using a portion of revenue improvements.
Government debt high and projected to rise to R4.35 trillion in 2021/22 despite some revenue improvements enabling deficit reduction over the MTEF. Gross loan debt is projected to stabilise at 75.1 per cent of GDP in 2024/25, given that revenue projections over the MTEF realises.
As a result, approximately 20 cents of every rand collected in revenue every year will be used to pay debt-service costs. 9 Consolidated fiscal framework Debt as percentage of GDP<br>
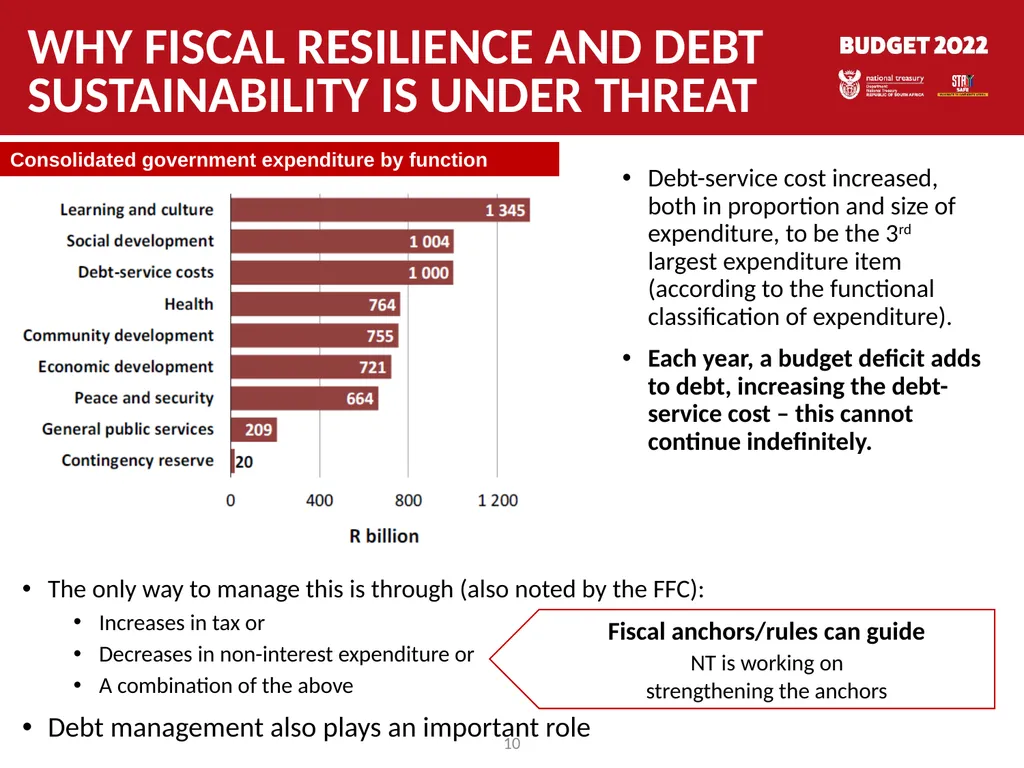
slide10. Why Fiscal resilience and debt sustainability is under threat 10 Consolidated government expenditure by function The only way to manage this is through (also noted by the FFC):
Increases in tax or
Decreases in non-interest expenditure or
A combination of the above
Debt management also plays an important role Debt-service cost increased, both in proportion and size of expenditure, to be the 3rd largest expenditure item (according to the functional classification of expenditure).
Each year, a budget deficit adds to debt, increasing the debt-service cost – this cannot continue indefinitely. Fiscal anchors/rules can guide
NT is working on
strengthening the anchors<br>
slide11. state-owned companies The operational and financial health of many state-owned companies continues to decline. Over the past 12 months, several have missed their capital investments and loan disbursements targets.
Investors have increasingly expressed an unwillingness to extend capital to such entities without government guarantees, leaving many state-owned companies at risk of defaulting on their debts.
To reduce their demands on limited public resources, state-owned companies need to develop and implement sustainable turnaround plans that align with their mandates, incorporate long-term structural considerations in their sectors and identify appropriate funding models.
During 2022/23, the National Treasury will publish a framework outlining the criteria for government funding of state-owned companies. Government will guide and support credible restructuring plans. Guaranteed debt continues to have full backing of government.
The total amount of approved guarantees to state-owned companies is expected to reach R560.1 billion by the end of 2021/22, which is R21.5 billion lower than in 2020/21. The associated exposure is estimated to increase by R32.1 billion to R416.8 billion by March 2022. Eskom accounts for 78.7 per cent of these guarantees.
Excluding Eskom, total debt maturing over the next three years is expected to amount to R67.4 billion, of which 22 per cent or R14.9 billion is guaranteed by government.
List of public entities can be found on the National Treasury Website (PFMA Schedules).<br>
slide12. PUBLIC PARTICIPATIONS platforms 12 South Africa ranked first, among 117 countries, in the 2017 and 2019 Open Budget Index. The index measures the quality of budget transparency, public participation in the budget processes and institutional oversight.
Pre-budget public participation : Budget tips (over 300 Budget tips received for 2022 Budget)
Post-budget public participation:
People’s Guide to the Budget – presented in 7 languages and circulated in communities
Community radio stations engagements – about 21 radio stations across different provinces
Budget Outreach Programme
Other public participation
National Treasury Website – All budget information including data sets (eg. new budget dashboard)
Vulekamali - an easily accessible online budget data portal
Fiscal Openness Accelerator - to support innovation to deepen participation by members of the public in fiscal policy. The initiative aims to improve public participation in the budget process.
NT is continuously looking at more inclusive public participation mechanisms<br>
slide13. What is NT doing to fight Corruption 13 The 2022 Budget Review states that funds are being reprioritised in the peace and security function to enhance capacity in institutions combatting crime and corruption.
The Investigating Directorate in the National Prosecuting Authority and the Financial Intelligence Centre are together allocated R426 million over the MTEF period.
This allocation will enable the permanent appointment of 68 personnel in the Financial Intelligence Centre and an estimated 90 personnel in the Investigating Directorate to provide specialised services.
Legal Aid South Africa is also allocated R34.3 million over the medium term to provide capacity at newly established Specialised Commercial Crime Courts in the provinces of Limpopo, Mpumalanga, North West, and Northern Cape.
The Public Procurement Bill will be tabled before Parliament in 2022/23.
The bill will be revisited to take into account the recent Constitutional Court judgement on the preferential procurement regulations and the Zondo Commission report.<br>
slide14. Taxation and revenue policy Treasury notes, and welcomes, the number of questions on tax policy and on revenue projections
In past years, we have requested that SCOF have a special session on tax policy and financial sector announcements soon after the Budget, either as part of the post-Budget hearings, or soon after this process
Tax announcements are market-sensitive, and no prior consultations take place before Budget Day announcements
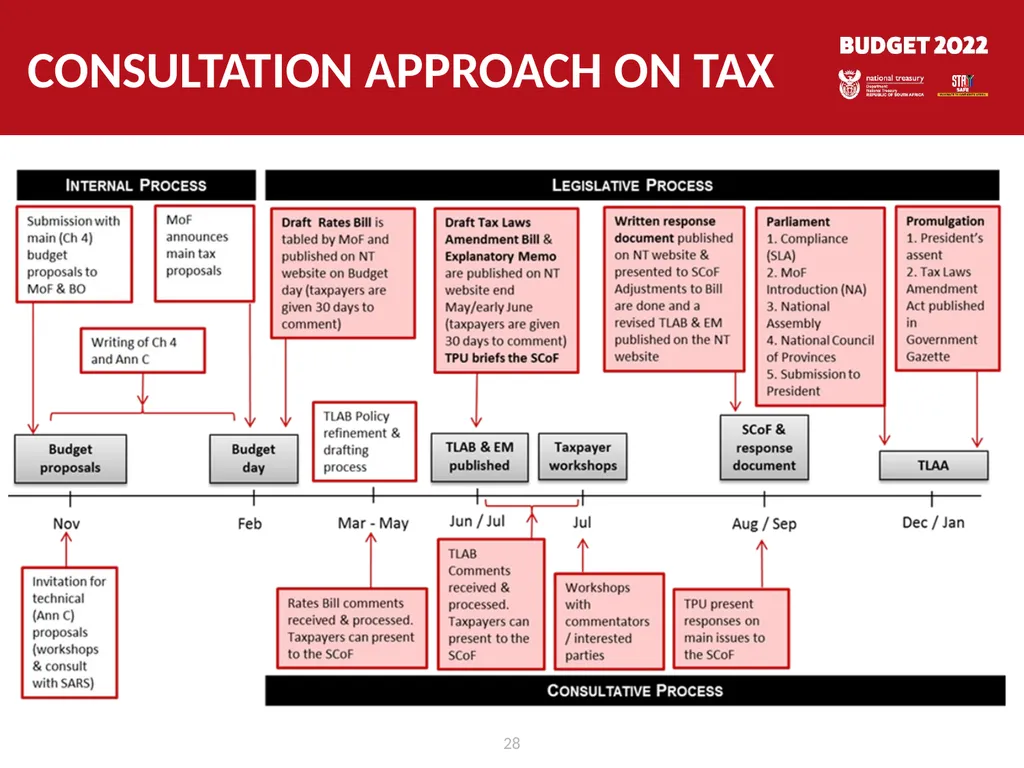
Rates and Monetary threshold announcements are finalised by Budget Day and hence publication of the draft Bill on Budget Day, and which SCOF can immediately have hearings on should it decide to do so (rather than wait till August as currently)
Consultations on non-rates issues (e.g. tax base) only begin post-Budget during March-June, followed by publication of TLAB and TALAB Bills in July
Taxpayers only learn the finer details on tax announcements in July from the two draft bills
In some instances, an extra round of consultation with some parts of TLAB around April/May 14<br>
slide15. Revenue estimates The 2022 Budget revenue estimates align with the baseline macroeconomic projections of the tax bases, and account for risks to revenue collections.
Estimates of medium-term nominal GDP growth are marginally higher than the 2021 MTBPS projections.
No additional revenue measures beyond those proposed in the 2022 Budget - tax policy focused on broadening the tax base, improving administration and lowering rather than raising tax rates to support the economic recovery, subject to major expenditure decisions.
Medium-term tax elasticity assumptions from the 2021 MTBPS are prudent and maintained for the 2022 Budget estimates.
Despite some reversal of commodity-driven revenues expected over the medium term, this is projected to add significant additional revenue over the next three years.
The rebuilding of SARS is evident in improved revenue collection and compliance trends. Additional revenues gains from SARS efficiency improvements represent an upside risk to the revenue estimates.<br>
slide16. Broad responses to tax policy approach Broad support for the policy outlook and policy proposals announced
Including inflationary adjustments for personal income taxes, no increase in the general fuel levy or RAF levy and the restructuring of corporate income tax,
Agreement that unexpected commodity revenue from 2021/22 cannot be viewed as permanent
FFC supportive of tax base broadening instead of tax rate increases
General suggestions from commentators
Some called for increases in taxes on the rich and a new net wealth tax, while others stated that the tax burden and tax rates are too high
Health promotion levy should be increased to 20 per cent and expanded, whilst some complain about any increase at all
Requestions for more consultation
Concerns about impacts of administrative practice can have on tax compliance and tax morale
Progress on Nugent recommendations – many implemented internally by SARS, also need to publish discussion document on external governance reforms<br>
slide17. Summary of responses to tax questions Tax-to-GDP: Minister of Finance has not mentioned a particular target or limit for the tax-to-GDP ratio, but this and previous budgets have highlighted research showing that tax increases are detrimental to growth, especially during economic downturns
Employment tax incentive: The ETI has been extensively reviewed, with some papers showing a small positive impact while others have shown no impact. The last review went through NEDLAC in 2018 and extended the incentive for 10 years to 2029
Tax rates on the rich and wealthy: Previous budgets have increased taxes - higher dividends taxes, capital gains taxes, estate duty and donations tax rates and a new top tax rate of 45 per cent. The 2022 Budget illustrated that the revenue from the higher rate appears to be lower than what was expected. The Budget also includes new asset declarations to provide a better picture of wealth holdings in South Africa.
Personal income tax adjustments: The adjustment for inflation means that the real personal income tax burden does not change from one year to the next. Not providing relief for inflation would draw low-income earners into the tax net when their income increases with inflation.
Adjustments for all monetary values: 2022 Budget announced that National Treasury will review the approach for adjustments to values to provide certainty.<br>
slide18. Summary of responses to tax questions Corporate income tax: This is not solely a reduction in the corporate income tax rate – it is a restructuring that should result in no revenue change for the fiscus. A broad base with a lower rate enhances efficiency and equity within the system.
Corporate income tax is the most distortionary of all taxes and the most harmful to growth. The incidence of CIT (who bears the burden) falls across consumers, workers and shareholders.
The intent of the corporate income tax package was largely welcomed. As pointed out by the FFC, effective tax rates (ETRs) are lower in some sectors. Given the finding that interest deductions and accelerated depreciation allowances are the leading factors for low ETRs, part of the aim of the package and upcoming work on depreciation allowances is to reduce the differences among businesses of different sizes and in different sectors.
Yes, some developing countries have similar headline rates, but many of them have incentives (including tax holidays, reduced rates and special allowances) that make their tax bases much smaller.
Corporate income tax impacts: The overall impact of the reform is not expected to reduce tax revenue. However, amongst sectors – the mining, retail and finance sectors are expected to have slightly higher tax liabilities in aggregate, while agriculture, manufacturing and transport should have lower tax liabilities in aggregate.
Corporate income tax effective date: Legislative response document stated that there could be a rationale for a delaying the package but that the effective date was up to the Minister of Finance. Given the stronger than expected recovery and the need to ensure policy continuity and certainty, effective date is next month.<br>
slide19. Impact of corporate income tax package per sector (based on micro data from sars)<br>
slide20. Business loan take up (loan guarantee scheme) To support the businesses during the pandemic, the government (and agencies) used two main tools:
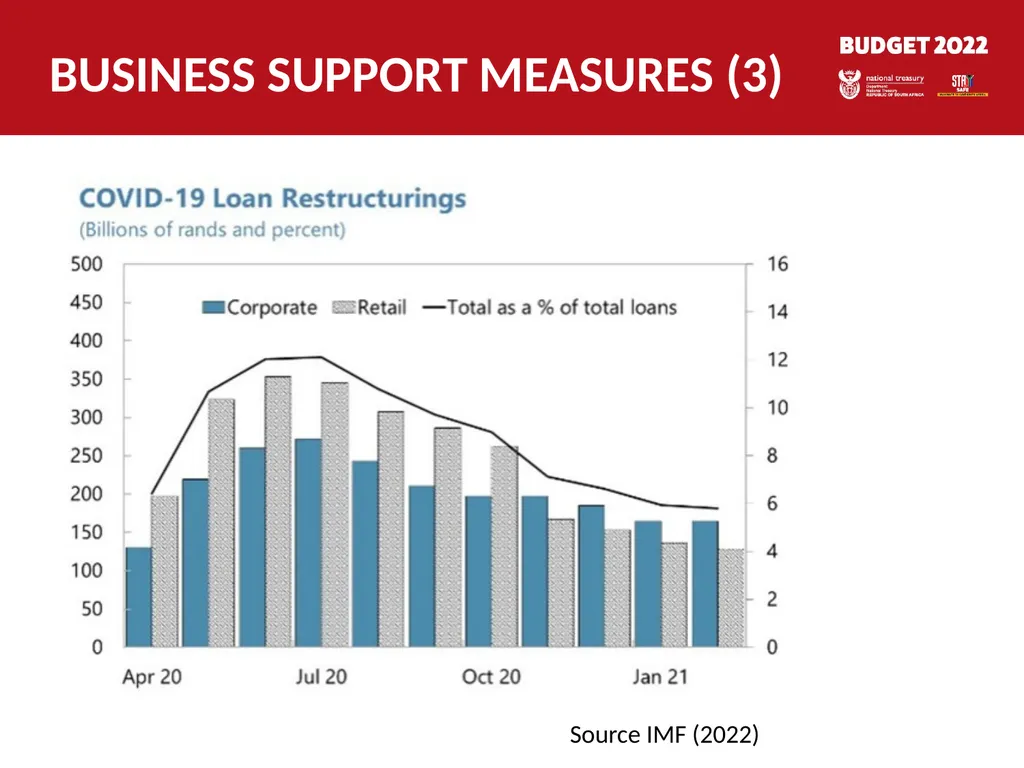
Regulatory measures: mainly restructuring of debt
Fiscal measures: the Loan Guarantee Scheme (LGS)
LGS wasn’t the preferred support mechanism, but it was very successful.
The number and value of loans provided to SME’s was significantly larger than any other permanent government loan guarantee mechanism like Khula.
Total relief to business was around R270 billion (restructuring and LGS). The LGS take-up:
The COVID 19 Loan Guarantee Scheme (LGS) came to an end on July 2021.
The total number of loans approved as at July 2021 (over the course of the availability period of the LGS) is 15 012
The total value of loans approved as at 17 July 2021 (over the course of the availability period of the LGS) is R18.4 billion
The average loan size is R 1.2 million
As the economy transitions to reopening, NT is introducing a new scheme to facilitate the bounce back i.e.” the bounce back loan guarantee scheme” (see Annex F of the 2022 Budget review)
This new support measure has two dimensions, starting with a loan guarantee scheme and then a smaller equity linked scheme.
The loan mechanism will support R15 billion worth of loans while the equity scheme will support R5 billion.
The aim to provide financing for firms affected by COVID-19 and the July 2021 social unrest.<br>
slide21. CONCLUSION Global uncertainties and an uneven domestic recovery will weigh on the economic outlook over the medium term. Inclusive growth, together with progress on structural reforms is required to create jobs and alleviate the social challenges in our country.
Government remains committed to stabilising the debt‐to‐GDP ratio by ensuring that spending is sustainable. This means reprioritising, reallocating and reviewing spending to meet policy priorities and improve efficiency.
The budget uses higher‐than‐anticipated revenue collection to alleviate short term spending pressures and reduce the deficit.
Risks remain, including the risk of higher‐than‐budgeted public‐service wages, demands for additional funding from financially distressed state‐owned companies, and calls for permanent increases in spending that exceed available resources.
Government is working on a sustainable long‐term approach to social protection, aligned to the broad development mandate and the need to ensure affordability.
Fighting corruption remains high on the agenda, through budget allocations and legislative reform. The Public Procurement Bill is scheduled for tabling in Parliament. 21<br>
slide22. Annexure<br>
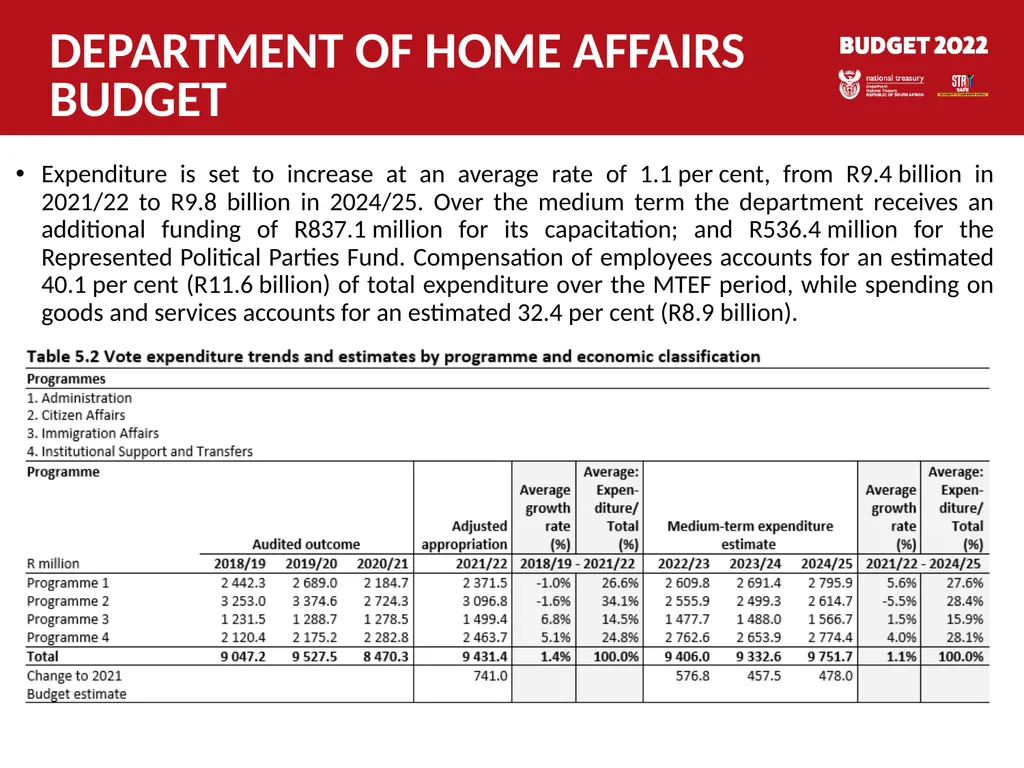
slide23. Department of home affairs budget Expenditure is set to increase at an average rate of 1.1 per cent, from R9.4 billion in 2021/22 to R9.8 billion in 2024/25. Over the medium term the department receives an additional funding of R837.1 million for its capacitation; and R536.4 million for the Represented Political Parties Fund. Compensation of employees accounts for an estimated 40.1 per cent (R11.6 billion) of total expenditure over the MTEF period, while spending on goods and services accounts for an estimated 32.4 per cent (R8.9 billion).<br>
slide24. Business support measures (1) Fiscal measures (LGS)
Later in the year (June) government also introduced the LGS. The scheme was complimentary to the principal tool (restructuring) of loans which at its high point amounted to R250 billion worth of loans. The restructuring of loans was strongly preferred because of the uncertainly of the path of the pandemic. However, NT also recognised the need to enable continued access to credit for businesses to be facilitates through the LGS. Given the uncertainly most businesses (especially small businesses didn’t want to take on additional debt).
The LGS take up:
The COVID 19 Loan Guarantee Scheme (LGS) came to an end on July 2021.
The total Number of Loans Approved as at July 2021 (over the course of the availability period of the LGS) is 15 012
The total Value of Loans approved as at 17 July 2021 (over the course of the availability period of the LGS) is R18.43 billion
The average loan size is R 1.23 million<br>
slide25. Business support measures (2) Regulatory measures
The Prudential Authority – which regulates banks and the broader financial sector – announced a temporary relaxation of regulations to support businesses and regulated financial institutions.
The measures broadly allowed for the rescheduling and restructuring of loans (liabilities) of businesses to allow them more space and time to repay as a result of lower (no) income during lockdowns.
These measures were introduced in May when there was significant uncertainly about the length and severity of the pandemic (and related lockdowns). Additionally, regulators also simultaneously introduced measures to ensure insurance companies were able to pay the business interruption insurance for policy holders.
This included:
Lowering the minimum capital and liquidity coverage ratio requirements for banks.
Reducing capital requirements for loans that banks restructured to assist their customers and guiding banks on the application of expected credit loss provisioning and accounting practices.
Advising banks to refrain from paying bonuses and dividends.
Monitoring banks’ operational risk and business continuity more closely to ensure the health and safety of staff and customers.
Extending financial and regulatory reporting timelines for financial institutions affected by strict lockdown restrictions.<br>
slide26. Business support measures (3) Source IMF (2022)<br>
slide27. Technical detail on the tax-to-gdp ratio Government balances difficult trade-offs when adjusting taxes.
The efficiency of tax policy changes in recent years has been a key focus given the low growth environment, and the potential contribution of the tax system.
While the tax-to-GDP ratio is an important consideration, government has not mentioned it as a target.
In the 2020 MTBPS, government noted that "The literature shows large negative multipliers from revenue increases, suggesting that South Africa’s growth slowdown over the past five years may be related to rising taxes."1
As such, to support economic recovery, the 2020 and 2021 Budgets did not propose to raise additional revenue from tax proposals, while the 2022 Budget provided tax relief.
The Budget Review presents the consolidated government account in a transparent format in line with the International Monetary Fund’s Government Finance Statistics Manual (2014)
Fiscal ratios reflecting revenue as a share of GDP are presented in key chapters:
Tax-to-GDP: showing the proportion of nationally-raised taxes relative to the economy (Chapter 4)
Main budget revenue to GDP: adjusting tax revenue for non-tax revenue and SACU payments (Chapter 3)
Consolidated budget revenue to GDP: revenue from provinces, public entities and social security funds (Chapter 3)
Differences in representation of these ratios across institutions may arise due to accounting for revenue items not defined as taxes, e.g. mineral royalties and departmental receipts (included in main budget revenue) and social security fund contributions and receipts from public entities (included in consolidated budget revenue) 27<br>
slide28. Consultation approach on tax 28<br>
slide29. Corporate income tax package For companies with years of assessment ending on or after 1 March 2023:
Headline rate reduced from 28% to 27%
Strengthening base protection measures to curb excessive interest deductions from eroding the tax base
Restricting the offset of assessed losses
Objective and underlying rationale:
This is not solely a reduction in the CIT rate – it is a restructuring in that, overall, the package should result in no revenue change for the fiscus
A broad base with a lower rate enhances efficiency and equity within the system
CIT is the most distortionary of all taxes and the most harmful to growth
Tax is one of the factors potential investors consider (whether new or expansion), and is relatively high in SA (and probably regarded to be more competitive at around 25%)
When combined with structural changes – can encourage investment
The bigger the difference between SA's rate and elsewhere, the larger the incentive to shift reported profits out of SA (reducing the tax base and CIT payments in SA)
The difference between SA's rate and our key trading and investment partners has been growing over time
Not all companies have global connections that provide opportunities to minimise their tax liability in SA – this also levels the playing field for purely domestic business 29<br>
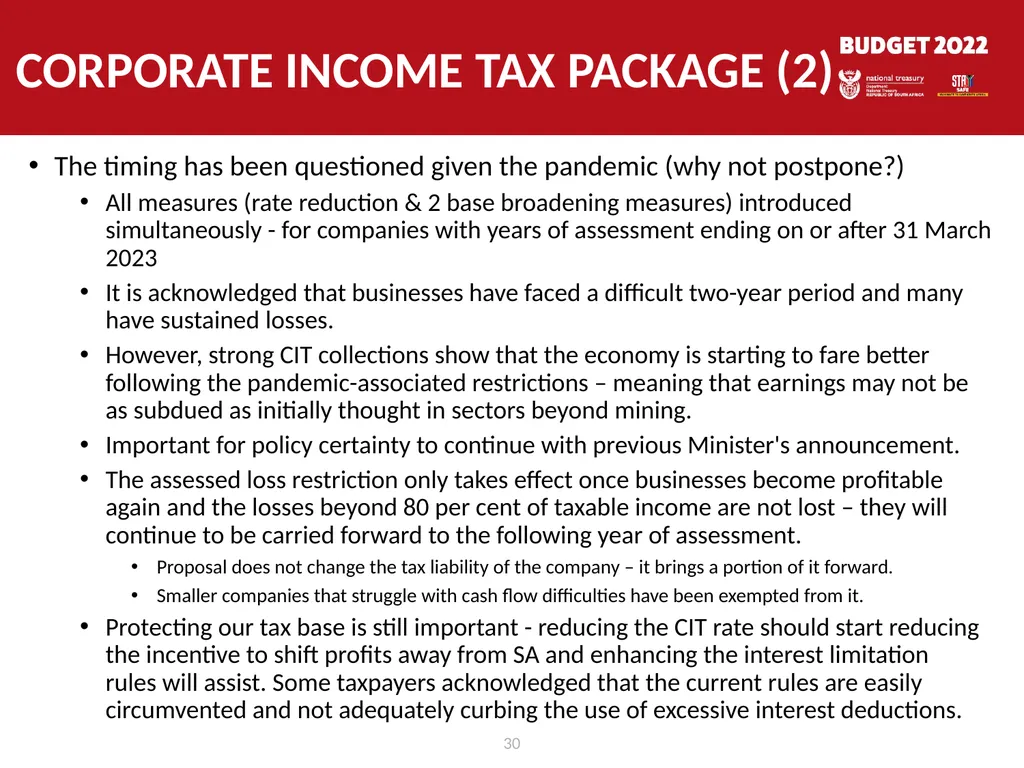
slide30. CORPORATE INCOME TAX PACKAGE (2) The timing has been questioned given the pandemic (why not postpone?)
All measures (rate reduction & 2 base broadening measures) introduced simultaneously - for companies with years of assessment ending on or after 31 March 2023
It is acknowledged that businesses have faced a difficult two-year period and many have sustained losses.
However, strong CIT collections show that the economy is starting to fare better following the pandemic-associated restrictions – meaning that earnings may not be as subdued as initially thought in sectors beyond mining.
Important for policy certainty to continue with previous Minister's announcement.
The assessed loss restriction only takes effect once businesses become profitable again and the losses beyond 80 per cent of taxable income are not lost – they will continue to be carried forward to the following year of assessment.
Proposal does not change the tax liability of the company – it brings a portion of it forward.
Smaller companies that struggle with cash flow difficulties have been exempted from it.
Protecting our tax base is still important - reducing the CIT rate should start reducing the incentive to shift profits away from SA and enhancing the interest limitation rules will assist. Some taxpayers acknowledged that the current rules are easily circumvented and not adequately curbing the use of excessive interest deductions. 30<br>
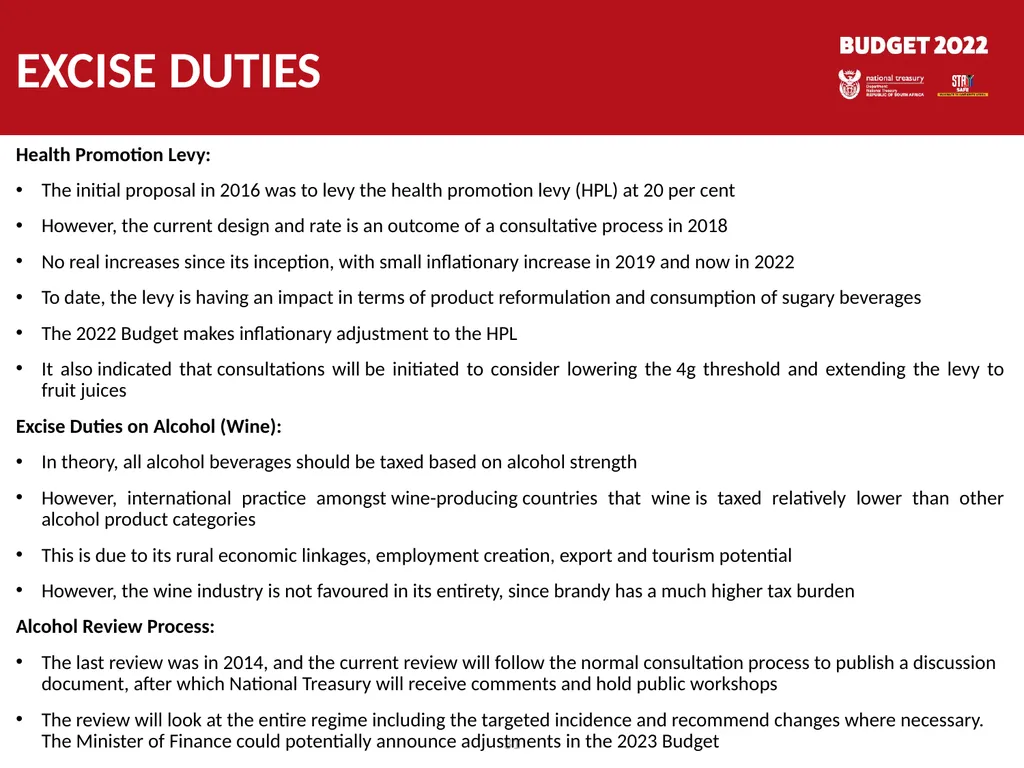
slide31. Excise duties Health Promotion Levy:
The initial proposal in 2016 was to levy the health promotion levy (HPL) at 20 per cent
However, the current design and rate is an outcome of a consultative process in 2018
No real increases since its inception, with small inflationary increase in 2019 and now in 2022
To date, the levy is having an impact in terms of product reformulation and consumption of sugary beverages
The 2022 Budget makes inflationary adjustment to the HPL
It also indicated that consultations will be initiated to consider lowering the 4g threshold and extending the levy to fruit juices
Excise Duties on Alcohol (Wine):
In theory, all alcohol beverages should be taxed based on alcohol strength
However, international practice amongst wine-producing countries that wine is taxed relatively lower than other alcohol product categories
This is due to its rural economic linkages, employment creation, export and tourism potential
However, the wine industry is not favoured in its entirety, since brandy has a much higher tax burden
Alcohol Review Process:
The last review was in 2014, and the current review will follow the normal consultation process to publish a discussion document, after which National Treasury will receive comments and hold public workshops
The review will look at the entire regime including the targeted incidence and recommend changes where necessary. The Minister of Finance could potentially announce adjustments in the 2023 Budget 31<br>
slide32. Employment tax incentive The PBO called for the Employment Tax Incentive (ETI) to be reviewed to determine its ability to partially reduce unemployment. Feedback is also required as to the effectiveness of the incentive. The IEJ called for the incentive to be scrapped.
Two reviews through NEDLAC (2016 and 2018) and independent research found that
Youth employment is significantly higher in firms that claim the ETI as opposed to those that do not.
The estimated number of jobs created in 2015 tax years is 81 646. This equates to a cost per new job of R11 704.
Overall, the ETI treatment effect is positive and significant for low wage youth employment growth rates.
Particularly effective tool to RETAIN employment. The ETI was introduced in 2014 – since then the baseline for employment has been shrinking. Therefore many of the positive impacts indicate that firms that claim ETI loose less jobs than other (informed emergency measures)
Greatest employment effects in smaller firms.
No evidence of displacement for low wage workers (30 - 35 year olds).
Qualitative: Youth beneficiaries highlighted the value of workplace-based learning and the acquisition of new skills.
Qualitative: The ETI as part of a range of factors has contributed to the employment of youth that would otherwise not have been employed.
The dominant view amongst the firms is that ETI jobs are not filled just for the two-year period.
Ongoing independent research, using tax administrative data
Findings of previous review in 2018 was shared with committees, who agreed with Nedlac partners that the incentive be extended from 2019 to 2029 32<br>
slide33. Employment tax incentive - bibliography National Treasury publishes monthly reporting on the revenue foregone - far in excess of the reporting requirement per the ETI Act of twice a year, in addition to regular feedback in budget review documents.
National Treasury published a Descriptive report of claims in 2016, in part to inform the review as data became available slowly
The reviews in 2016 and 2018 was convened by Nedlac, with an open invitation for evidence.
Both reviews were informed by all available research: independent academic studies, commissioned research and surveys of claimants. Where final, published papers were available, we referred to them – but work-in-progress was also considered, as there a very long lags in data availability. Both reviews included critiques, arguments for and arguments against each potential finding. This included the following research papers (along with unpublished inputs from constituencies):
https://ideas.repec.org/a/bla/sajeco/v84y2016i2p199-216.html
Becoming Youthful? An Evaluation of the South African Employment Tax Incentive (ETI) (unu.edu)
UNU-WIDER : Working Paper : The effects of the Employment Tax Incentive on South African mployment and ebrahim_a28067.pdf (iza.org)
The Employment Tax Incentive Scheme in South Africa: An Impact Assessment (africaportal.org)
Deliberations in Nedlac resulted in unanimous recommendations for extensions of the programme in 2016 and 2018. In the latter case, NT initially proposed a 5 year extension, while social partners recommended a 10 year extension (also indicated in the Framework agreement of the Presidential Jobs Summit in 2018), in order to give certainty and to encourage building systems to ease compliance burdens. In both cases, the reports from Nedlac were not only shared with SCOF, but were required before the committee assented to the draft.
Research findings since the review
UNU-WIDER : Working Paper : Can a wage subsidy system help reduce 50 per cent youth unemployment?
UNU-WIDER : Working Paper : Estimating employment responses to South Africa’s Employment Tax Incentive(sound caution about the methodology for future impact assessments) 33<br>
slide34. Implementing nugent recommendations Delay in announcement due to need for a comprehensive response by Government on Zondo Commission
Need to align both Zondo and Nugent Commission proposals
Still hope to table a draft bill on SARS governance and management reforms in July with TLAB and TALAB Bills 34<br>
slide35. Climate change response and carbon tax price path To meet SA’s climate commitments, the country’s greenhouse gas emissions must peak by 2025 and then quickly decline to between 350 million and 420 million tonnes by 2030, and approach net‐zero emissions by 2050.
The carbon tax is integral to lowering emissions.
To prepare South Africa for the structural transition to a climate‐resilient economy, government proposes to progressively increase the carbon price every year by at least US$1 to reach US$20 per tonne of carbon dioxide equivalent by 2026.
For the second phase, government intends to increase the carbon price more rapidly every year, to at least US$30 by 2030, accelerating to higher levels by 2035, 2040 and up to US$120 beyond 2050.
The basic tax‐free allowances will also be gradually reduced to strengthen the price signals under the carbon tax from 1 January 2026 to 31 December 2030.
To encourage investments in carbon offset projects, government intends to increase the carbon offset allowance by 5 per cent from 1 January 2026.
This approach aligns with global institutions. The World Bank’s High‐Level Commission on Carbon Prices recommends carbon prices of US$40 to US$80 per tonne by 2025 and US$50 to US$100 by 2030. The International Monetary Fund recommends lower minimum carbon prices for developing countries of US$25 to US$50 by 2030 to achieve the Paris climate goals. 35<br>
slide2. List of organisations that made submissions Parliament Budget Office (PBO)
Financial and Fiscal Commission (FFC)
Fiscal Cliff Study Group
South African Institute of Chartered Accountants (SAICA)
PWC
South African Institute of Taxation (SAIT)
Amandla.Mobi
Congress of South African Trade Unions (COSATU)
Financial and Fiscal Commission (FFC)
Healthy Living Alliance (HEALA)
1 Road consulting
South African Breweries (SAB)
Women on Farms Project
Institute for Economic Justice (IEJ)<br>
slide3. Main responses Economic growth and reforms: Fiscal policy alone cannot solve the problems of inequality, poverty and unemployment. Inclusive growth and economic reforms are essential.
Revenue and tax proposals: Several responses are noted.
Expenditure: No further budget reductions were announced in the 2022 Budget. The 2020 Budget allows increases in critical spending areas using a portion of revenue improvements.
Fiscal resilience and debt sustainability: Ever increasing debt and debt service cost crowds out the space to spend on critical priority areas.
Other matters raised:
SOCs: Significant reforms are necessary to improve efficiency of SOCs so that they are not a fiscal burden to the country and serve the people of South Africa in an effective way.
Corruption: NT has implemented several new measures to support the fight against corruption in government.
Public participation platforms: NT is continuously looking into new ways to make the budget more consultative, transparent and accessible.
Business support measures: More regulatory measures (than loan guarantee measures) were taken-up for the loan guarantee scheme which ended in July 2021. An additional loan guarantee scheme is initiated in the new year.<br>
slide4. Inclusive growth and structural reforms are critical Structural constraints have reduced potential growth for the past decade and remain an impediment to the recovery. The economic effects of the pandemic (lost jobs and delayed investments) were exacerbated by inadequate electricity supply, with the highest levels of load-shedding to date.
Reducing regulatory constraints, providing effective services, and coordinating and sequencing economic interventions will bolster public and private investment, which will, in turn, increase resilience and support economic transformation.
Reforms are needed to promote growth and employment. These reforms include:
Stimulate demand through investment in infrastructure, complemented by employment programmes and social transfers that will boost household consumption.
Modernising network industries will support an increase in the economy’s productive capacity
Boost electricity production
Reduce the cost of doing business.
The 2021 MTBPS detailed notable progress on structural reforms through Operation Vulindlela. Work is underway to expedite the approvals required to register embedded electricity generation plants, complete the analogue to digital migration and auction spectrum, and clear the backlog of water-use licences.
Post-COVID-19 recovery strategies include stimulating the economy through public employment programmes and tax incentives, while implementing reforms to ease the skill constraints and make it easier to do business. Labour-intensive, export-orientated sectors are receiving additional support.
Fiscal policy may only affect economic growth to a certain extent. Structural reforms are imperative to accelerate economic growth needed to reduce poverty and unemployment while also increasing investment.<br>
slide5. Main fiscal policy issues Over the past few years there has been a disconnect between government spending and economic growth. Higher spending should be accompanied by inclusive economic growth.
Despite measures aimed at controlling expenditure growth, the funding for the social wage has been protected to ensure that necessary goods and services are provided to those who are in need.
The decision not to implement the final leg of the 2018 wage agreement, together with other measures to reduce average wage costs have improved the wage trajectory. Government is firmly committed to the compensation ceiling as announced in the budget.
No further budget reductions were announced in the 2022 Budget. Instead, additional spending in critical spending areas were made using a portion of revenue improvements.
Despite projections to reach a primary surplus by 2023/24, debt is high. Each year, a budget deficit adds to debt, increasing debt-service cost, limiting our capacity to spend more – this cannot continue indefinitely. 5<br>
slide6. BREAKDOWN IN THE Relationship between spending and economic growth The projected revenue overcollection allows for the responds to immediate spending pressures. The windfall in 2021/22 will be used to finance the special COVID-19 social relief of distress grant until the end of March 2023. Significant portions are also allocated to Education and Health, as well as for Infrastructure investment and public employment.
Higher spending on the social wage should be accompanied by inclusive economic growth. 6 Spending growth and economic growth Between 2010/11 and 2019/20, non-interest consolidated expenditure has grown at an average annual increase of 7.8 per cent, while nominal GDP grew at 7.2 per cent.
In the 2013 Budget, government initiated a process to slow expenditure growth by reducing baseline budgets and setting ceilings on compensation spending. However, unfunded policy decisions contributed to a persistently large budget deficit, increasing pressure on basic service delivery.
The composition of public spending has also deteriorated, the proportion that supports long-term growth is smaller, while debt-service costs consume an increasing share of GDP and revenue.<br>
slide7. The redistributing effect of the budget 7 The consolidated budget has grown from R712.8 billion in 2008/09 to R2.08 trillion in 2021/22 – an average annual increase of 8.6 per cent.
Over the MTEF, an allocation of R3.33 trillion, or 59.4 per cent of total non‐interest spending is dedicated to the social wage. This aims to alleviate poverty, reduce unemployment and accelerate growth. This includes the 12-month extension of the SRD grant, additional funding for health, education and the presidential employment initiative. Consolidated government expenditure Despite measures aimed at controlling expenditure growth, the funding for the social wage has been protected to ensure that necessary goods and services are provided to those who are in need.
A key weakness in recent economic performance has been persistently high joblessness, which lies at the root of weak economic development outcomes.
Government and stakeholders are working on a sustainable long‐term approach to social protection consistent with government’s broad development mandate and the need to ensure affordability.<br>
slide8. Managing the public‐service wage bill Compensation spending for national and provincial government grew by 7.3 per cent on average for the period 2014/15 to 2019/20, compared with 6.8 per cent average growth in non-interest expenditure.
The decision not to implement the final leg of the 2018 wage agreement and other measures to reduce average wage costs have improved the wage trajectory.
A new round of collective bargaining will begin in March 2022. The National Treasury is working with the Department of Public Service and Administration to keep the compensation baseline within affordable limits. 8 Over the MTEF, consolidated government wage bill increases by an annual average growth of 1.8 per cent, which is 0.8 percentage points higher than pencilled in the 2021 MTBPS. The higher growth reflects an exception made for additional funding to frontline services such as health, education and police.
Government is firmly committed to the compensation ceiling as announced in the budget, and has tasked the National Treasury and all departments to align to the budget. Consolidated budget compensation of employees* *Excludes public entities<br>
slide9. Our current fiscal challenges Government expects to realise a primary surplus (revenue exceeds non-interest expenditure) by 2023/24, ending fiscal consolidation.
No further budget reductions were announced in the 2022 Budget. Increases in critical spending areas were made by using a portion of revenue improvements.
Government debt high and projected to rise to R4.35 trillion in 2021/22 despite some revenue improvements enabling deficit reduction over the MTEF. Gross loan debt is projected to stabilise at 75.1 per cent of GDP in 2024/25, given that revenue projections over the MTEF realises.
As a result, approximately 20 cents of every rand collected in revenue every year will be used to pay debt-service costs. 9 Consolidated fiscal framework Debt as percentage of GDP<br>
slide10. Why Fiscal resilience and debt sustainability is under threat 10 Consolidated government expenditure by function The only way to manage this is through (also noted by the FFC):
Increases in tax or
Decreases in non-interest expenditure or
A combination of the above
Debt management also plays an important role Debt-service cost increased, both in proportion and size of expenditure, to be the 3rd largest expenditure item (according to the functional classification of expenditure).
Each year, a budget deficit adds to debt, increasing the debt-service cost – this cannot continue indefinitely. Fiscal anchors/rules can guide
NT is working on
strengthening the anchors<br>
slide11. state-owned companies The operational and financial health of many state-owned companies continues to decline. Over the past 12 months, several have missed their capital investments and loan disbursements targets.
Investors have increasingly expressed an unwillingness to extend capital to such entities without government guarantees, leaving many state-owned companies at risk of defaulting on their debts.
To reduce their demands on limited public resources, state-owned companies need to develop and implement sustainable turnaround plans that align with their mandates, incorporate long-term structural considerations in their sectors and identify appropriate funding models.
During 2022/23, the National Treasury will publish a framework outlining the criteria for government funding of state-owned companies. Government will guide and support credible restructuring plans. Guaranteed debt continues to have full backing of government.
The total amount of approved guarantees to state-owned companies is expected to reach R560.1 billion by the end of 2021/22, which is R21.5 billion lower than in 2020/21. The associated exposure is estimated to increase by R32.1 billion to R416.8 billion by March 2022. Eskom accounts for 78.7 per cent of these guarantees.
Excluding Eskom, total debt maturing over the next three years is expected to amount to R67.4 billion, of which 22 per cent or R14.9 billion is guaranteed by government.
List of public entities can be found on the National Treasury Website (PFMA Schedules).<br>
slide12. PUBLIC PARTICIPATIONS platforms 12 South Africa ranked first, among 117 countries, in the 2017 and 2019 Open Budget Index. The index measures the quality of budget transparency, public participation in the budget processes and institutional oversight.
Pre-budget public participation : Budget tips (over 300 Budget tips received for 2022 Budget)
Post-budget public participation:
People’s Guide to the Budget – presented in 7 languages and circulated in communities
Community radio stations engagements – about 21 radio stations across different provinces
Budget Outreach Programme
Other public participation
National Treasury Website – All budget information including data sets (eg. new budget dashboard)
Vulekamali - an easily accessible online budget data portal
Fiscal Openness Accelerator - to support innovation to deepen participation by members of the public in fiscal policy. The initiative aims to improve public participation in the budget process.
NT is continuously looking at more inclusive public participation mechanisms<br>
slide13. What is NT doing to fight Corruption 13 The 2022 Budget Review states that funds are being reprioritised in the peace and security function to enhance capacity in institutions combatting crime and corruption.
The Investigating Directorate in the National Prosecuting Authority and the Financial Intelligence Centre are together allocated R426 million over the MTEF period.
This allocation will enable the permanent appointment of 68 personnel in the Financial Intelligence Centre and an estimated 90 personnel in the Investigating Directorate to provide specialised services.
Legal Aid South Africa is also allocated R34.3 million over the medium term to provide capacity at newly established Specialised Commercial Crime Courts in the provinces of Limpopo, Mpumalanga, North West, and Northern Cape.
The Public Procurement Bill will be tabled before Parliament in 2022/23.
The bill will be revisited to take into account the recent Constitutional Court judgement on the preferential procurement regulations and the Zondo Commission report.<br>
slide14. Taxation and revenue policy Treasury notes, and welcomes, the number of questions on tax policy and on revenue projections
In past years, we have requested that SCOF have a special session on tax policy and financial sector announcements soon after the Budget, either as part of the post-Budget hearings, or soon after this process
Tax announcements are market-sensitive, and no prior consultations take place before Budget Day announcements
Rates and Monetary threshold announcements are finalised by Budget Day and hence publication of the draft Bill on Budget Day, and which SCOF can immediately have hearings on should it decide to do so (rather than wait till August as currently)
Consultations on non-rates issues (e.g. tax base) only begin post-Budget during March-June, followed by publication of TLAB and TALAB Bills in July
Taxpayers only learn the finer details on tax announcements in July from the two draft bills
In some instances, an extra round of consultation with some parts of TLAB around April/May 14<br>
slide15. Revenue estimates The 2022 Budget revenue estimates align with the baseline macroeconomic projections of the tax bases, and account for risks to revenue collections.
Estimates of medium-term nominal GDP growth are marginally higher than the 2021 MTBPS projections.
No additional revenue measures beyond those proposed in the 2022 Budget - tax policy focused on broadening the tax base, improving administration and lowering rather than raising tax rates to support the economic recovery, subject to major expenditure decisions.
Medium-term tax elasticity assumptions from the 2021 MTBPS are prudent and maintained for the 2022 Budget estimates.
Despite some reversal of commodity-driven revenues expected over the medium term, this is projected to add significant additional revenue over the next three years.
The rebuilding of SARS is evident in improved revenue collection and compliance trends. Additional revenues gains from SARS efficiency improvements represent an upside risk to the revenue estimates.<br>
slide16. Broad responses to tax policy approach Broad support for the policy outlook and policy proposals announced
Including inflationary adjustments for personal income taxes, no increase in the general fuel levy or RAF levy and the restructuring of corporate income tax,
Agreement that unexpected commodity revenue from 2021/22 cannot be viewed as permanent
FFC supportive of tax base broadening instead of tax rate increases
General suggestions from commentators
Some called for increases in taxes on the rich and a new net wealth tax, while others stated that the tax burden and tax rates are too high
Health promotion levy should be increased to 20 per cent and expanded, whilst some complain about any increase at all
Requestions for more consultation
Concerns about impacts of administrative practice can have on tax compliance and tax morale
Progress on Nugent recommendations – many implemented internally by SARS, also need to publish discussion document on external governance reforms<br>
slide17. Summary of responses to tax questions Tax-to-GDP: Minister of Finance has not mentioned a particular target or limit for the tax-to-GDP ratio, but this and previous budgets have highlighted research showing that tax increases are detrimental to growth, especially during economic downturns
Employment tax incentive: The ETI has been extensively reviewed, with some papers showing a small positive impact while others have shown no impact. The last review went through NEDLAC in 2018 and extended the incentive for 10 years to 2029
Tax rates on the rich and wealthy: Previous budgets have increased taxes - higher dividends taxes, capital gains taxes, estate duty and donations tax rates and a new top tax rate of 45 per cent. The 2022 Budget illustrated that the revenue from the higher rate appears to be lower than what was expected. The Budget also includes new asset declarations to provide a better picture of wealth holdings in South Africa.
Personal income tax adjustments: The adjustment for inflation means that the real personal income tax burden does not change from one year to the next. Not providing relief for inflation would draw low-income earners into the tax net when their income increases with inflation.
Adjustments for all monetary values: 2022 Budget announced that National Treasury will review the approach for adjustments to values to provide certainty.<br>
slide18. Summary of responses to tax questions Corporate income tax: This is not solely a reduction in the corporate income tax rate – it is a restructuring that should result in no revenue change for the fiscus. A broad base with a lower rate enhances efficiency and equity within the system.
Corporate income tax is the most distortionary of all taxes and the most harmful to growth. The incidence of CIT (who bears the burden) falls across consumers, workers and shareholders.
The intent of the corporate income tax package was largely welcomed. As pointed out by the FFC, effective tax rates (ETRs) are lower in some sectors. Given the finding that interest deductions and accelerated depreciation allowances are the leading factors for low ETRs, part of the aim of the package and upcoming work on depreciation allowances is to reduce the differences among businesses of different sizes and in different sectors.
Yes, some developing countries have similar headline rates, but many of them have incentives (including tax holidays, reduced rates and special allowances) that make their tax bases much smaller.
Corporate income tax impacts: The overall impact of the reform is not expected to reduce tax revenue. However, amongst sectors – the mining, retail and finance sectors are expected to have slightly higher tax liabilities in aggregate, while agriculture, manufacturing and transport should have lower tax liabilities in aggregate.
Corporate income tax effective date: Legislative response document stated that there could be a rationale for a delaying the package but that the effective date was up to the Minister of Finance. Given the stronger than expected recovery and the need to ensure policy continuity and certainty, effective date is next month.<br>
slide19. Impact of corporate income tax package per sector (based on micro data from sars)<br>
slide20. Business loan take up (loan guarantee scheme) To support the businesses during the pandemic, the government (and agencies) used two main tools:
Regulatory measures: mainly restructuring of debt
Fiscal measures: the Loan Guarantee Scheme (LGS)
LGS wasn’t the preferred support mechanism, but it was very successful.
The number and value of loans provided to SME’s was significantly larger than any other permanent government loan guarantee mechanism like Khula.
Total relief to business was around R270 billion (restructuring and LGS). The LGS take-up:
The COVID 19 Loan Guarantee Scheme (LGS) came to an end on July 2021.
The total number of loans approved as at July 2021 (over the course of the availability period of the LGS) is 15 012
The total value of loans approved as at 17 July 2021 (over the course of the availability period of the LGS) is R18.4 billion
The average loan size is R 1.2 million
As the economy transitions to reopening, NT is introducing a new scheme to facilitate the bounce back i.e.” the bounce back loan guarantee scheme” (see Annex F of the 2022 Budget review)
This new support measure has two dimensions, starting with a loan guarantee scheme and then a smaller equity linked scheme.
The loan mechanism will support R15 billion worth of loans while the equity scheme will support R5 billion.
The aim to provide financing for firms affected by COVID-19 and the July 2021 social unrest.<br>
slide21. CONCLUSION Global uncertainties and an uneven domestic recovery will weigh on the economic outlook over the medium term. Inclusive growth, together with progress on structural reforms is required to create jobs and alleviate the social challenges in our country.
Government remains committed to stabilising the debt‐to‐GDP ratio by ensuring that spending is sustainable. This means reprioritising, reallocating and reviewing spending to meet policy priorities and improve efficiency.
The budget uses higher‐than‐anticipated revenue collection to alleviate short term spending pressures and reduce the deficit.
Risks remain, including the risk of higher‐than‐budgeted public‐service wages, demands for additional funding from financially distressed state‐owned companies, and calls for permanent increases in spending that exceed available resources.
Government is working on a sustainable long‐term approach to social protection, aligned to the broad development mandate and the need to ensure affordability.
Fighting corruption remains high on the agenda, through budget allocations and legislative reform. The Public Procurement Bill is scheduled for tabling in Parliament. 21<br>
slide22. Annexure<br>
slide23. Department of home affairs budget Expenditure is set to increase at an average rate of 1.1 per cent, from R9.4 billion in 2021/22 to R9.8 billion in 2024/25. Over the medium term the department receives an additional funding of R837.1 million for its capacitation; and R536.4 million for the Represented Political Parties Fund. Compensation of employees accounts for an estimated 40.1 per cent (R11.6 billion) of total expenditure over the MTEF period, while spending on goods and services accounts for an estimated 32.4 per cent (R8.9 billion).<br>
slide24. Business support measures (1) Fiscal measures (LGS)
Later in the year (June) government also introduced the LGS. The scheme was complimentary to the principal tool (restructuring) of loans which at its high point amounted to R250 billion worth of loans. The restructuring of loans was strongly preferred because of the uncertainly of the path of the pandemic. However, NT also recognised the need to enable continued access to credit for businesses to be facilitates through the LGS. Given the uncertainly most businesses (especially small businesses didn’t want to take on additional debt).
The LGS take up:
The COVID 19 Loan Guarantee Scheme (LGS) came to an end on July 2021.
The total Number of Loans Approved as at July 2021 (over the course of the availability period of the LGS) is 15 012
The total Value of Loans approved as at 17 July 2021 (over the course of the availability period of the LGS) is R18.43 billion
The average loan size is R 1.23 million<br>
slide25. Business support measures (2) Regulatory measures
The Prudential Authority – which regulates banks and the broader financial sector – announced a temporary relaxation of regulations to support businesses and regulated financial institutions.
The measures broadly allowed for the rescheduling and restructuring of loans (liabilities) of businesses to allow them more space and time to repay as a result of lower (no) income during lockdowns.
These measures were introduced in May when there was significant uncertainly about the length and severity of the pandemic (and related lockdowns). Additionally, regulators also simultaneously introduced measures to ensure insurance companies were able to pay the business interruption insurance for policy holders.
This included:
Lowering the minimum capital and liquidity coverage ratio requirements for banks.
Reducing capital requirements for loans that banks restructured to assist their customers and guiding banks on the application of expected credit loss provisioning and accounting practices.
Advising banks to refrain from paying bonuses and dividends.
Monitoring banks’ operational risk and business continuity more closely to ensure the health and safety of staff and customers.
Extending financial and regulatory reporting timelines for financial institutions affected by strict lockdown restrictions.<br>
slide26. Business support measures (3) Source IMF (2022)<br>
slide27. Technical detail on the tax-to-gdp ratio Government balances difficult trade-offs when adjusting taxes.
The efficiency of tax policy changes in recent years has been a key focus given the low growth environment, and the potential contribution of the tax system.
While the tax-to-GDP ratio is an important consideration, government has not mentioned it as a target.
In the 2020 MTBPS, government noted that "The literature shows large negative multipliers from revenue increases, suggesting that South Africa’s growth slowdown over the past five years may be related to rising taxes."1
As such, to support economic recovery, the 2020 and 2021 Budgets did not propose to raise additional revenue from tax proposals, while the 2022 Budget provided tax relief.
The Budget Review presents the consolidated government account in a transparent format in line with the International Monetary Fund’s Government Finance Statistics Manual (2014)
Fiscal ratios reflecting revenue as a share of GDP are presented in key chapters:
Tax-to-GDP: showing the proportion of nationally-raised taxes relative to the economy (Chapter 4)
Main budget revenue to GDP: adjusting tax revenue for non-tax revenue and SACU payments (Chapter 3)
Consolidated budget revenue to GDP: revenue from provinces, public entities and social security funds (Chapter 3)
Differences in representation of these ratios across institutions may arise due to accounting for revenue items not defined as taxes, e.g. mineral royalties and departmental receipts (included in main budget revenue) and social security fund contributions and receipts from public entities (included in consolidated budget revenue) 27<br>
slide28. Consultation approach on tax 28<br>
slide29. Corporate income tax package For companies with years of assessment ending on or after 1 March 2023:
Headline rate reduced from 28% to 27%
Strengthening base protection measures to curb excessive interest deductions from eroding the tax base
Restricting the offset of assessed losses
Objective and underlying rationale:
This is not solely a reduction in the CIT rate – it is a restructuring in that, overall, the package should result in no revenue change for the fiscus
A broad base with a lower rate enhances efficiency and equity within the system
CIT is the most distortionary of all taxes and the most harmful to growth
Tax is one of the factors potential investors consider (whether new or expansion), and is relatively high in SA (and probably regarded to be more competitive at around 25%)
When combined with structural changes – can encourage investment
The bigger the difference between SA's rate and elsewhere, the larger the incentive to shift reported profits out of SA (reducing the tax base and CIT payments in SA)
The difference between SA's rate and our key trading and investment partners has been growing over time
Not all companies have global connections that provide opportunities to minimise their tax liability in SA – this also levels the playing field for purely domestic business 29<br>
slide30. CORPORATE INCOME TAX PACKAGE (2) The timing has been questioned given the pandemic (why not postpone?)
All measures (rate reduction & 2 base broadening measures) introduced simultaneously - for companies with years of assessment ending on or after 31 March 2023
It is acknowledged that businesses have faced a difficult two-year period and many have sustained losses.
However, strong CIT collections show that the economy is starting to fare better following the pandemic-associated restrictions – meaning that earnings may not be as subdued as initially thought in sectors beyond mining.
Important for policy certainty to continue with previous Minister's announcement.
The assessed loss restriction only takes effect once businesses become profitable again and the losses beyond 80 per cent of taxable income are not lost – they will continue to be carried forward to the following year of assessment.
Proposal does not change the tax liability of the company – it brings a portion of it forward.
Smaller companies that struggle with cash flow difficulties have been exempted from it.
Protecting our tax base is still important - reducing the CIT rate should start reducing the incentive to shift profits away from SA and enhancing the interest limitation rules will assist. Some taxpayers acknowledged that the current rules are easily circumvented and not adequately curbing the use of excessive interest deductions. 30<br>
slide31. Excise duties Health Promotion Levy:
The initial proposal in 2016 was to levy the health promotion levy (HPL) at 20 per cent
However, the current design and rate is an outcome of a consultative process in 2018
No real increases since its inception, with small inflationary increase in 2019 and now in 2022
To date, the levy is having an impact in terms of product reformulation and consumption of sugary beverages
The 2022 Budget makes inflationary adjustment to the HPL
It also indicated that consultations will be initiated to consider lowering the 4g threshold and extending the levy to fruit juices
Excise Duties on Alcohol (Wine):
In theory, all alcohol beverages should be taxed based on alcohol strength
However, international practice amongst wine-producing countries that wine is taxed relatively lower than other alcohol product categories
This is due to its rural economic linkages, employment creation, export and tourism potential
However, the wine industry is not favoured in its entirety, since brandy has a much higher tax burden
Alcohol Review Process:
The last review was in 2014, and the current review will follow the normal consultation process to publish a discussion document, after which National Treasury will receive comments and hold public workshops
The review will look at the entire regime including the targeted incidence and recommend changes where necessary. The Minister of Finance could potentially announce adjustments in the 2023 Budget 31<br>
slide32. Employment tax incentive The PBO called for the Employment Tax Incentive (ETI) to be reviewed to determine its ability to partially reduce unemployment. Feedback is also required as to the effectiveness of the incentive. The IEJ called for the incentive to be scrapped.
Two reviews through NEDLAC (2016 and 2018) and independent research found that
Youth employment is significantly higher in firms that claim the ETI as opposed to those that do not.
The estimated number of jobs created in 2015 tax years is 81 646. This equates to a cost per new job of R11 704.
Overall, the ETI treatment effect is positive and significant for low wage youth employment growth rates.
Particularly effective tool to RETAIN employment. The ETI was introduced in 2014 – since then the baseline for employment has been shrinking. Therefore many of the positive impacts indicate that firms that claim ETI loose less jobs than other (informed emergency measures)
Greatest employment effects in smaller firms.
No evidence of displacement for low wage workers (30 - 35 year olds).
Qualitative: Youth beneficiaries highlighted the value of workplace-based learning and the acquisition of new skills.
Qualitative: The ETI as part of a range of factors has contributed to the employment of youth that would otherwise not have been employed.
The dominant view amongst the firms is that ETI jobs are not filled just for the two-year period.
Ongoing independent research, using tax administrative data
Findings of previous review in 2018 was shared with committees, who agreed with Nedlac partners that the incentive be extended from 2019 to 2029 32<br>
slide33. Employment tax incentive - bibliography National Treasury publishes monthly reporting on the revenue foregone - far in excess of the reporting requirement per the ETI Act of twice a year, in addition to regular feedback in budget review documents.
National Treasury published a Descriptive report of claims in 2016, in part to inform the review as data became available slowly
The reviews in 2016 and 2018 was convened by Nedlac, with an open invitation for evidence.
Both reviews were informed by all available research: independent academic studies, commissioned research and surveys of claimants. Where final, published papers were available, we referred to them – but work-in-progress was also considered, as there a very long lags in data availability. Both reviews included critiques, arguments for and arguments against each potential finding. This included the following research papers (along with unpublished inputs from constituencies):
https://ideas.repec.org/a/bla/sajeco/v84y2016i2p199-216.html
Becoming Youthful? An Evaluation of the South African Employment Tax Incentive (ETI) (unu.edu)
UNU-WIDER : Working Paper : The effects of the Employment Tax Incentive on South African mployment and ebrahim_a28067.pdf (iza.org)
The Employment Tax Incentive Scheme in South Africa: An Impact Assessment (africaportal.org)
Deliberations in Nedlac resulted in unanimous recommendations for extensions of the programme in 2016 and 2018. In the latter case, NT initially proposed a 5 year extension, while social partners recommended a 10 year extension (also indicated in the Framework agreement of the Presidential Jobs Summit in 2018), in order to give certainty and to encourage building systems to ease compliance burdens. In both cases, the reports from Nedlac were not only shared with SCOF, but were required before the committee assented to the draft.
Research findings since the review
UNU-WIDER : Working Paper : Can a wage subsidy system help reduce 50 per cent youth unemployment?
UNU-WIDER : Working Paper : Estimating employment responses to South Africa’s Employment Tax Incentive(sound caution about the methodology for future impact assessments) 33<br>
slide34. Implementing nugent recommendations Delay in announcement due to need for a comprehensive response by Government on Zondo Commission
Need to align both Zondo and Nugent Commission proposals
Still hope to table a draft bill on SARS governance and management reforms in July with TLAB and TALAB Bills 34<br>
slide35. Climate change response and carbon tax price path To meet SA’s climate commitments, the country’s greenhouse gas emissions must peak by 2025 and then quickly decline to between 350 million and 420 million tonnes by 2030, and approach net‐zero emissions by 2050.
The carbon tax is integral to lowering emissions.
To prepare South Africa for the structural transition to a climate‐resilient economy, government proposes to progressively increase the carbon price every year by at least US$1 to reach US$20 per tonne of carbon dioxide equivalent by 2026.
For the second phase, government intends to increase the carbon price more rapidly every year, to at least US$30 by 2030, accelerating to higher levels by 2035, 2040 and up to US$120 beyond 2050.
The basic tax‐free allowances will also be gradually reduced to strengthen the price signals under the carbon tax from 1 January 2026 to 31 December 2030.
To encourage investments in carbon offset projects, government intends to increase the carbon offset allowance by 5 per cent from 1 January 2026.
This approach aligns with global institutions. The World Bank’s High‐Level Commission on Carbon Prices recommends carbon prices of US$40 to US$80 per tonne by 2025 and US$50 to US$100 by 2030. The International Monetary Fund recommends lower minimum carbon prices for developing countries of US$25 to US$50 by 2030 to achieve the Paris climate goals. 35<br>