
Sorted User Survey February 2022 CONFIDENTIAL
LD
Published · 44 slides · 0 views

1 / 1




Description
Sorted User Survey February 2022 CONFIDENTIAL Sample 5214 started the survey n 3722 completed surveys 54 of non-completes were infrequent or non-users (an increase on 2020) Women strongly overrepresented as usual As in 2020, male users
Related Topics
Share
Embed code
Download this presentation From Below
"Sorted User Survey February 2022 CONFIDENTIAL" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Sorted User Survey February 2022 CONFIDENTIAL<br>
02
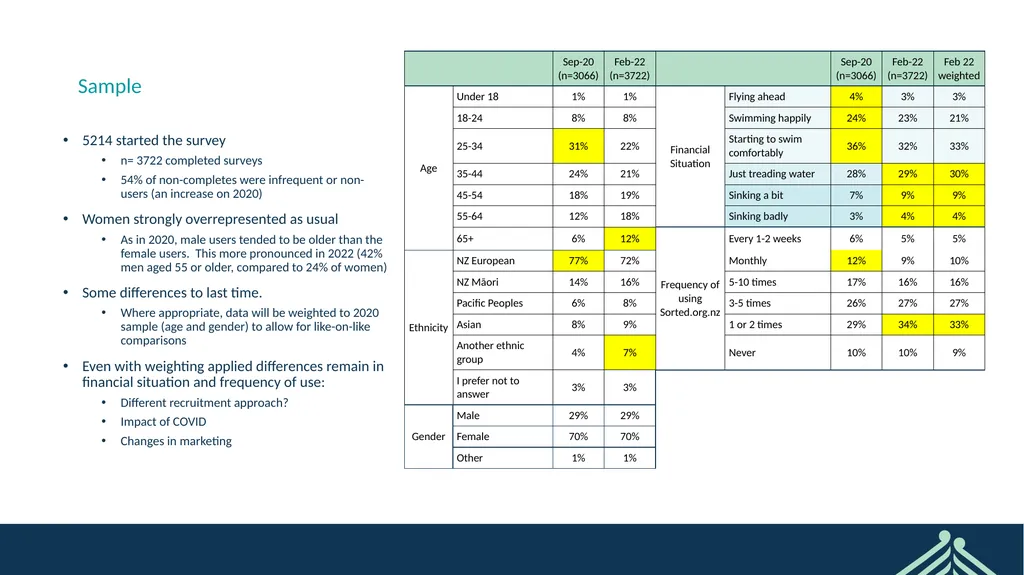
Sample 5214 started the survey
n= 3722 completed surveys
54% of non-completes were infrequent or non-users (an increase on 2020)
Women strongly overrepresented as usual
As in 2020, male users tended to be older than the female users. This more pronounced in 2022 (42% men aged 55 or older, compared to 24% of women)
Some differences to last time.
Where appropriate, data will be weighted to 2020 sample (age and gender) to allow for like-on-like comparisons
Even with weighting applied differences remain in financial situation and frequency of use:
Different recruitment approach?
Impact of COVID
Changes in marketing<br>
03
Triggers and Reasons to Visit Sorted.Org.NZ<br>
04
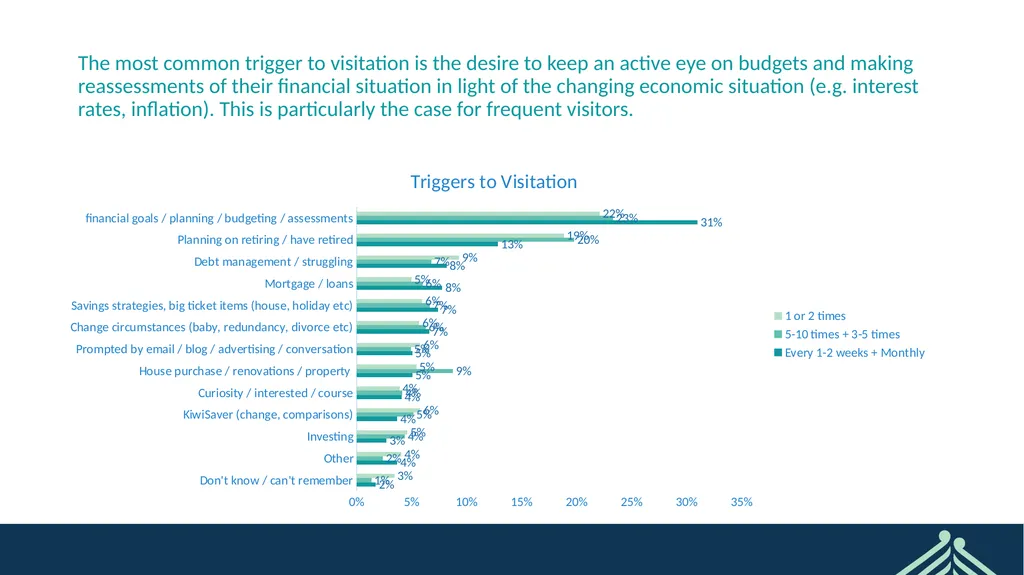
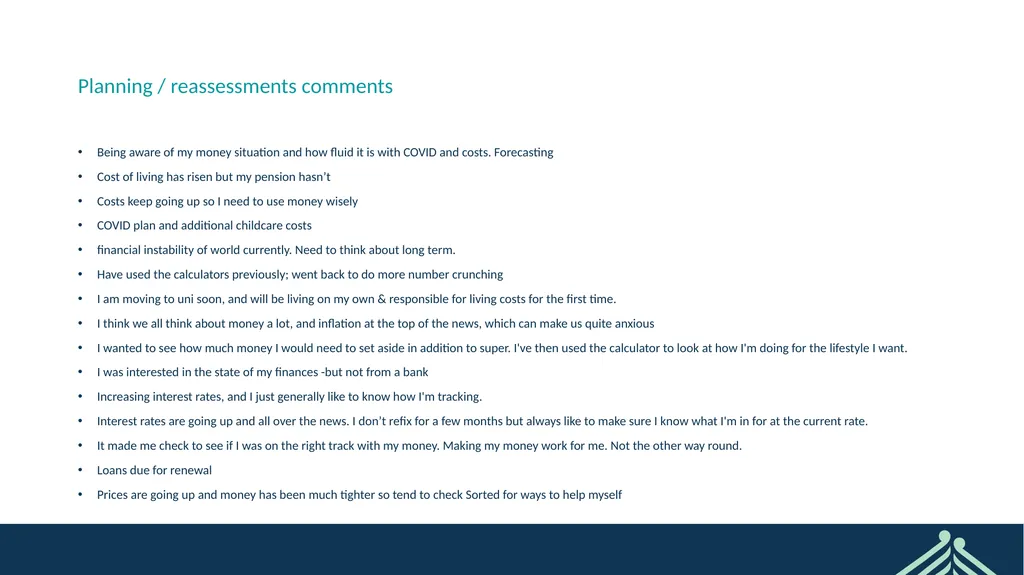
The most common trigger to visitation is the desire to keep an active eye on budgets and making reassessments of their financial situation in light of the changing economic situation (e.g. interest rates, inflation). This is particularly the case for frequent visitors. Total sample; Unweighted; base n = 3032; total n = 3722; 690 missing<br>
05
Planning / reassessments comments Being aware of my money situation and how fluid it is with COVID and costs. Forecasting
Cost of living has risen but my pension hasn’t
Costs keep going up so I need to use money wisely
COVID plan and additional childcare costs
financial instability of world currently. Need to think about long term.
Have used the calculators previously; went back to do more number crunching
I am moving to uni soon, and will be living on my own & responsible for living costs for the first time.
I think we all think about money a lot, and inflation at the top of the news, which can make us quite anxious
I wanted to see how much money I would need to set aside in addition to super. I've then used the calculator to look at how I'm doing for the lifestyle I want.
I was interested in the state of my finances -but not from a bank
Increasing interest rates, and I just generally like to know how I'm tracking.
Interest rates are going up and all over the news. I don’t refix for a few months but always like to make sure I know what I'm in for at the current rate.
It made me check to see if I was on the right track with my money. Making my money work for me. Not the other way round.
Loans due for renewal
Prices are going up and money has been much tighter so tend to check Sorted for ways to help myself<br>
06
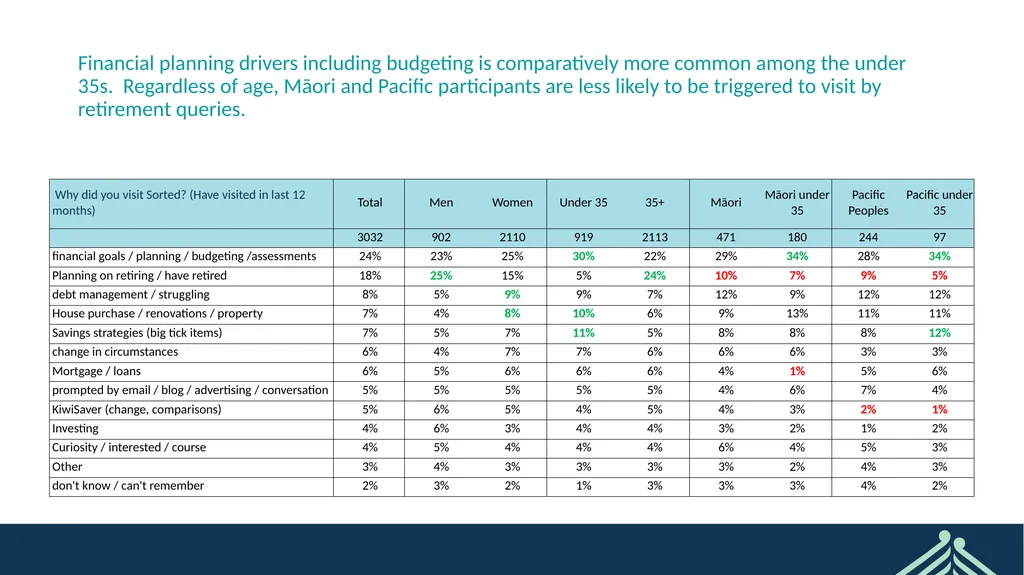
Financial planning drivers including budgeting is comparatively more common among the under 35s. Regardless of age, Māori and Pacific participants are less likely to be triggered to visit by retirement queries.<br>
07
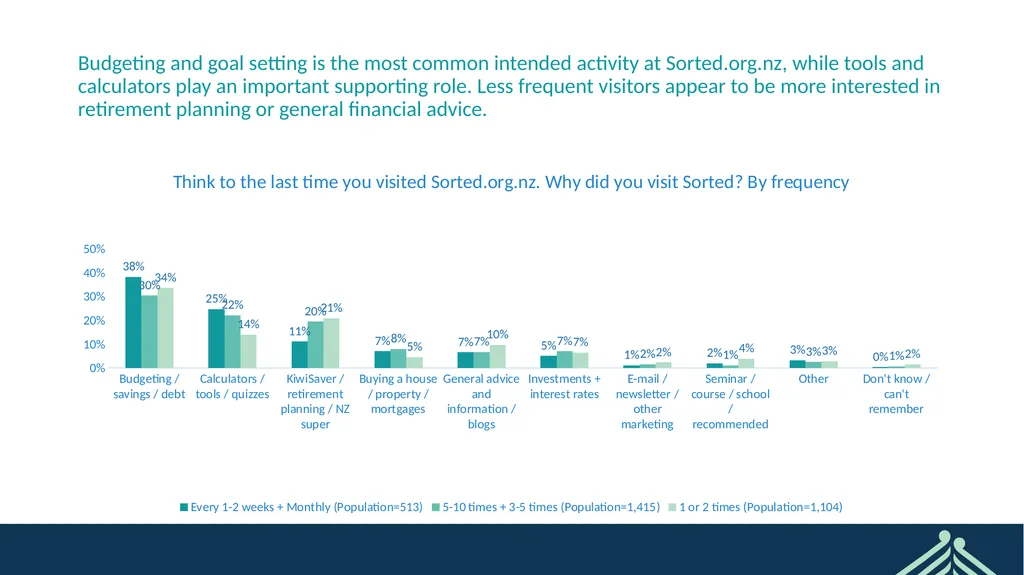
Budgeting and goal setting is the most common intended activity at Sorted.org.nz, while tools and calculators play an important supporting role. Less frequent visitors appear to be more interested in retirement planning or general financial advice. Total sample; Unweighted; base n = 3032; total n = 3722; 690 missing<br>
08
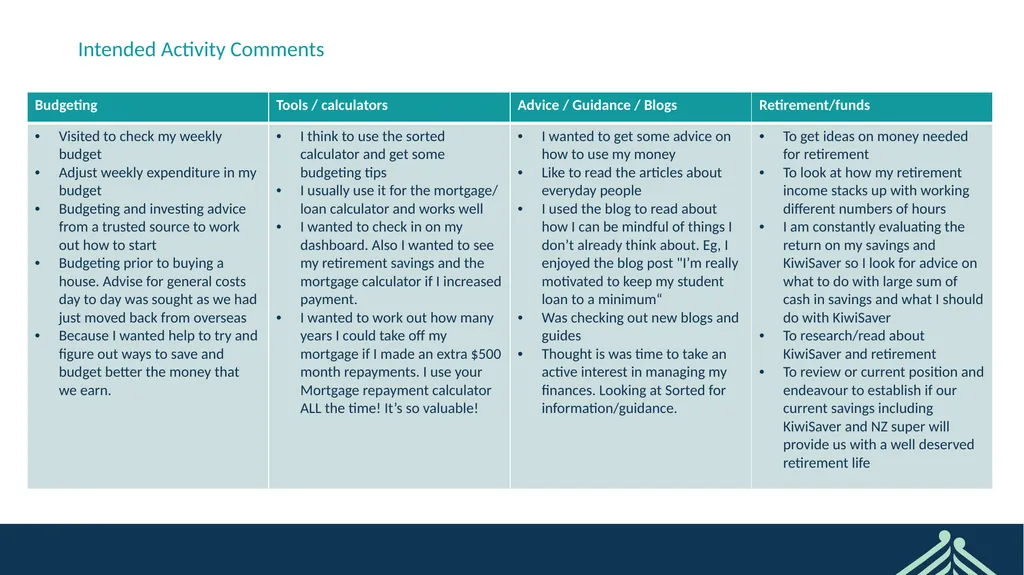
Intended Activity Comments Total sample; Unweighted; base n = 3032; total n = 3722; 690 missing<br>
09
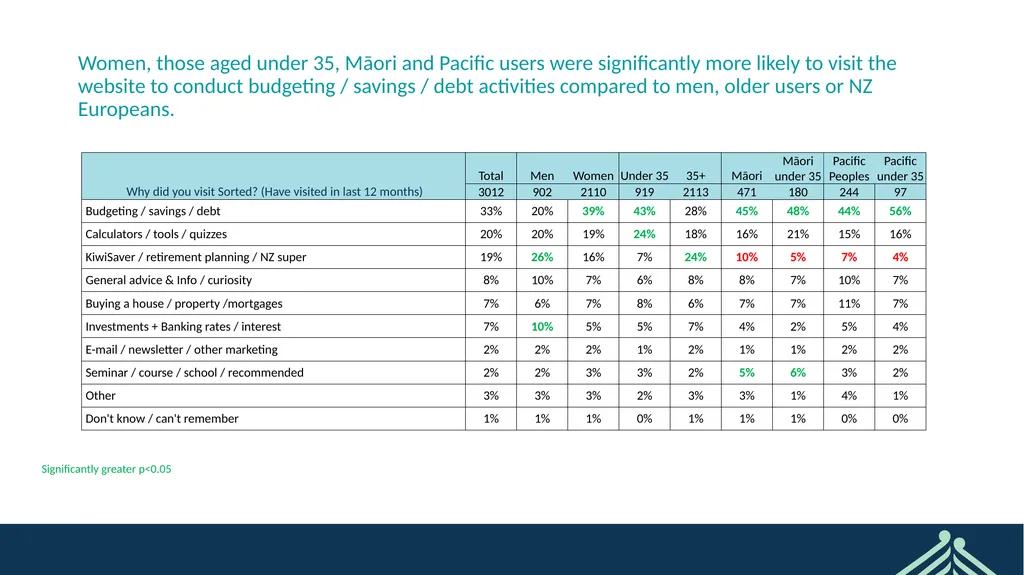
Women, those aged under 35, Māori and Pacific users were significantly more likely to visit the website to conduct budgeting / savings / debt activities compared to men, older users or NZ Europeans. Significantly greater p<0.05<br>
10
Triggers and reasons to visit Sorted.org.nz Total sample; Unweighted; base n = 3032; total n = 3722; 690 missing<br>
11
Impacts<br>
12
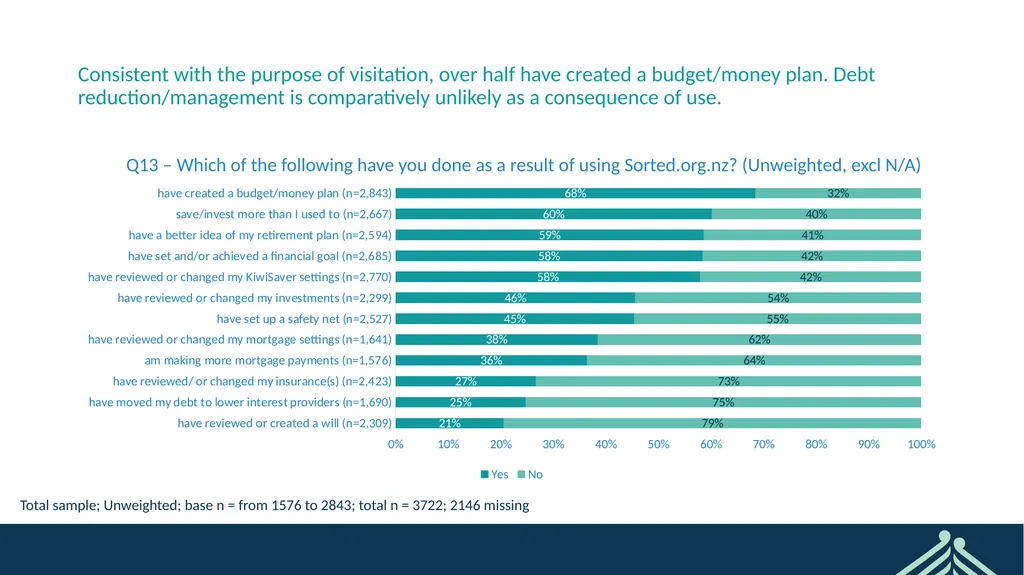
Consistent with the purpose of visitation, over half have created a budget/money plan. Debt reduction/management is comparatively unlikely as a consequence of use. Total sample; Unweighted; base n = from 1576 to 2843; total n = 3722; 2146 missing Q13 – Which of the following have you done as a result of using Sorted.org.nz? (Unweighted, excl N/A)<br>
13
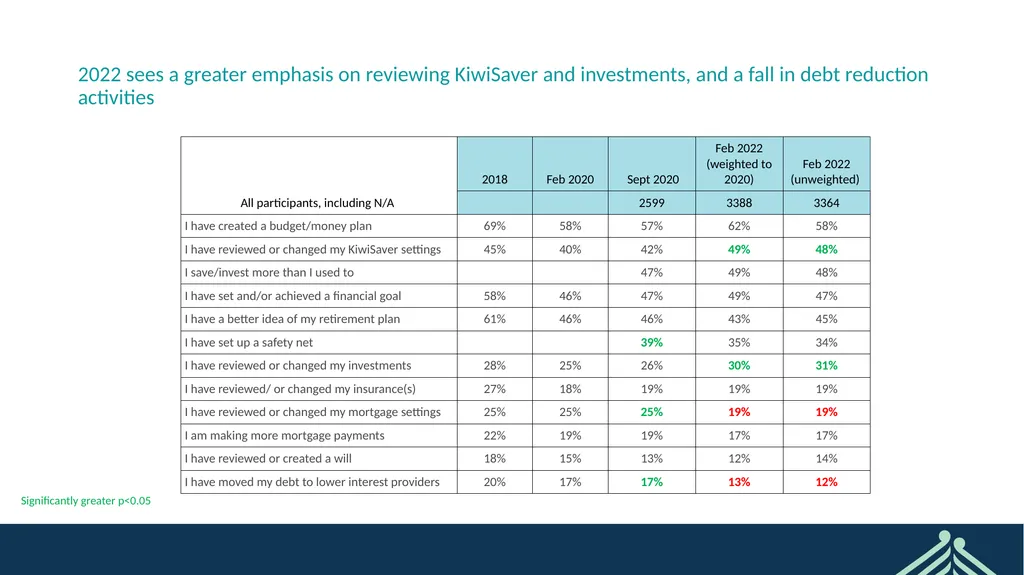
2022 sees a greater emphasis on reviewing KiwiSaver and investments, and a fall in debt reduction activities Significantly greater p<0.05<br>
14
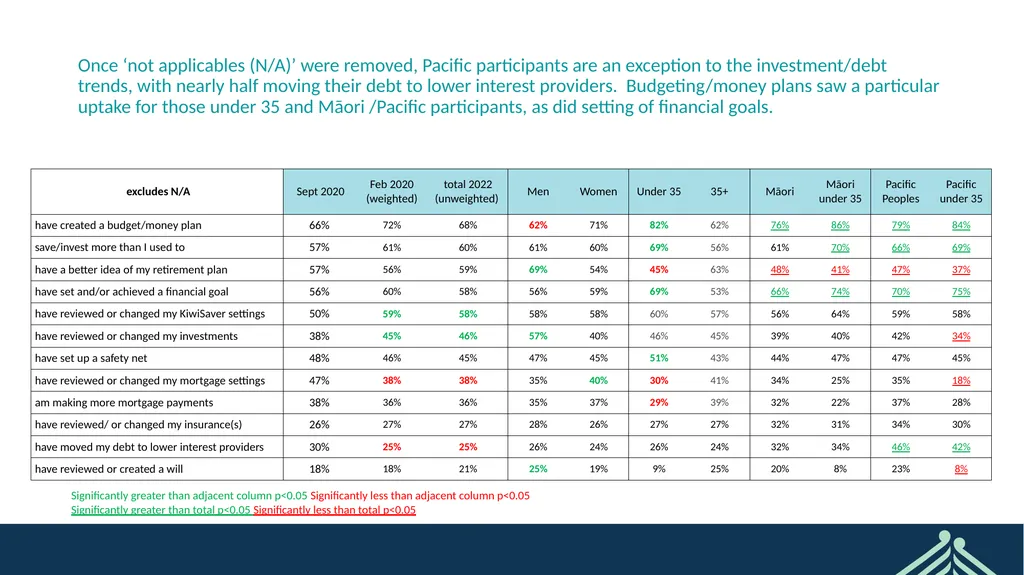
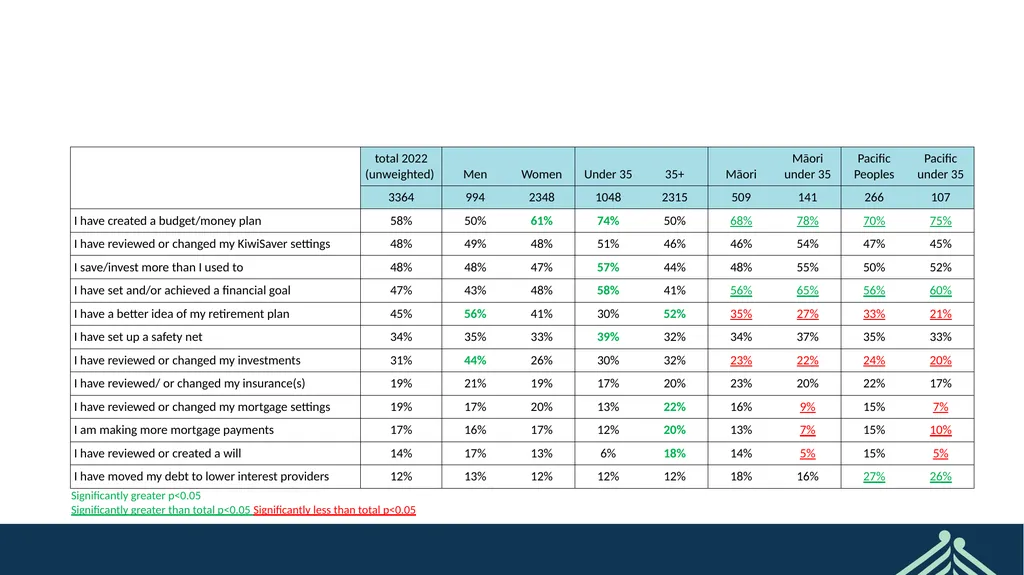
Once ‘not applicables (N/A)’ were removed, Pacific participants are an exception to the investment/debt trends, with nearly half moving their debt to lower interest providers. Budgeting/money plans saw a particular uptake for those under 35 and Māori /Pacific participants, as did setting of financial goals. Significantly greater than adjacent column p<0.05 Significantly less than adjacent column p<0.05
Significantly greater than total p<0.05 Significantly less than total p<0.05<br>
Significantly greater than total p<0.05 Significantly less than total p<0.05<br>
15
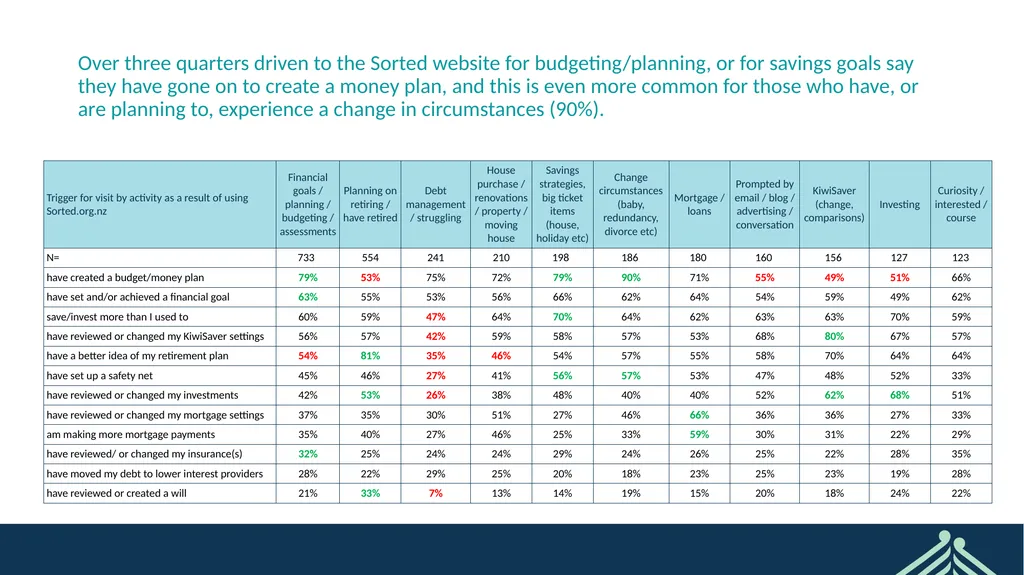
Over three quarters driven to the Sorted website for budgeting/planning, or for savings goals say they have gone on to create a money plan, and this is even more common for those who have, or are planning to, experience a change in circumstances (90%).<br>
16
Performance<br>
17
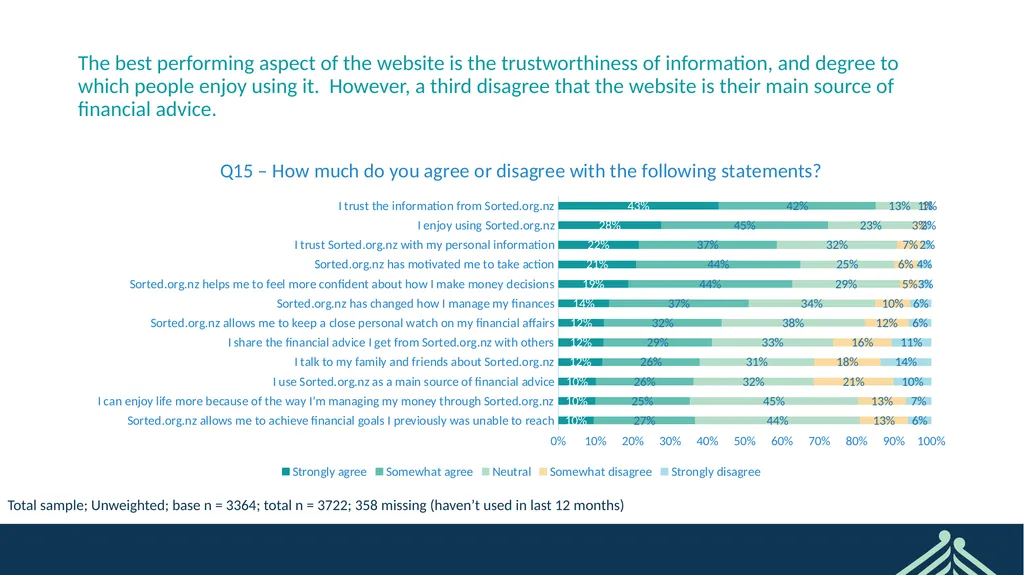
The best performing aspect of the website is the trustworthiness of information, and degree to which people enjoy using it. However, a third disagree that the website is their main source of financial advice. Total sample; Unweighted; base n = 3364; total n = 3722; 358 missing (haven’t used in last 12 months)<br>
18
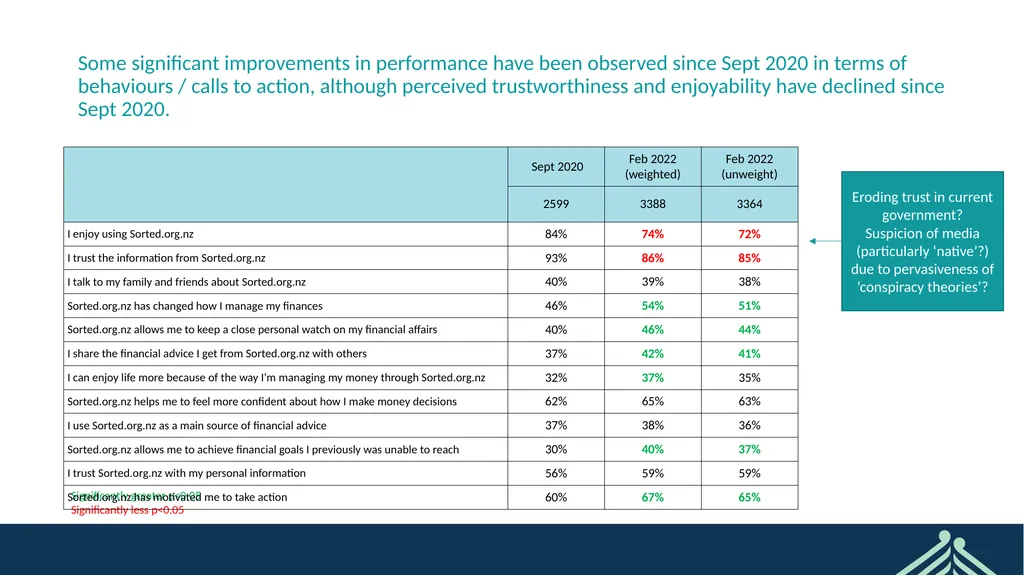
Some significant improvements in performance have been observed since Sept 2020 in terms of behaviours / calls to action, although perceived trustworthiness and enjoyability have declined since Sept 2020. Significantly greater p<0.05
Significantly less p<0.05 Eroding trust in current government?
Suspicion of media (particularly ‘native’?) due to pervasiveness of ‘conspiracy theories’?<br>
Significantly less p<0.05 Eroding trust in current government?
Suspicion of media (particularly ‘native’?) due to pervasiveness of ‘conspiracy theories’?<br>
19
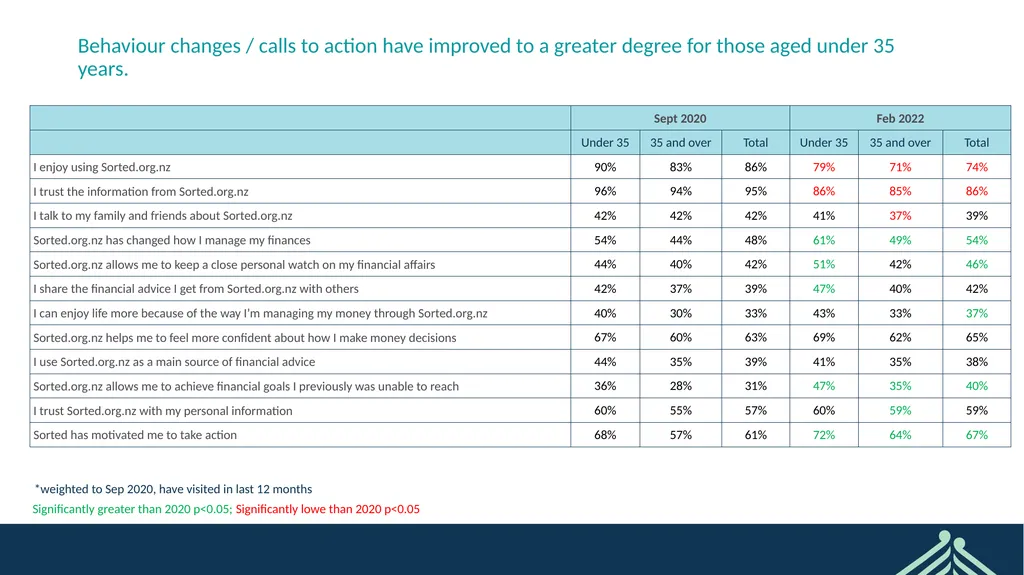
Behaviour changes / calls to action have improved to a greater degree for those aged under 35 years. *weighted to Sep 2020, have visited in last 12 months Significantly greater than 2020 p<0.05; Significantly lowe than 2020 p<0.05<br>
20
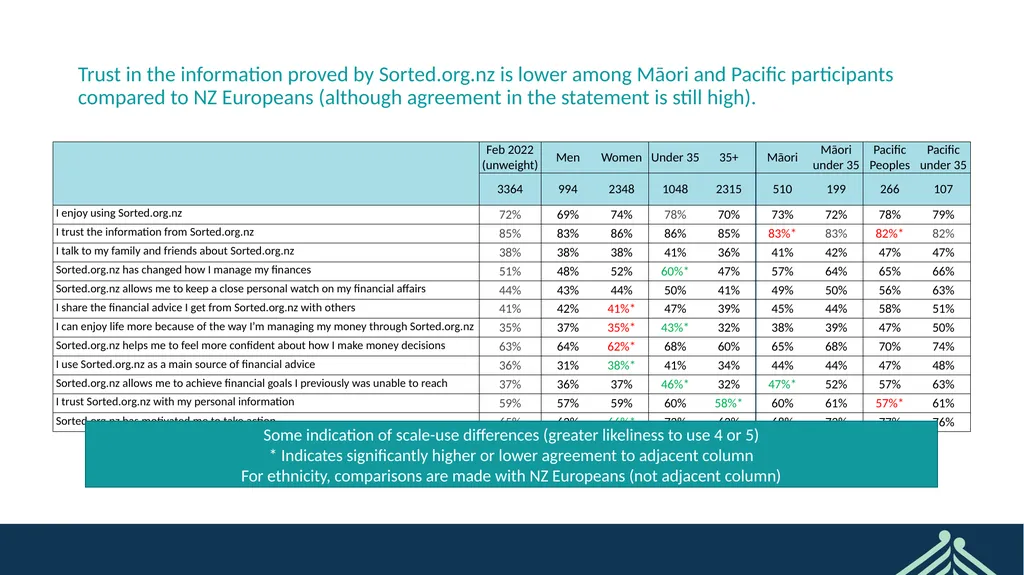
Trust in the information proved by Sorted.org.nz is lower among Māori and Pacific participants compared to NZ Europeans (although agreement in the statement is still high). Some indication of scale-use differences (greater likeliness to use 4 or 5)
* Indicates significantly higher or lower agreement to adjacent column
For ethnicity, comparisons are made with NZ Europeans (not adjacent column)<br>
* Indicates significantly higher or lower agreement to adjacent column
For ethnicity, comparisons are made with NZ Europeans (not adjacent column)<br>
21
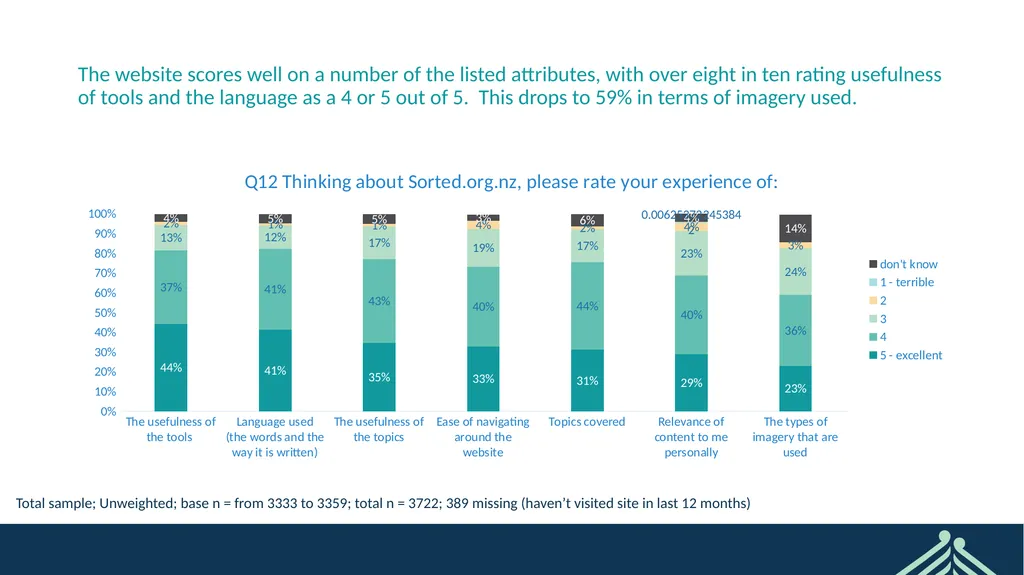
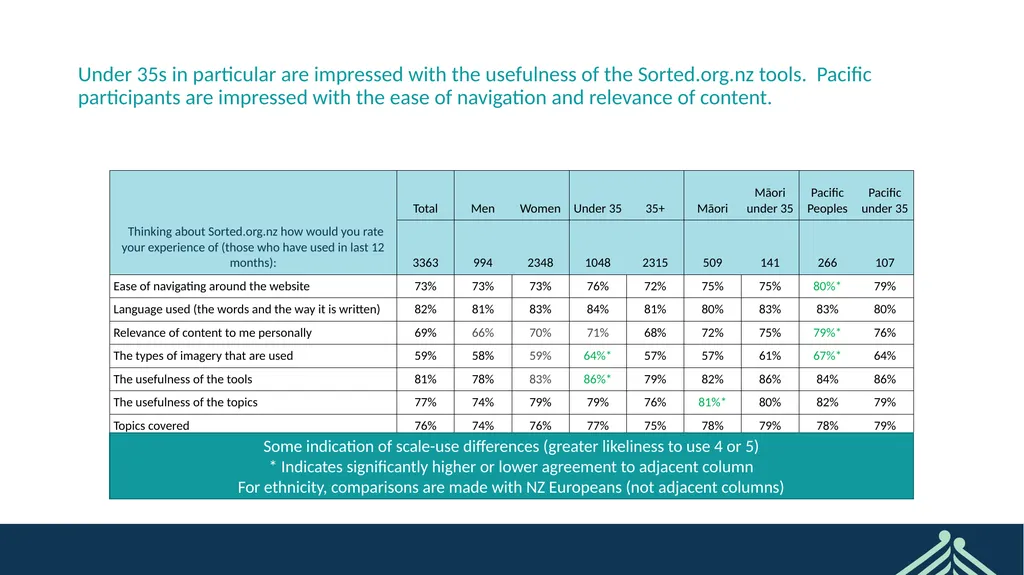
The website scores well on a number of the listed attributes, with over eight in ten rating usefulness of tools and the language as a 4 or 5 out of 5. This drops to 59% in terms of imagery used. Total sample; Unweighted; base n = from 3333 to 3359; total n = 3722; 389 missing (haven’t visited site in last 12 months)<br>
22
Under 35s in particular are impressed with the usefulness of the Sorted.org.nz tools. Pacific participants are impressed with the ease of navigation and relevance of content. Some indication of scale-use differences (greater likeliness to use 4 or 5)
* Indicates significantly higher or lower agreement to adjacent column
For ethnicity, comparisons are made with NZ Europeans (not adjacent columns)<br>
* Indicates significantly higher or lower agreement to adjacent column
For ethnicity, comparisons are made with NZ Europeans (not adjacent columns)<br>
23
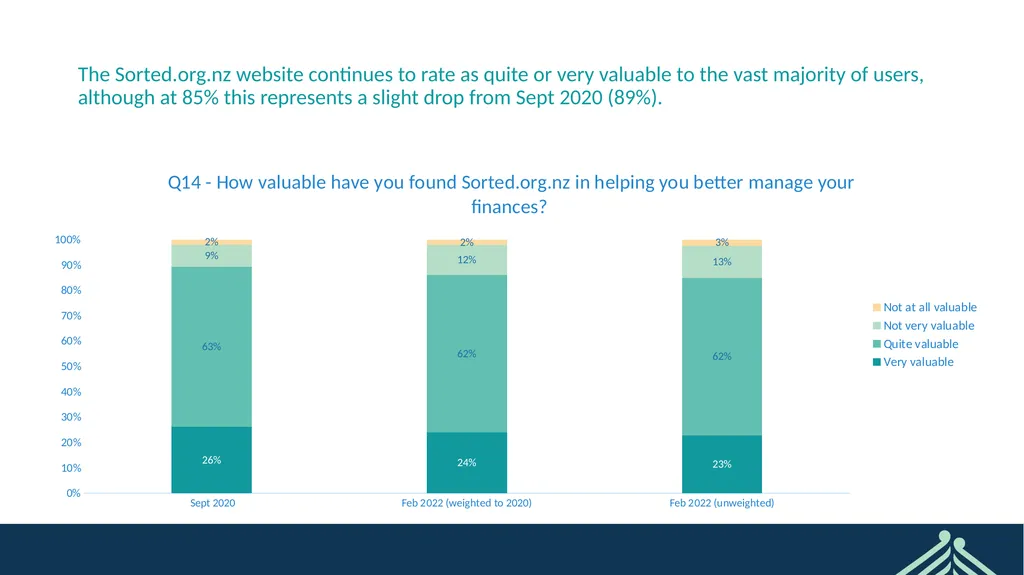
The Sorted.org.nz website continues to rate as quite or very valuable to the vast majority of users, although at 85% this represents a slight drop from Sept 2020 (89%). Total sample; Weight: Weight; base n = 3361; total n = 3722; 361 missing; effective sample size = 3076 (92%)<br>
24
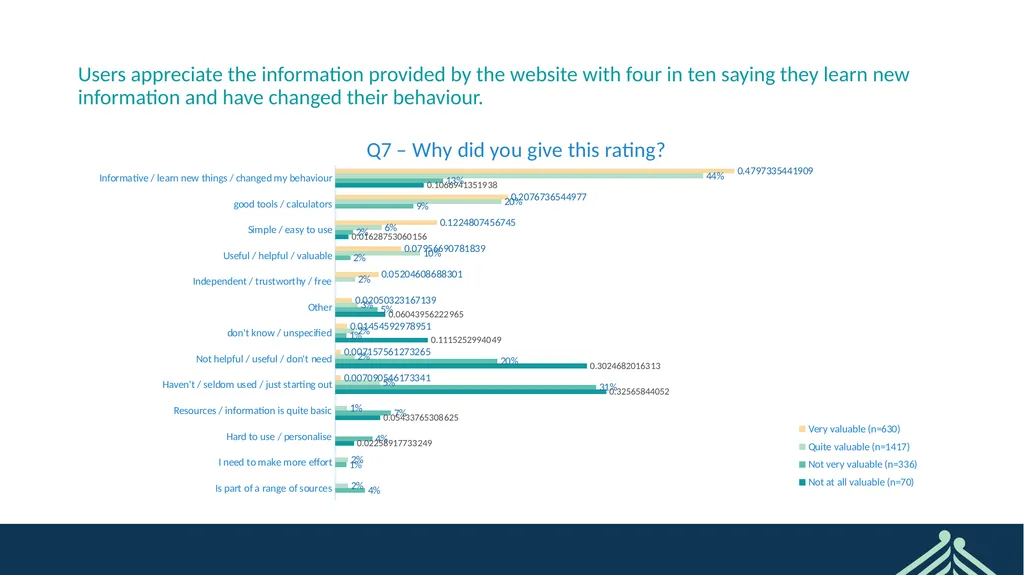
Users appreciate the information provided by the website with four in ten saying they learn new information and have changed their behaviour. Total sample; Weight: Weight; base n = 2450; total n = 3722; 1272 missing; effective sample size = 2253 (92%)<br>
25
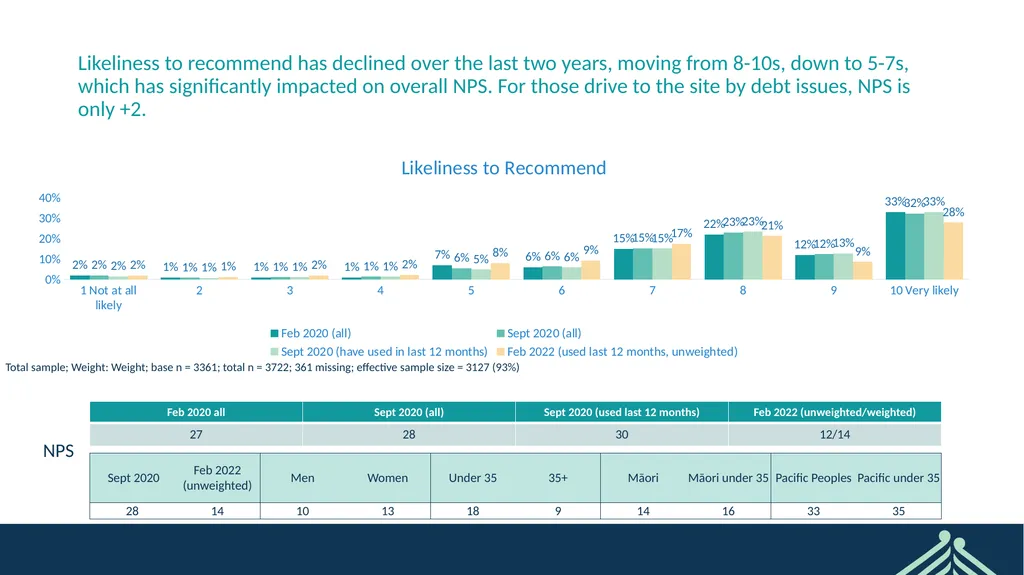
Likeliness to recommend has declined over the last two years, moving from 8-10s, down to 5-7s, which has significantly impacted on overall NPS. For those drive to the site by debt issues, NPS is only +2. Total sample; Weight: Weight; base n = 3361; total n = 3722; 361 missing; effective sample size = 3127 (93%) NPS<br>
26
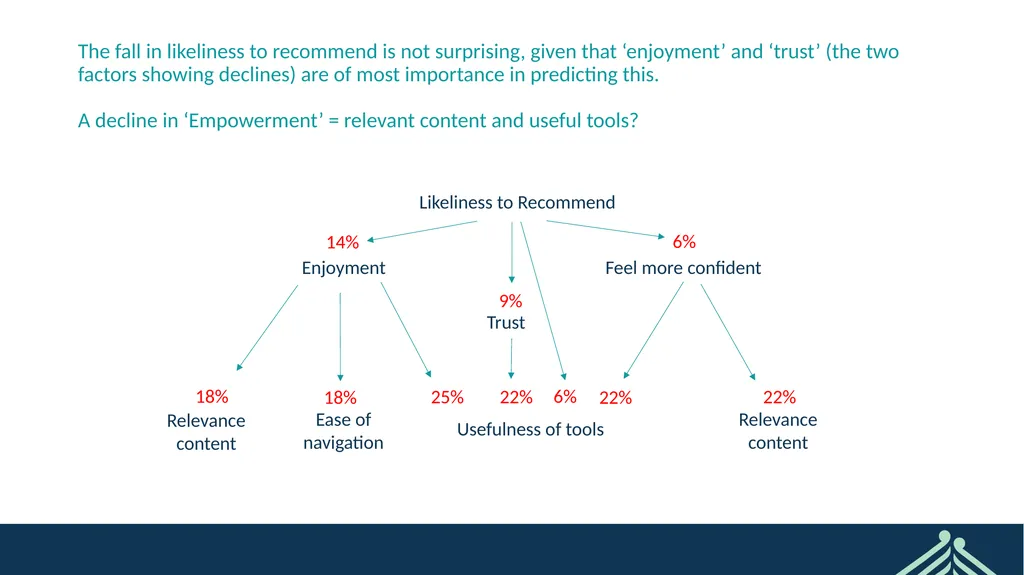
The fall in likeliness to recommend is not surprising, given that ‘enjoyment’ and ‘trust’ (the two factors showing declines) are of most importance in predicting this.
A decline in ‘Empowerment’ = relevant content and useful tools? Enjoyment Likeliness to Recommend Trust Usefulness of tools Feel more confident 14% 9% 6% 6% 25% Ease of navigation Relevance content 18% 18% 22% 22% Relevance content 22%<br>
27
Moving Forward<br>
28
Investments and savings are of most relevance to users, followed by budgeting and retirement planning. Total sample; Weight: Weight; base n = 3717; total n = 3722; 5 missing; effective sample size = 3399 (91%)<br>
29
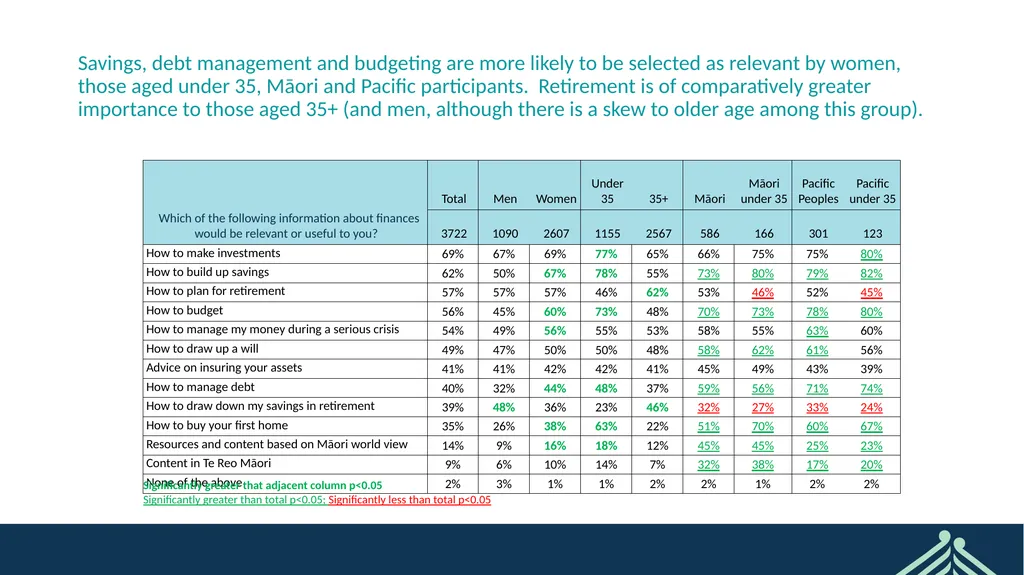
Savings, debt management and budgeting are more likely to be selected as relevant by women, those aged under 35, Māori and Pacific participants. Retirement is of comparatively greater importance to those aged 35+ (and men, although there is a skew to older age among this group). Significantly greater that adjacent column p<0.05
Significantly greater than total p<0.05; Significantly less than total p<0.05<br>
Significantly greater than total p<0.05; Significantly less than total p<0.05<br>
30
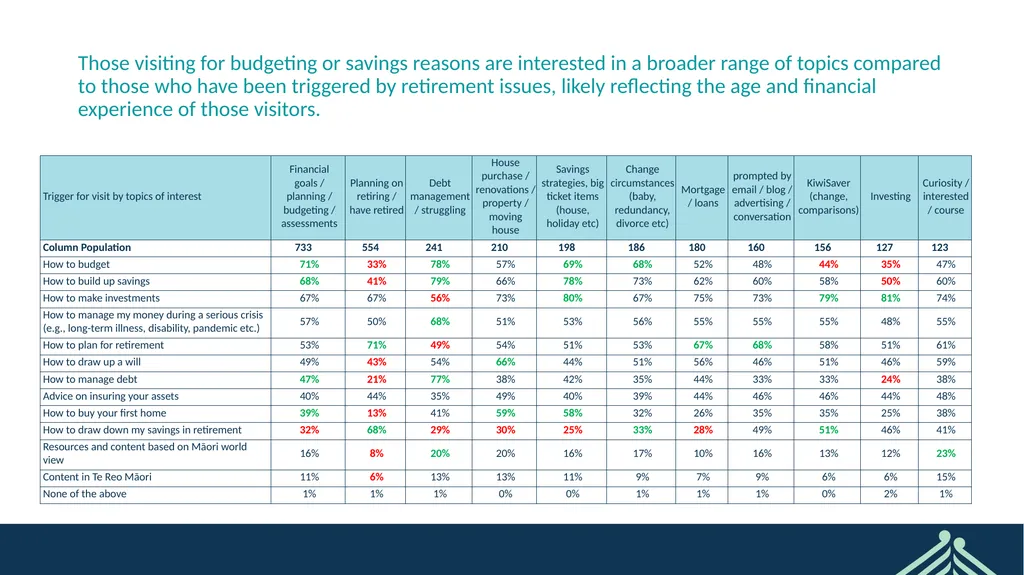
Those visiting for budgeting or savings reasons are interested in a broader range of topics compared to those who have been triggered by retirement issues, likely reflecting the age and financial experience of those visitors.<br>
31
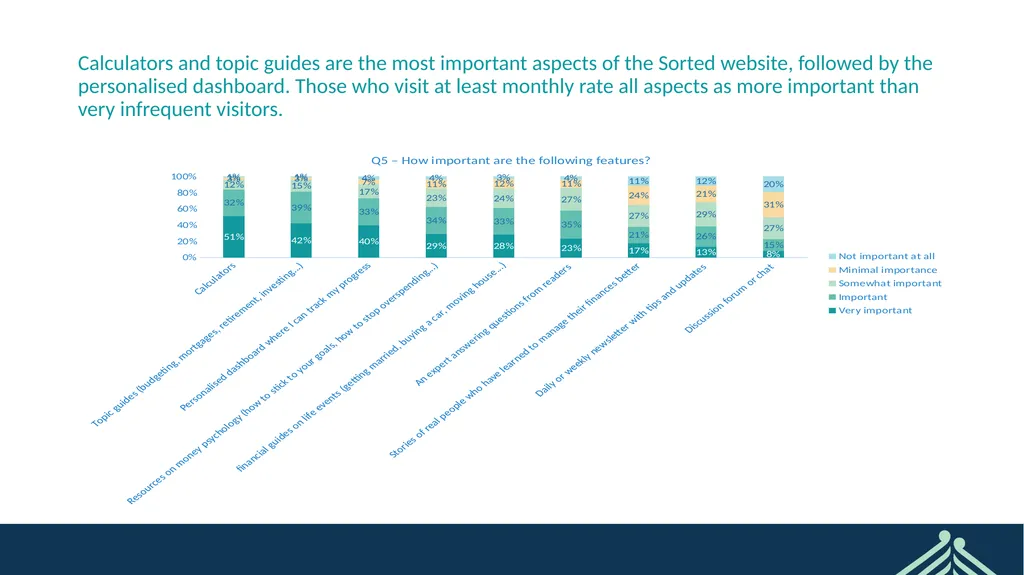
Calculators and topic guides are the most important aspects of the Sorted website, followed by the personalised dashboard. Those who visit at least monthly rate all aspects as more important than very infrequent visitors. Total sample; Weight: Weight; base n = 3717; total n = 3722; 5 missing; effective sample size = 3397 (91%)<br>
32
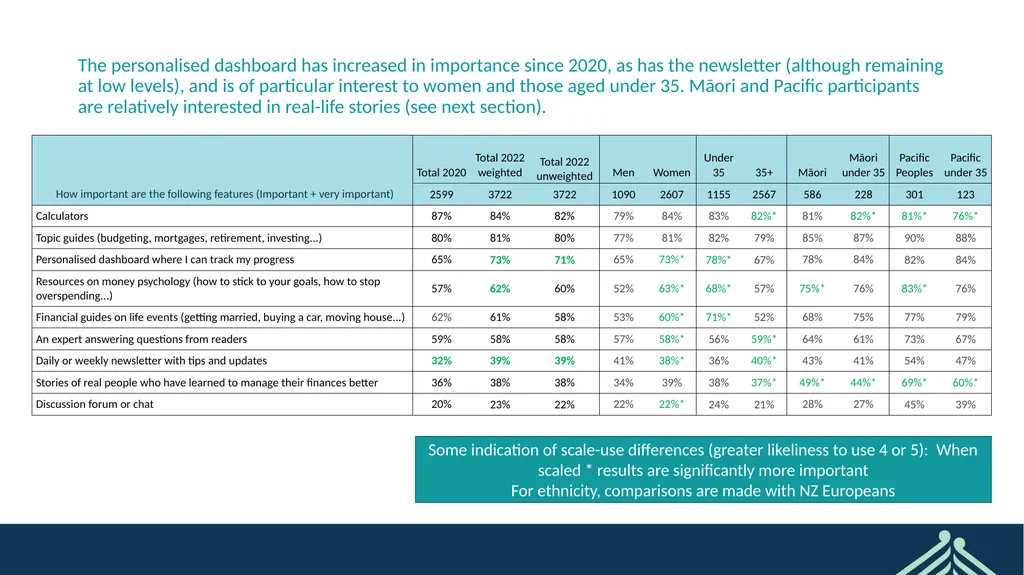
The personalised dashboard has increased in importance since 2020, as has the newsletter (although remaining at low levels), and is of particular interest to women and those aged under 35. Māori and Pacific participants are relatively interested in real-life stories (see next section). Total sample; Weight: Weight; base n = 3717; total n = 3722; 5 missing; effective sample size = 3397 (91%) Some indication of scale-use differences (greater likeliness to use 4 or 5): When scaled * results are significantly more important
For ethnicity, comparisons are made with NZ Europeans<br>
For ethnicity, comparisons are made with NZ Europeans<br>
33
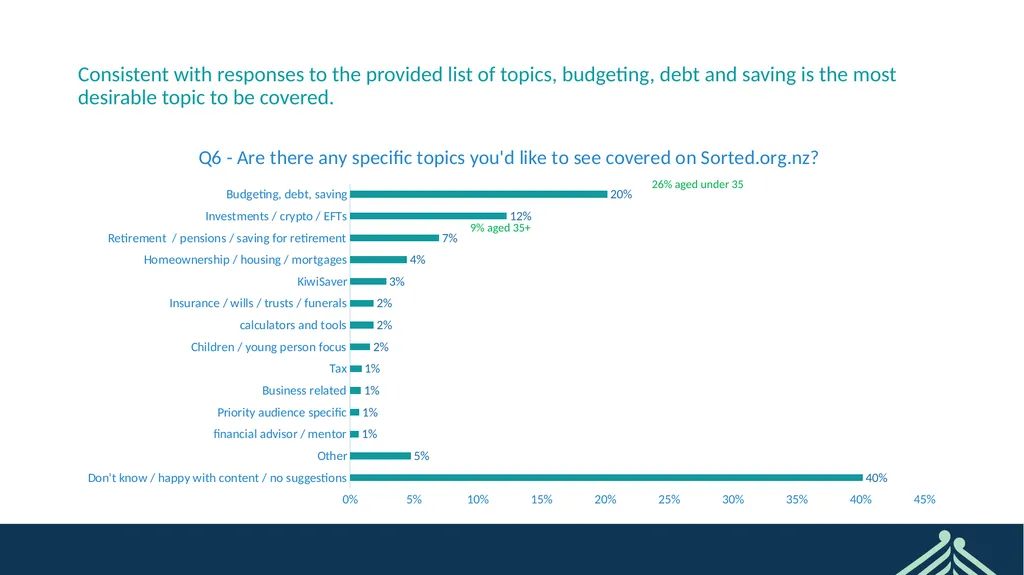
Consistent with responses to the provided list of topics, budgeting, debt and saving is the most desirable topic to be covered. Total sample; Weight: Weight; base n = 2219; total n = 3722; 1503 missing; effective sample size = 1998 (90%) 9% aged 35+ 26% aged under 35<br>
34
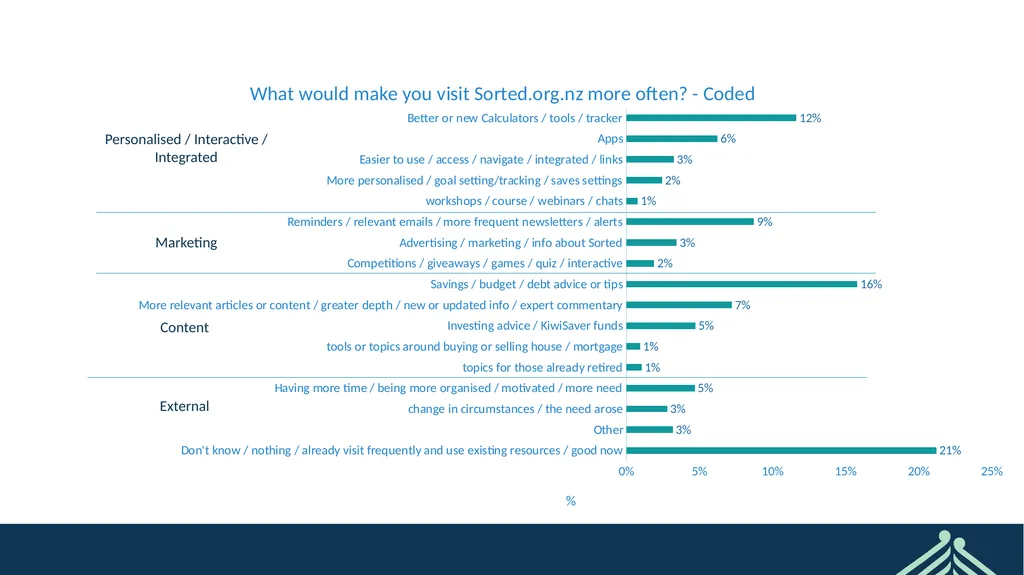
Total sample; Weight: Weight; base n = 3717; total n = 3722; 5 missing; effective sample size = 3394 (91%) Personalised / Interactive / Integrated Marketing Content External<br>
35
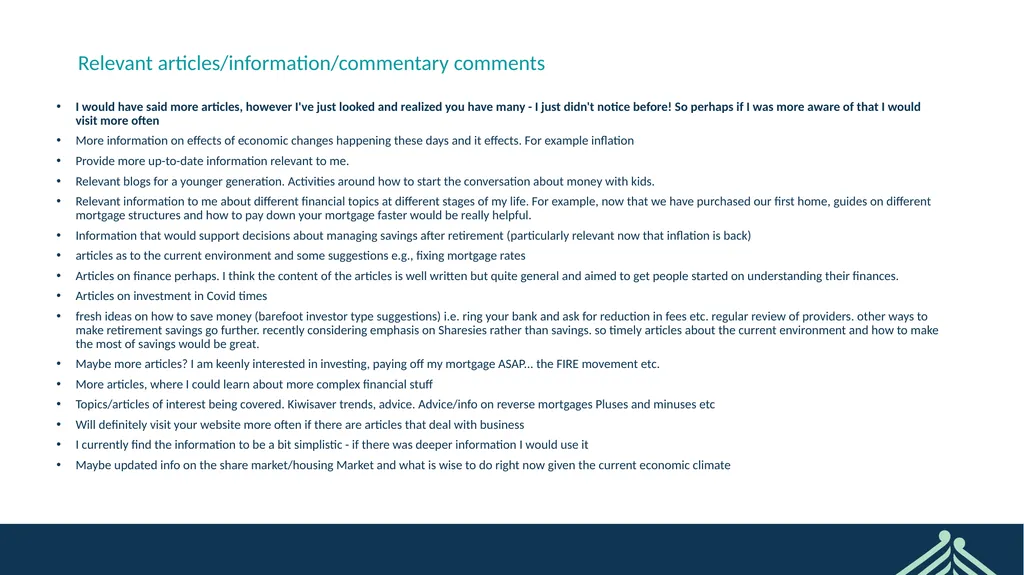
Relevant articles/information/commentary comments I would have said more articles, however I've just looked and realized you have many - I just didn't notice before! So perhaps if I was more aware of that I would visit more often
More information on effects of economic changes happening these days and it effects. For example inflation
Provide more up-to-date information relevant to me.
Relevant blogs for a younger generation. Activities around how to start the conversation about money with kids.
Relevant information to me about different financial topics at different stages of my life. For example, now that we have purchased our first home, guides on different mortgage structures and how to pay down your mortgage faster would be really helpful.
Information that would support decisions about managing savings after retirement (particularly relevant now that inflation is back)
articles as to the current environment and some suggestions e.g., fixing mortgage rates
Articles on finance perhaps. I think the content of the articles is well written but quite general and aimed to get people started on understanding their finances.
Articles on investment in Covid times
fresh ideas on how to save money (barefoot investor type suggestions) i.e. ring your bank and ask for reduction in fees etc. regular review of providers. other ways to make retirement savings go further. recently considering emphasis on Sharesies rather than savings. so timely articles about the current environment and how to make the most of savings would be great.
Maybe more articles? I am keenly interested in investing, paying off my mortgage ASAP... the FIRE movement etc.
More articles, where I could learn about more complex financial stuff
Topics/articles of interest being covered. Kiwisaver trends, advice. Advice/info on reverse mortgages Pluses and minuses etc
Will definitely visit your website more often if there are articles that deal with business
I currently find the information to be a bit simplistic - if there was deeper information I would use it
Maybe updated info on the share market/housing Market and what is wise to do right now given the current economic climate<br>
36
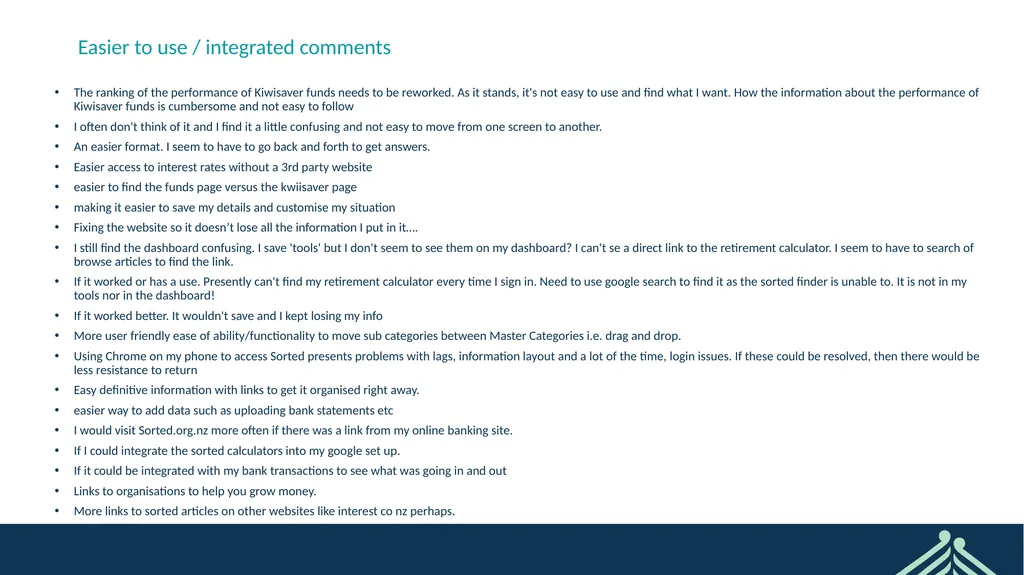
Easier to use / integrated comments The ranking of the performance of Kiwisaver funds needs to be reworked. As it stands, it's not easy to use and find what I want. How the information about the performance of Kiwisaver funds is cumbersome and not easy to follow
I often don't think of it and I find it a little confusing and not easy to move from one screen to another.
An easier format. I seem to have to go back and forth to get answers.
Easier access to interest rates without a 3rd party website
easier to find the funds page versus the kwiisaver page
making it easier to save my details and customise my situation
Fixing the website so it doesn’t lose all the information I put in it….
I still find the dashboard confusing. I save 'tools' but I don't seem to see them on my dashboard? I can't se a direct link to the retirement calculator. I seem to have to search of browse articles to find the link.
If it worked or has a use. Presently can't find my retirement calculator every time I sign in. Need to use google search to find it as the sorted finder is unable to. It is not in my tools nor in the dashboard!
If it worked better. It wouldn't save and I kept losing my info
More user friendly ease of ability/functionality to move sub categories between Master Categories i.e. drag and drop.
Using Chrome on my phone to access Sorted presents problems with lags, information layout and a lot of the time, login issues. If these could be resolved, then there would be less resistance to return
Easy definitive information with links to get it organised right away.
easier way to add data such as uploading bank statements etc
I would visit Sorted.org.nz more often if there was a link from my online banking site.
If I could integrate the sorted calculators into my google set up.
If it could be integrated with my bank transactions to see what was going in and out
Links to organisations to help you grow money.
More links to sorted articles on other websites like interest co nz perhaps.<br>
37
Te Ao Māori<br>
38
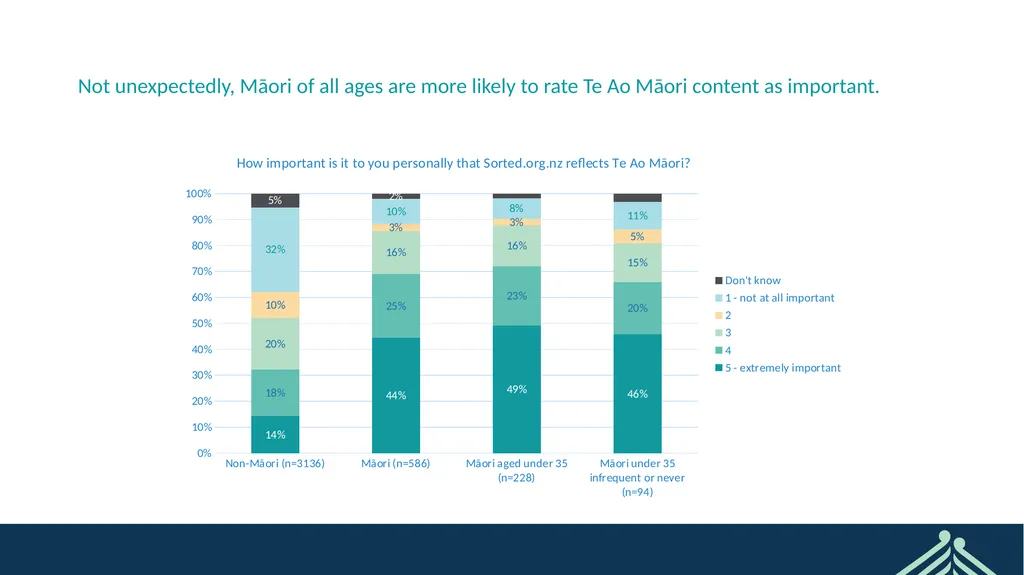
Not unexpectedly, Māori of all ages are more likely to rate Te Ao Māori content as important.<br>
39
A third of Māori don’t have an opinion on how well Sorted.org.nz does at reflecting Te Ao Māori. Of those who do have an opinion, fewer than a quarter feel the website does well (T2B).<br>
40
Te Reo is important to Māori, but reflecting Te Ao Māori needs to go further, by incorporating stories, values, whakatauki and Te Whare Tapa Whā into content. This potentially ties in with the relative interest in real-life stories for Māori (and Pacific) participants.<br>
41
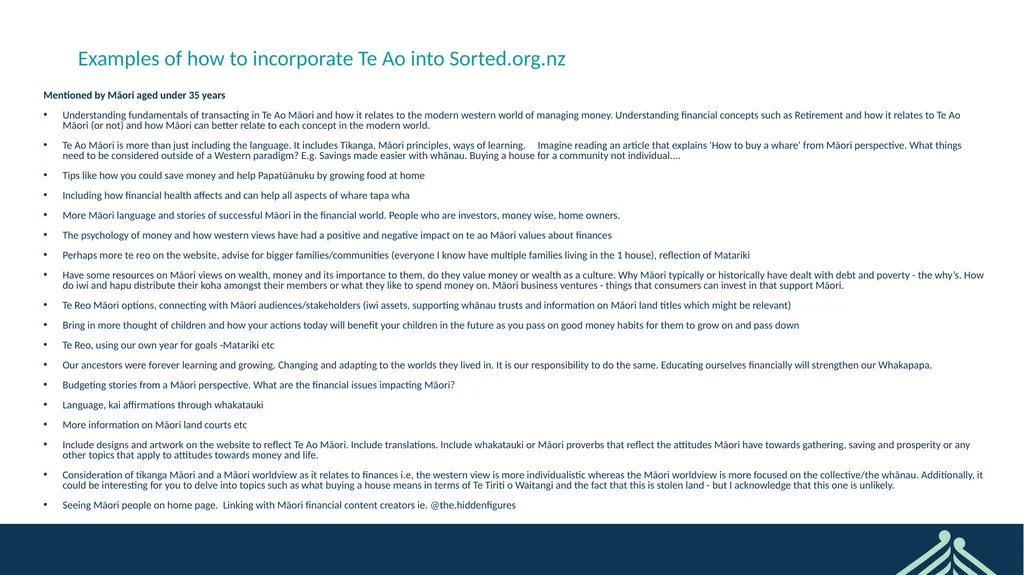
Examples of how to incorporate Te Ao into Sorted.org.nz Mentioned by Māori aged under 35 years
Understanding fundamentals of transacting in Te Ao Māori and how it relates to the modern western world of managing money. Understanding financial concepts such as Retirement and how it relates to Te Ao Māori (or not) and how Māori can better relate to each concept in the modern world.
Te Ao Māori is more than just including the language. It includes Tikanga, Māori principles, ways of learning. Imagine reading an article that explains 'How to buy a whare' from Māori perspective. What things need to be considered outside of a Western paradigm? E.g. Savings made easier with whānau. Buying a house for a community not individual....
Tips like how you could save money and help Papatūānuku by growing food at home
Including how financial health affects and can help all aspects of whare tapa wha
More Māori language and stories of successful Māori in the financial world. People who are investors, money wise, home owners.
The psychology of money and how western views have had a positive and negative impact on te ao Māori values about finances
Perhaps more te reo on the website, advise for bigger families/communities (everyone I know have multiple families living in the 1 house), reflection of Matariki
Have some resources on Māori views on wealth, money and its importance to them, do they value money or wealth as a culture. Why Māori typically or historically have dealt with debt and poverty - the why’s. How do iwi and hapu distribute their koha amongst their members or what they like to spend money on. Māori business ventures - things that consumers can invest in that support Māori.
Te Reo Māori options, connecting with Māori audiences/stakeholders (iwi assets, supporting whānau trusts and information on Māori land titles which might be relevant)
Bring in more thought of children and how your actions today will benefit your children in the future as you pass on good money habits for them to grow on and pass down
Te Reo, using our own year for goals -Matariki etc
Our ancestors were forever learning and growing. Changing and adapting to the worlds they lived in. It is our responsibility to do the same. Educating ourselves financially will strengthen our Whakapapa.
Budgeting stories from a Māori perspective. What are the financial issues impacting Māori?
Language, kai affirmations through whakatauki
More information on Māori land courts etc
Include designs and artwork on the website to reflect Te Ao Māori. Include translations. Include whakatauki or Māori proverbs that reflect the attitudes Māori have towards gathering, saving and prosperity or any other topics that apply to attitudes towards money and life.
Consideration of tikanga Māori and a Māori worldview as it relates to finances i.e, the western view is more individualistic whereas the Māori worldview is more focused on the collective/the whānau. Additionally, it could be interesting for you to delve into topics such as what buying a house means in terms of Te Tiriti o Waitangi and the fact that this is stolen land - but I acknowledge that this one is unlikely.
Seeing Māori people on home page. Linking with Māori financial content creators ie. @the.hiddenfigures<br>
42
Appendices<br>
43
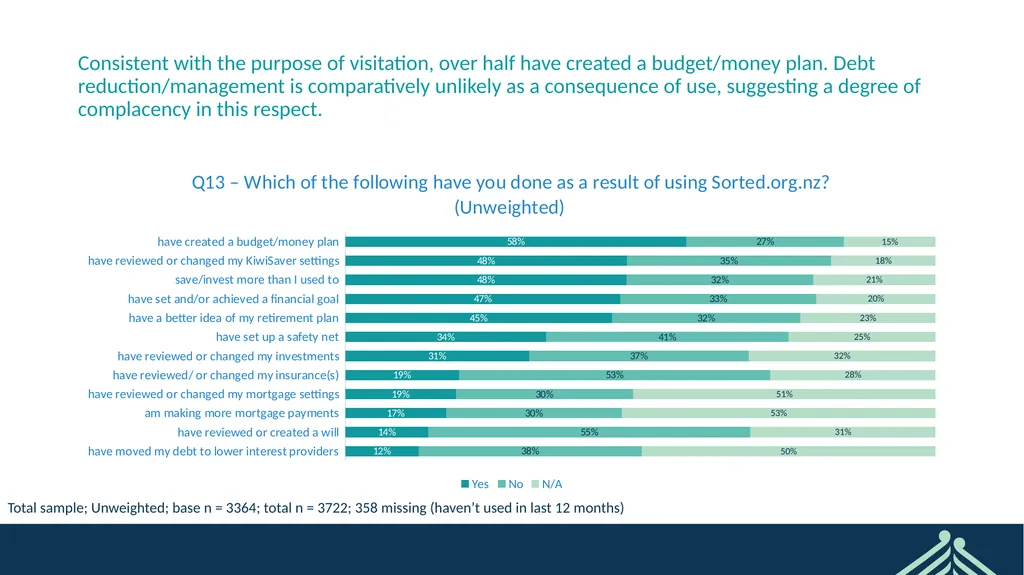
Consistent with the purpose of visitation, over half have created a budget/money plan. Debt reduction/management is comparatively unlikely as a consequence of use, suggesting a degree of complacency in this respect. Total sample; Unweighted; base n = 3364; total n = 3722; 358 missing (haven’t used in last 12 months)<br>
44
Significantly greater p<0.05
Significantly greater than total p<0.05 Significantly less than total p<0.05<br>
Significantly greater than total p<0.05 Significantly less than total p<0.05<br>