
STRATEGIC PLANNING FOR Post-Clearance Audit (PCA)
Description: STRATEGIC PLANNING FOR Post-Clearance Audit (PCA) (based on WCO PCA Guidelines, Vol.1) A structured examination of a business relevant commercial systems, sales contracts, financial and non-financial records, physical stock and other
Related Topics
Download Presentation
"STRATEGIC PLANNING FOR Post-Clearance Audit (PCA)" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. STRATEGIC PLANNING FOR Post-Clearance Audit (PCA) (based on WCO PCA Guidelines, Vol.1)<br>
slide2. “A structured examination of a business’ relevant commercial systems, sales contracts, financial and non-financial records, physical stock and other assets as a means to measure and improve compliance.” WHAT IS POST CLEARANCE AUDIT (PCA)?<br>
slide3. What pca isn’t! AN ENFORCEMENT TOOL
NOT A MEANS OF INVESTIGATING POSSIBLE FRAUD
WHERE FRAUD IS SUSPECTED, REFER TO INVESTIGATION SPECIALISTS
A FORM OF INTERNAL AUDIT
NOT DESIGNED AS A MECHANISM FOR CHECKING CONTROLS CONDUCTED BY CUSTOMS AT THE FRONTIER<br>
slide4. What are the objectives of PCA? To assure that Customs declarations have been completed in compliance with Customs requirements, via examination of a trader’s systems, accounting records and premises;
To verify that the amount of revenue legally due has been identified and paid;
To facilitate international trade movements of the compliant trade sector;
To ensure goods liable to specific import/export controls are properly declared, including prohibitions and restrictions, licenses, quota, etc.;
To ensure conditions relating to specific approvals and authorizations are being observed<br>
slide5. Benefits derived from PCA Compliant trade facilitated at time of Customs clearance
Customs gain better information and understanding of clients’ business
Risk levels more easily assessed and reviewed
Facilitates client education and comprehensive compliance management focus
Customs can promote concept of voluntary compliance and self-assessment
Customs administrations’ resources more effectively deployed
Suspected fraudulent activities may be identified
Provides platform for evaluating entitlement to certain authorisations; e.g. AEO status<br>
slide6. Types of post-import controls Post-importation transaction verification
Port referrals
Risk selection
Disputed decisions/ importer requests
Field / on-site audit
Risk selection
Office/ desk audit
Risk selection
Large business focus – special teams<br>
slide7. Transition from border-focused controls to PCA as the prime basis for Customs controls typically evolves over several years
PCA implementation should be embedded in a wider facilitation/modernization context
Infrastructure considerations
Consider as a first step, post-importation transaction-based controls STEPPING STONES TOWARDS AN EFFECTIVE PCA SYSTEM<br>
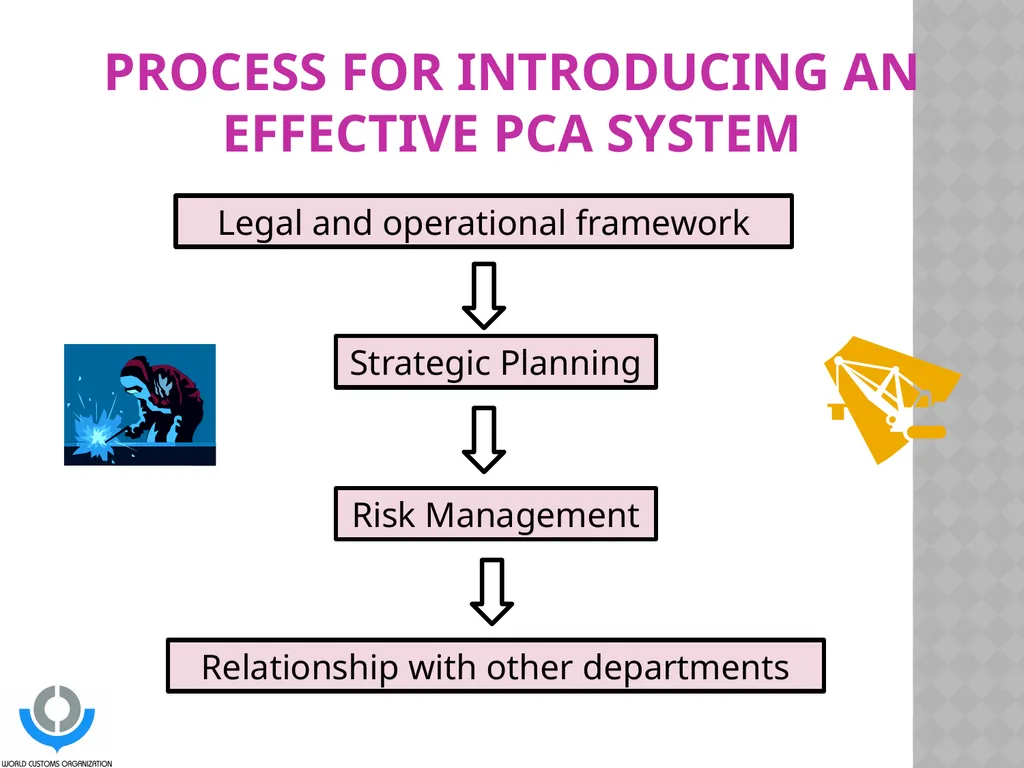
slide8. Process for introducing an effective PCA system Legal and operational framework Strategic Planning Risk Management Relationship with other departments<br>
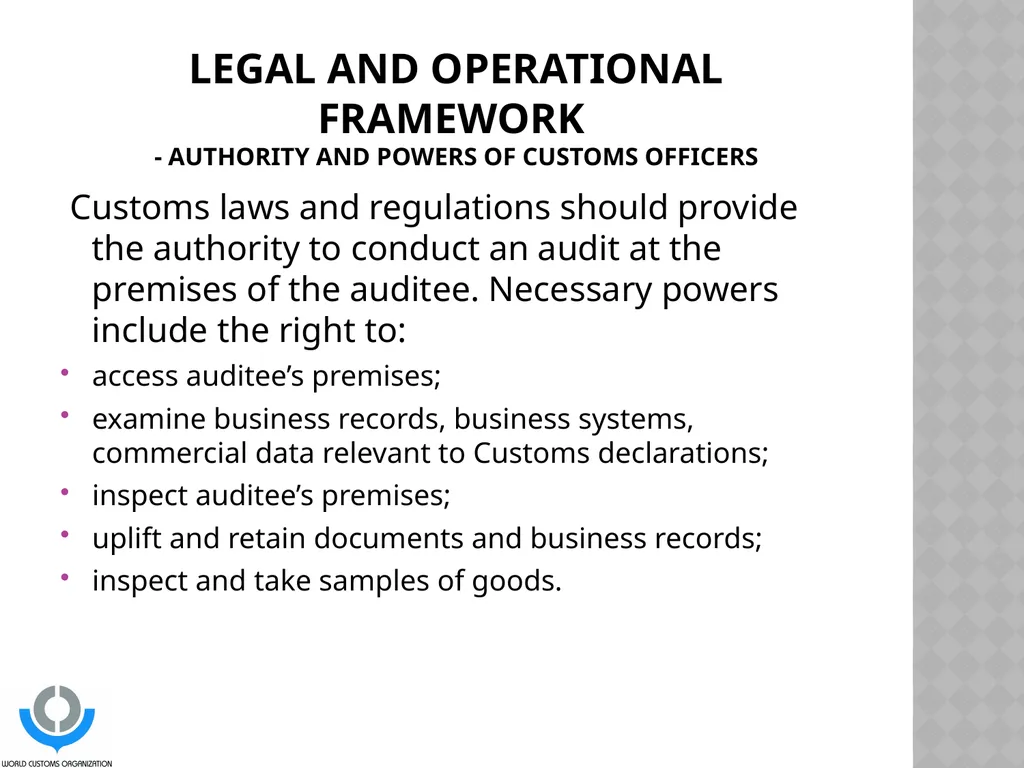
slide9. LEGAL and operational framework - Authority and powers of Customs officers Customs laws and regulations should provide the authority to conduct an audit at the premises of the auditee. Necessary powers include the right to:
access auditee’s premises;
examine business records, business systems, commercial data relevant to Customs declarations;
inspect auditee’s premises;
uplift and retain documents and business records;
inspect and take samples of goods.<br>
slide10. LEGAL and operational framework - Obligations and rights of auditees (I) Customs laws and regulations should set out the rights and obligations of persons & companies involved in international trade. Provisions should include:
The requirement to maintain specified documentation, information and records
The duration for retaining such records (no less than the maximum period after importation for effecting duty adjustments)<br>
slide11. LEGAL and operational framework - Obligations and rights of auditees (II) requirement to make such documentation, information and records available in a timely manner;
right to appeal ;
right to an explanation from Customs concerning determination of Customs value;
right to expect confidential treatment of business documentation;
right to clearance of goods at the frontier with provision of security.<br>
slide12. Introduction of Strategic Planning for PCA The audit plan should include the following :
How importers will be selected/targeted
How to improve compliance via self-assessment
How to manage resources for PCA
Relationship with other Customs sections:
e.g. border control, risk management, enforcement etc.<br>
slide13. Training needs and professional skills (I) All auditors need a range of general skills including:
accounting techniques and principles :
knowledge of auditing standards and procedures;
familiarity with Customs laws and regulations;
general knowledge of Customs procedures (valuation, classification, origin, etc.);
knowledge of computer-based accounting systems;
commercial awareness and knowledge of business strategies in international trade<br>
slide14. Training needs and professional skills (II) Additional specialist skills include:
Customs Valuation, Tariff Classification (as required)
I.T.-based accounting
Multi-national corporation accounting, including transfer pricing
specialist trade sector knowledge<br>
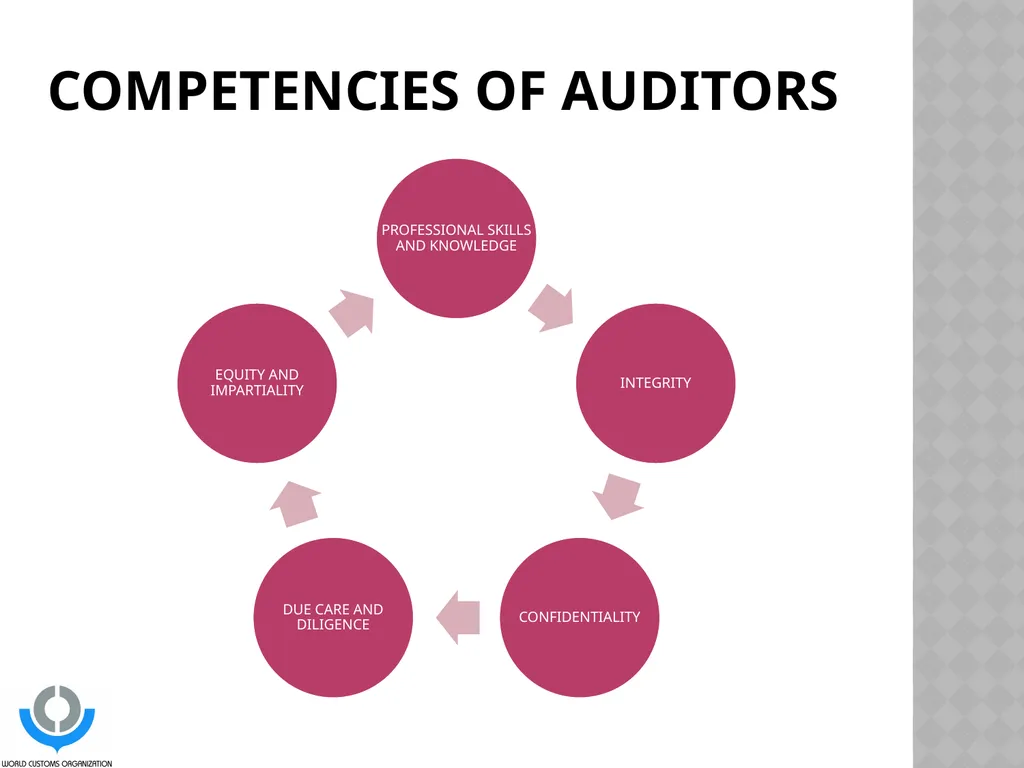
slide15. Competencies of auditors<br>
slide16. Limitations of PCA PCA is the most effective means of ensuring compliance : thorough verification requires access to importers’ records and accounting system.
Not a practical tool for informal traders :
Problems locating the trader
Lack of a structured accounting system and supporting books and records, etc.
Cash payments etc.
Customs should encourage all operators to improve compliance, including informal sector
Provide opportunity and incentive to formalize their procedures in line with Customs requirements.<br>
slide2. “A structured examination of a business’ relevant commercial systems, sales contracts, financial and non-financial records, physical stock and other assets as a means to measure and improve compliance.” WHAT IS POST CLEARANCE AUDIT (PCA)?<br>
slide3. What pca isn’t! AN ENFORCEMENT TOOL
NOT A MEANS OF INVESTIGATING POSSIBLE FRAUD
WHERE FRAUD IS SUSPECTED, REFER TO INVESTIGATION SPECIALISTS
A FORM OF INTERNAL AUDIT
NOT DESIGNED AS A MECHANISM FOR CHECKING CONTROLS CONDUCTED BY CUSTOMS AT THE FRONTIER<br>
slide4. What are the objectives of PCA? To assure that Customs declarations have been completed in compliance with Customs requirements, via examination of a trader’s systems, accounting records and premises;
To verify that the amount of revenue legally due has been identified and paid;
To facilitate international trade movements of the compliant trade sector;
To ensure goods liable to specific import/export controls are properly declared, including prohibitions and restrictions, licenses, quota, etc.;
To ensure conditions relating to specific approvals and authorizations are being observed<br>
slide5. Benefits derived from PCA Compliant trade facilitated at time of Customs clearance
Customs gain better information and understanding of clients’ business
Risk levels more easily assessed and reviewed
Facilitates client education and comprehensive compliance management focus
Customs can promote concept of voluntary compliance and self-assessment
Customs administrations’ resources more effectively deployed
Suspected fraudulent activities may be identified
Provides platform for evaluating entitlement to certain authorisations; e.g. AEO status<br>
slide6. Types of post-import controls Post-importation transaction verification
Port referrals
Risk selection
Disputed decisions/ importer requests
Field / on-site audit
Risk selection
Office/ desk audit
Risk selection
Large business focus – special teams<br>
slide7. Transition from border-focused controls to PCA as the prime basis for Customs controls typically evolves over several years
PCA implementation should be embedded in a wider facilitation/modernization context
Infrastructure considerations
Consider as a first step, post-importation transaction-based controls STEPPING STONES TOWARDS AN EFFECTIVE PCA SYSTEM<br>
slide8. Process for introducing an effective PCA system Legal and operational framework Strategic Planning Risk Management Relationship with other departments<br>
slide9. LEGAL and operational framework - Authority and powers of Customs officers Customs laws and regulations should provide the authority to conduct an audit at the premises of the auditee. Necessary powers include the right to:
access auditee’s premises;
examine business records, business systems, commercial data relevant to Customs declarations;
inspect auditee’s premises;
uplift and retain documents and business records;
inspect and take samples of goods.<br>
slide10. LEGAL and operational framework - Obligations and rights of auditees (I) Customs laws and regulations should set out the rights and obligations of persons & companies involved in international trade. Provisions should include:
The requirement to maintain specified documentation, information and records
The duration for retaining such records (no less than the maximum period after importation for effecting duty adjustments)<br>
slide11. LEGAL and operational framework - Obligations and rights of auditees (II) requirement to make such documentation, information and records available in a timely manner;
right to appeal ;
right to an explanation from Customs concerning determination of Customs value;
right to expect confidential treatment of business documentation;
right to clearance of goods at the frontier with provision of security.<br>
slide12. Introduction of Strategic Planning for PCA The audit plan should include the following :
How importers will be selected/targeted
How to improve compliance via self-assessment
How to manage resources for PCA
Relationship with other Customs sections:
e.g. border control, risk management, enforcement etc.<br>
slide13. Training needs and professional skills (I) All auditors need a range of general skills including:
accounting techniques and principles :
knowledge of auditing standards and procedures;
familiarity with Customs laws and regulations;
general knowledge of Customs procedures (valuation, classification, origin, etc.);
knowledge of computer-based accounting systems;
commercial awareness and knowledge of business strategies in international trade<br>
slide14. Training needs and professional skills (II) Additional specialist skills include:
Customs Valuation, Tariff Classification (as required)
I.T.-based accounting
Multi-national corporation accounting, including transfer pricing
specialist trade sector knowledge<br>
slide15. Competencies of auditors<br>
slide16. Limitations of PCA PCA is the most effective means of ensuring compliance : thorough verification requires access to importers’ records and accounting system.
Not a practical tool for informal traders :
Problems locating the trader
Lack of a structured accounting system and supporting books and records, etc.
Cash payments etc.
Customs should encourage all operators to improve compliance, including informal sector
Provide opportunity and incentive to formalize their procedures in line with Customs requirements.<br>